GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
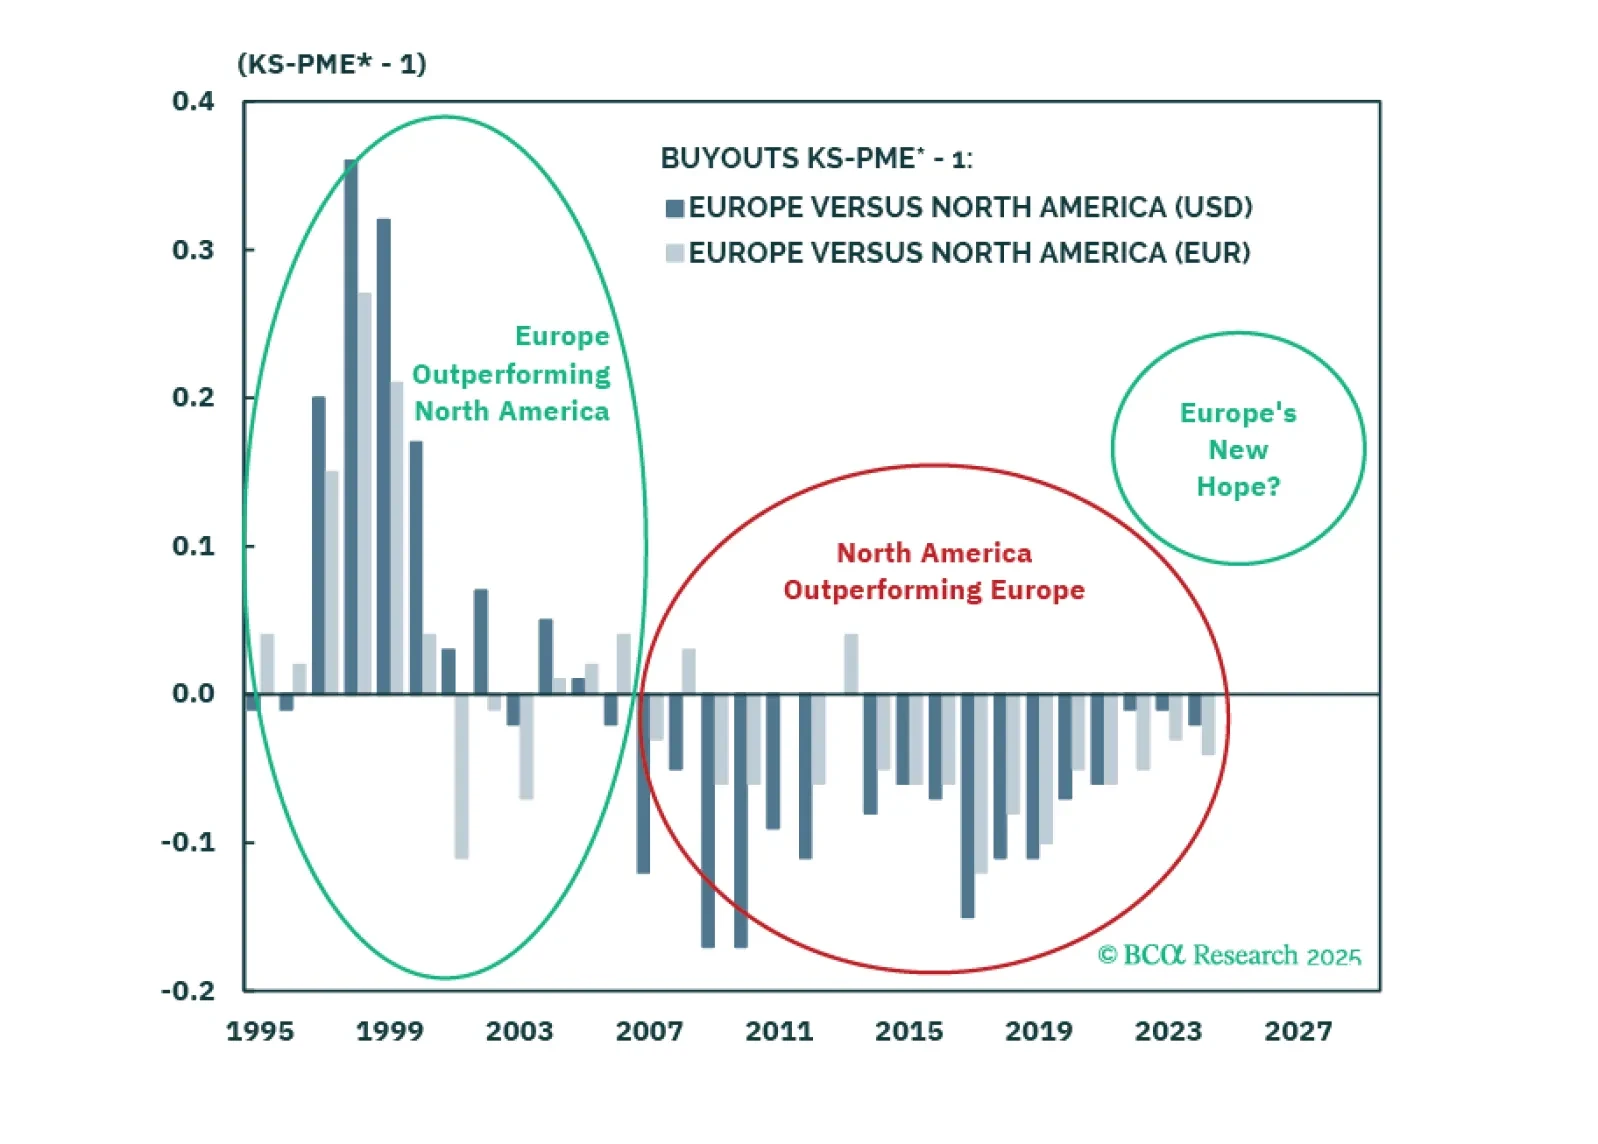
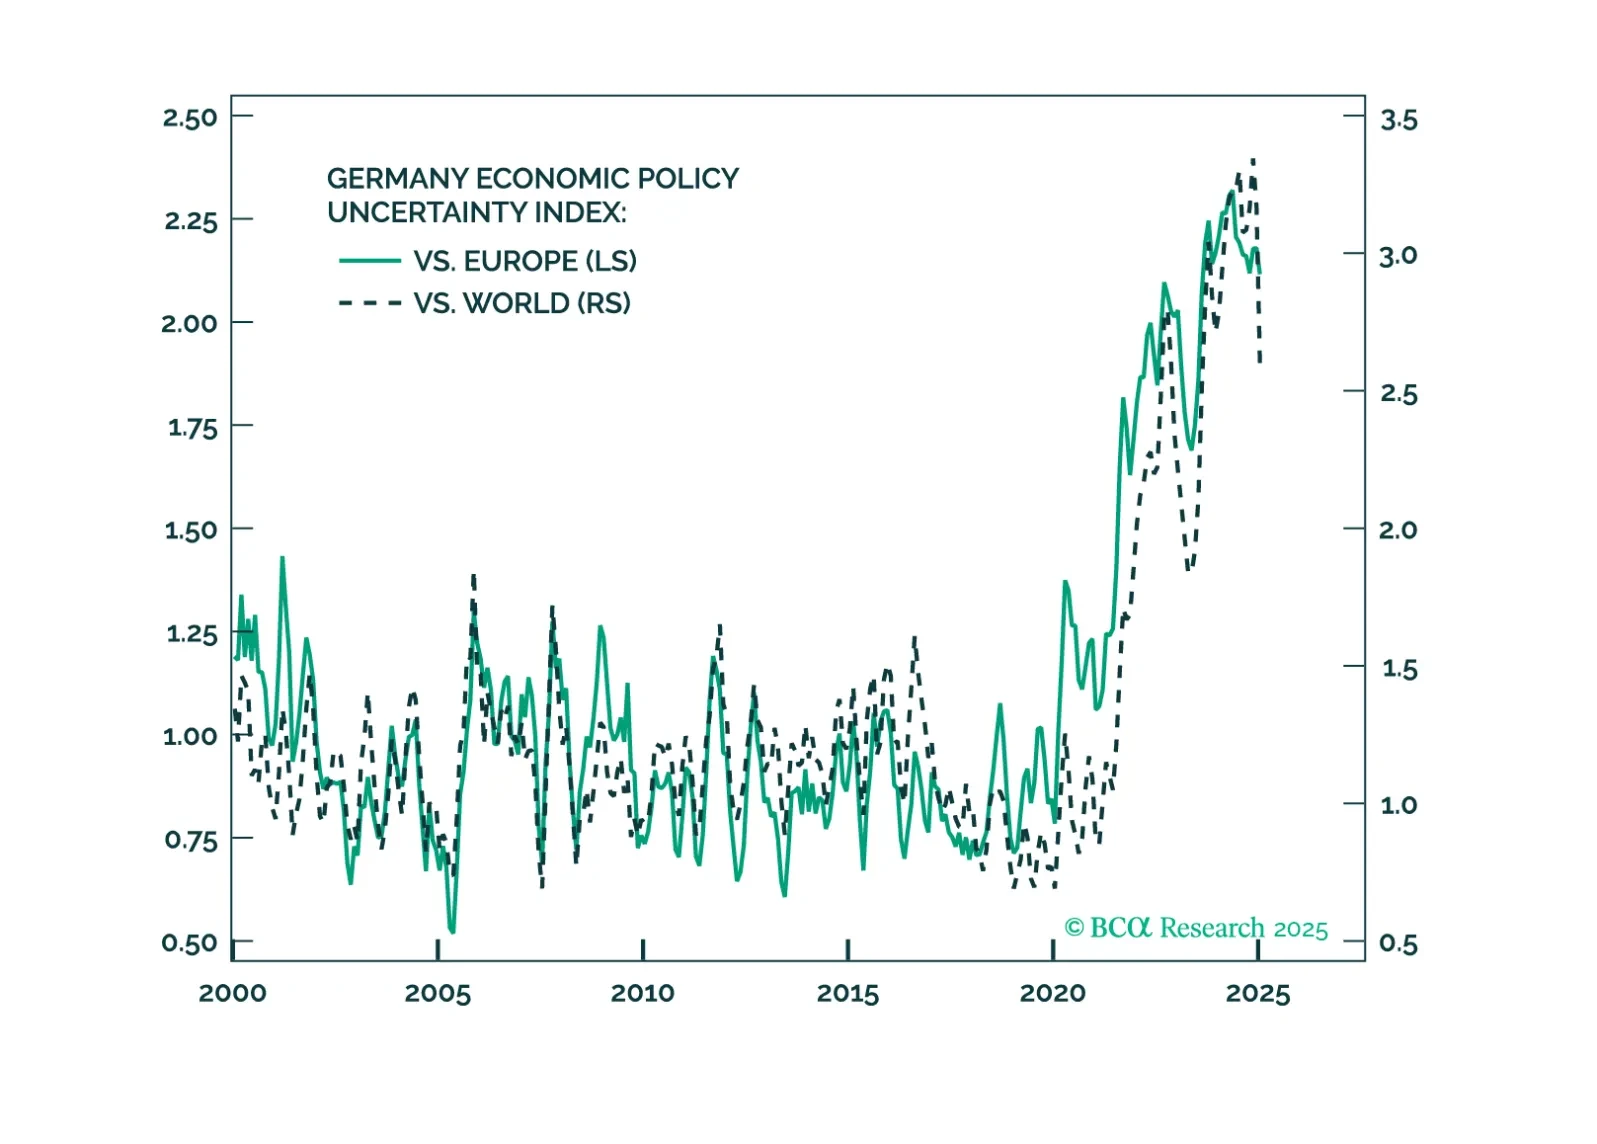
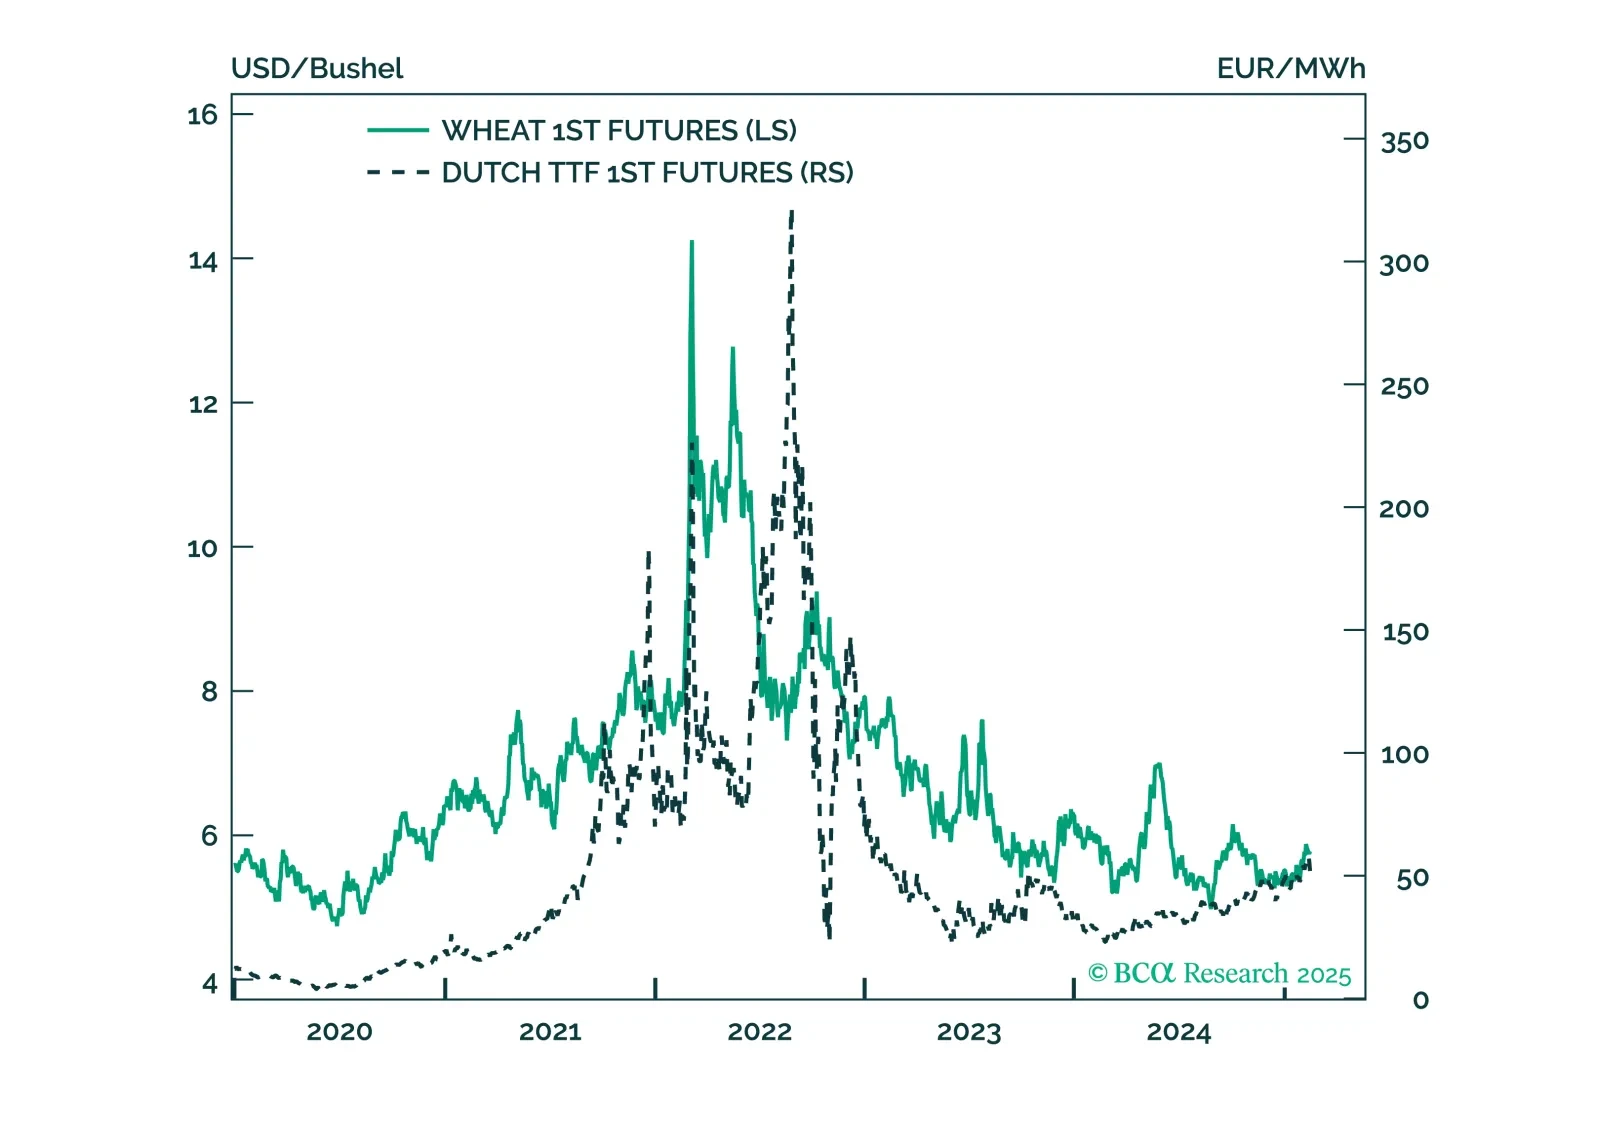
President Trump is negotiating a ceasefire in Ukraine. This will be a marginal headwind to some commodities which benefitted from the conflict like natural gas and wheat, and will be a marginal tailwind for European assets, specifically EM Europe. Use Trump’s tariff shock as an opportunity to buy European assets.
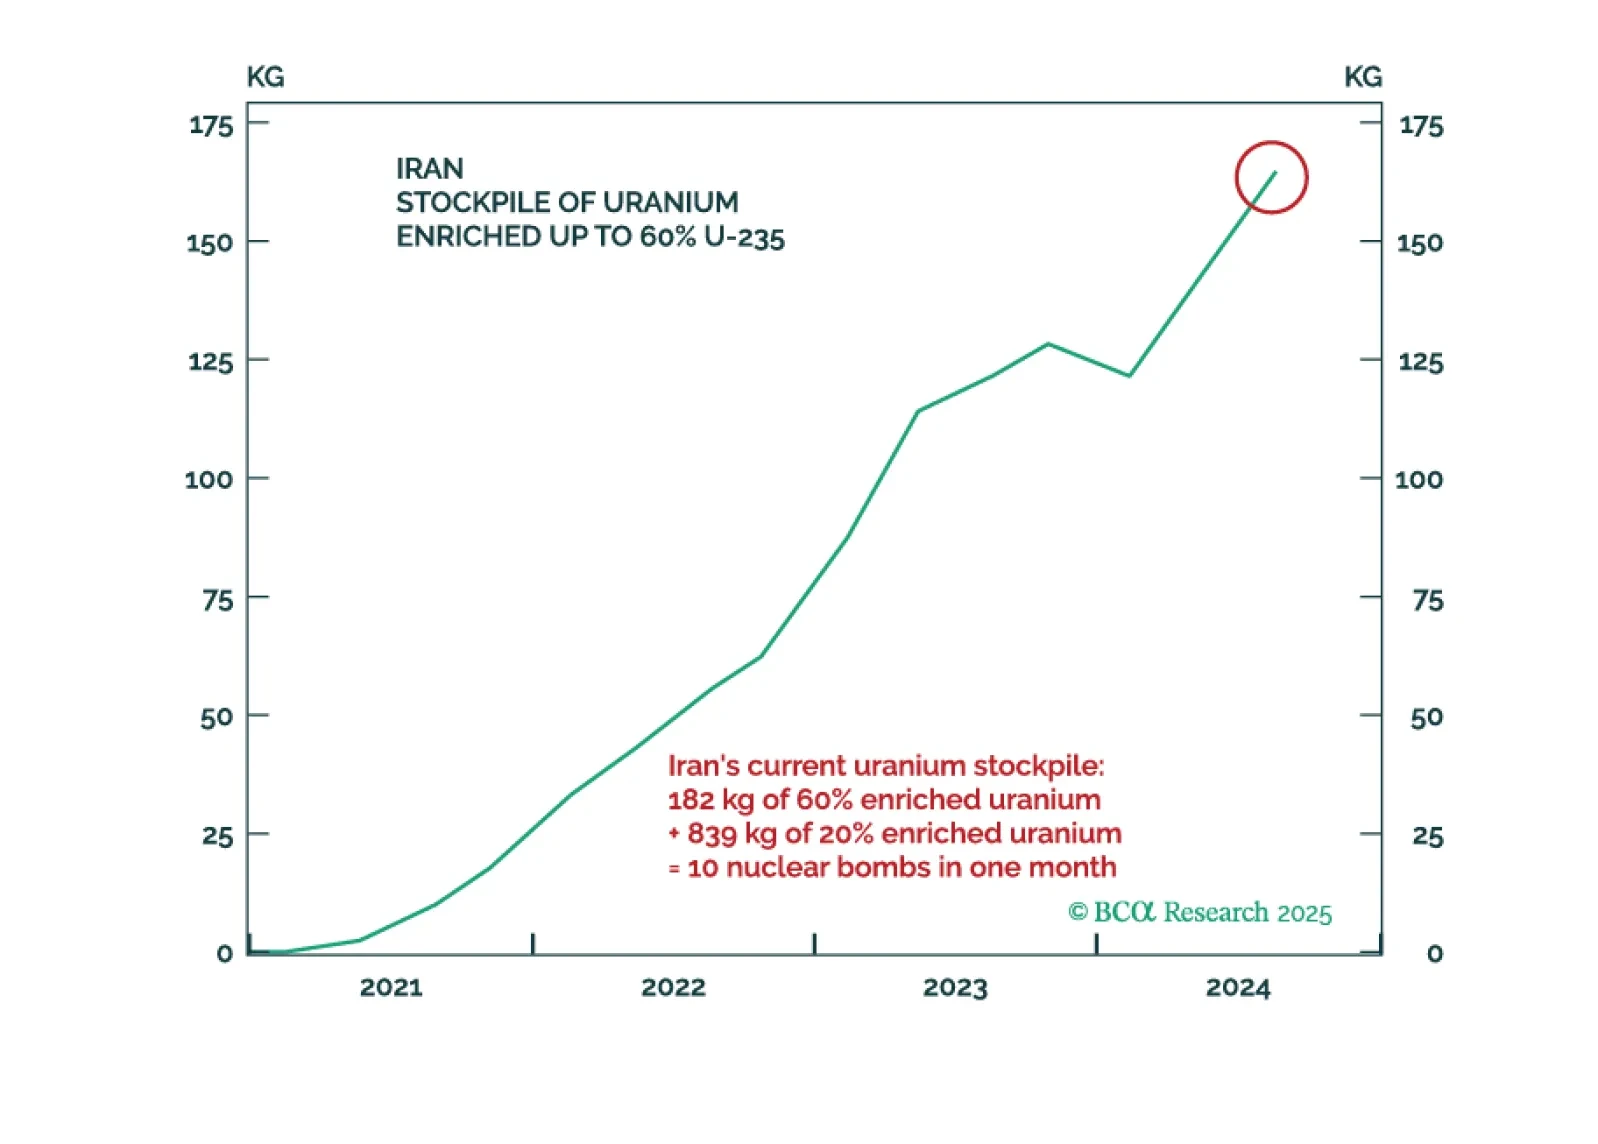
The budget process and debt ceiling will cause stock and bond market volatility. US trade policies will provoke foreign pushback at a time of stretched valuations. Hence US politics and geopolitics will be bullish for US energy, but bearish for the internationally exposed US tech sector.
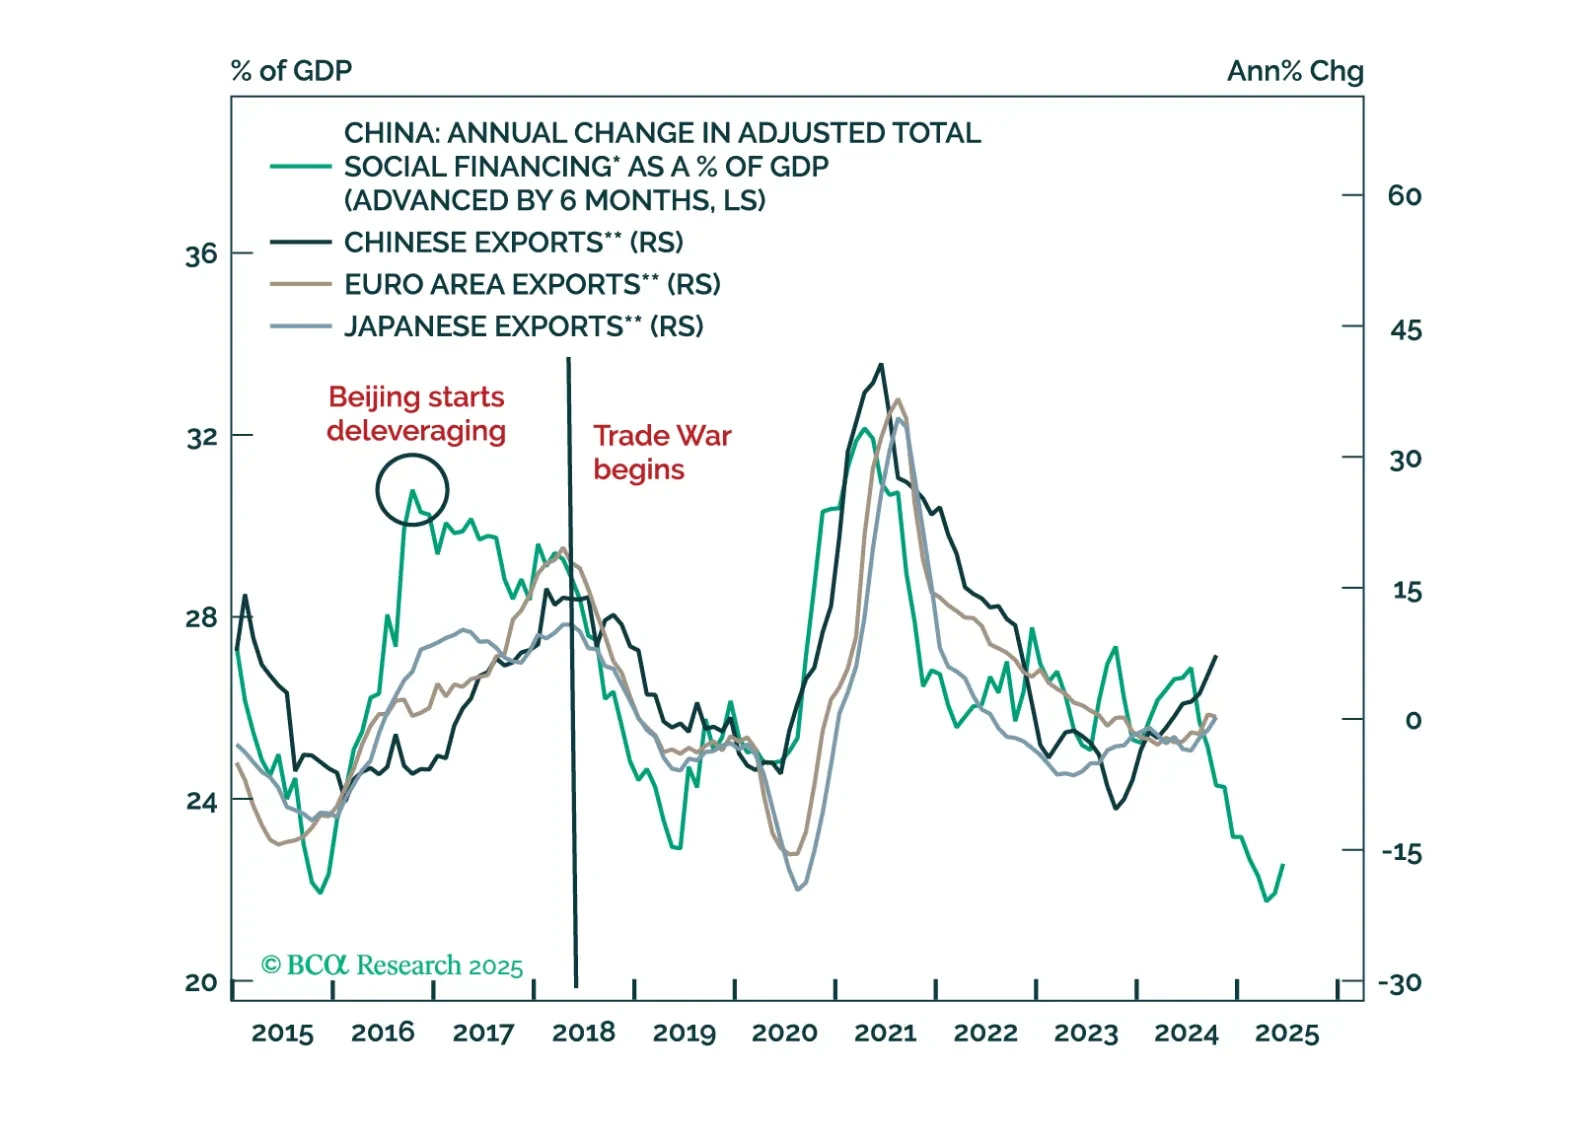
The bond market has paused its selloff thanks to a revolt by the Republicans in the House of Representatives against much of President Trump’s fiscal agenda. Gone are the lofty projections of the expanded deficit and we are now looking at merely the 2017 tax cuts being extended. This is positive for bonds, but by extension of the relationship also somewhat positive for equities. The US economy, effectively, does not need any more growth and certainly does not need any more inflation. Our thesis that we are at peak fiscal is therefore in effect.
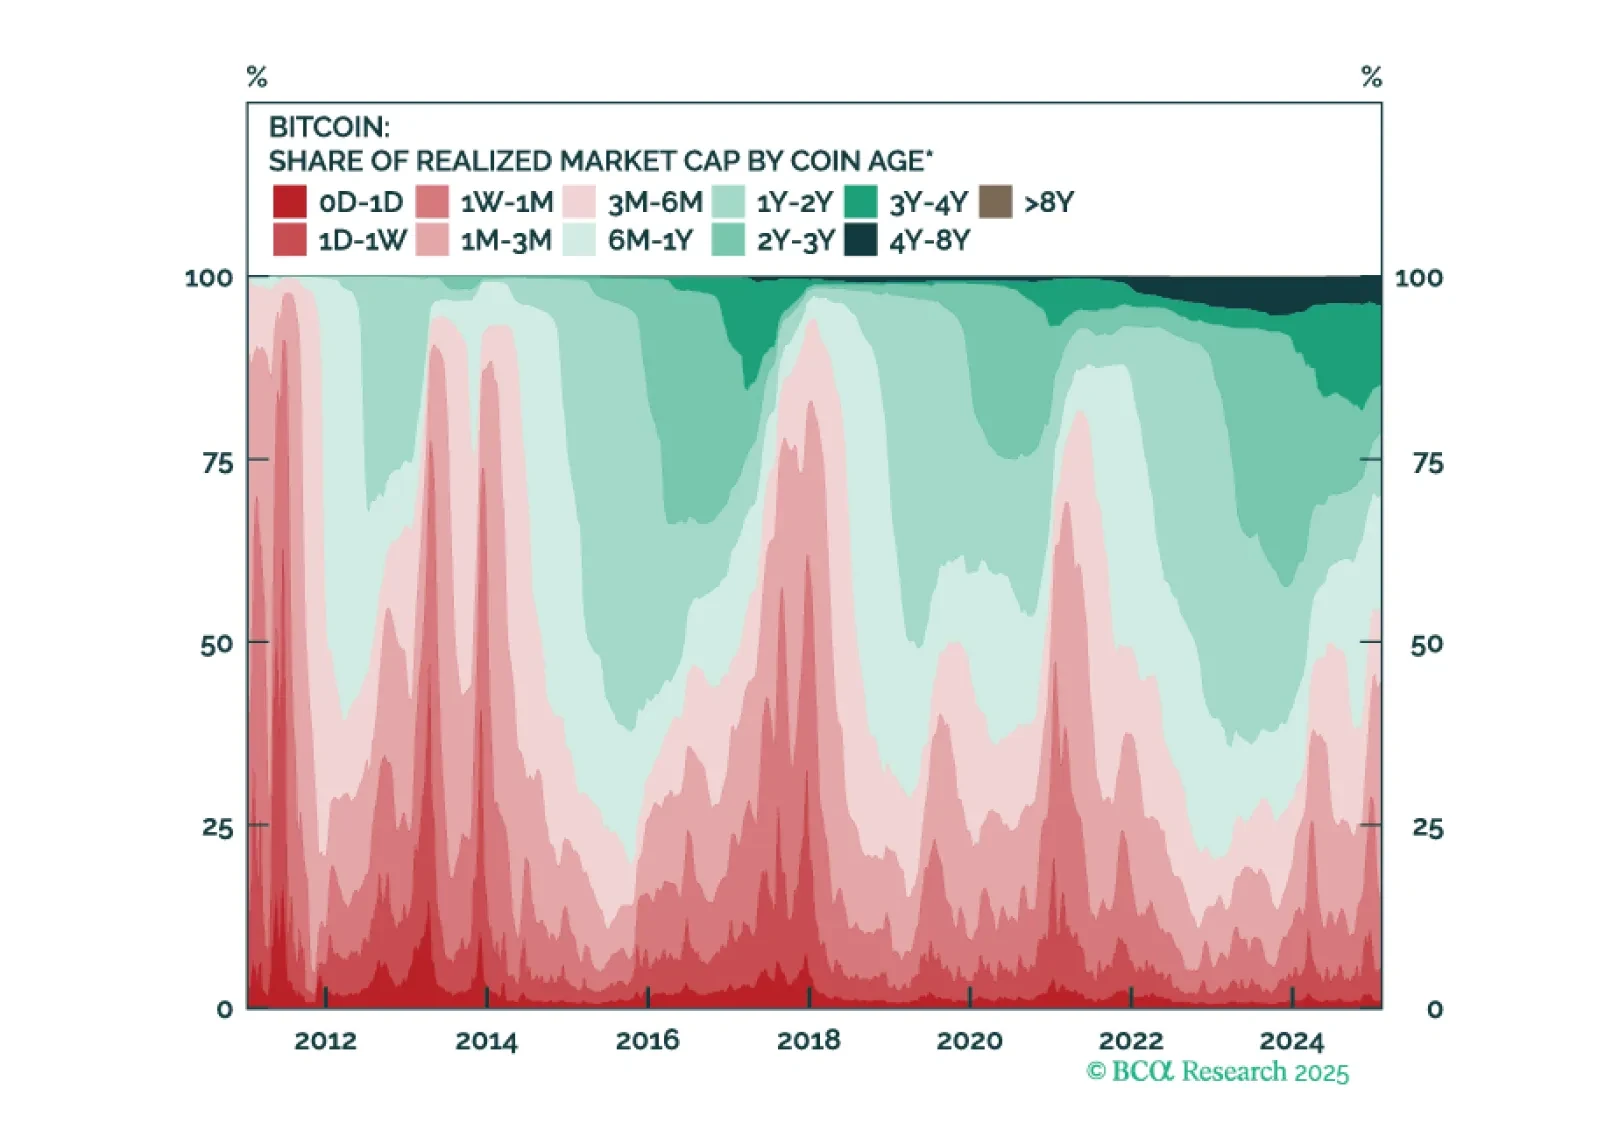
In this report, we reassess our bullish stance on crypto from early 2023, following Bitcoin’s recent all-time highs. While institutional adoption is broadening, there are also signs of excessive exuberance, speculation, and optimism. Given these conditions, a near-term correction appears likely. We are booking profits and will look to re-enter the market at $75,000.
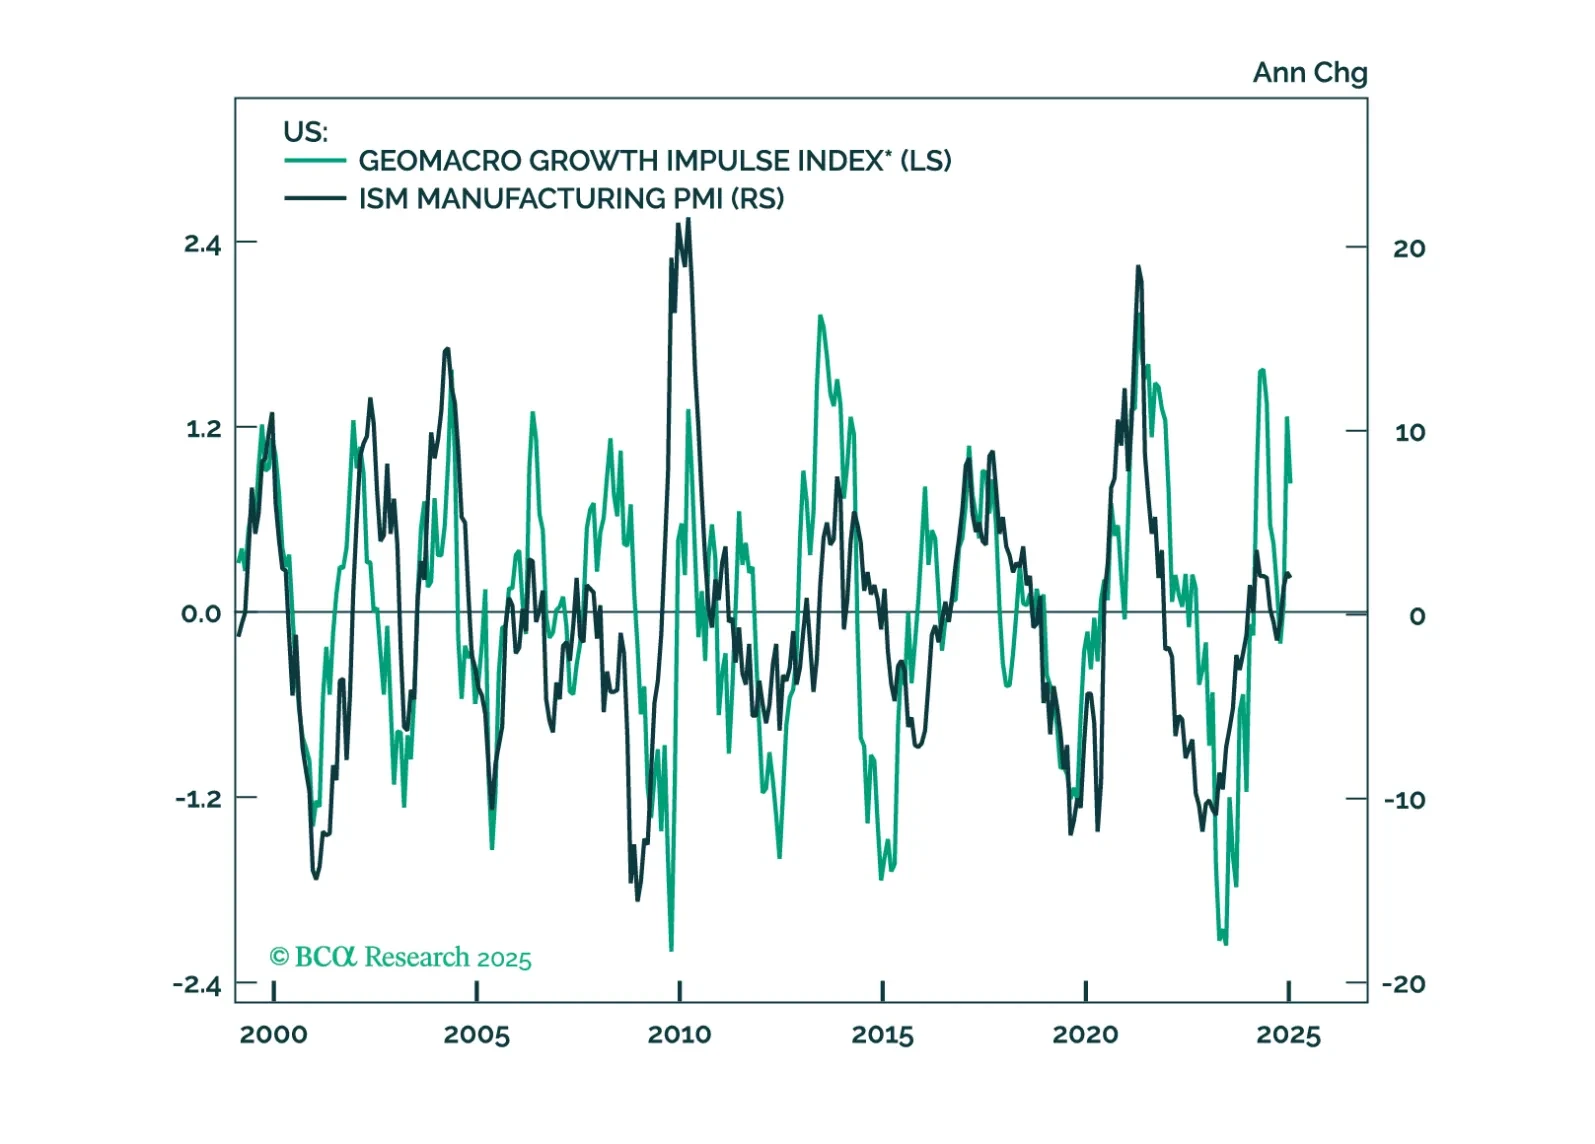
We revisit our view on the “fiscal gravy train” as well as President Trump’s negotiating style. We re-print parts of our March 2024 net assessment, particularly for the benefit of our new clients who have joined us at BCA Research. Our analysis of President Trump’s first term is our guide into how the White House will negotiate future trade wars and skirmishes.
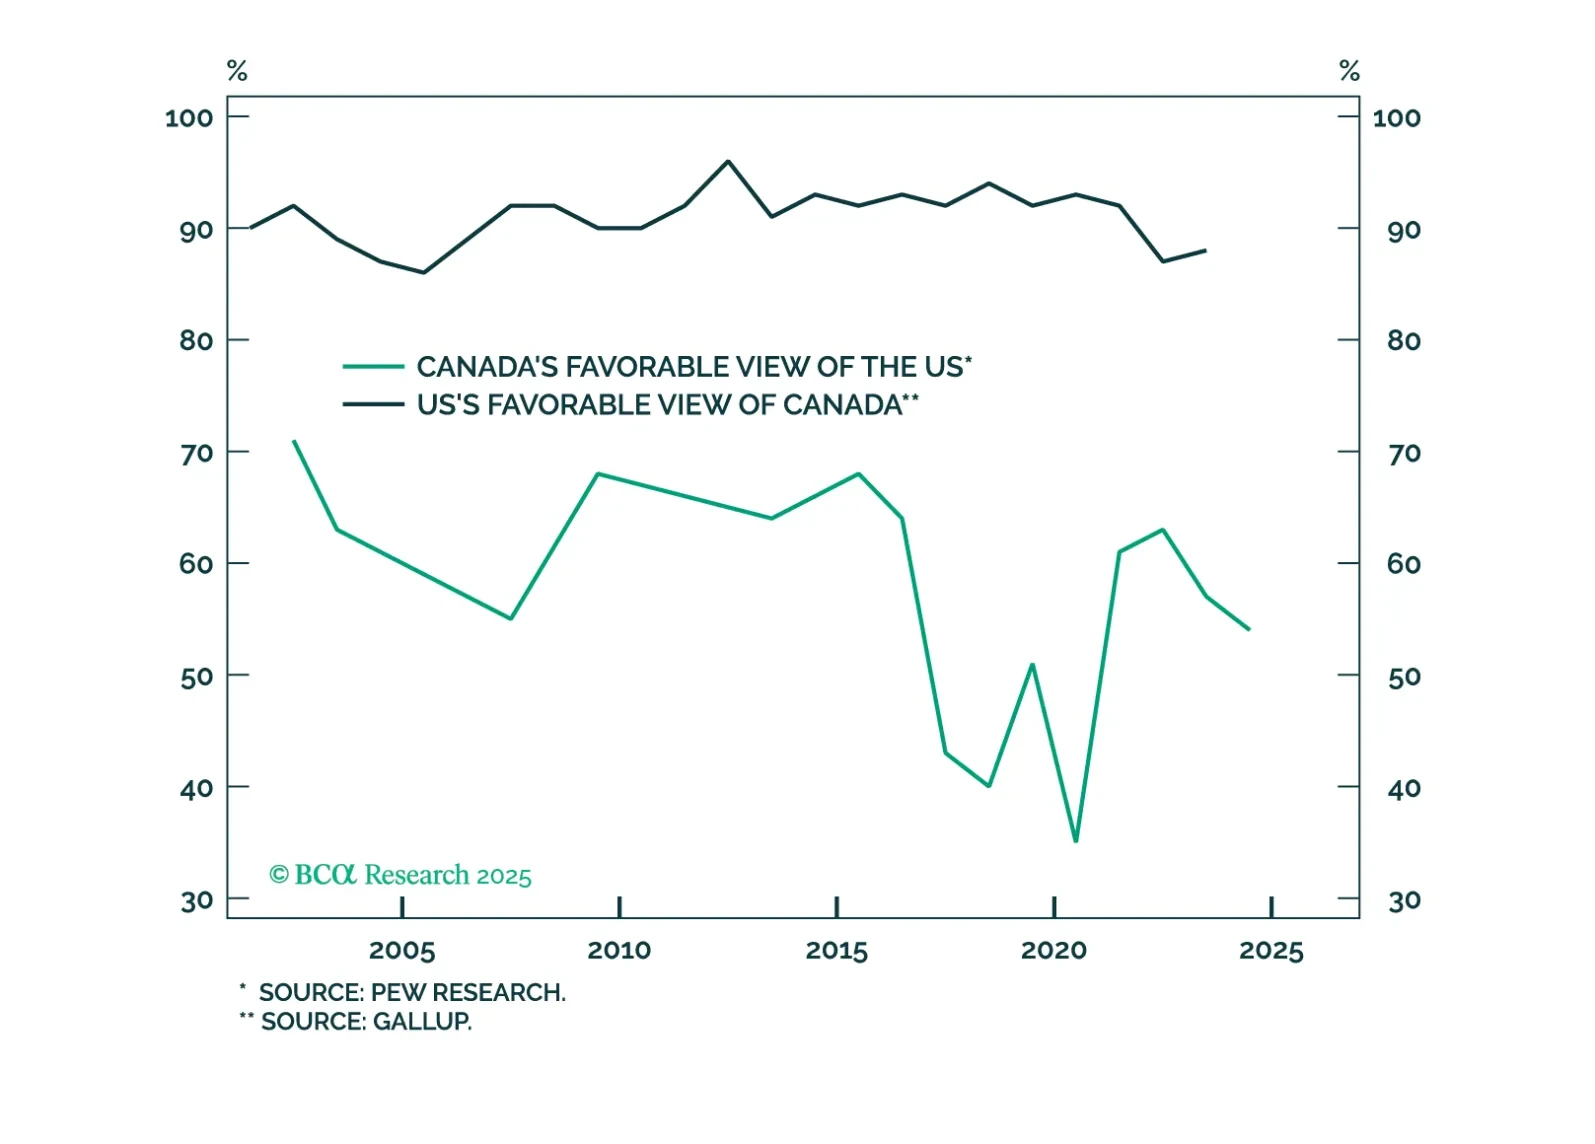
Trump’s territorial ambitions threaten to deliver negative surprises and “black swan” risks during his four-year term. Military conflicts on the Mexican border raise the biggest risk, but US intervention in Panama can never be ruled out. The investment impact will be limited unless the trans-Atlantic alliance is damaged.