 Essentials
| Thematic Reports
Deep dives on the biggest investment debates of the moment, from strategists across BCA.
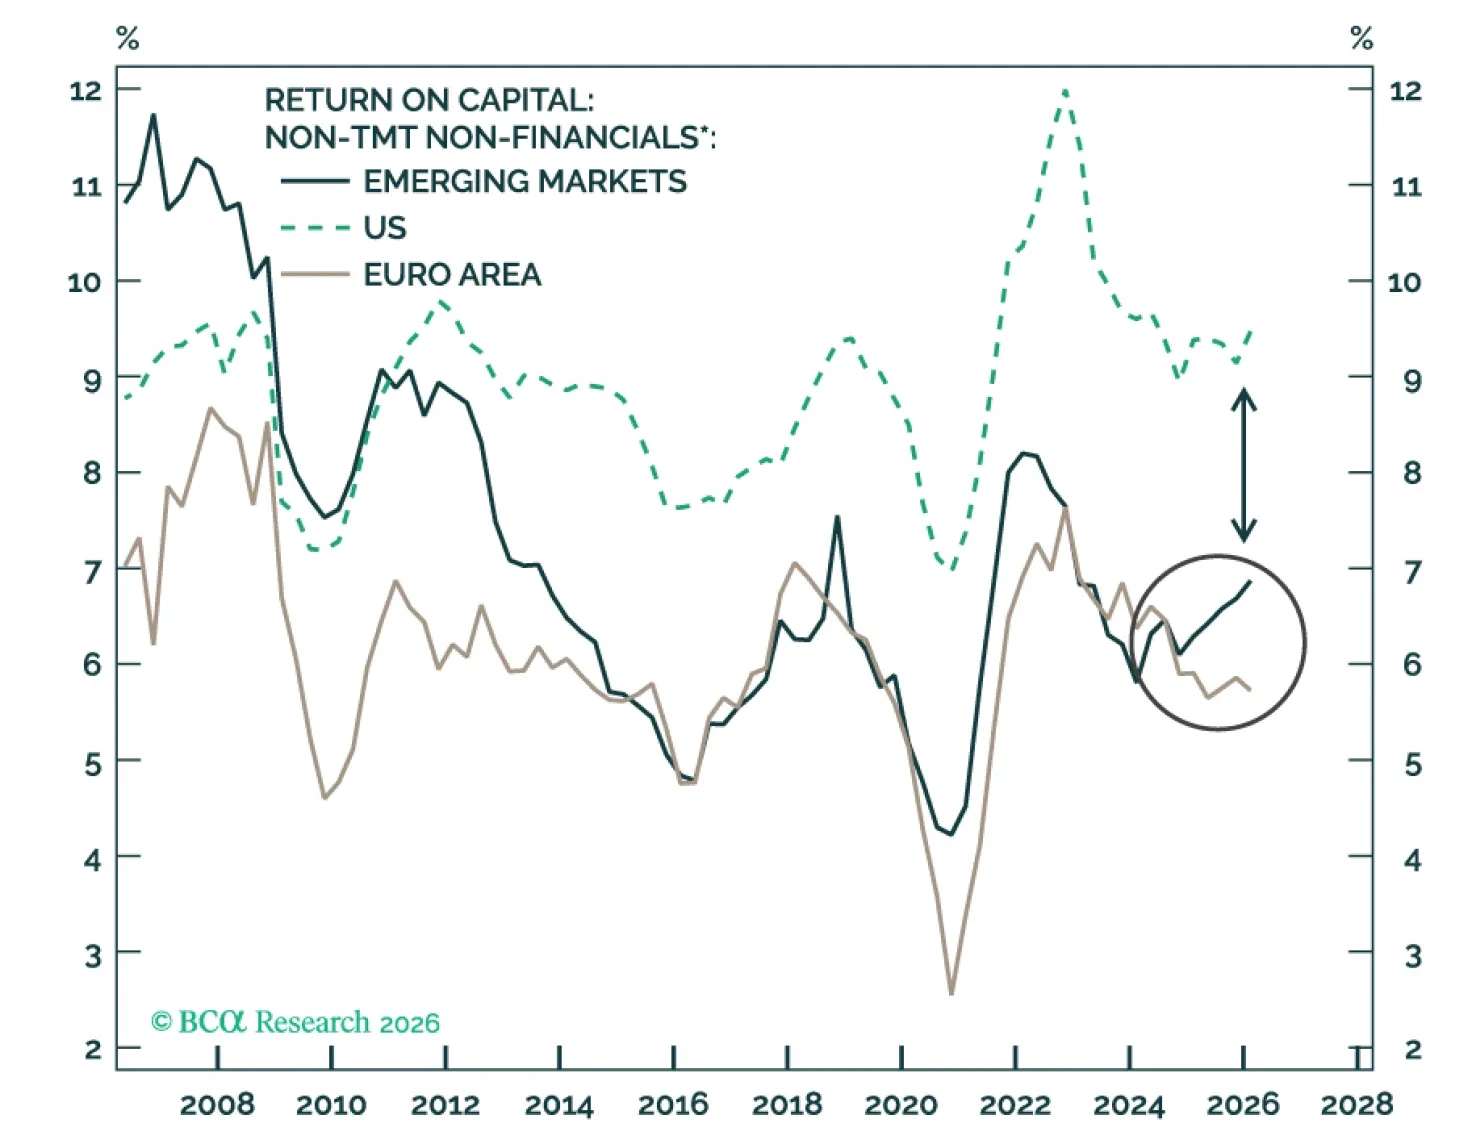
This series brings together five reports on corporate profitability across the US, Europe, Japan, China, and EM. The findings reveal a structurally desynchronized nature between regional corporate profitability. This is critical to alpha generation.
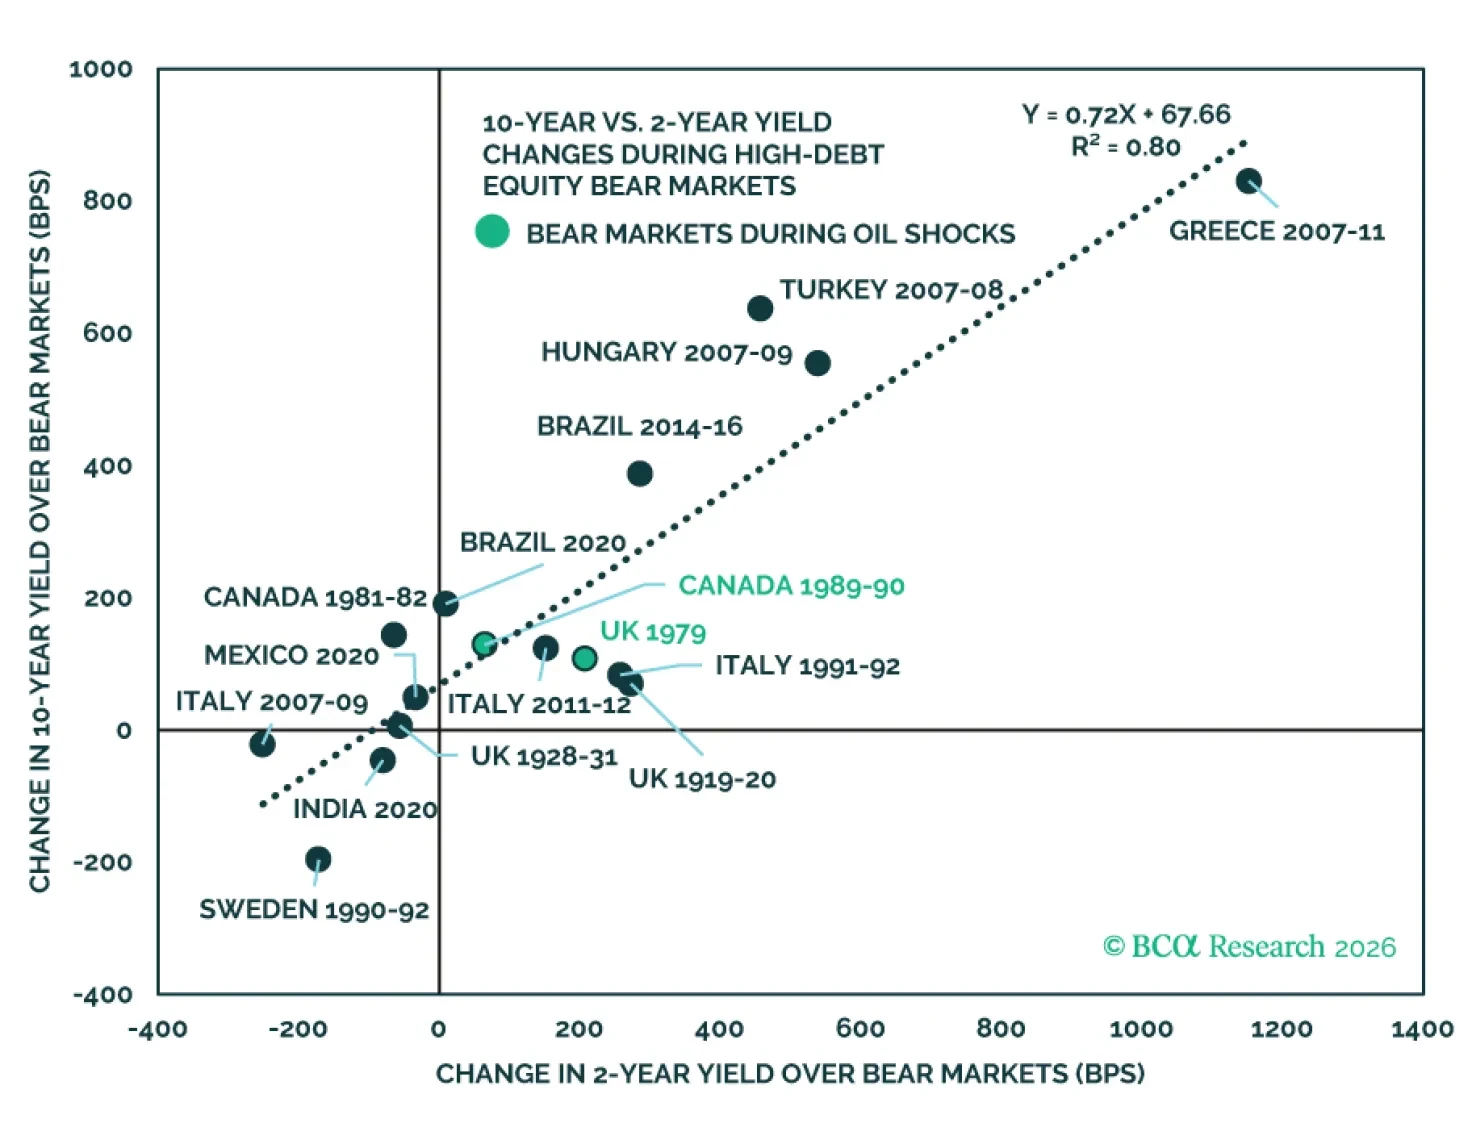
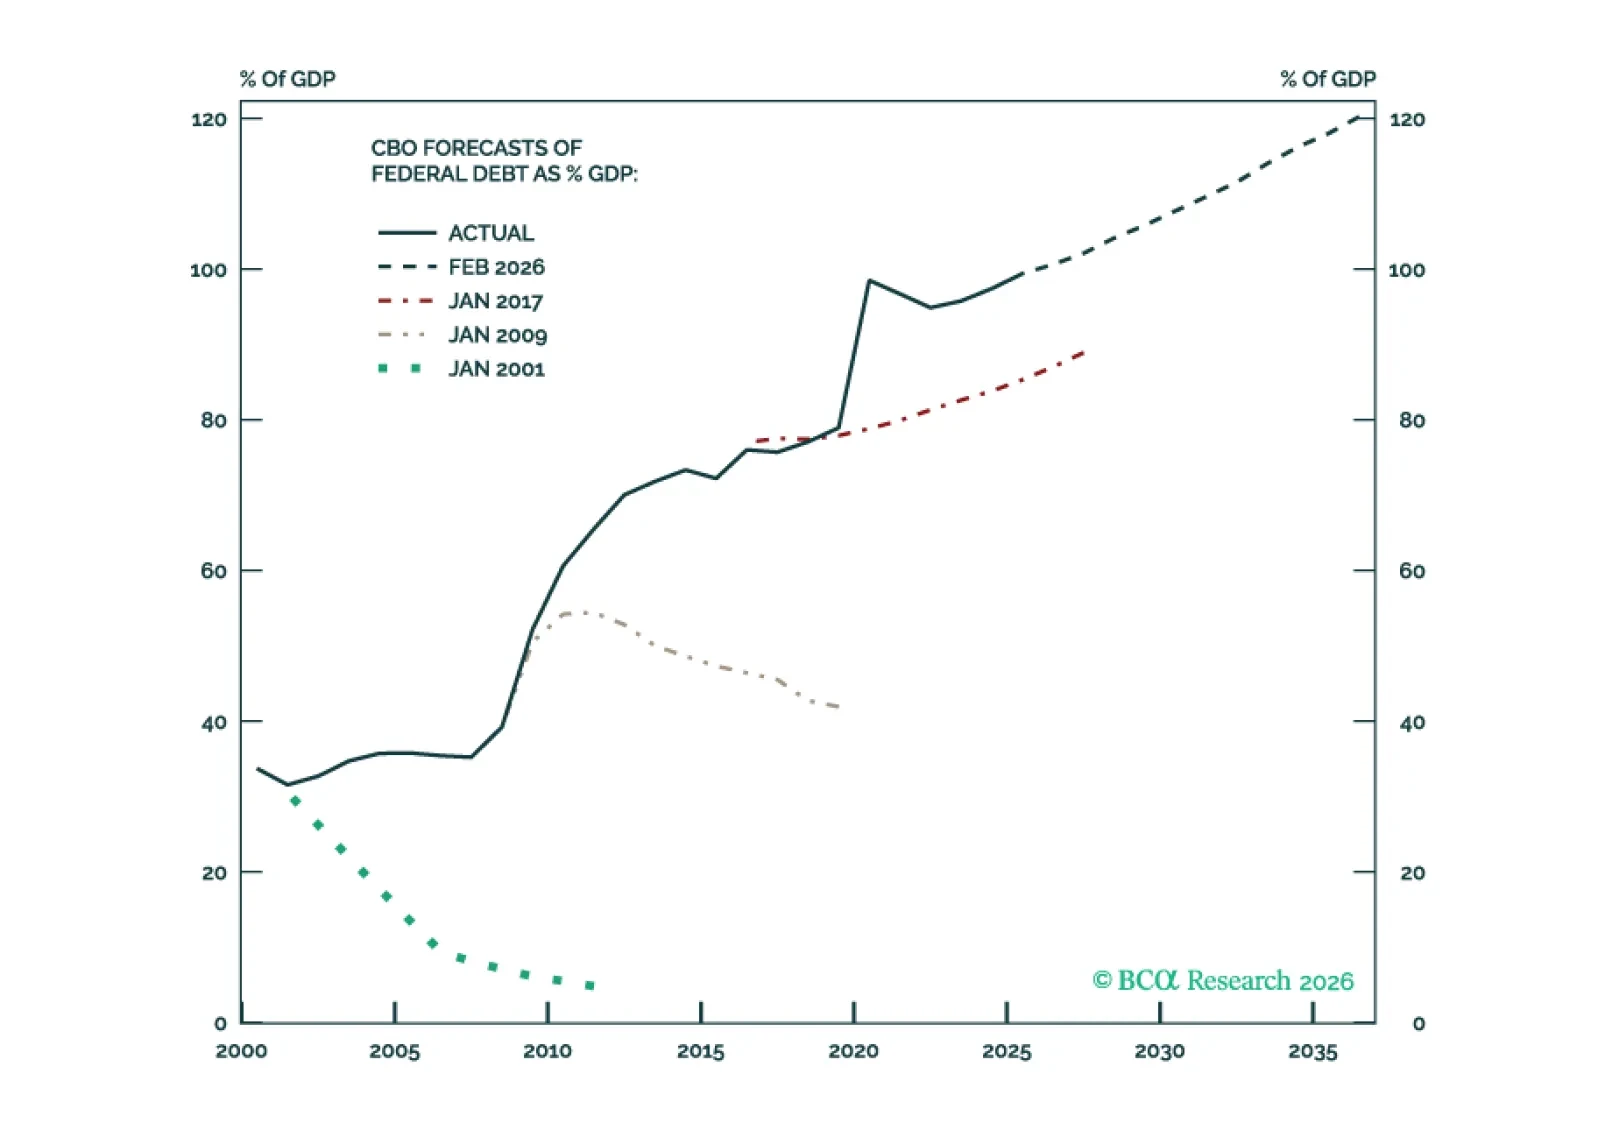
History suggests central bank policy determines how bonds behave in recessions, even for high-debt countries. The Fed should be able to cut into a slowdown, making Treasurys an effective equity hedge… for USD-based investors. Foreign investors will see currency depreciation erase their gains.
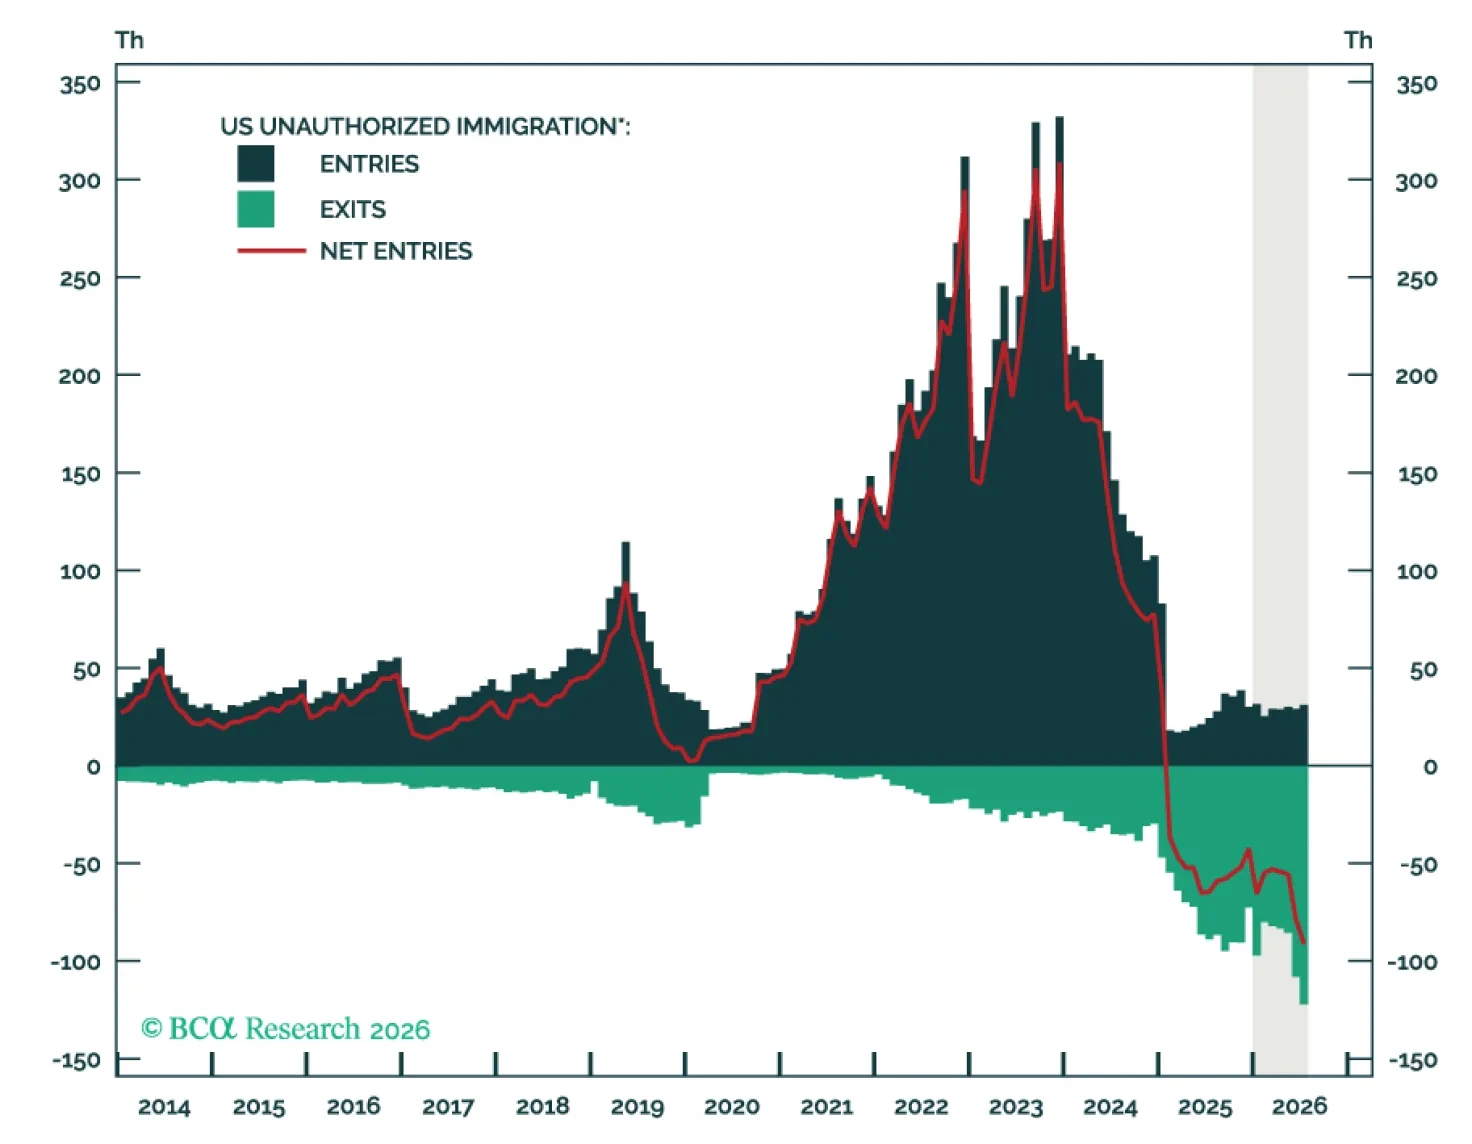
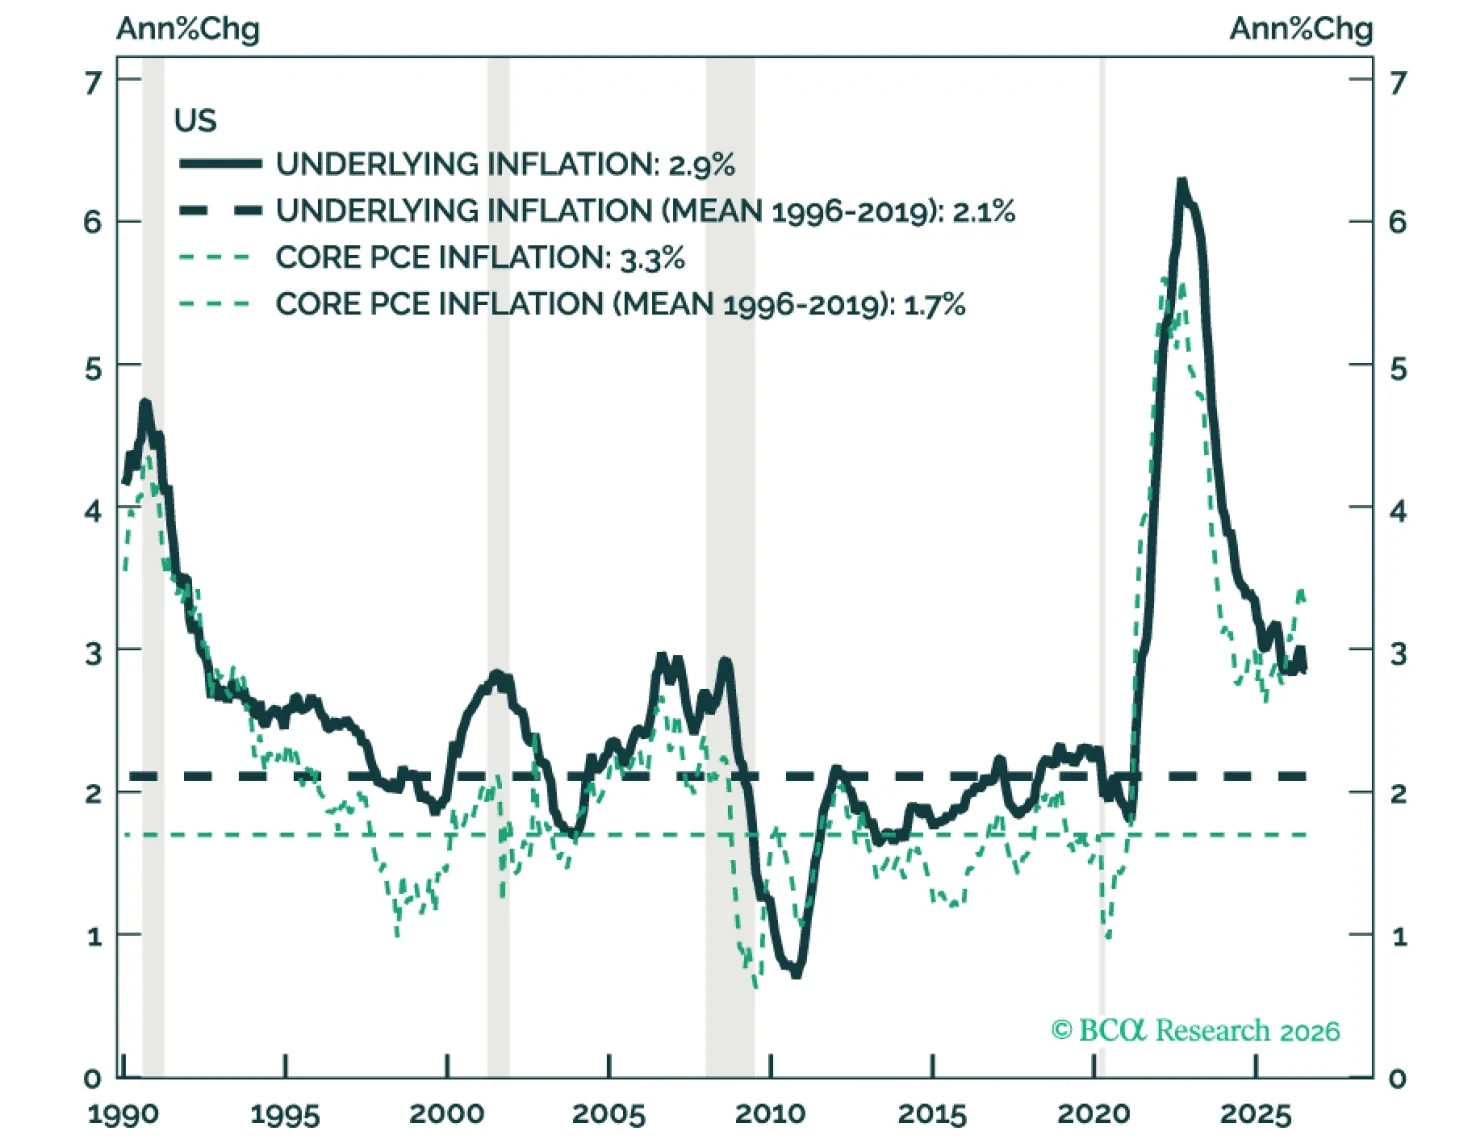
Labor supply is not meaningfully boosting inflation today, but the net exit of unauthorized immigrants has lowered the bar for stronger labor demand to turn inflationary. Hawkish monetary policy surprises over the coming year are possible.
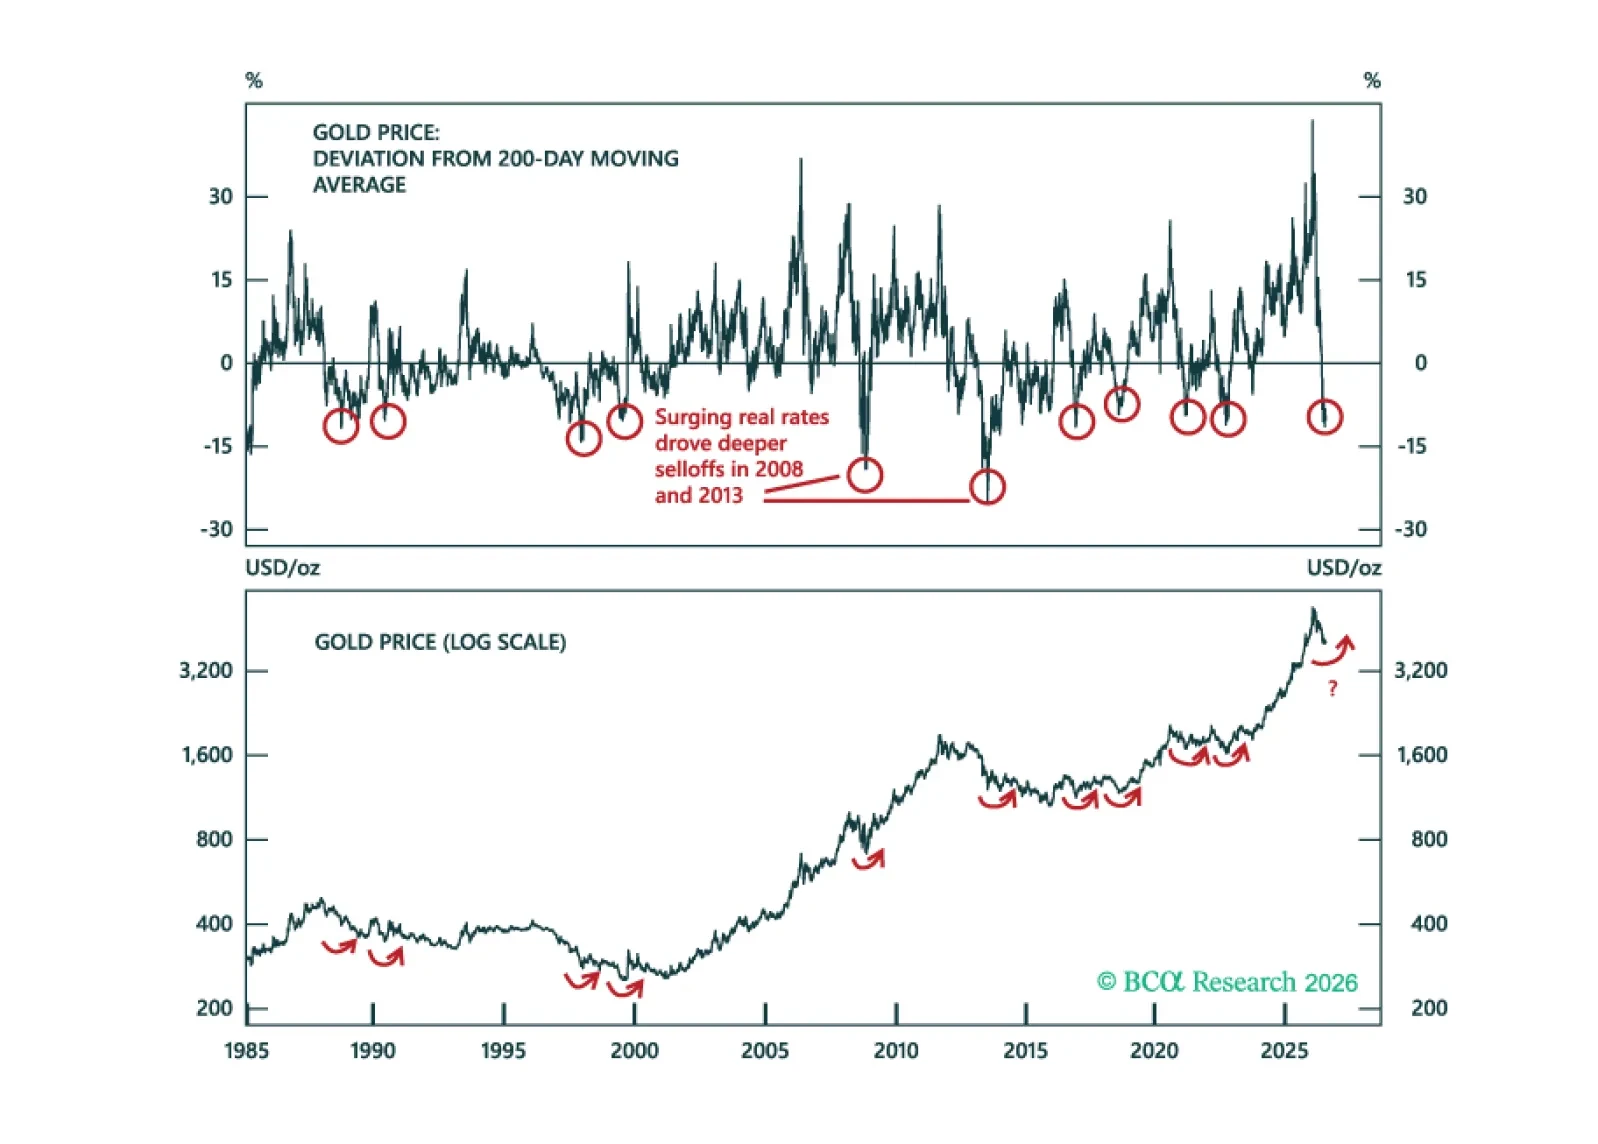
Section I outlines BCA’s views on the US-Iran conflict, Europe’s near-term outlook, the currency and bond selloffs in Japan and the early days of the Warsh Fed. In Section II, Roukaya, Matt, and Artem argue that the worst of gold's downturn is likely behind us. Real rates and the dollar — which have reasserted themselves as gold's primary drivers — are set to shift from headwinds to tailwinds for the metal.
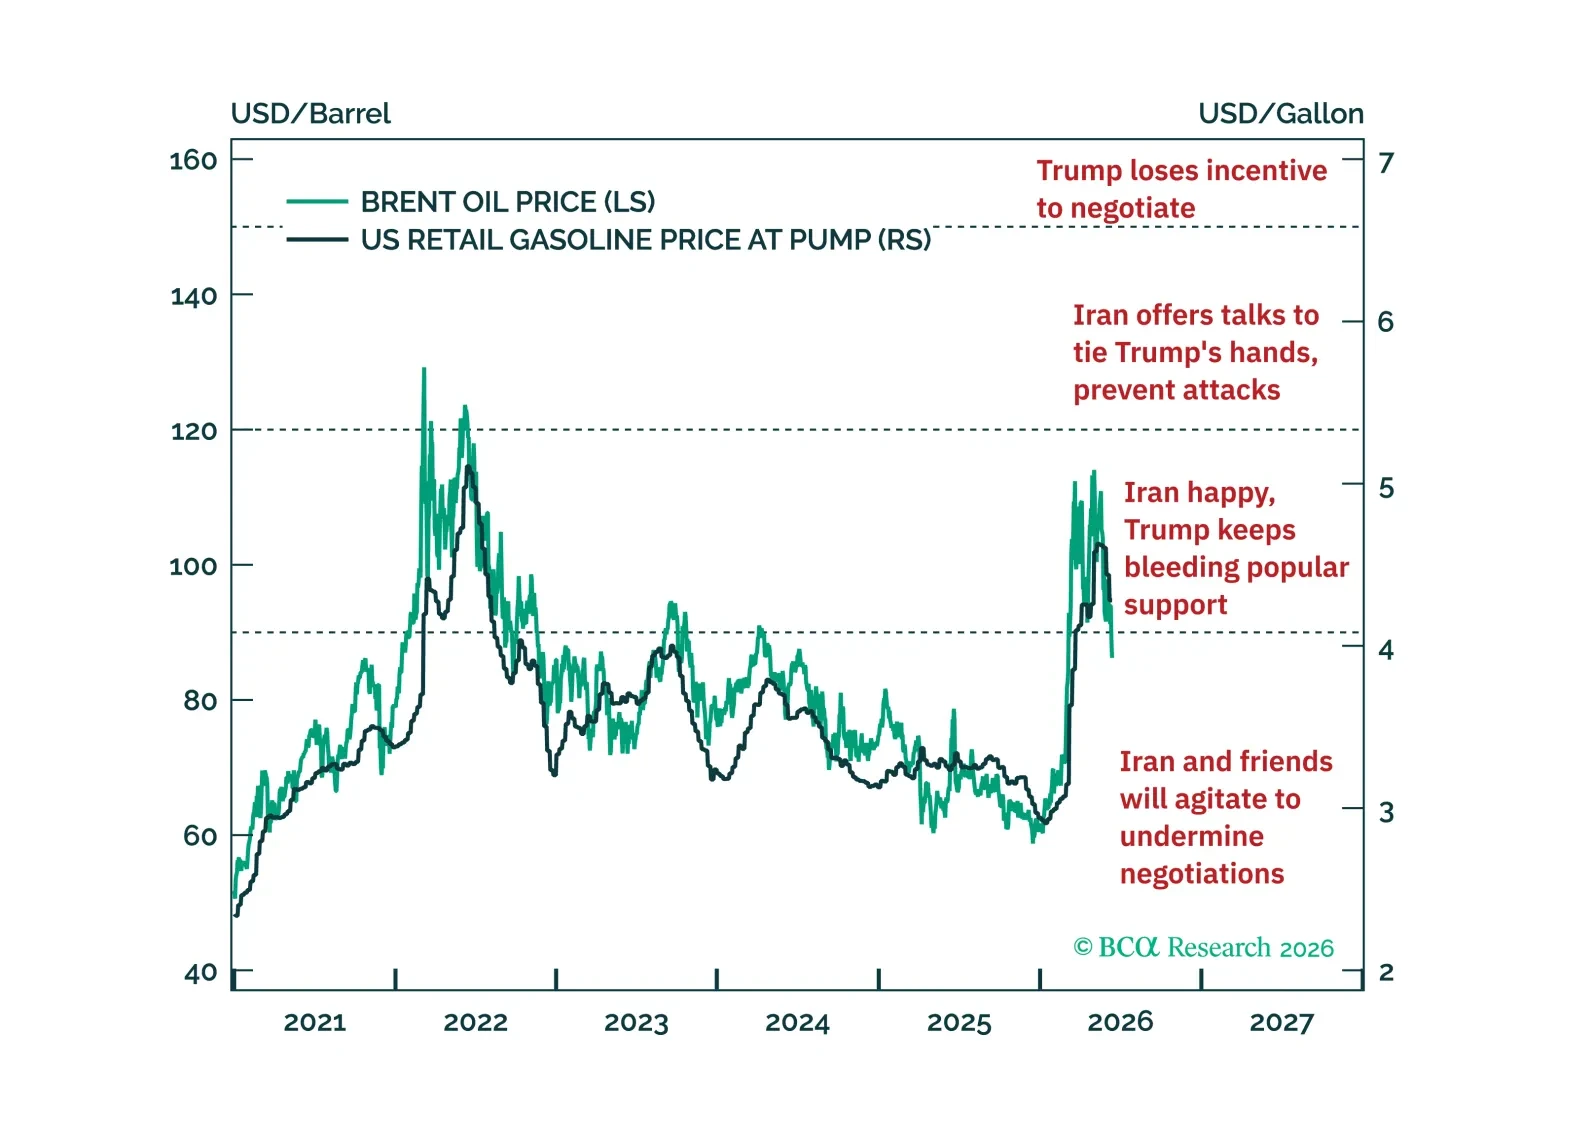
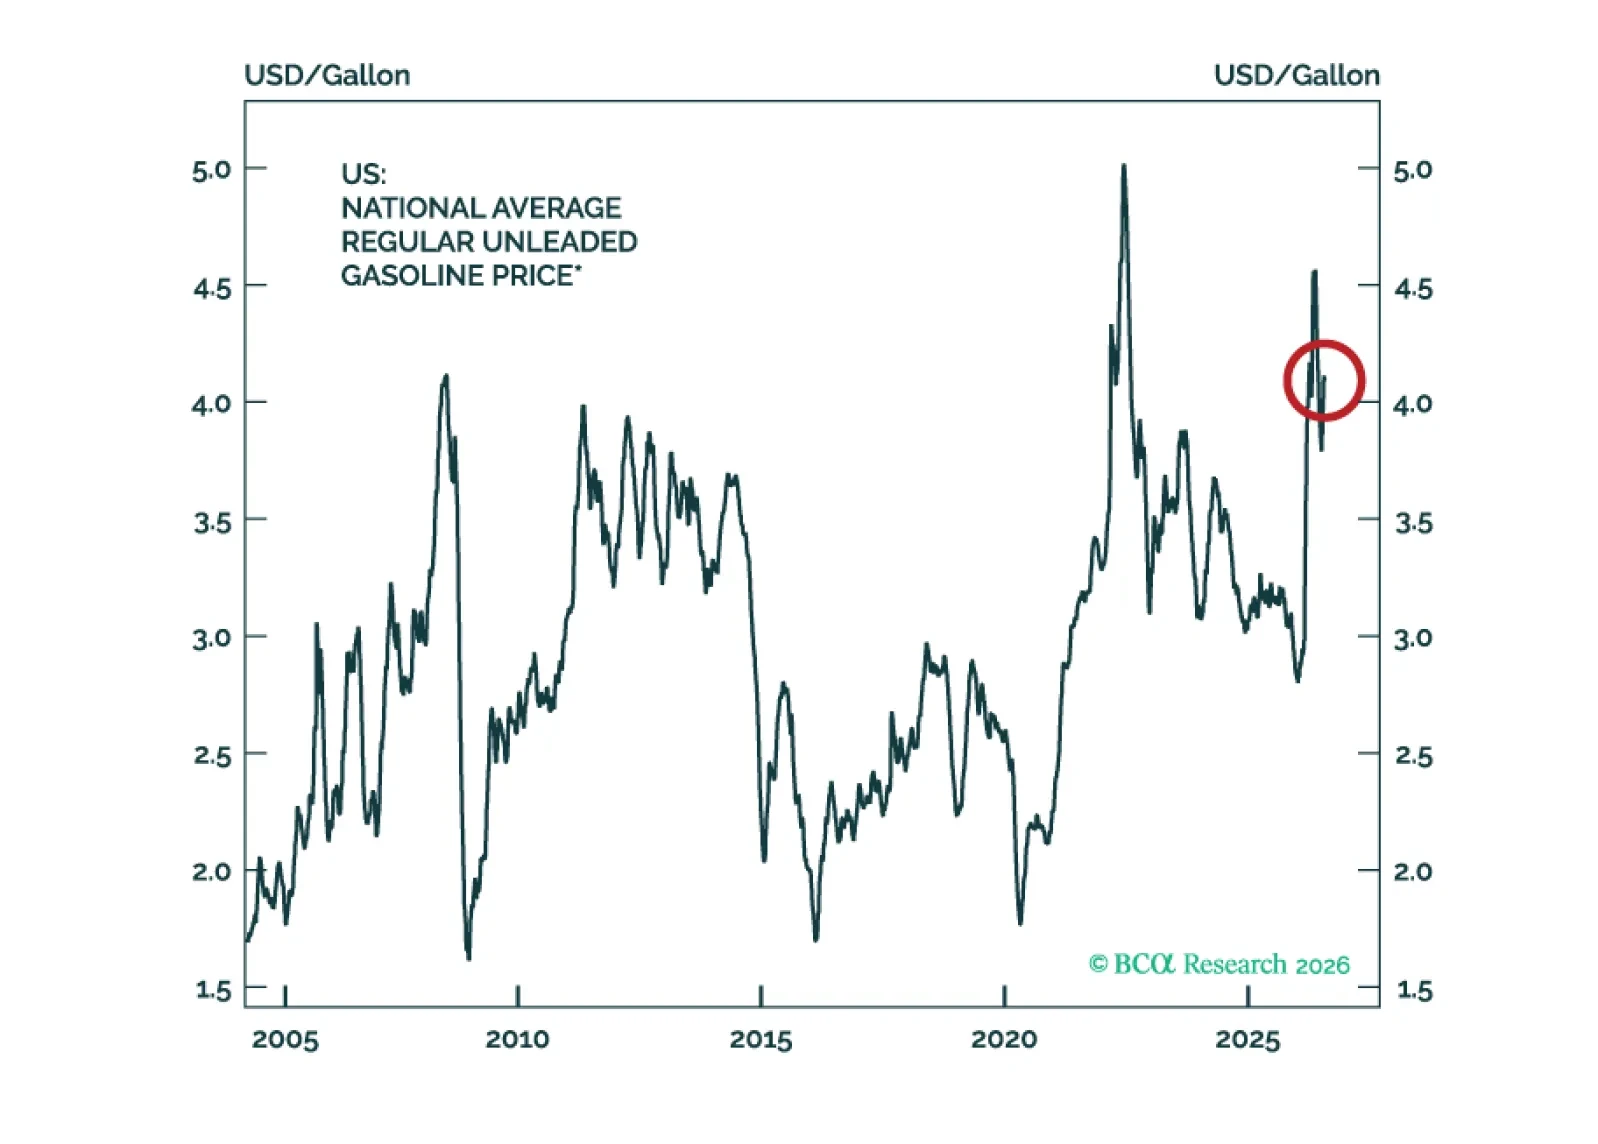
The US-Iran deal is a marginal improvement in global commodity supply risk, but we still give a 60% chance of renewed fighting later this year or in 2027.