CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
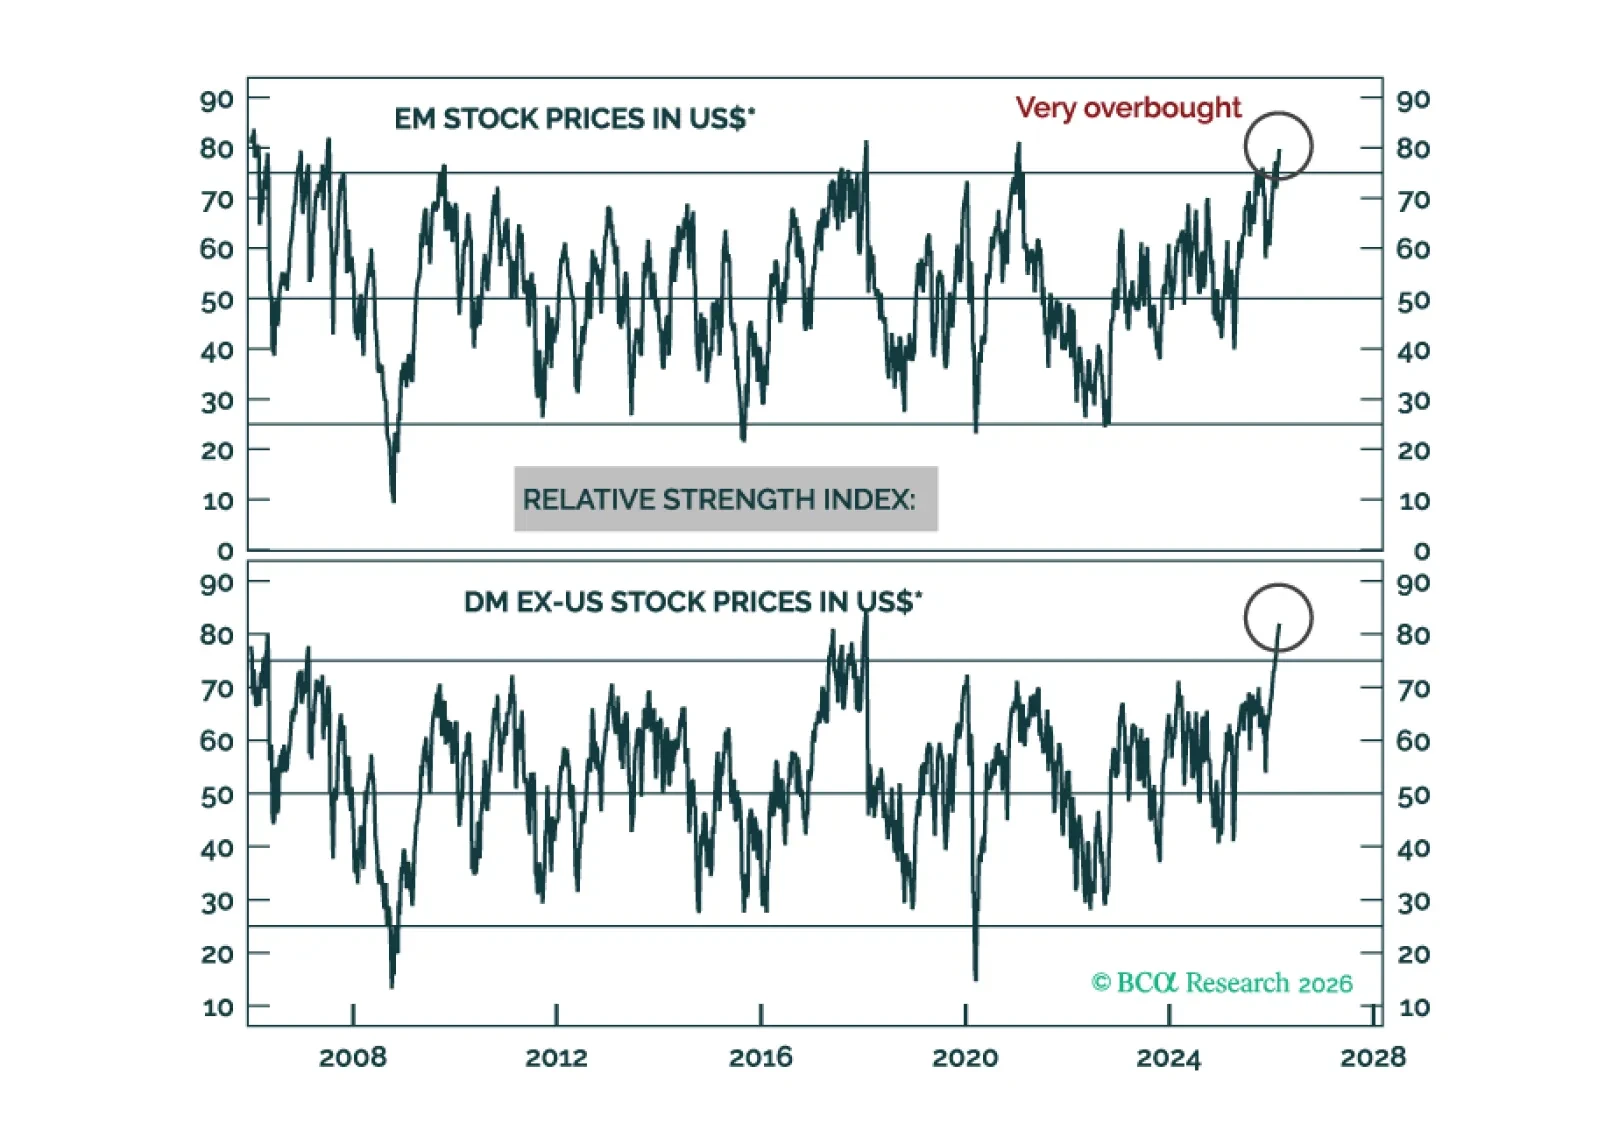
Avoid EM and DM risk assets. In the near term (one-to-three months), the odds favor US equity outperformance and a US dollar rebound. Nevertheless, the cyclical outlook (nine-to-12 months) warrants underweighting US equities and staying short the greenback.
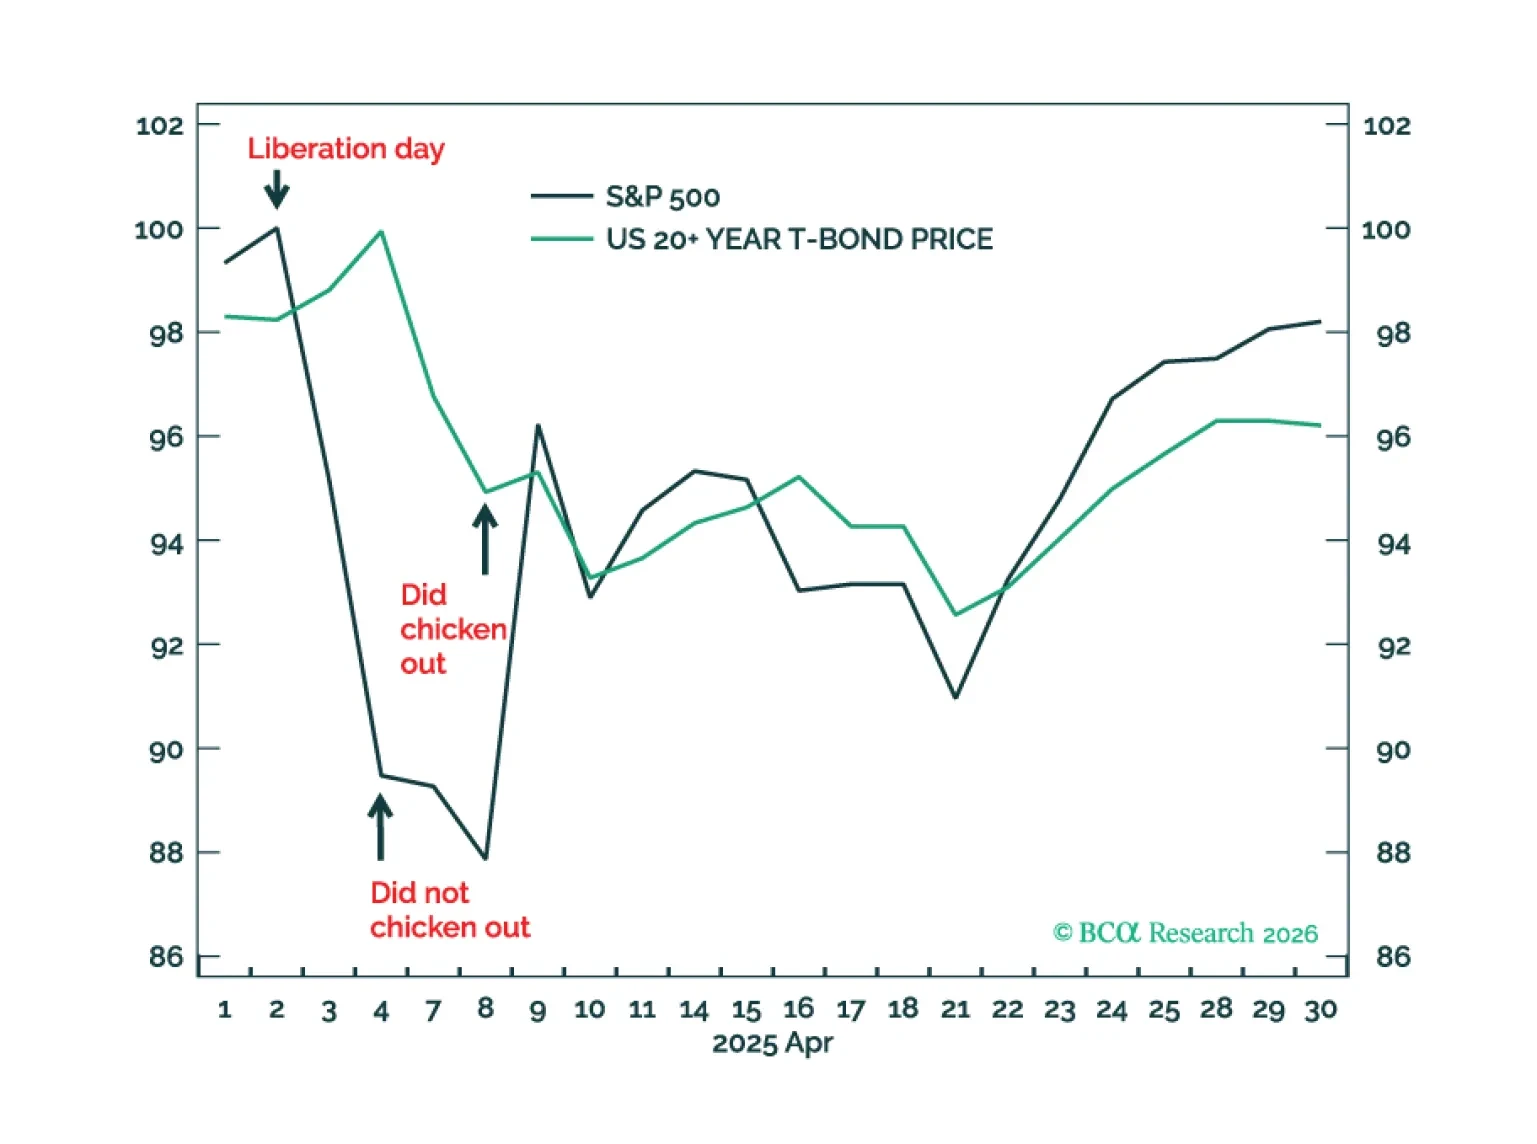
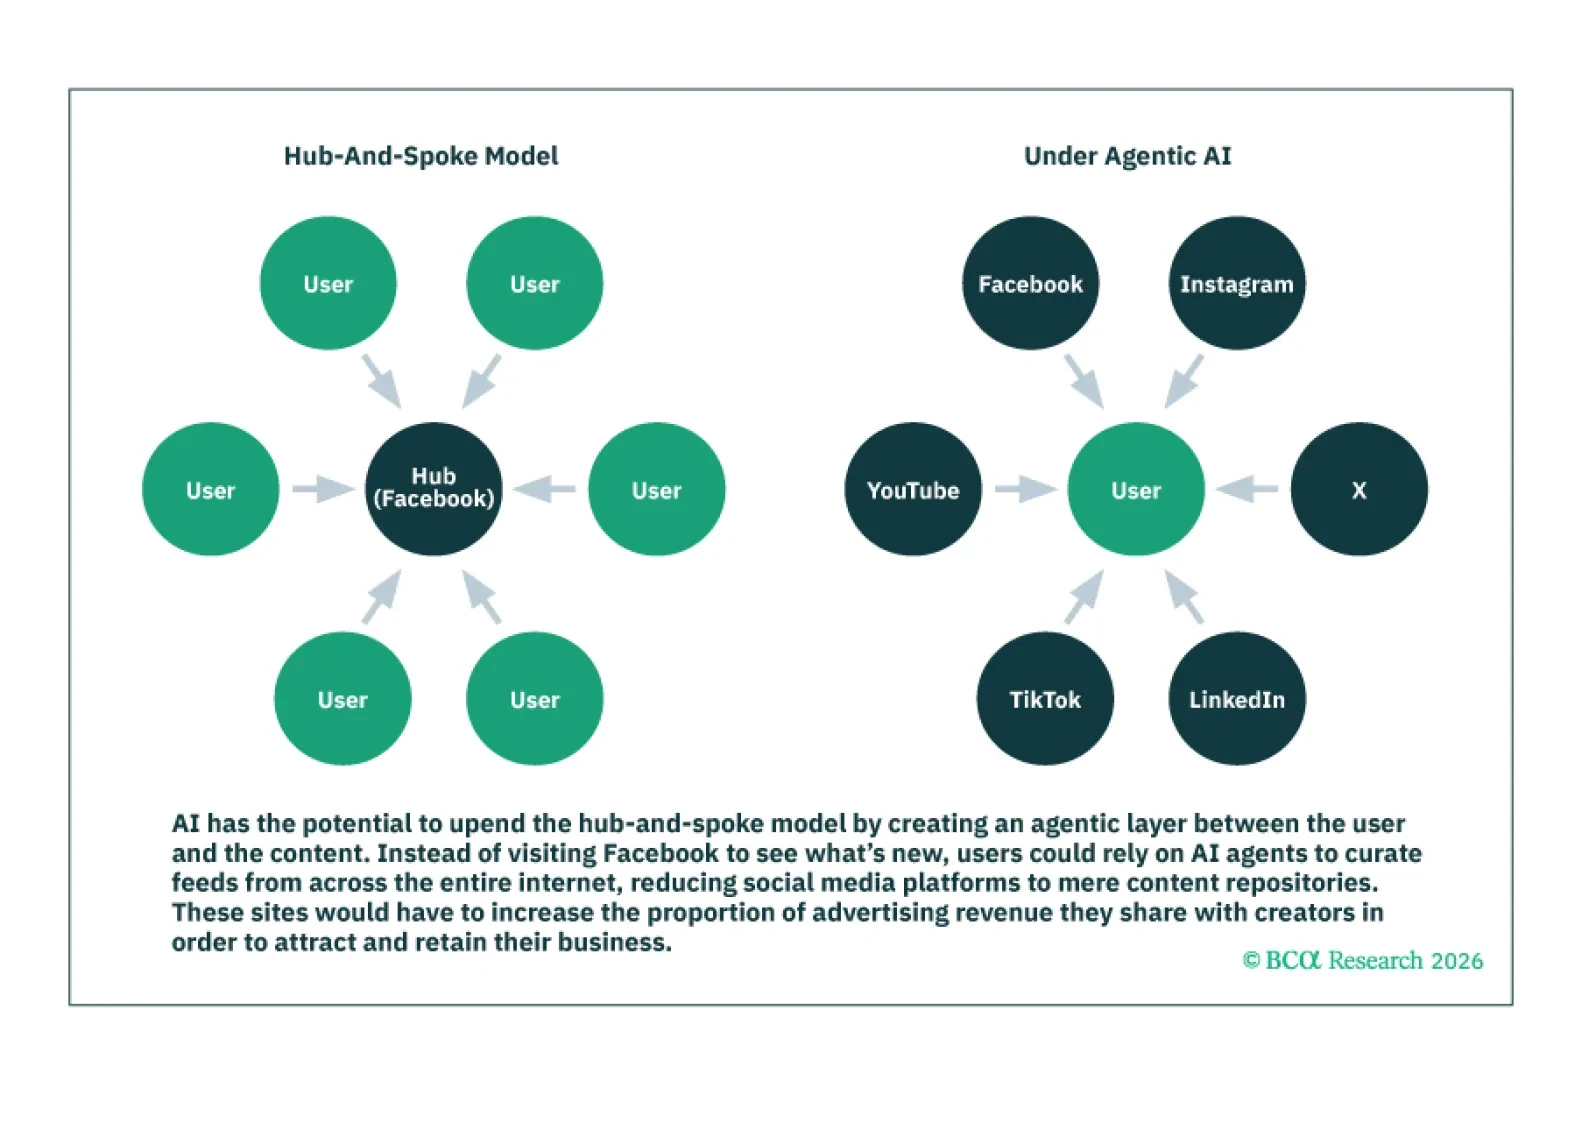
Iran doesn’t need to sink a single US warship; it could inflict much more damage by sinking the US stock and bond markets by disrupting shipping, trade, and oil tankers with decentralised low-tech drone warfare. We discuss why it is not the direct pain of higher oil prices, but the knock-on repercussions for stock and bond markets that could inflict the greater damage. Plus, a new tactical trade is to underweight Materials.
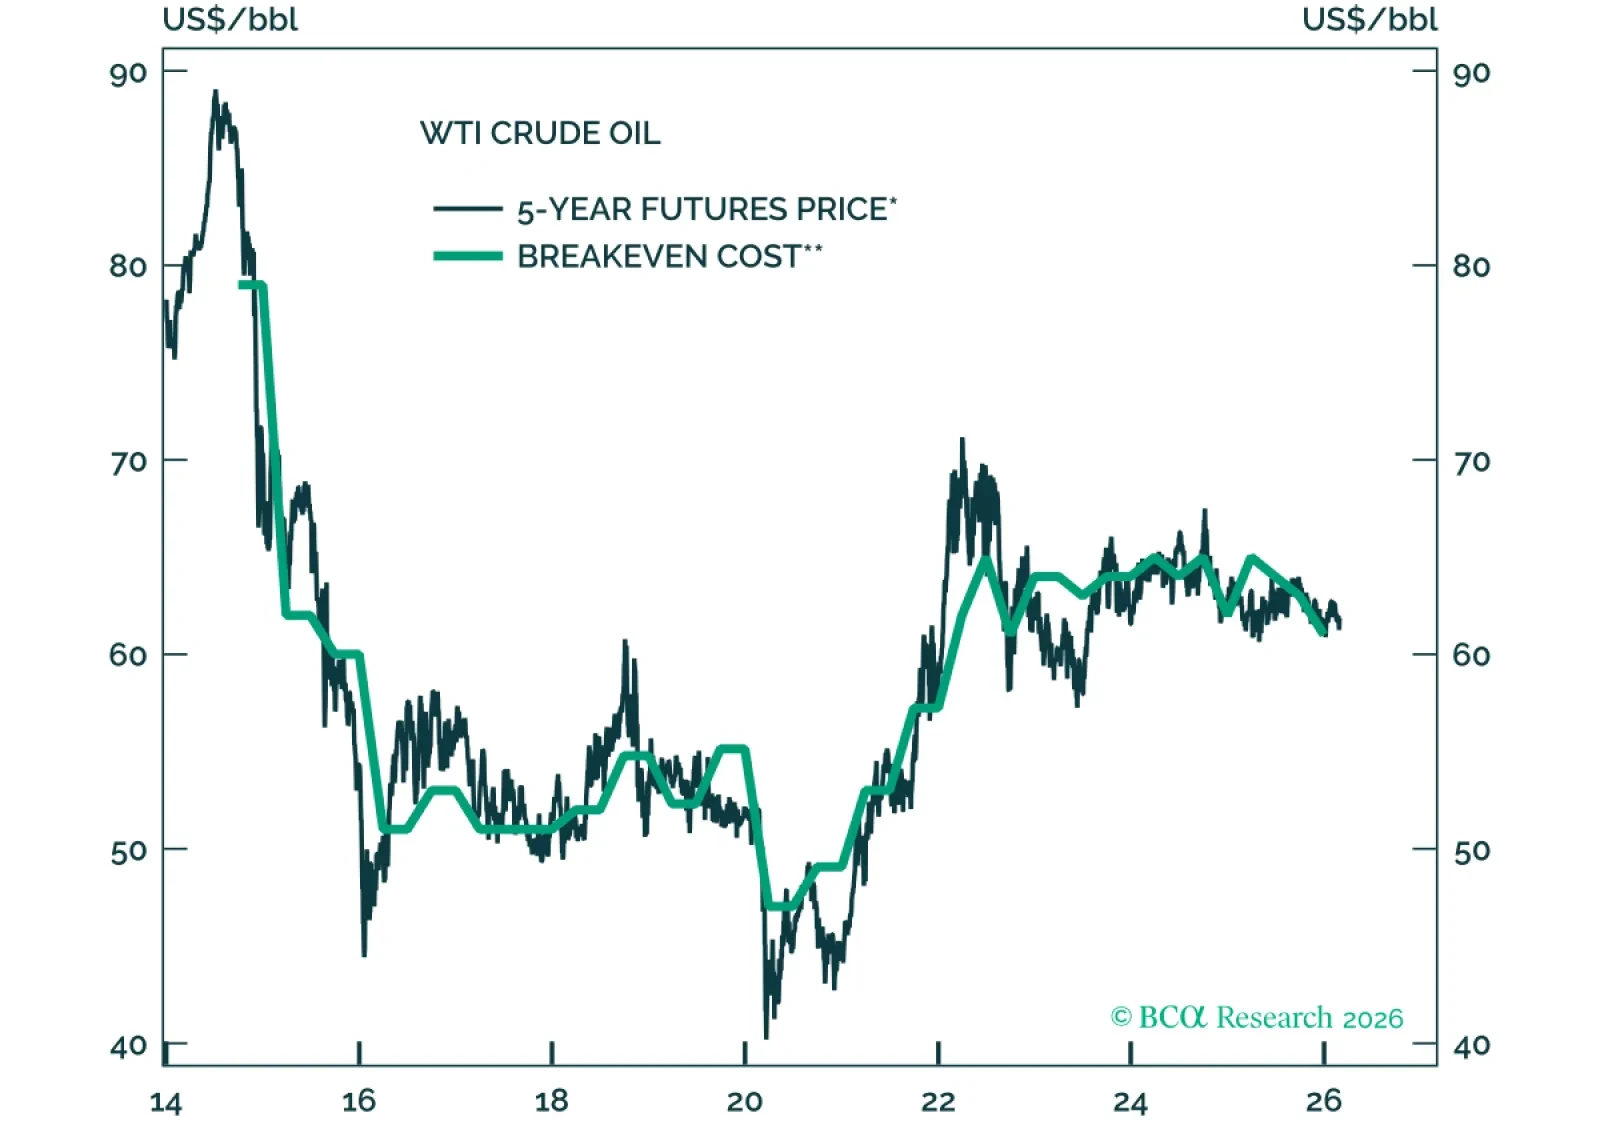
Since 1970, every US recession excluding the pandemic downturn was preceded by a sharp rise in oil prices. As I write this, WTI is trading at $71/bbl, up 24% year-to-date and up 19% relative to the Q4 2025 average. That said, today’s oil price is still only 8% higher than the average for all of 2025. If oil prices stay broadly where they are, the impact on the US economy should be limited.

India is seeing net capital outflows for the first time in a generation. The central bank is selling foreign reserves to defend the rupee, which is draining banking system liquidity. The latter risks derailing the nascent credit revival. Indian stock prices remain vulnerable.
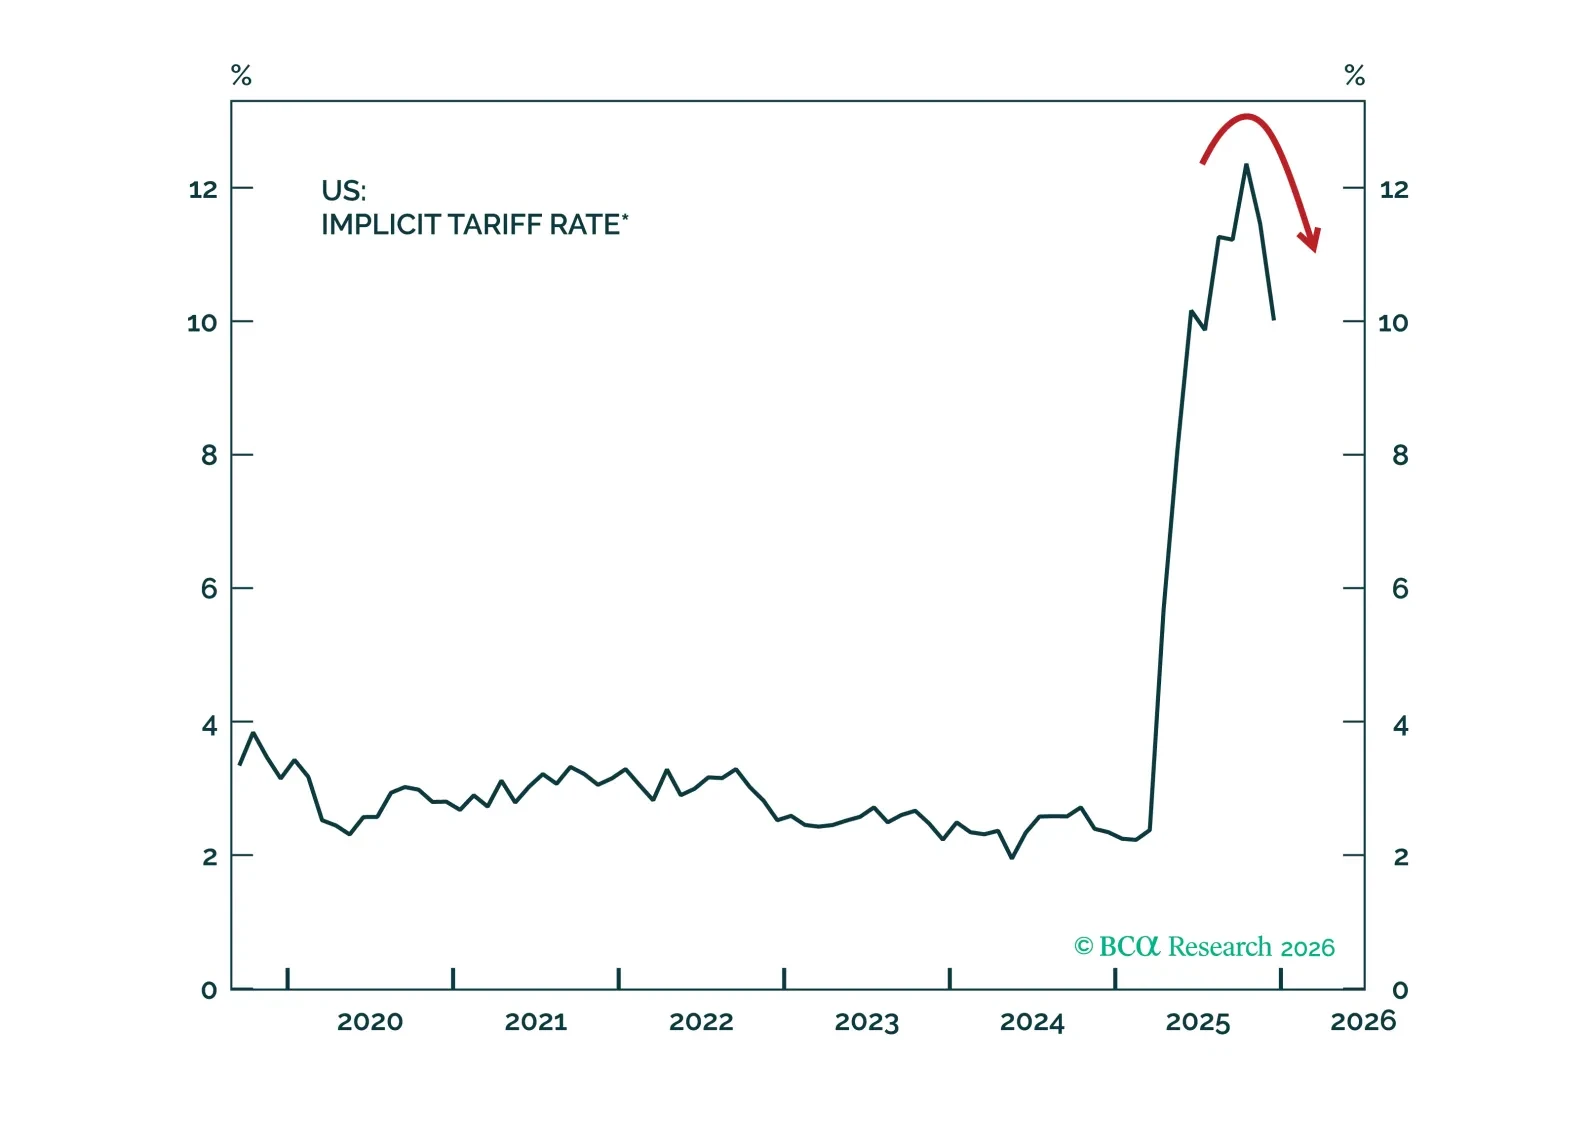
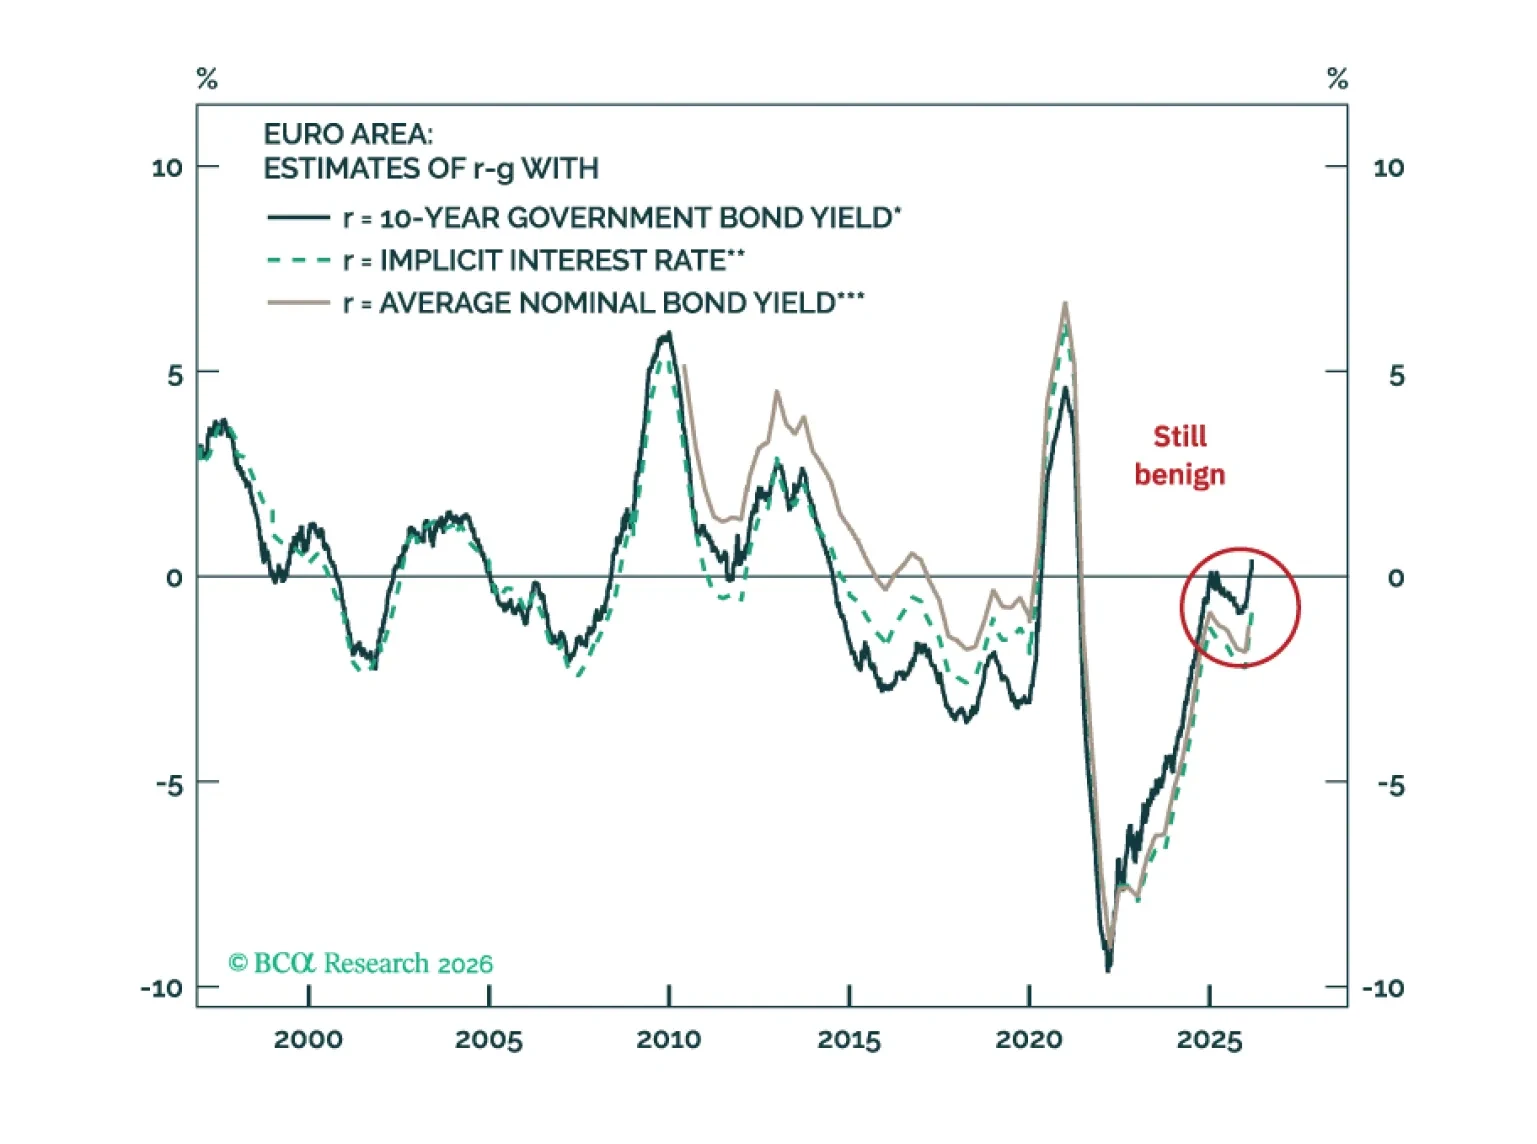
The Section 122 tariffs under the US Trade Act of 1974 are more favorable to Europe; the trade-weighted tariff rate falls to 10.45%, from 11.74% pre-ruling. This positive development does not change our overall views on Europe, as we expected lower tariffs ahead of the US midterms.
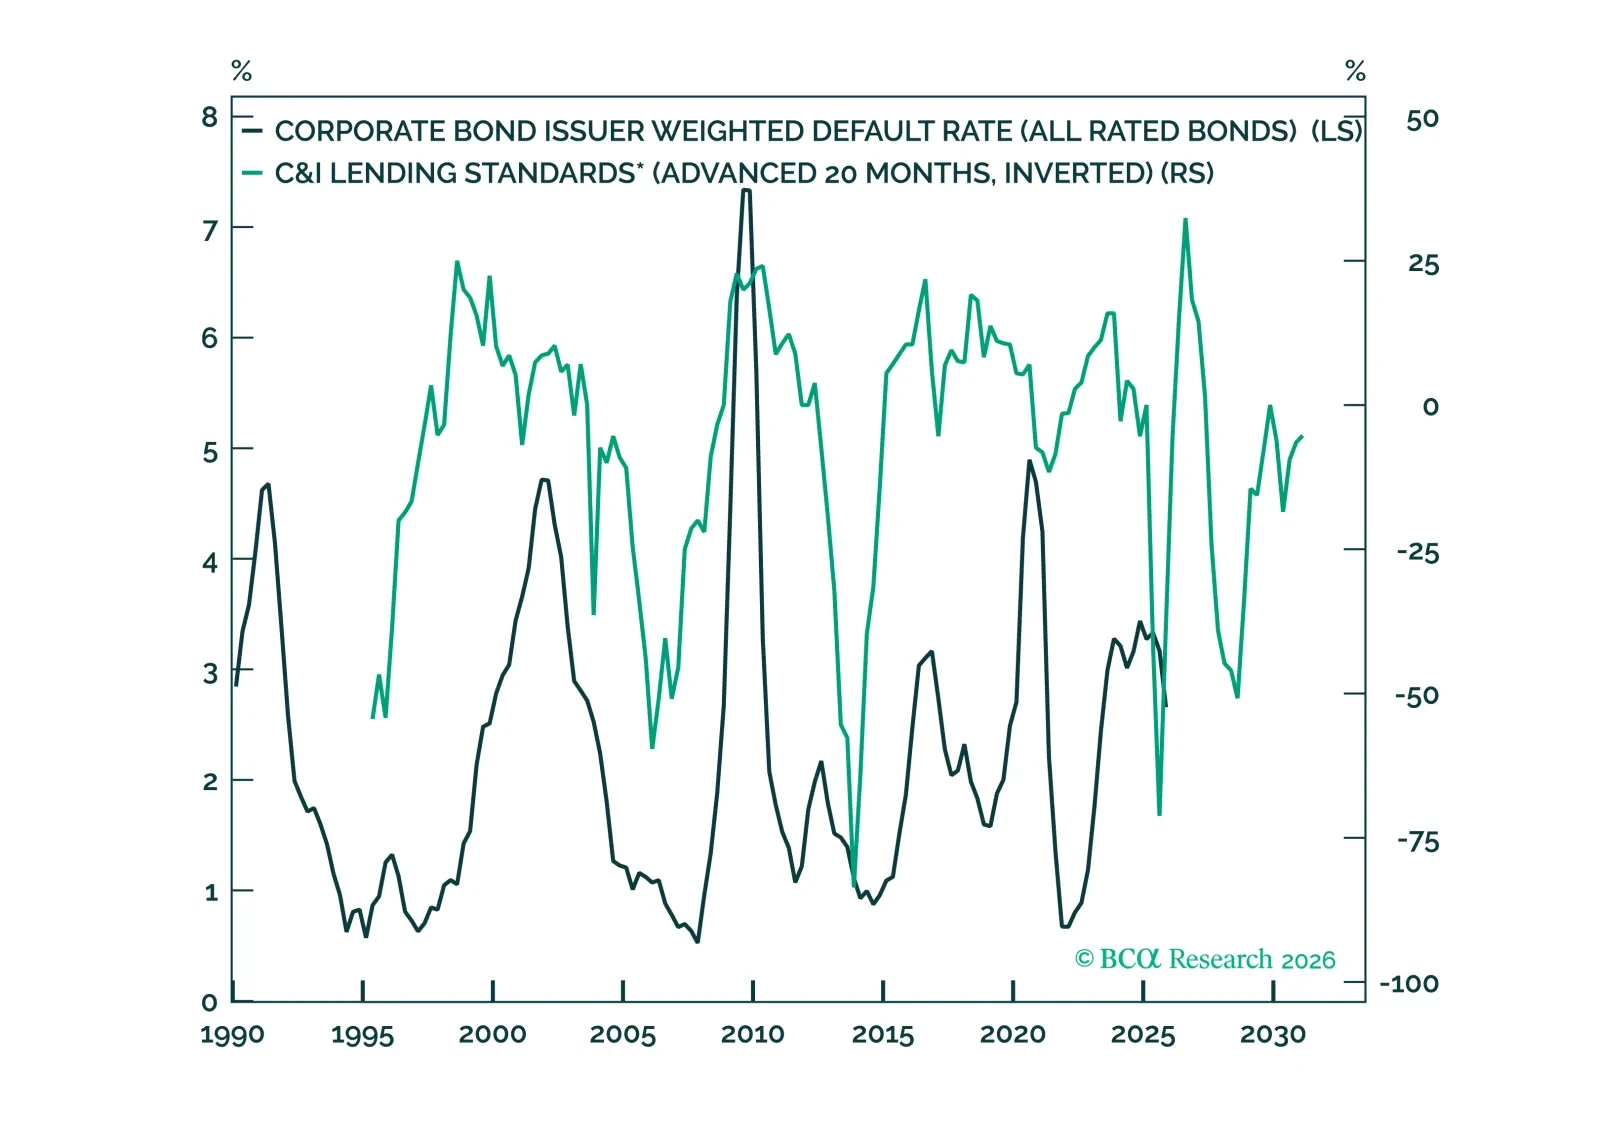
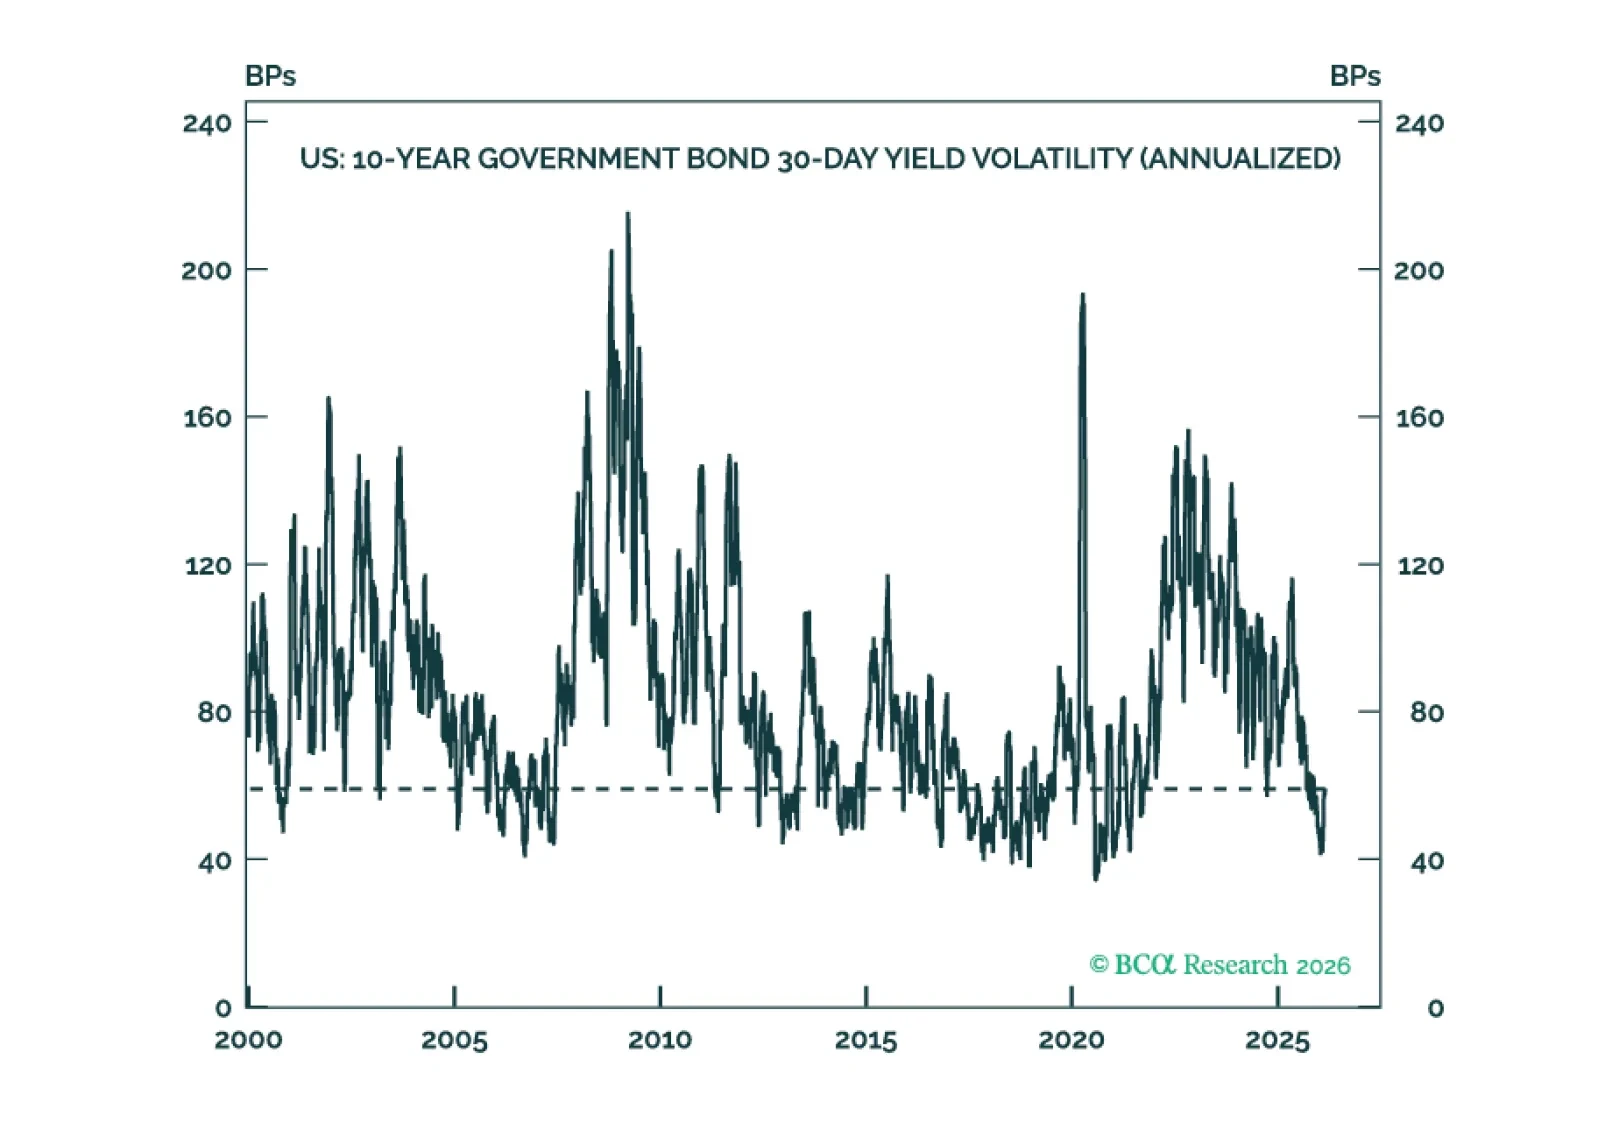
The turmoil in private credit is a wild card, but our traditional suite of credit cycle indicators does not point to an imminent spread-widening episode. We reiterate our benchmark weightings on Treasuries, investment-grade and high-yield corporate bonds.
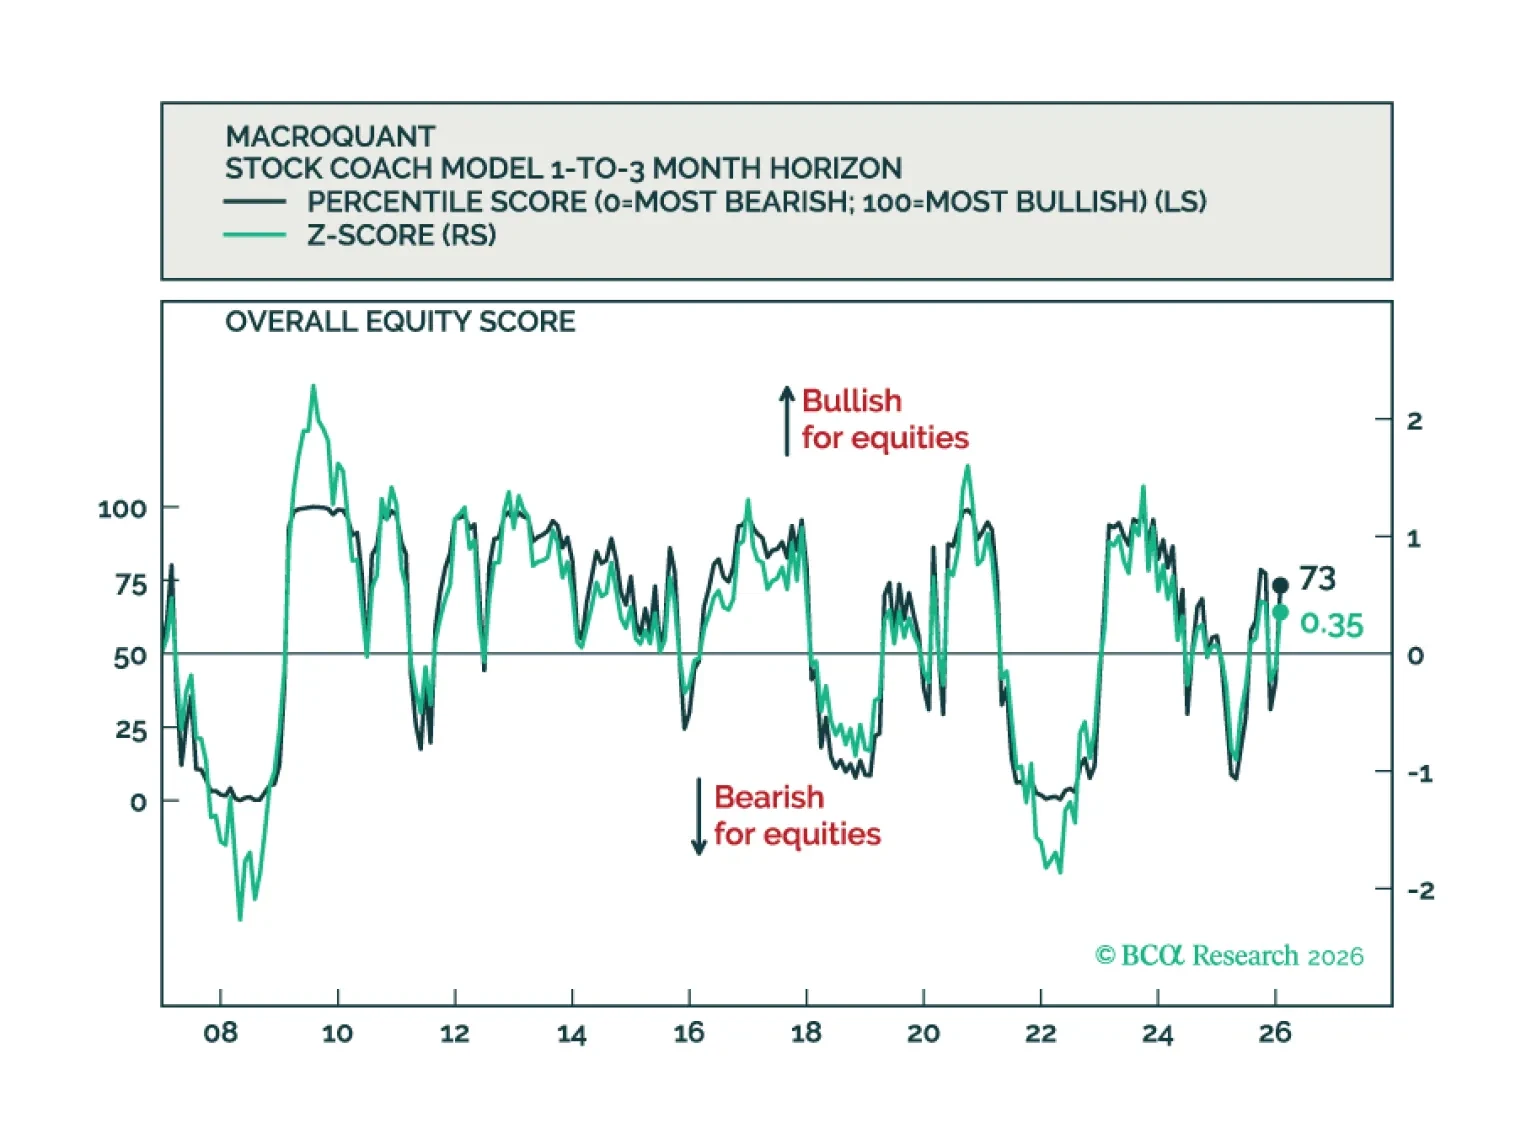
MacroQuant recommends a modest overweight position in equities, favors an above-benchmark duration stance in fixed-income portfolios, remains bearish on the US dollar, has downgraded oil to neutral, and is bullish on copper and gold.