Skip to main content
Explore CoreMacro

CoreMacro | Global

Macro research covering the global economy and markets, investment implications. Typically published four times a month.
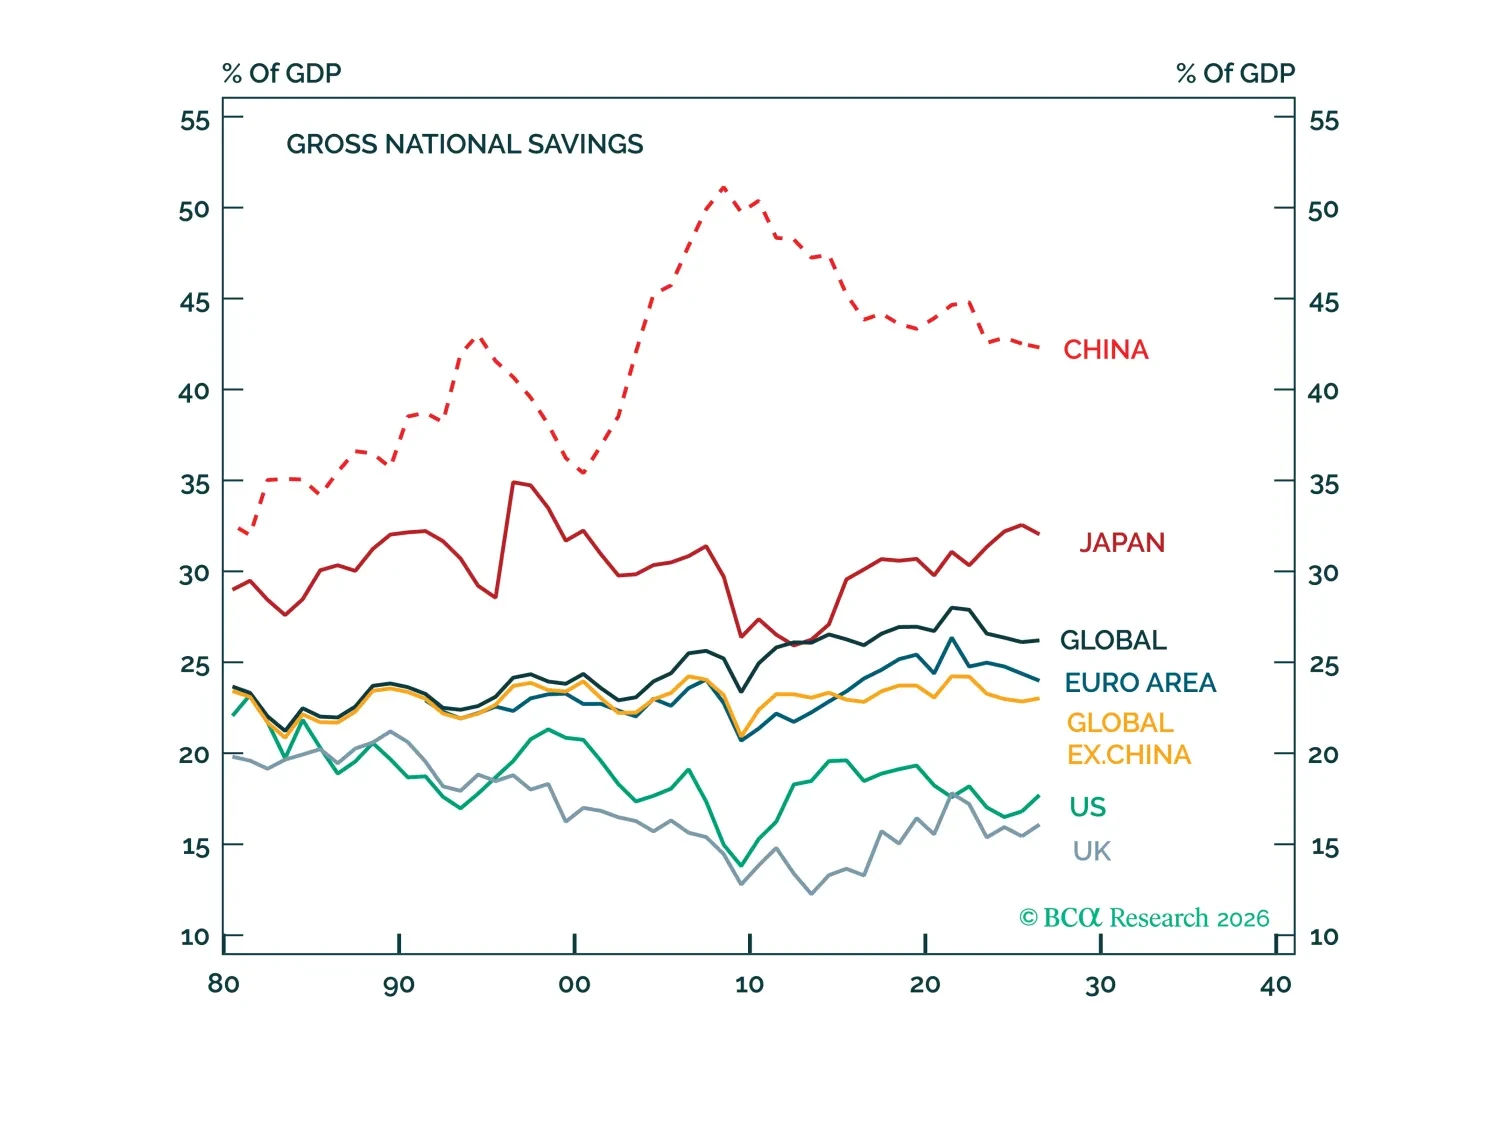
Special Report China does not produce too much. It spends too little. The only viable way for China to reduce investment without raising unemployment is by lowering national savings. Doing so is likely to be politically challenging, however. This suggests that China will suffer from subpar growth and deflationary pressures for the foreseeable future.
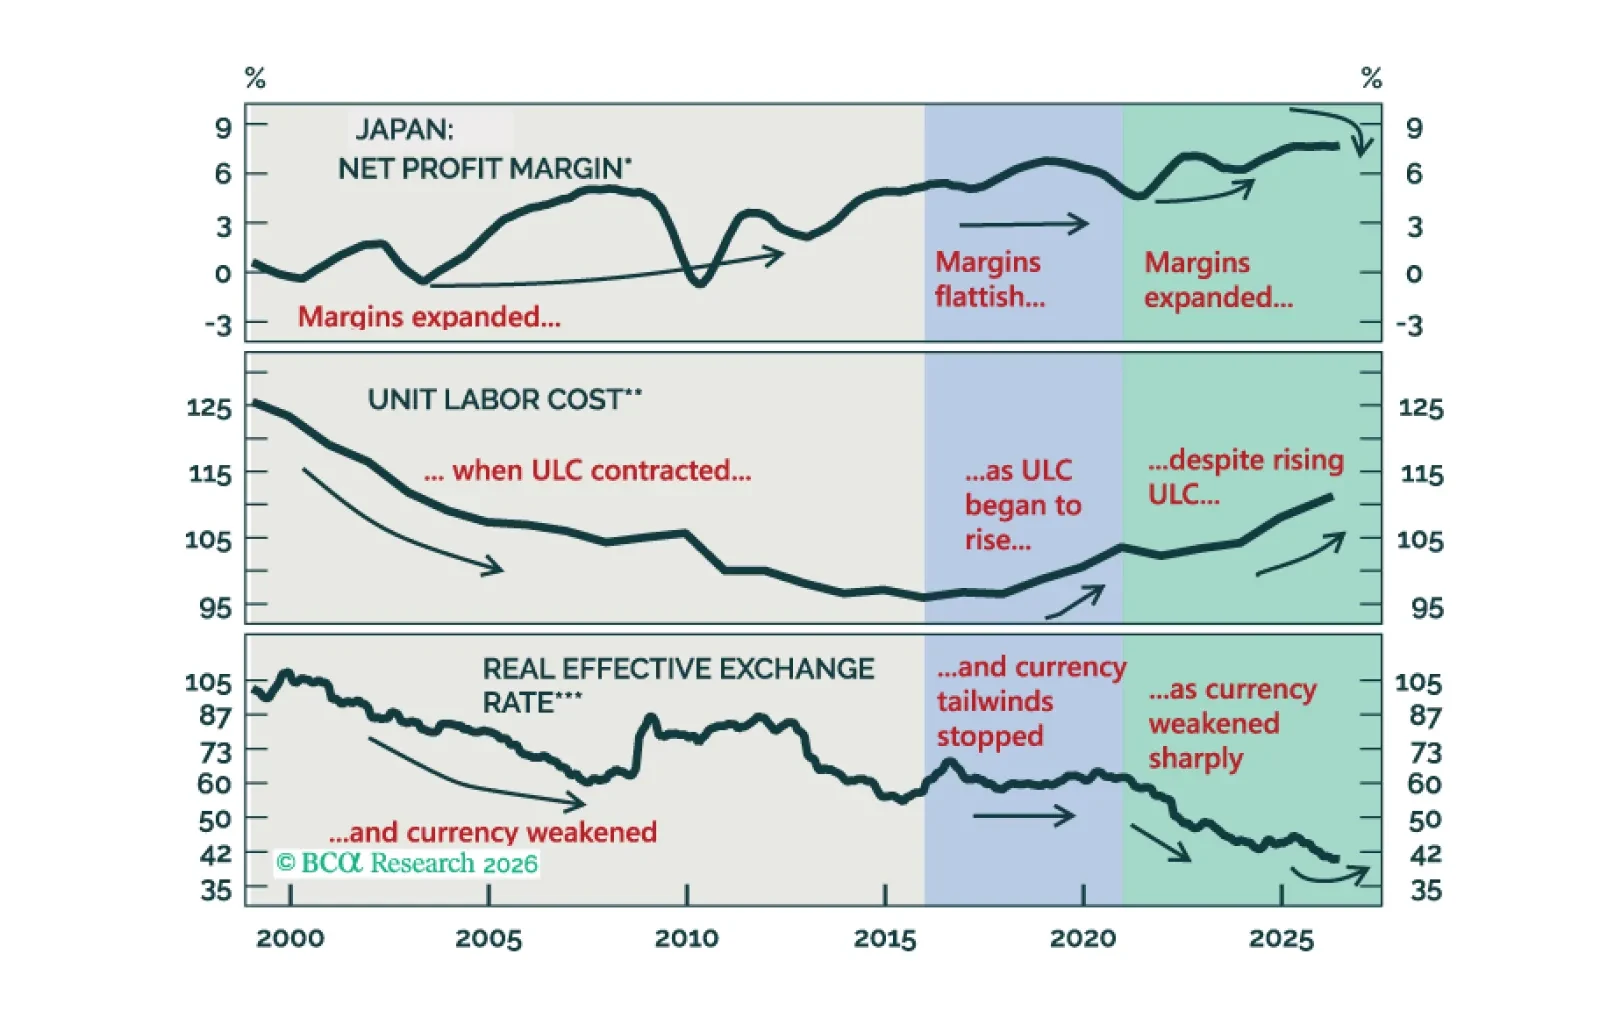
Special Report Over the past 10 years, Japan’s profit margin expansion has been driven neither by advances in labor productivity nor by operational efficiency gains, but by massive currency devaluation and lower depreciation charges. Going forward, higher wages and unit labor costs, as well as currency appreciation, will become major headwinds to margins.
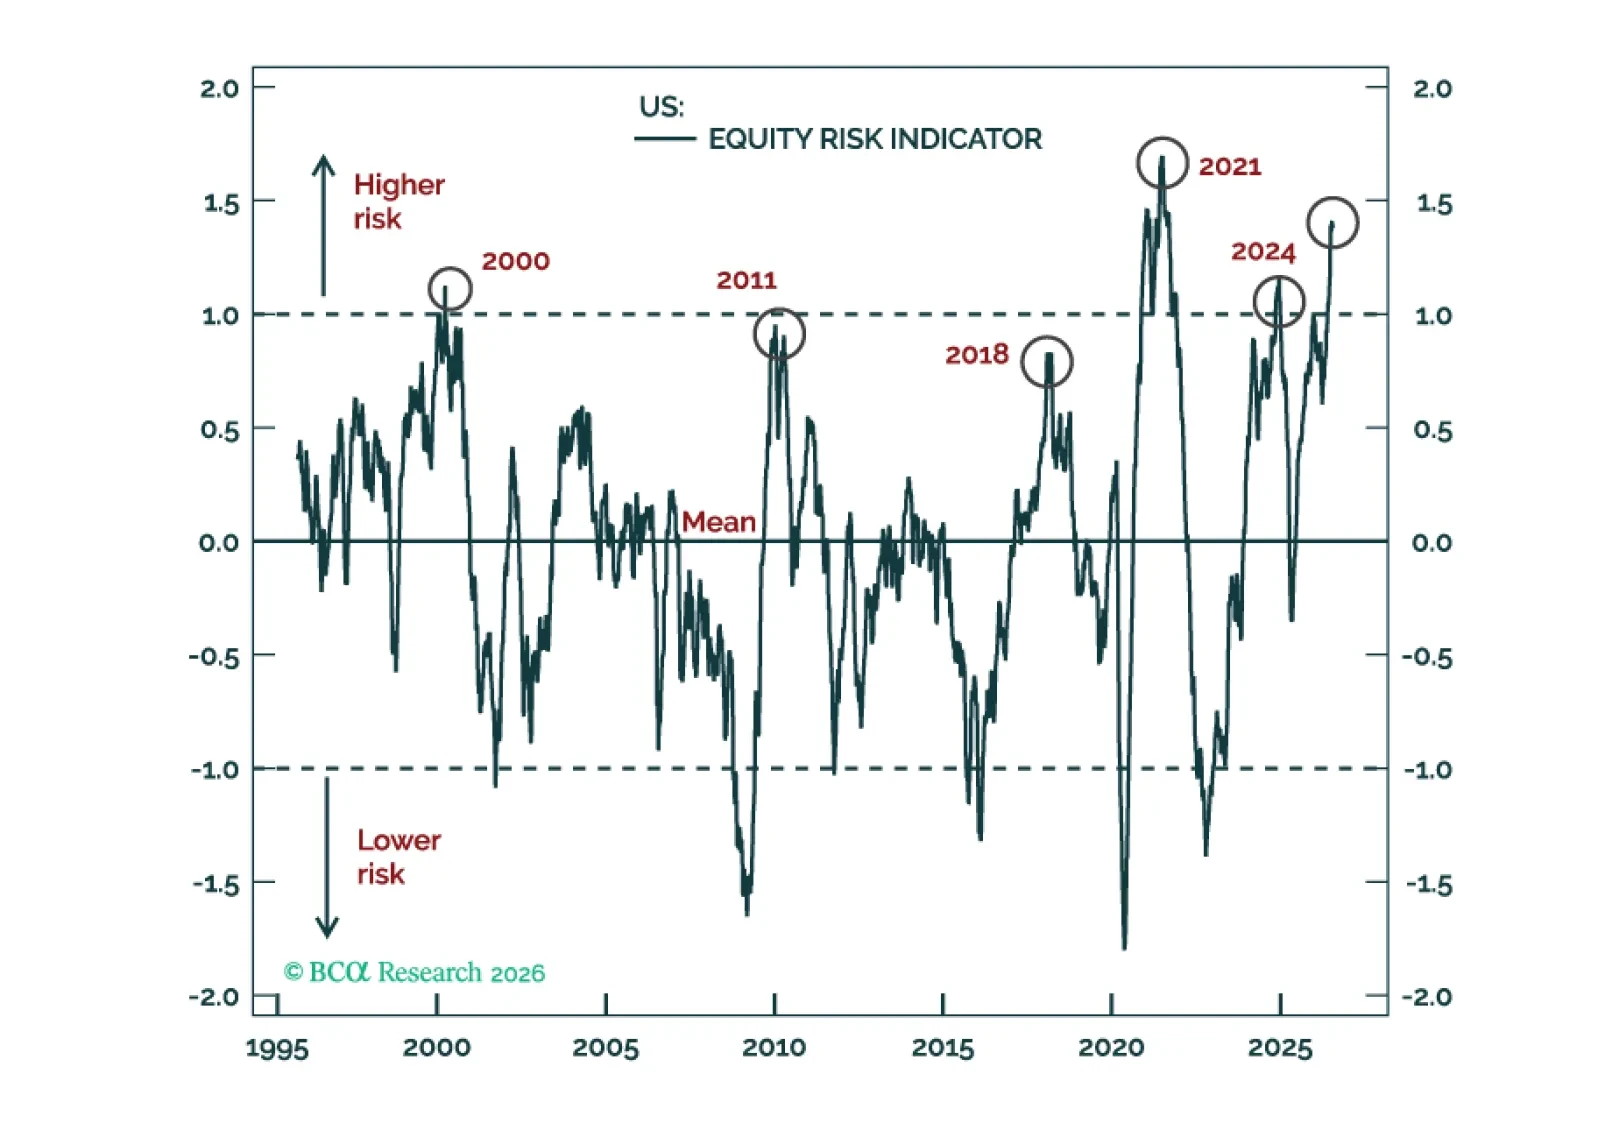
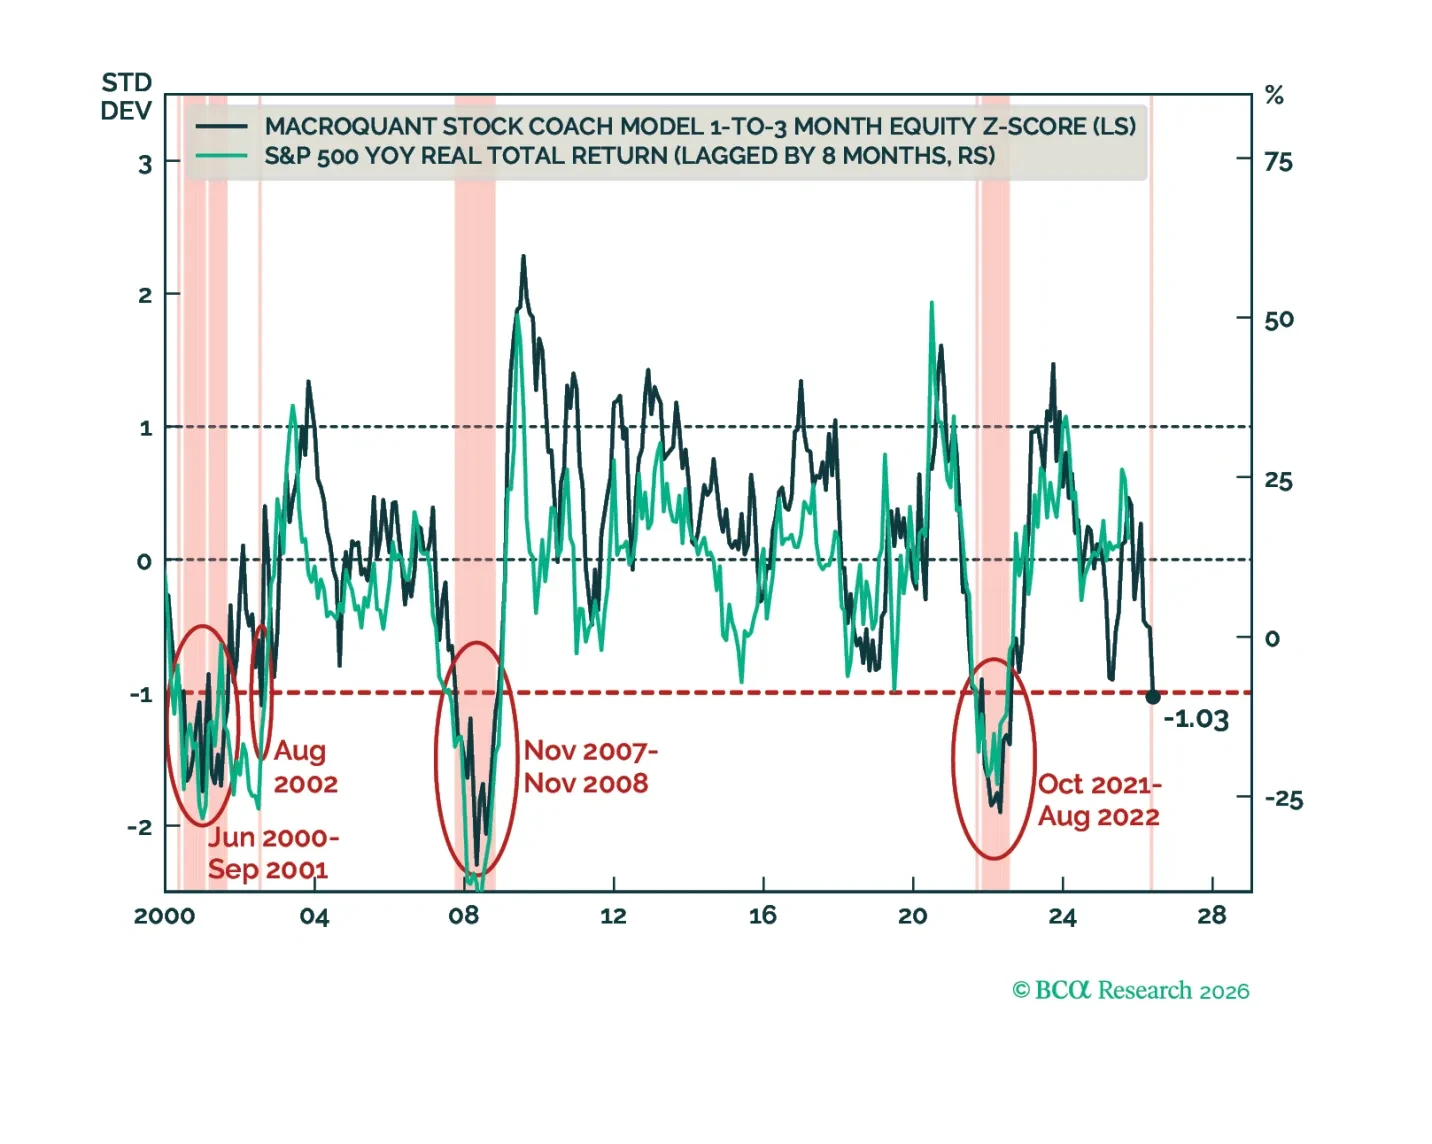
Global equities have reached extremes on multiple measures, none of which are reliable timing tools. But imbalances in economics and investing can build for far longer than rational analysis would predict - and usually unravel much faster than investors expect.
As long as the AI boom keeps booming, all other investment considerations will remain on the back burner. However, if the AI trade fizzles, this would expose deep-seated problems within the global economy, which could very well lead to an economic downturn as early as next year.
Special Report BCA's bull/bear debate webcast, held on July 13, 2026 (replay here) and moderated by Chief Investment Strategist Marko Papic, pitted Peter Berezin and Arthur Budaghyan on the bearish side against Juan Correa and Noah Weisberger on the bullish side. This edited summary condenses, reorganizes by theme, and lightly paraphrases their remarks.
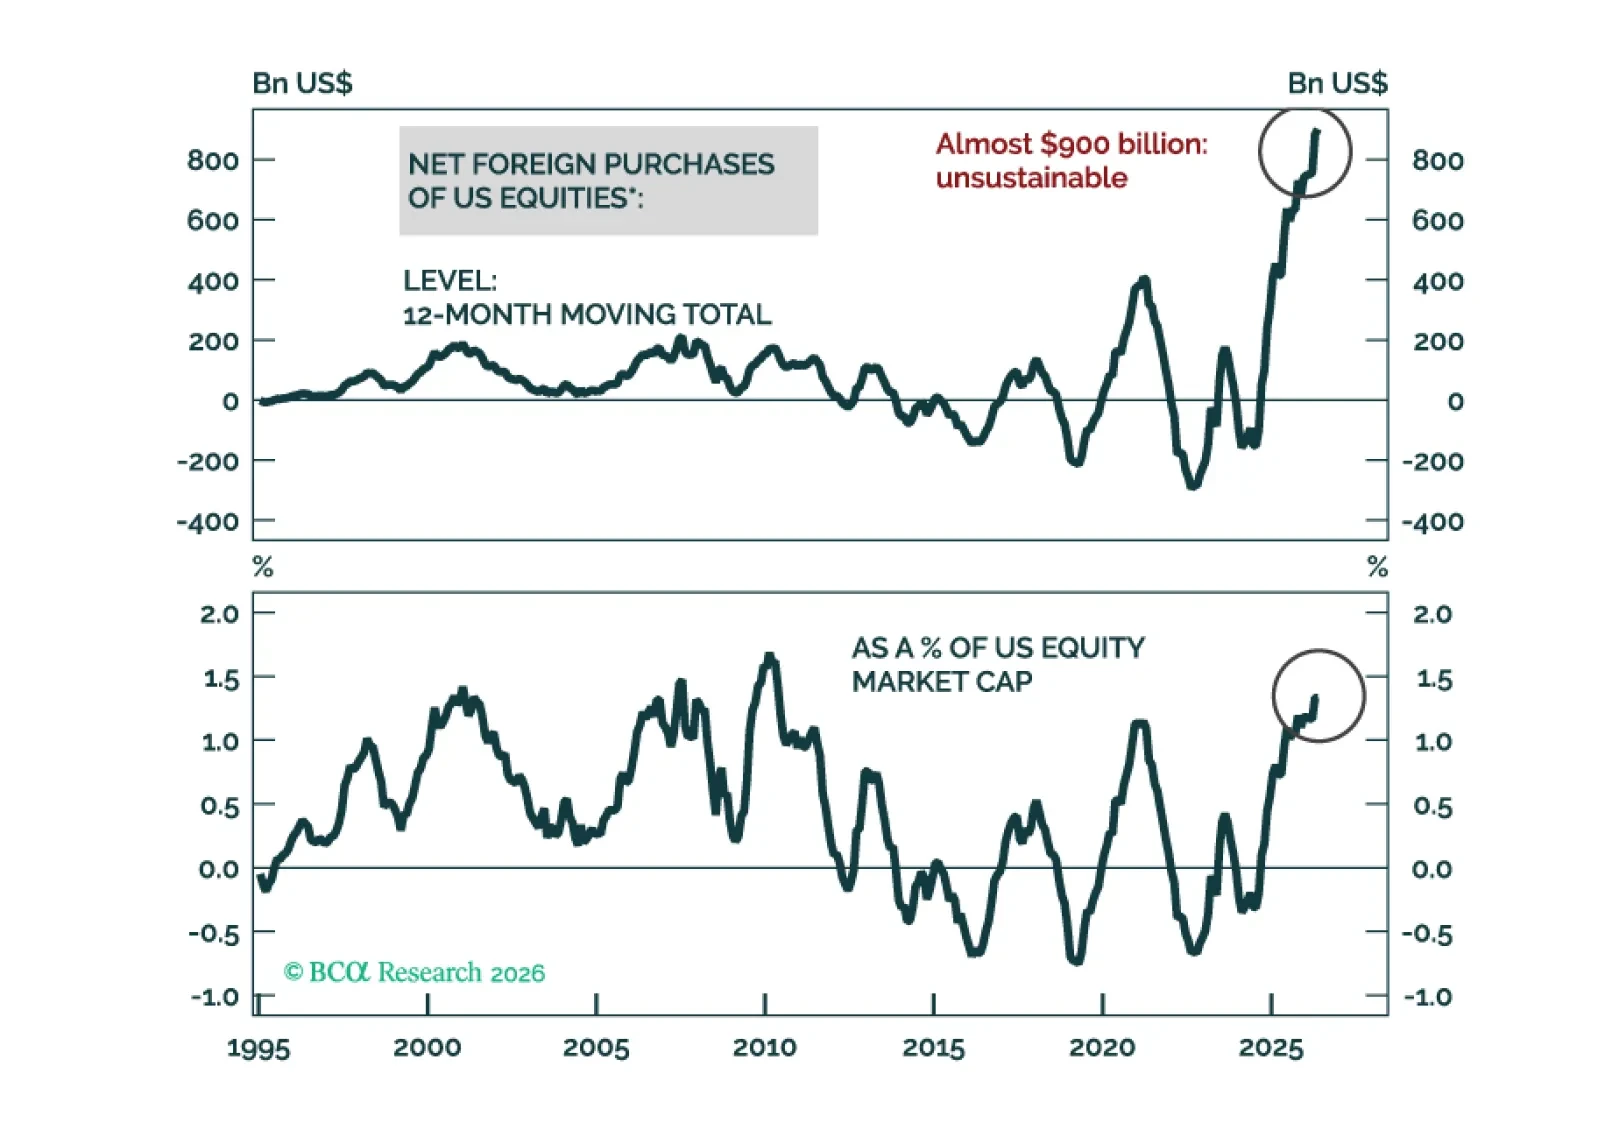
Special Report The US dollar will become a pro-cyclical currency going forward. This regime shift would upend financial market correlations, and most investment portfolios are not positioned for it. A great deal of money is made or lost during regime changes - and one is coming soon. That is why our message remains loud and clear: Get Out of the Dollar (G.O.D.).
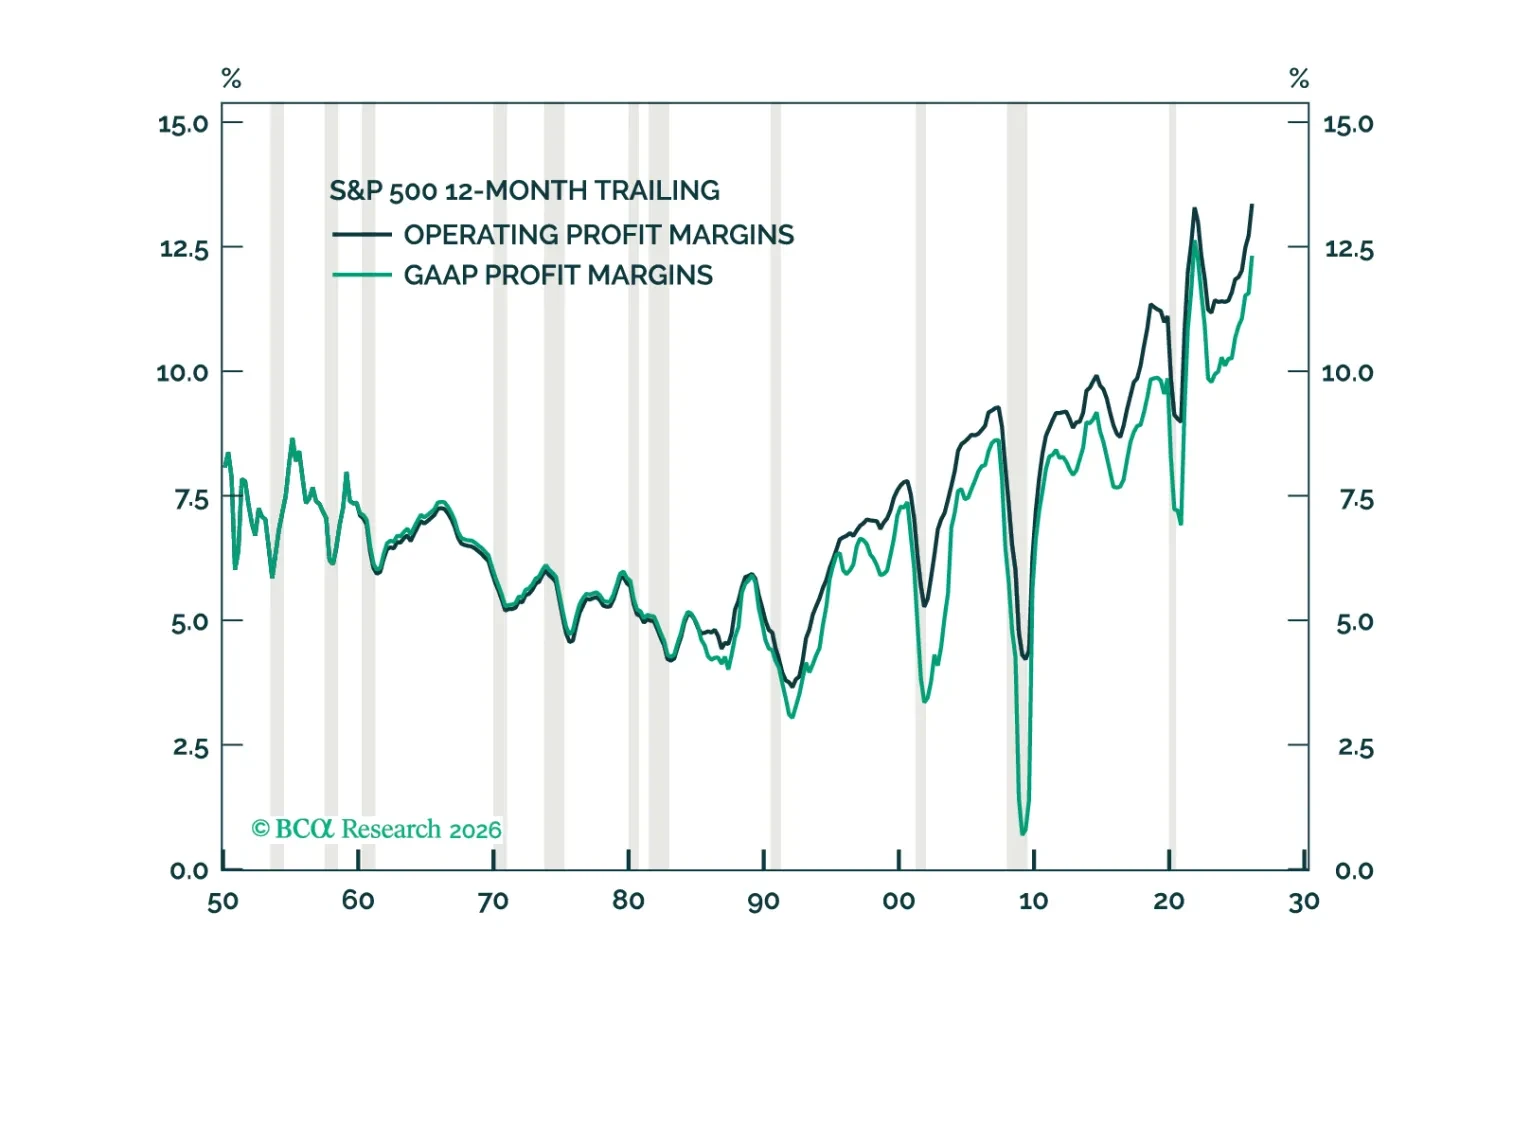
Special Report The Goldilocks environment for US profit margins should start to sour next year. Contrary to conventional wisdom, AI could end up eroding margins for both producers and consumers of artificial intelligence.
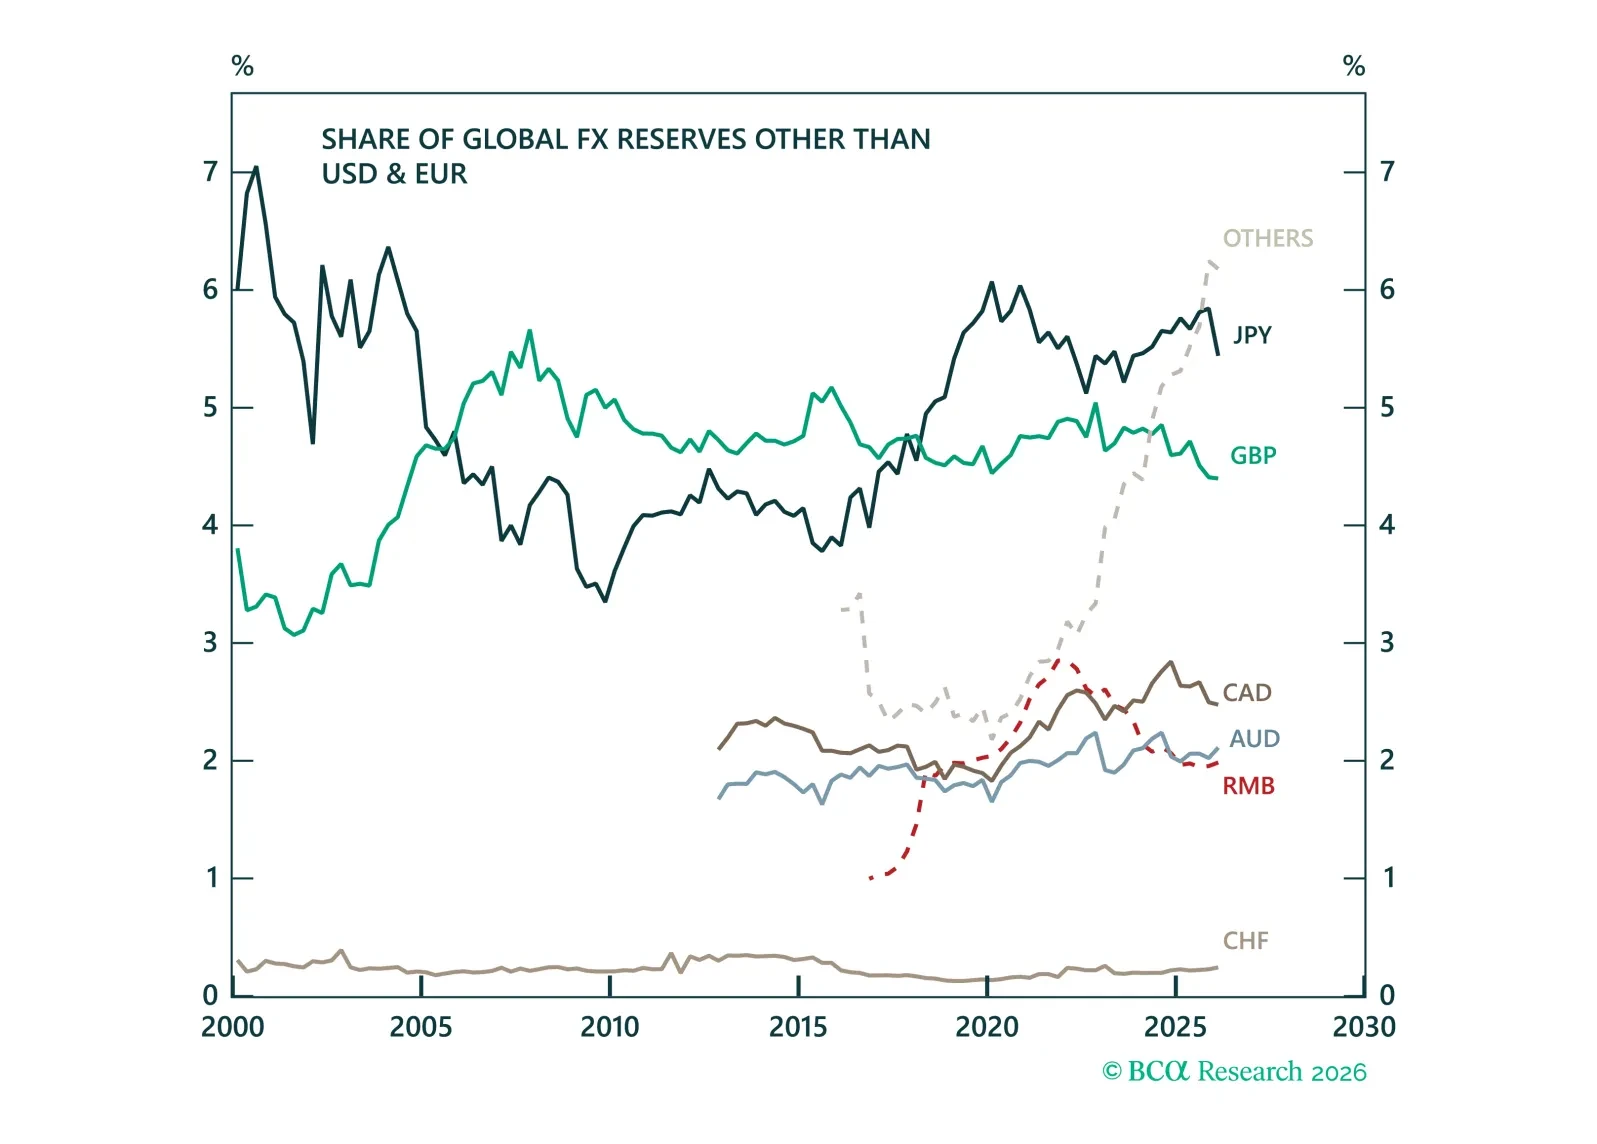
Special Report The dollar is not being replaced by a single rival, it is being diluted by a rising cast of “other” reserve currencies. This report identifies the hidden winners of reserve diversification and why they may matter more than investors think.
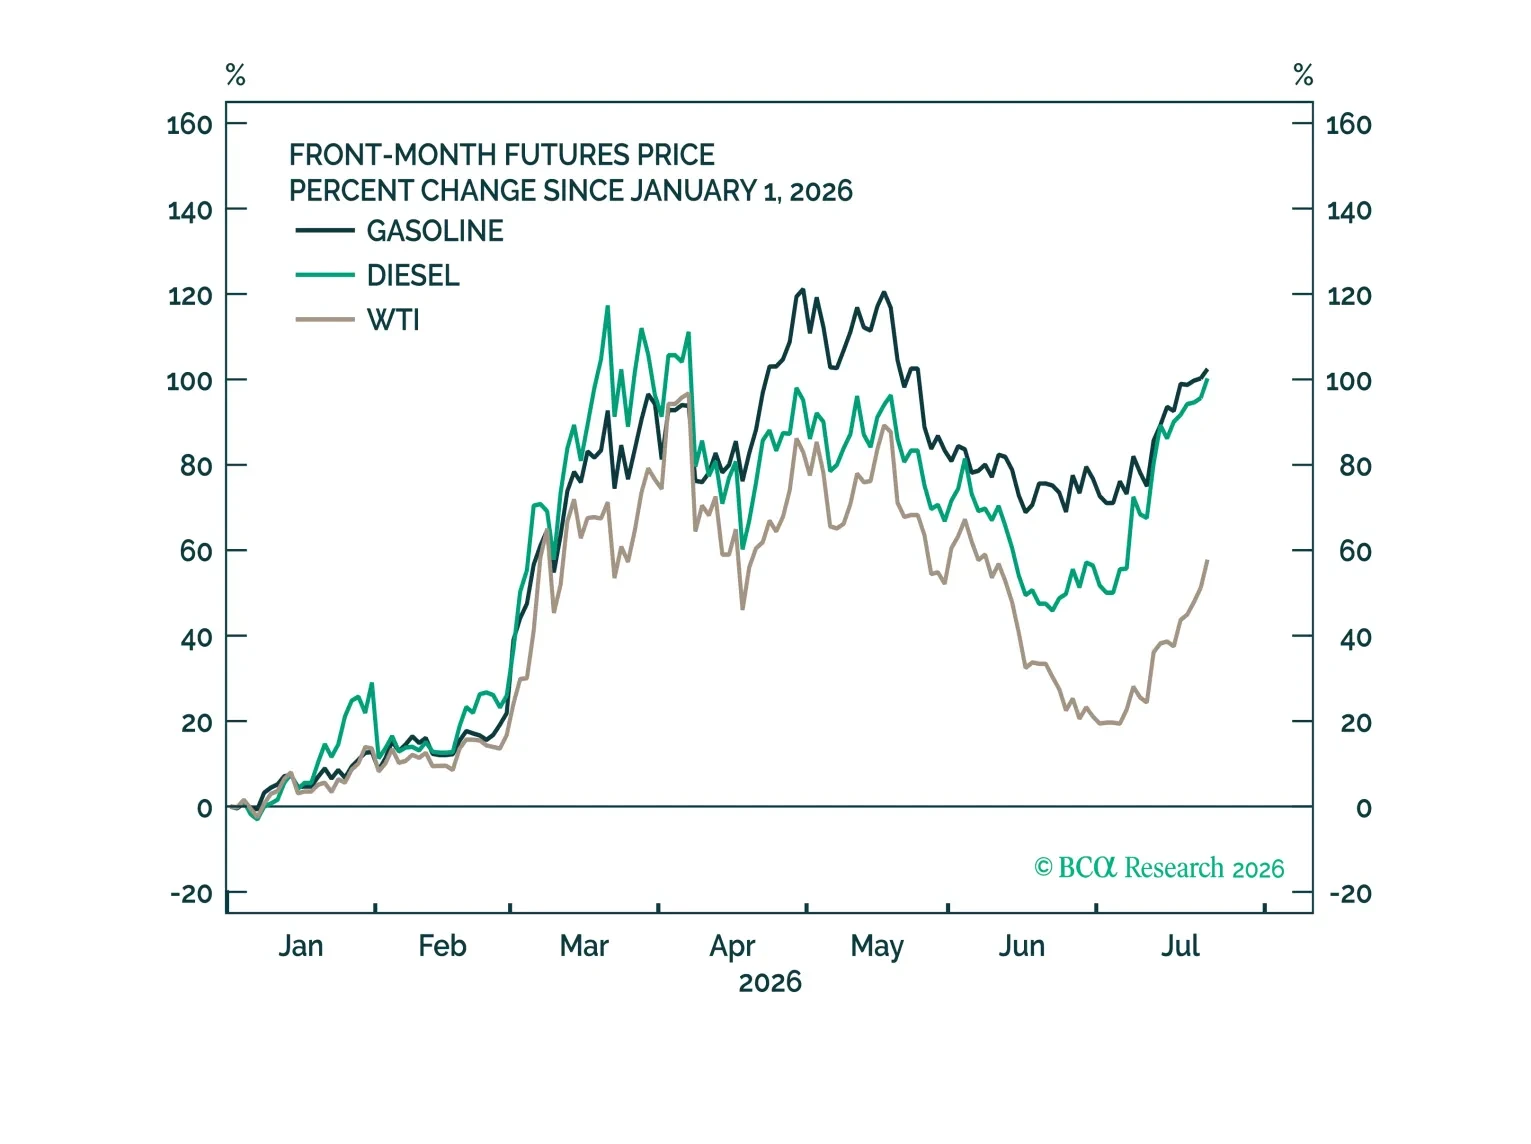
The equity bull market is getting long in the tooth. Bonds should perform well once economic growth begins to slow. The dollar will strengthen over the coming months before resuming its downtrend. While crude has likely found a near-term floor, we favor metals over energy in the long run.
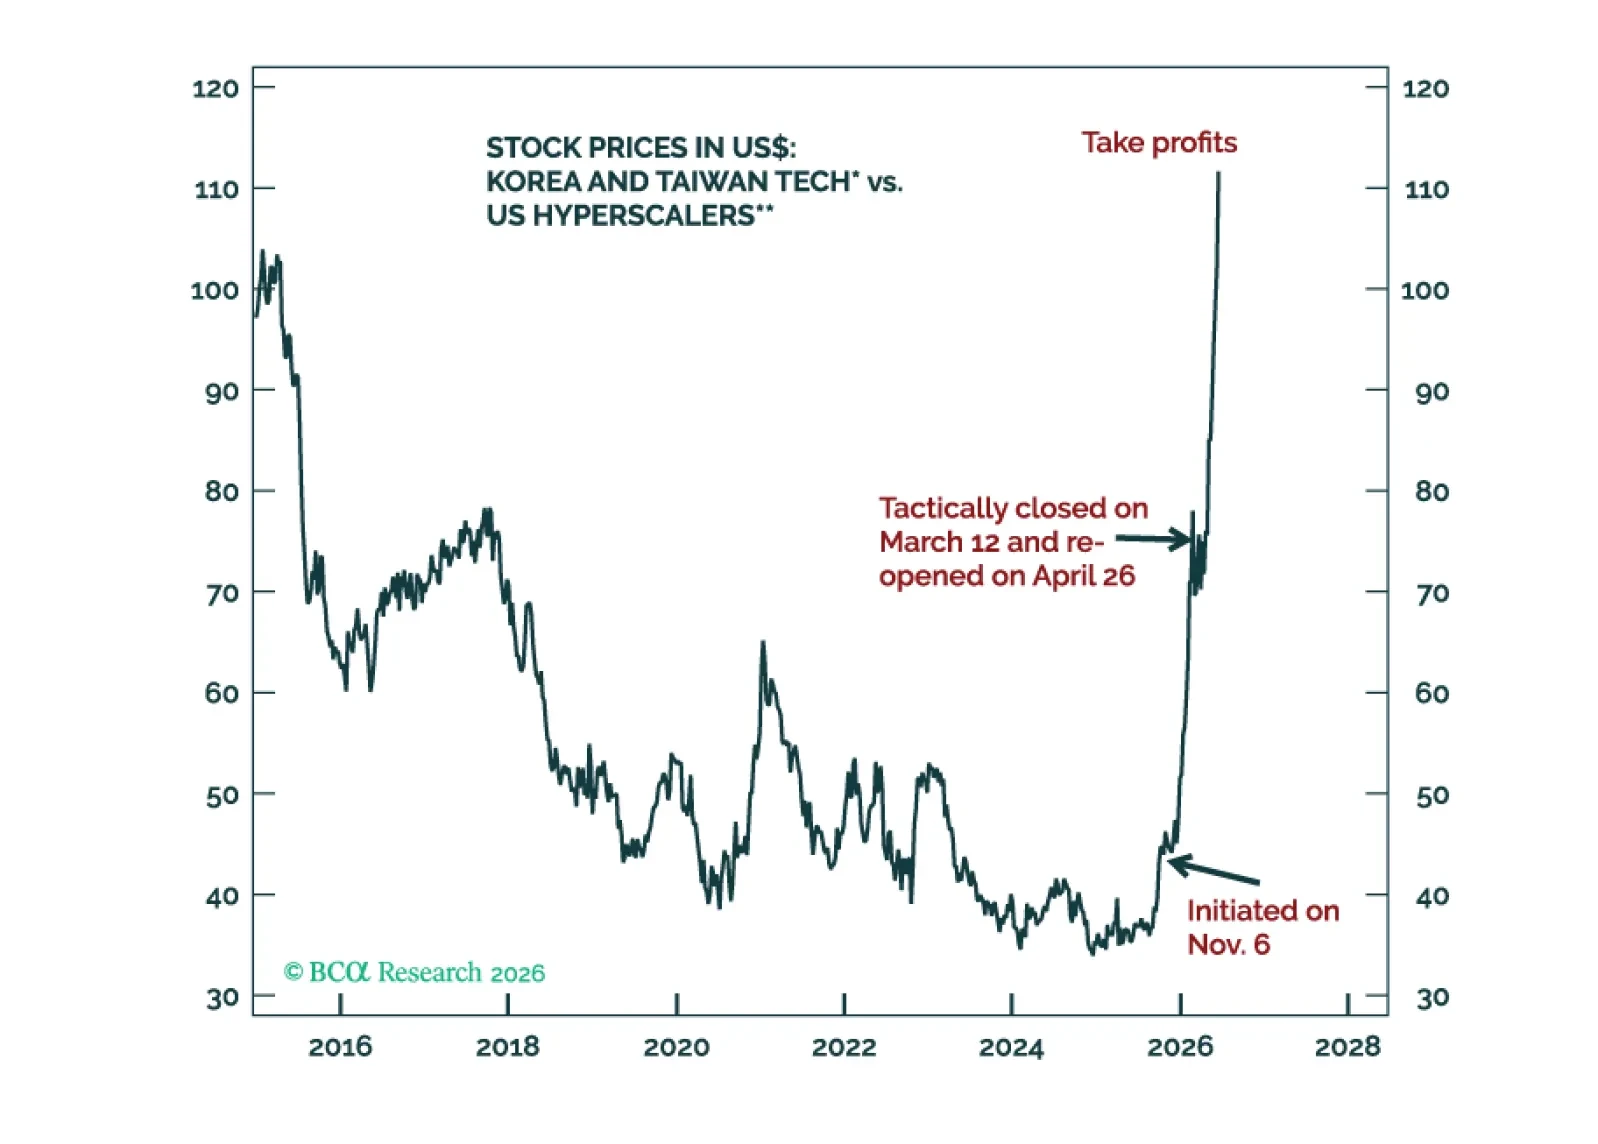
Korea’s recent equity market tantrum is a warning signal for global risk assets. We are booking profits on the long Asian semiconductor stocks / short US hyperscalers trade and downgrading Korea from overweight to neutral in an EM equity portfolio.