US Election
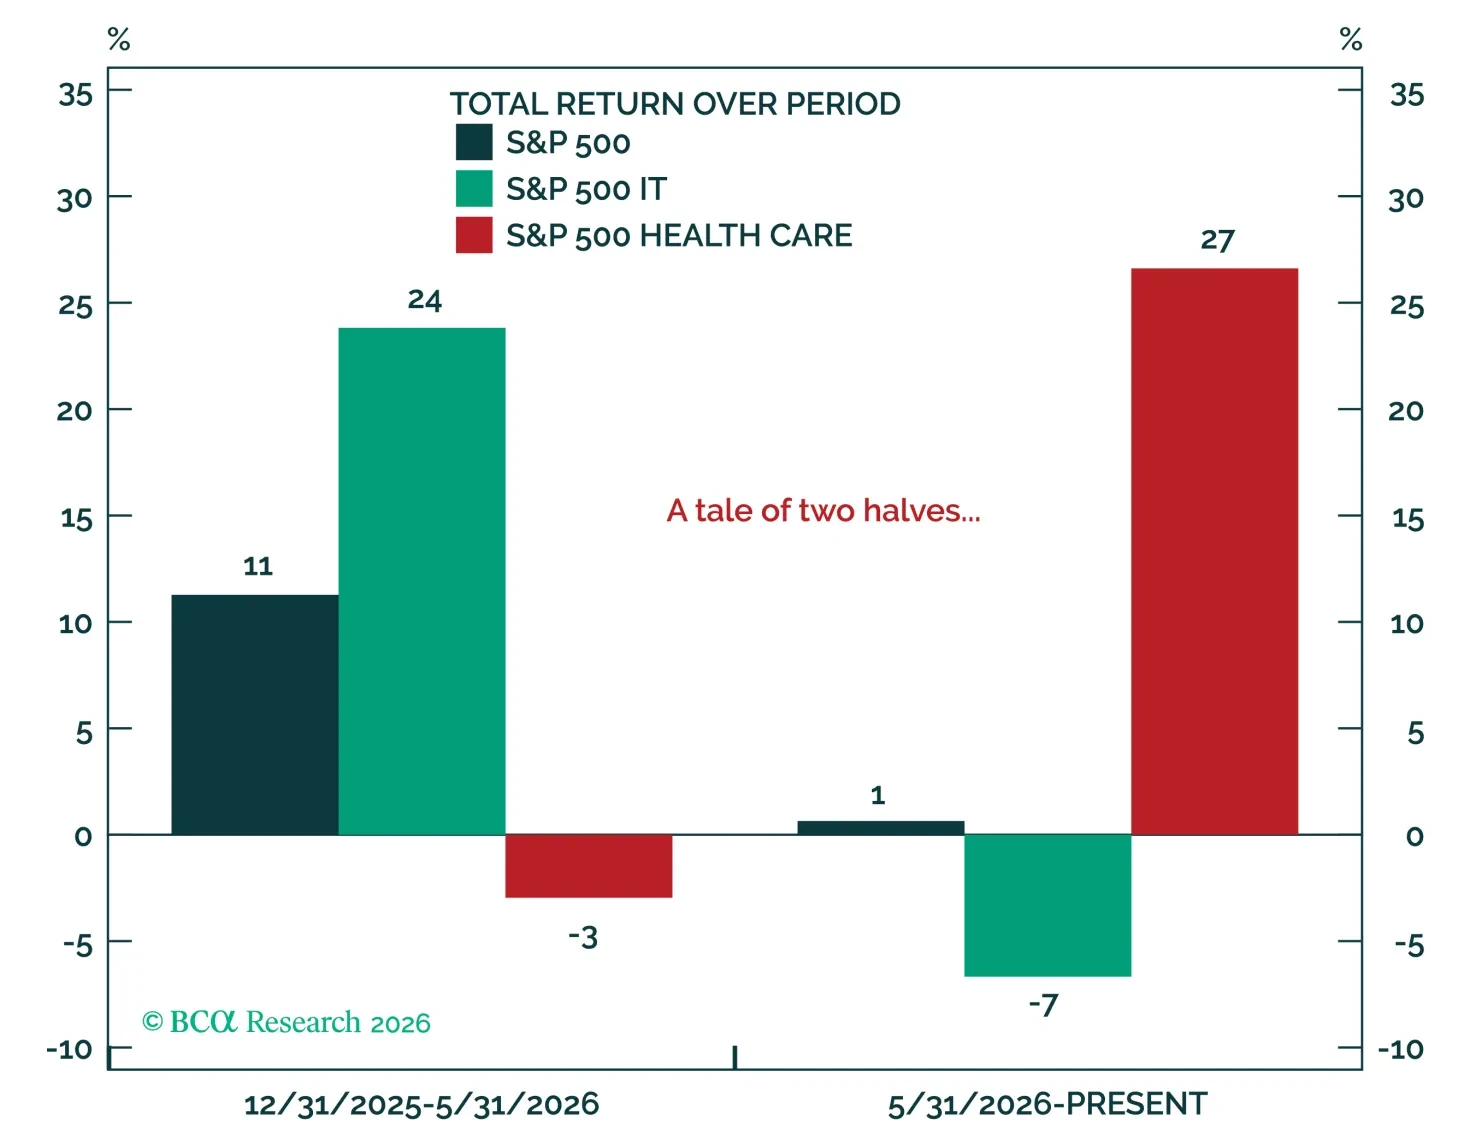
Health Care’s second-half 2026 rally has largely been a defensive rotation, not the start of a new bull market. Health Care leadership is more typical when the economy is slowing/contracting and is hard to sustain in a rising market. With the cycle still firm and our expectation that the market rallies into year end, we are neutral on the sector, though we recognize its hedging value. Within Health Care, we are underweight Providers & Services, overweight Equipment & Supplies, and market weight Pharmaceuticals, Biotech & Life Sciences (“Pharma”).
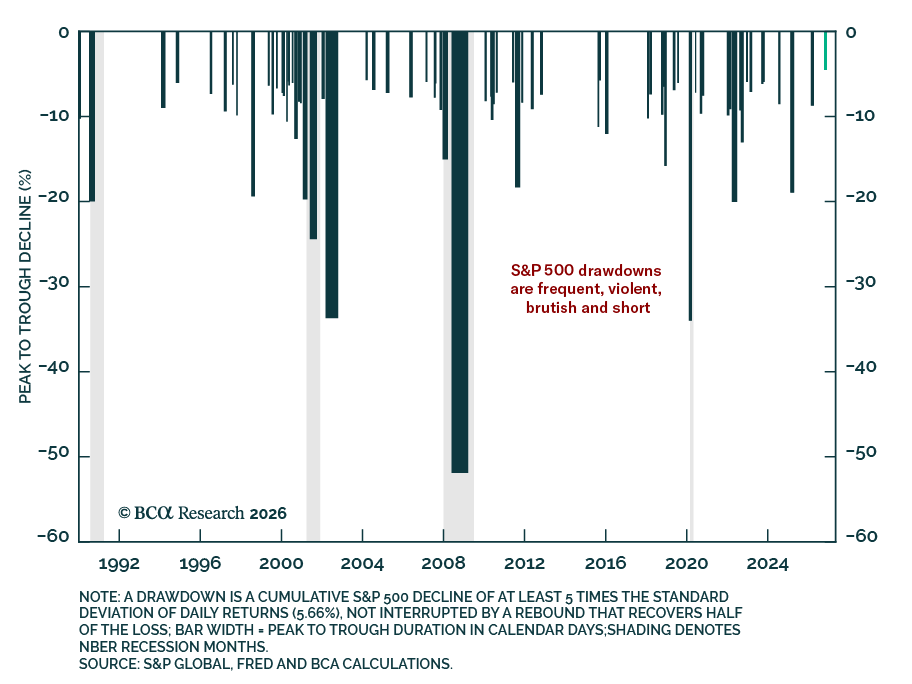
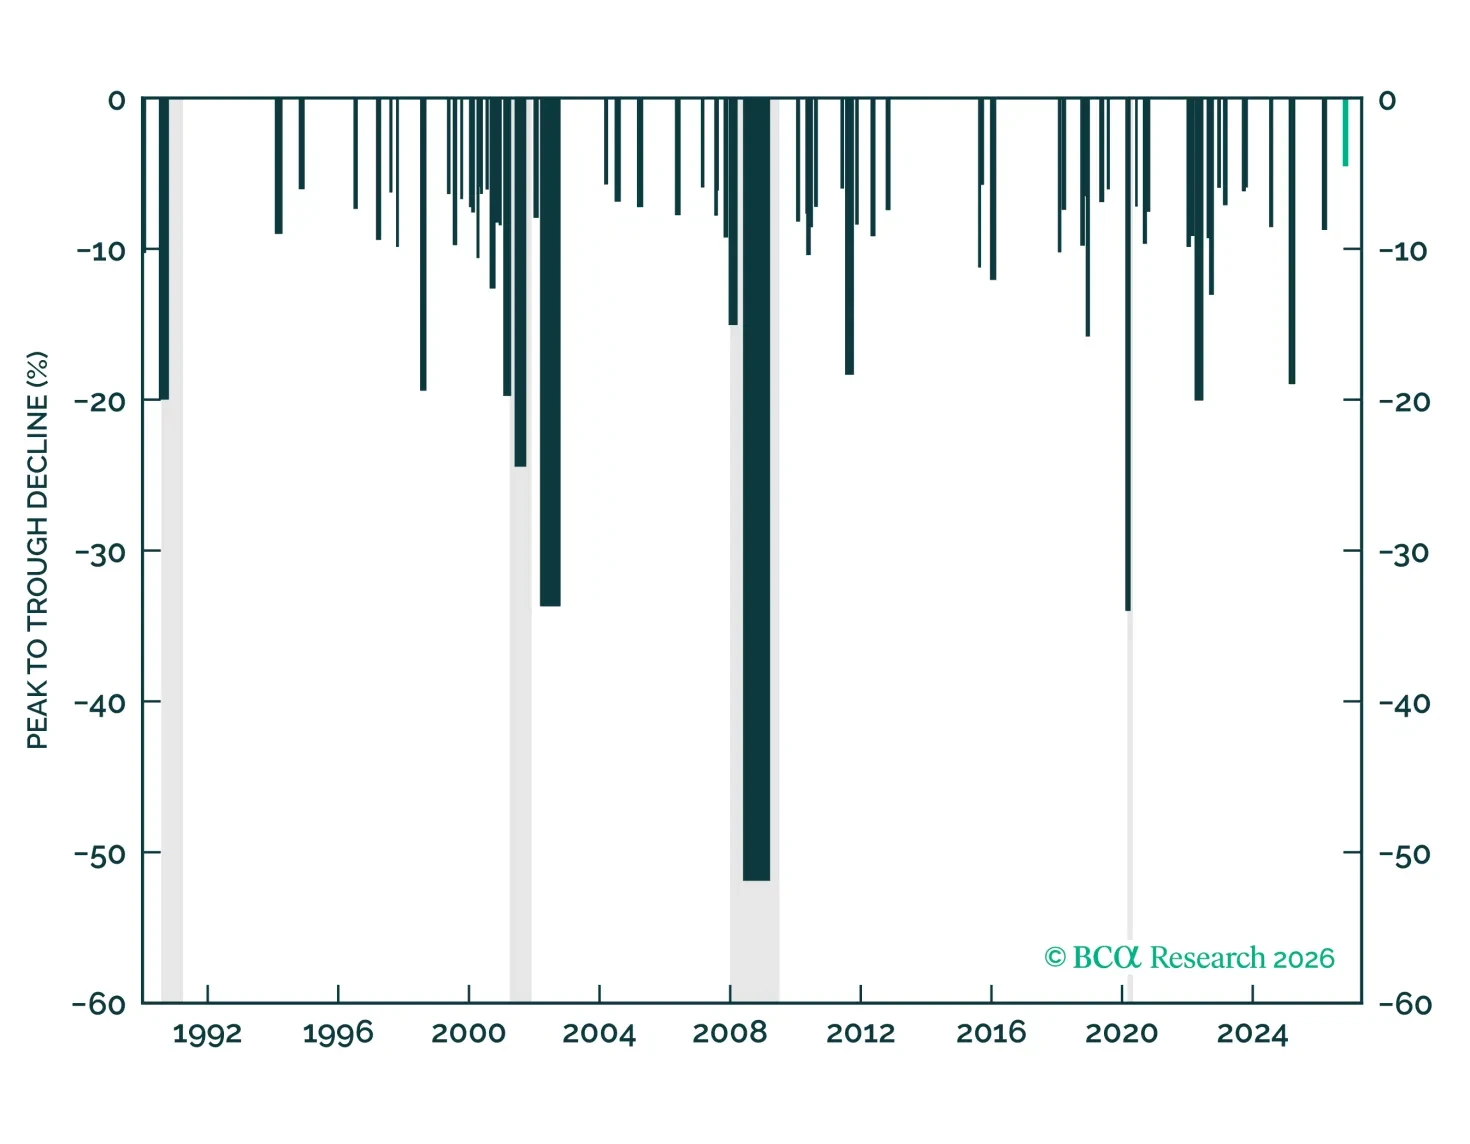
AI capex concerns have pushed the S&P 500 to the brink of a drawdown. But the cycle remains strong, drawdowns rarely last long, and Tech valuations had already compressed. And while Democratic governors now oversee about 80% of the data-center pipeline, a blue governor alone is not necessarily a build-out moratorium.
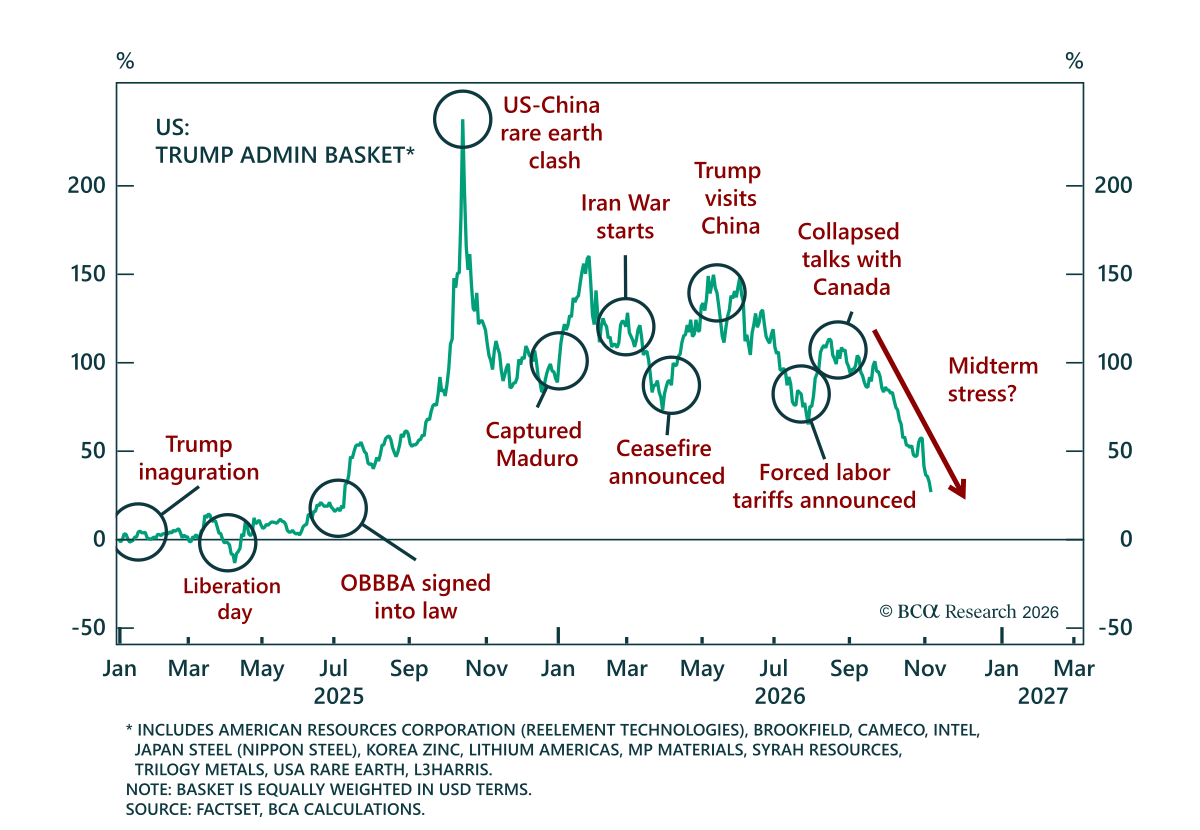
On October 13, we asked what would happen “if Gina wins?” Gina Hinojosa, a Democratic state legislator from the traditionally Republican-voting Texas, was at the time given only a 1-in-5 chance of winning the state’s governorship, despite being tied in the polls with the conservative incumbent.
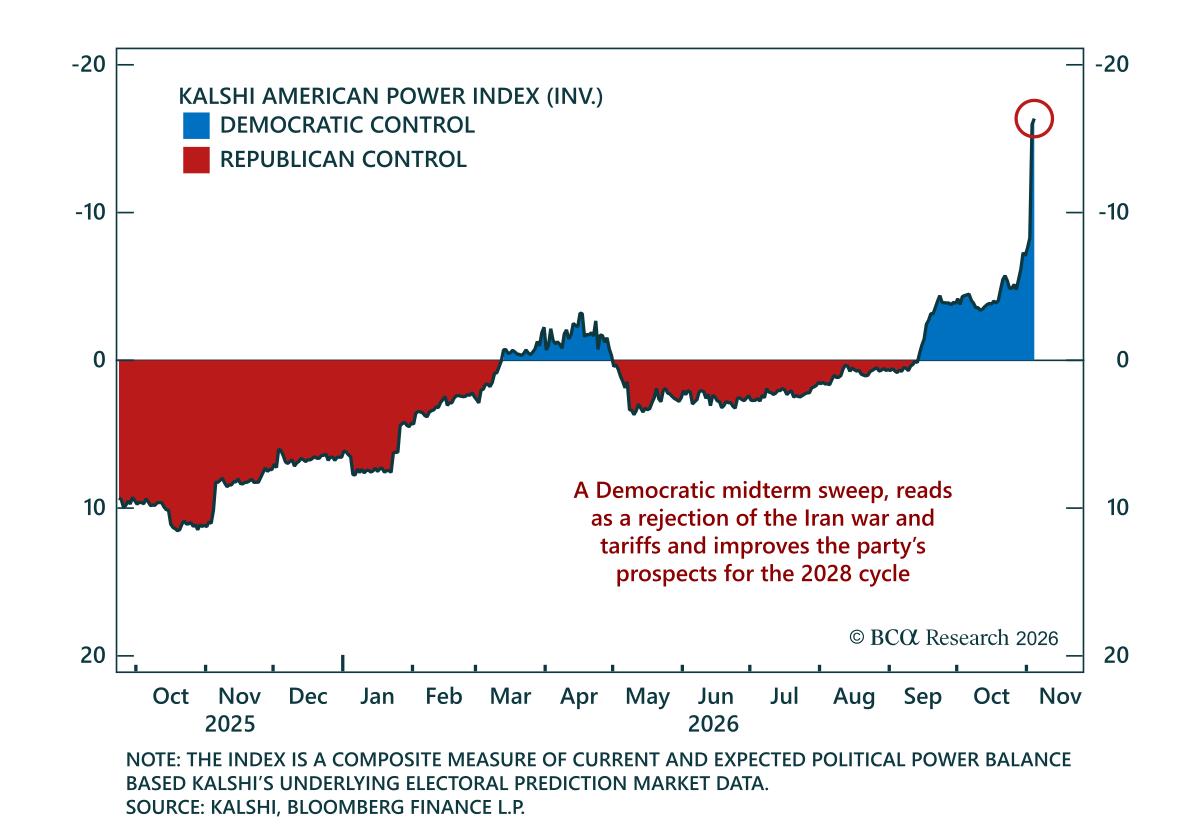
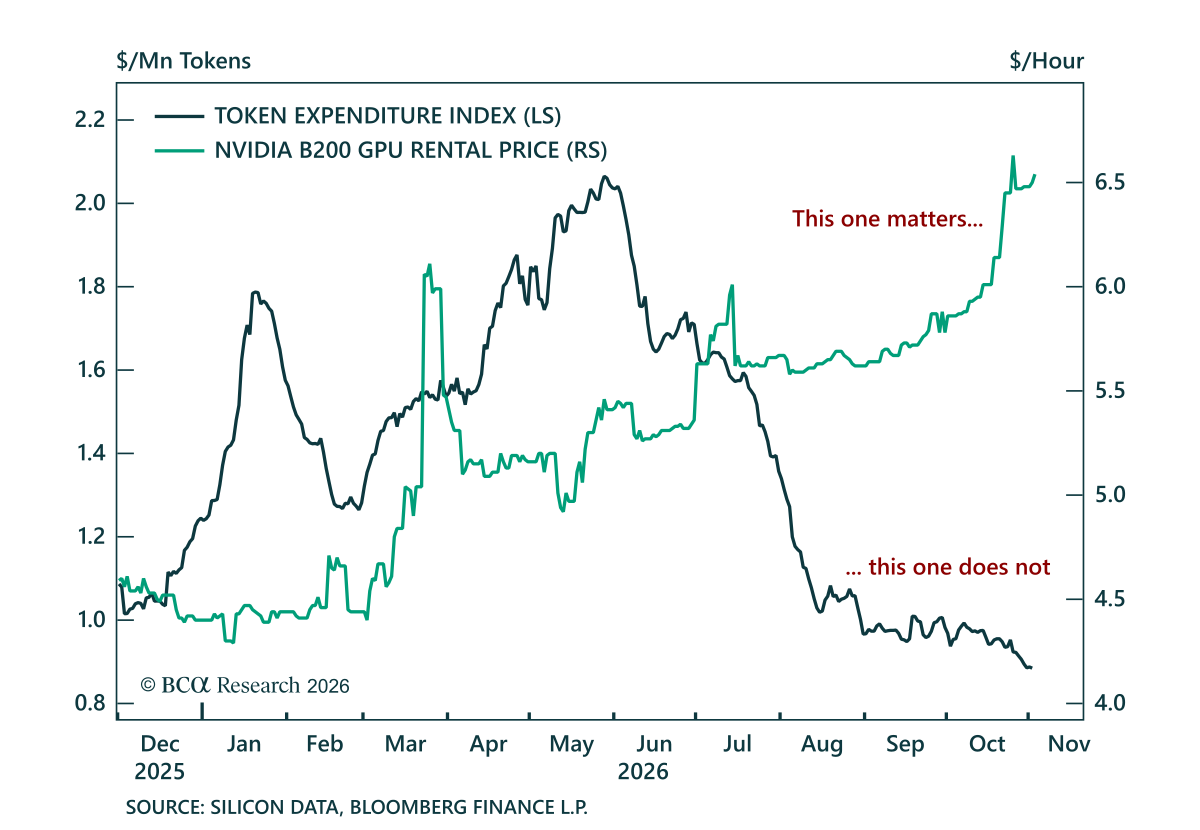
October has been a bad month for equities — particularly AI/tech ones — and a great month for oil. We do not think that the AI supercycle is ending, it has more room to go. Token price decline is a sign of a price war between LLMs, not a decline in demand. In fact, that price war is what is driving datacenter profitability, which is what the bull market is actually based on.
As such, what matters on a tactical time horizon is whether Trump capitulates on Iran. If he does not, the market will have to correct. We take the bullish side and expect oil prices to decline imminently, forcing a short squeeze and powering equities higher.