Developed Countries
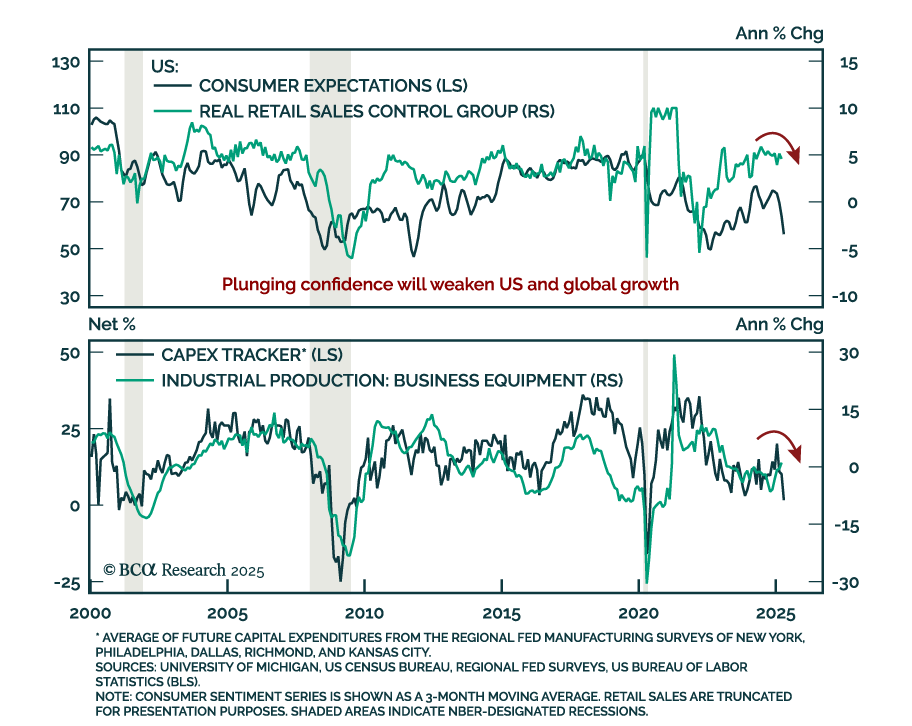
Soft data continues to deteriorate and hard data will soon follow, reinforcing our defensive asset allocation. Consumer and business confidence have plunged as policy uncertainty and inflation expectations rise, with spending, hiring and capex plans…
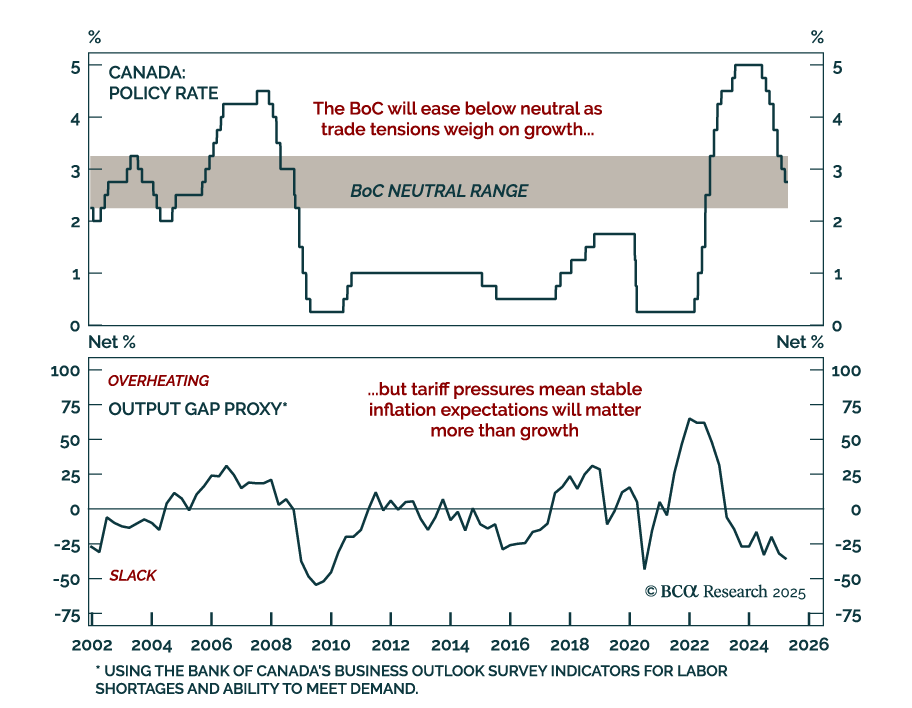
After seven consecutive cuts brought policy into neutral territory, the BoC held its deposit rate at 2.75% reinforcing our neutral-to-negative stance on Canadian government bonds. With policy now within the 2.25%-3.25% neutral range, the Bank comfortably…
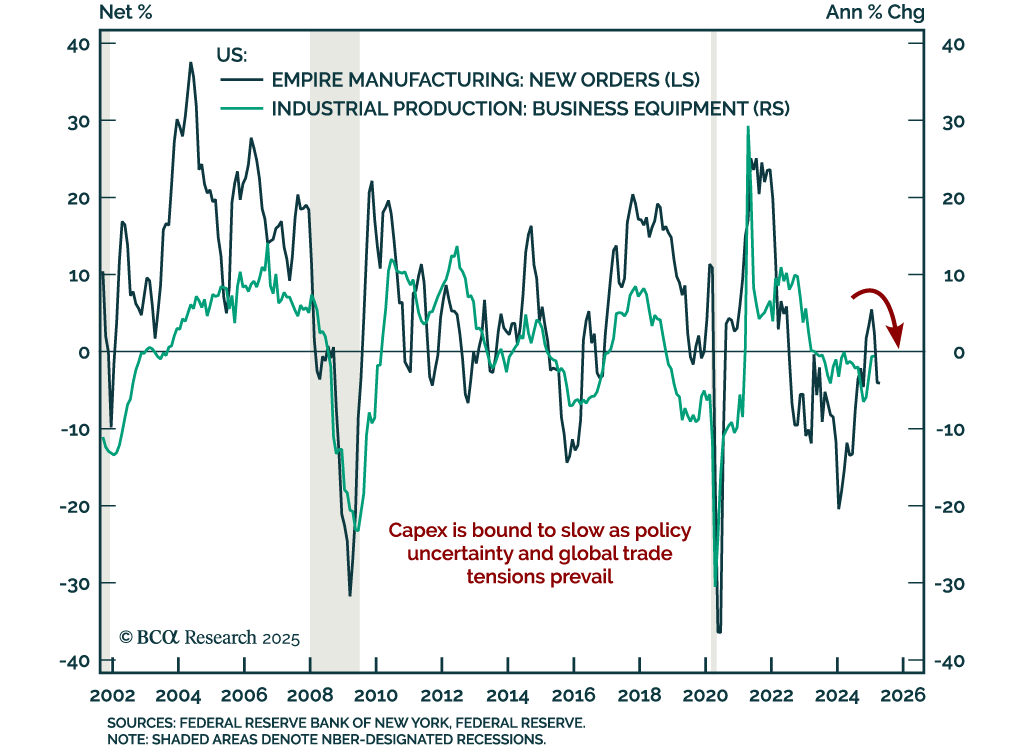
The NY Fed Empire Manufacturing survey adds to recent stagflationary worries, reinforcing our underweight in risk assets and overweight in government bonds. The general business conditions index rose slightly to -8.1 but remains in contraction, while the…
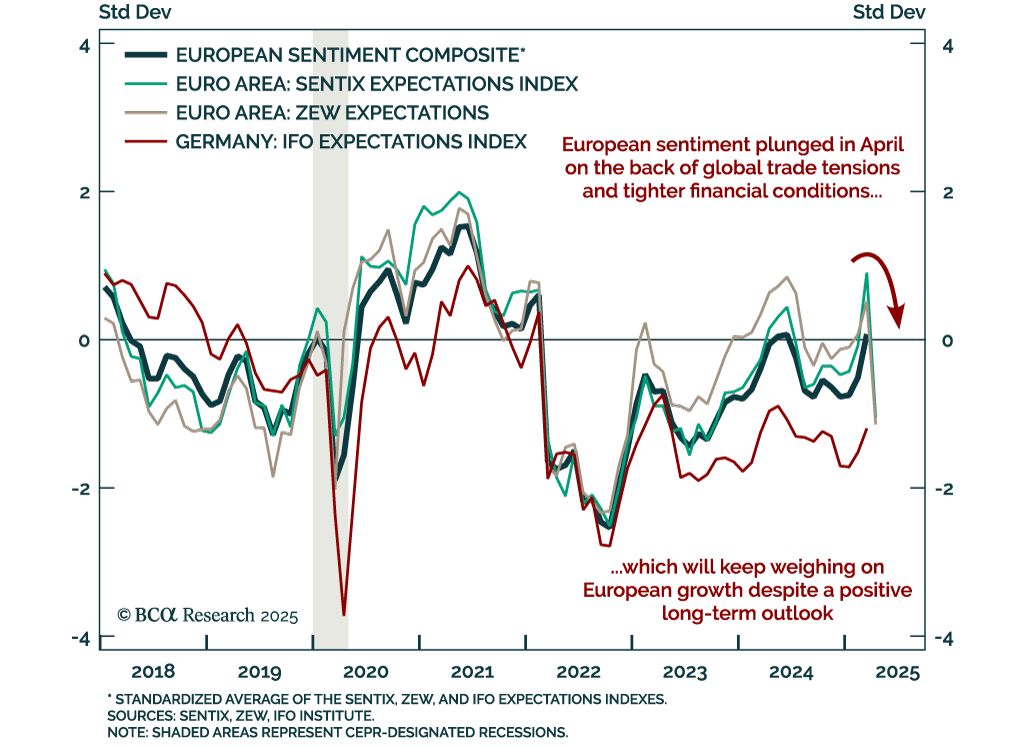
Eurozone sentiment has sharply deteriorated, reinforcing a cautious stance on European assets over the next 6 to 12 months. The April ZEW expectations index for the eurozone collapsed to -18.5 from 39.8, while Germany’s gauge also plunged and missed…
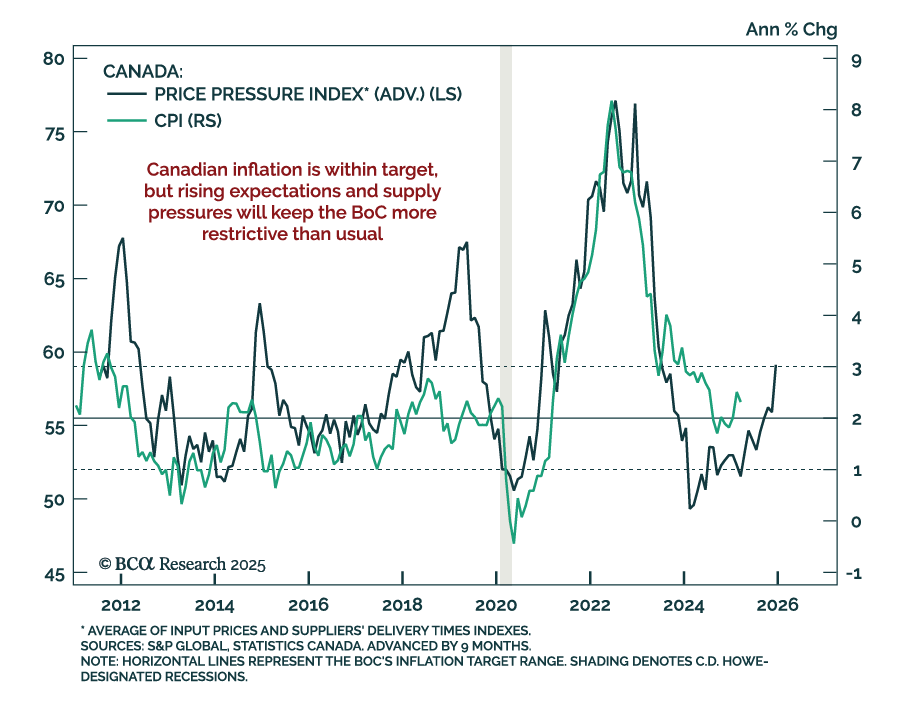
Cooler inflation will not shift the BoC’s stance, as stagflation limits potential easing, keeping us neutral on Canadian bonds. In March, headline CPI slowed more than expected to 2.3% y/y from 2.6%. However, lower energy prices drove much of the downside…
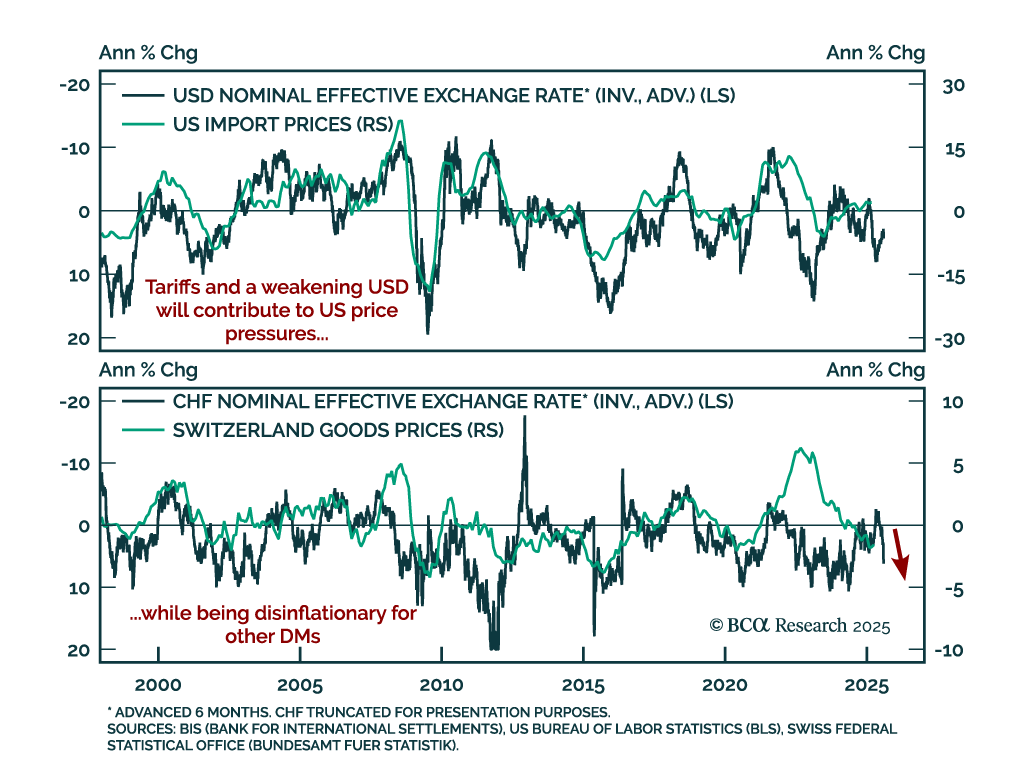
Tariff-driven inflation is diverging across economies, with the US facing mounting pressures while disinflation persists elsewhere. In theory, US tariffs should strengthen the dollar and weaken targeted currencies. In practice, the opposite has occurred: The…
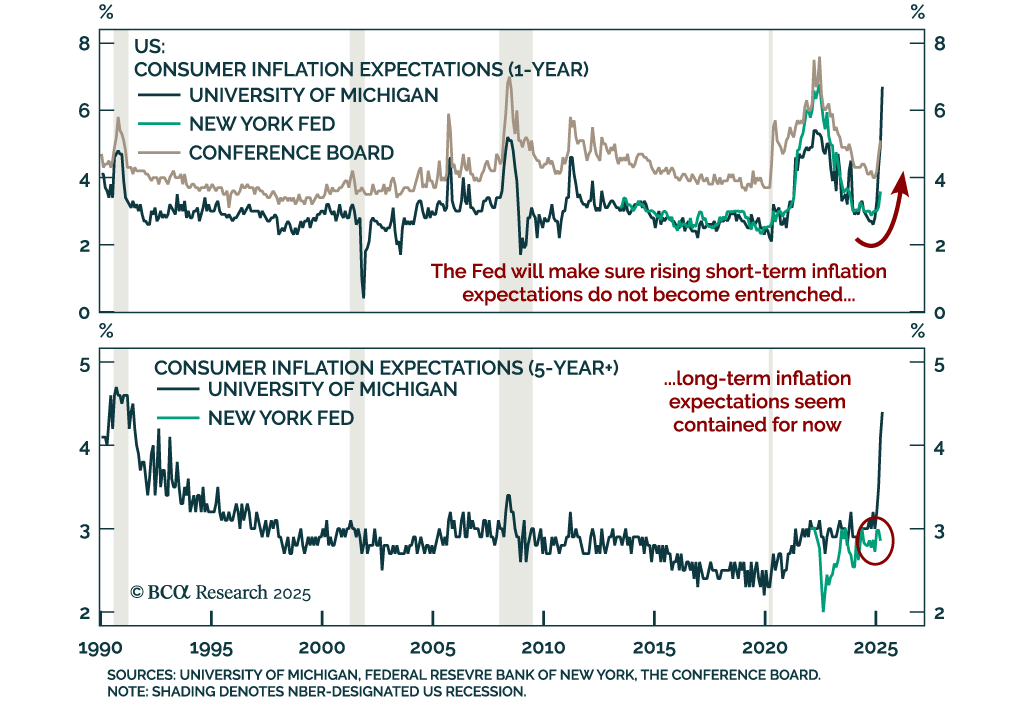
The latest NY Fed Survey of Consumer Expectations reinforces our defensive stance, with growth concerns deepening even as long-term inflation expectations remain anchored. The survey is a useful cross-check against broader sentiment and inflation indicators,…
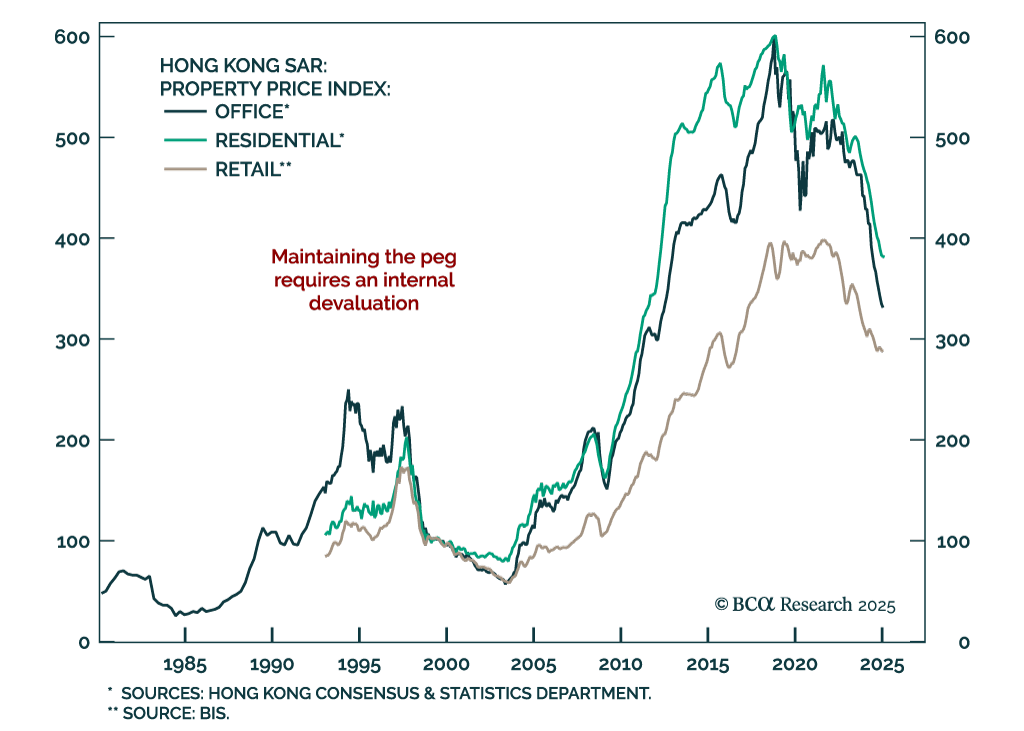
Our FX strategists expect the HKD peg to hold, but at the cost of prolonged economic weakness and debt deflation in Hong Kong. Interest rates remain too high for the local economy, yet monetary easing is off-limits due to the peg.The currency’s…
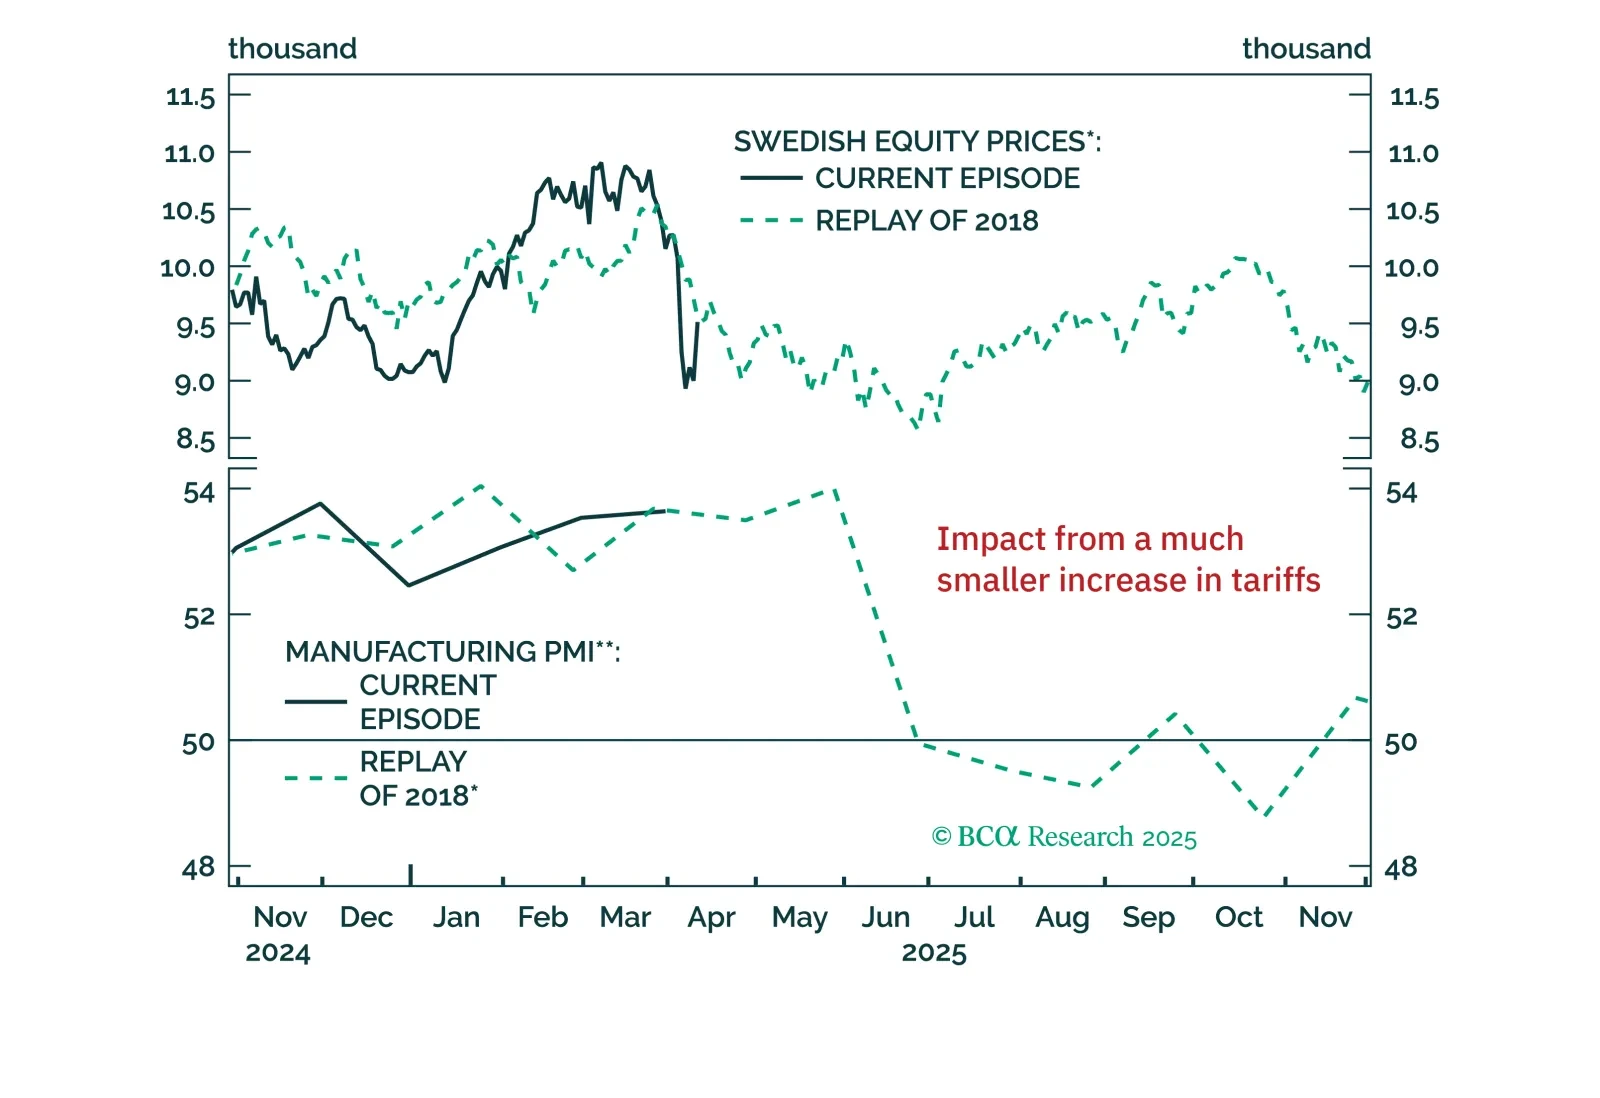
Europe’s near-term outlook remains clouded by uncertainty, even after the tariff reprieve. Our latest update breaks down why the risks to growth, profits, and financial conditions are still skewed to the downside — with Sweden standing out as a key bellwether.
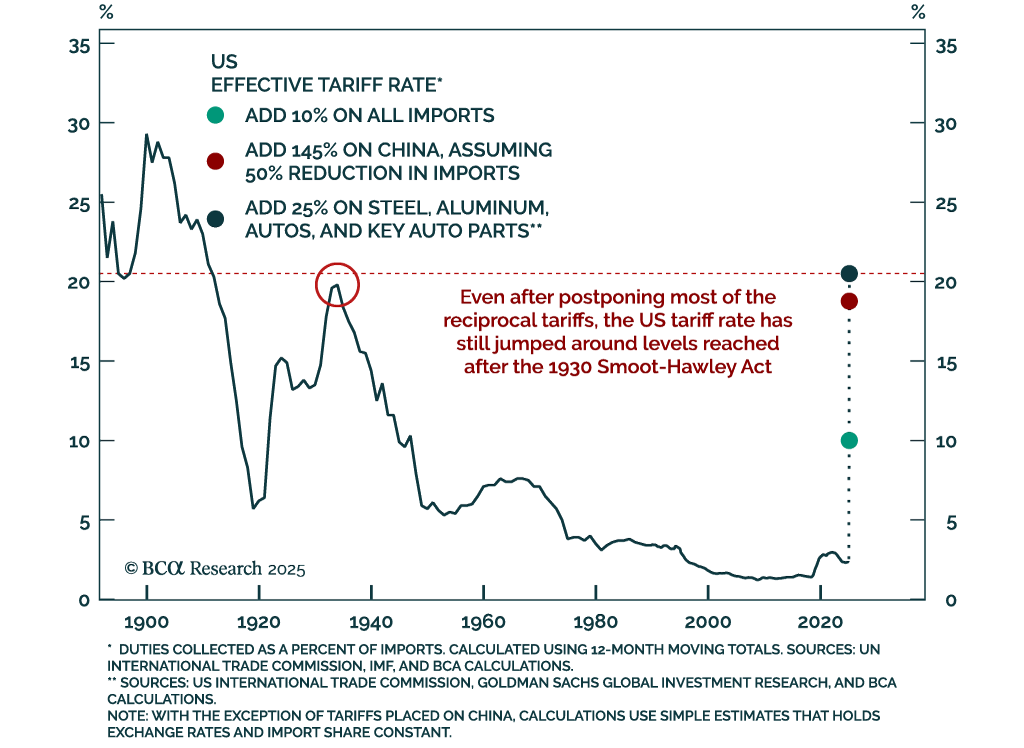
Our Global Investment Strategists remain defensive, expecting a global recession in the coming months unless the trade war de-escalates meaningfully. They maintain a year-end S&P 500 target of 4450, with downside risk to 4200.While reciprocal tariffs were…