Bear/Bull Market
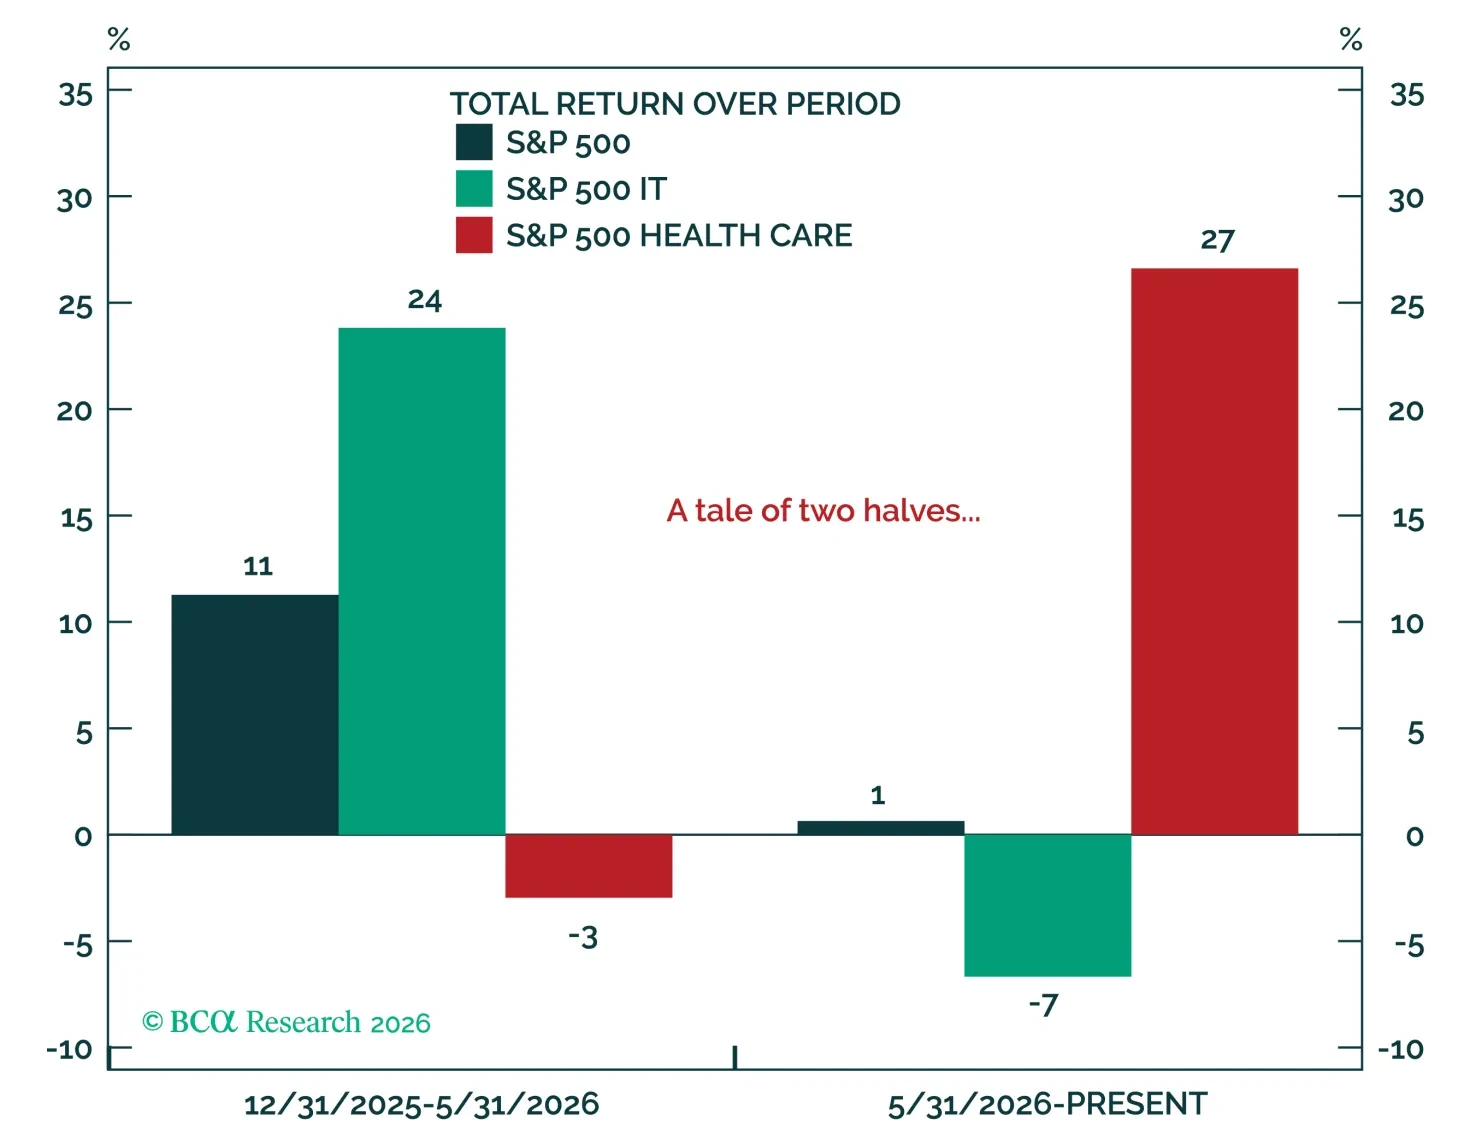
Health Care’s second-half 2026 rally has largely been a defensive rotation, not the start of a new bull market. Health Care leadership is more typical when the economy is slowing/contracting and is hard to sustain in a rising market. With the cycle still firm and our expectation that the market rallies into year end, we are neutral on the sector, though we recognize its hedging value. Within Health Care, we are underweight Providers & Services, overweight Equipment & Supplies, and market weight Pharmaceuticals, Biotech & Life Sciences (“Pharma”).
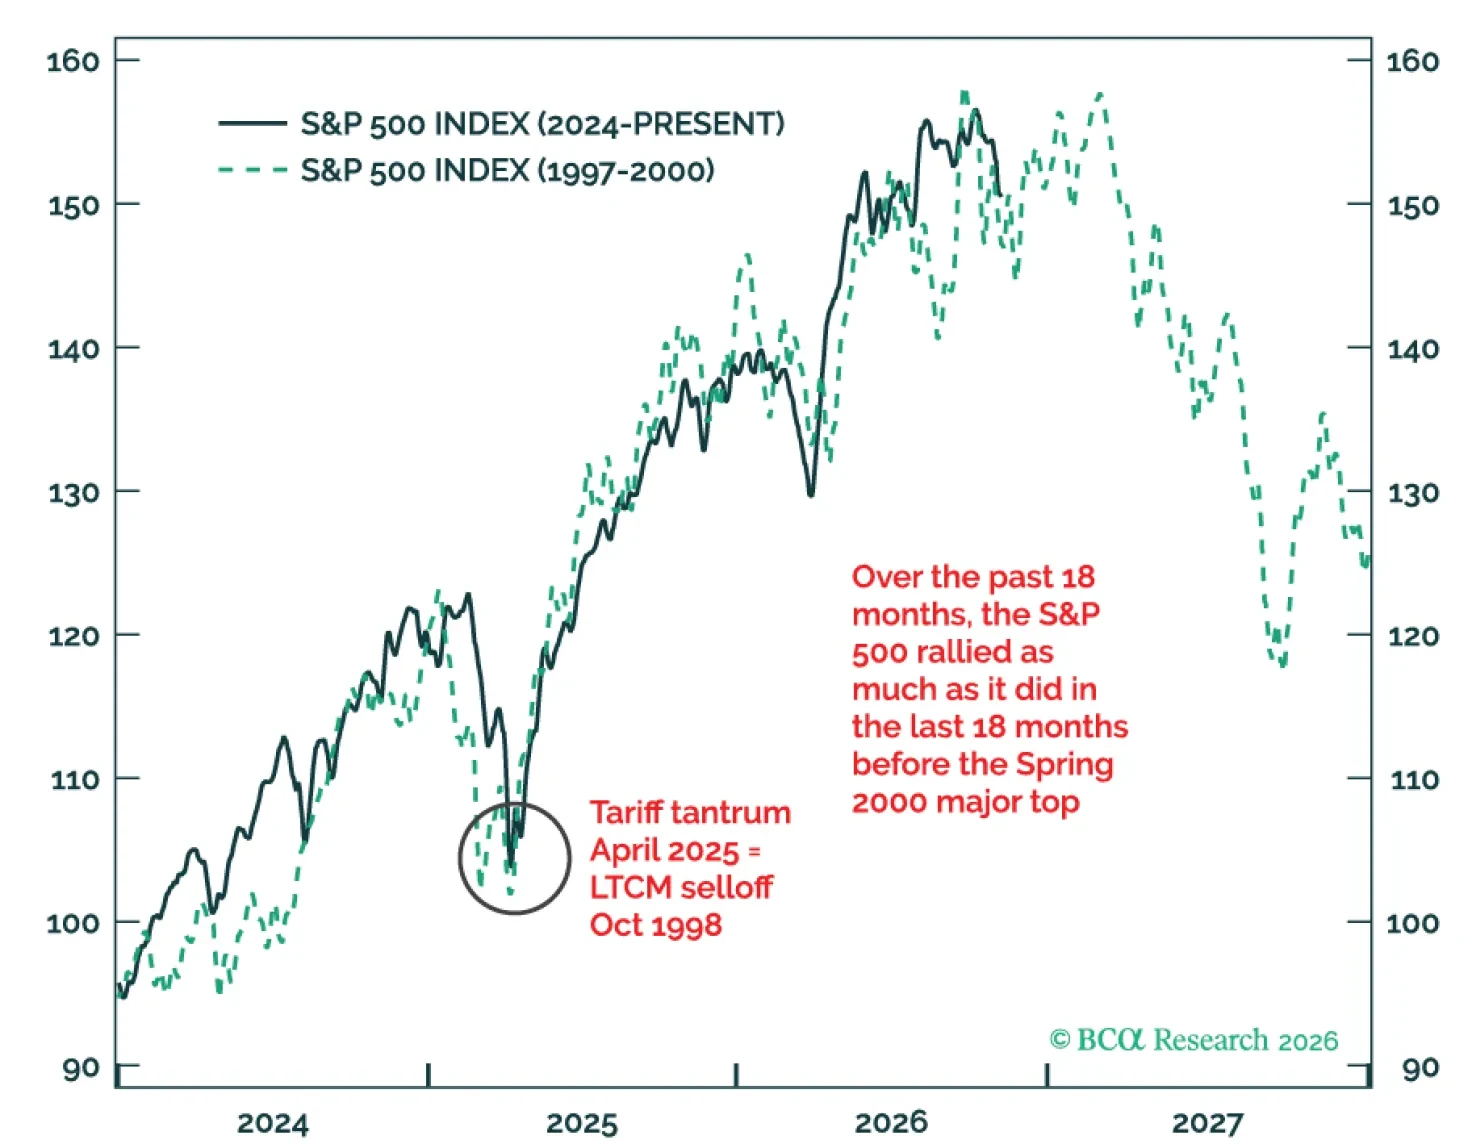
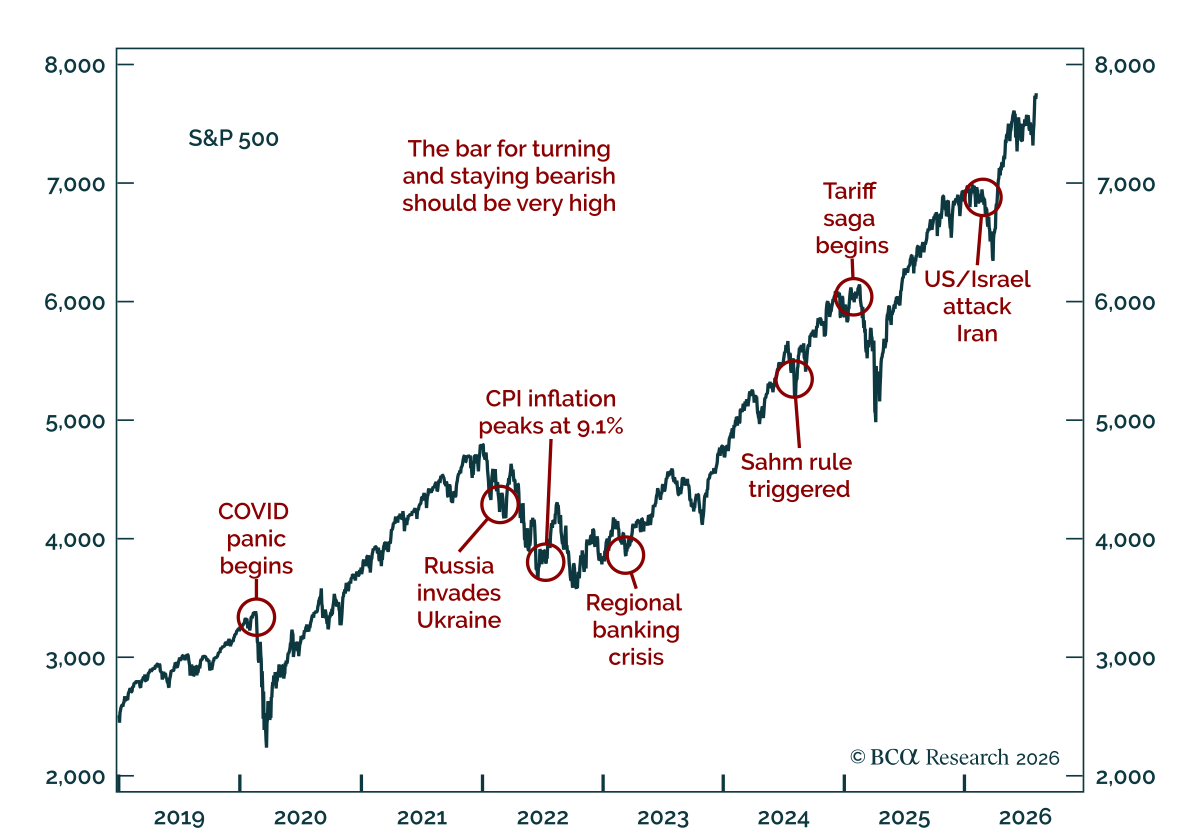
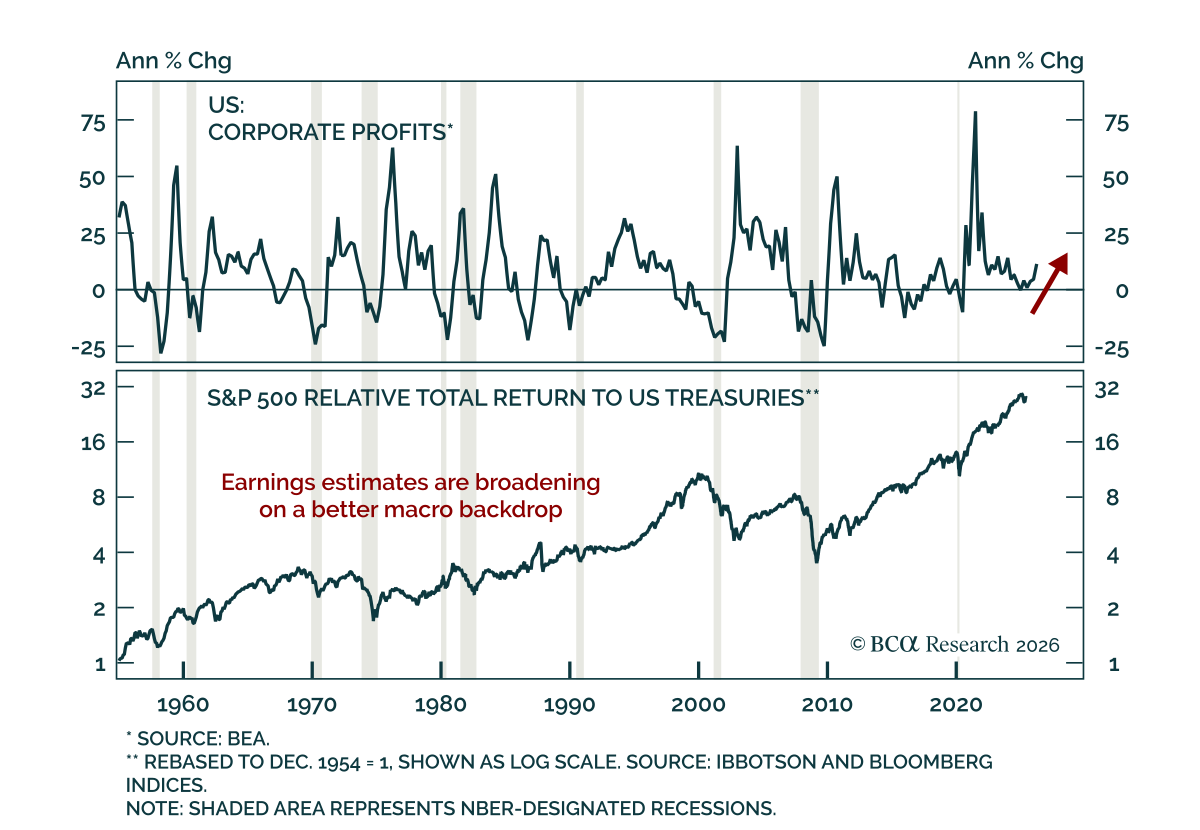
Resist buying the equity dip: a major global market top may already be behind us. Sell the US dollar on strength. Accumulate bonds on weakness, favoring those in countries with current account surpluses.
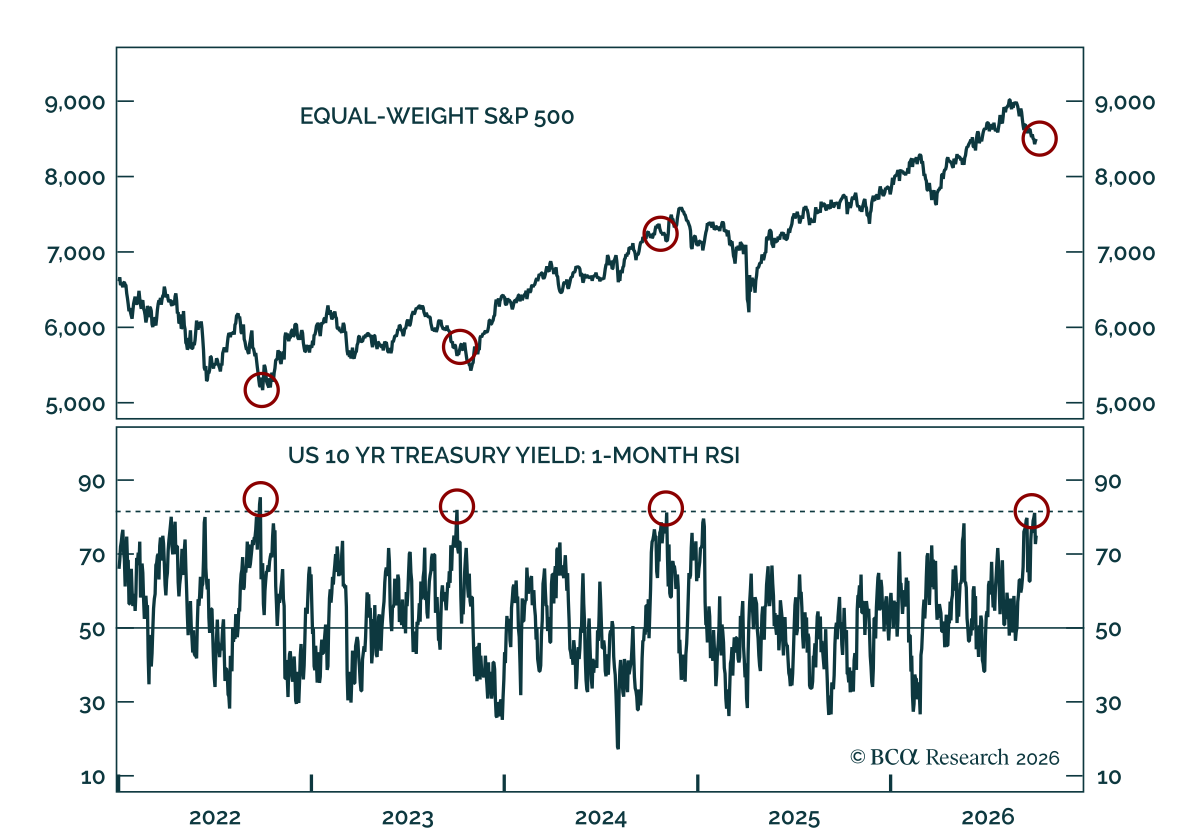
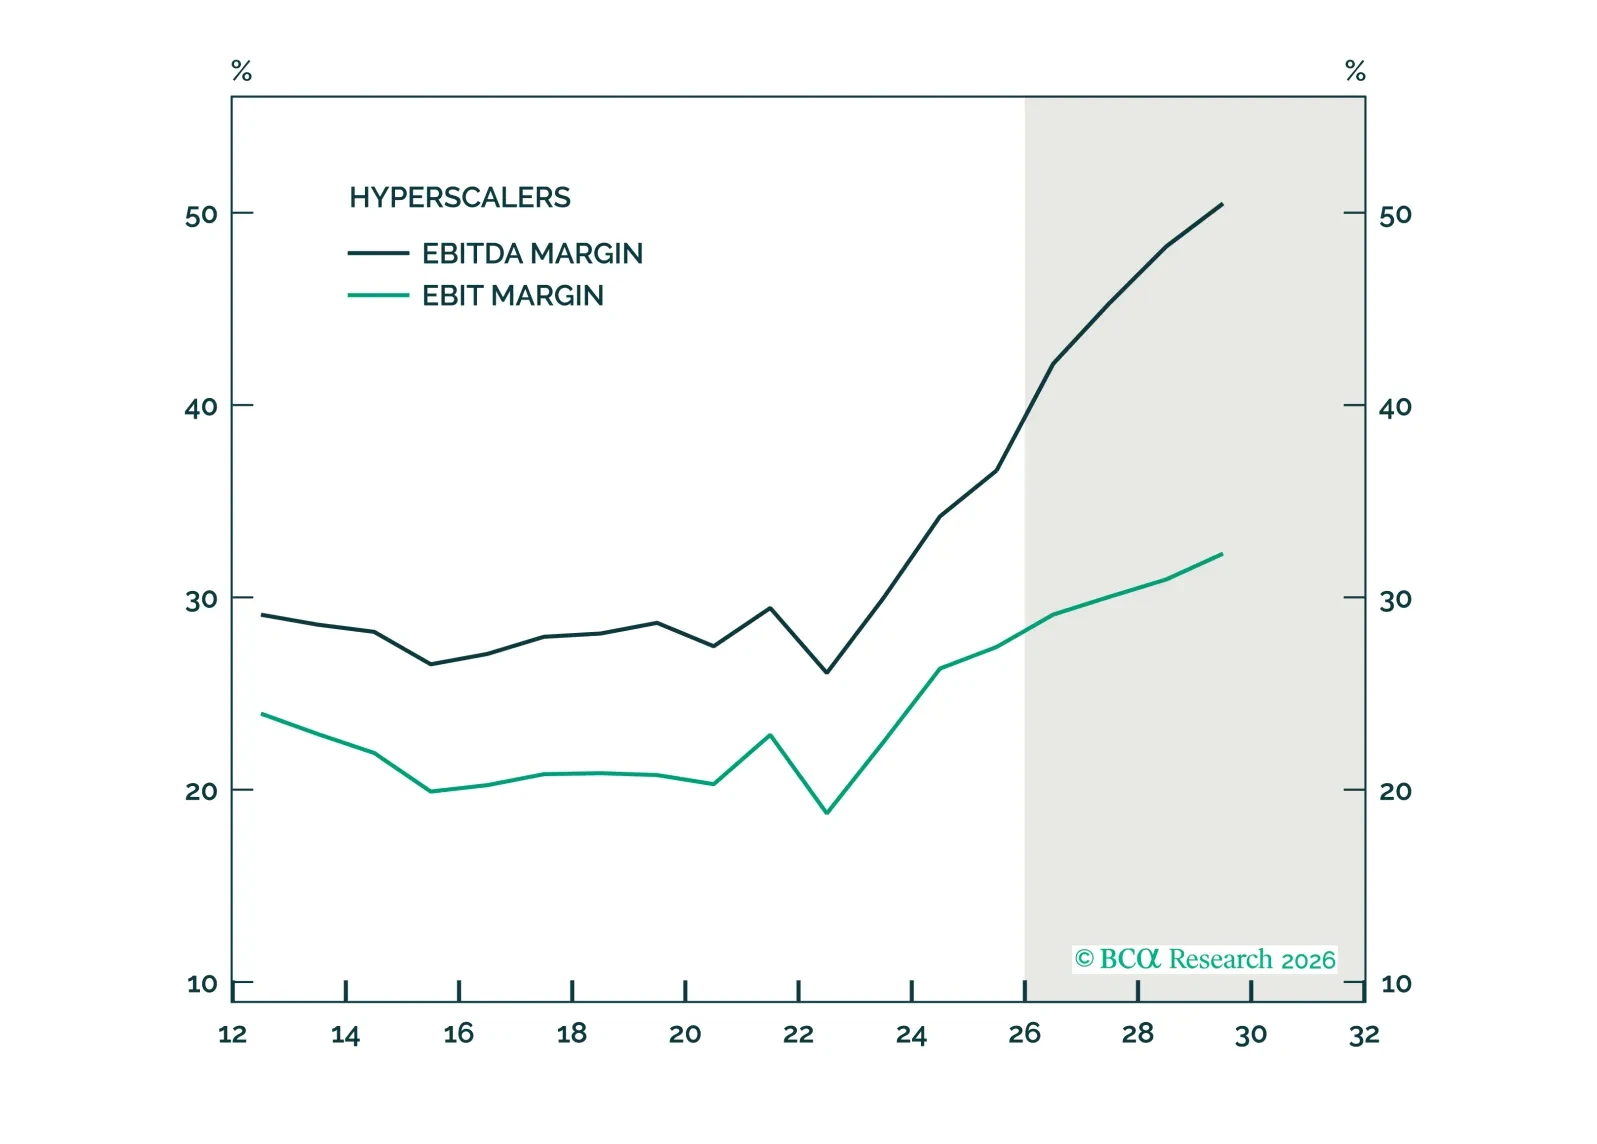
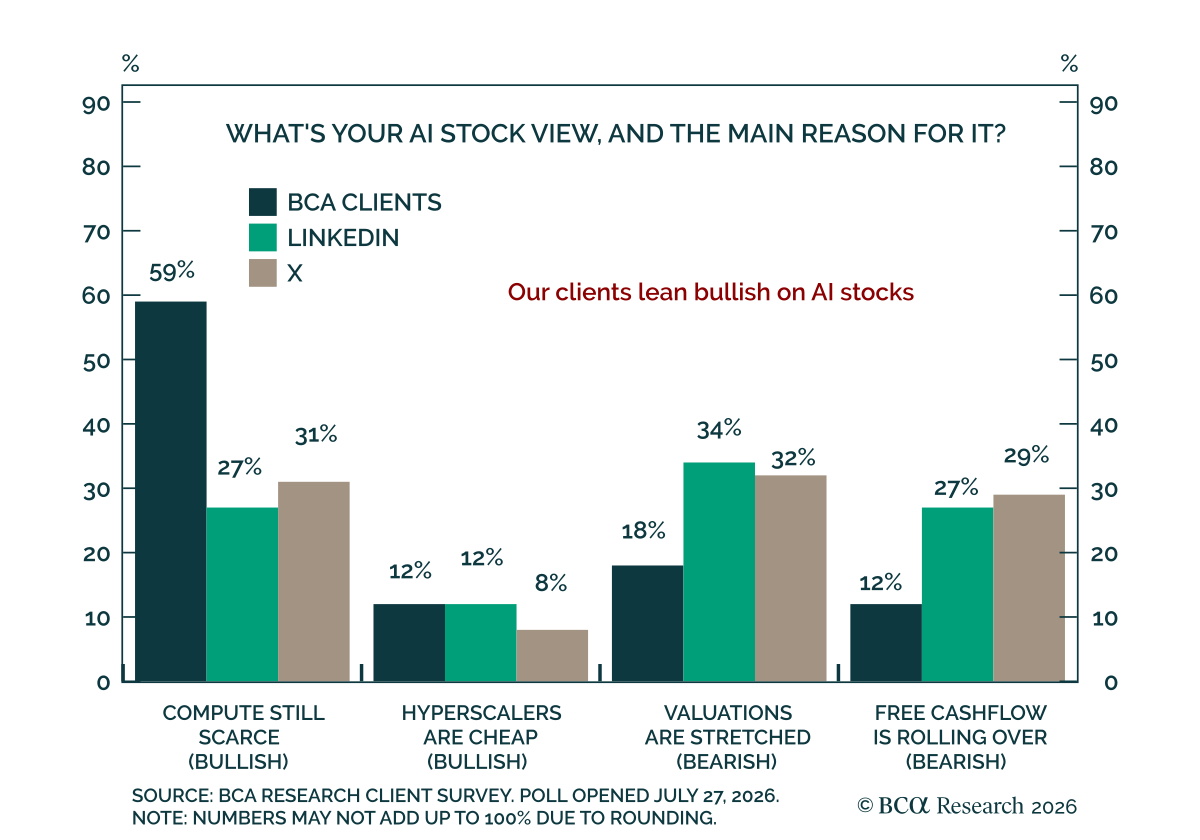
An acute shortage of AI hardware will support tech stocks into year-end. However, AI companies may need to ultimately generate $10 trillion per year in revenue to justify their capex. Barring a massive increase in productivity growth, this will be very difficult to achieve. Despite today’s Treasury announcement of upsized buyback operations, bond yields are likely to remain elevated over the coming months. Rising crack spreads have reduced the demand for crude, which is not encouraging for global growth. On the FX front, recent intervention to support the yen will probably be insufficient, but there is significant long-term upside for the currency.
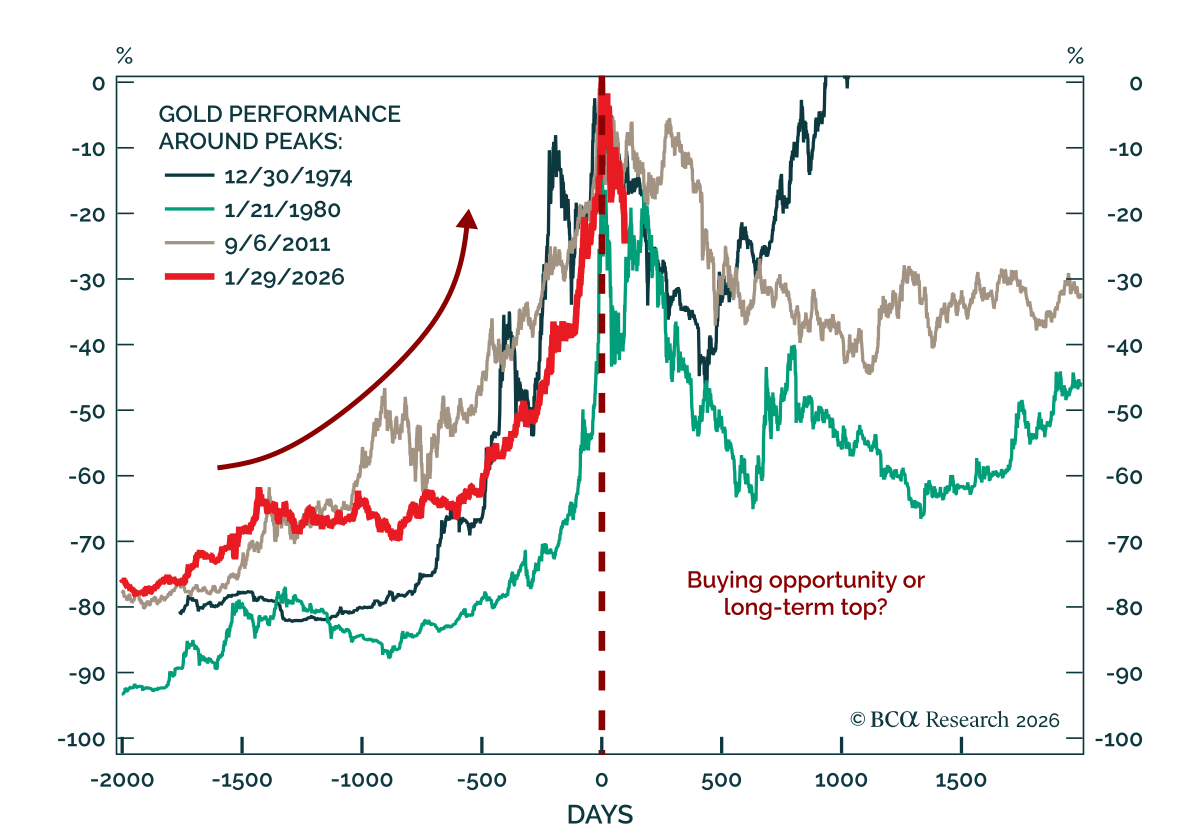
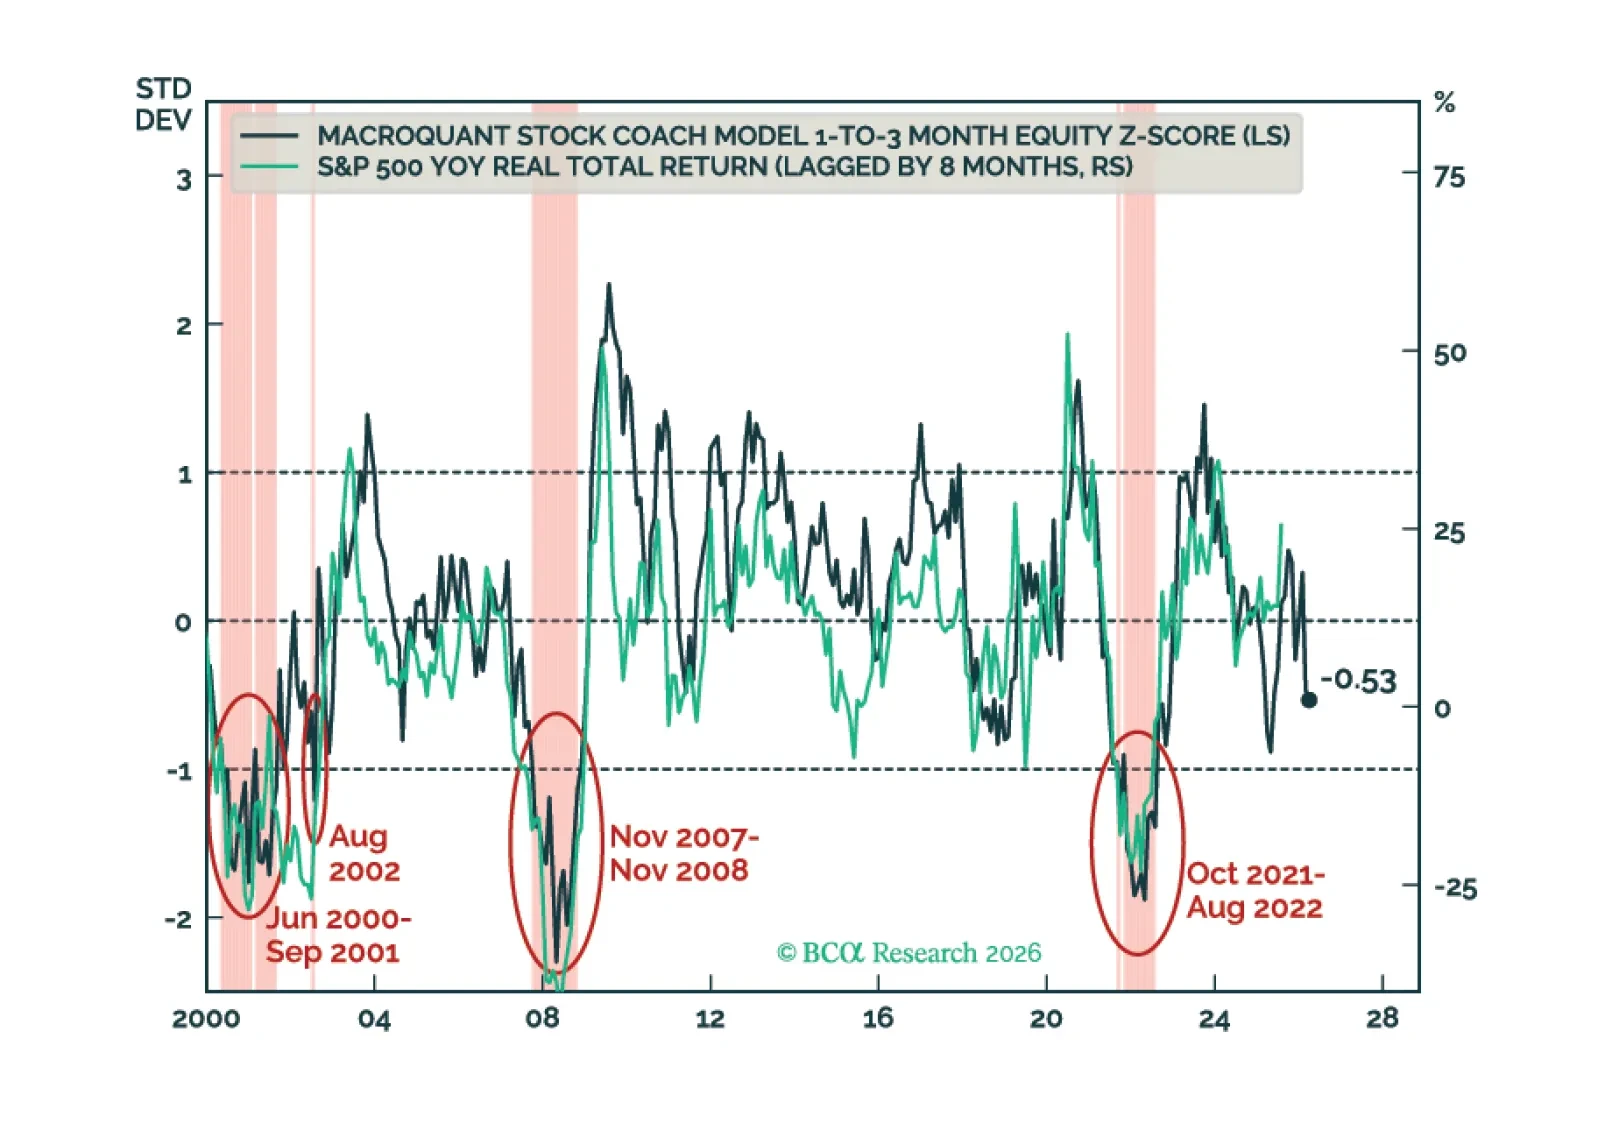
MacroQuant recommends an underweight position in equities, favors a below-benchmark duration stance in fixed-income portfolios, is neutral-to-slightly positive on the US dollar, remains neutral on gold, upgrades copper to neutral, and is very bullish on oil.