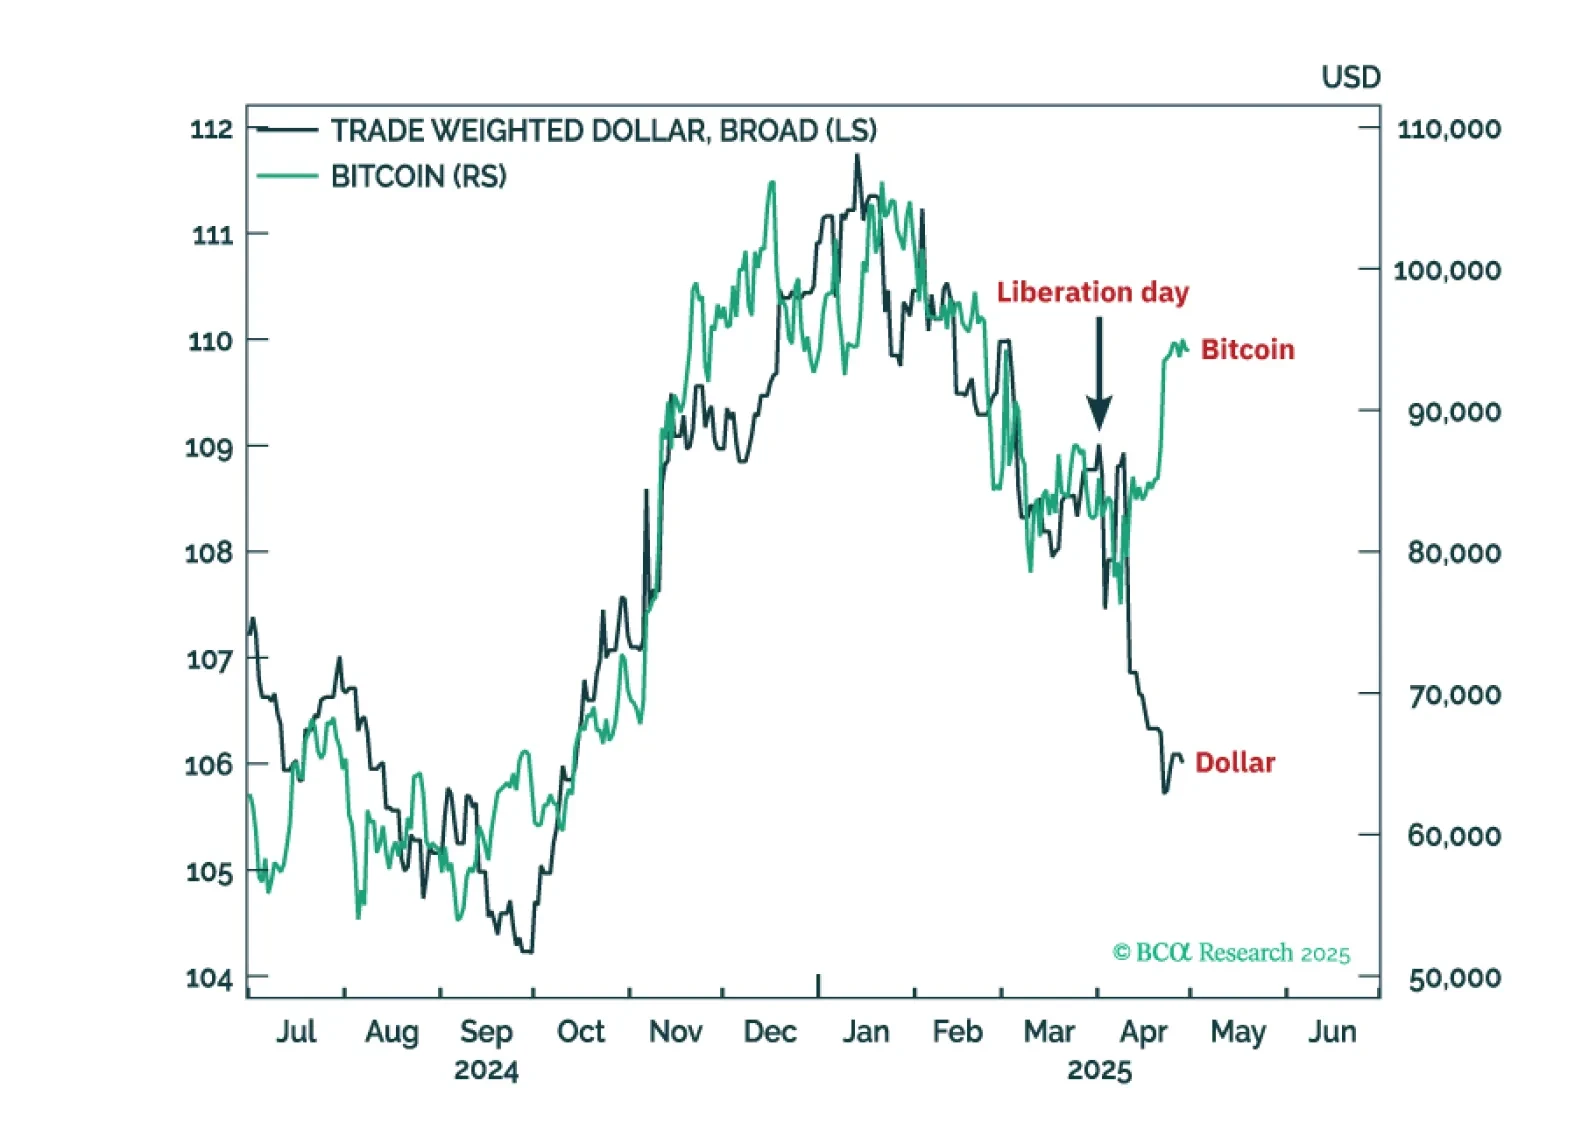
Latest from BCA Research
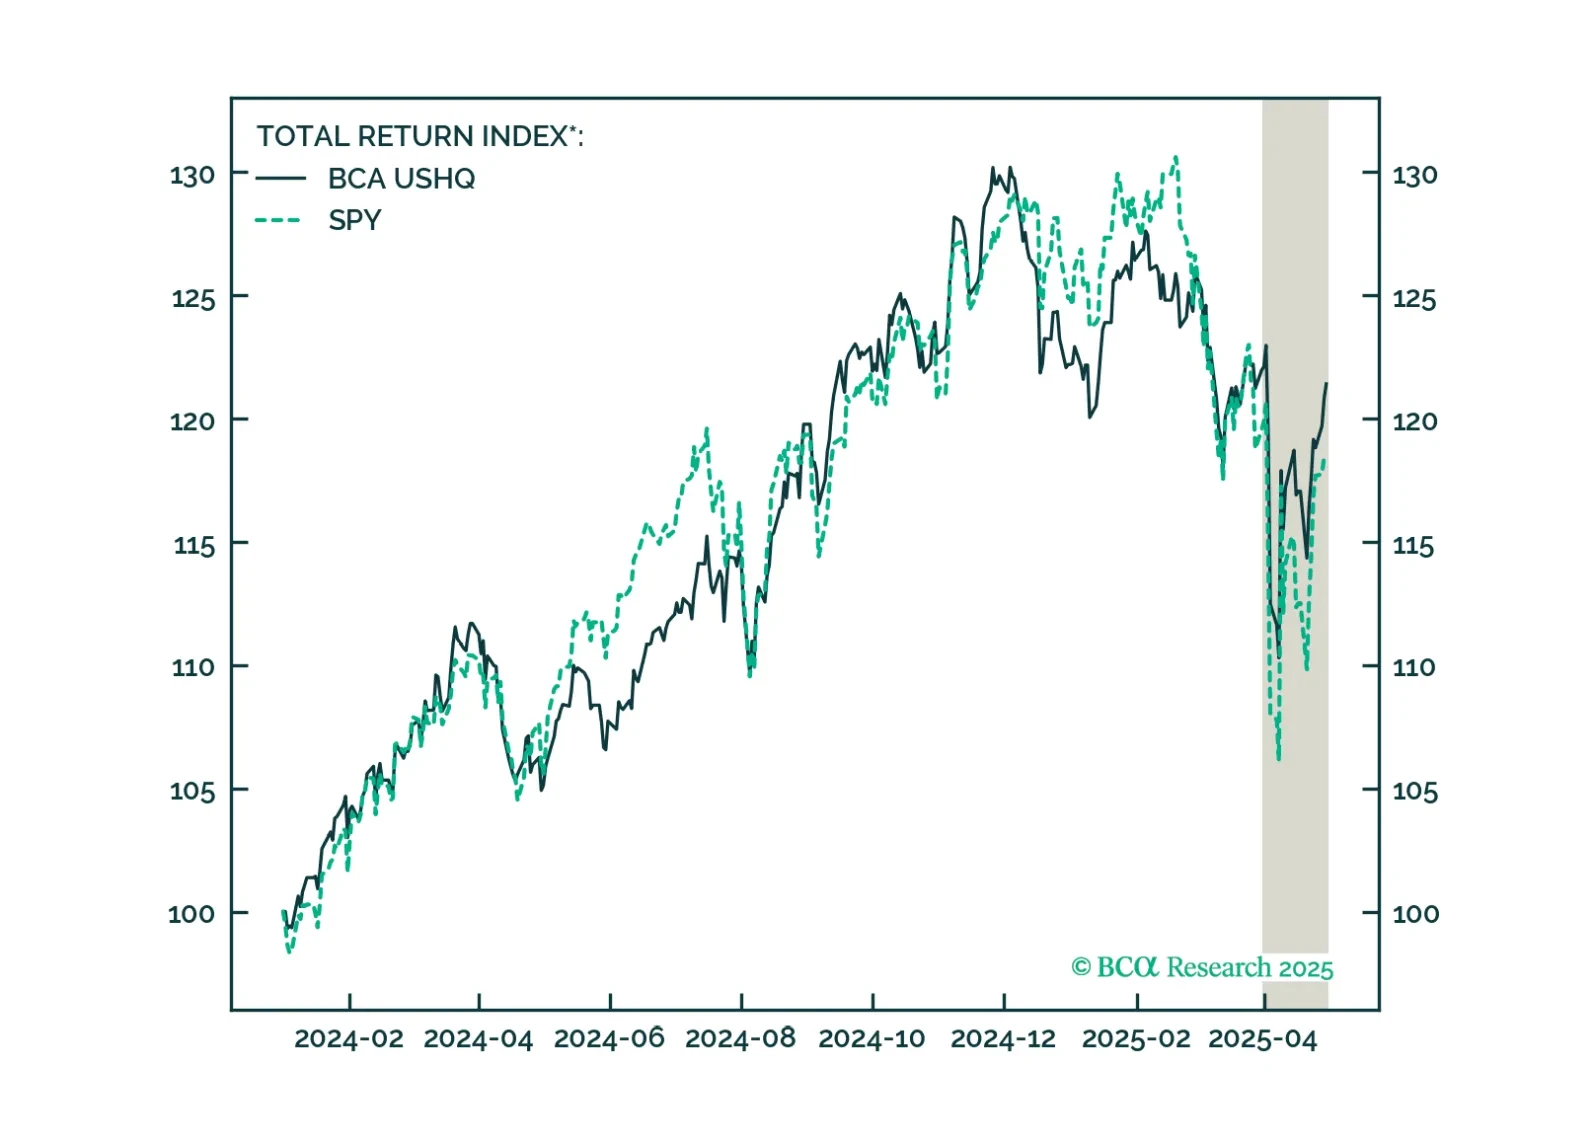
The US High Quality (USHQ) portfolio outperformed on the margin through April, returning -0.6%, whilst its SPY benchmark returned -1.2%. On a trailing three-month basis, performance remains robust vs. benchmark, with USHQ generating +230bps of excess return. Volatility and drawdown are lower too.

In the long run, Mexico will emerge as one of the biggest winners of US tariffs as the US diversifies supply chains away from China. In the medium term, however, a US growth slowdown and tariffs will push Mexico into recession. In EM portfolios, we remain overweight Mexican equities, domestic bonds, and sovereign credit. We are reiterating a buy on 10-year domestic bonds. Go long MXN versus CNH.
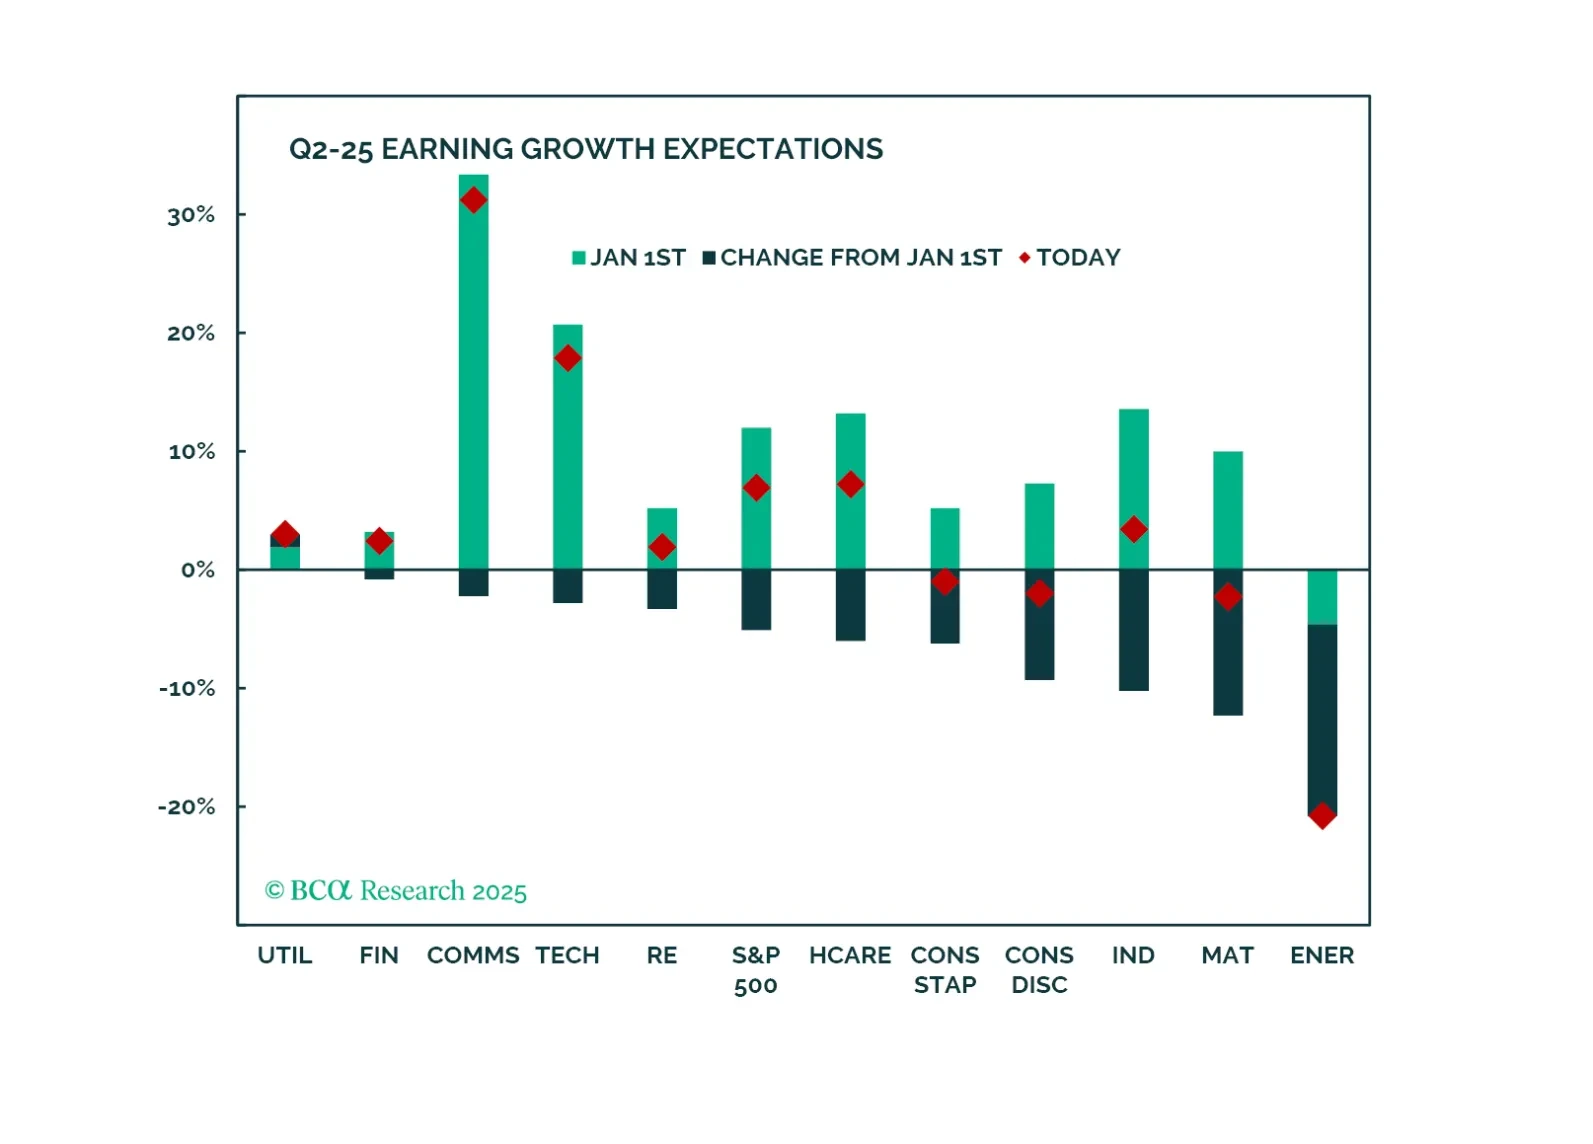
In the front section of the chart pack, we review April and YTD market performance, provide an update on the Q1 earnings season, examine the outlook for the Magnificent Seven, and adjust portfolio positioning.
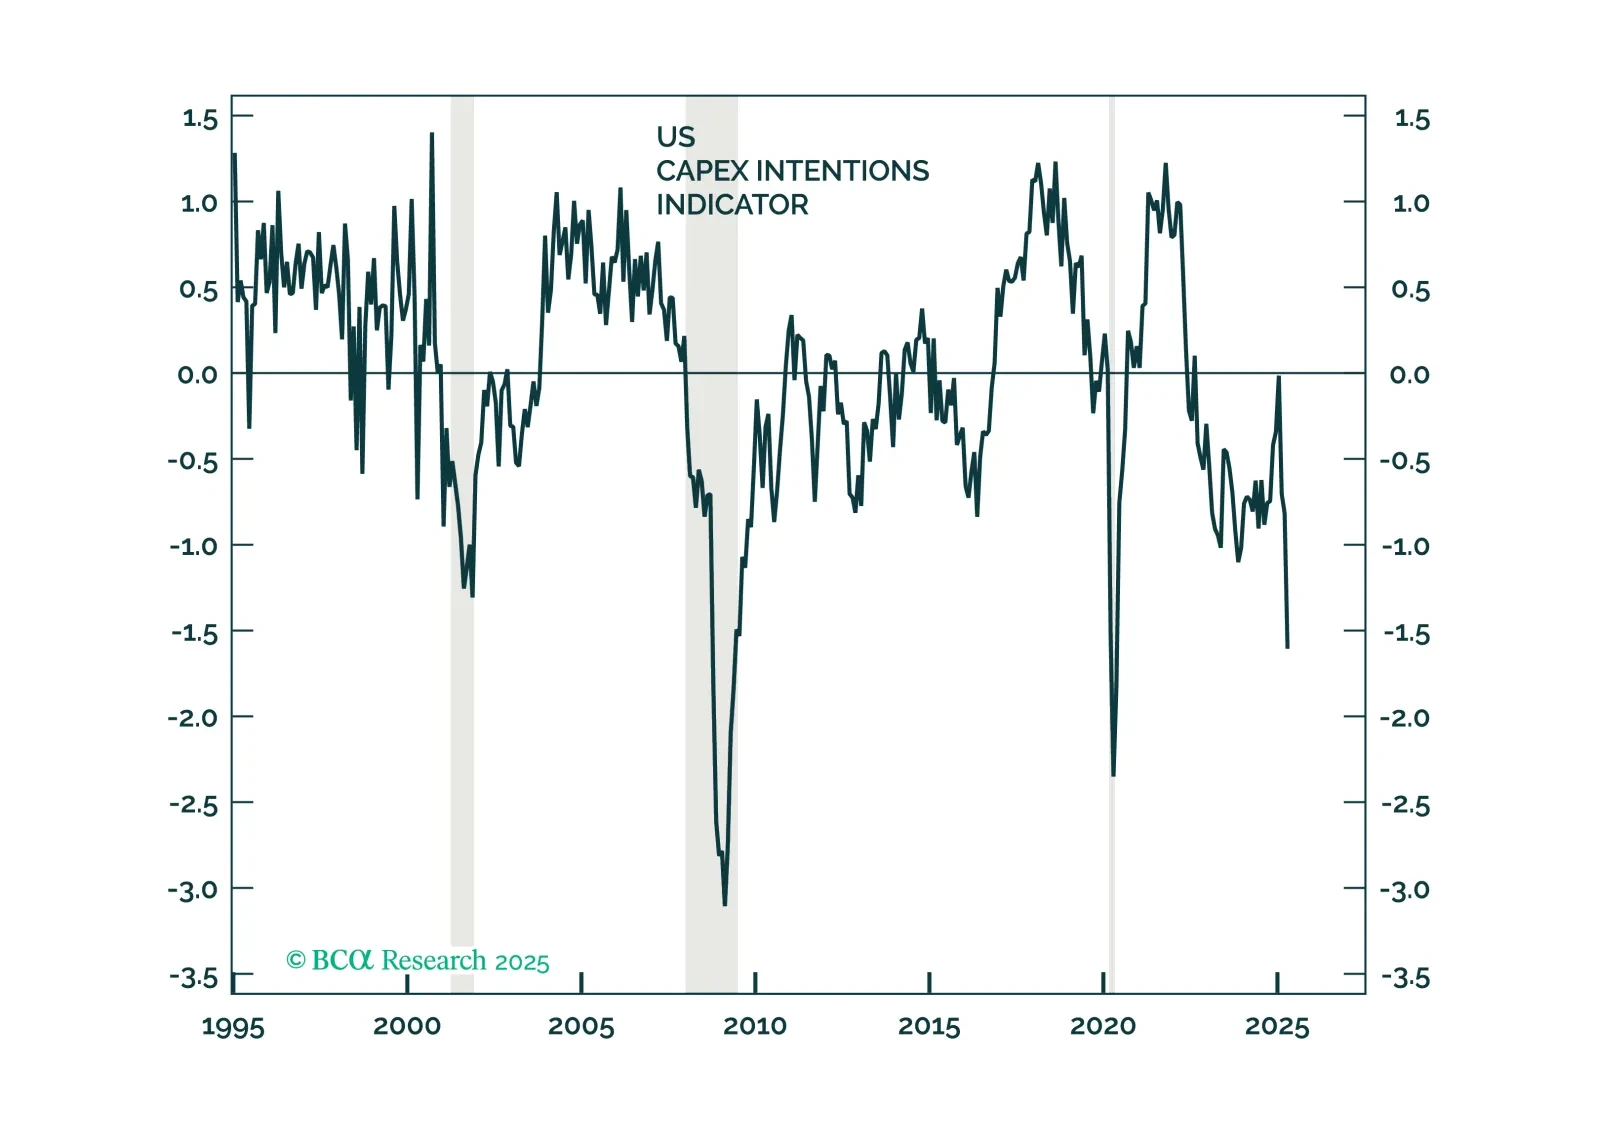
Hard aggregate macro data series remain solid, but surveys of businesses and consumers continue to worsen and the list of consumer-facing companies lowering earnings estimates gets longer by the week. We believe surging equities are ignoring the adverse effects of tariffs and reiterate our defensive asset allocation recommendations.

We apply our systematic approach to investing based on economic, inflation, and monetary policy surprises to the major global bond markets. The economic regimes defined by the current macro-surprises setup confirm our existing fixed-income portfolio tactical recommendations.
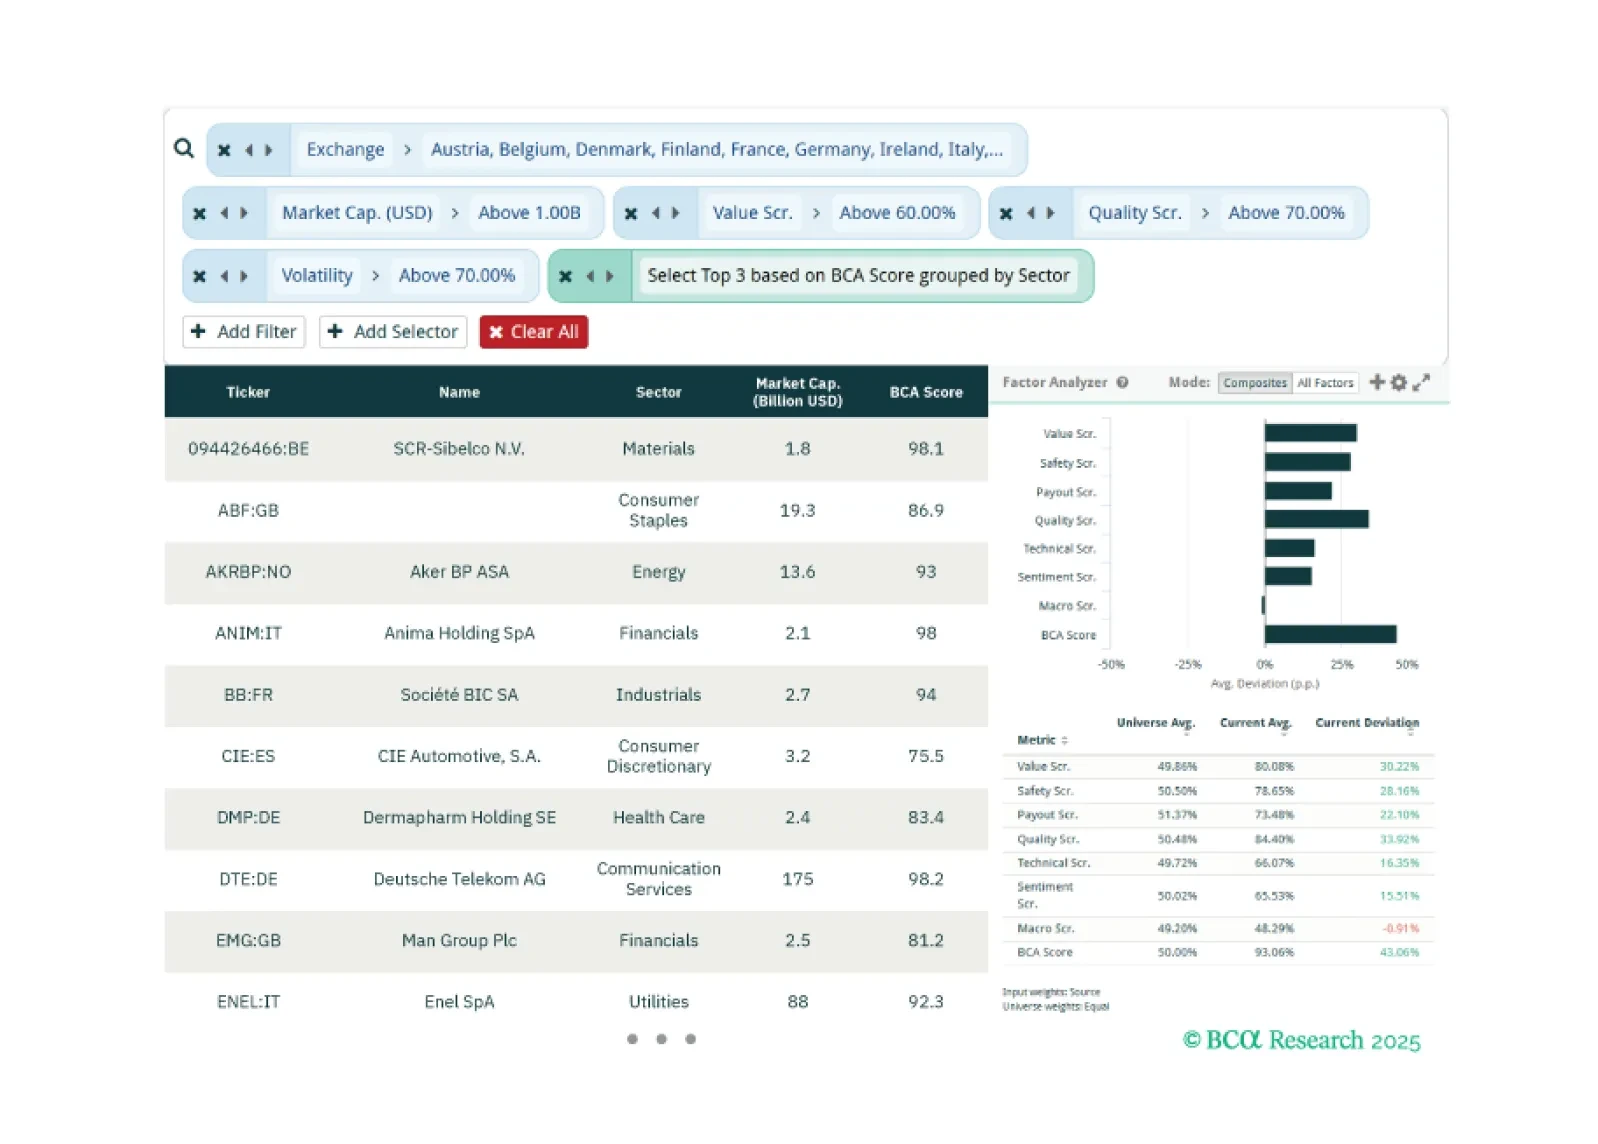
This week, our three screeners cover: Favoring European equities over US equities, cybersecurity stocks, and large caps with large moves in their BCA Score.
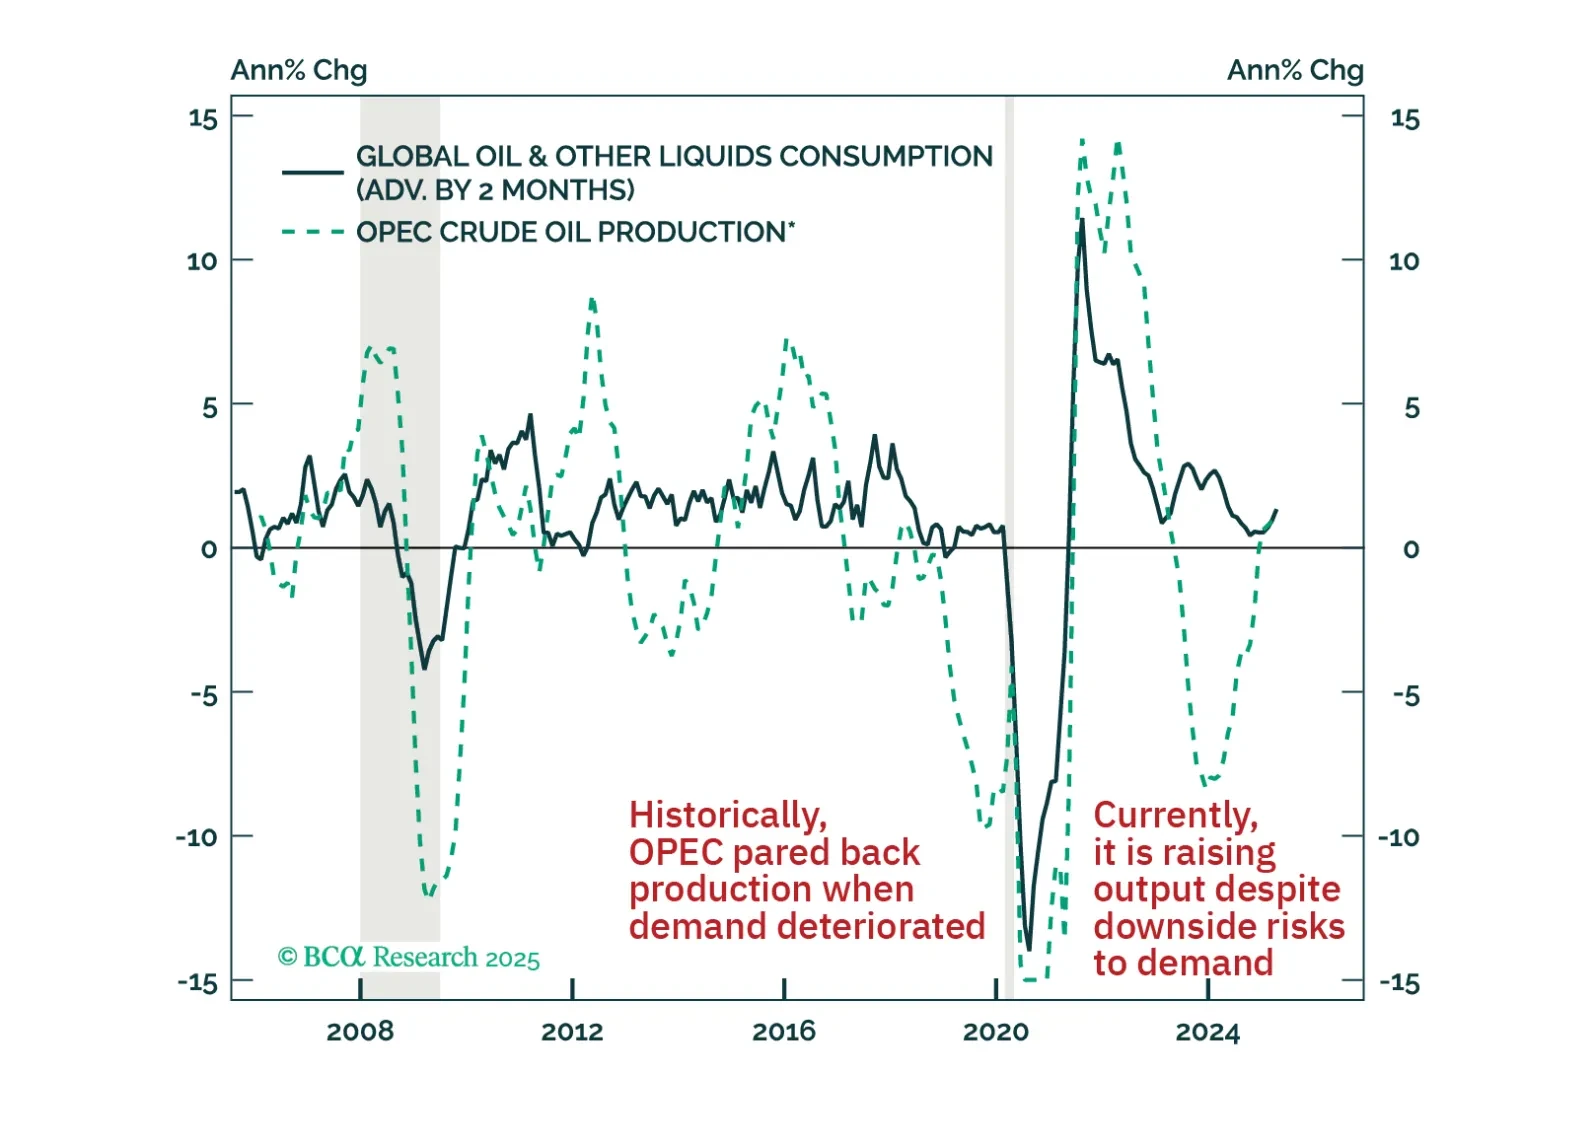
Oil has borne the brunt of the year-to-date deterioration in cyclically sensitive financial assets. It is a key underperformer both within the commodity space and among global risk assets. This underperformance underscores that in addition to the trade war-induced headwind to demand, bearish supply-side developments are also weighing down on crude prices. As we discuss in this report, these dynamics will likely continue exerting downside pressure on oil prices over the coming weeks and months.
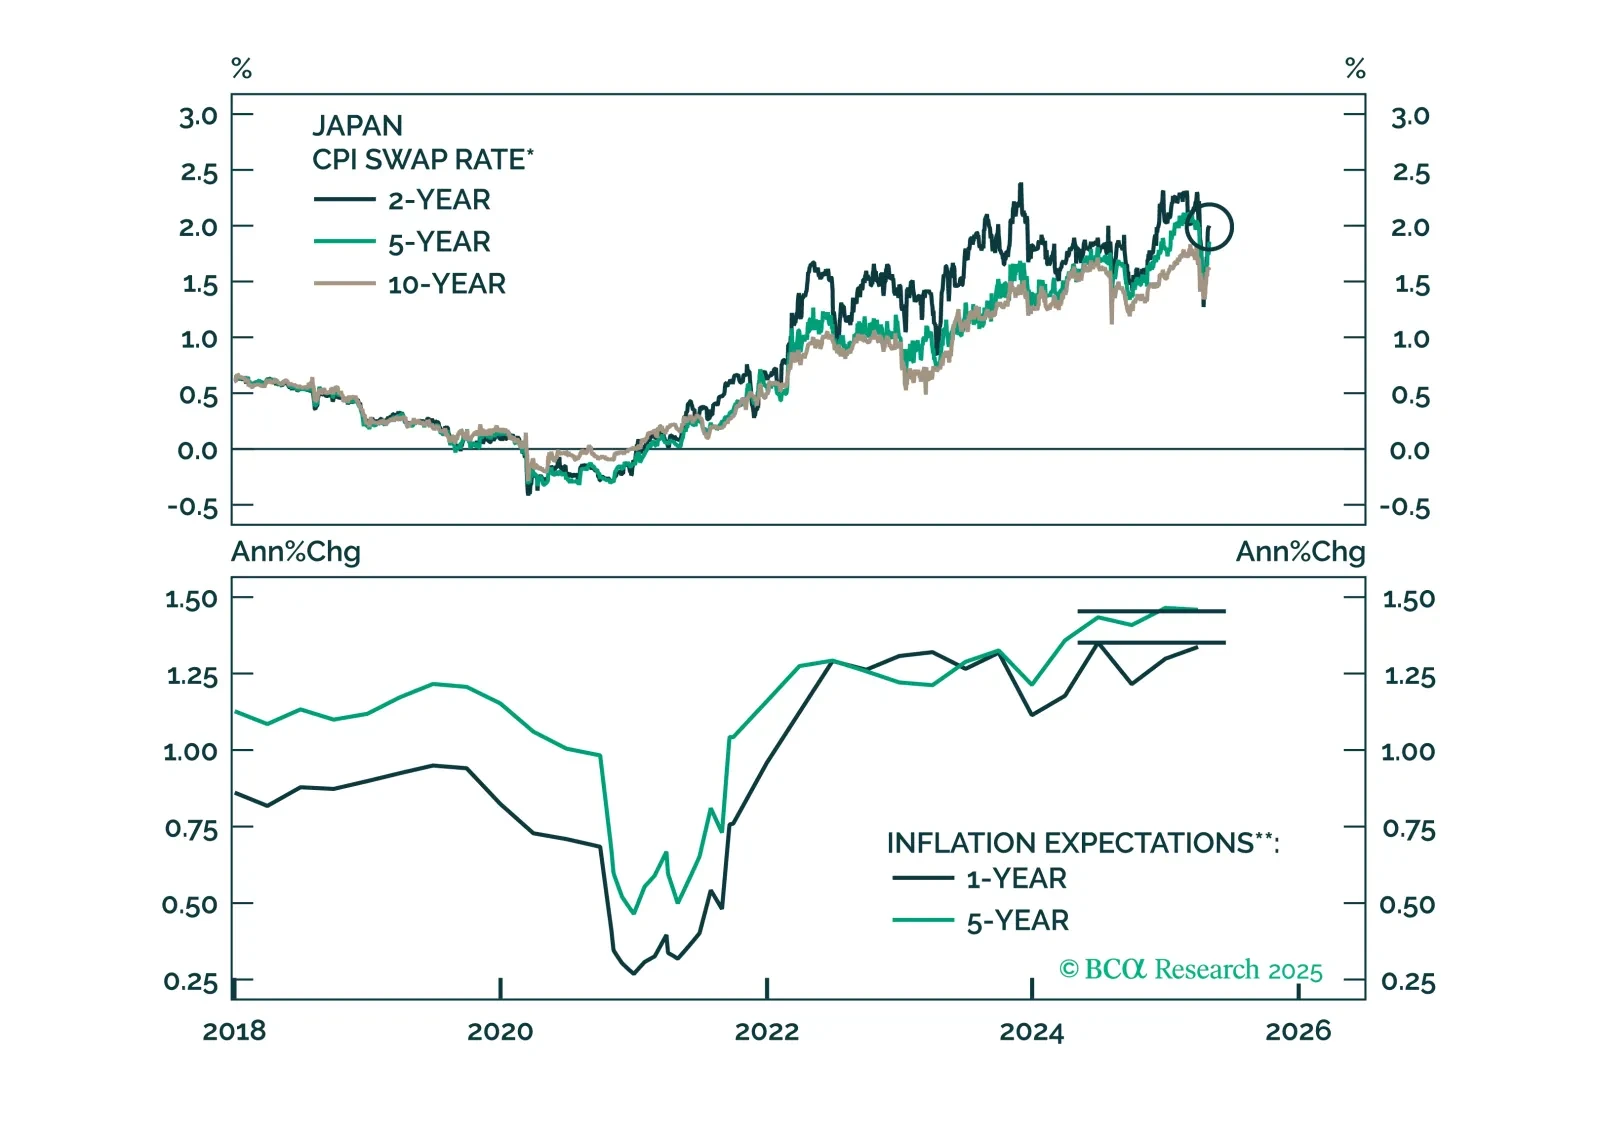
This week’s report looks at Japan, with the recent BoJ meeting. While a trade war has injected uncertainty into the Japanese economy, our conviction remains high that JGBs will underperform other government bond markets, and the yen will ultimately rally. That said, JPY is due for a tactical pullback.
This year’s corporate bond sell off has hit high-yield more than investment grade, and high-yield spreads have turned relatively more attractive as a result.