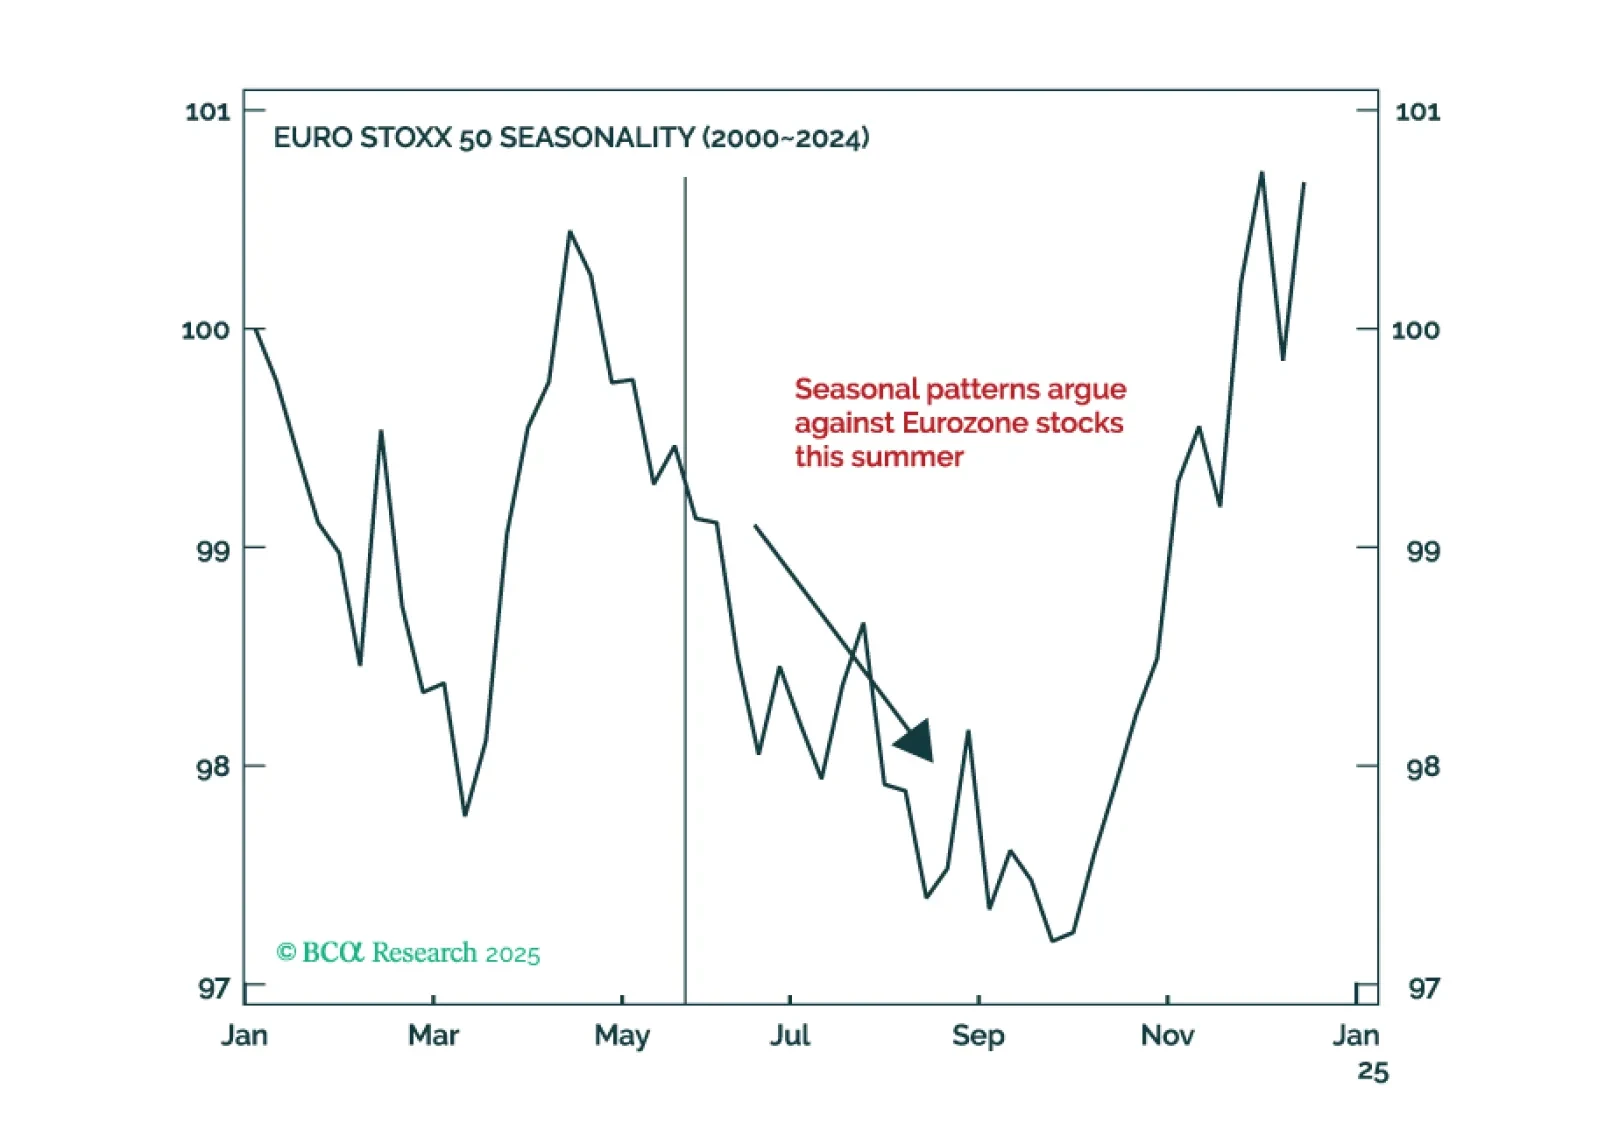
Latest from BCA Research
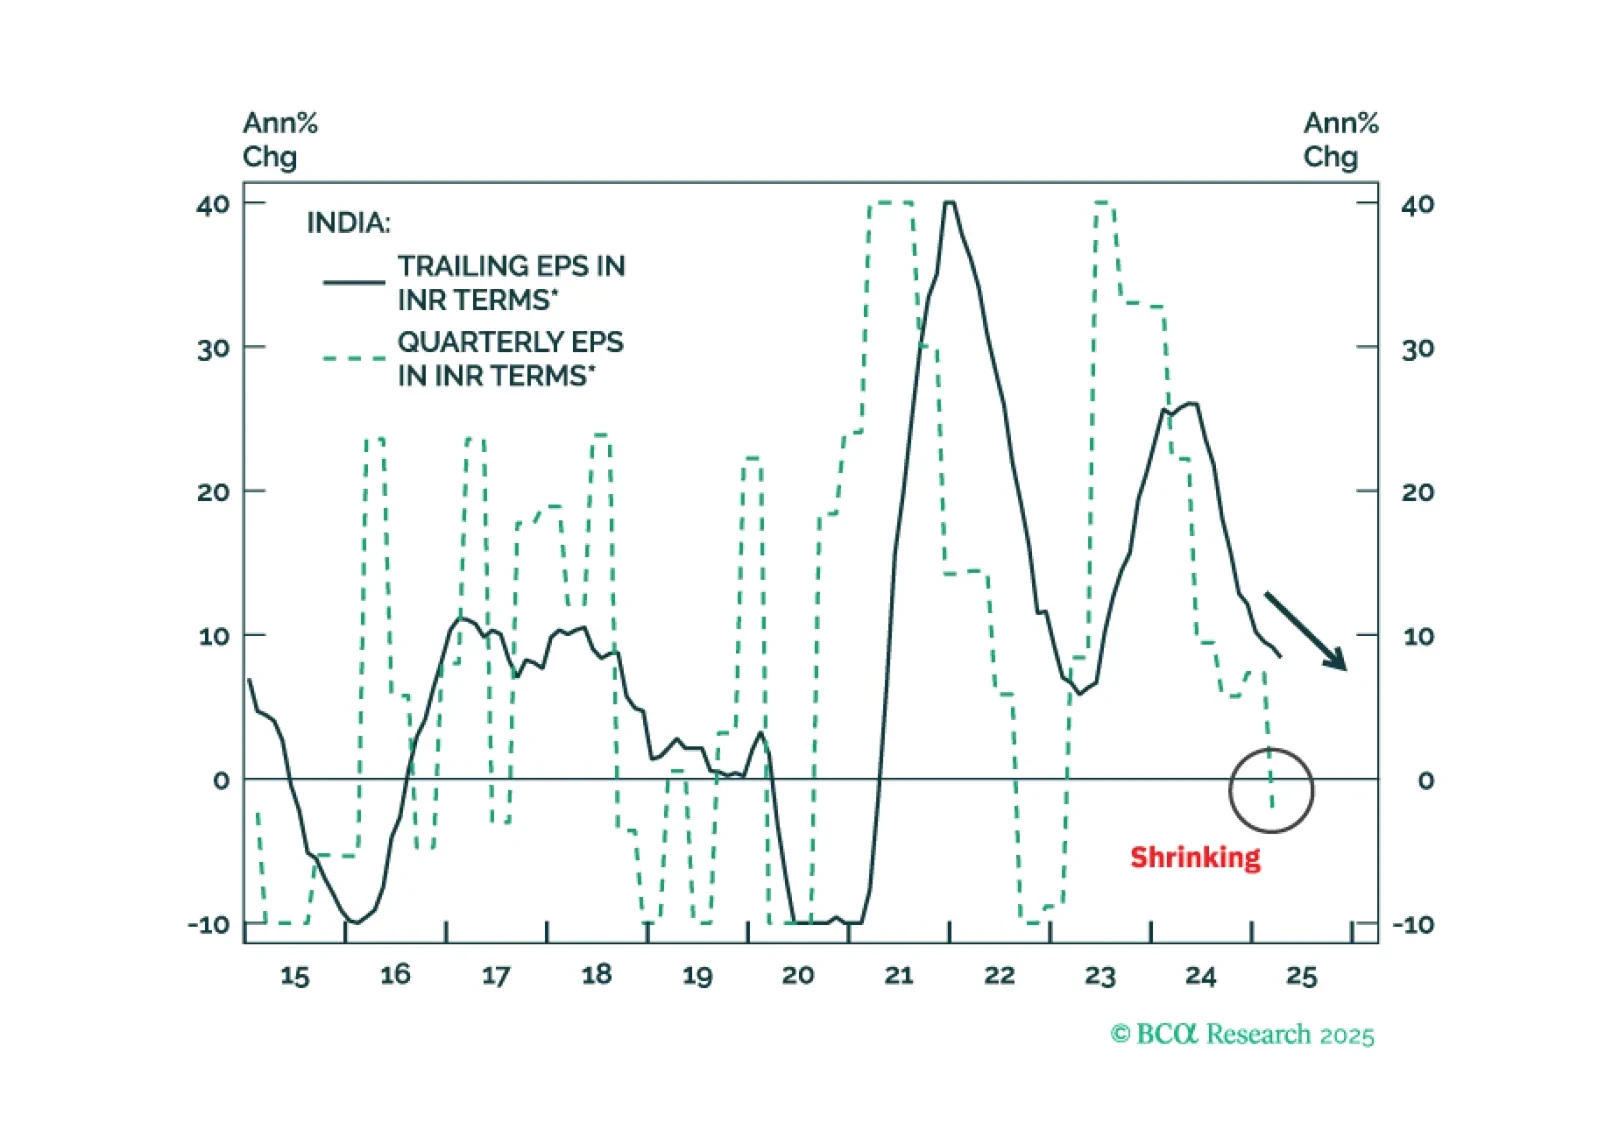
India's IT service exports have been booming and will continue to do so despite wider AI usage. Indian IT stocks, however, will not benefit from it as the expanding Global Capability Centers (GCCs) in India compete with the nation’s IT companies, driving the latter's profitability down.
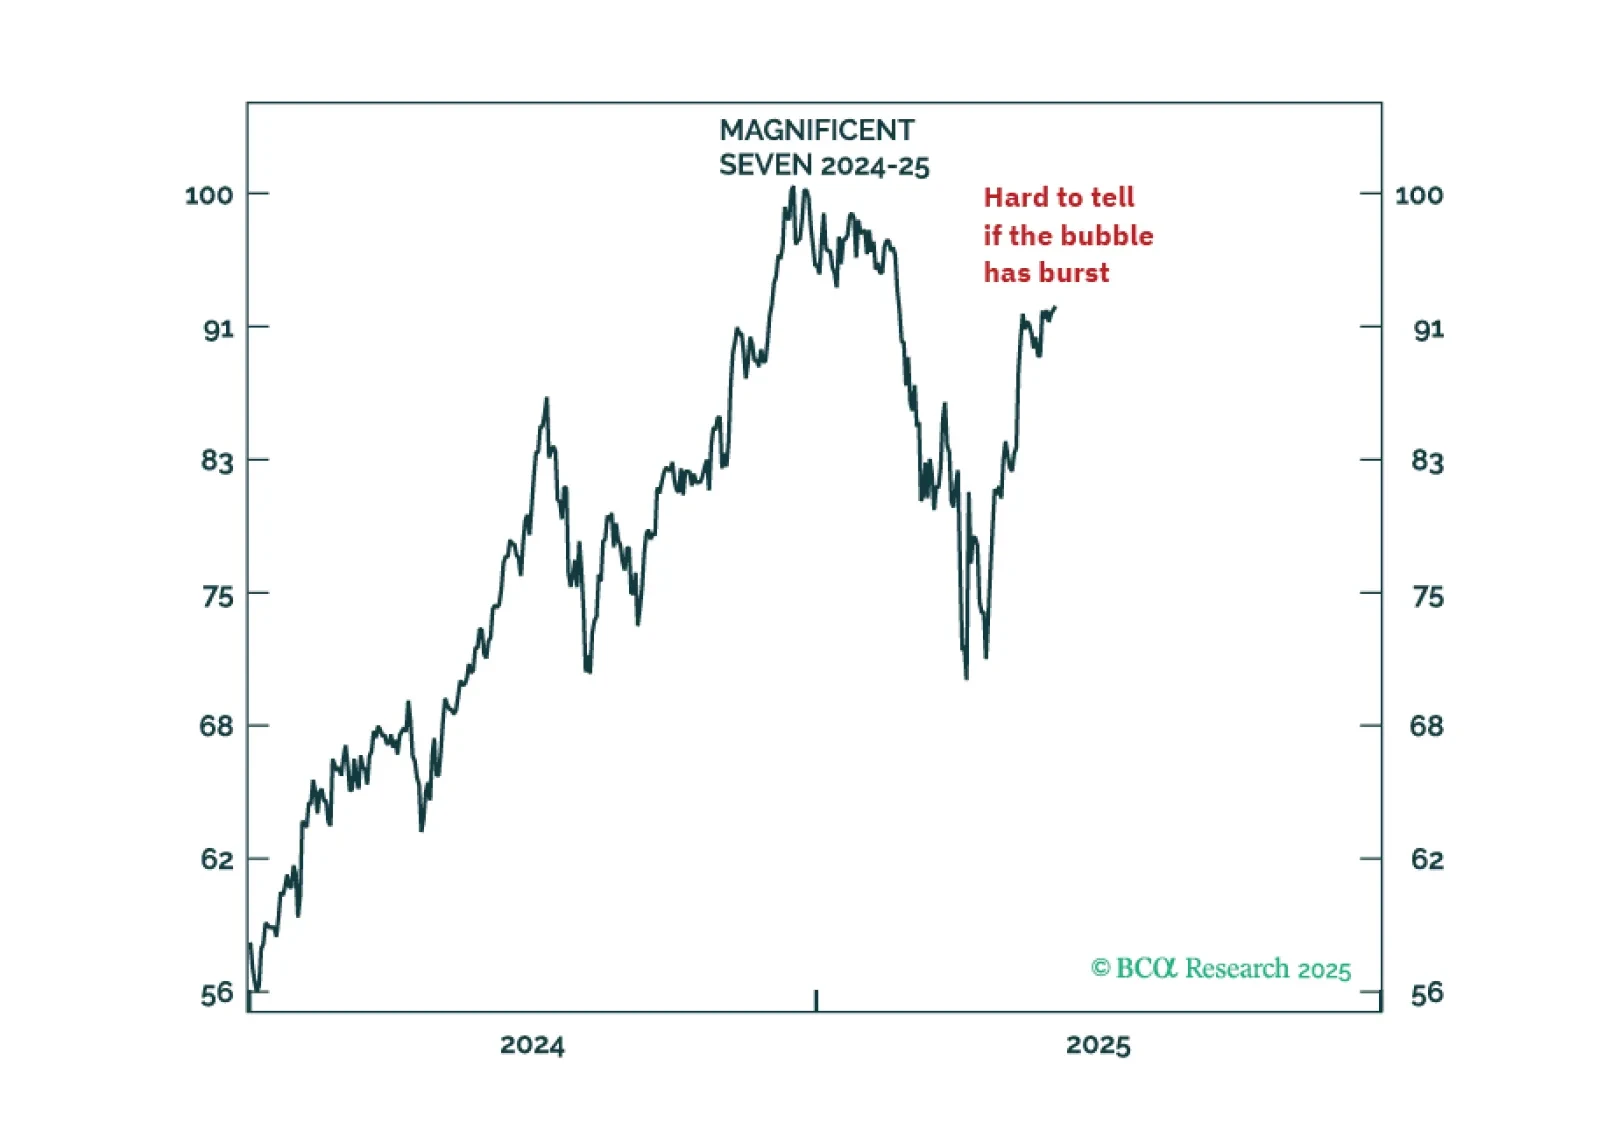
I am a structural disbeliever in the US superstar stocks because these winners of the previous technology, Web 2.0, are unlikely all to be the winners of the latest technology, AI. But I would suspend my disbelief if the Magnificent-7 index reaches a new high and the bursting AI-bubble configuration is broken. Plus, a new recommendation is to overweight Global Healthcare (IXJ).
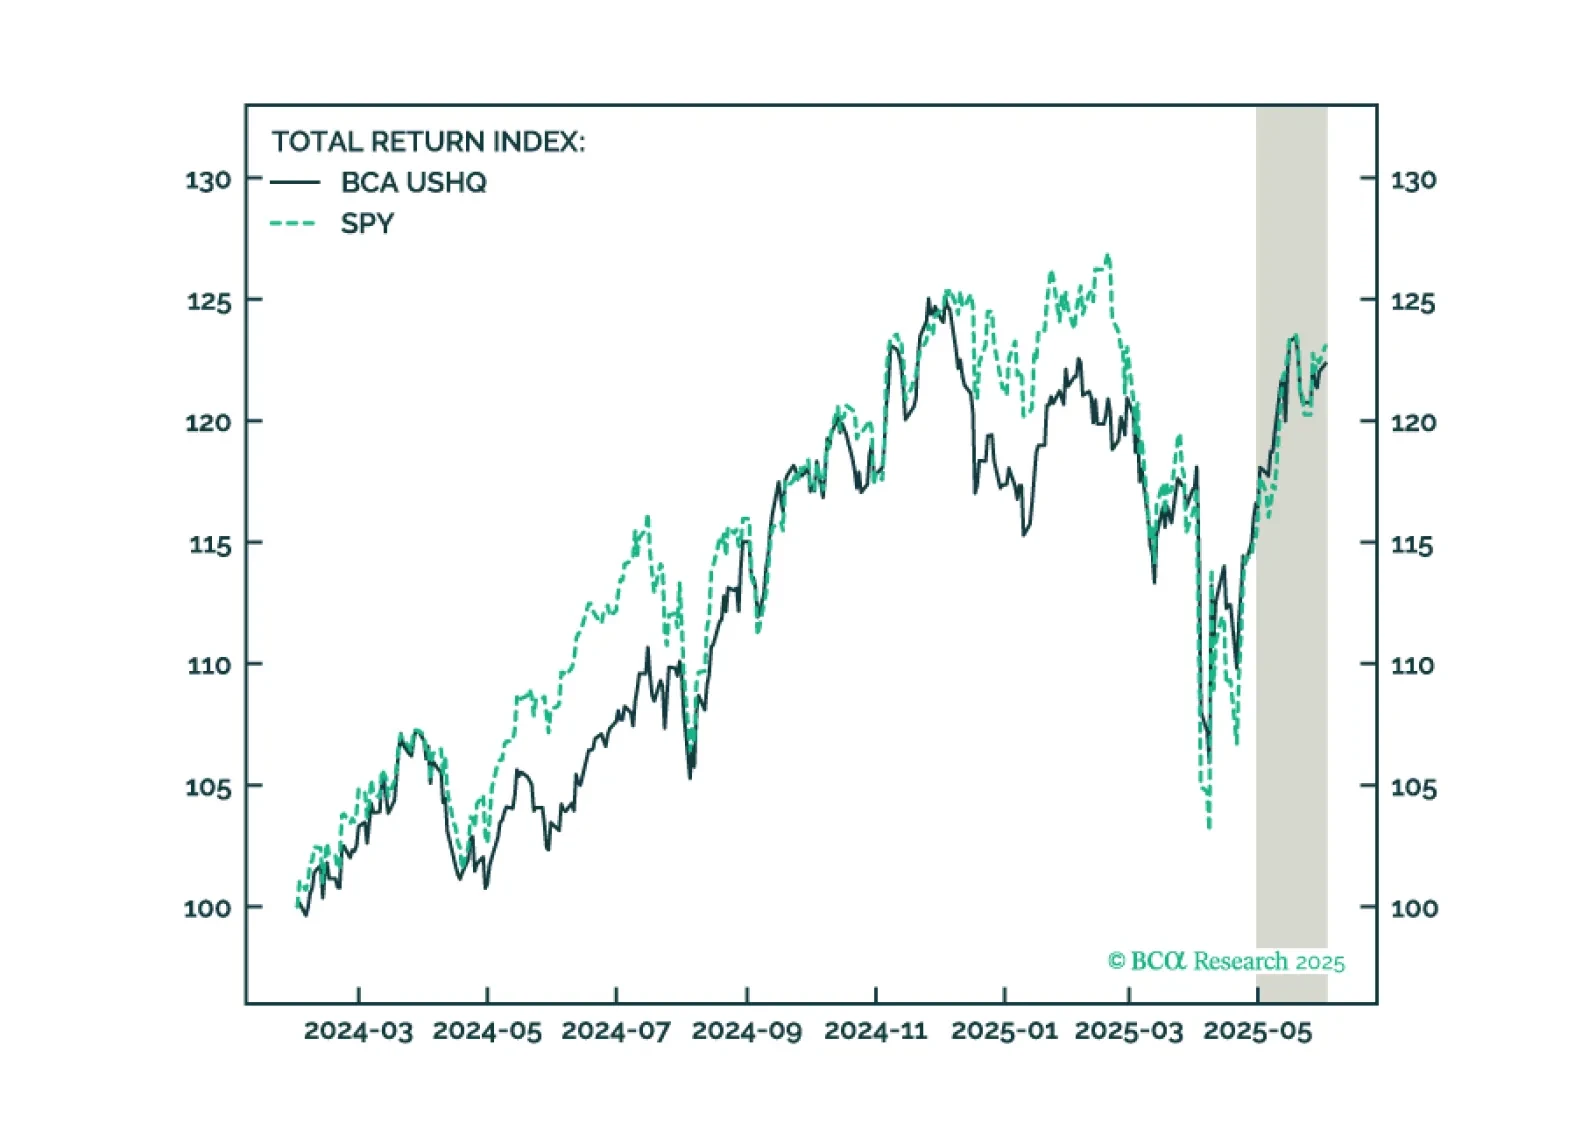
The US High Quality (USHQ) portfolio underperformed its benchmark through May, returning 5.1%, whilst its SPY benchmark returned 6.1%. On a trailing three-month basis, performance is also slightly weaker vs. benchmark, with USHQ underperforming by approx. 130bps. Notably, volatility and drawdown remain lower than the SPY, aiding risk-adjusted performance.

The Bank of Canada may be on hold for now, but deflationary risks are rising fast. Find out why rate cuts may come sooner than markets expect.
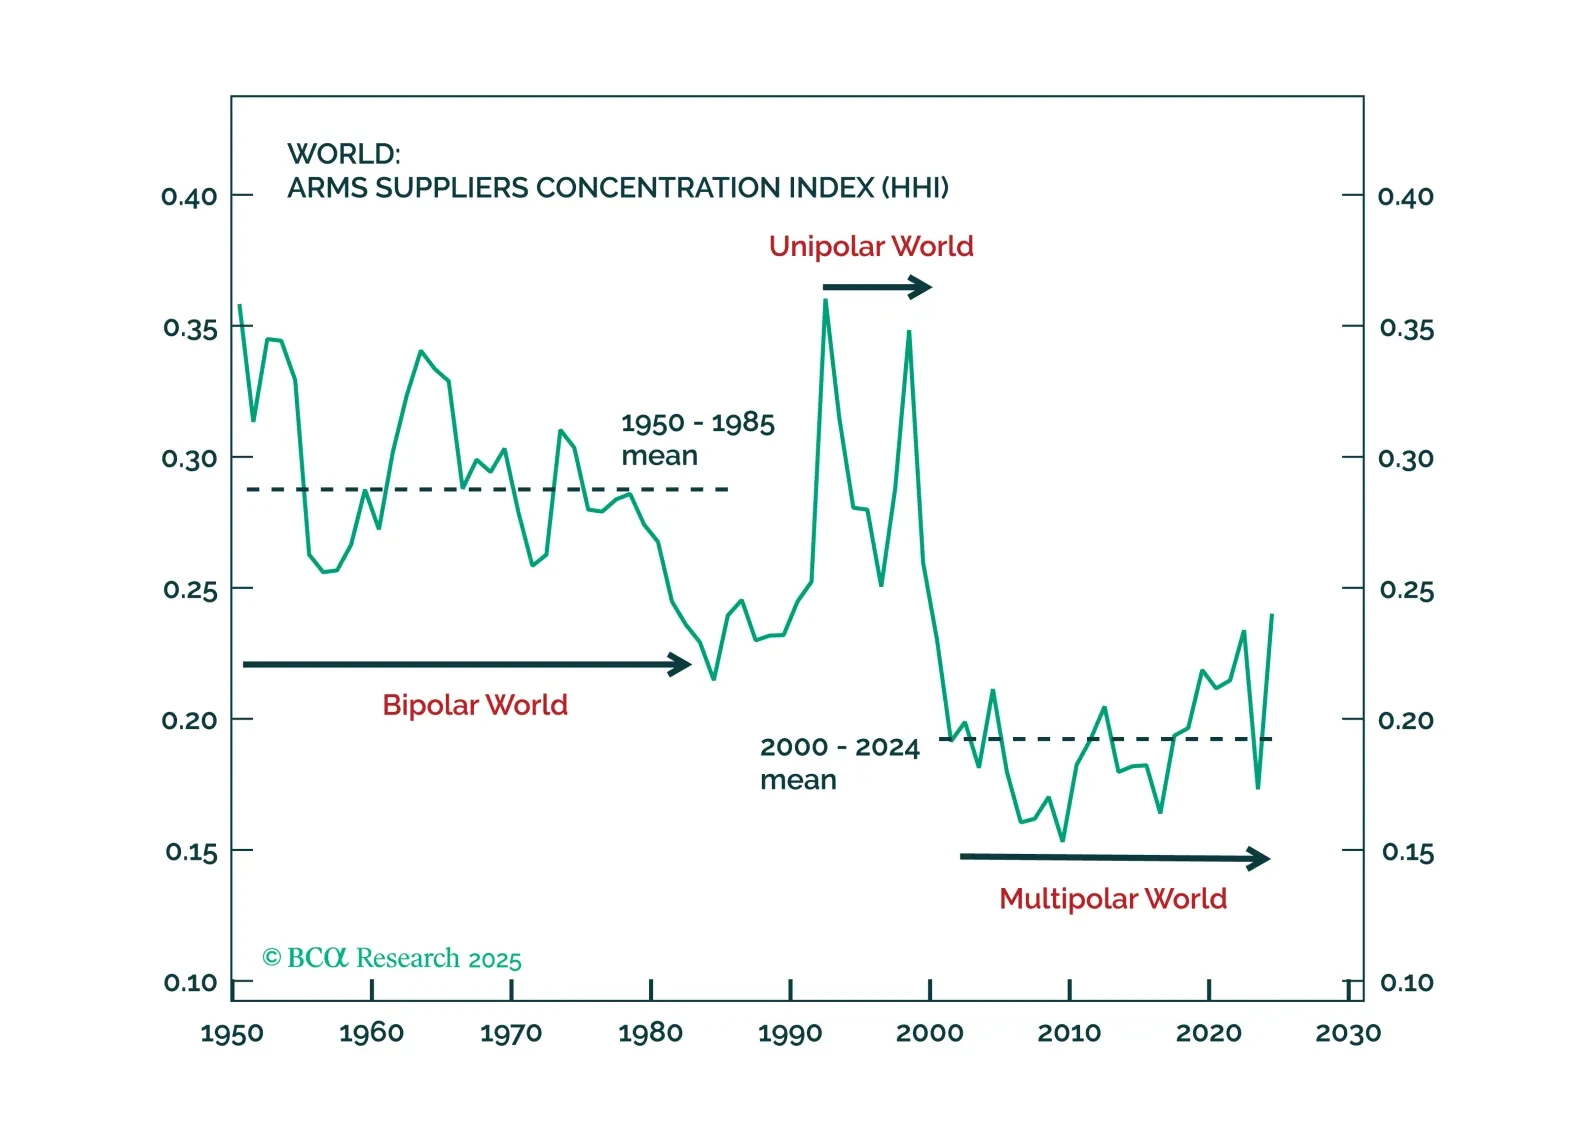
In our Beta report, we focus on our decade view. Many of our global allocator clients are scrambling to incorporate geopolitics into their strategic asset allocation. For most, this means thinking about war… or about future end-states. This is a mistake. We consider the next five years (maybe a decade) as the transition to the new era, a transition away from American unipolarity. And the transition itself is investment relevant. A transition to a multipolar world – which we think is occurring – will crush the USD and favor non-US assets. A transition to a bipolar world – not our base case, but still possible – would do the opposite.
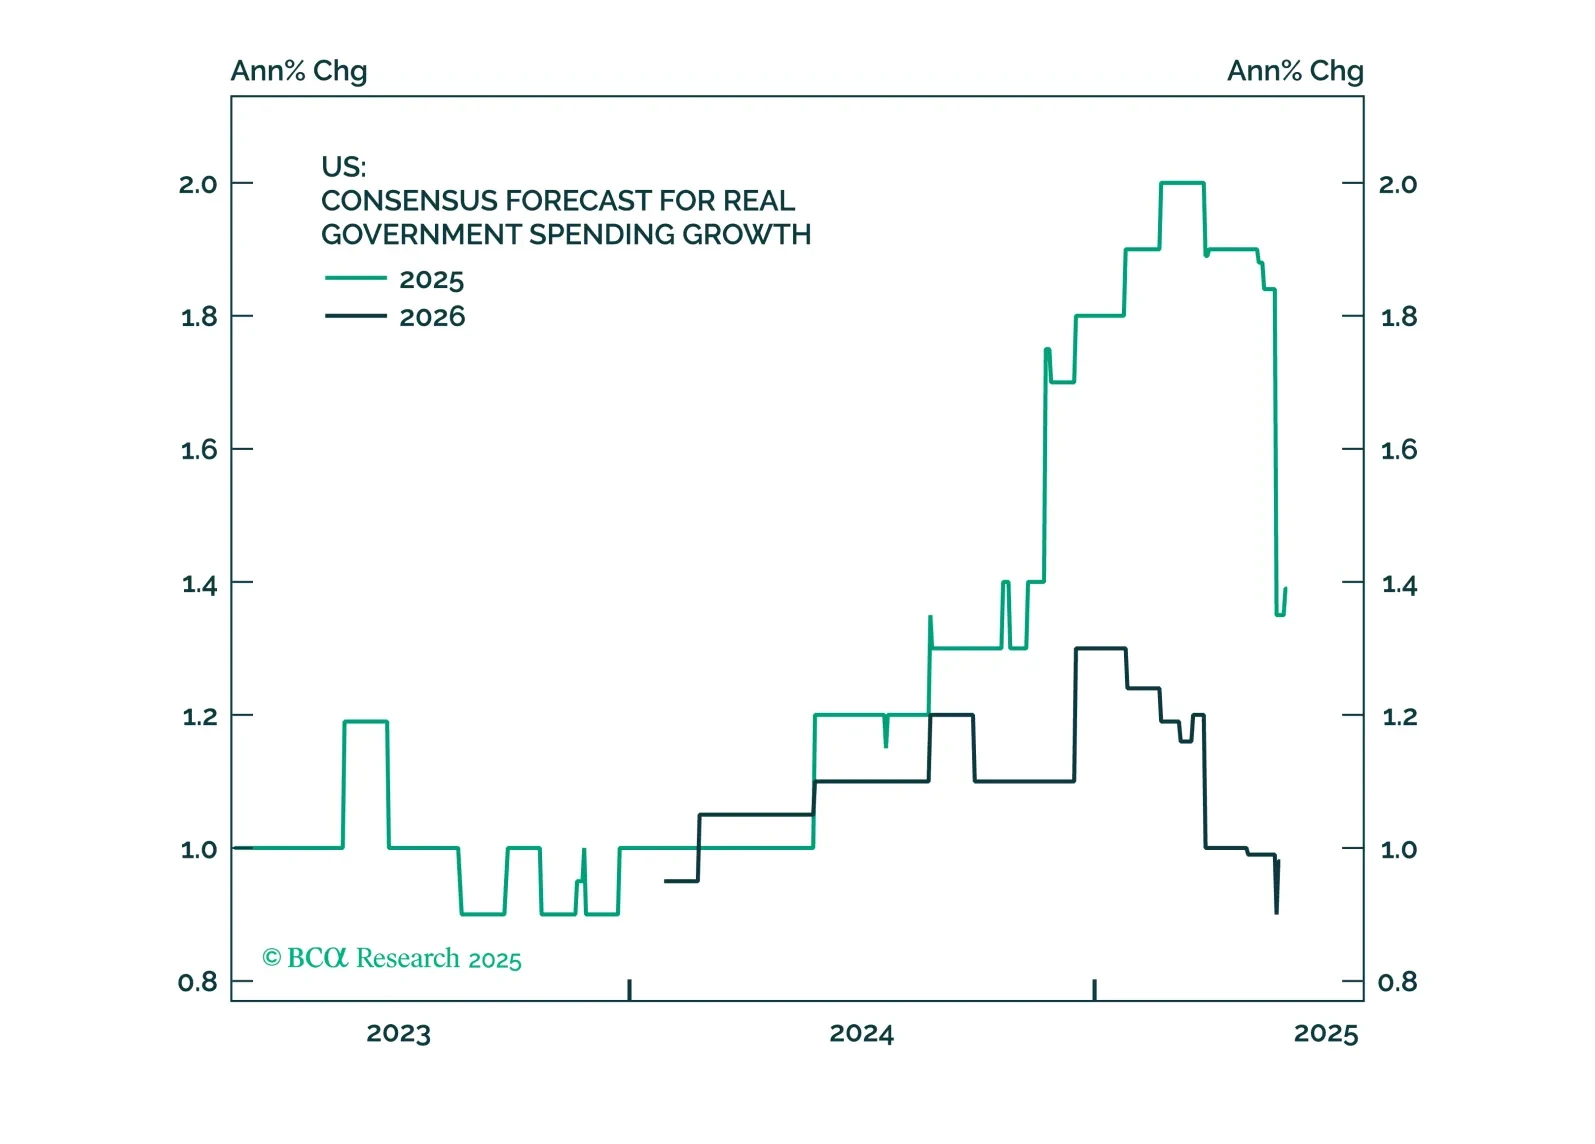
This month, we focus on the One Big Beautiful Bill Act (OBBBA). Our assessment in the Alpha report is that there won’t be any remaining alpha to harvest by shorting duration. The team that coined the “Human Steepener” moniker for President Trump is, effectively, throwing in the towel on looking for more upside to yields. There are many reasons for that view, but the main one is that the OBBBA legislation is just not that profligate, especially not relative to the investors’ expectations in the early days of the Trump 2.0 term.

In the front section of the chart pack, we review May’s performance and adjust our portfolio positioning.
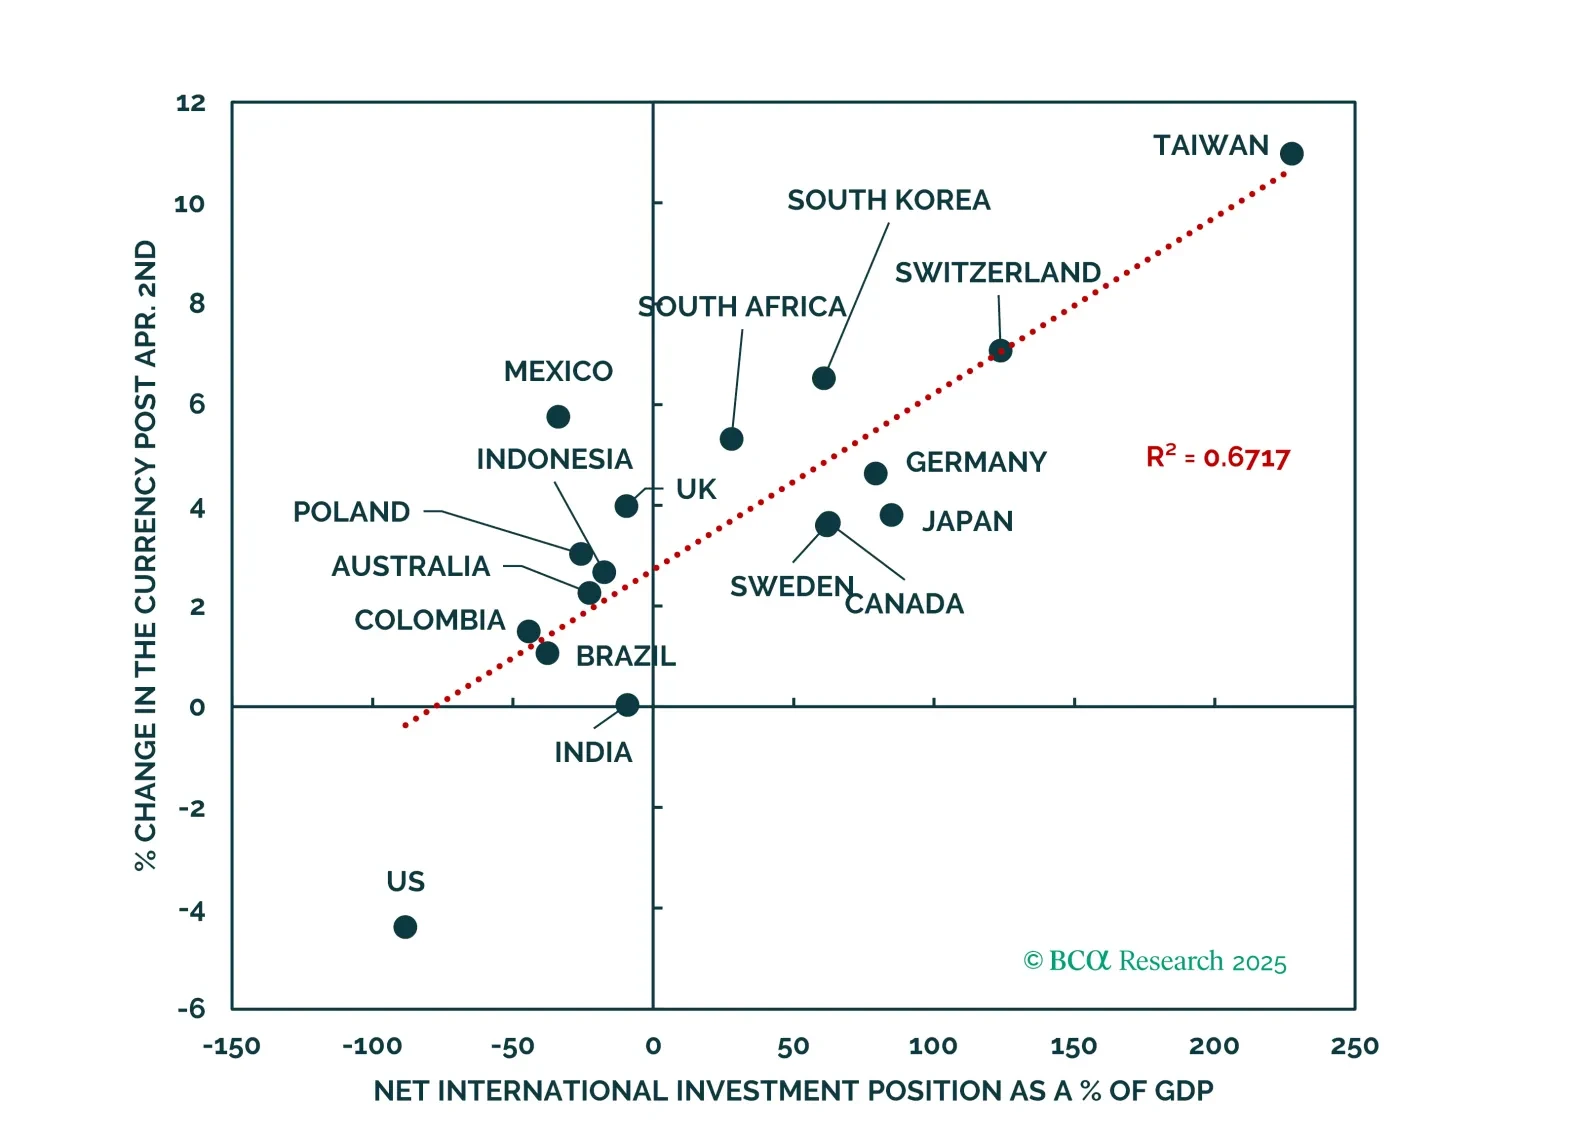
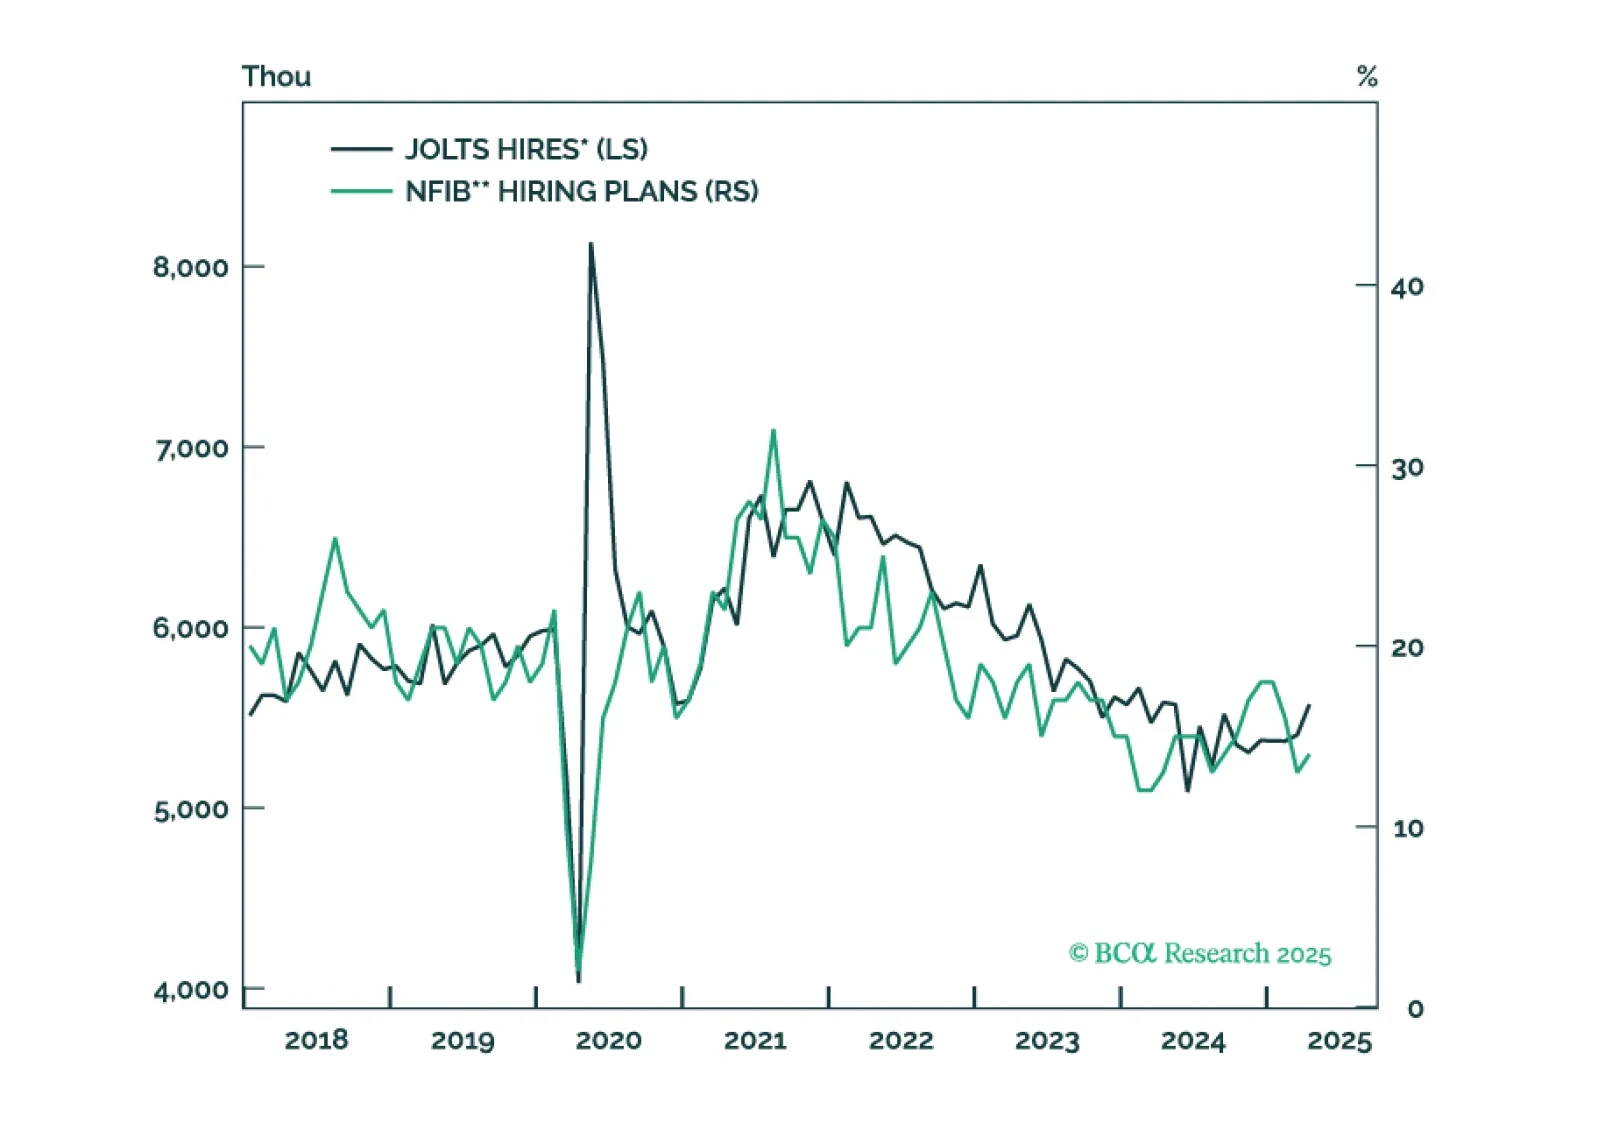
Fiscal policy, not tariffs, is now driving markets as Congress advances the One Big Beautiful Bill. The Senate cannot afford to remove the spending cuts in the bill, as they risk sparking a bond market riot. Even with this more modest bill, US interest rates are already pressuring housing and labor markets. US assets are also losing their defensive tilt. Better opportunities for both equity and fixed income investors are available internationally. We conserve our defensive stance but do not want to be dogmatic. Sentiment is more cautious than last year, and the US economy is not showing signs of imminent collapse. We remain underweight the US dollar and US equities. Upgrade Communication Services and downgrade Consumer Staples. Upgrade the CNY and EM currencies to neutral.