Latest from BCA Research
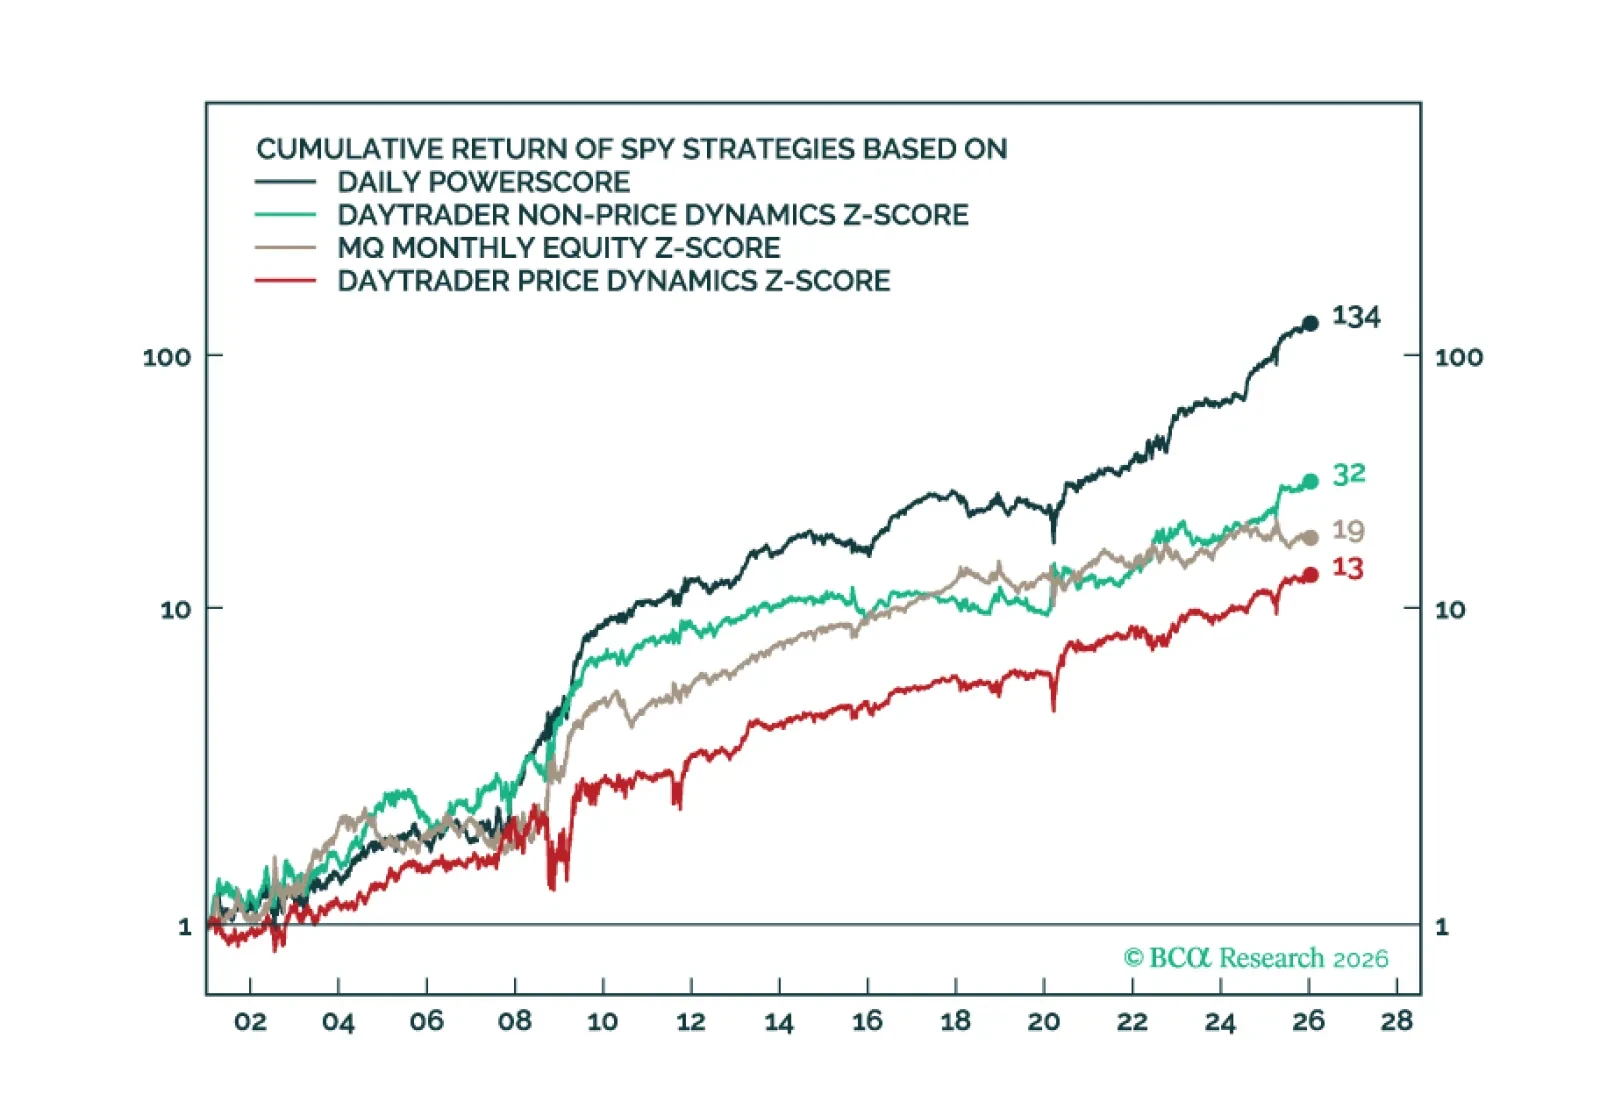
Over the past few months, we have been deploying new market-timing tools aimed at improving the accuracy of our calls. Today’s report highlights our ultra high-frequency Daily Oscillators, which provide daily signals on the near-term direction of the S&P 500 and long-term Treasuries.
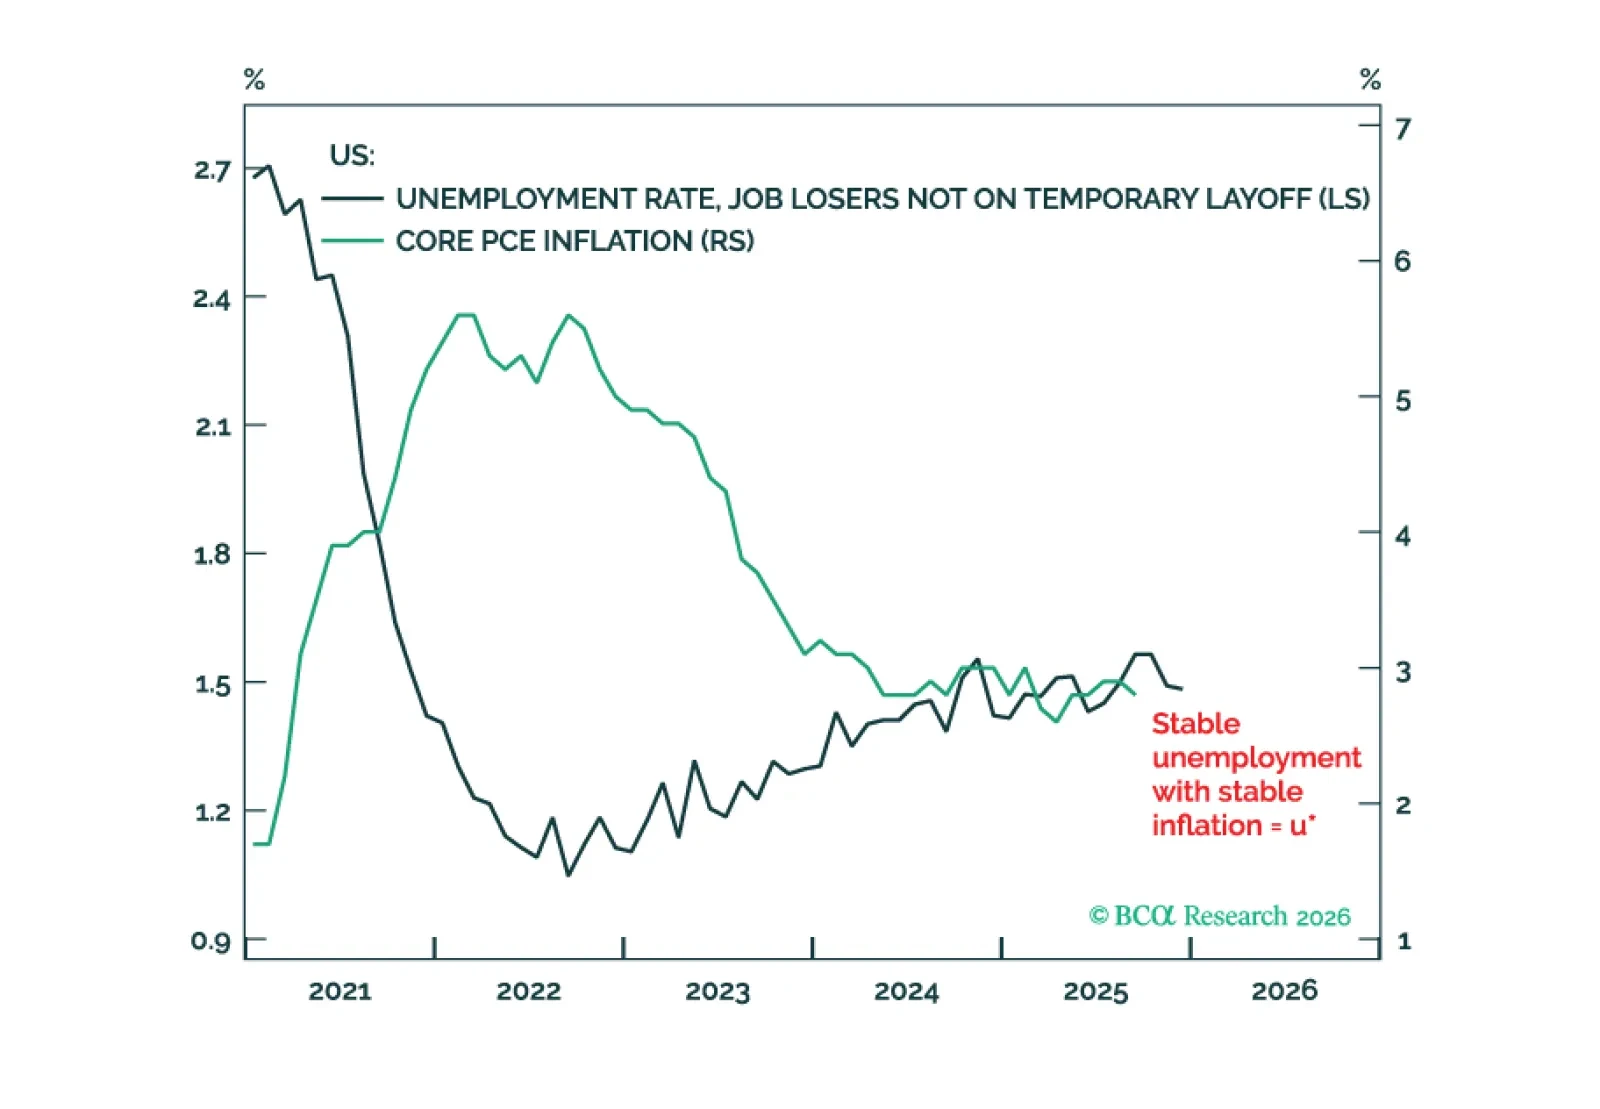
With the US unemployment rate and interest rate close to the ‘neutral’ u-star and r-star respectively, further Fed rate cuts risk pushing up inflation and long-term inflation expectations. This is bad for bonds but good for stocks. Plus, two new trades are: short TOPIX versus DAX; and short CAT versus SPX.

This morning’s CPI report signals that the worst of the tariff impact on inflation may already be in the rearview mirror.
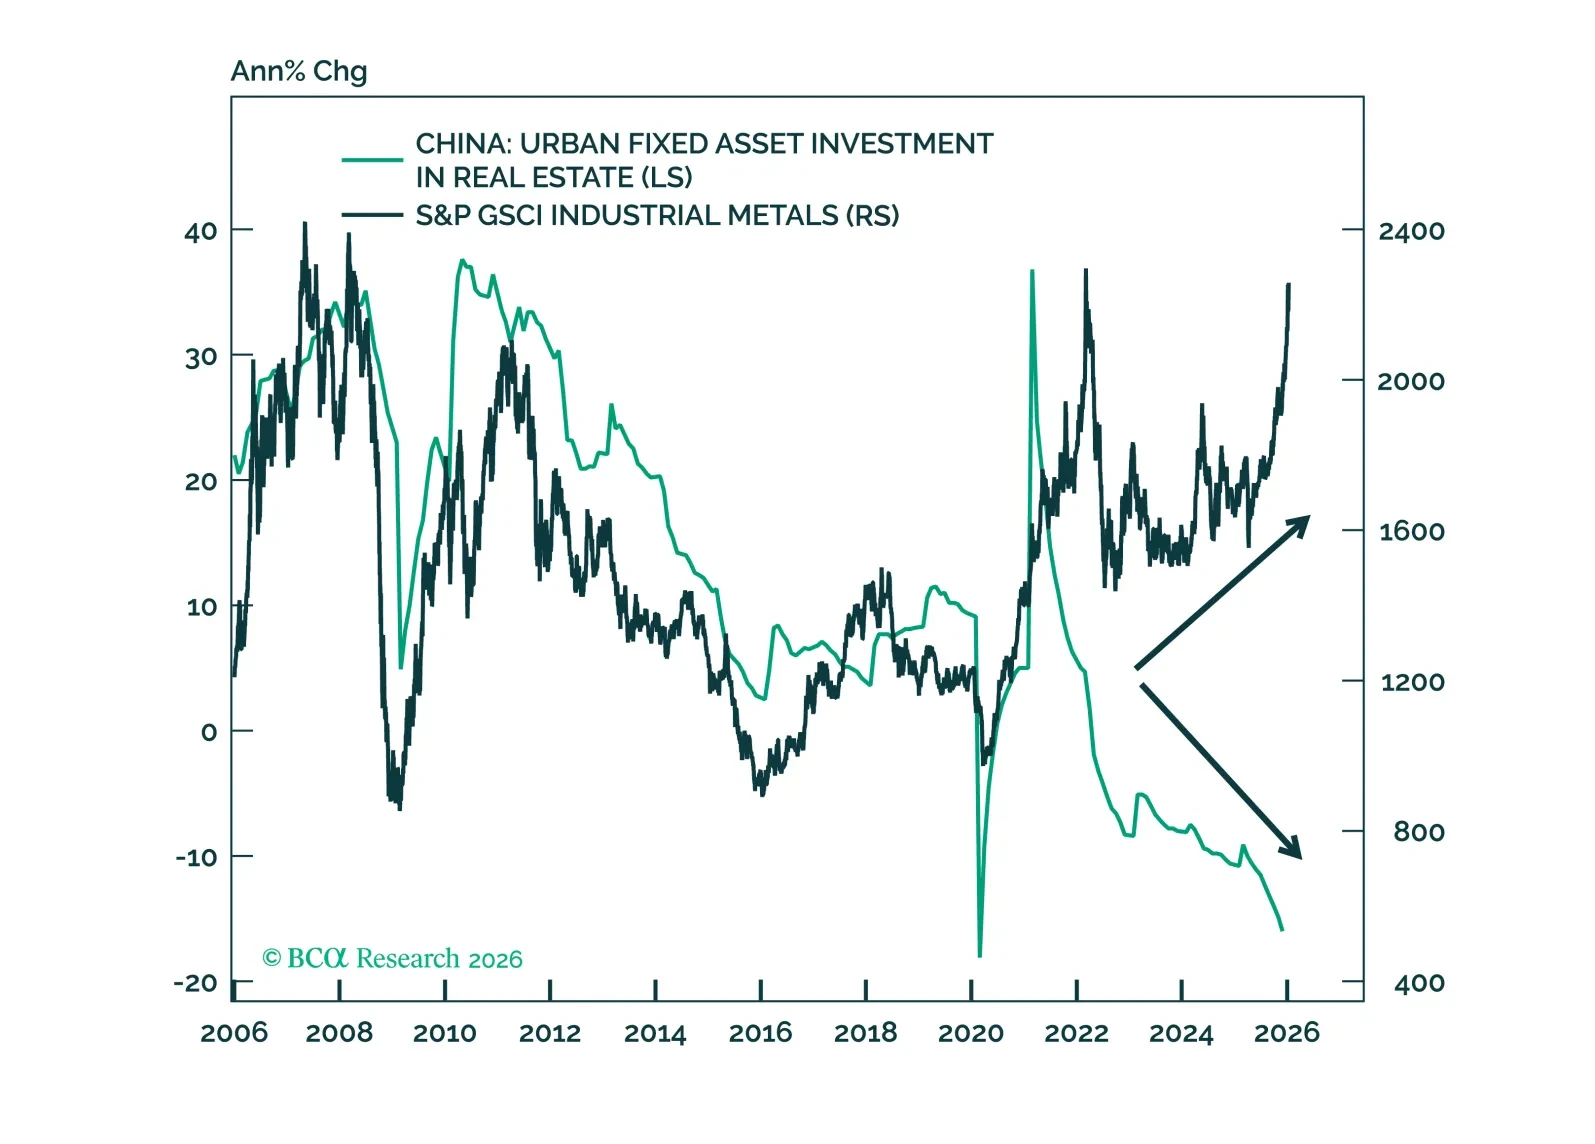
The year 2026 has started off well, with not even the threat to central bank independence denting the market's enthusiasm. Perhaps our tactical caution is misplaced.

Our Q1 outlook maps global growth, curve dynamics, and policy surprises, which we then translate to our recommended global fixed income portfolio allocations and trades.
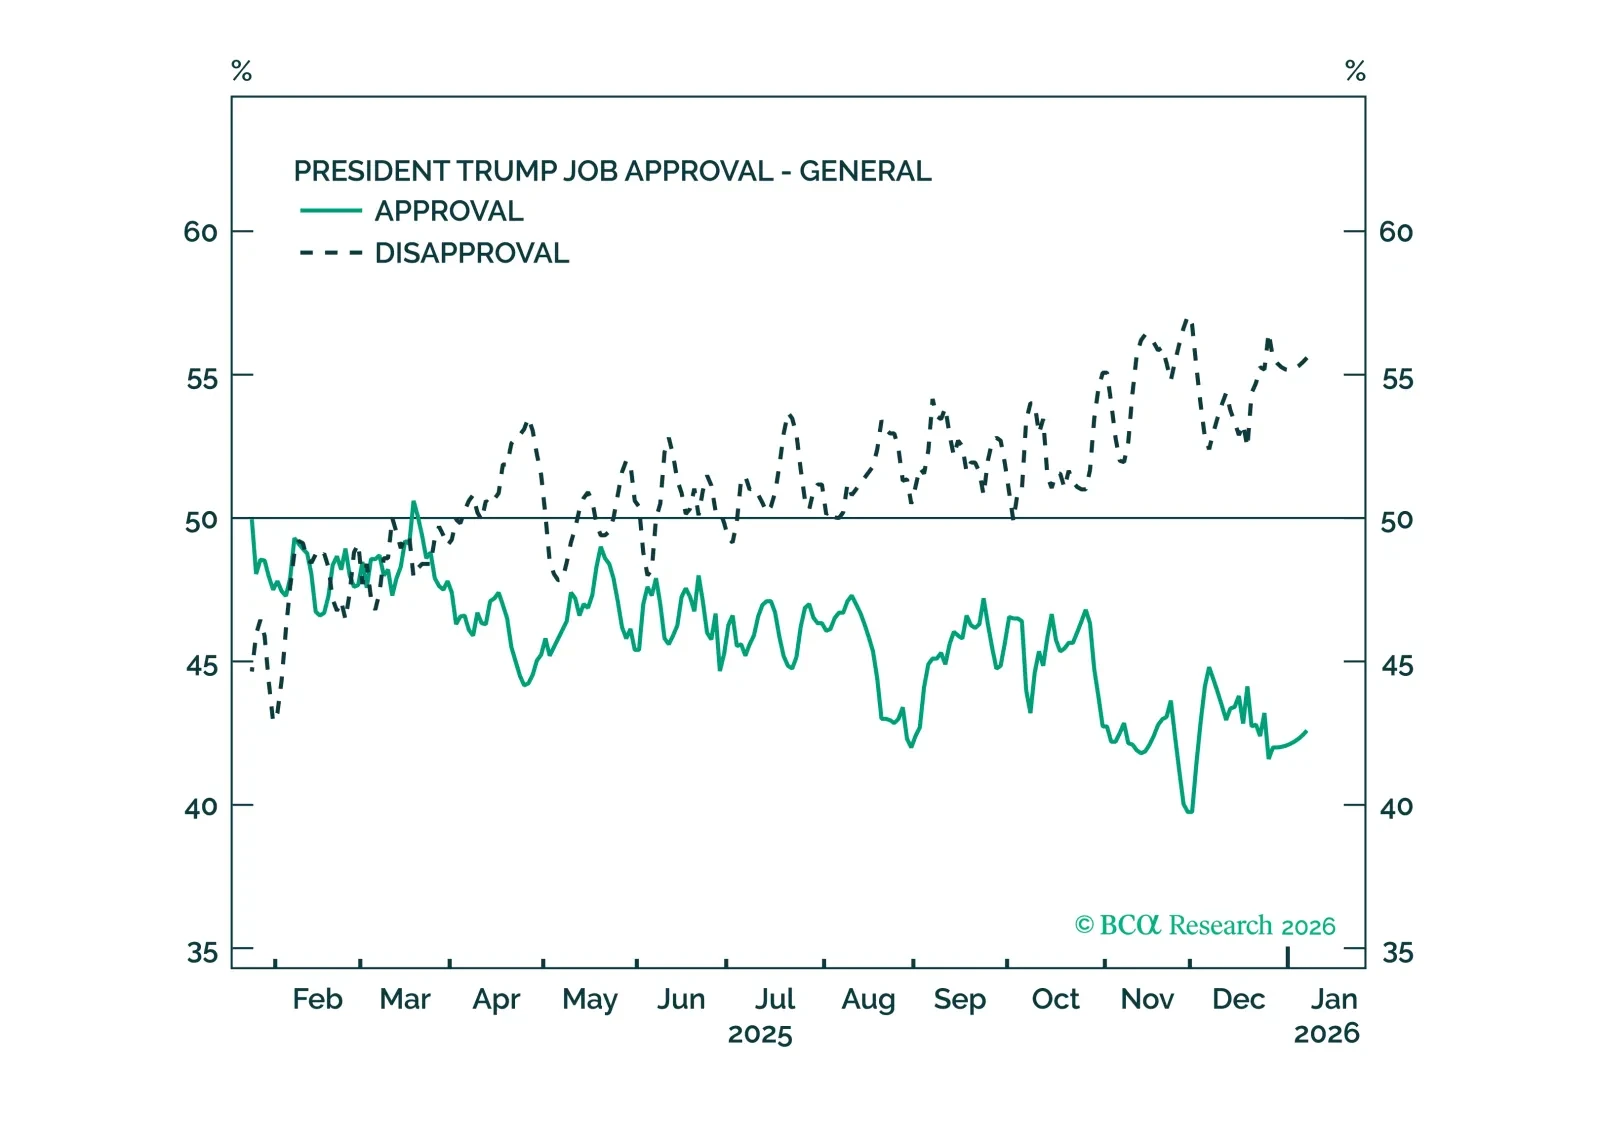
Congress will ultimately limit Trump from acting on his worst impulses, but his efforts to bypass those limits will cause market volatility.
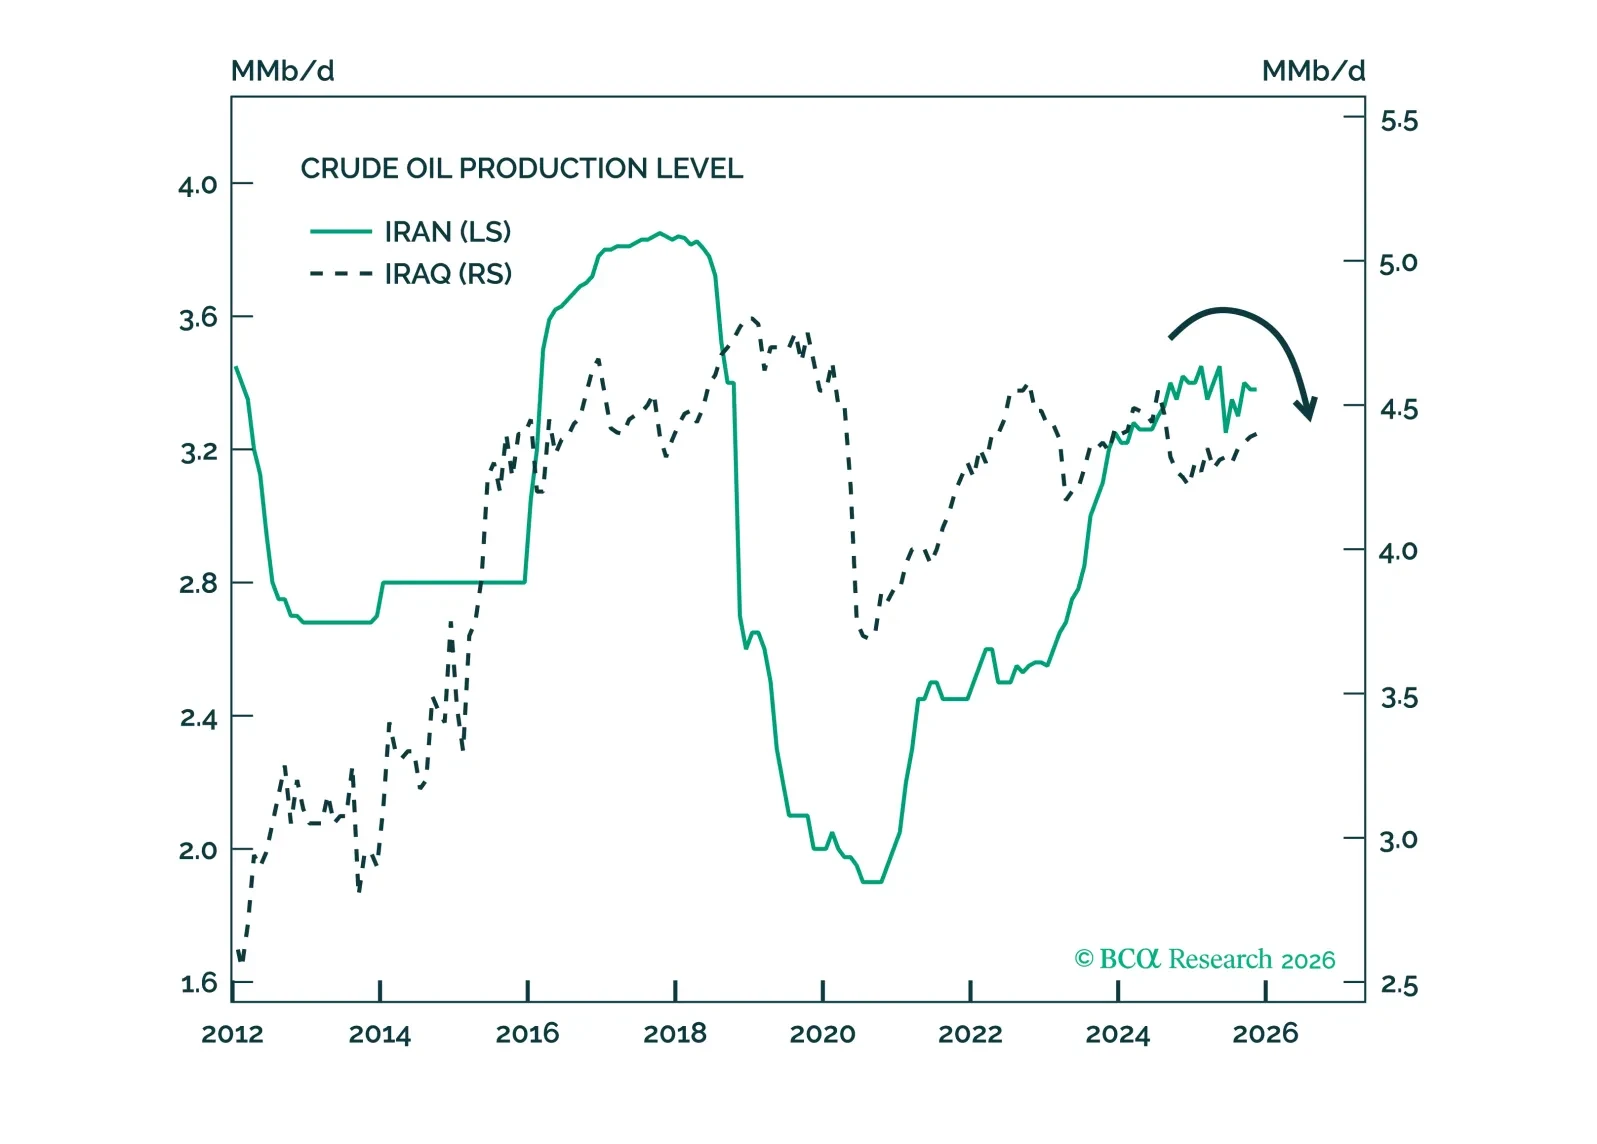
The risk to Iran's regime survival raises the probability of a massive global oil supply shock back to around 40%, where we put it last year.

Measures of labor market utilization improved in December, ruling out a January cut and significantly reducing the odds of a March cut.