Latest from BCA Research
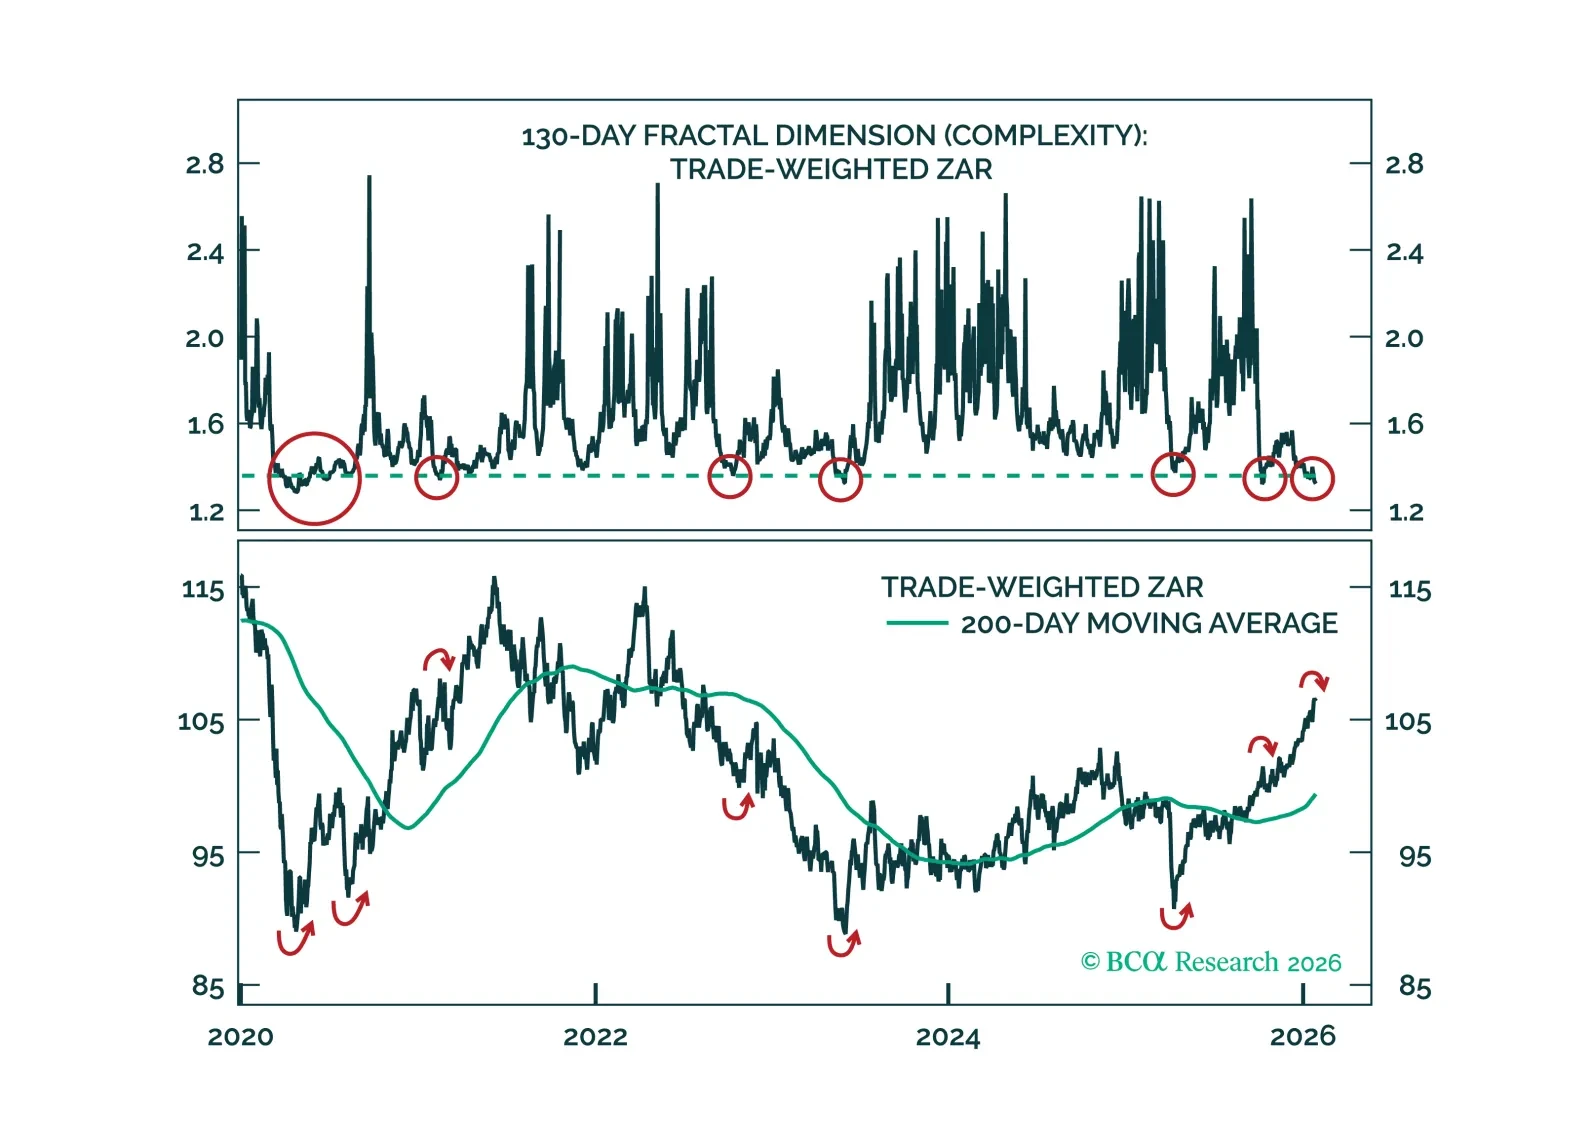
South Africa’s commodity boost is fading, but its cyclical headwinds remain. As growth weakens and capital inflows dry up, the rand looks increasingly vulnerable to a reversal.
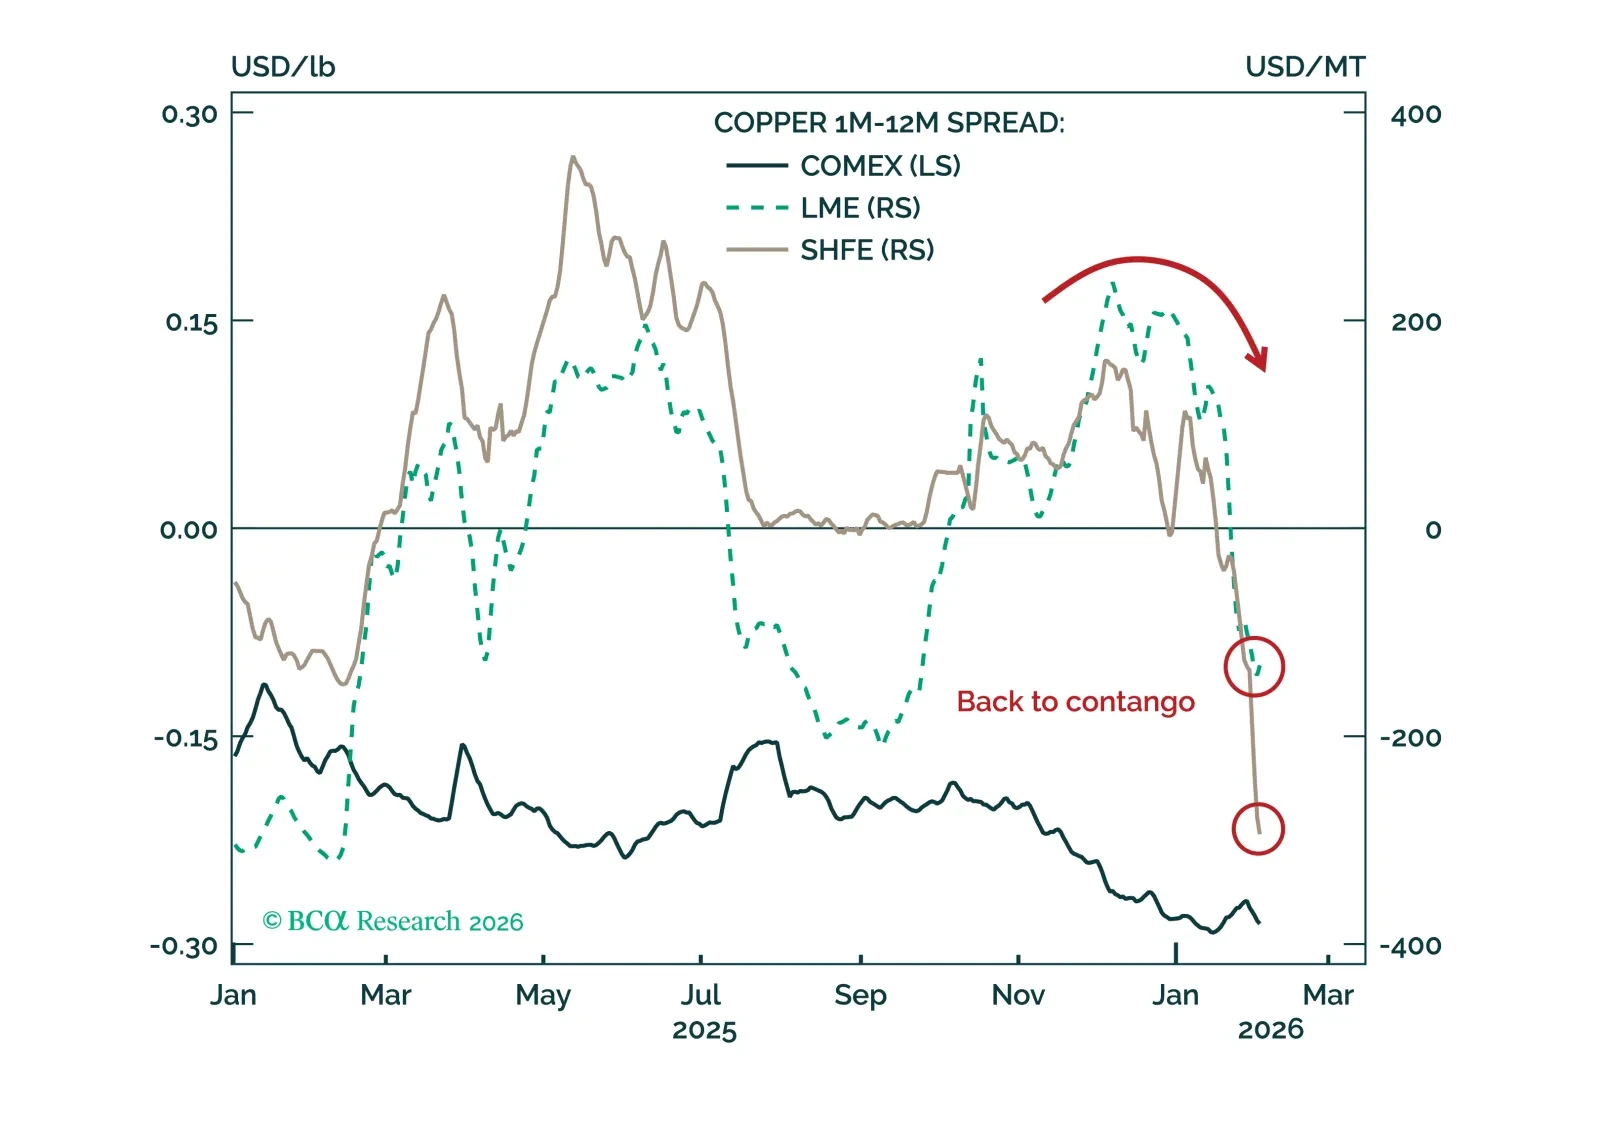
The metals mania is fueling extreme volatility. In particular, the price of copper has become detached from fundamentals and is vulnerable to the downside.
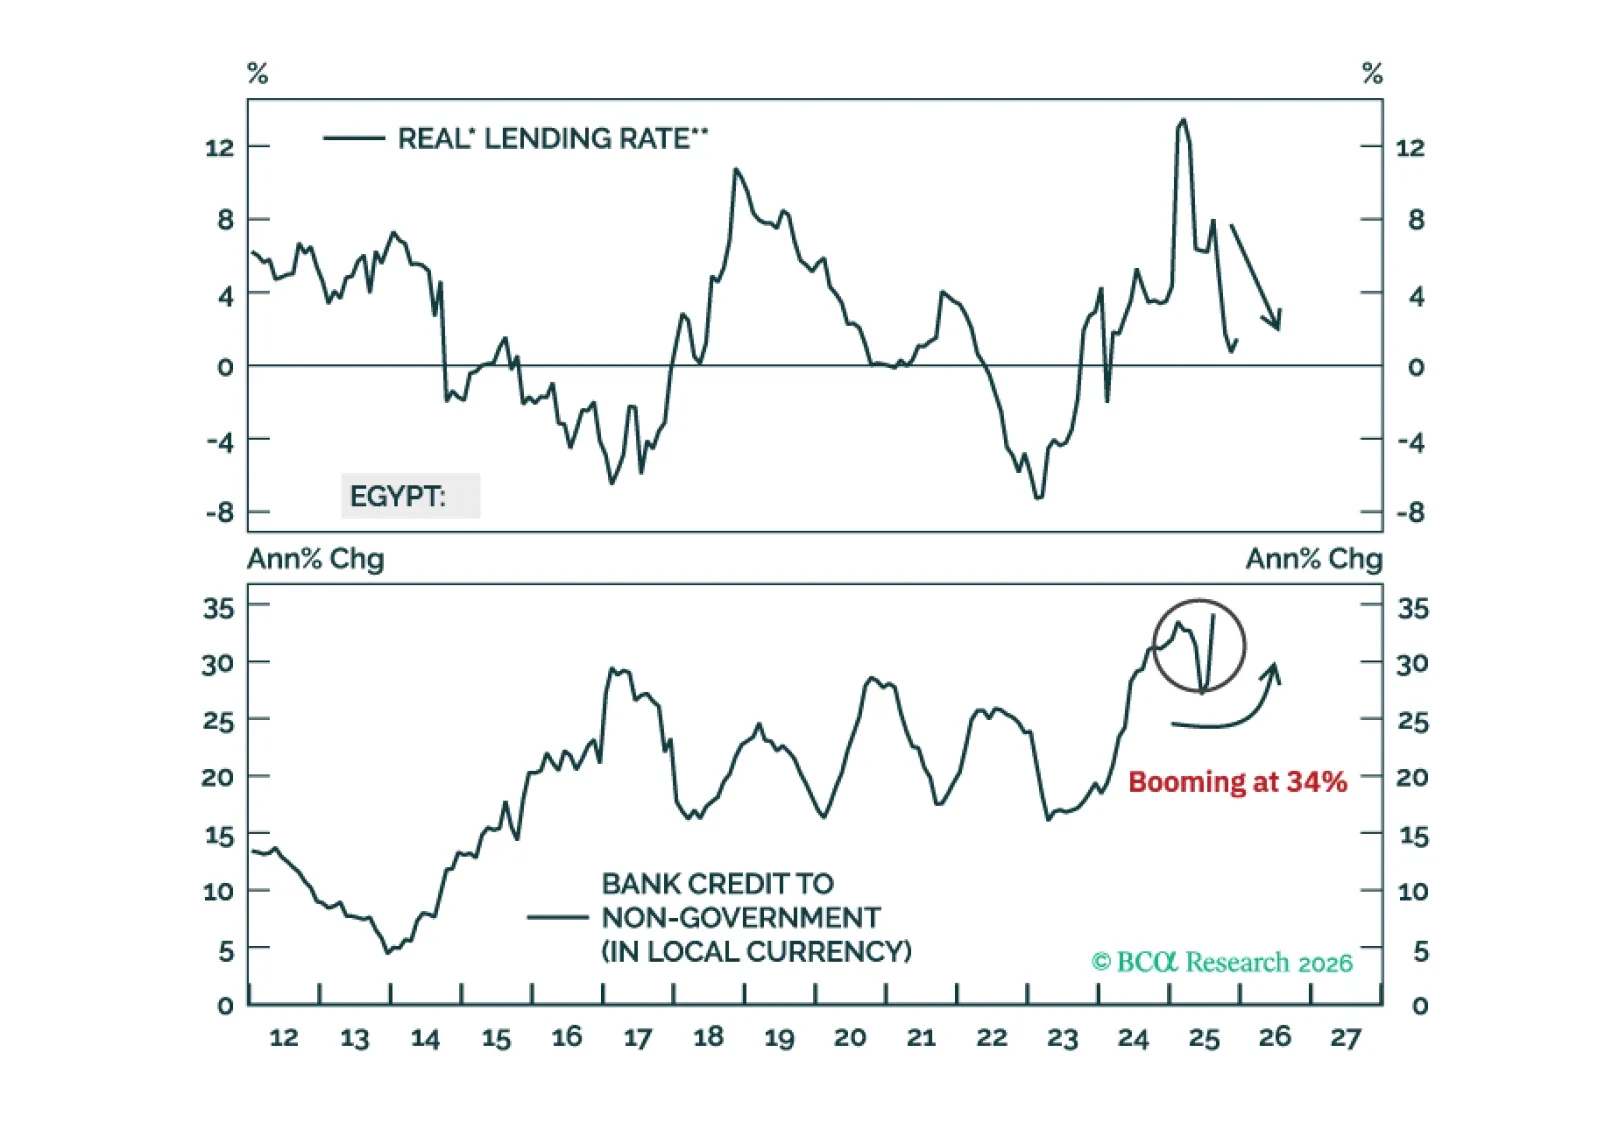
Egypt’s underlying inflation pressures are much higher than the headline CPI numbers imply. Real interest rates have plunged. As such, domestic bond yields have stayed high for a reason. Steer clear.
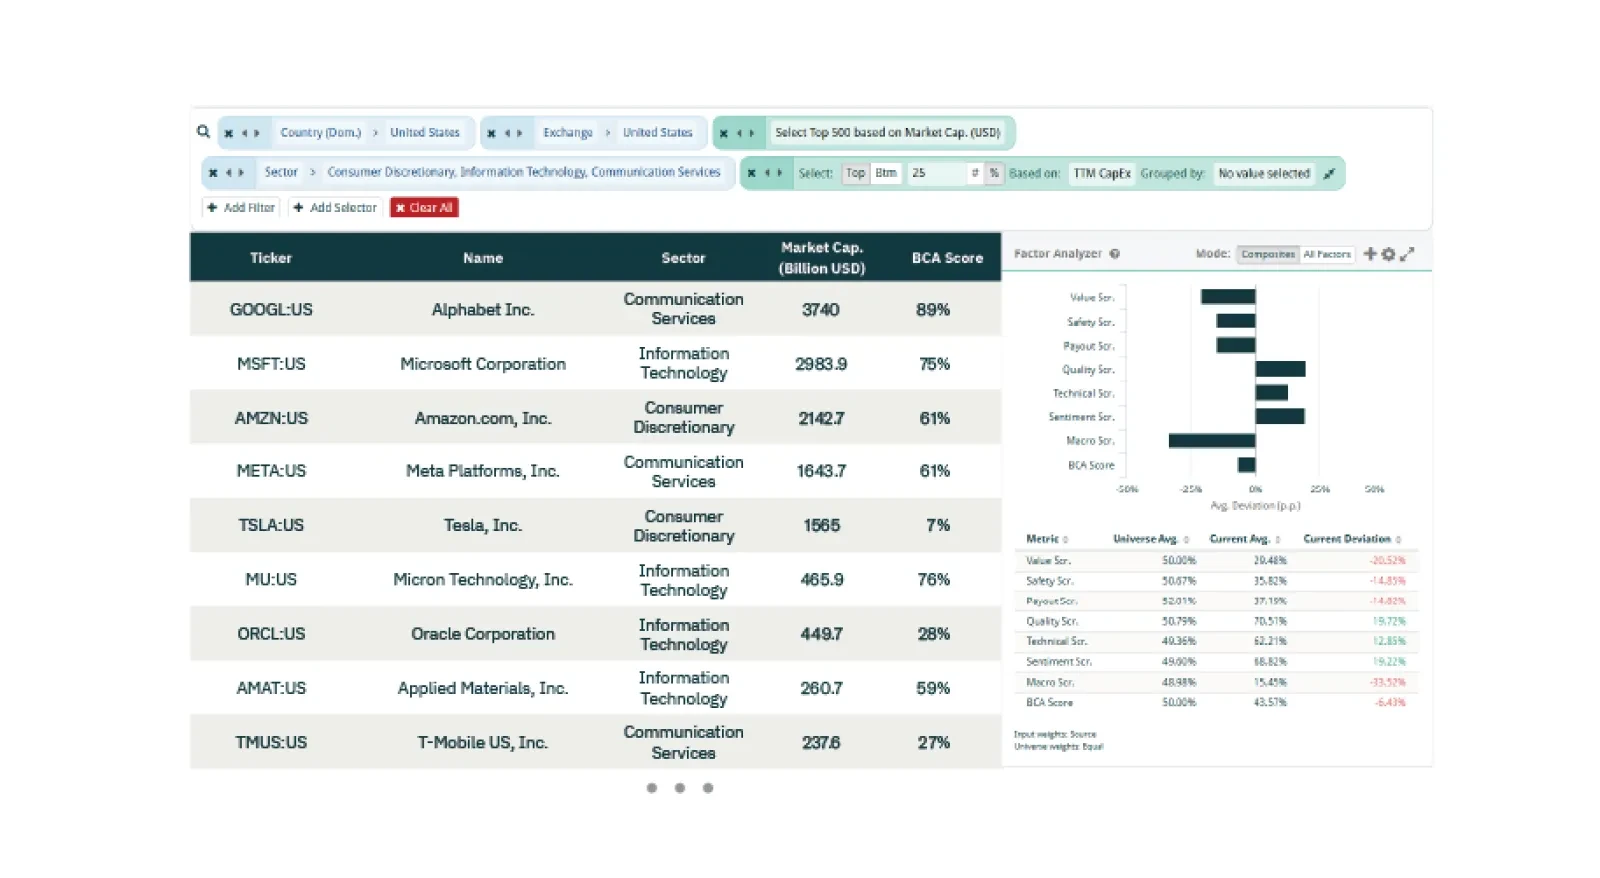
For this screener report, we explore opportunities in a CapEx premium divergence trade, a valuation convergence trade, and European Defense Stocks.
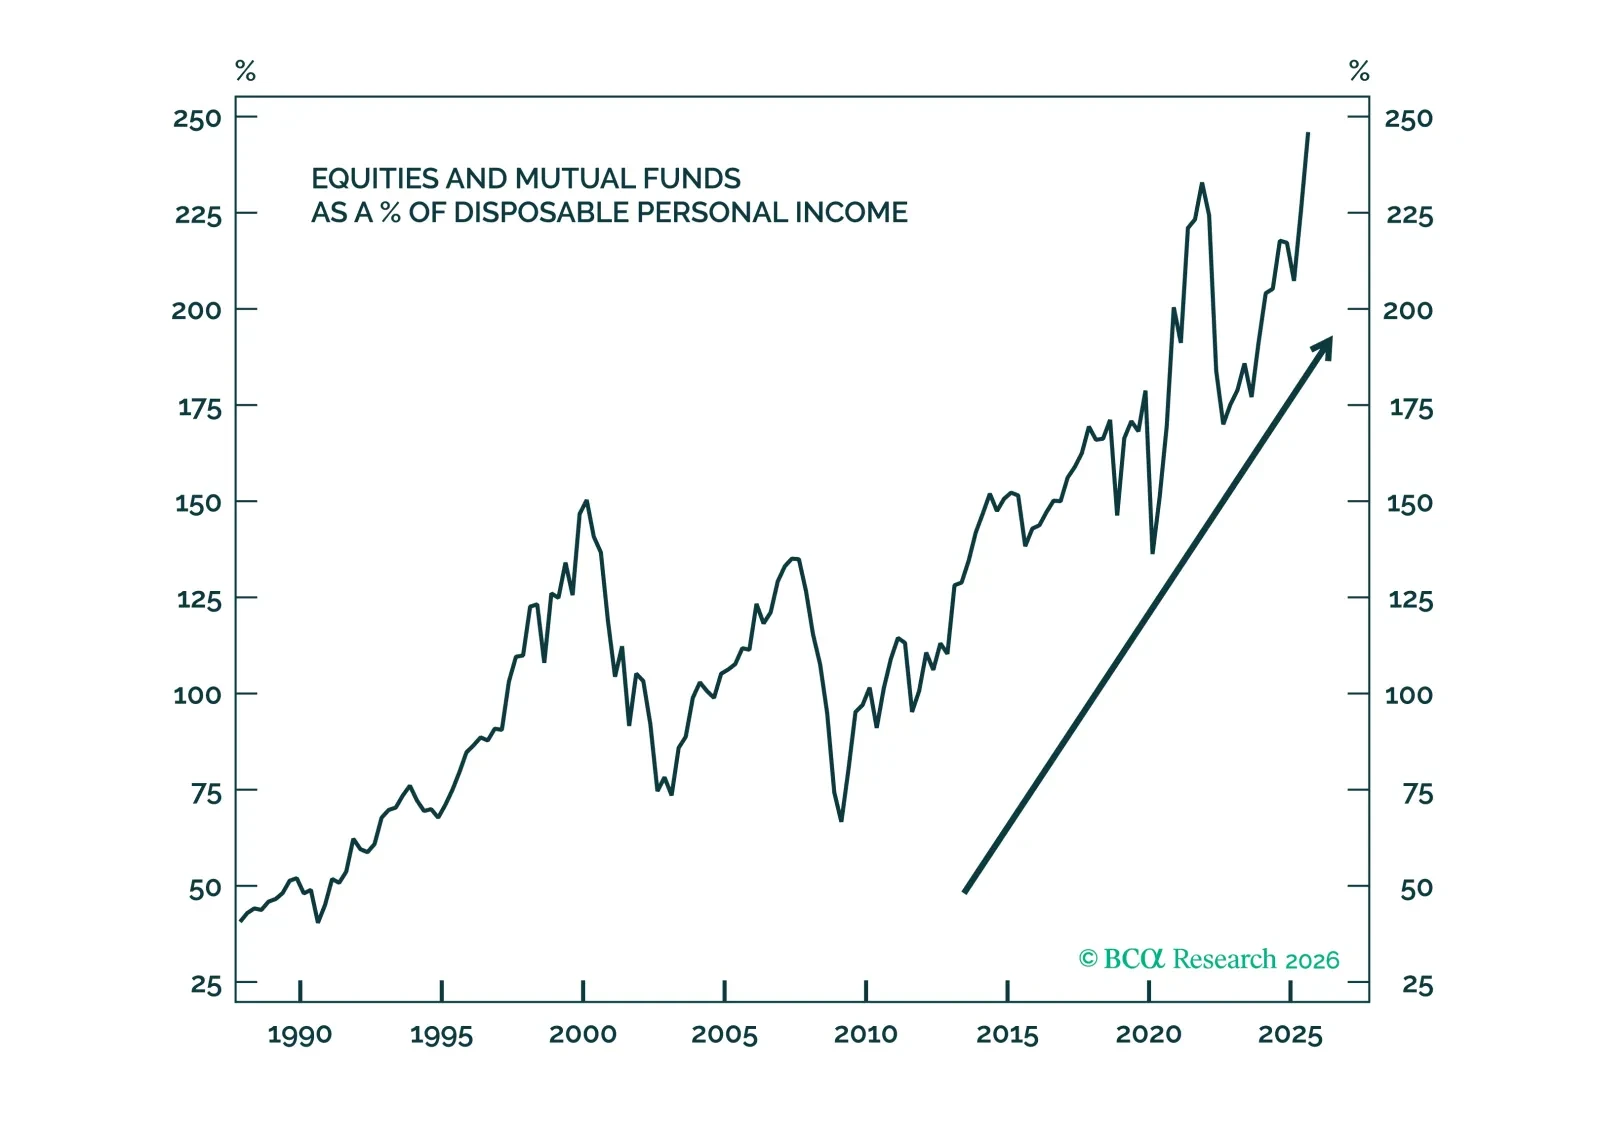
It appears that households have been able to spend more than they’ve earned since May by dipping into their swollen brokerage accounts. Bulked-up equity holdings could herald a future where consumption is more sensitive to stock market ups and downs. That’s great in bull markets but could be an unexpected drag on activity when the next bear arrives.
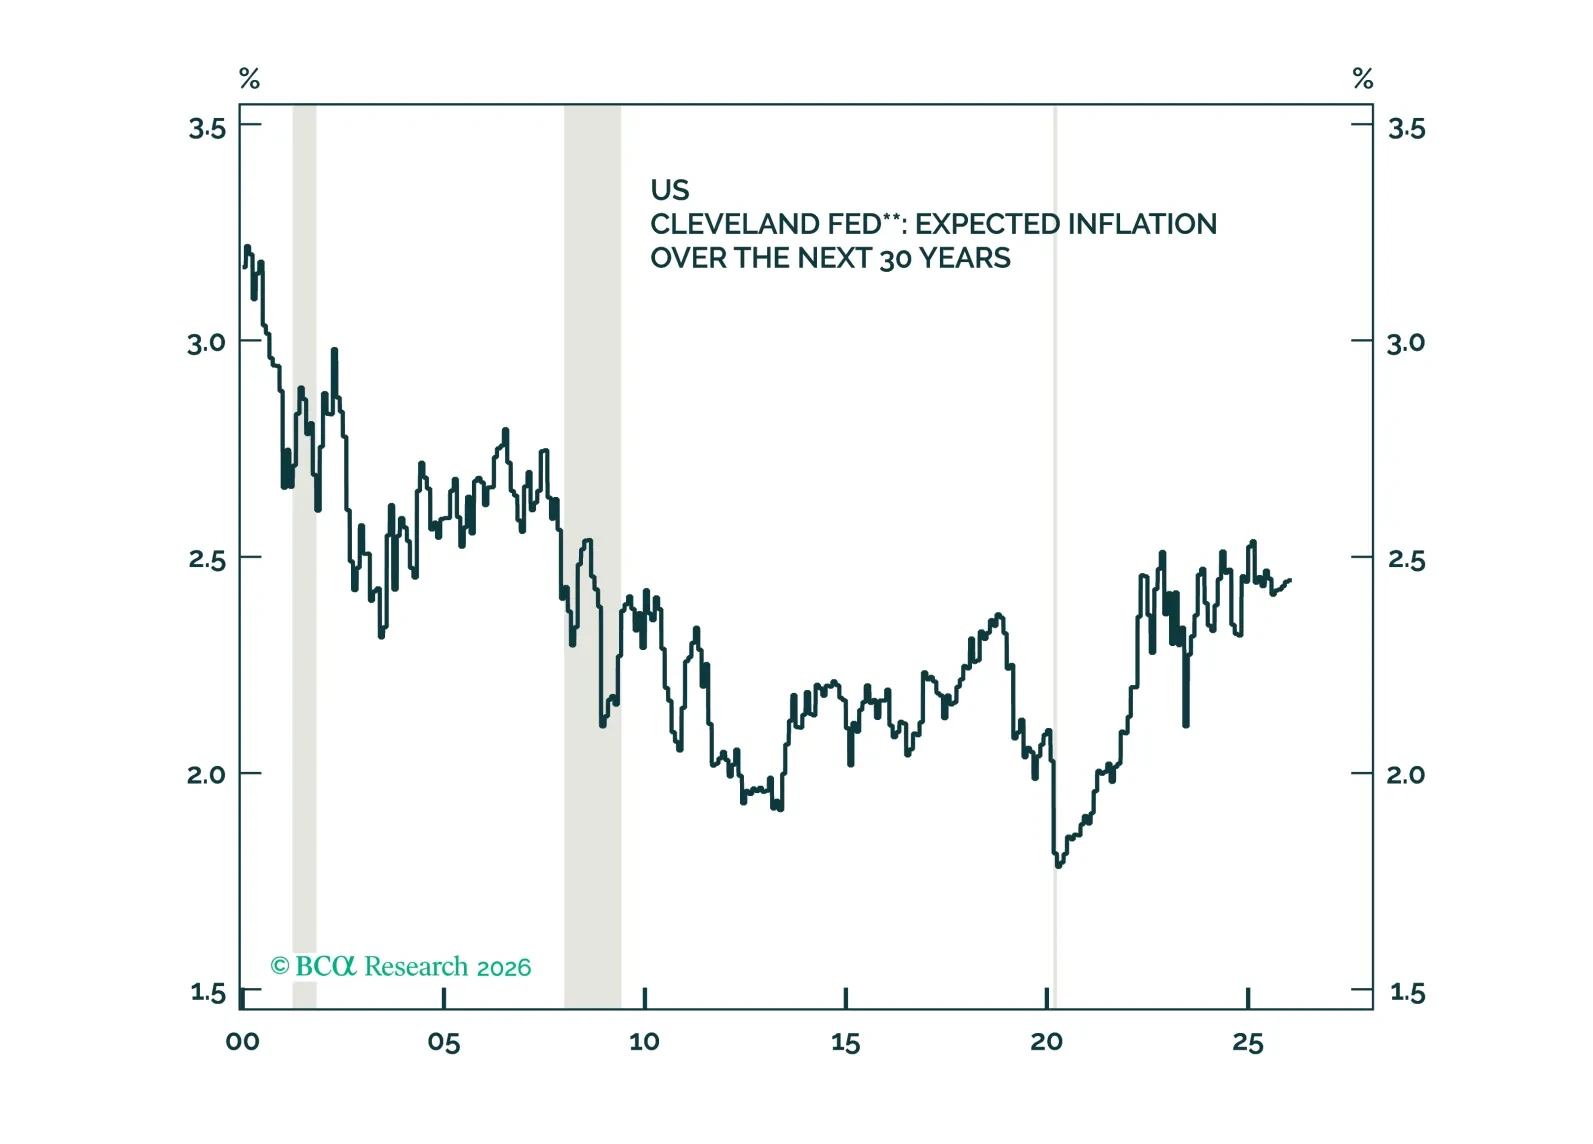
Almost all bull markets are built on a foundation of truth. With enough time, however, FOMO takes over, causing prices to overshoot fundamentals. This is what has happened to gold and silver, and increasingly to other metals as well.

2026 should see another year of gains for the S&P 500, but, as the bull market matures and growth slows, returns will be capped by revenue growth rather than being boosted by expanding margins and multiples. We think Tech can outperform, but leadership will broaden and performance gaps will narrow.
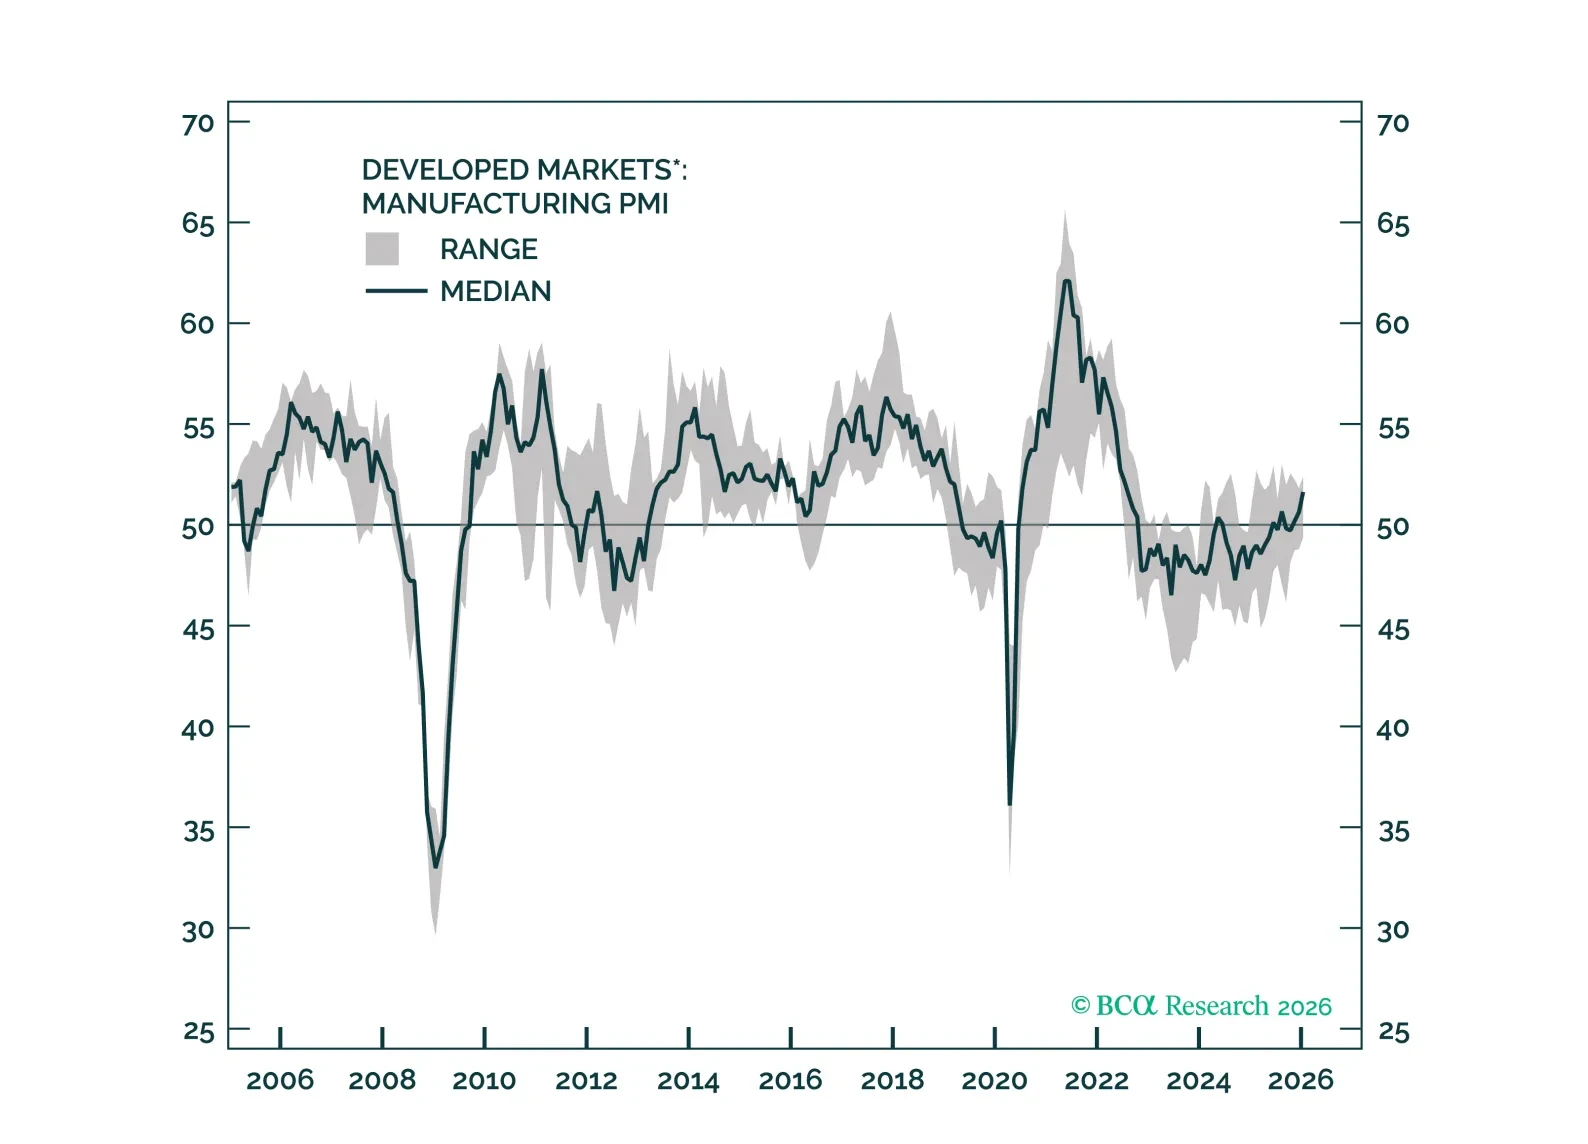
The actions of the Trump administration have dominated the headlines over the past month. They are all noise. Focus on the reactions from the rest of the world. Policy makers outside of the US are now determined to stimulate and reform their domestic economies. Global growth is accelerating without a corresponding increase in inflation. This combination is not only positive for risk assets but is also supercharging returns for Ex-US stocks. Downgrade Fixed Income and duration.
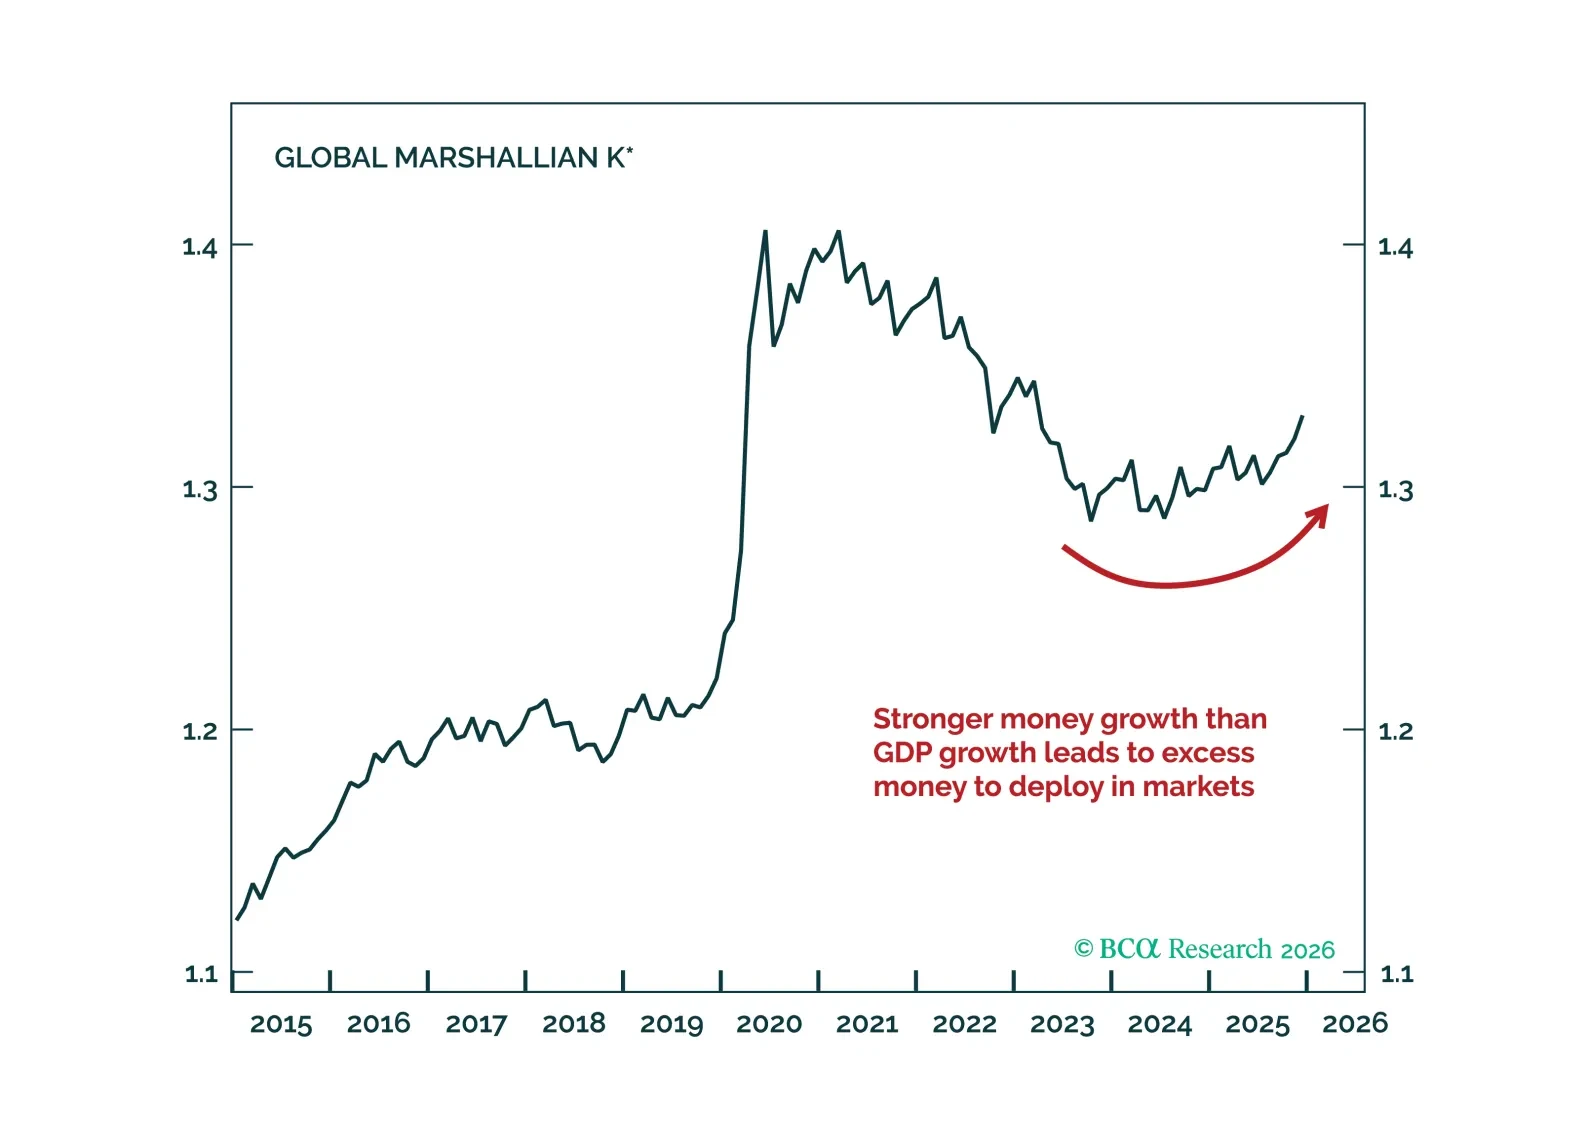
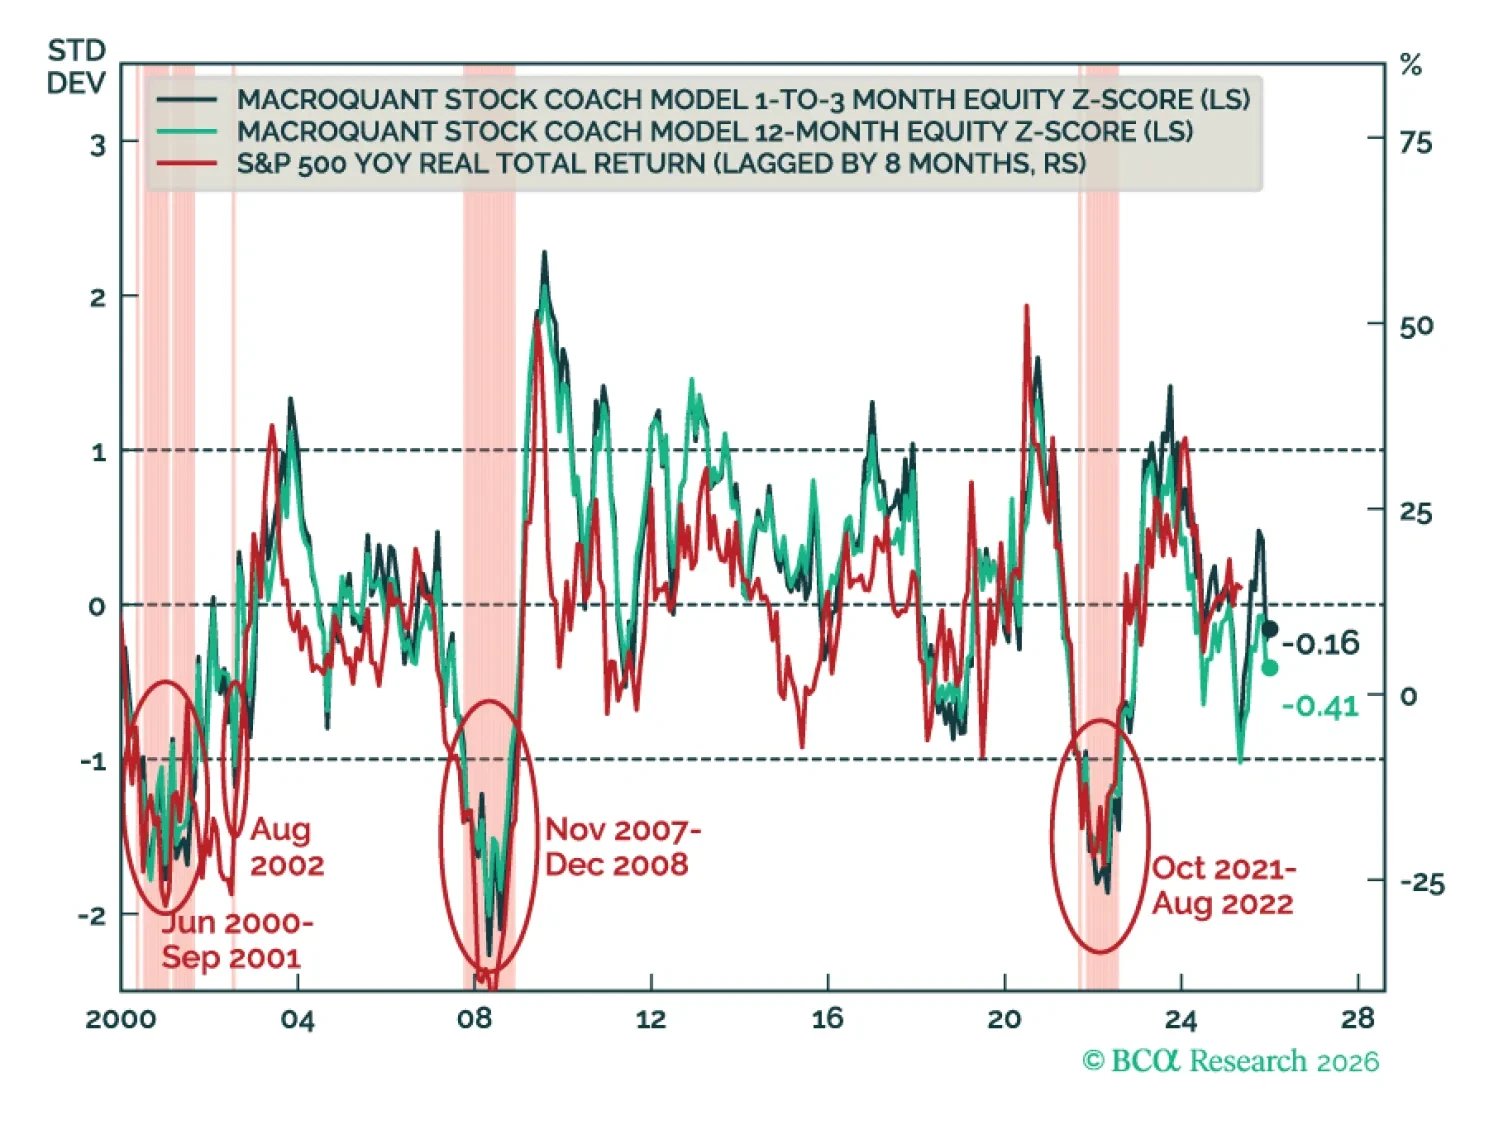
MacroQuant recommends a slight underweight in equities, favors a below-benchmark duration stance in fixed-income portfolios, remains bearish on the US dollar, has upgraded oil and copper to overweight, and is bullish on gold.