Latest from BCA Research
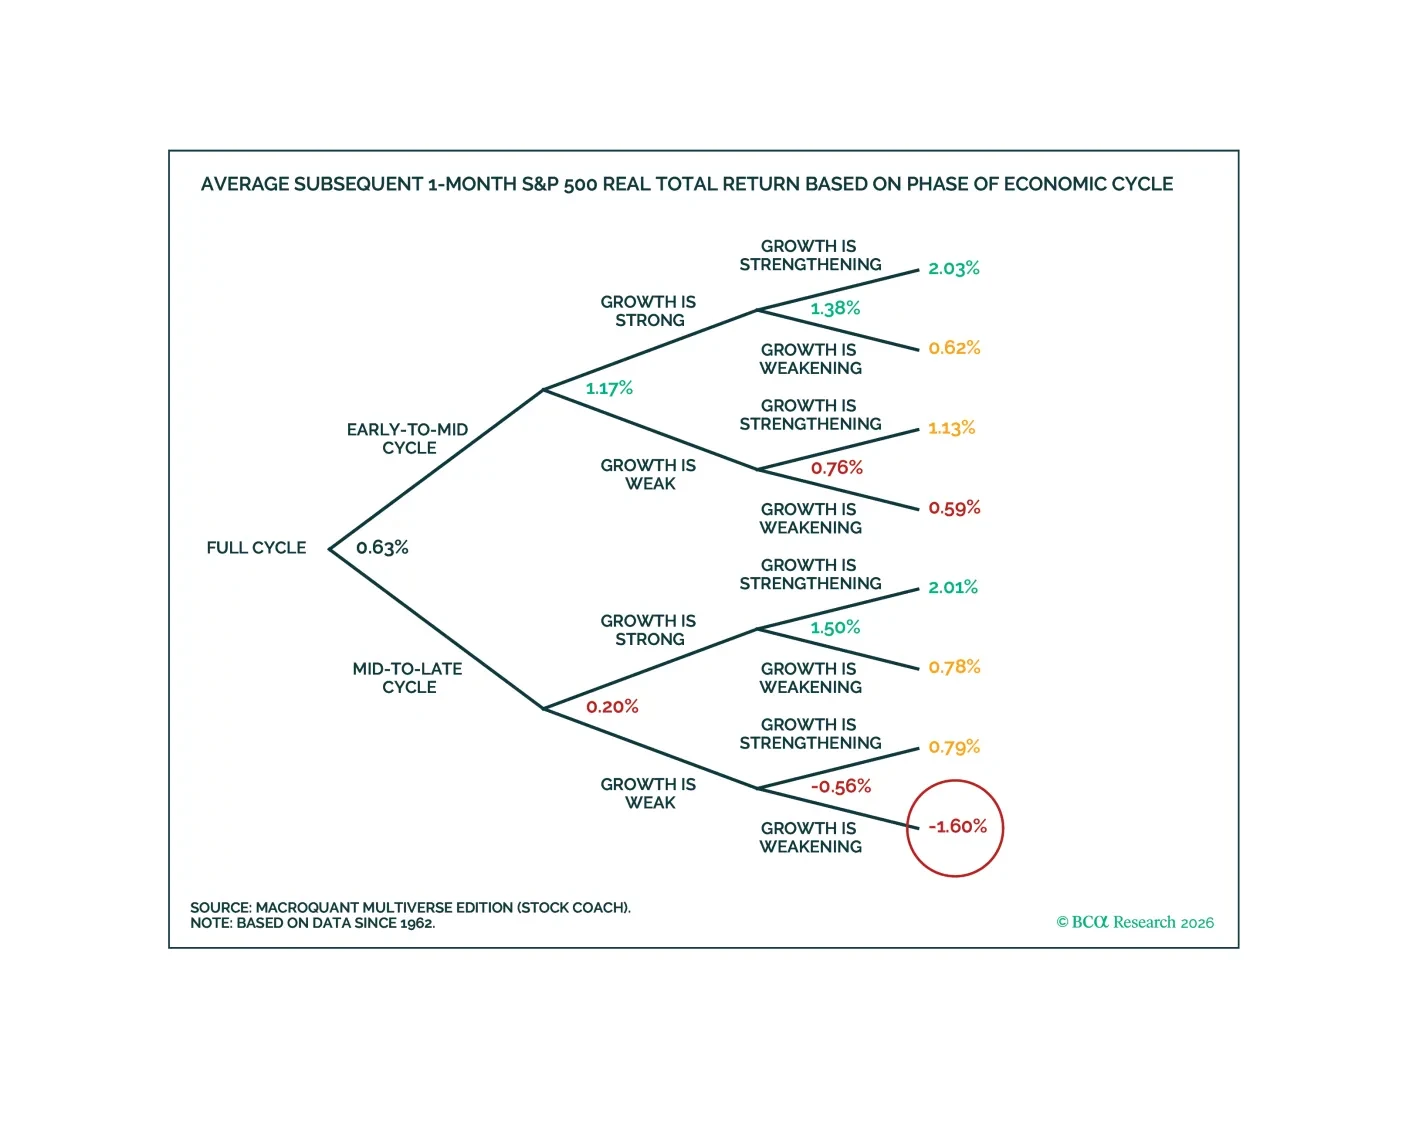
MacroQuant recommends underweighting equities and adopting a benchmark duration stance in fixed-income portfolios. The model is very positive on the US dollar, bearish on gold, neutral on copper, and bullish on oil.
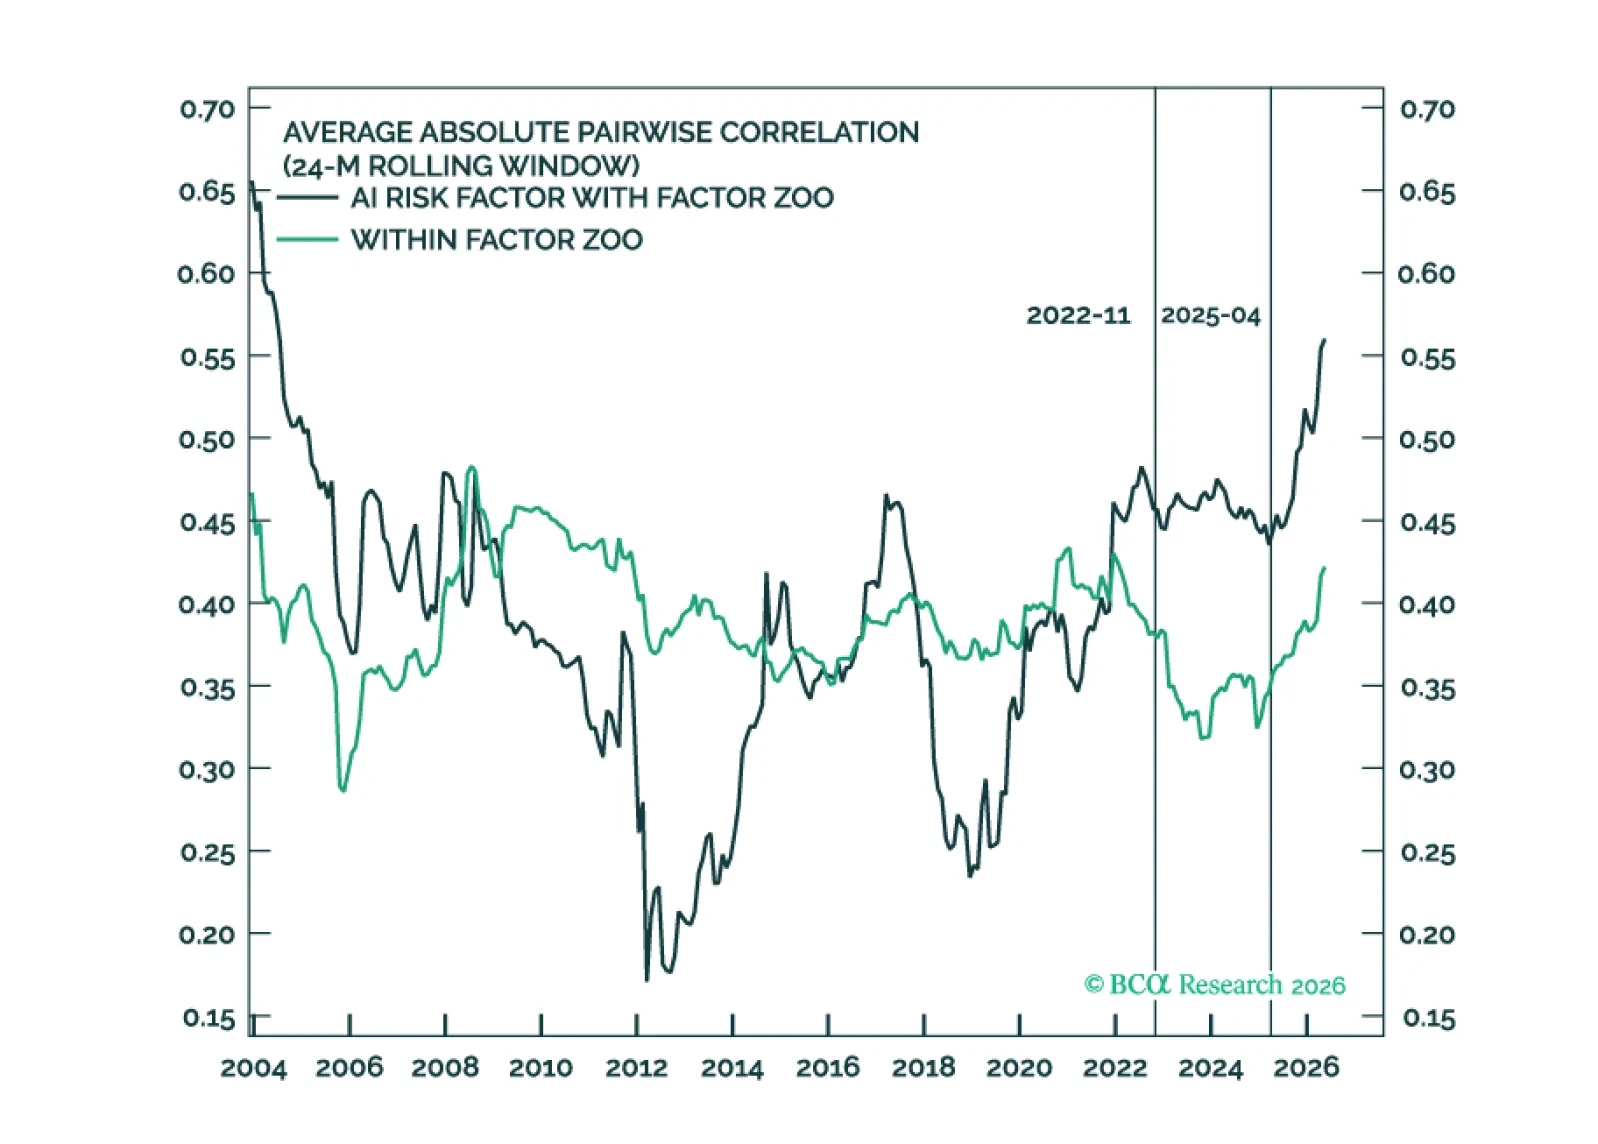
The S&P 500 has become increasingly concentrated. We know that. But the critical question is not how many stocks are driving the market; it is how many factors are driving stocks. We define an AI risk factor to test whether AI has become the dominant common exposure throughout much of the factor zoo.
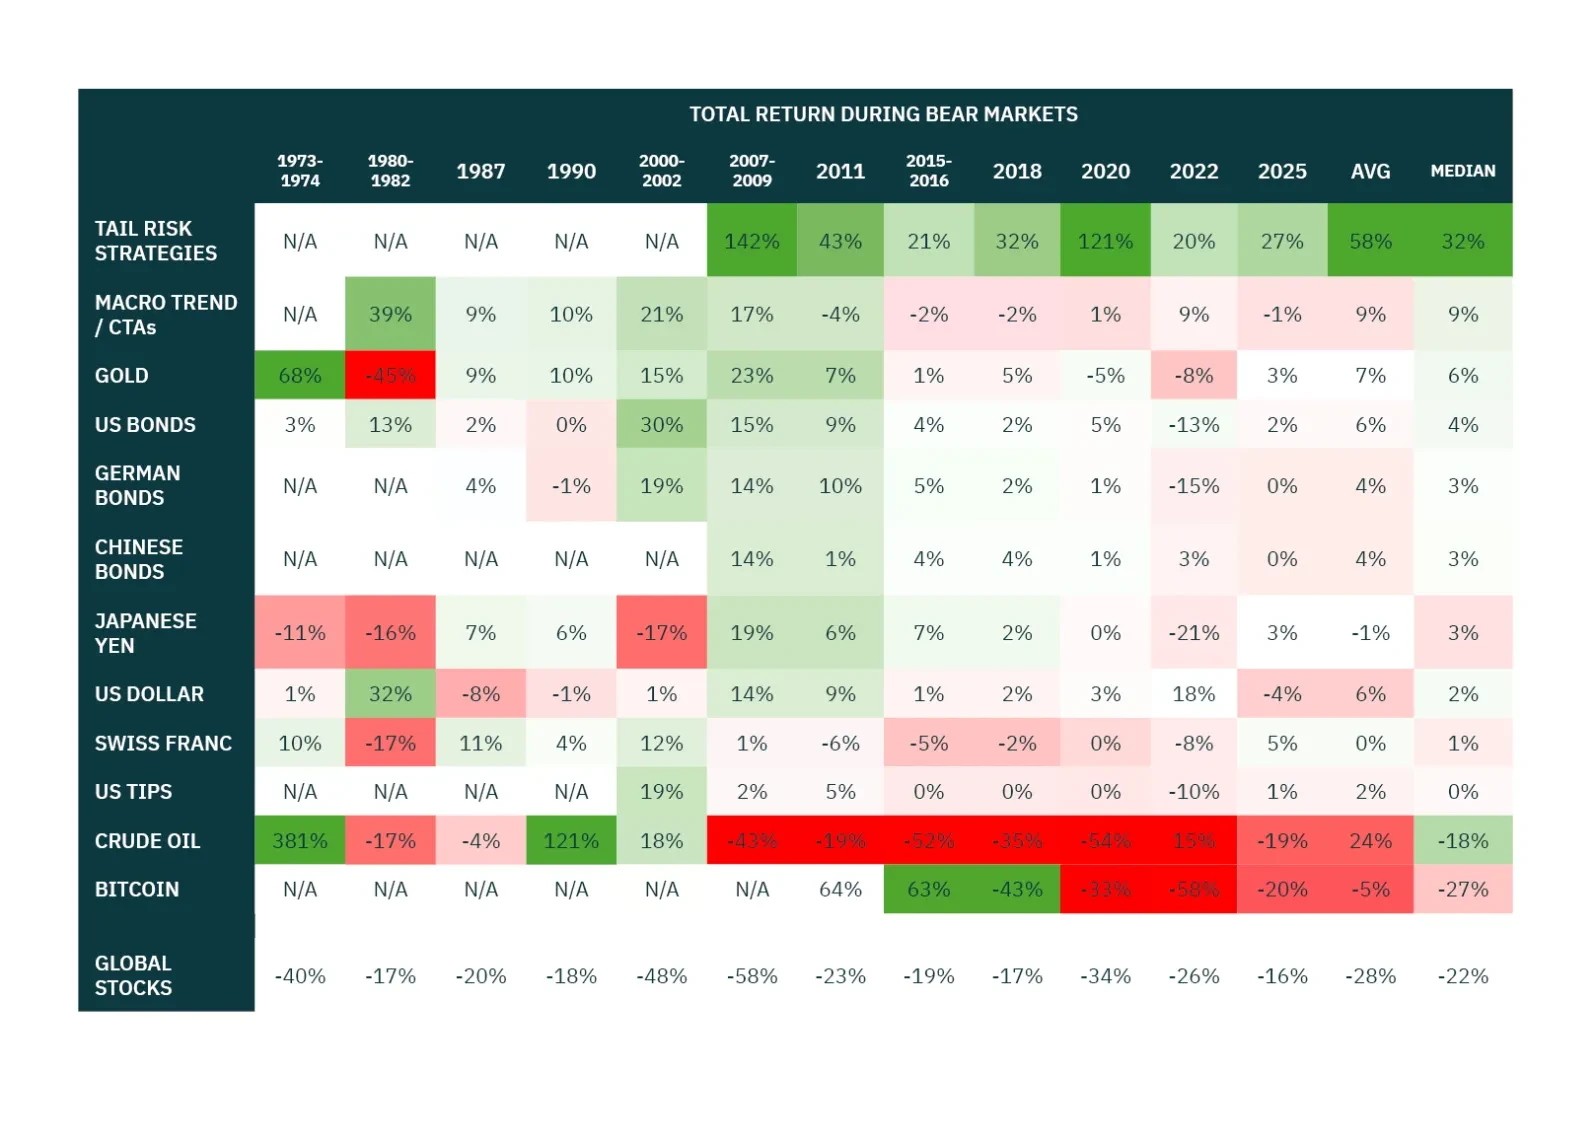
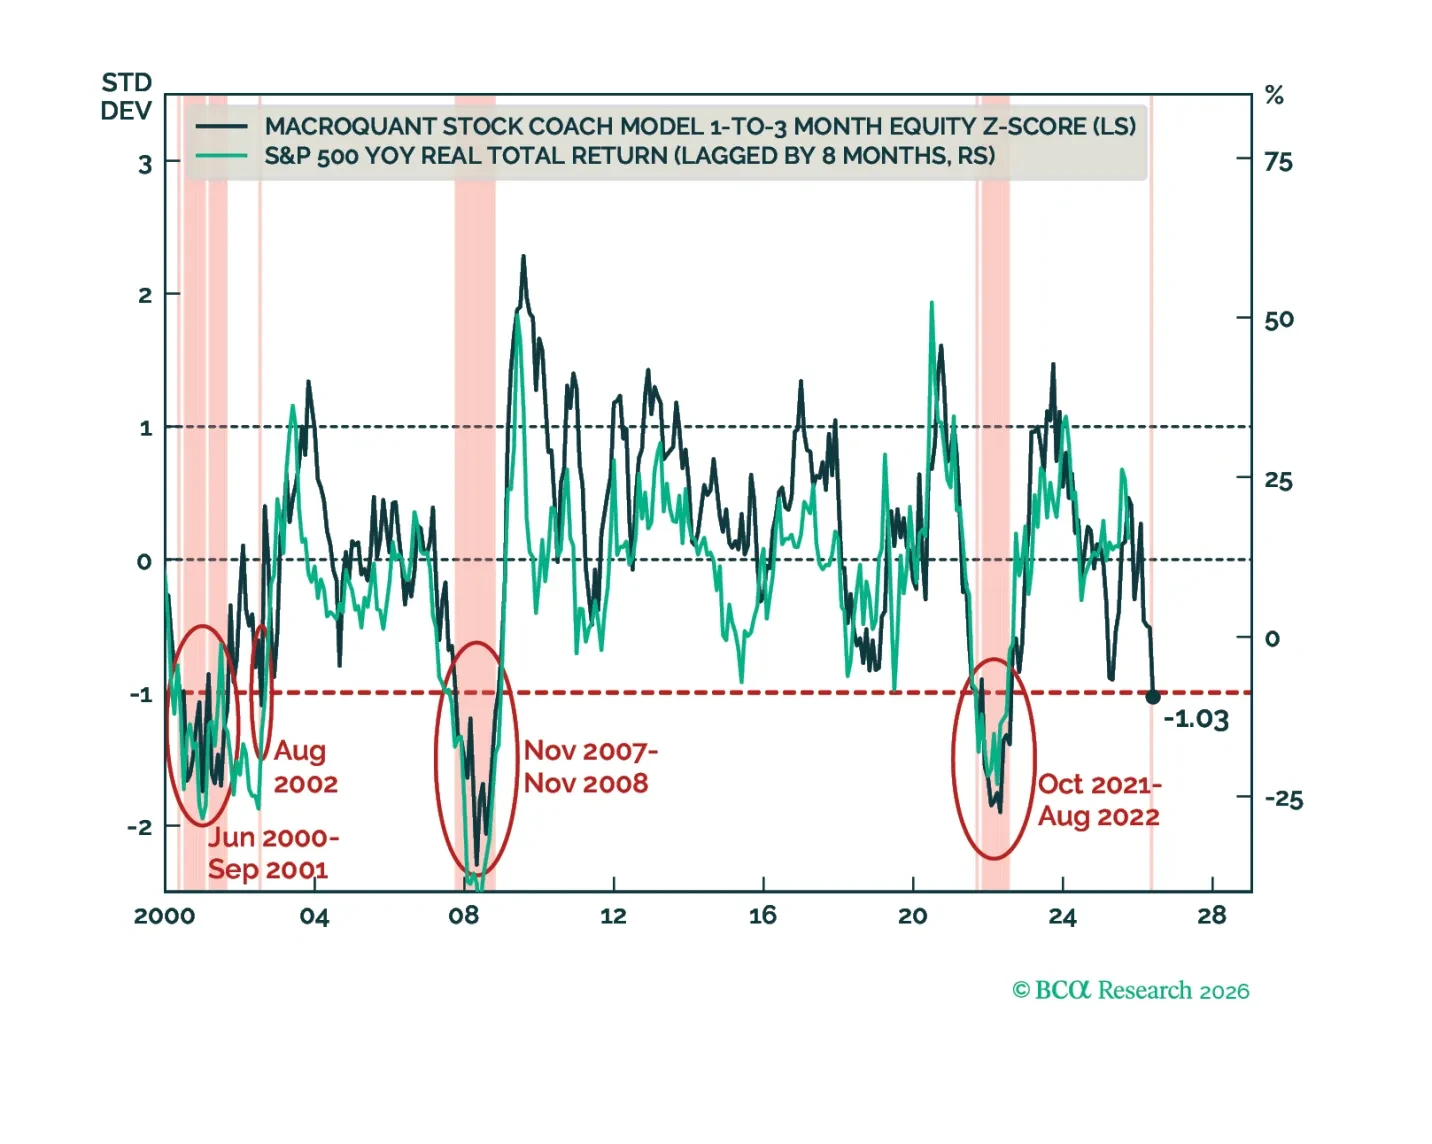
The equity bull market is getting long in the tooth. Bonds should perform well once economic growth begins to slow. The dollar will strengthen over the coming months before resuming its downtrend. While crude has likely found a near-term floor, we favor metals over energy in the long run.
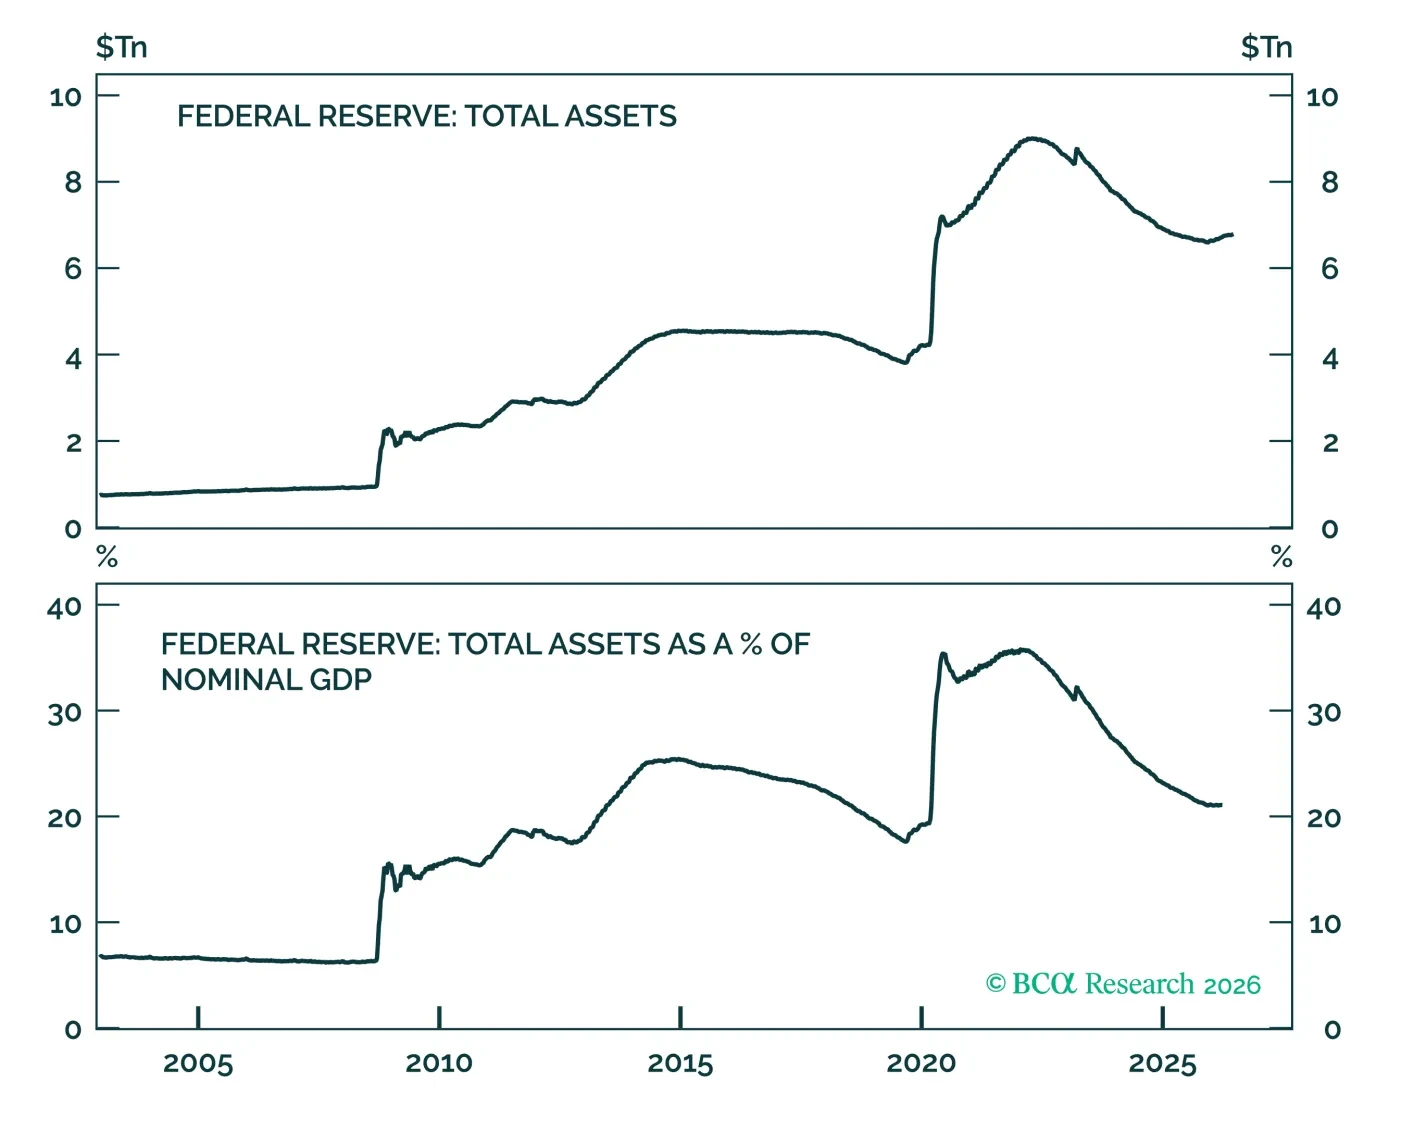
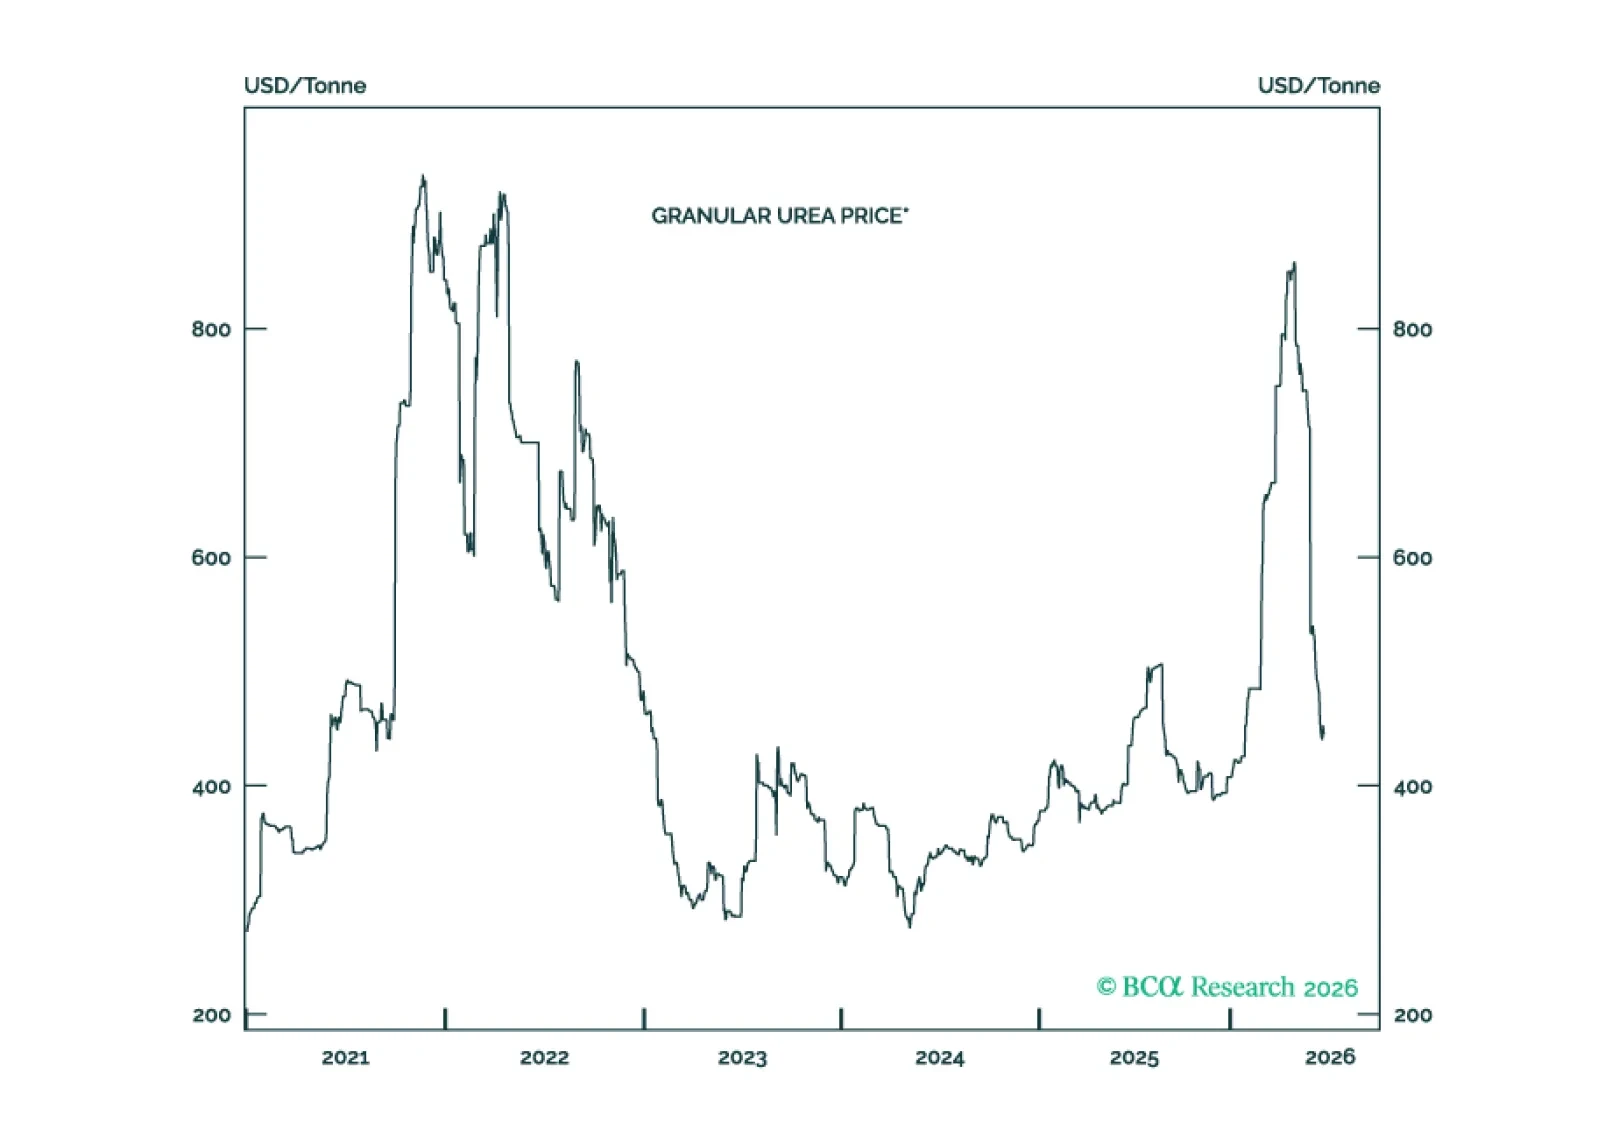
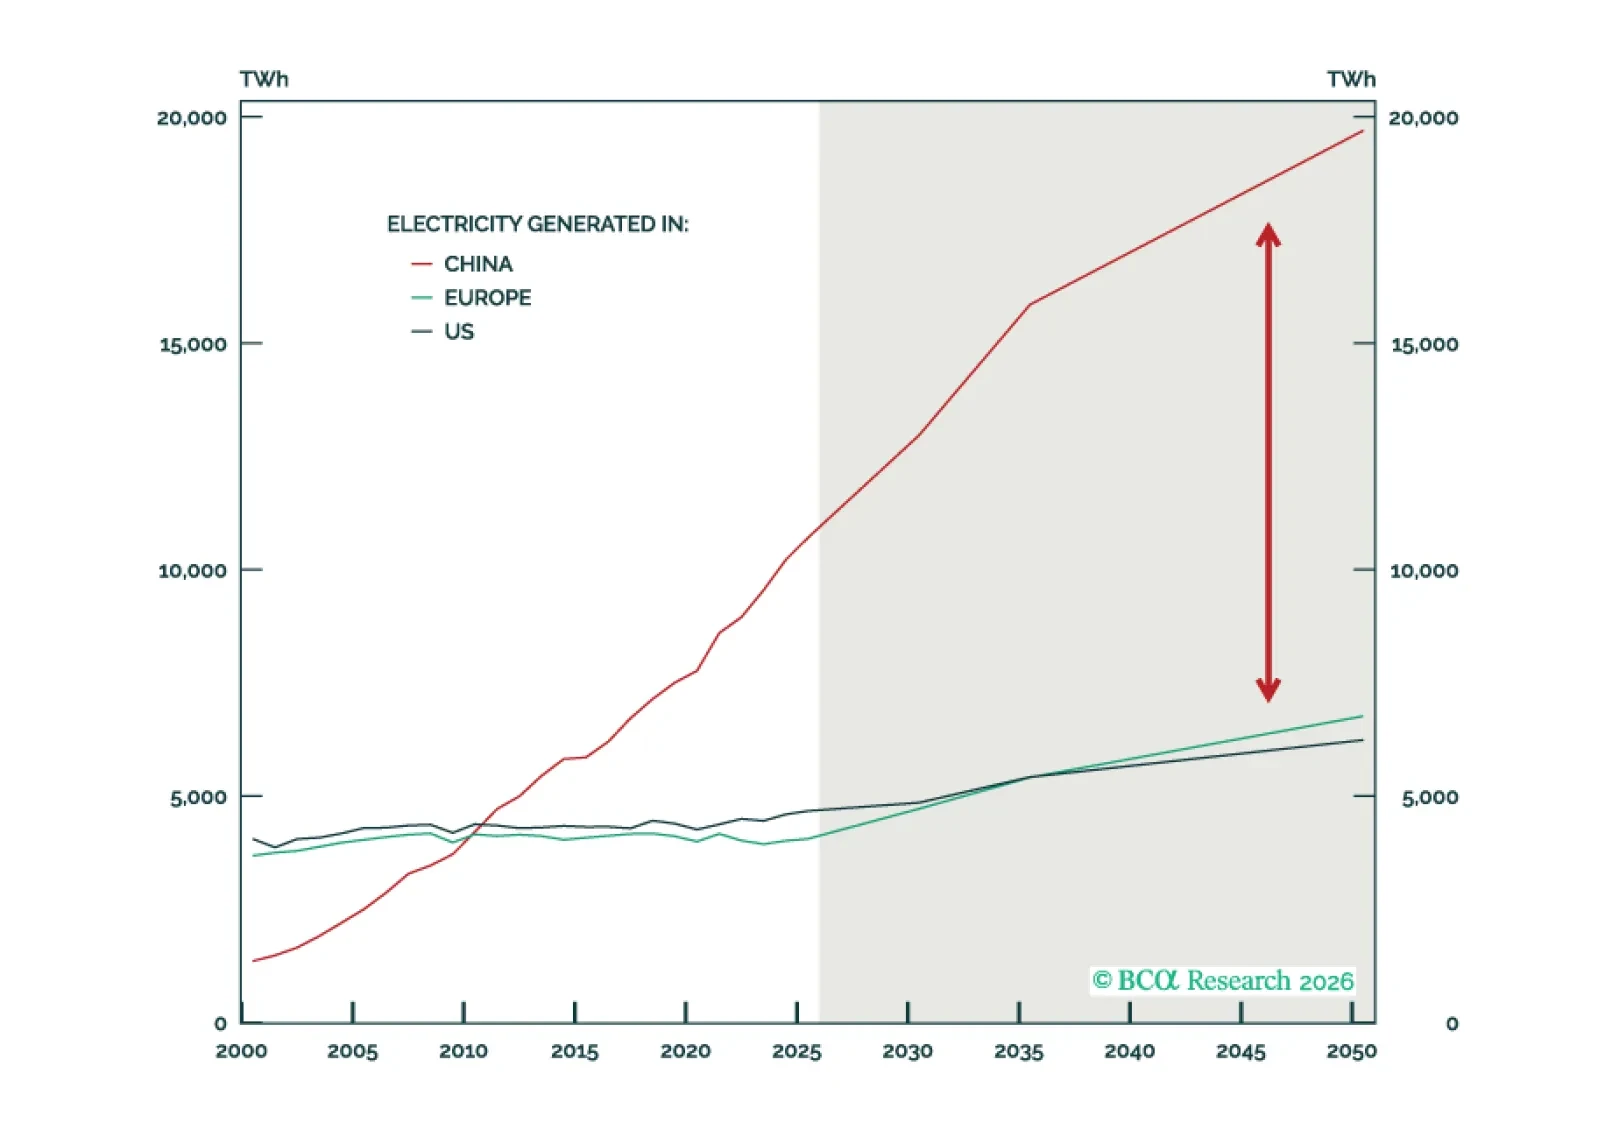
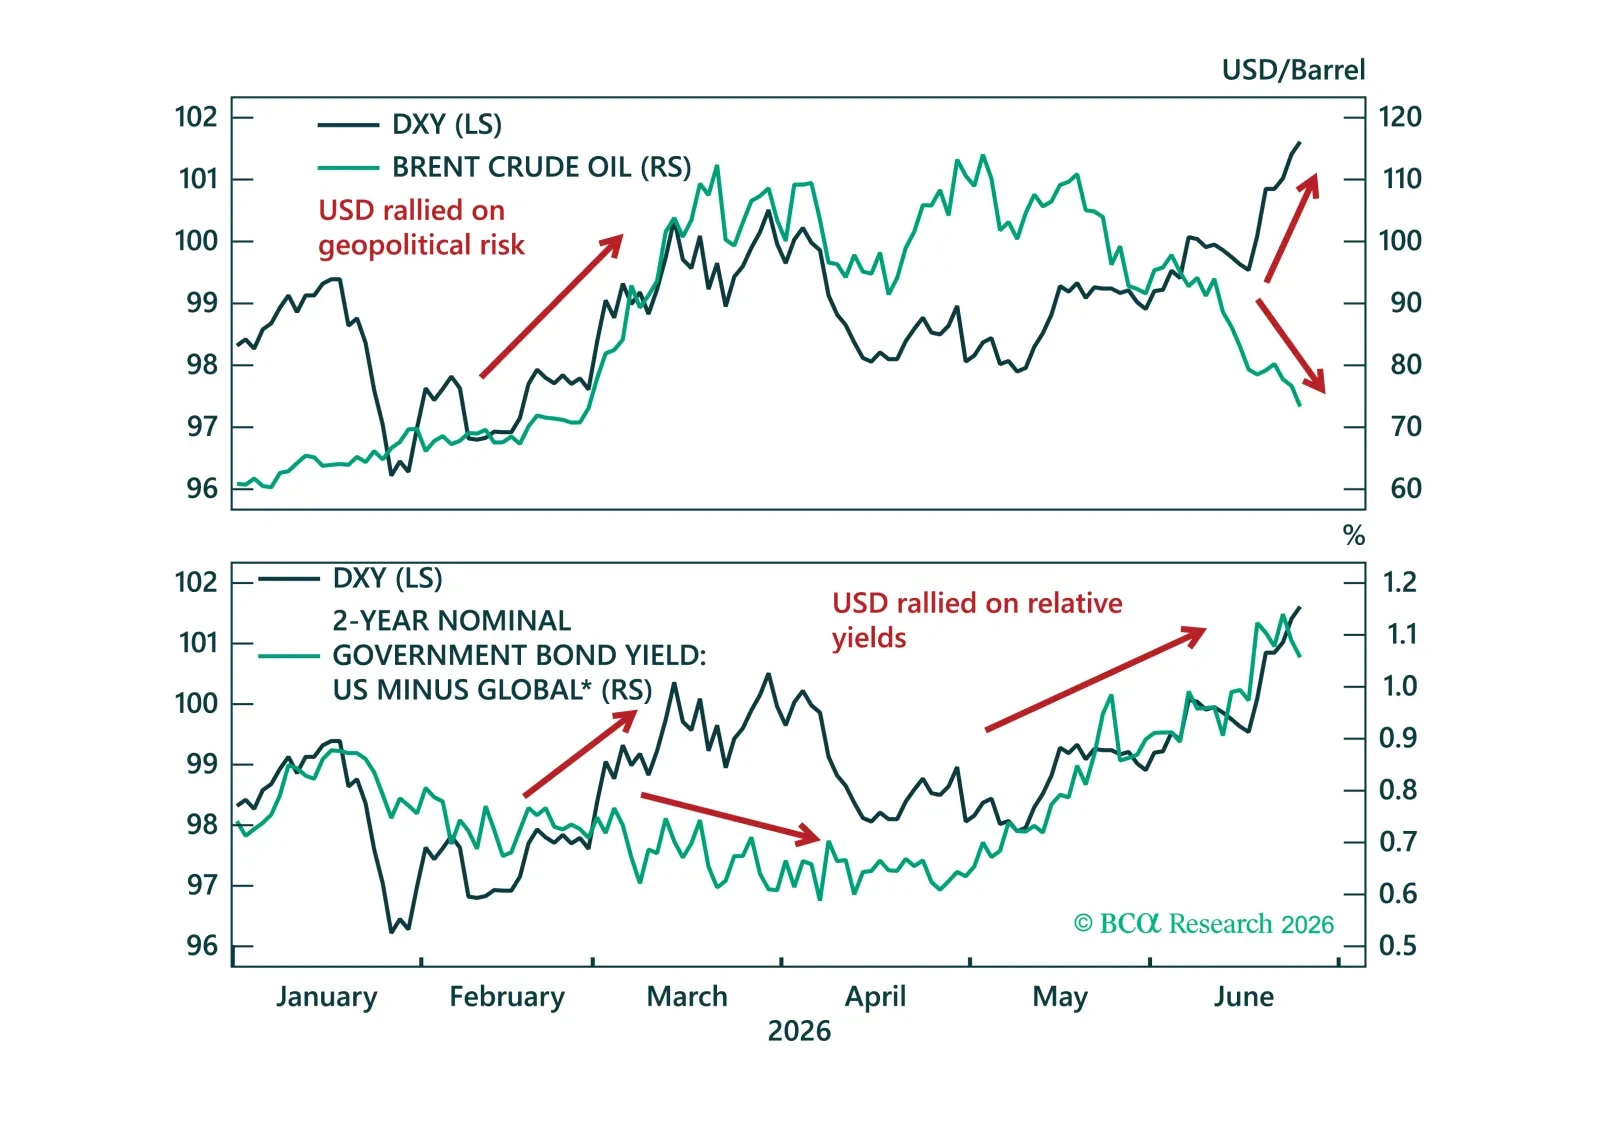
The dollar has had a strong run but its key supports from Fed repricing, positioning, and terms of trade are starting to fade. We close our tactical long USD positions and turn to short USD/JPY, where intervention risk makes yen shorts look increasingly dangerous.
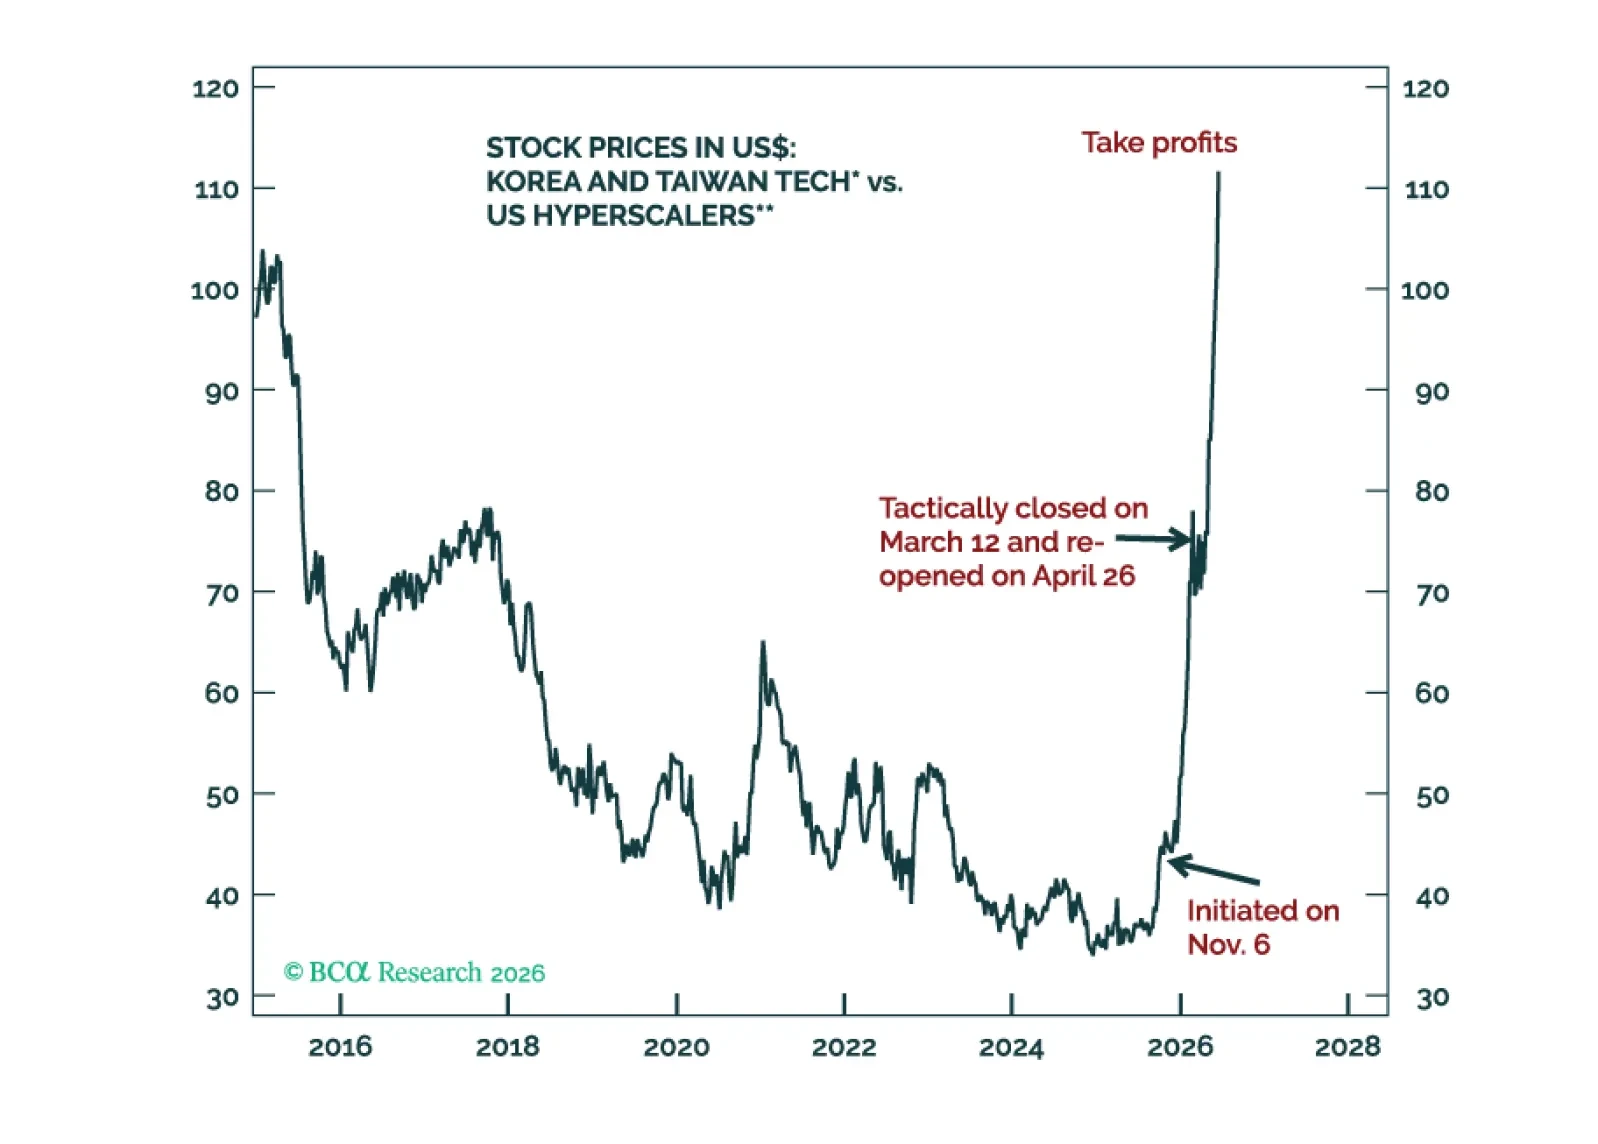
Korea’s recent equity market tantrum is a warning signal for global risk assets. We are booking profits on the long Asian semiconductor stocks / short US hyperscalers trade and downgrading Korea from overweight to neutral in an EM equity portfolio.