Latest from BCA Research
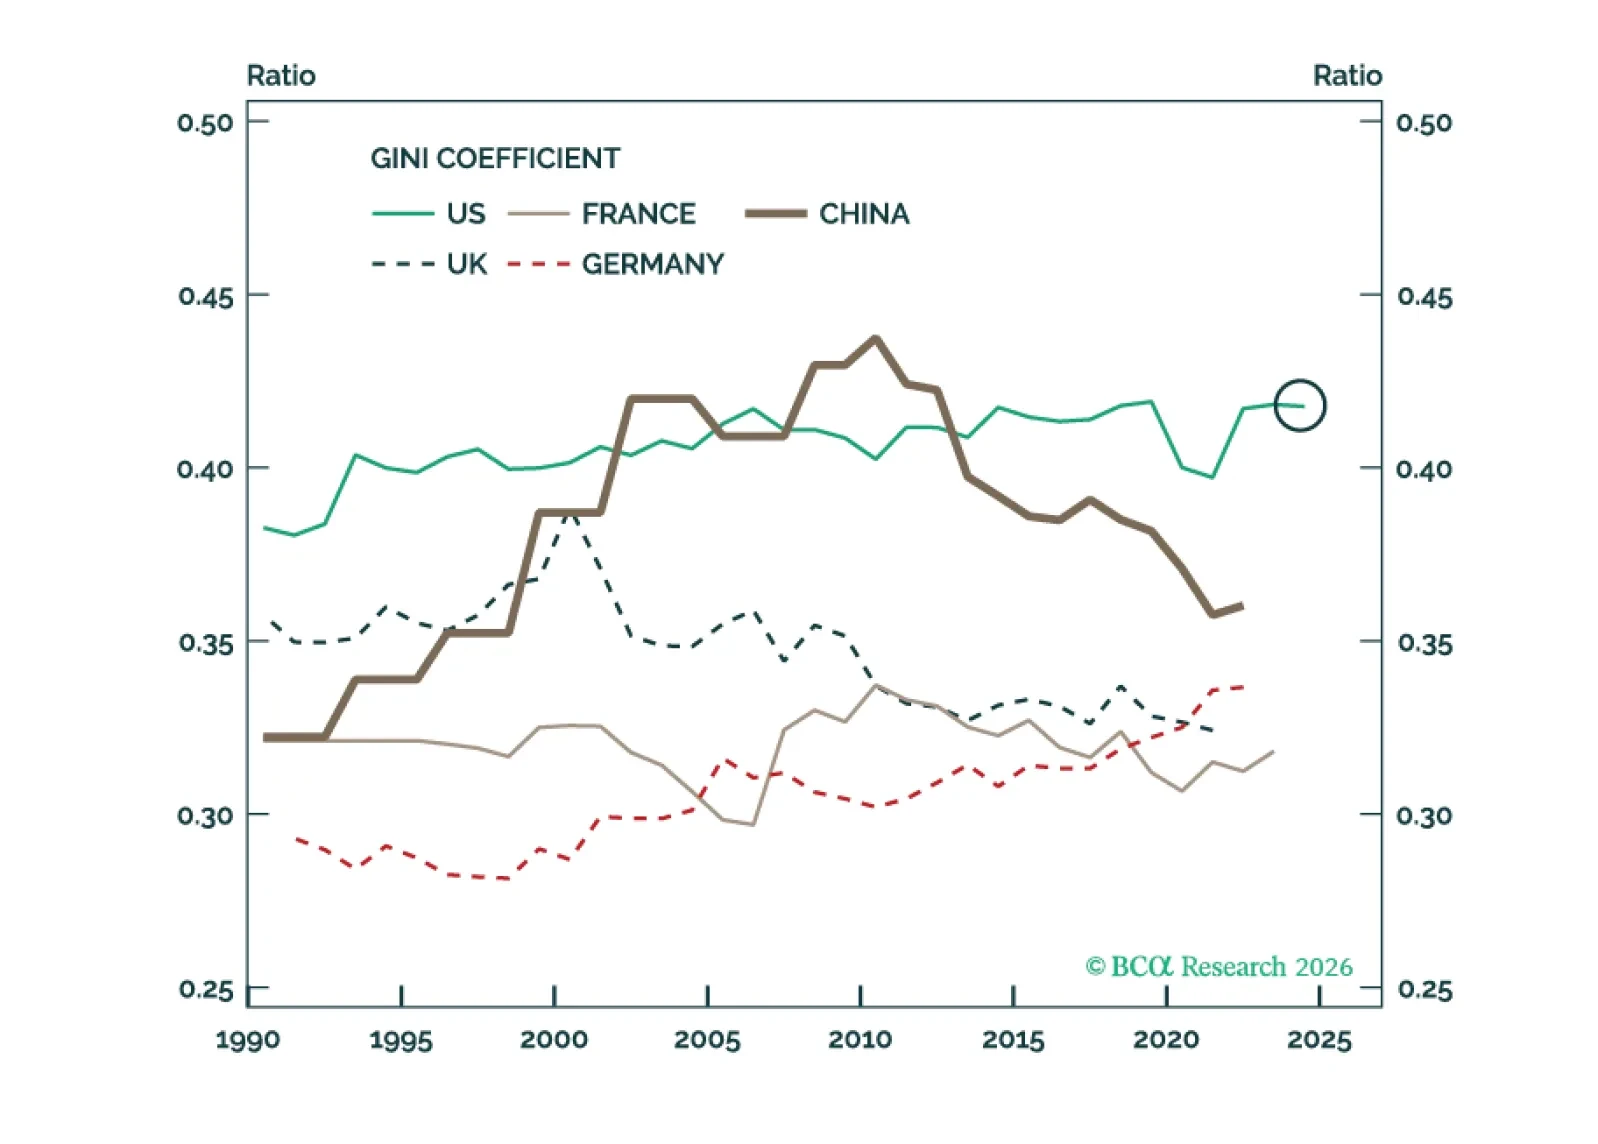
Left-wing populism will likely prevail within the Democratic Party and inspire large tax hikes in 2029. But the US does not face a socialist takeover.
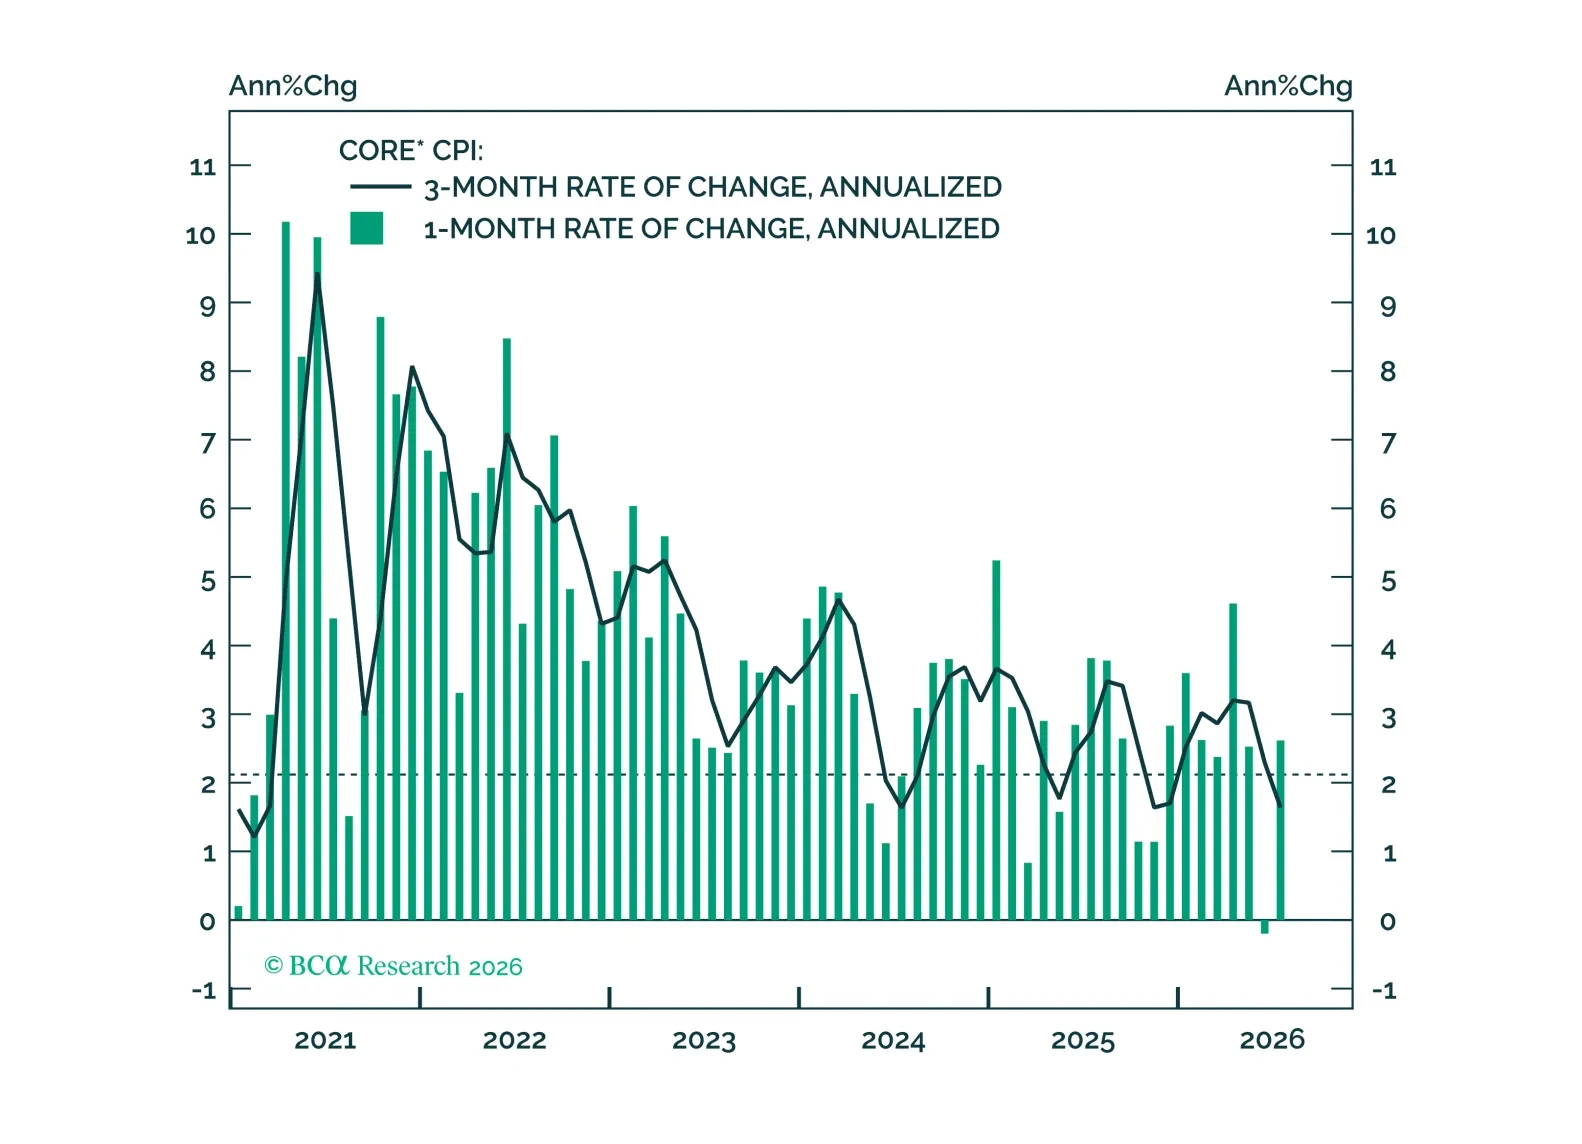
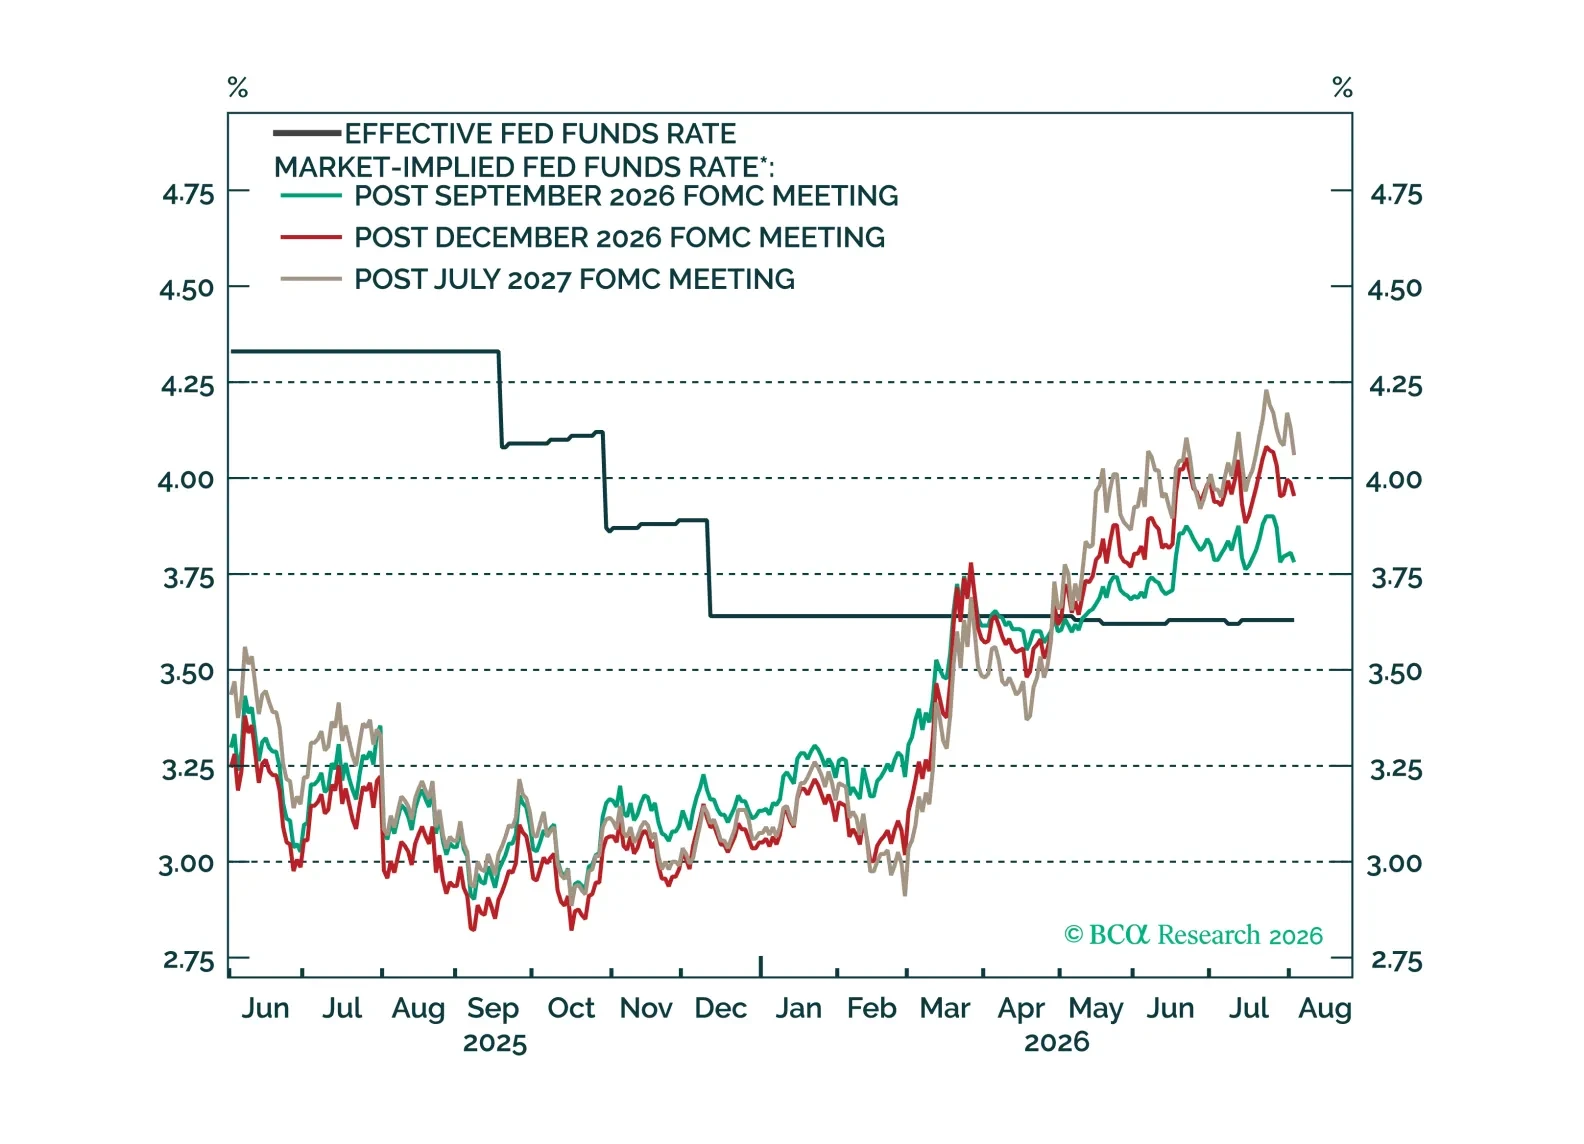
July’s CPI reading was low enough to keep the Fed on hold for now, but near-term upside inflation risks remain.
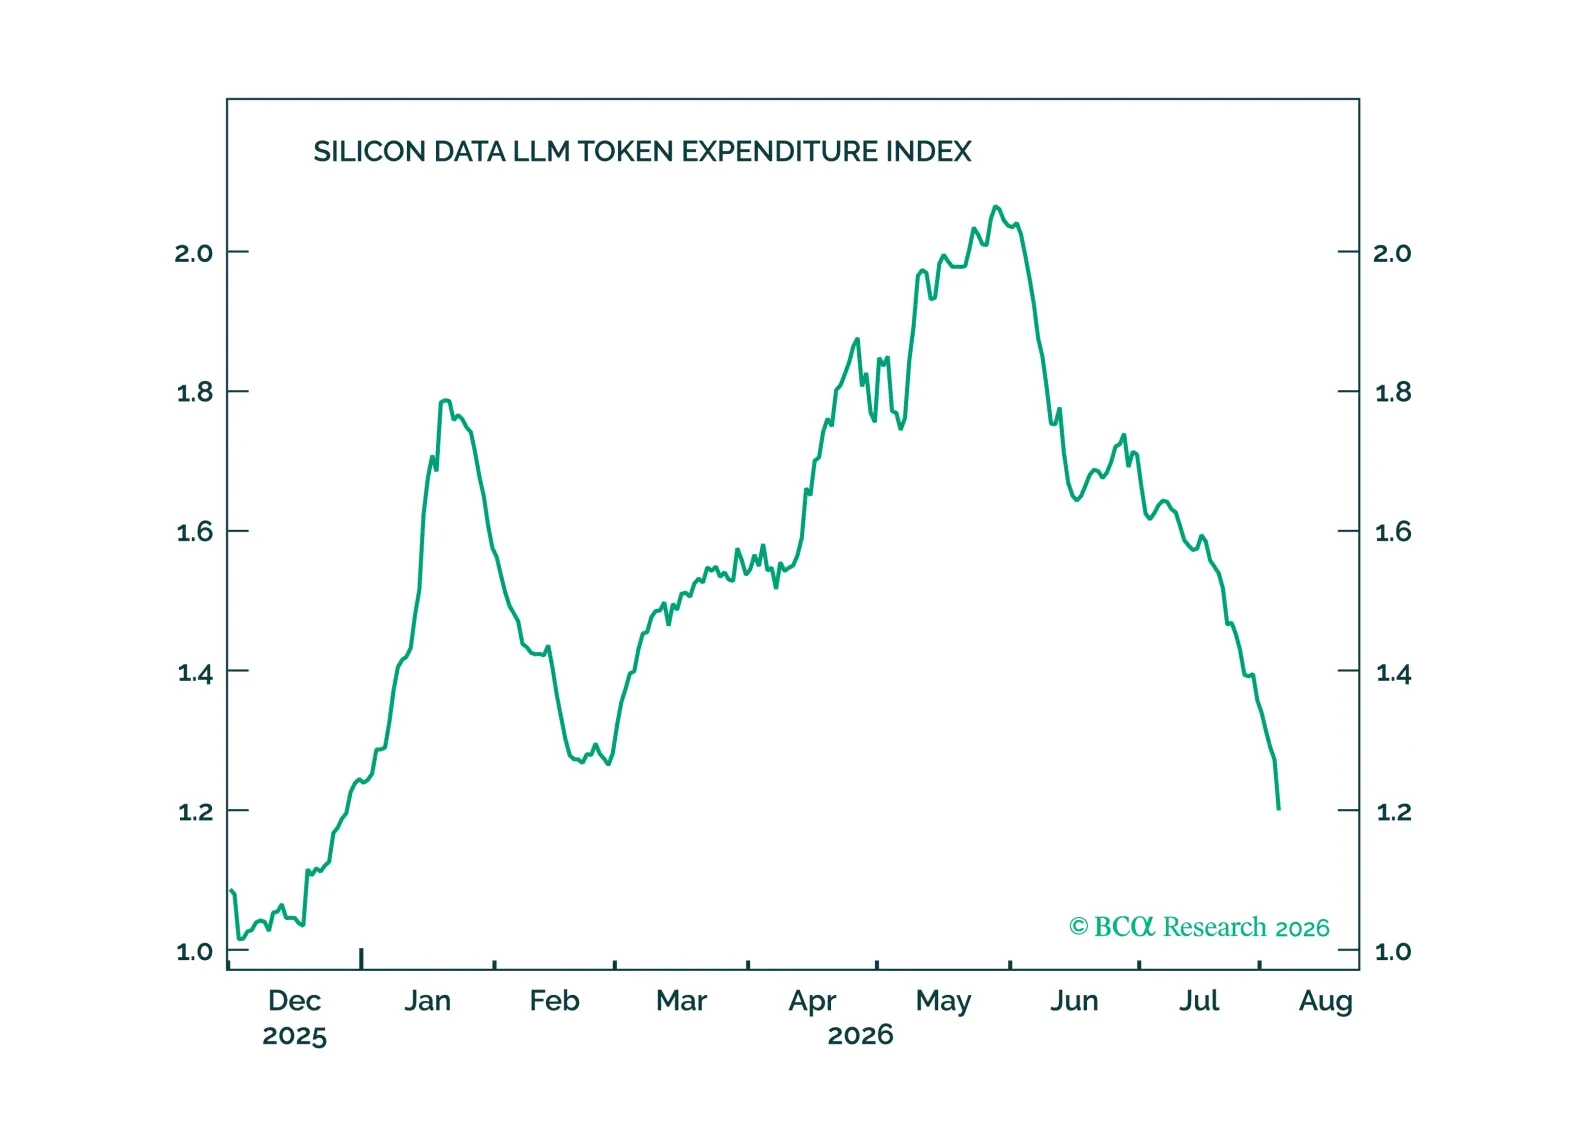
We remain tactically bullish due to the combination of geopolitical risks in the Middle East easing and the ramping up of the AI boom. In this month’s chartpack, we articulate the reasoning behind both sanguine views.
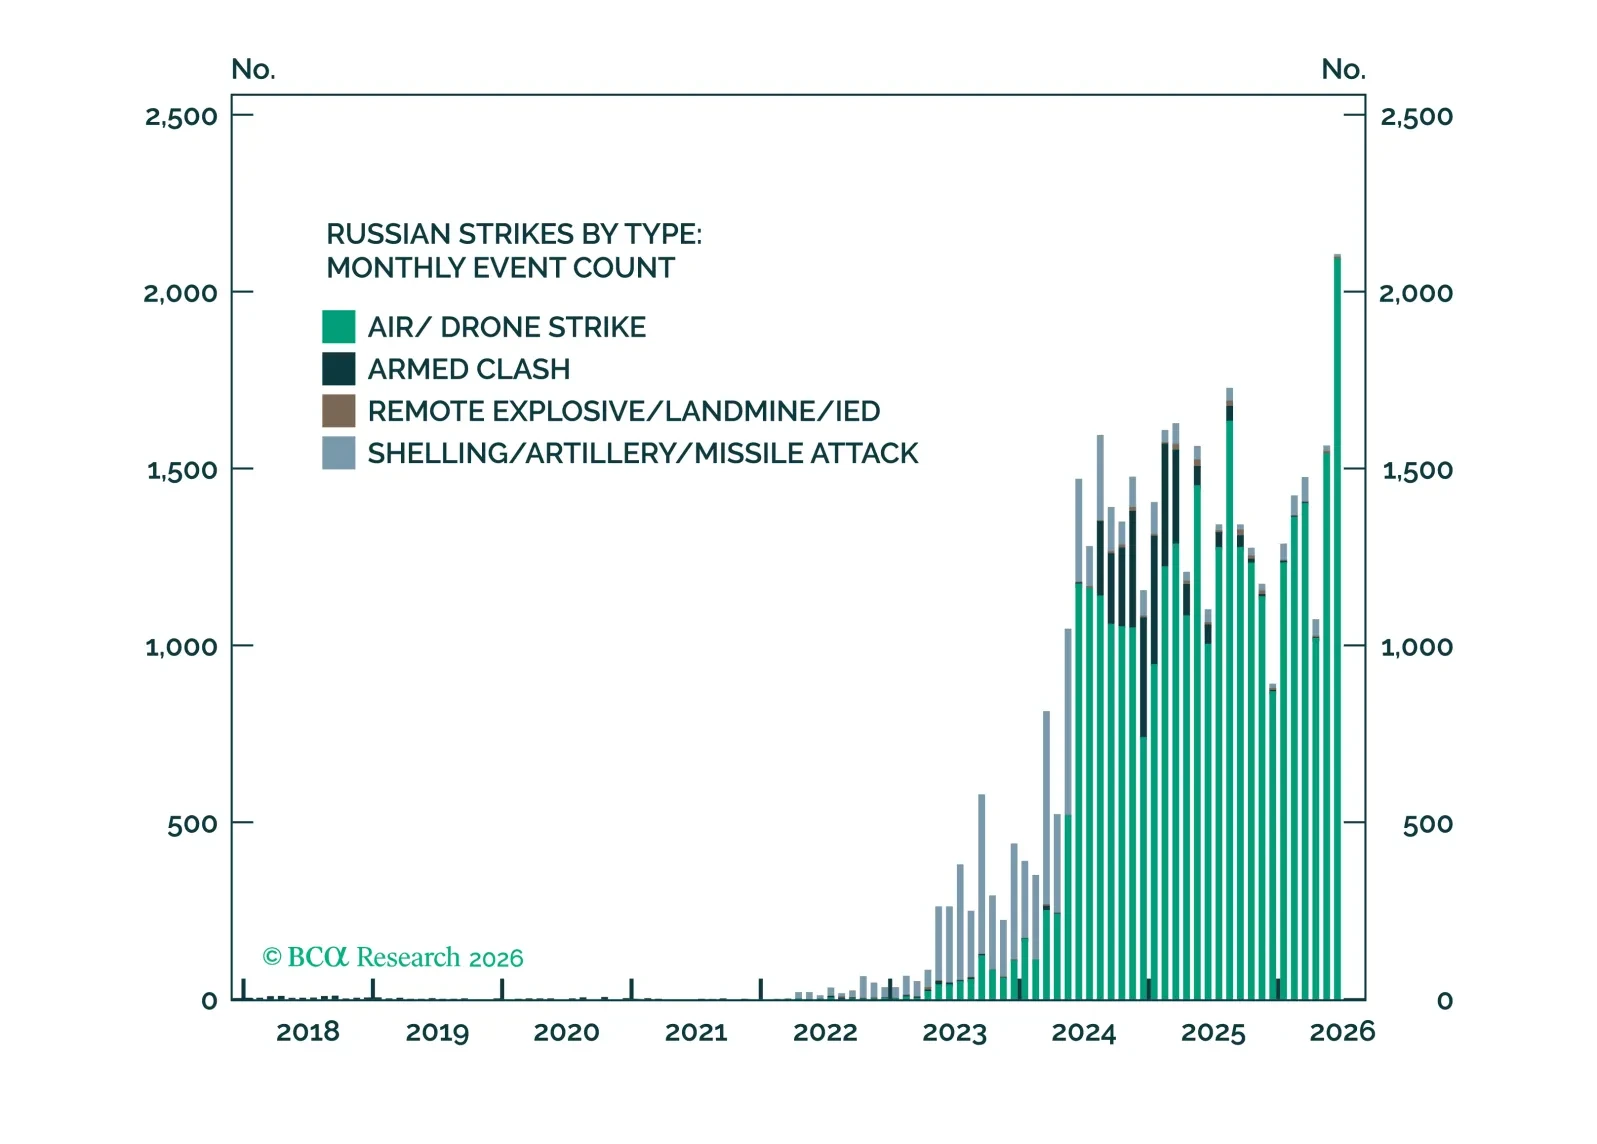
The fragile balance in the Ukraine war has broken – the conflict can escalate and take investors who are focused on Iran by surprise.
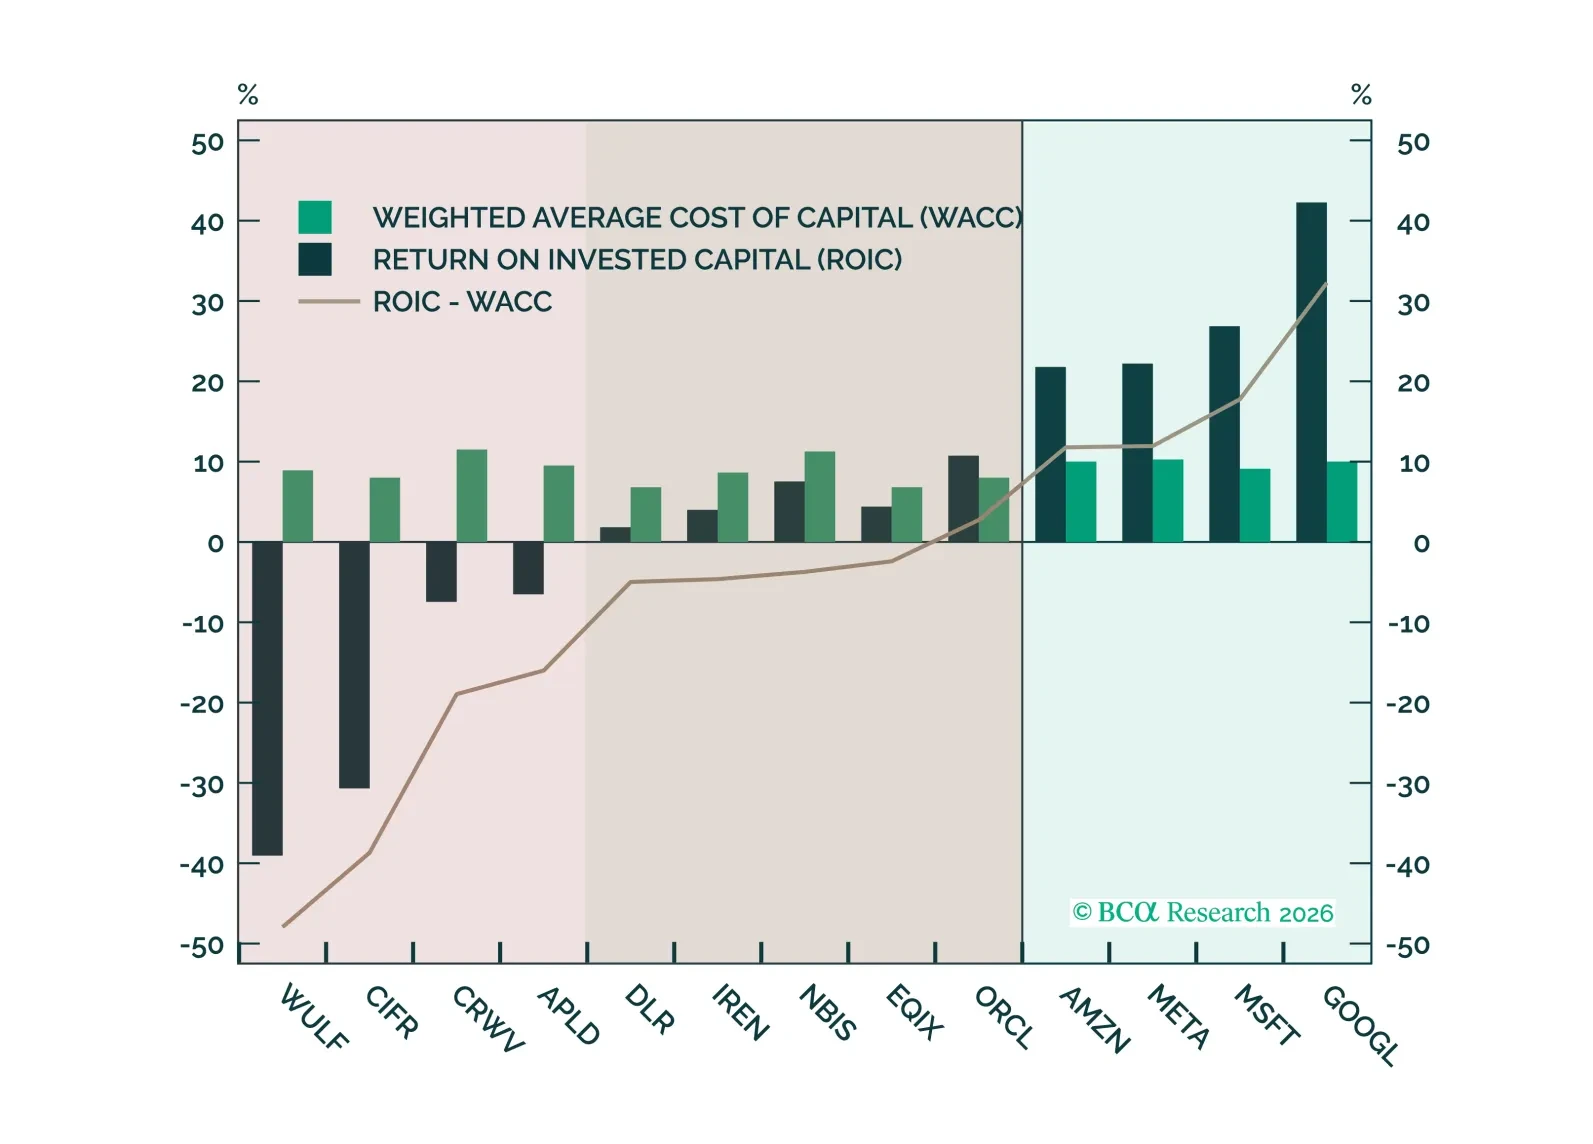
AI demand remains strong, but the capex boom is creating a growing divide within Tech. Hyperscalers combine superior margins, capital efficiency and financing capacity with multiple paths to monetize AI investment. Neoclouds rely more heavily on leverage and scarcity economics, potentially making them more vulnerable should capacity expand and compute pricing normalize.
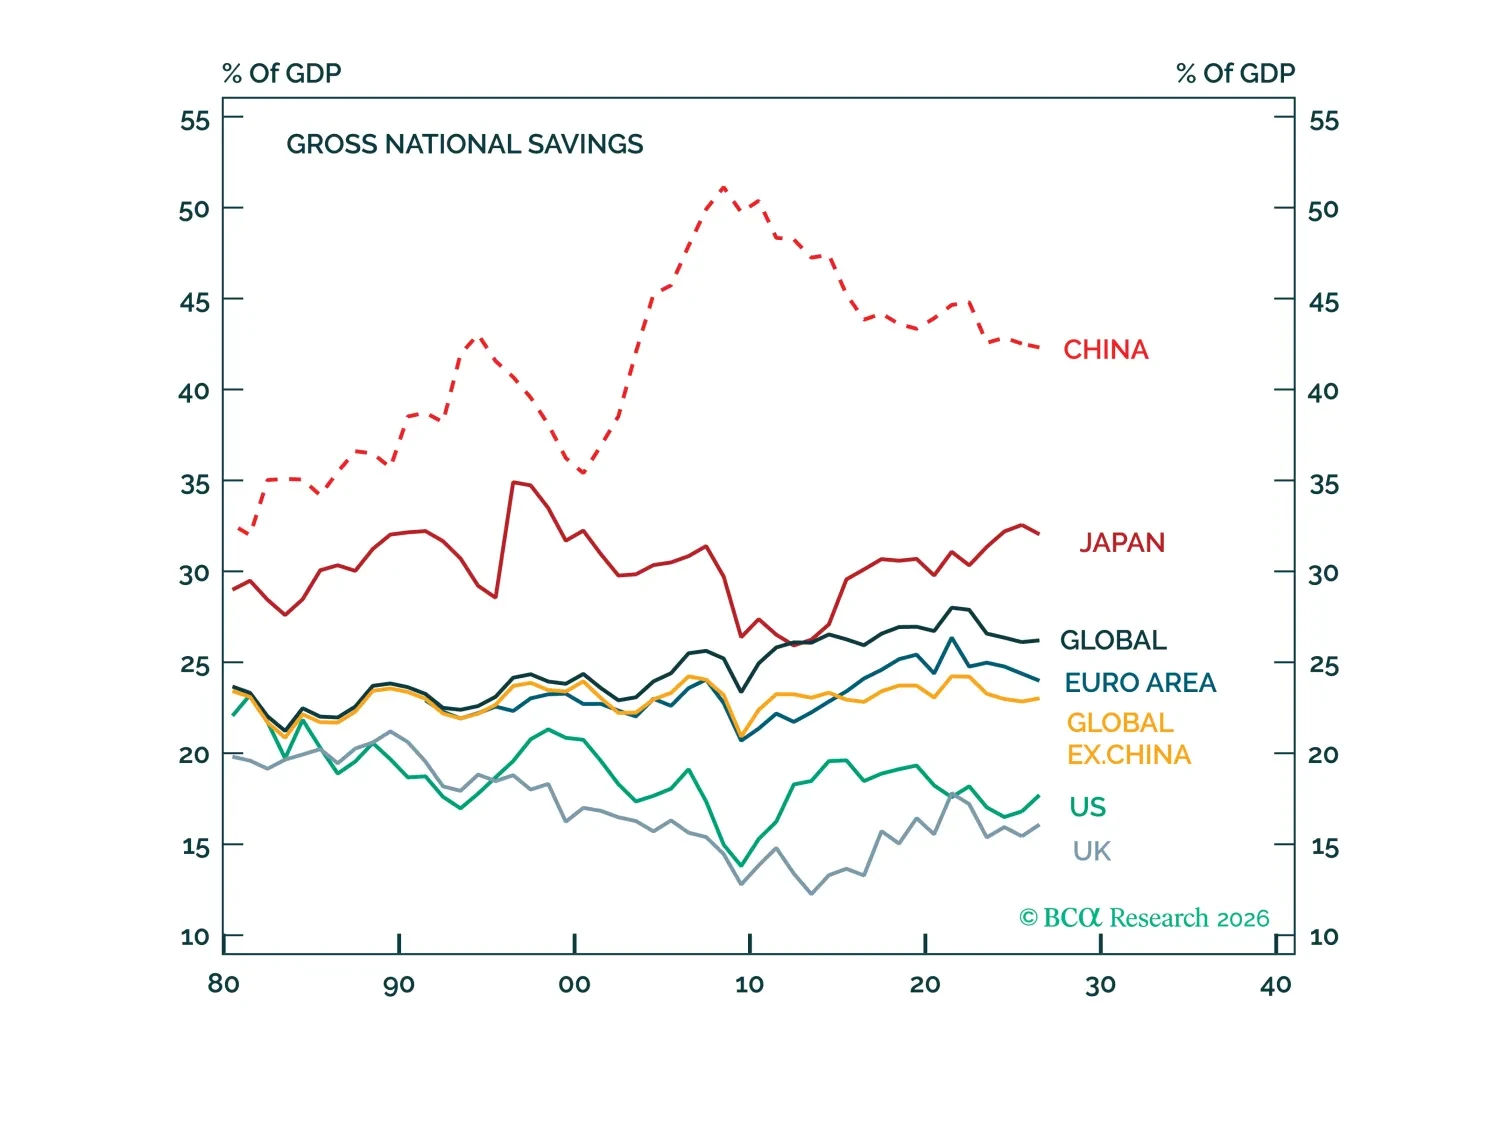
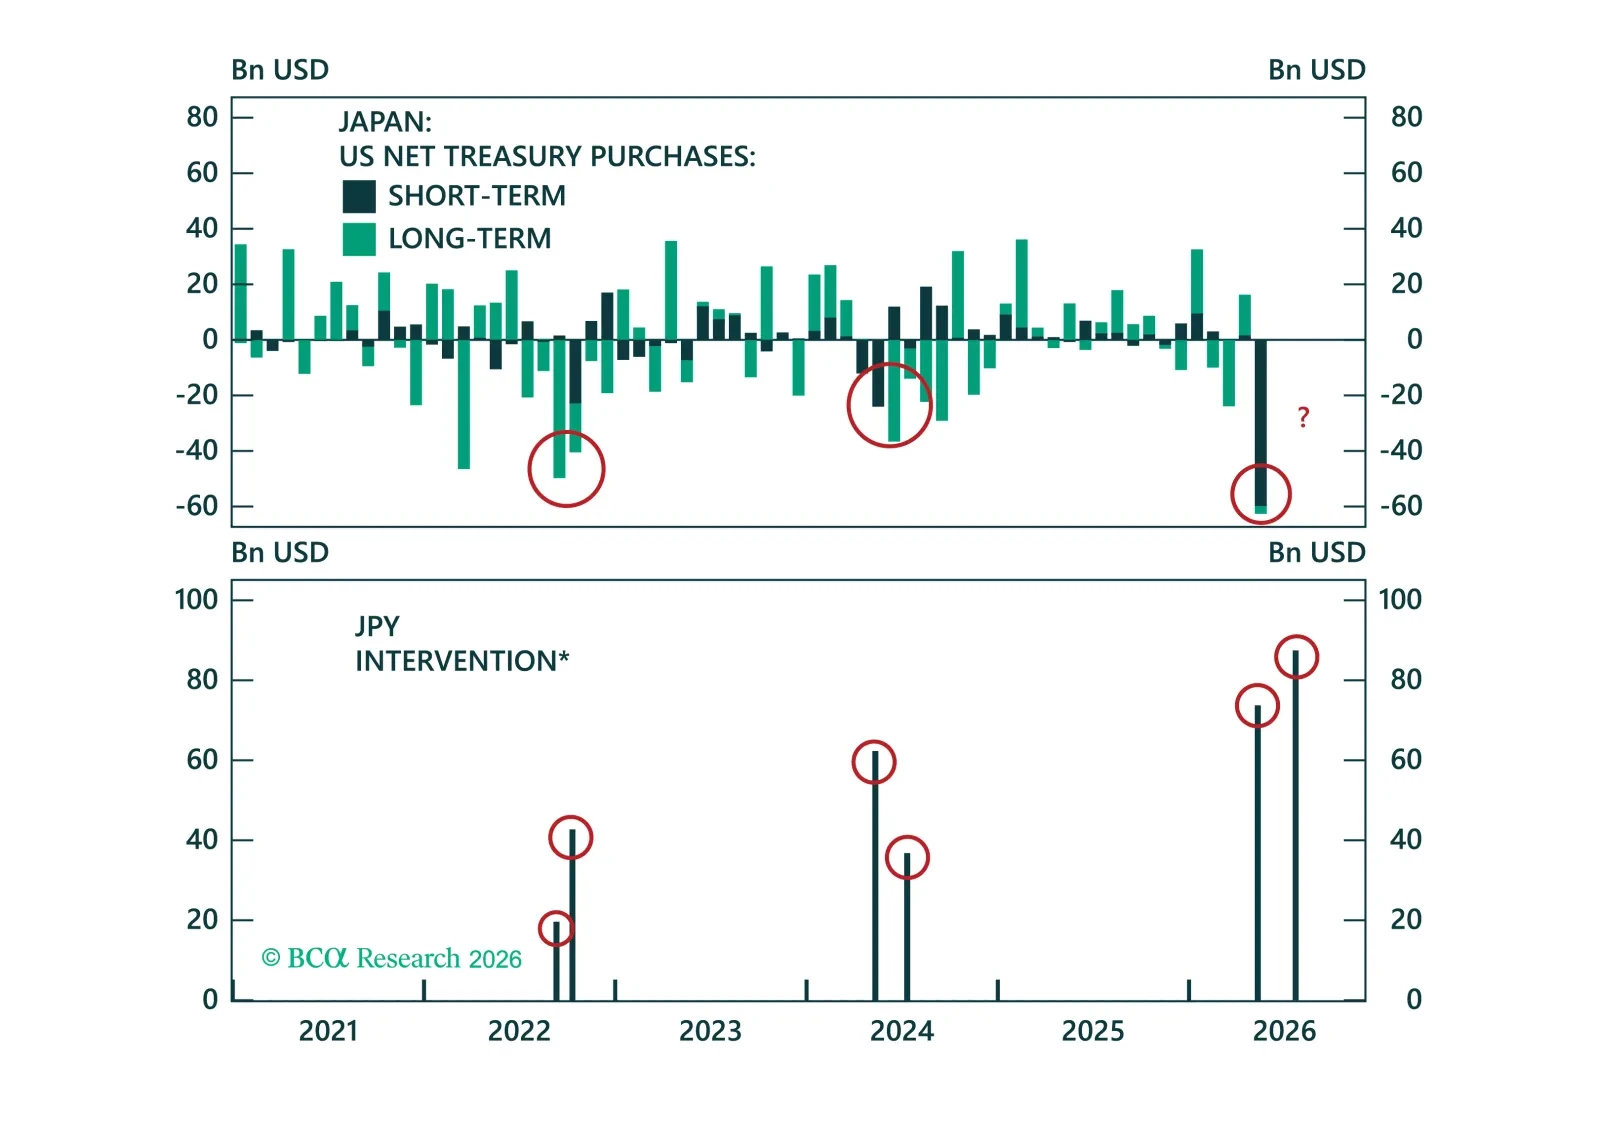
MoF and the US Treasury stepped in together to defend the yen, but even joint intervention cannot reset the fundamentals still weighing on the currency. Washington's pursuit of its own incentives, meanwhile, offers another glimpse of a more activist US Treasury.