Latest from BCA Research
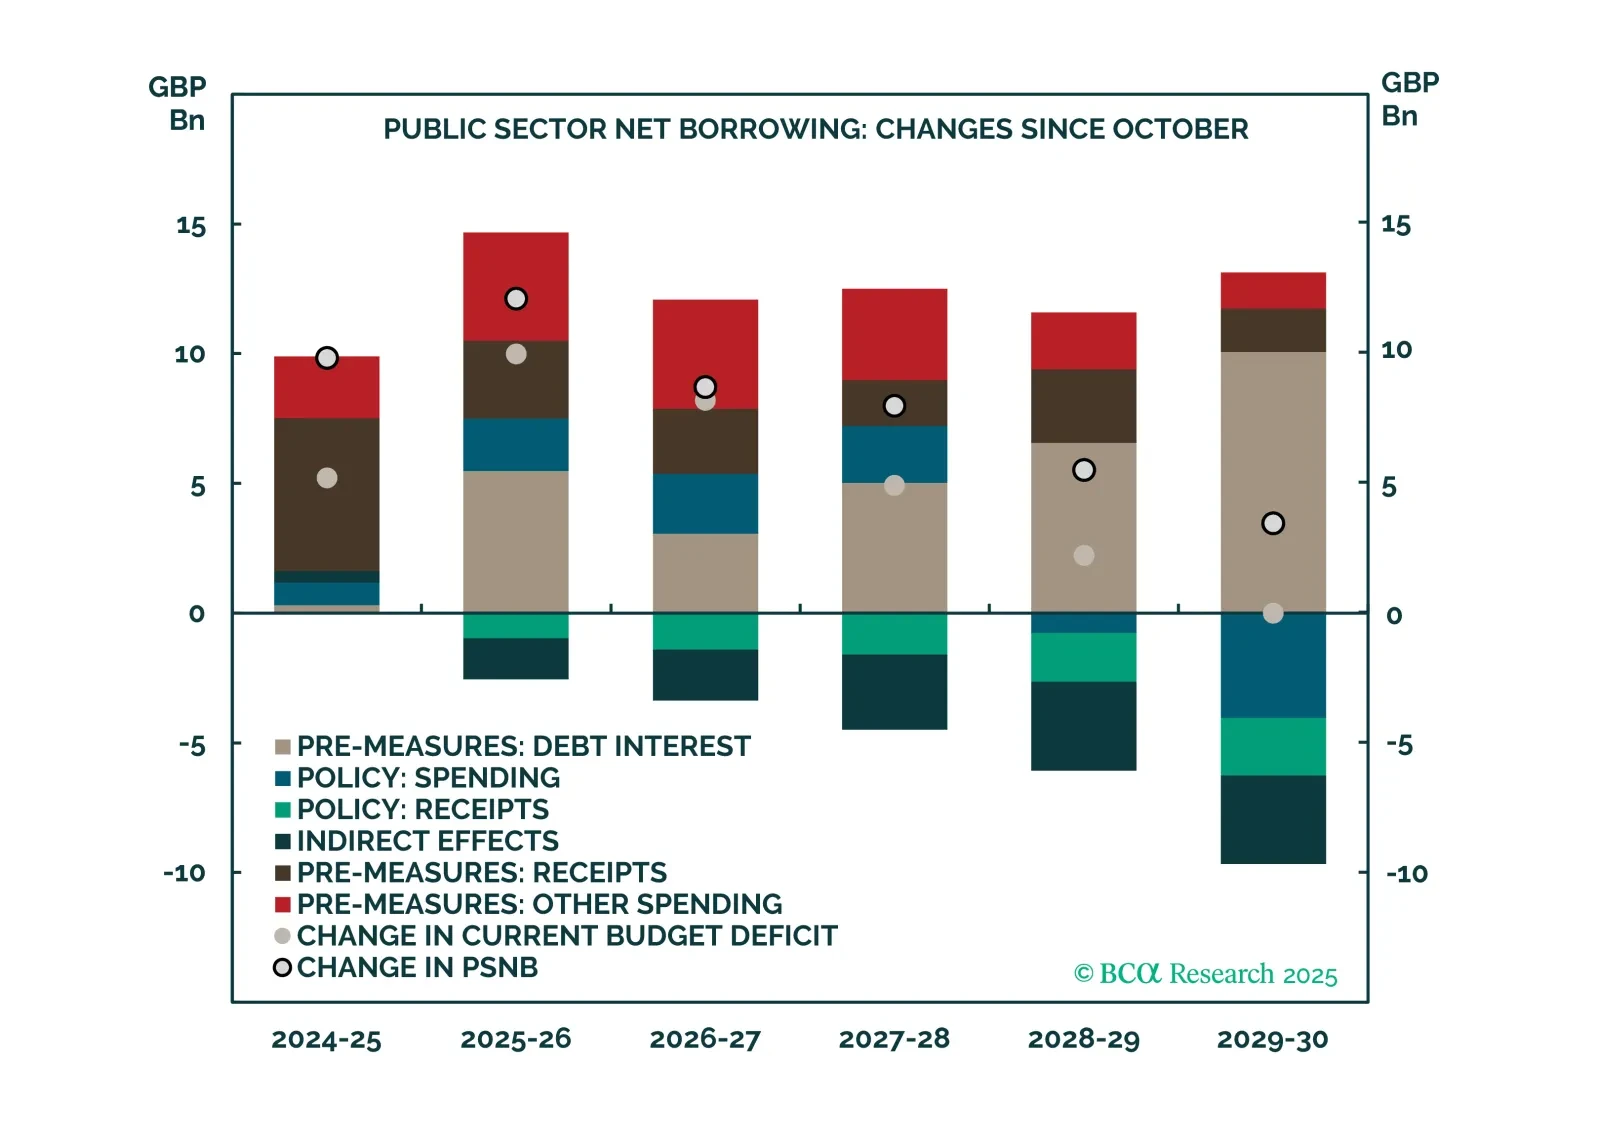
This report is a quick take on our views on UK bonds and FX, given the recent budget.
Clients have asked us repeatedly about our thoughts on the Mar-a-Lago Accord. Our readers know that we believe that the US is constrained by its median voter and the reality of geopolitical multipolarity. As such, the path of least resistance is towards a cheaper USD, which is currently being achieved through an organic macro see-saw of relative fiscal policy. The idea that the US gets to “restructure the global trading system” on its own is, therefore, ludicrous.
This report presents our interpretation of signals from the main equity, bond, and currency markets around the world. The key takeaways are: (1) Chinese stocks are behind the resilience of the EM MSCI Index; (2) Investors have become too bullish on Europe and will be disappointed; (3) The US dollar will likely rebound in the near term; (4) US long-term bond yields will be sticky in the short run; (5) The global equity selloff is not over.
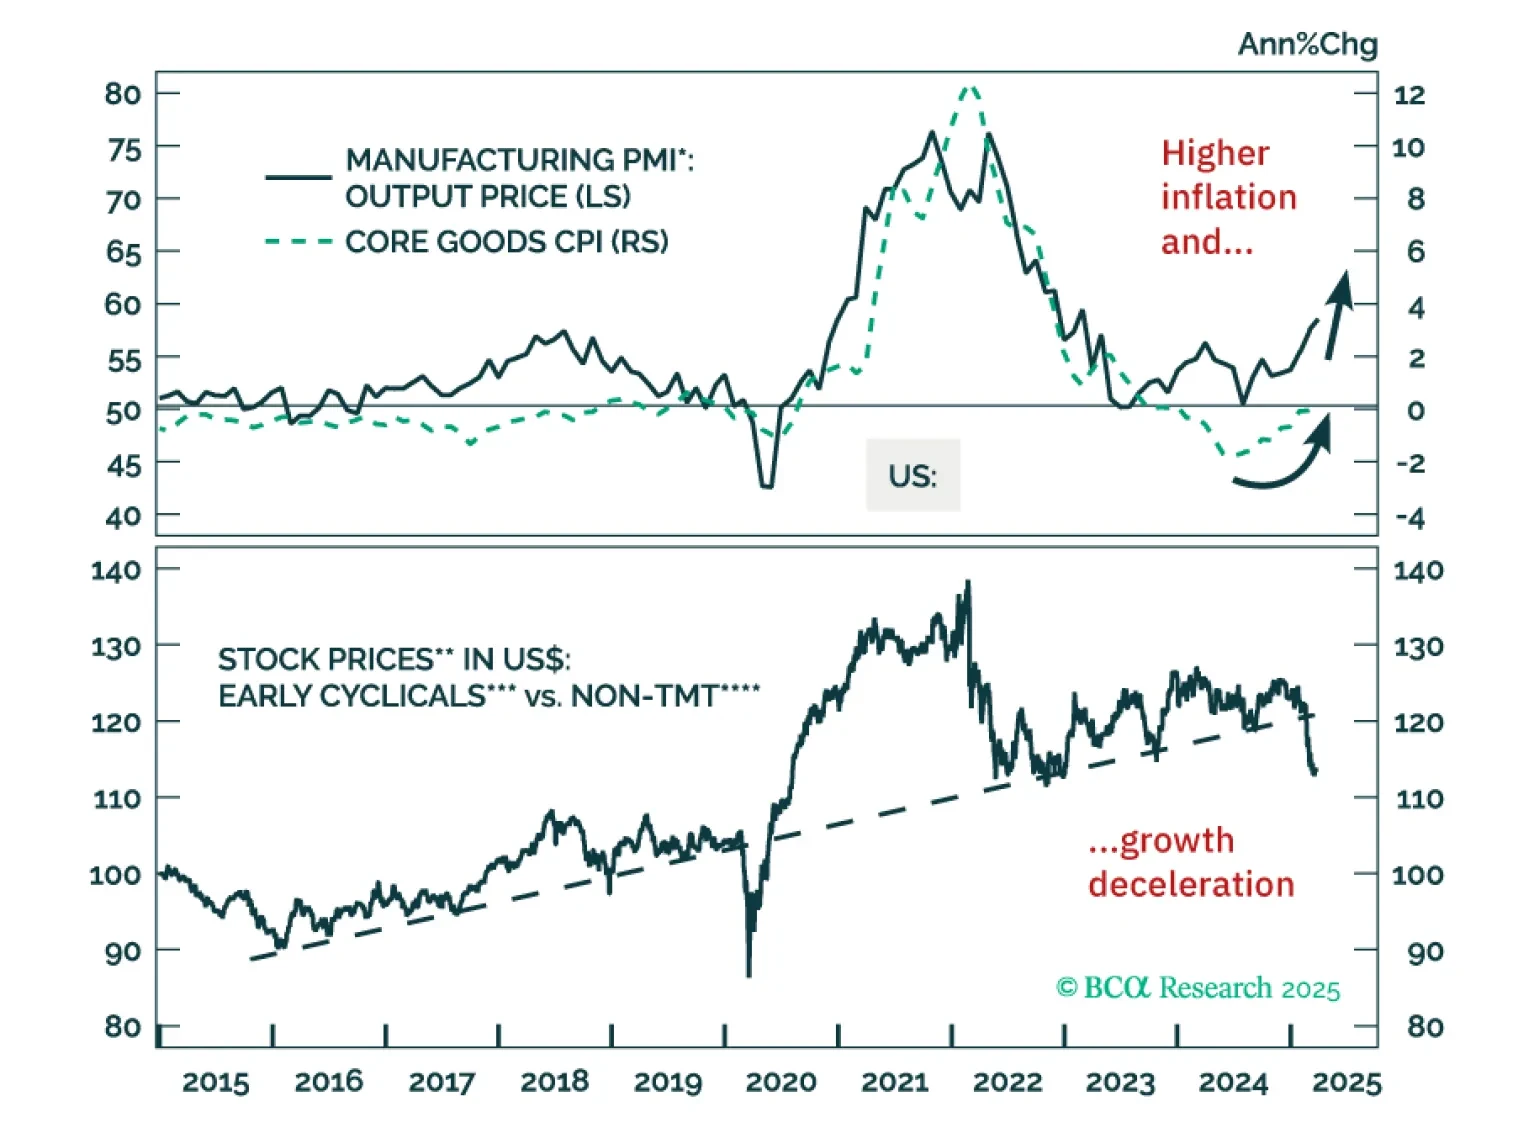
The US economy faces a new investment regime characterized by tighter fiscal and easier monetary policies. The market corrected fast, and a short-lived equity rebound is likely. However, over the long term, US equities face economic headwinds.
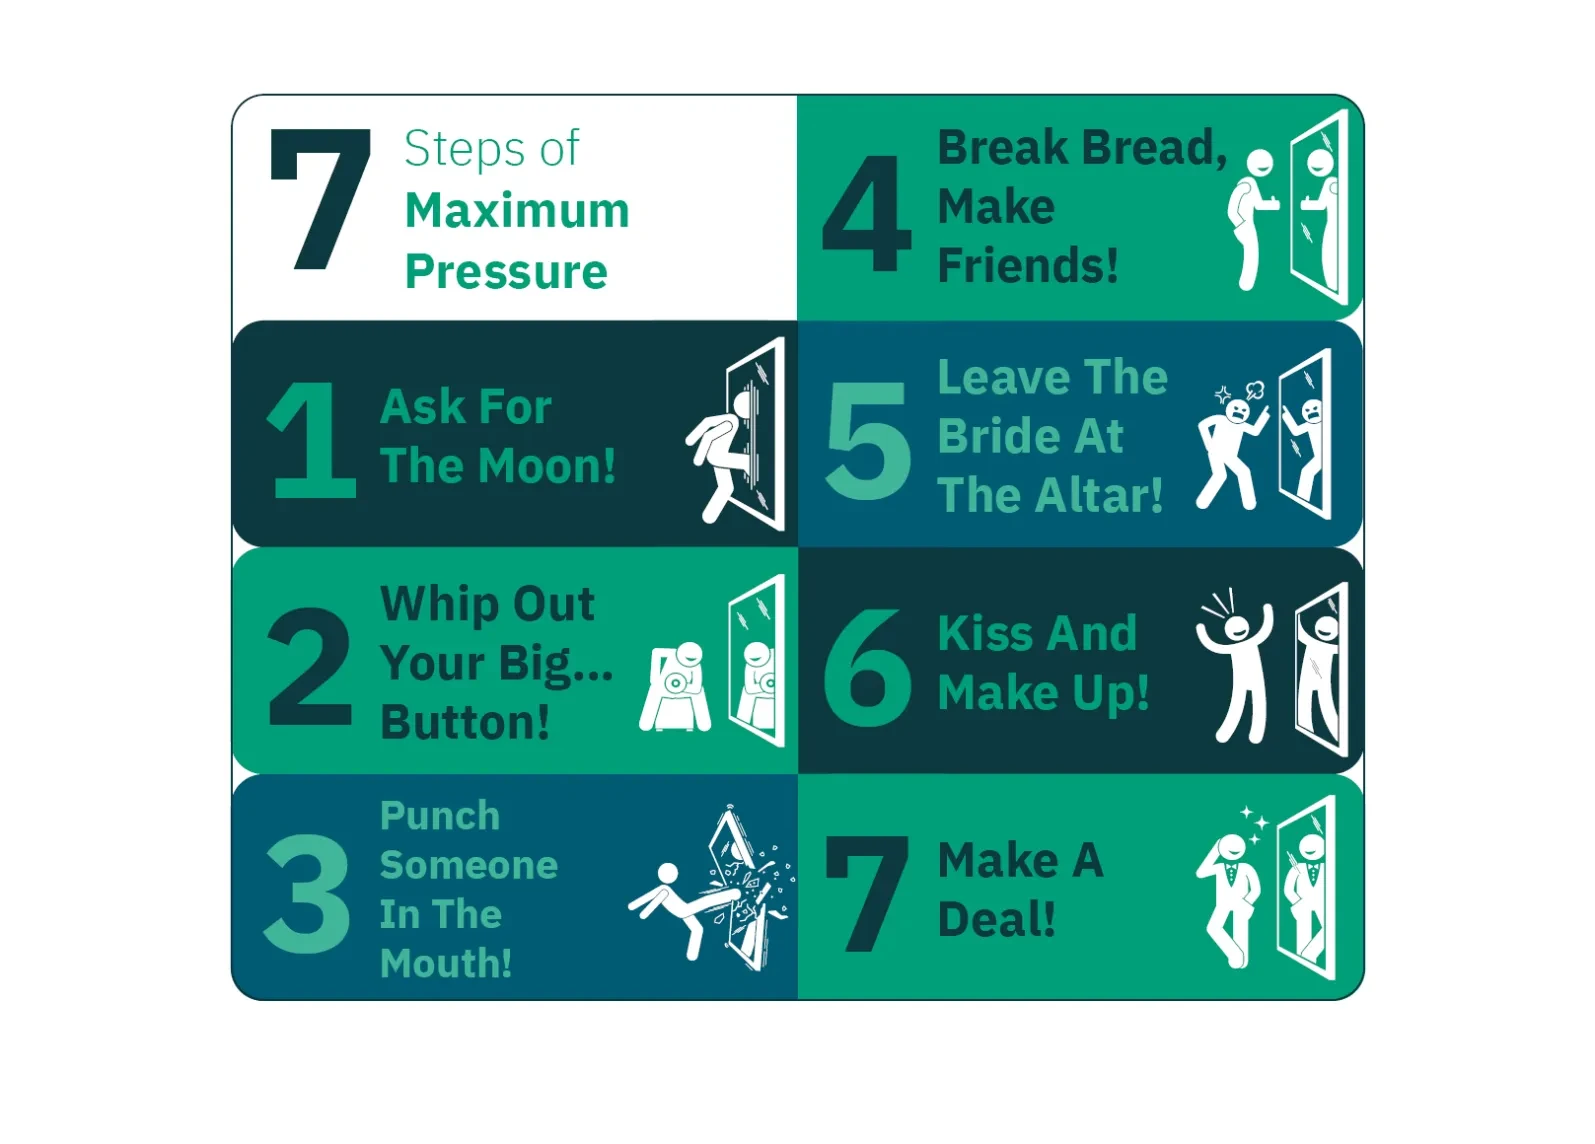
We share with our clients a brief rundown of “Washington, DC” intelligence on the upcoming April 2 tariffs. Most of it is bearish. However, the day may mark “peak de-globalization hysteria.” President Trump is also starting his Maximum Pressure campaign against Iran. That is two such campaigns at the same time, perhaps more than the administration can handle simultaneously.

An analysis of historical data shows that Ba-rated bonds outperform other corporate credit tiers in the long-run on a risk-adjusted basis. That said, today’s fragile macro environment warrants a more cautious allocation.

Households’ healthy balance sheets do not square with the rise in credit cards and auto loans delinquencies. The tailwinds that have supported higher-income cohorts’ spending have faded, presaging broad-based deterioration in credit performance.
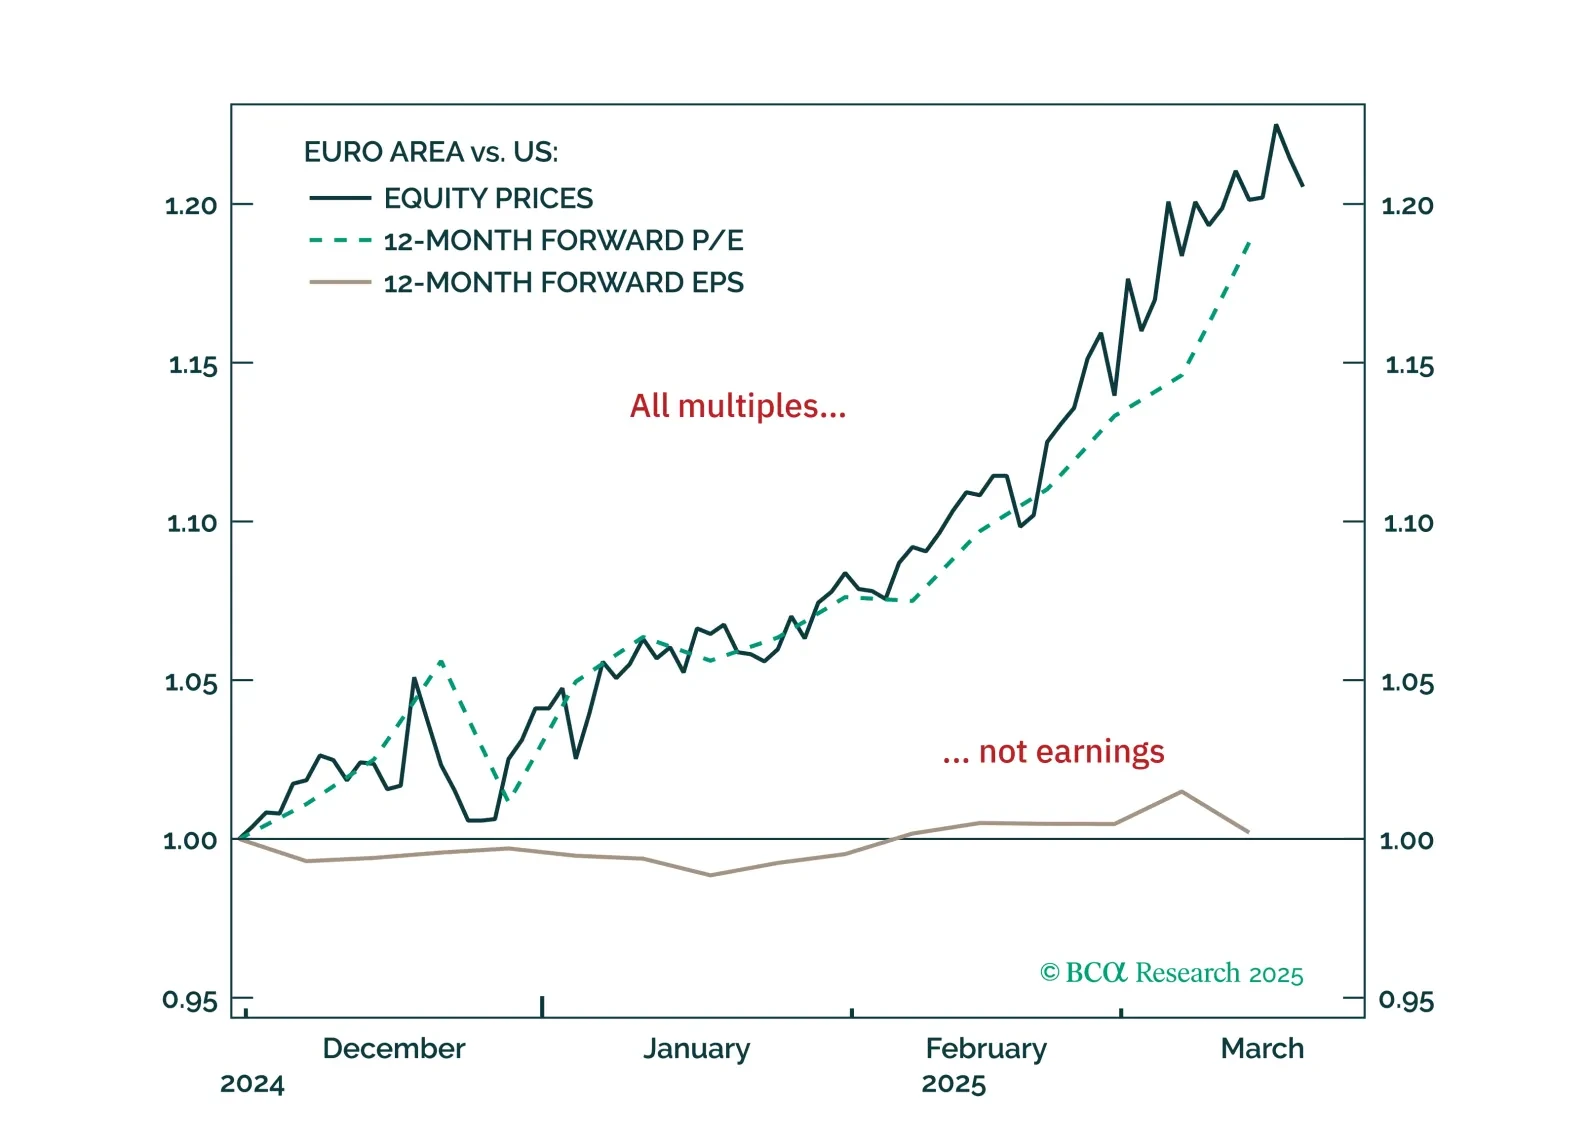
European equities have surged on hopes of a low-inflation boom—but the rally has likely gone too far, too fast. With a pullback now likely, how should investors position themselves over the next 3–6 months?
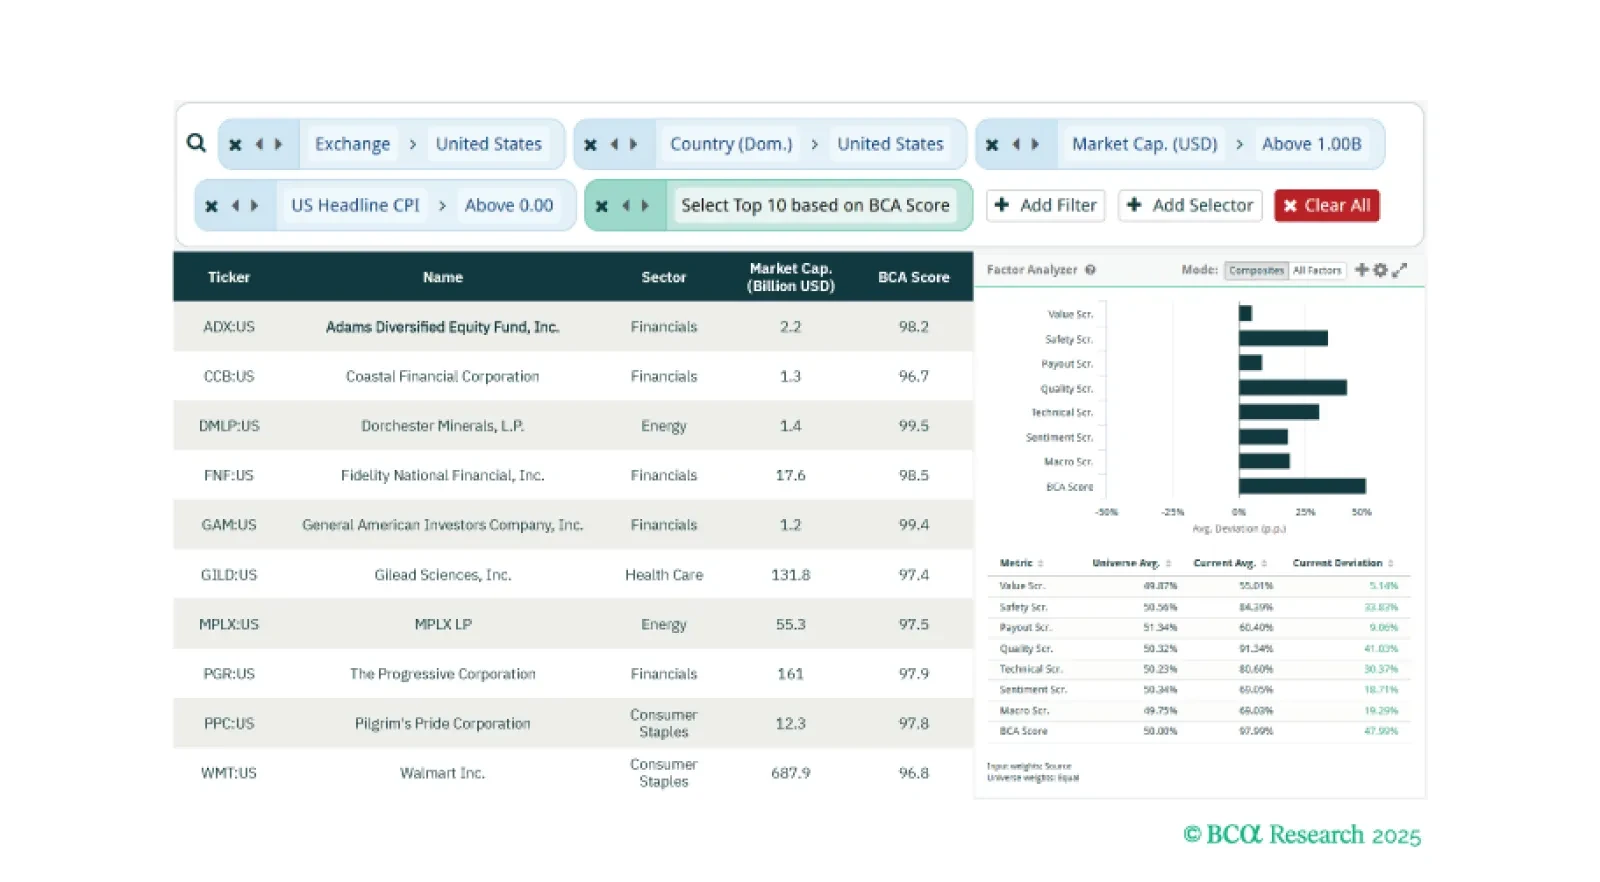
Weekly Screeners: “Transitory” Inflation 2.0, European Aerospace & Defense, And Buffett’s Philosophy
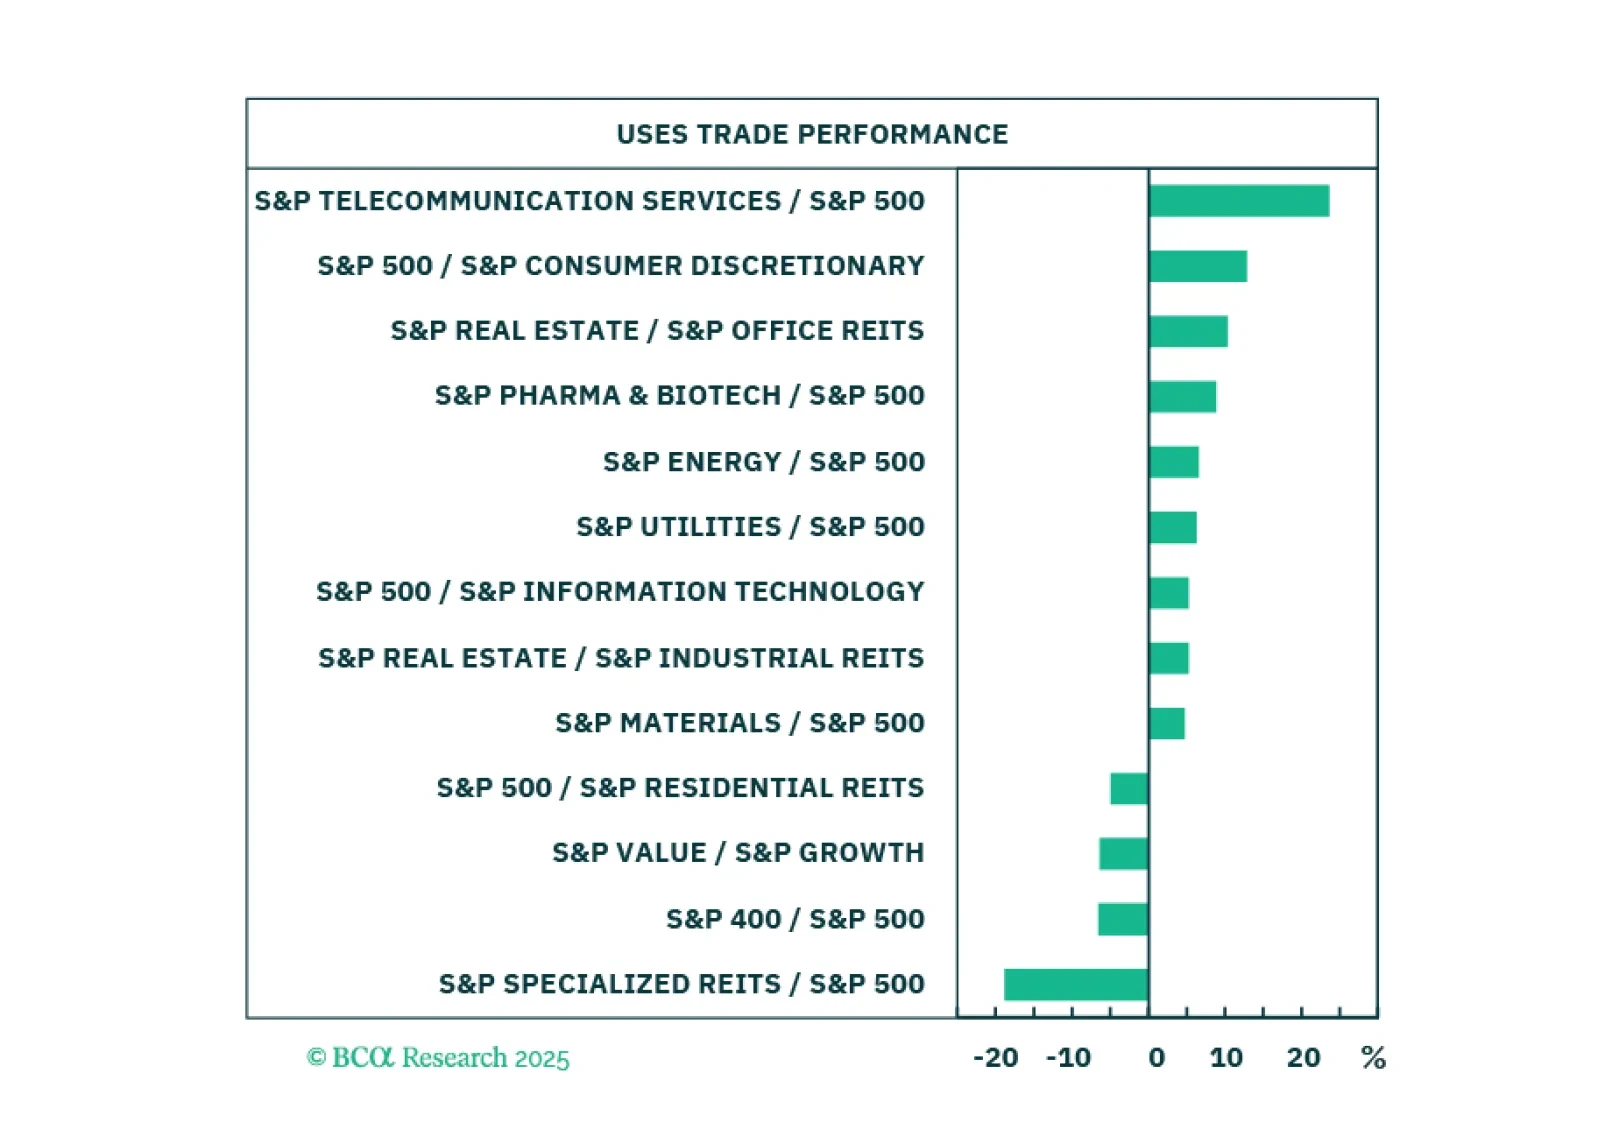
This week, our three screeners cover equity plays for “transitory” inflation impacts from US tariffs, a correction in sentiment within the European Aerospace and Defense industry, and Value Investor, Warren Buffett’s Philosophy.

Brazilian policymakers are stuck between a rock and a hard place. There is no combination of fiscal and monetary policies that can assure decent growth, on-target inflation, a stable exchange rate, and public debt sustainability. We recommend investors maintain an underweight allocation to Brazilian fixed-income markets versus their EM peers and continue shorting BRL versus MXN. We have been bearish on the Bovespa in absolute terms and are now downgrading Brazilian stocks from neutral to underweight within an EM equity portfolio.