Latest from BCA Research
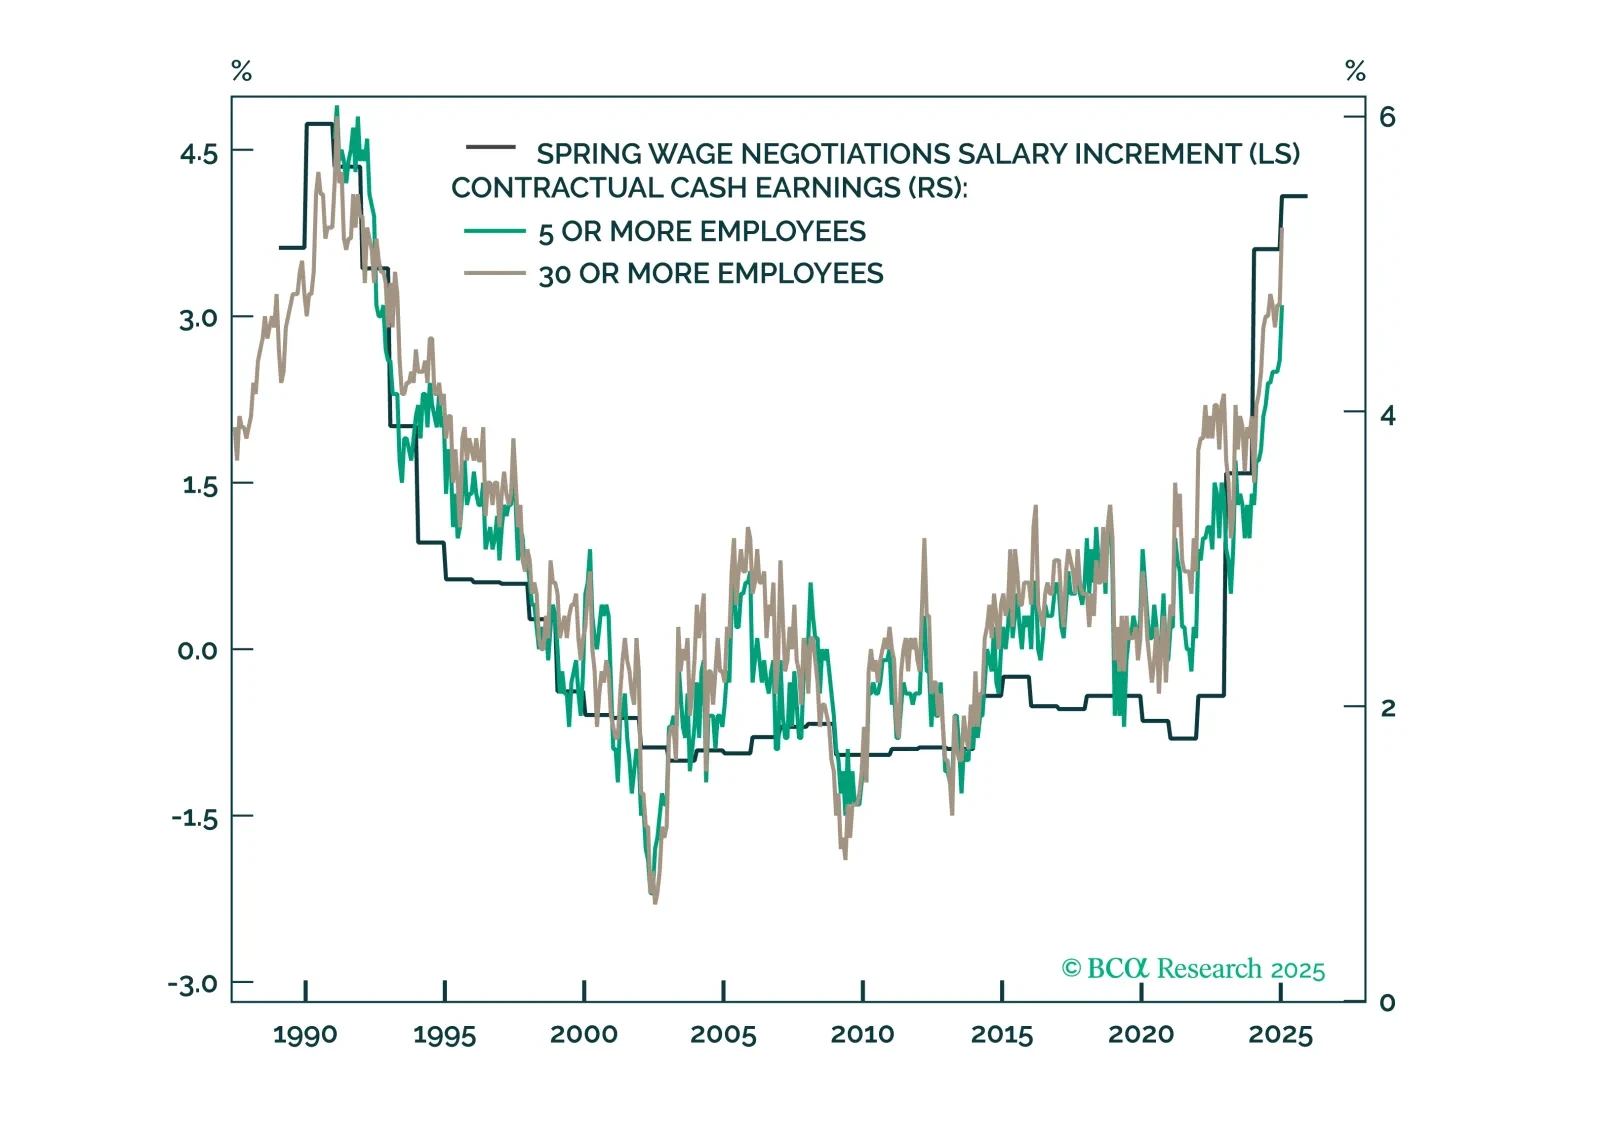
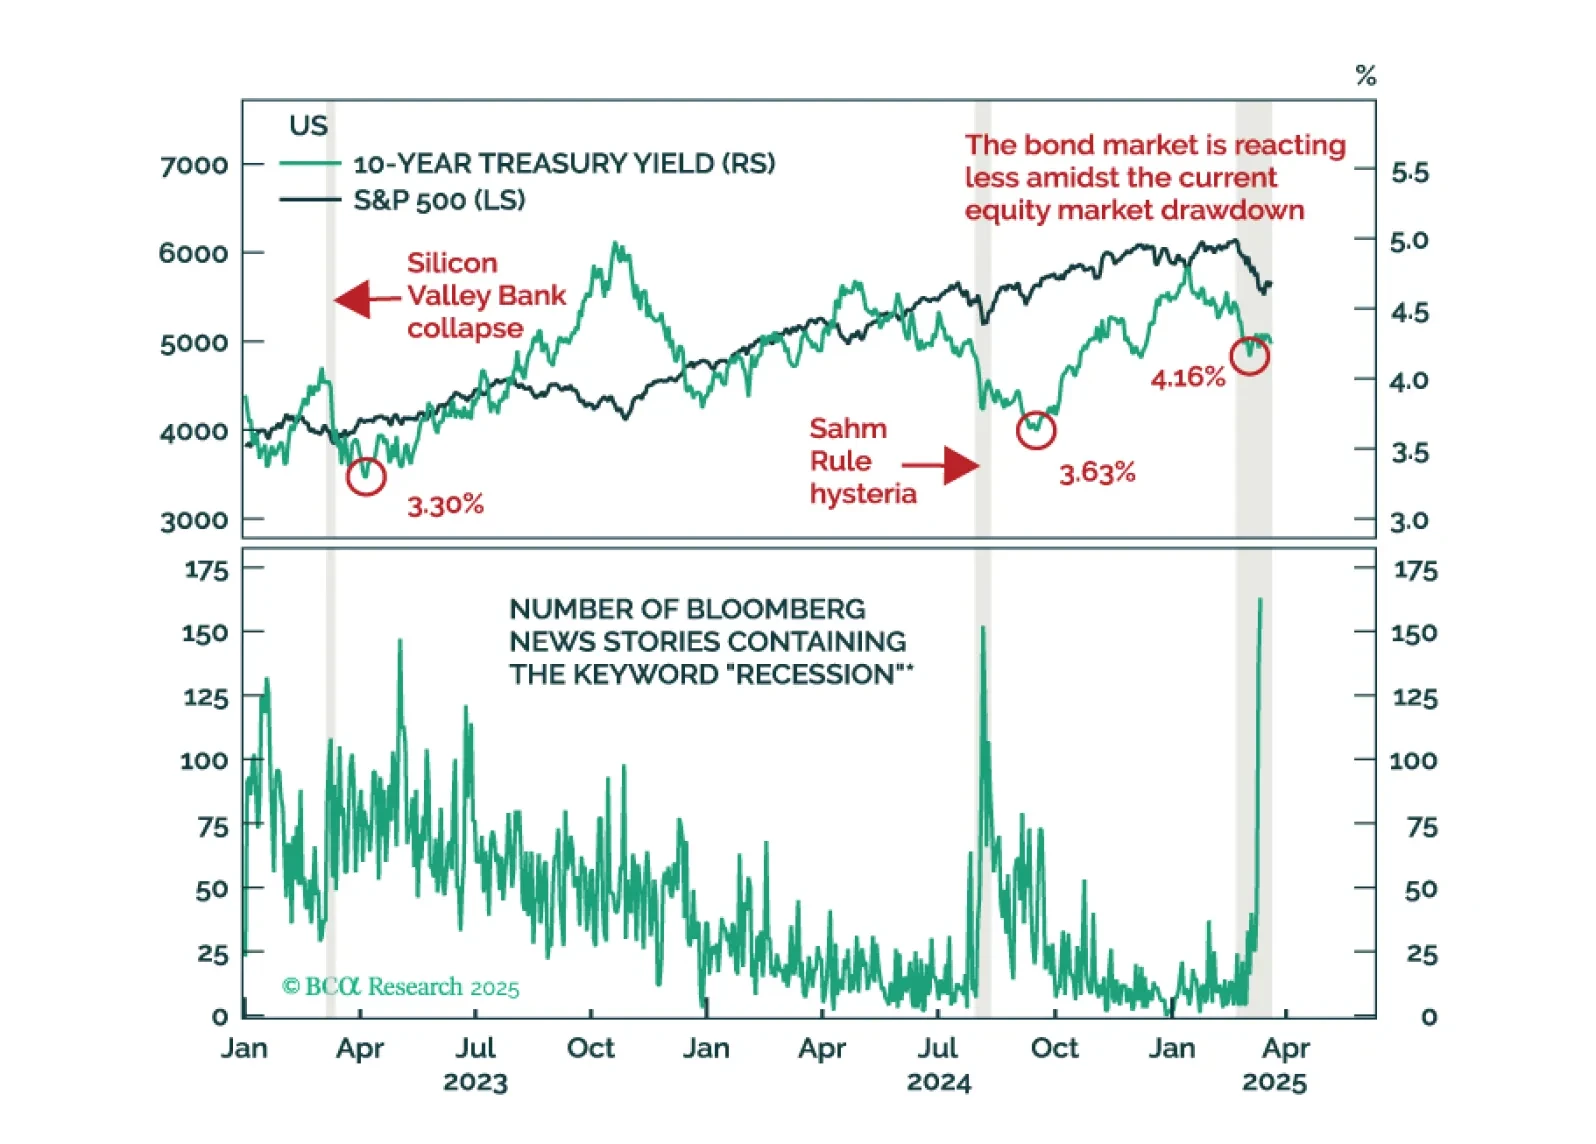
Given the meetings between the Bank of Japan, the Bank of England, and the Swiss National Bank, our highest convictions views are: Overweight UK Gilts. It is also time to sell sterling. We are short sterling, as of 1.30. Underweight JGBs. Correspondingly, be long the yen. A short CHF/JPY position remains a core holding. Selling GBP/JPY is also a great trade.
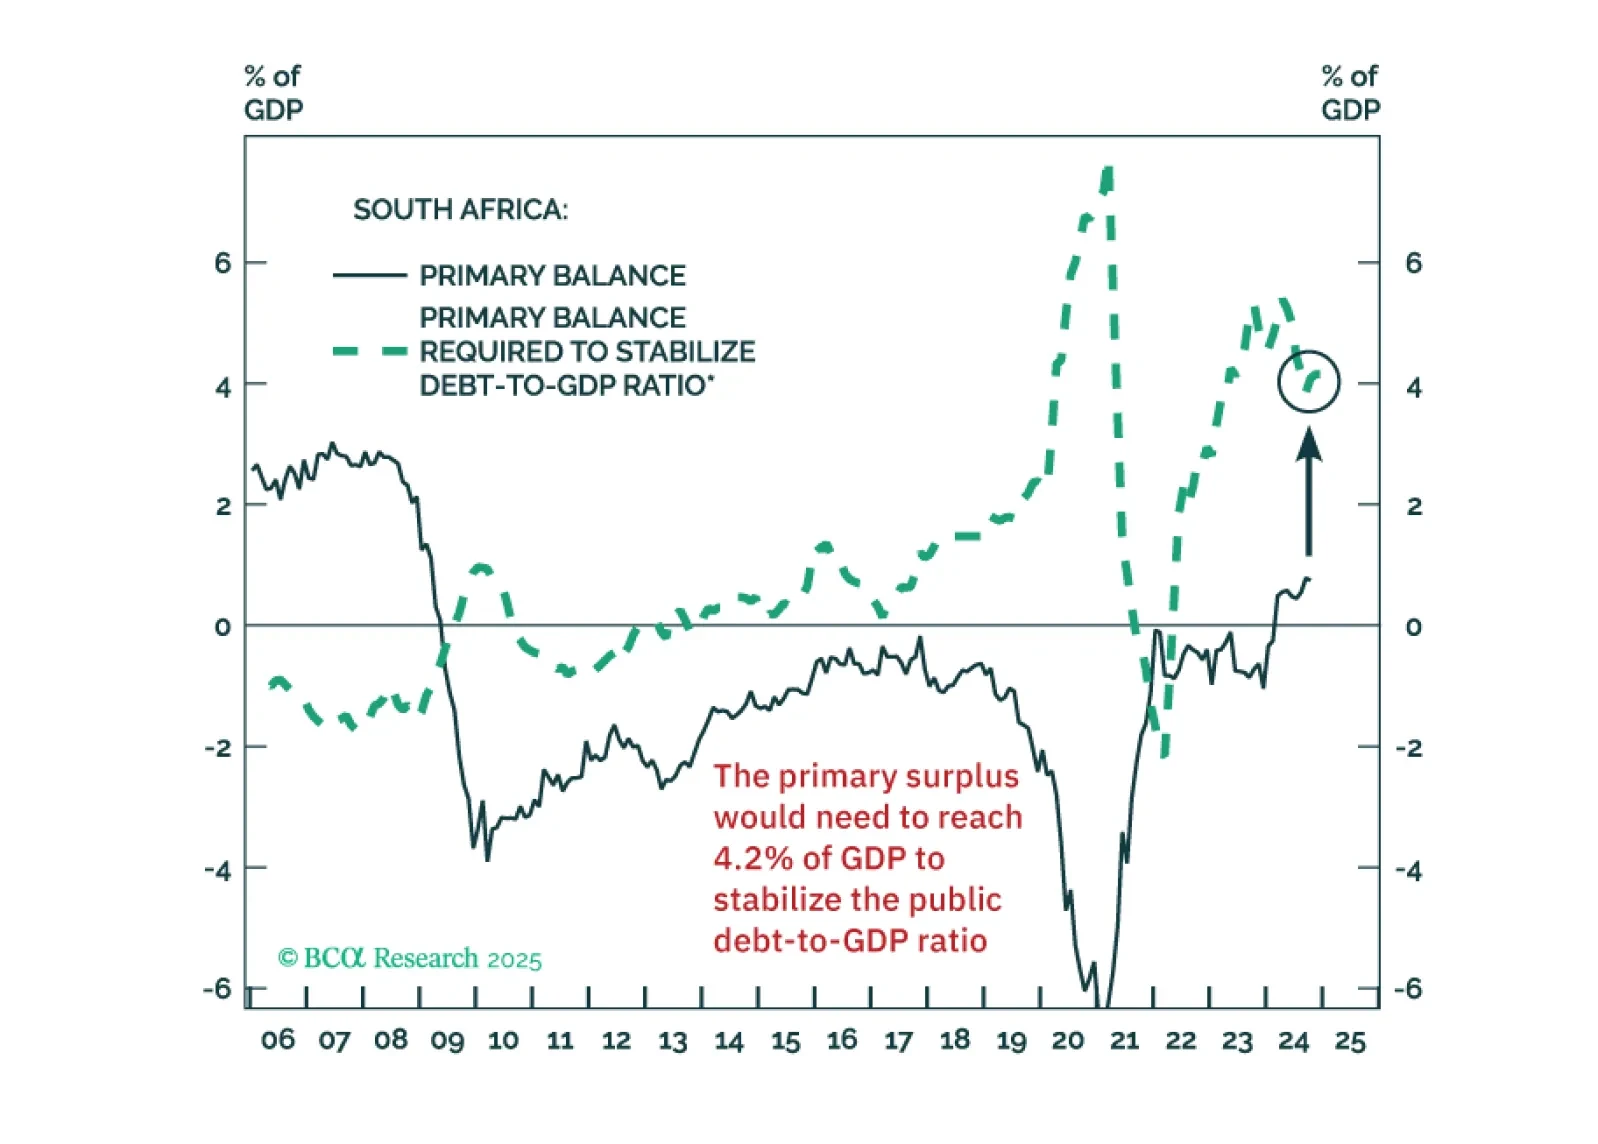
The South African government seems to believe that some fiscal retrenchment can stabilize the public debt-to-GDP ratio. But that’s a misconception. The country will need draconian spending cuts to achieve this.
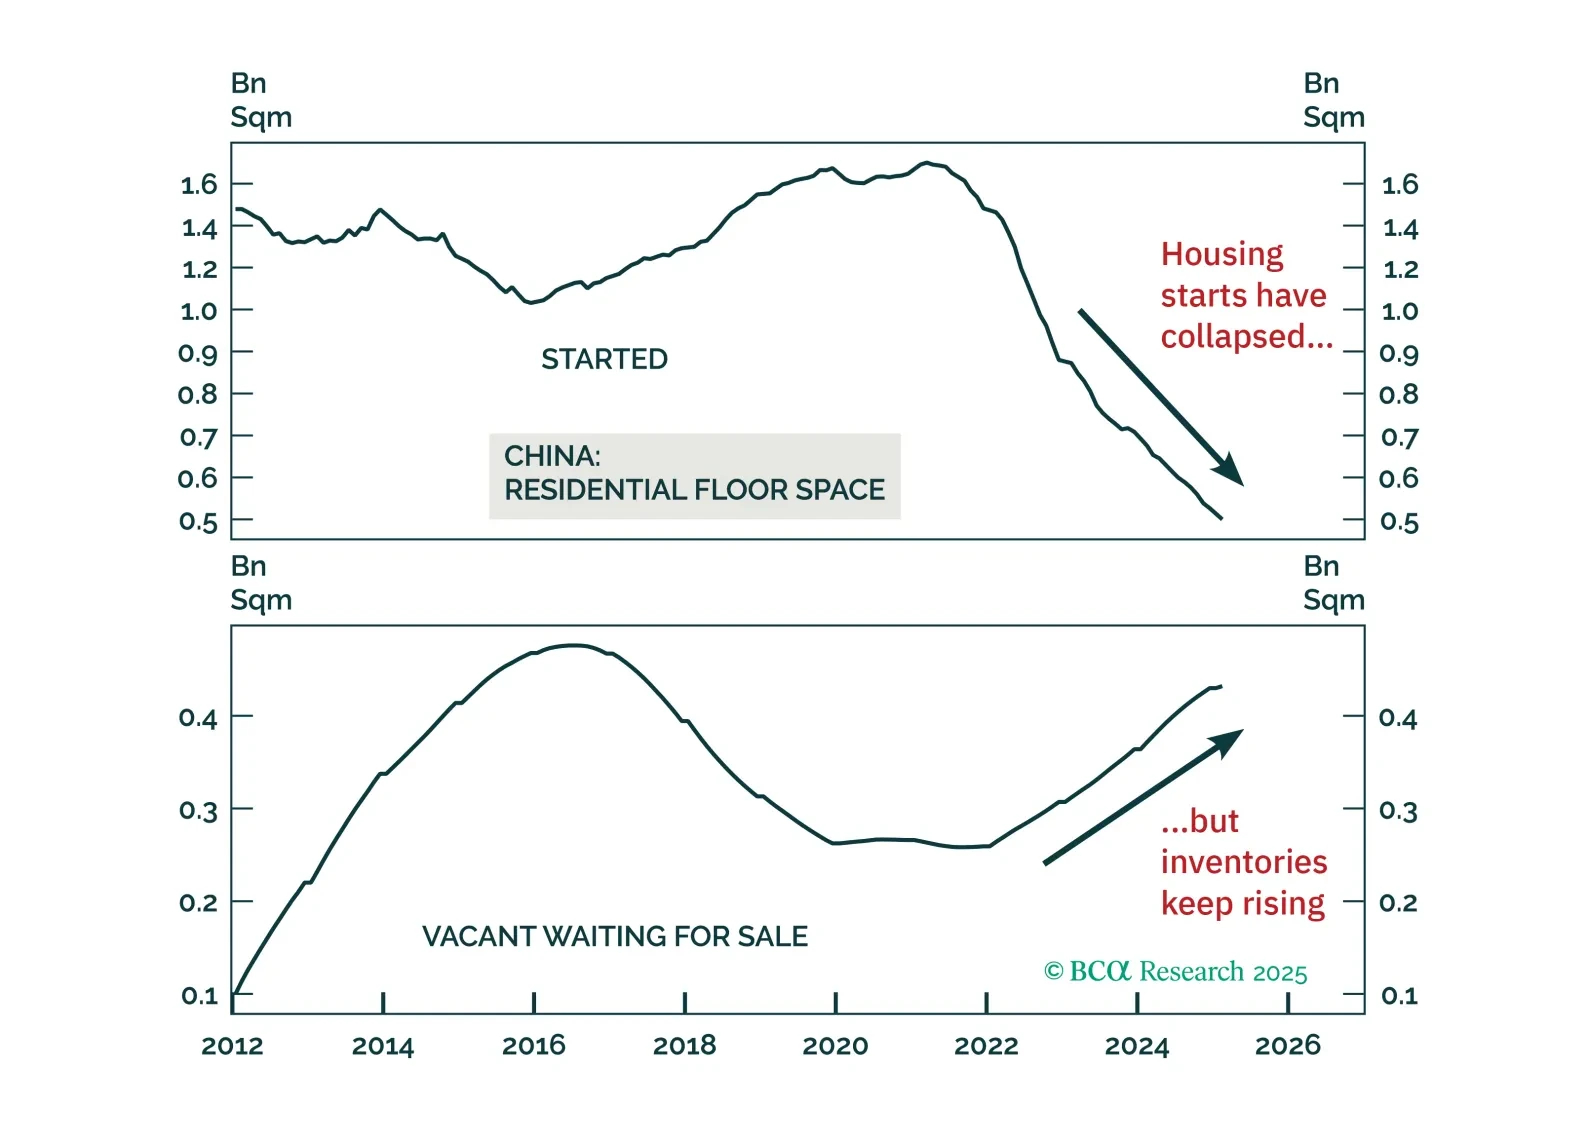
Data released this Monday suggests that while China’s housing market is no longer worsening, the secular adjustment remains ongoing. Although aggregate housing demand may be stabilizing at a low level, supply will continue to significantly outpace demand, indicating that home price deflation will persist. Additionally, property developers’ poor financing will hinder new project initiations, leading to a further decline in housing starts over the next six to 12 months.
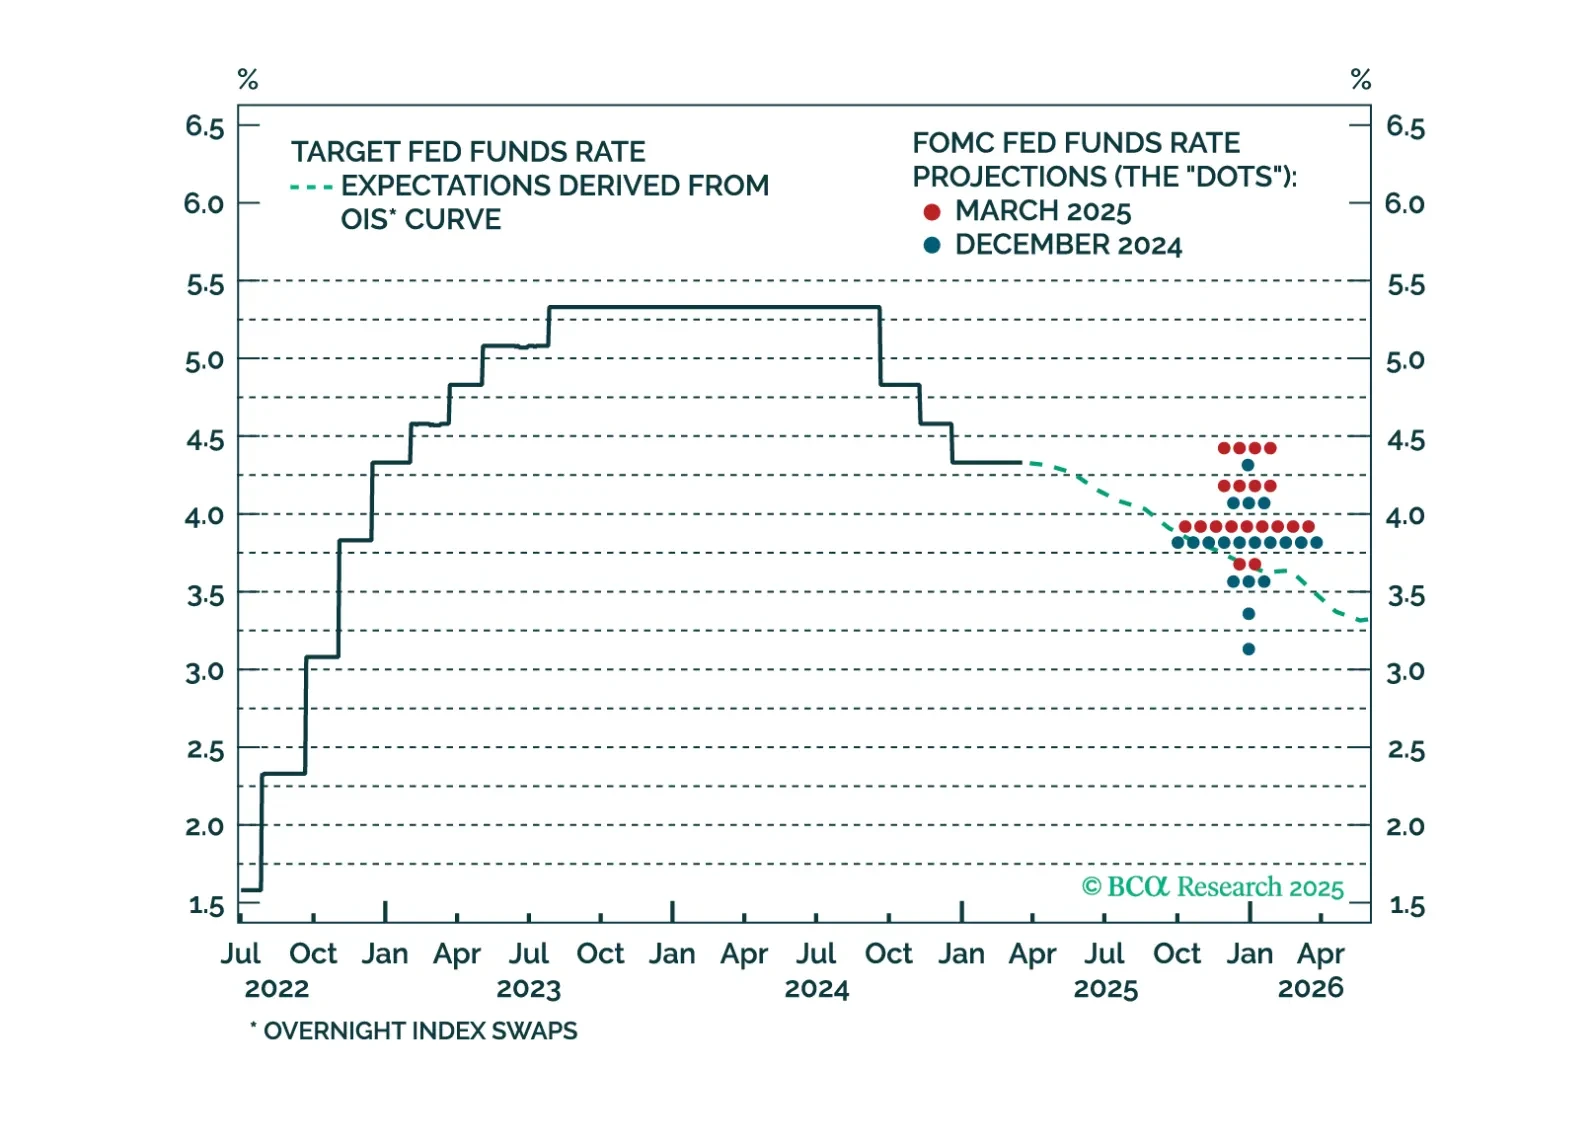
The market reaction to this afternoon’s Fed meeting looks overdone. Investors could be in for a hawkish surprise when it becomes apparent that the Fed won’t ease policy into higher tariff-driven inflation prints.
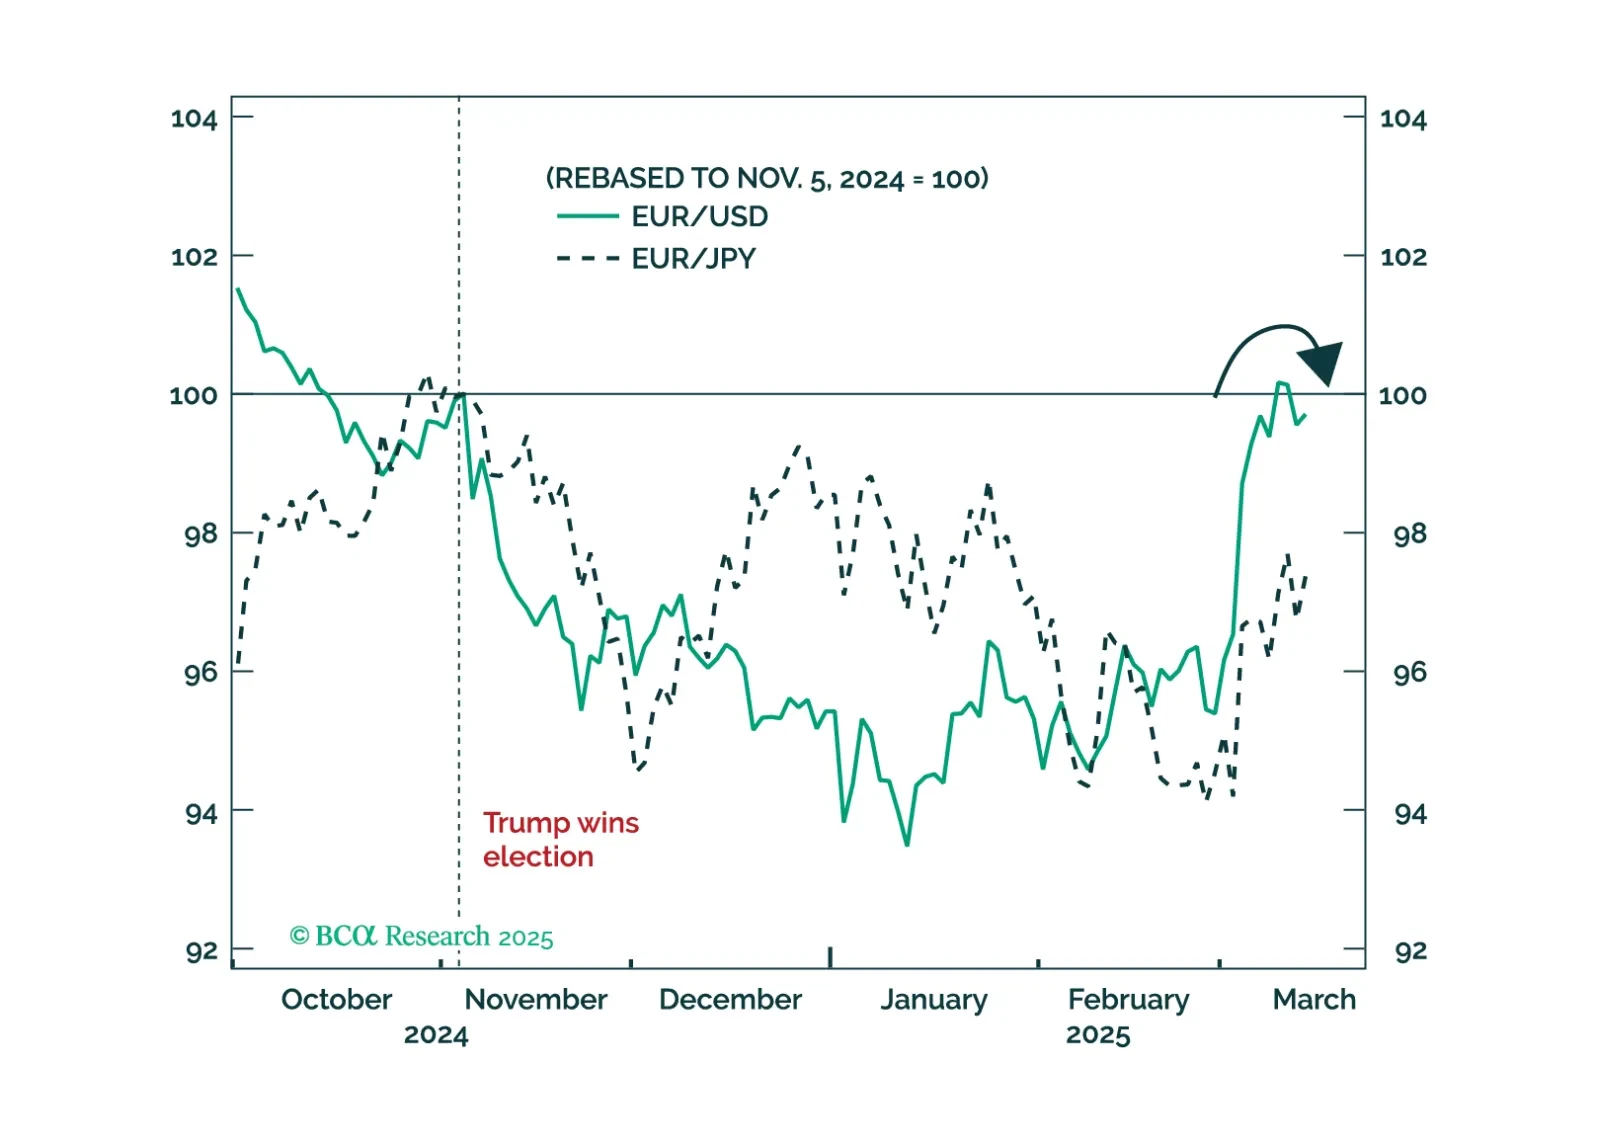
Trump’s foreign policy can be explained by rational US interests, but it requires settling the trade war with allies sooner rather than later. Book gains on EUR-USD for now.
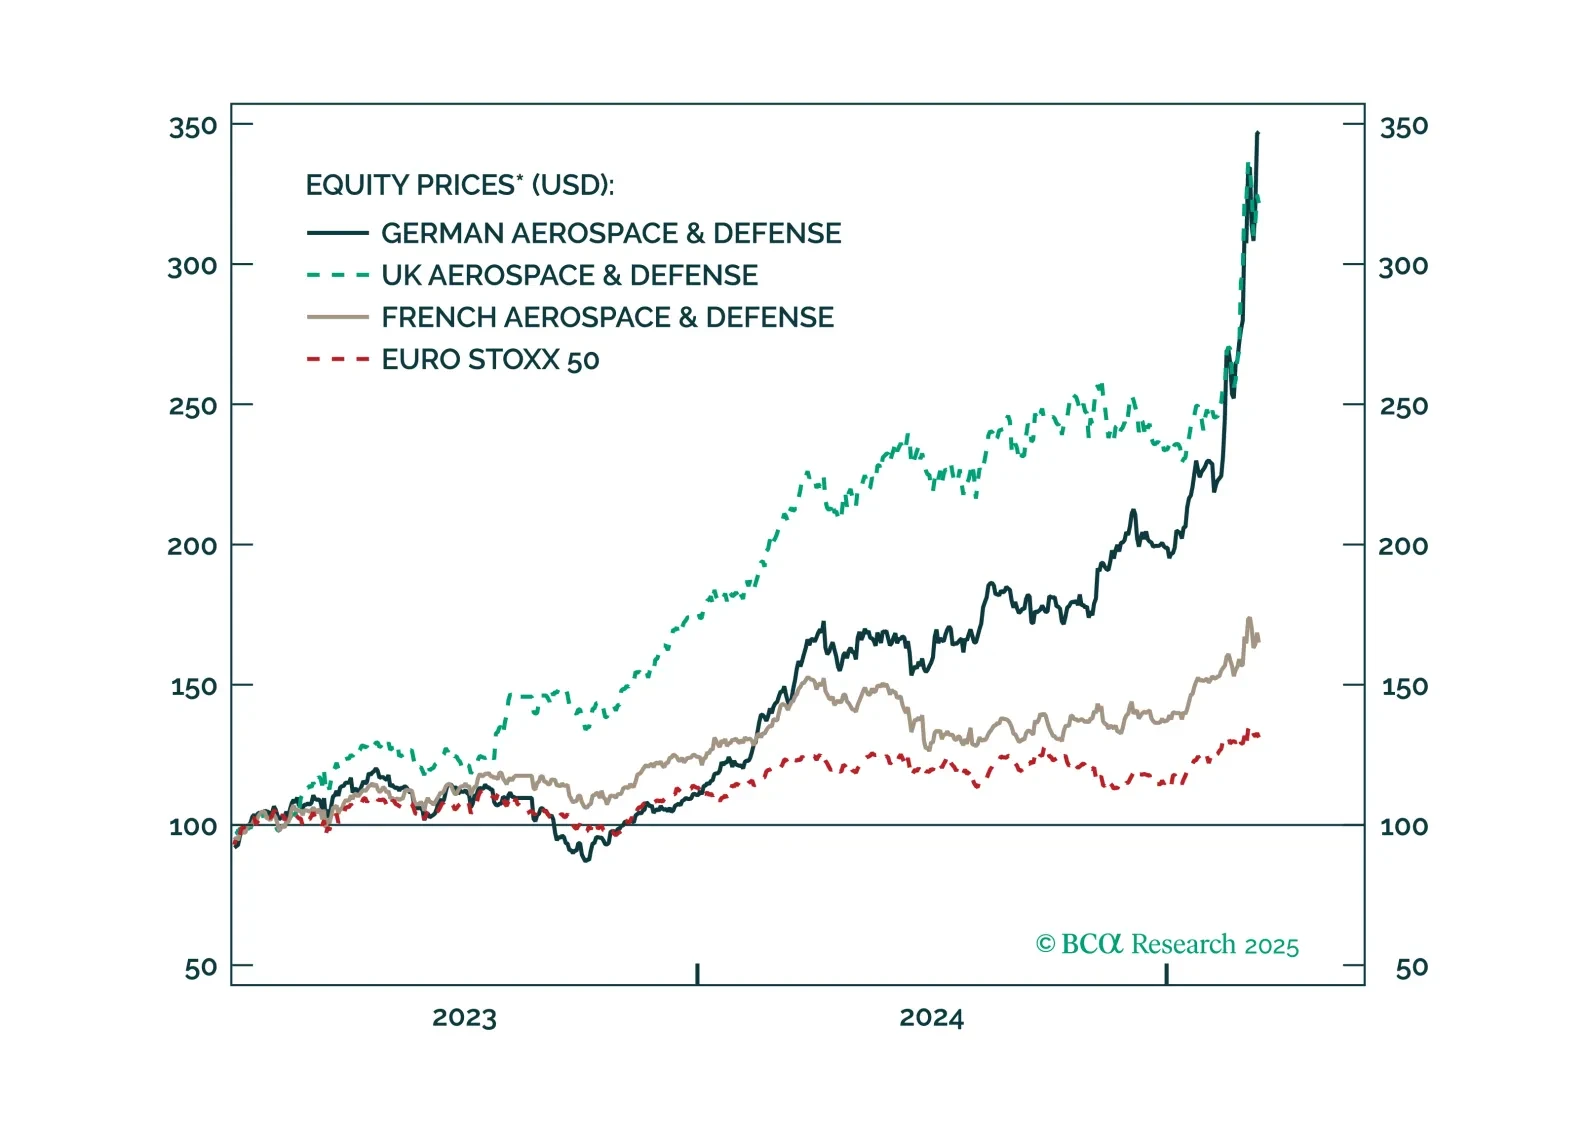
Investors should not chase the rally in European defense names any further. Too much good news has been priced in too quickly.
Trump’s foreign policy can be explained by rational US interests, but it requires settling the trade war with allies sooner rather than later. Book gains on EUR-USD for now.
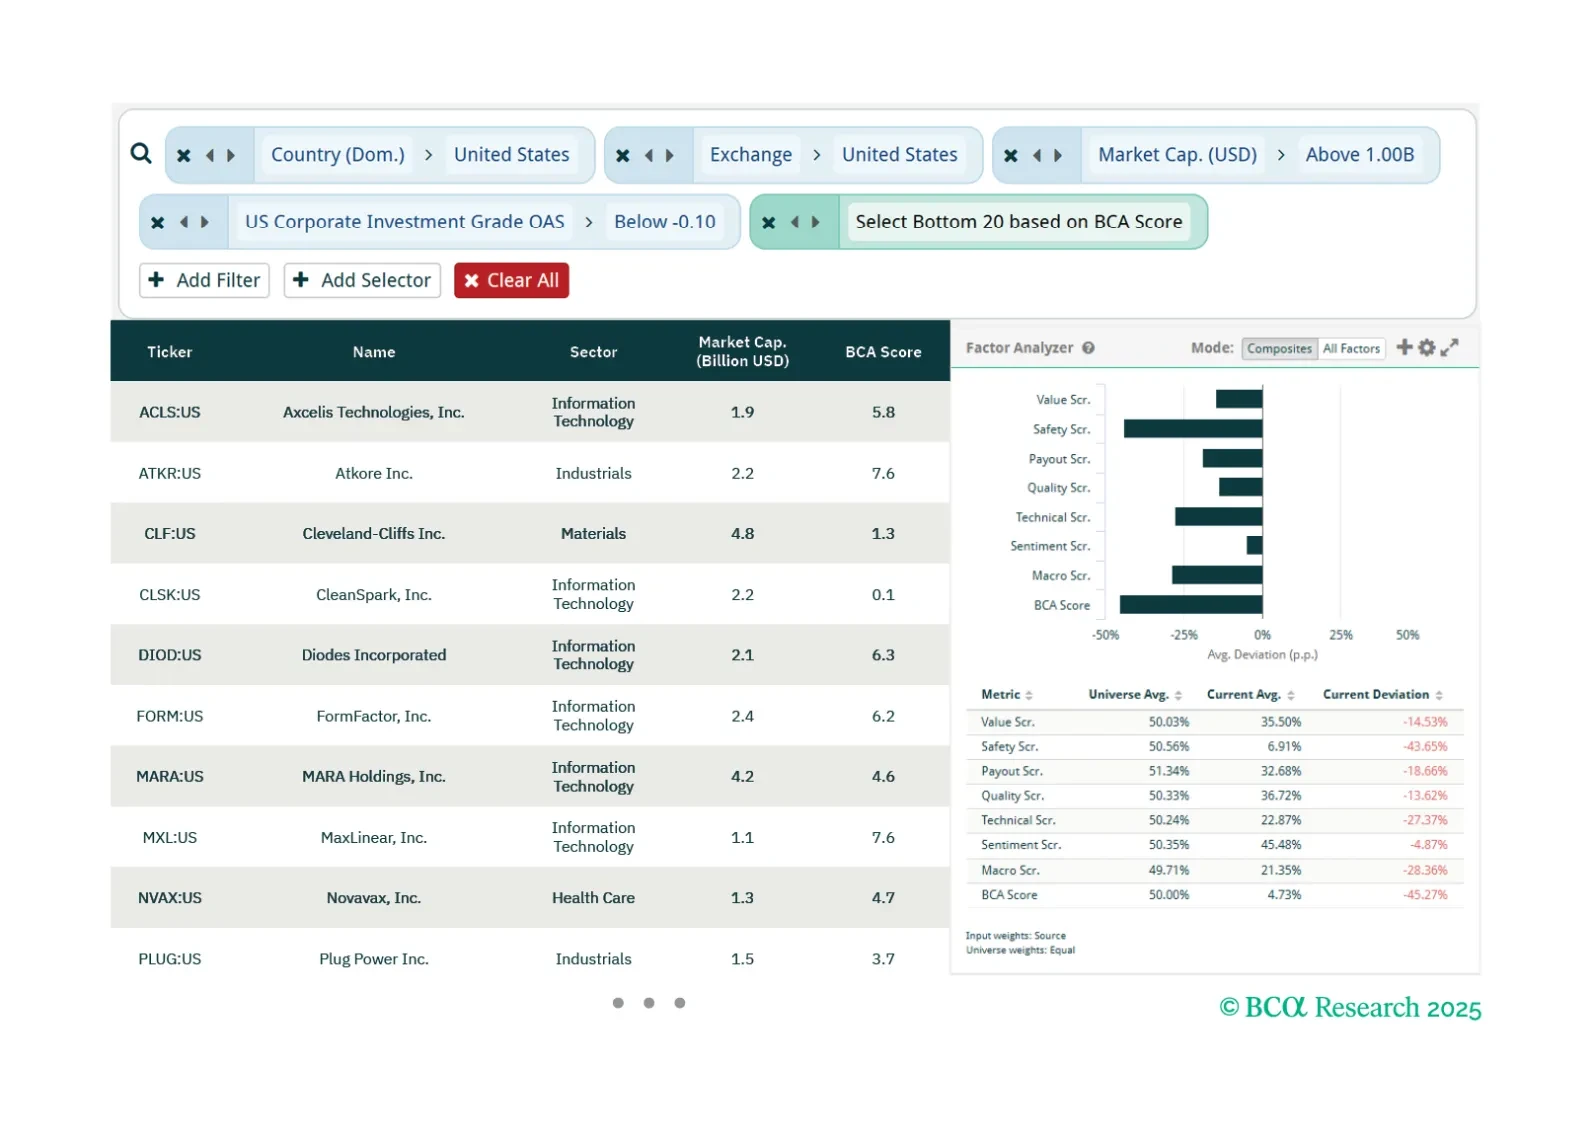
This week, our three screeners cover equity plays in US OAS Spreads, US Exceptionalism, and “DIVE”.
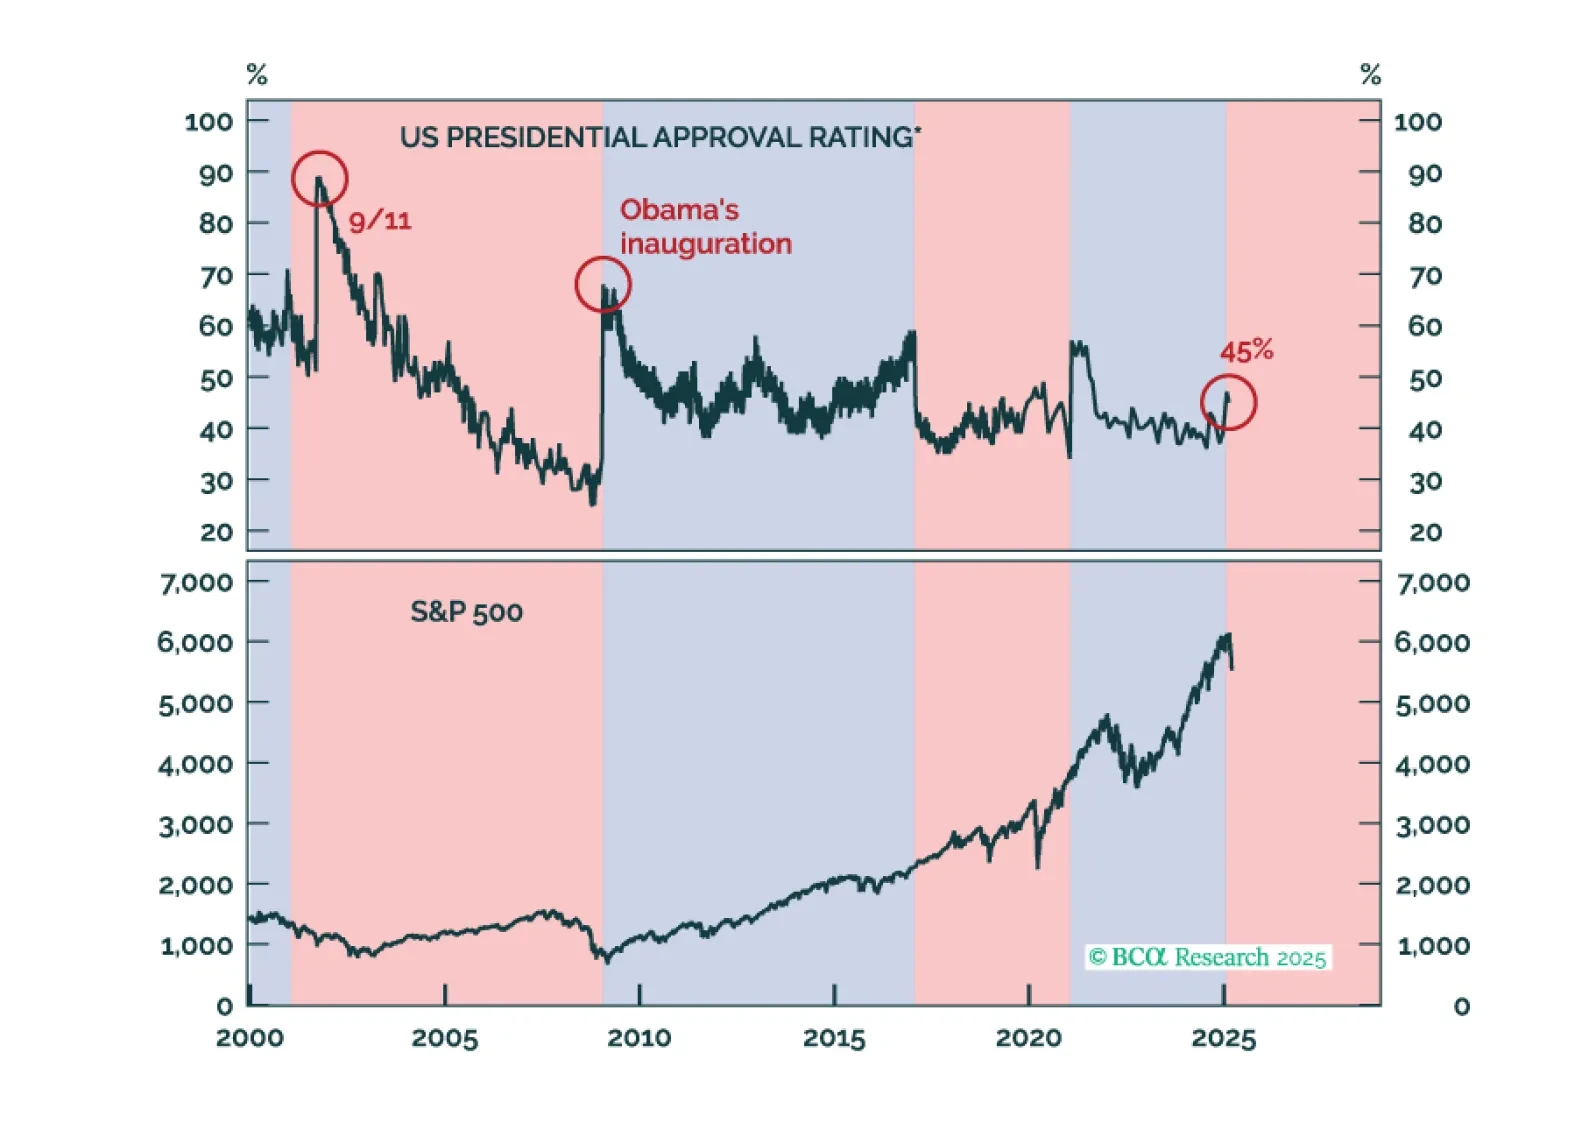
Despite our bearish predisposition towards stocks, we are open-minded to anything that could challenge our thesis. As such, in this report, we review five upside scenarios for equities.