CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
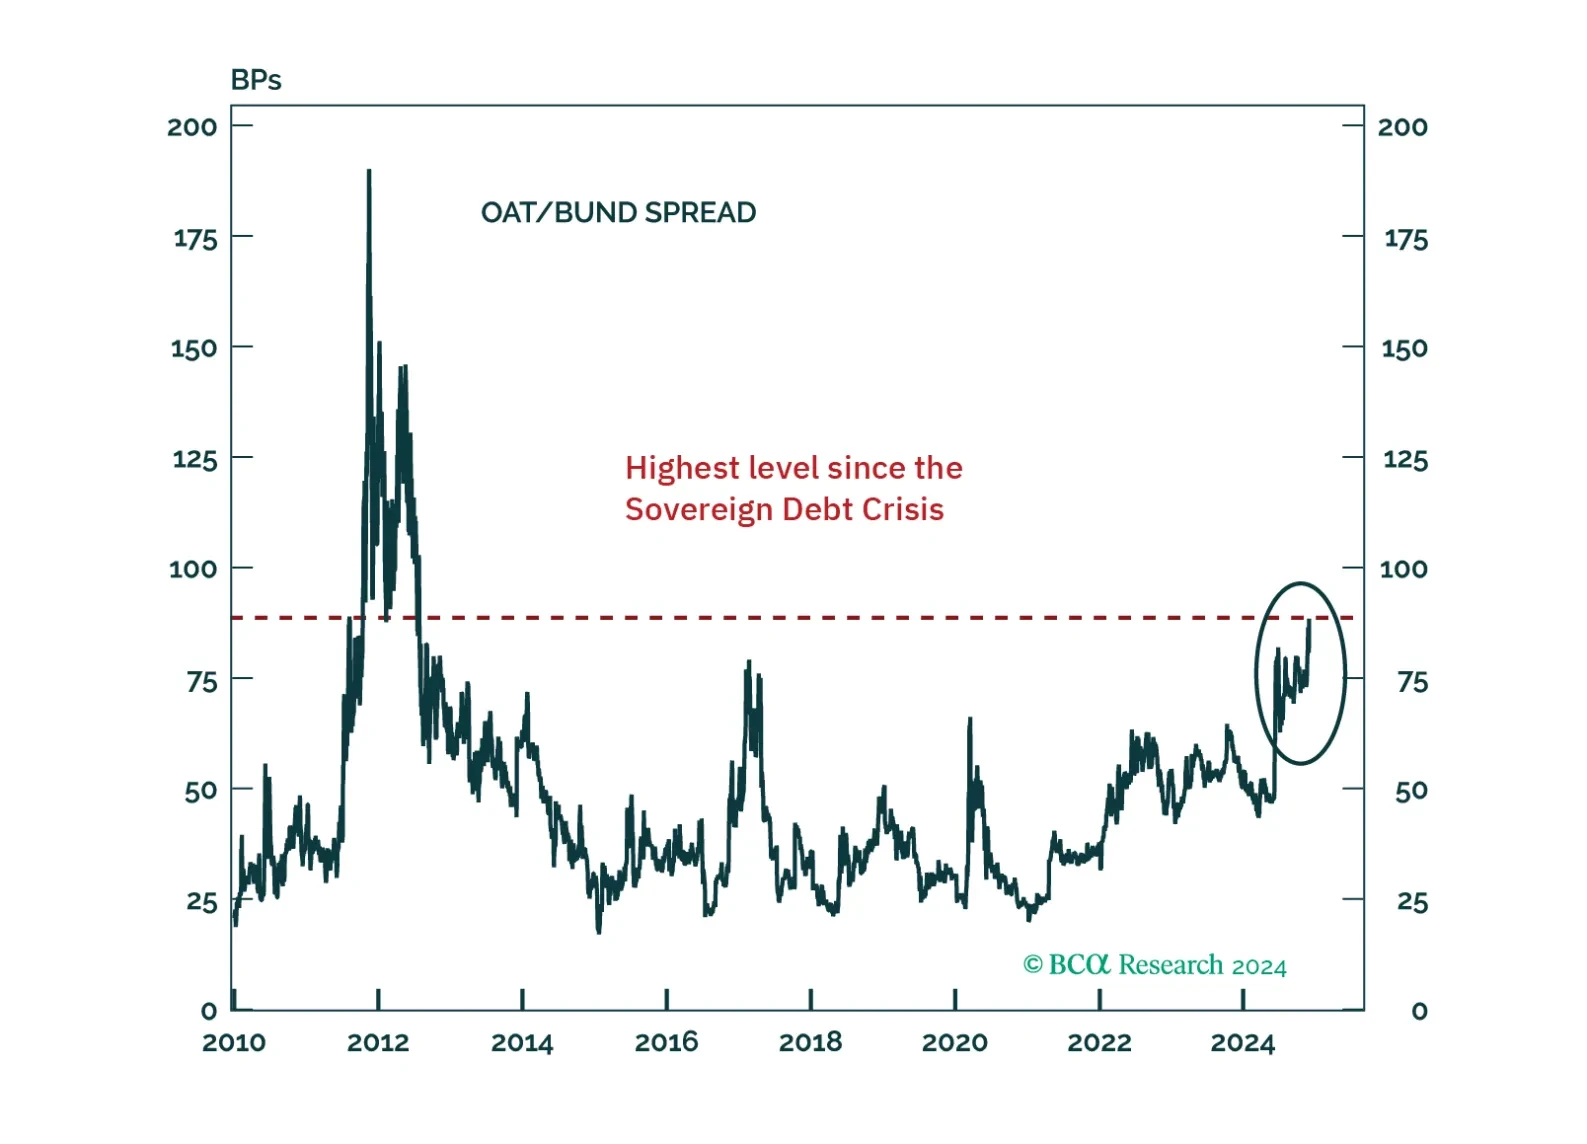
France finds itself in a unique, thorny situation. Can it heave itself out of it? And what does it mean for investors?
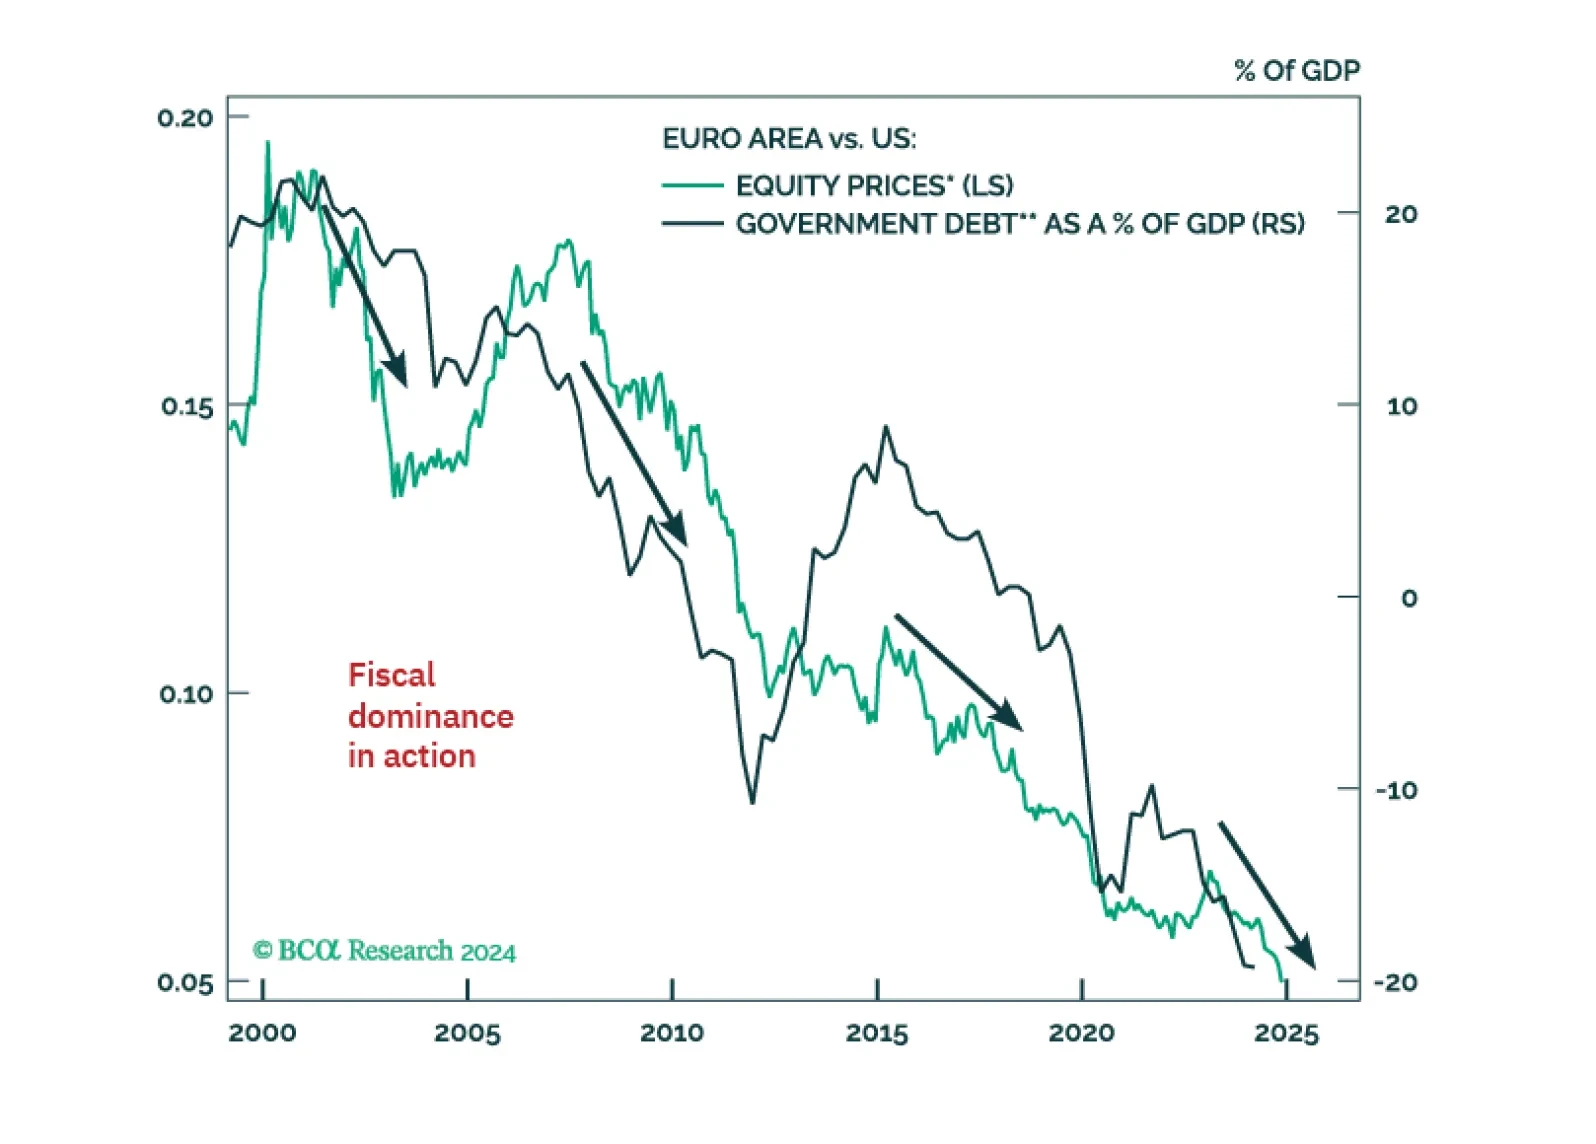
Investors have given up on European assets, which now suffer exceptional discounts to US ones. However, tighter US fiscal policy, the end of Europe’s austerity and deleveraging, the LNG Tsunami about to hit European shores, and the global capex fueled by the Impossible Geopolitical Trinity mean that Europe’s time to shine will soon come back.
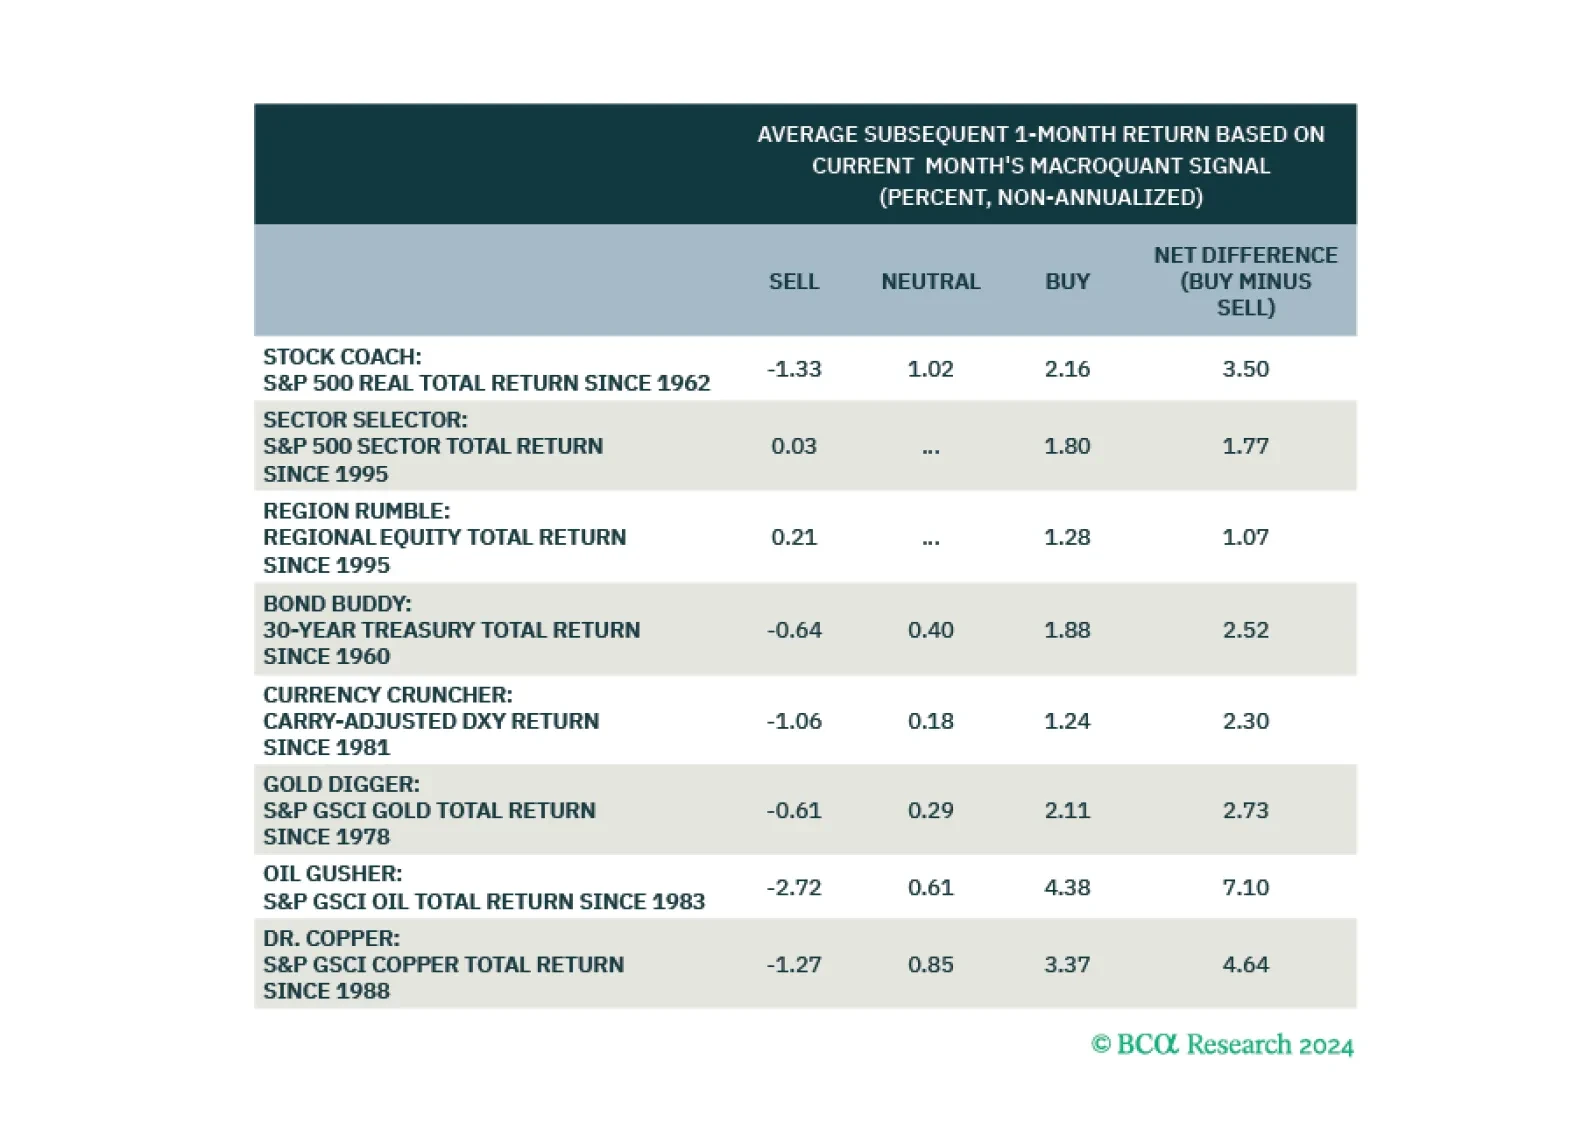
Today, we are unveiling an update to our MacroQuant model. The latest version of the MacroQuant model sees downside risk to stocks going into December and recommends increasing duration exposure in global fixed-income portfolios.
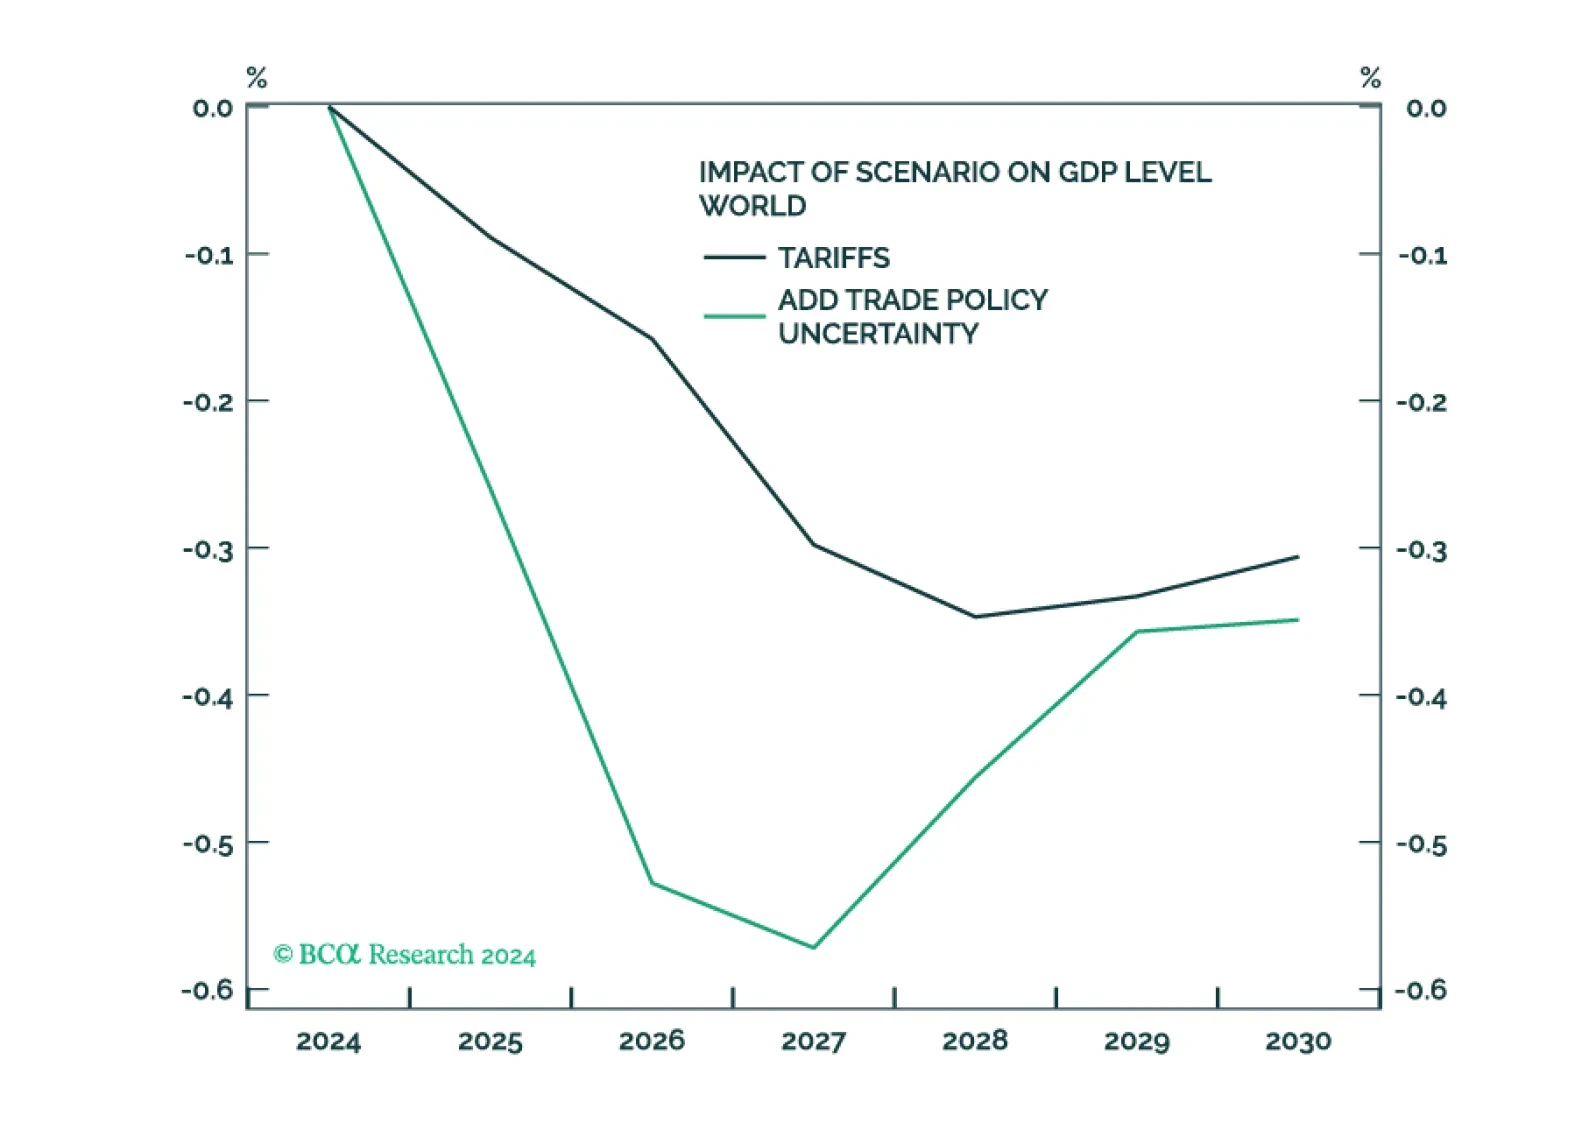
On October 15, speaking at the Economic Club of Chicago, Donald Trump called tariffs “the most beautiful word in the dictionary.” On Monday, he put those words into action by threatening to slap a 25% tariff on all imports from Canada and Mexico, and an additional 10% tariff on Chinese imports. Collectively, the three countries account for 45% of US imports.
This week we conduct a thorough audit of our open positions by revisiting the original basis and subsequent performance of all 13 cyclical recommendations. Following the review, we recommend closing 6 of the 13 positions.
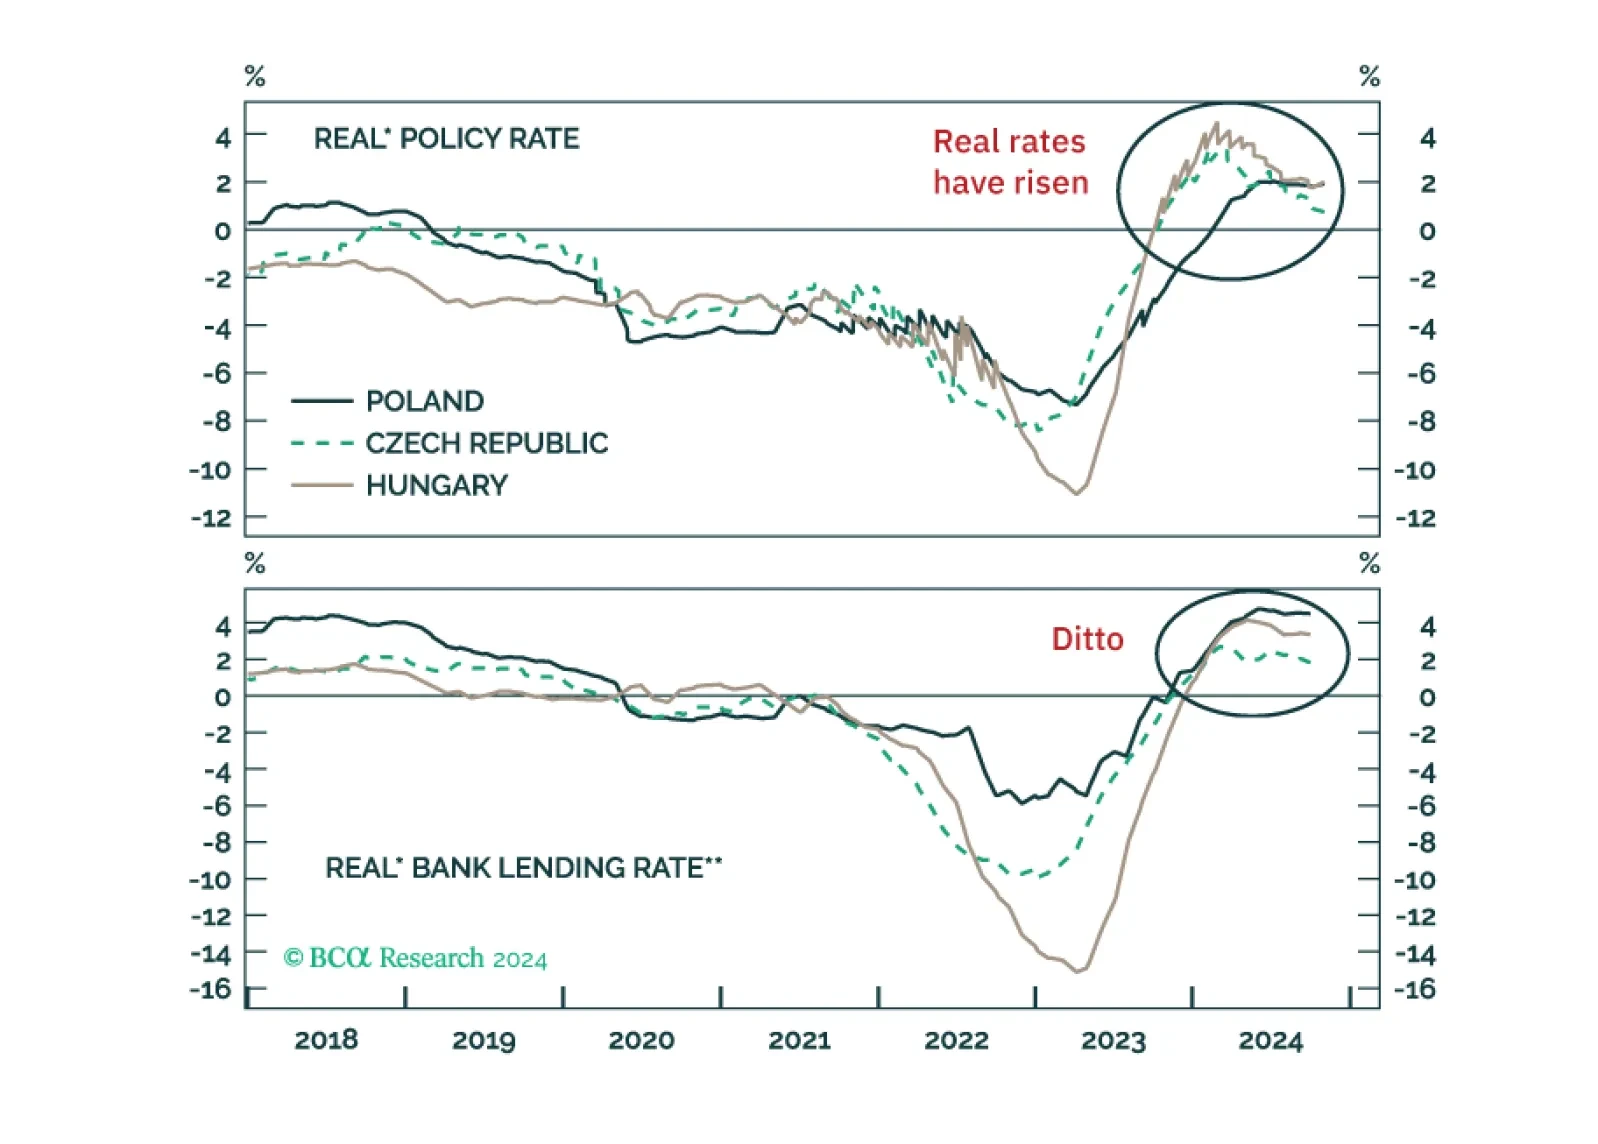
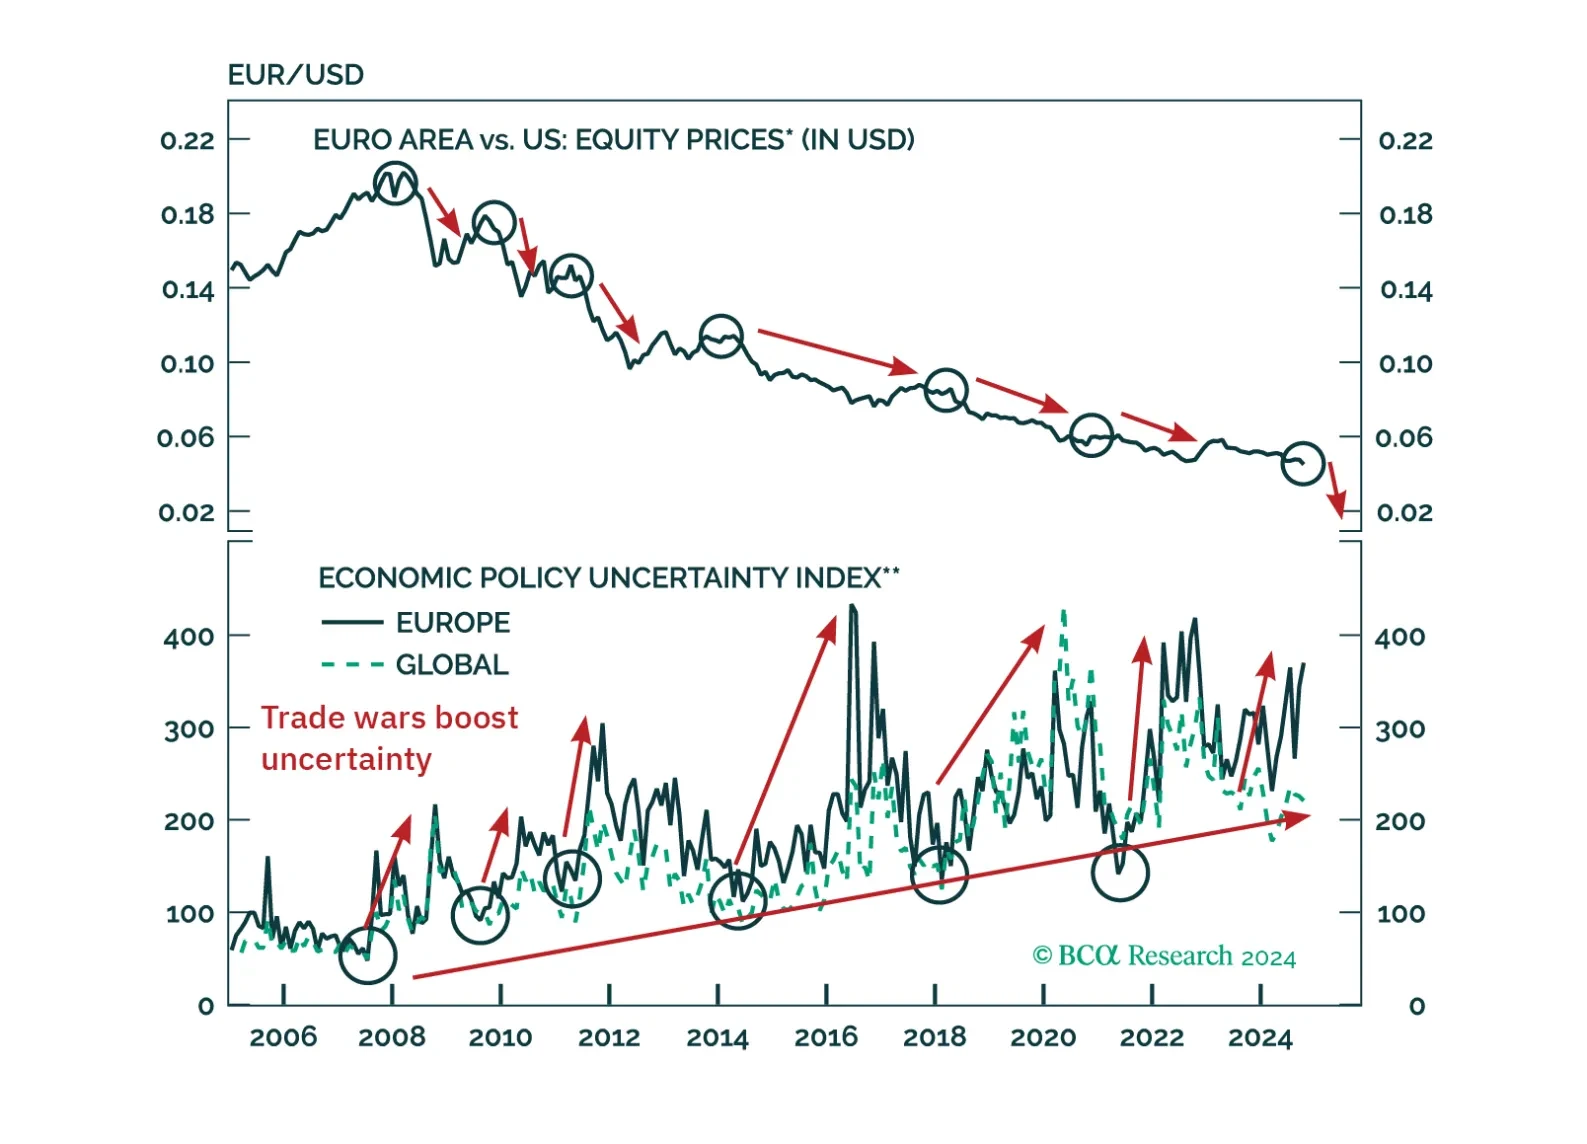
European assets and the euro have become oversold and are likely to rebound. Will this move be nothing more than a dead cat bounce leading to more weakness?