Financieros
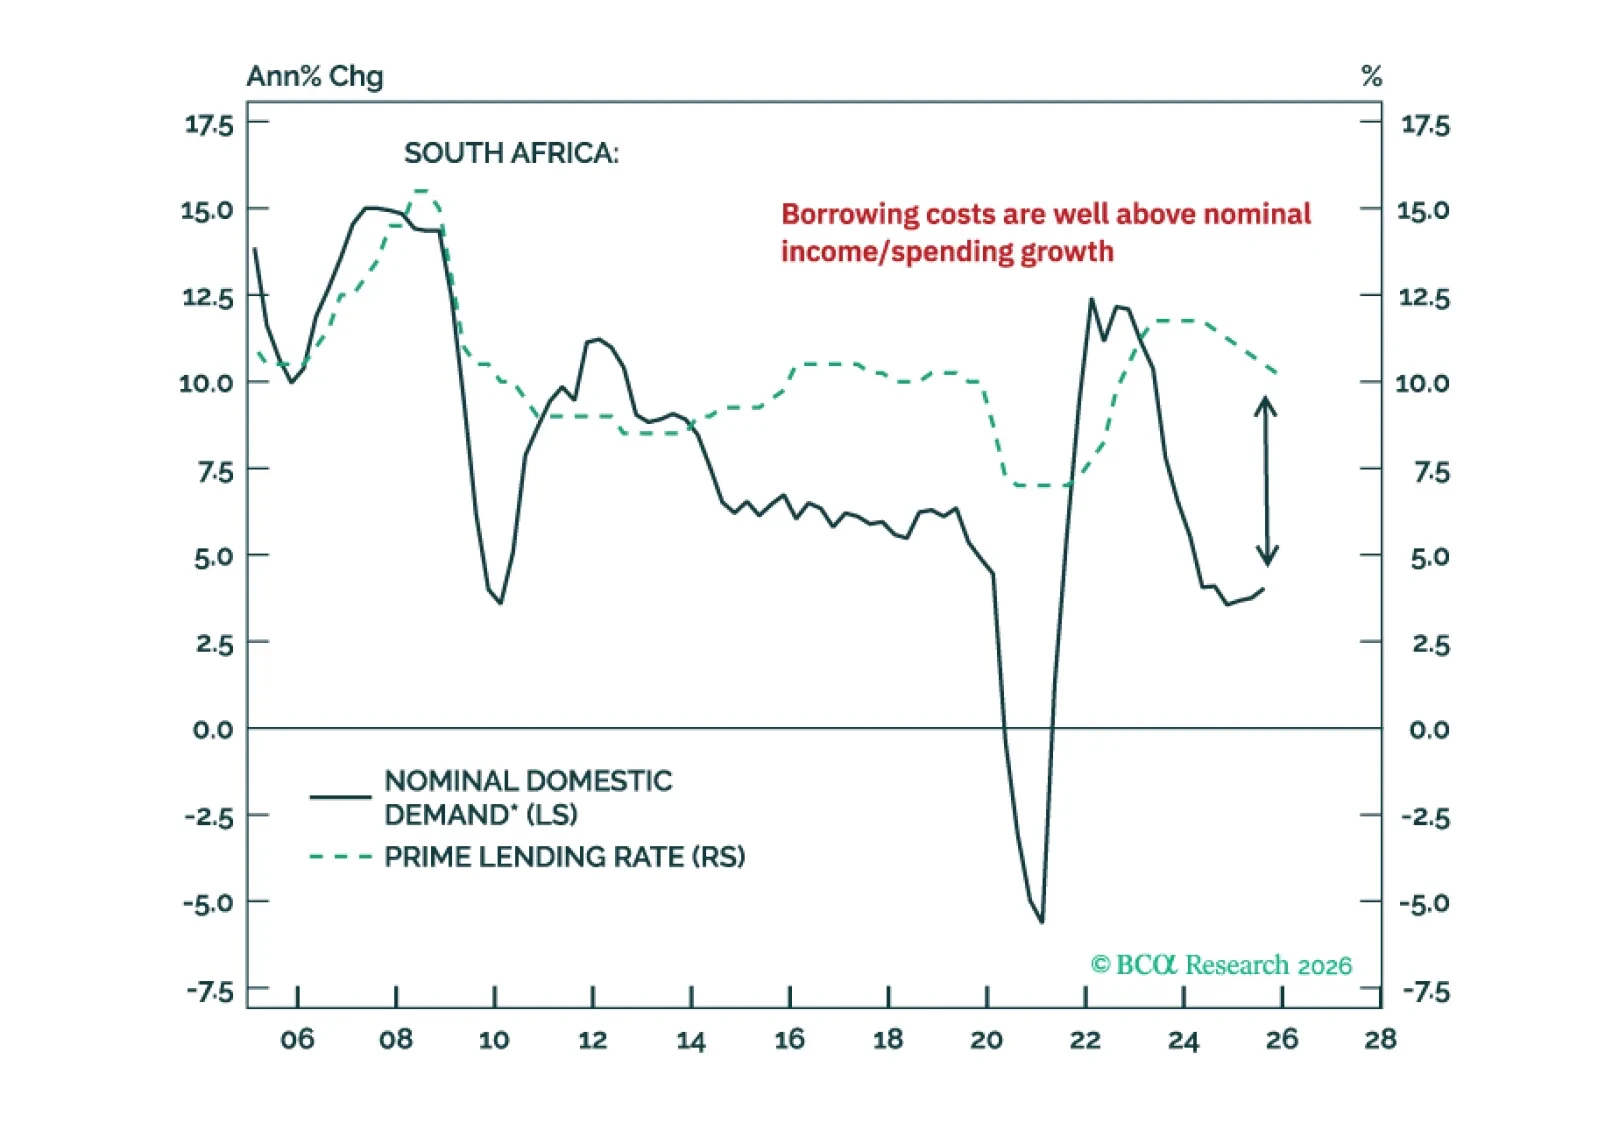
La bonanza de los metales preciosos no ha resuelto la difícil situación de la economía sudafricana. Tampoco mejoró sus problemas de sostenibilidad de la deuda pública. Los inversores deberían prepararse para una reversión en las acciones, los bonos y la moneda de Sudáfrica.

Desde los bonos del Tesoro hasta la tokenización, las stablecoins se están convirtiendo silenciosamente en una de las fuerzas más disruptivas en las finanzas globales, con el poder de comprimir rendimientos, profundizar la penetración del dólar y cambiar el equilibrio dentro de los mercados cripto. Explora los últimos análisis de BCA sobre su creciente impacto.
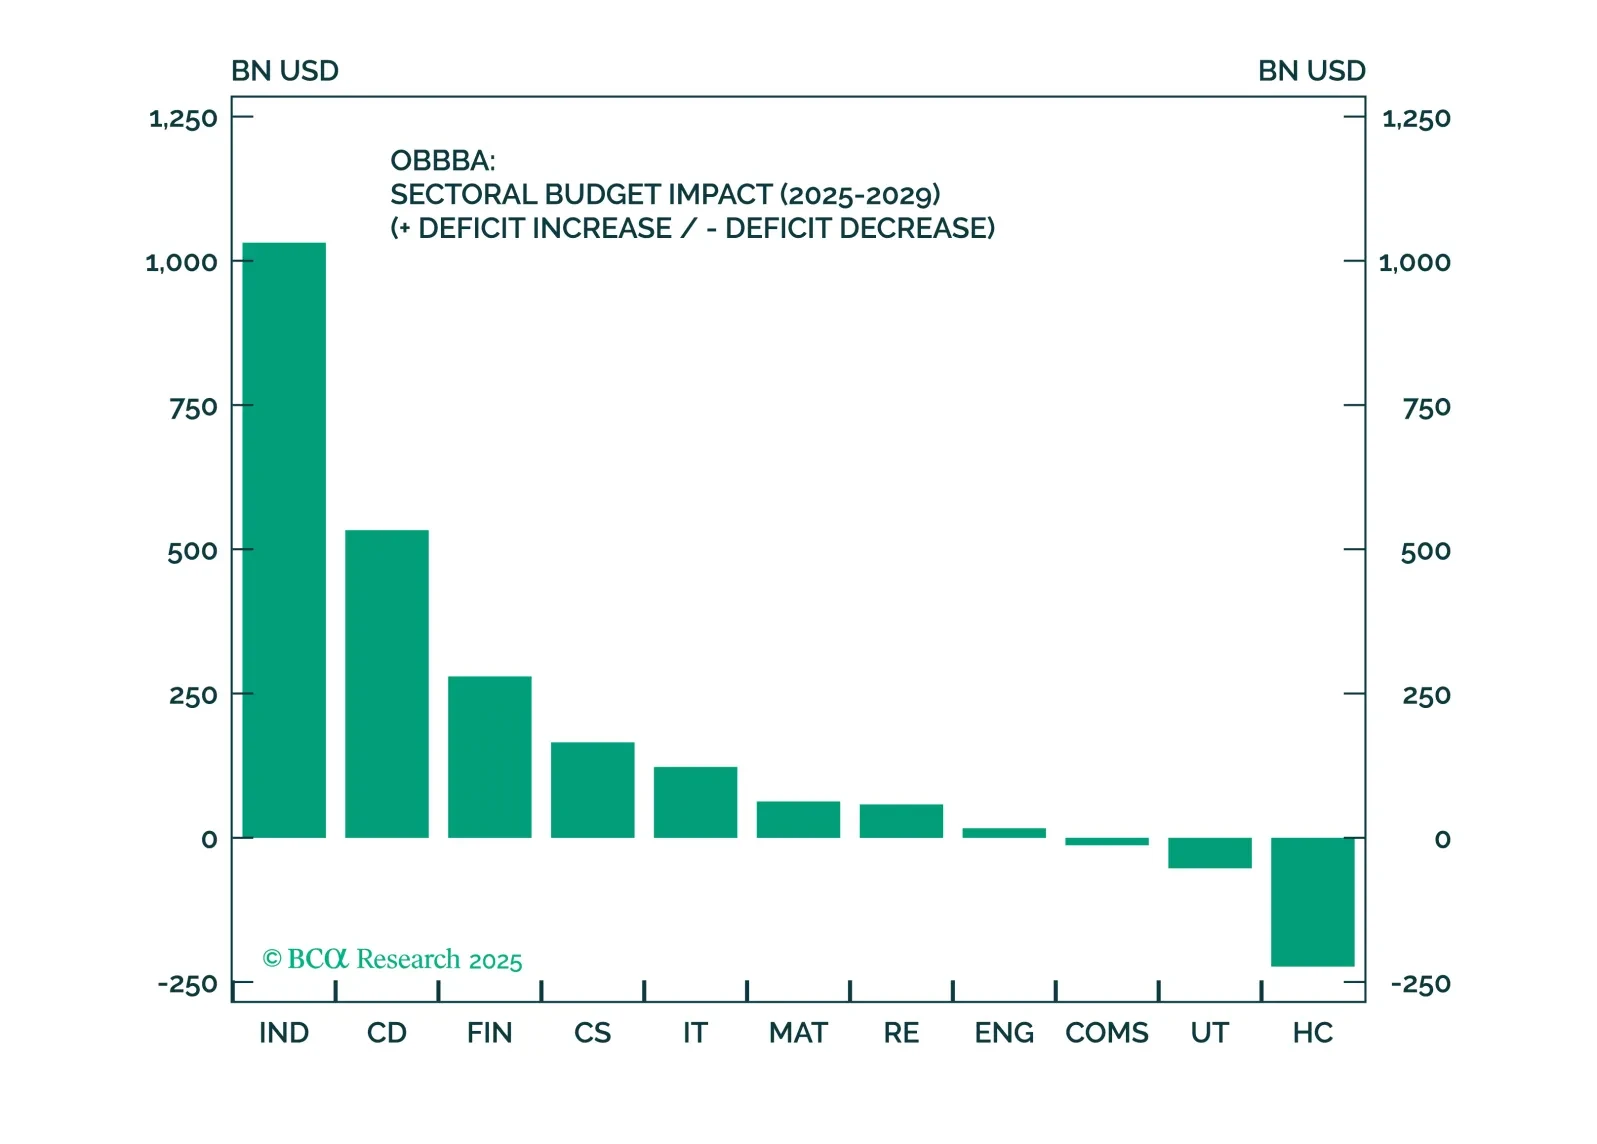
A pesar de los vientos en contra macroeconómicos, el OBBBA claramente favorece los sectores de renta variable de Industriales, Financieros y Consumo Discrecional. Una canasta cuidadosamente construida y consciente de factores en estos sectores está bien posicionada para superar en un entorno incierto impulsado por factores fiscales.
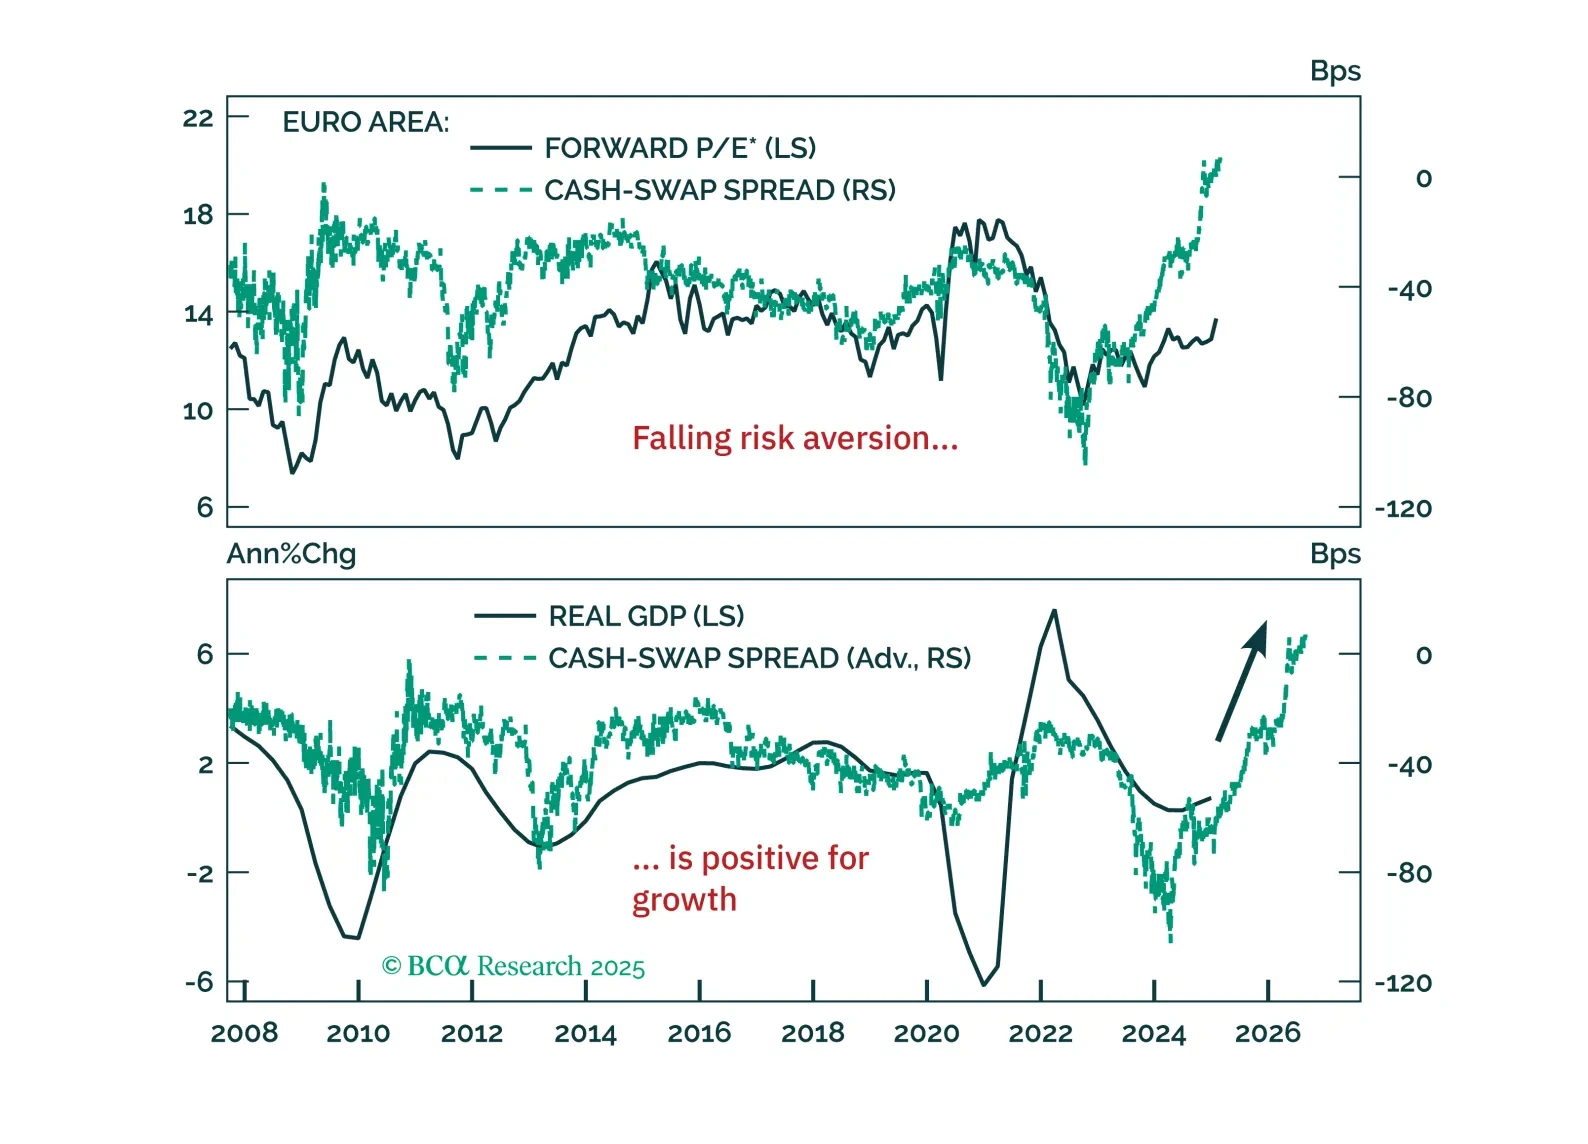
Europe’s resilience to global liquidity deterioration isn’t a fluke—it signals a structural shift. Our latest report explains why the decline in precautionary money demand marks the end of Europe’s liquidity trap and what it means for investors.
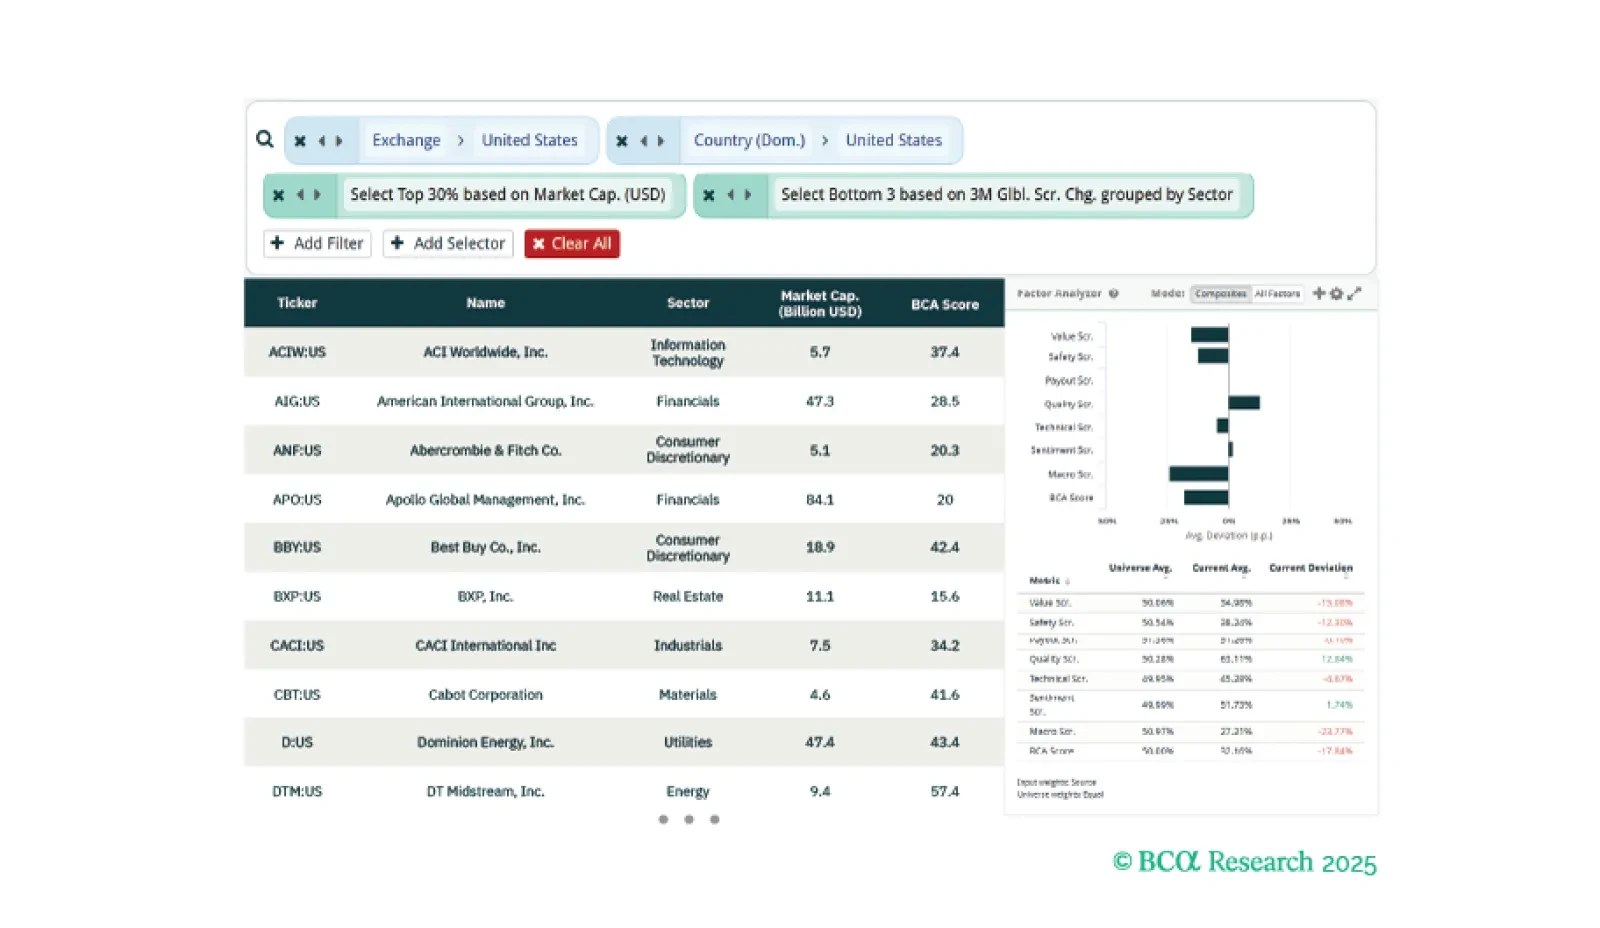
This week, our three screeners cover equity plays in European Banks, US Financials, And US Stocks that are “Grave Diggers”.
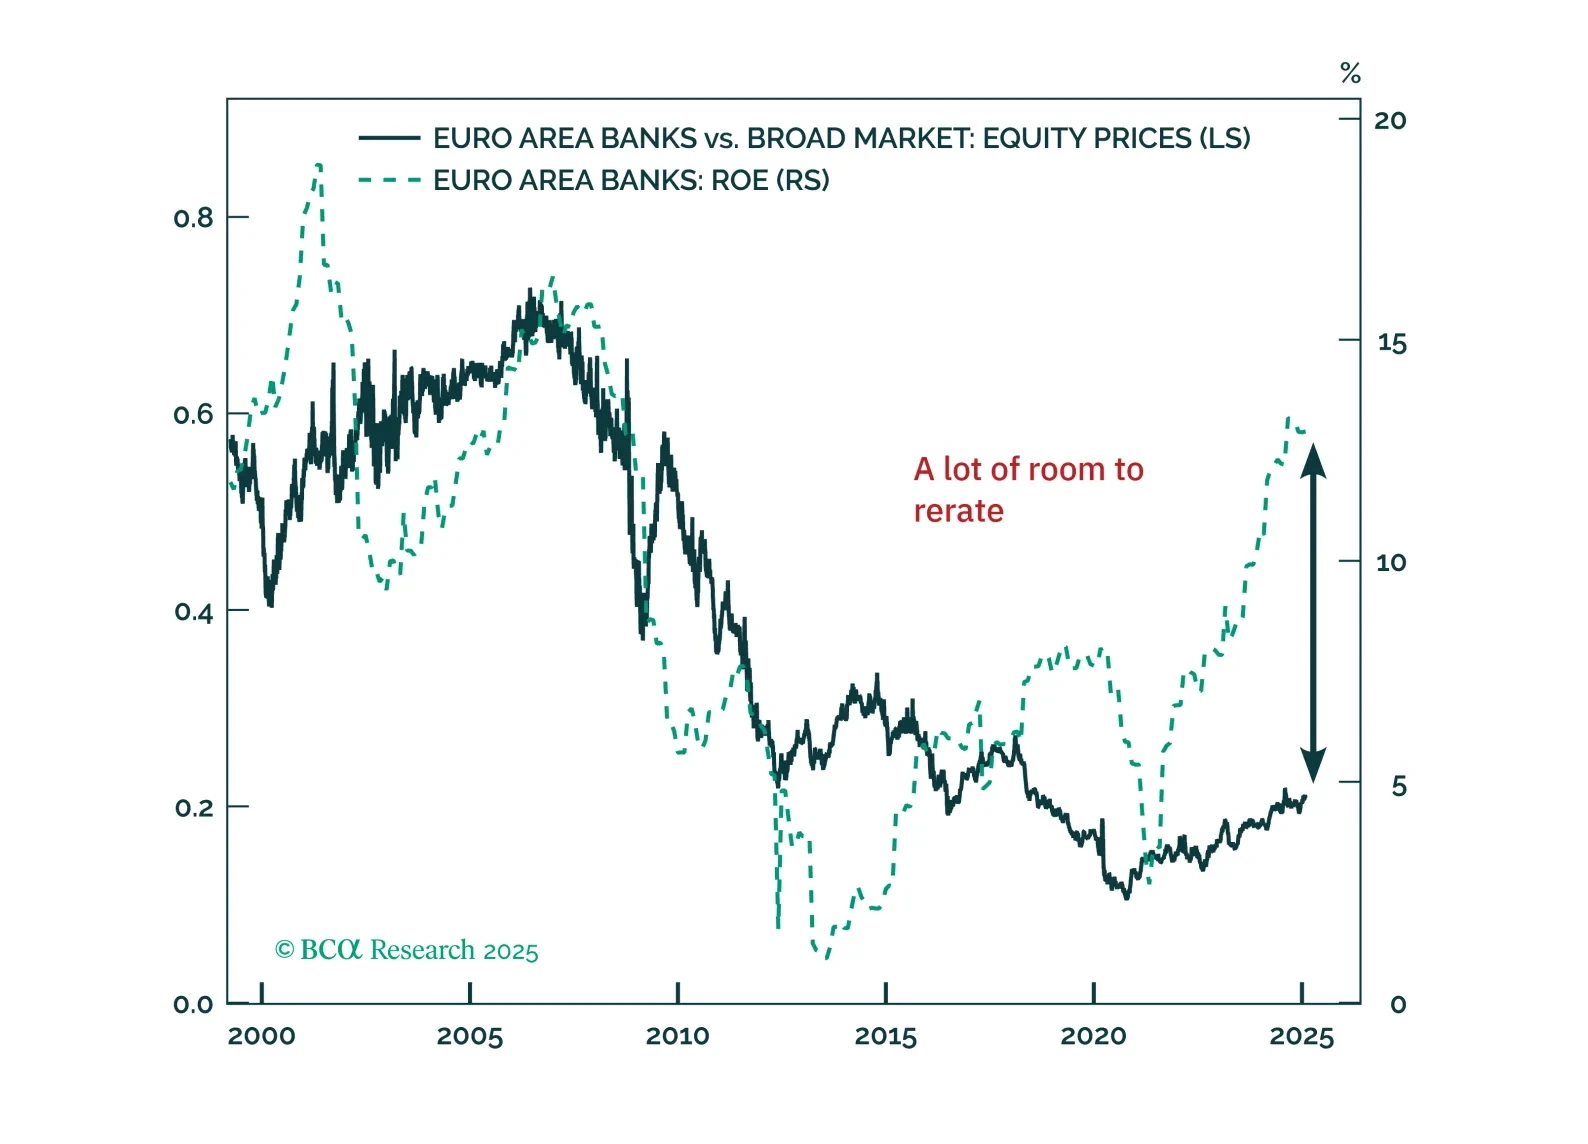
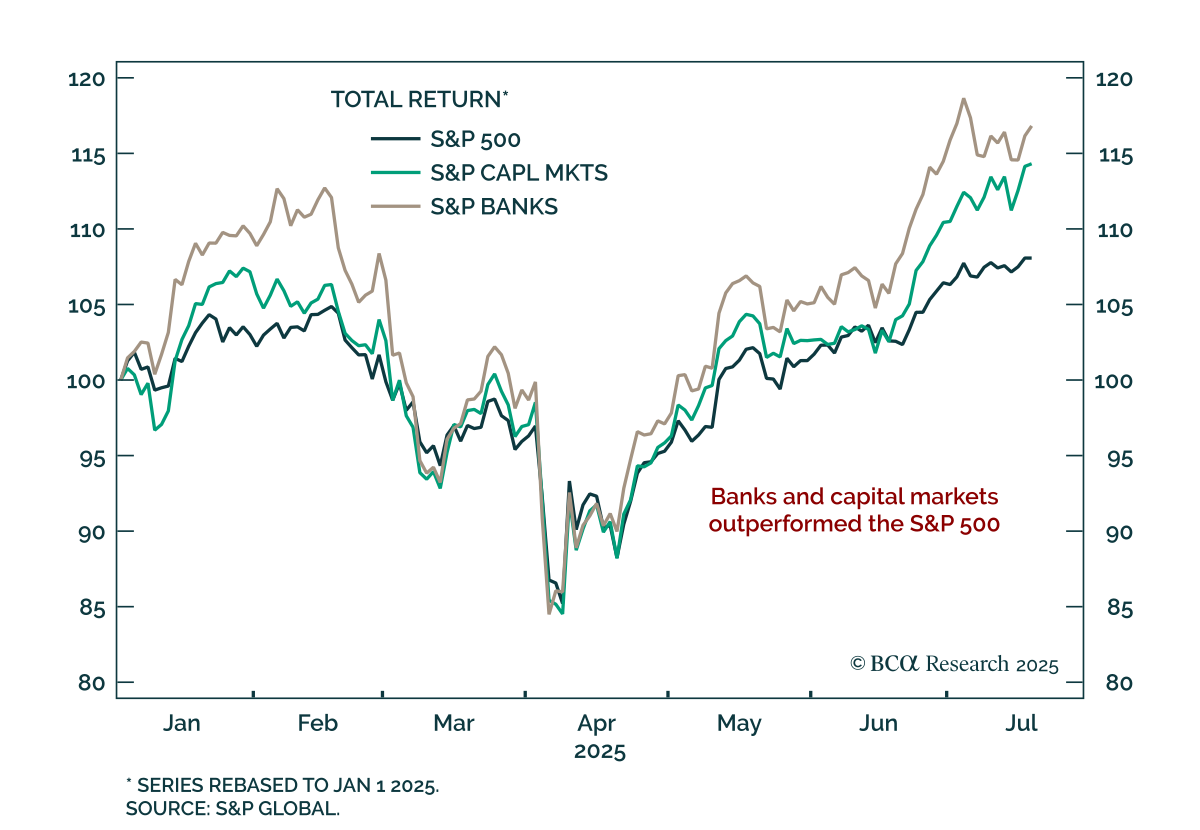
Eurozone banks have quietly outpaced the Magnificent 7—can they keep winning? With strong balance sheets, rising profitability, and structural tailwinds, European lenders still offer value despite short-term risks. Meanwhile, German equities continue to defy expectations, but is a near-term pullback on the horizon?
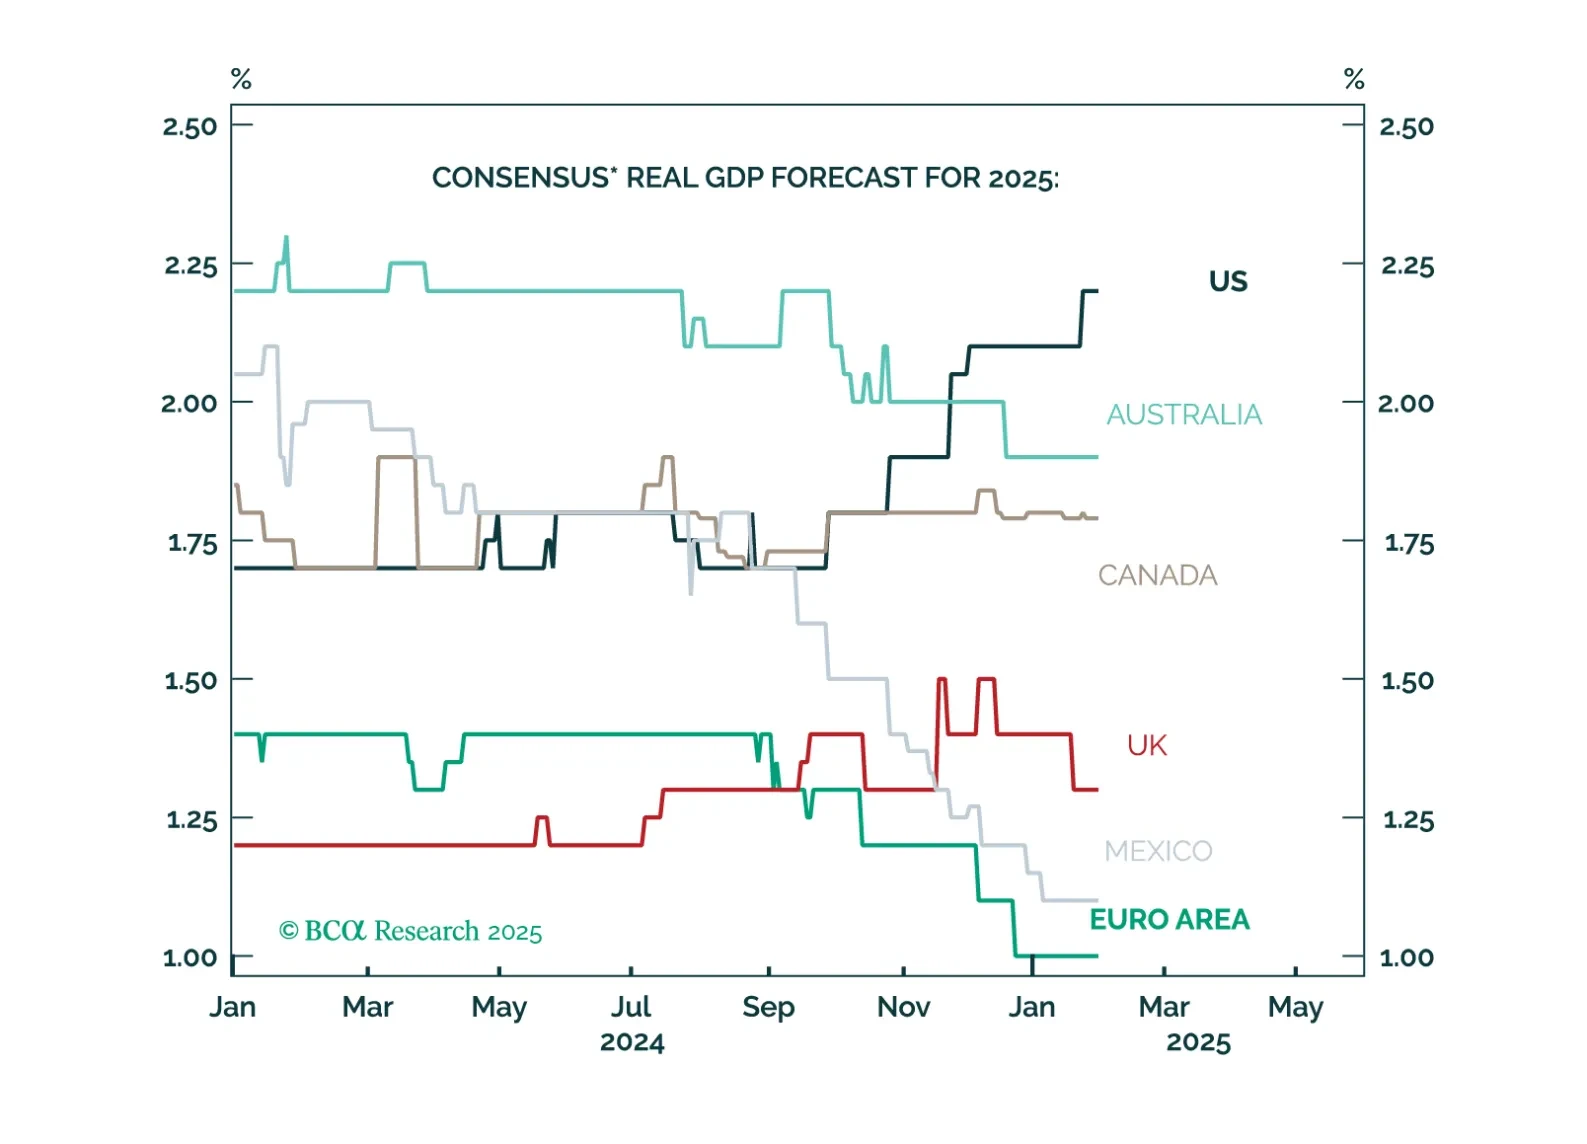
Markets and forecasters anticipate a “Golden Age” for Trump’s America, with US growth expectations soaring while the rest of the world lags. However, this extreme optimism means that there is a lot of room for disappointment. Cooling income growth, weak housing and less deficit spending than expected will result in US growth underperforming expectations. Maintain a modest underweight to equities and modest overweight to fixed income. US markets have become more expensive relative to the rest of the world even as quality differentials have stabilized. Prepare to downgrade US equities to underweight and to upgrade Euro Area and China to overweight. We will wait to pull the trigger until we have more clarity on trade policy and when the dollar's momentum turns negative.
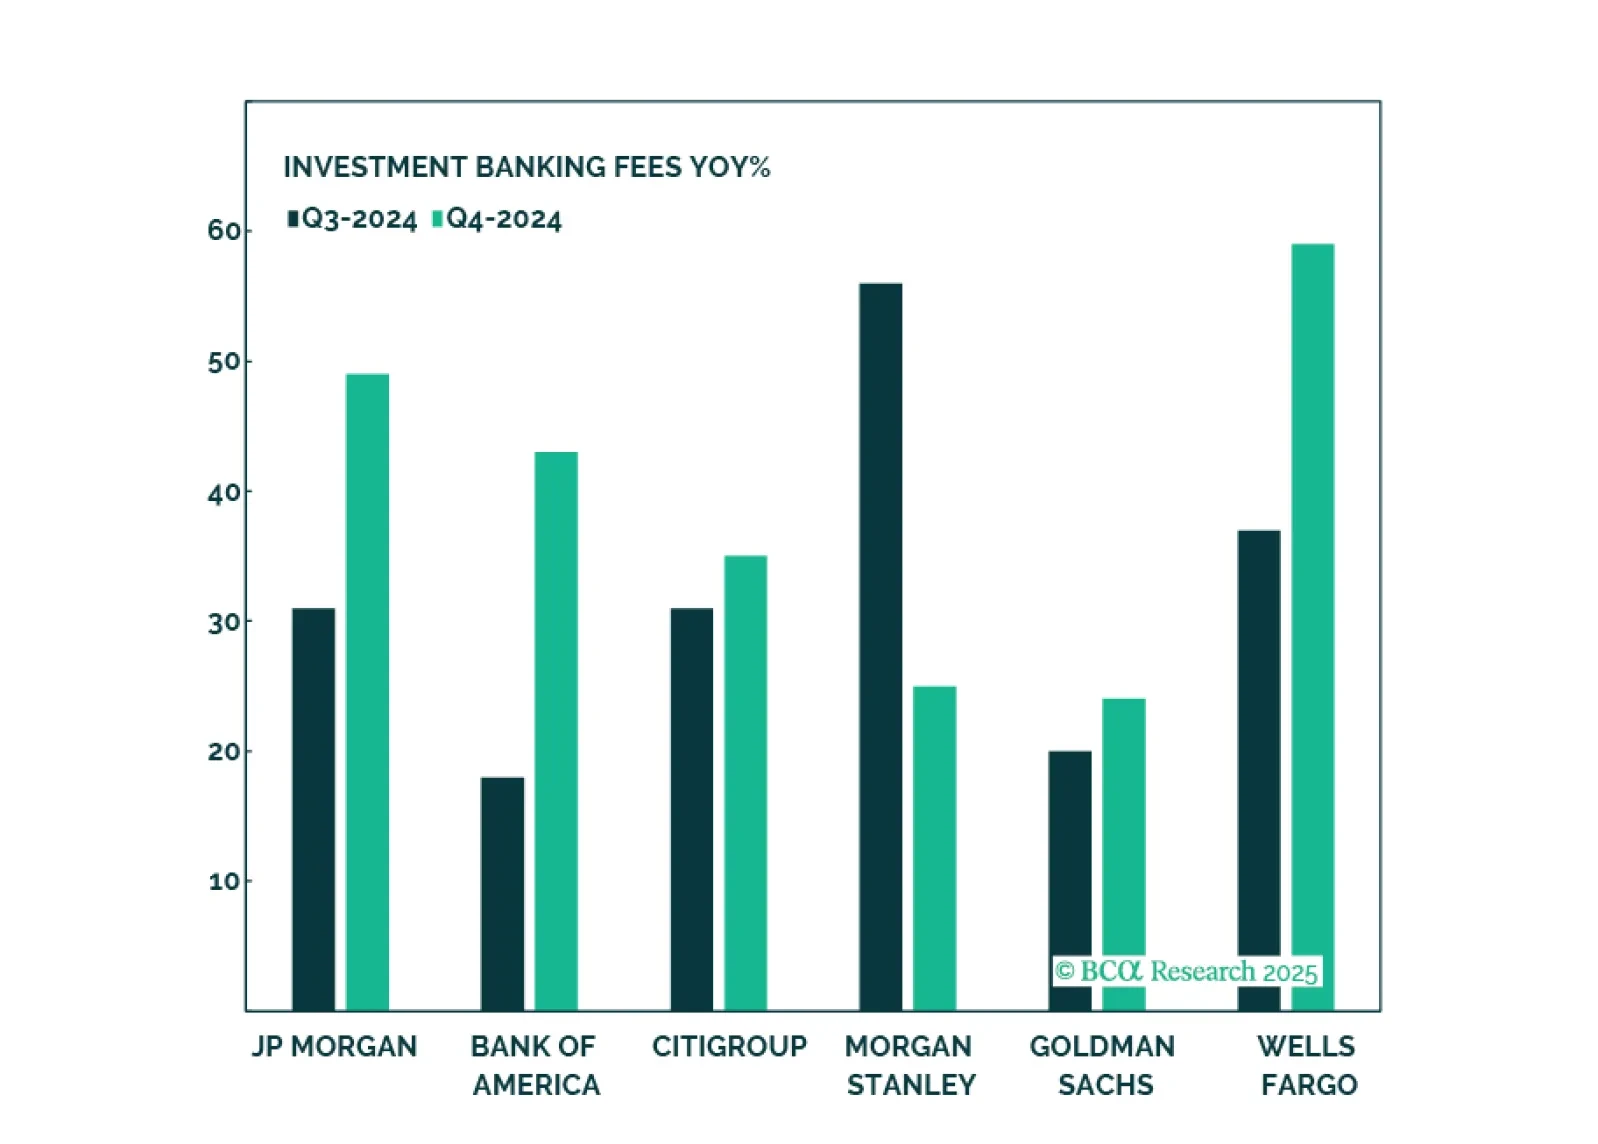
Banks have had an amazing run, and while such strong performance is unlikely to repeat, there is still oomph left in the trade thanks to a more favorable regulatory environment, stronger demand for loans, a steeper yield curve, and a strong pipeline of capital market activity. Key risks are further tightening of monetary policy and an increase in bad loans. We reiterate our overweight on Capital Markets, Diversified Banks, and Regional Banks.
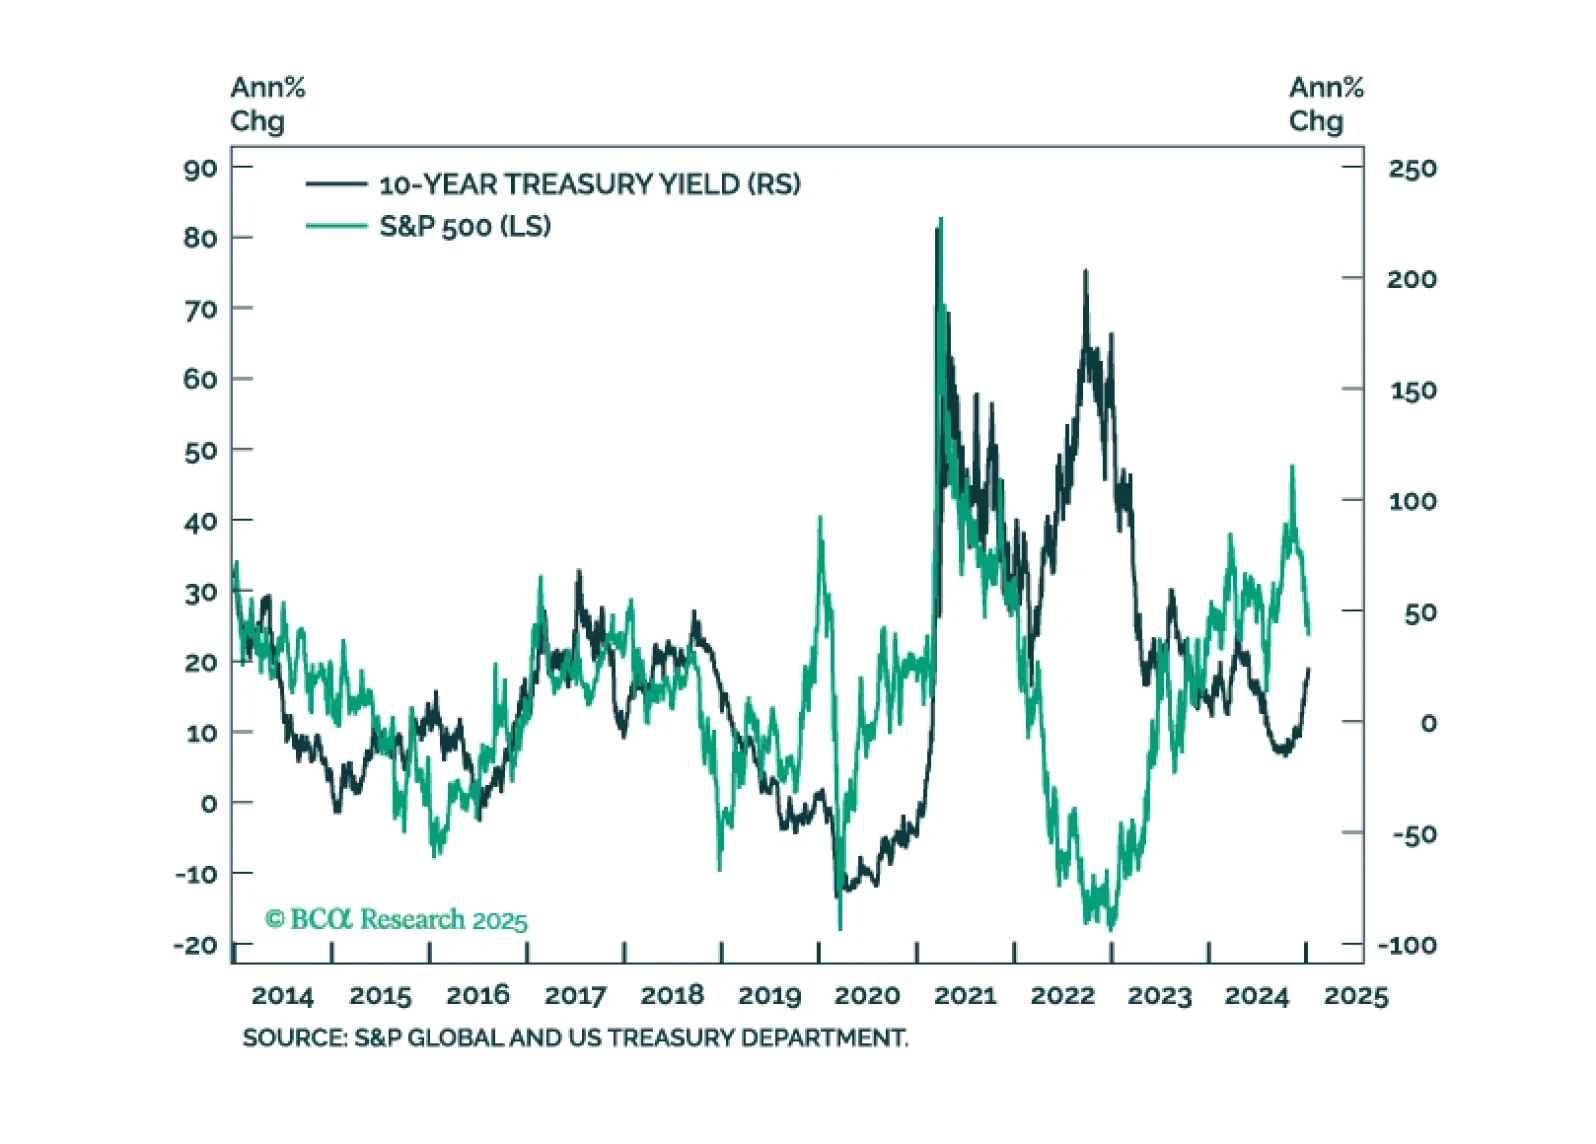
In this first presentation of 2025, we start with an overview of the 2025 outlook webcast polls, and a brief post-mortem of the 2024 market performance. Then, we shift gears and examine what is behind the recent surge in bond yields and its implications for equities. We also review market technicals and positioning and conclude with a list of trades to prepare our portfolio for continued moves in yields.