 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
Equities have thrown caution to the wind for much of April and early May. We do not disagree with the sanguine mood, but caution that the Hormuz saga is far from over. Still, the AI capex mania continues and the labor market is firming in the US, suggesting that there is more upside to equities.

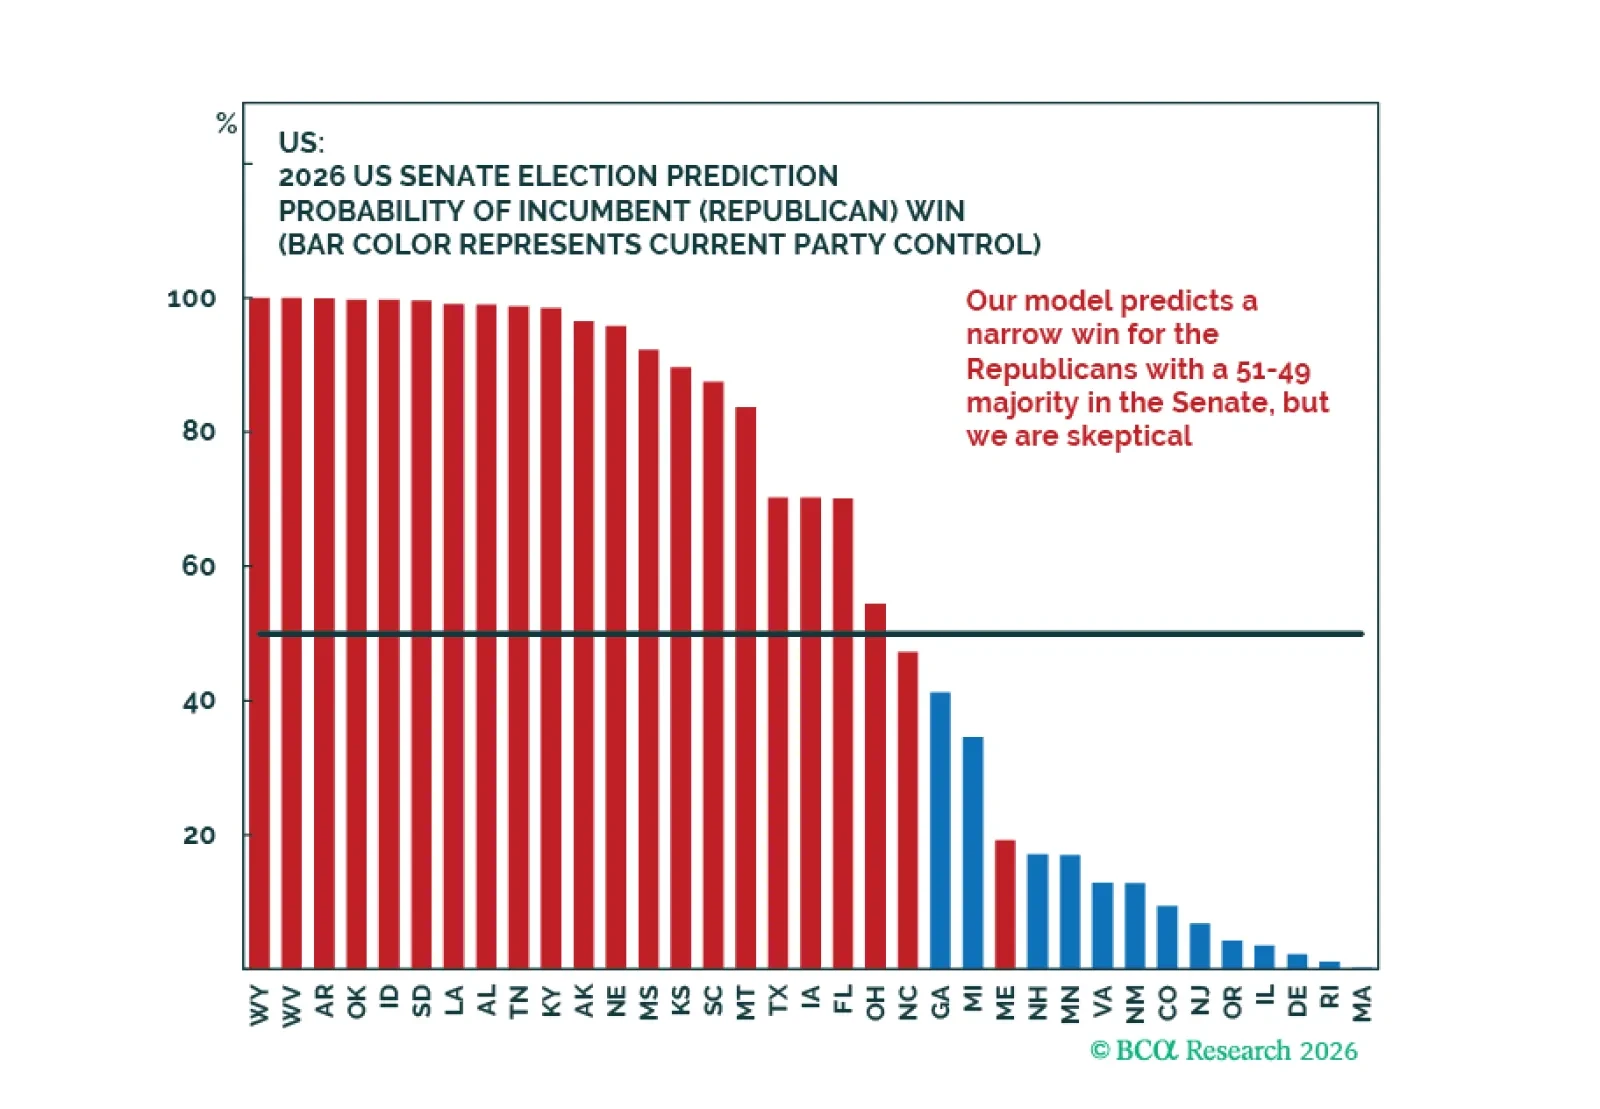
Aggregate Senate betting market pricing appears too pessimistic on Democrats relative to state-level odds and early polling, suggesting a potential mispricing and a relatively sanguine attitude towards the still-unresolved conflict in Iran and its aftermath.
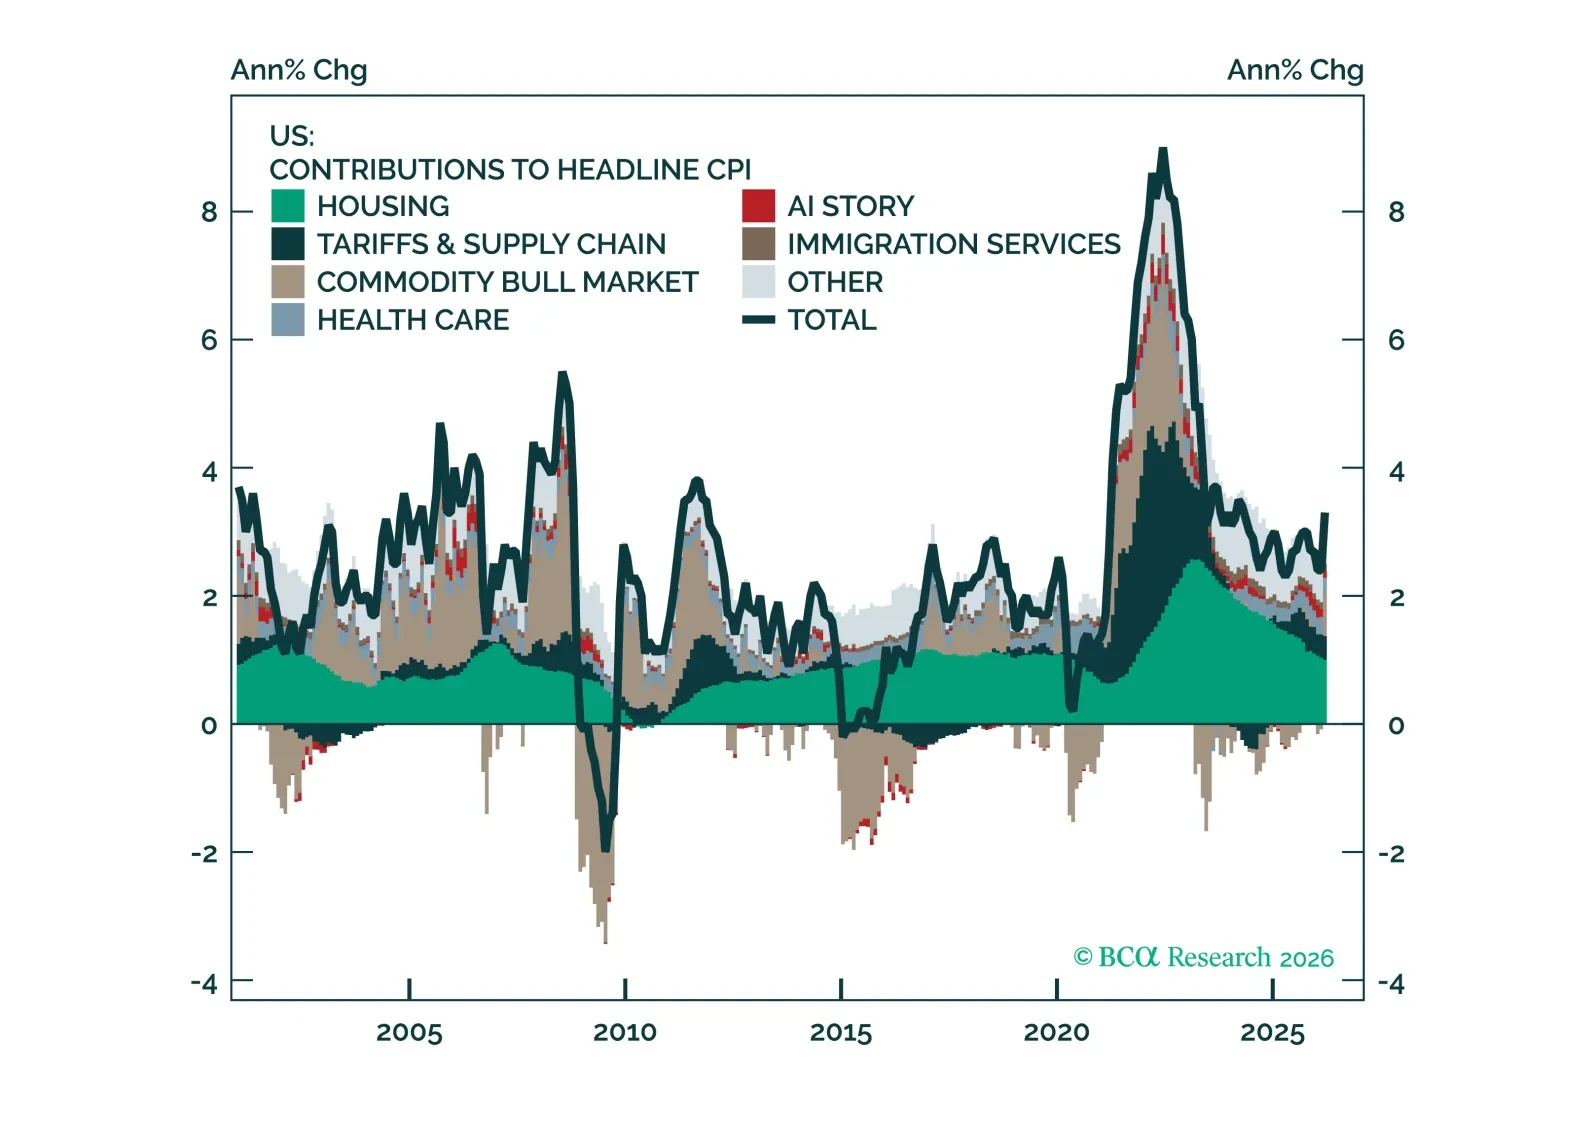
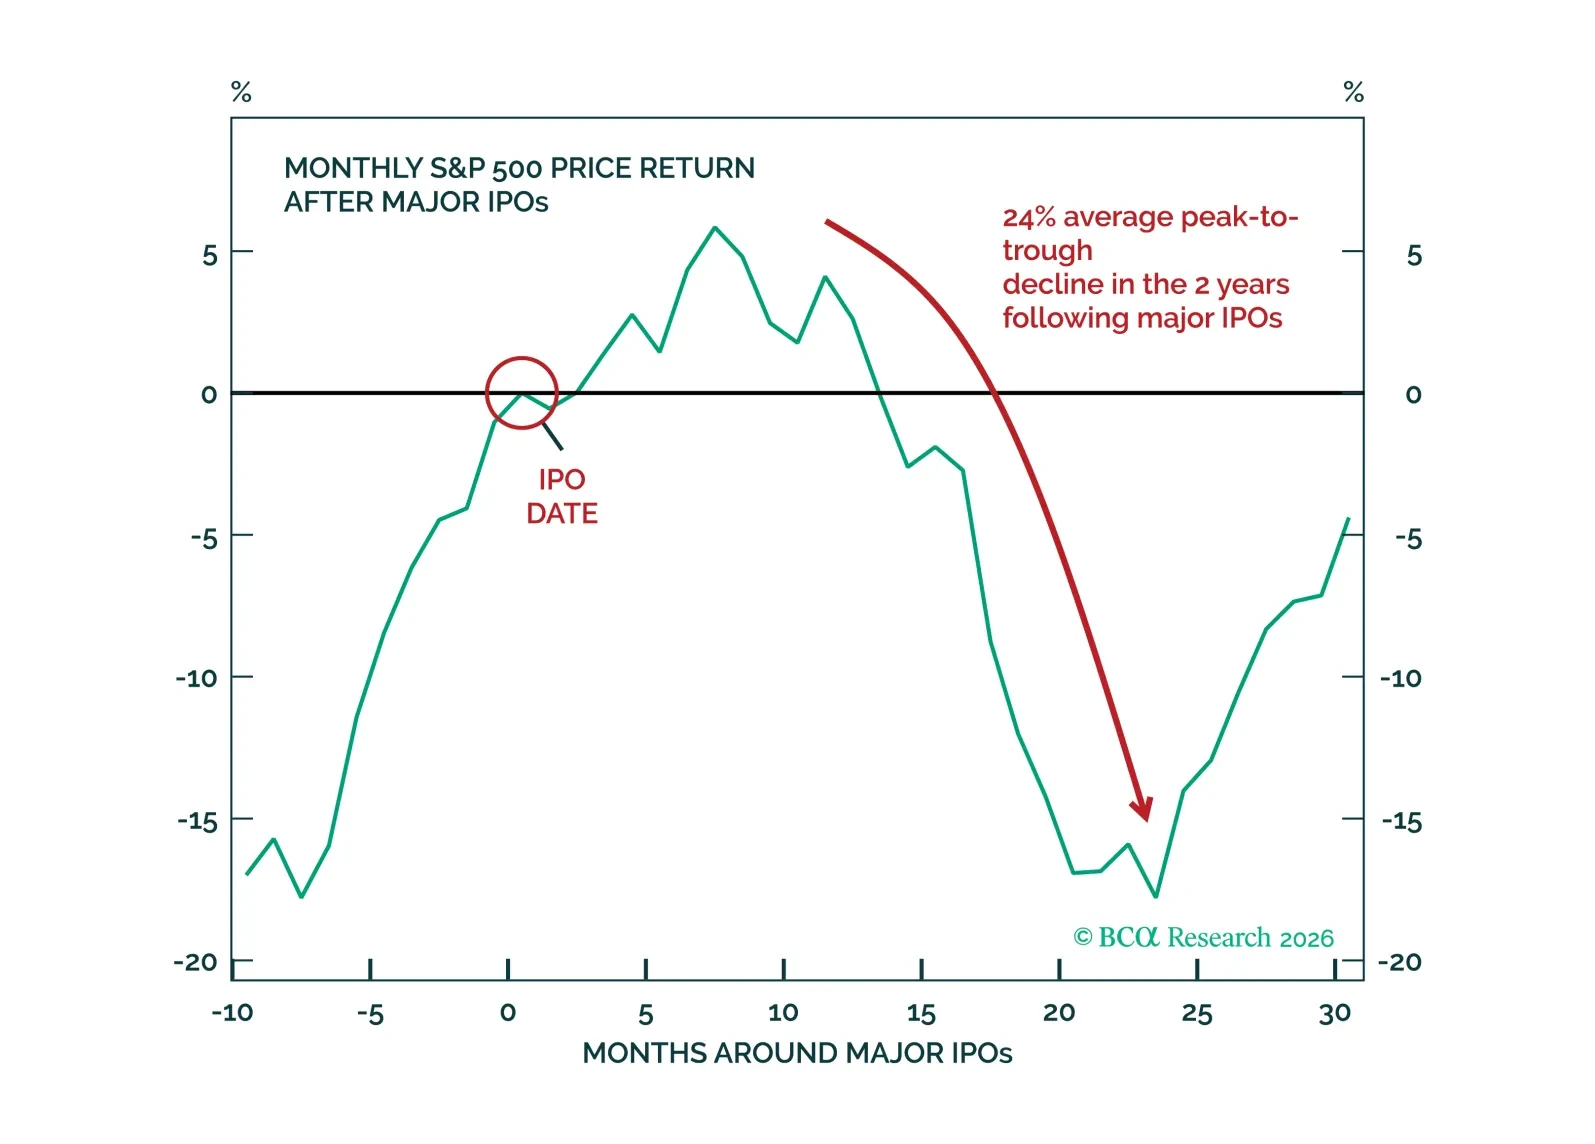
The tenuous ceasefire holds, with the "new geopolitical equilibrium scenario" remaining in place. Enough crude trickles through Hormuz to avert a global recession, but not to alleviate building inflationary pressures, a product of a complicated geomacro context that is not transitory. The Fed will look to ignore these in the short term, fueling the equity rally in the US. Chinese equities may pop thanks to the upcoming détente. When does it all end? Beware of major IPOs!
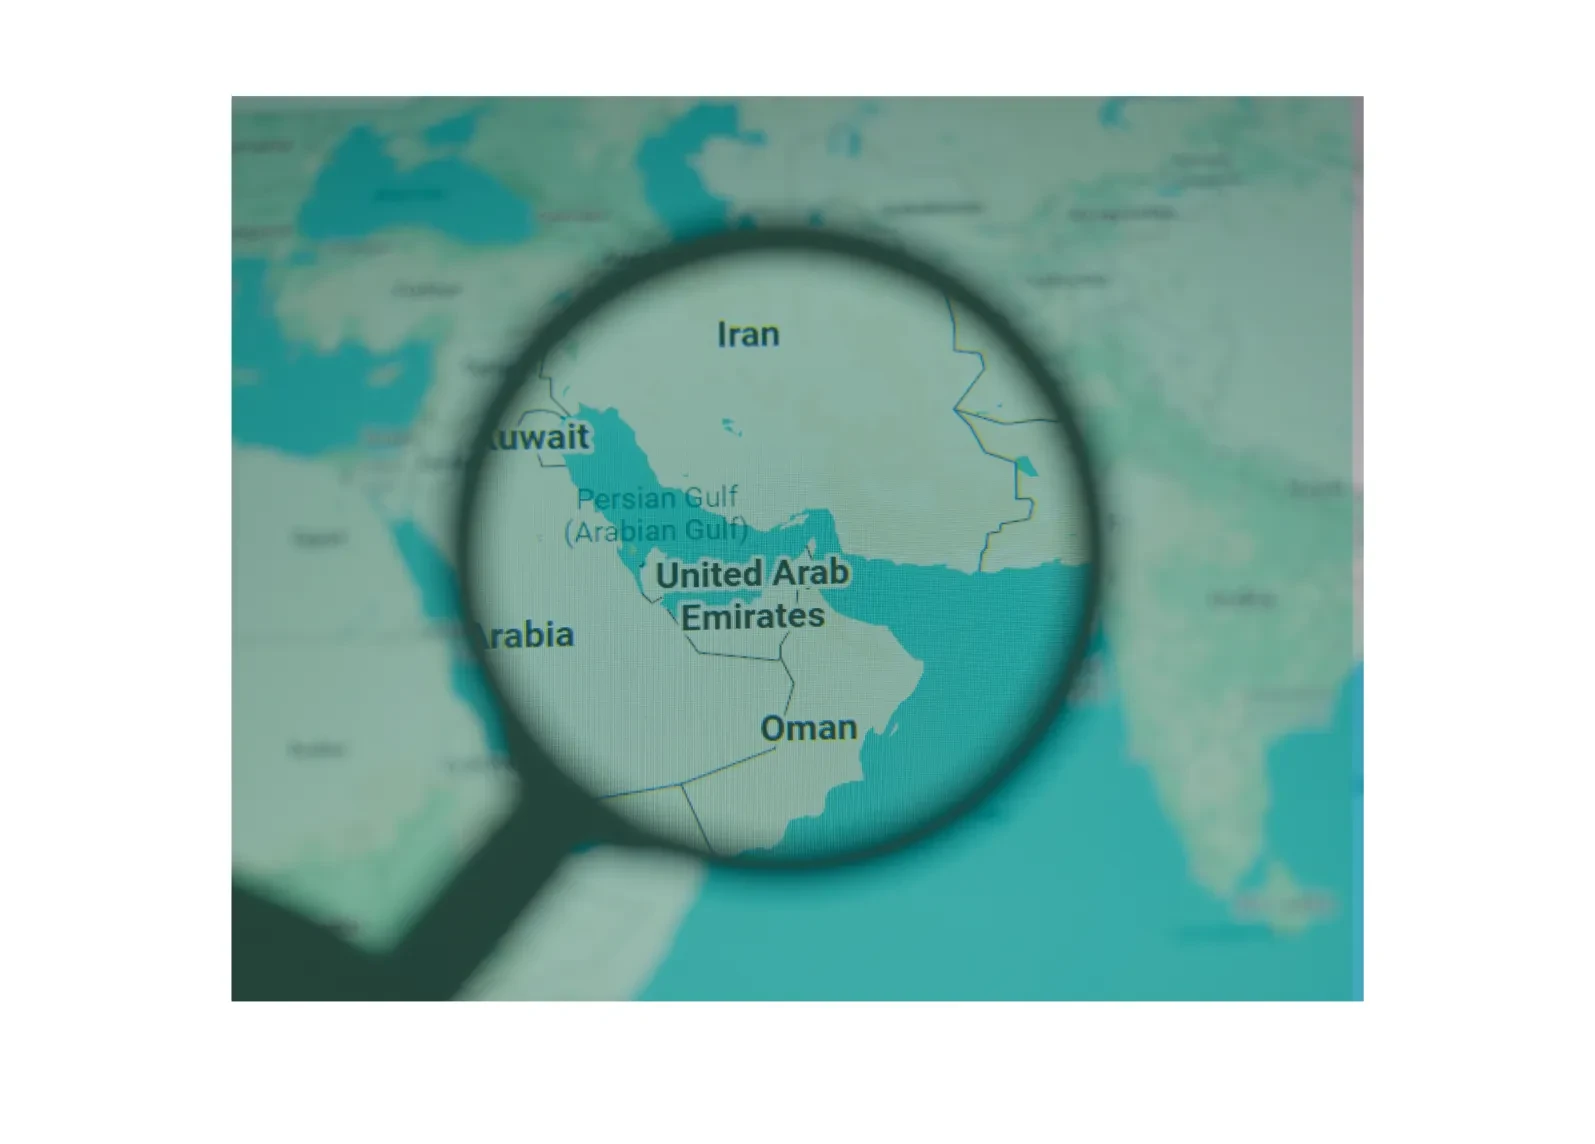
The surprisingly solid ceasefire between Iran, the US, Israel, and GCC countries broke on May 4 with a ballistic missile and drone attack against the UAE. According to reports, UAE defense forces intercepted 12 ballistic missiles, three cruise missiles, and four drones, launched by Iran.
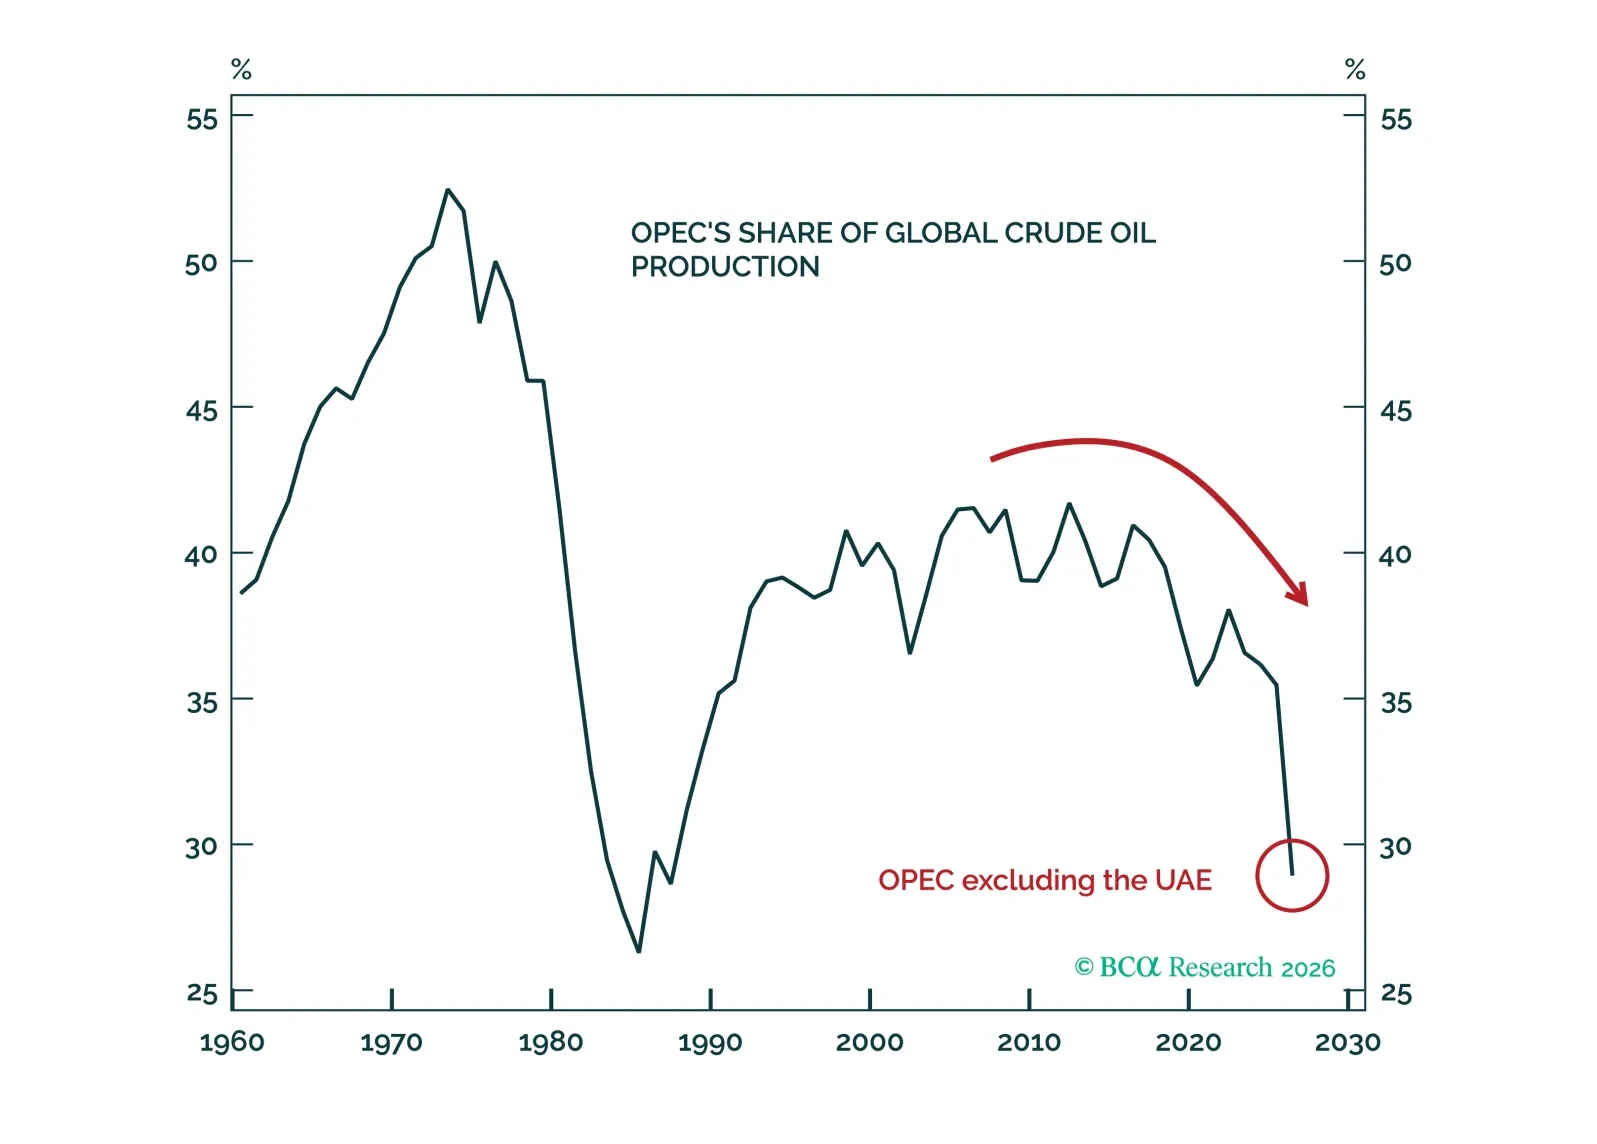
The UAE’s exit from OPEC is unlikely to impact oil markets in 2026. Over the longer term, however, the emergence of an “anti-OPEC club” of producers favoring unconstrained oil output growth would create a headwind to crude prices and weaken the price floor that OPEC seeks to defend.
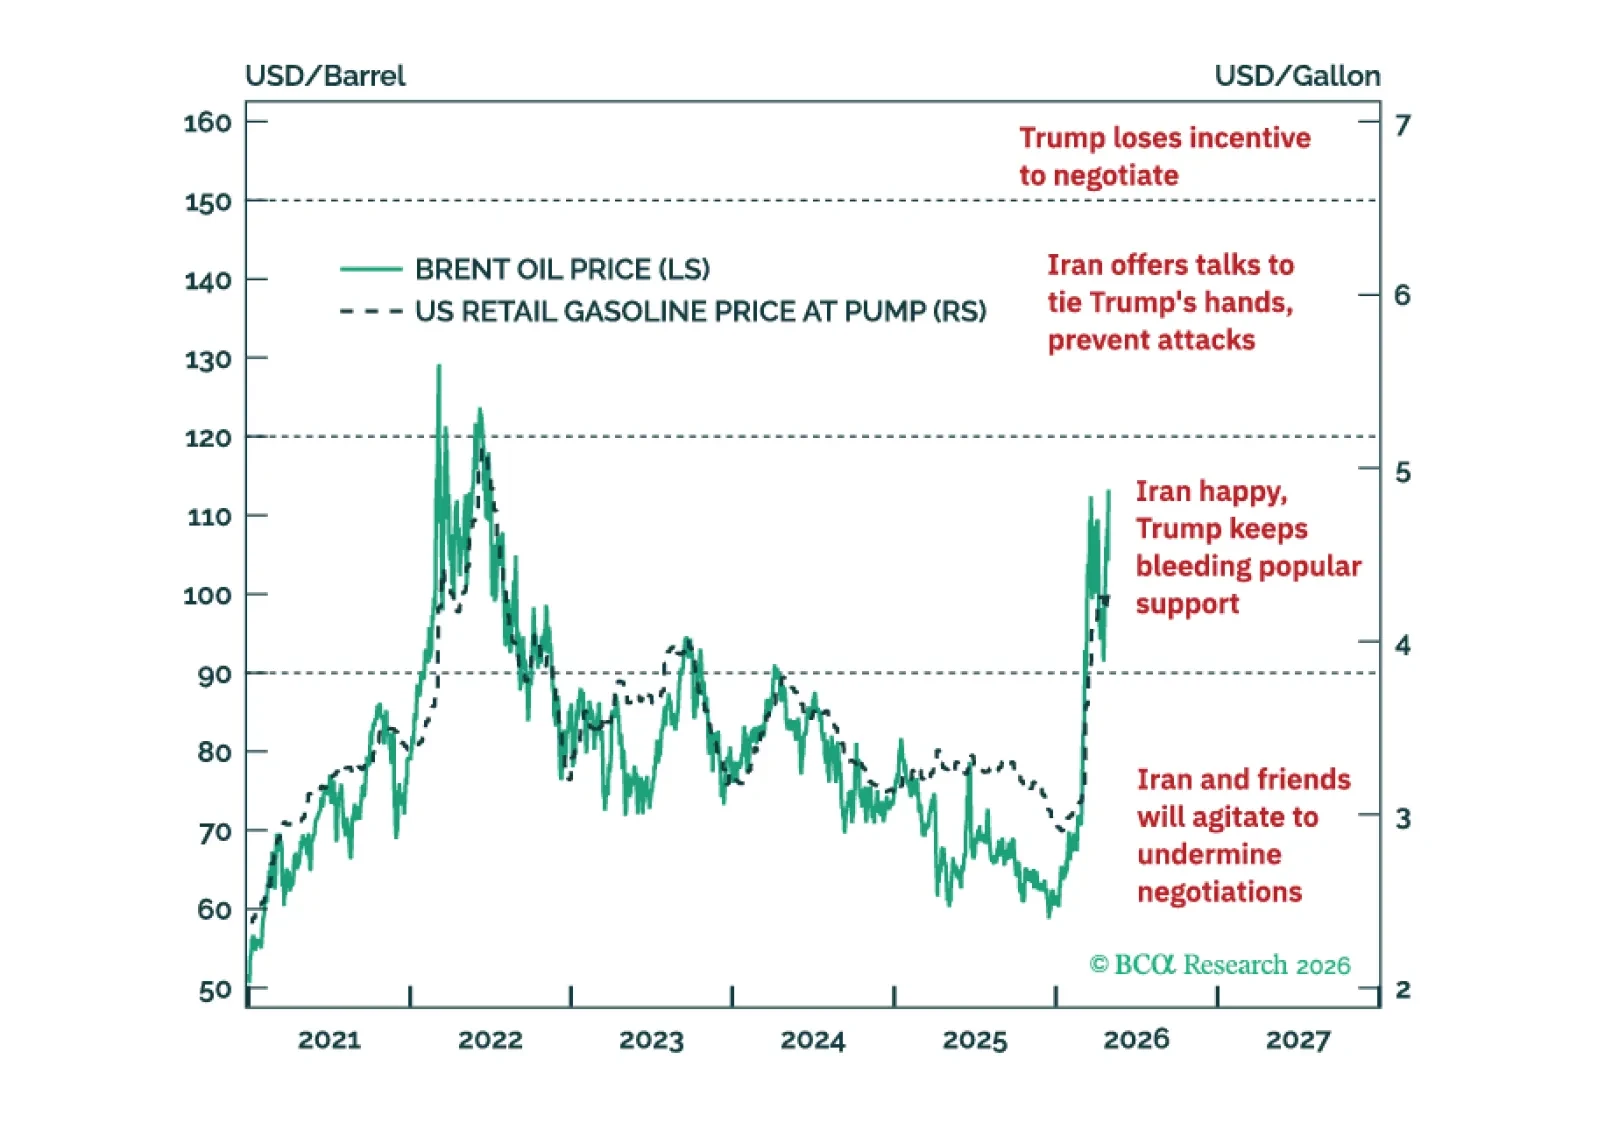
The Iran war is likely to re-escalate later this year even if shipping somehow resumes in the very near term — and yet an early reopening is looking less likely.
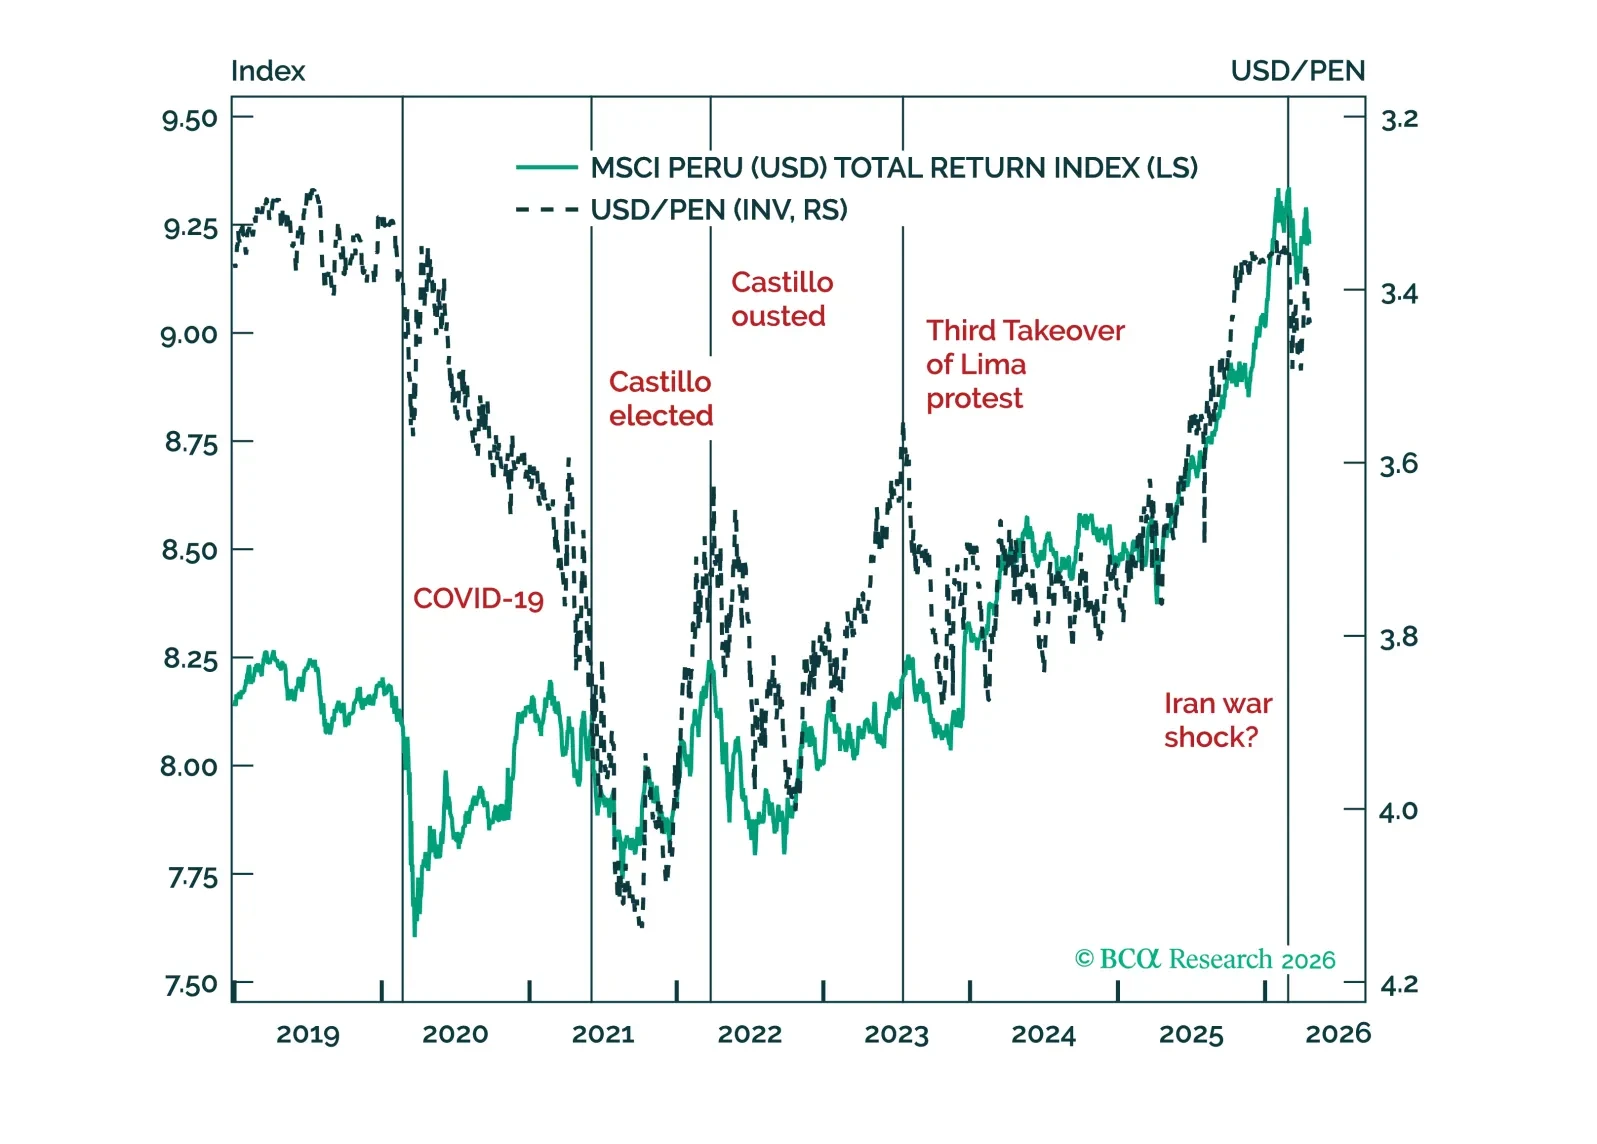
Peru is well established to elect a pro-market government in the June 7 run-off, with institutional constraints limiting left-tail policy risks. We will go long Peruvian assets when Hormuz volatility subsides.
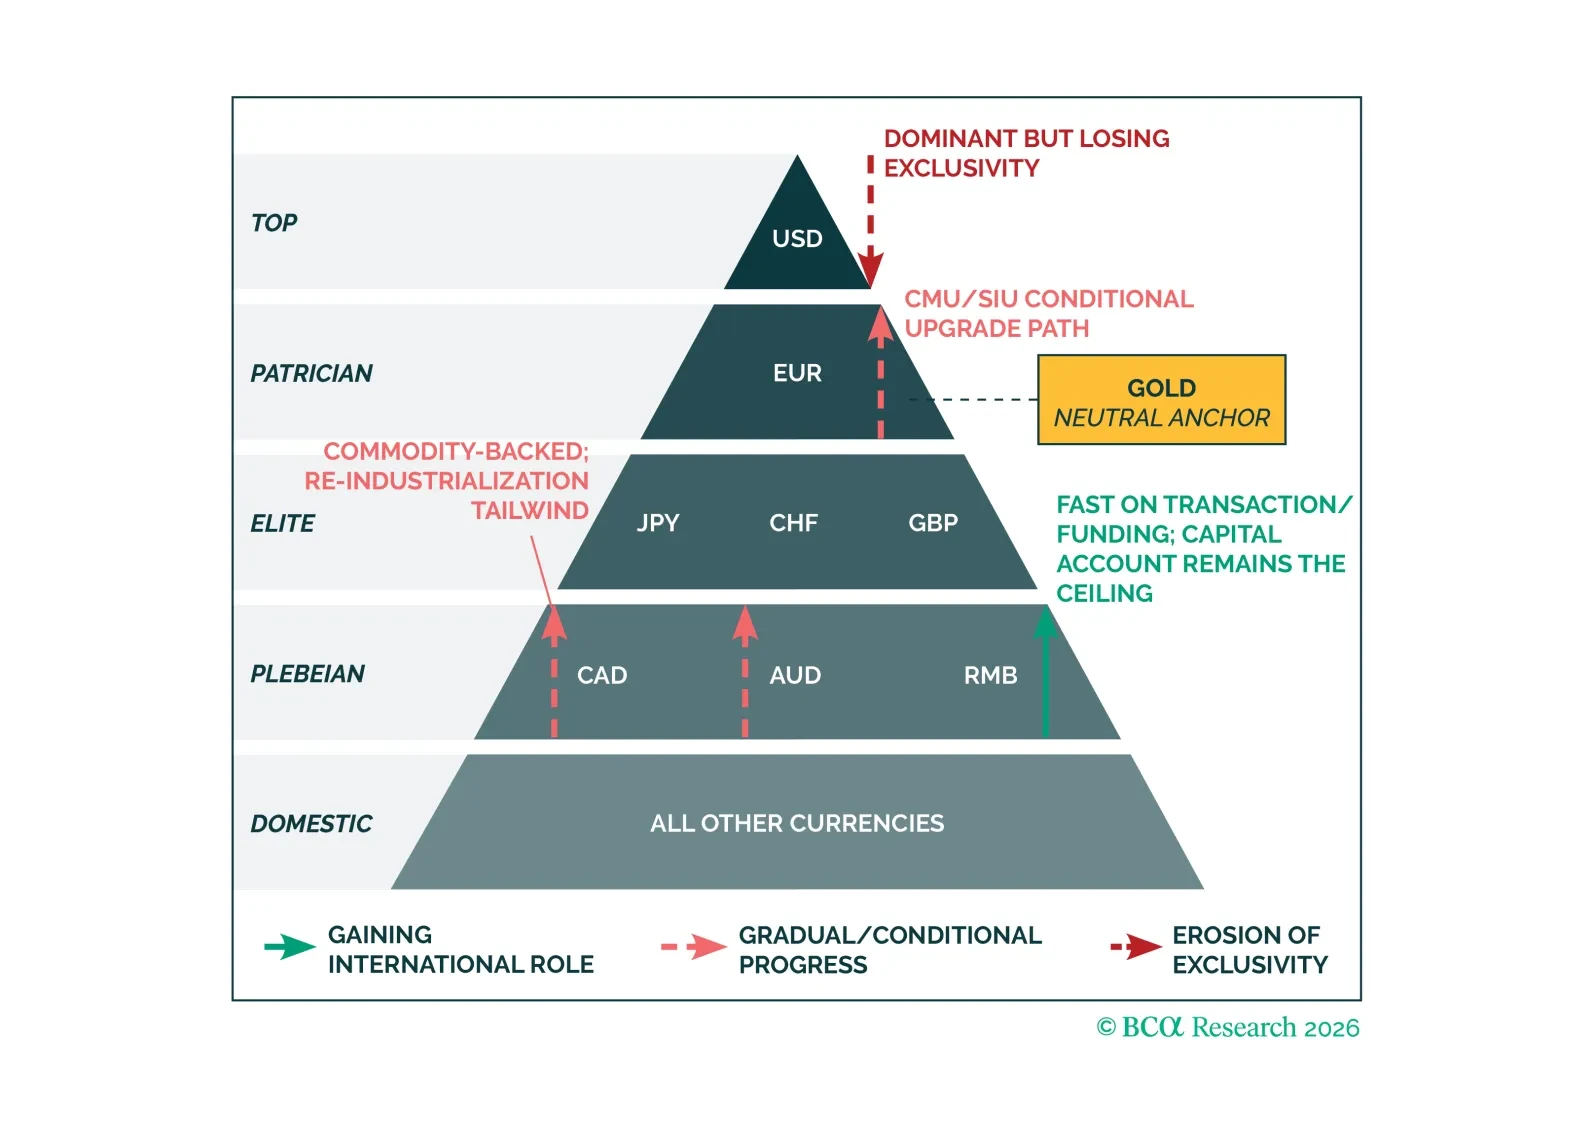
The debate over “what replaces the dollar” is misguided. The real shift is toward a multi-anchor system where reserve functions fragment. That changes everything from term premia to cross-asset correlations. The implication: portfolios built for the old regime are already behind the curve.
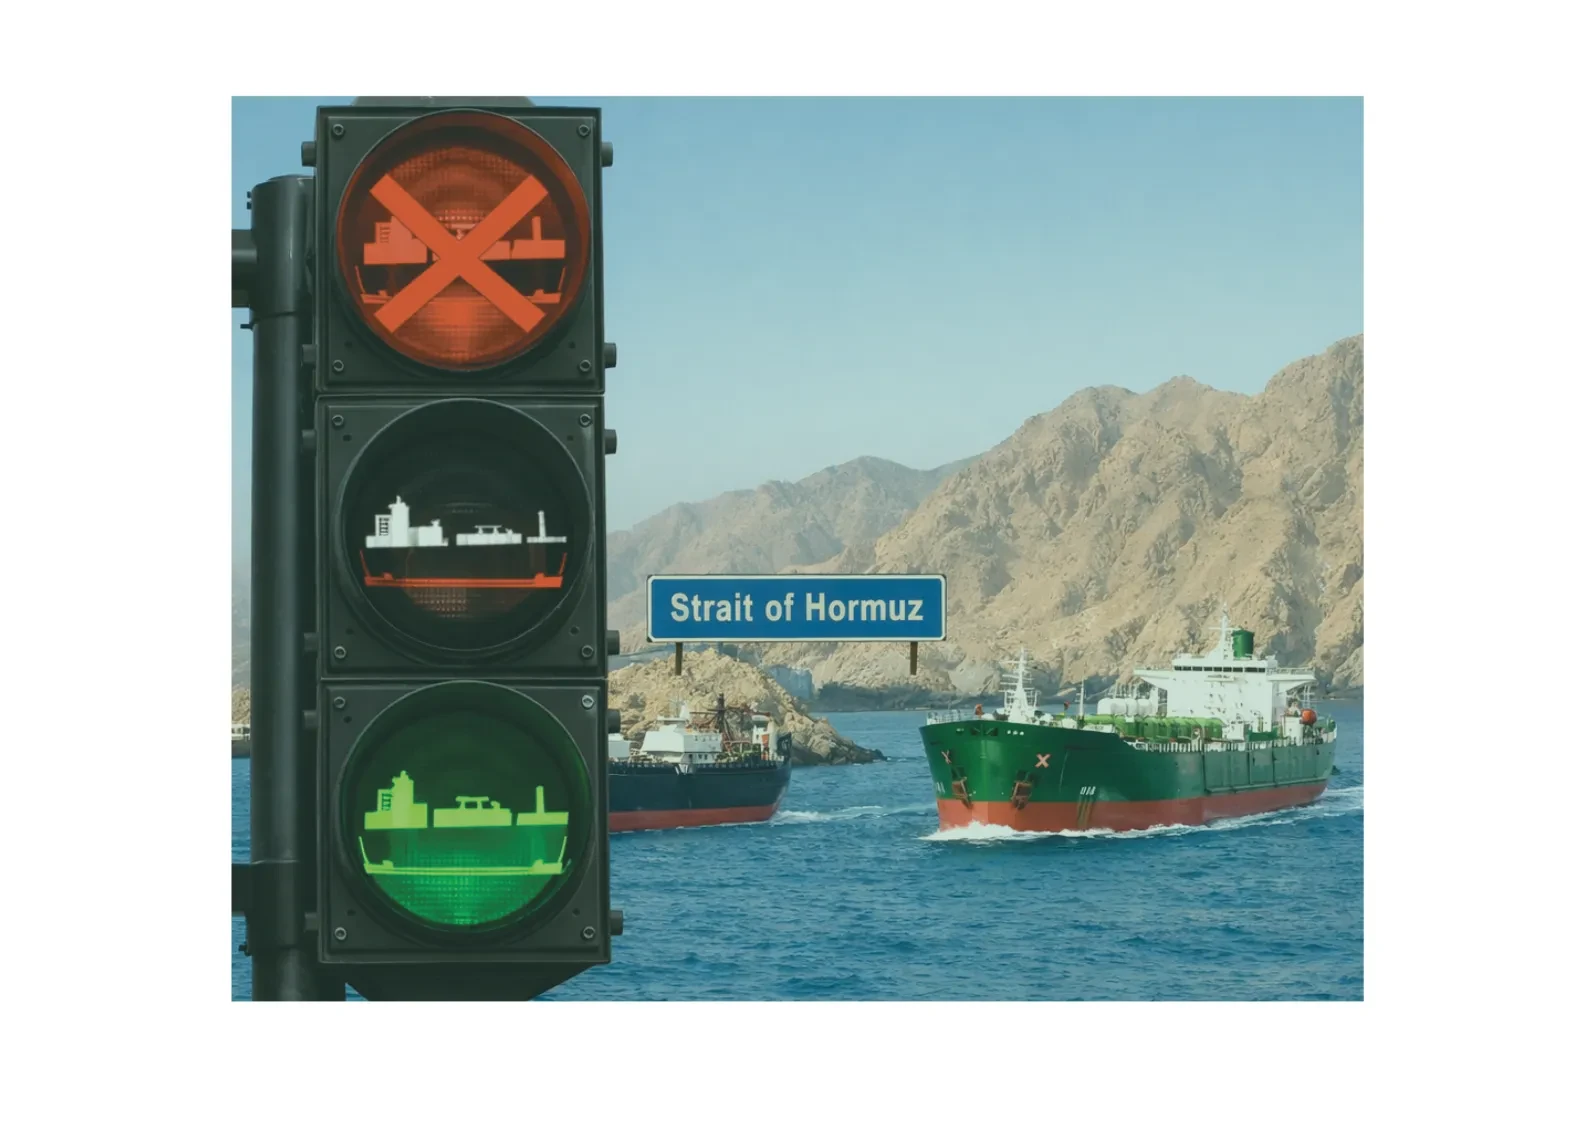
Red Light. Green Light. So much for the “all clear” in the Hormuz saga.