 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
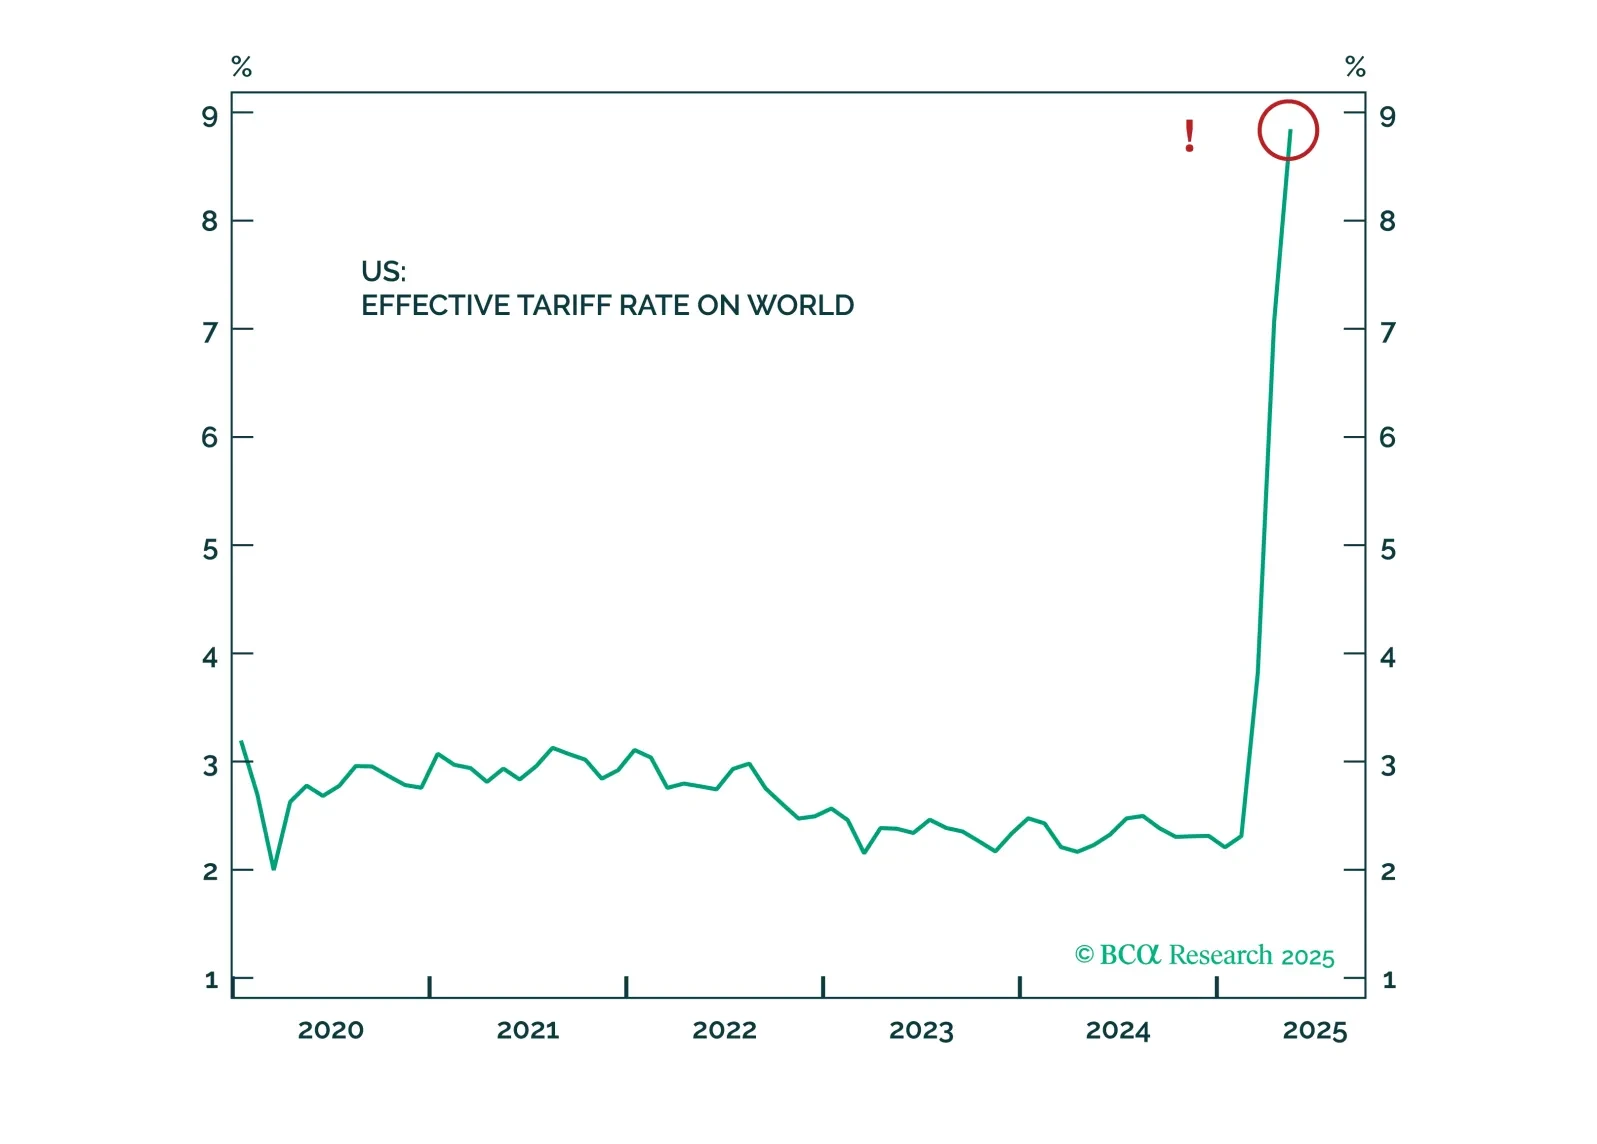
Investors should stick to a defensive stance in the very near term as the Russia-Ukraine conflict and persistent trade tensions cause market volatility.
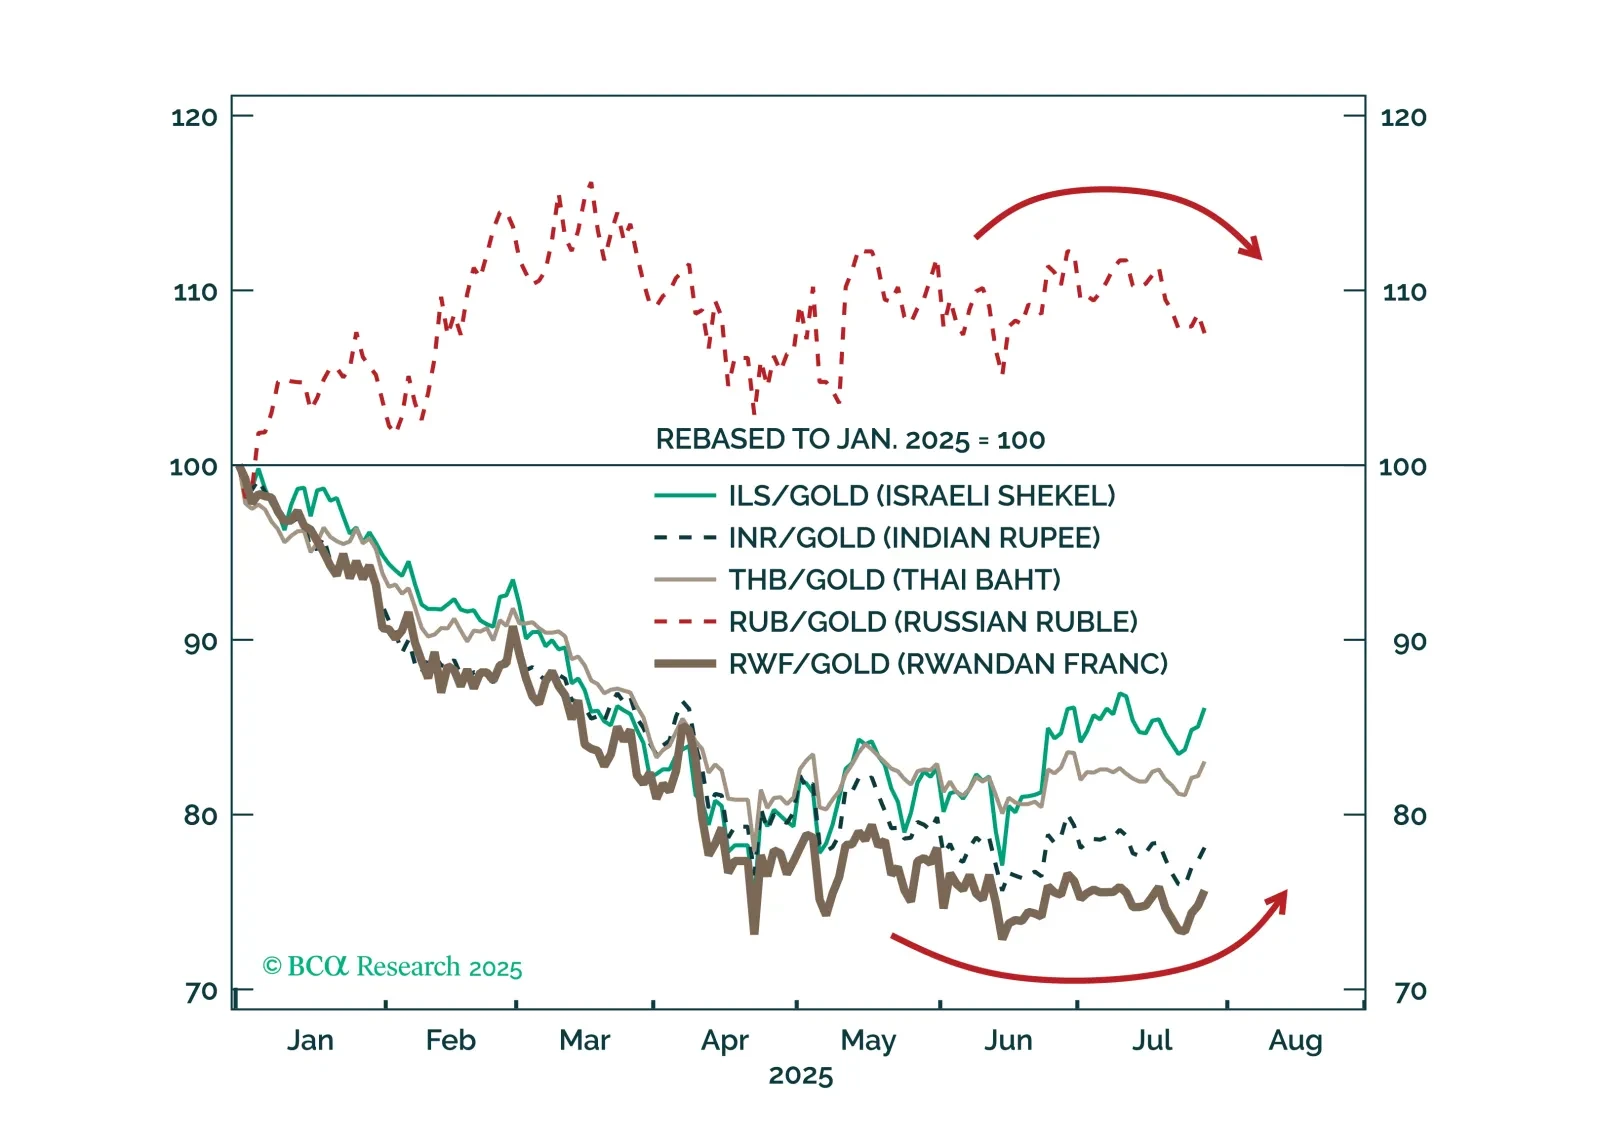
Russia poses an immediate risk to global financial markets, and then perhaps a buying opportunity. Trump is pivoting to ceasefires and trade deals, but Russia could trigger a new tariff shock first.

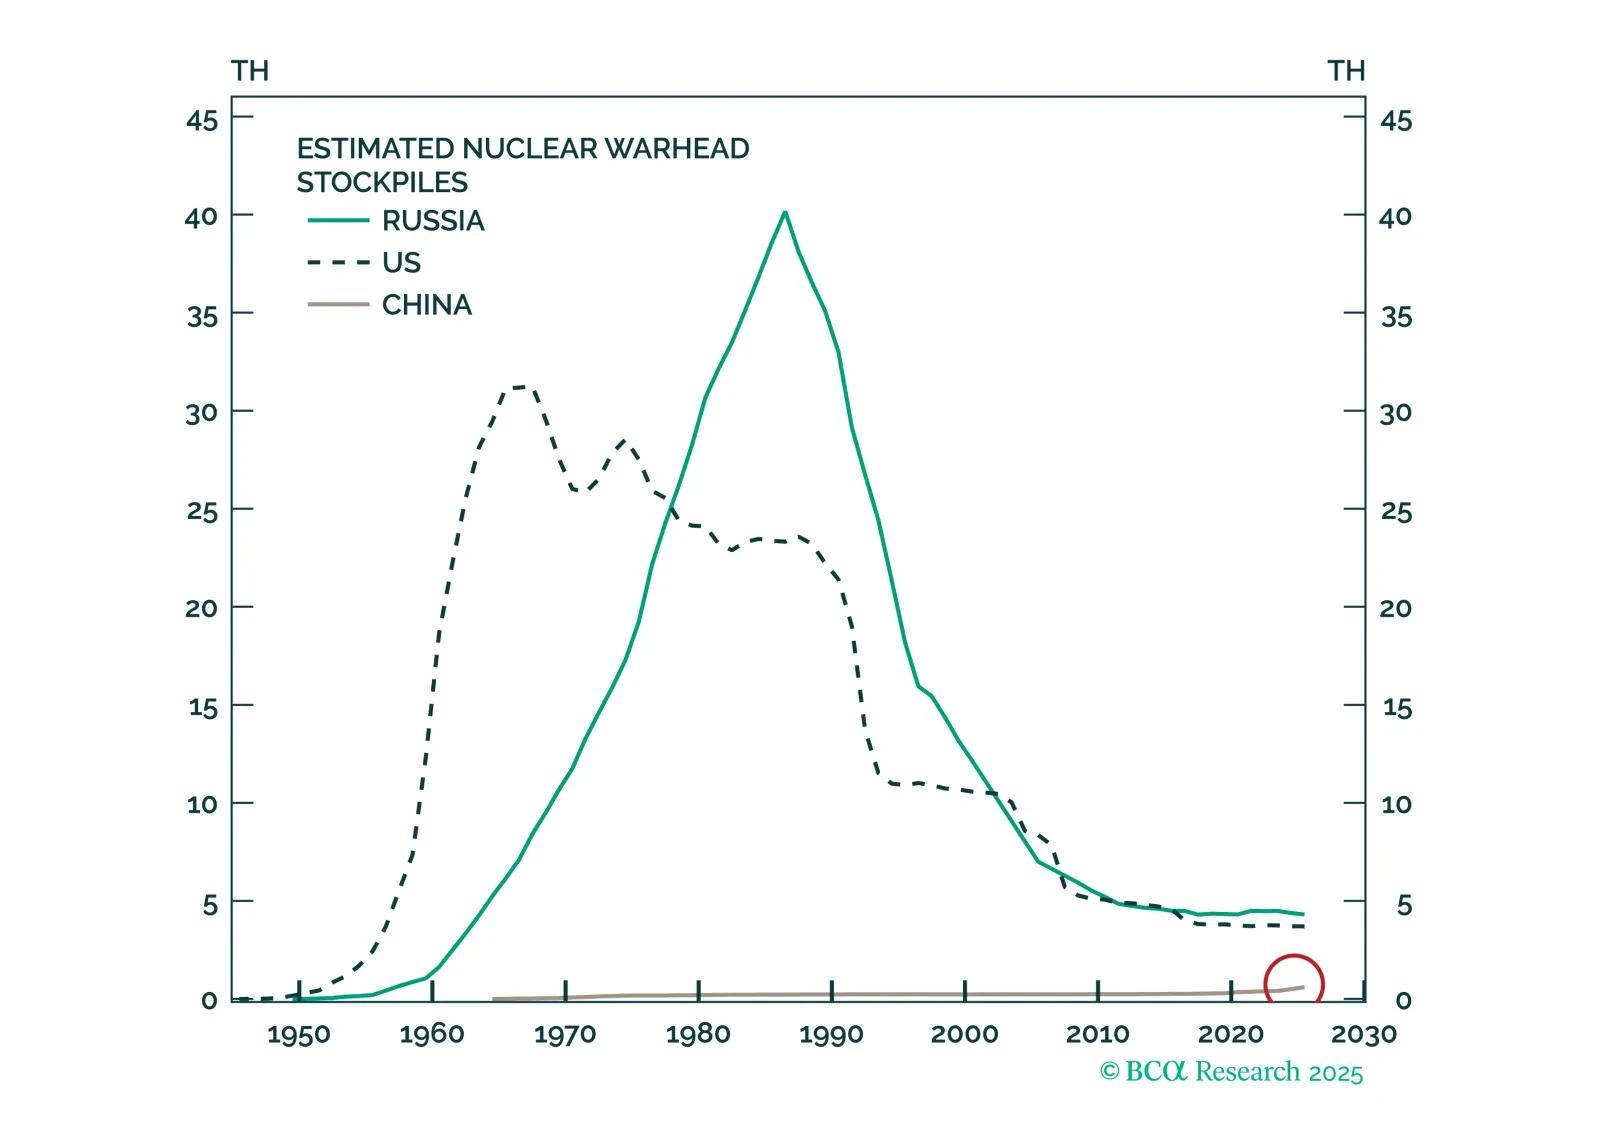
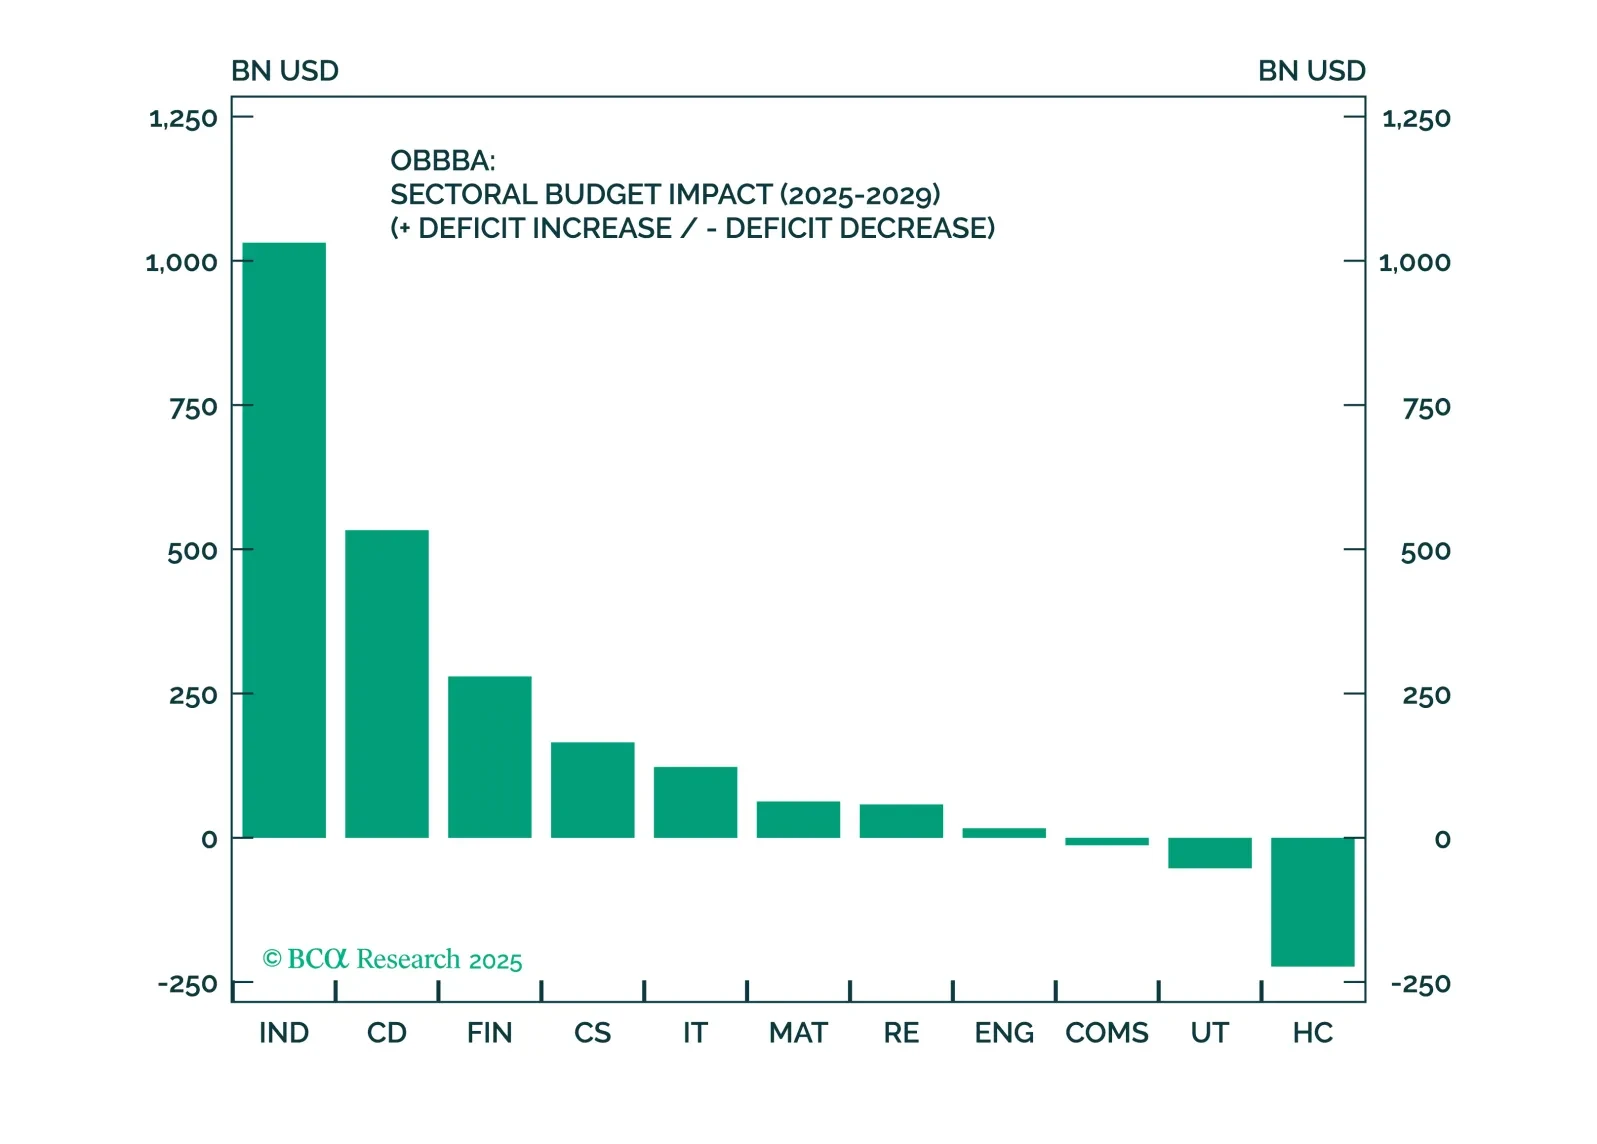
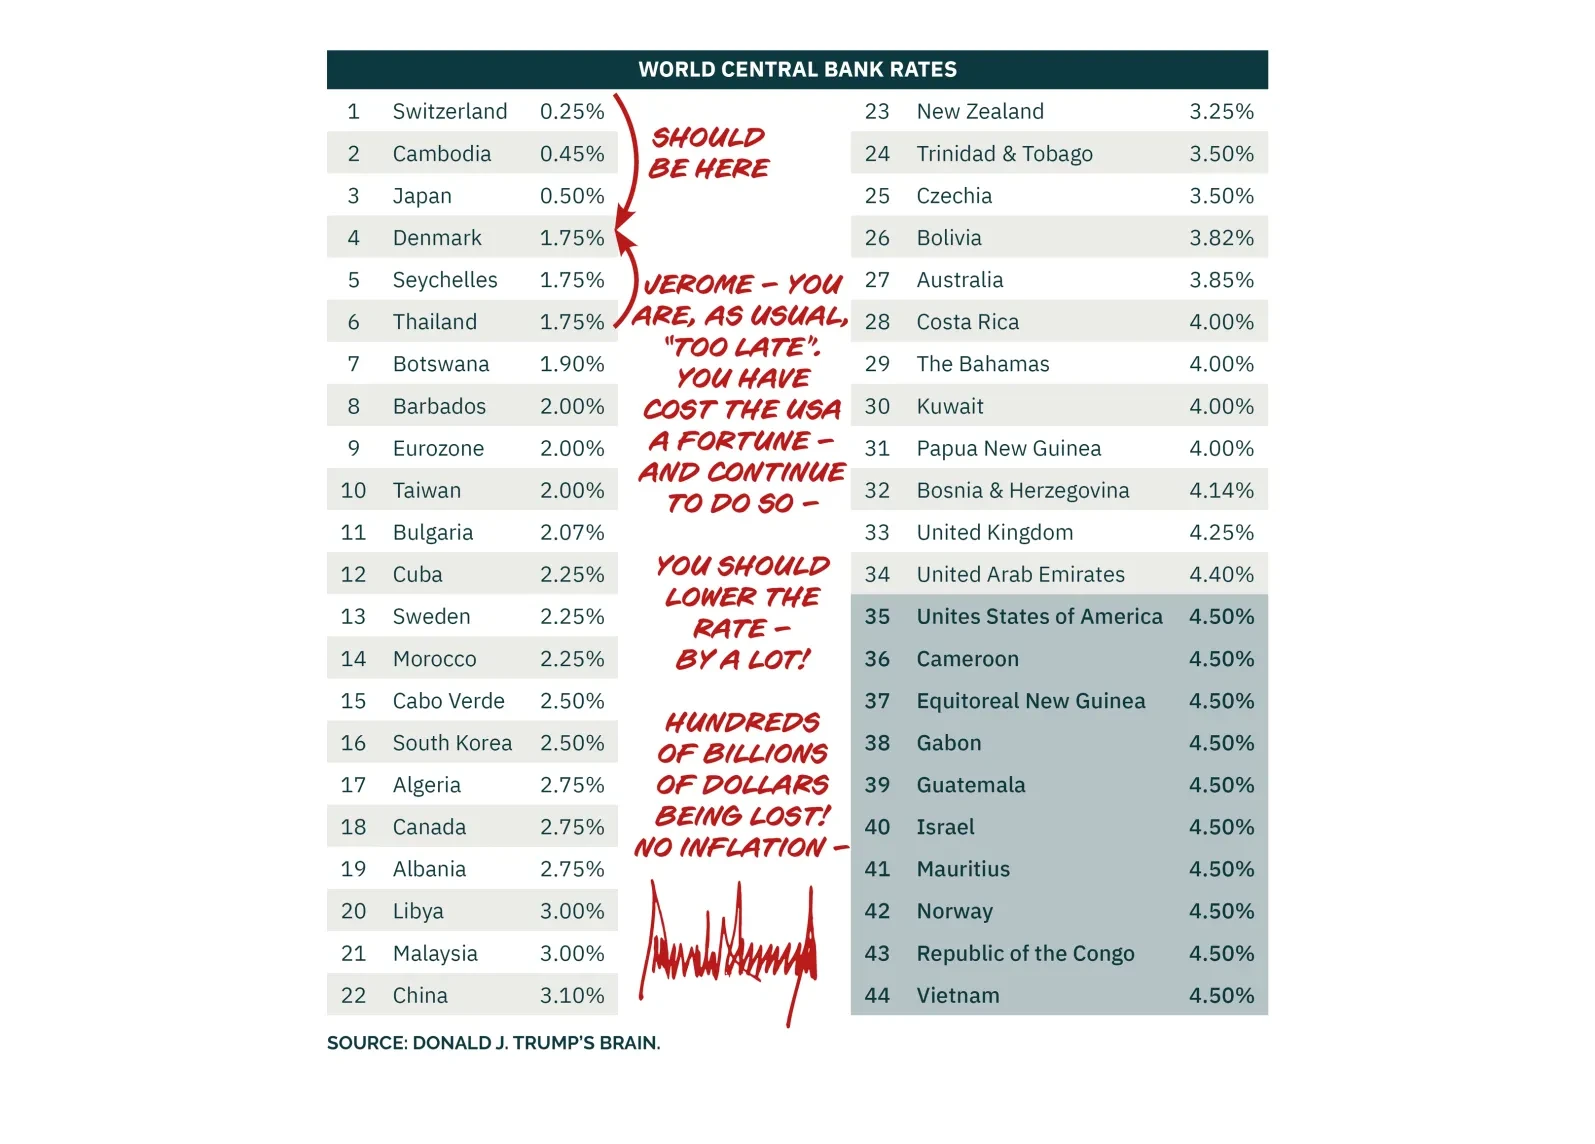
We have thrown caution to the wind and gone overweight equities. Why? Three reasons: the Fed is under immense political pressure to pivot, USD has depreciated, and inflation is in check. It is going to be a very difficult job for Fed Chair Powell to ignore the downside risks to both inflation and growth. If he does, he will be accused – correctly – of political bias.
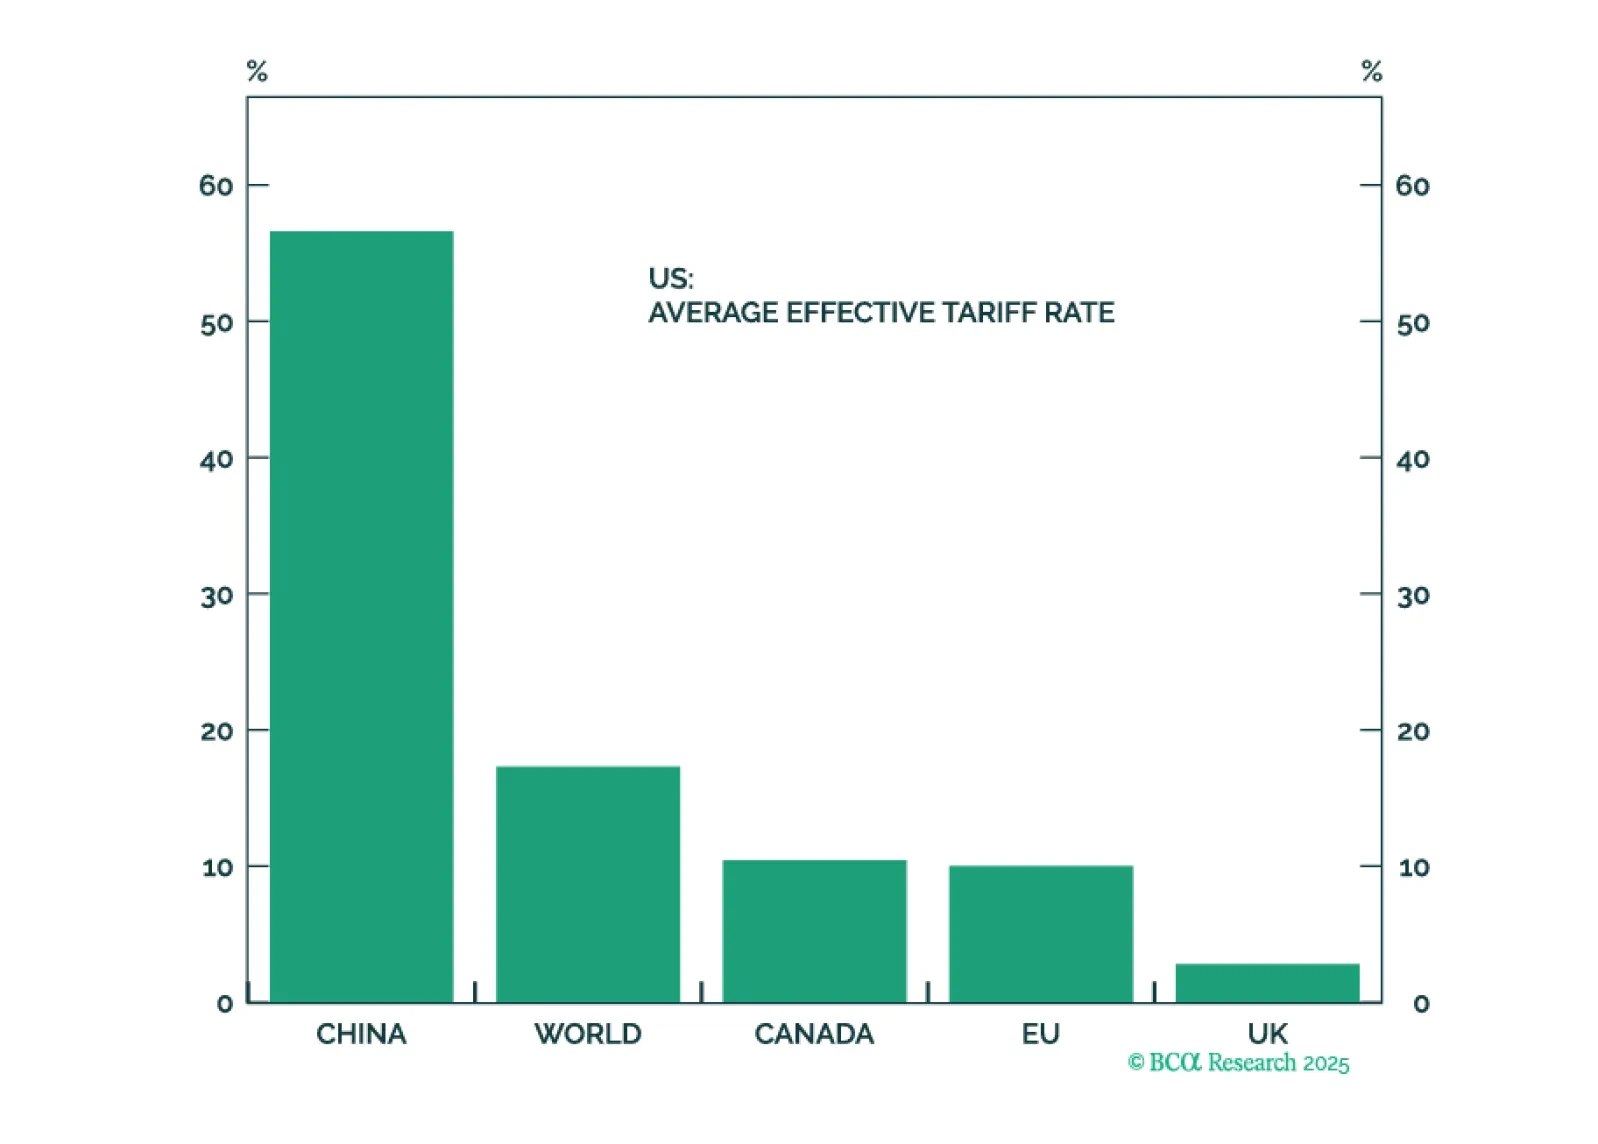
Acute geopolitical risks, like a massive oil shock, may be abating. But structural geopolitical risk remains high and could upset a blithe market. Cyclical economic risks are underrated as the US slows down and China continues to stumble. Investors should book some profits in anticipation of tariff implementation and a downturn in hard economic data.
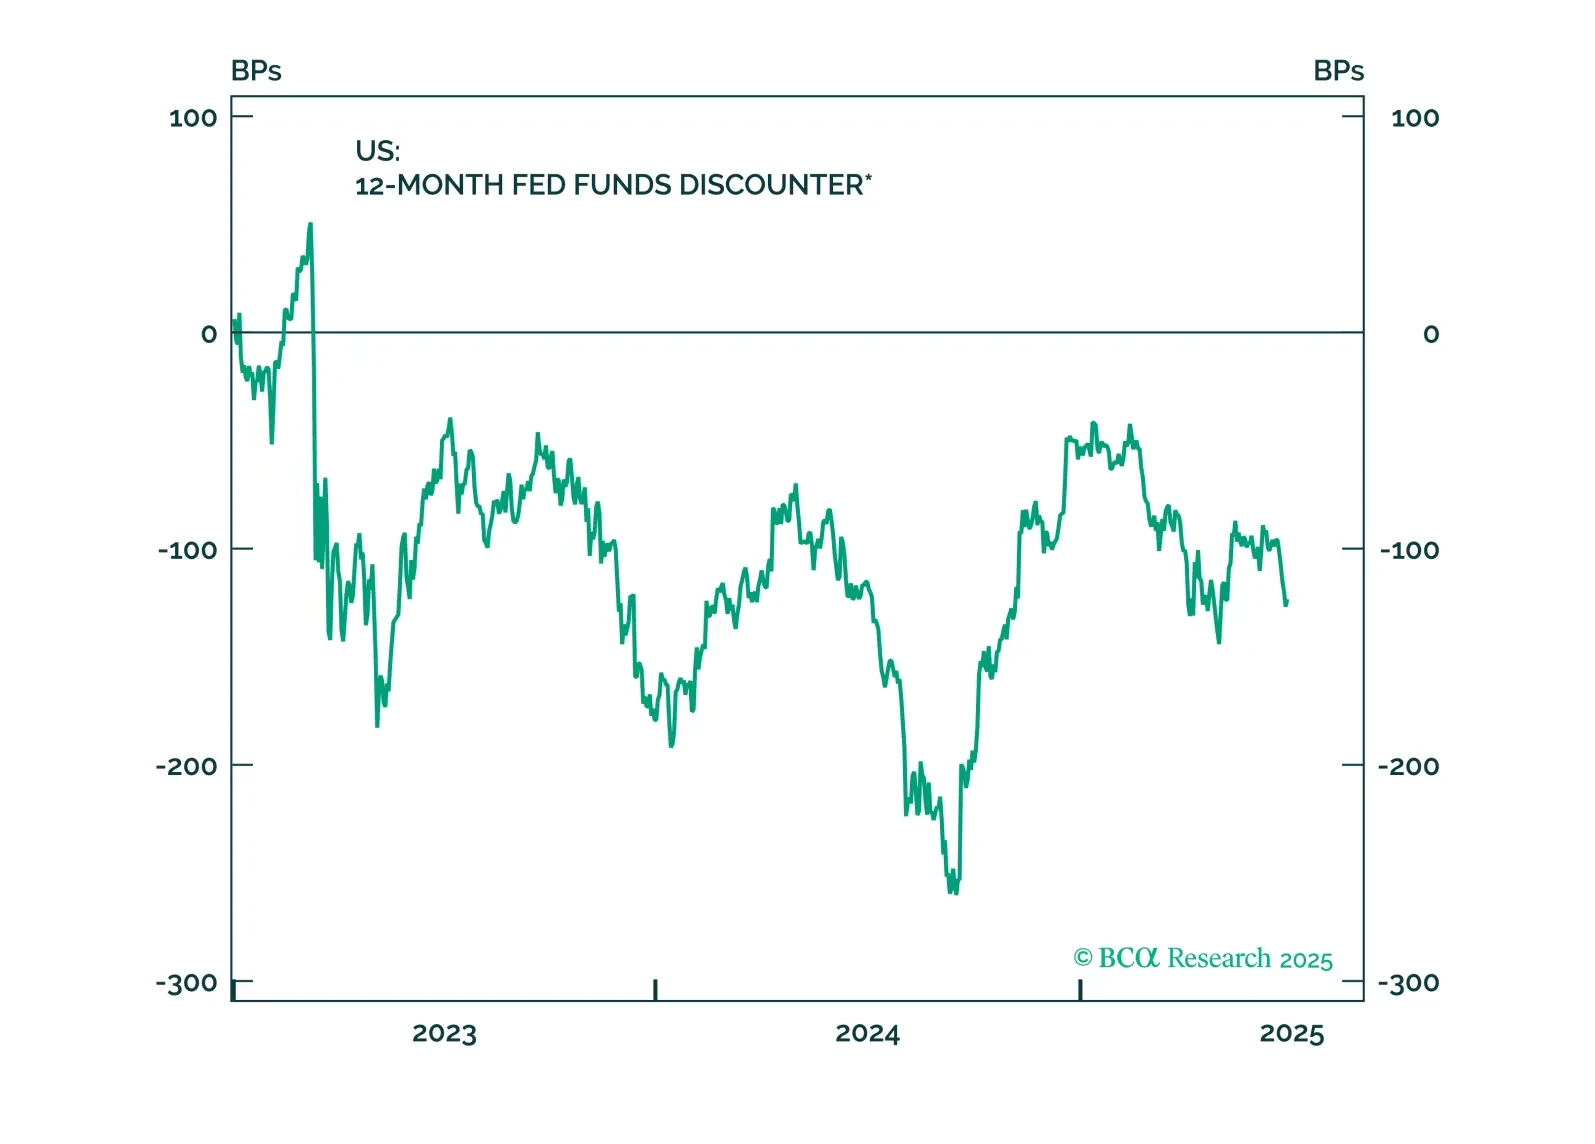
Monetary policy is about to become a powerful tailwind to the already bullish brew that includes Trump’s repeated step-downs from a global trade war, irrelevant geopolitical risks in the Middle East, and a fiscal policy that is no longer as alarming to the bond markets as the raft of campaign promises appears to be. Investors should hesitate to get overly bearish either bonds or stocks. However, we remain uber USD bears.