 FICC
Find out more
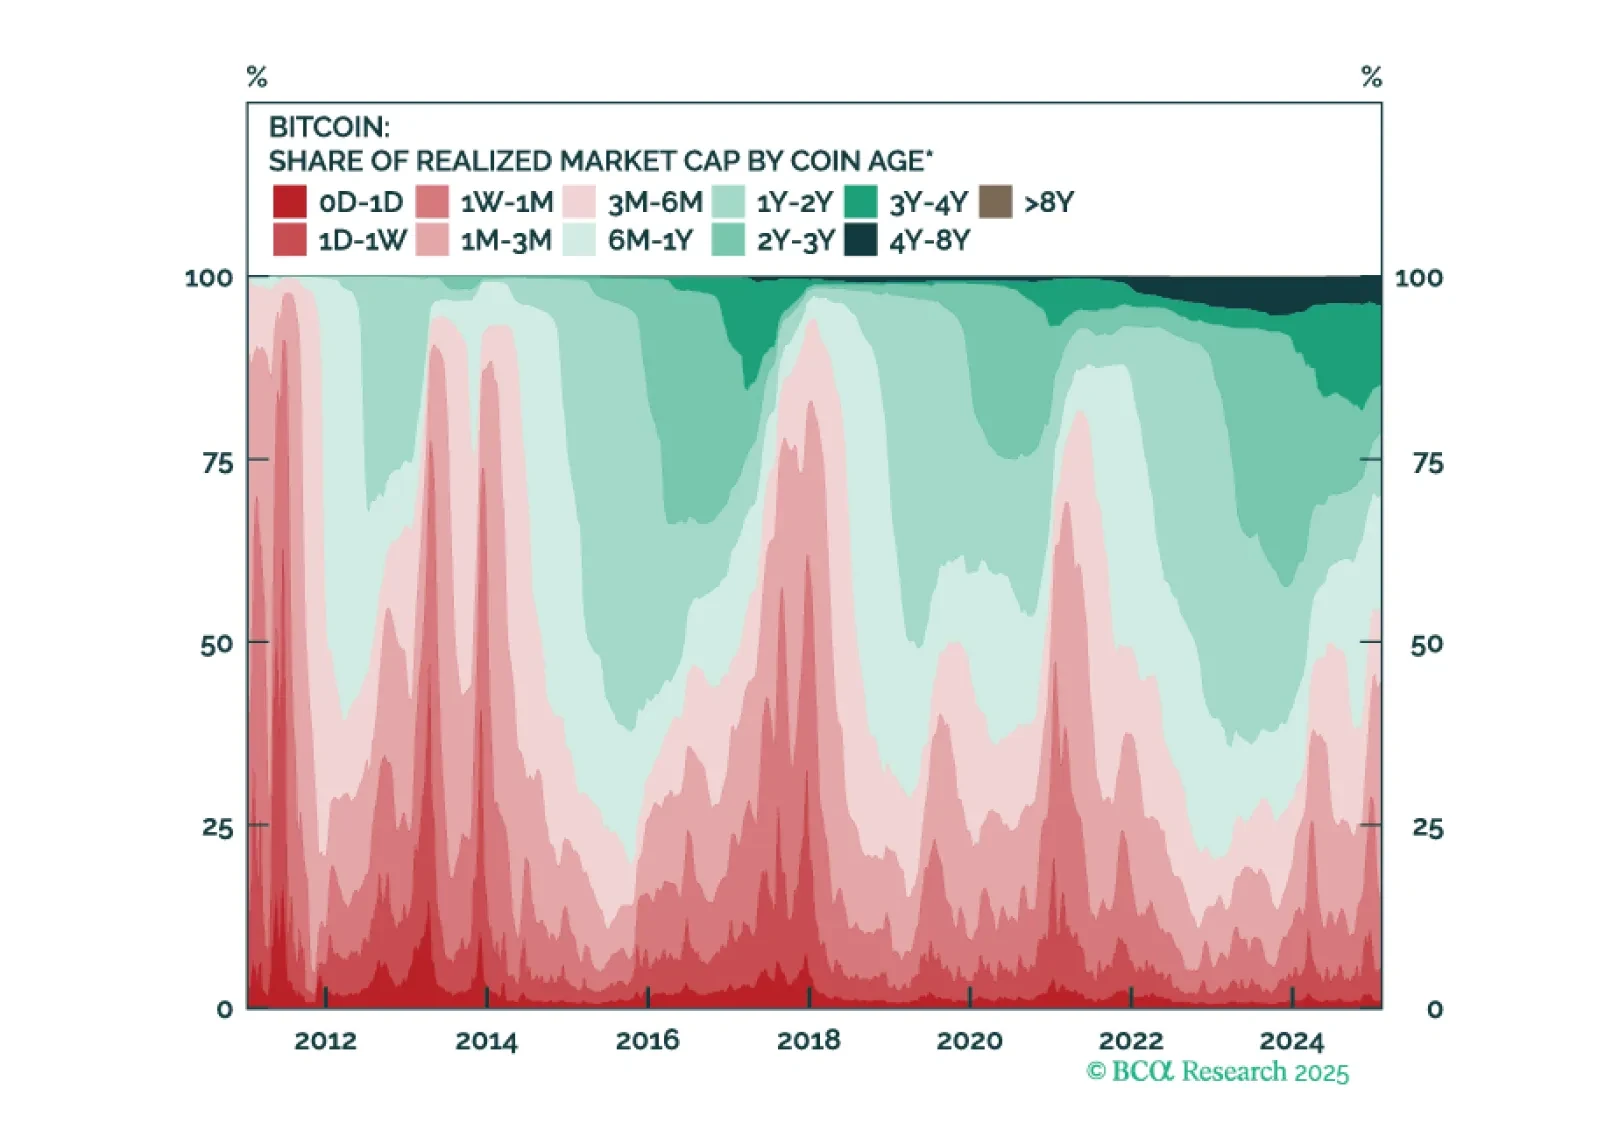
In this report, we reassess our bullish stance on crypto from early 2023, following Bitcoin’s recent all-time highs. While institutional adoption is broadening, there are also signs of excessive exuberance, speculation, and optimism. Given these conditions, a near-term correction appears likely. We are booking profits and will look to re-enter the market at $75,000.
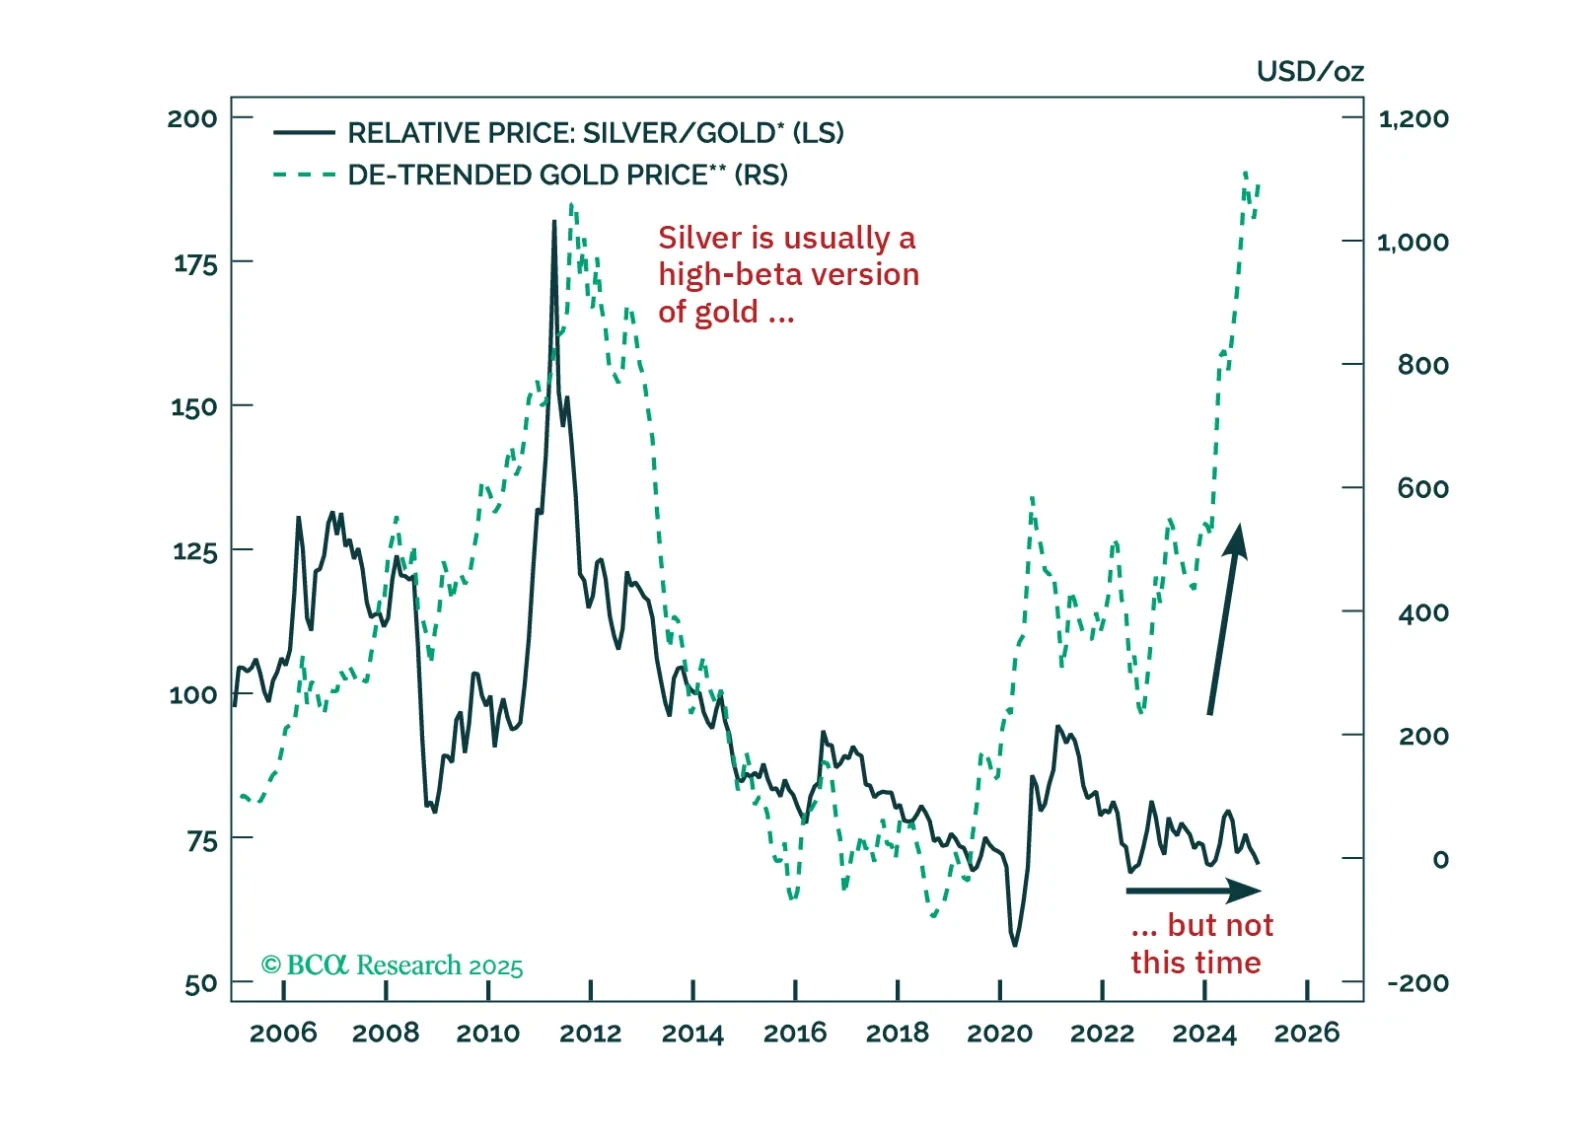
Last week’s tariff debacle kicks off a period of heightened global policy uncertainty under the new US administration. That is bad news for financial assets exposed to the business cycle. Meanwhile, it creates an opportunity for safe-haven assets to shine. Gold is capturing headlines for soaring to fresh record highs. Yet, what about the other precious metals? In this report, we argue that not all precious metals are created equal.
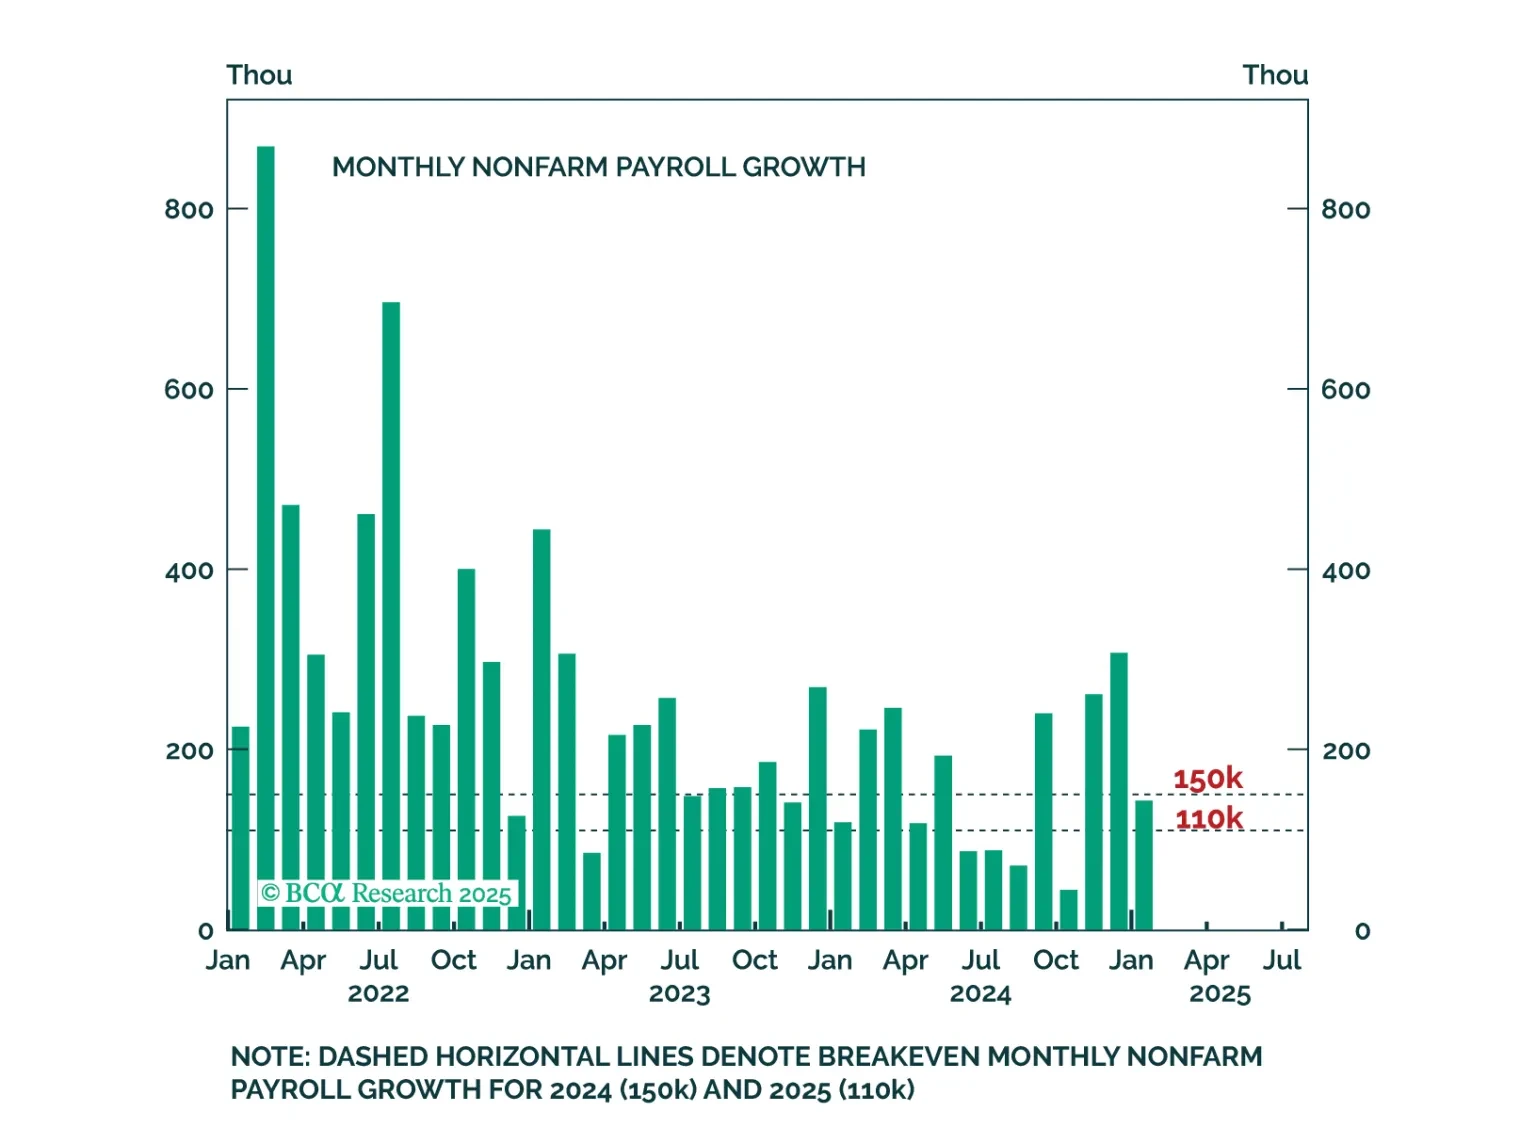
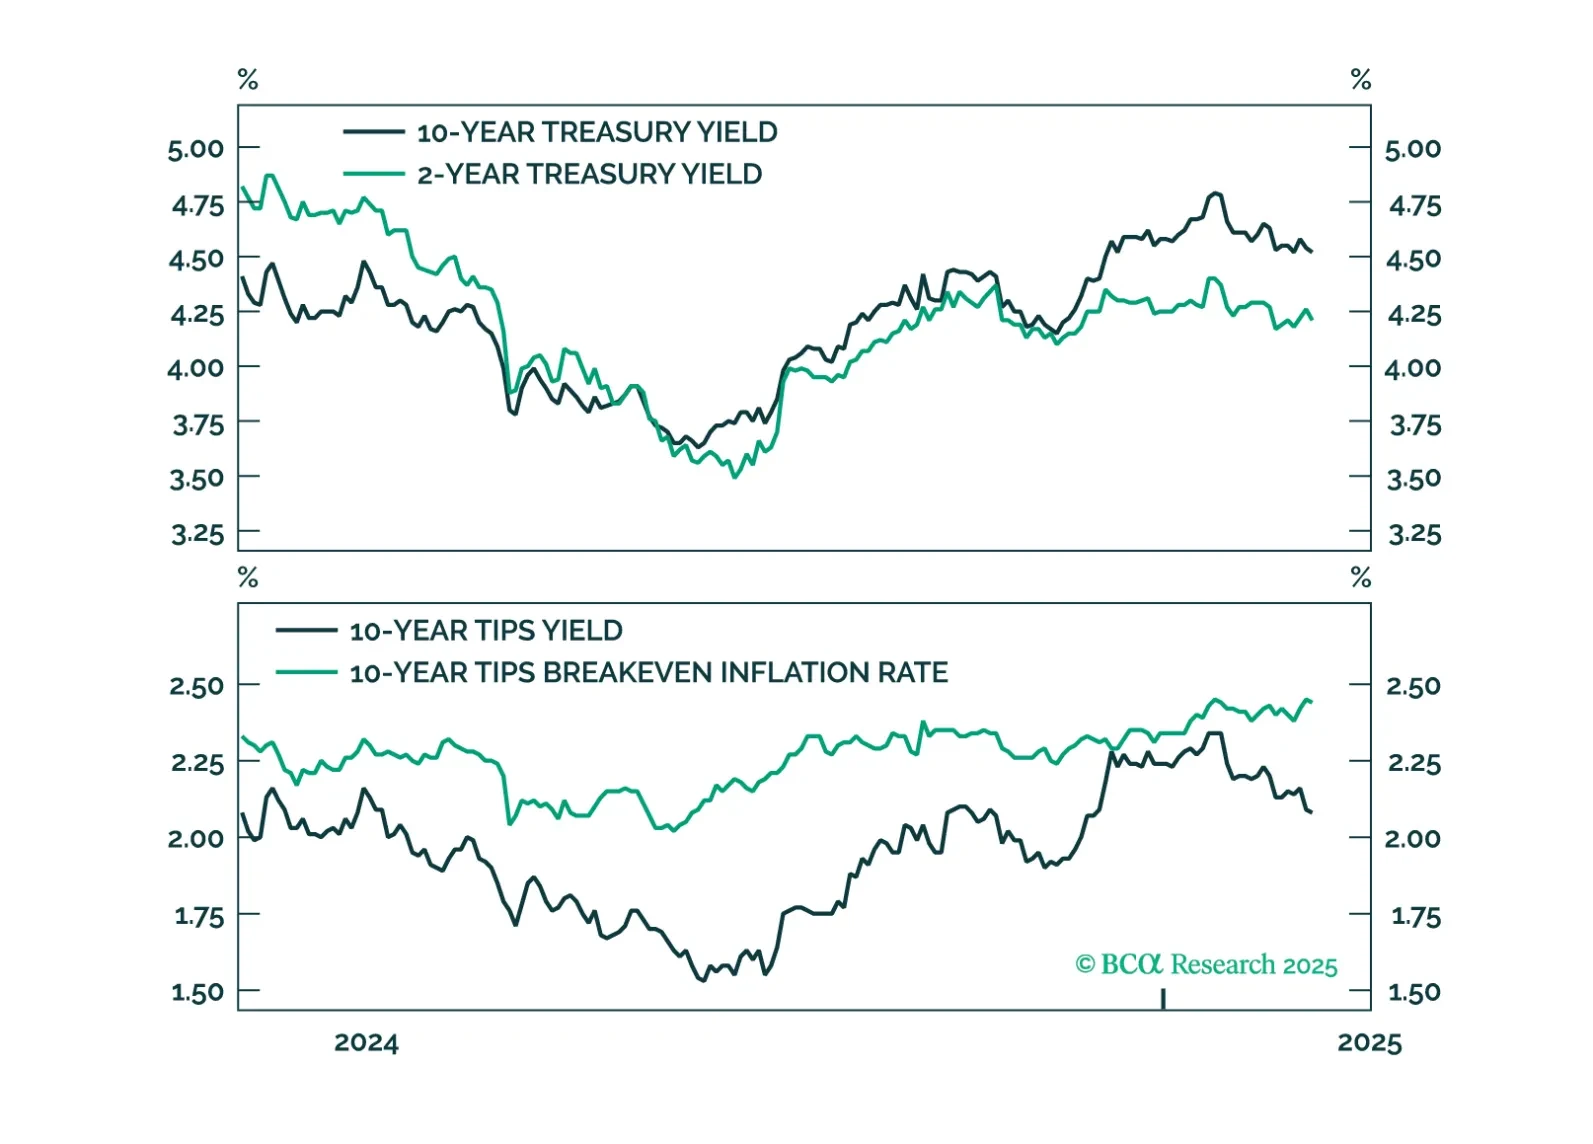
Some thoughts on this morning's employment data and Treasury Secretary Bessent's recent attempts to talk down the 10-year Treasury yield.
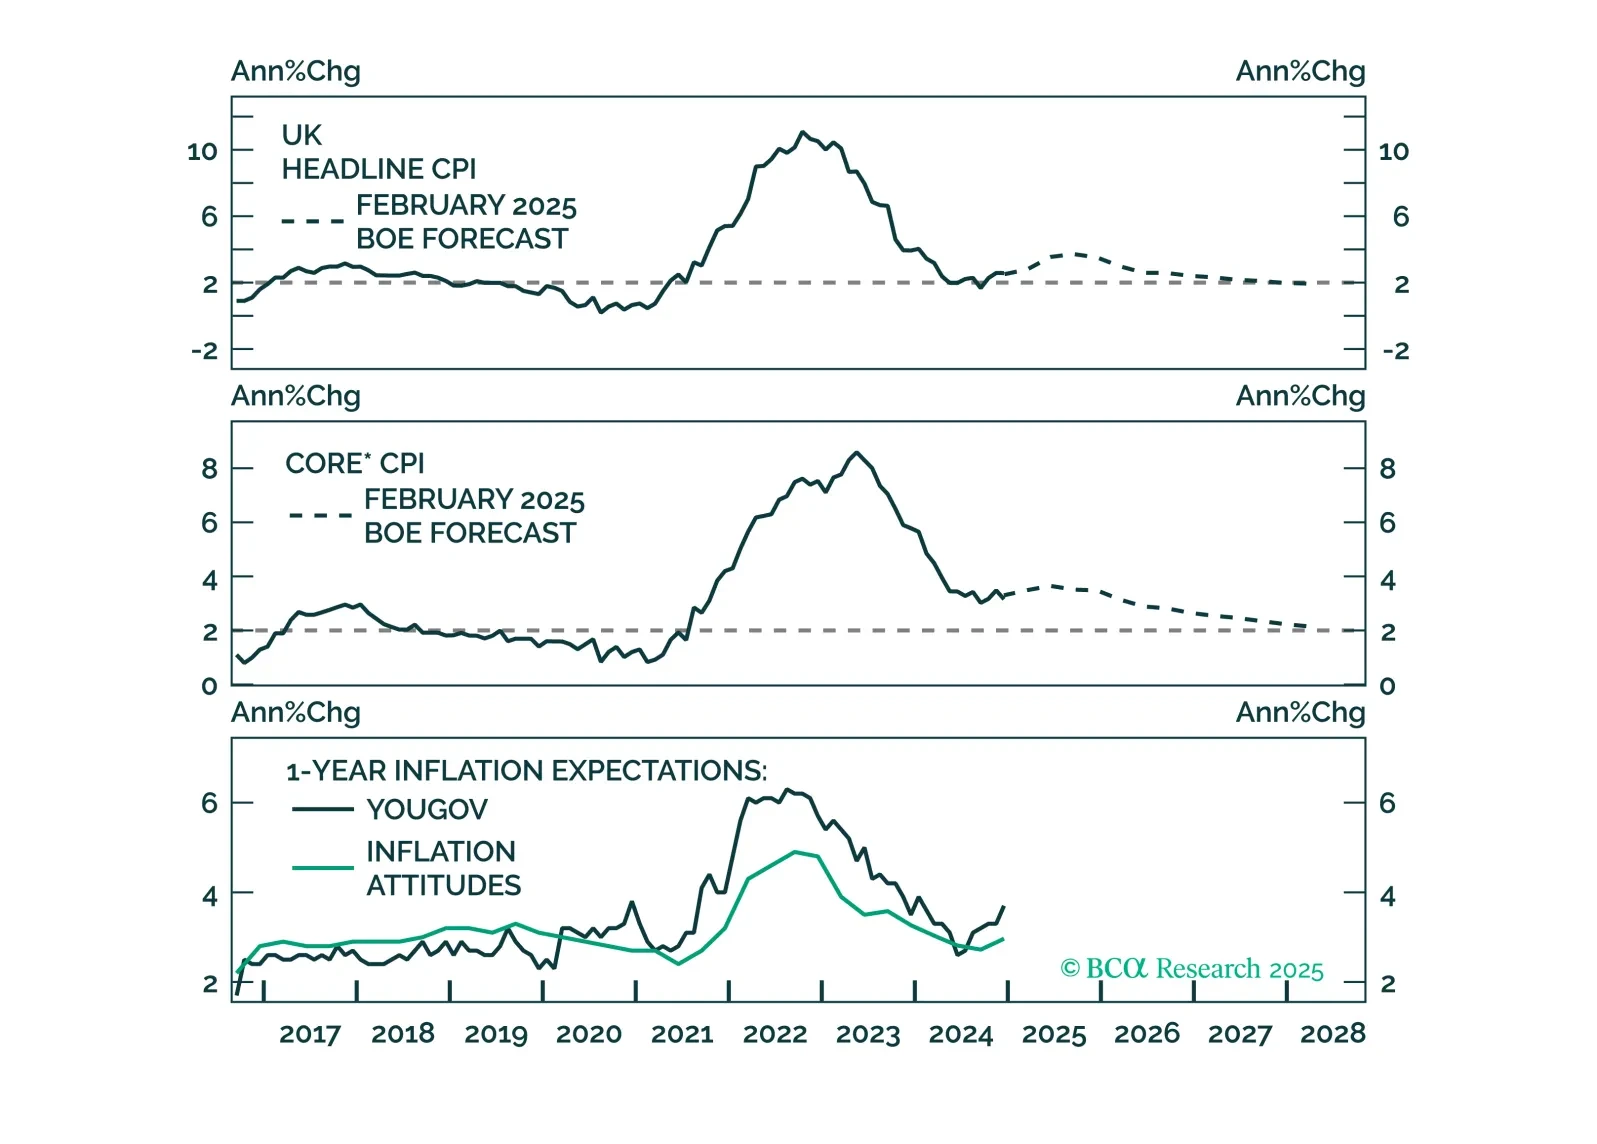
Following today’s Bank of England’s policy meeting, at which the policy rate was cut by 25 bps, we discuss our outlook for monetary policy in the UK. We expect the gradual easing to continue and discuss the investment implications for UK gilts and sterling.
Our Portfolio Allocation Summary for January 2025.
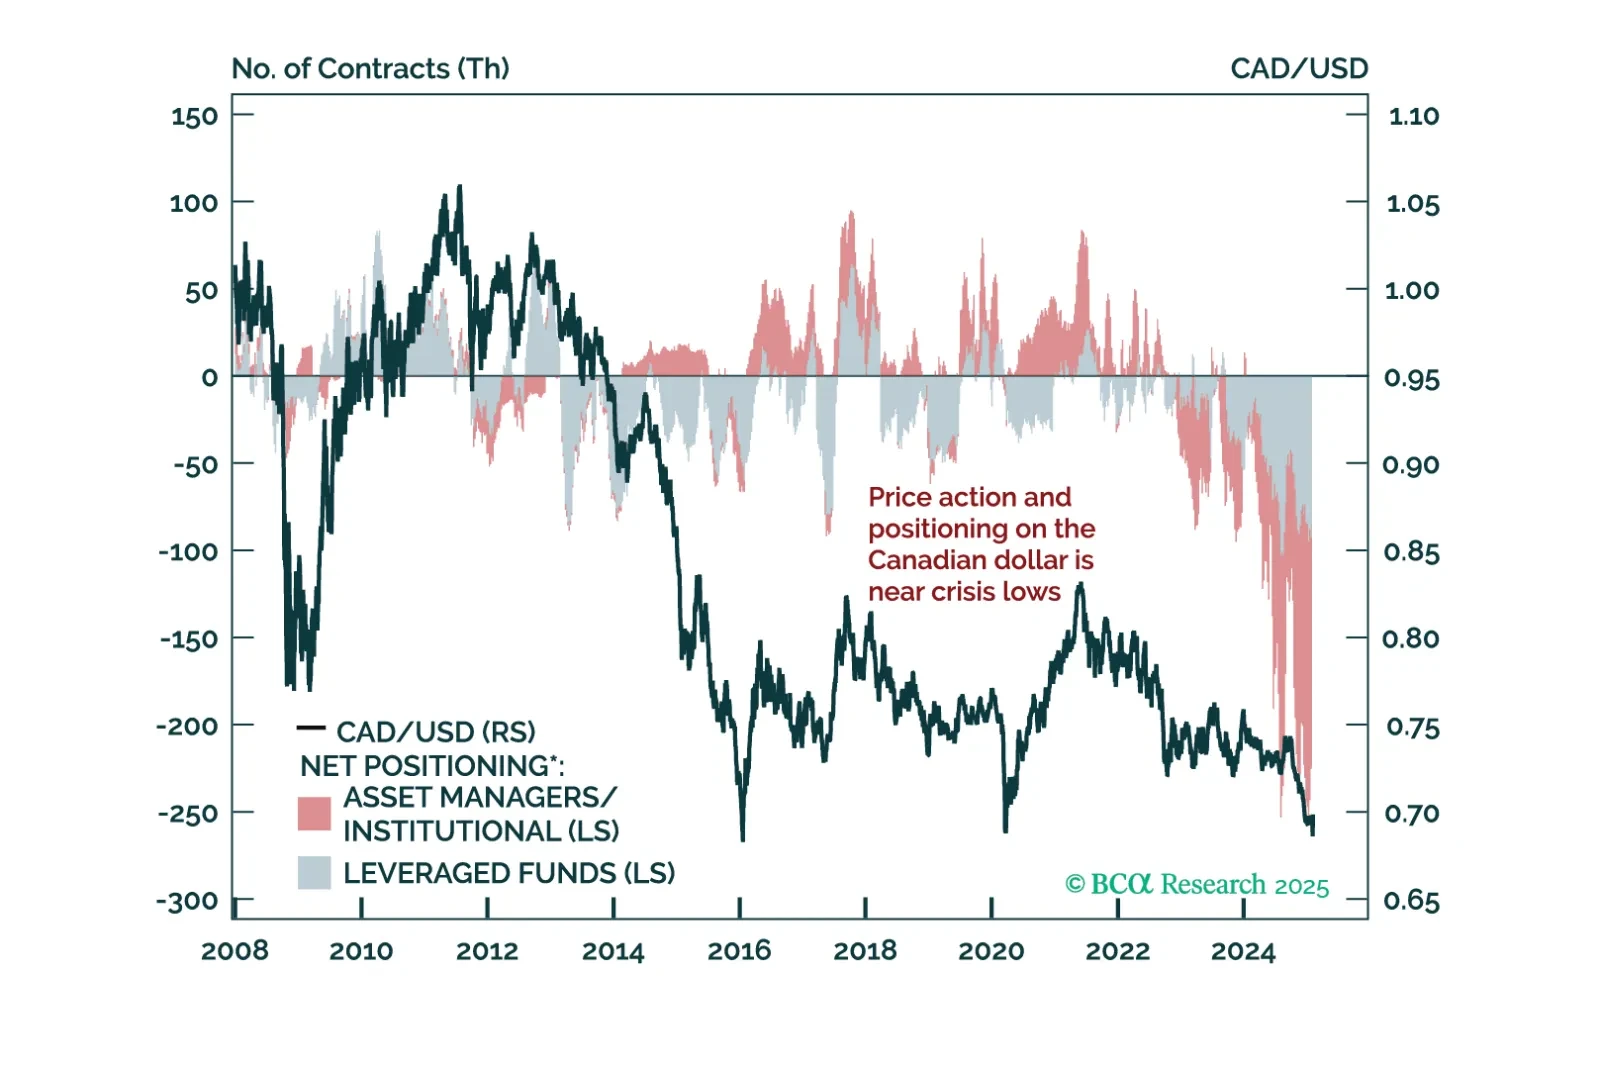
This Insight is a post mortem on Canadian assets, after the threat of tariff wars.
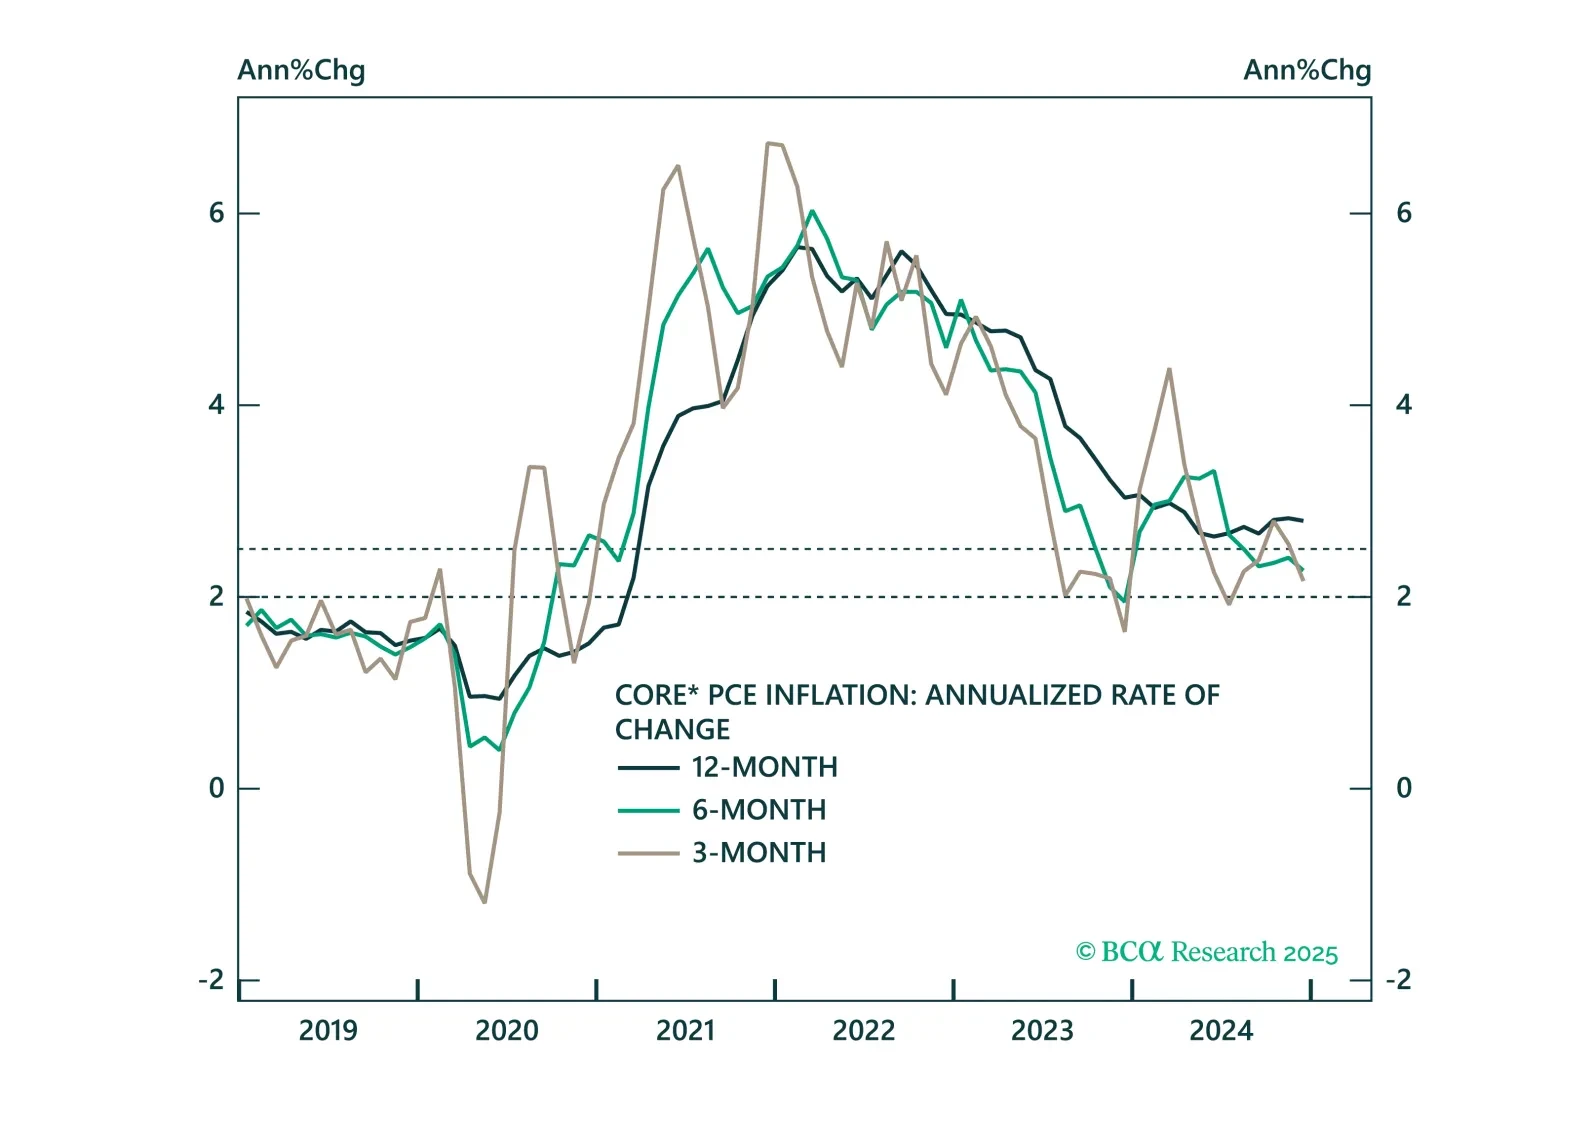
Core PCE inflation came in soft this morning and is tracking well below the Fed’s 2025 forecast. We highlight three upside risks to inflation and preview next week’s employment report.
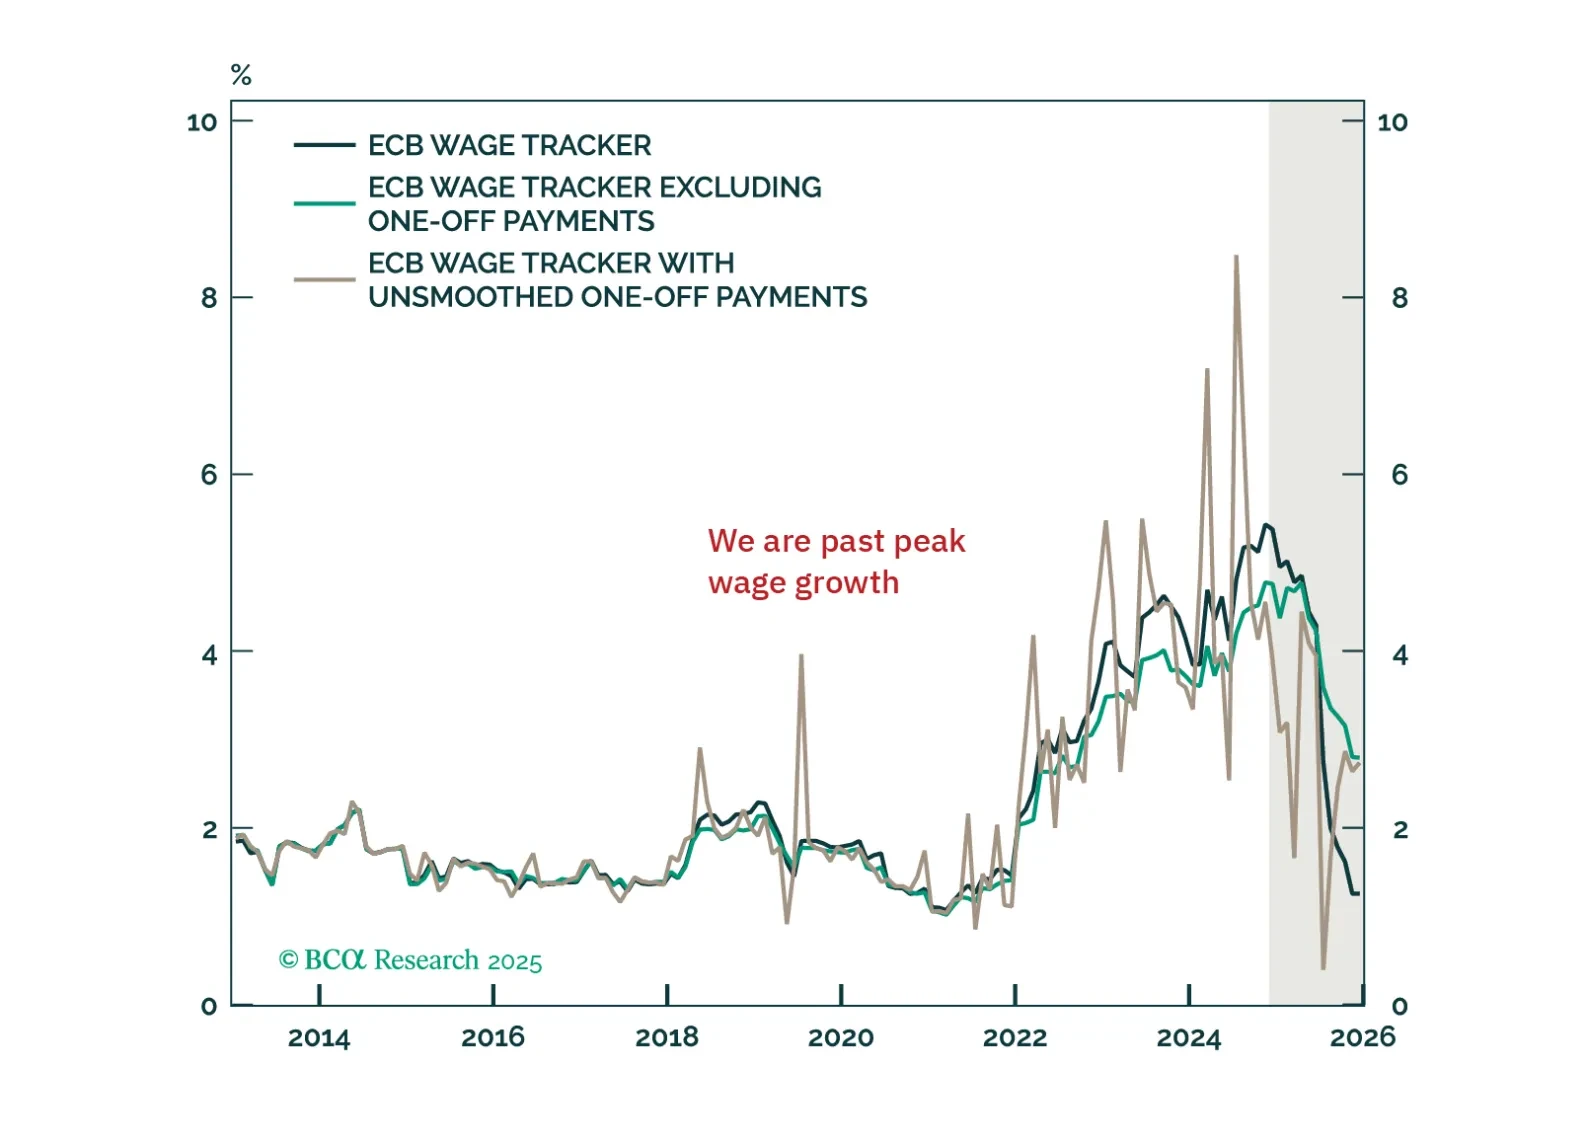
The ECB cut its deposit rate to 2.75%, as was widely anticipated. President Christine Lagarde did not provide any fireworks, but the Governing Council’s message was clear: Policy is restrictive, and inflation will fall further. As a result, if we combine our economic forecasts for the Eurozone with Frankfurt’s data dependency, we continue to expect the ECB’s deposit rate to settle below 2%. Consequently, German bond yields have downside, and the euro has yet to bottomed.
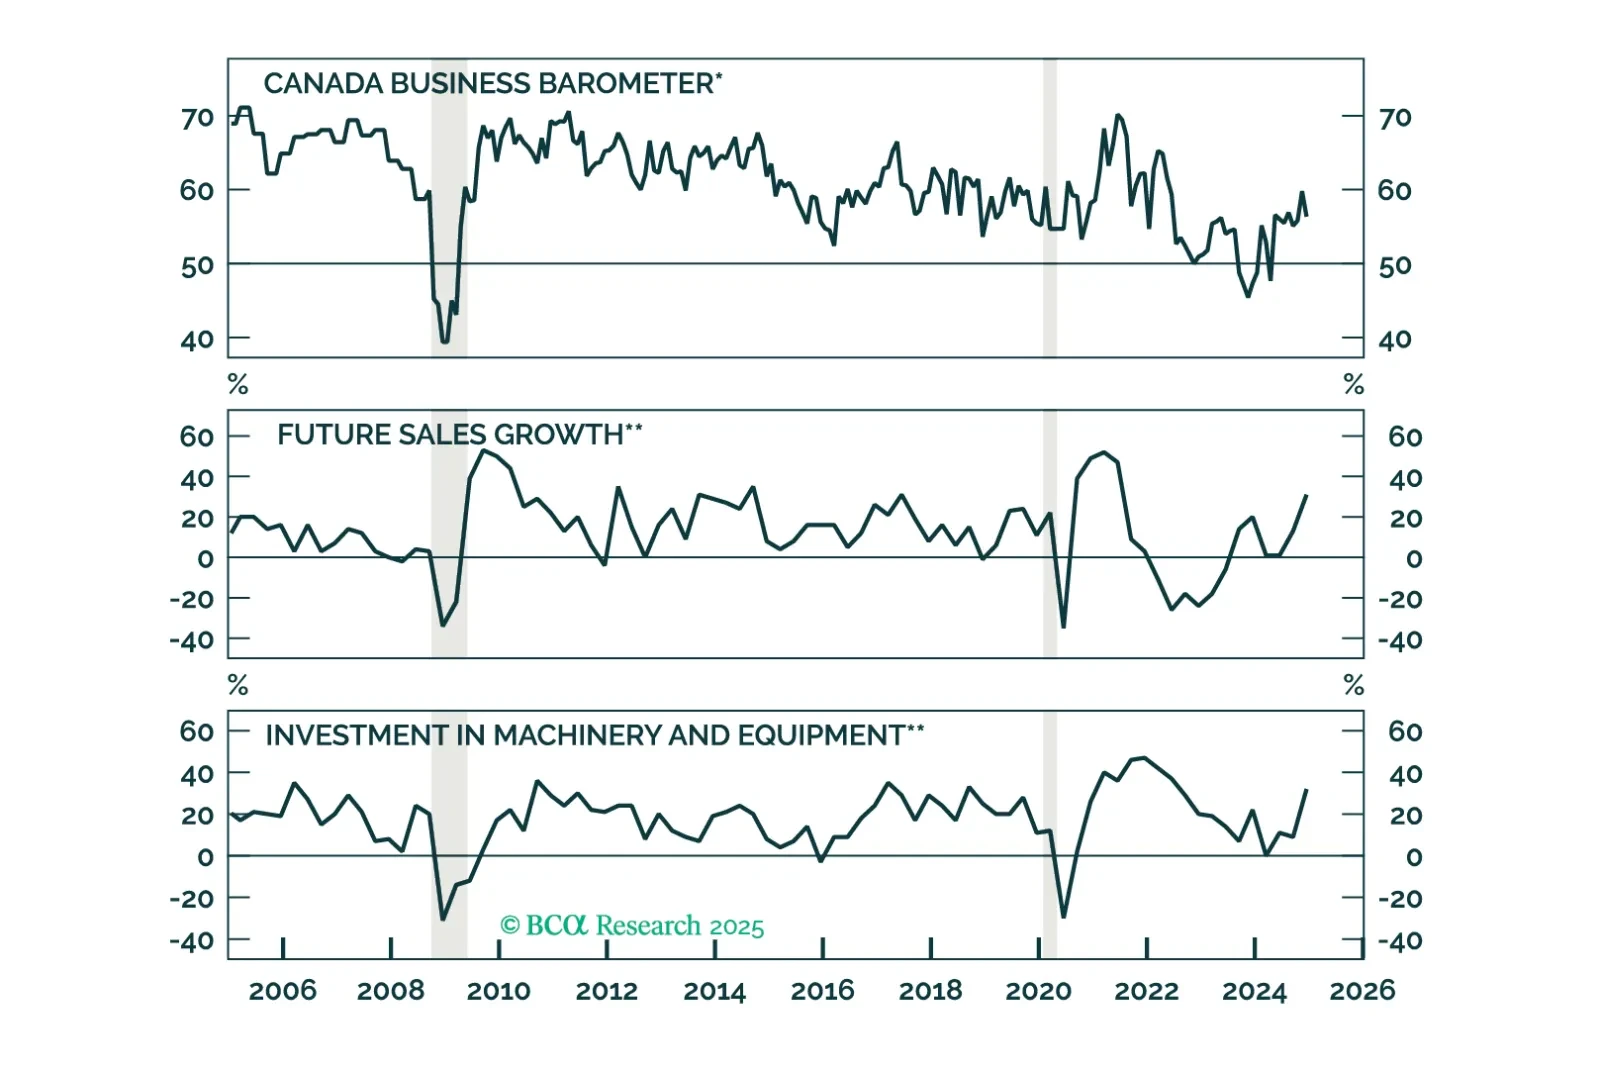
This Insight looks at what investors should do with CAD and fixed-income assets, given the rate cut by the Bank of Canada today.