 Explore FICC
FICC | Currencies
Tactical and strategic guidance on all major DM and EM currencies. Typically published twice a month.
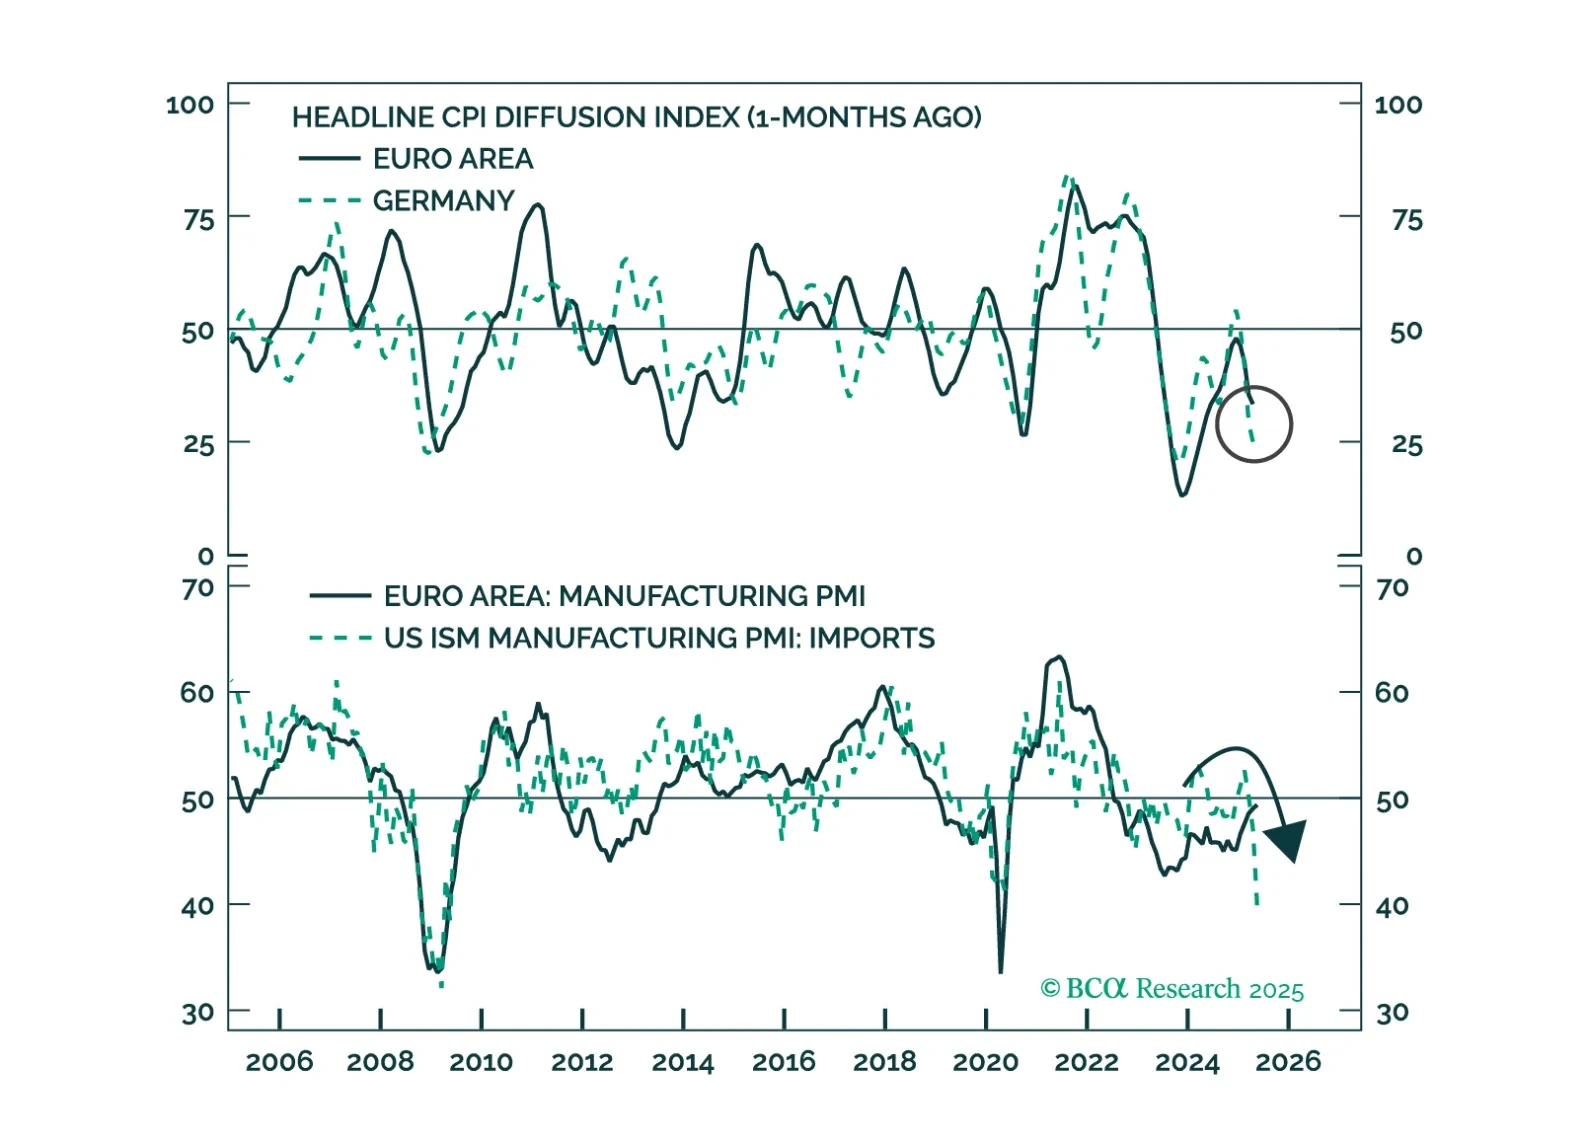
The ECB is changing its tone, but don’t call it a pivot. Slower cuts, sticky disinflation, and a soft growth patch shift the opportunity set. We break down the tactical bond trades and why EUR/USD dips are still for buying.

The Bank of Canada may be on hold for now, but deflationary risks are rising fast. Find out why rate cuts may come sooner than markets expect.
Global currency markets have entered a new era. This implies that the framework for analyzing exchange rates must also change. We introduce a new framework for analyzing EM currencies and classify them into resilient and vulnerable categories. Finally, we are adding more EM domestic bonds to our portfolio and making many changes to our currency trades.
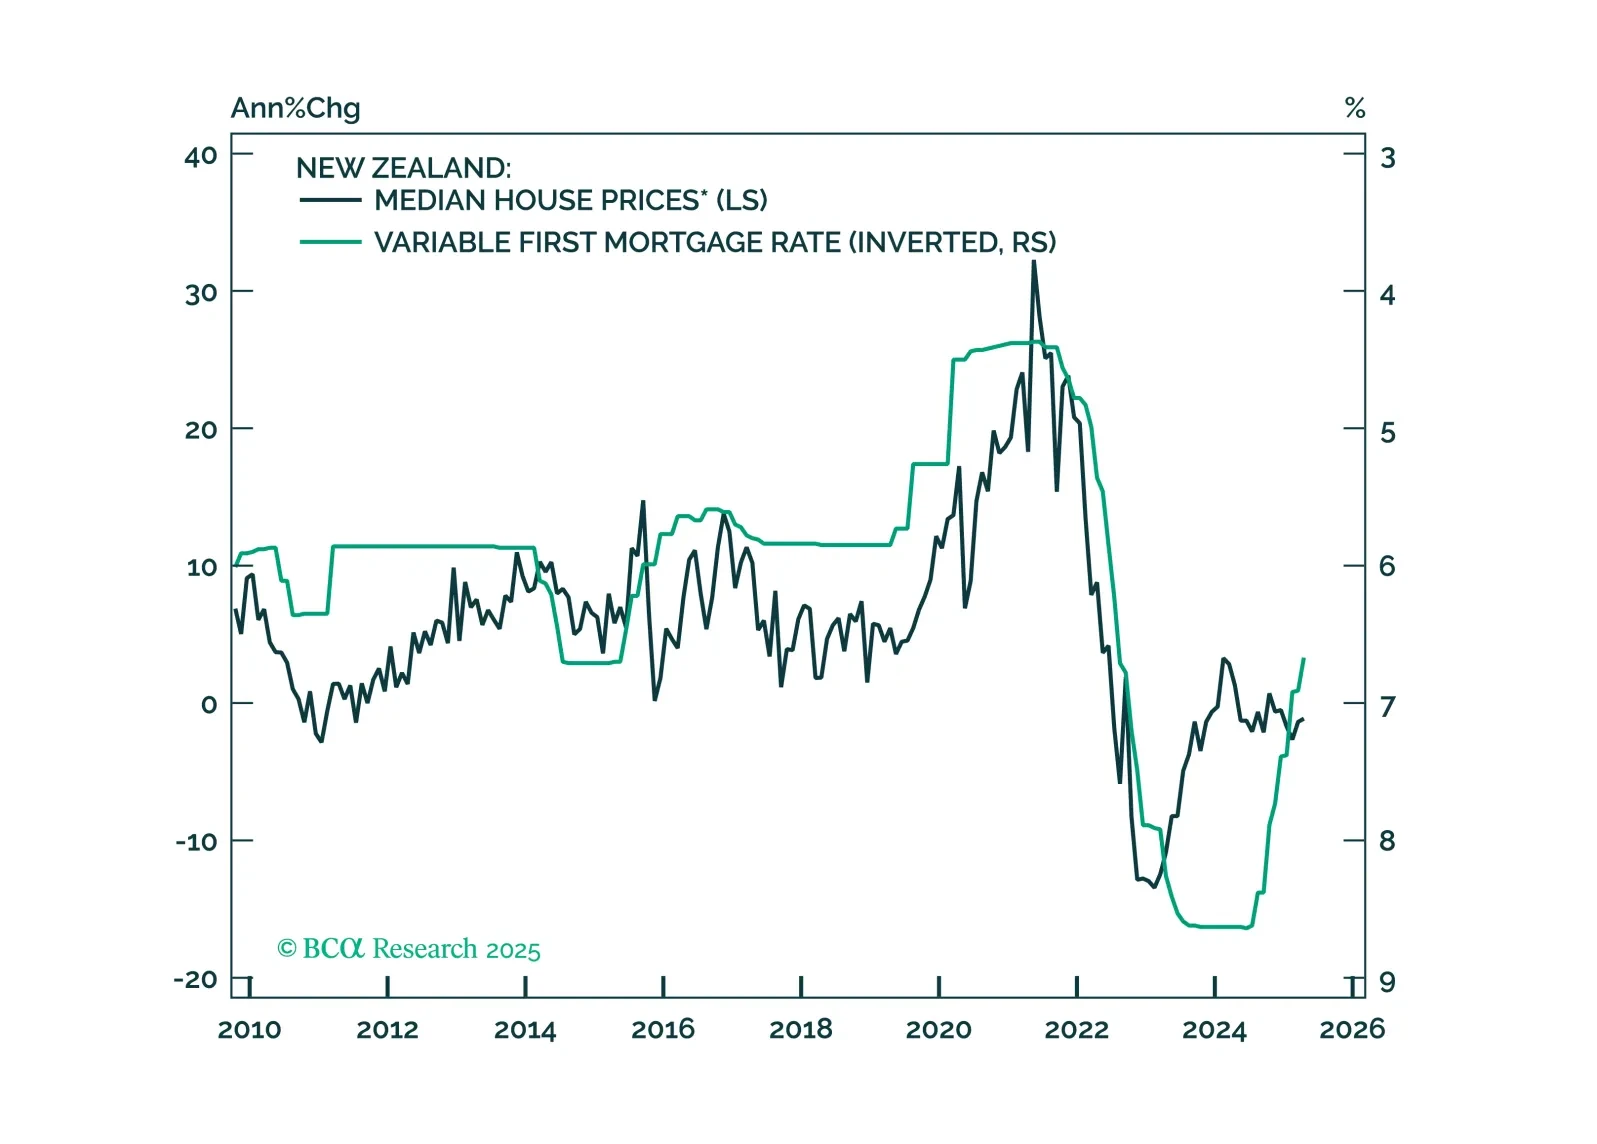
This Insight looks at the implications of the RBNZ’s rate cut on New Zealand assets.
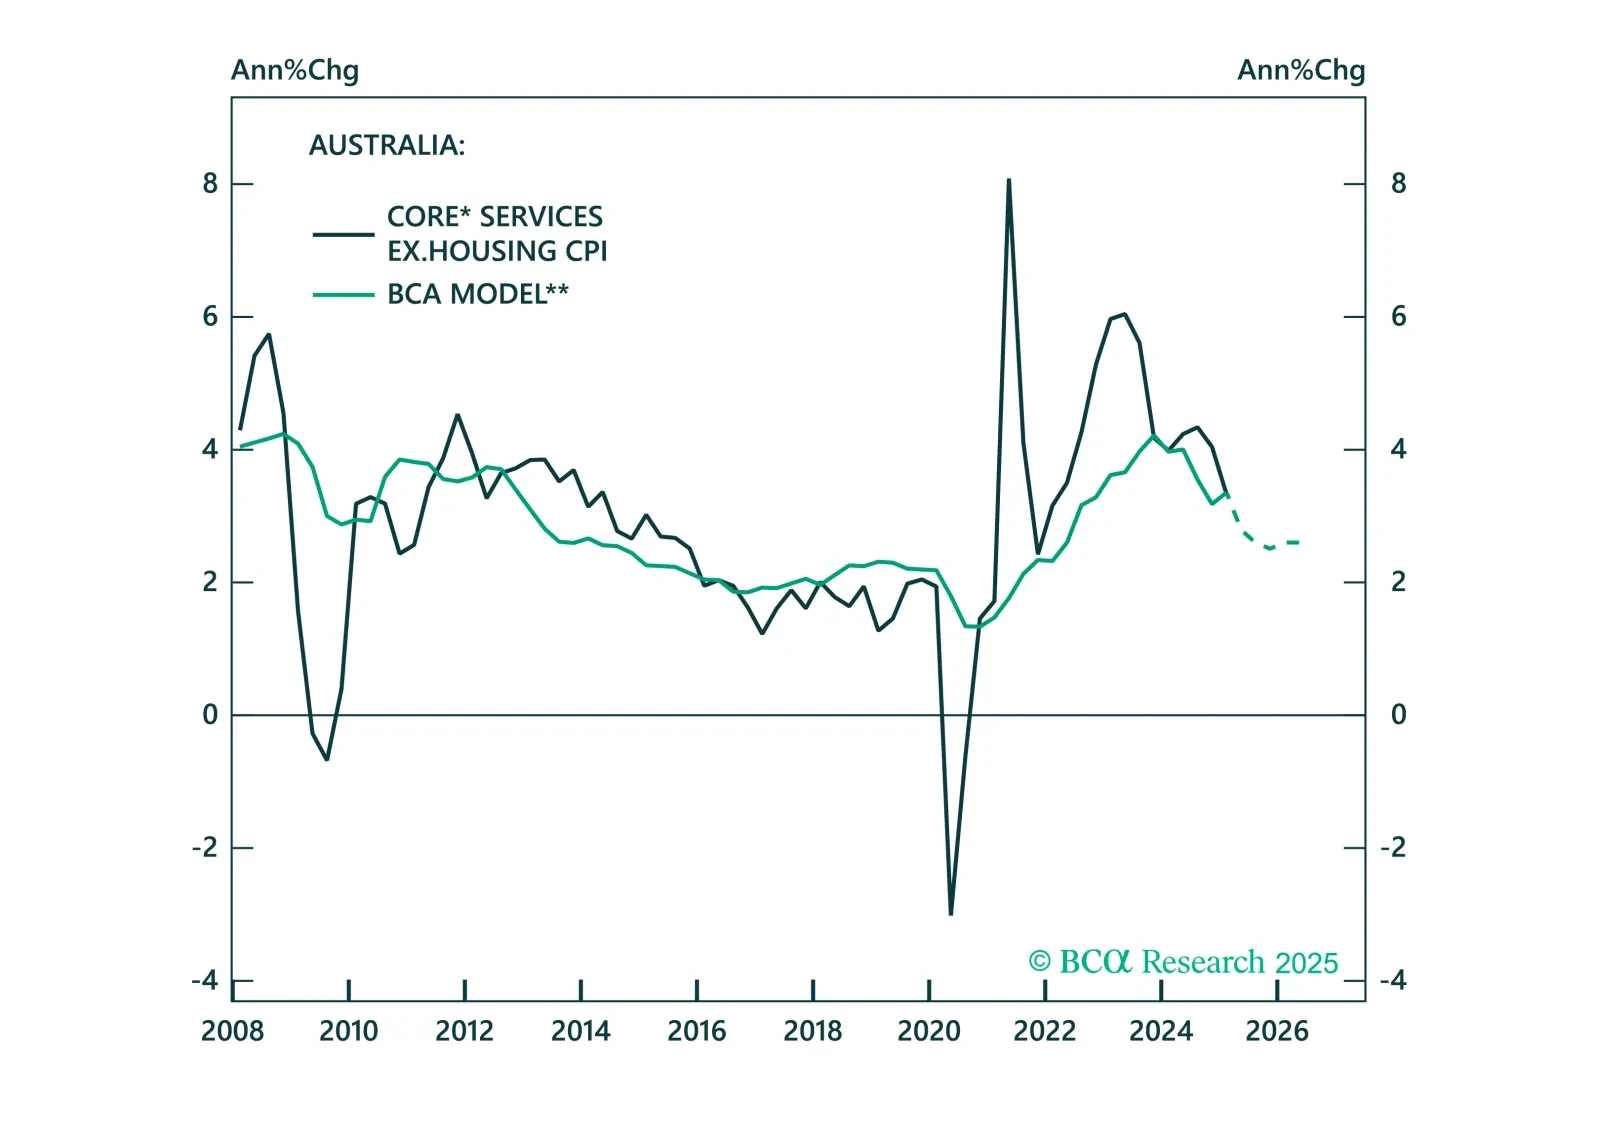
The RBA just turned dovish, but the macro data do not justify many more cuts. We unpack why Australia’s strong labor market and sticky inflation limit the scope for further easing.

The easing bias remains, but not all central banks are equal. This Central Bank Monitor update reveals who is ready to cut more and who is still pretending not to.
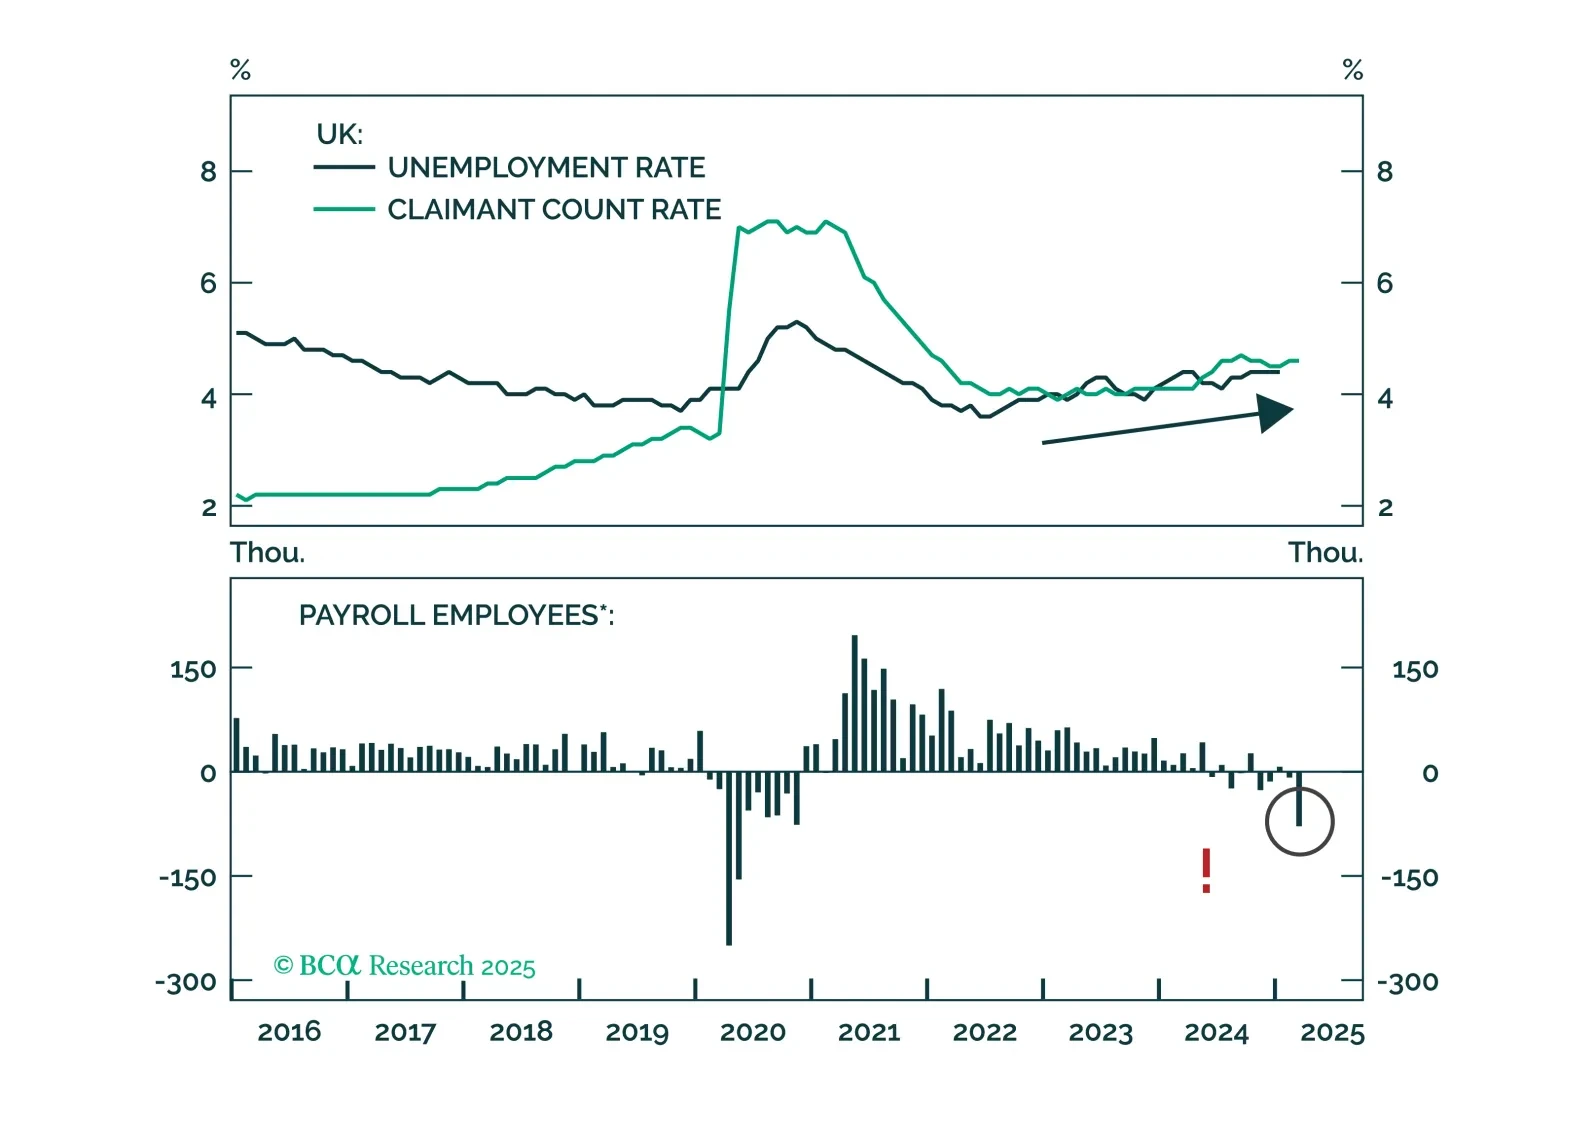
Rate cuts, recession risks, and relative value. This report unpacks how the BoE, Riksbank, and Norges Bank are reacting to global trade turmoil and where the opportunities lie.
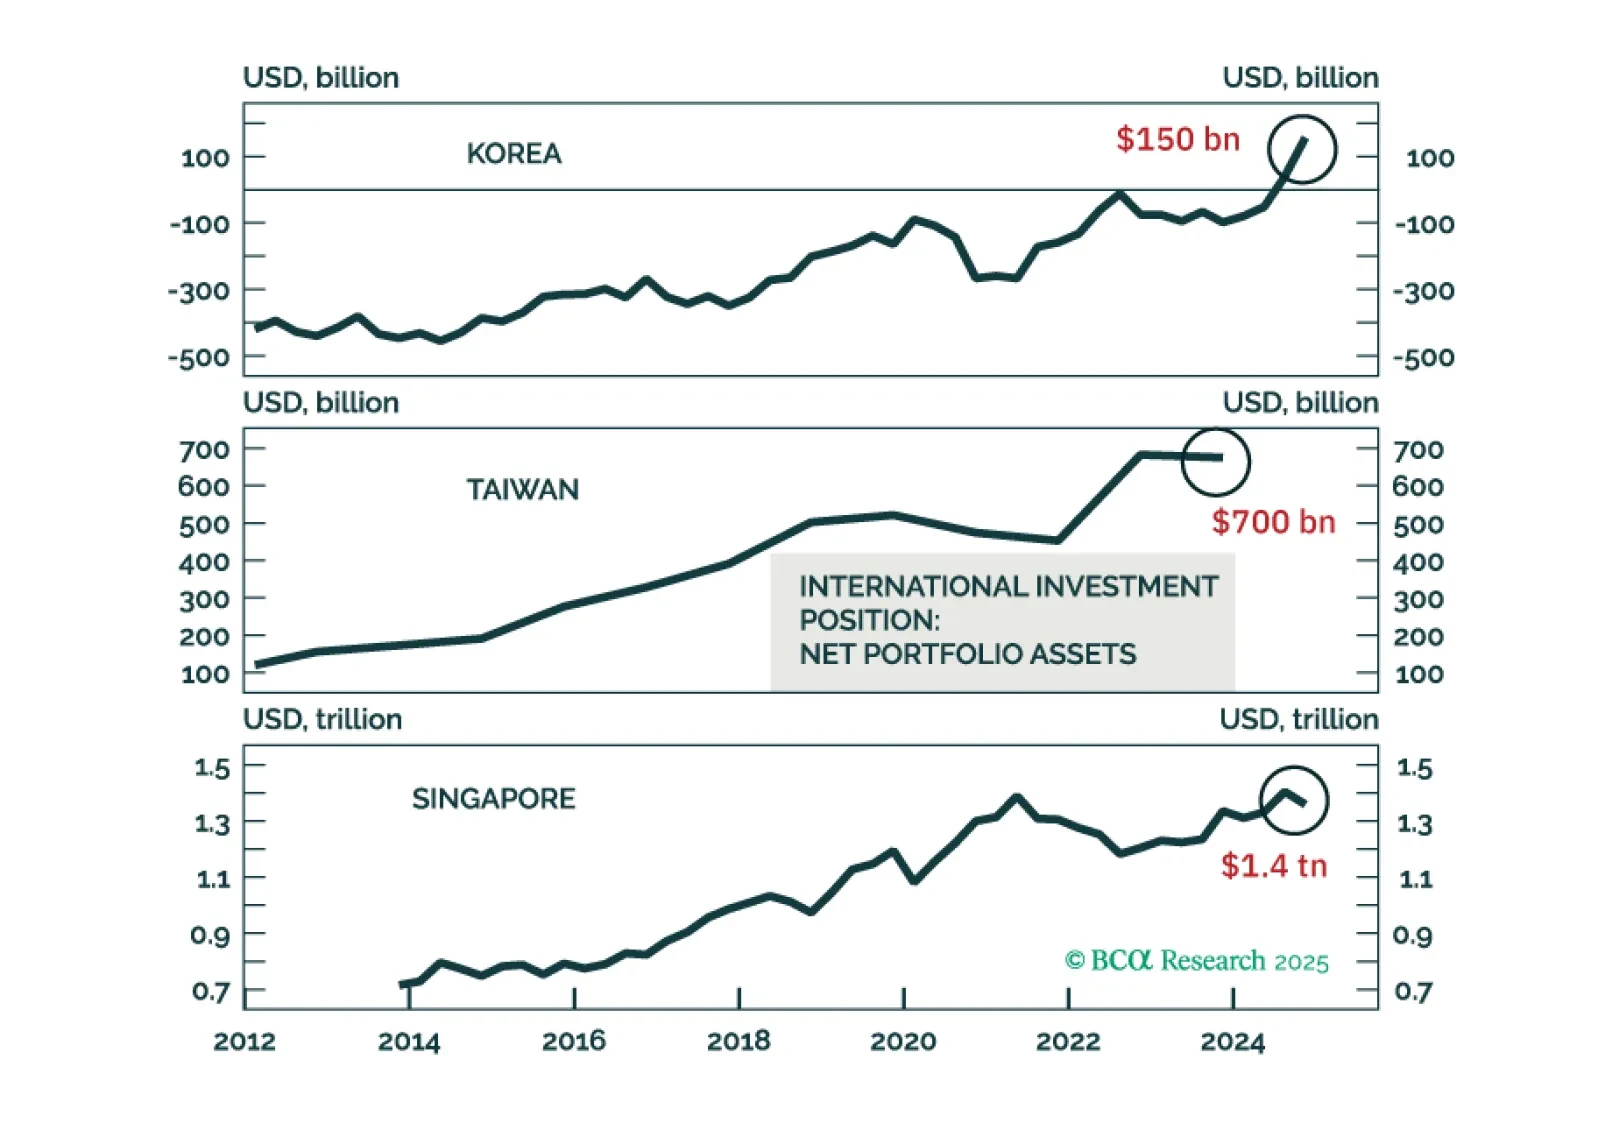
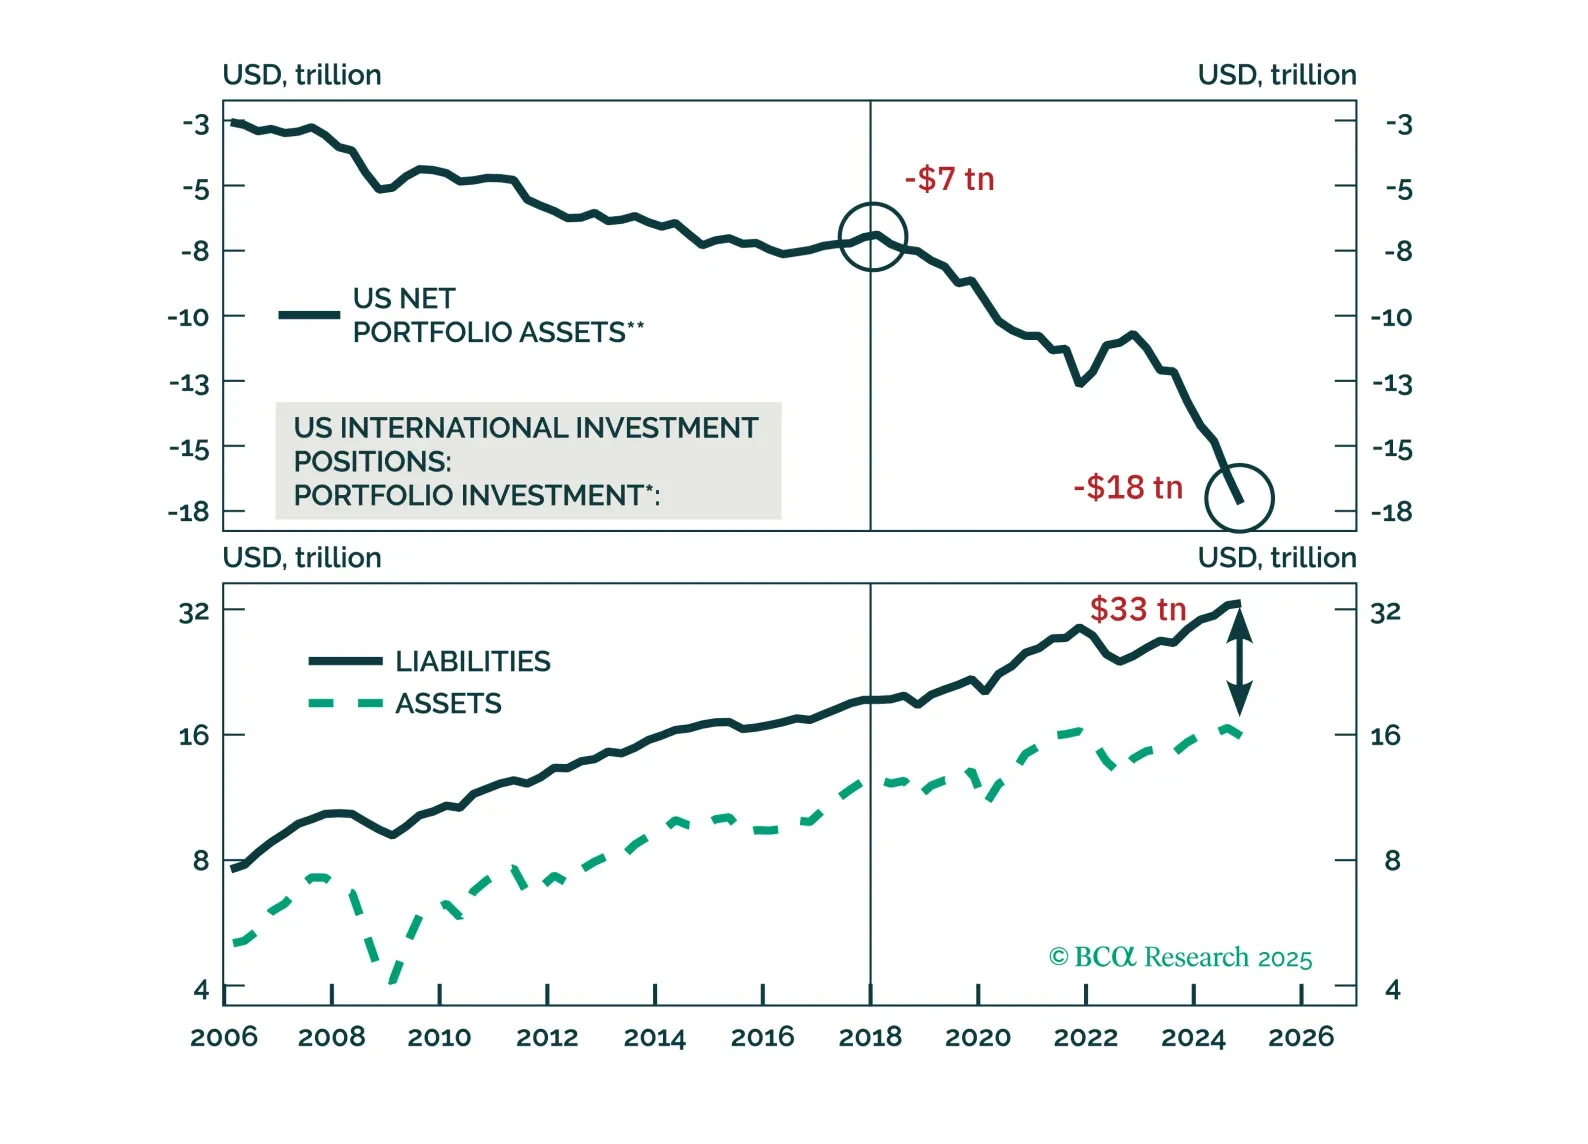
Taiwan, Singapore, and Korea's currencies might appreciate versus the USD, driven by capital repatriation from domestic private investors away from the US. This thesis is less pertinent to India, Indonesia, and the Philippines because they have large net foreign portfolio liabilities. Malaysia and Thailand fall in the middle, while China is an exception. Investors should play intensifying deflationary pressures in Asia by betting on lower interest rates in the region.
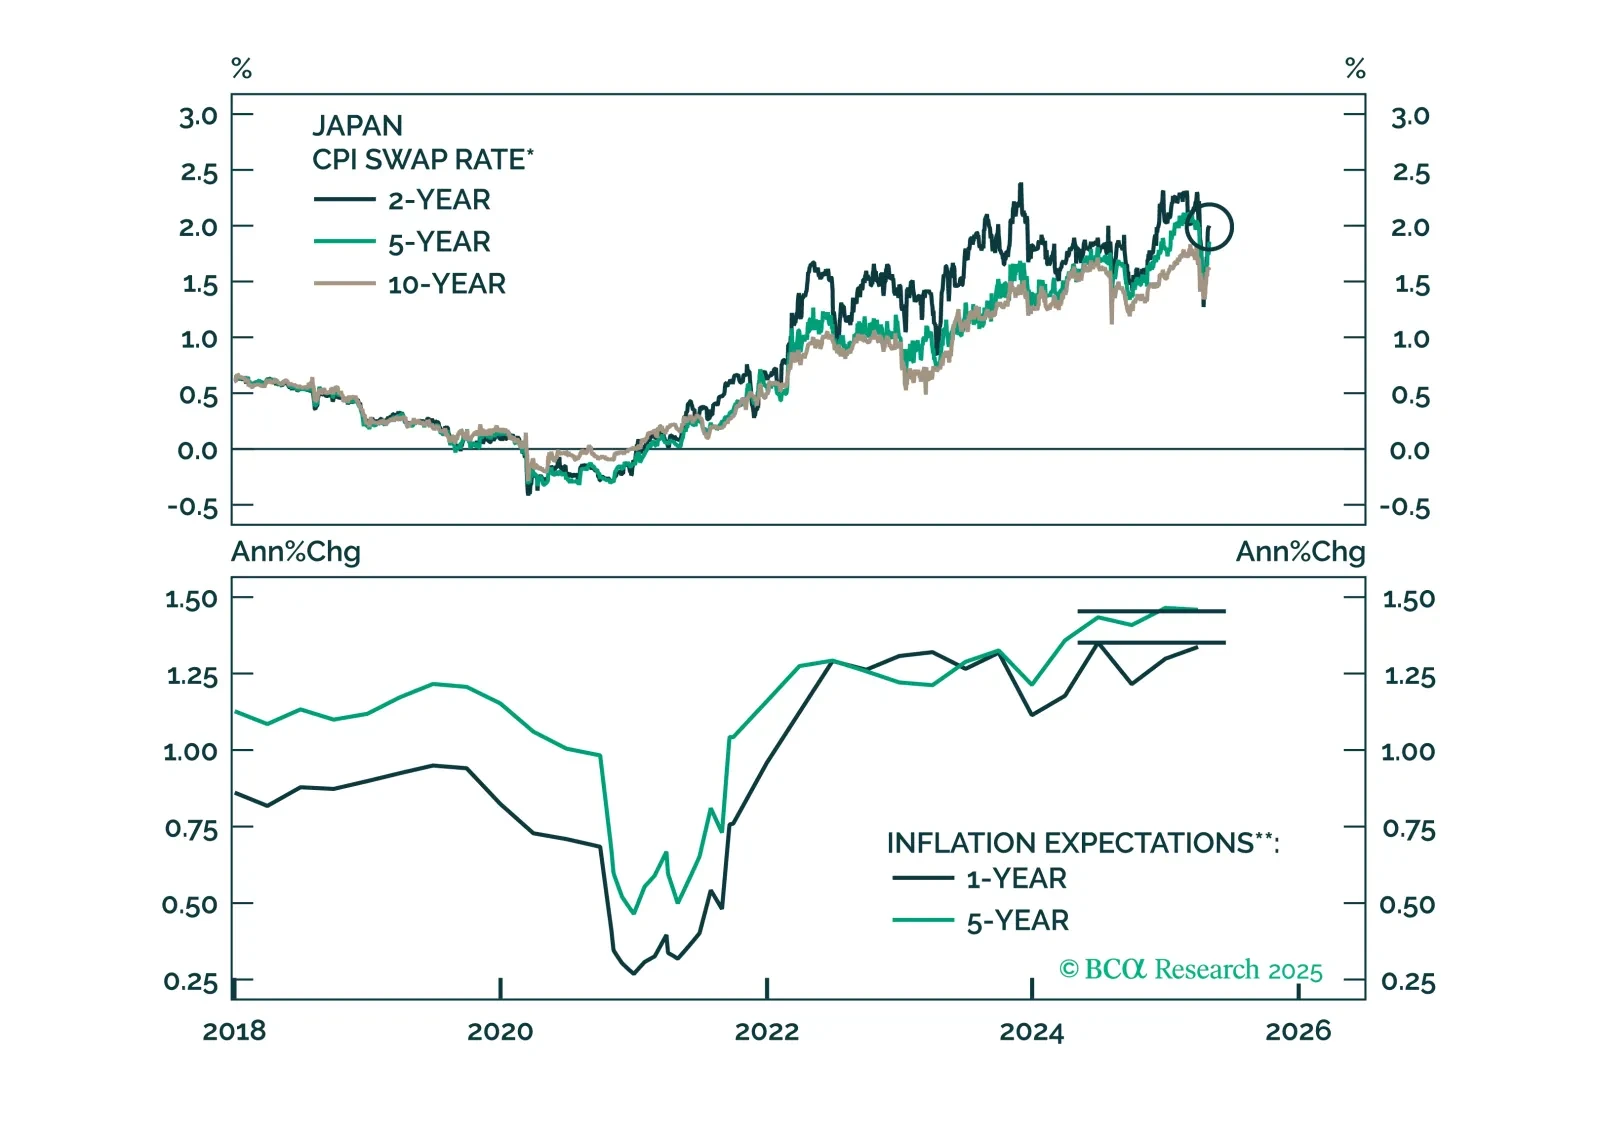
This week’s report looks at Japan, with the recent BoJ meeting. While a trade war has injected uncertainty into the Japanese economy, our conviction remains high that JGBs will underperform other government bond markets, and the yen will ultimately rally. That said, JPY is due for a tactical pullback.
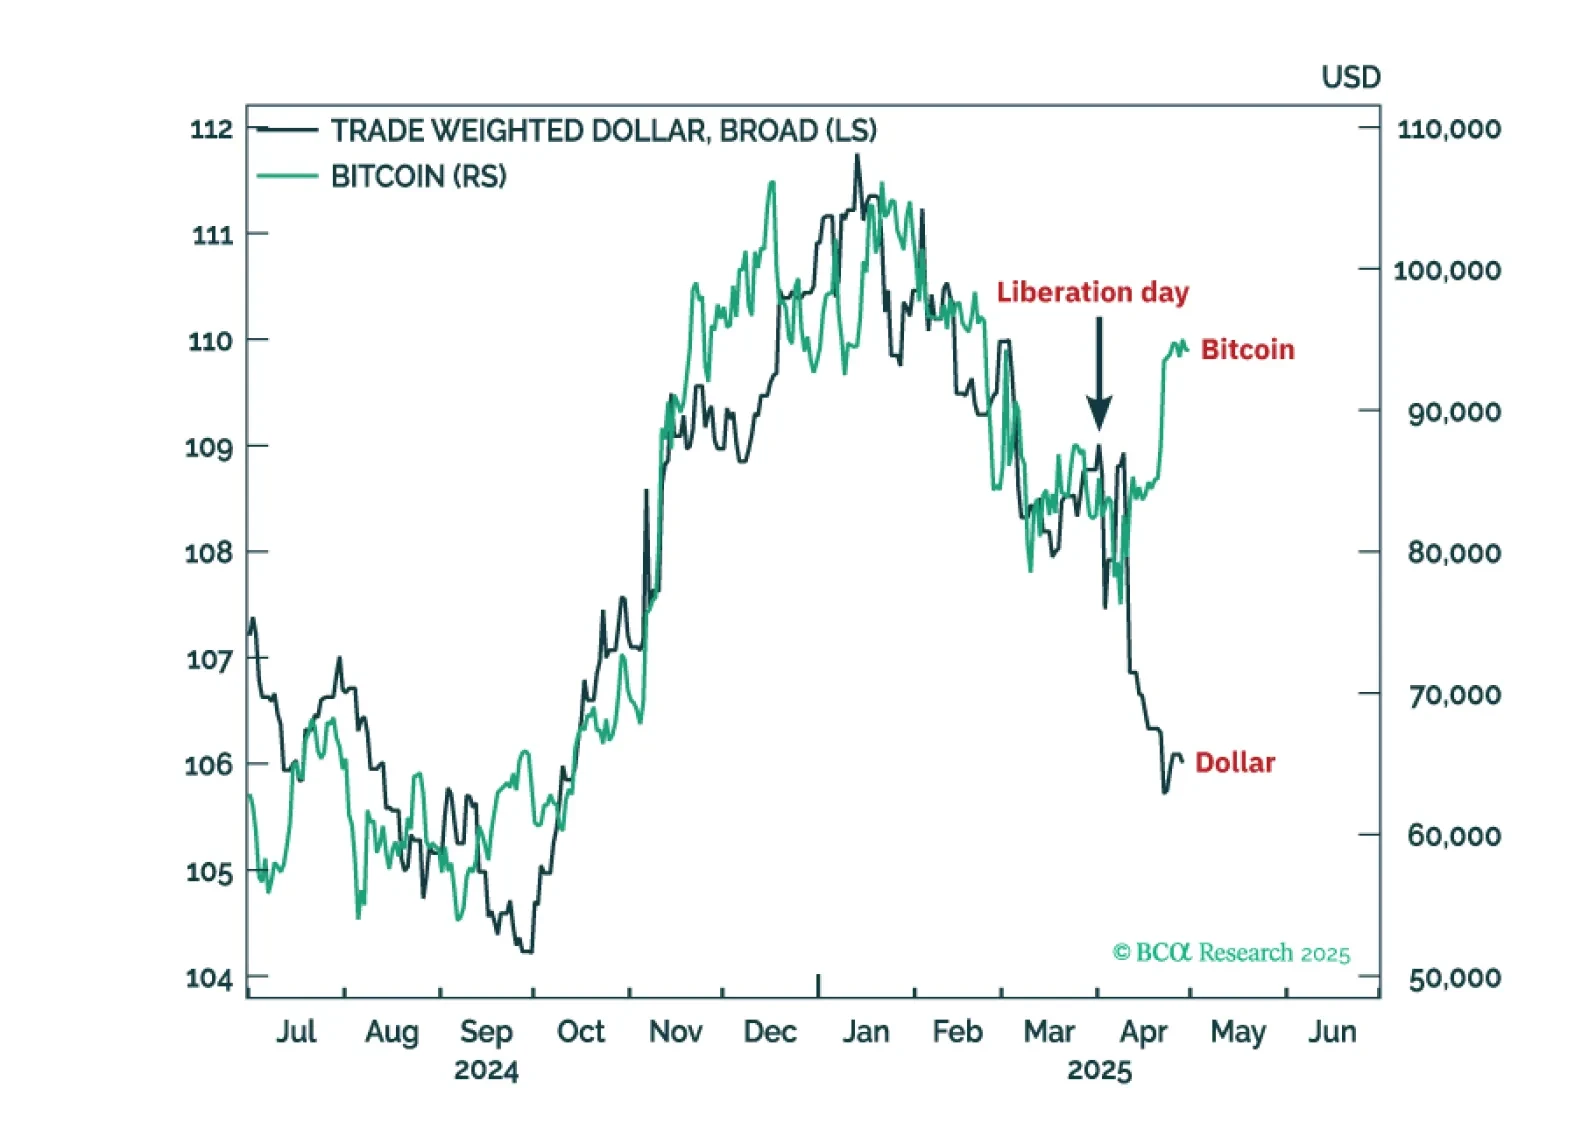
If Trump’s tariffs are ‘America's Brexit’, then UK gilts will recoup ten years of underperformance versus US T-bonds. Meanwhile, as the AI bubble fully deflates, Europe’s stock market valuation versus the US will rerate by about 25 percent. The big ‘currency’ winner of the structural exodus from the US dollar will be bitcoin. Plus: a trade for the next four weeks is to go tactically long USD/CHF.