 Explore FICC
FICC | Currencies
Tactical and strategic guidance on all major DM and EM currencies. Typically published twice a month.
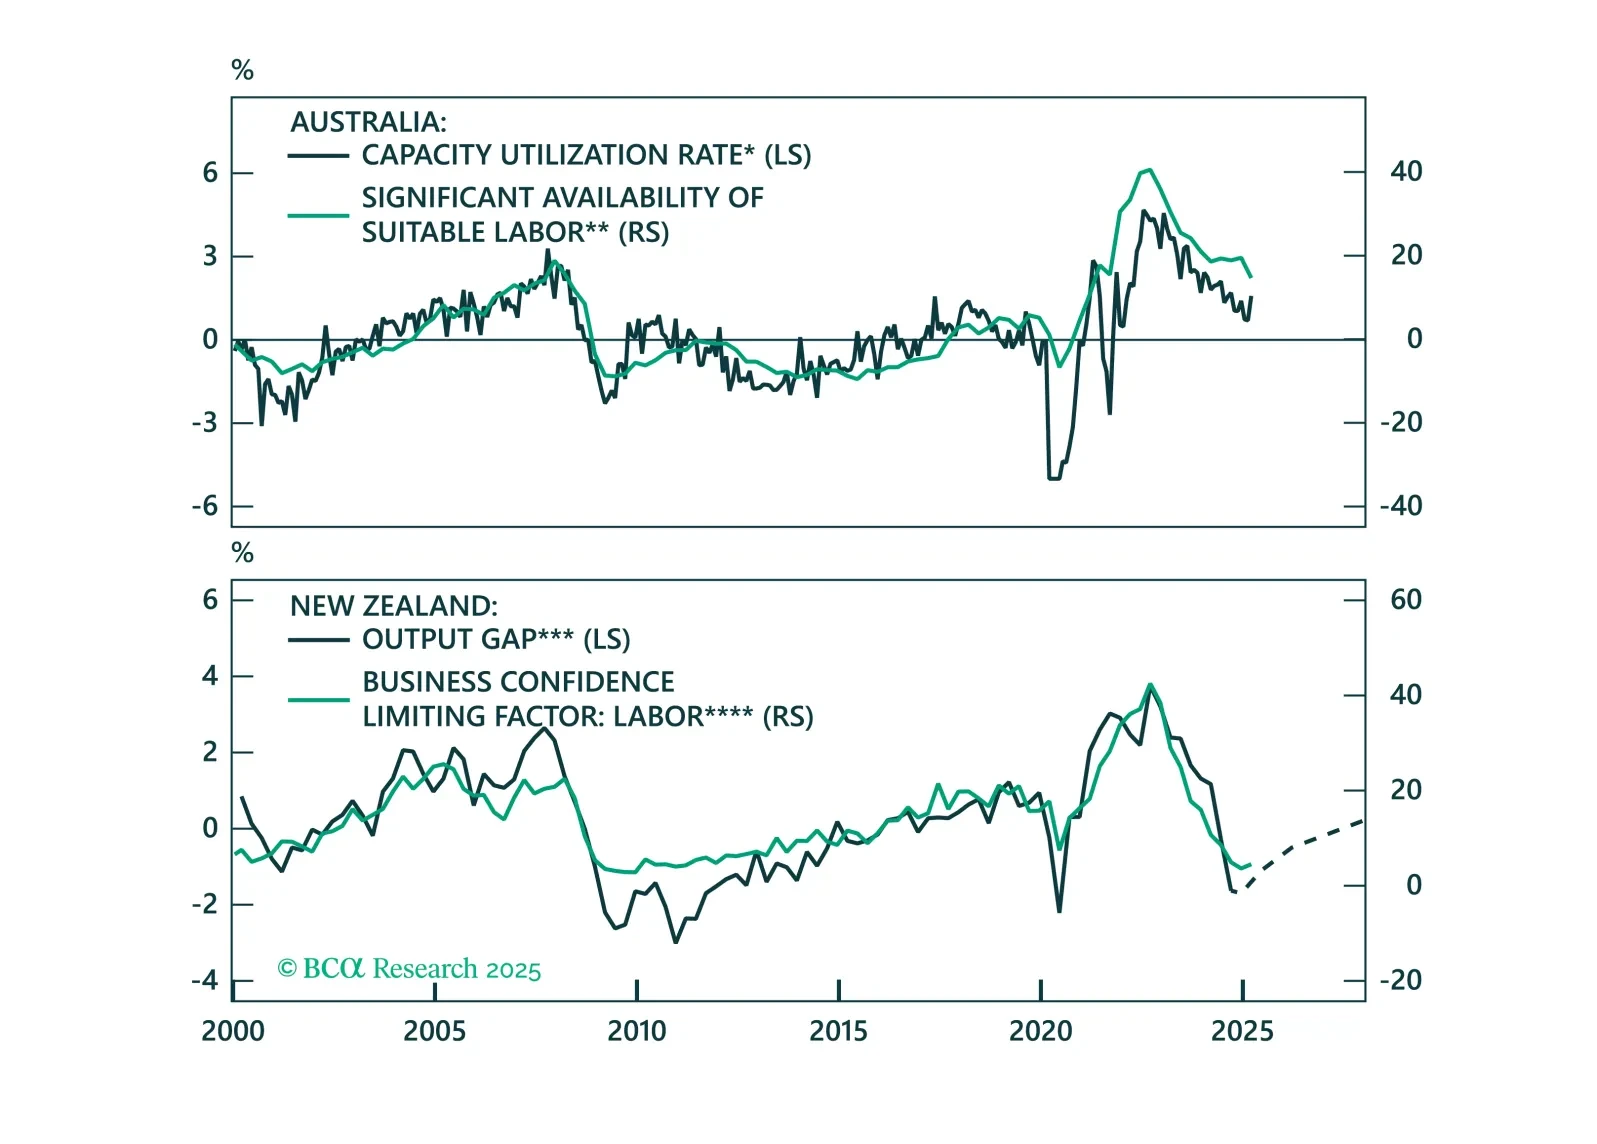
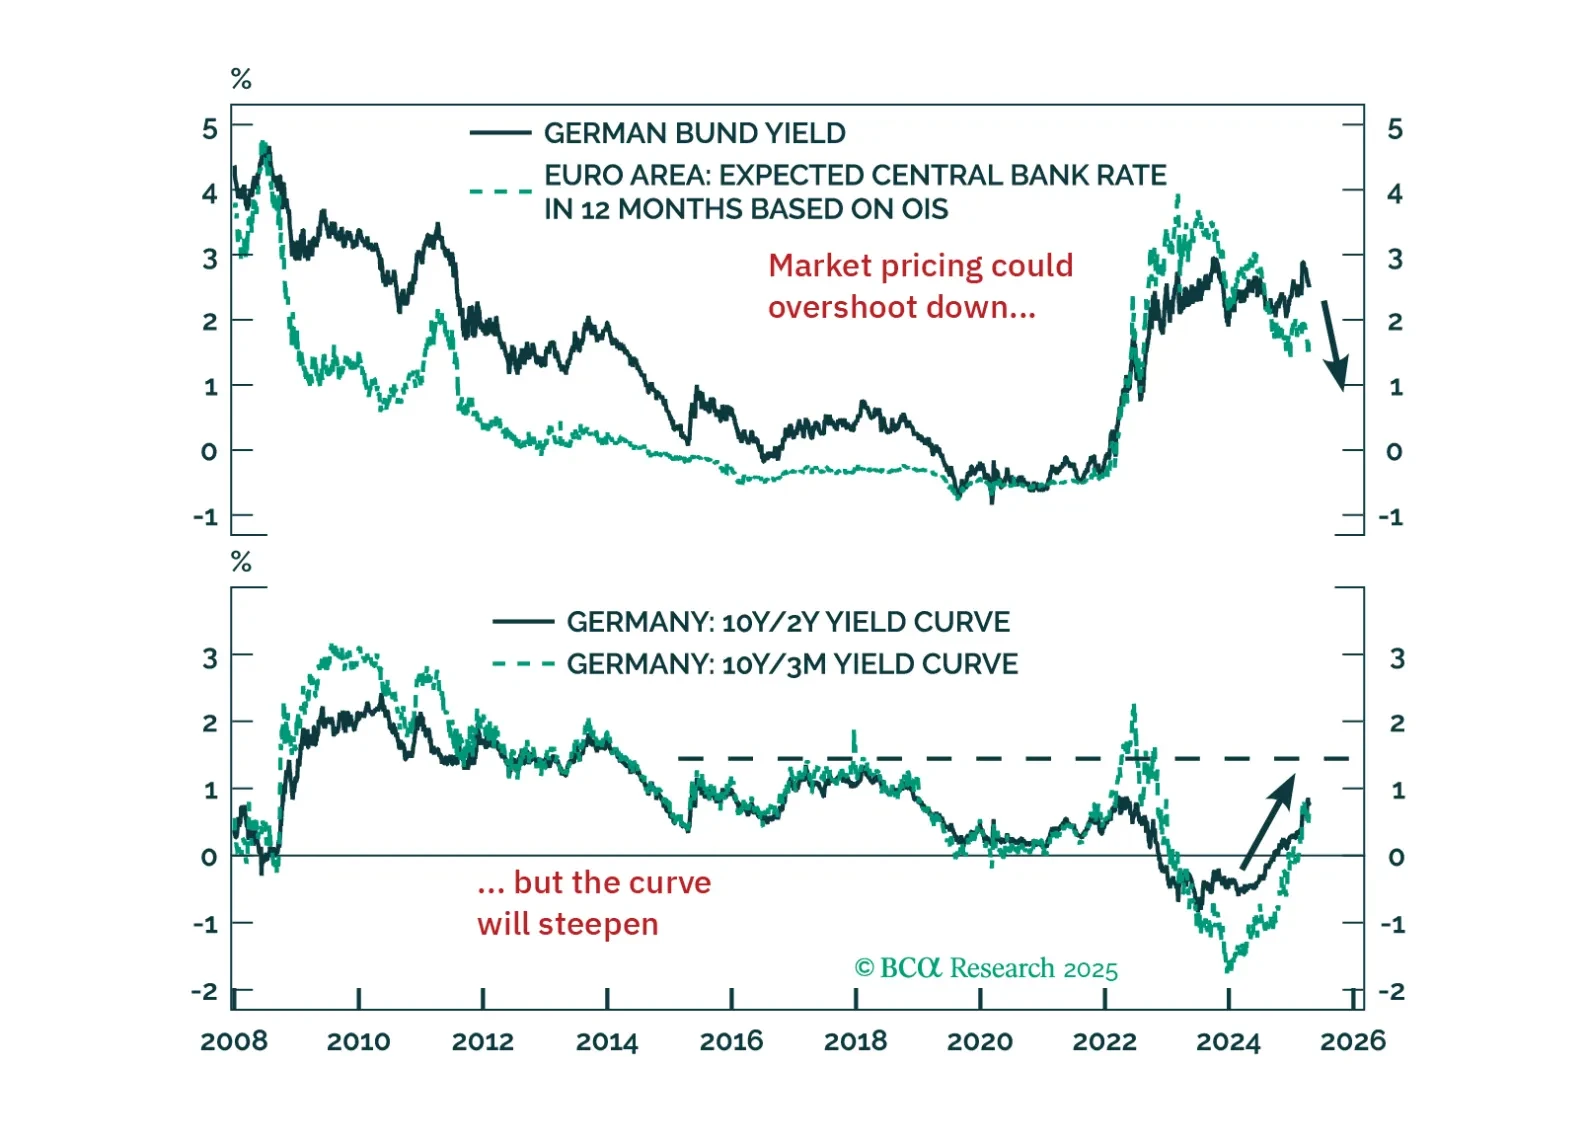
Europe’s deflation problem is getting harder to ignore. This week’s ECB cut is just the beginning — tariffs, the euro’s rally, and softening demand all point to more easing ahead. We explain what it means for yields, equities, and EUR/USD.
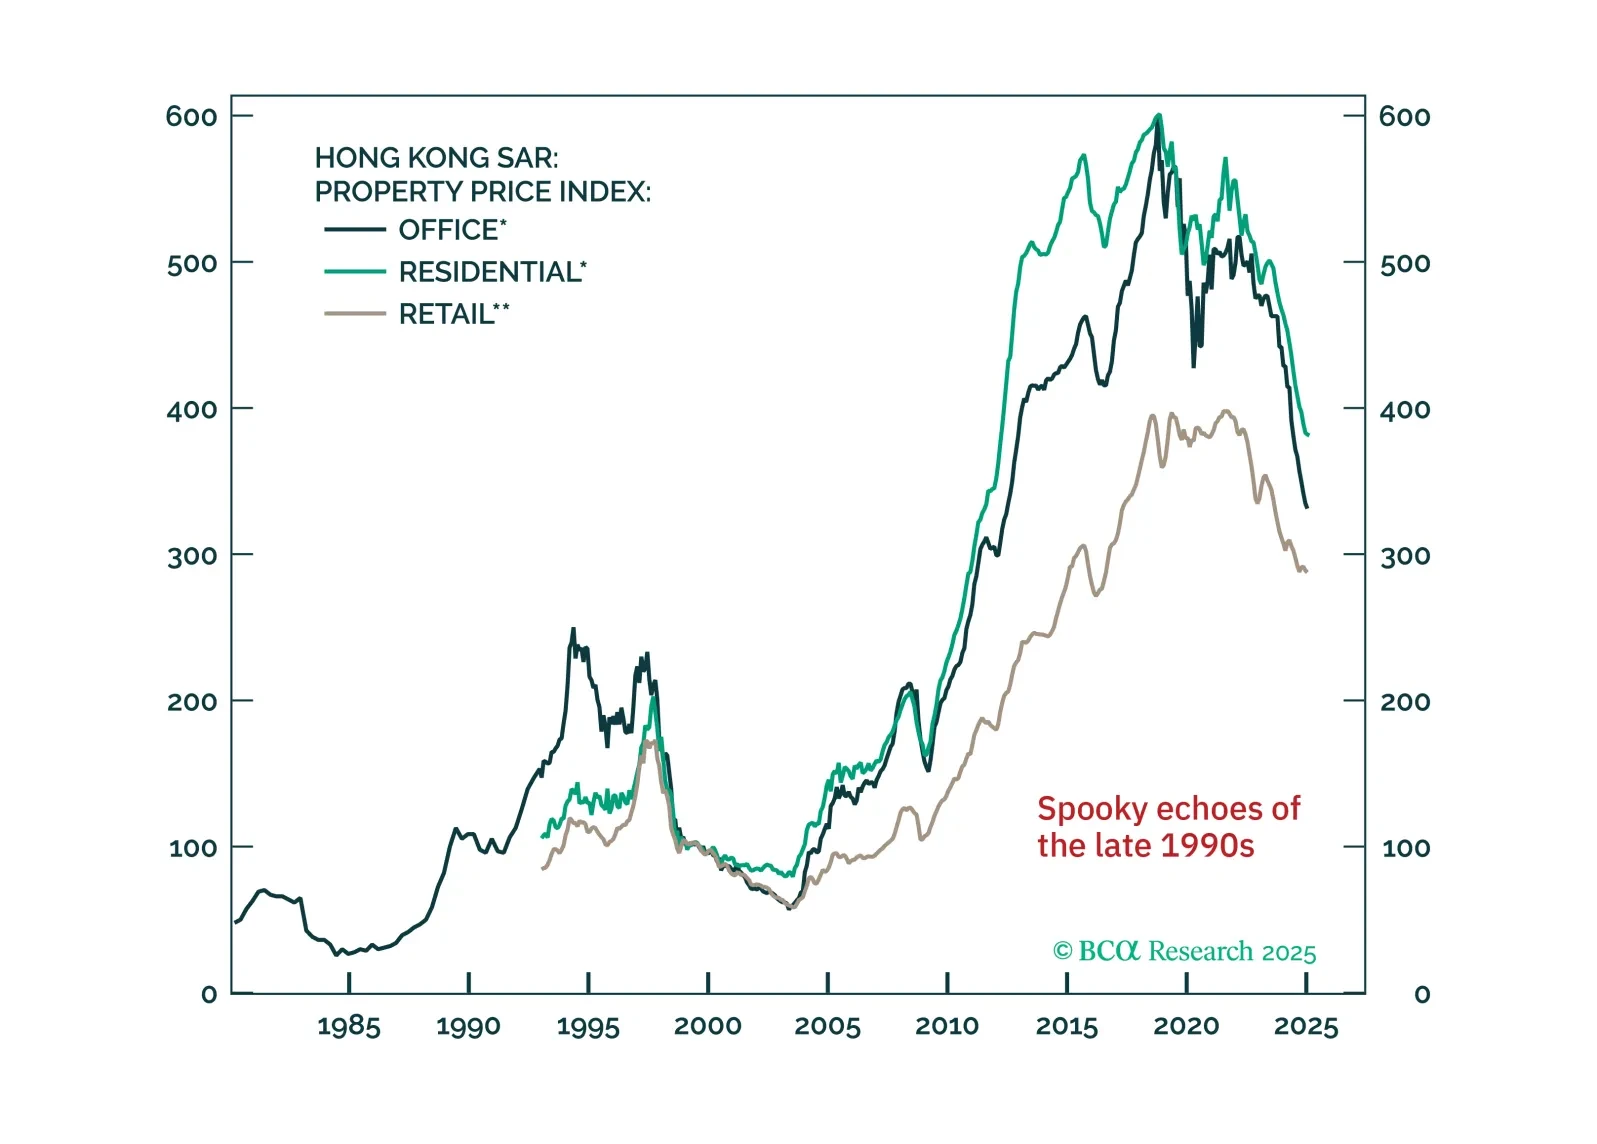
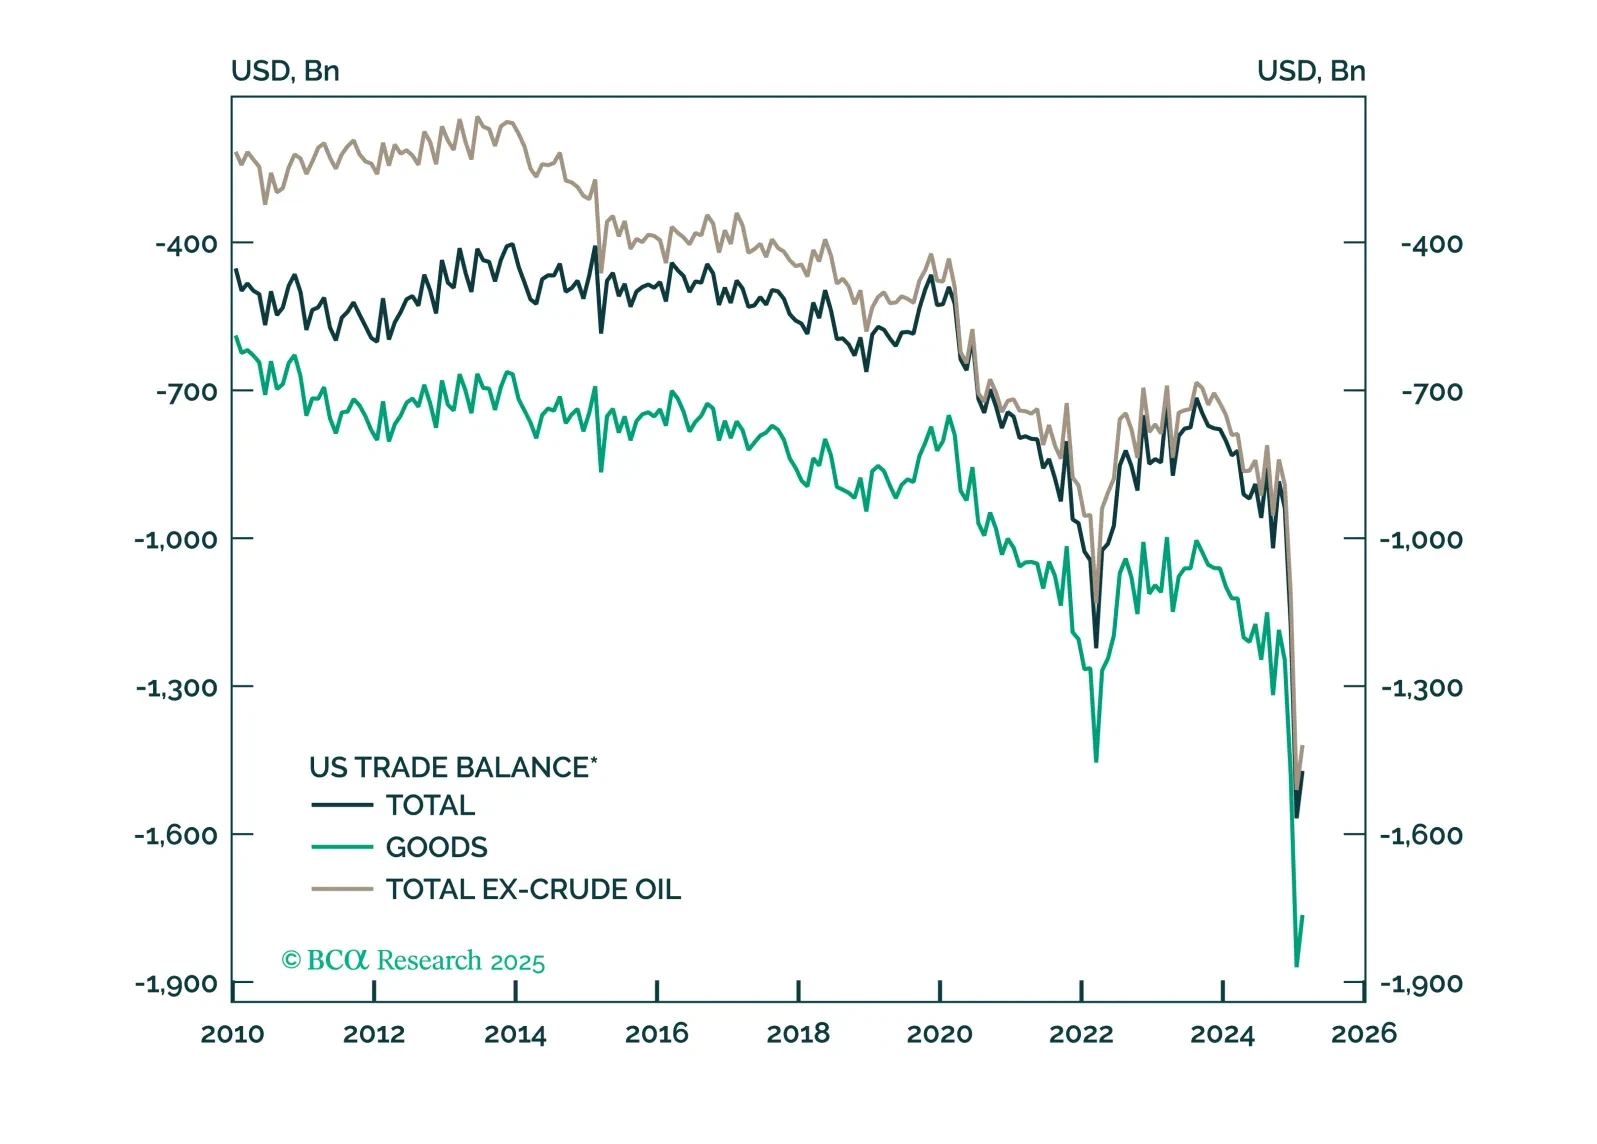
This report looks at the FX implications of the Trump tariffs, and the review of our Q1 trades.
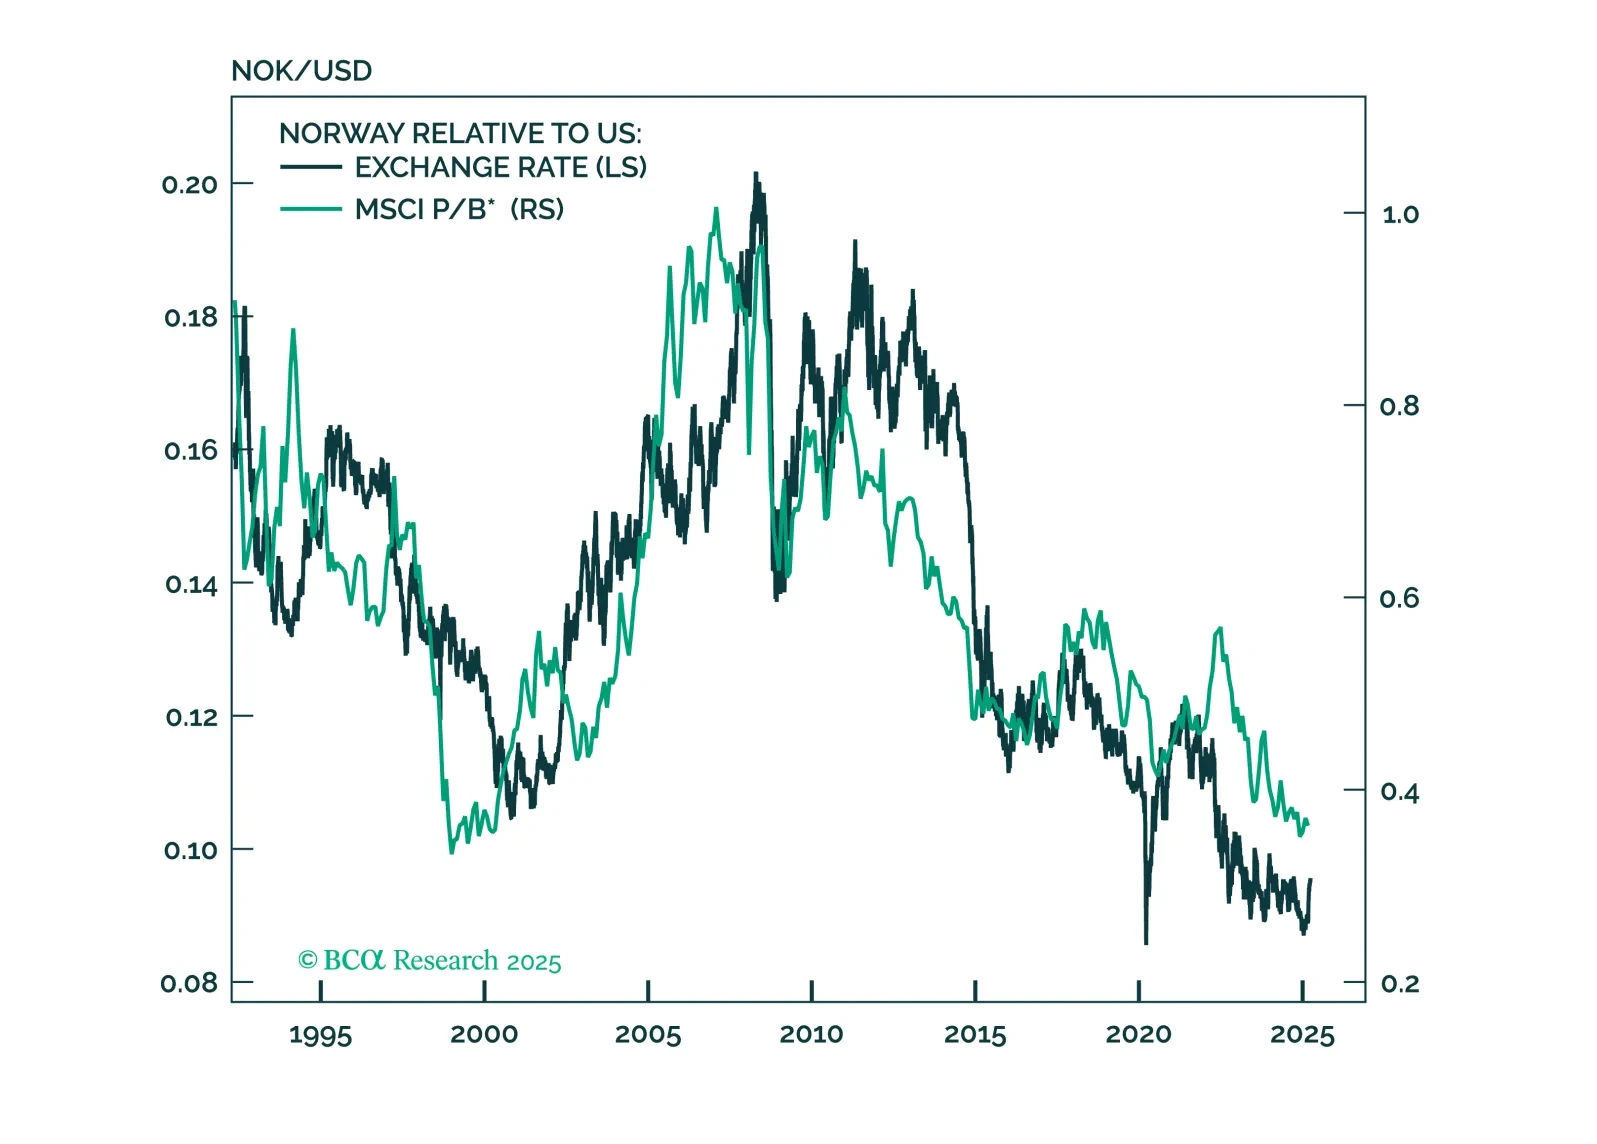
This report looks at investment implications, for Norwegian assets, given the recent meeting, from the Norges Bank.
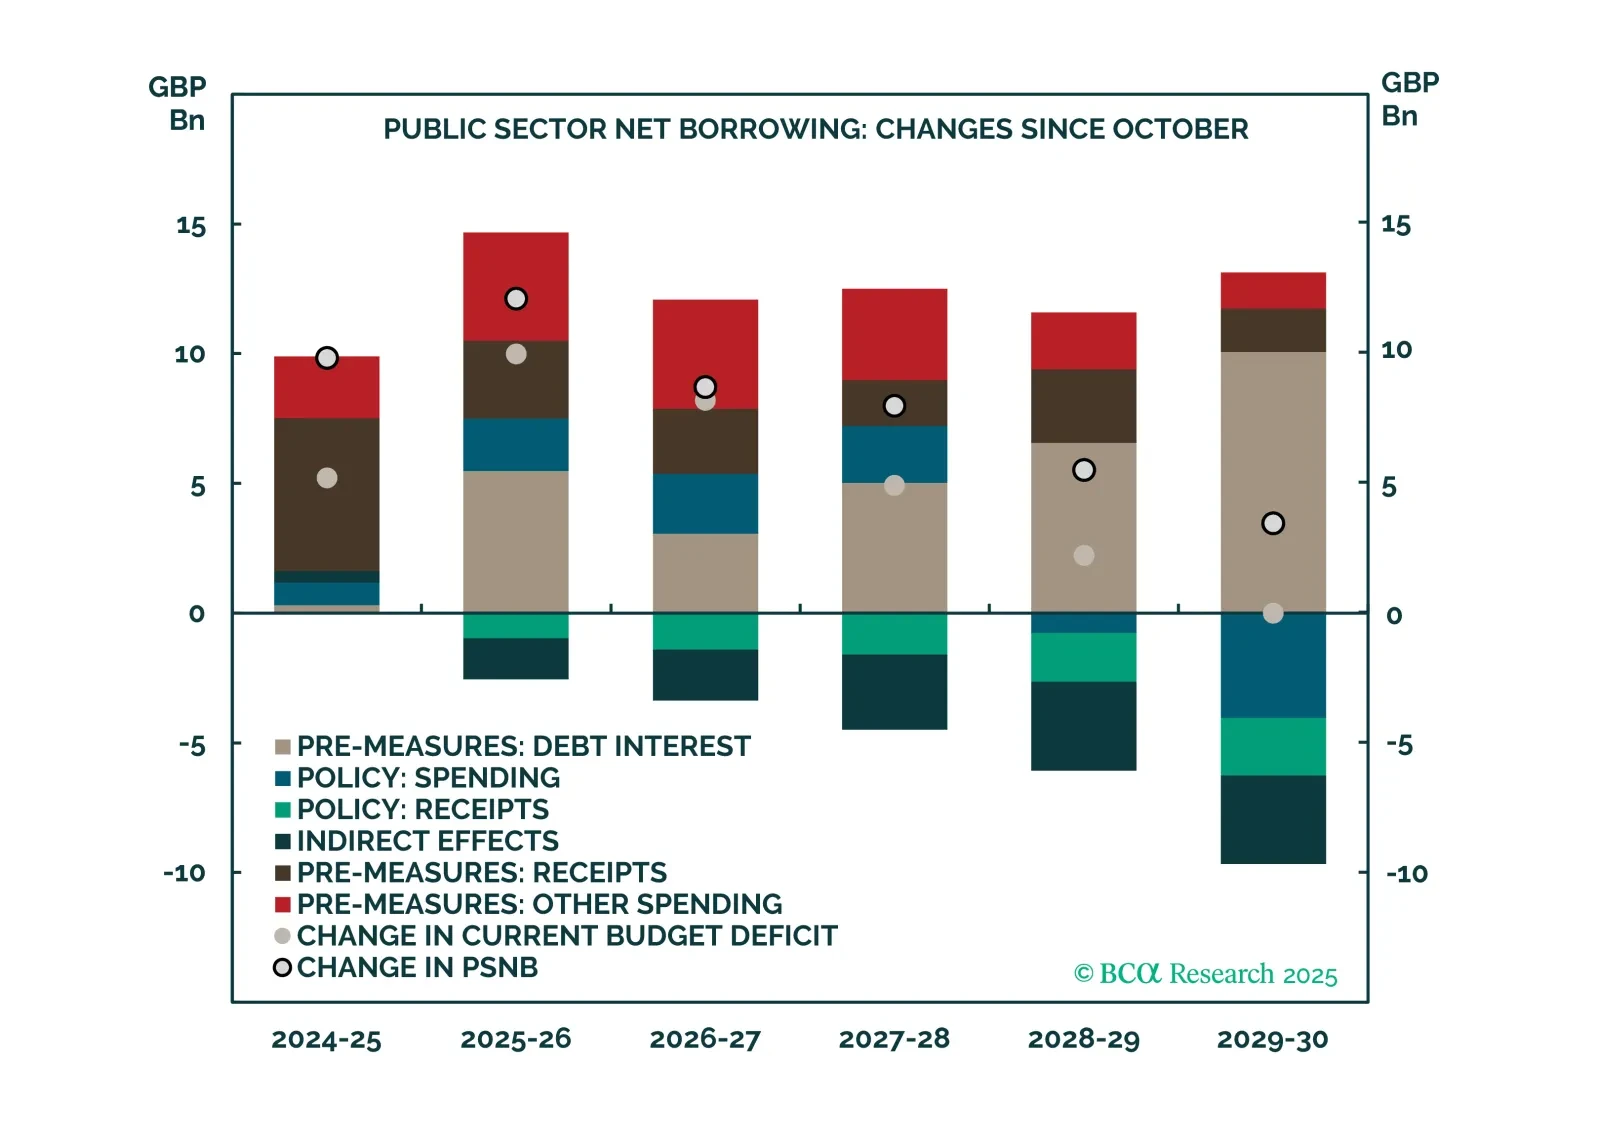
This report is a quick take on our views on UK bonds and FX, given the recent budget.
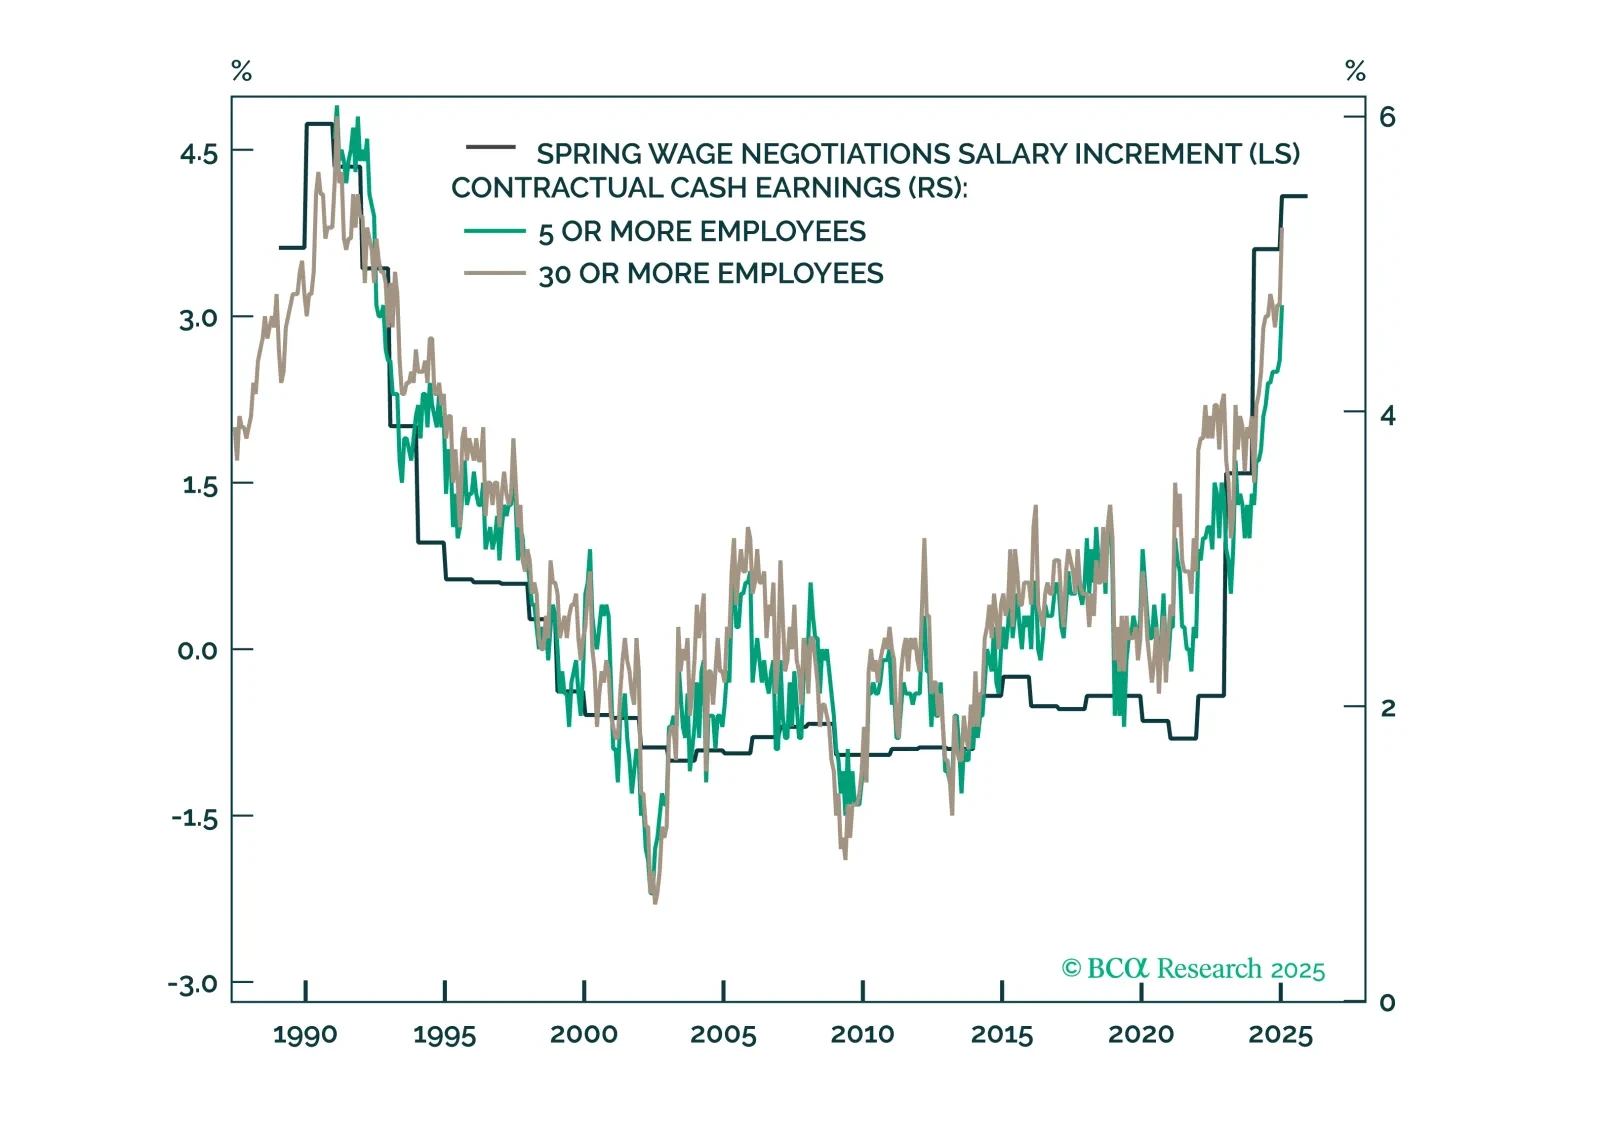
Given the meetings between the Bank of Japan, the Bank of England, and the Swiss National Bank, our highest convictions views are: Overweight UK Gilts. It is also time to sell sterling. We are short sterling, as of 1.30. Underweight JGBs. Correspondingly, be long the yen. A short CHF/JPY position remains a core holding. Selling GBP/JPY is also a great trade.
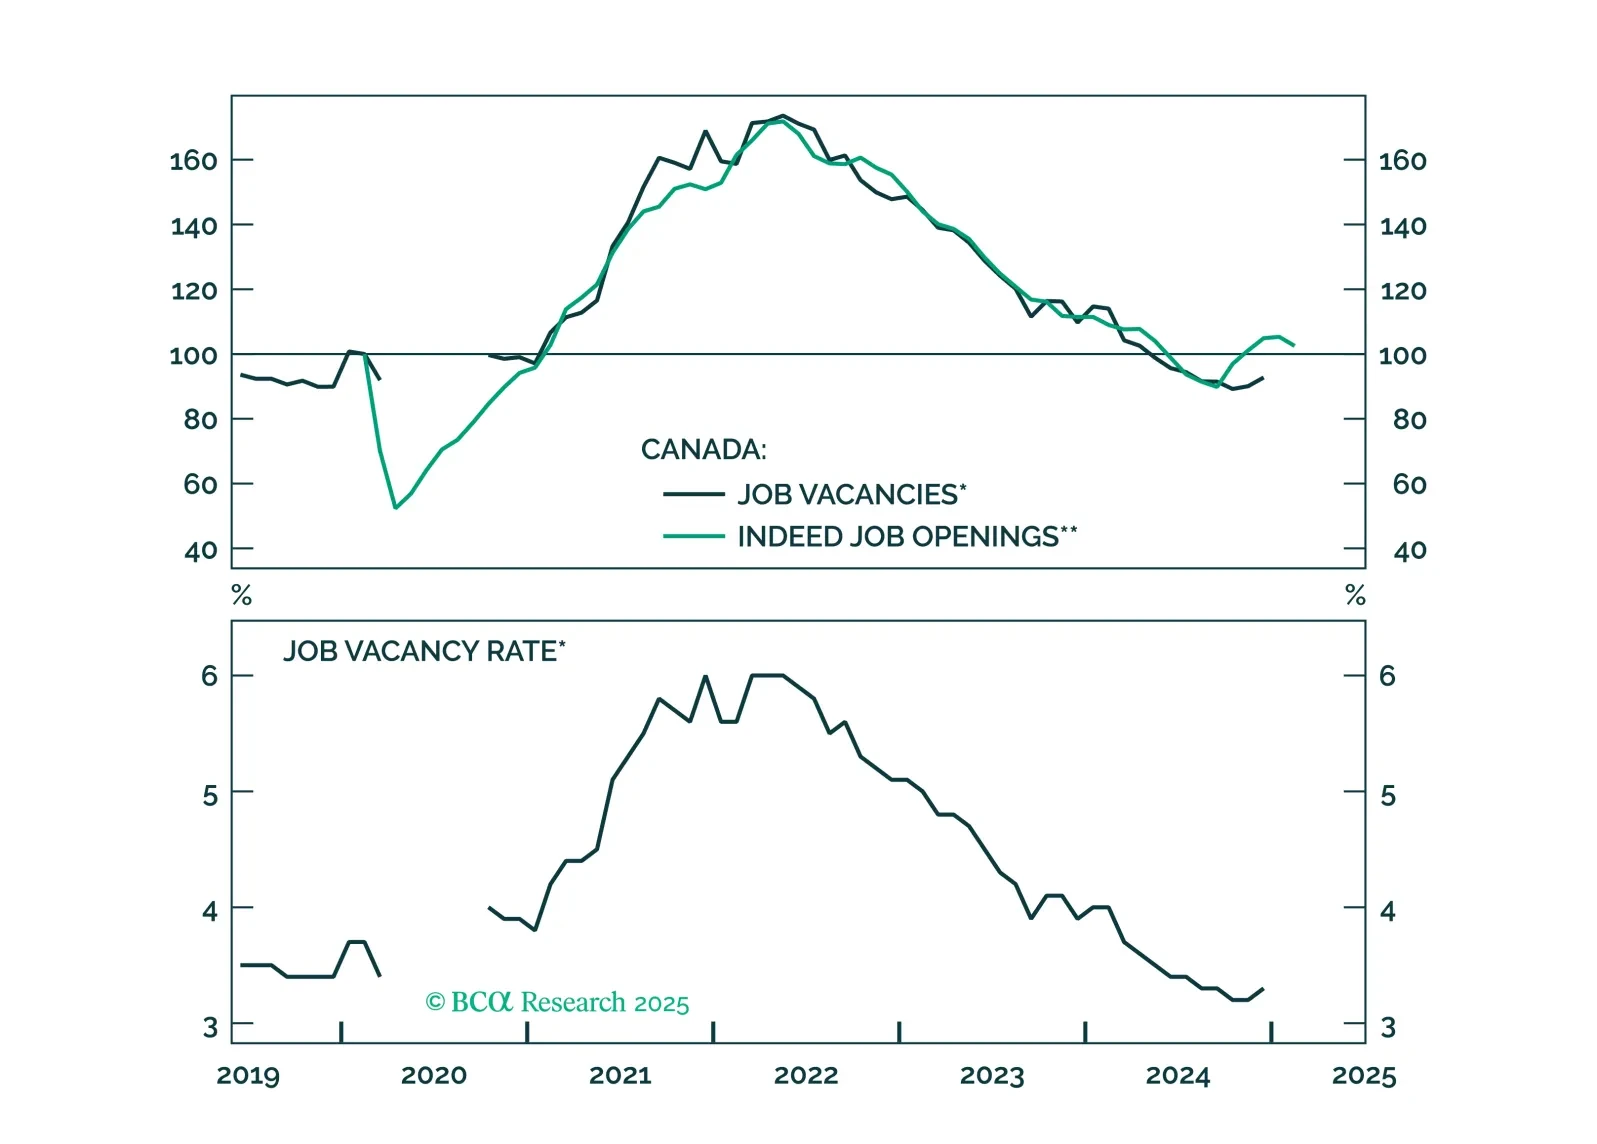
The trade war complicates the Bank of Canada’s task to achieve stable inflation. But the bottom line is that rising uncertainty, which will dampen business sentiment, will cause the BoC to cut rates by at least what is priced in the CORRA curve, and likely to 2%. The CAD, which is very oversold, might not depreciate much. The big trade is a bet on a spread widening for Canadian provincial bonds.
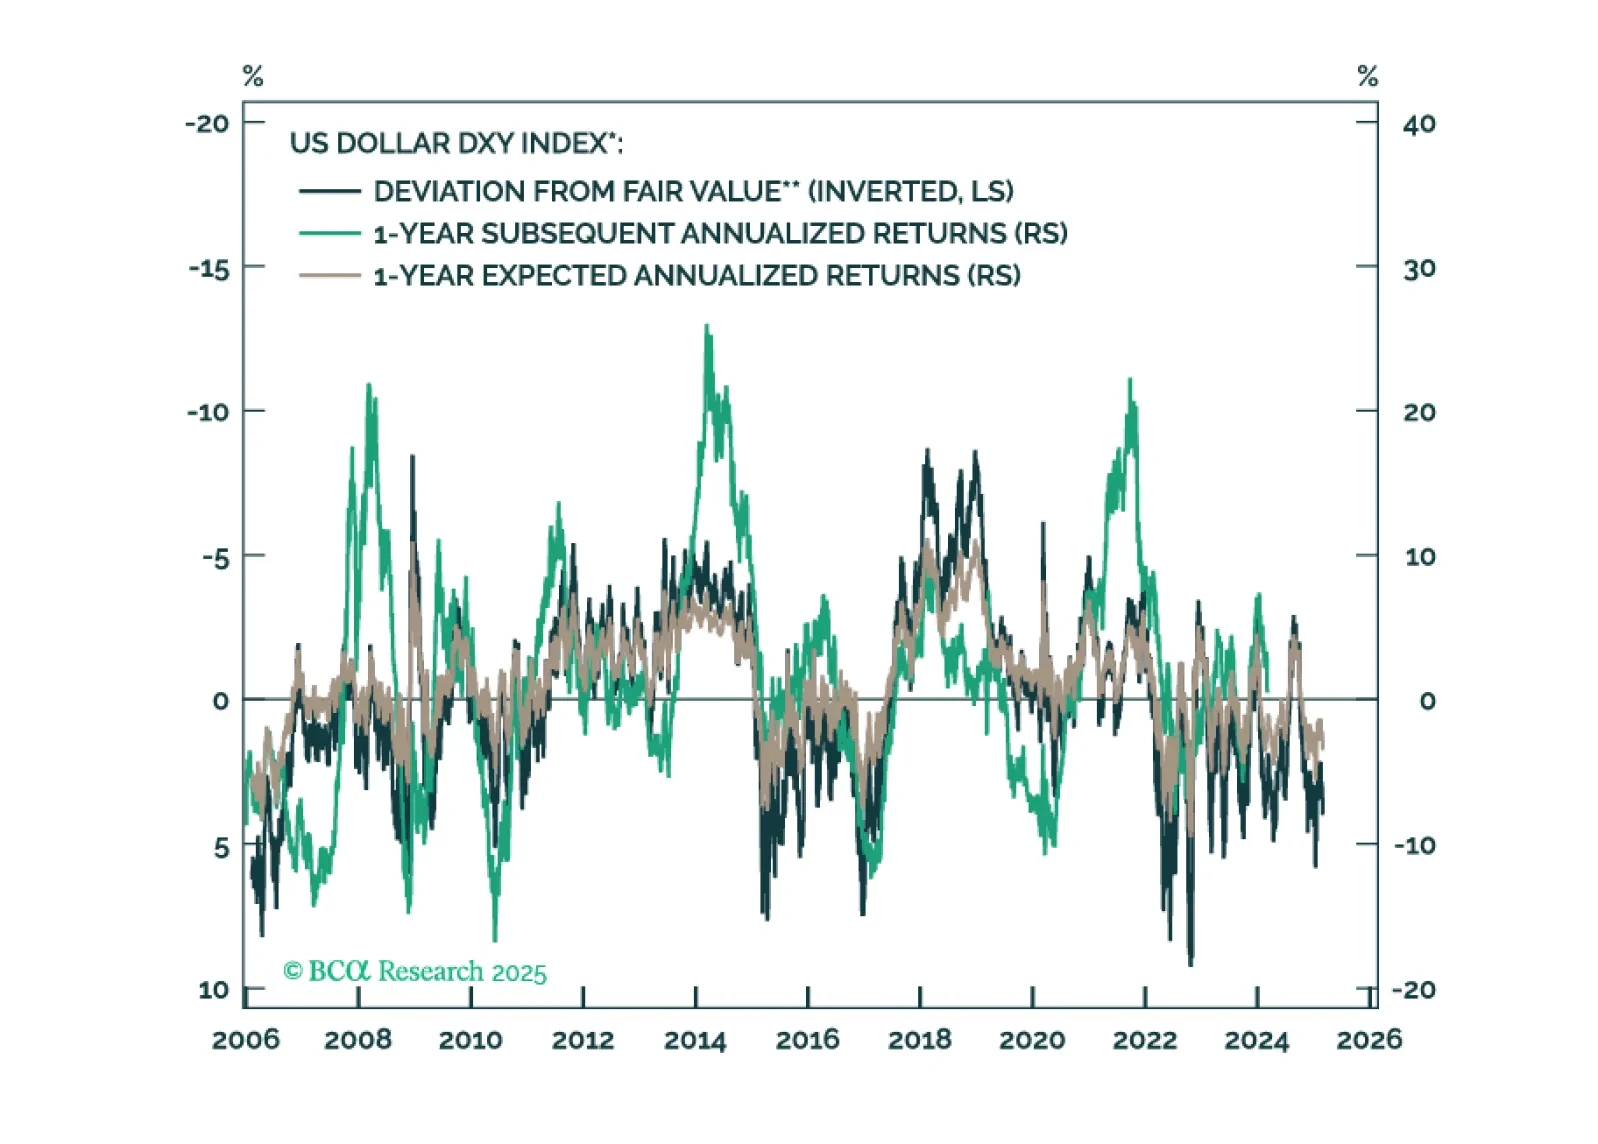
This report is our Part III series on valuation and subsequent returns, where we recalibrate our short-term models to emphasize signals over the next nine-to-twelve months. We will henceforth call these models STTM: Short Term Timing Models.
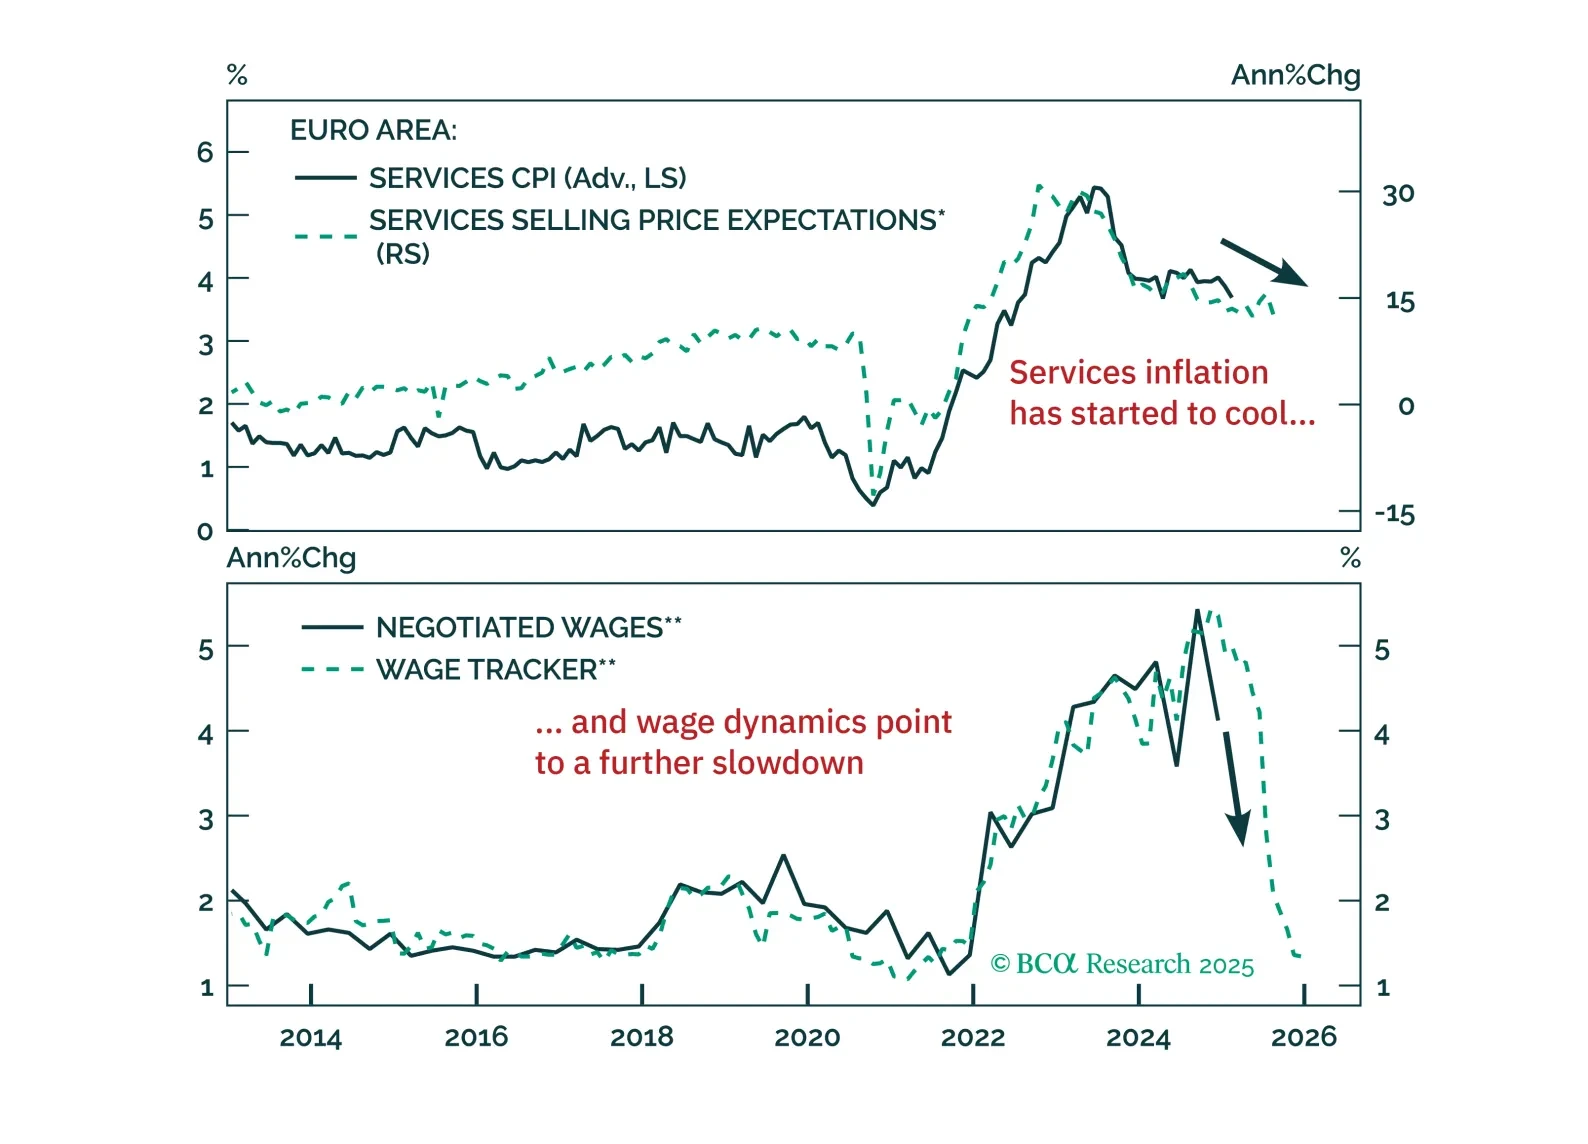
The ECB cut rates as expected, but rising yields and a stronger euro are tightening financial conditions just as fiscal policy shifts the macro landscape. With more rate cuts ahead and market positioning stretched, we outline the key risks, investment opportunities, and our updated call on the ECB’s terminal rate. Read our full report for actionable insights.