 Explore FICC
FICC | Currencies
Tactical and strategic guidance on all major DM and EM currencies. Typically published twice a month.
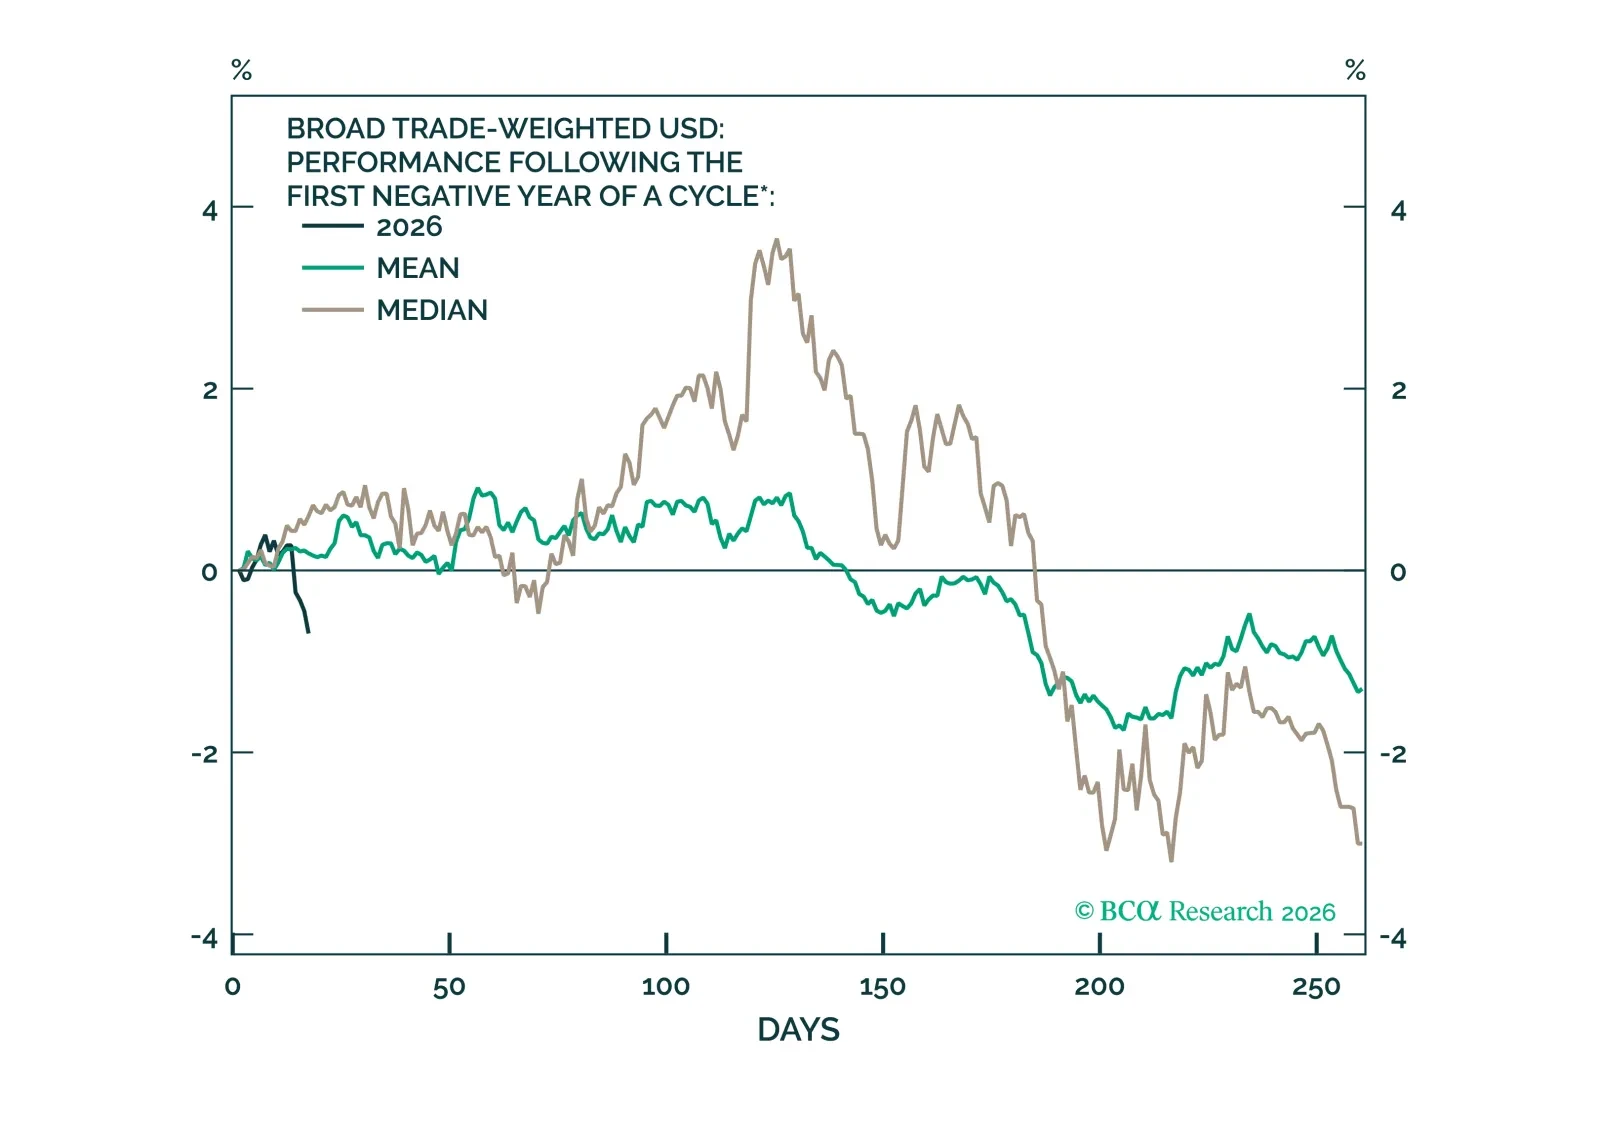
FX markets have dominated headlines over the past week, with a meltdown in the dollar and a surge in the yen. This week’s note unpacks the forces behind these moves and assesses whether recent price action marks a temporary dislocation or the start of a more durable FX shift.
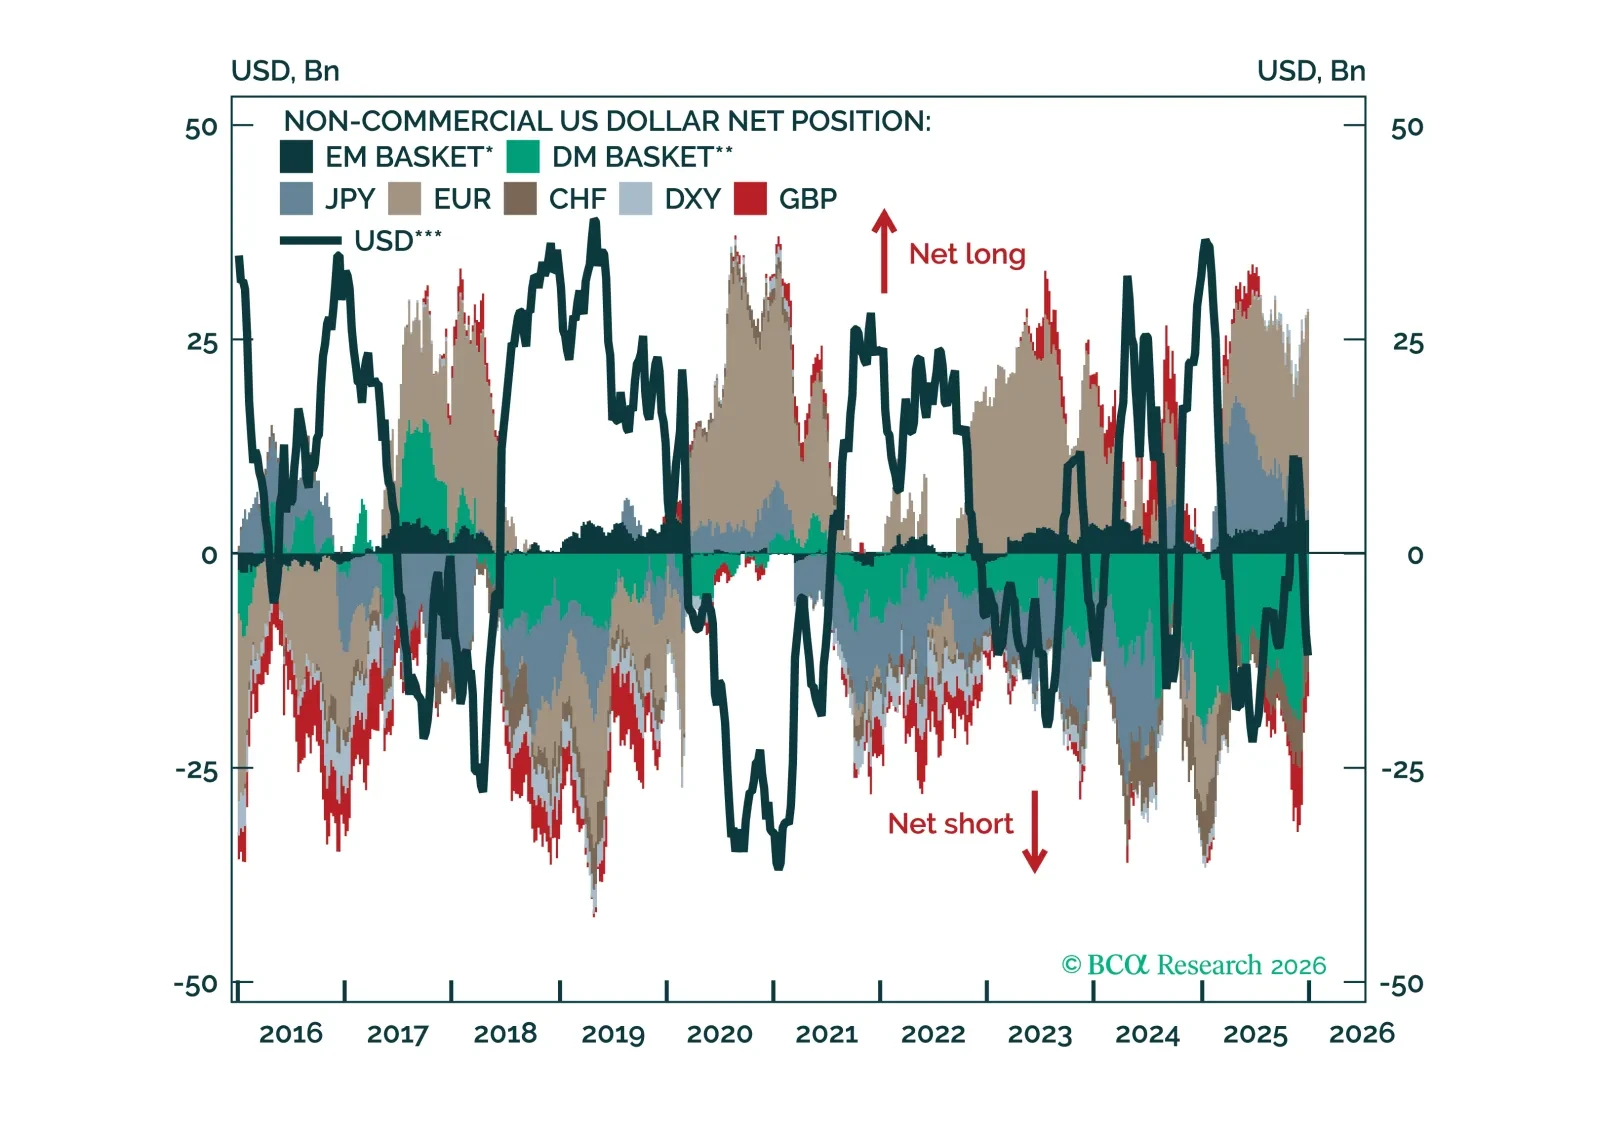
With FX volatility near cycle lows, this Insight examines where positioning has become most stretched across G10, EM FX, and precious metals – and what that implies for near-term moves and reversal risks.
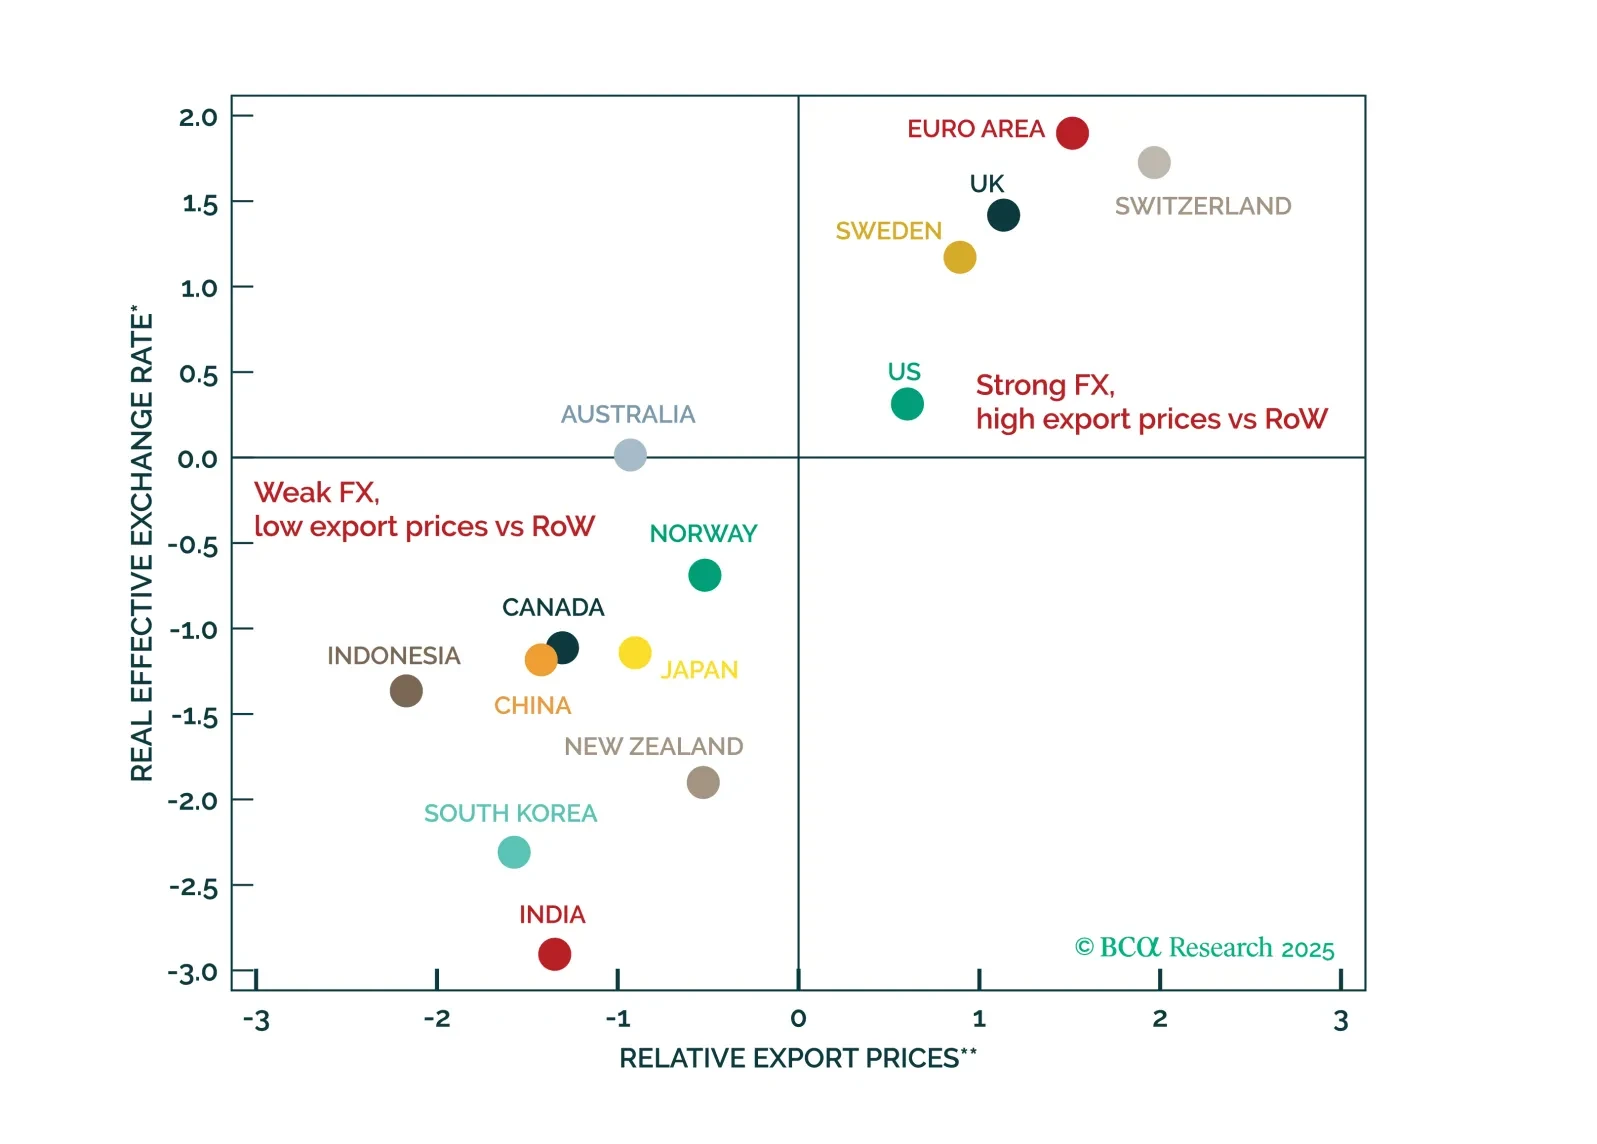
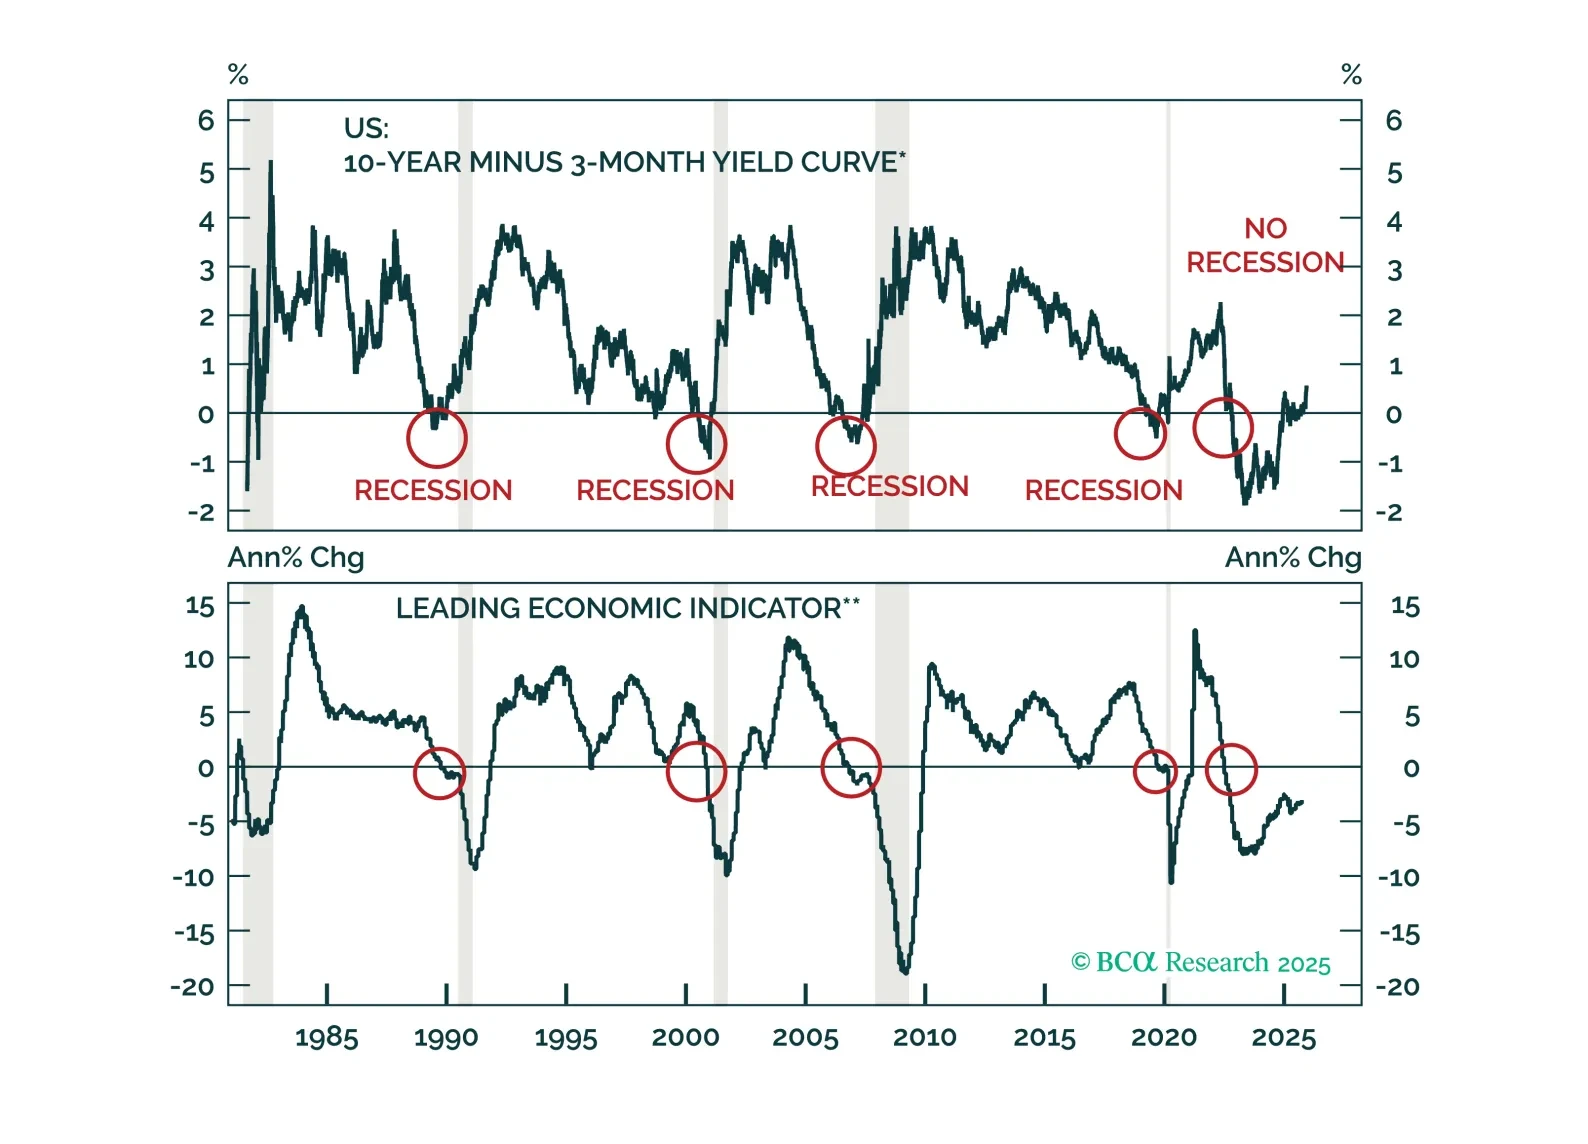
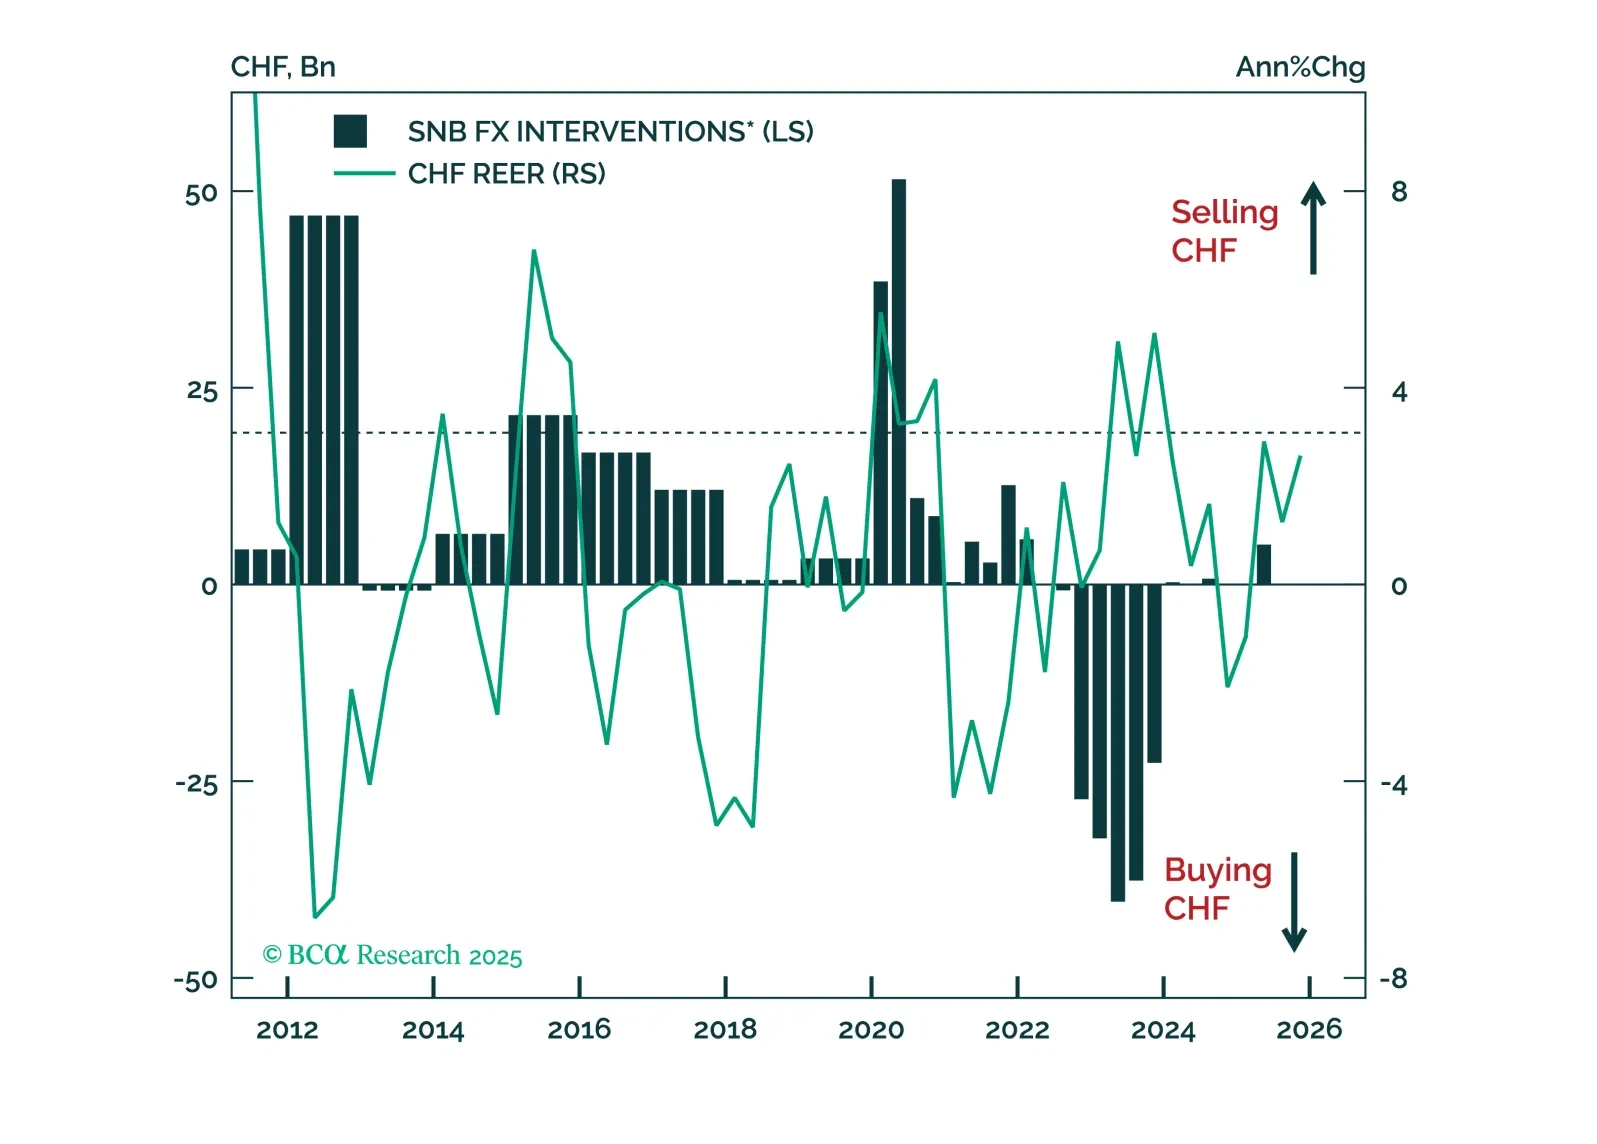
The SNB remains on hold, but the bar for further easing is falling quickly – even as Switzerland secures a breakthrough trade deal with the US. With CHF now pressing against a policy ceiling, the franc looks increasingly attractive as a funding currency.
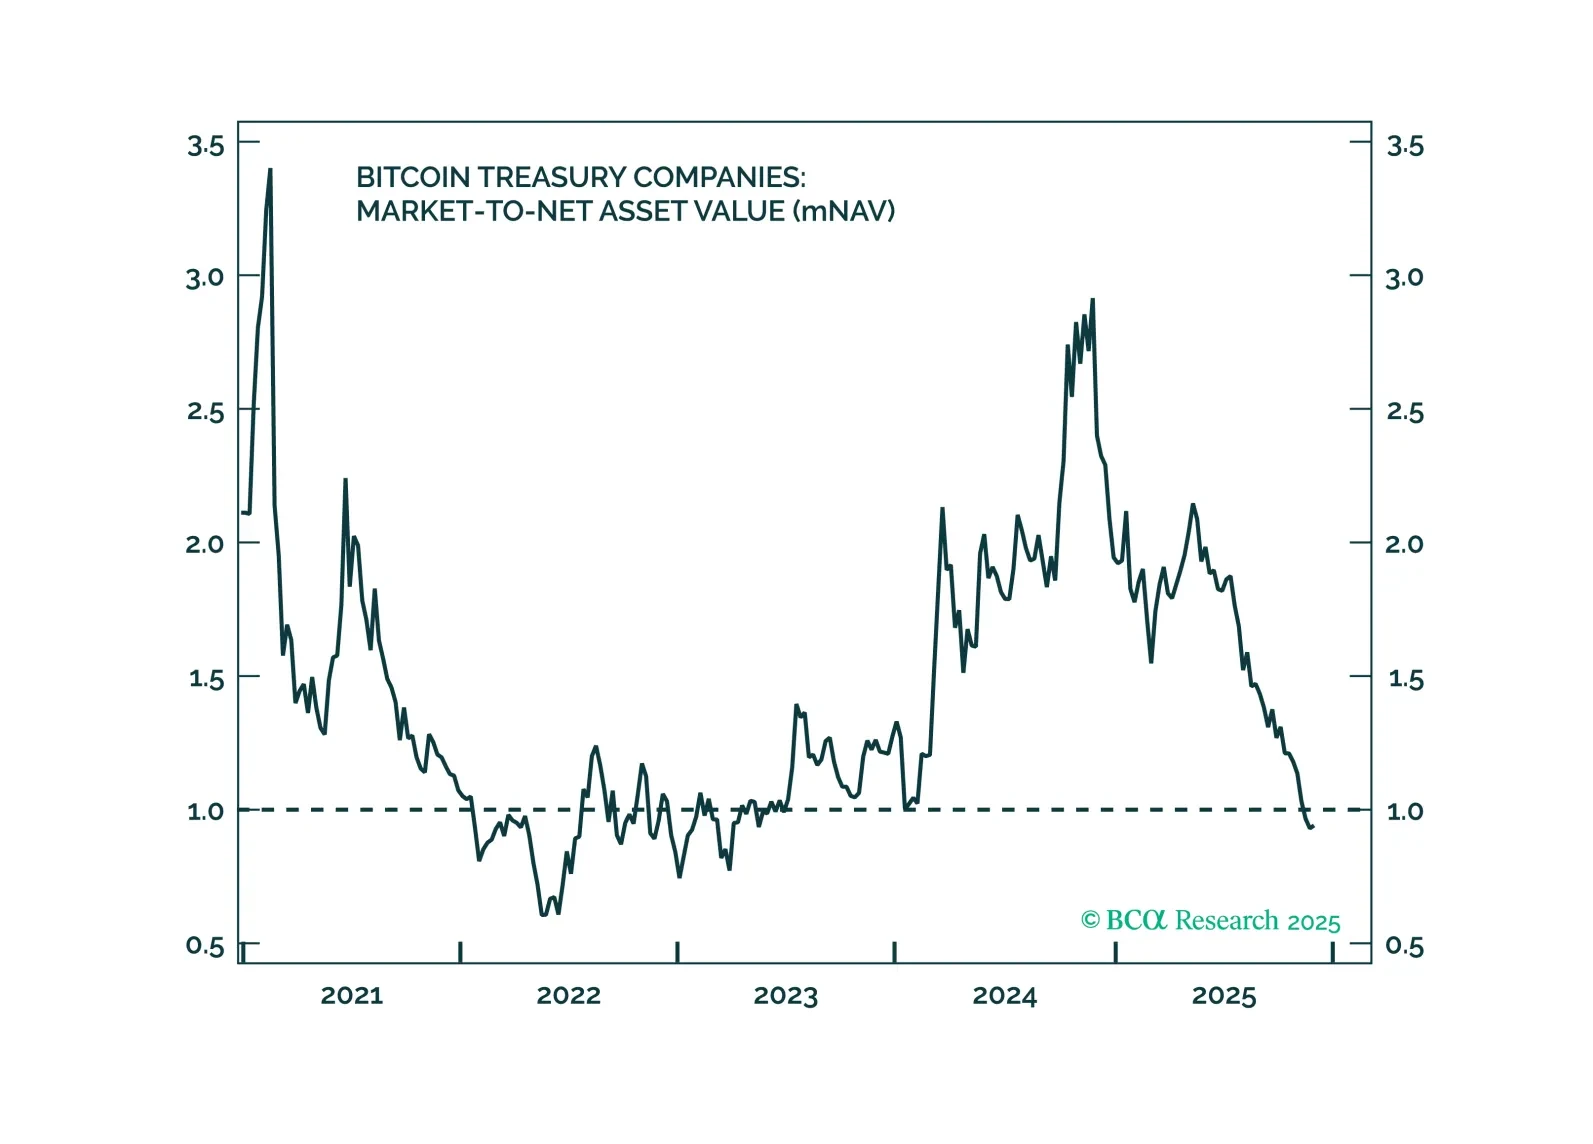
Bitcoin’s recent volatility masks a deeper story – the widest disconnect from traditional macro drivers since 2022. With sentiment now deeply negative and institutional demand still building, the conditions for a realignment with fundamentals are falling into place.
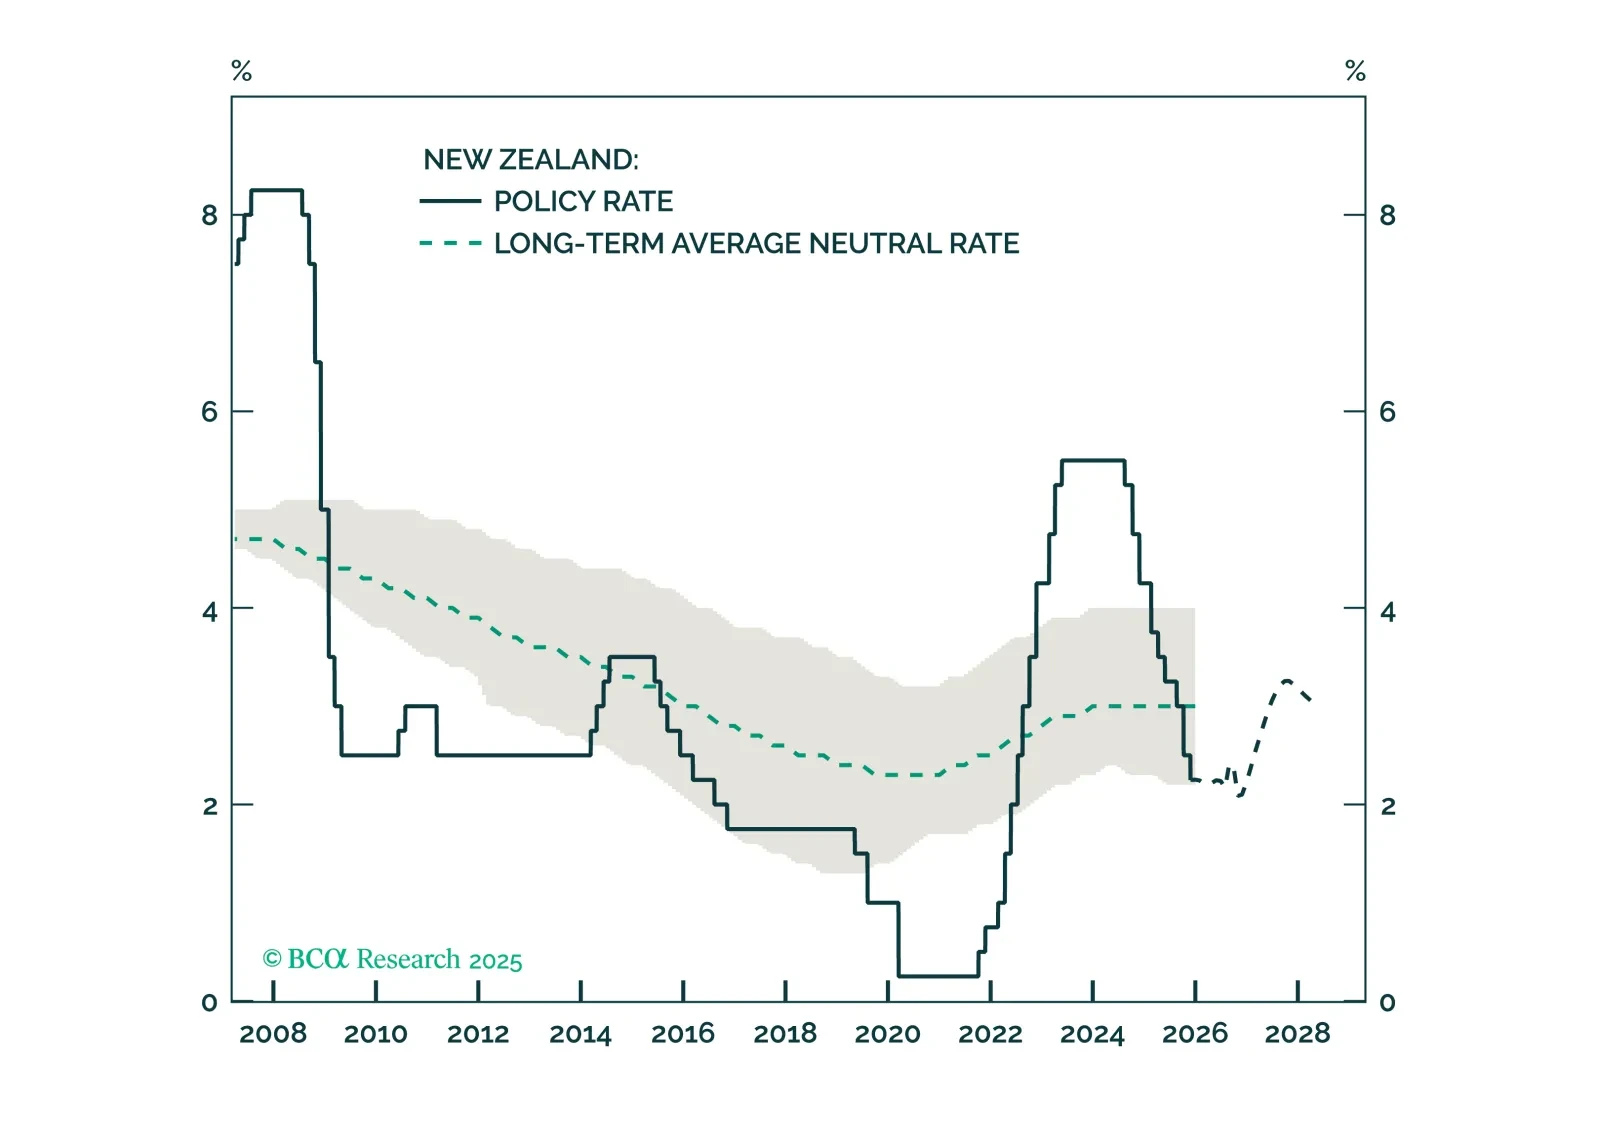
The RBNZ has concluded its aggressive easing blitz. With New Zealand economy finally showing signs of life, both the kiwi and local rates now look ripe for a reversal.
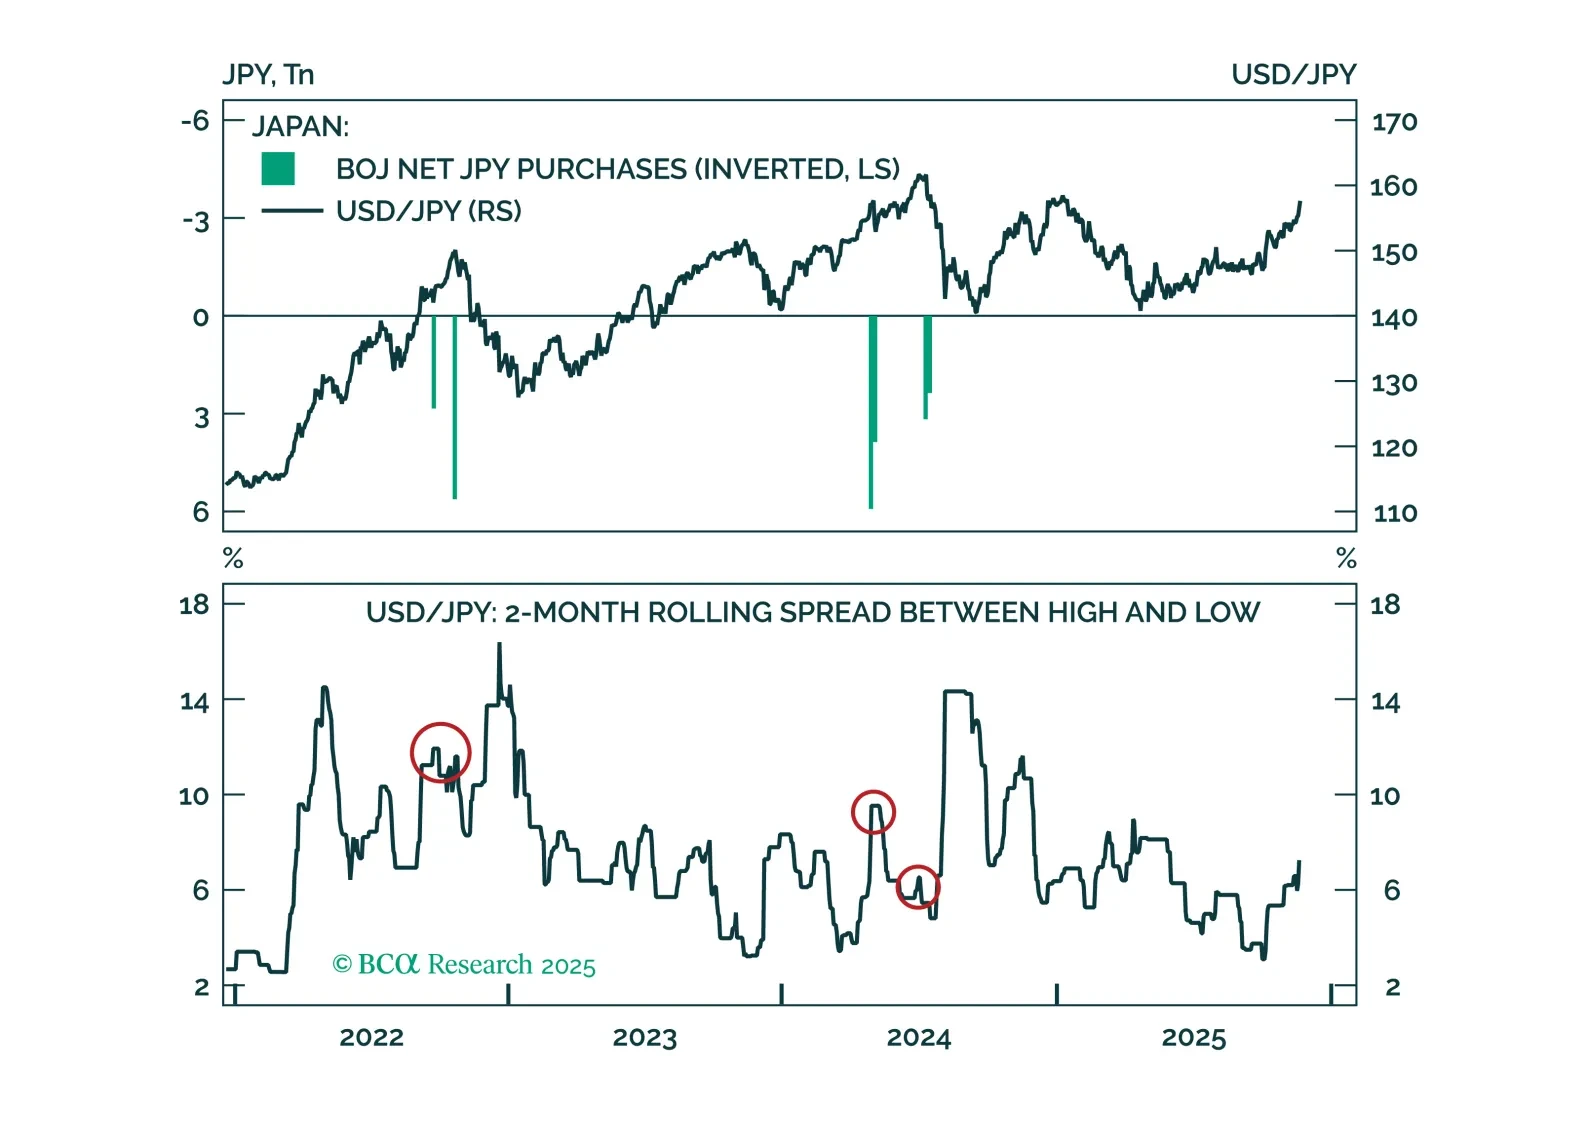
Markets are misreading Japan’s fiscal headlines. Our latest Insight examines what will shape BoJ policy next, when intervention might come, and the timing of a yen reversal.
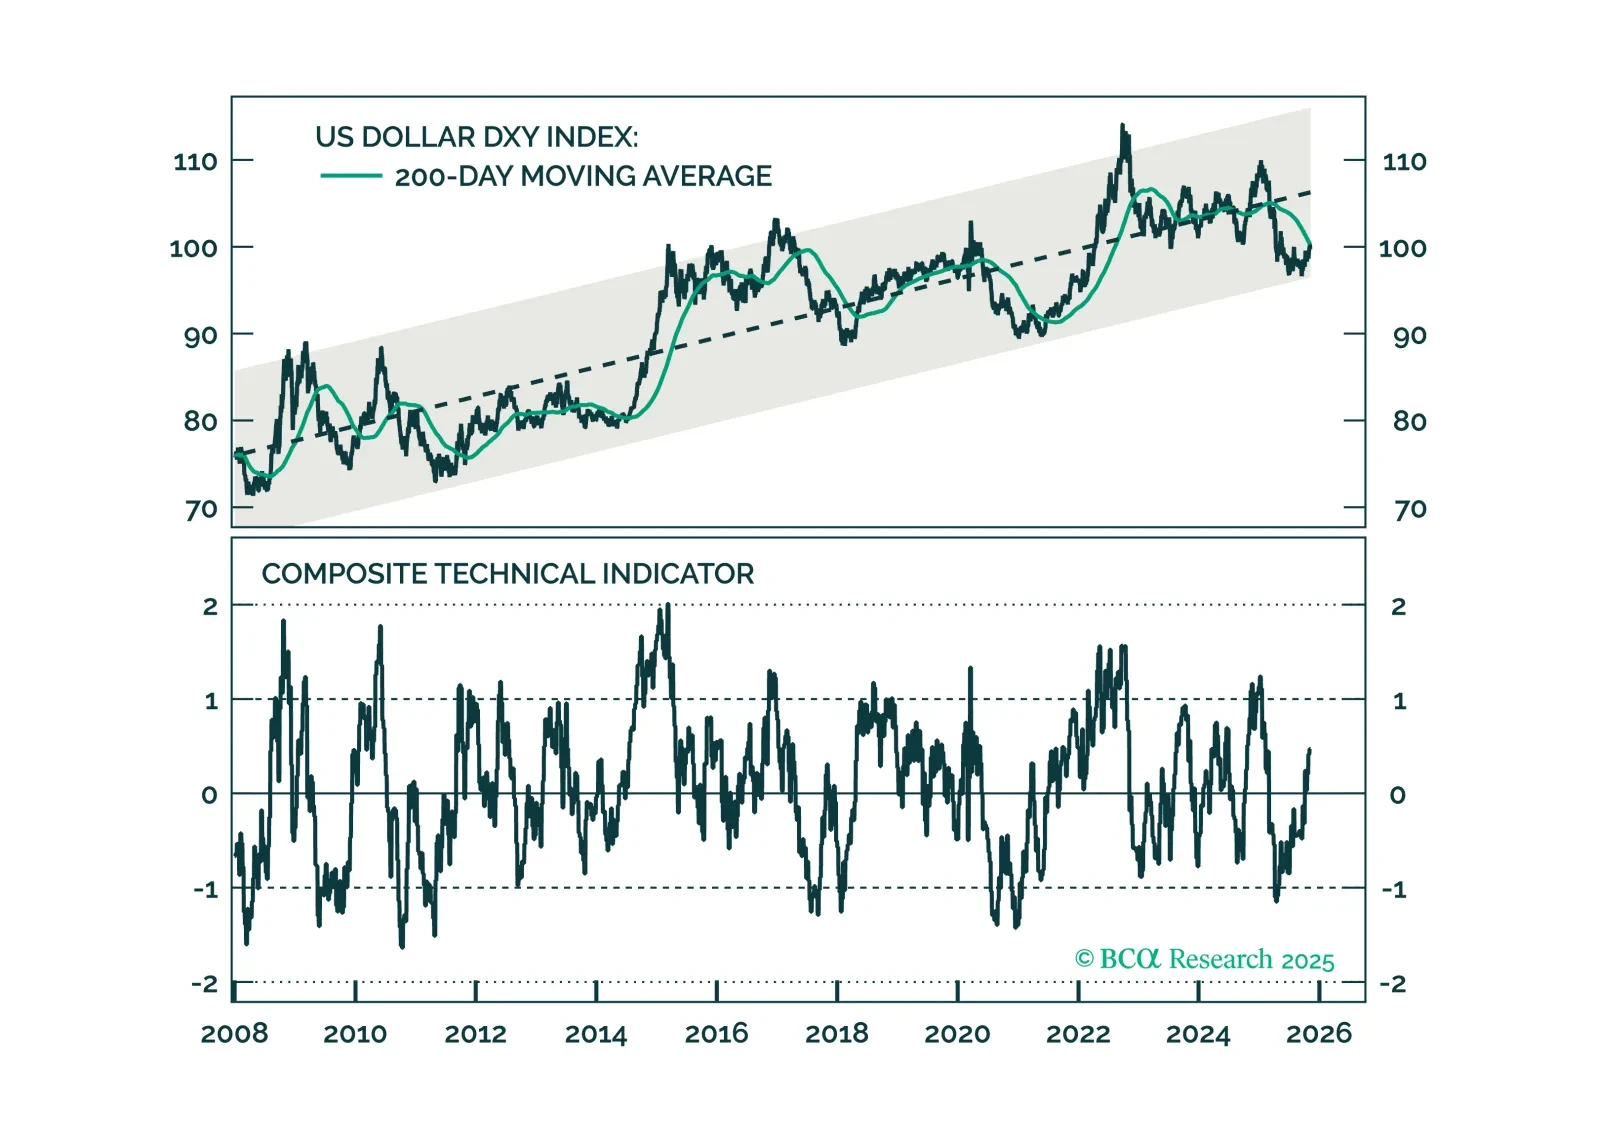
The dollar rebound has paused, but not yet peaked. With near-term momentum still intact, we see room for further upside before structural headwinds reassert, favoring selling into strength.
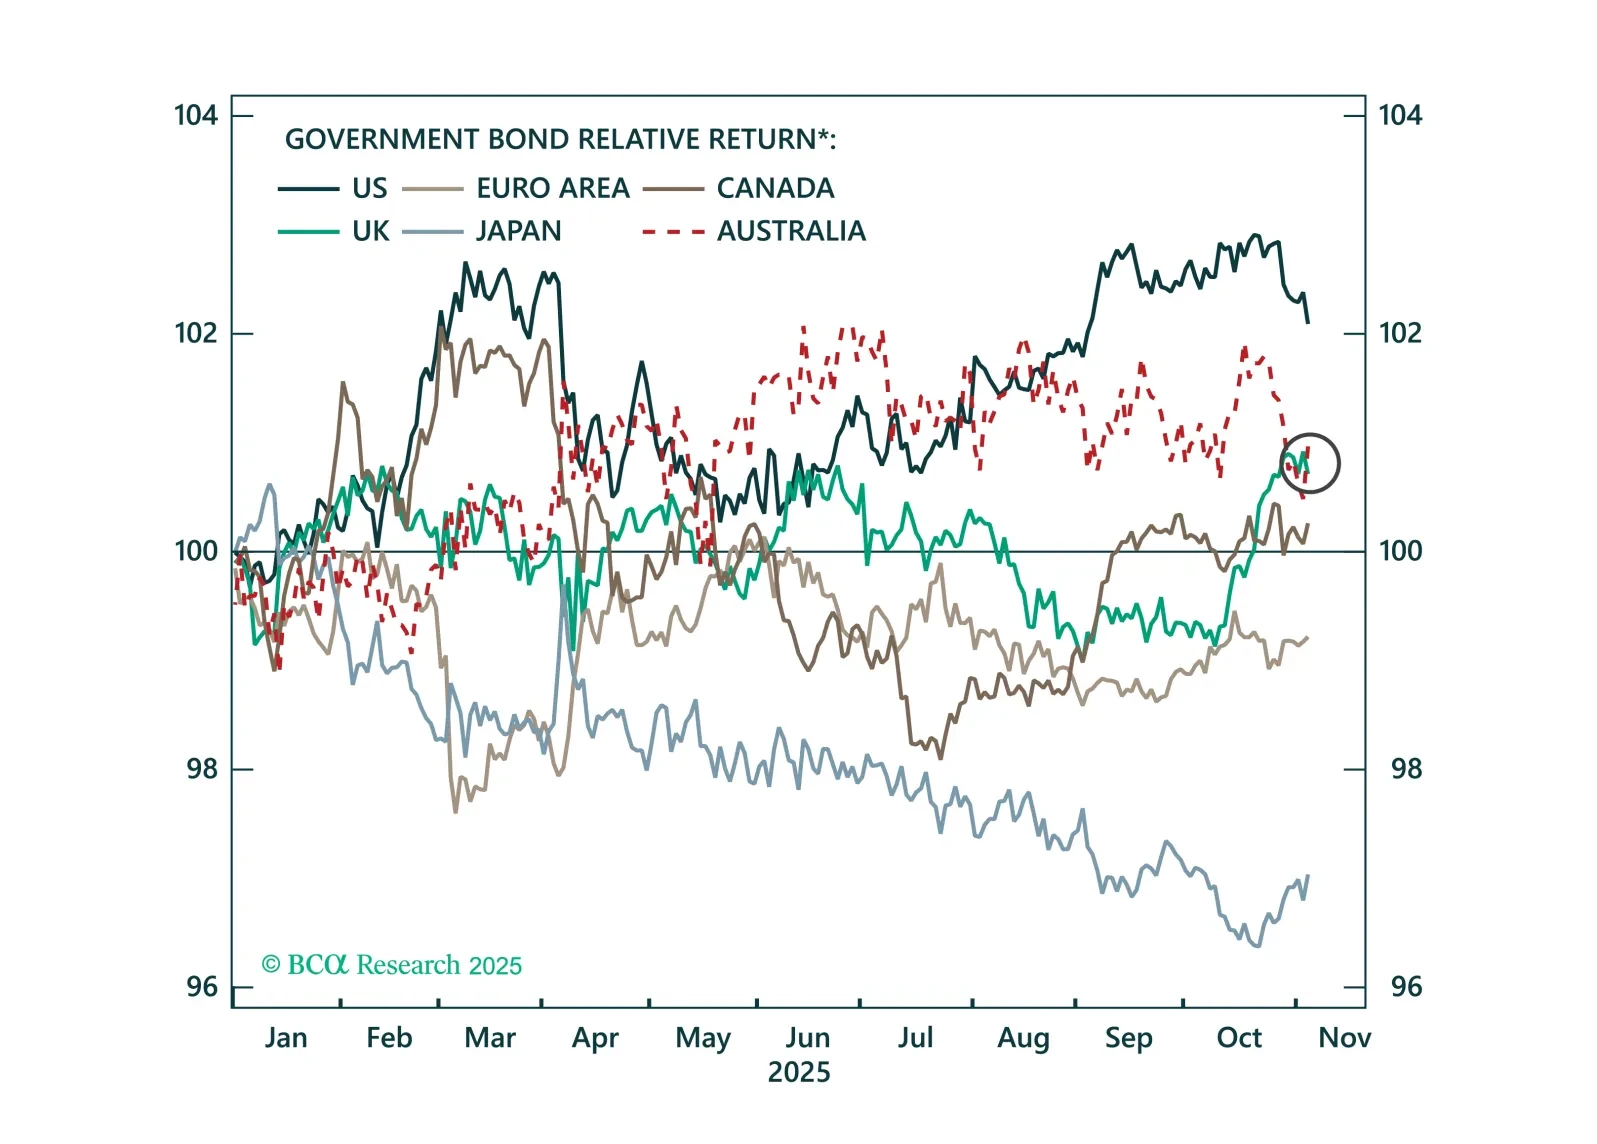
The Bank of England will resume rate cuts in December after the autumn budget is passed. Today’s Strategy Insight discusses what this means for UK gilts and the pound.