 Explore FICC
FICC | Commodities
Global macro commodity and energy coverage, combining top-down and bottom-up fundamental research. Typically published twice a month.
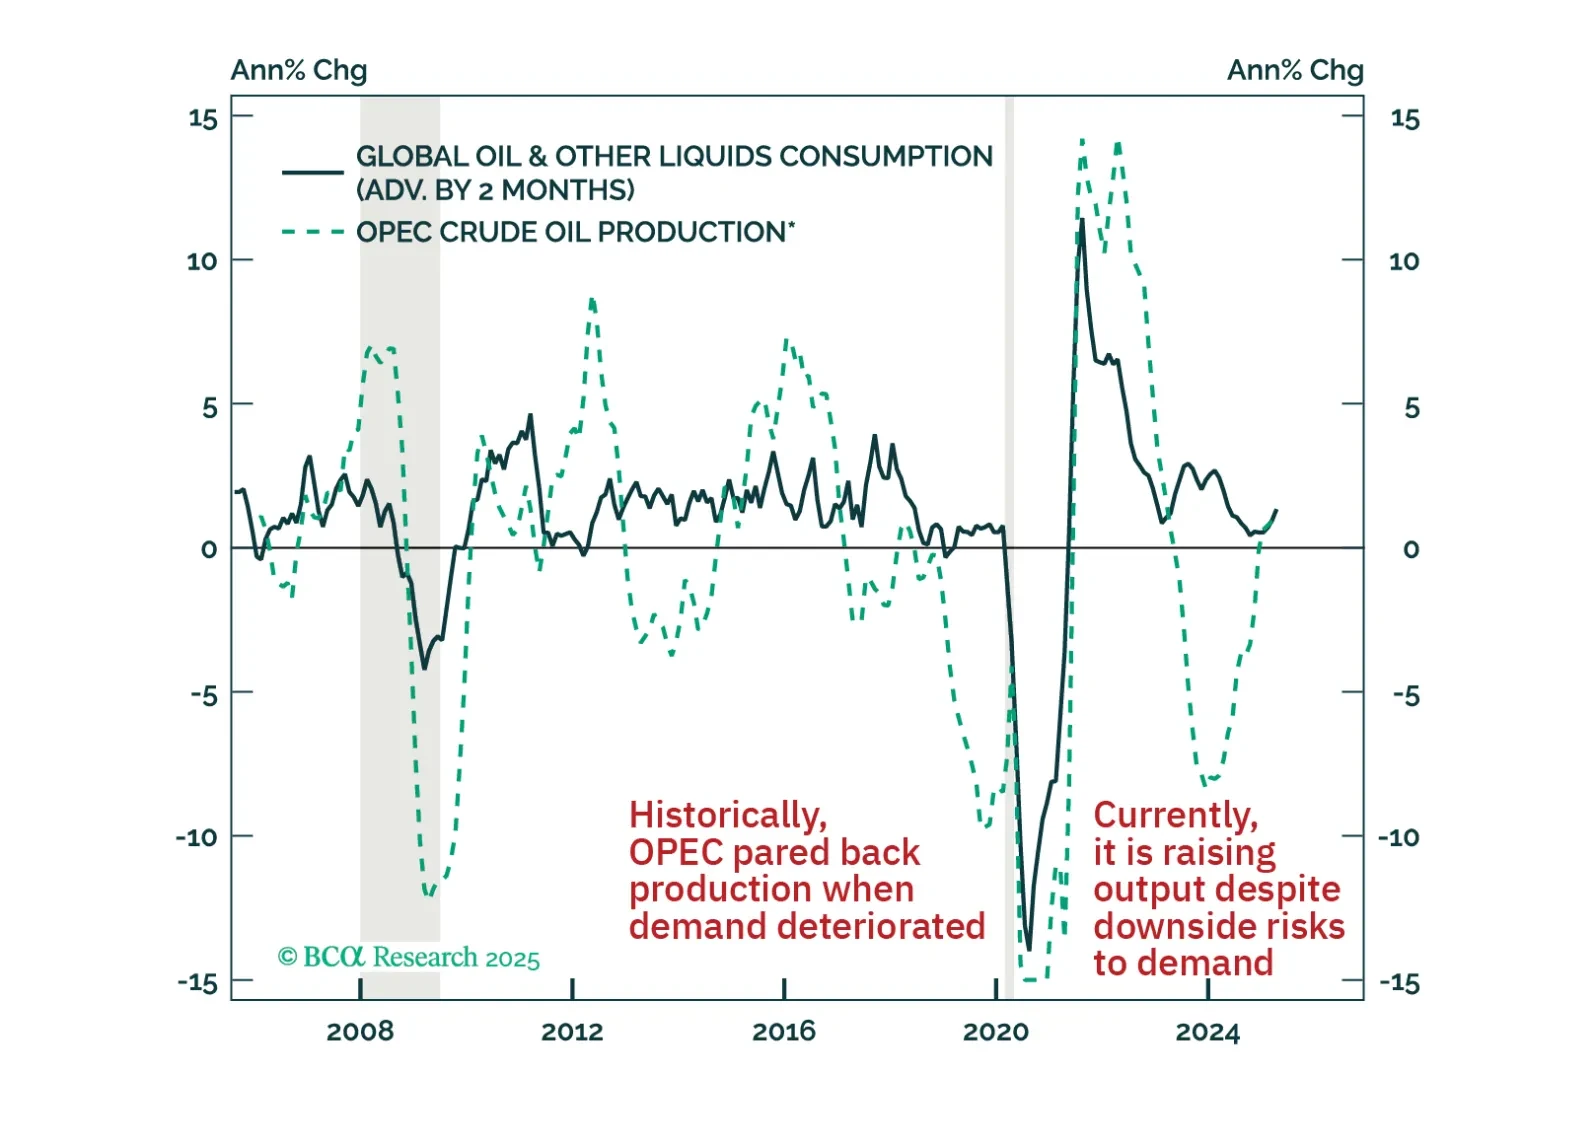
Oil has borne the brunt of the year-to-date deterioration in cyclically sensitive financial assets. It is a key underperformer both within the commodity space and among global risk assets. This underperformance underscores that in addition to the trade war-induced headwind to demand, bearish supply-side developments are also weighing down on crude prices. As we discuss in this report, these dynamics will likely continue exerting downside pressure on oil prices over the coming weeks and months.
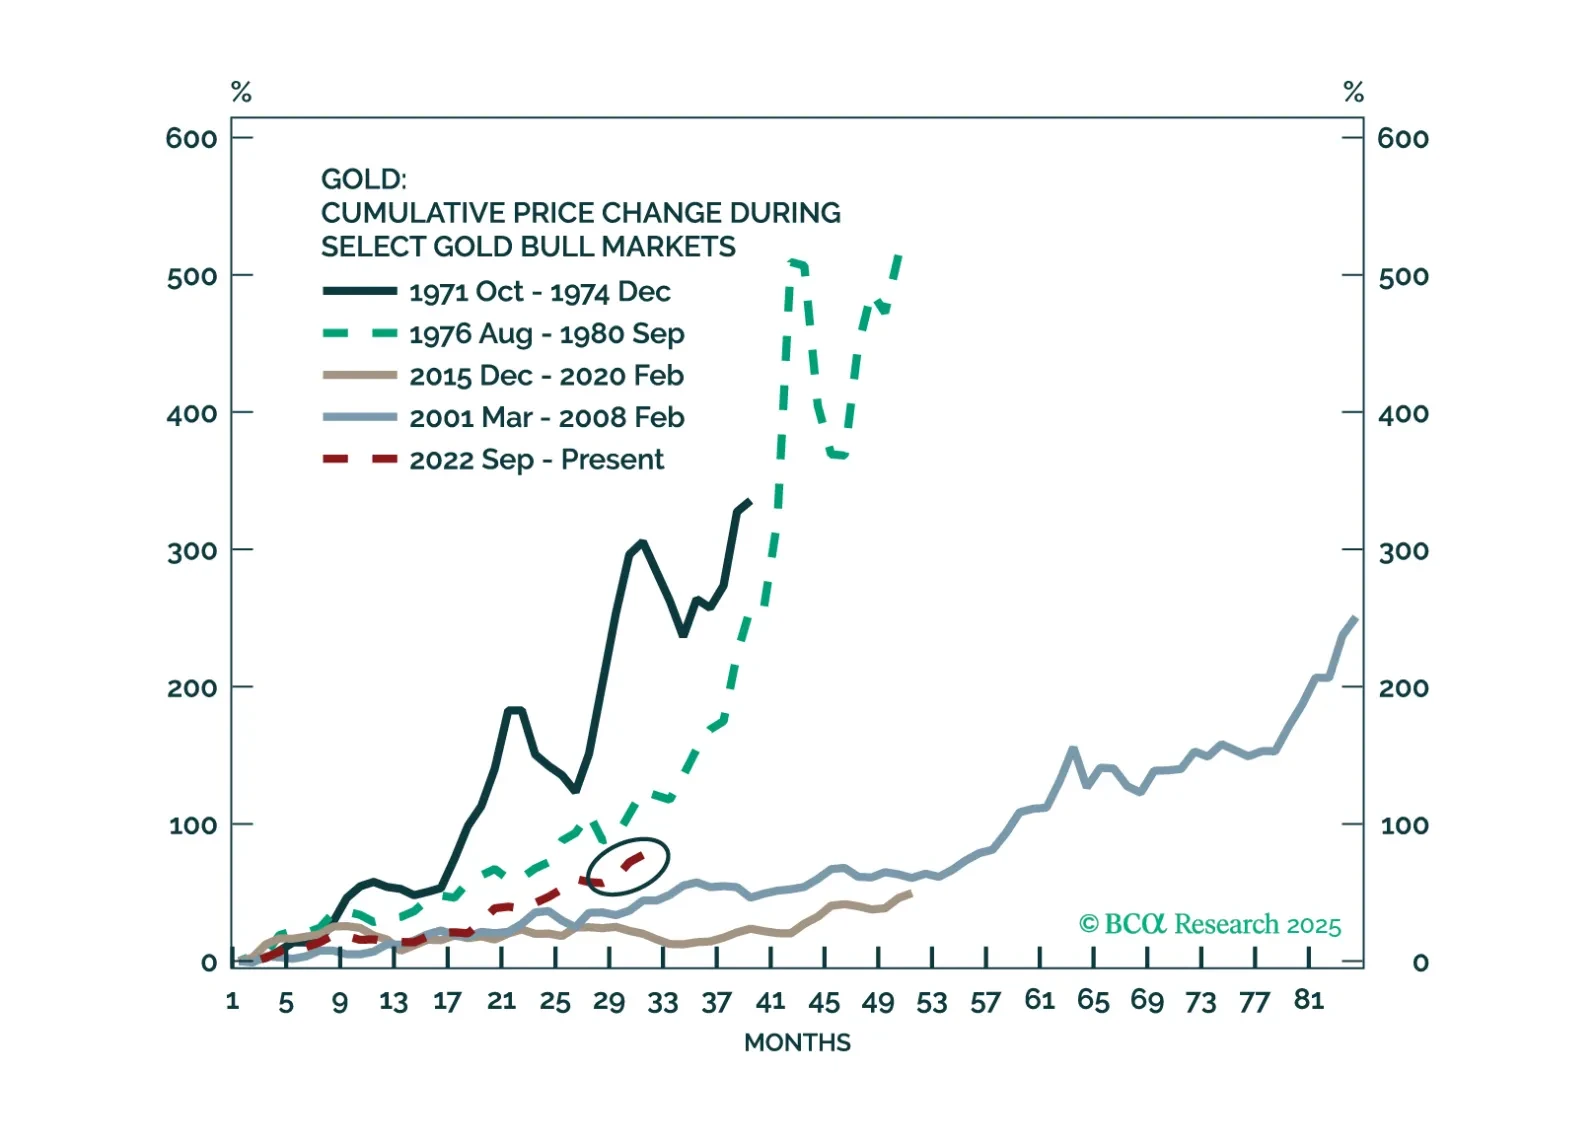
Commodities have not been spared the wrath of the post-"Liberation Day" selloff. However, in the sea of red, gold continues to shine bright, climbing to a fresh record high. How much further does the recent price action have left to run? We explore technical indicators to gauge the likely price outlook for gold, oil, and copper over the coming months.
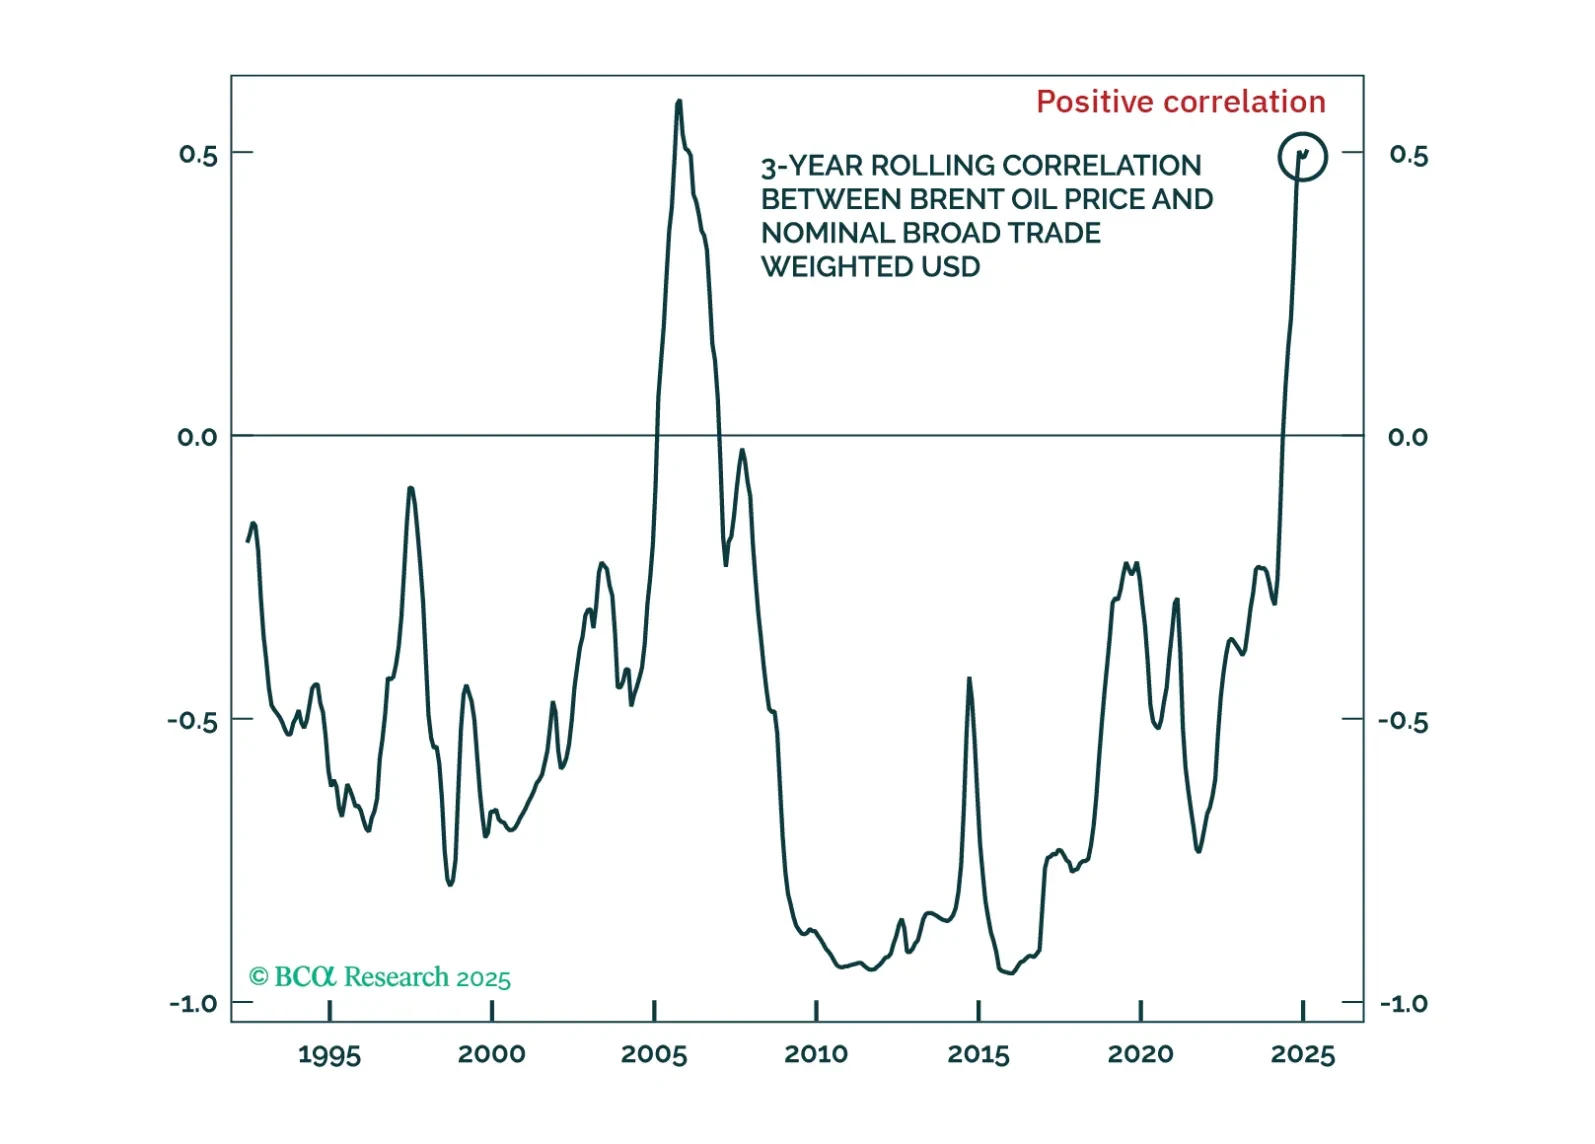
Commodity prices are succumbing to the risk-off environment triggered by President Trump’s reciprocal tariff announcement. The latest events and market moves raise several important questions about the outlook for commodity markets. In this Strategy Report we address some of the most pressing questions raised during our recent discussions.

In this month’s Beta report, we continue our series supporting our bullish thesis on Europe. We take a deep dive into the aftermath of the European energy crisis – dispelling the myth that Europe faces risks of imminent deindustrialization – and evaluate the impact the approaching LNG wave will have on European industry and the global natural gas market.
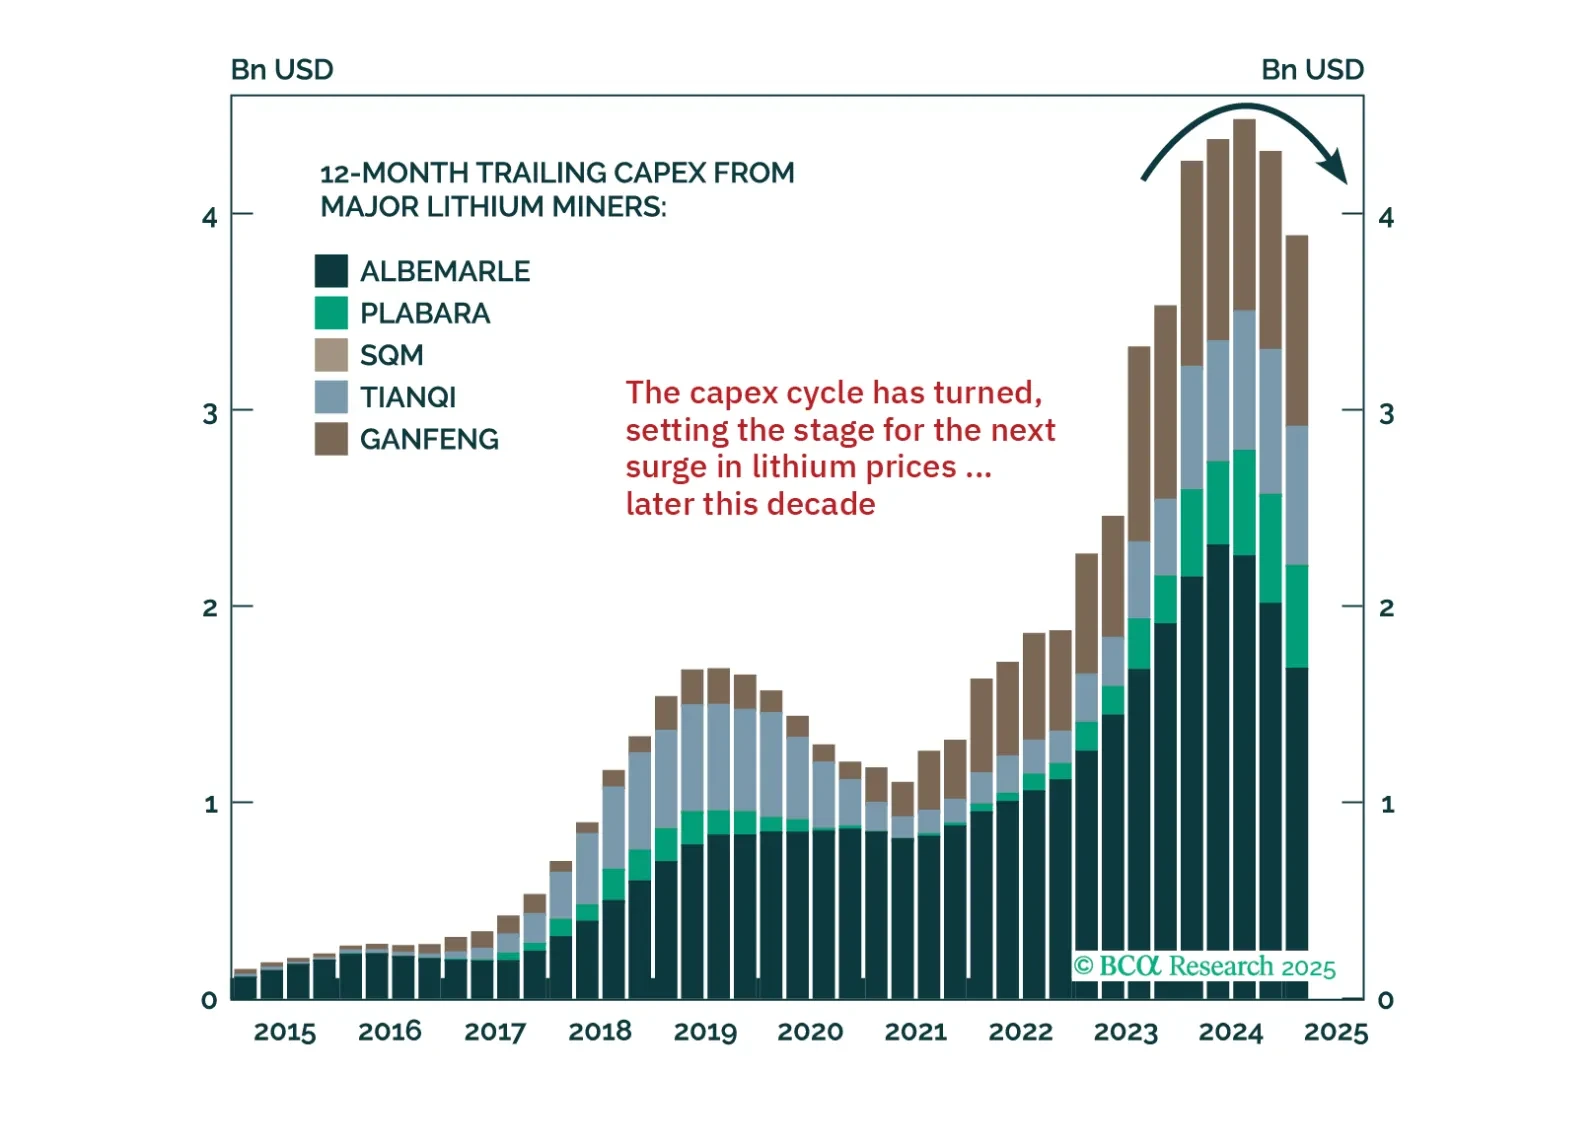
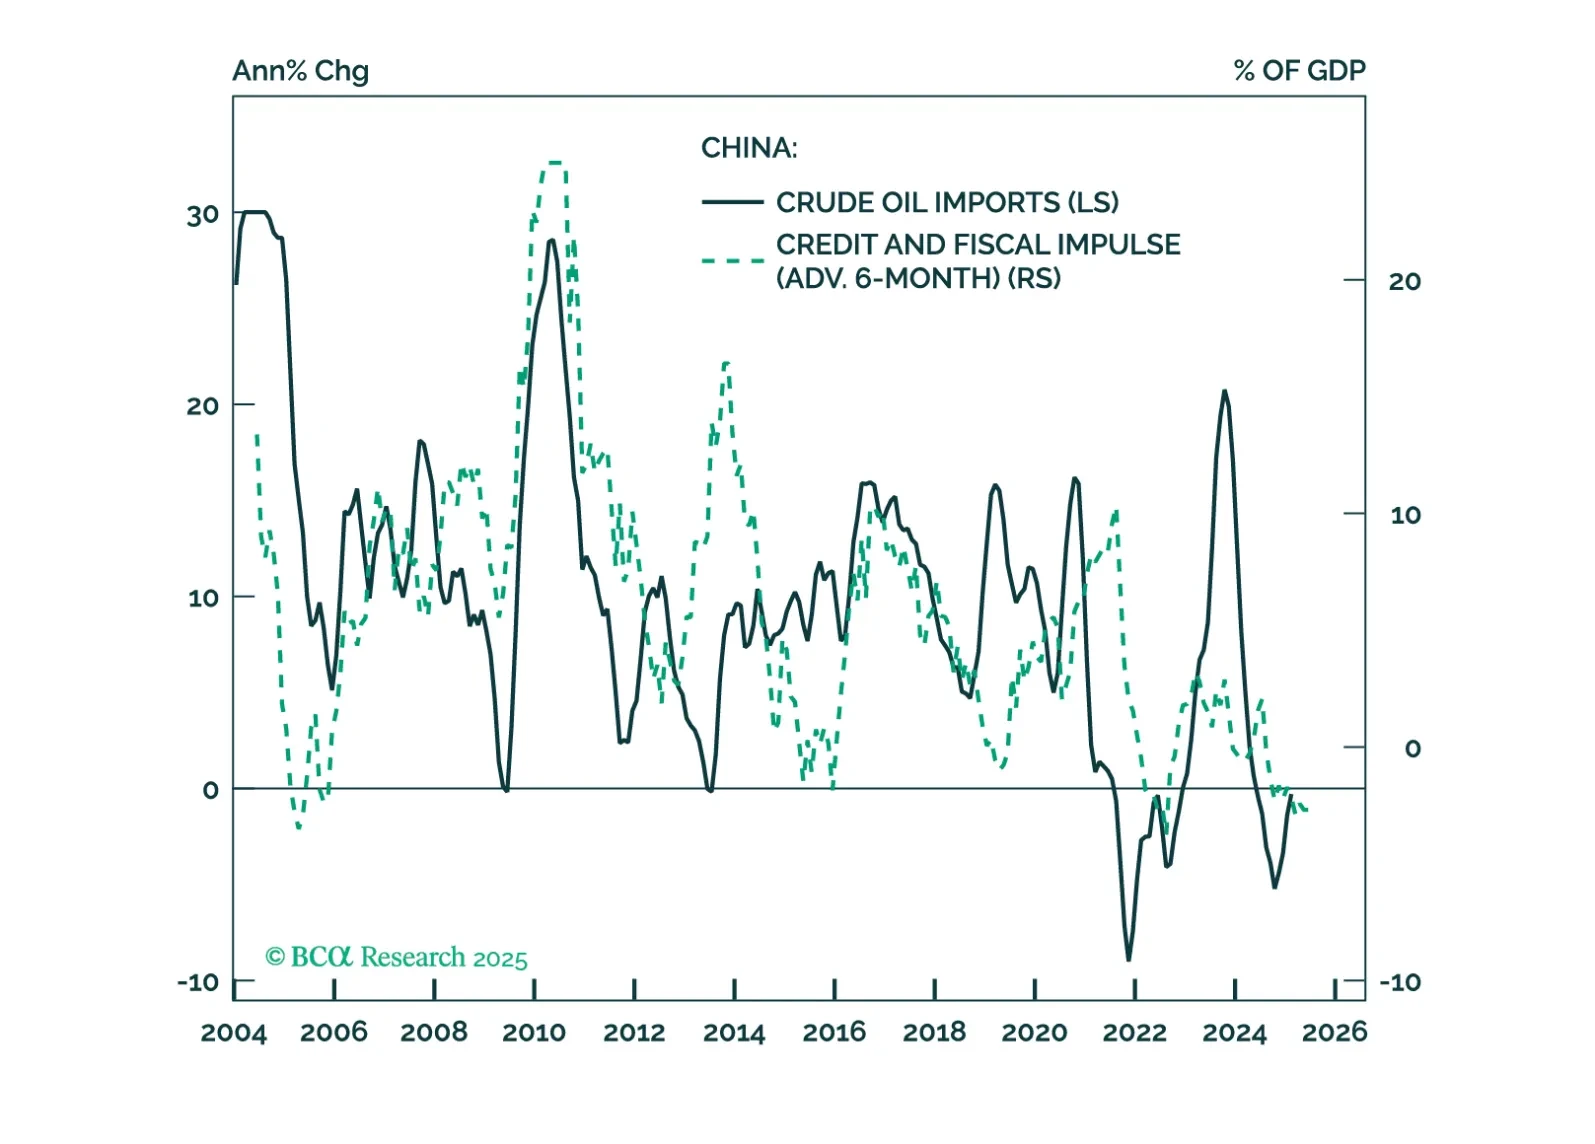
OPEC+ is planning to boost its crude oil output at a time of lingering demand weakness. What is driving this decision? And will Chinese oil consumption – historically a key contributor to global oil demand growth – reaccelerate and justify the coalition’s decision to bring back more supply to the market? This report answers these questions and more.
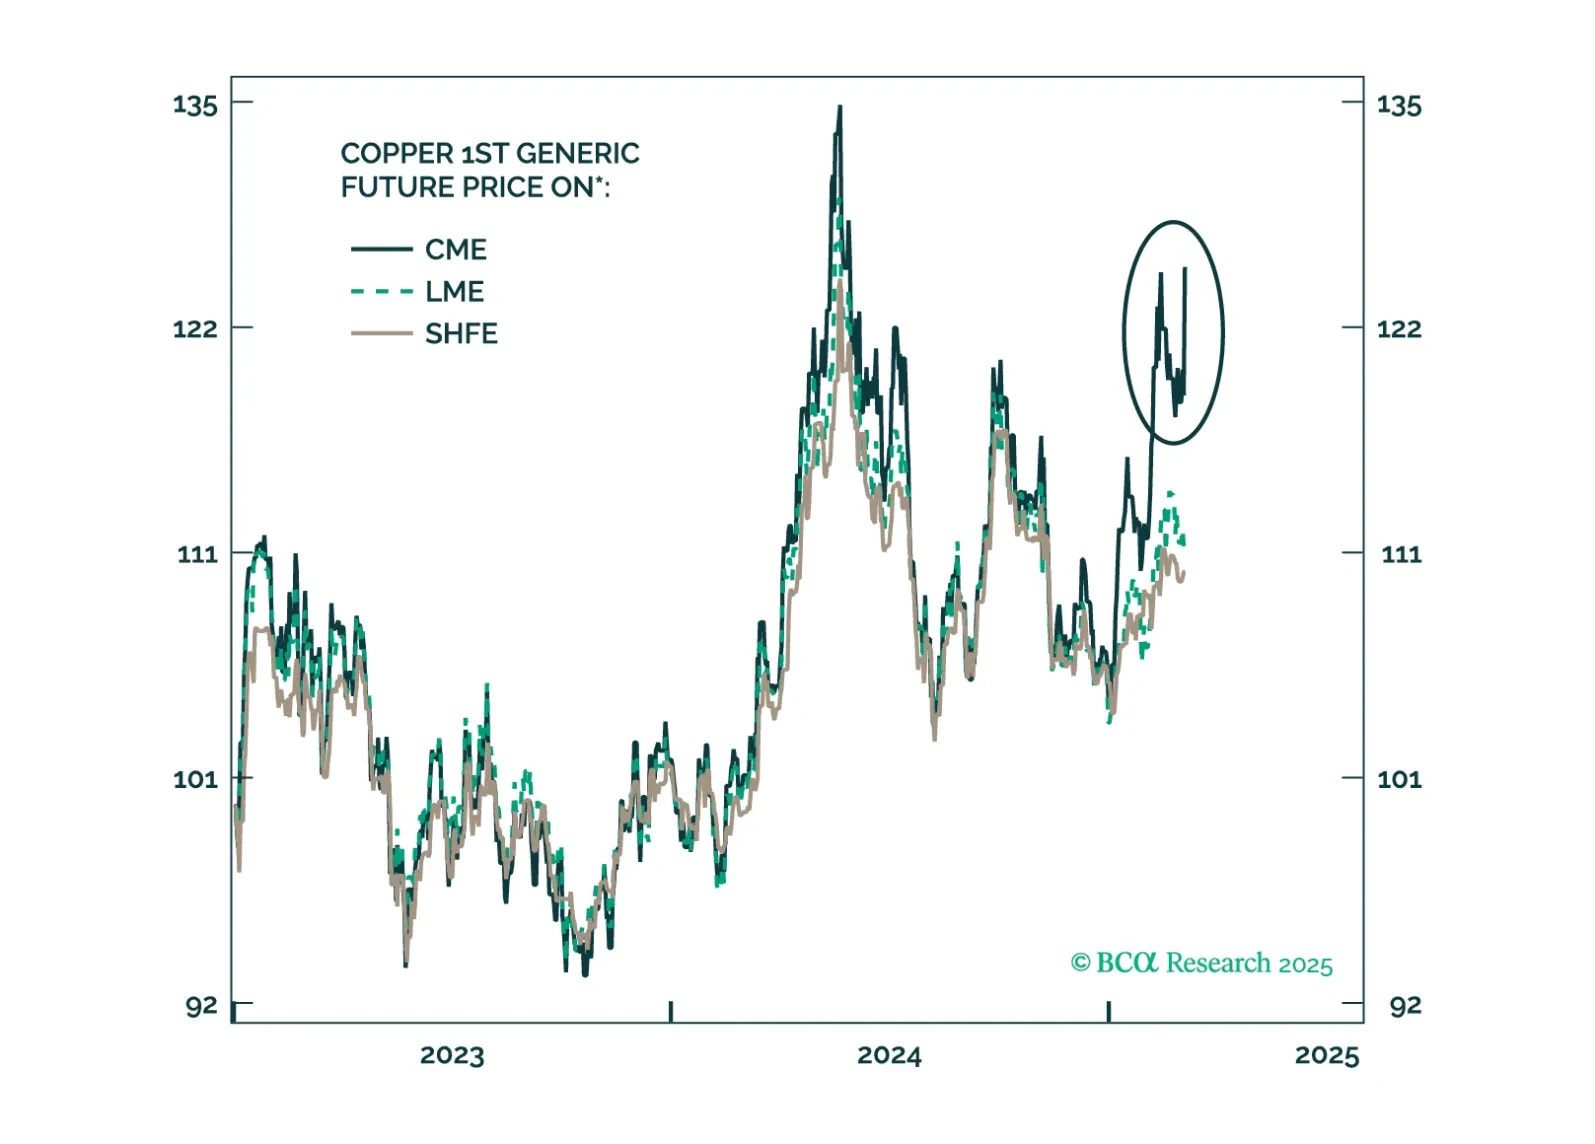
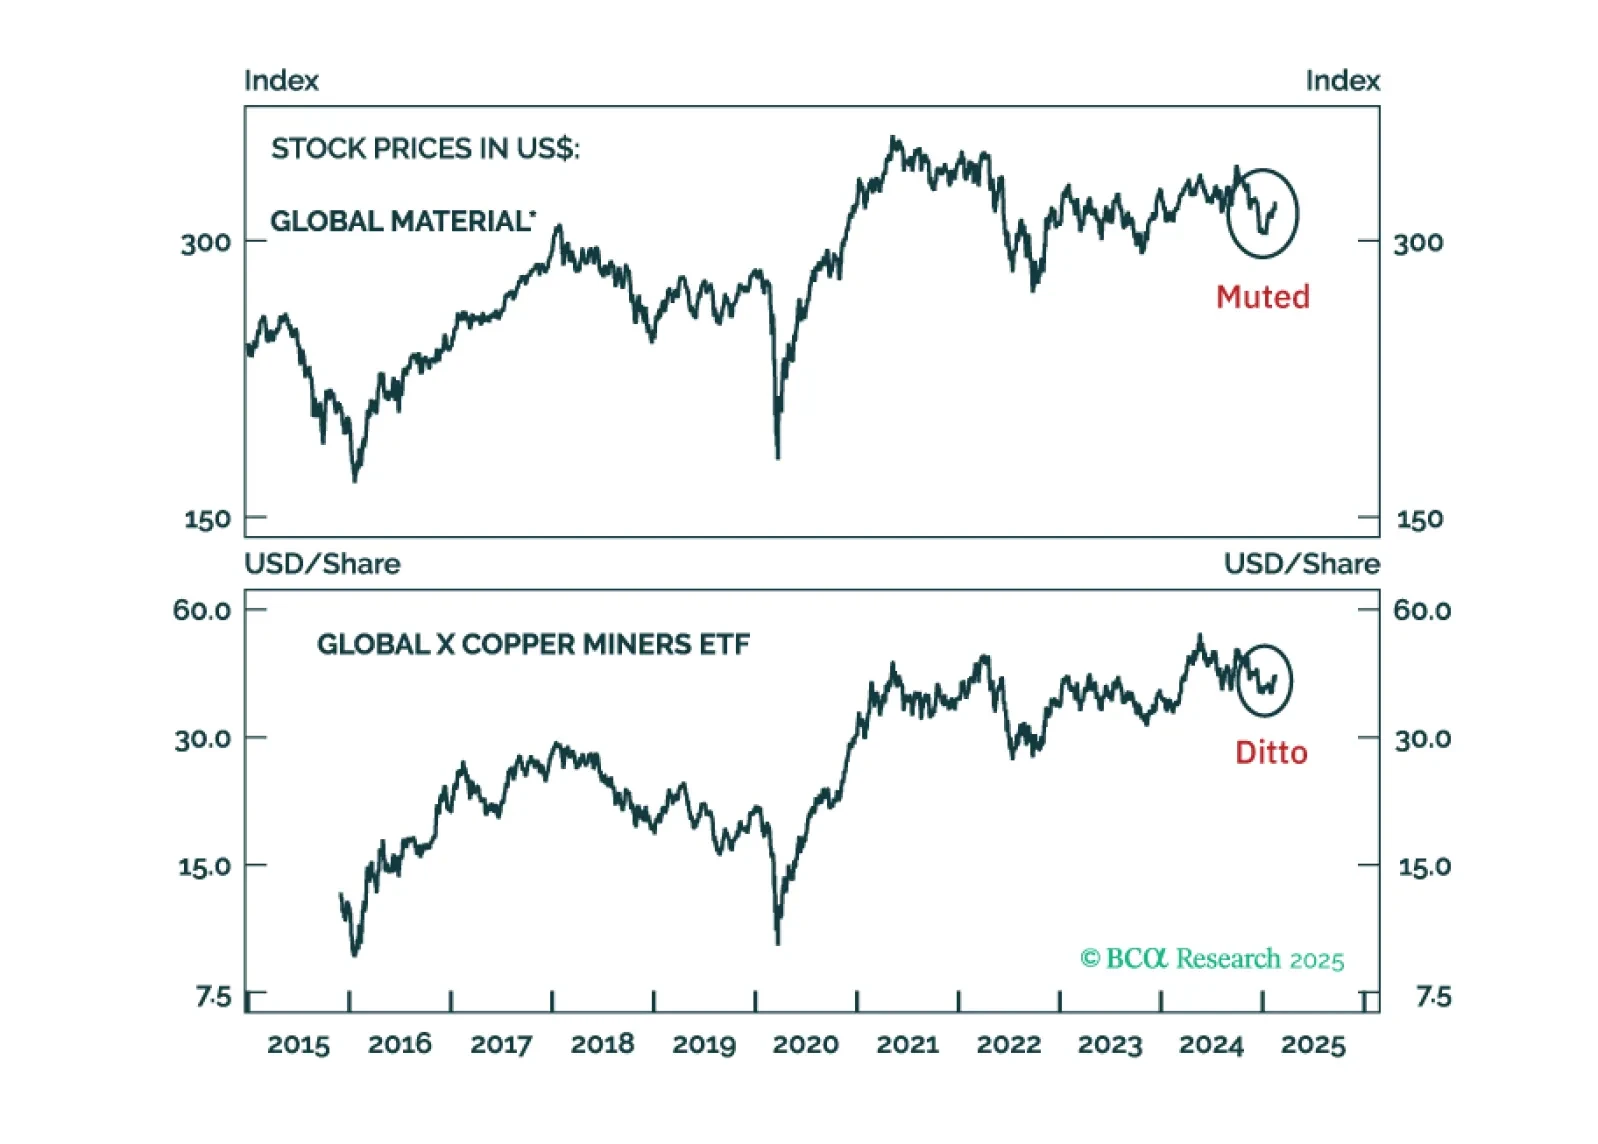
Expectations of US import tariffs drove the latest upleg in the prices of precious and industrial metals. However, there are no significant economic or political incentives for the US to impose import tariffs on these metals. Therefore, investors should fade the recent spike in gold, silver, platinum and copper prices. We are initiating a short position on silver as a tactical trade.
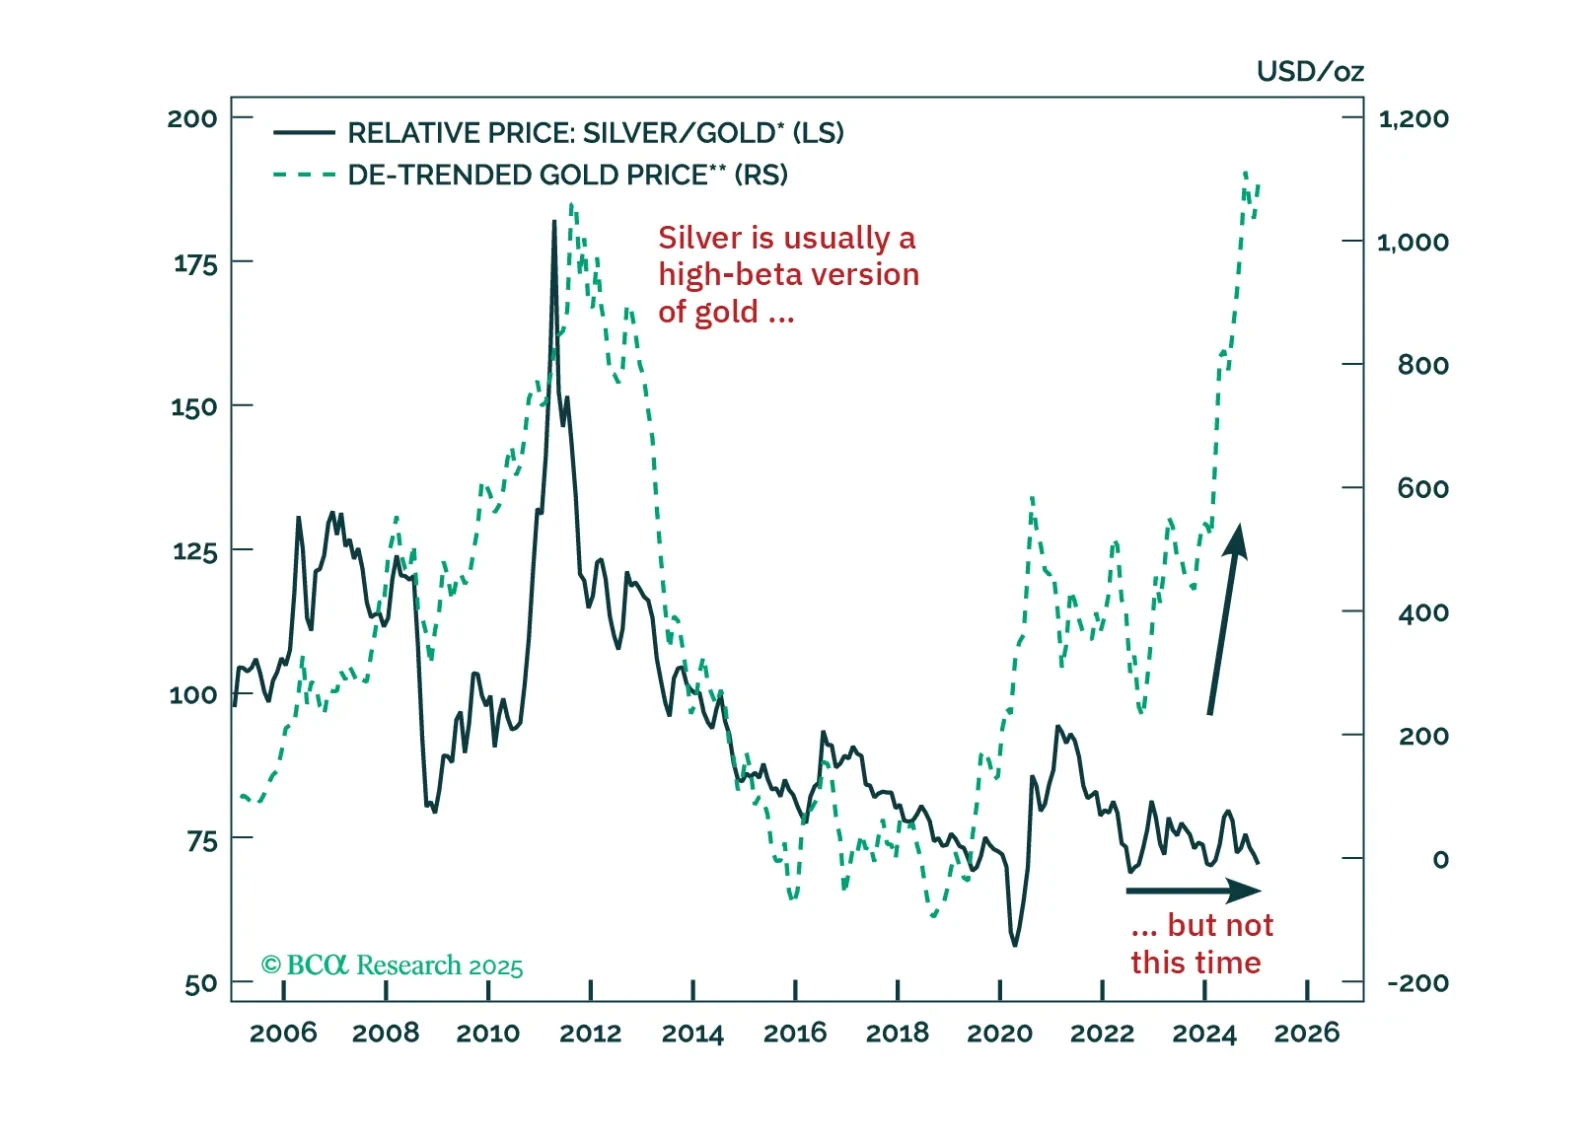
Last week’s tariff debacle kicks off a period of heightened global policy uncertainty under the new US administration. That is bad news for financial assets exposed to the business cycle. Meanwhile, it creates an opportunity for safe-haven assets to shine. Gold is capturing headlines for soaring to fresh record highs. Yet, what about the other precious metals? In this report, we argue that not all precious metals are created equal.
