Skip to main content
Explore CoreMacro

CoreMacro | Europe

Europe-focused research - including  in-depth country reports. Typically published twice a month.  
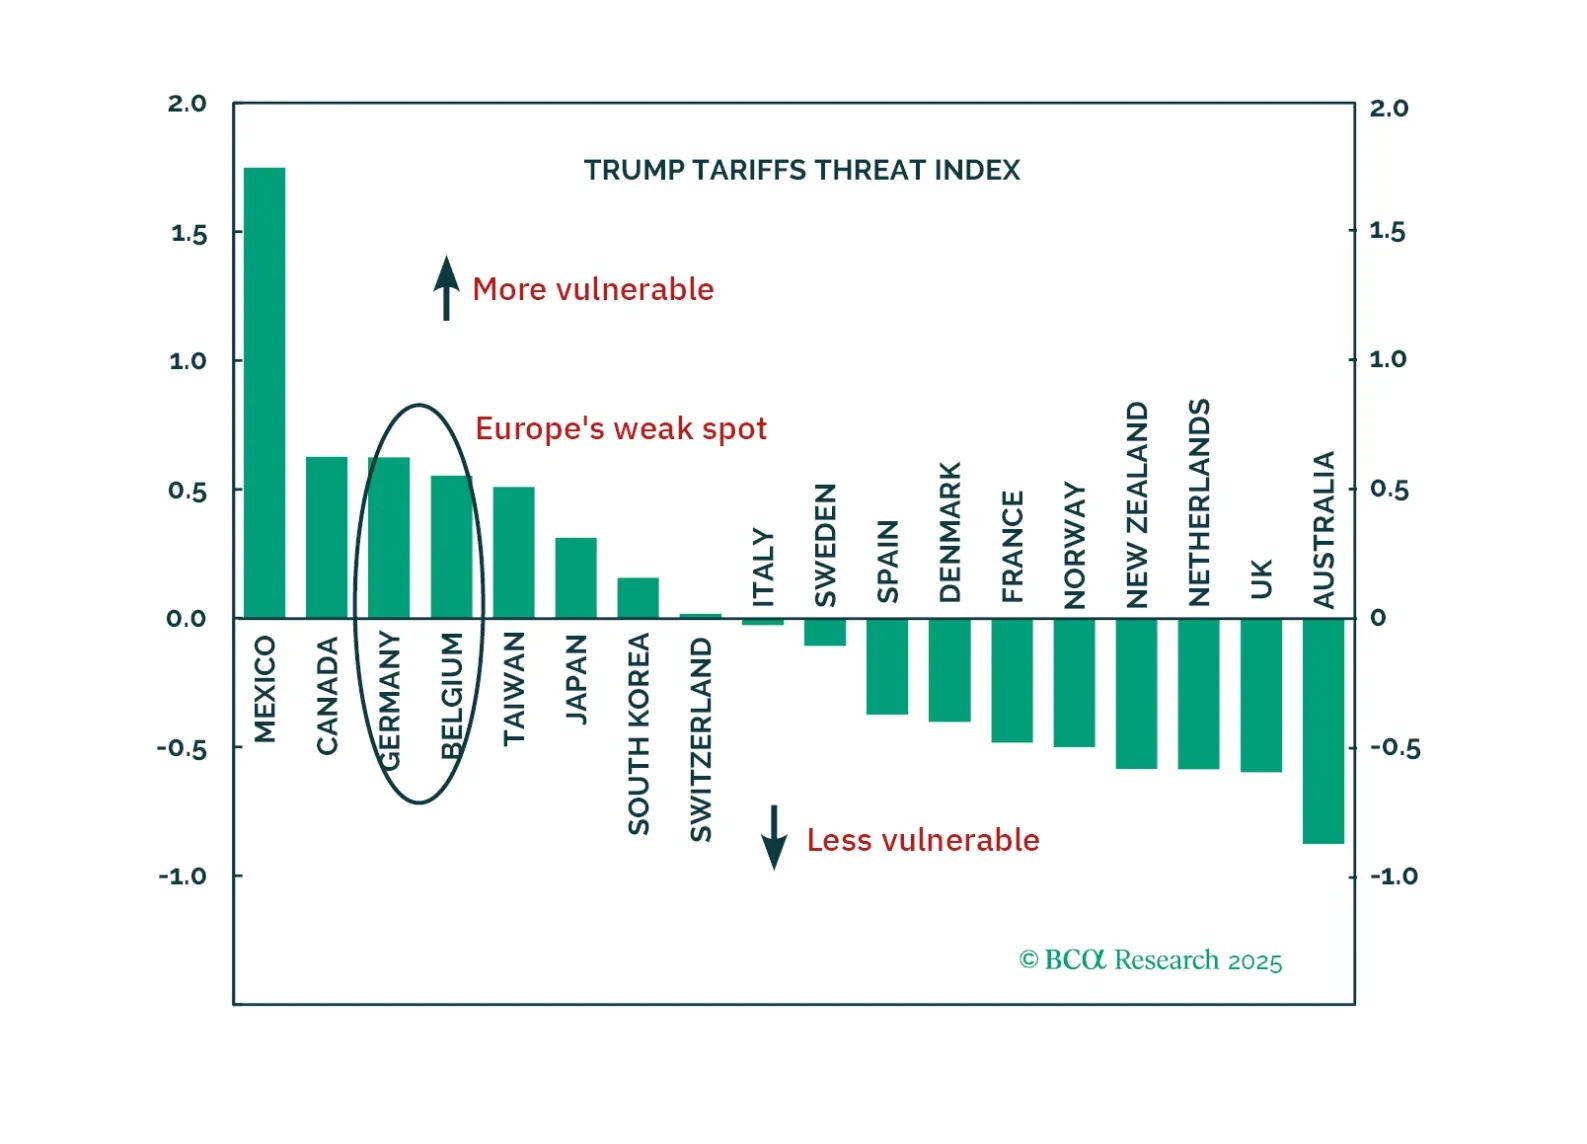
President Trump is about to be inaugurated. Investors often assume all his policies will hurt Europe, but the reality is more nuanced.
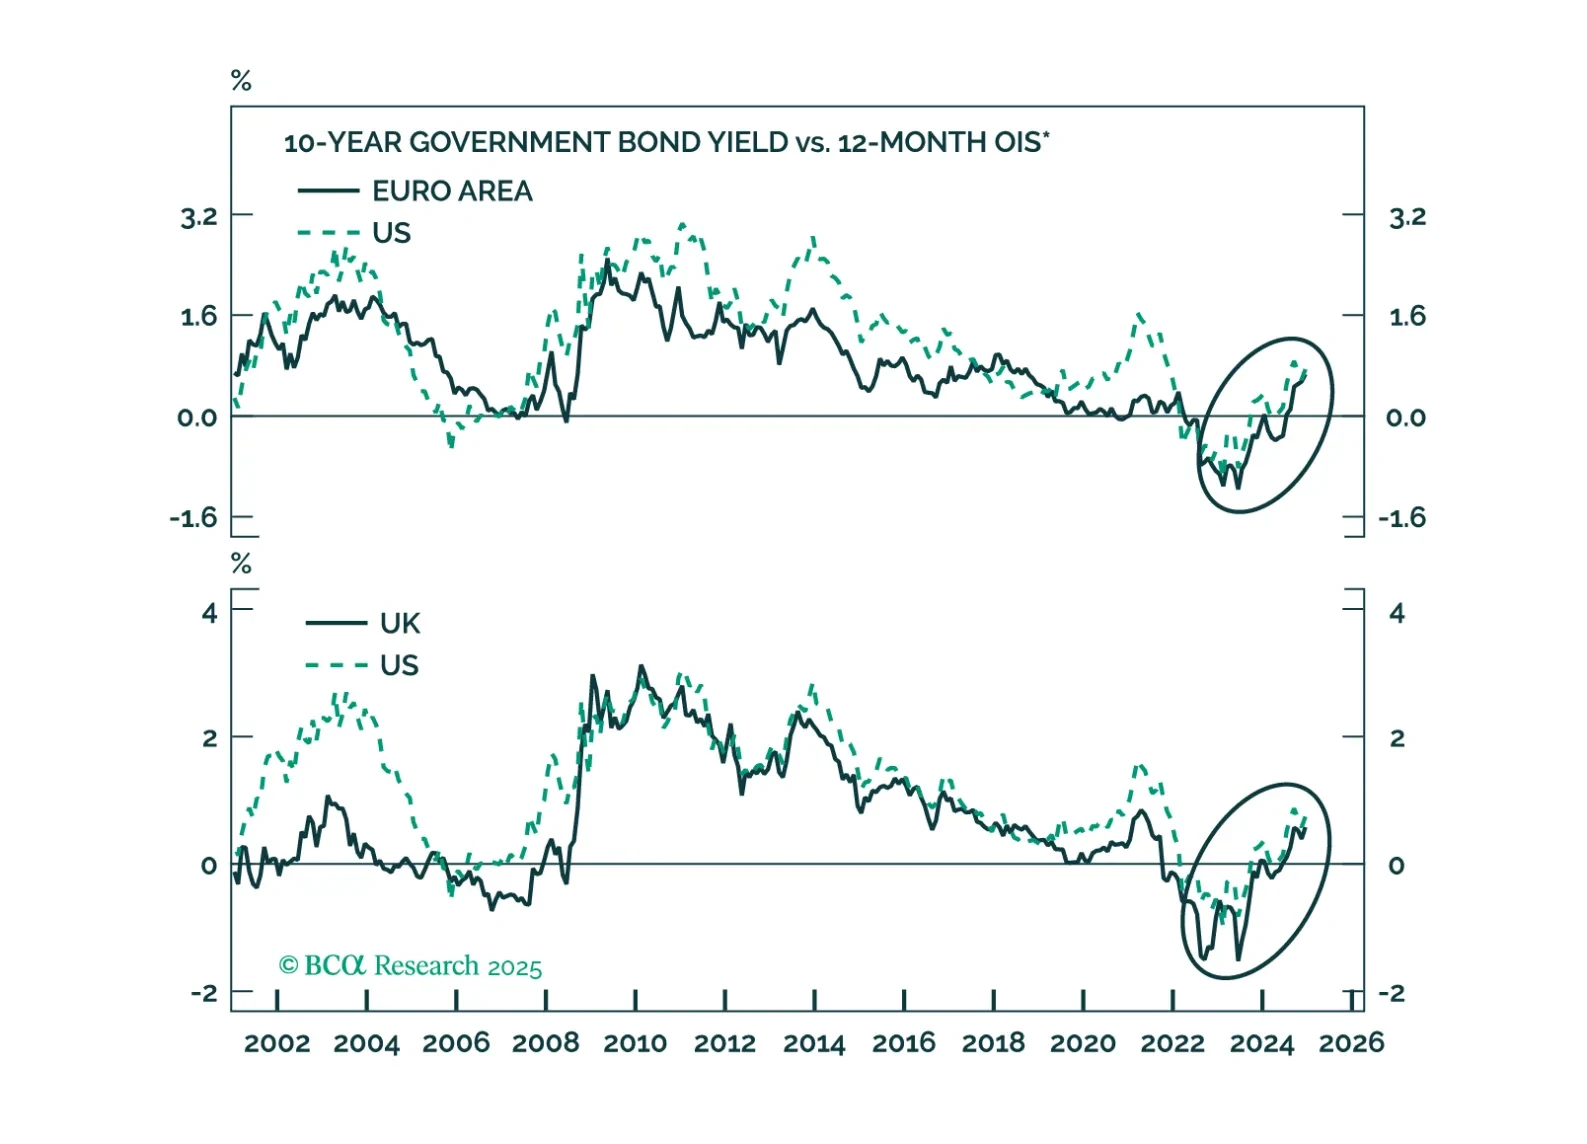
UK and German bonds are victims of the global bond market riots. Will European yields continue to move higher and will the euro and the pound find a floor anytime soon?
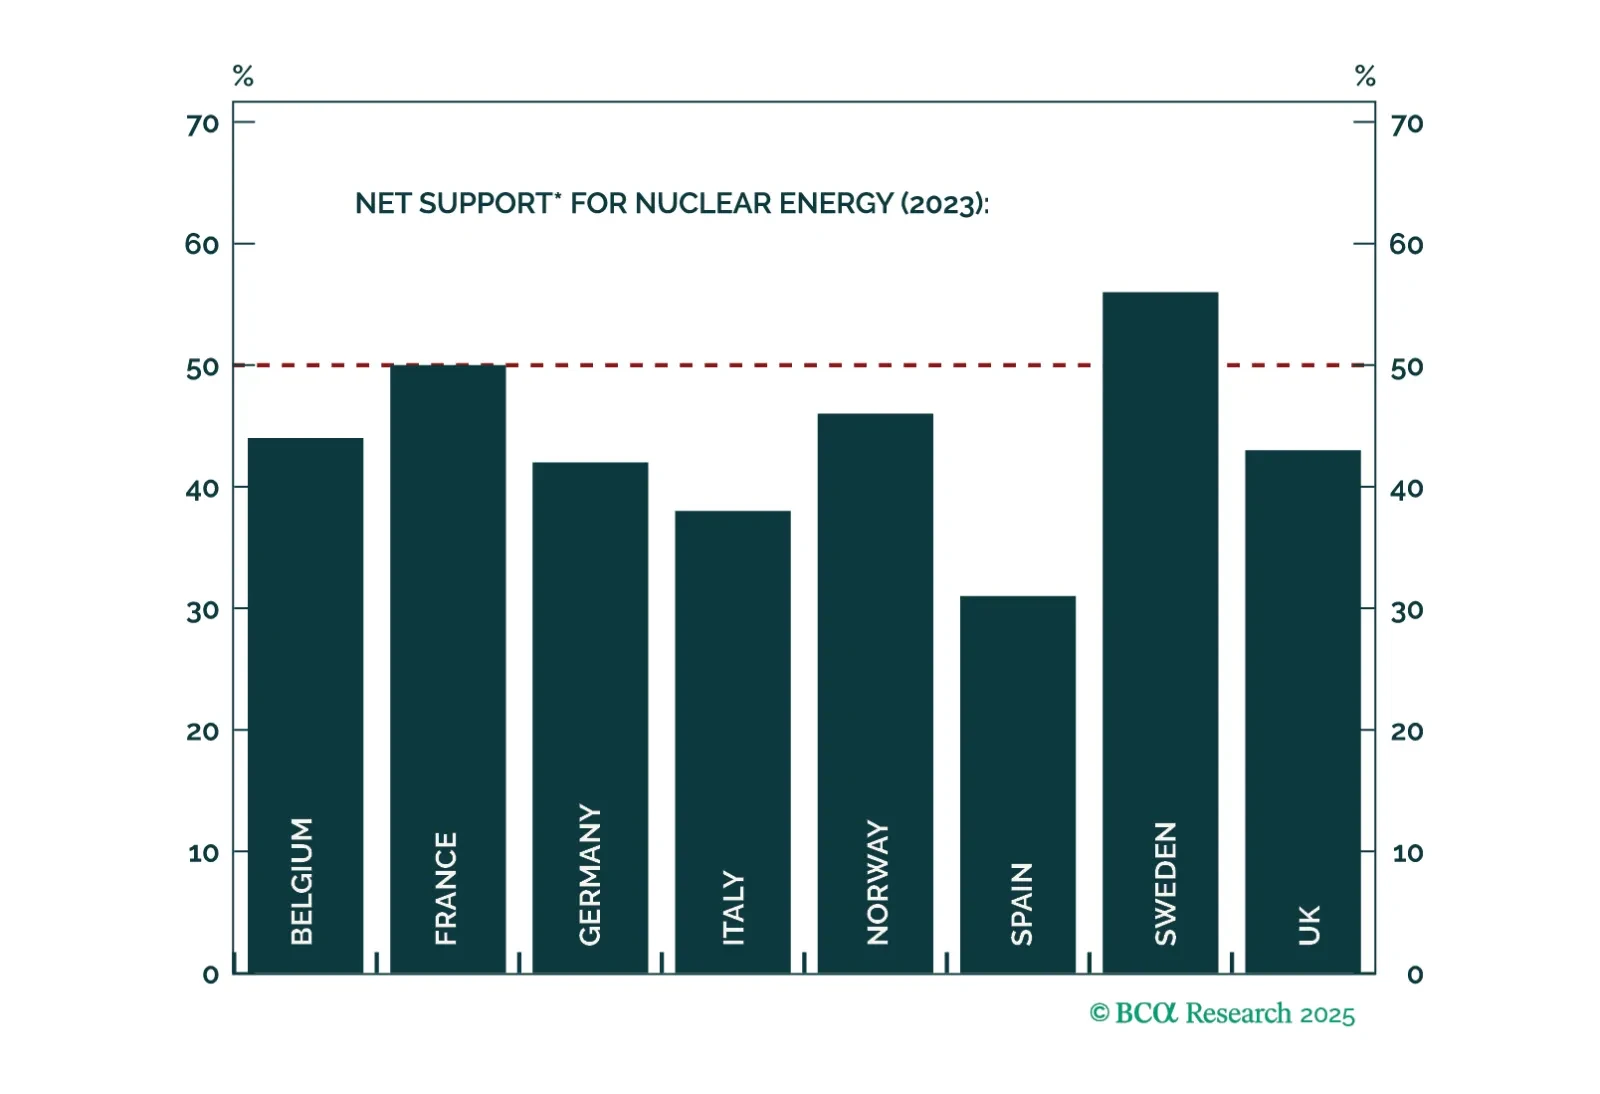
Special Report This report takes you on a tour of Europe’s nuclear energy industry, assessing its current situation and possible future.
Special Report This year, our annual "What Else To Read" report focuses on academic work. We asked our research teams to share academic work that has influenced their thinking. The result is a diverse collection of papers and books that span investing, economics and geopolitics. We hope you will find something in this report that broadens your perspective and inspires your work in the year ahead. As always, we wish you all a joyful holiday season and a prosperous and healthy 2025.
Special Report For our last publication of the year, we explore five key themes that will dominate the European macro landscape and markets next year. While the start of 2025 will be challenging for European assets, the latter part will offer some much-needed relief.
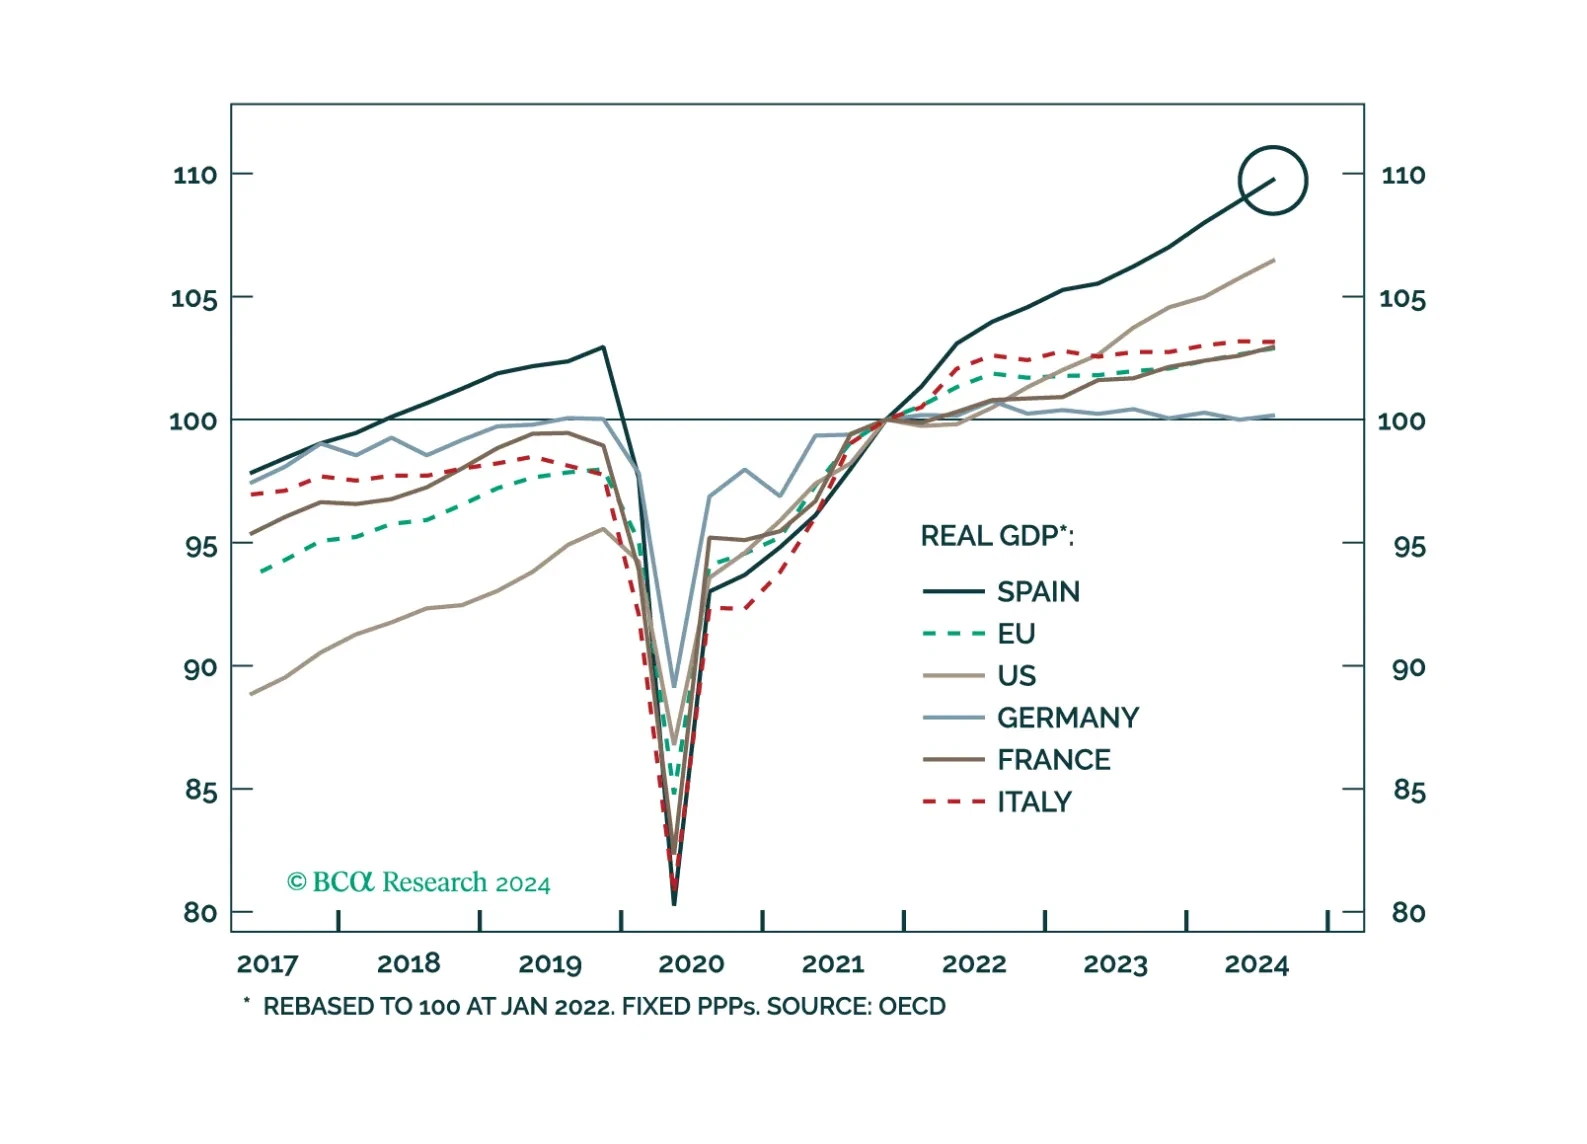
Special Report Spain has outperformed most developed markets since 2022 – real economic output and risk assets alike. Can it last?
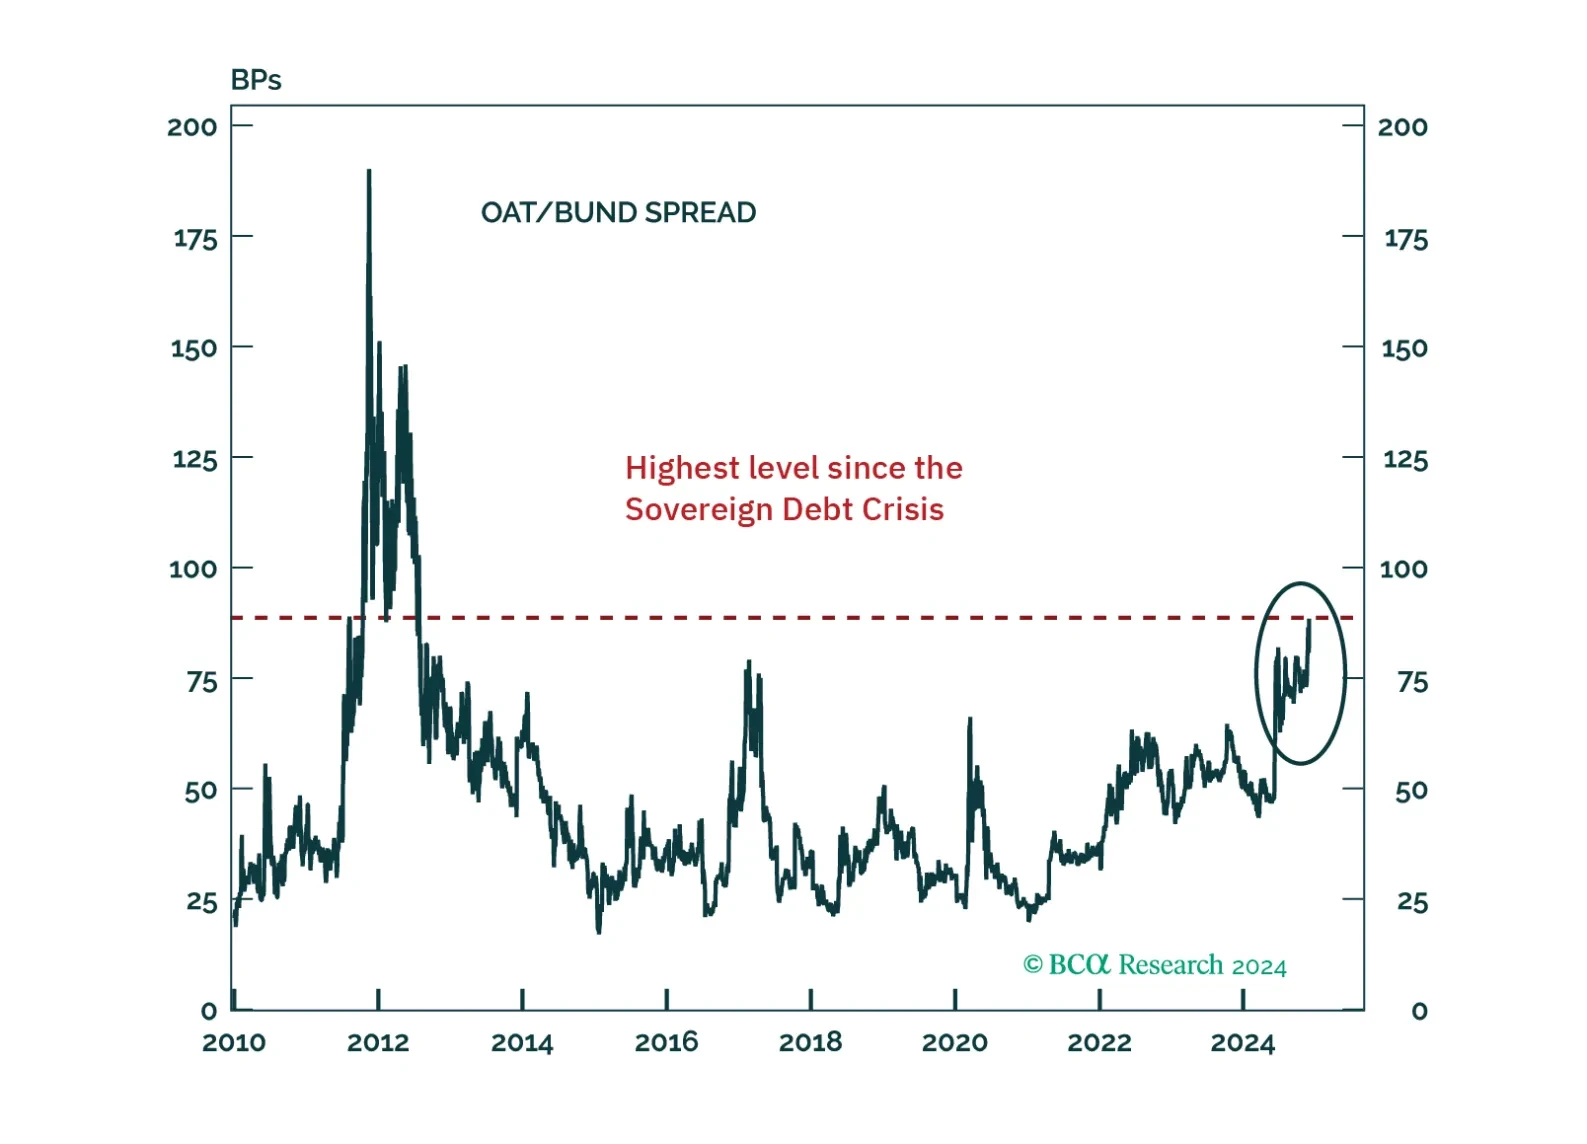
France finds itself in a unique, thorny situation. Can it heave itself out of it? And what does it mean for investors?
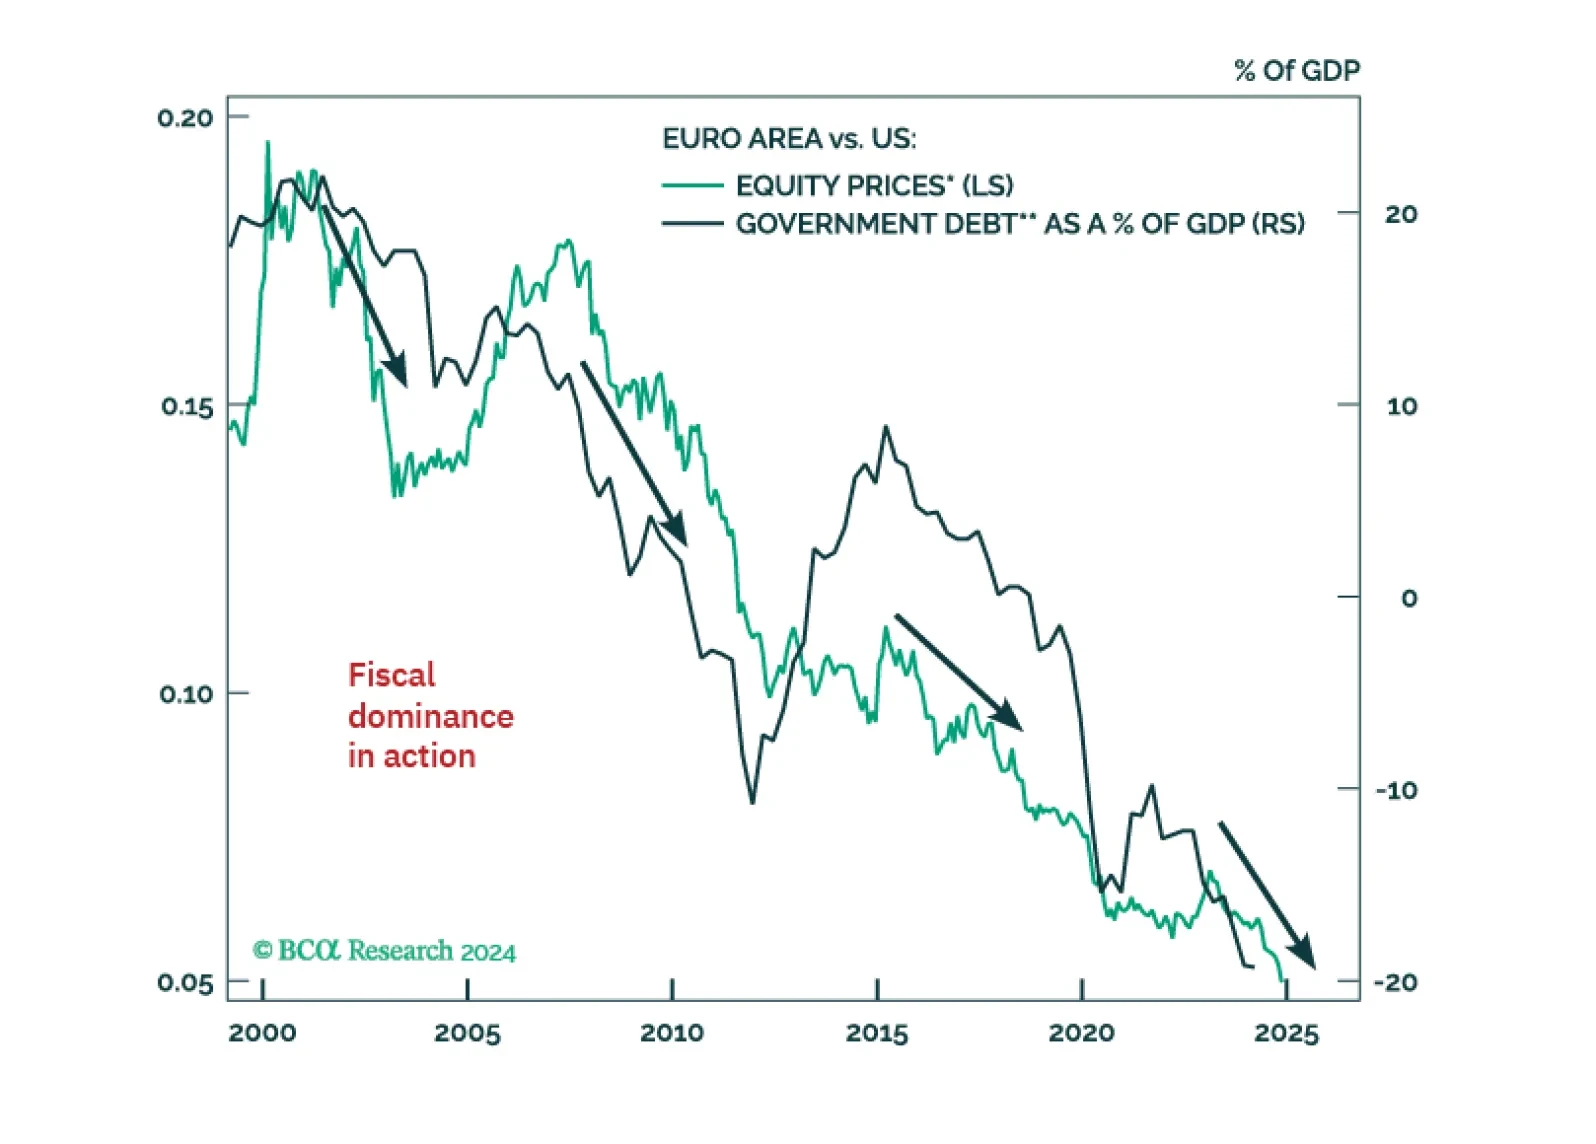
Investors have given up on European assets, which now suffer exceptional discounts to US ones. However, tighter US fiscal policy, the end of Europe’s austerity and deleveraging, the LNG Tsunami about to hit European shores, and the global capex fueled by the Impossible Geopolitical Trinity mean that Europe’s time to shine will soon come back.
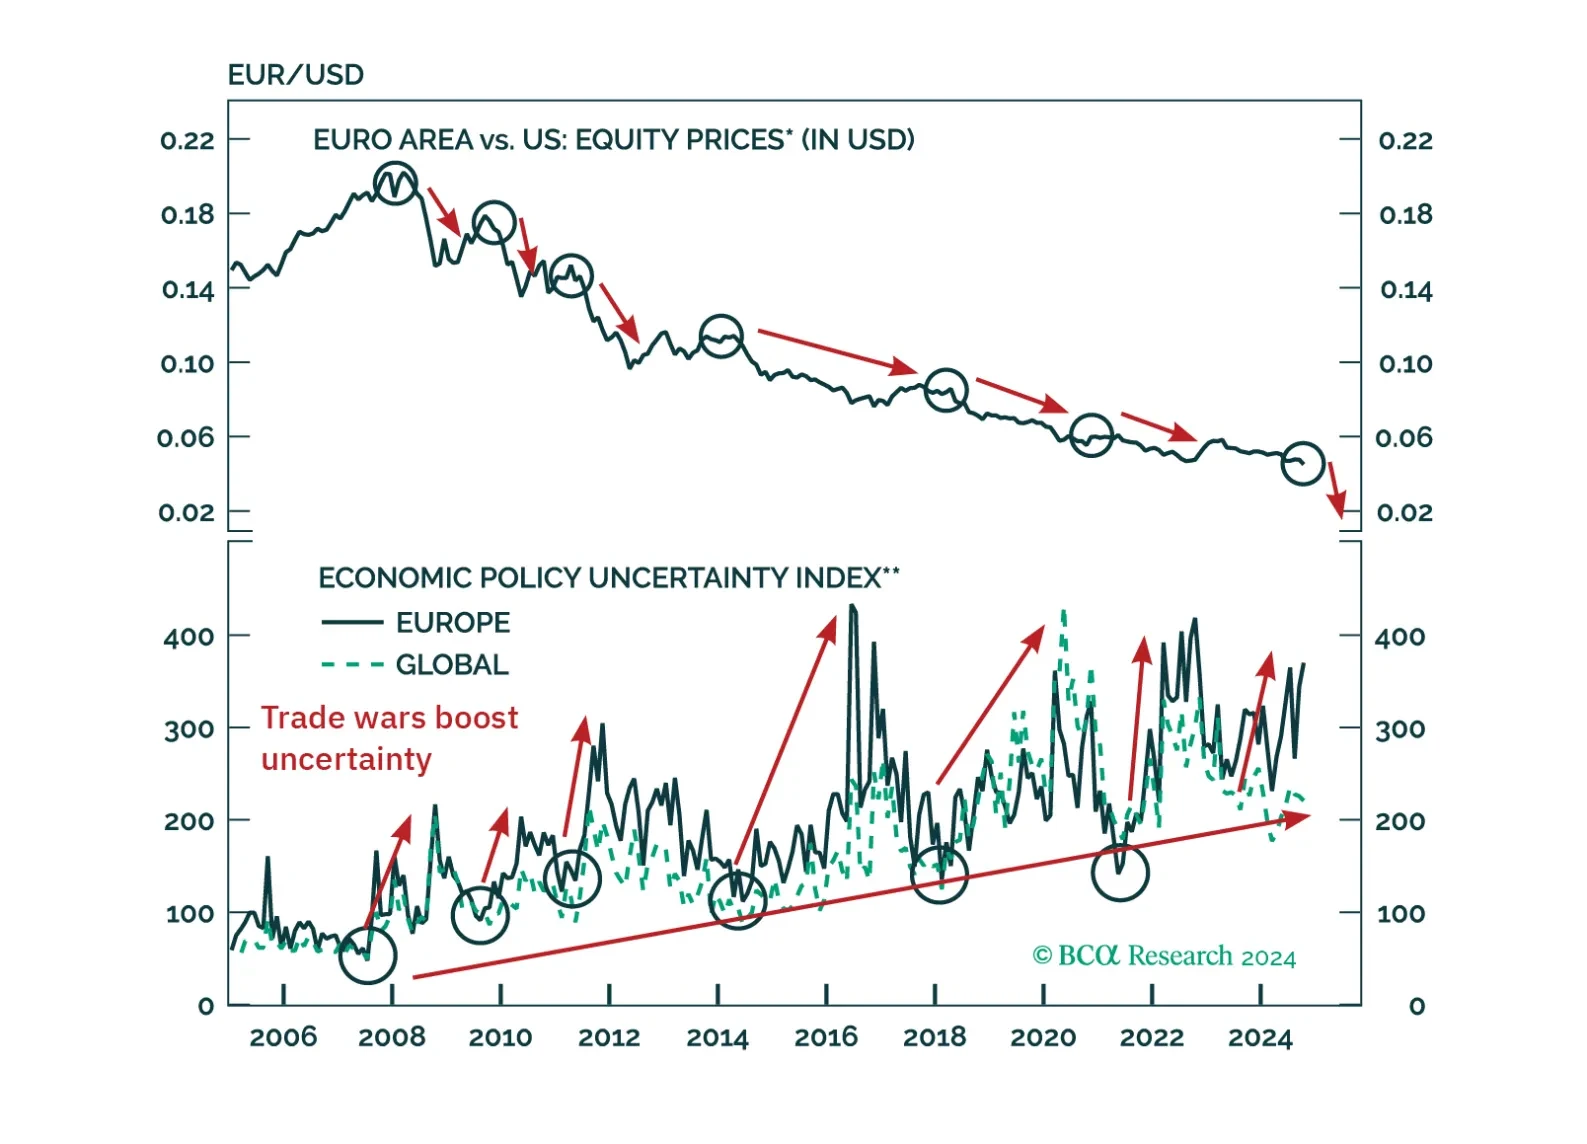
Special Report Investors have given up on European assets, which now suffer exceptional discounts to US ones. However, tighter US fiscal policy, the end of Europe’s austerity and deleveraging, the LNG Tsunami about to hit European shores, and the global capex fueled by the Impossible Geopolitical Trinity mean that Europe’s time to shine will soon come back.
European assets and the euro have become oversold and are likely to rebound. Will this move be nothing more than a dead cat bounce leading to more weakness?