Monetary Policy
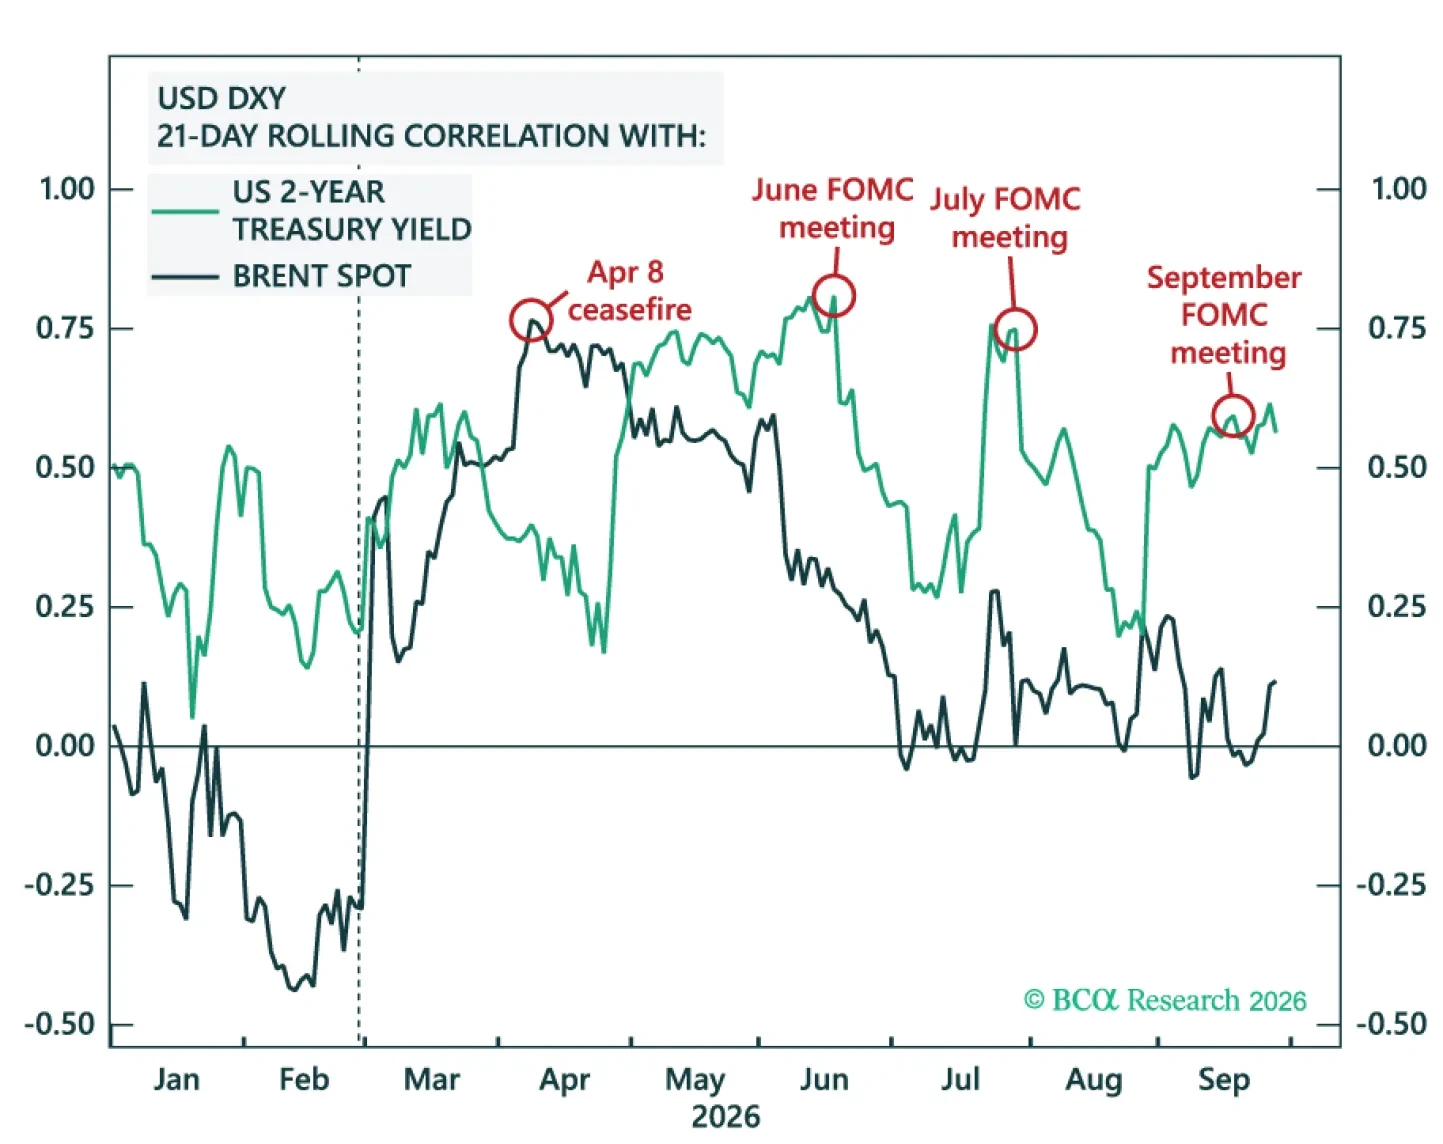
Global capex is driving the strongest industrial cycle since 2021. The US is best positioned to capture the gains and to weather near-term risks, supporting widening real-rate differentials and favoring continued upside in the dollar in the coming months.
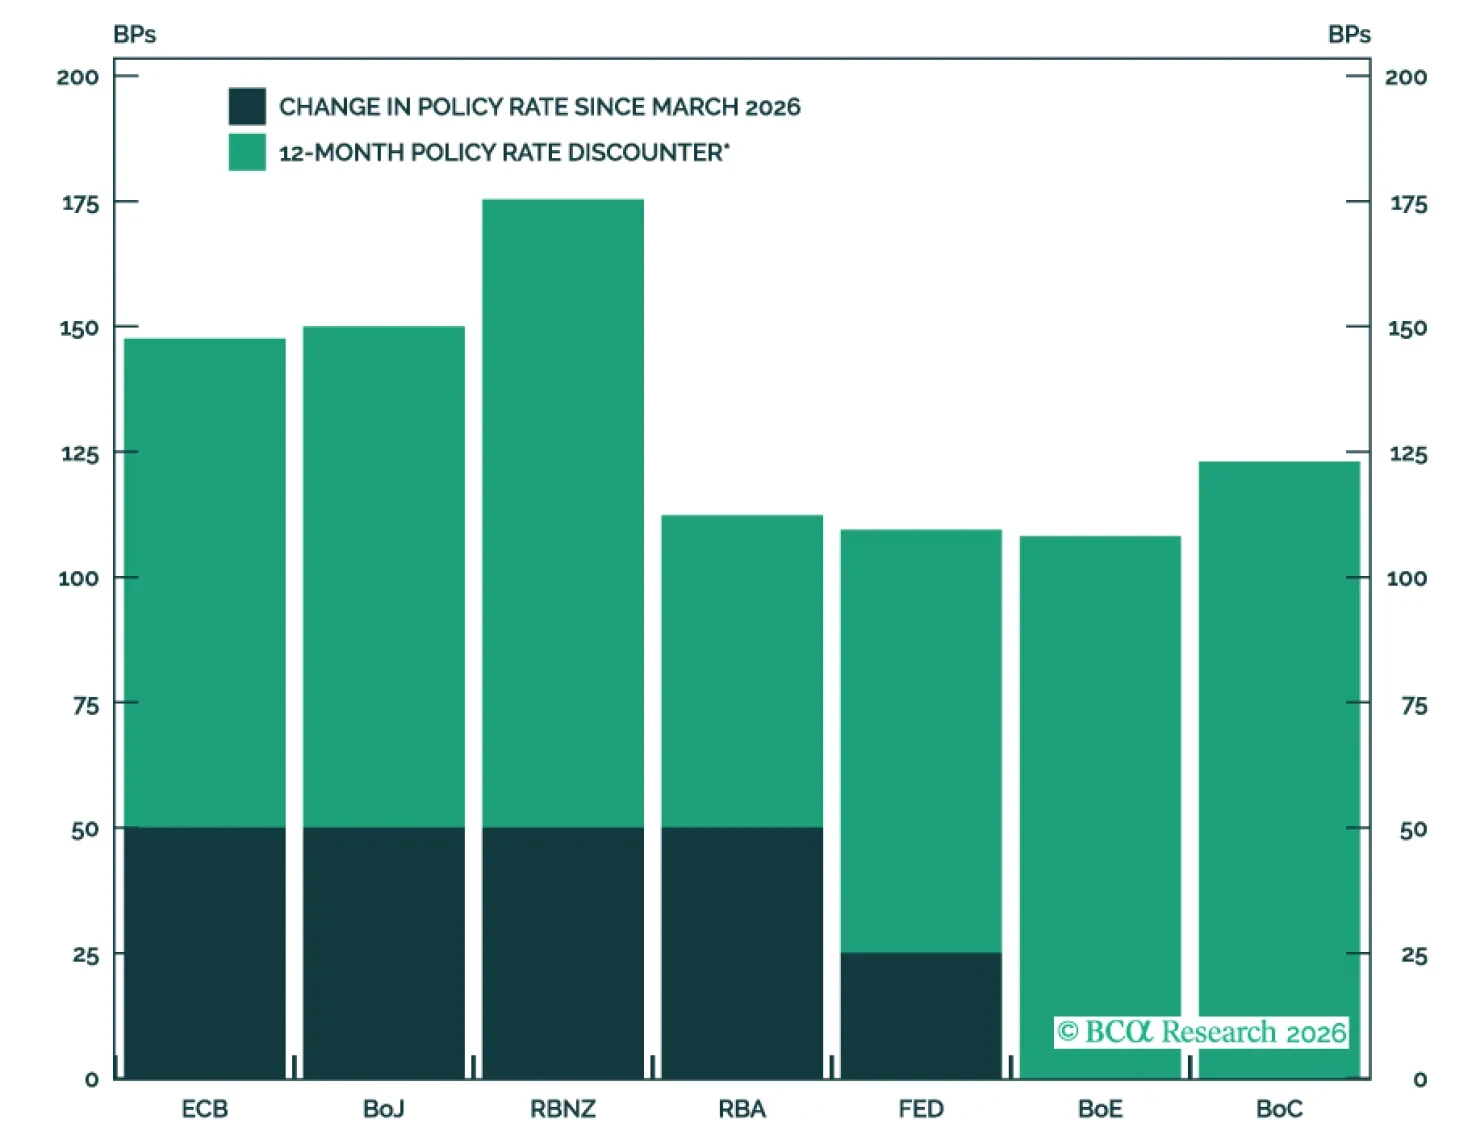
Policy rates are poised to rise across the developed world as central banks are no longer willing to wait out the Iran-US standoff before taking action to combat the inflationary effects of higher oil prices. Outside of Japan, however, we do not think central banks will hike as much as markets expect.
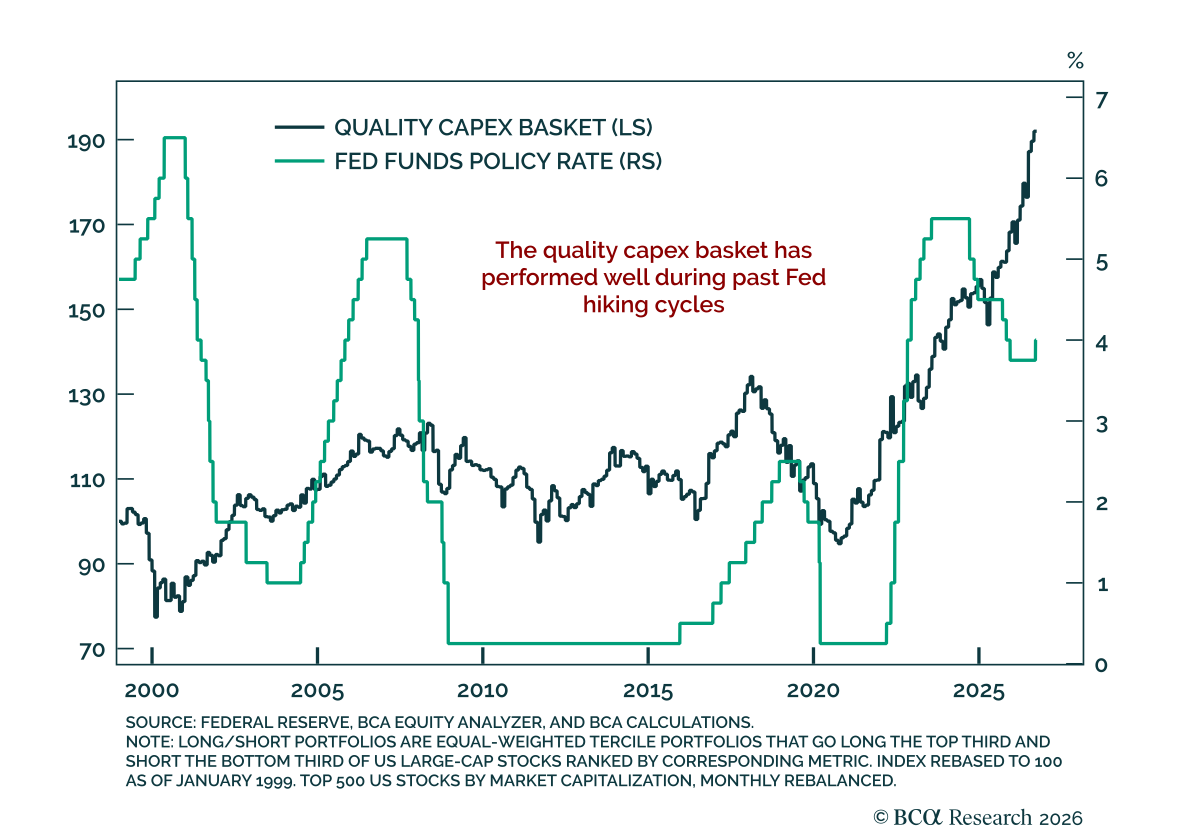
The Fed’s first hike is unlikely to be an equity-market cliff. Recent multiple compression has absorbed some of the rate shock, while bond risk premia, rate volatility, and inflation expectations remain contained. Stocks have typically climbed through hiking cycles, but we favor moving up in quality through our long/short Quality Capex Basket.
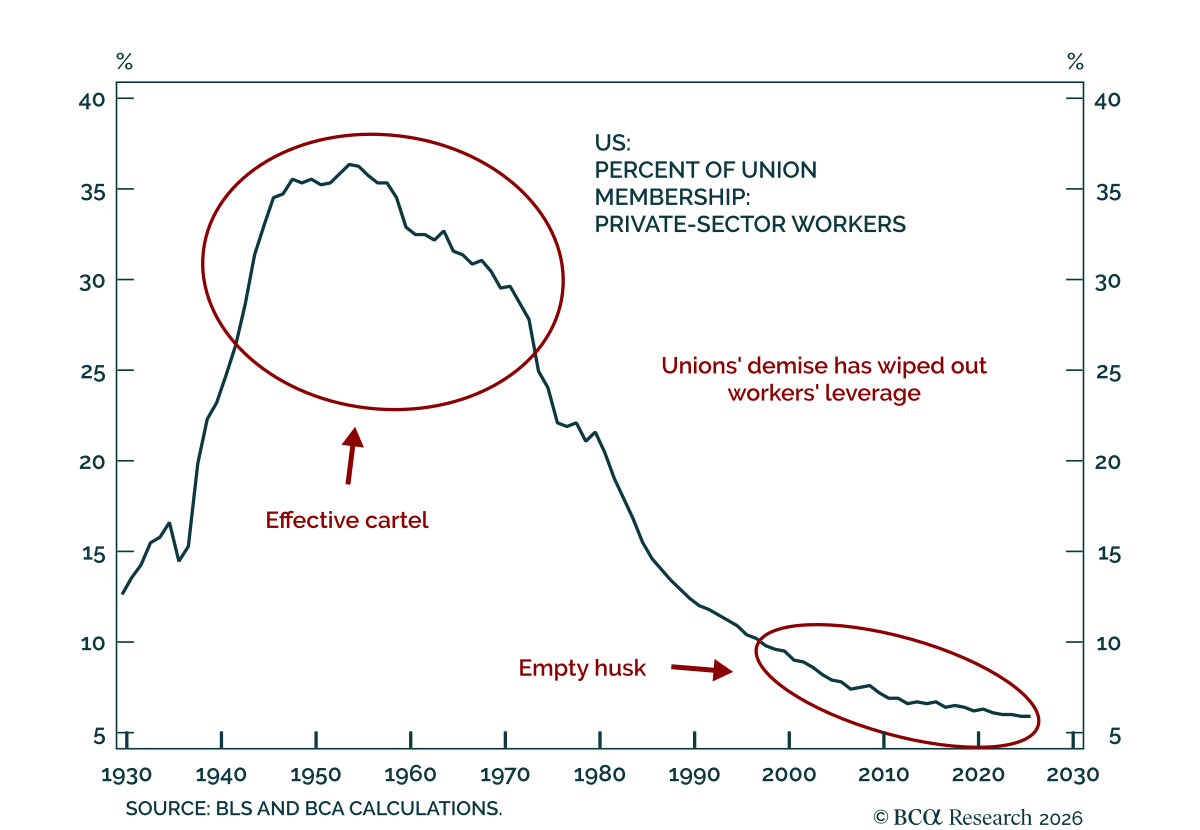
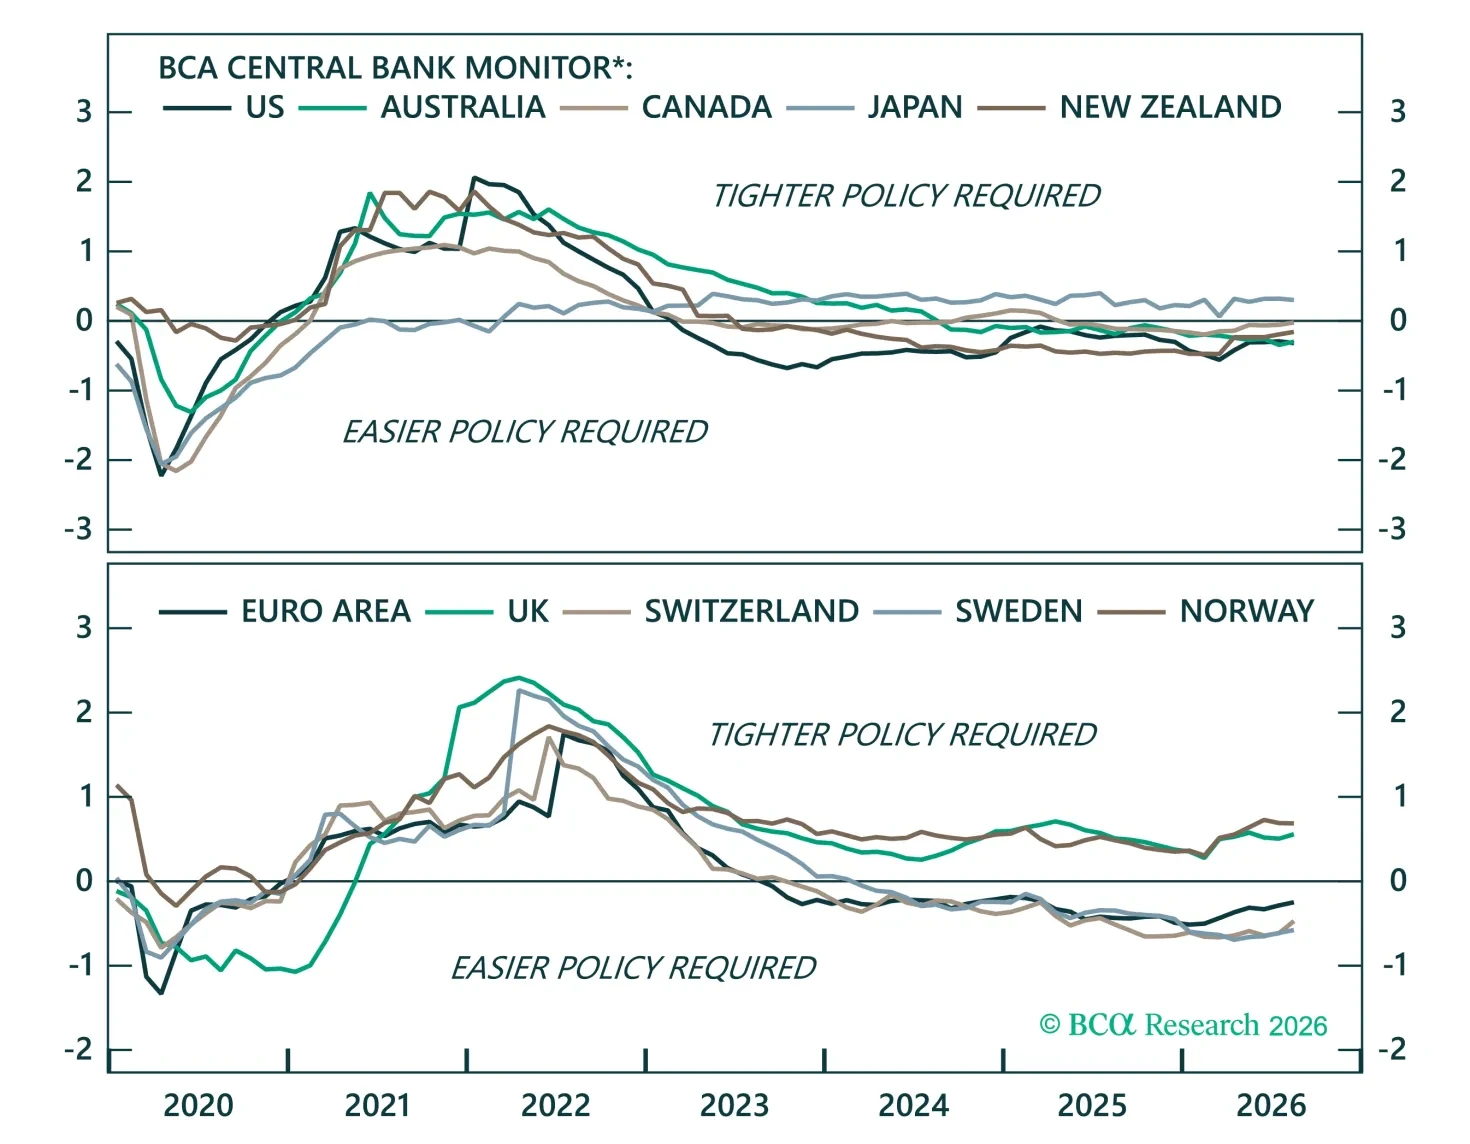
Central banks have begun a mild tightening cycle as elevated energy prices raise concerns about second-round inflation effects. We use BCA’s Central Bank Monitors to test whether hawkish market pricing is justified and identify tactical opportunities across global bond and currency markets.
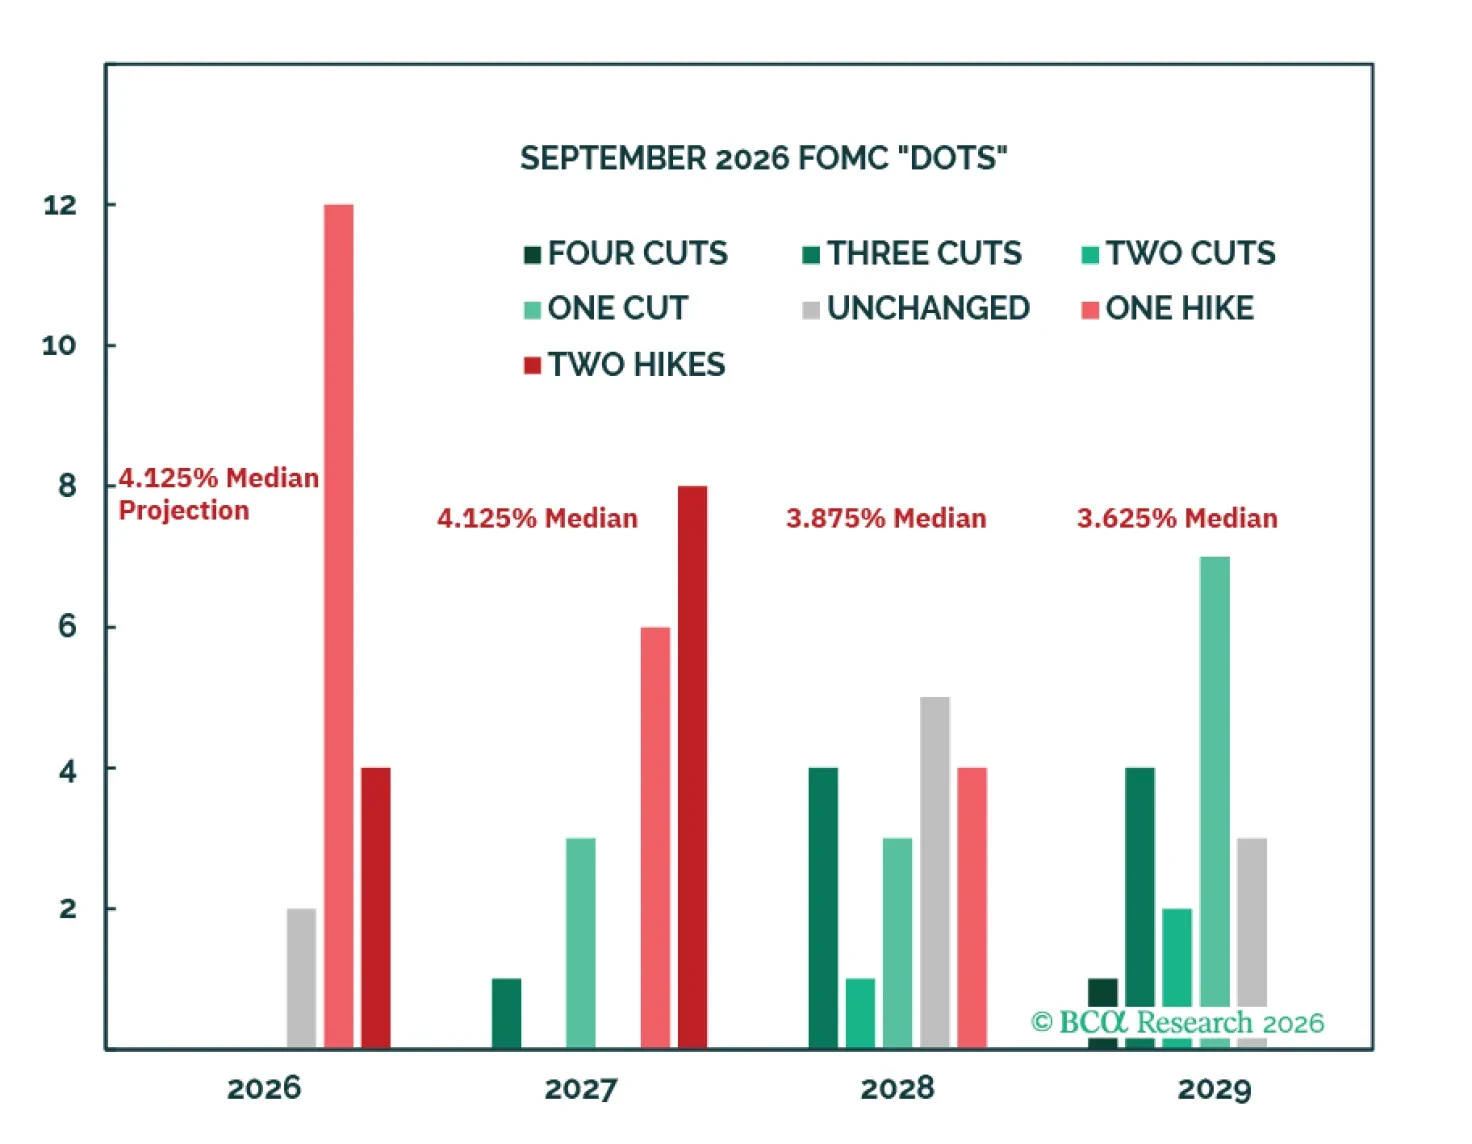
The Fed hiked rates last week, but Fed officials expect this tightening cycle will involve no more than three 25-basis point hikes, contingent on inflation coming down quickly in 2027. We’re inclined to agree.