Inflation
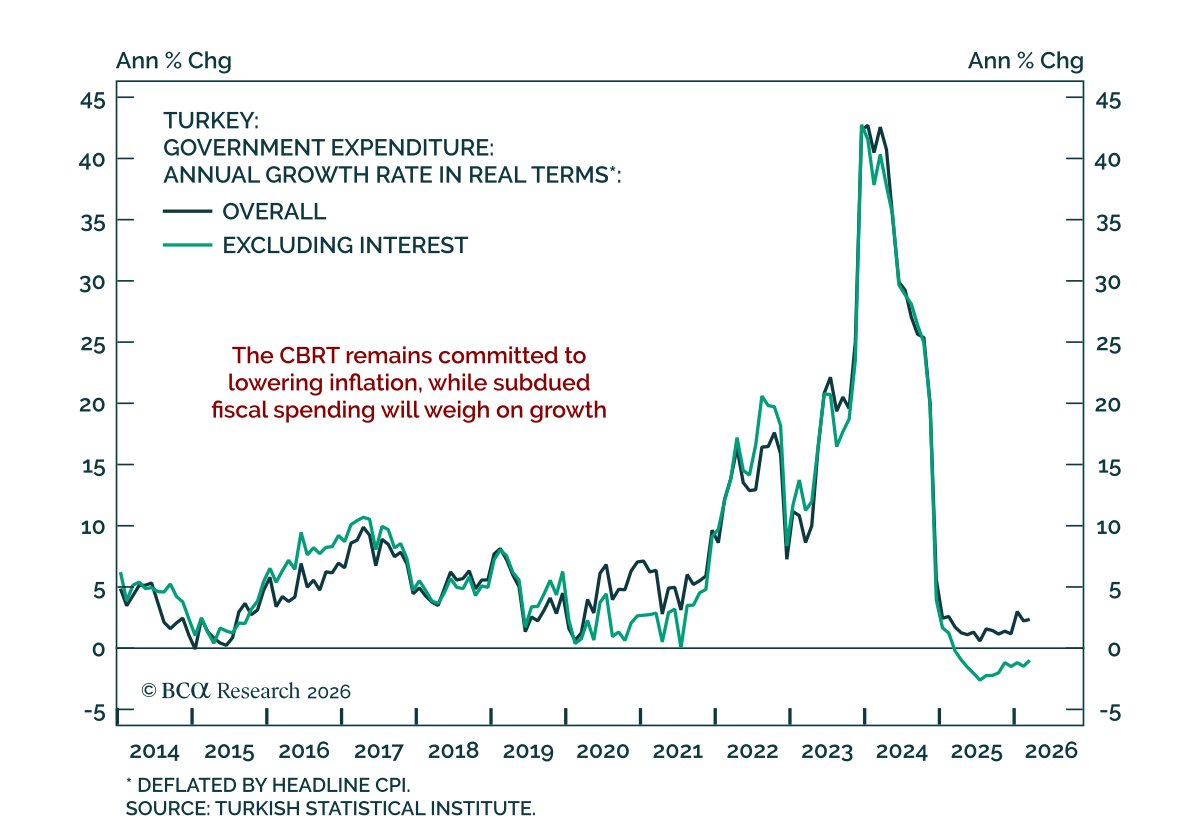
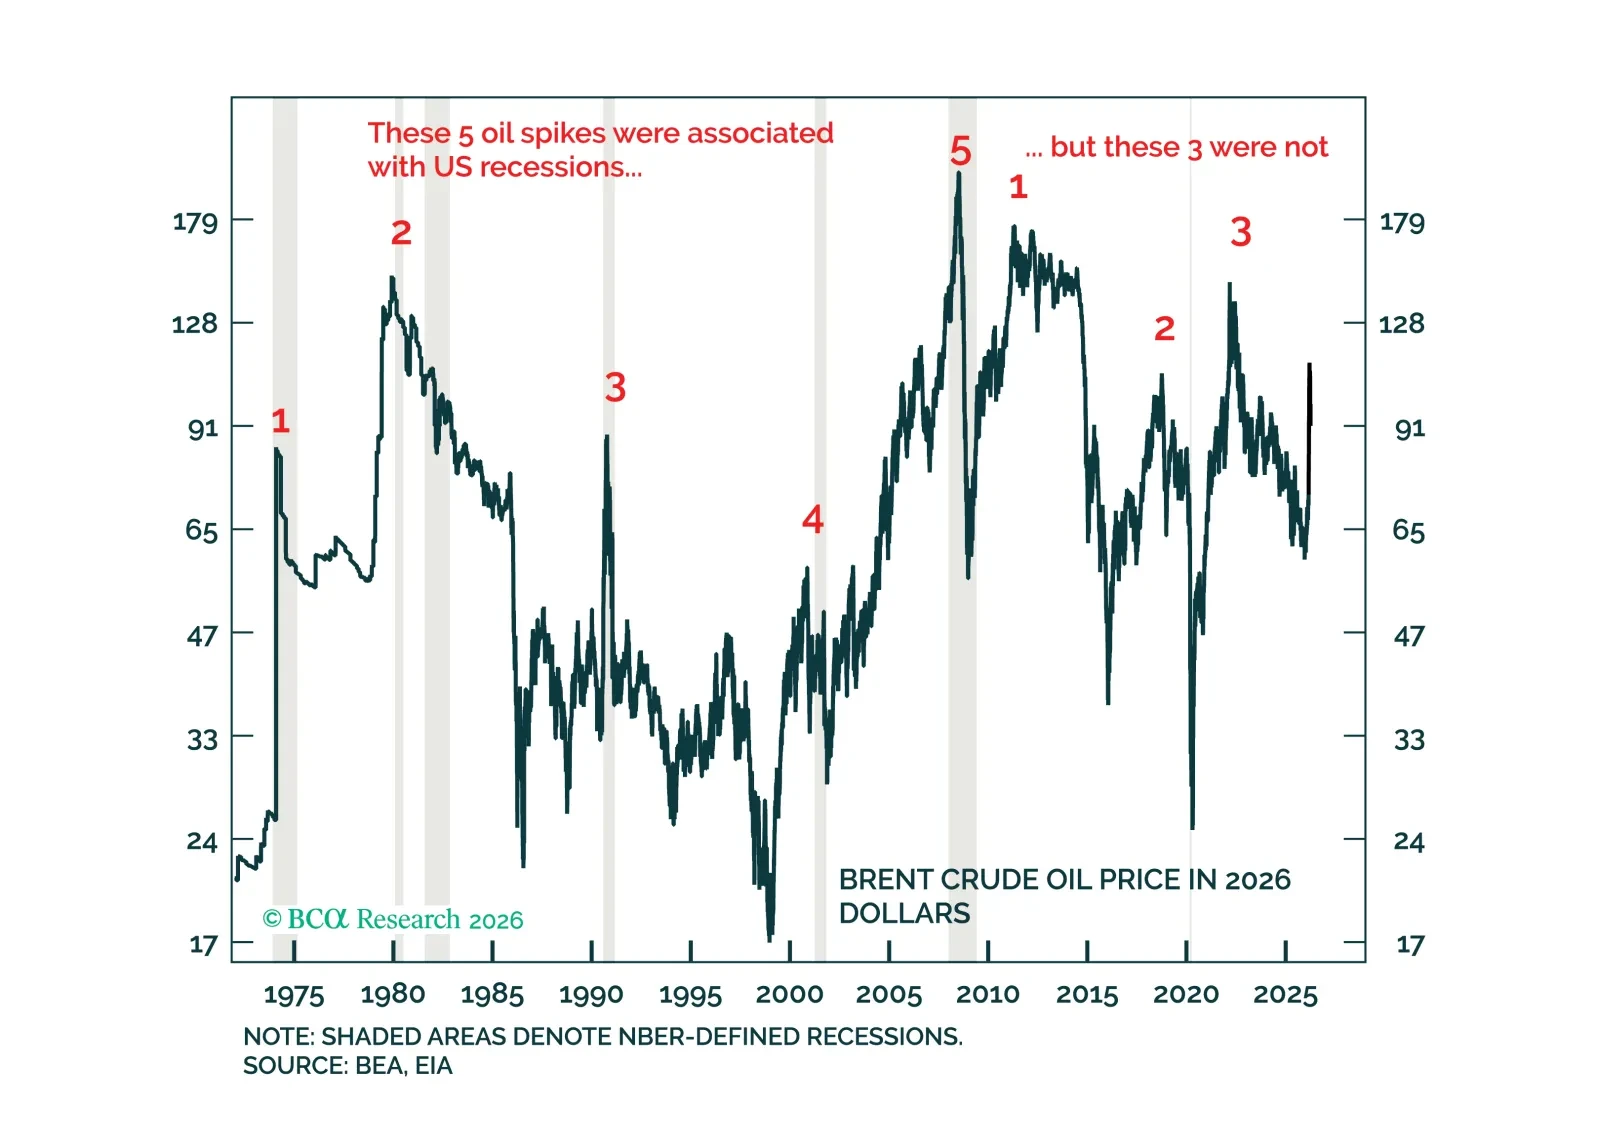
In the US, the oil shock’s impact is more inflationary than recessionary but in the other economies, like the UK, the impact is both inflationary and recessionary. This creates relative value opportunities for bond investors. Plus, we reiterate short AUD/JPY as a trade.
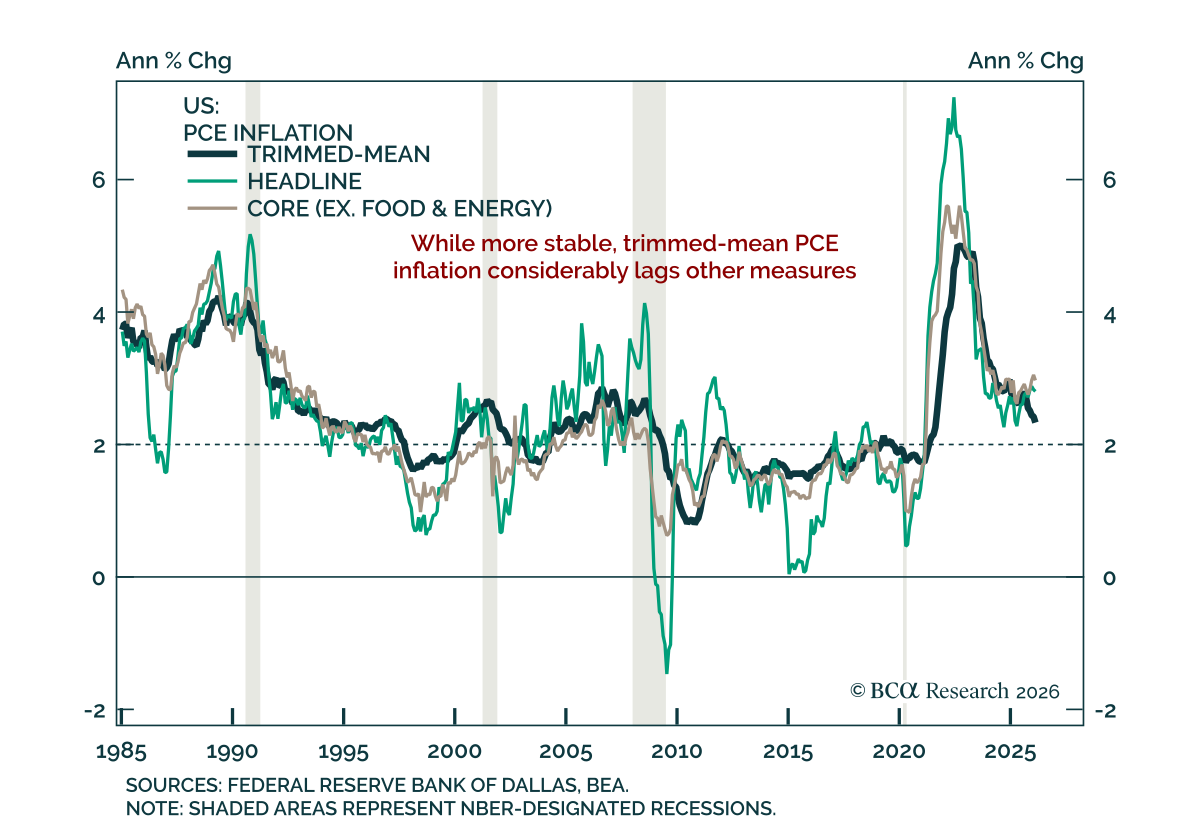

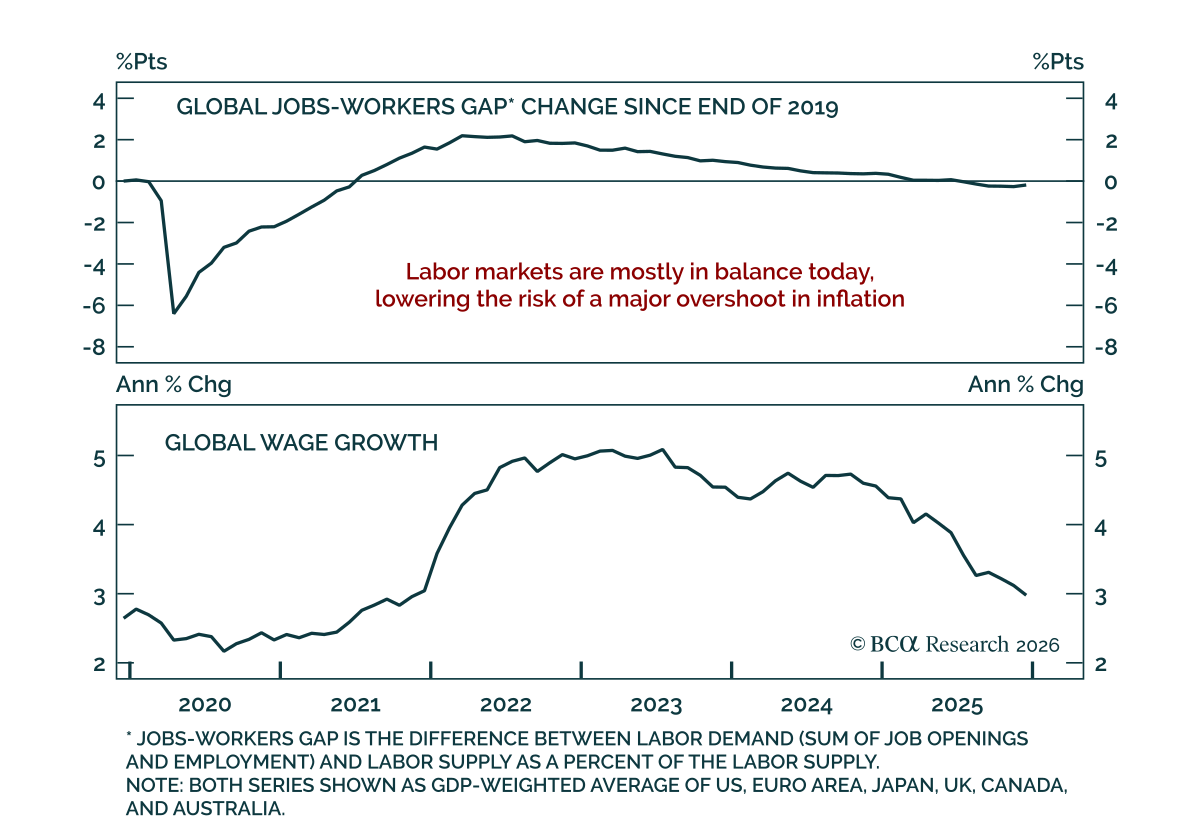


We do not expect the oil shock to have a lasting effect on inflation. Looking further out, a variety of structural forces will influence inflation, including fiscal policy, globalization, demographics, and AI.
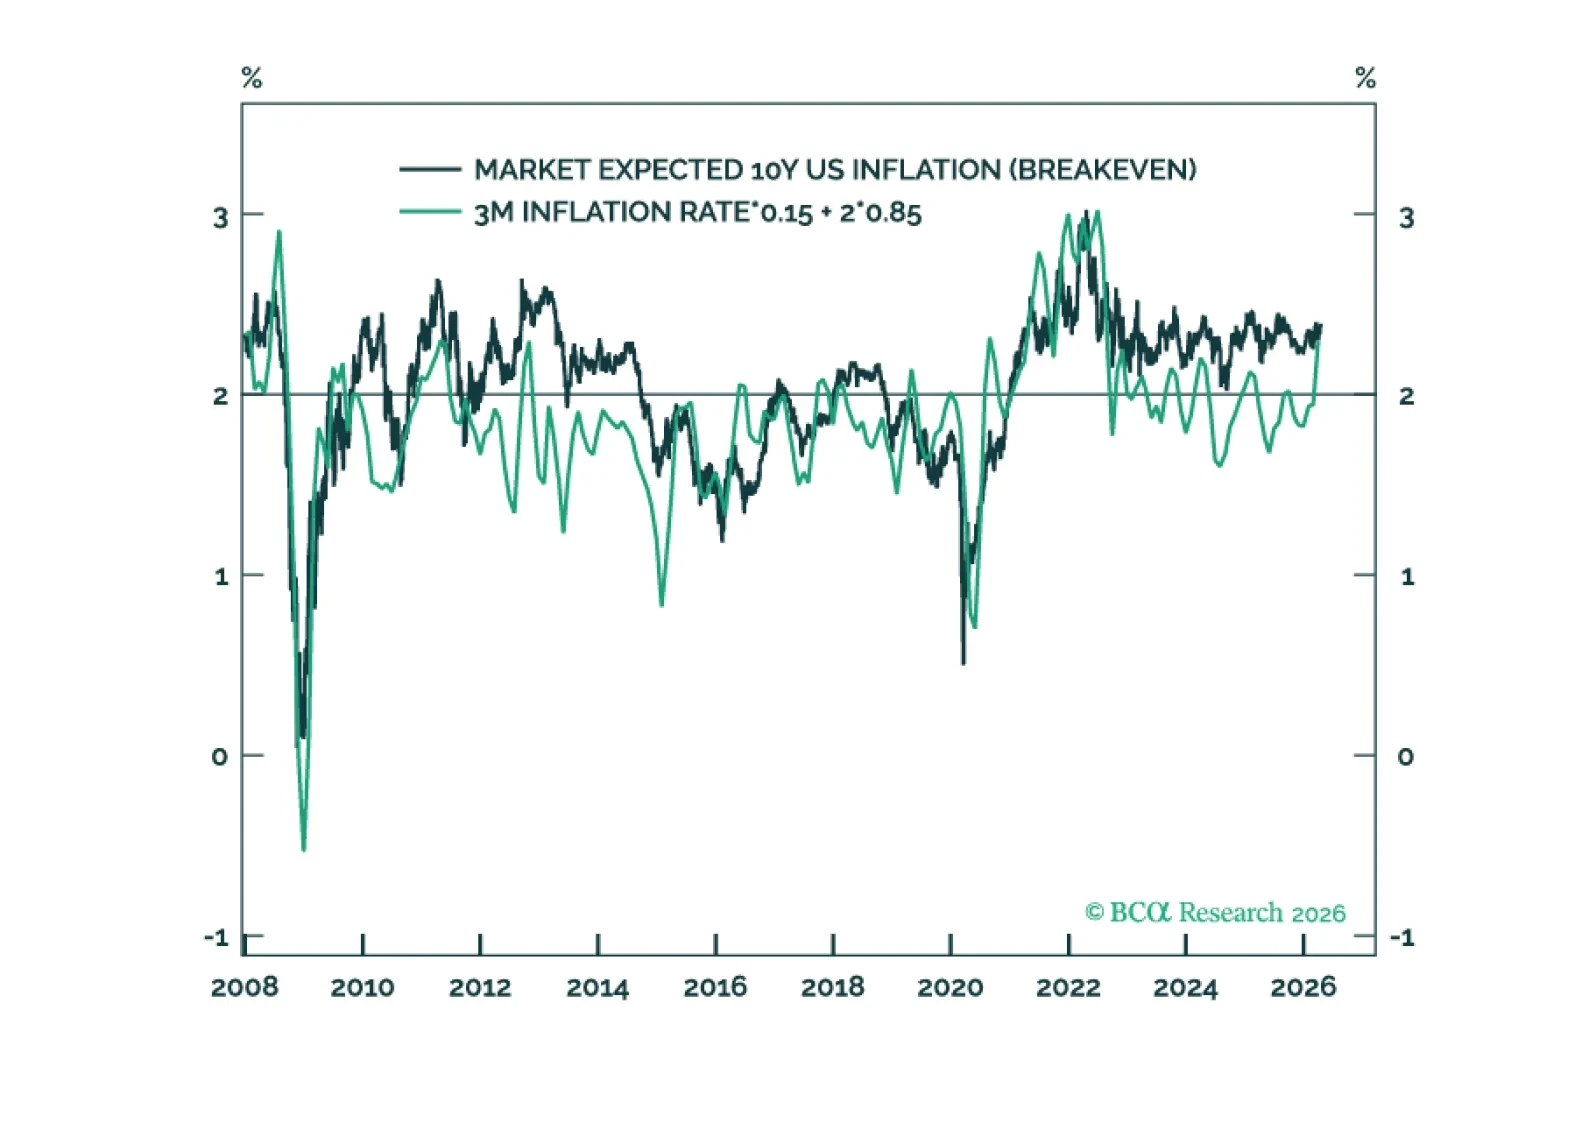
In this Special Report, we describe how inflation expectations are formed. We then demonstrate that steady state inflation expectations have un-anchored in the UK, are un-anchoring in Japan, and are at high risk of un-anchoring in the US. And we conclude with some implications for bond markets.
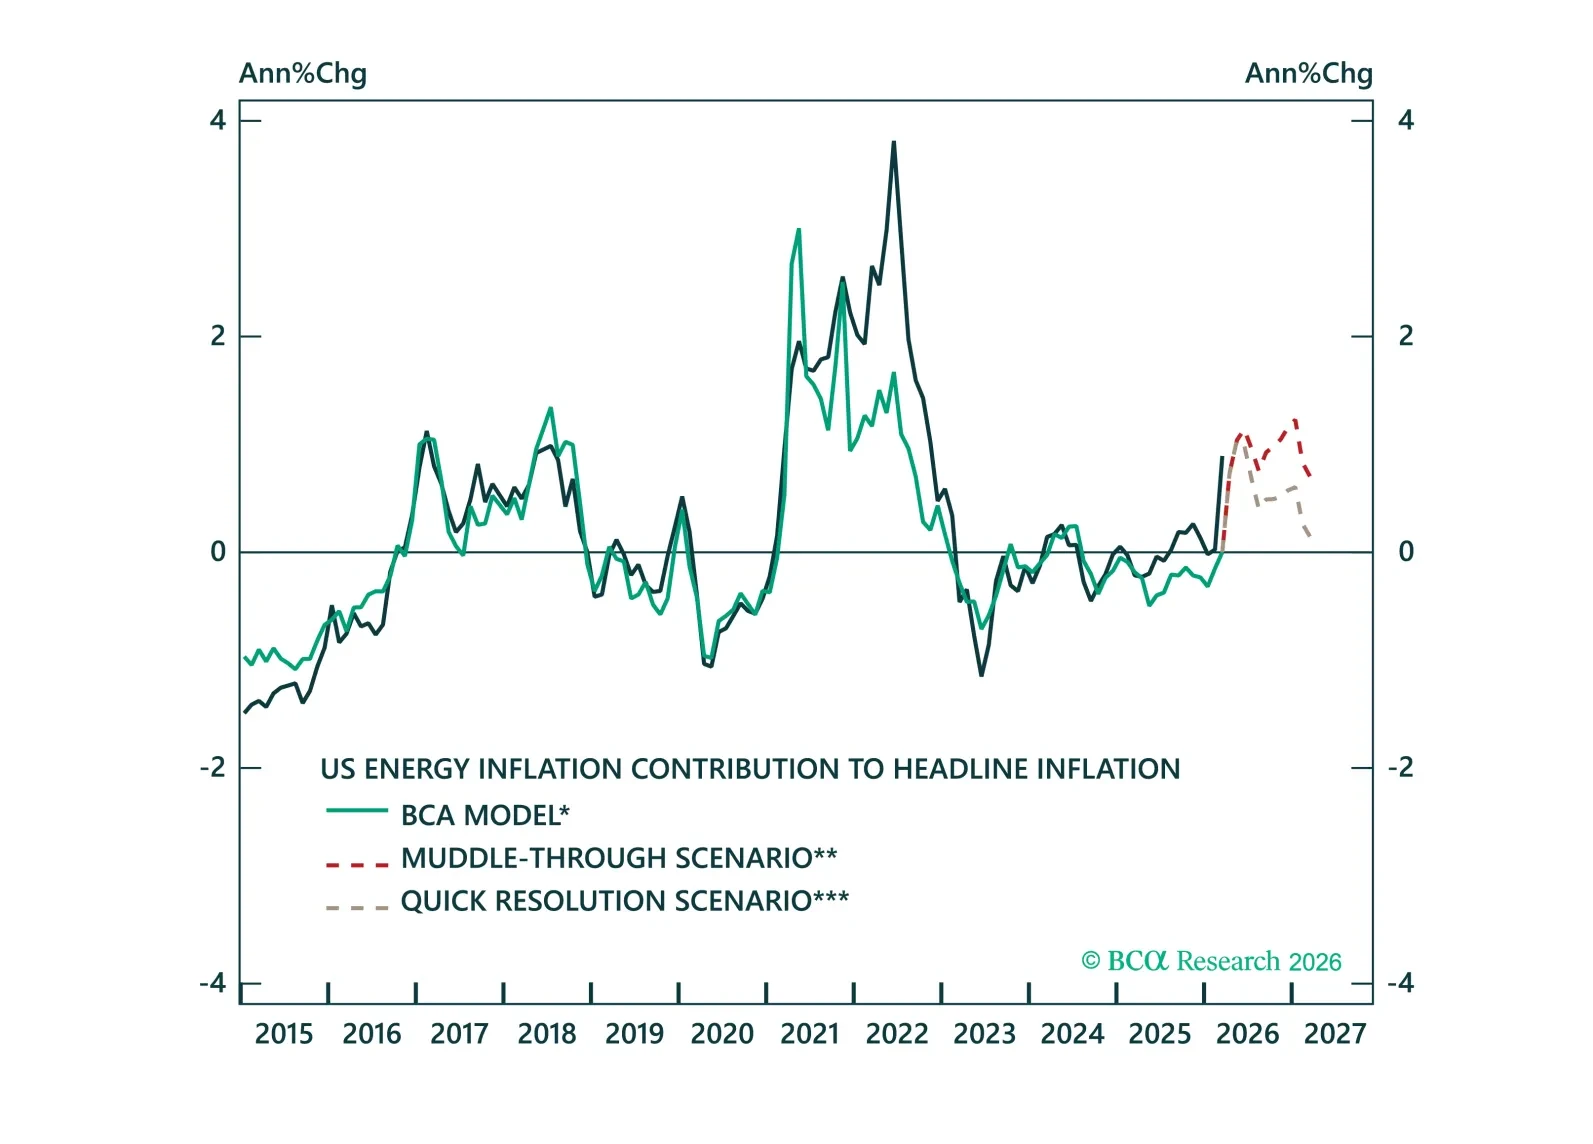
Volatility is high, but the path for yields is clearer than it looks. Across three oil scenarios, we show how policy responses shape fixed income markets and why the balance of risks still points to lower yields.
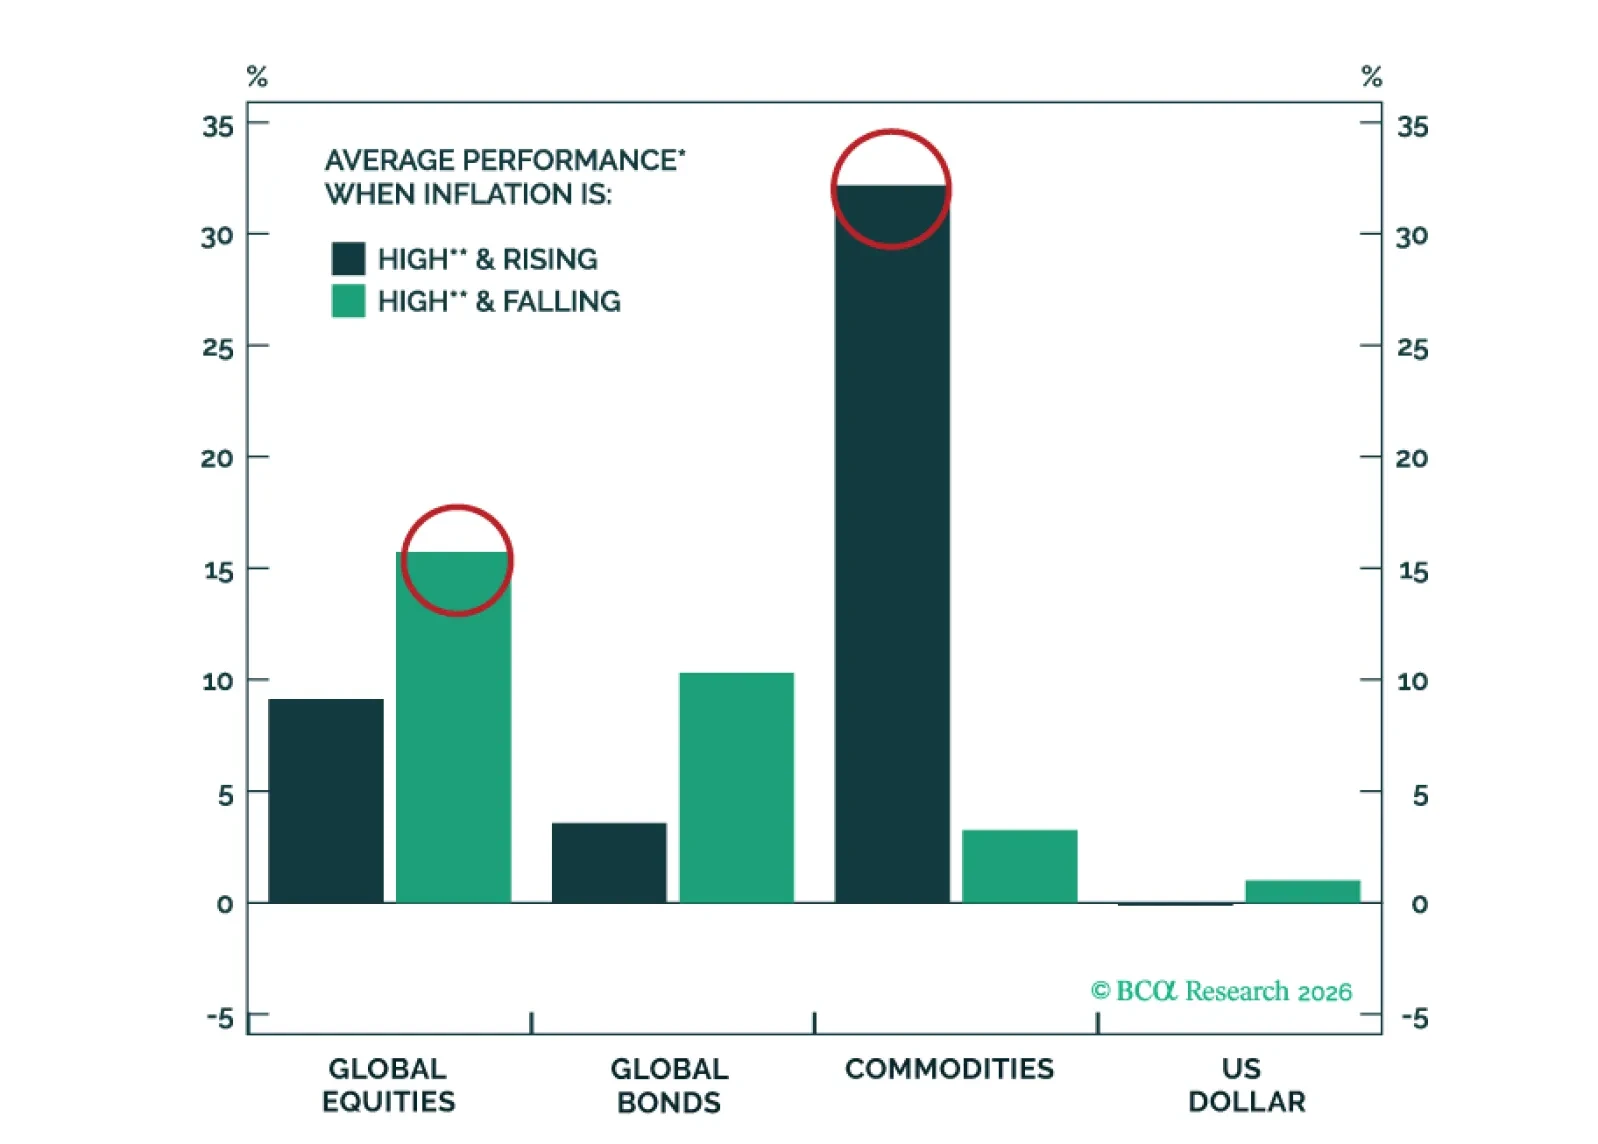
The Iran war provides a timely motivation for examining how the main financial asset classes and commodity sectors perform across different inflation regimes and during periods of elevated geopolitical risk.