Skip to main content

AI

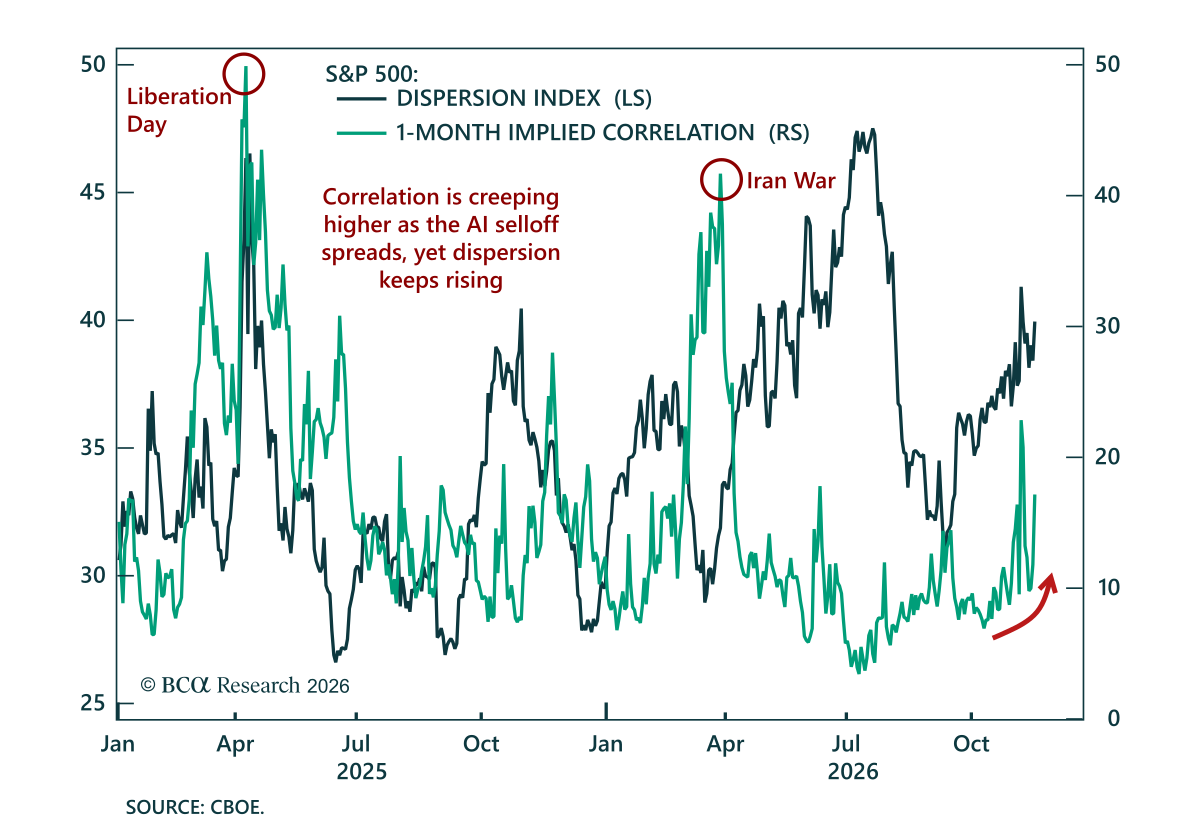
Rising implied correlation could expose the market to a sharp VIX repricing. Global equities resumed their slide on Monday as the semiconductor-led selloff spread to Asian and US markets. The Nasdaq 100 fell more than 2.5%, as markets weighed Nvidia’s…

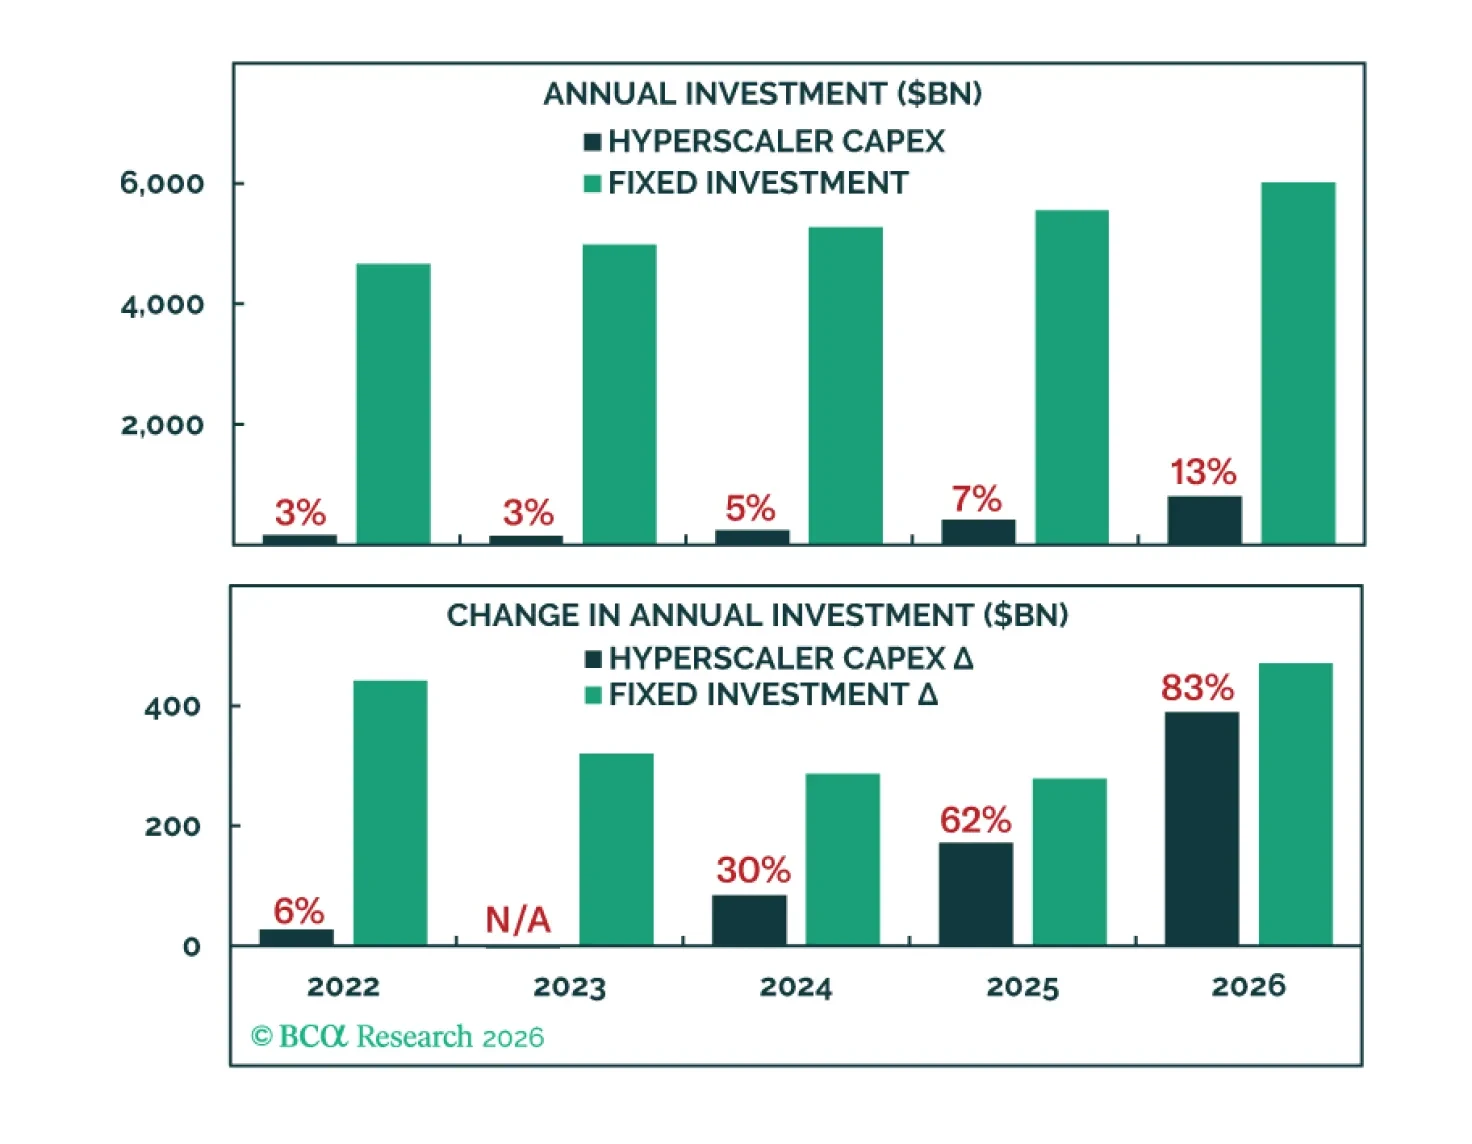
Data centers have swallowed aggregate US investment to such an extent that even a modest hyperscaler capex pullback could sink the expansion and bull market.
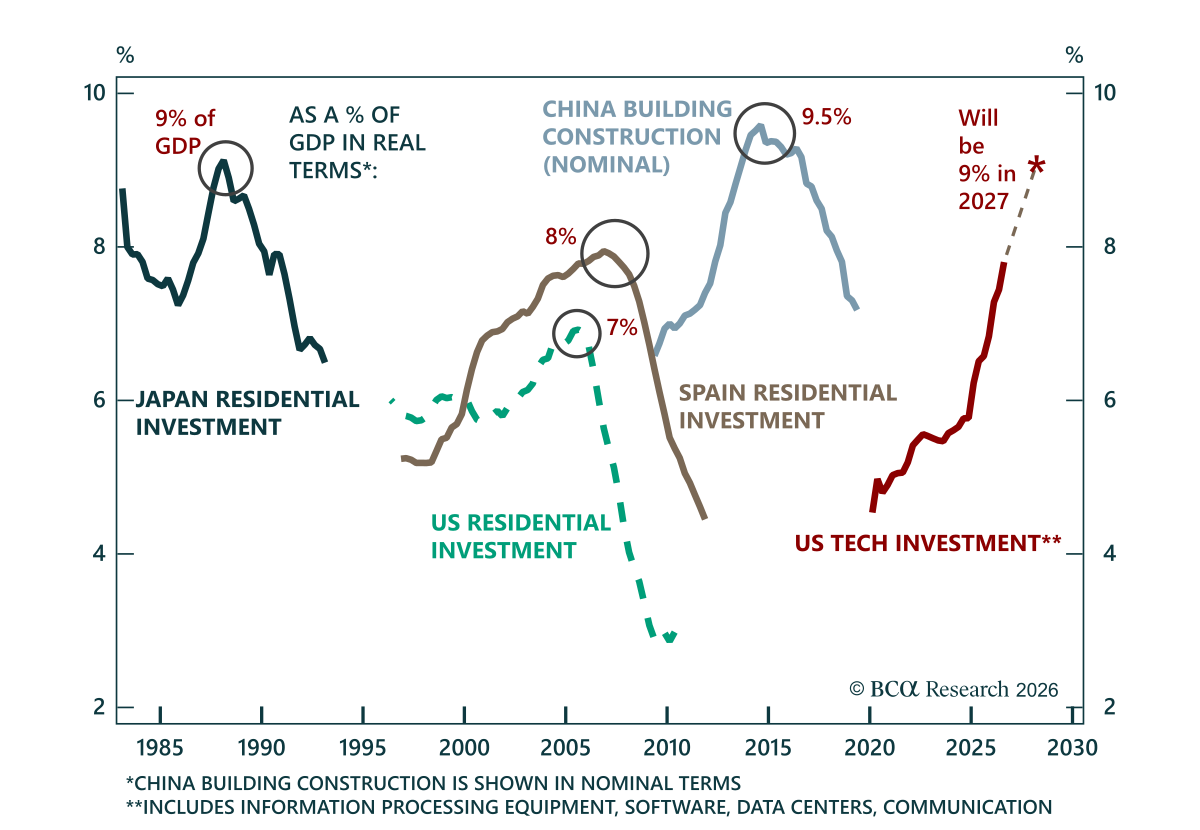
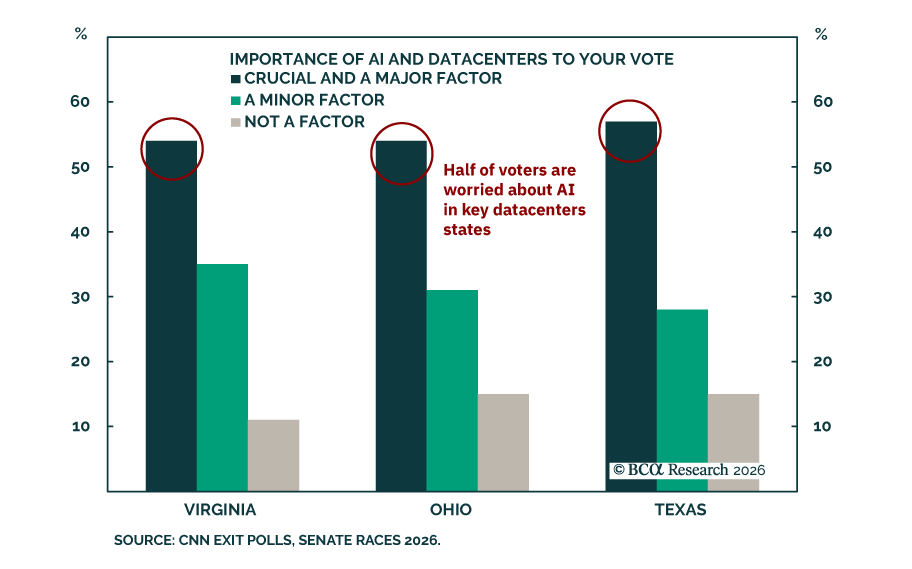
Our Chart of the Week, from Arthur Budaghyan of the CoreMacro team, shows that the AI capex cycle may be nearing its peak next year and highlights the bearish case for AI plays. All recent major capex cycles peaked near 7-9% of domestic GDP, a range that…
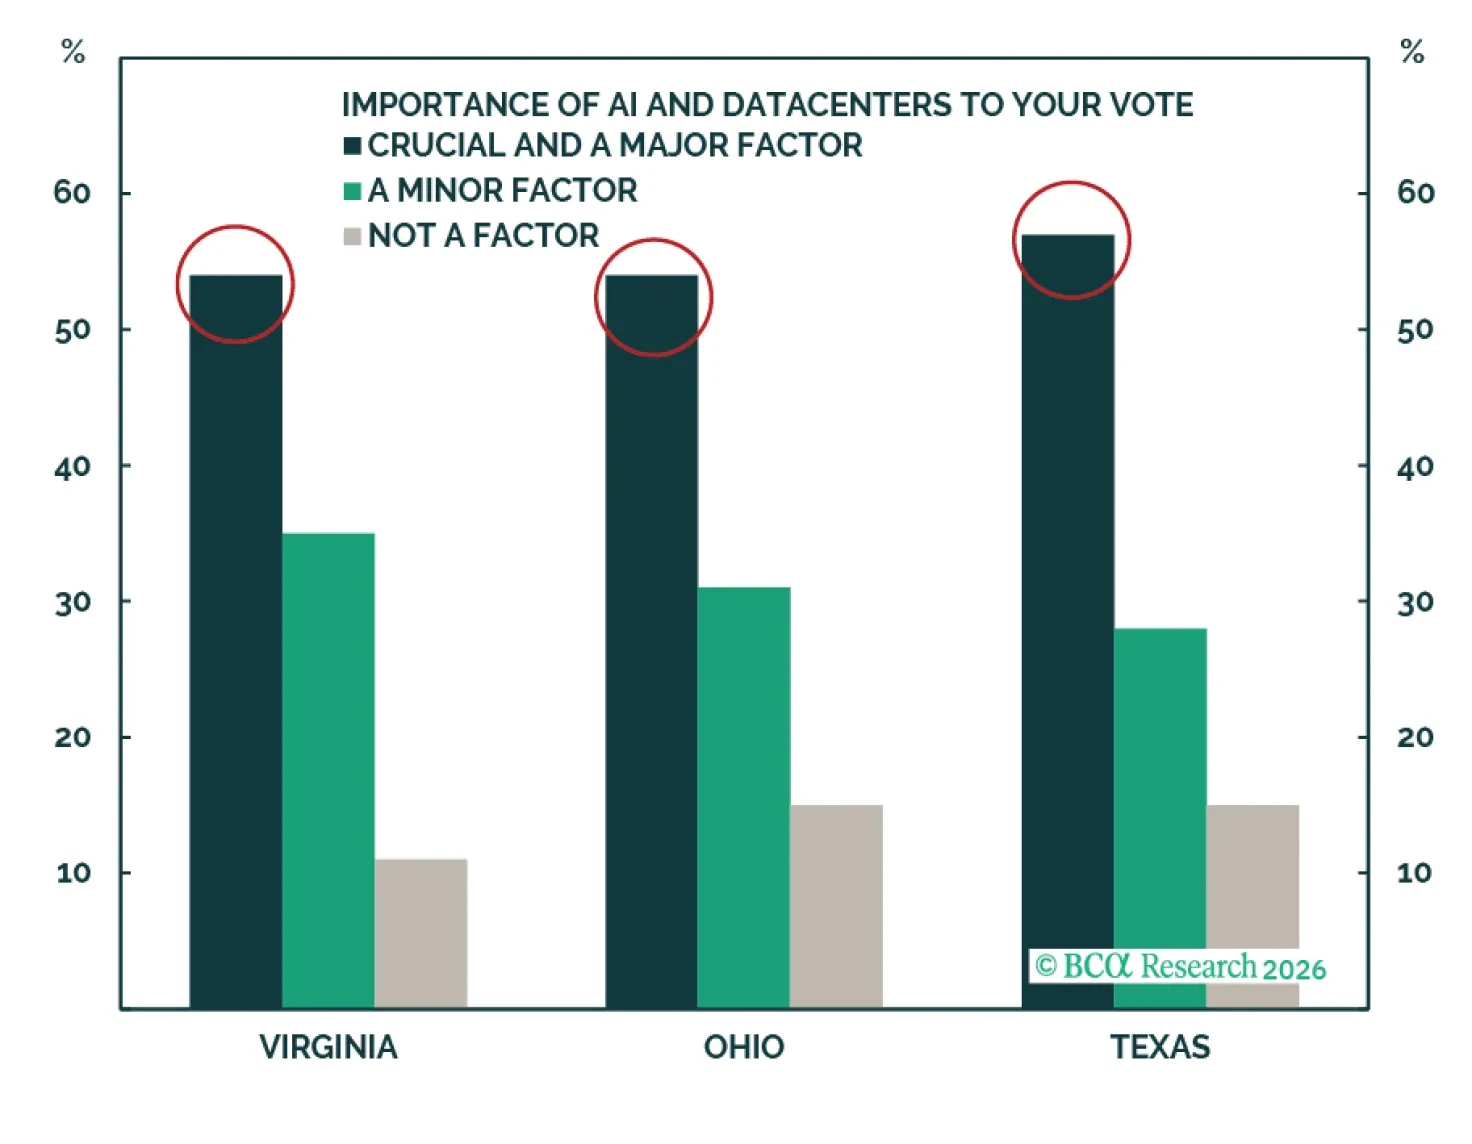
Our GeoMacro strategists see fears of AI regulation as overblown after the US midterms, but some regulation will pass, and data centers will need to generate their own electricity. Any bill will need to be bipartisan, consensus-oriented, tax free, and focused…

Fears of AI regulation are overblown after the US midterms. But some regulation will pass – and data centers will need to generate their own electricity.
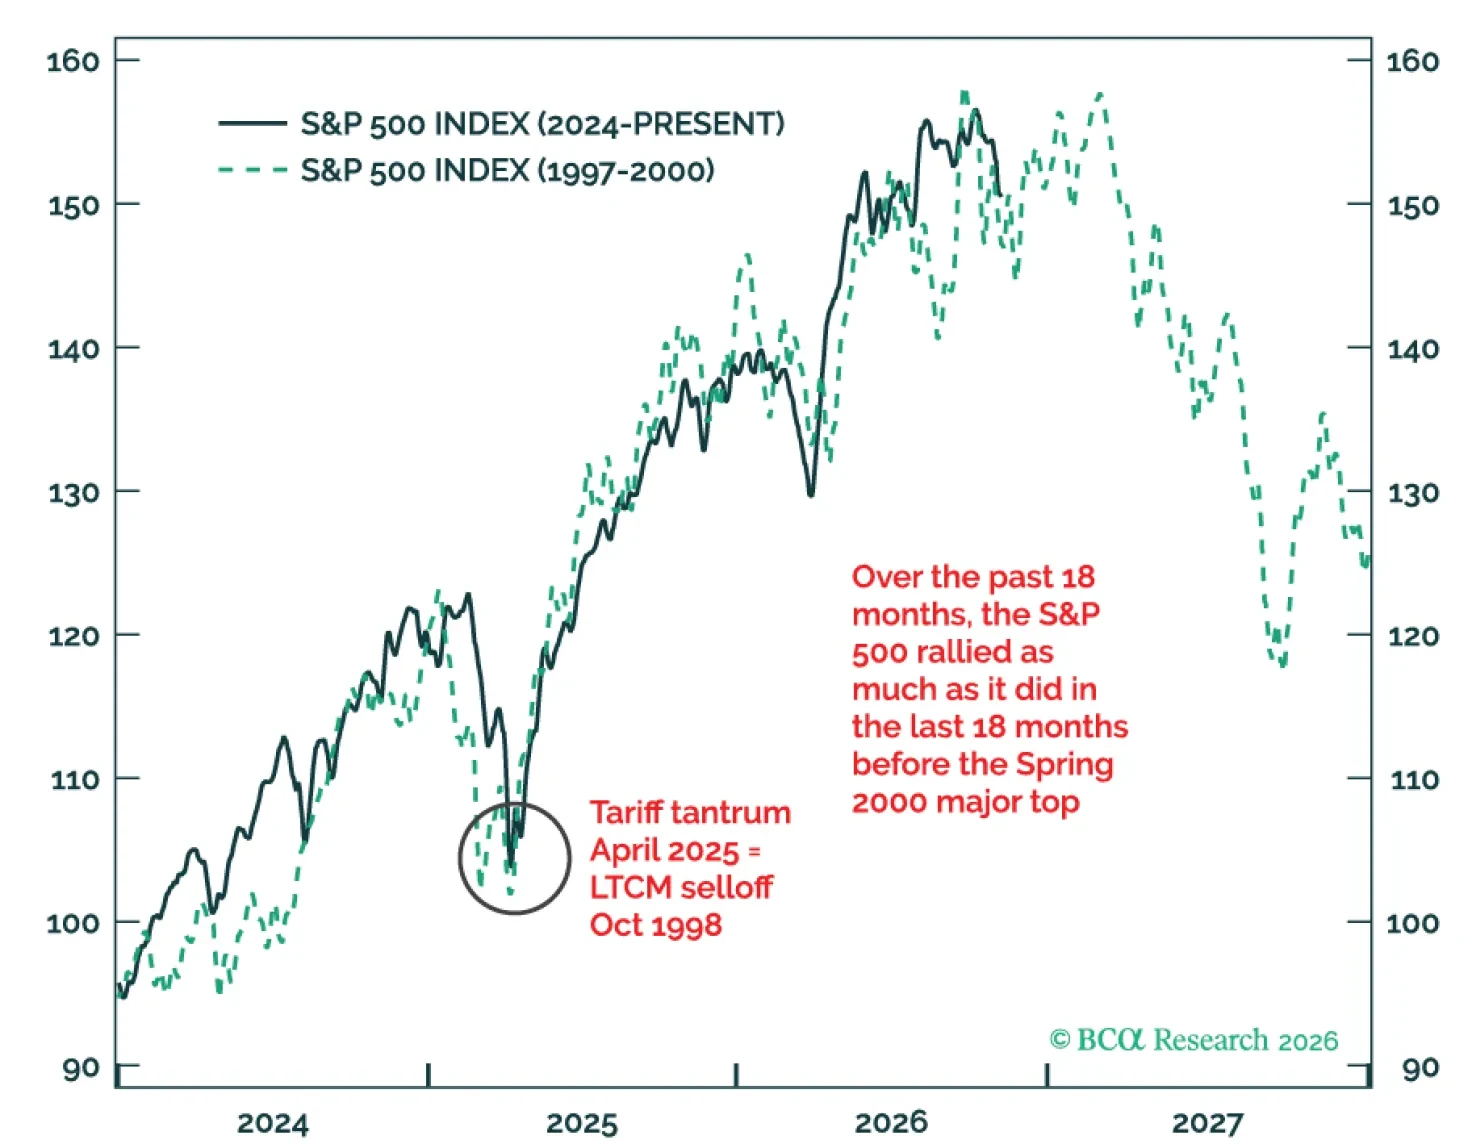
Resist buying the equity dip: a major global market top may already be behind us. Sell the US dollar on strength. Accumulate bonds on weakness, favoring those in countries with current account surpluses.
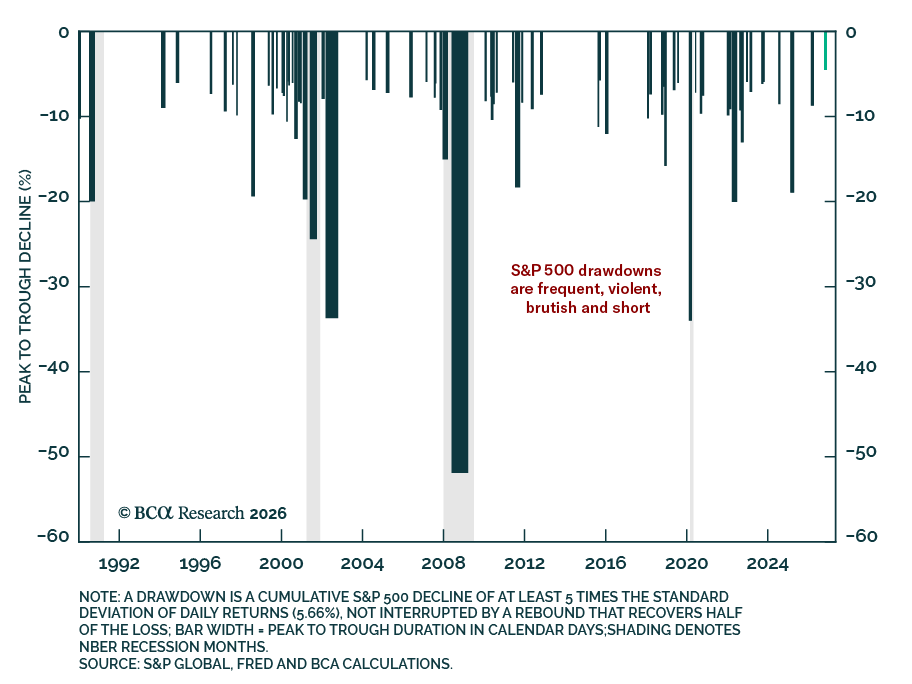
Our US Equity strategists view the post-election selloff as overdone and continue to expect the S&P 500 to move higher into year-end. AI capex concerns have pushed the index to the brink of a drawdown, but the cycle remains strong and Tech valuations had…

AI capex concerns have pushed the S&P 500 to the brink of a drawdown. But the cycle remains strong, drawdowns rarely last long, and Tech valuations had already compressed. And while Democratic governors now oversee about 80% of the data-center pipeline, a blue governor alone is not necessarily a build-out moratorium.
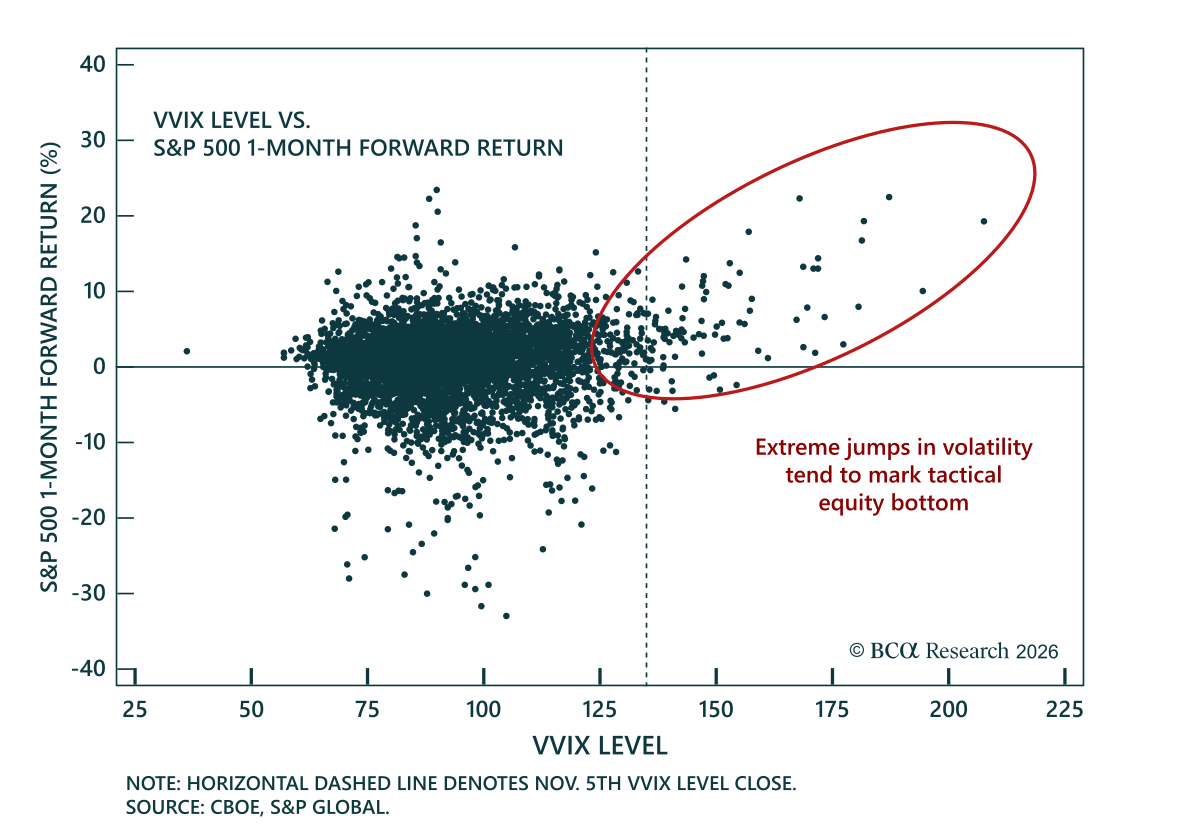
Thursday’s selloff reflects equities moving into self-reinforcing de-risking, with technicals rather than fundamentals driving near-term moves. The S&P 500 fell close to 4% and the Nasdaq 100 close to 6% into the open on high volumes, pointing to forced…
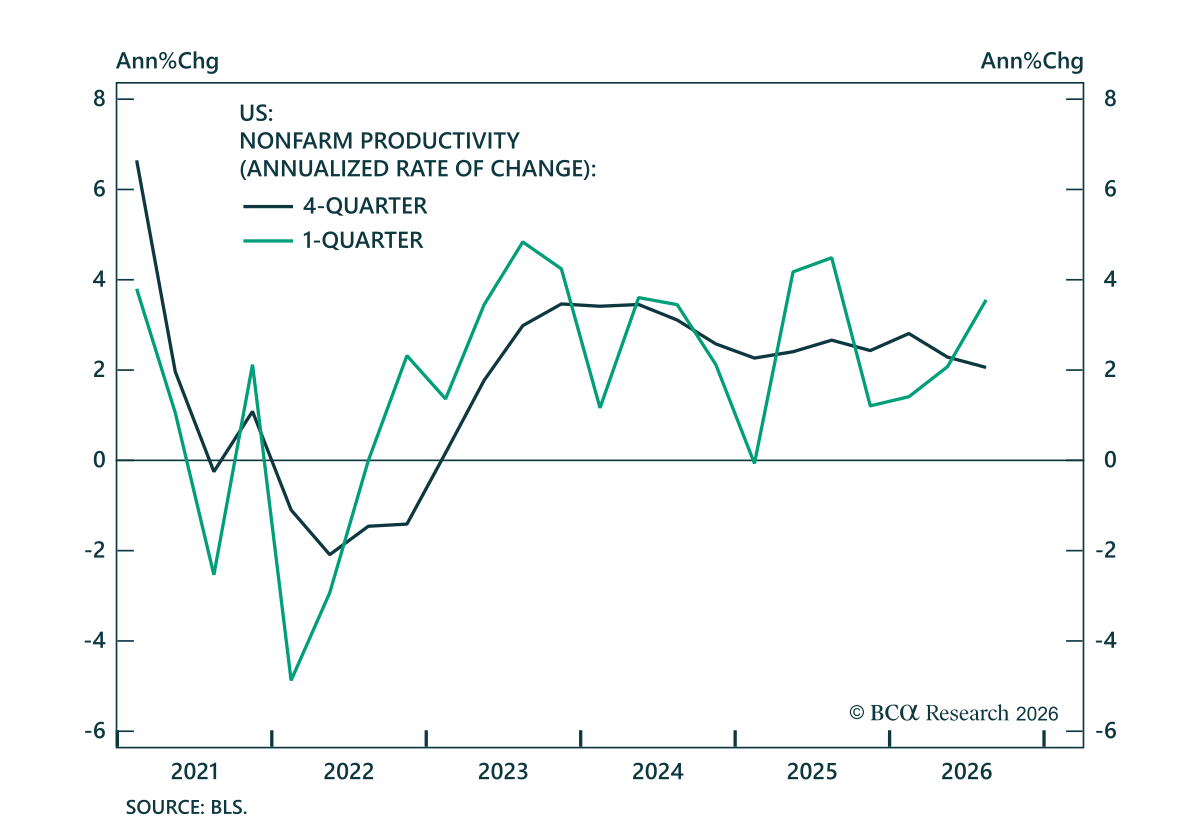
Strong Q3 US productivity reflects the demand-side impact of the AI capex boom, not supply-side gains from ex-tech AI adoption. Preliminary Q3 US nonfarm productivity came in surprisingly strong, growing at a 3.6% annualized q/q rate versus expectations of…