Latest from BCA Research

Everyone has opinions on Private Credit, but few have the data, and fewer have the objectivity. We give you both. In under 5 minutes, you will understand how we got here and, more importantly, how to allocate from here.
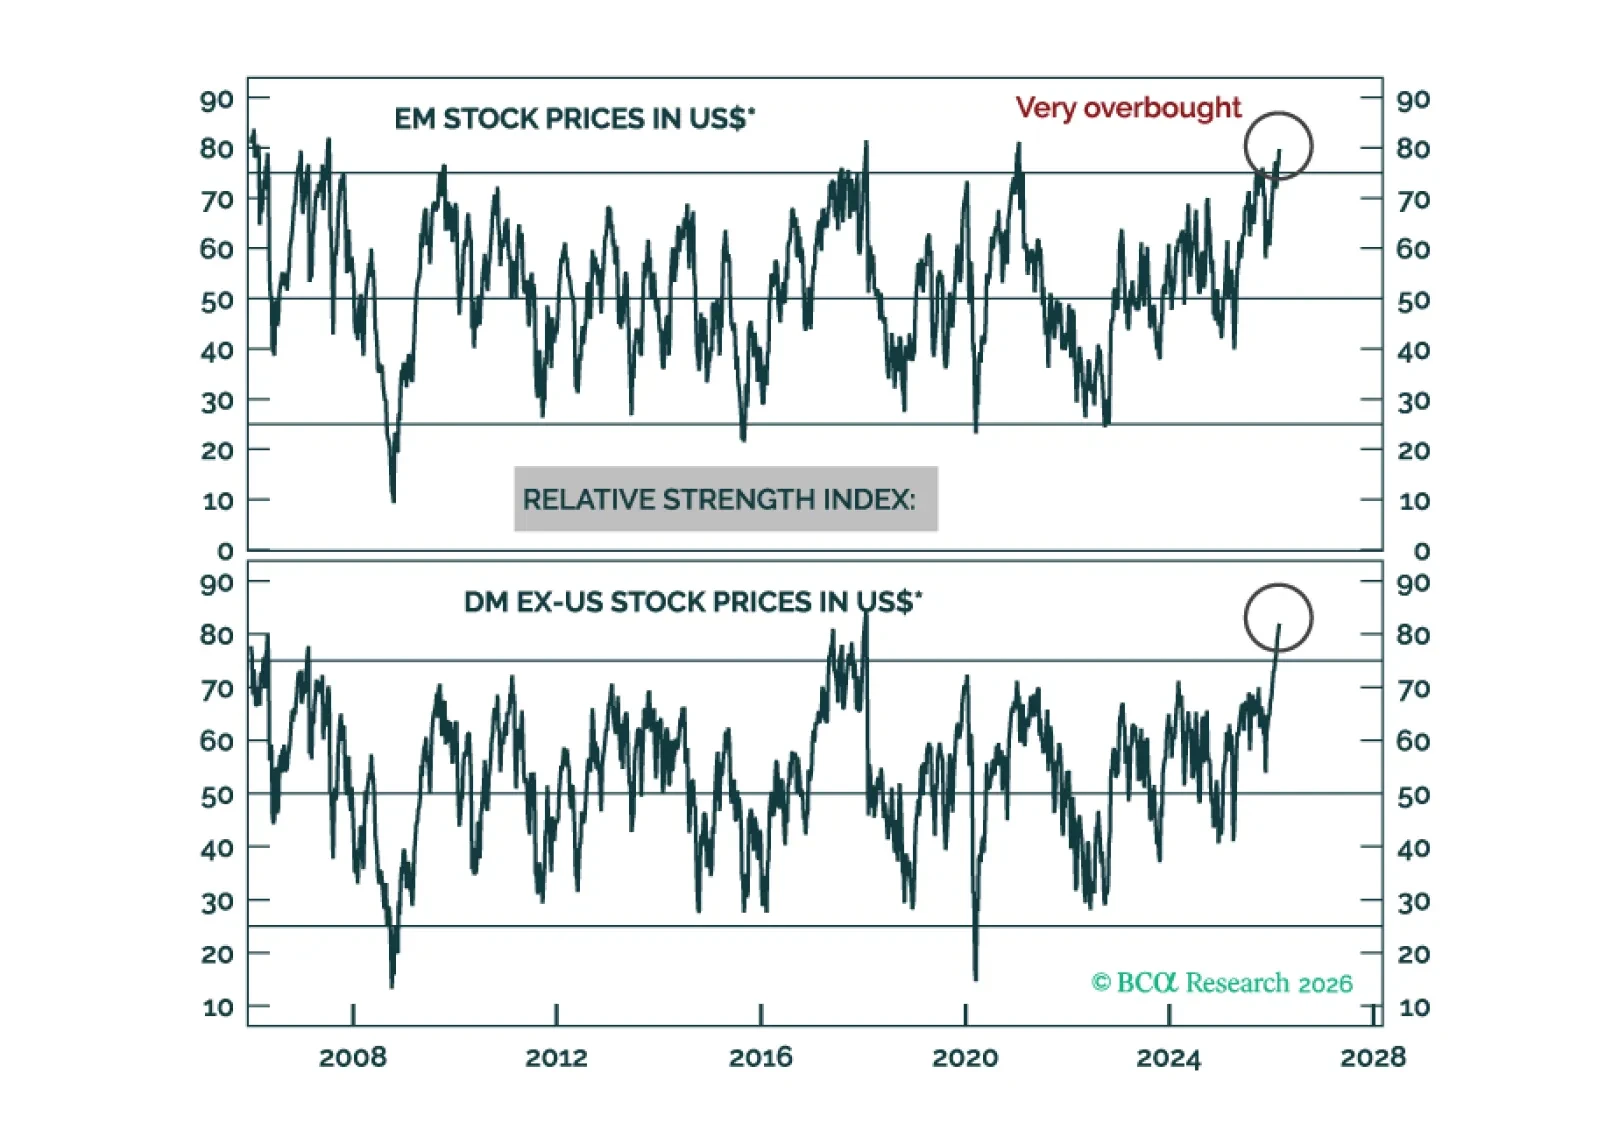
Avoid EM and DM risk assets. In the near term (one-to-three months), the odds favor US equity outperformance and a US dollar rebound. Nevertheless, the cyclical outlook (nine-to-12 months) warrants underweighting US equities and staying short the greenback.
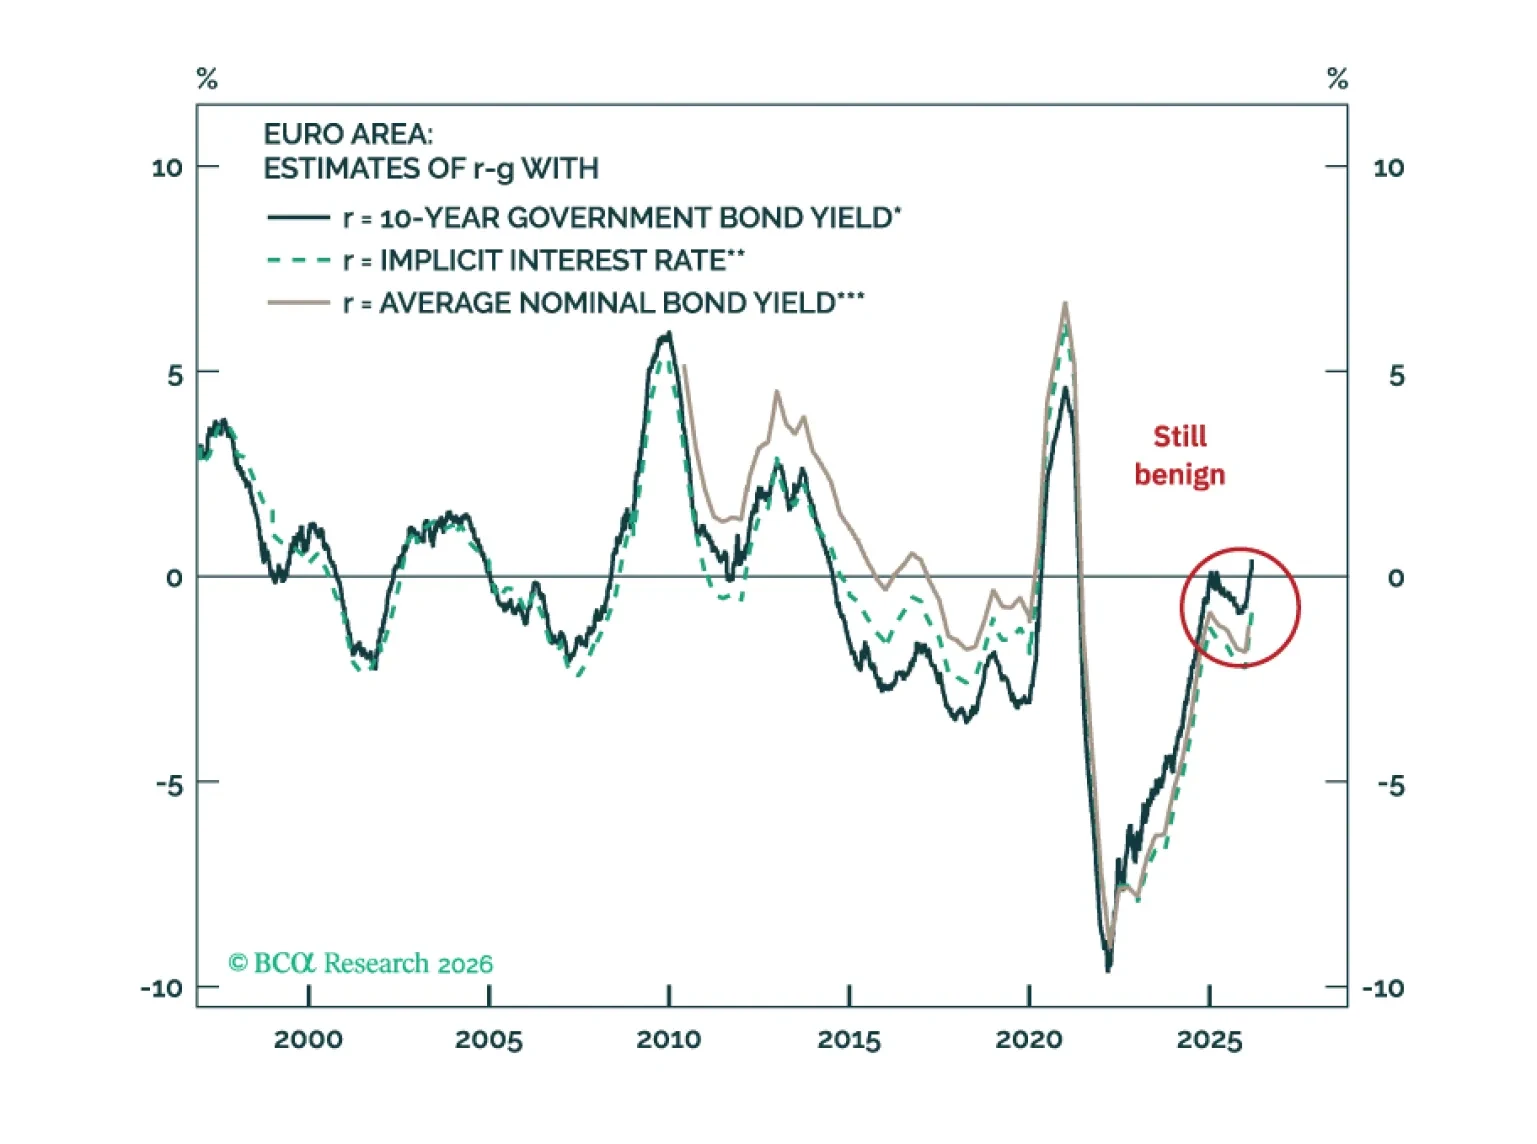
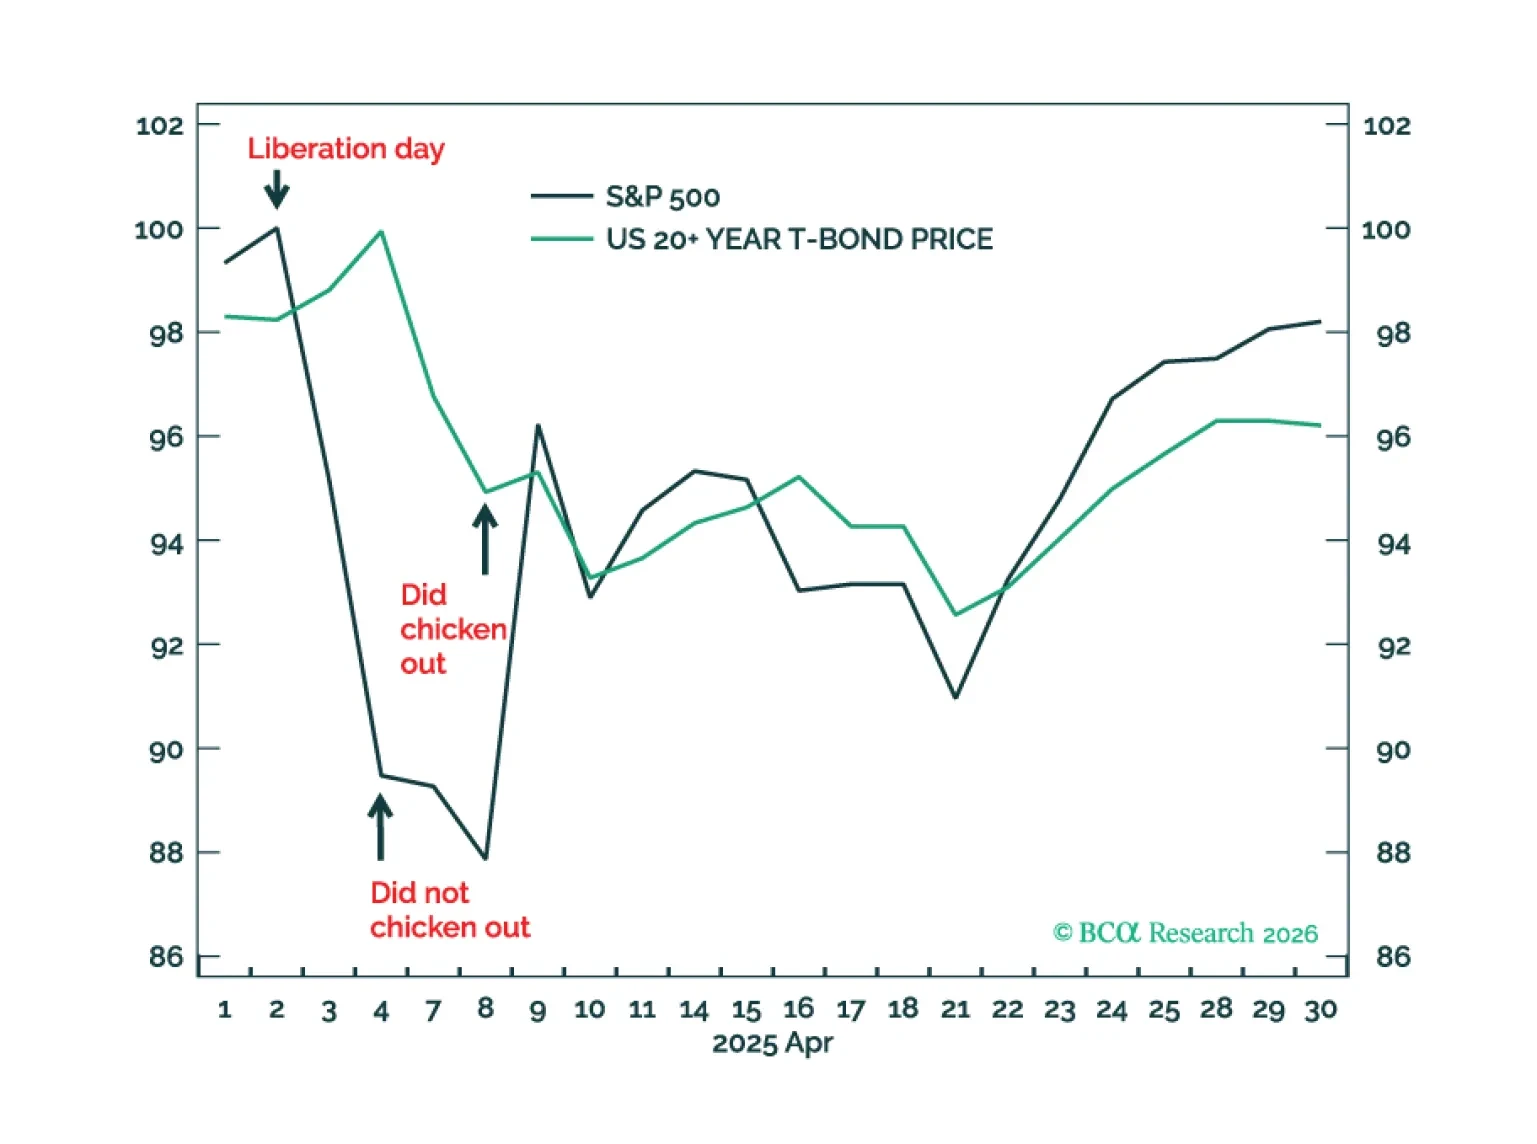
Iran doesn’t need to sink a single US warship; it could inflict much more damage by sinking the US stock and bond markets by disrupting shipping, trade, and oil tankers with decentralised low-tech drone warfare. We discuss why it is not the direct pain of higher oil prices, but the knock-on repercussions for stock and bond markets that could inflict the greater damage. Plus, a new tactical trade is to underweight Materials.
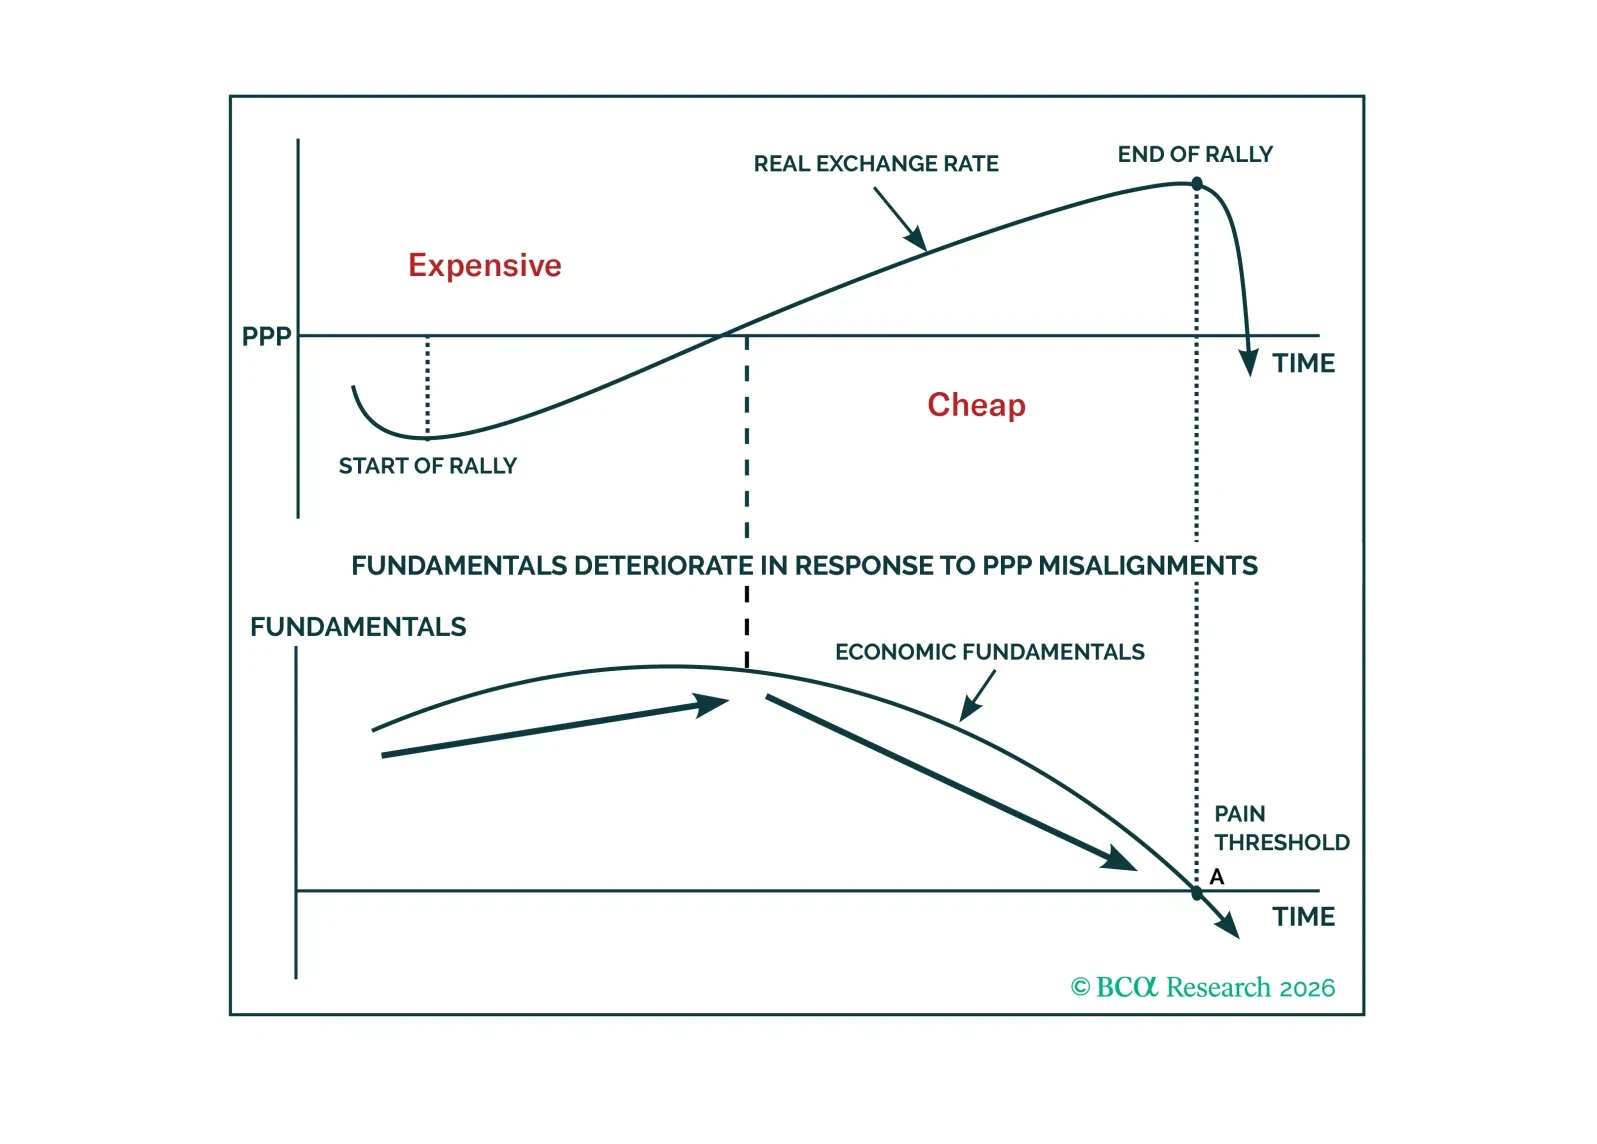
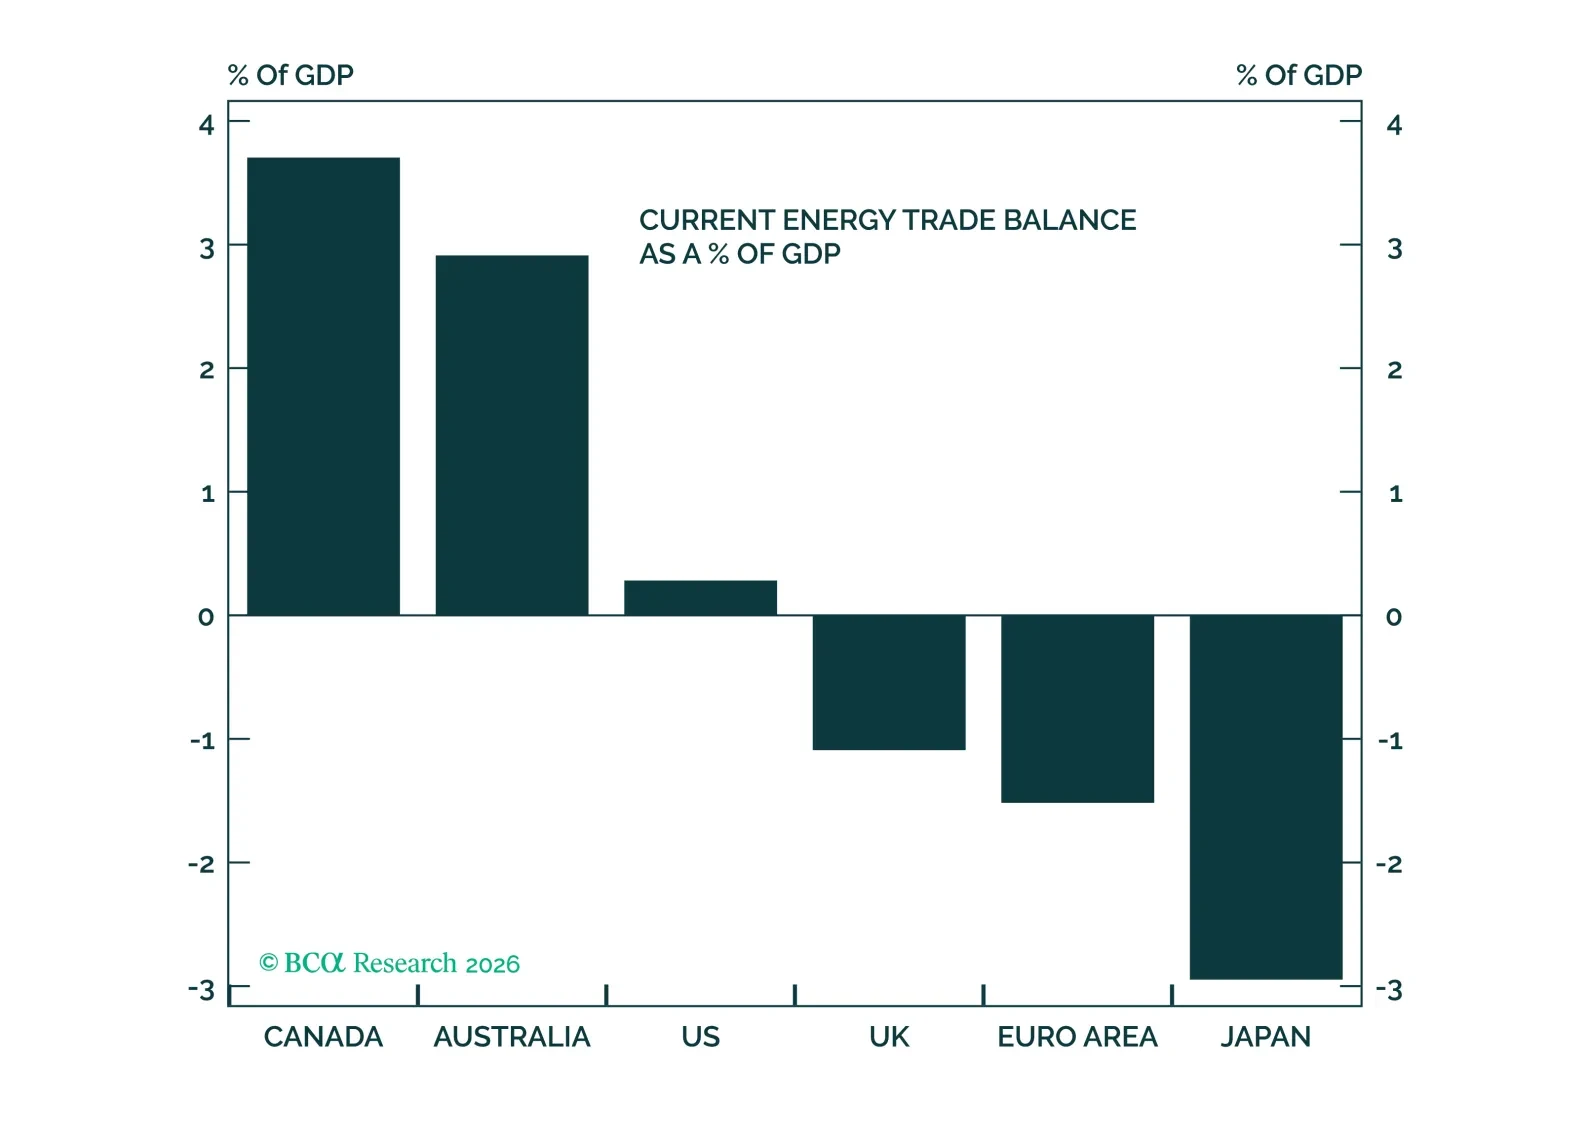
A key risk to our view has materialized. Our base case remains constructive, but risks have increased. Upgrade Tail Risk Strategies from overweight to max overweight. Upgrade Canadian equities and the Canadian dollar to overweight. Upgrade Australian equities and the Australian dollar to overweight.
Clients are universally asking us when we expect President Trump to activate the legendary “Trump Put.” We believe that the S&P 500 would have to correct by more than 10% to practically guarantee a put. We are open minded that it could occur before; it could also occur later. But a double-digit stock price decline will certainly be a greater motivator.

An energy price spike caused by a Middle Eastern war almost guarantees that Republicans will lose control of the House, and the chance of a Democratic Senate victory increases from 35% to 40%.
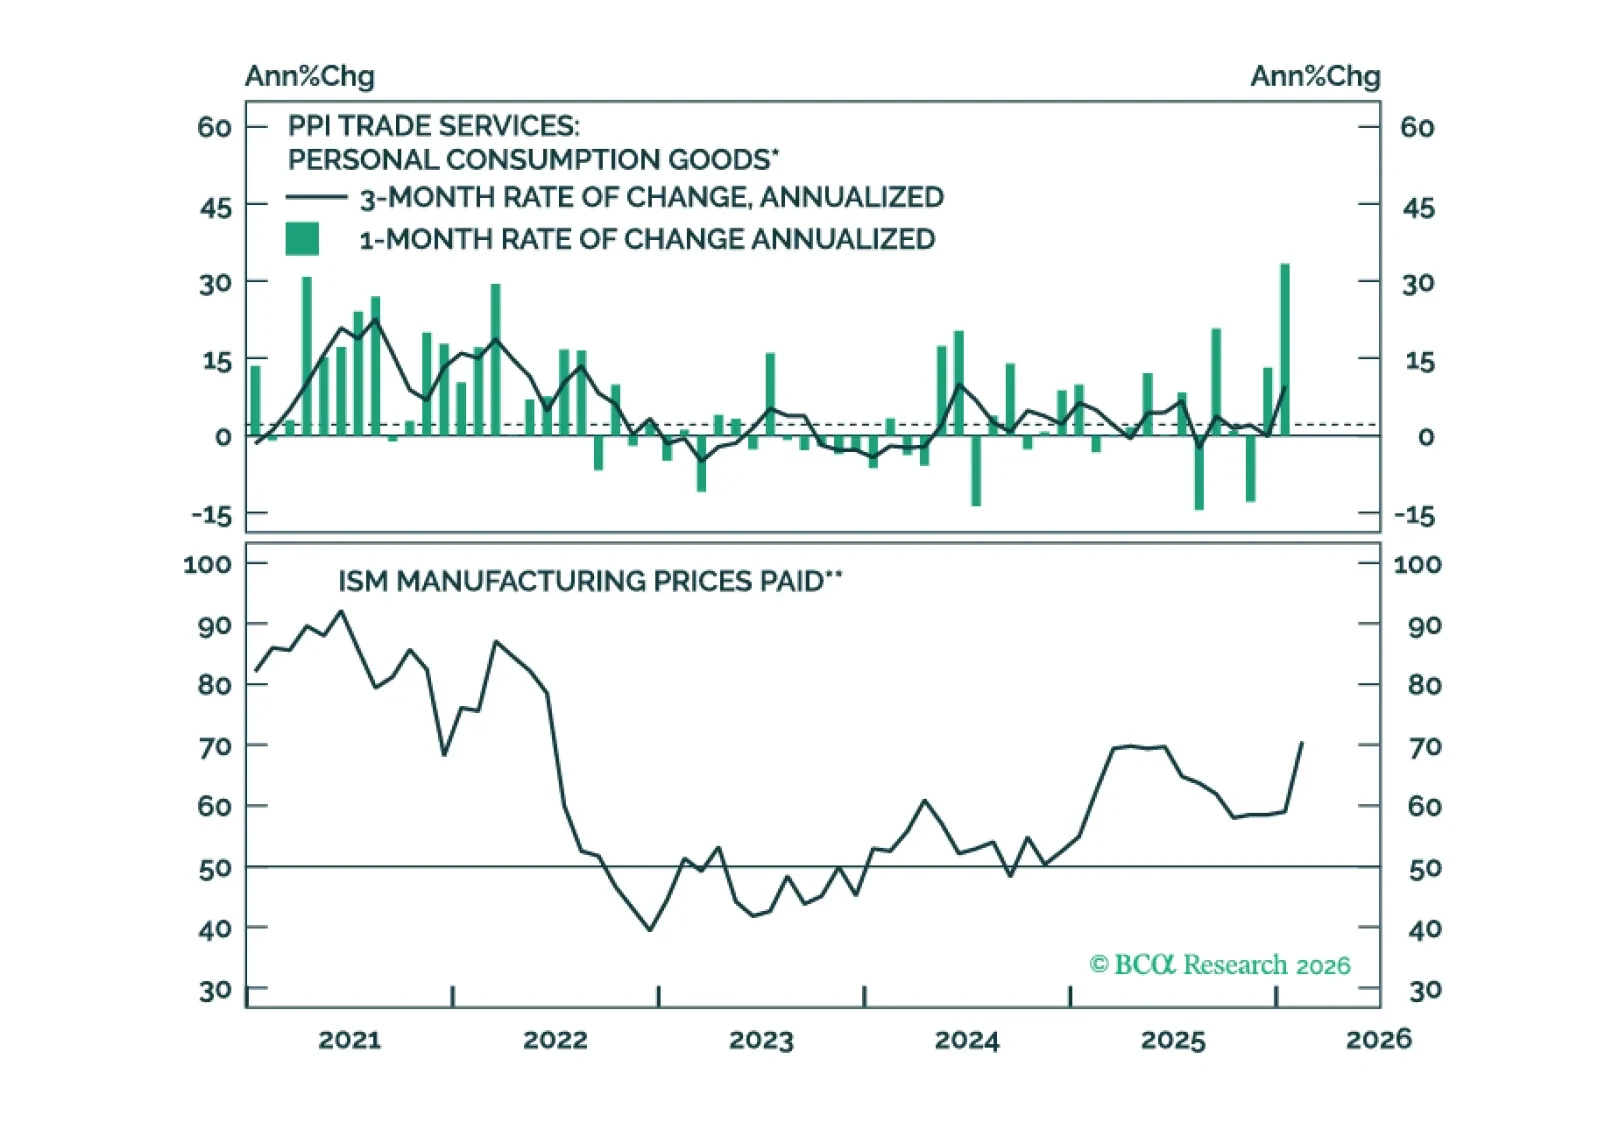
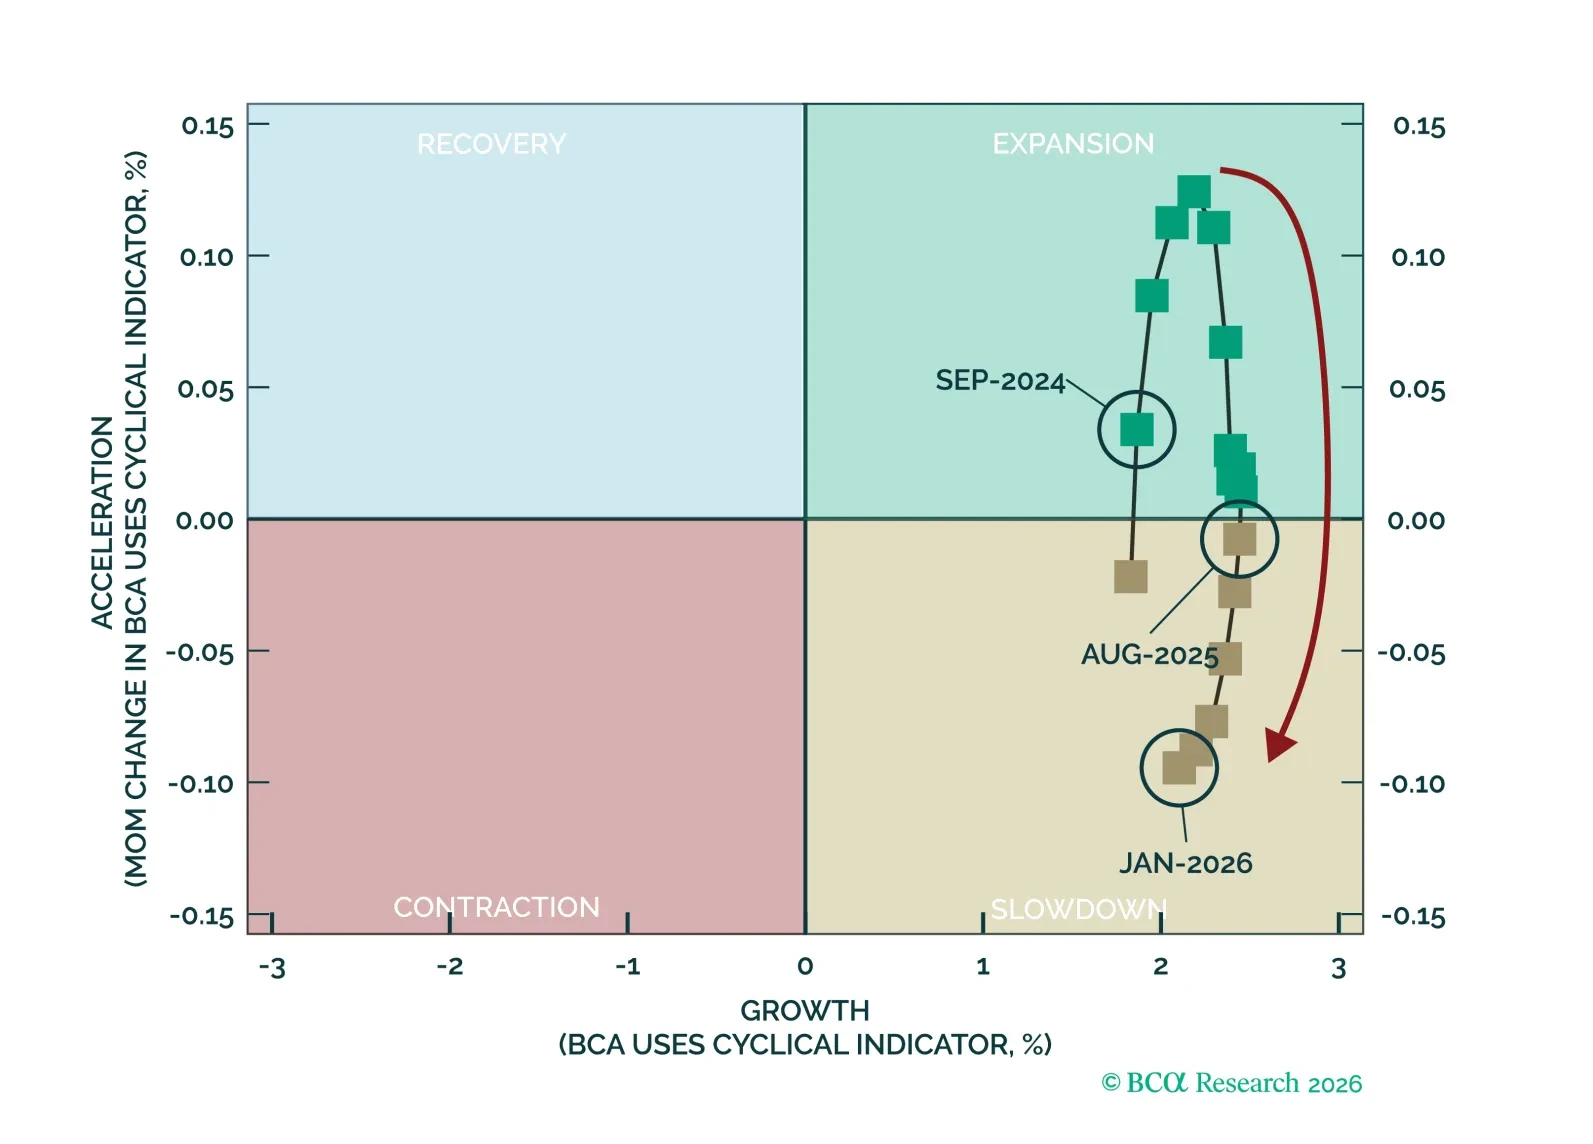
This screener report builds on the US Equity Strategy and Equity Analyzer collaboration published on 23 February 2026, where we introduced our latest framework for assessing the US business cycle. Here, we apply the framework to our screener to identify how bottom-up equity positioning should adapt as the cycle evolves.