Latest from BCA Research
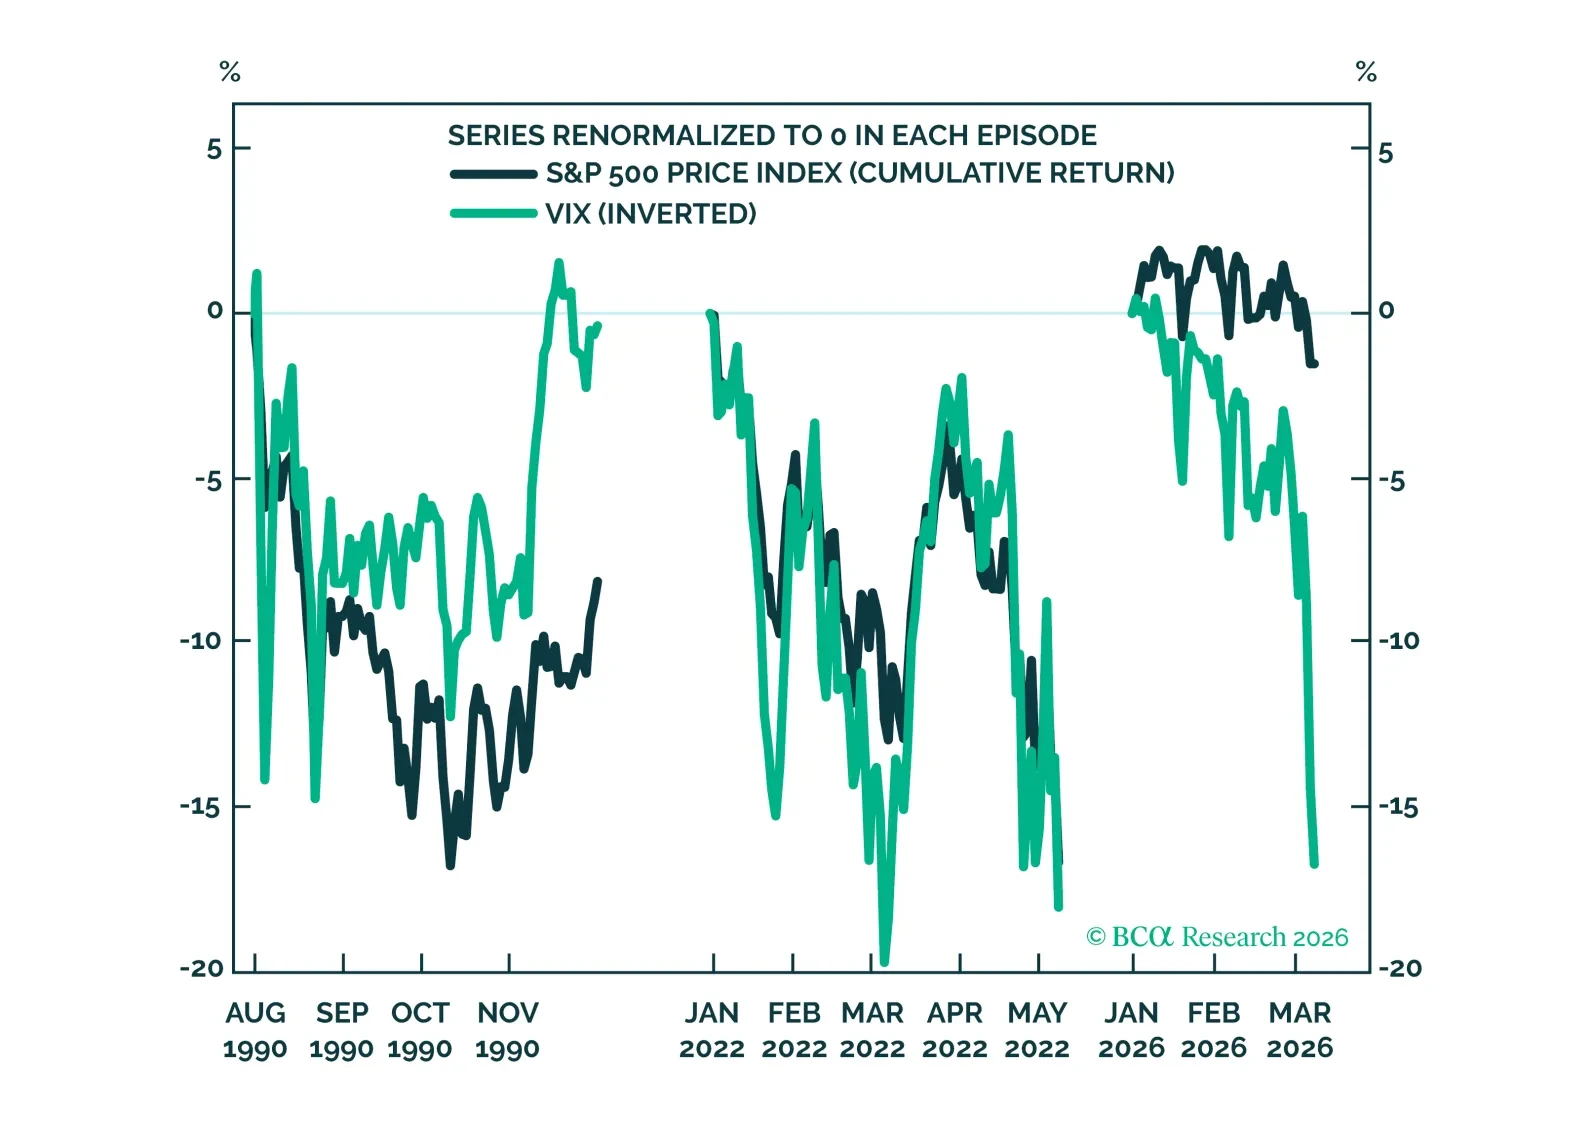
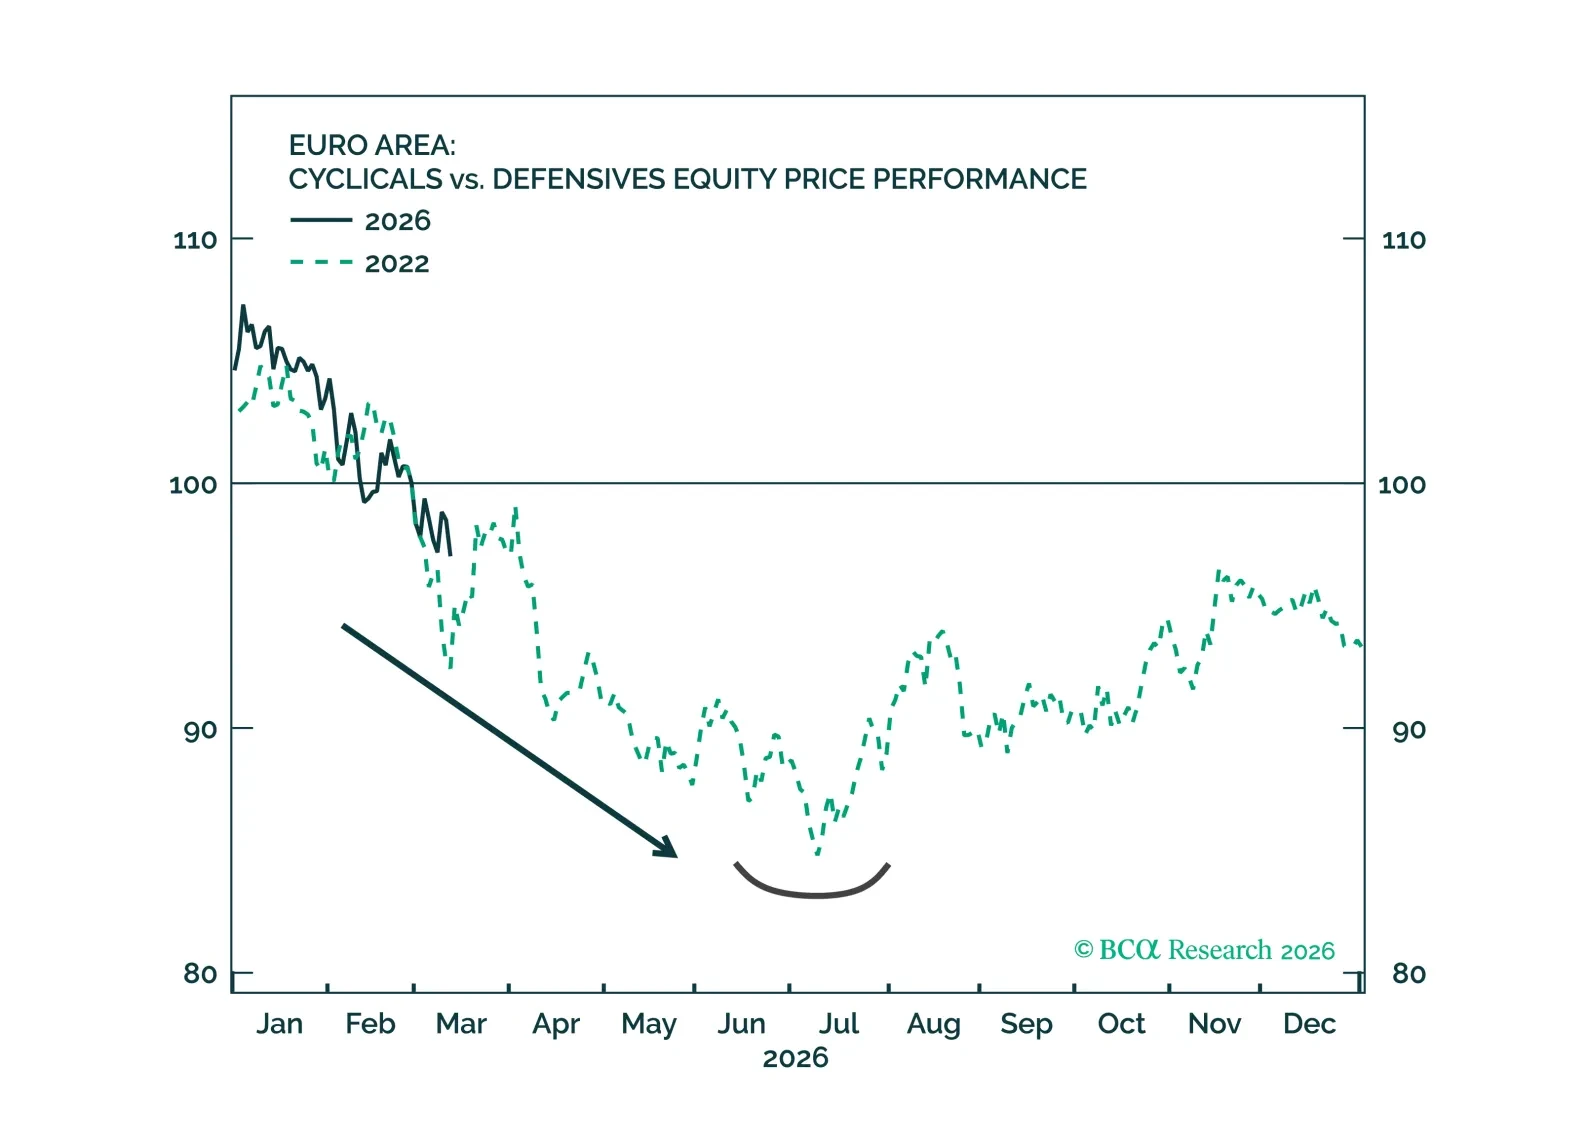
Middle East tensions sparked a surge in volatility, yet the S&P 500 decline has been comparatively modest. Across asset classes, moves seem related to risk preferences and near-term inflation concerns. Within equities, some cyclicals are under pressure, but the equity market’s growth view has been resilient, while the inflation view has climbed.
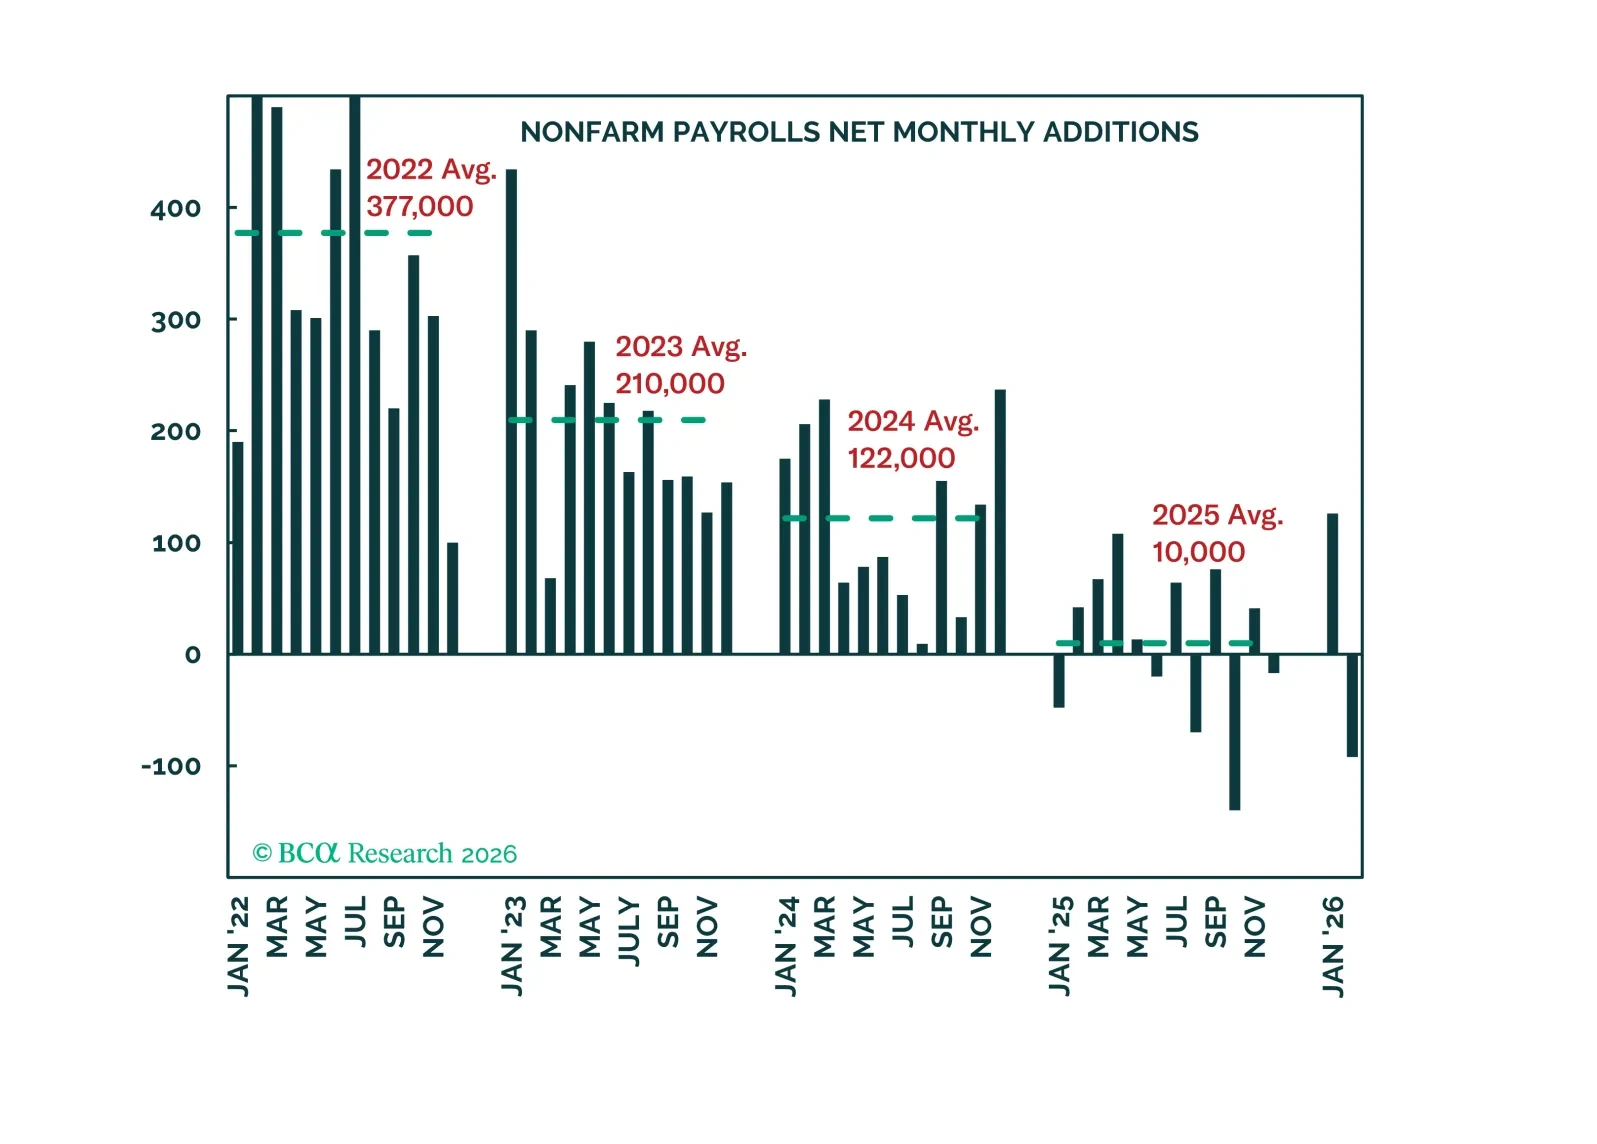
Job creation remains stalled, but consumers are carrying on and S&P 500 earnings have been growing by double digits. Although the repercussions from the war in the Middle East are not yet clear, the US economy was doing just fine before it began.
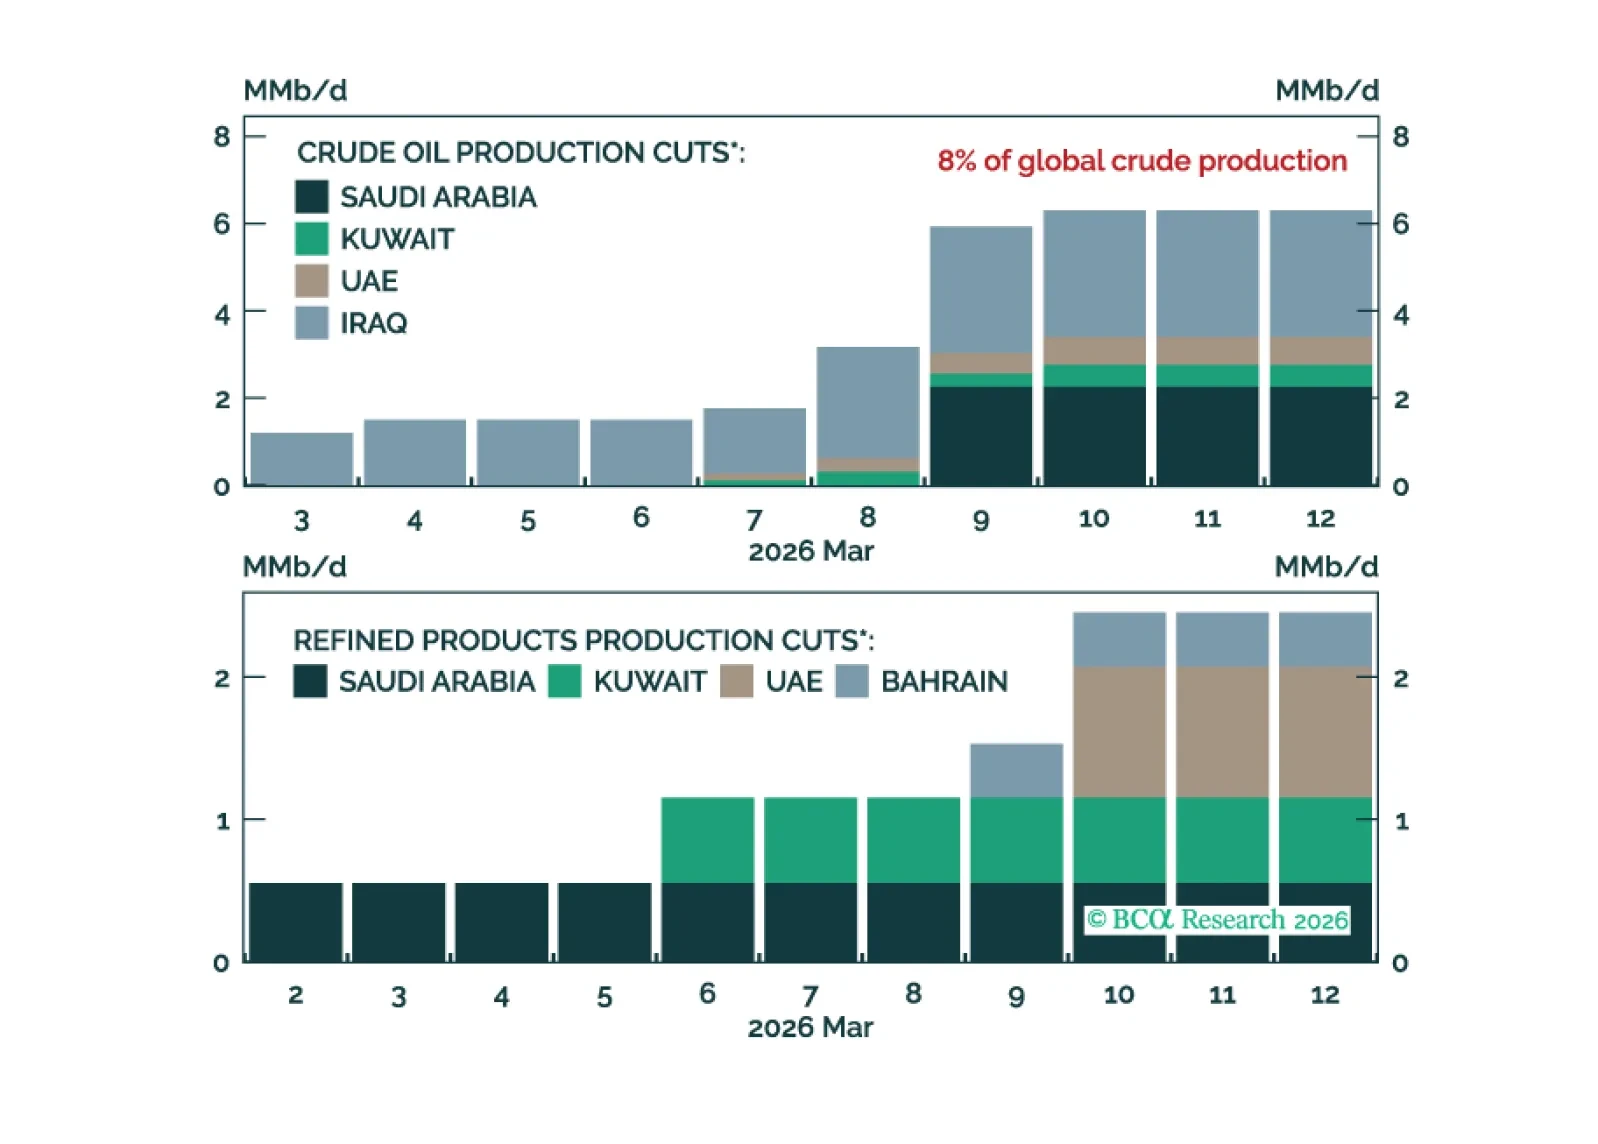
War momentum and escalating rhetoric around the Strait of Hormuz have pushed Brent above $100 and raised the risk of a broader supply shock. While parallels with 2022 offer a roadmap, today’s shock is likely shorter but more globally disruptive. Markets are repricing monetary tightening risks, though we see rate hikes as a mistake absent second-round inflation. Beyond oil, sulfur, helium, and fertilizer disruptions threaten food prices and the AI supply chain. Position defensively.
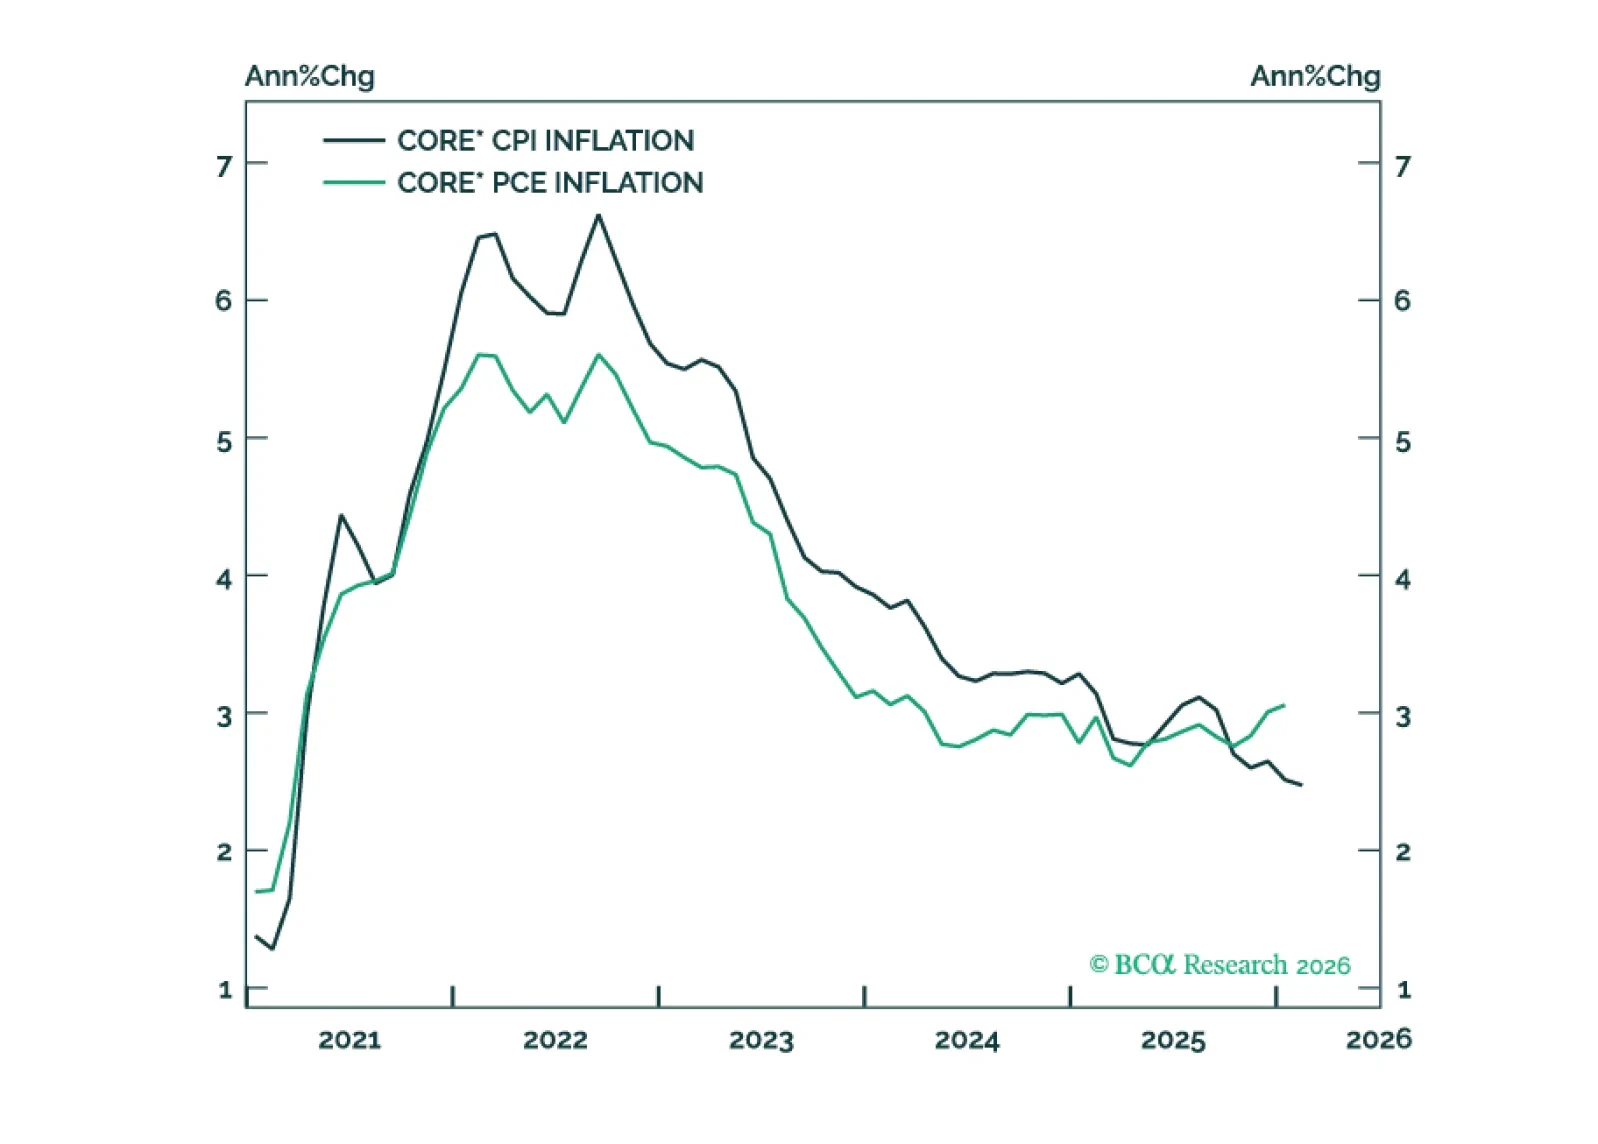
The gap between PCE and CPI inflation will narrow within the next few months, mostly driven by core PCE inflation converging toward its trimmed mean.
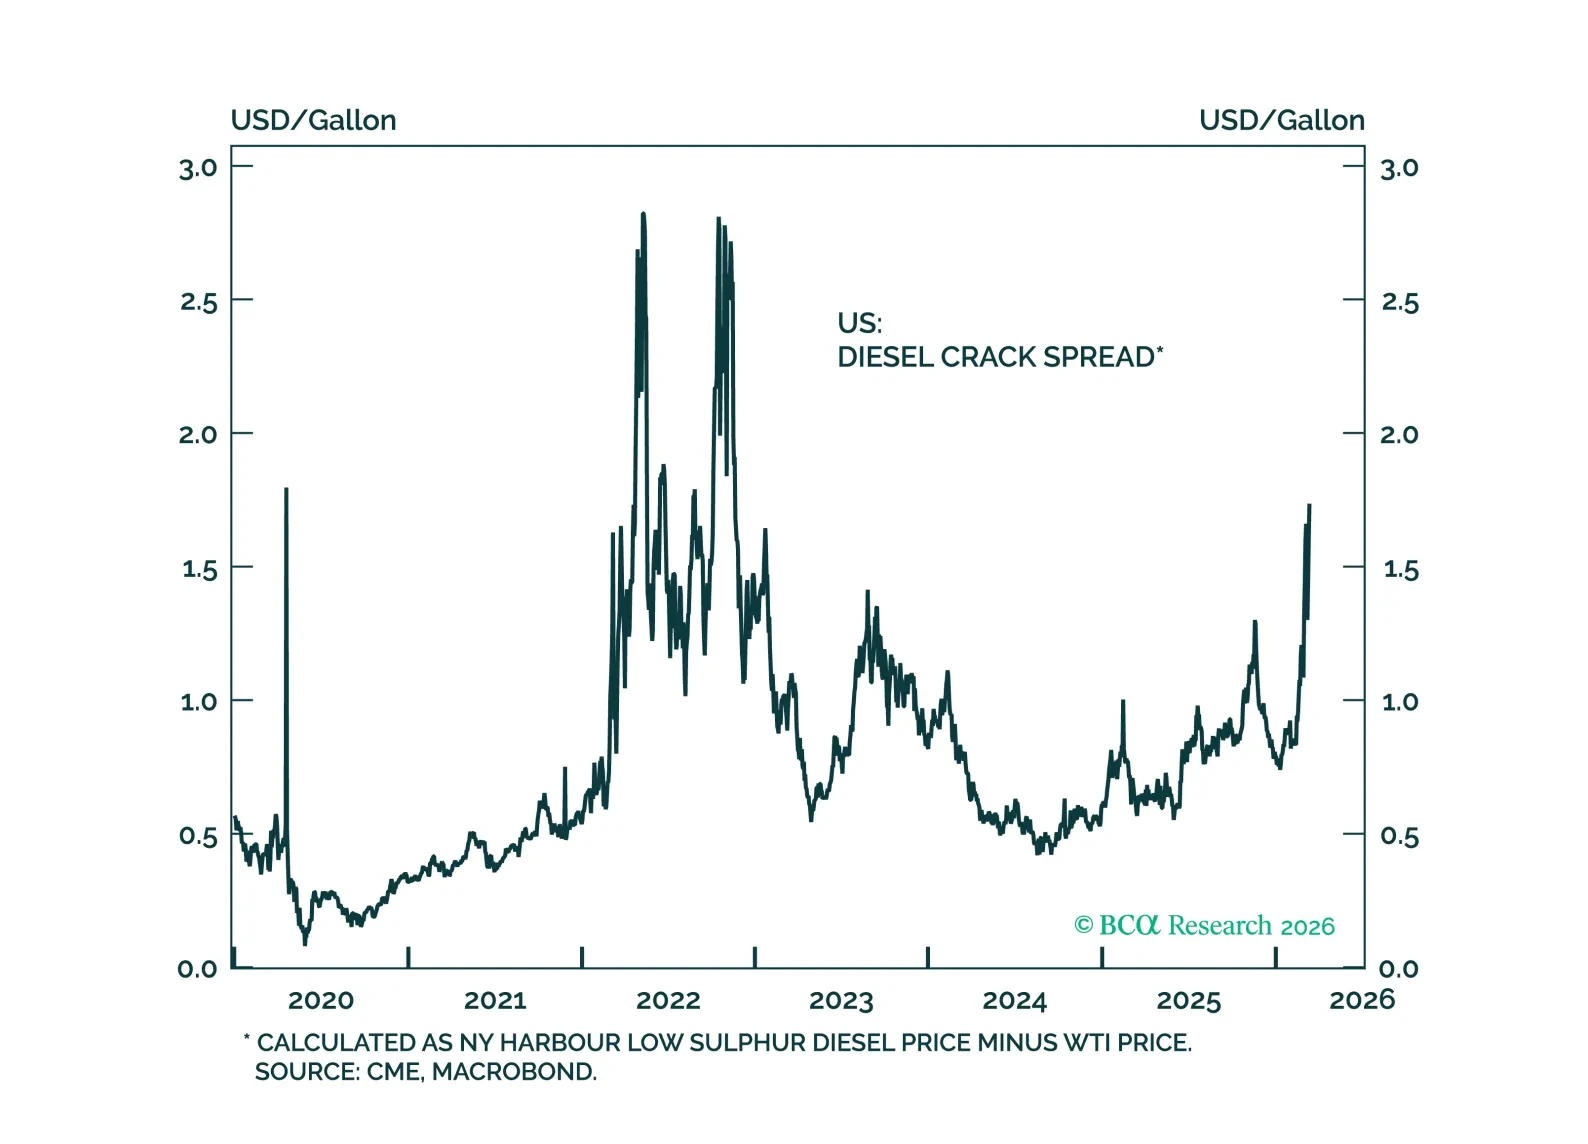
Investors are too complacent on the closure of the Strait of Hormuz. Upgrade cash and downgrade equities, both to neutral.
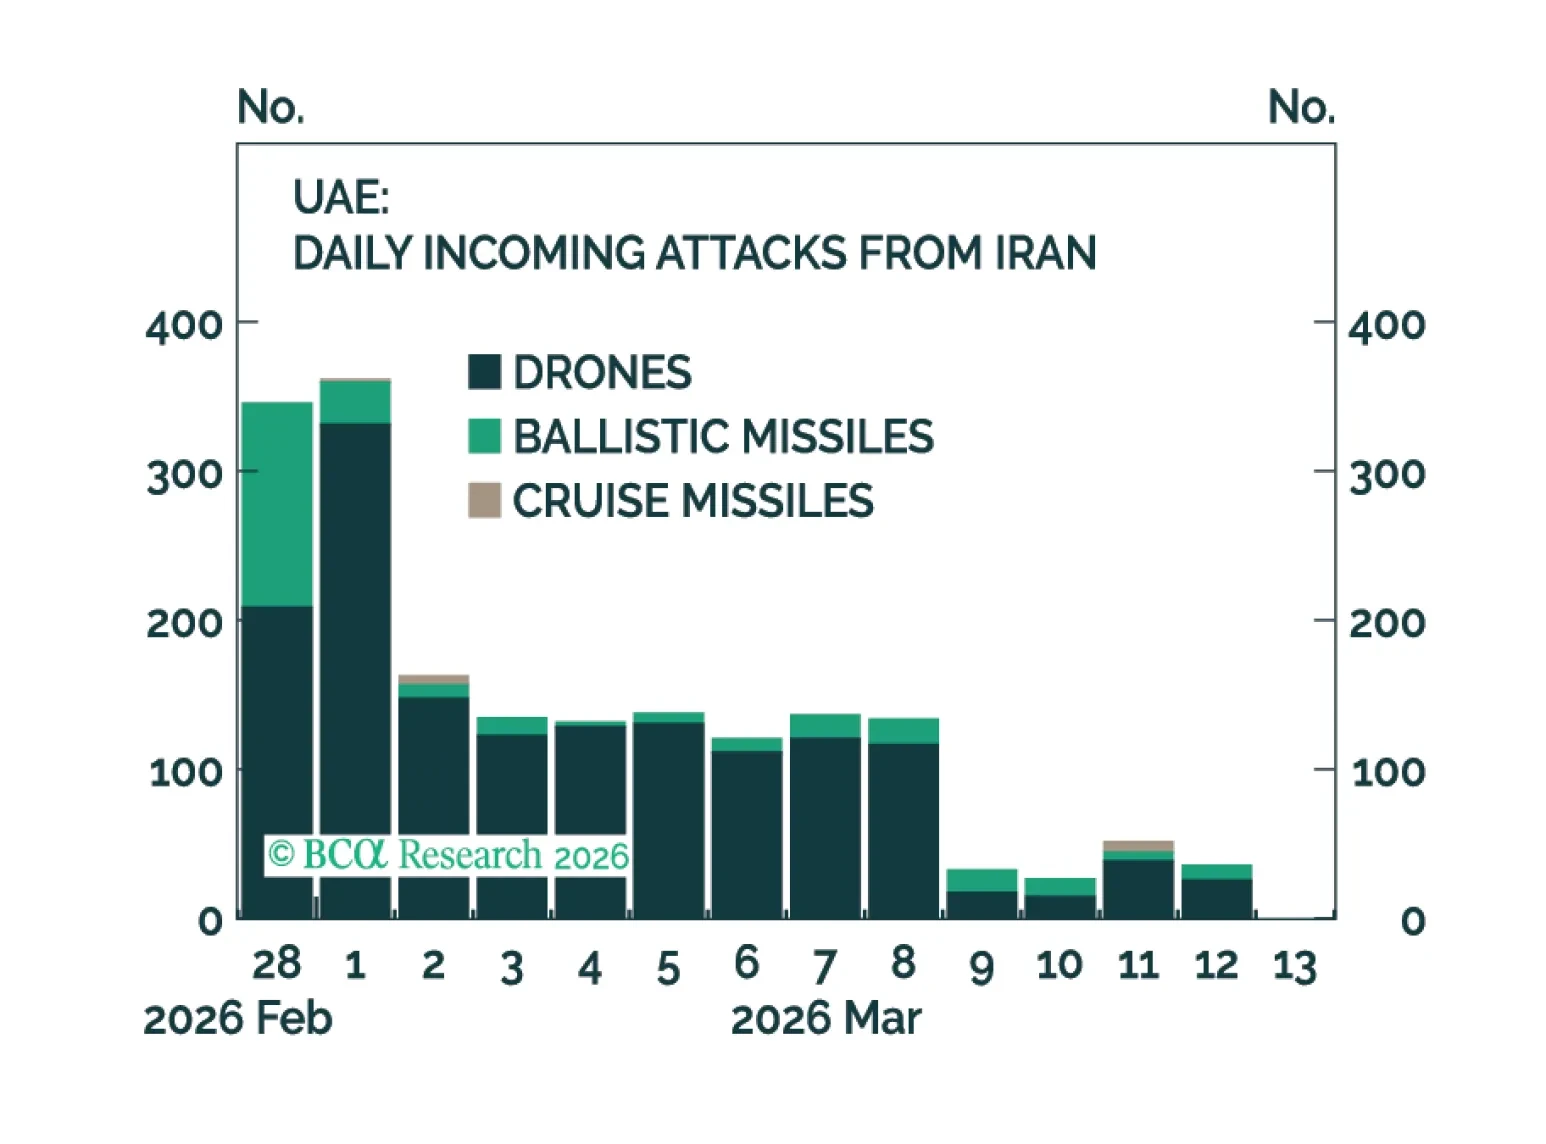
The conflict in Iran has entered the “post-Trump taco zone” where it is now all about Tehran’s reaction function.
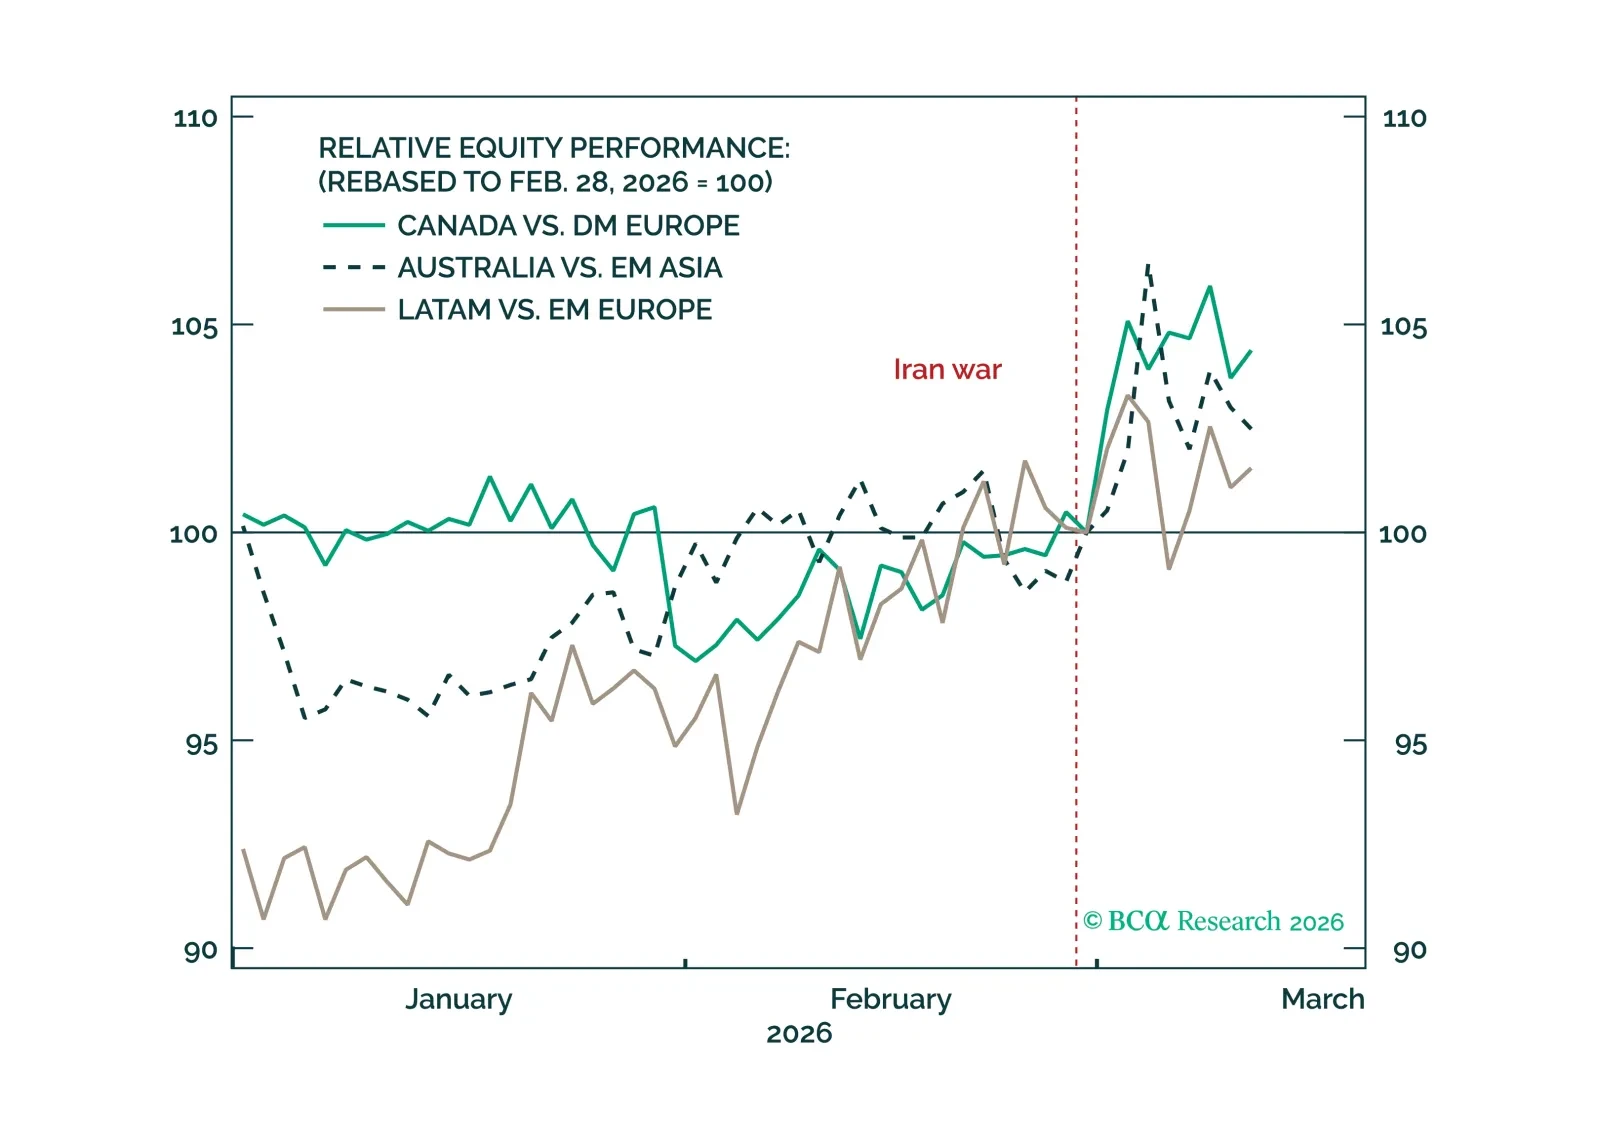
Regional geopolitical risk is rising for Europe, EM Asia, and South Asia. We adjust our regional risk matrix accordingly.
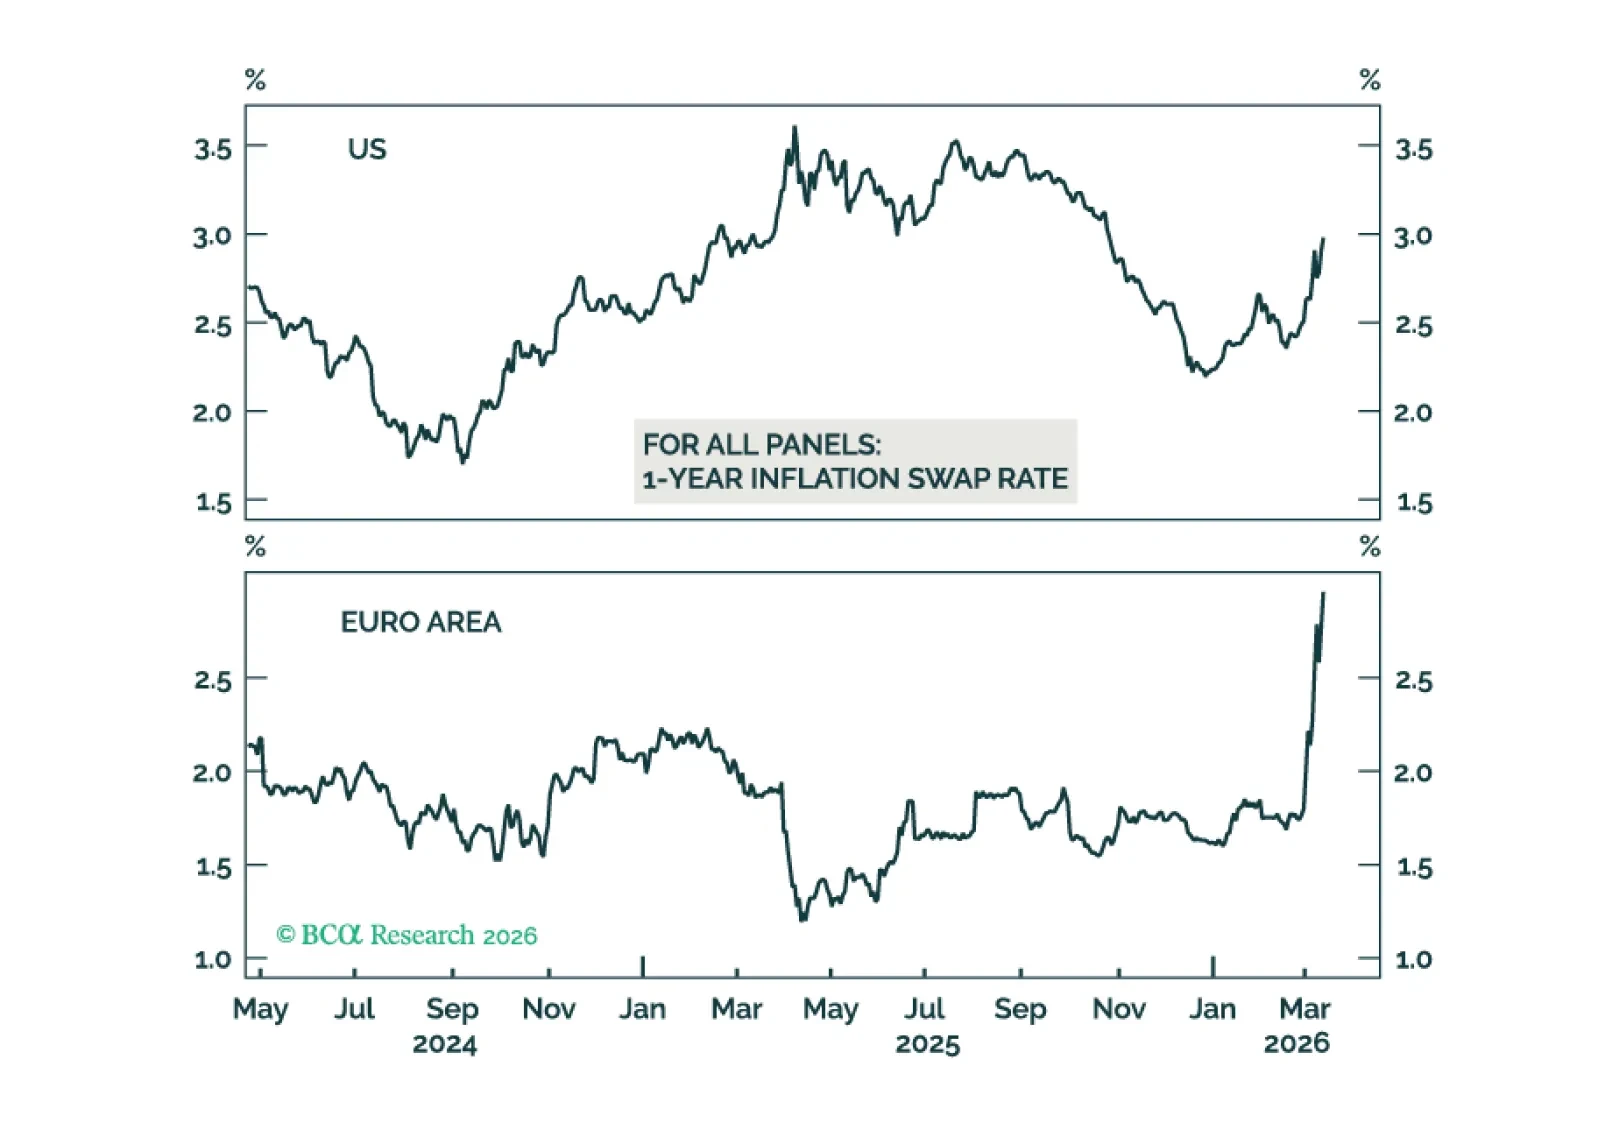
The spike in oil and gas prices has raised the odds of a global economic downturn. Combined with a more negative signal from our MacroQuant model, this warrants tactically downgrading stocks from neutral to underweight. Looking further ahead, the Iran war will lead to bigger defense budgets and a greater focus on energy self-sufficiency.