Latest from BCA Research
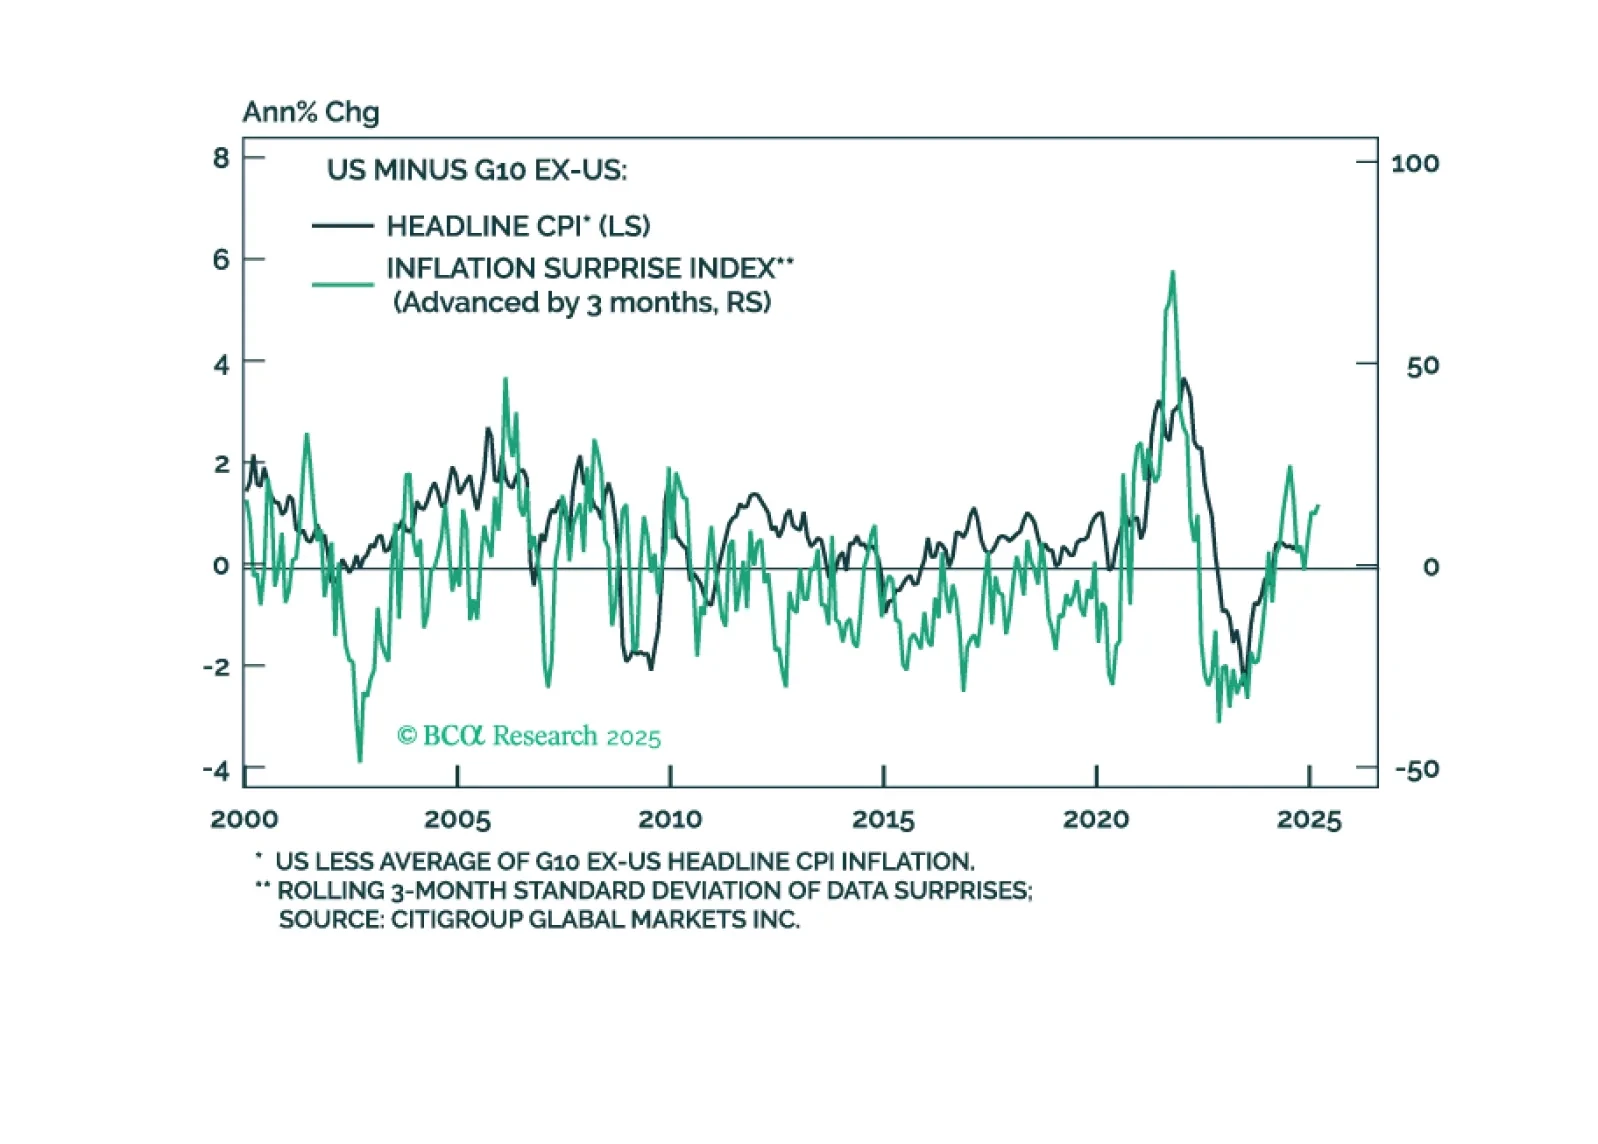
In this week’s report, we look at the likely trend for bonds yields and the dollar in the coming months.
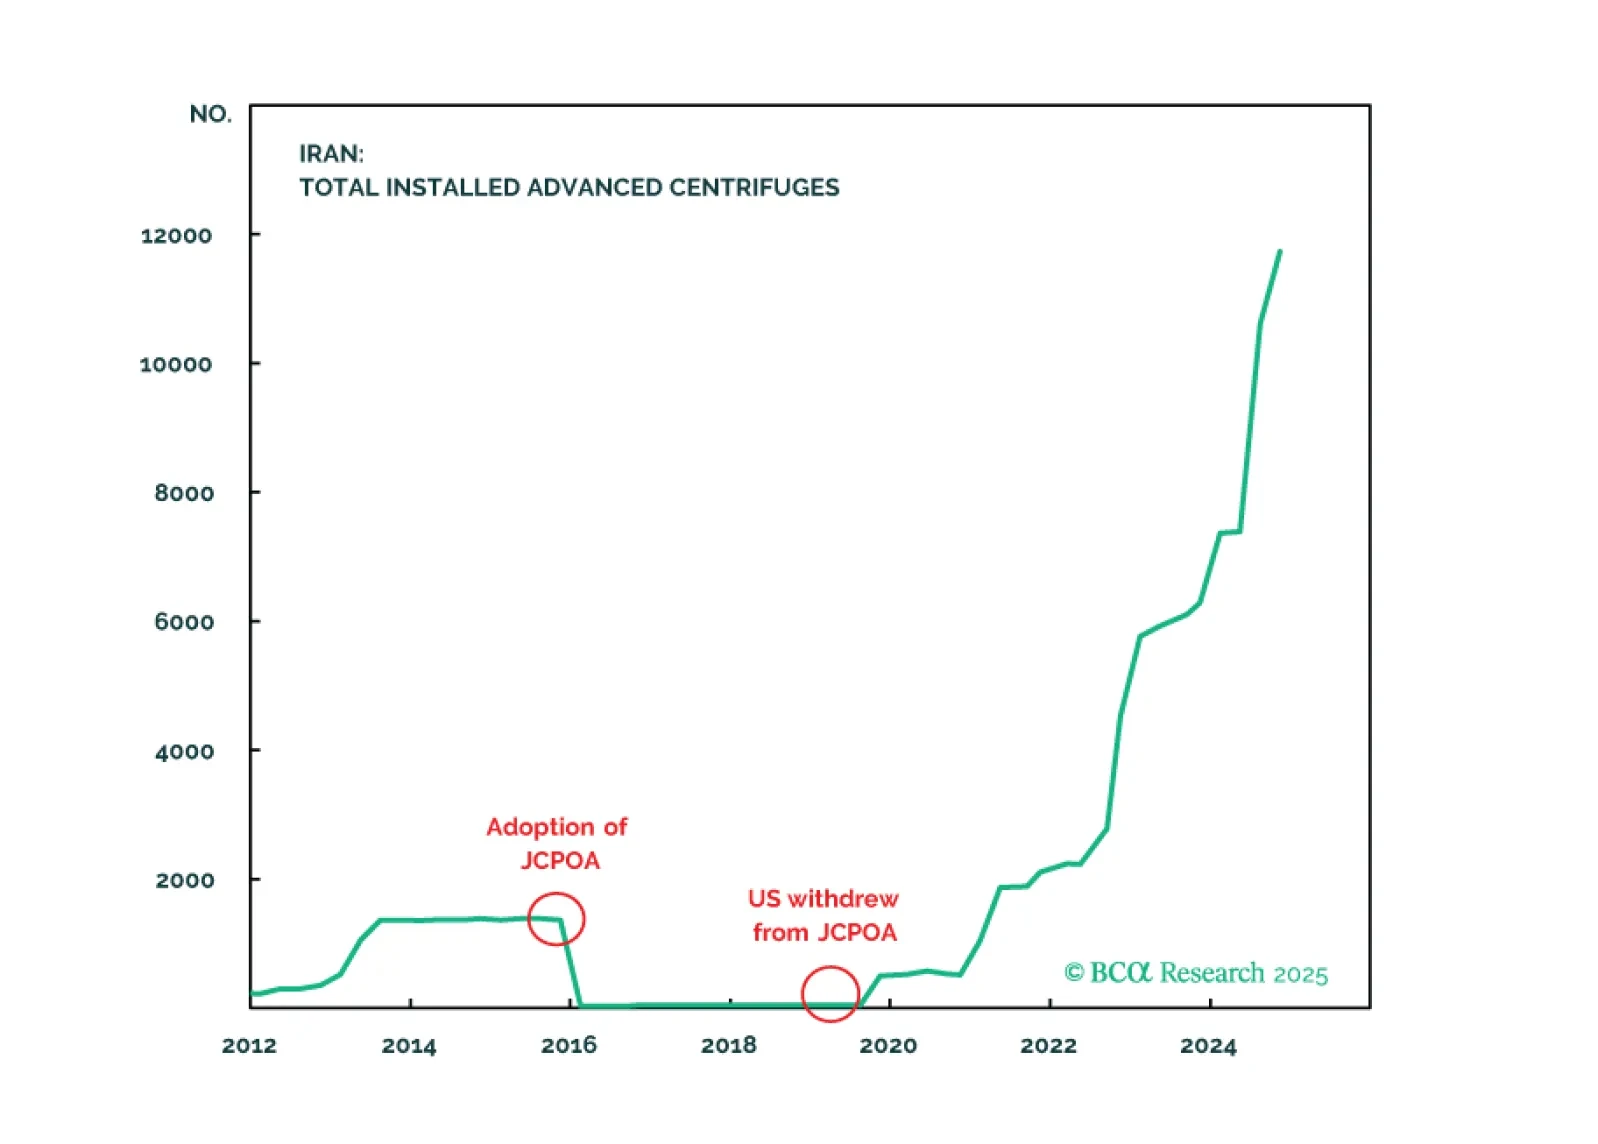
Every year we highlight five low-odds scenarios that would have a major impact on global financial markets if they happened. This year we contemplate a total reversal of Chinese policy, a US-Iran nuclear deal, a breakdown of NATO, US military action across the Americas, and an internationally coordinated FX intervention.
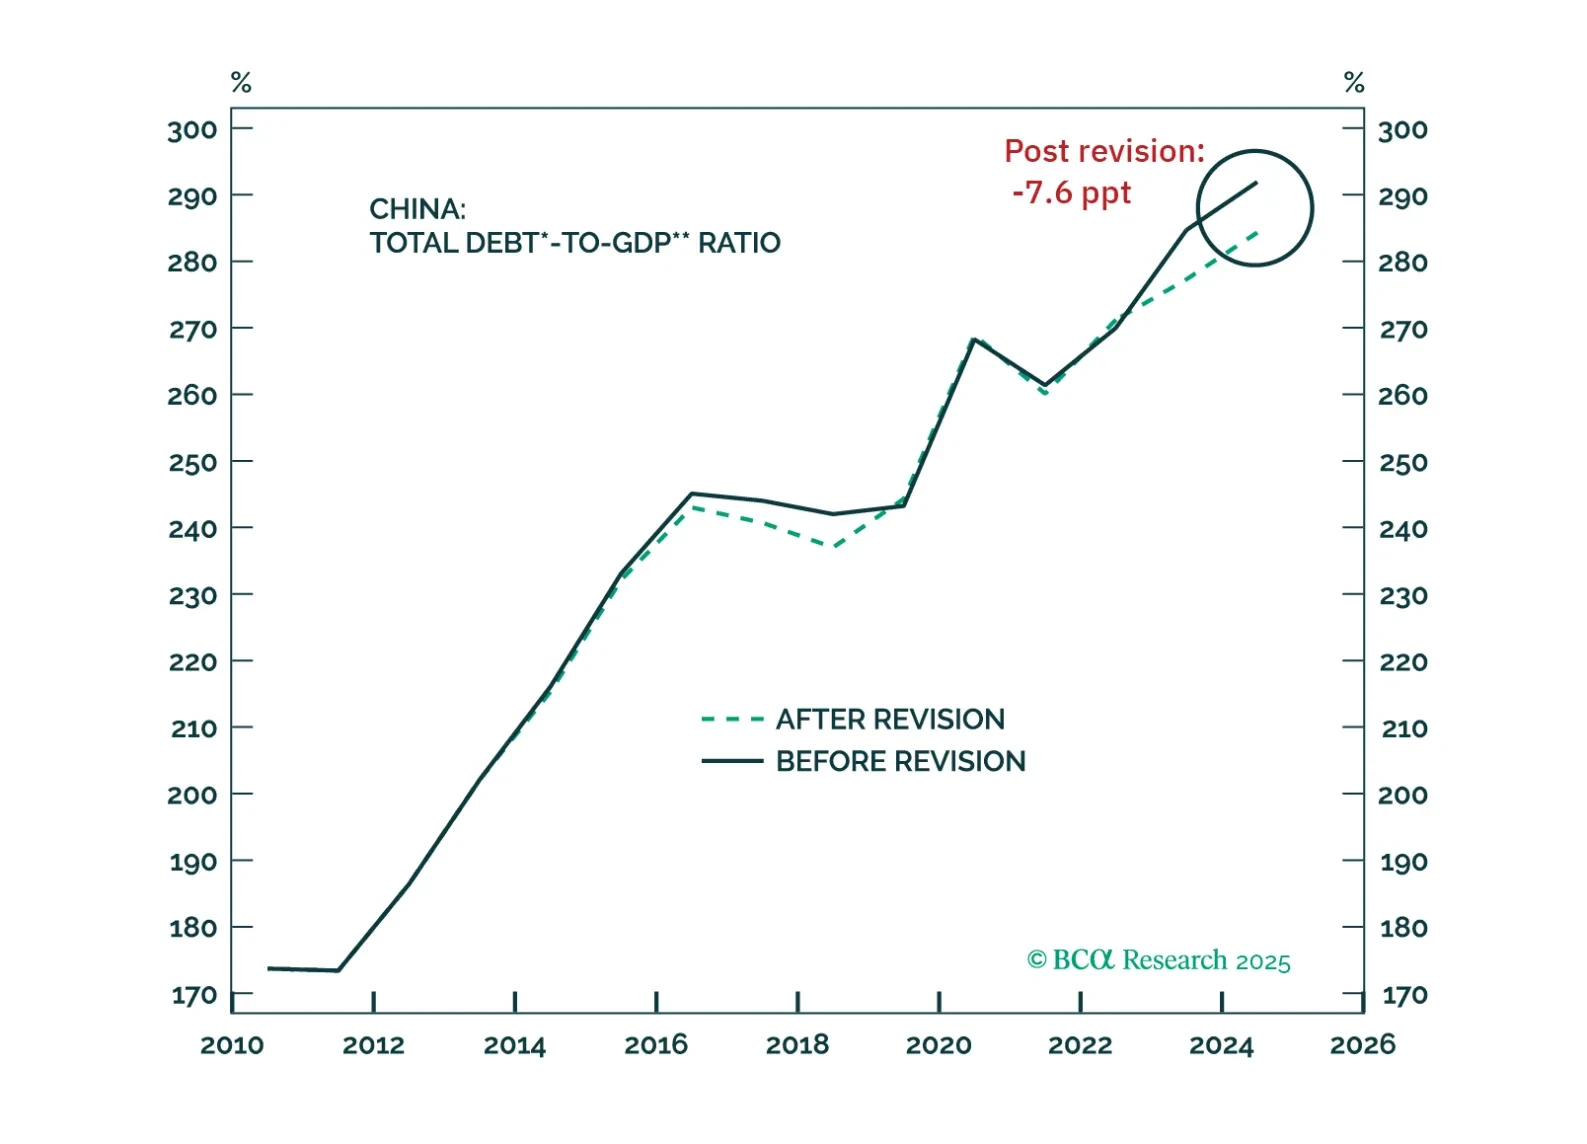
In this week’s report, we present our key takeaways from China's two notable adjustments recently implemented: an upward revision to its 2023 GDP and the reduction of the USD weighting in the RMB Exchange Rate Index.
It is rare for BCA Research strategists to be at the literal scene of macro calamities. The denizens of our GeoMacro team – including yours truly – live within the mandatory evacuation zones of the now increasingly on fire Los Angeles. Contrary to the conventional view, this does not make for a sober analysis. Those impacted by natural disasters and geopolitical events are often the least likely to be able to provide a neutral analysis.
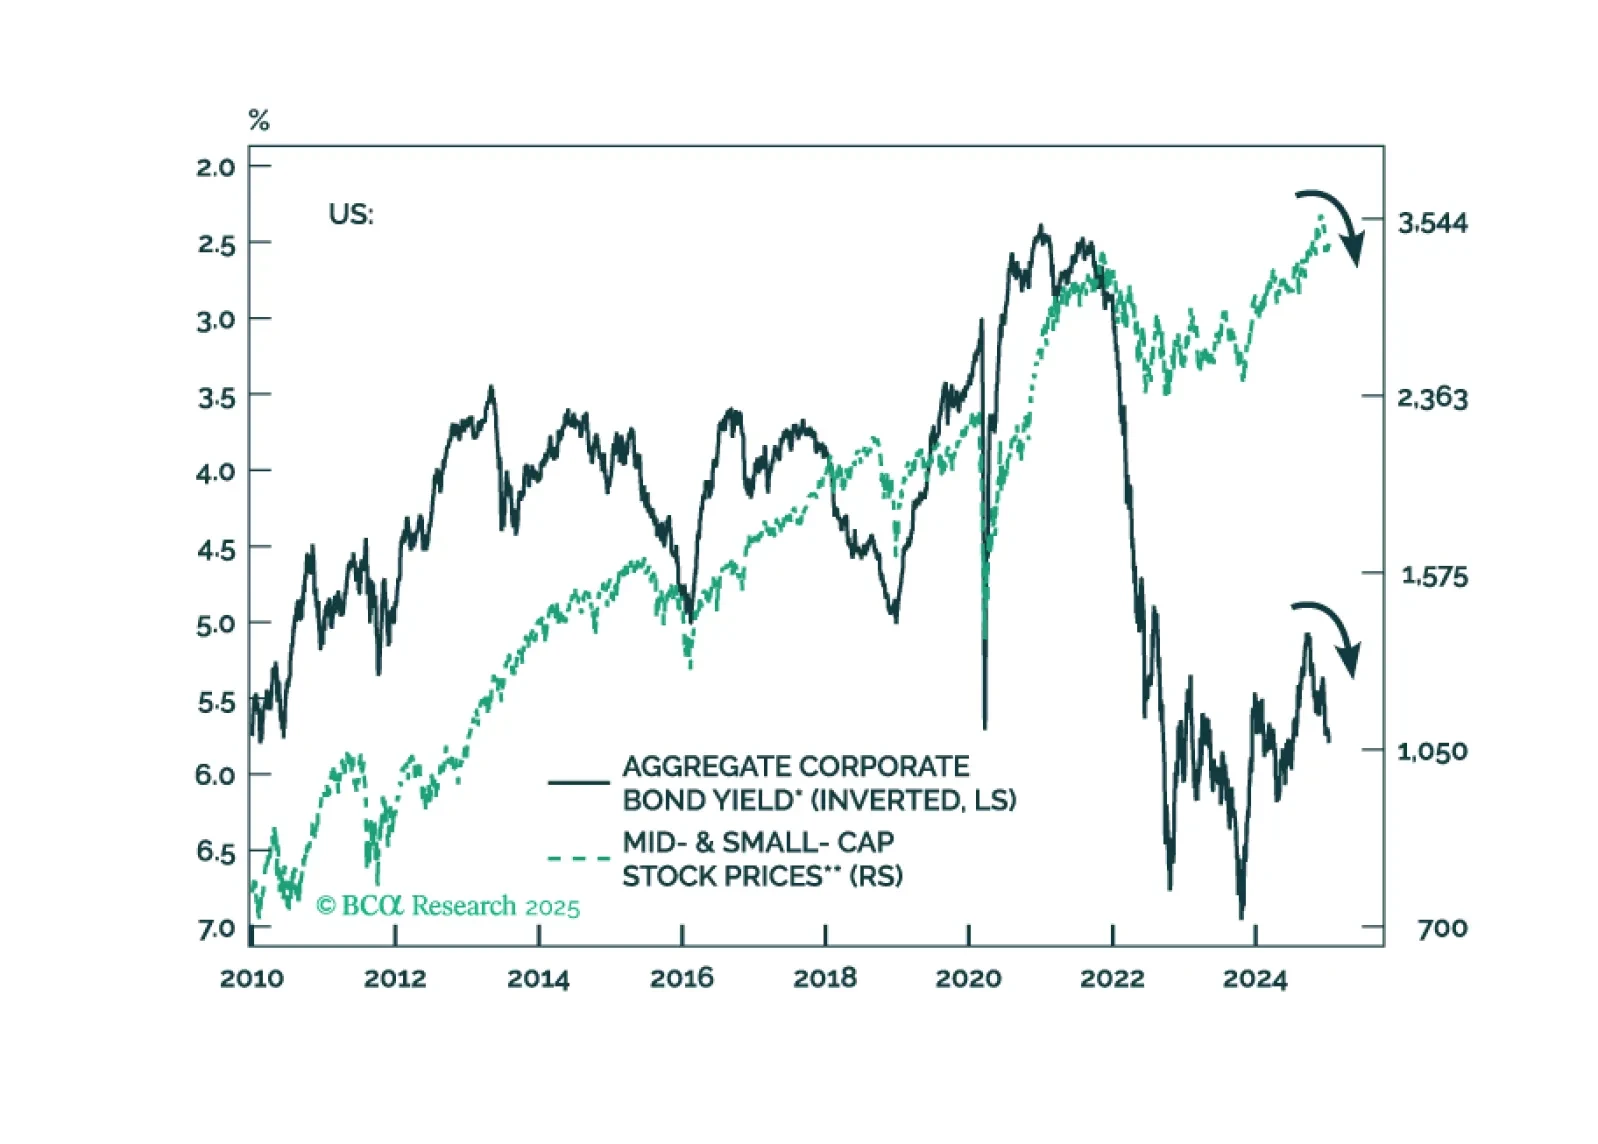
US bond yields will move higher, unleashing a storm in global financial markets. In the US, rising corporate bond yields will produce a selloff in share prices. In Mainstream EM, rising domestic and USD bond yields will weigh on share prices.
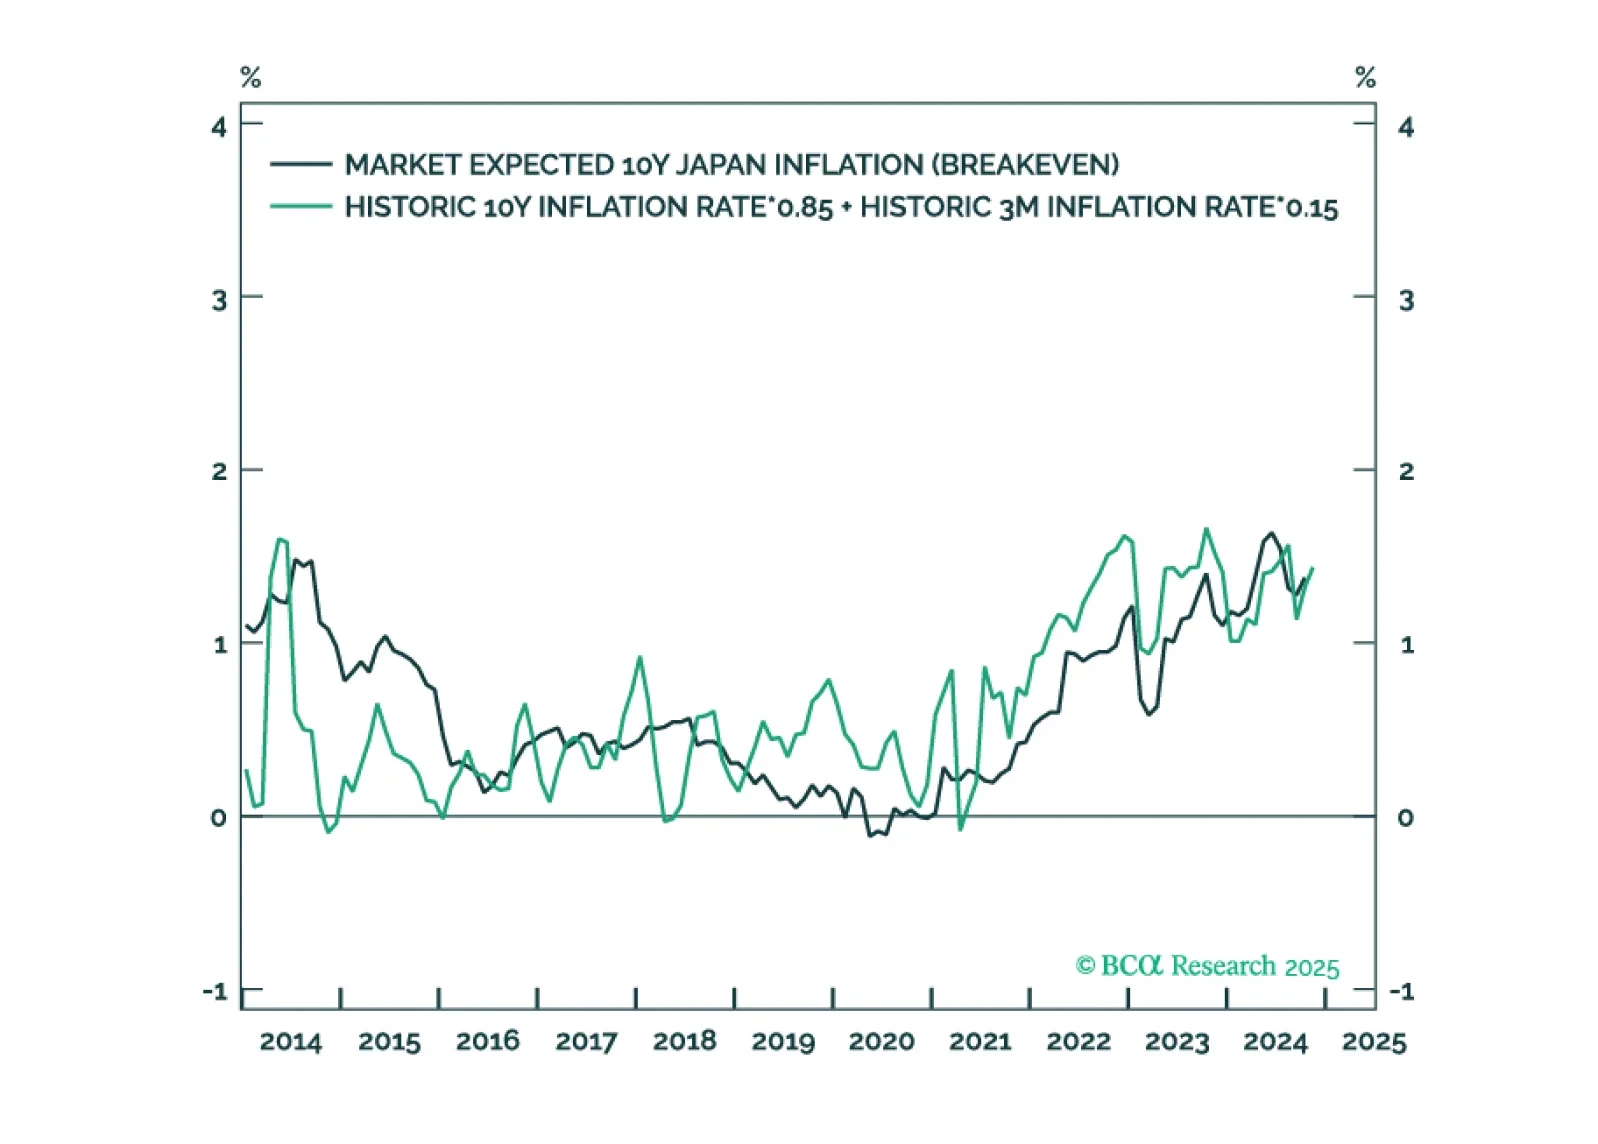
In most developed economies, rising inflation expectations will lift them further above the 2 percent target, limiting the scope for further interest rate cuts. But in Japan, rising inflation expectations will lift them up to the BoJ’s 2 percent target, removing the BoJ’s justification for its zero-interest rate policy. The normalisation of Japan’s monetary policy poses a big structural risk to stocks because Japan has been the main source of financial market liquidity, and thereby, of rising stock market valuations. From a timing perspective though, wait until the complexities of the price trends in USD/JPY and/or Nasdaq versus 30-year T-bond have collapsed. Plus: go tactically long copper.
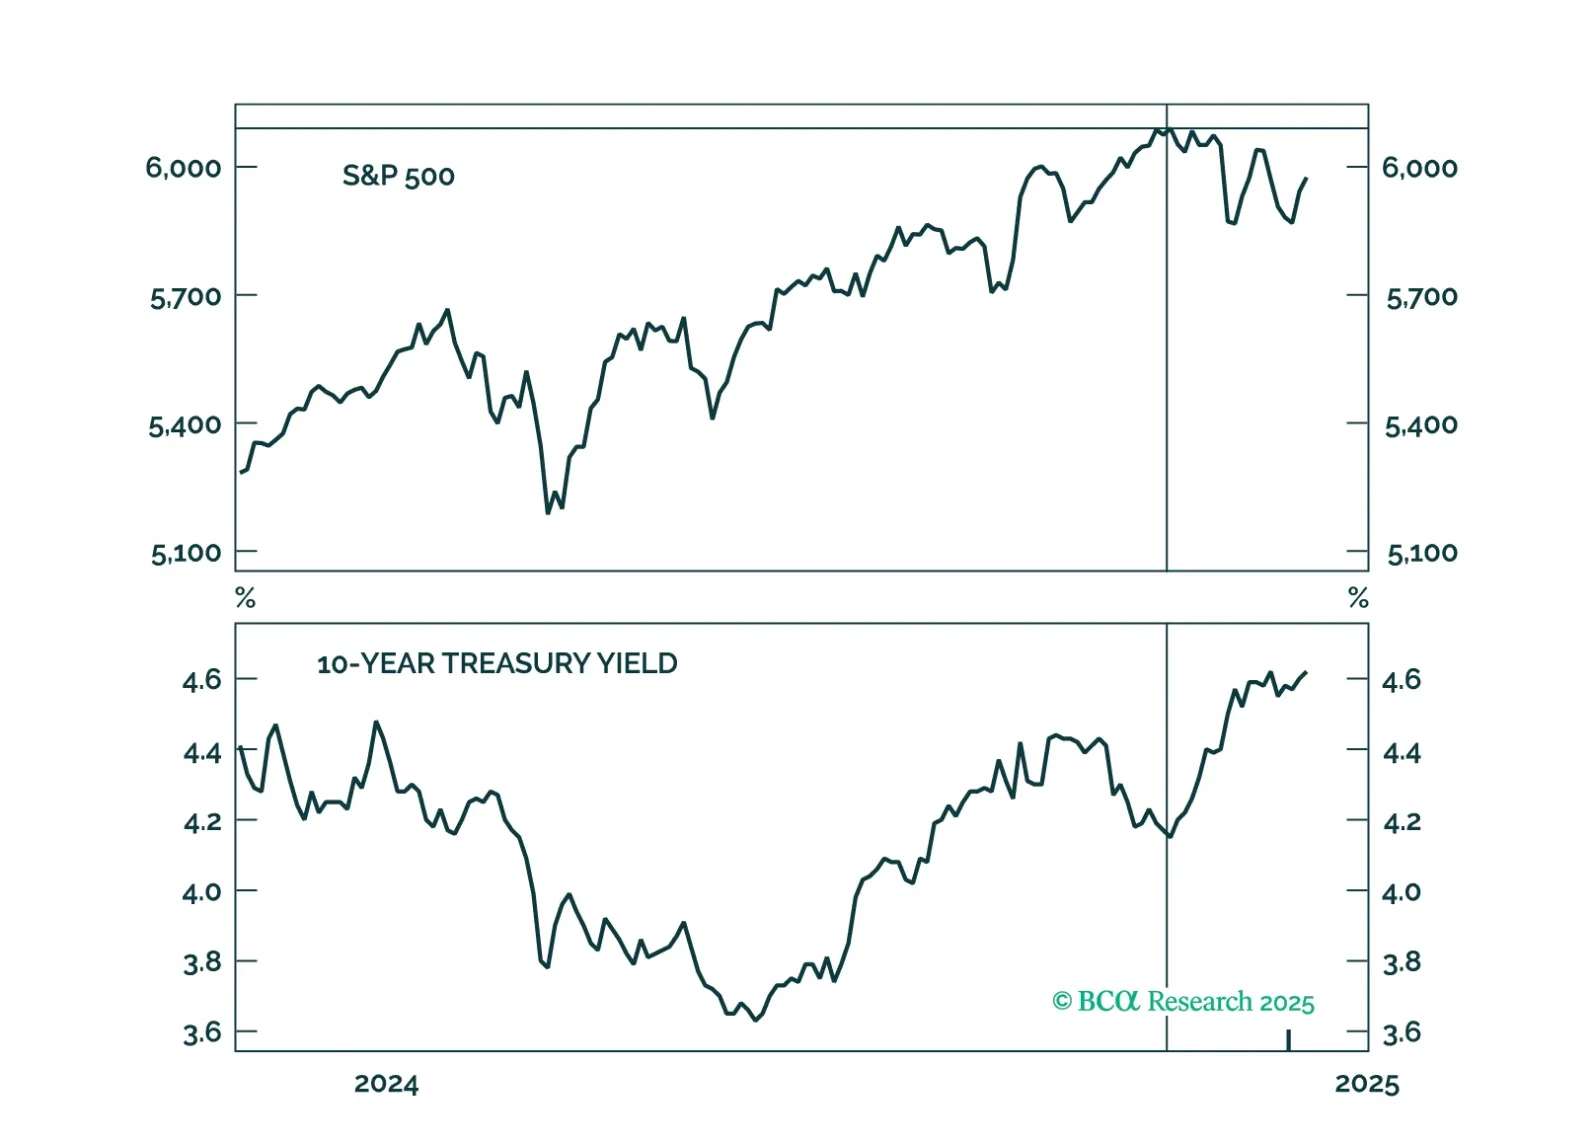
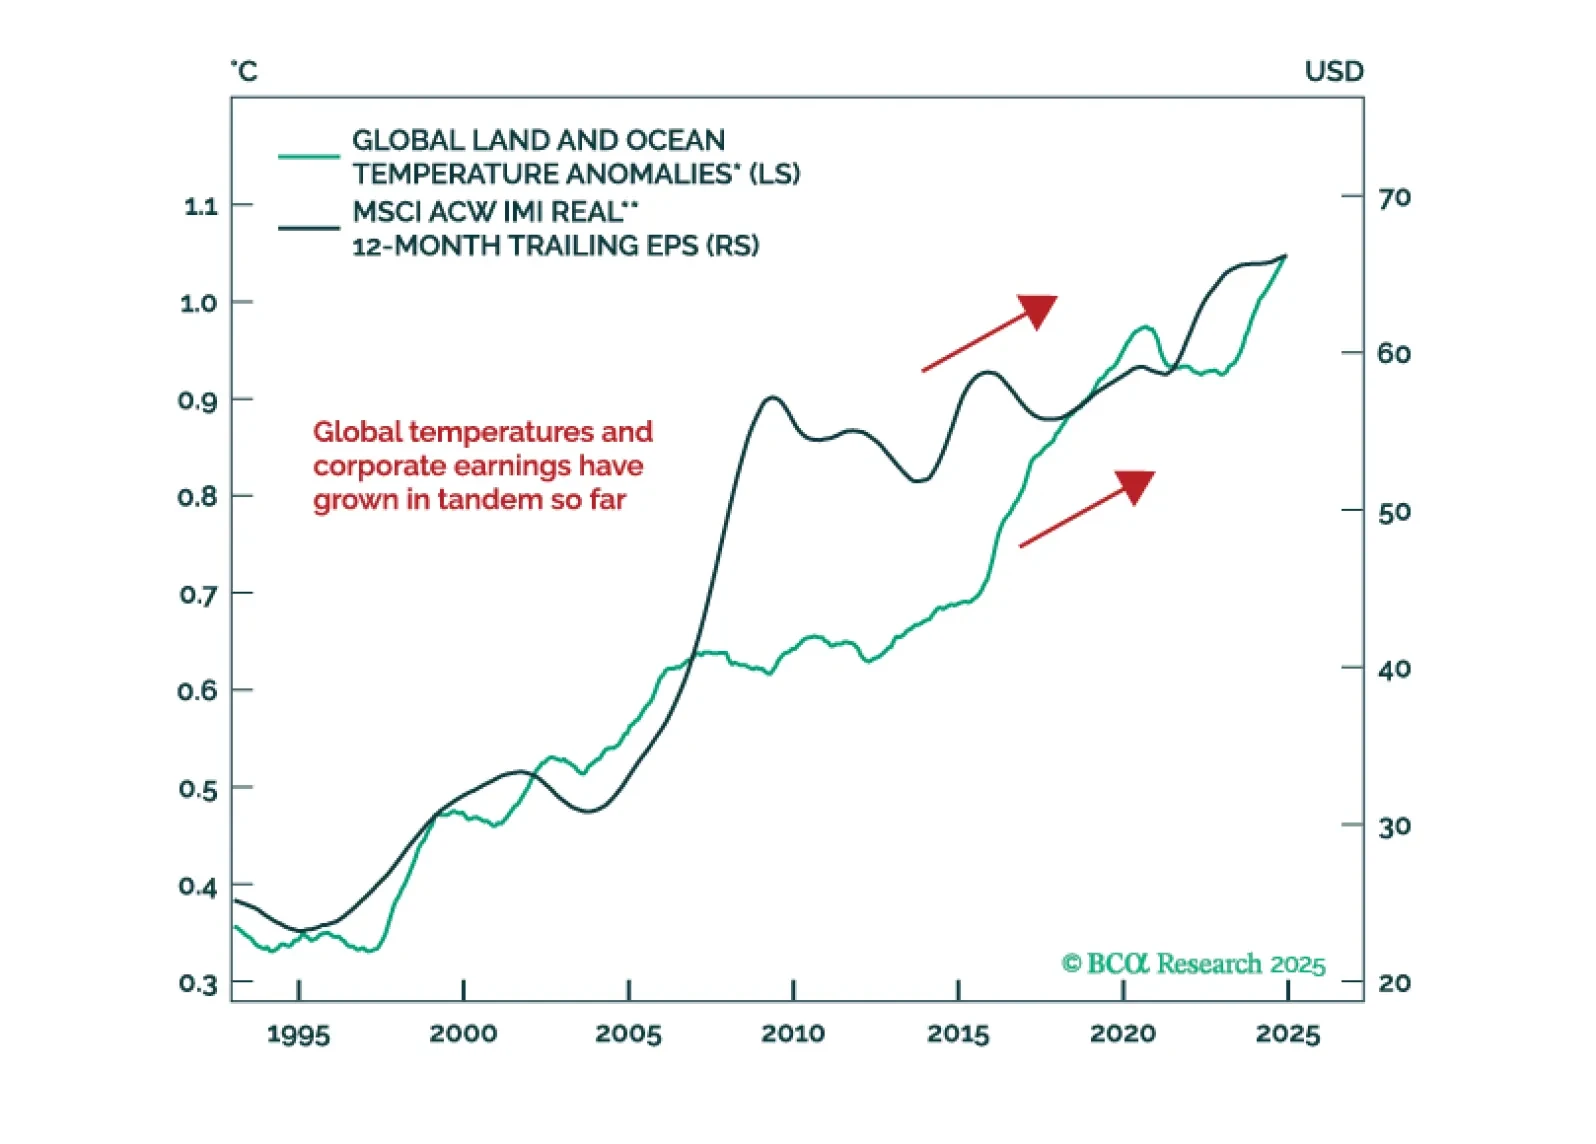
In our Beta report, we take a break from US politics and focus on the investment implications of climate change. Our colleague Ritika Mankar, of BCA’s Global Investment Strategy, makes a case for long-term investors to actually completely ignore climate change in their strategic asset allocation. Global warming will simply not make any difference, macroeconomically speaking, over the next five to ten years. Over a longer time horizon, climate change may even spur more economic growth, although with higher inflation as well.
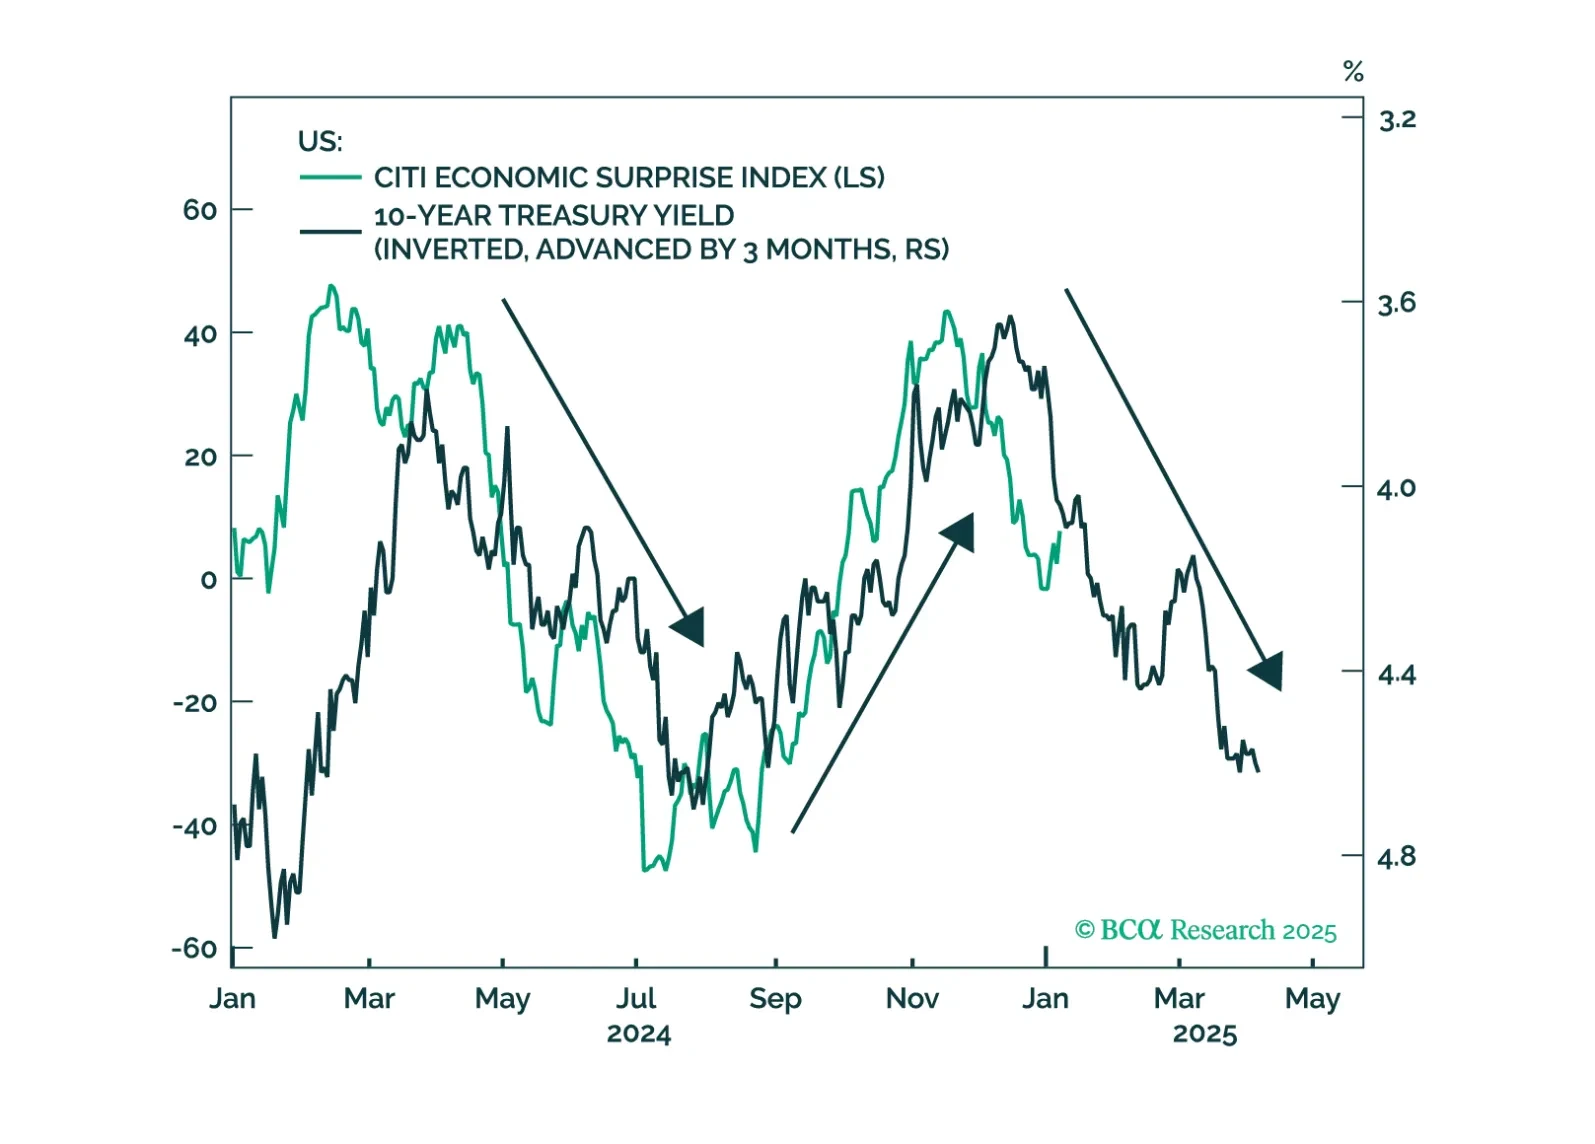
In our Alpha report, we reiterate that we expect President Trump to curb his most enthusiastic plans for tax cuts due to the pressure from the bond market. That will be good for equities in the long run – as it will assuage the pressure on yields. However, it should be negative for the USD as investors grapple with far less fiscal support for the US economy over the next four years than expected. We also give our readers a blueprint for following the news flow when it comes to trade policy. Stick to a framework and ignore tweets.