Latest from BCA Research
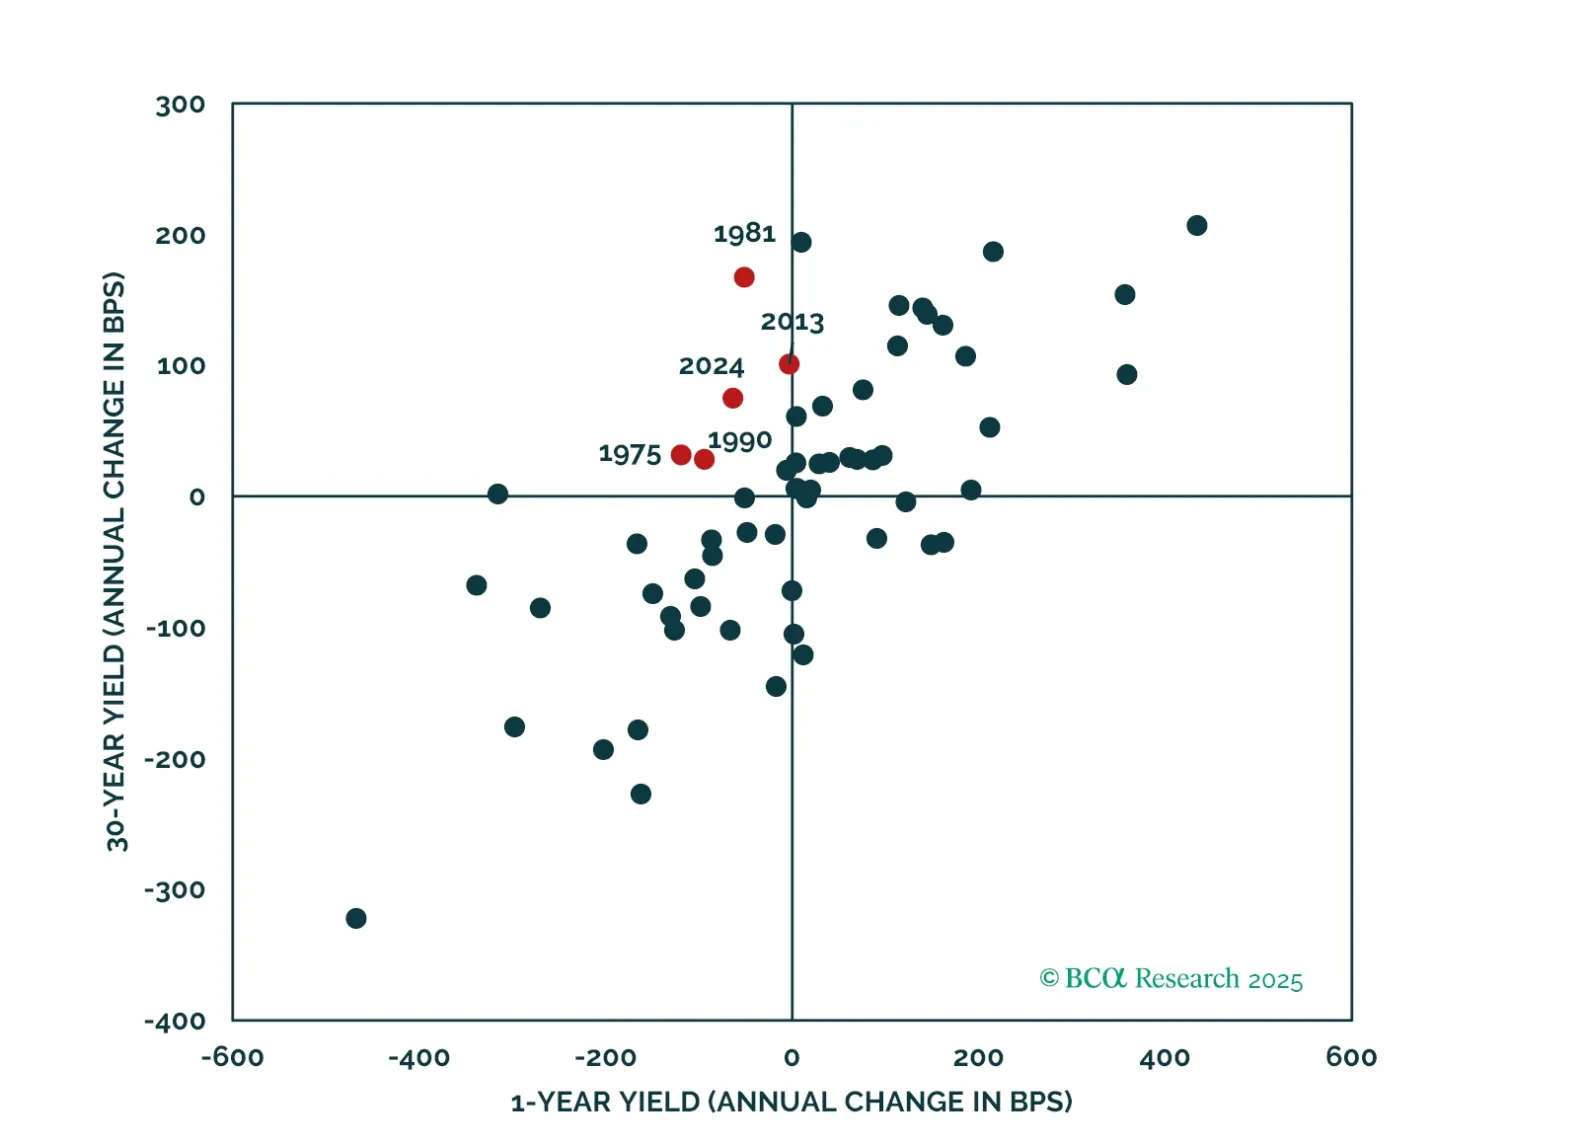
Paradoxically, raging optimism on the US economy is making a reacceleration in growth less likely in 2025. The reaction of the bond market has made the Fed rethink its cutting campaign. Markets are also constraining Trump’s agenda. US manufacturing will not recover with a surging dollar. Fears of inflation and debt sustainability have made moderate House Republicans push back against the President Elect’s wishes. Given the sky-high optimism embedded in asset prices, we believe a defensive portfolio stance is warranted on a 12-month horizon. Overweight gold to hedge the risk of a fiscal crisis.
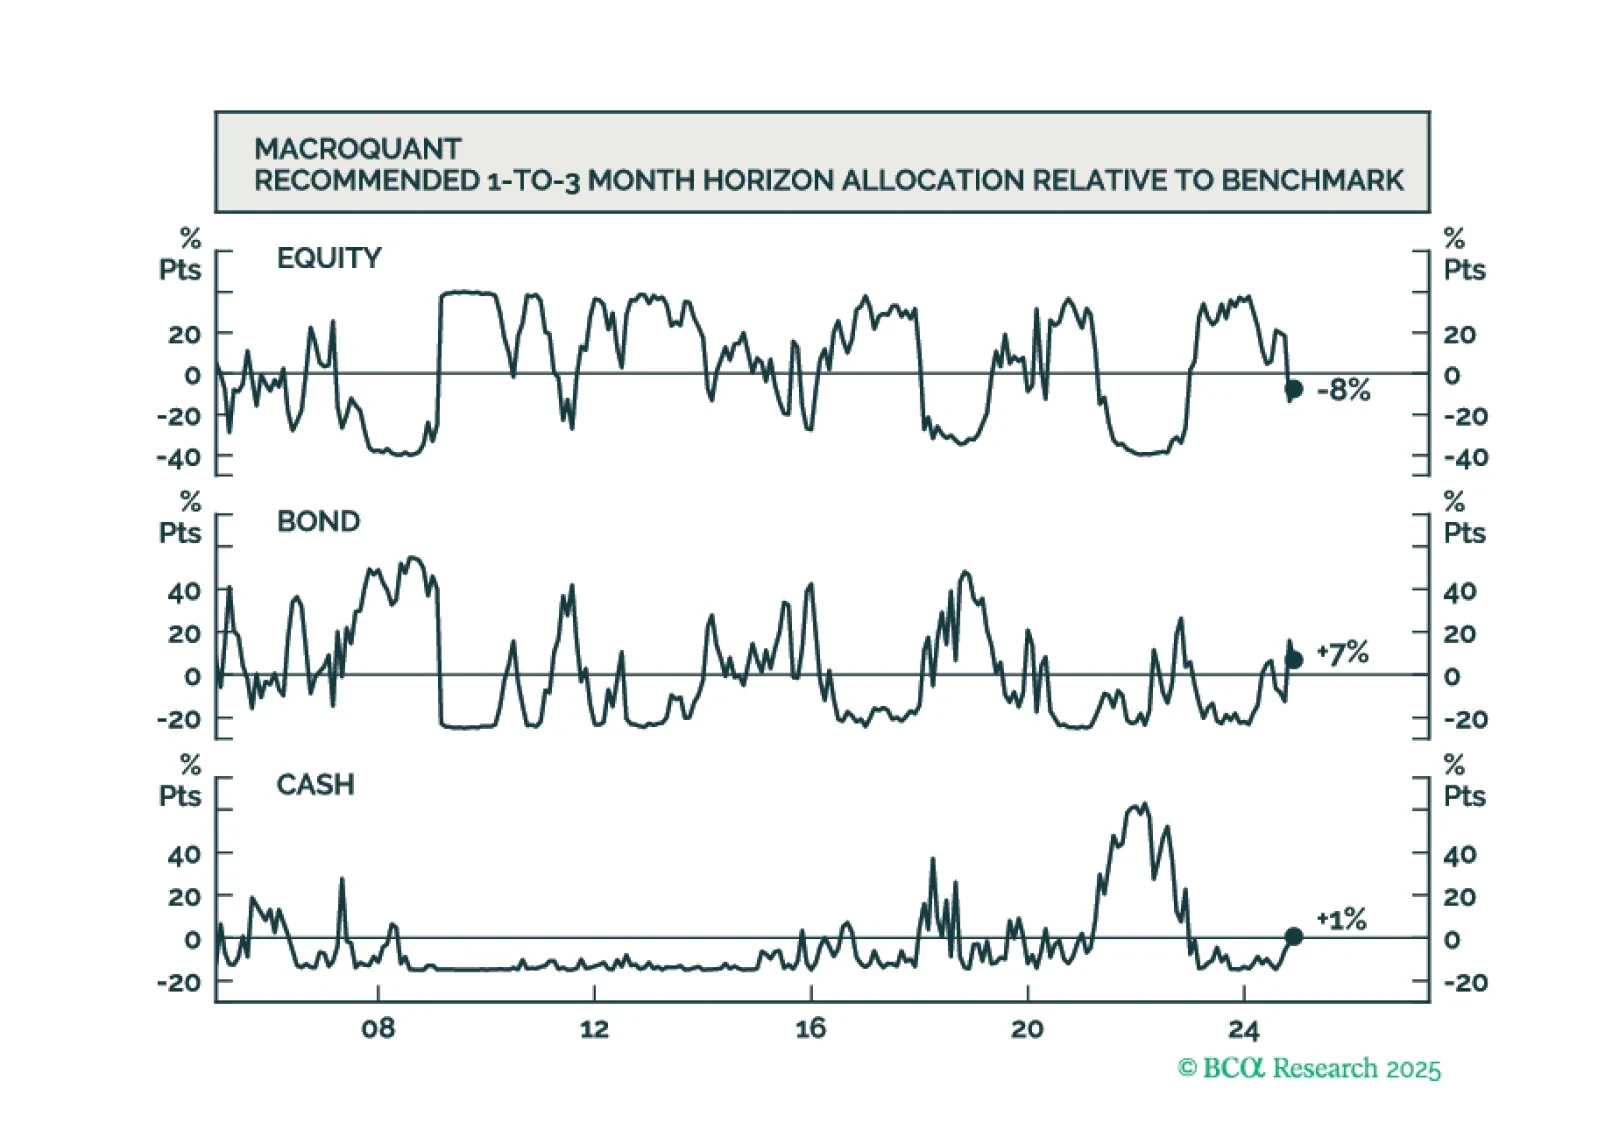
The latest version of the MacroQuant model sees the near-term risks to stocks as slightly tilted to the downside. It is neutral on bond duration and expects the US dollar to continue strengthening in the near term.
The latest version of the MacroQuant model sees the near-term risks to stocks as slightly tilted to the downside. It is neutral on bond duration and expects the US dollar to continue strengthening in the near term.
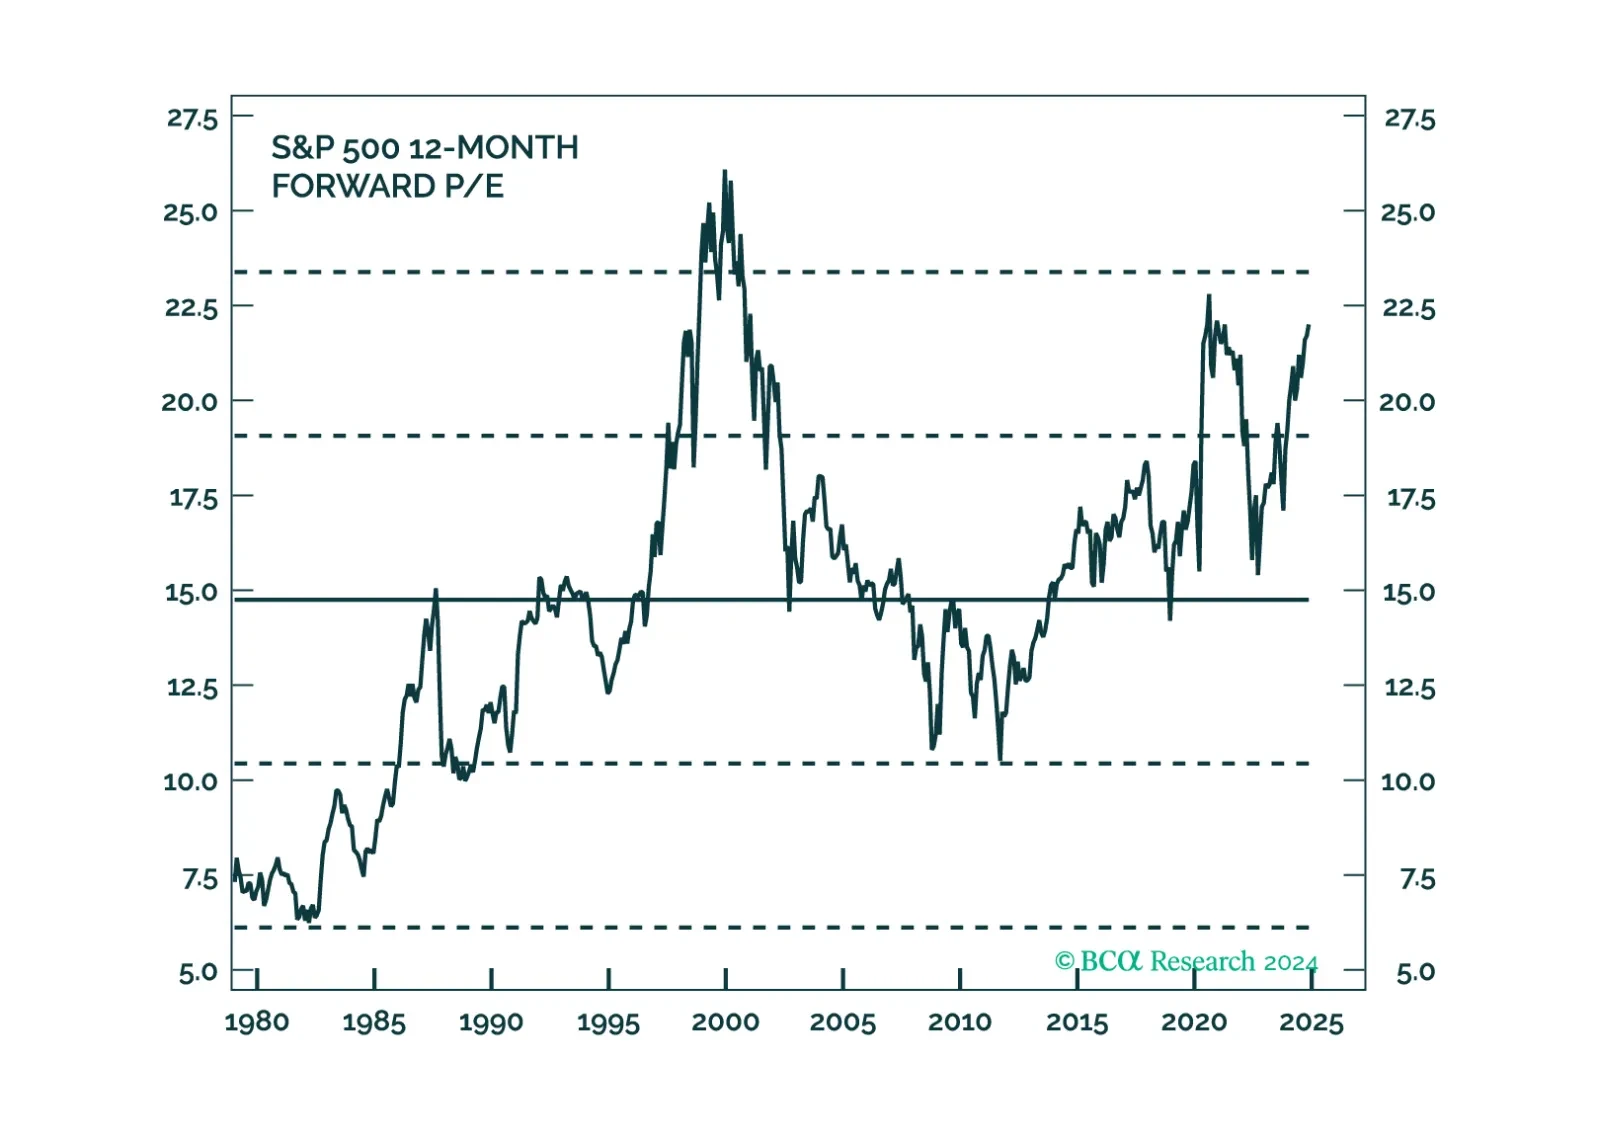
Our last publication of the year lets the charts do the talking about why we think the consumer post-pandemic momentum is fading along with the labor market.
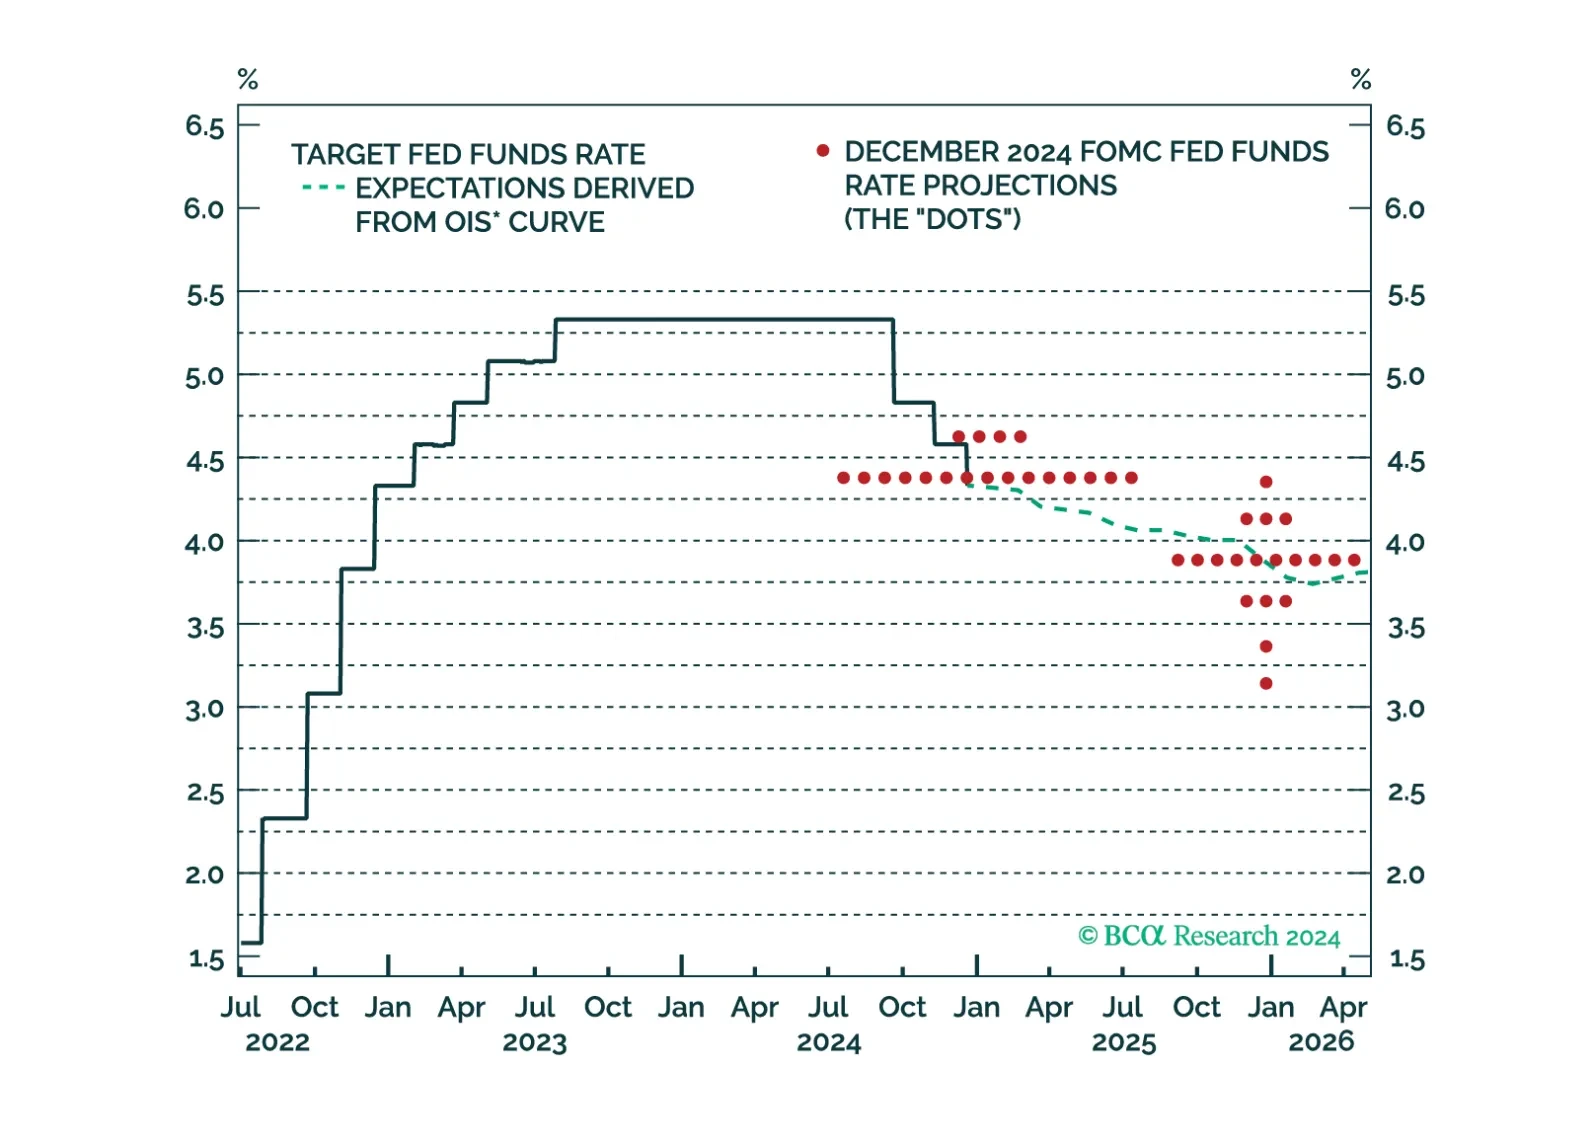
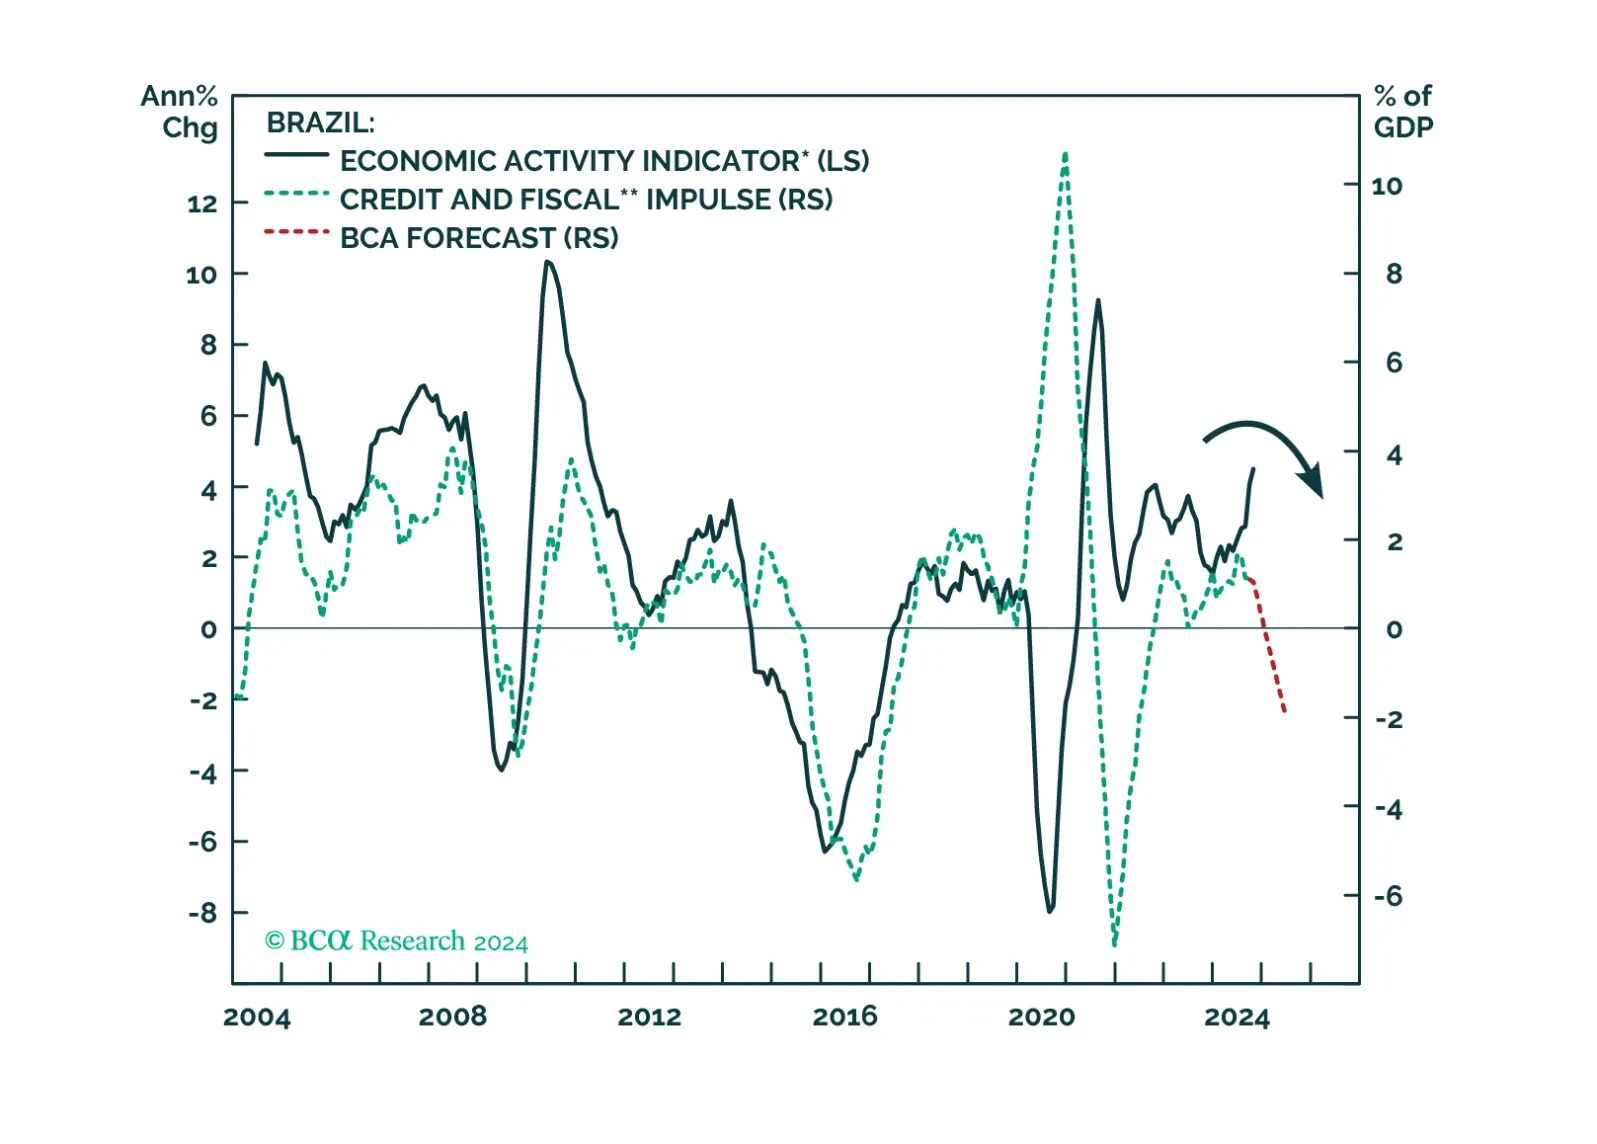
Any additional fiscal tightening and further rate hikes might serve as a band-aid, but not a cure, to Brazilian markets. The country’s risk assets and the currency will continue to face headwinds from an impending recession, a strengthening USD, weak commodity prices, and worsening public debt dynamics. Investors should fade out any relief rallies in Brazilian markets for now.
As the US faces renewed government shutdown risk, I thought it was prudent to highlight two developments to GeoMacro clients.
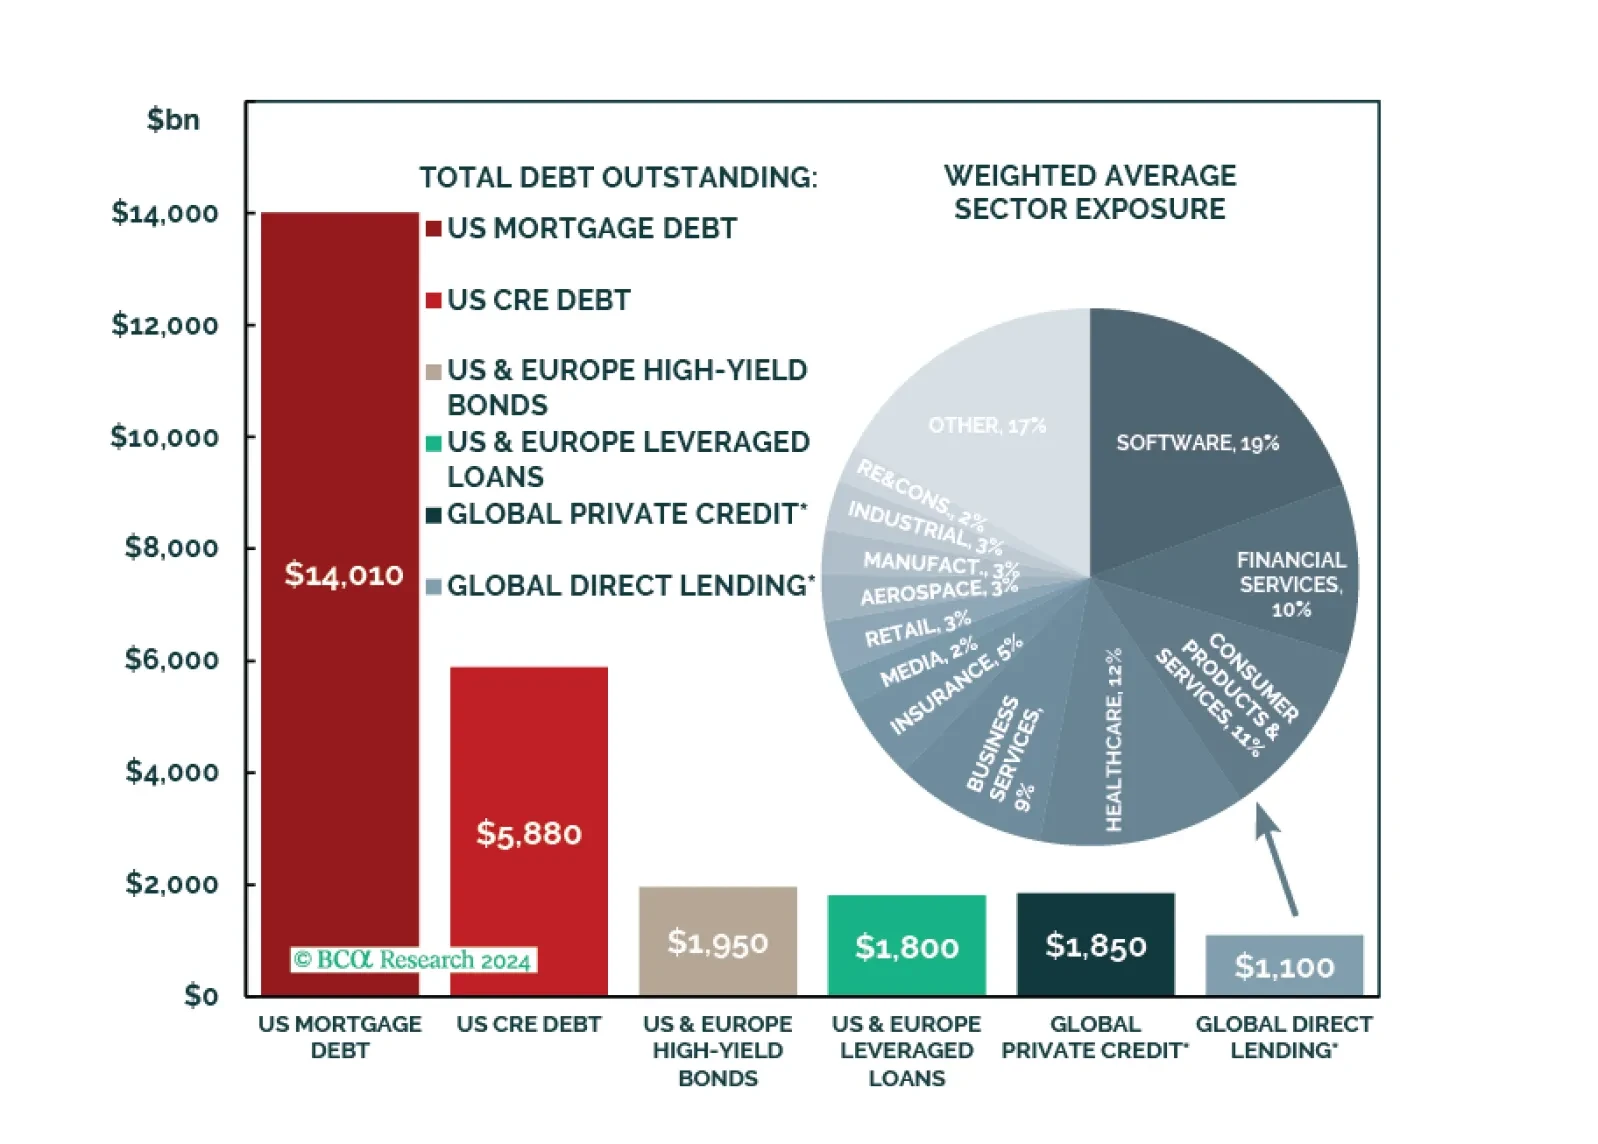
Understanding the risks across Private Credit will enable investors to be offensive, not just with sizing but across their total portfolio. Senior Direct Lending is not risk-free, Private Credit is not systemic, and a liquidity crisis will not be born in this asset class.