Latest from BCA Research
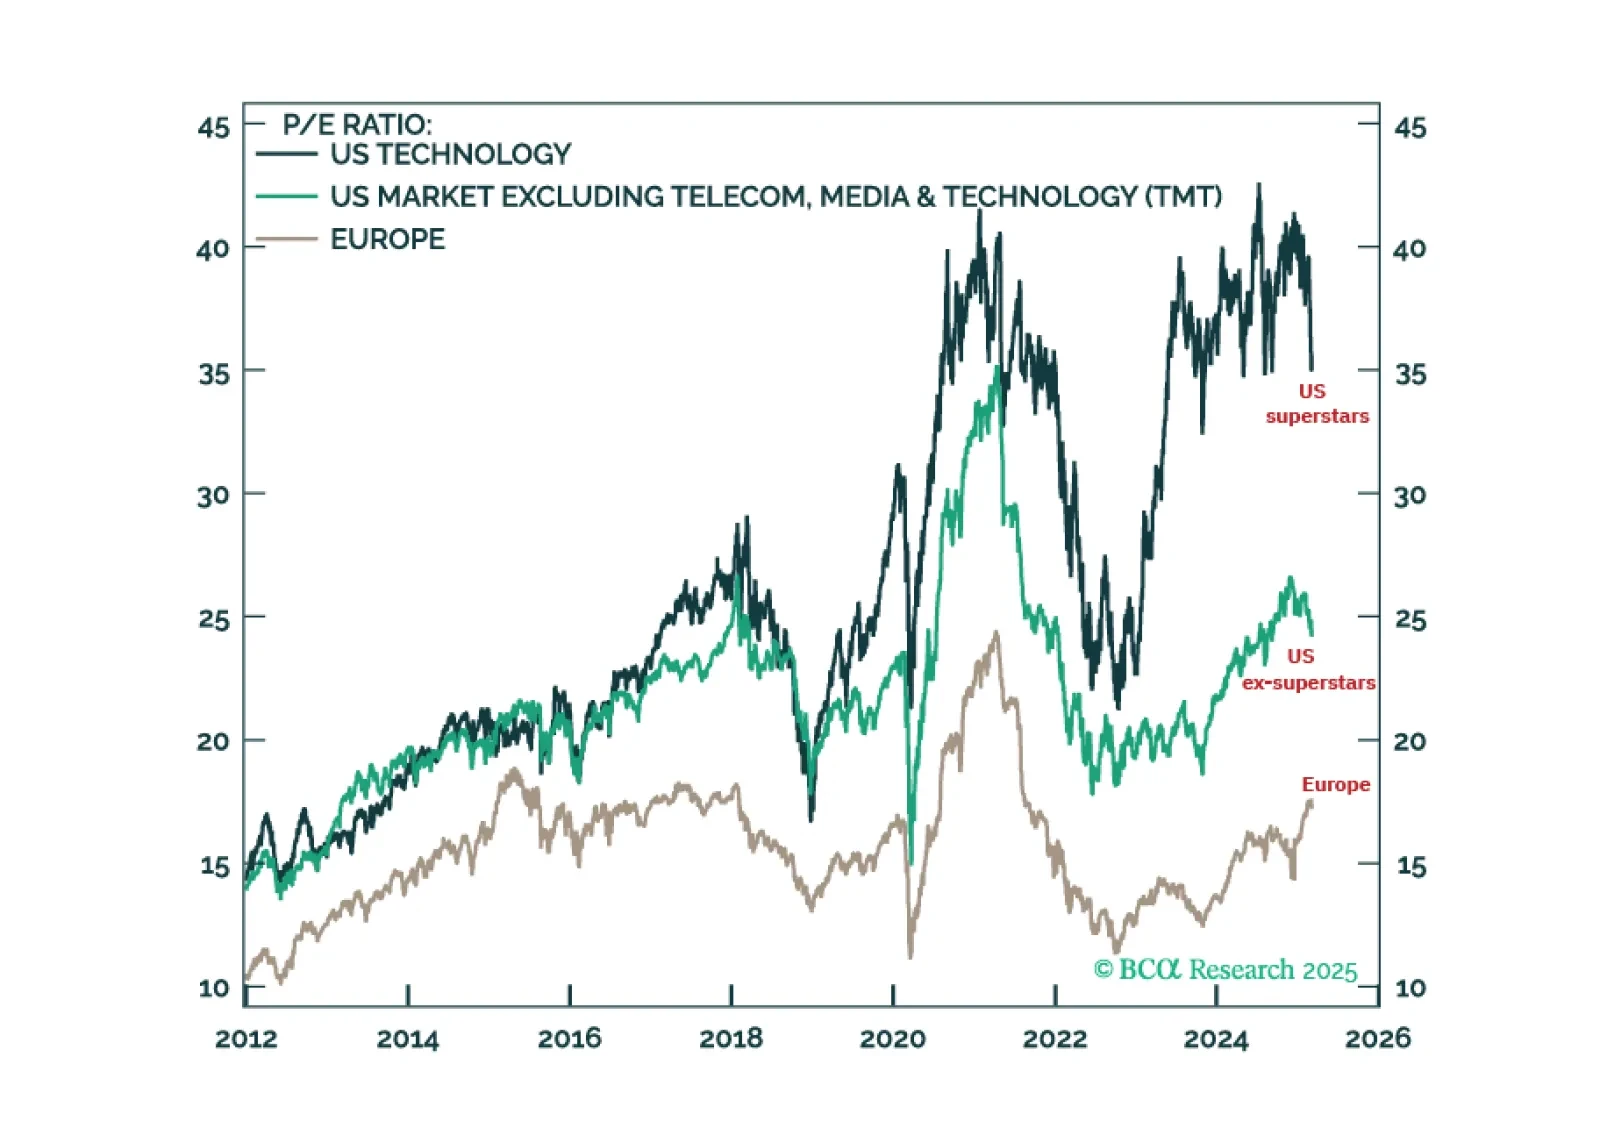
US stock market outperformance has been driven entirely by the 0.0002 percent of US superstar companies. But this superstar outperformance is based on two highly questionable assumptions: that all productivity gains from the generative-AI revolution will go into corporate profits; and specifically, into the profits of the Web 2.0 superstars which will morph into the generative-AI superstars. As these assumptions become undermined in the coming quarters, relative performance will reverse, starkly. On a structural horizon, stay maximum overweight Europe versus the US. Plus: time to go underweight global financials (IXG).
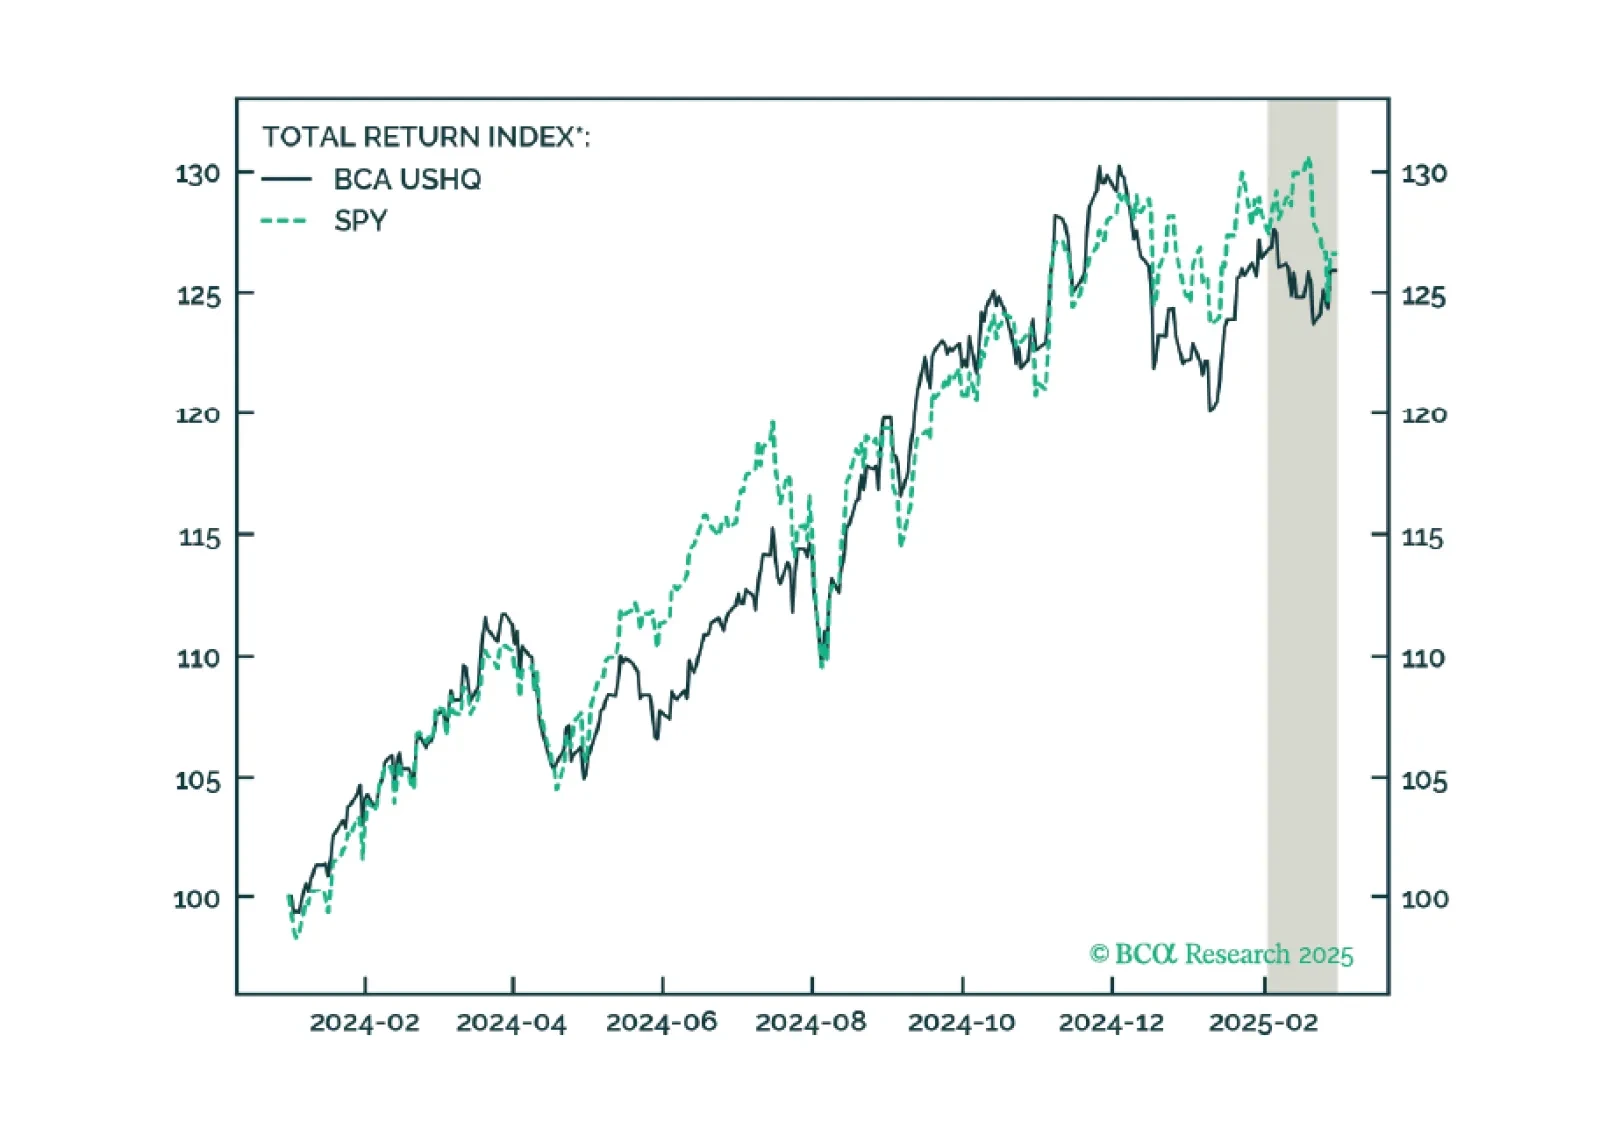
The US High Quality (USHQ) portfolio slightly underperformed in February, returning -0.7%, whilst its SPY benchmark returned -0.6%. While we continue to monitor the portfolio monthly, over a quarter-on-quarter basis, USHQ posted meaningful outperformance vs. benchmark, generating +130bps of excess return, while also exhibiting lower volatility and drawdown.
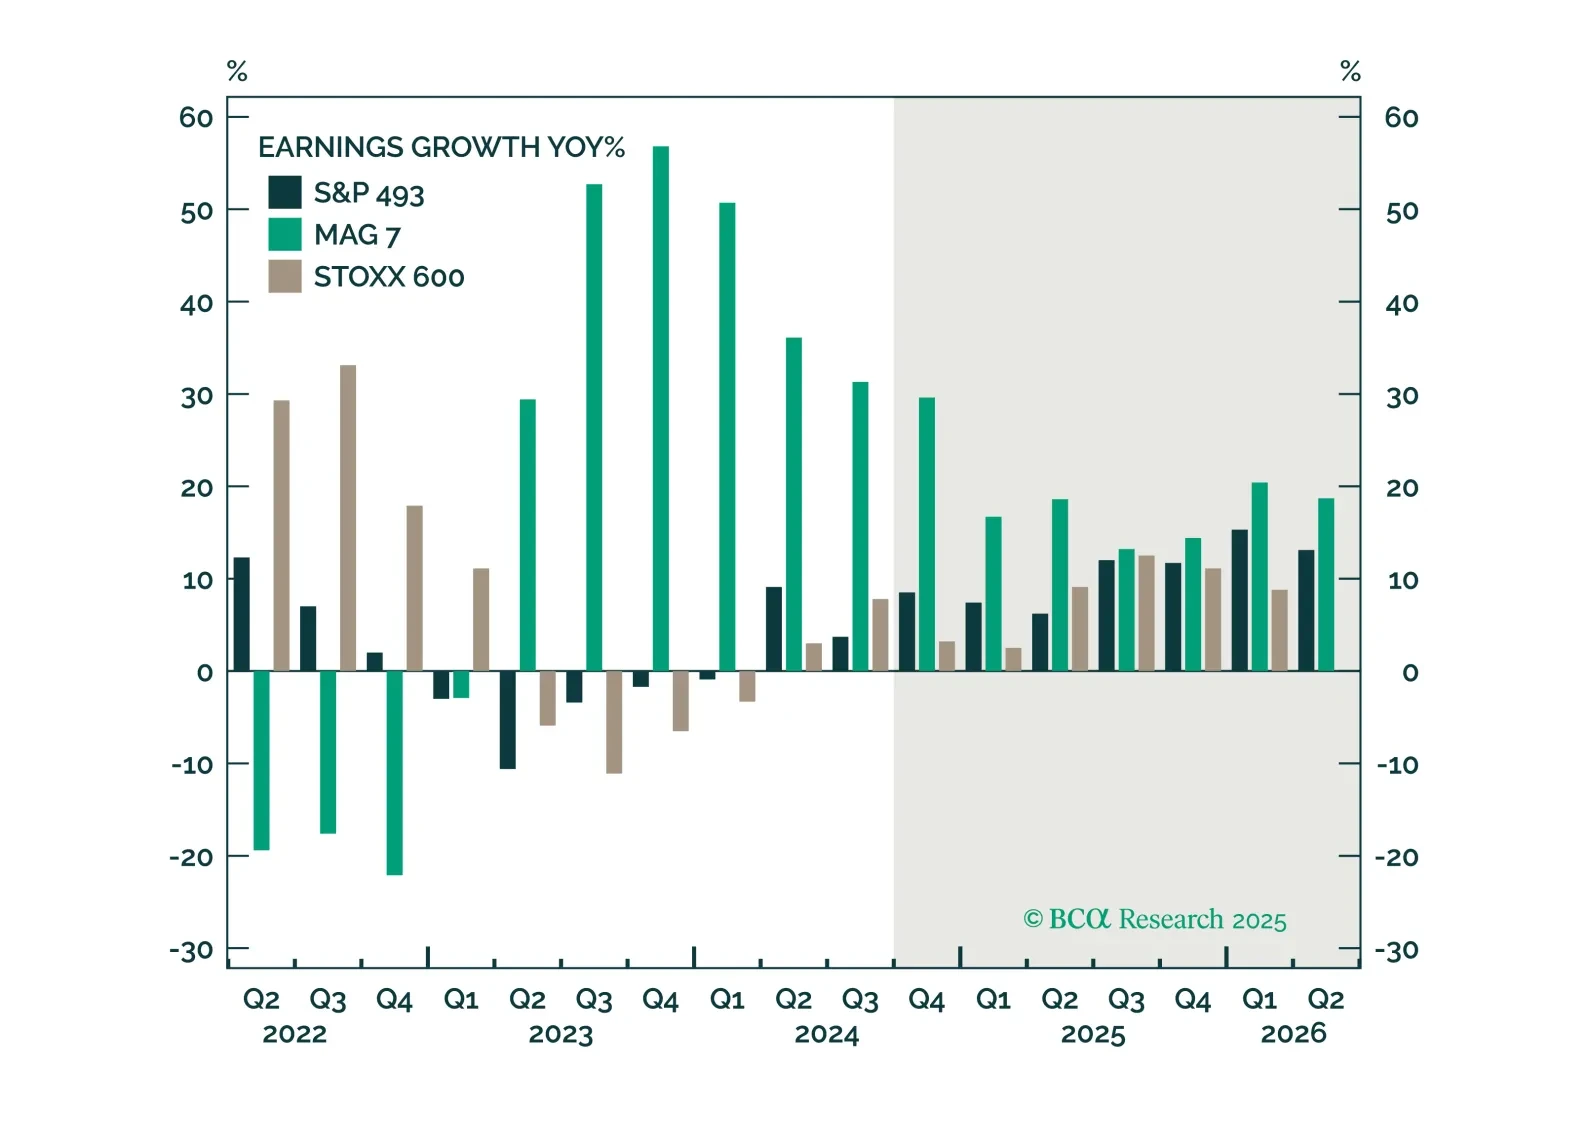
This week we are sending you a sector chart pack. In the front section of the chart pack, we review February’s performance, take stock of the recent macroeconomic developments, and examine whether market rotation will continue. We also review whether the US valuation premium relative to Europe is justified.
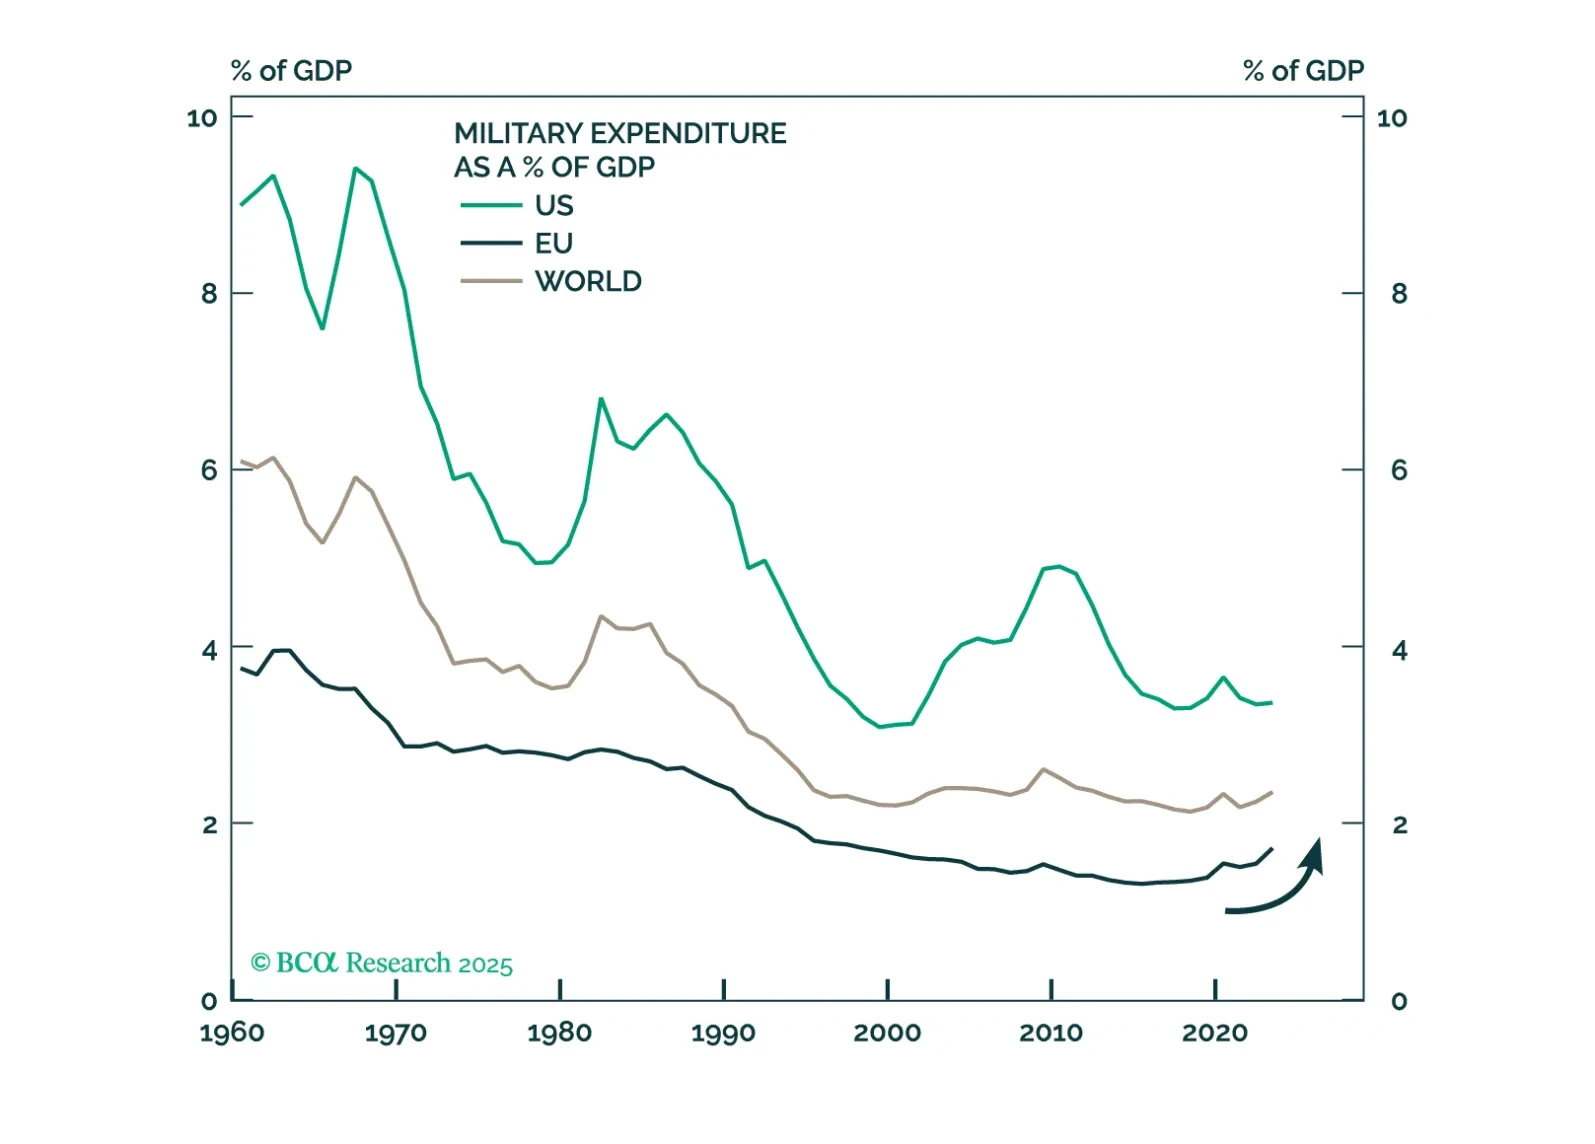
Fears of Europe’s decline due to Russian aggression and shifting US policy are overblown. President Trump’s tough stance on Ukraine is a strategic move to consolidate domestic support, not an abandonment of Europe, while Russia’s threat is exaggerated. As Europe responds with higher defense spending, stronger market integration, and greater political unity, investors should overweight European defense stocks and position for Europe’s broader market outperformance.
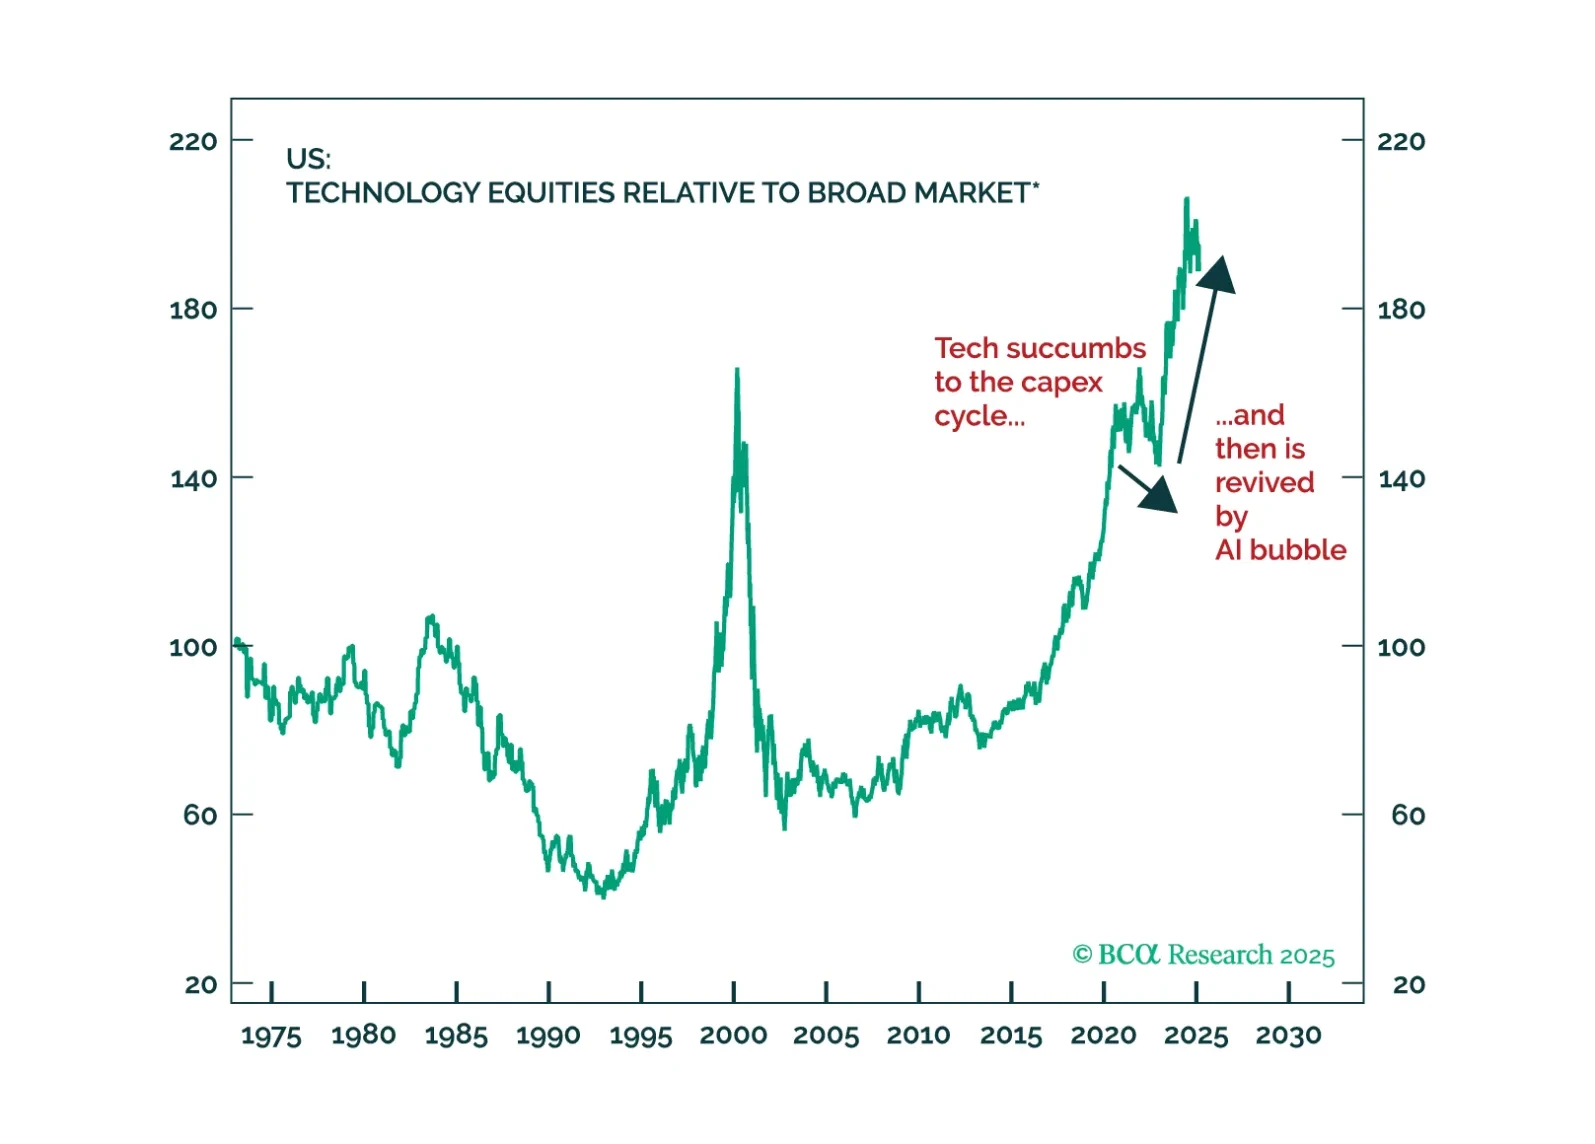
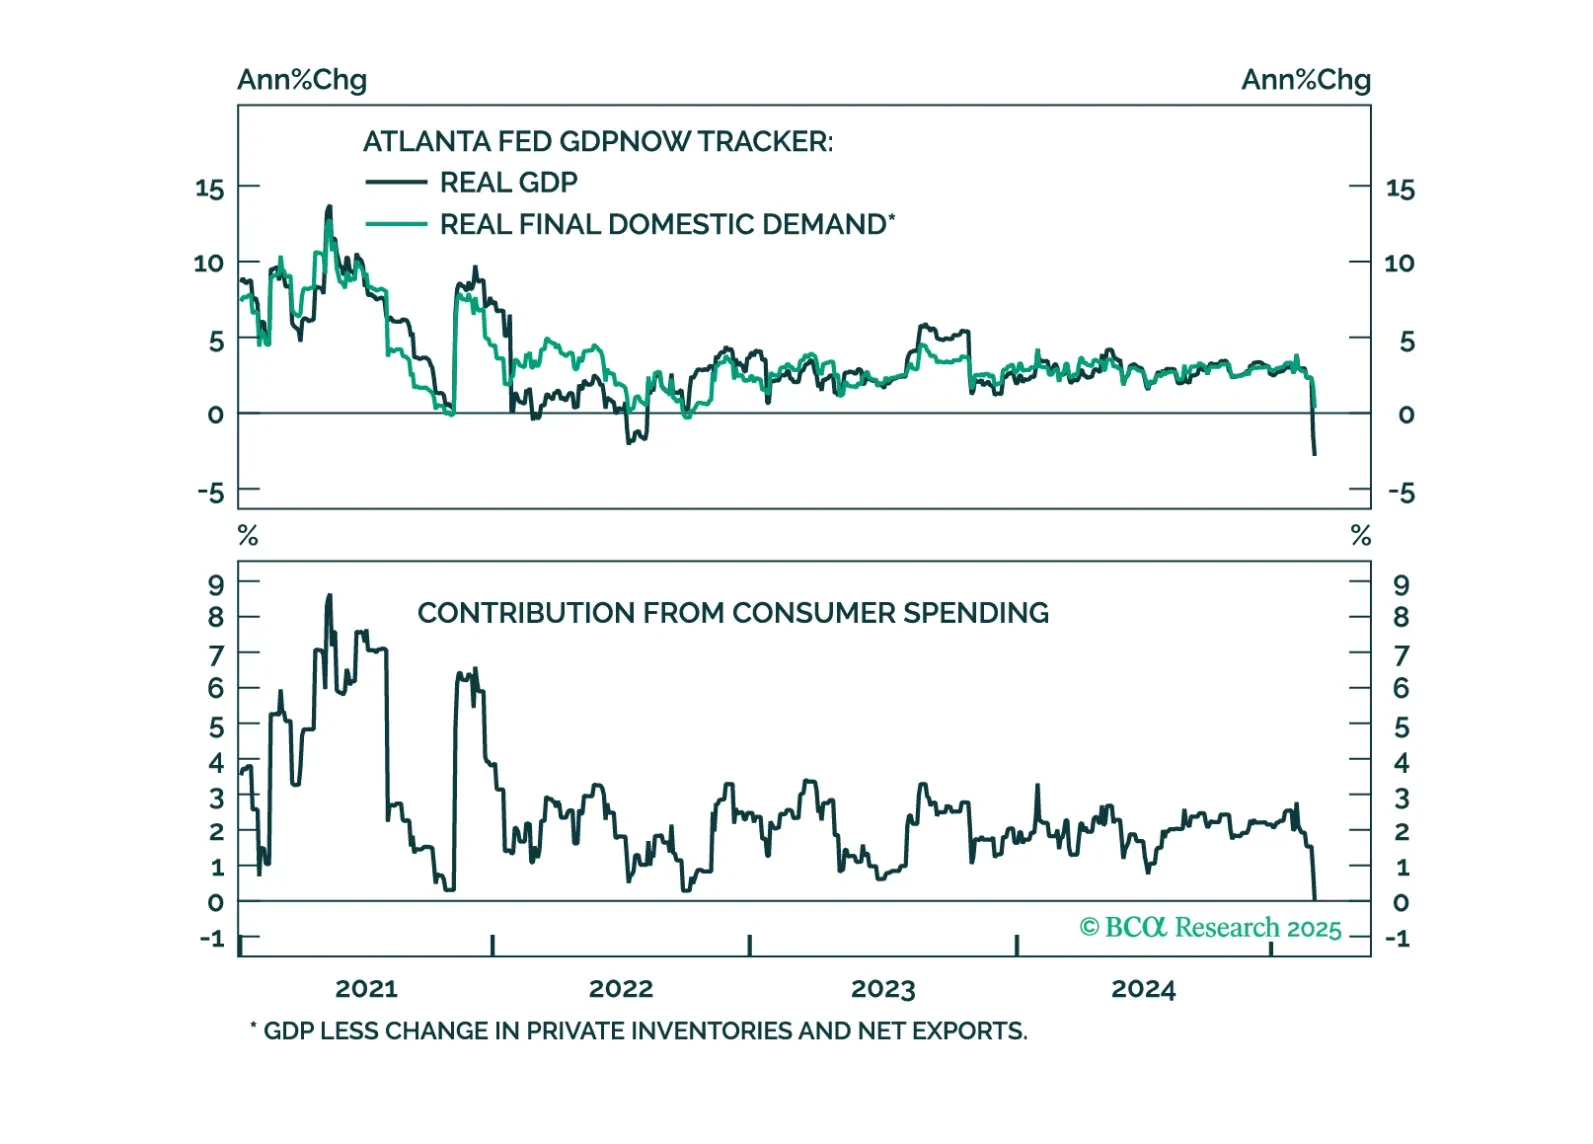
Are you sure you are in a trade war-induced selloff and/or recession? Or, is America – writ large – the bubble? Fed a steady dose of fiscal profligacy over the past five years, the US economy and its various associated assets have become fat and complacent. As such, the end of the fiscal gravy train – our signature macro call for 2025 – is what is causing the underlying weakness, with the Big Tech – the biggest beneficiary of US Exceptionalism – now buckling. Our message? The tech bros are lying to you. The AI revolution is not positive for Big Tech, not at their current valuation. Play the rotation, even if a (mild) recession may be afoot, as we have been saying throughout 2024.
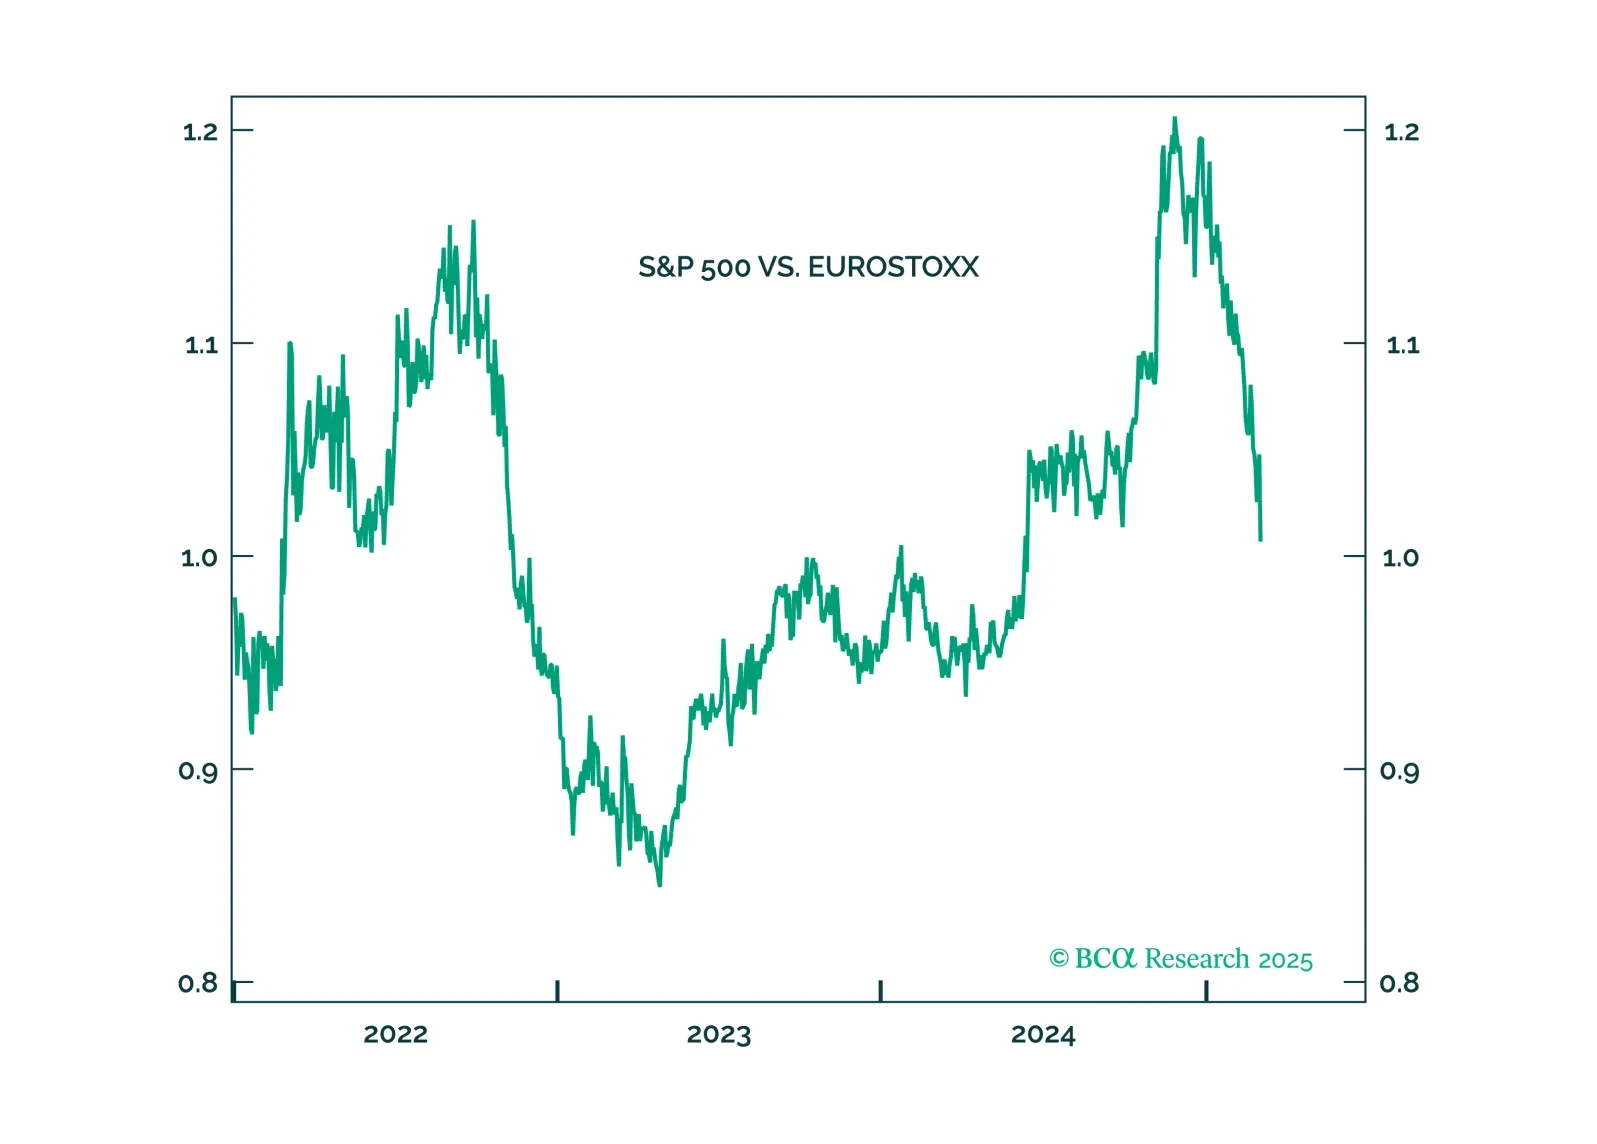
Trump will pull back from the trade war when stocks approach bear market territory. He will not withdraw from NATO. Favor European stocks on fiscal policy.
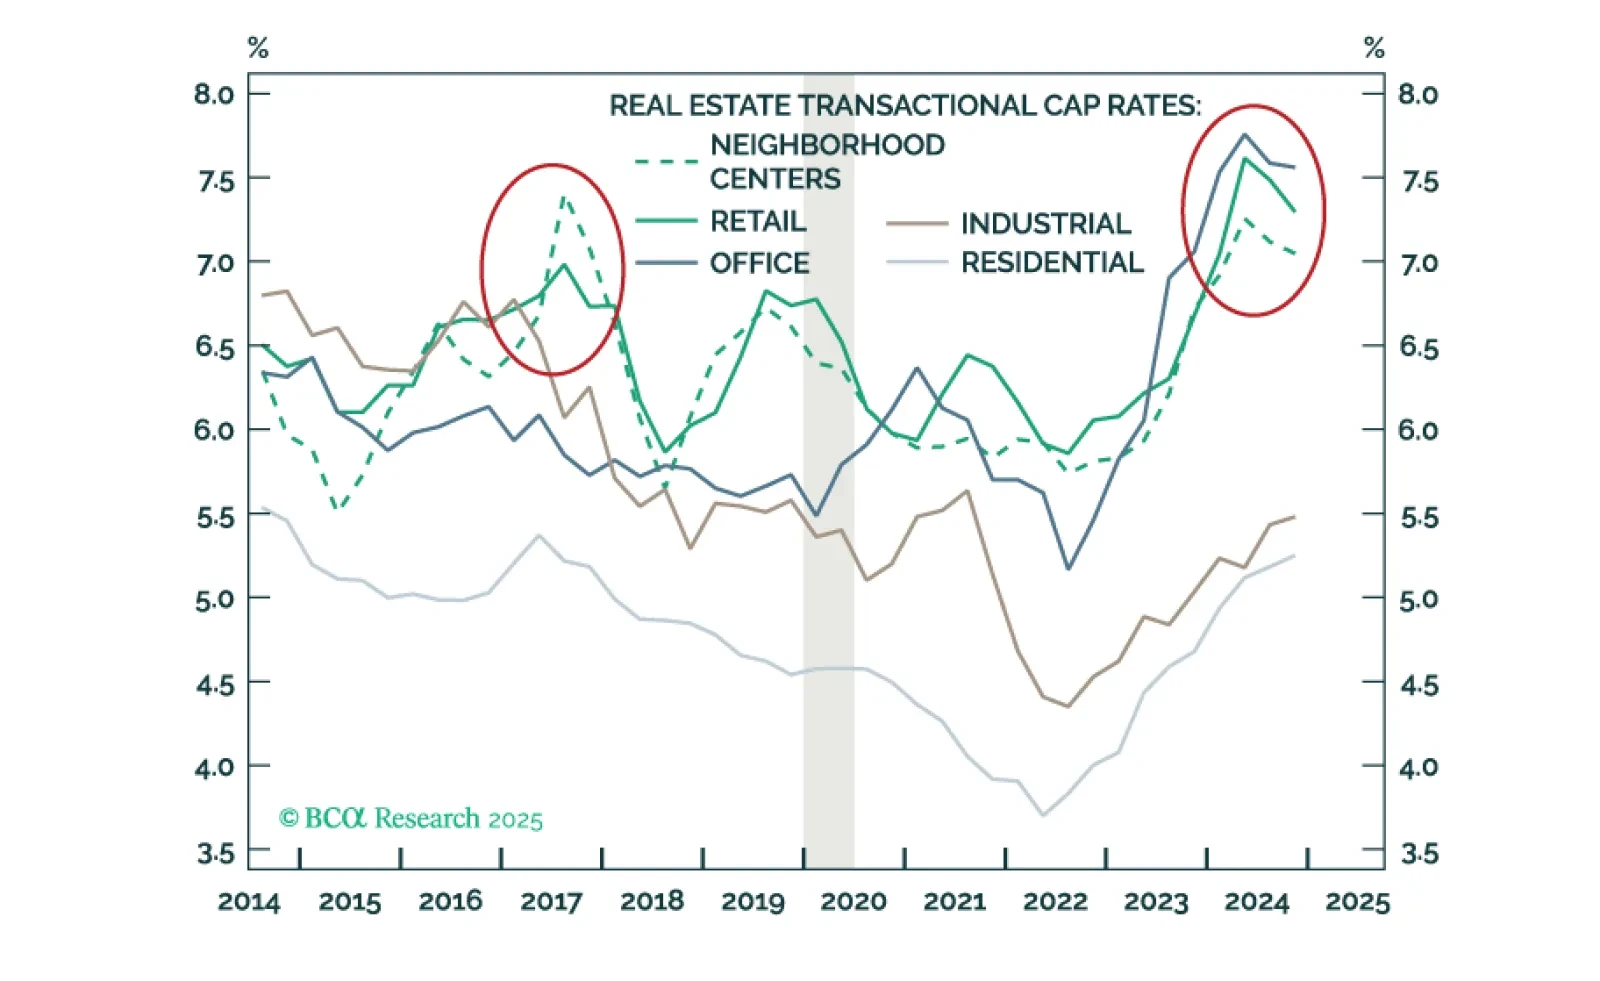
It is time to bet on brick-and-mortar again. The next time you step around your partner's Amazon package on your way to a physical store, consider this: Rock-bottom investor expectations, attractive initial fundamentals, and ongoing demographic shifts make Retail Real Estate a buy for the first time in a decade.
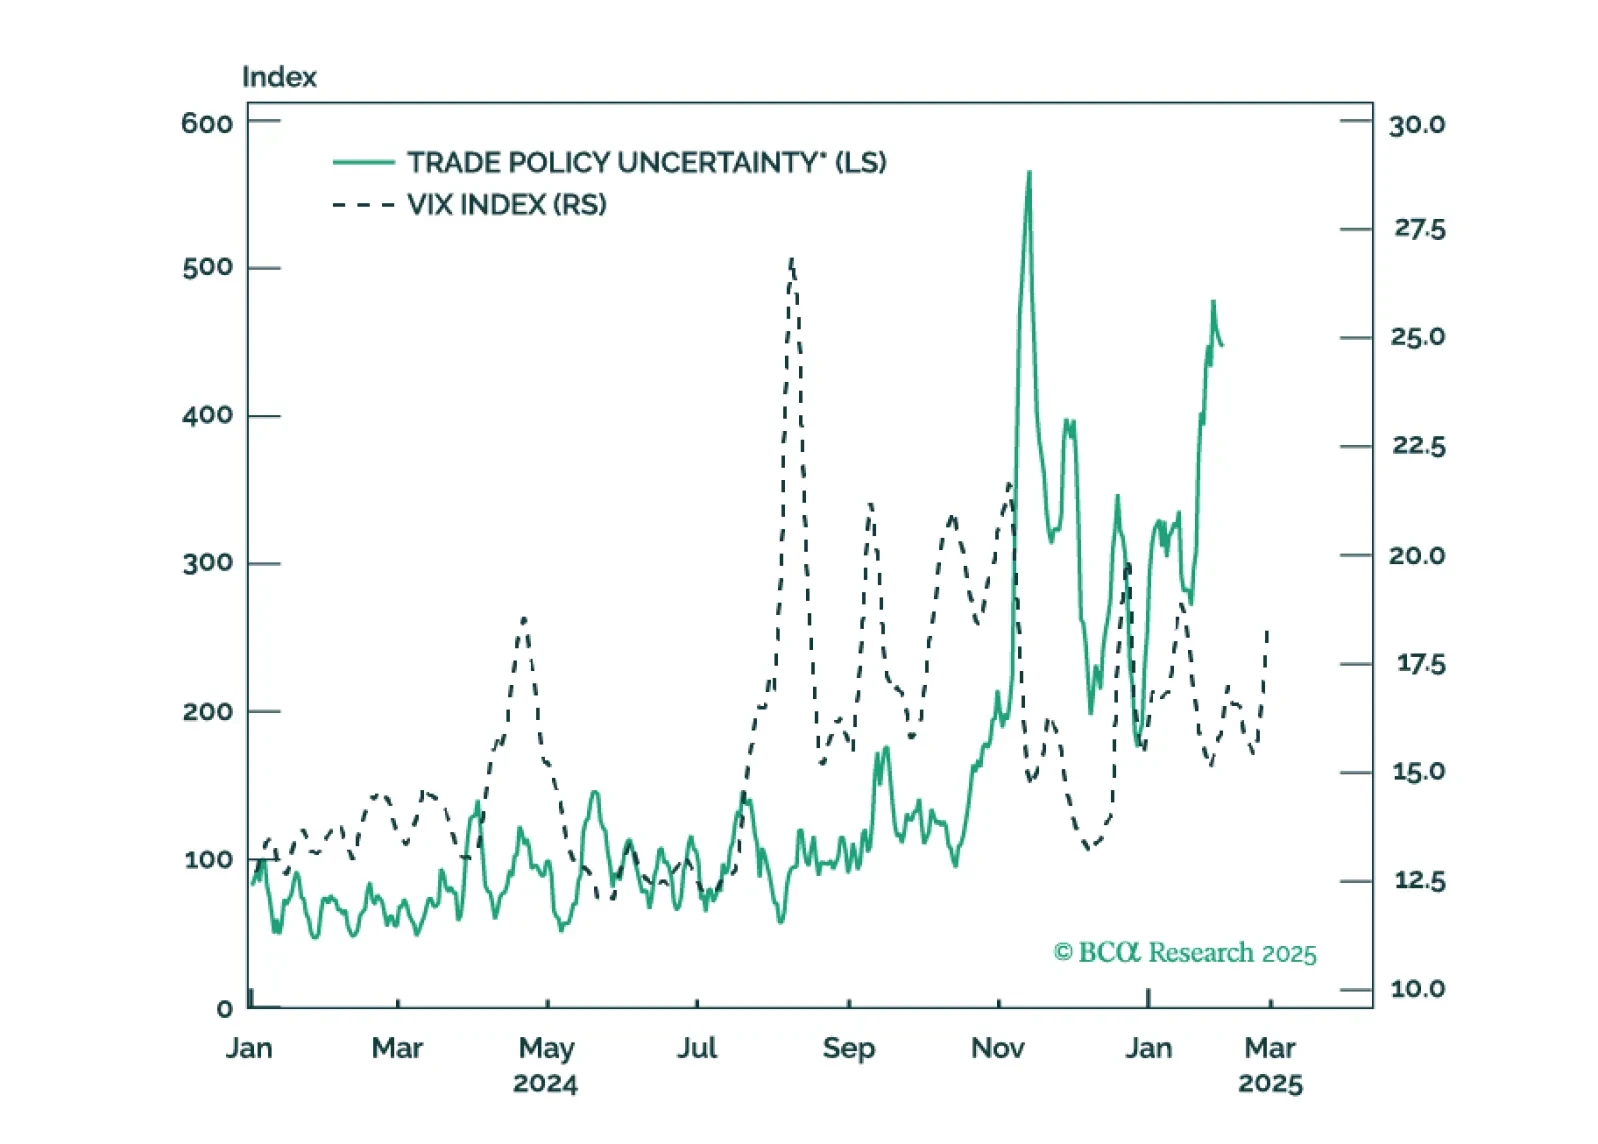
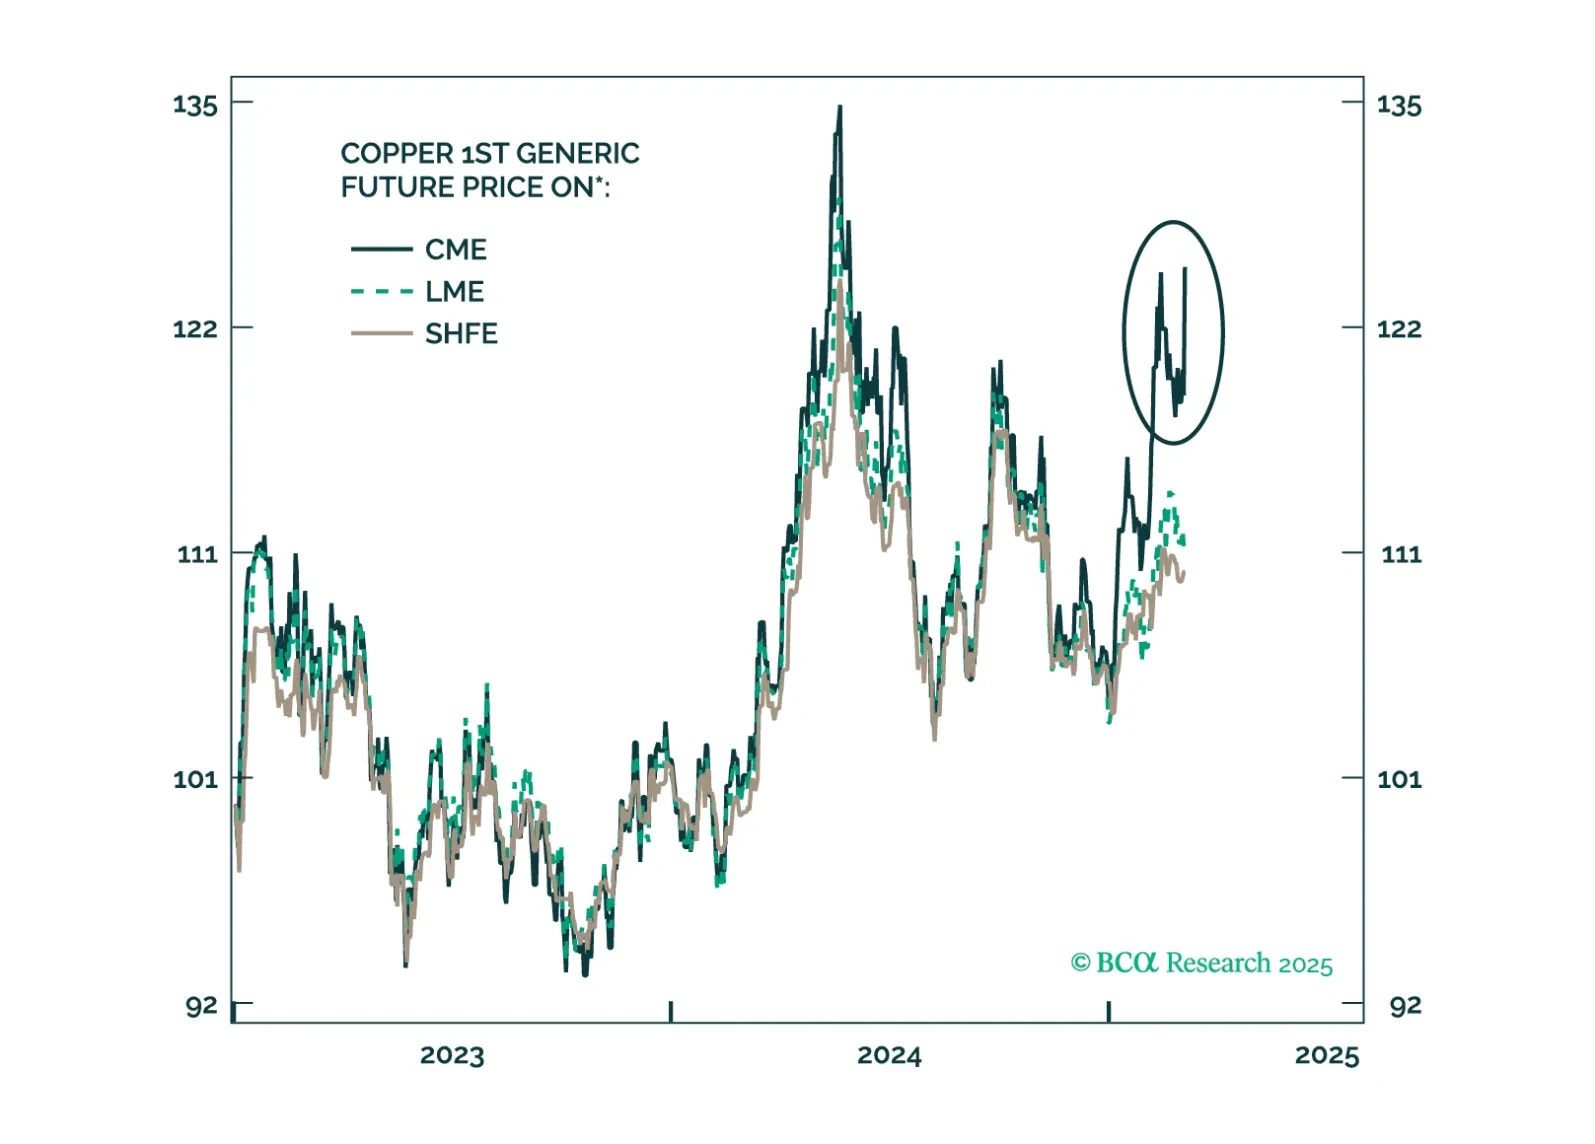
Our defensive strategy for 2025 is coming to fruition so we are re-initiating some of our defensive and risk-off trades. Tariff implementation, hurdles in the tax bill, and geopolitical shocks are materializing in the near term.