Equities
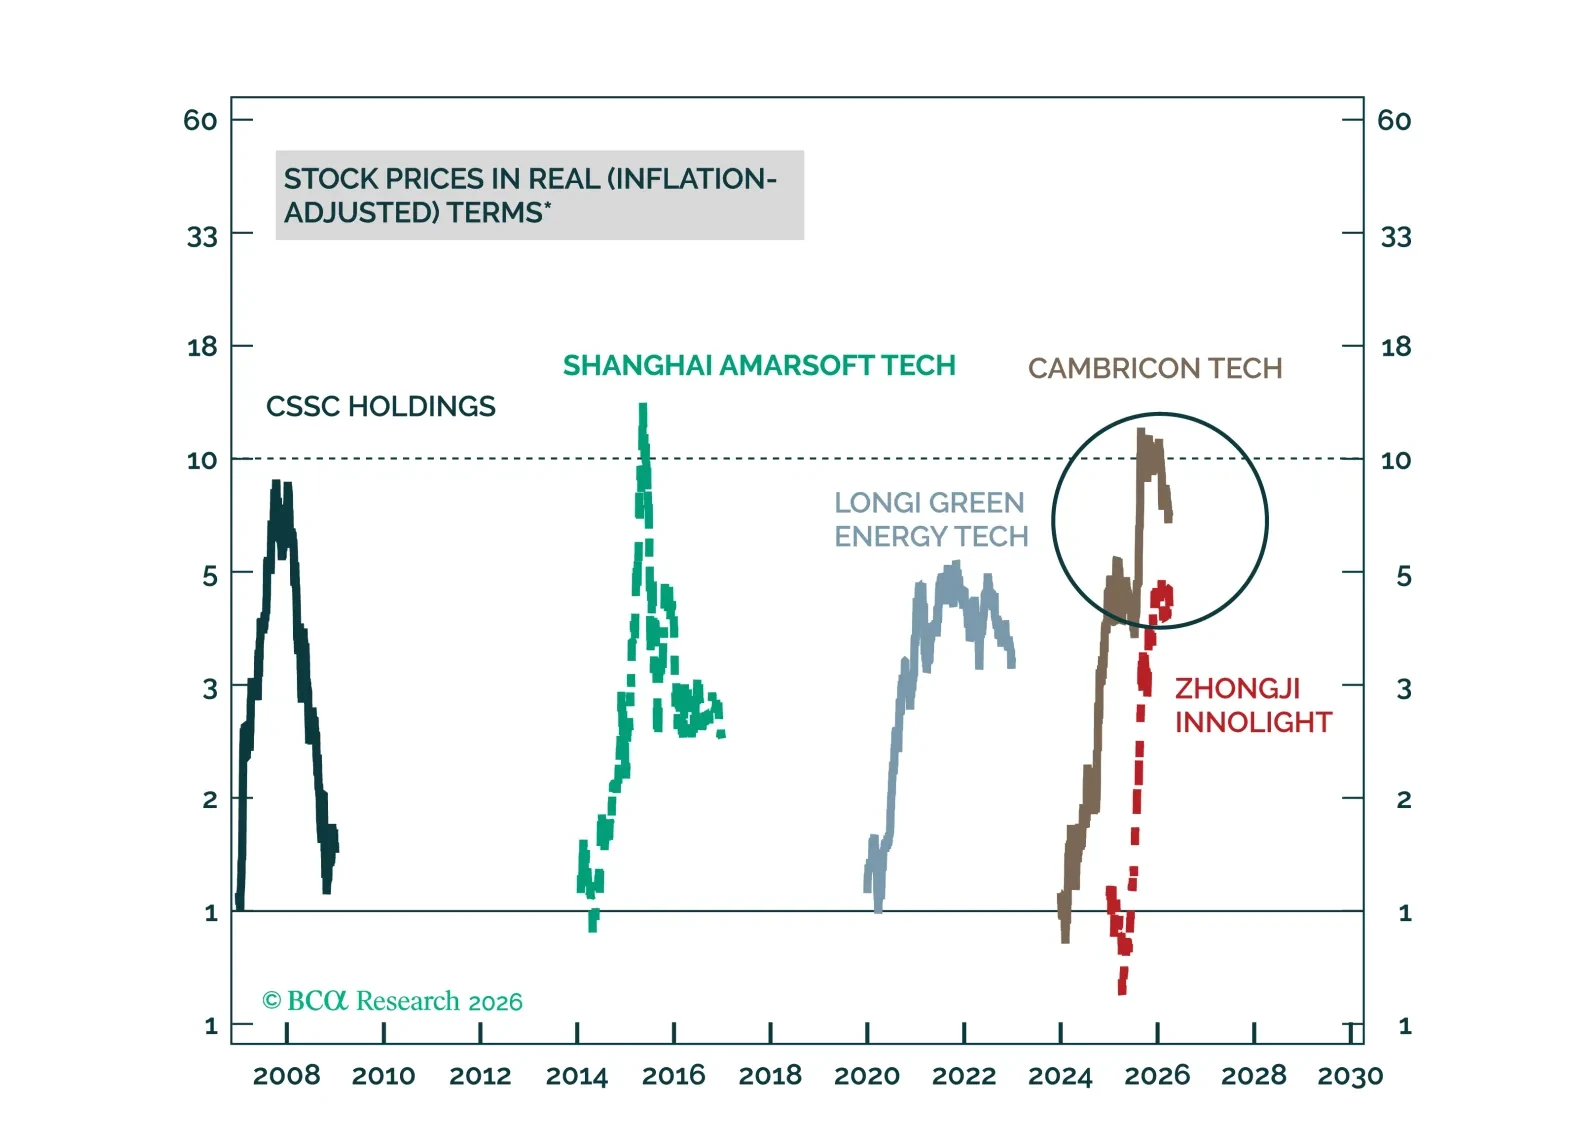
Chinese onshore equities are riding the global “scarcity trade,” powered by tight semi supply and surging alternative-energy demand. How should investors position in this environment?
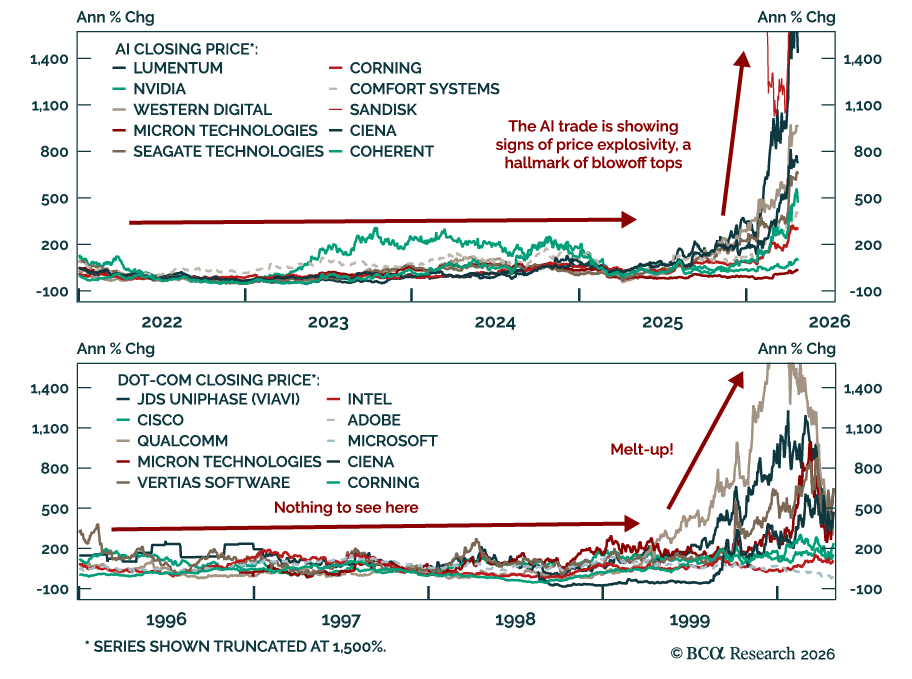
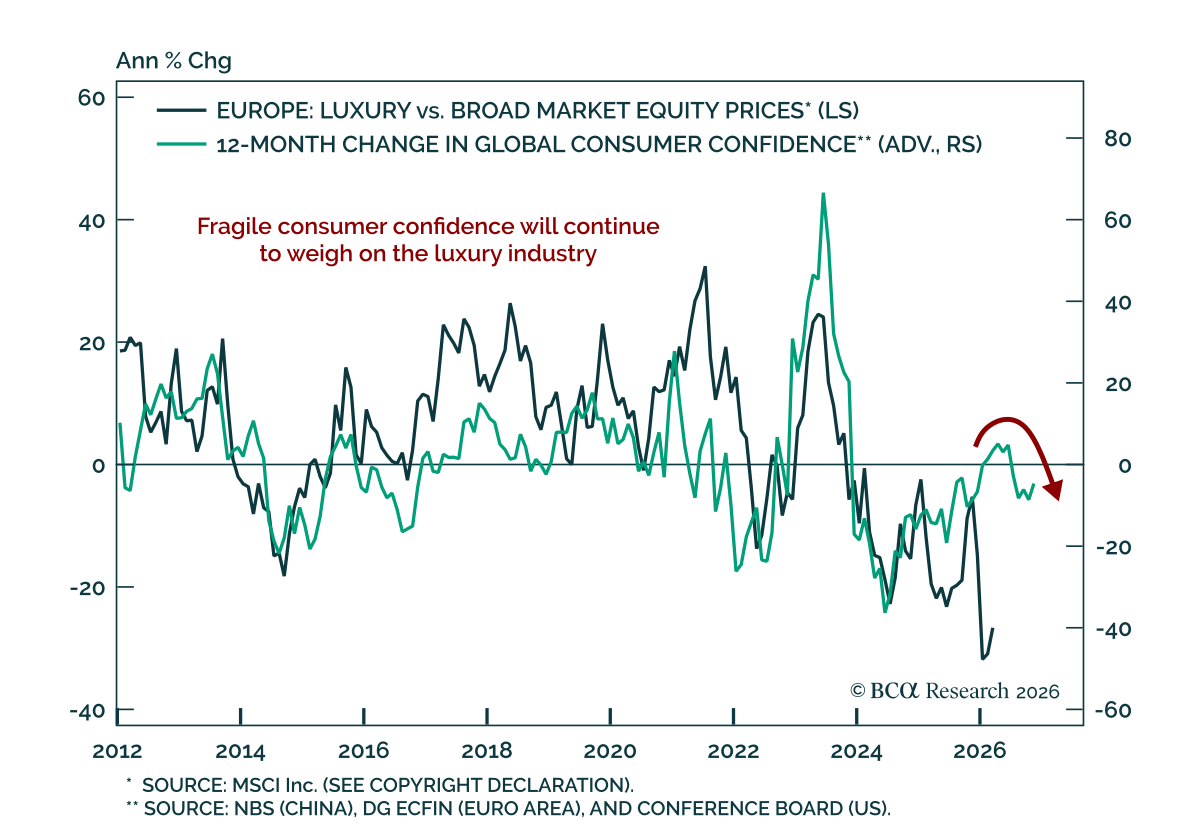


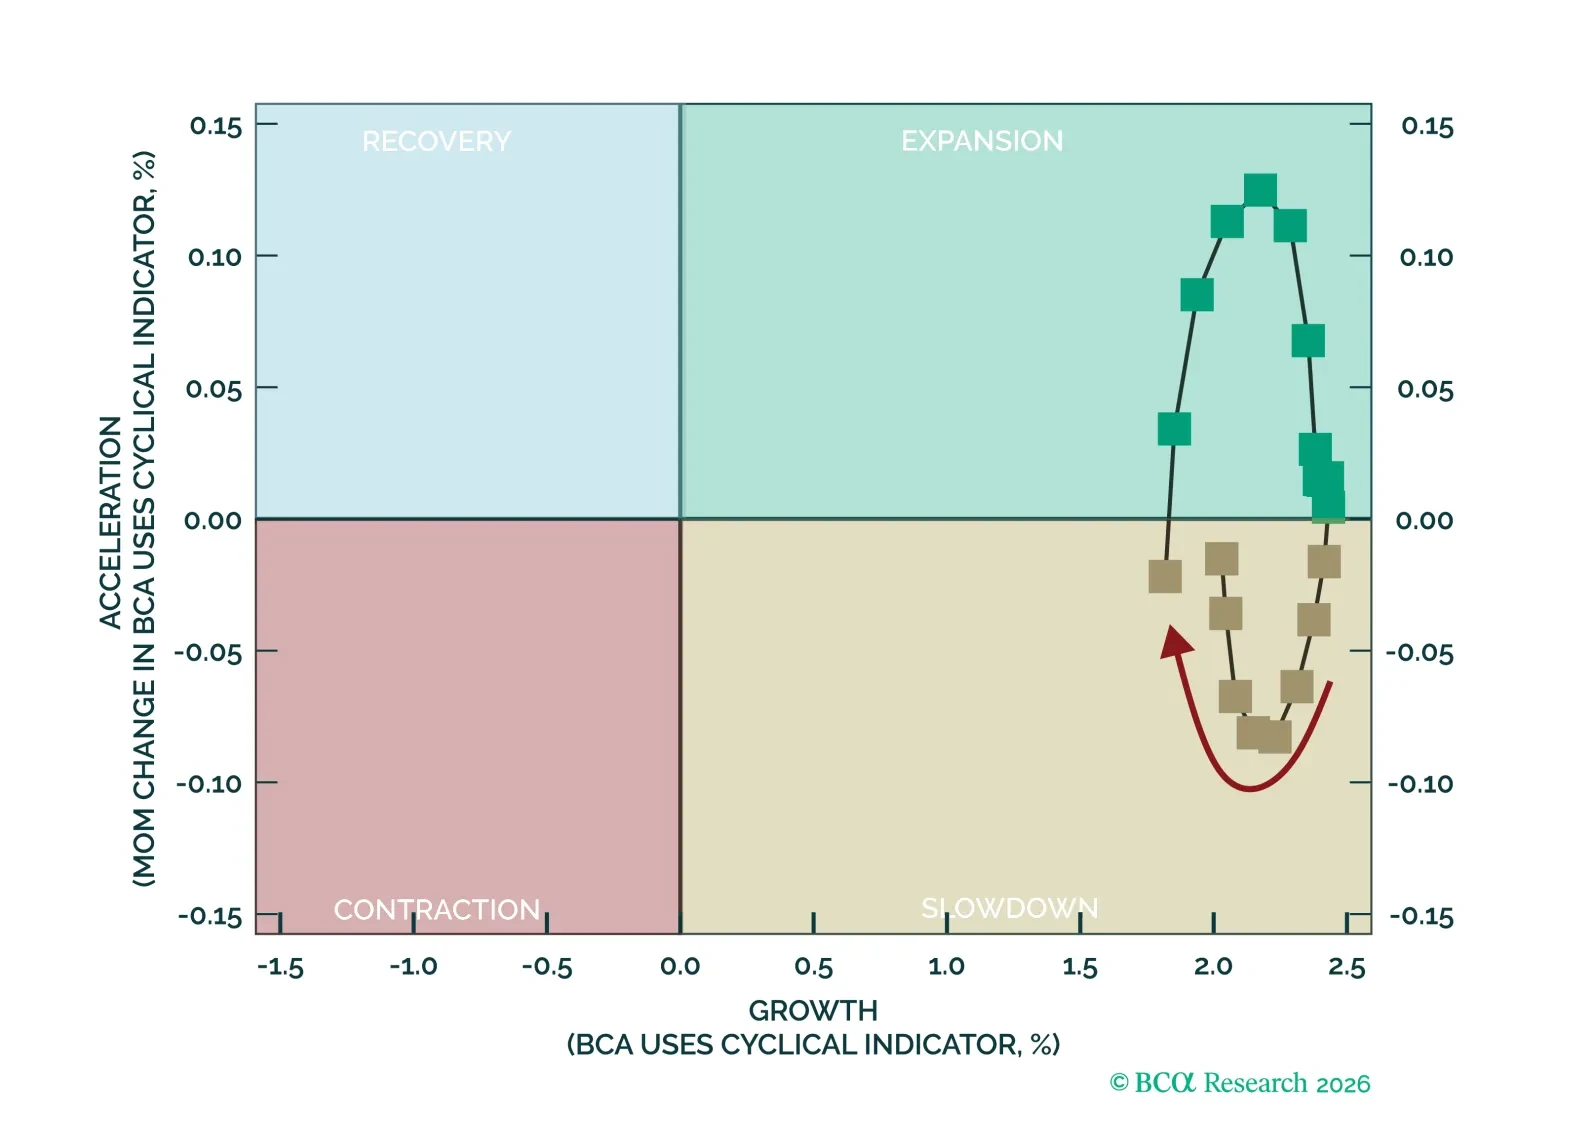
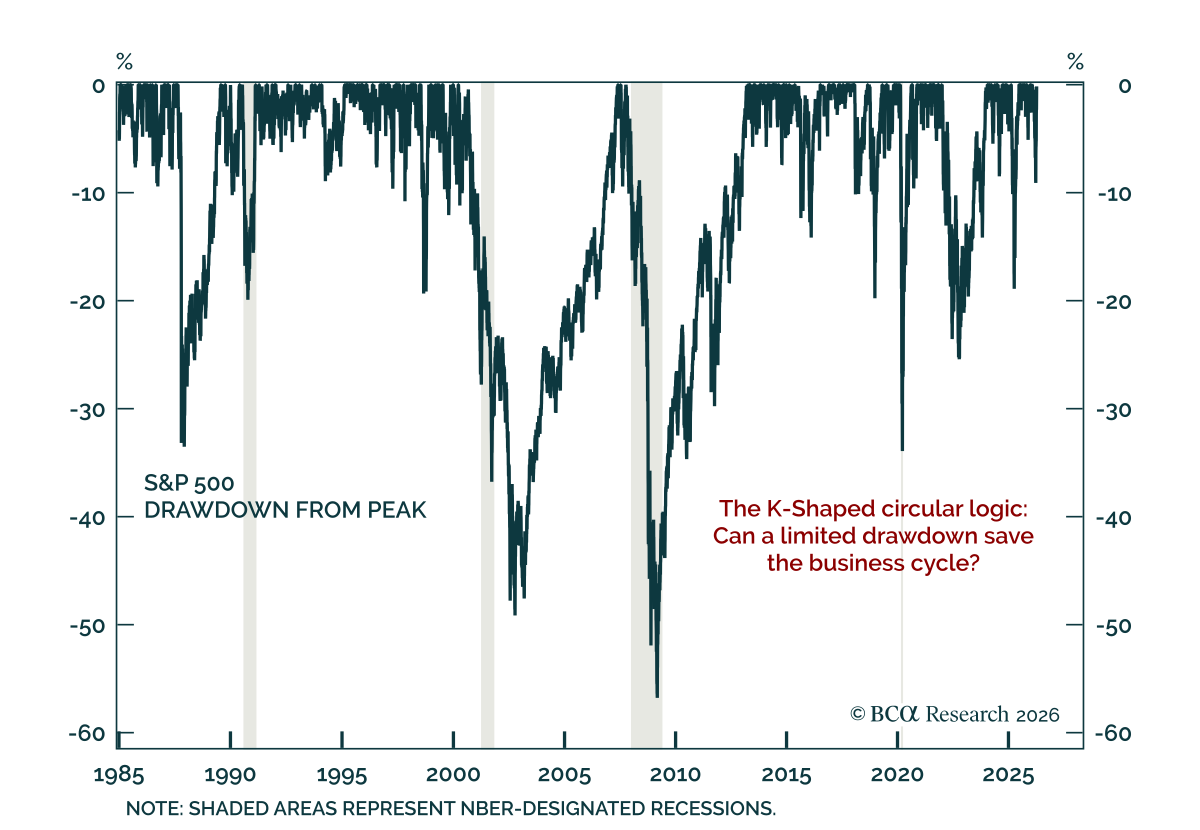
The S&P 500 rally is likely more than just risk-relief. Market internals reflect strengthening economic growth and higher inflation, with support coming from robust earnings. Tight financial conditions have compressed valuations, particularly within the Tech sector. We are initiating a long Software trade ahead of earnings season, given that multiples have declined and earnings growth is strong.
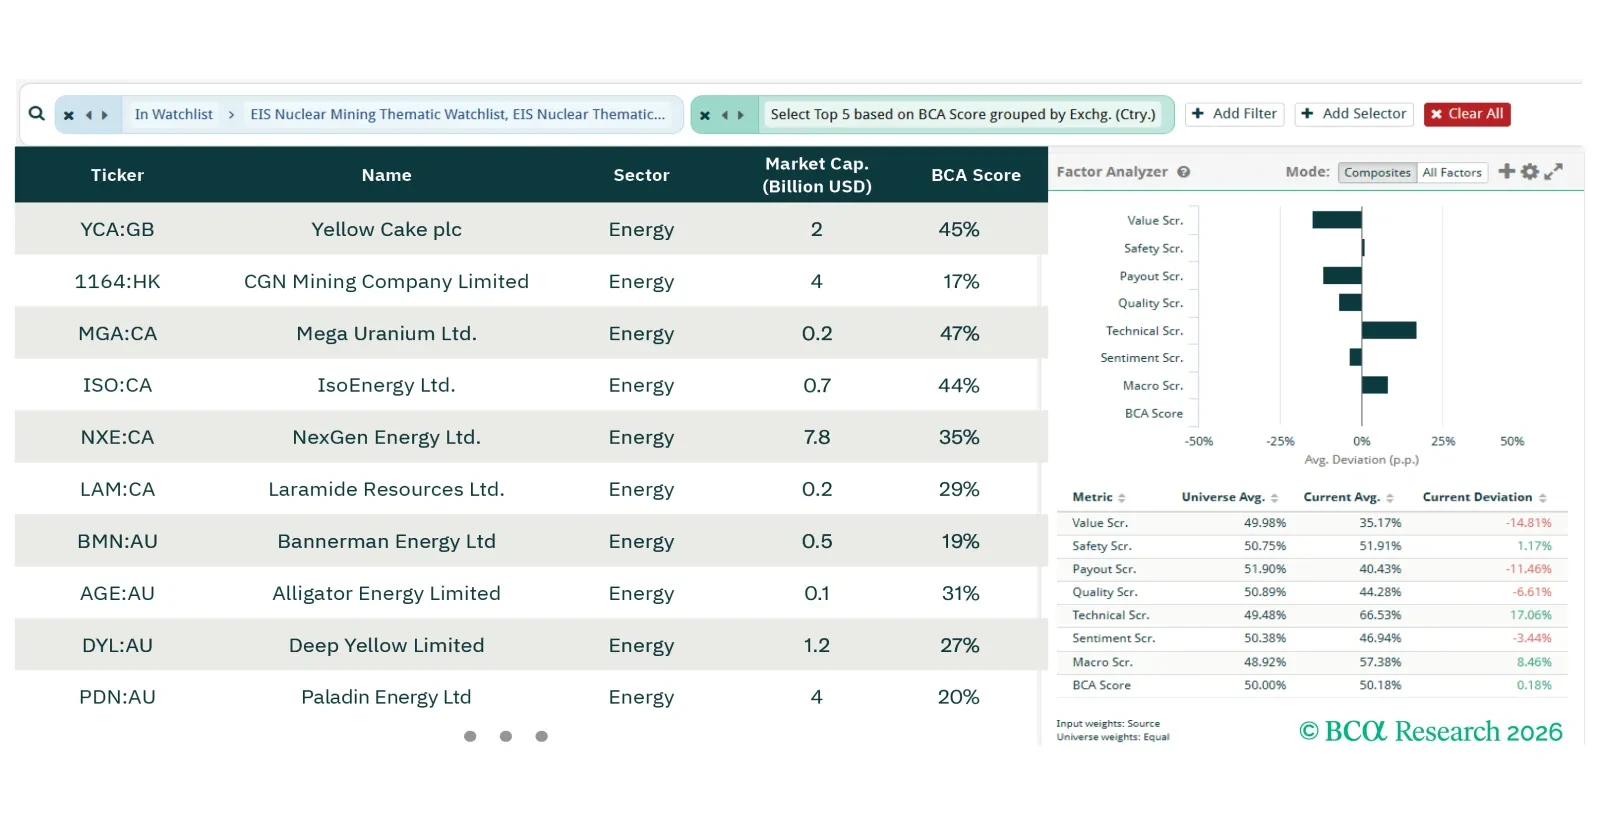
In this screener report, we explore opportunities in nuclear theme, geopolitical hedge, and winners from AI productivity boom.
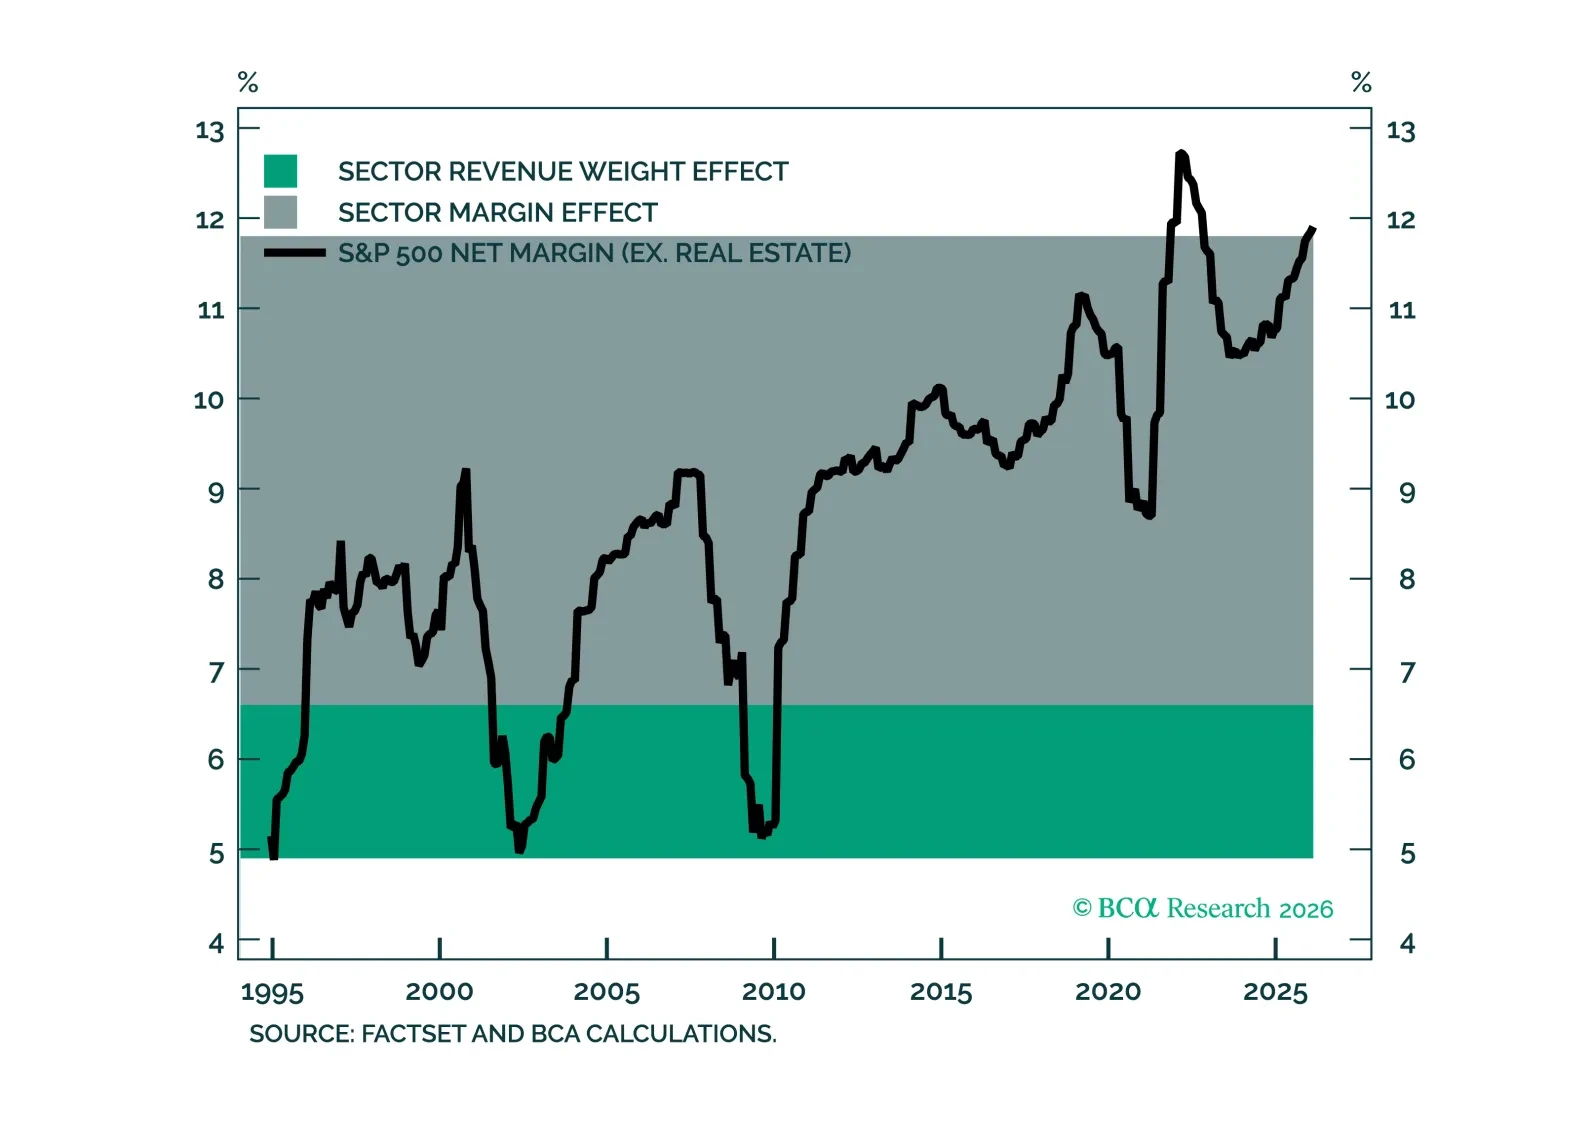
The long-run rise in S&P 500 margins reflects more than a shift toward higher-margin sectors. Most of the increase has come from higher profitability within sectors, supported by favorable mix of macro forces. Looking ahead, many of those tailwinds are likely to fade, with AI-driven productivity gains as a potential offsetting upside driver of margins.
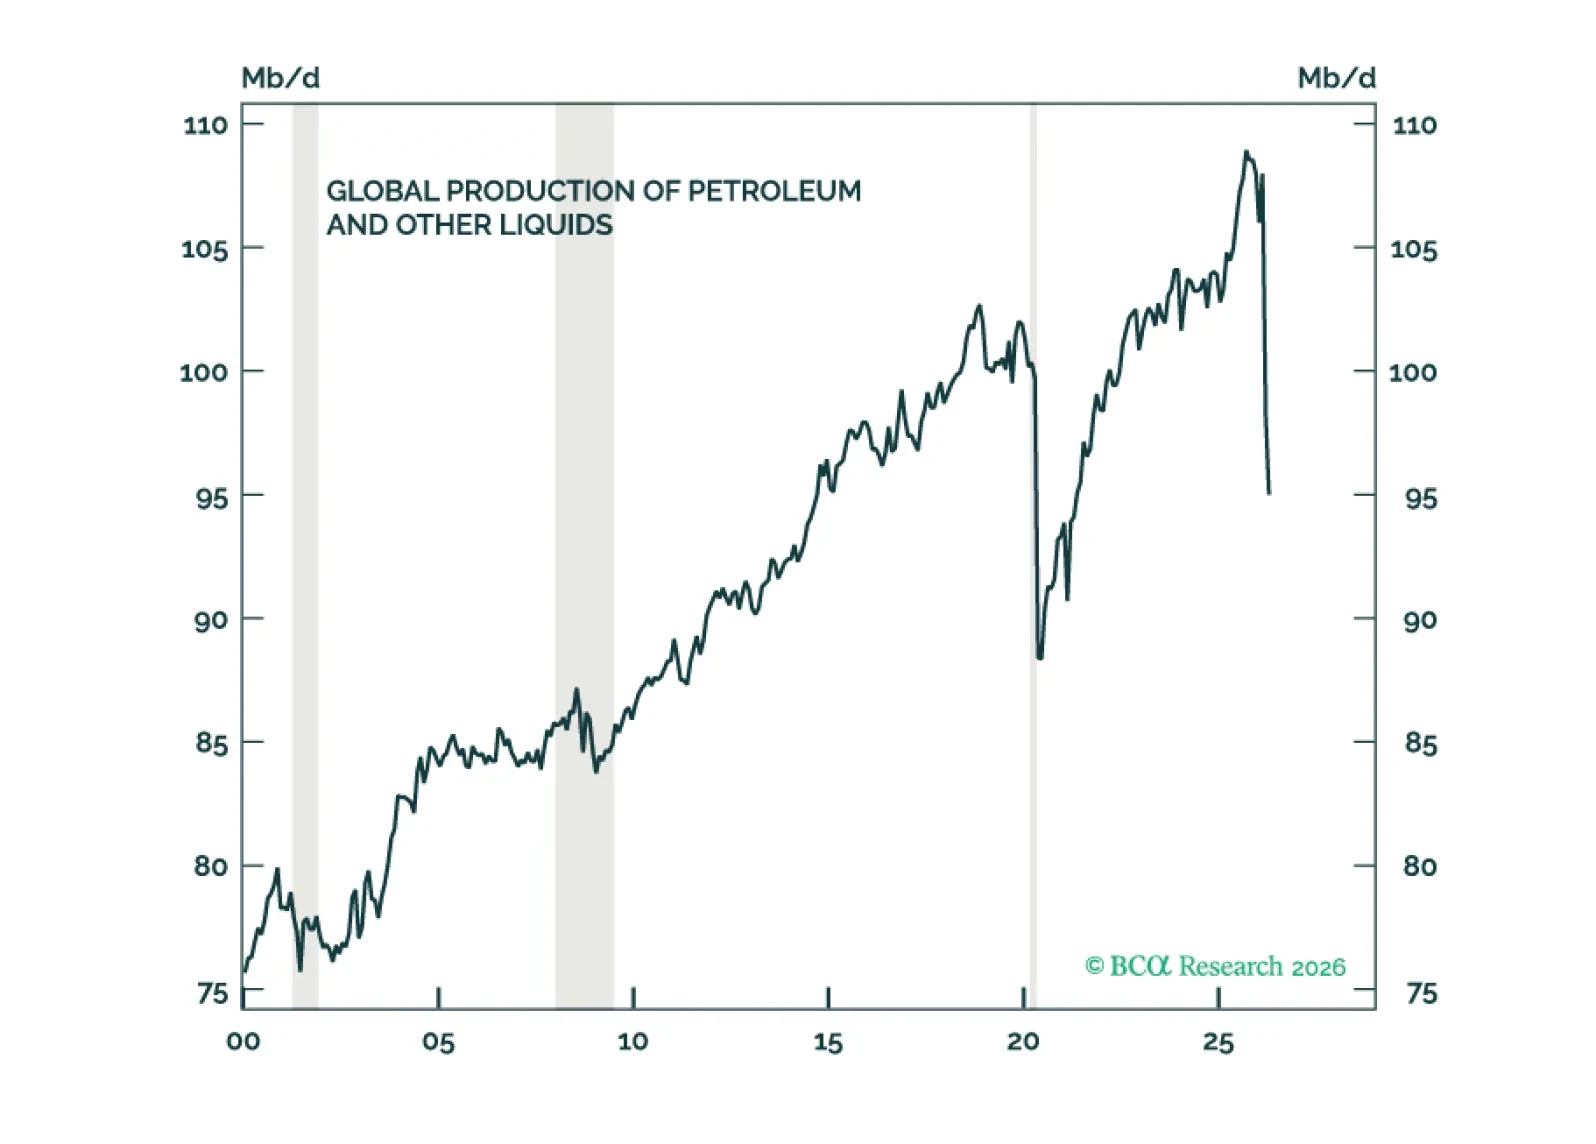
The relief rally in stocks can continue a while longer. However, much can still go wrong. As such, we are retaining a 12-month underweight to stocks but are moving to neutral on a short-term tactical horizon.