Economy

The April ISM Manufacturing report was flat on the headline, but softer on growth and hotter on inflation underneath. The index held at 52.7, missing estimates. Despite the unchanged headline, the underlying signals pointed to mild growth deterioration. New…
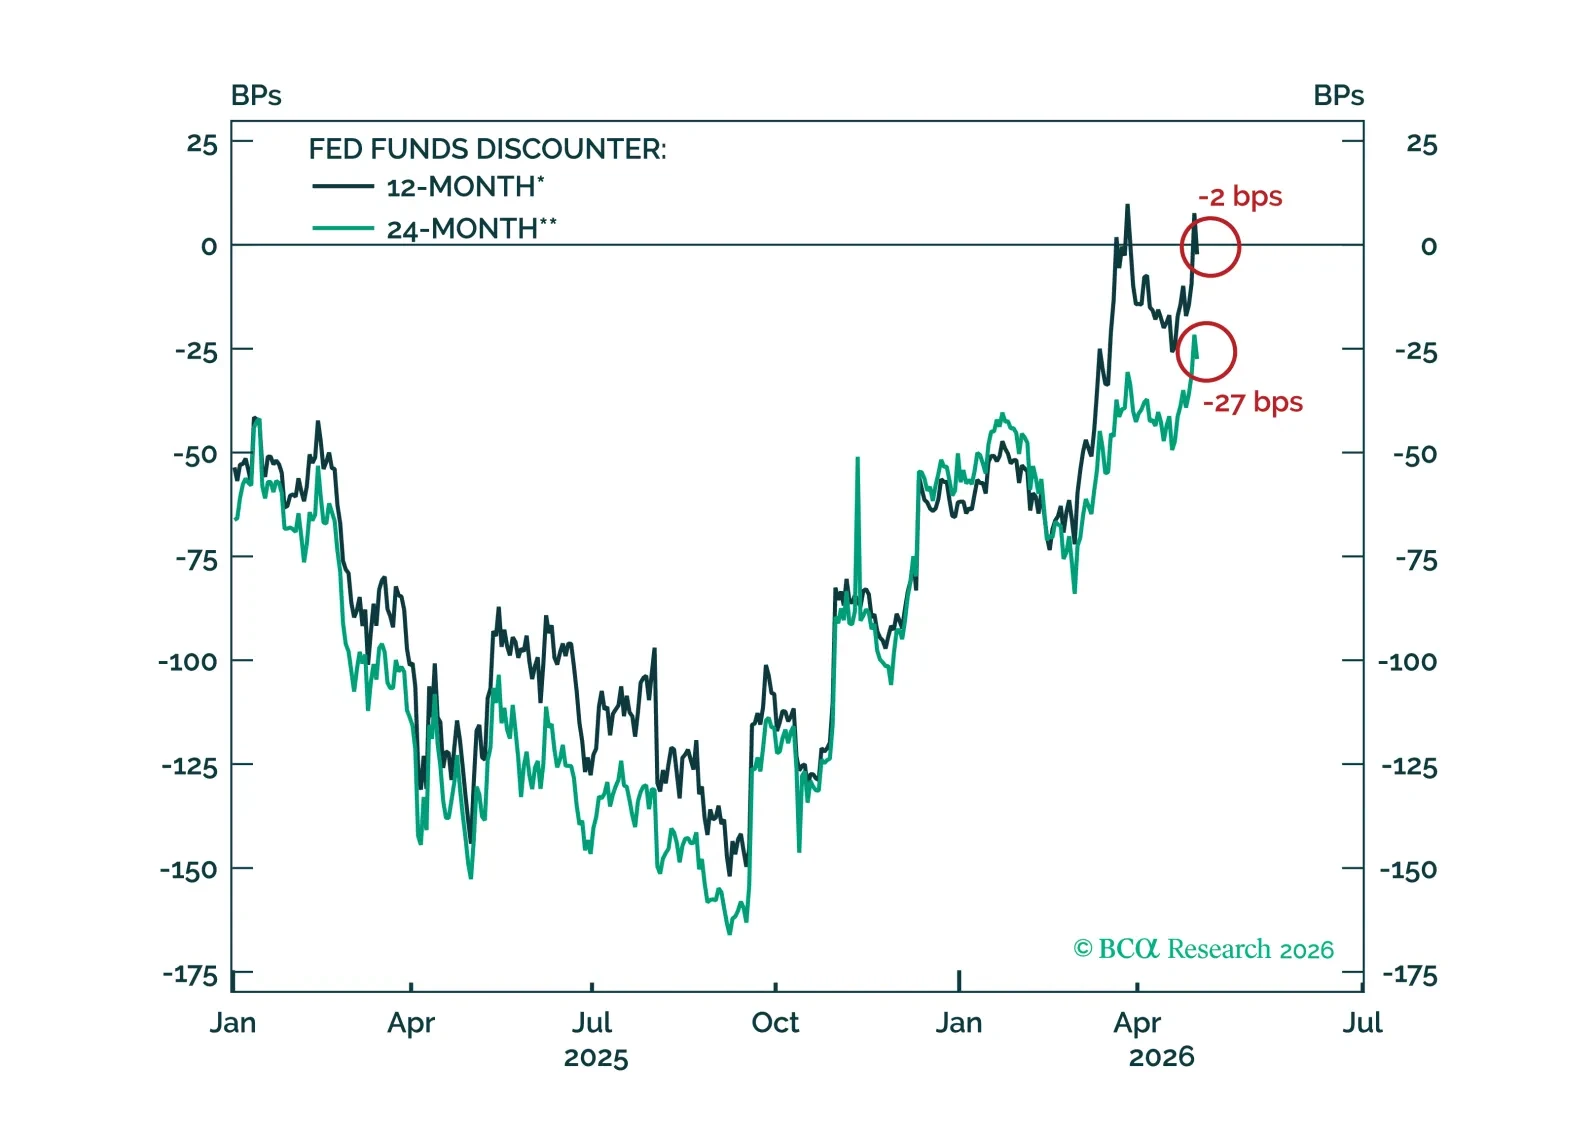
So far, there is no evidence of second-round effects from the oil price shock showing up in the US economy. Fed rate hikes are off the table unless those effects emerge.

FOMC participants are coalescing around the idea that the funds rate will stay on hold for some time, an outcome that is now well priced in the bond market and that will not materially change under a new Fed Chair.
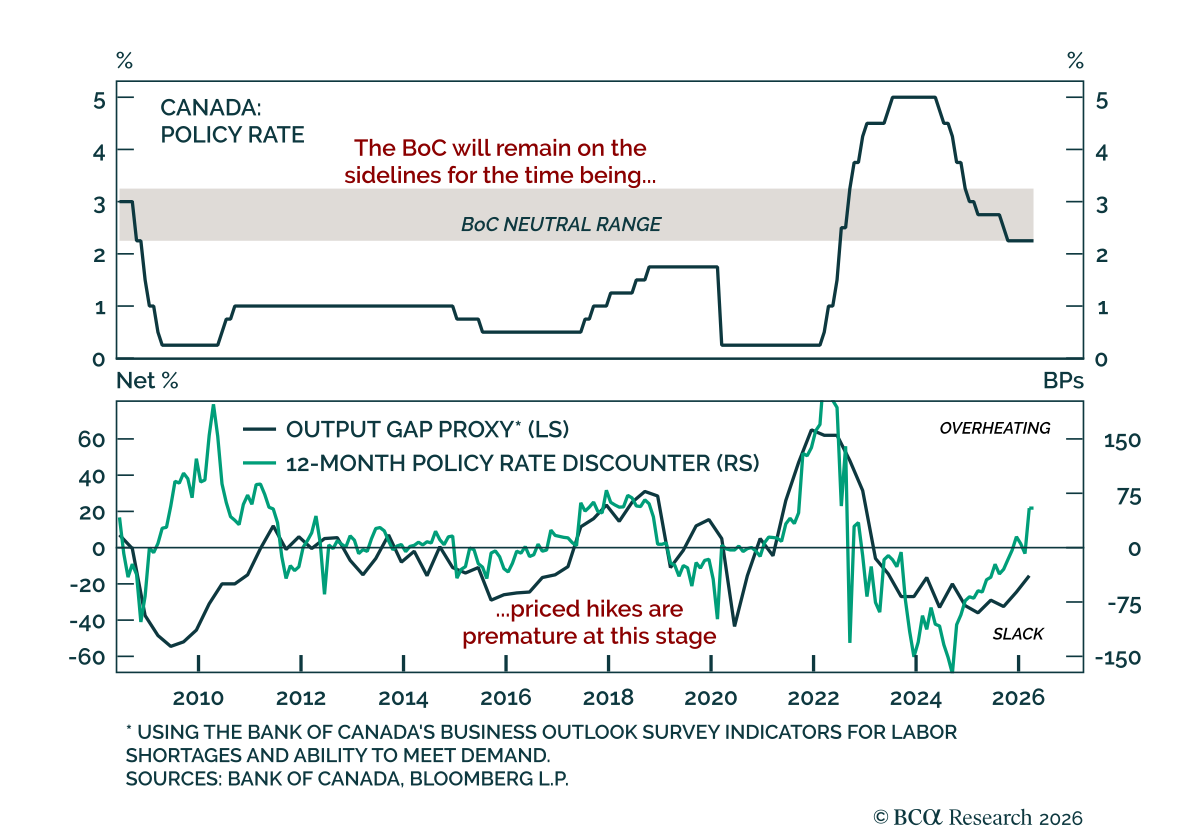
The Bank of Canada held rates at 2.25% for a fourth consecutive meeting; a weak domestic economy still argues for looking through supply-side inflation. The hold was expected, and at 2.25%, the policy rate sits at the bottom of the BoC’s estimated 2.25%-3.25%…
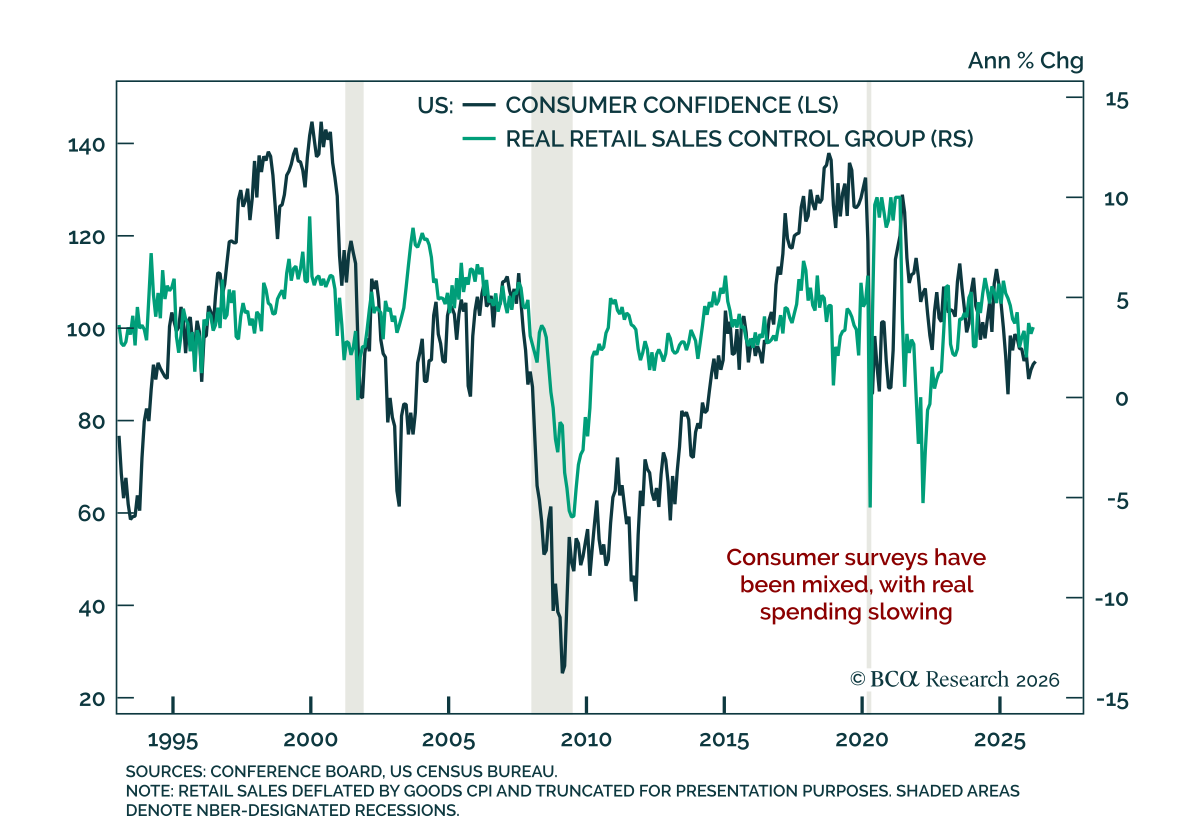
The April Conference Board survey beat estimates, with both current conditions and expectations improving. Consumer confidence rose to 92.8 from 92.2, when consensus expected a pullback. Consumers’ assessment of their present situation was mostly flat after…

The April Dallas Fed survey missed estimates, but underlying activity remained firmer than the headline suggested. The manufacturing headline index fell to -2.3 from -0.2. Comments were mixed, but respondents broadly pointed to slower sales due to uncertainty…

German data continue to deteriorate, reinforcing Europe’s vulnerability to a prolonged energy shock. The May GfK German Consumer Climate indicator fell to -33.3 from -28.1, a level not seen since the 2022 energy shock and near all-time lows for the series.…
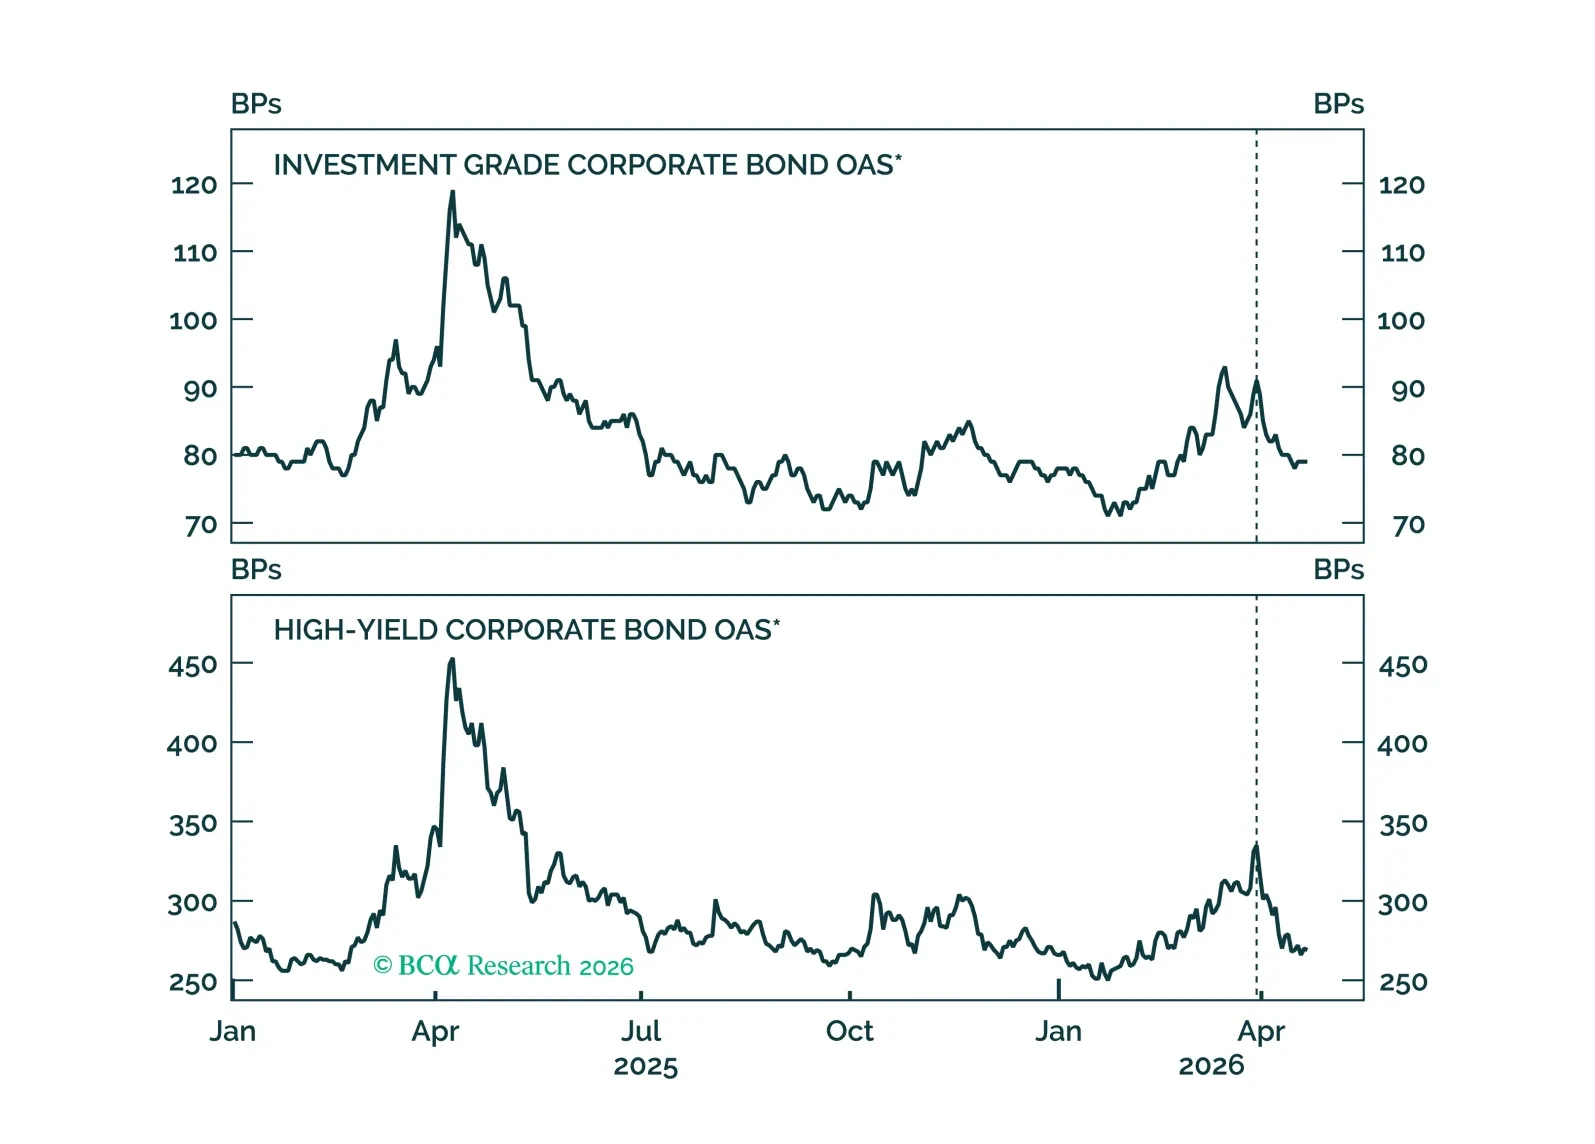
We recommend increasing exposure to spread product as the US economy transitions back into a low rate vol regime.

The April ZEW showed continued deterioration in European sentiment, with no sign yet of a rebound. Germany’s expectations component missed estimates and fell to -17.2 from -0.5, while the eurozone measure fell to -20.4 from -8.5. Current conditions in Germany…
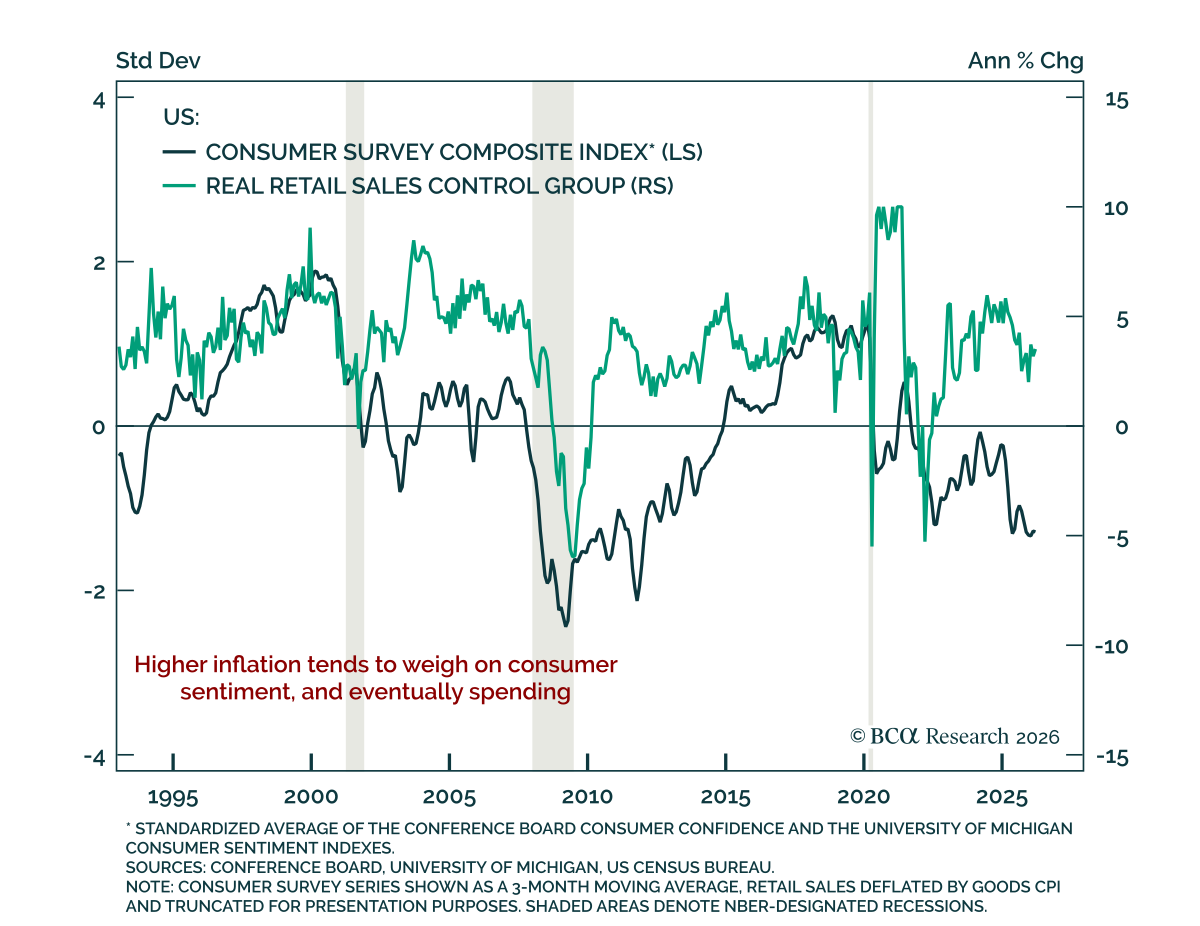
March US retail sales beat estimates, but the strength was nominal rather than real. Headline sales rose 1.7% m/m from 0.7%, while core sales (excluding autos and gas) held at 0.6%. The control group, which feeds into GDP, rose 0.7%. The report was however…