Latest from BCA Research
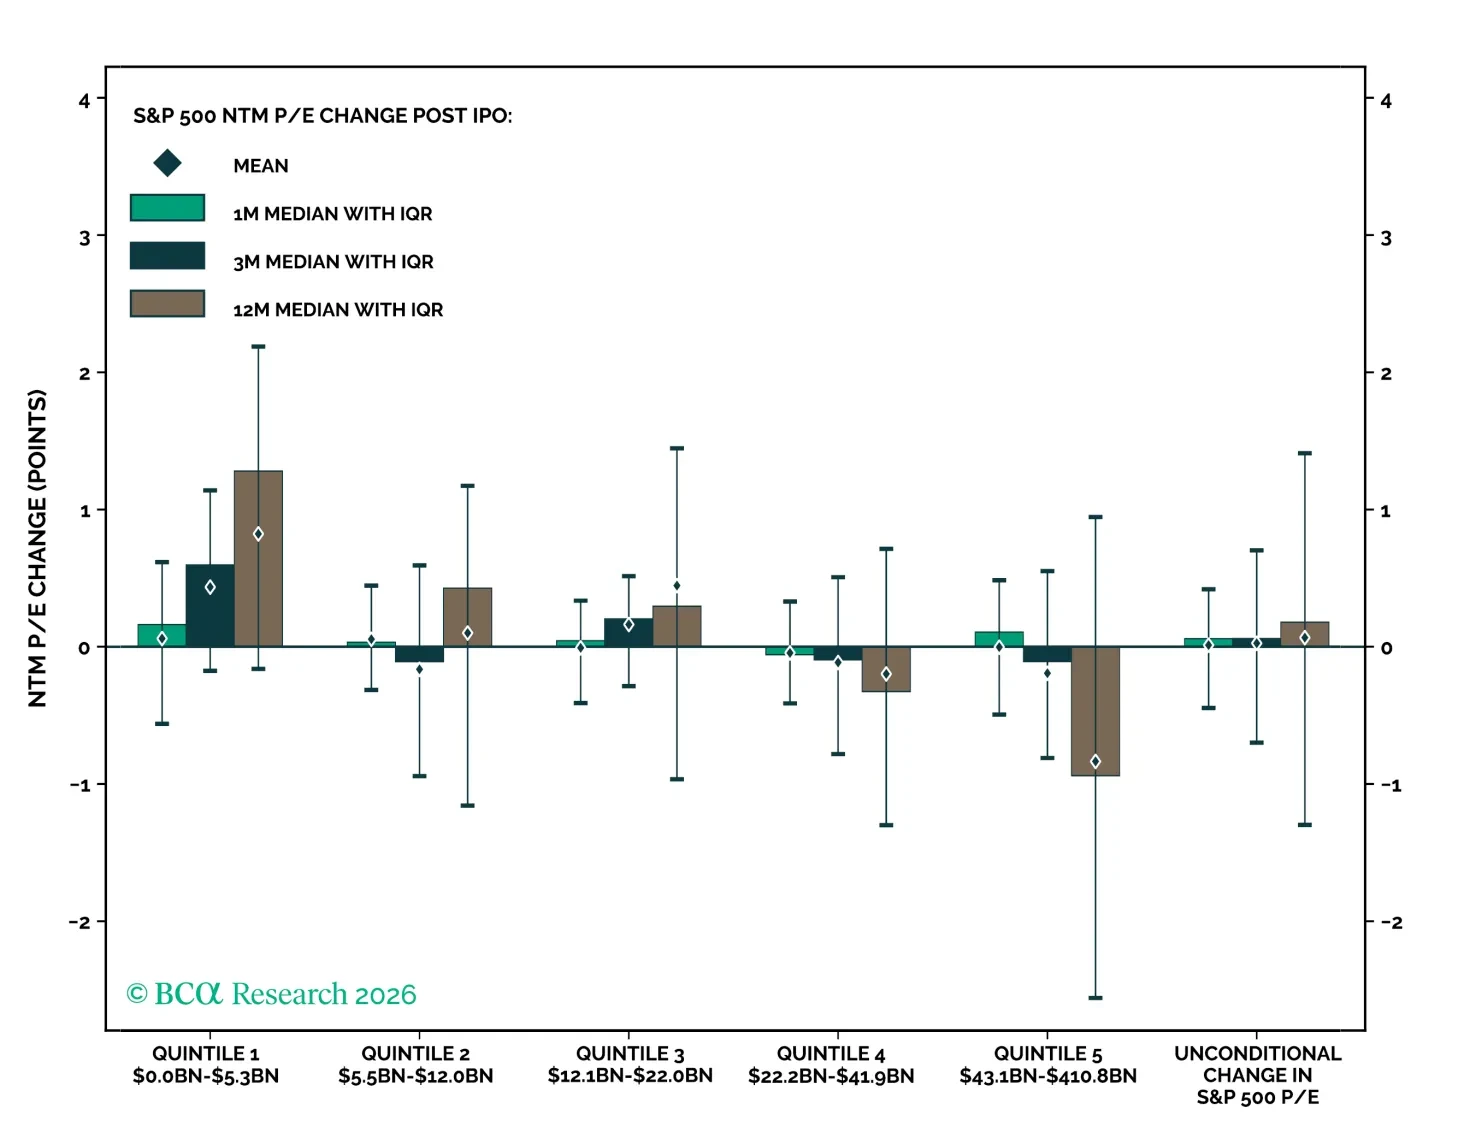
The IPO wave has arrived, dominated by SpaceX’s massive listing. Aftermarket performance has been weak, and elevated issuance is weighing on S&P 500 multiples, although some pressure is already priced. SpaceX remains only partly digested, while Anthropic and OpenAI will bring further supply and greater business model scrutiny.
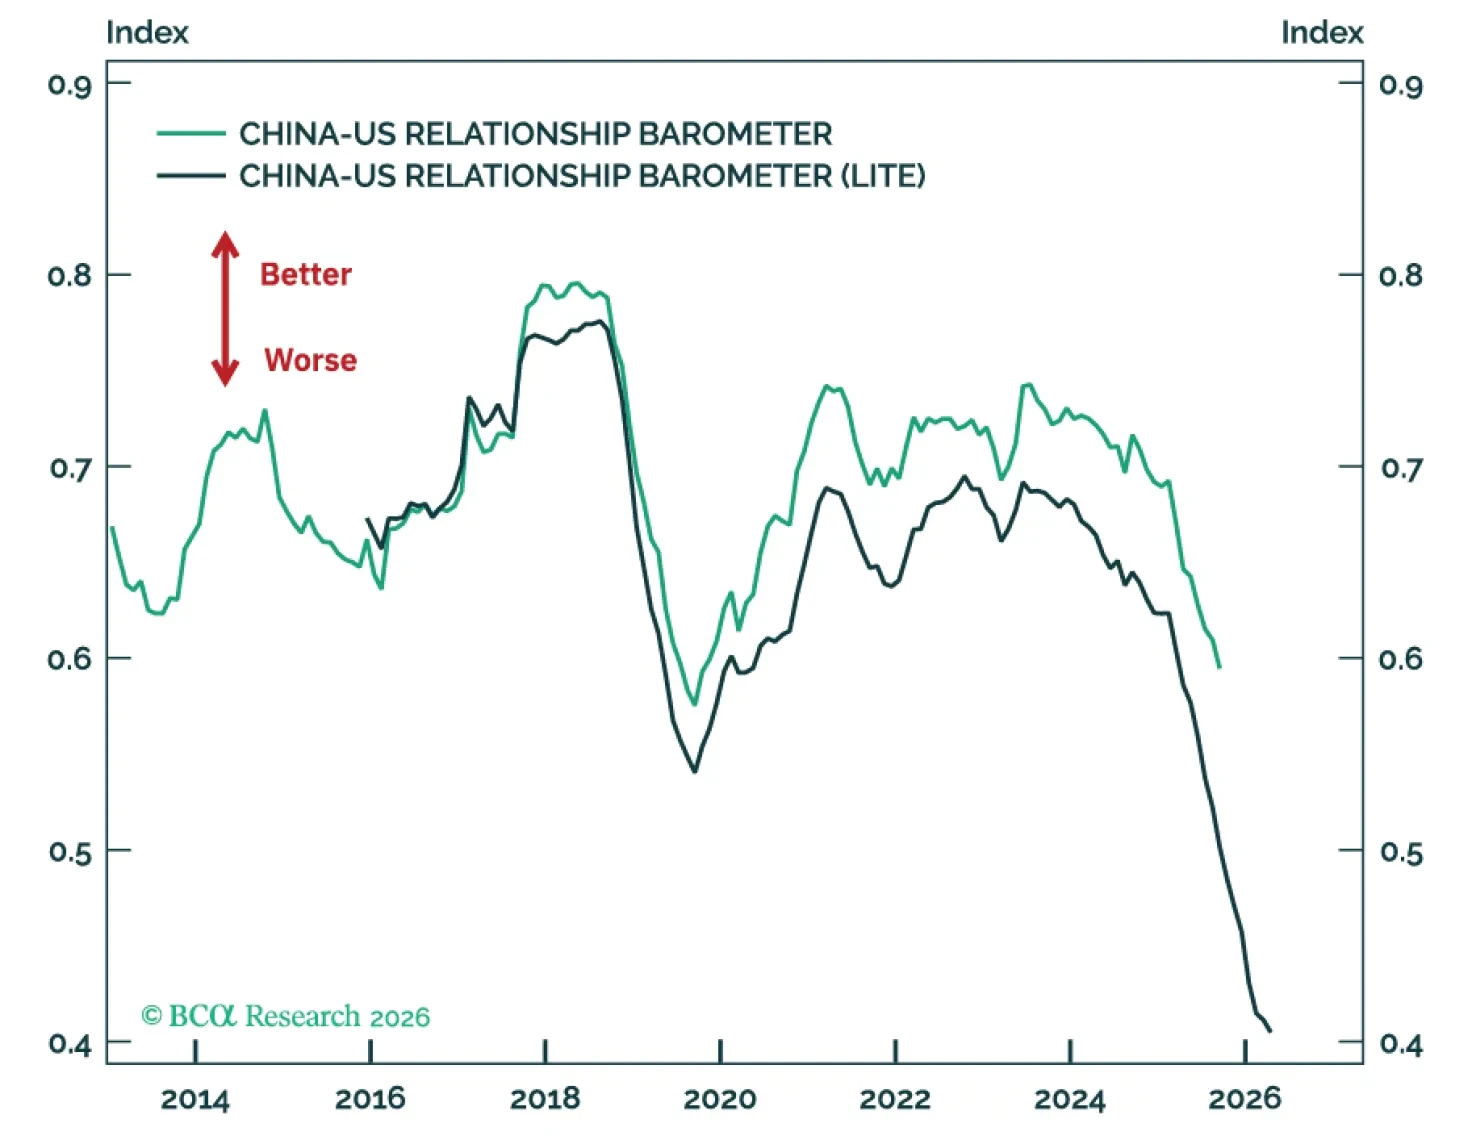
The Trump-Xi summit does not imply concrete benefits to US-China trade. Strategic tensions persist, forcing China to increase fiscal stimulus in 2027.
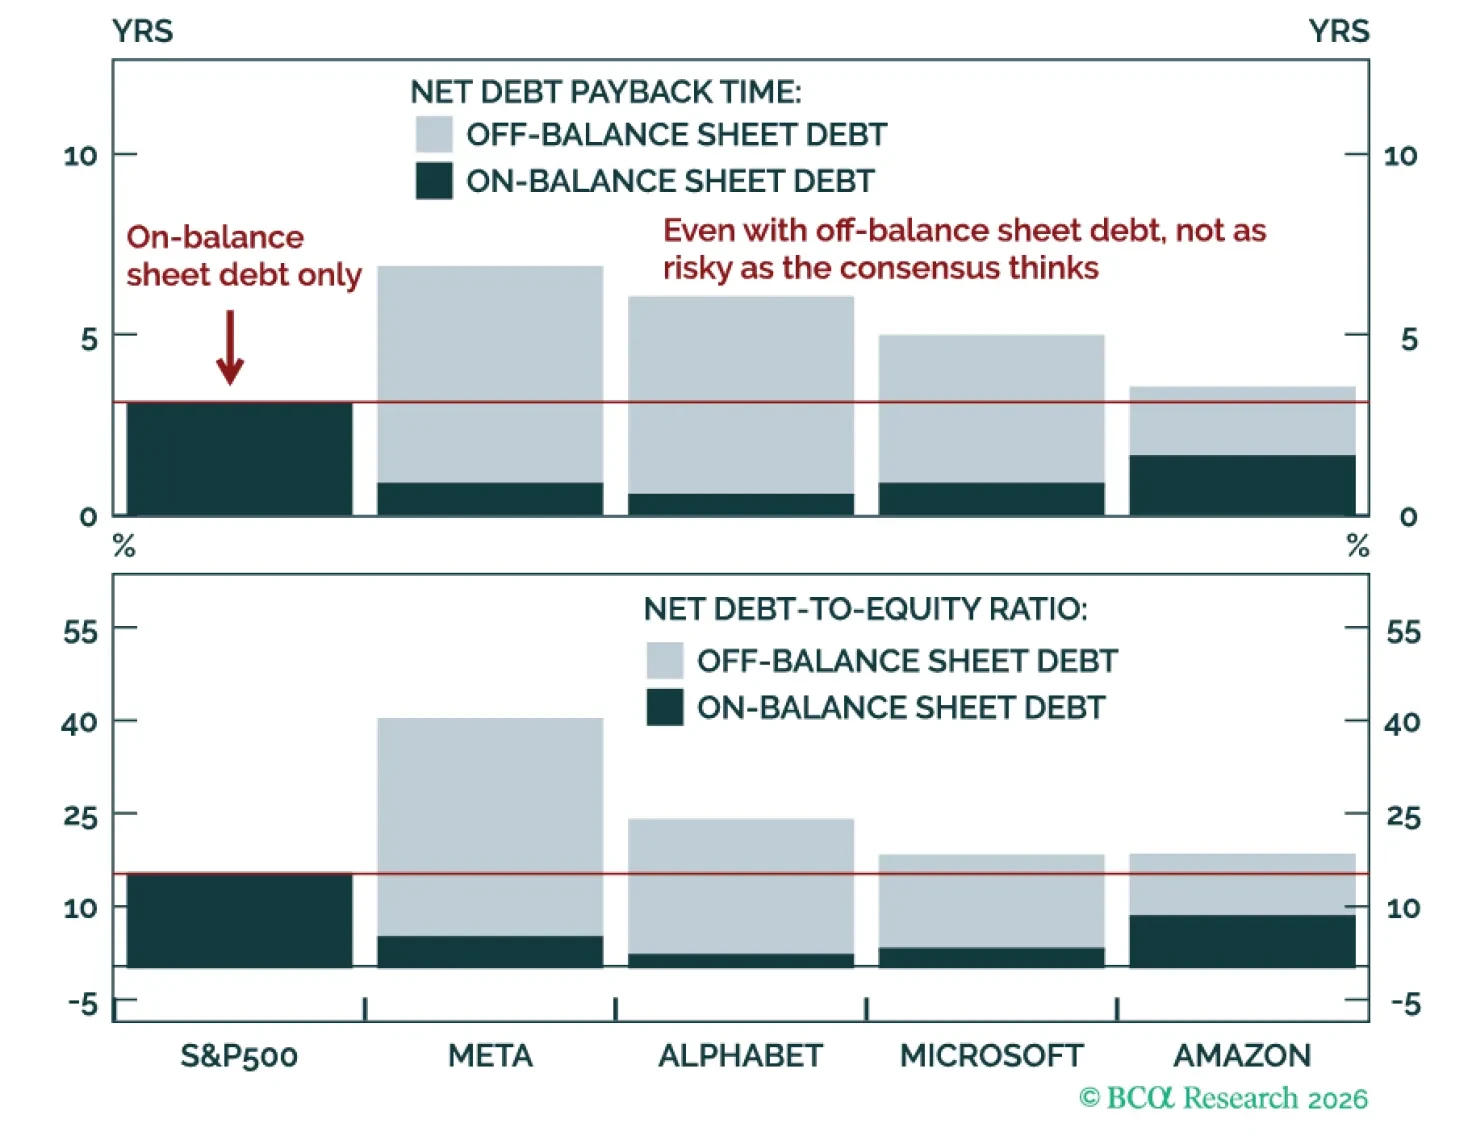
Nerves are rising around Data Center financing but most of the fear comes from GPU financing. GPUs are not Data Centers. Data Center collateral is solid, and so are the tenants.
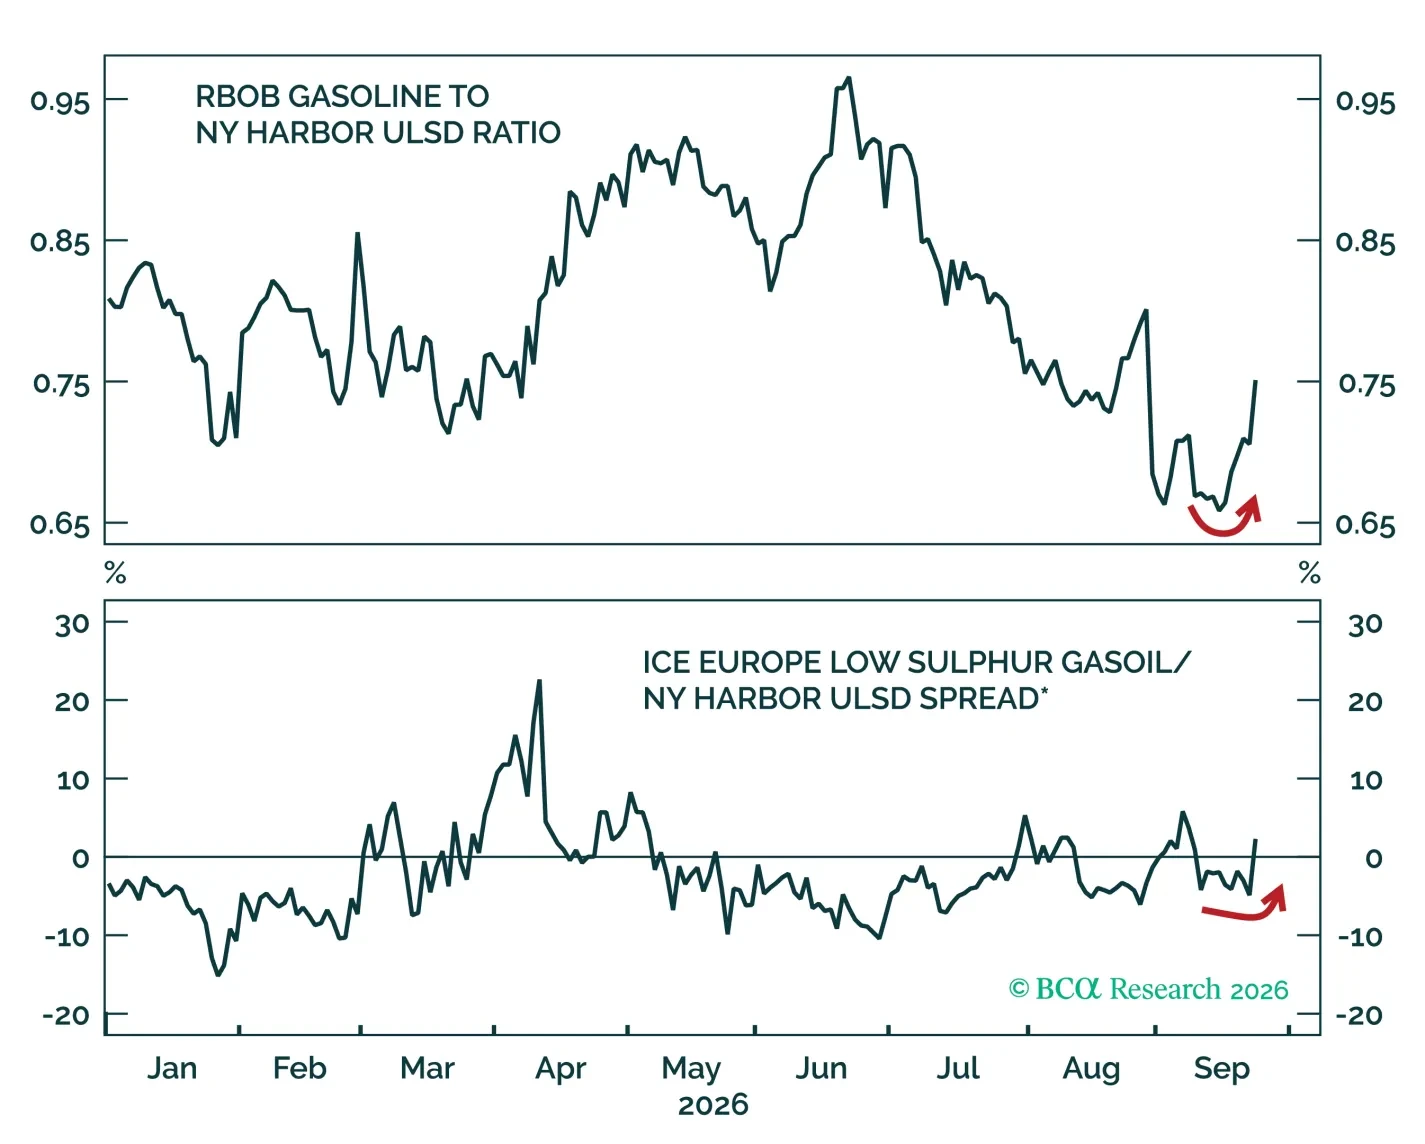
Record diesel prices and mounting political pressure make some form of US export restriction likely. But it wouldn't be a clean solution. We reveal why relief would be fleeting, who would pay the price, and how to trade it.
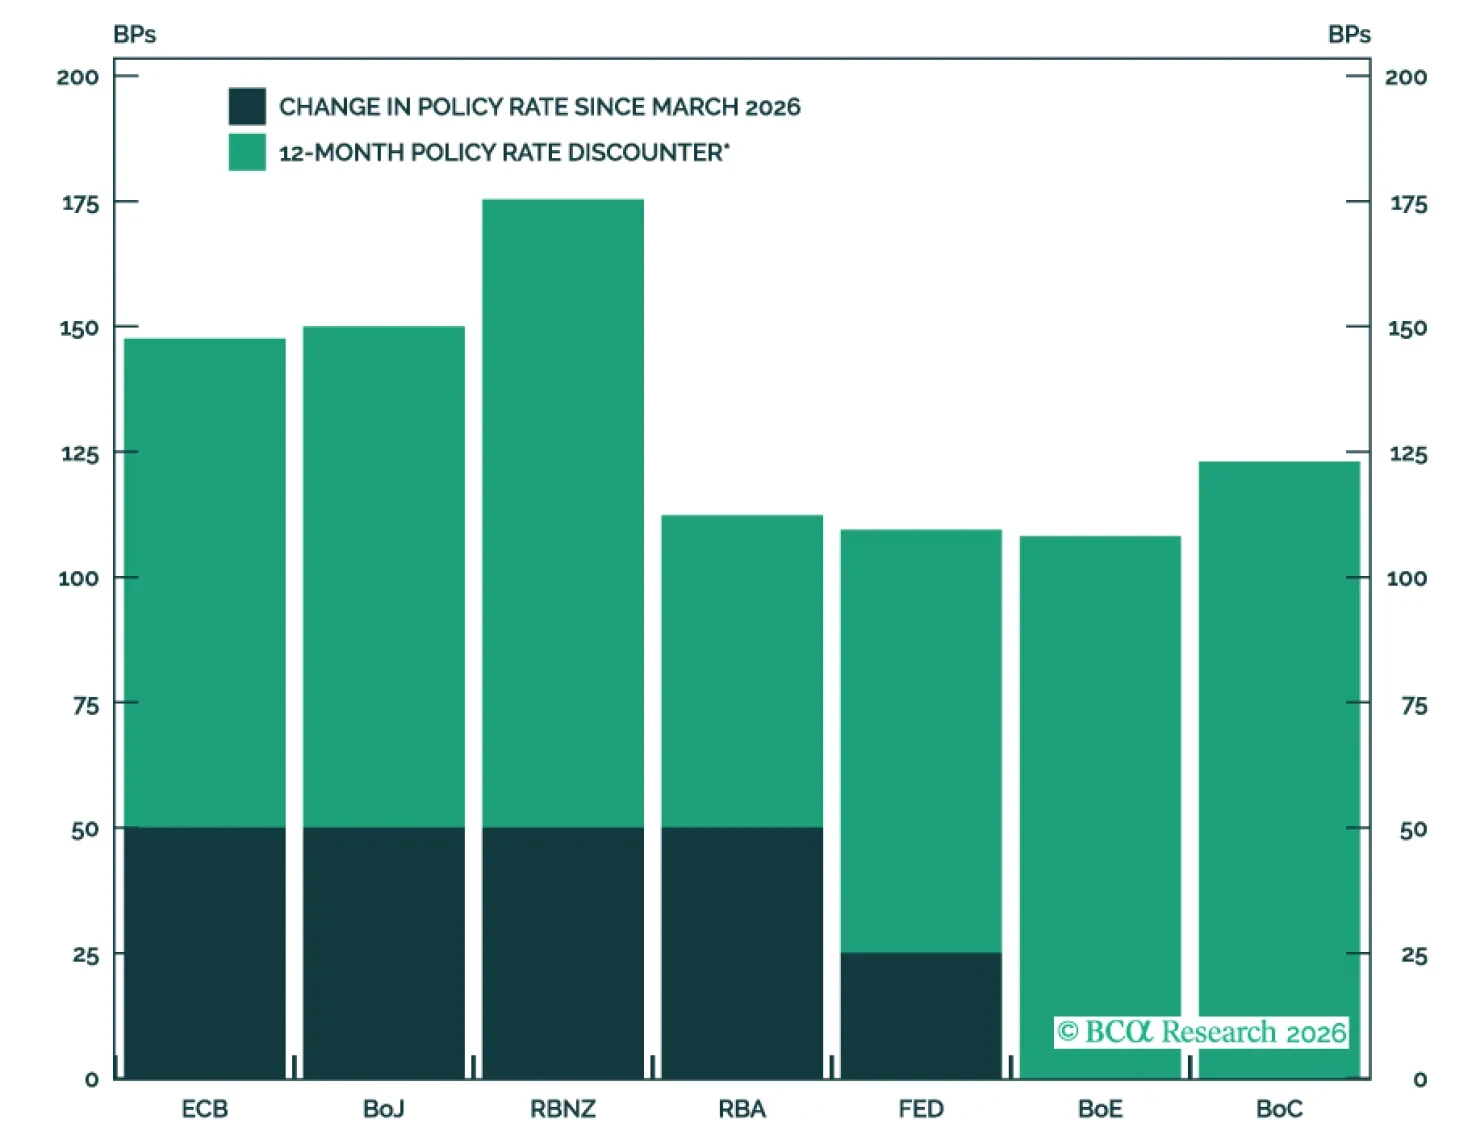
Policy rates are poised to rise across the developed world as central banks are no longer willing to wait out the Iran-US standoff before taking action to combat the inflationary effects of higher oil prices. Outside of Japan, however, we do not think central banks will hike as much as markets expect.
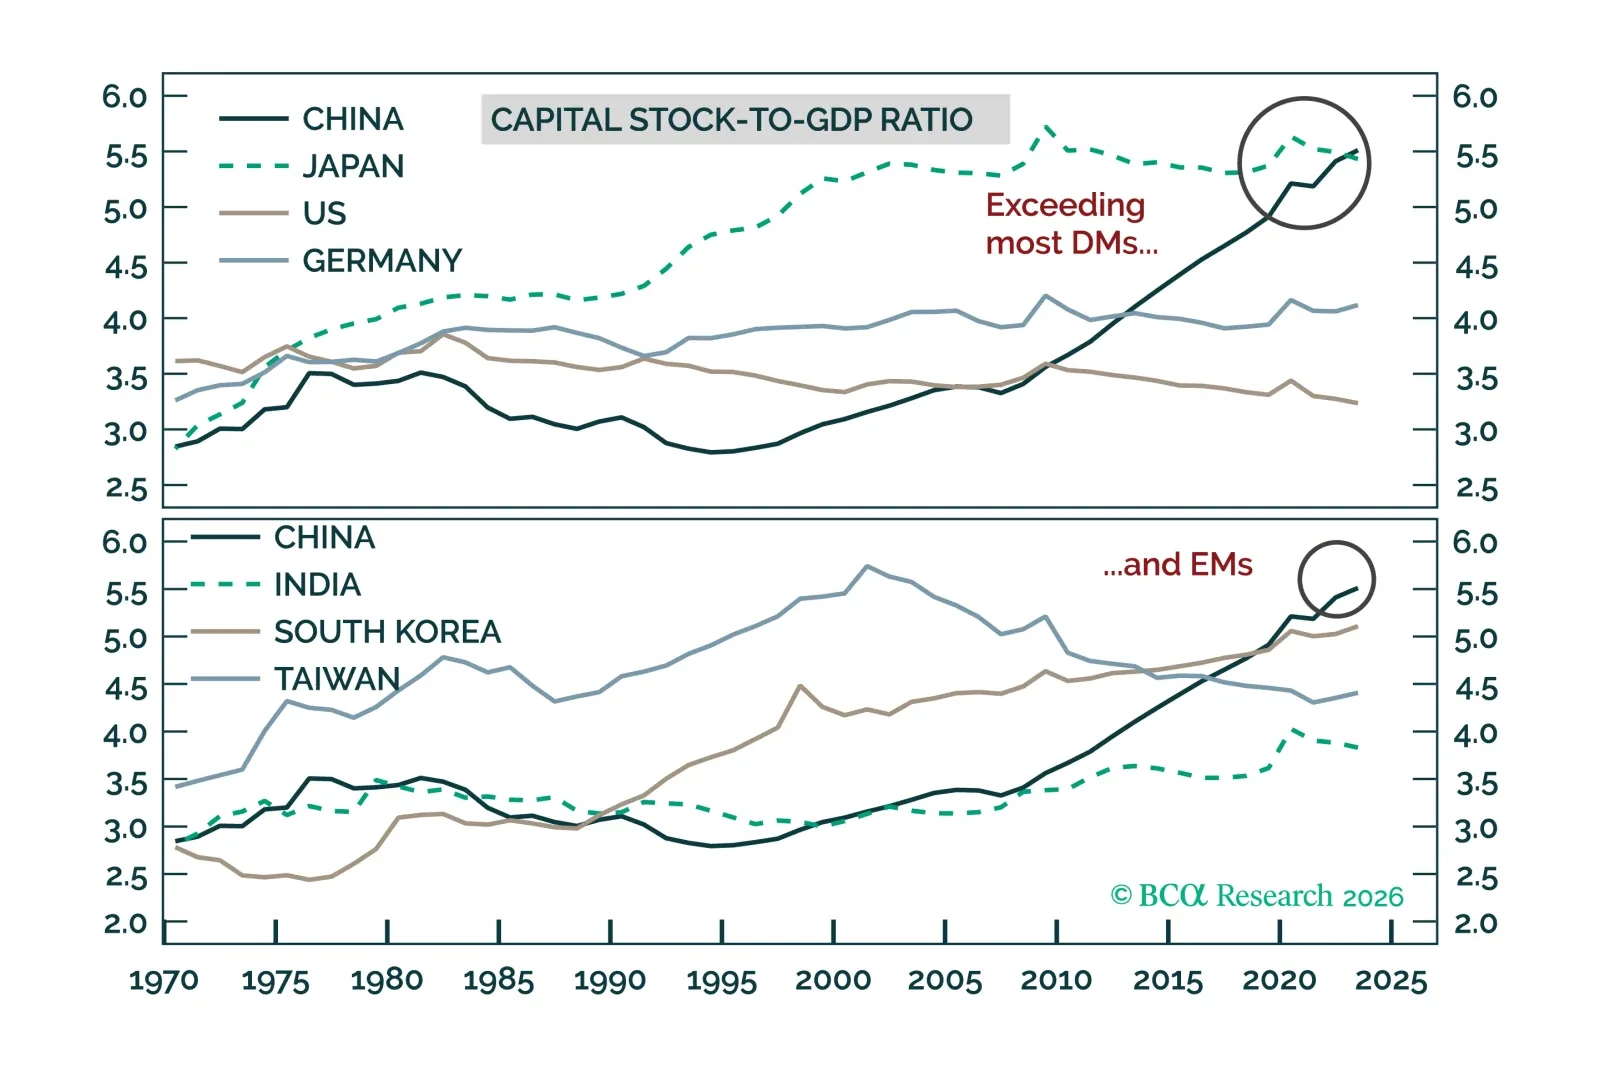
China’s investment has hit cyclical and structural limits. Mounting economic pressures will likely push Beijing toward a more aggressive, consumer-focused reflationary stance over the next one to two years.
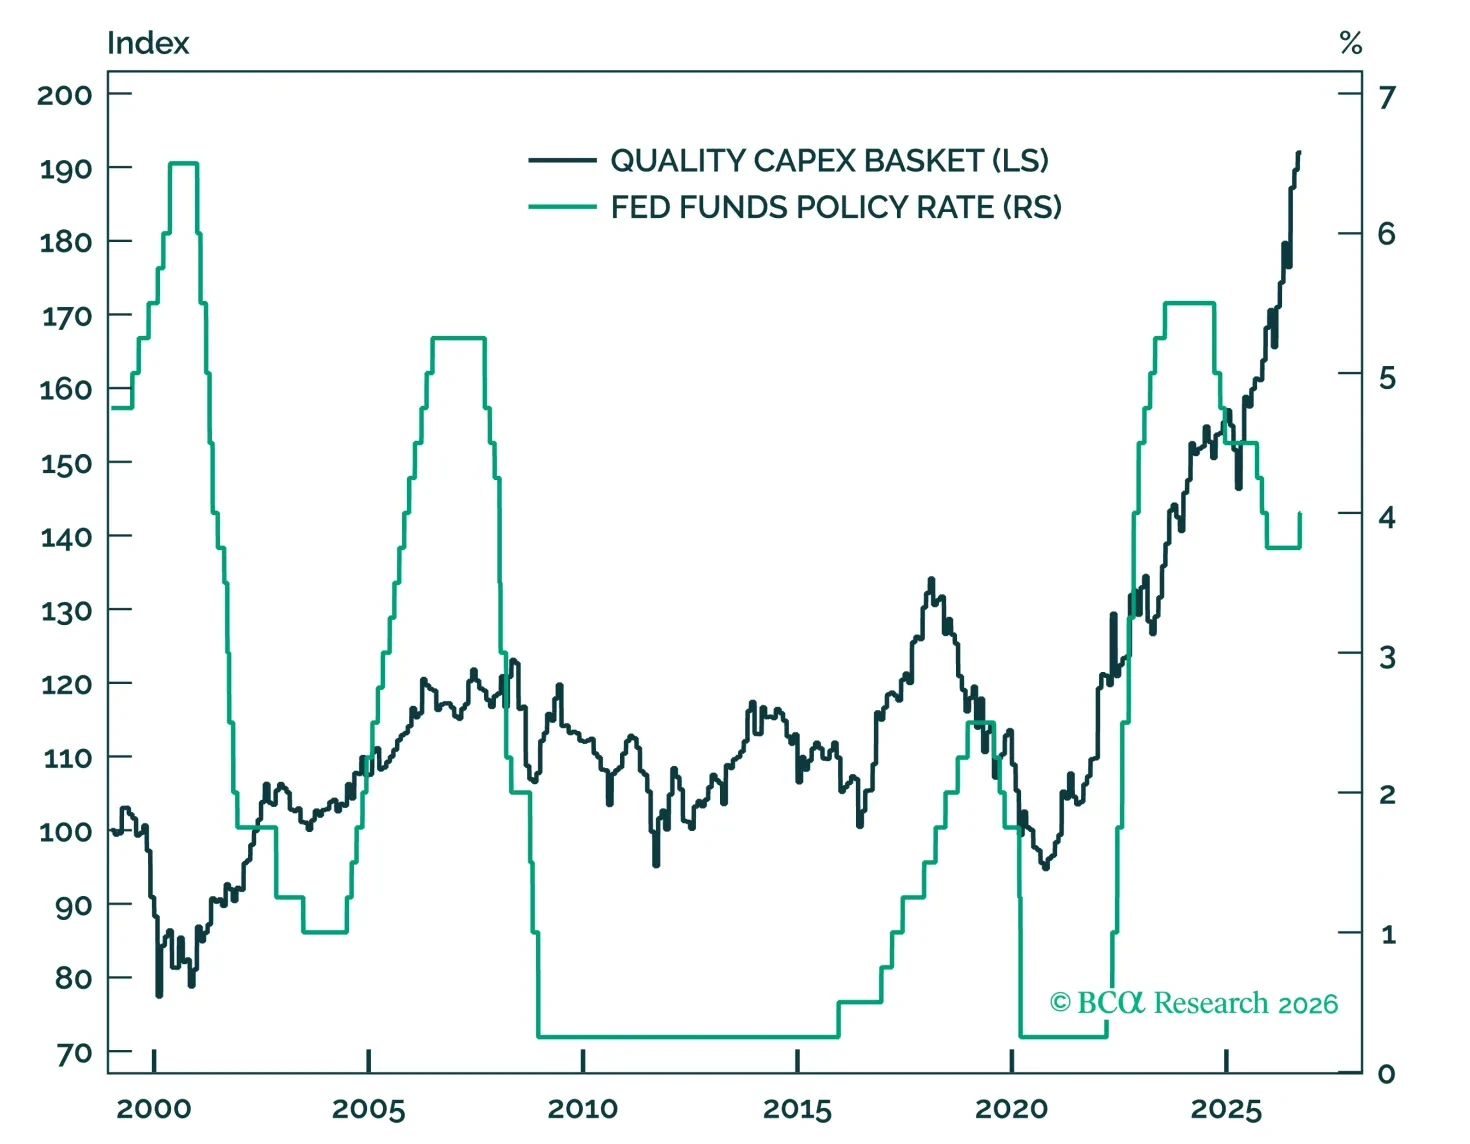
The Fed’s first hike is unlikely to be an equity-market cliff. Recent multiple compression has absorbed some of the rate shock, while bond risk premia, rate volatility, and inflation expectations remain contained. Stocks have typically climbed through hiking cycles, but we favor moving up in quality through our long/short Quality Capex Basket.
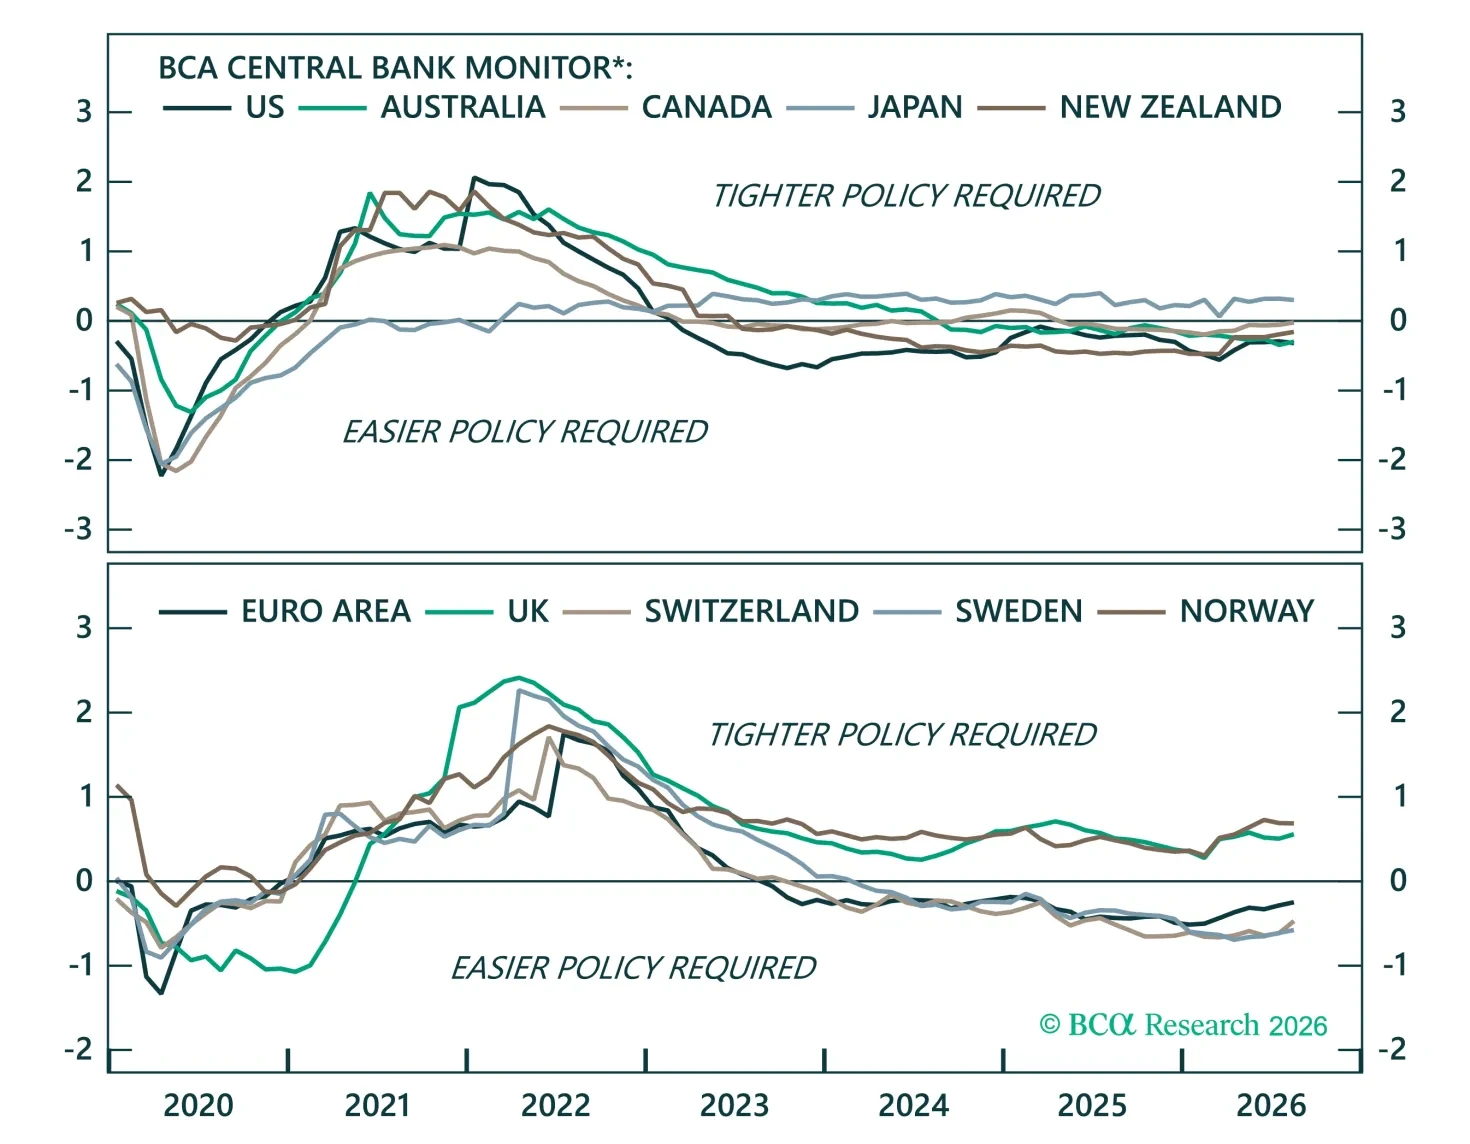
Central banks have begun a mild tightening cycle as elevated energy prices raise concerns about second-round inflation effects. We use BCA’s Central Bank Monitors to test whether hawkish market pricing is justified and identify tactical opportunities across global bond and currency markets.
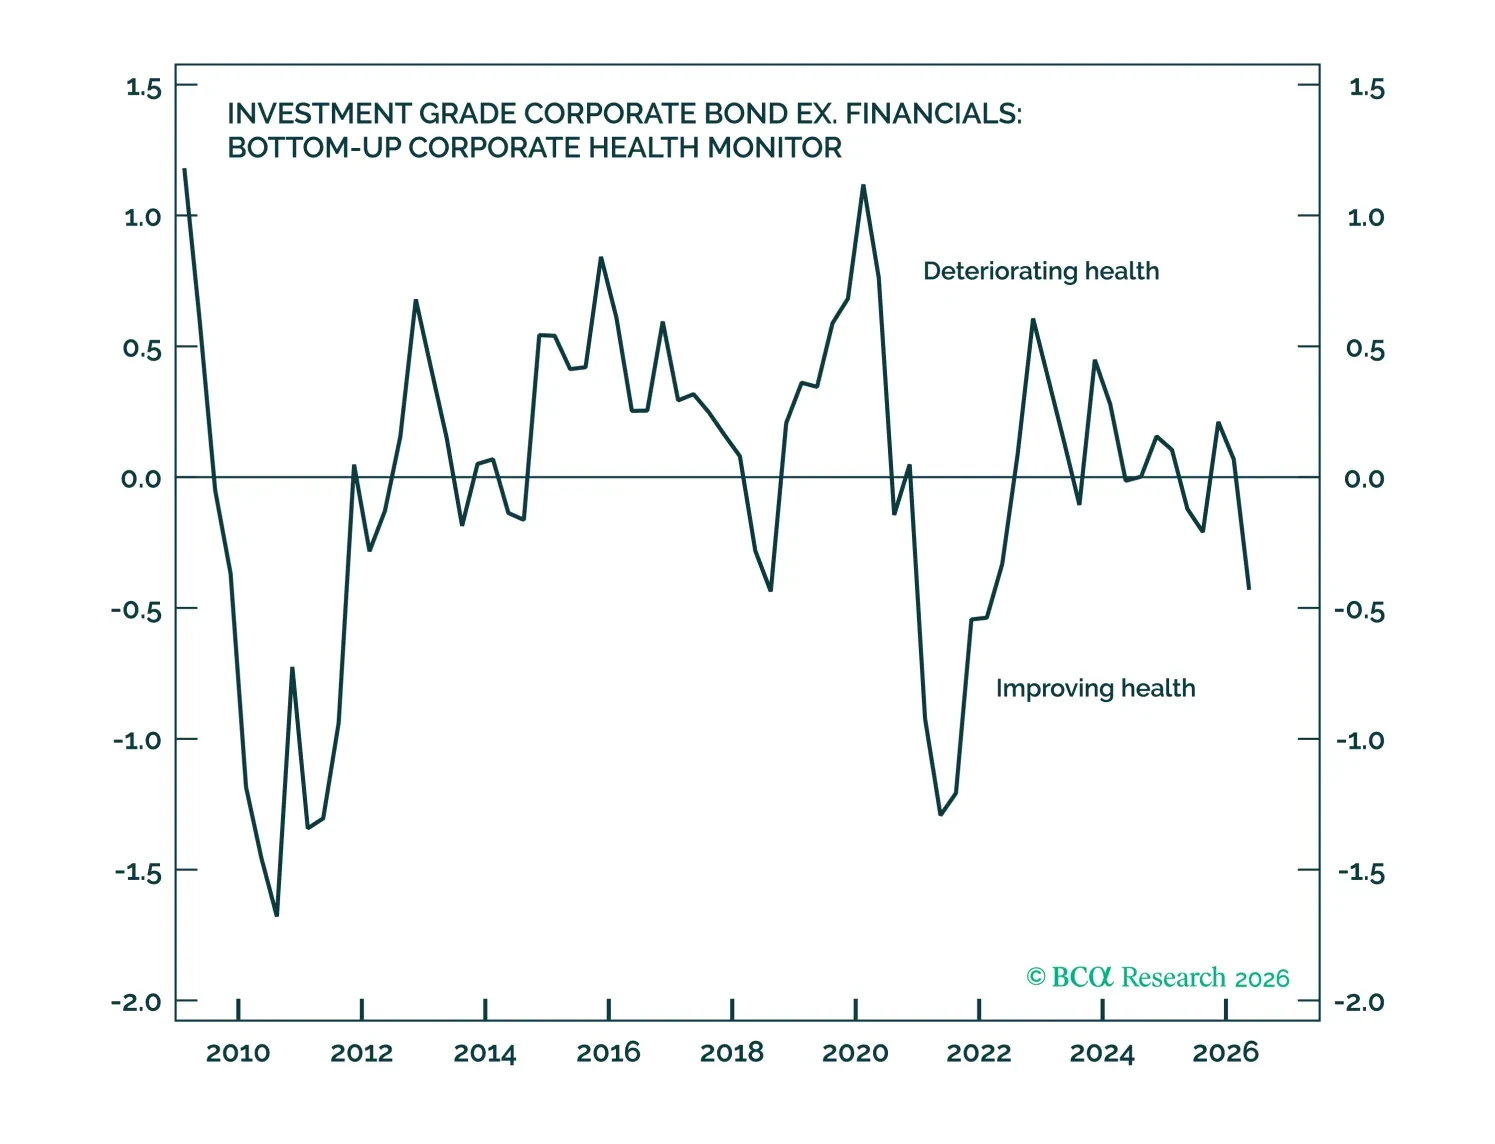
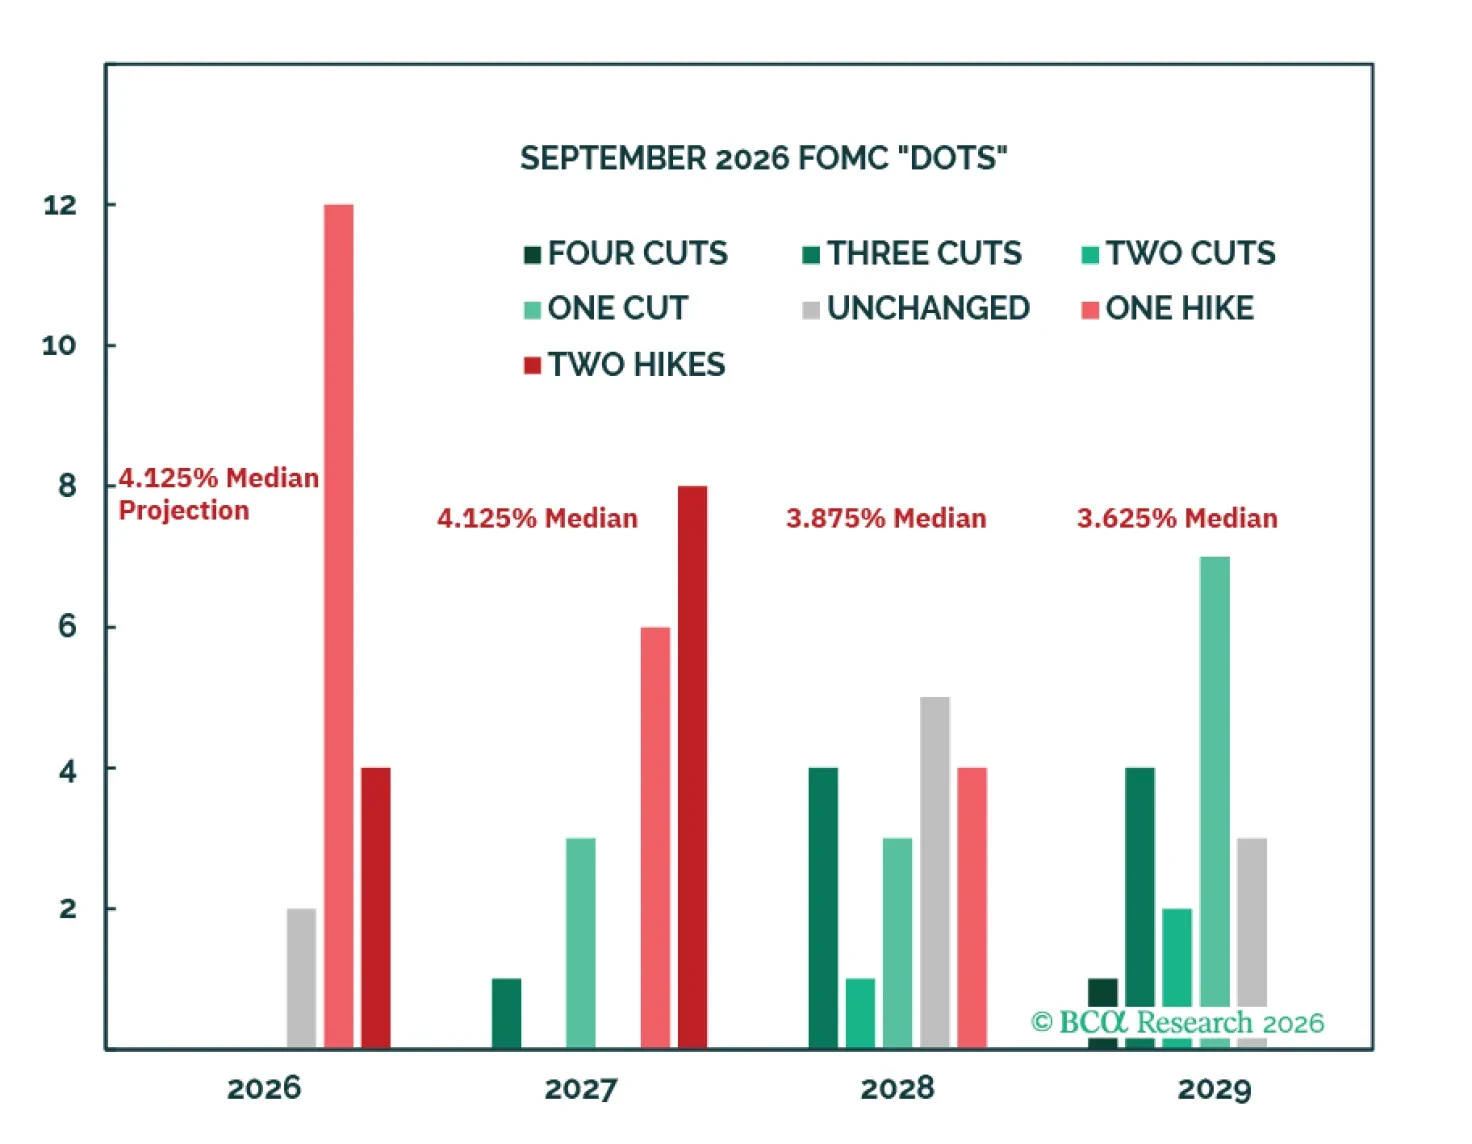
The Fed hiked rates last week, but Fed officials expect this tightening cycle will involve no more than three 25-basis point hikes, contingent on inflation coming down quickly in 2027. We’re inclined to agree.