 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
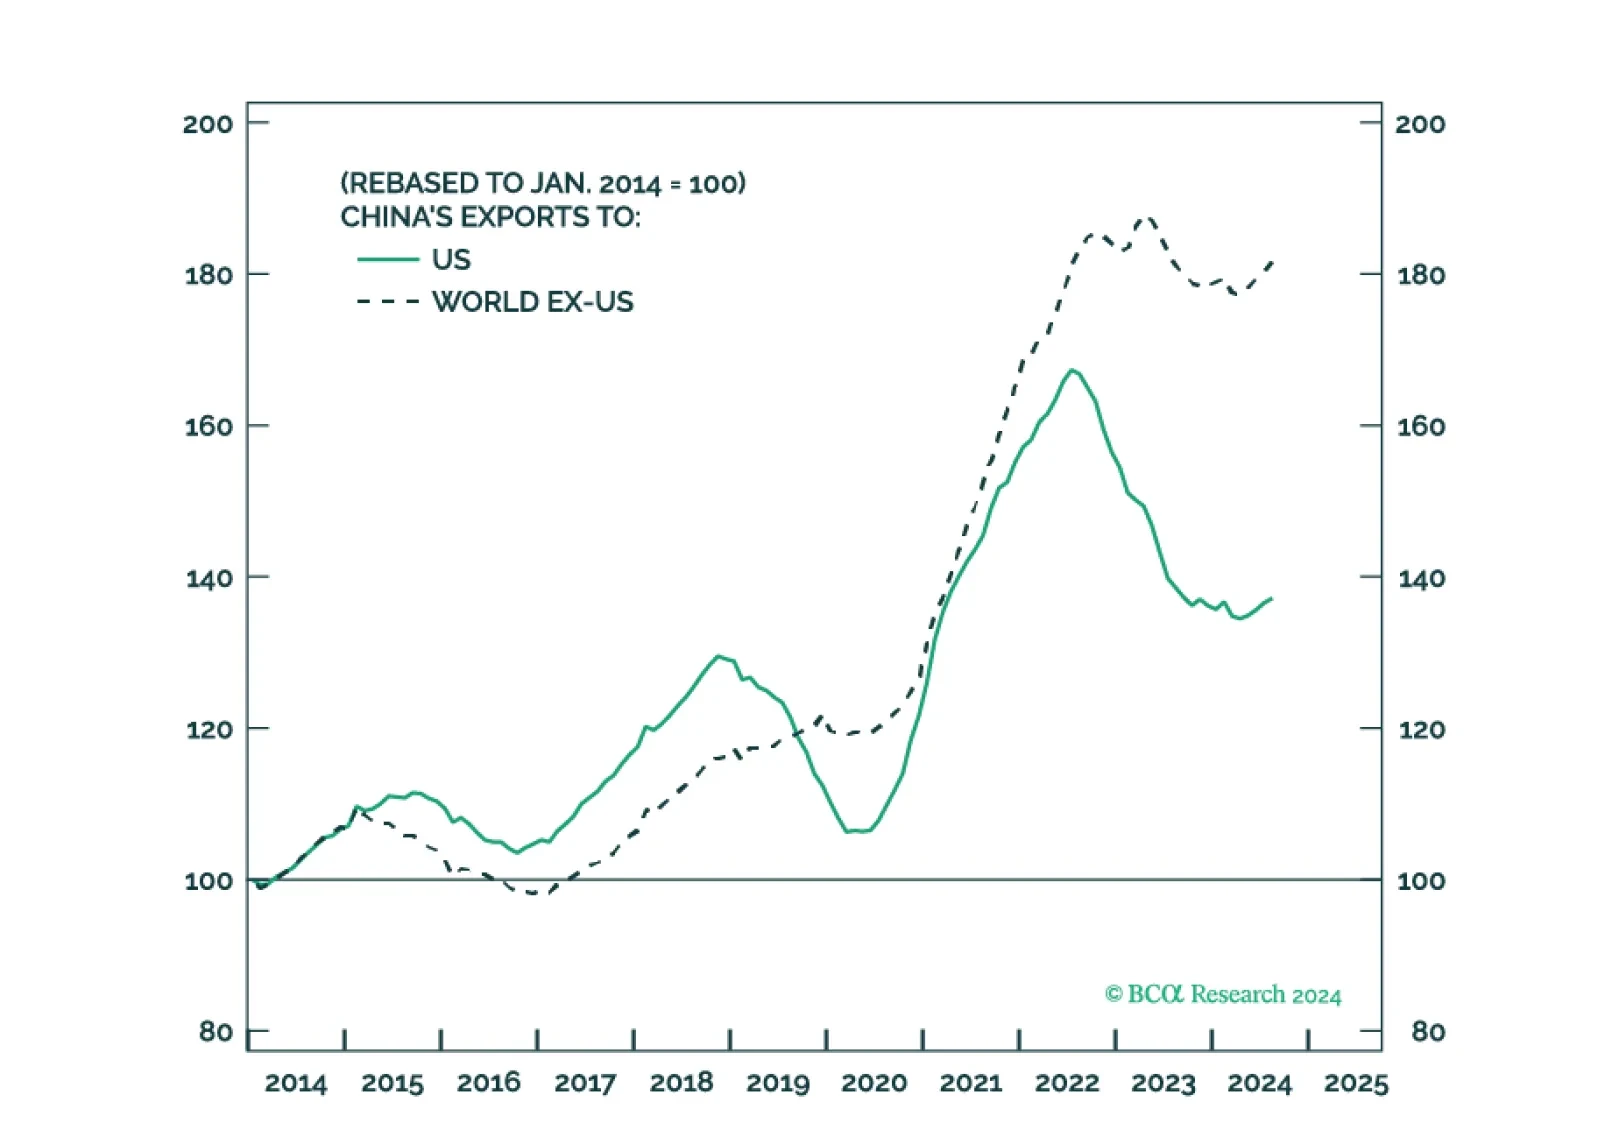
Congress will pass tax cuts by end of 2025 producing a fiscal thrust of about 0.9% of GDP in 2026. Trump will count on that stimulus as a basis for slapping tariffs on leading trade partners. China will retaliate against Trump and stimulate its domestic economy, while pursuing stronger trade ties with other countries. Europe will also retaliate. Geopolitical risk will shift from Ukraine-Russia to Israel-Iran, where the conflict will continue to escalate until a crisis point is reached within 2025.
This month, our Here, There, And Everywhere Chartpack summarizes our main thesis for 2025: the three main narratives driving markets today – fiscal profligacy, trade war, and geopolitical conflict – will peak at some point in 2025.
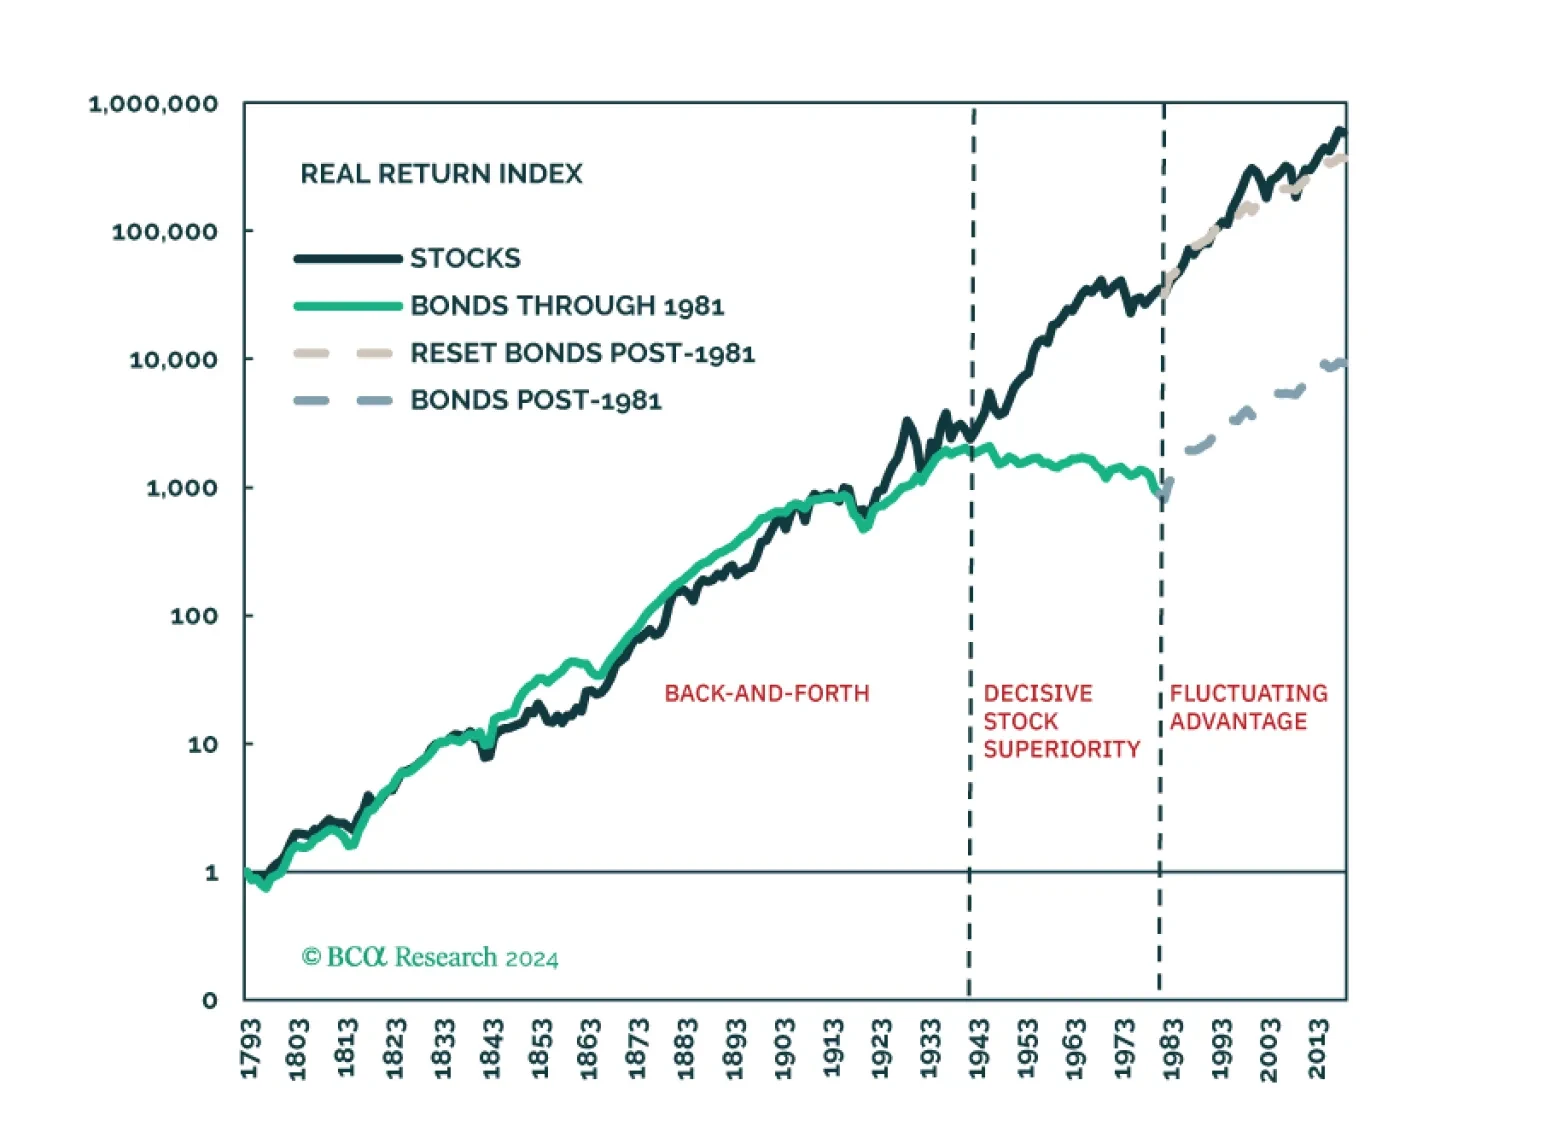
Four years after the pandemic, it feels like there has not been enough self-reflection of that fascinating period in history. One lesson for the world of finance continues to go ignored.
The extraordinary fall of Bashar al-Assad has taken mere days. The Islamist Hayat Tahrir al-Sham (HTS) - made up of the remnants of Al Qaeda (!) - has taken effective control of the country. What are the implications for global investors?
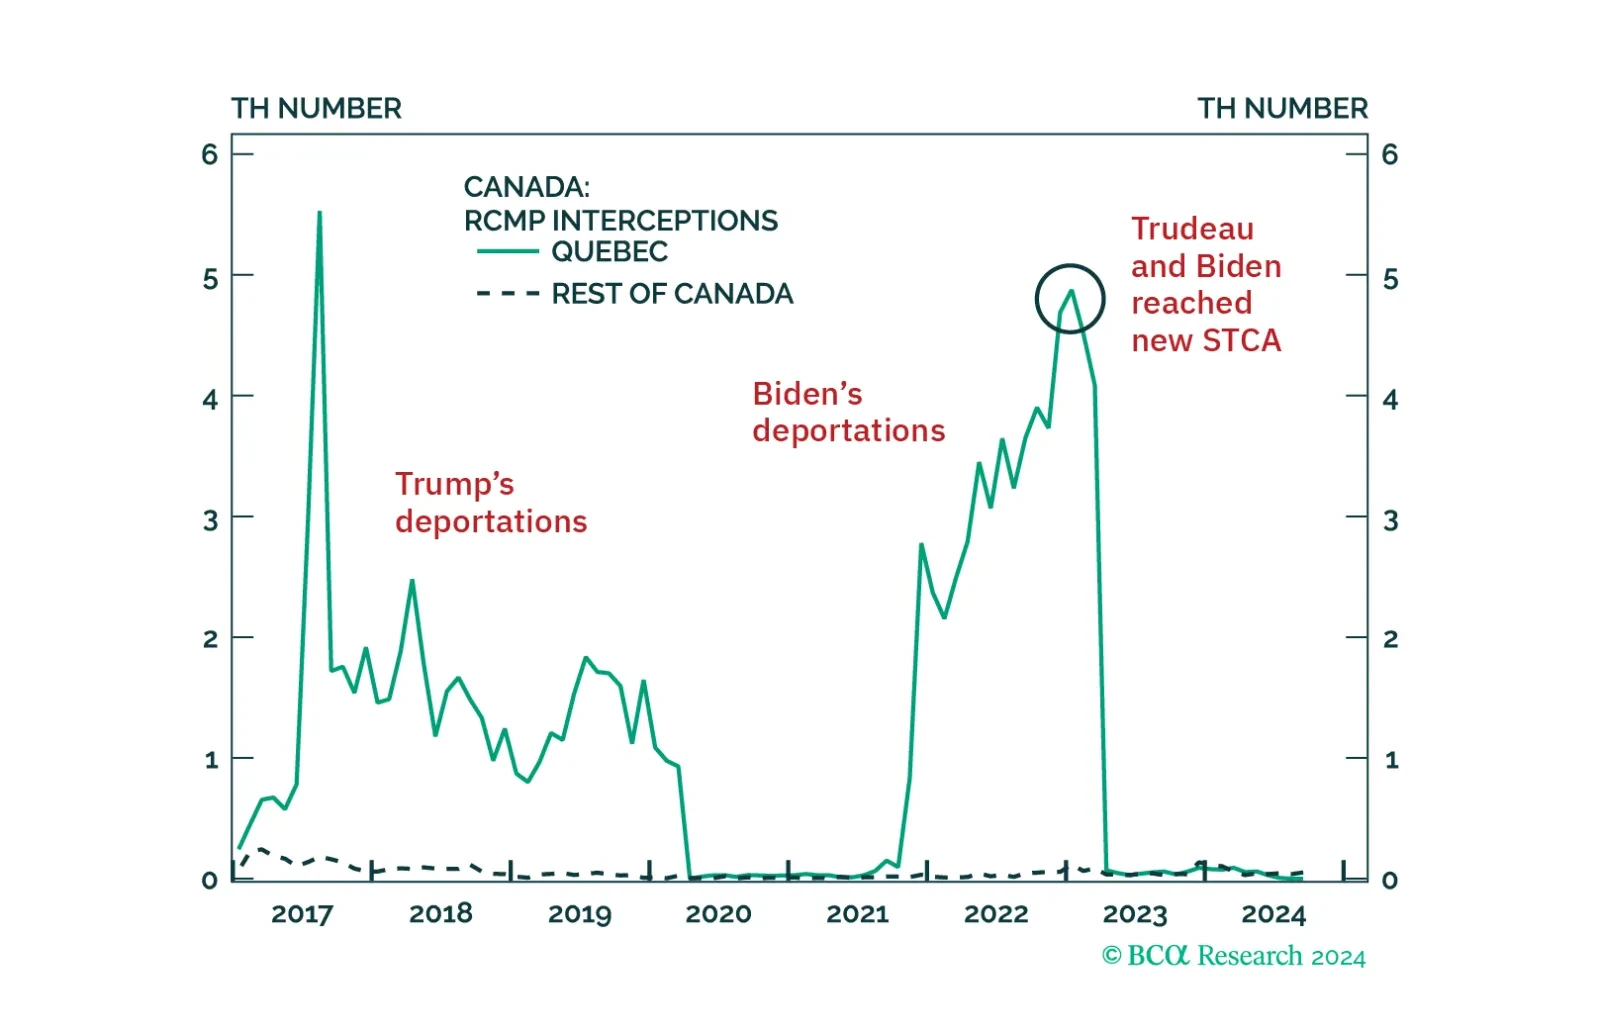
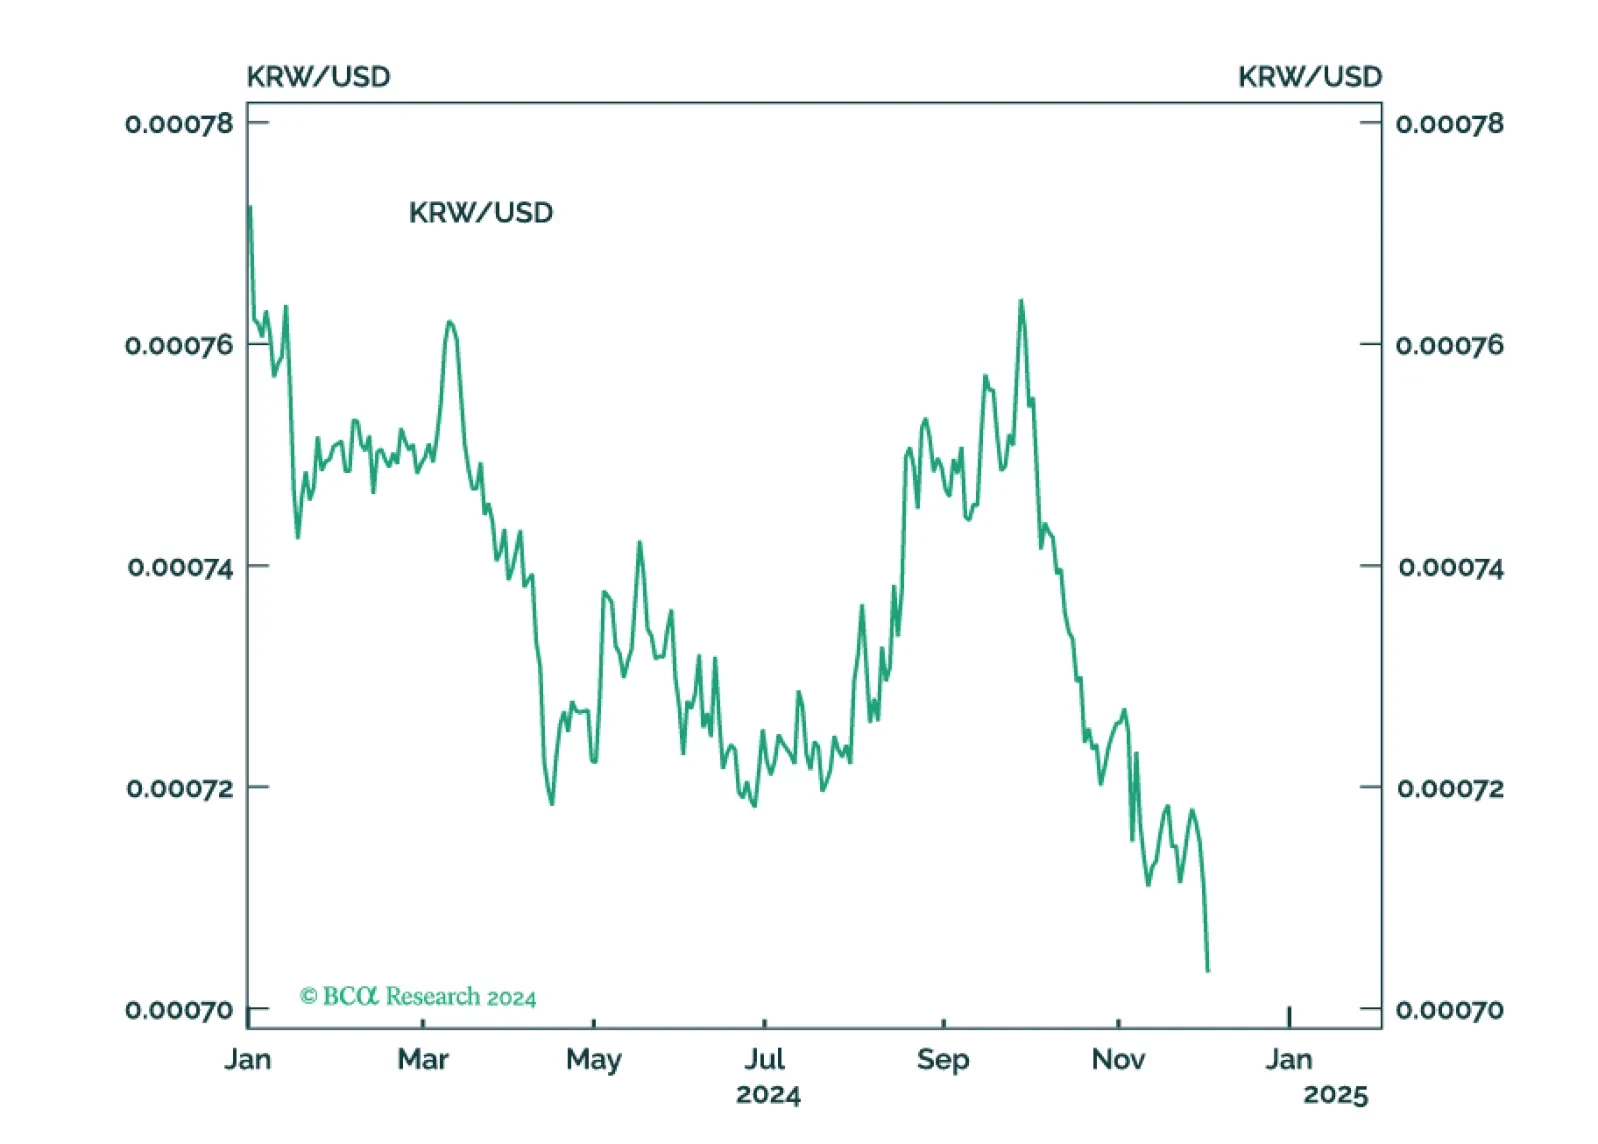
The flurry of global political instability that we expected after the US election is coming to pass. Investors should de-risk in the near term as stocks are flying high but face the turmoil of Biden's last months and then Trump tariffs.
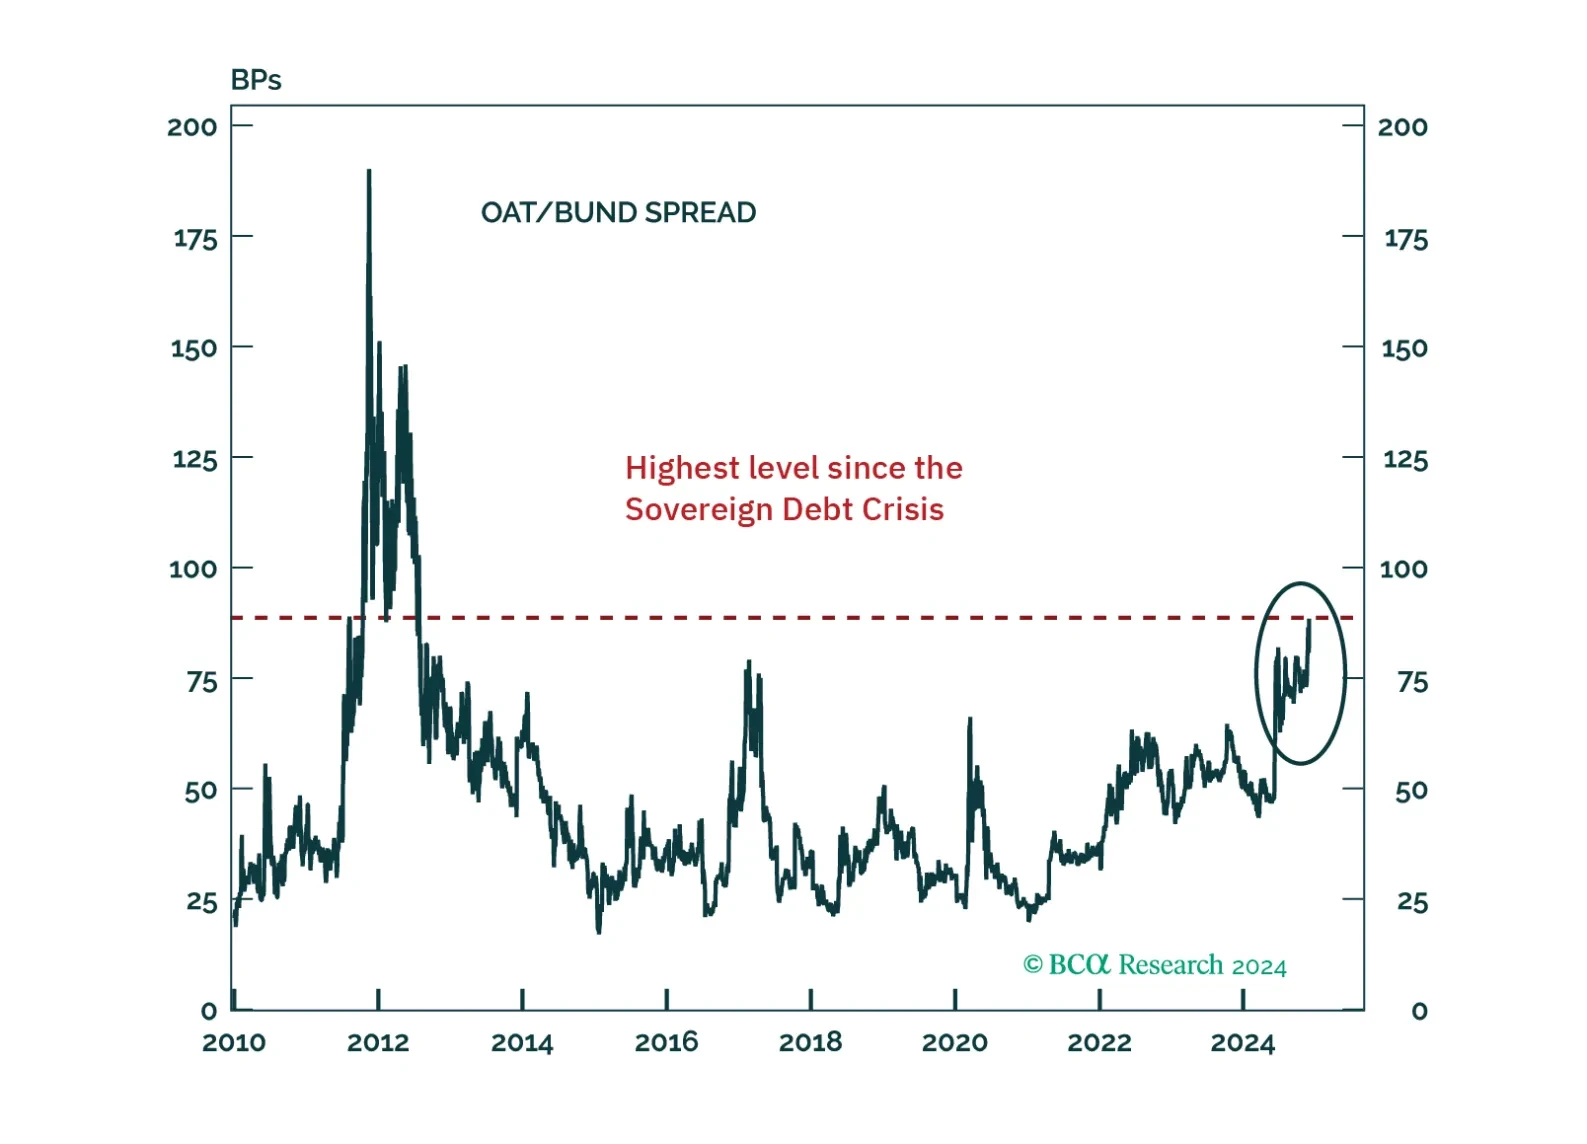
France finds itself in a unique, thorny situation. Can it heave itself out of it? And what does it mean for investors?
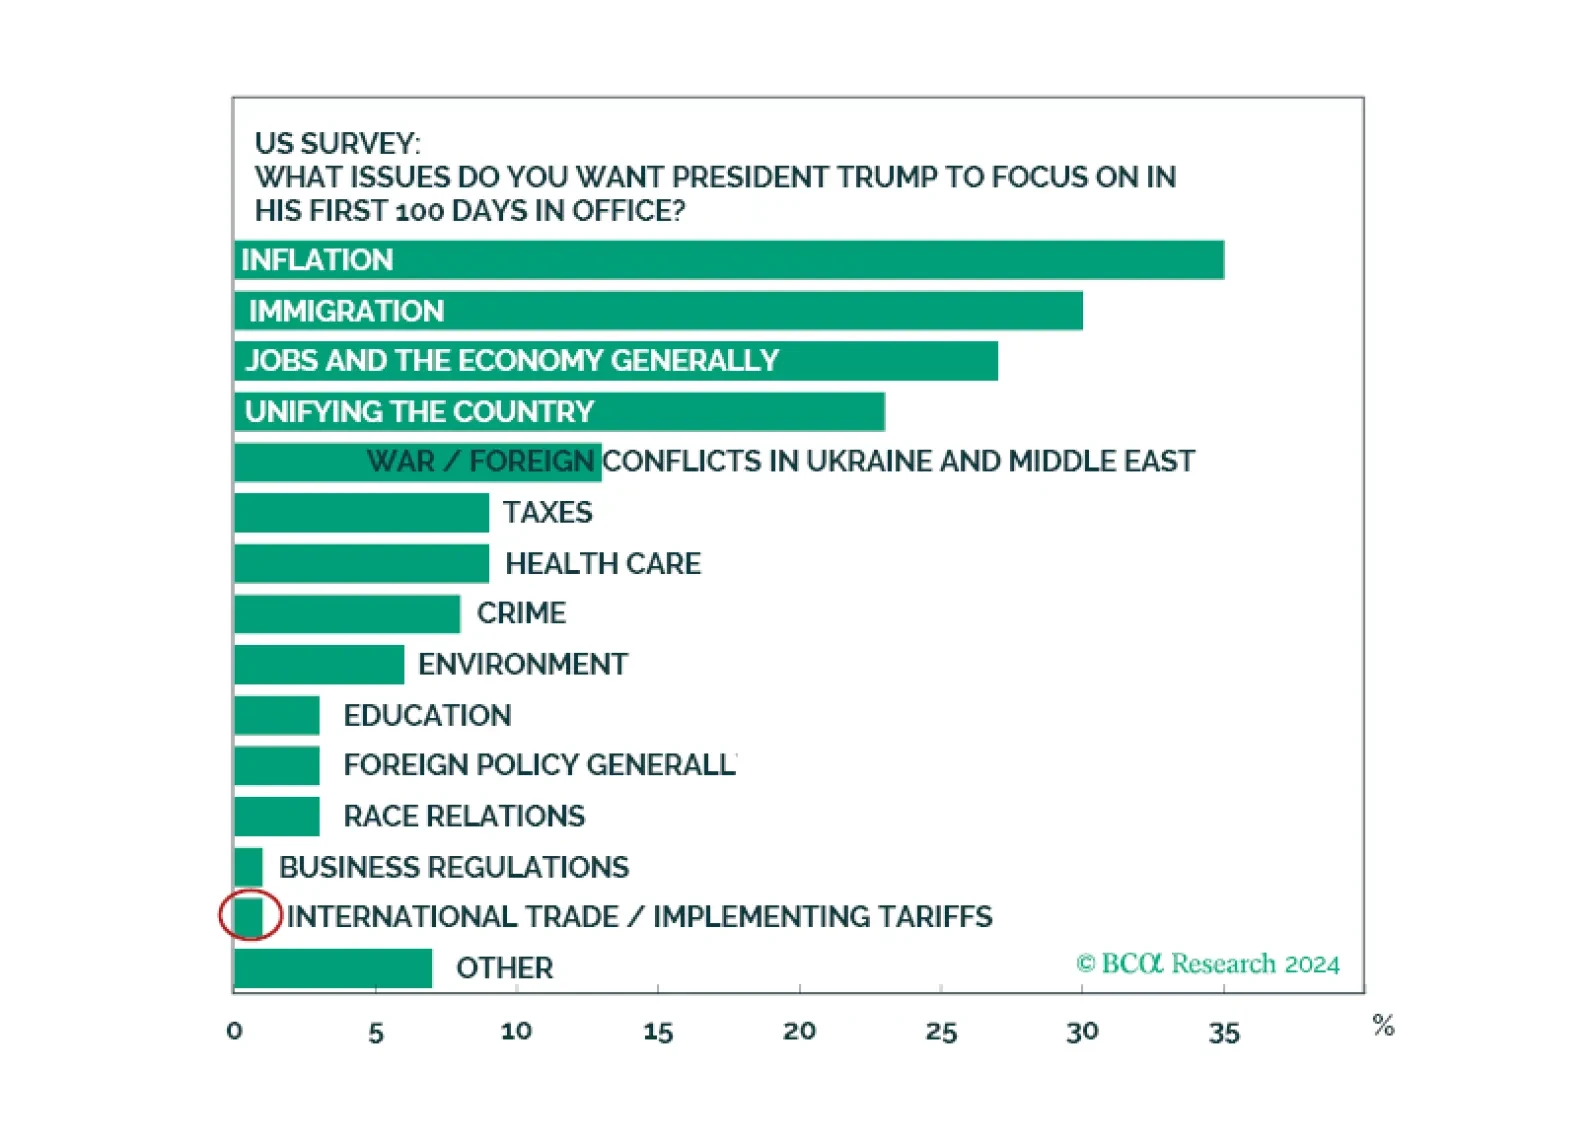
In our Alpha report, we deliver our Annual Forecast. The current macro narrative is that the US will continue to outperform the rest of the world, in large part because President Trump will again deliver fiscally led growth and global tariff carnage. In our view, 2025 will be the year of “Peaks.” Peak fiscal profligacy, peak de-globalization hysteria, and peak geopolitical risks. All three will reverse US Exceptionalism. But getting ahead of that trade is folly. For the time being, we concede that it is “America First” on all fronts. Particularly with the Greenback being a momentum currency.
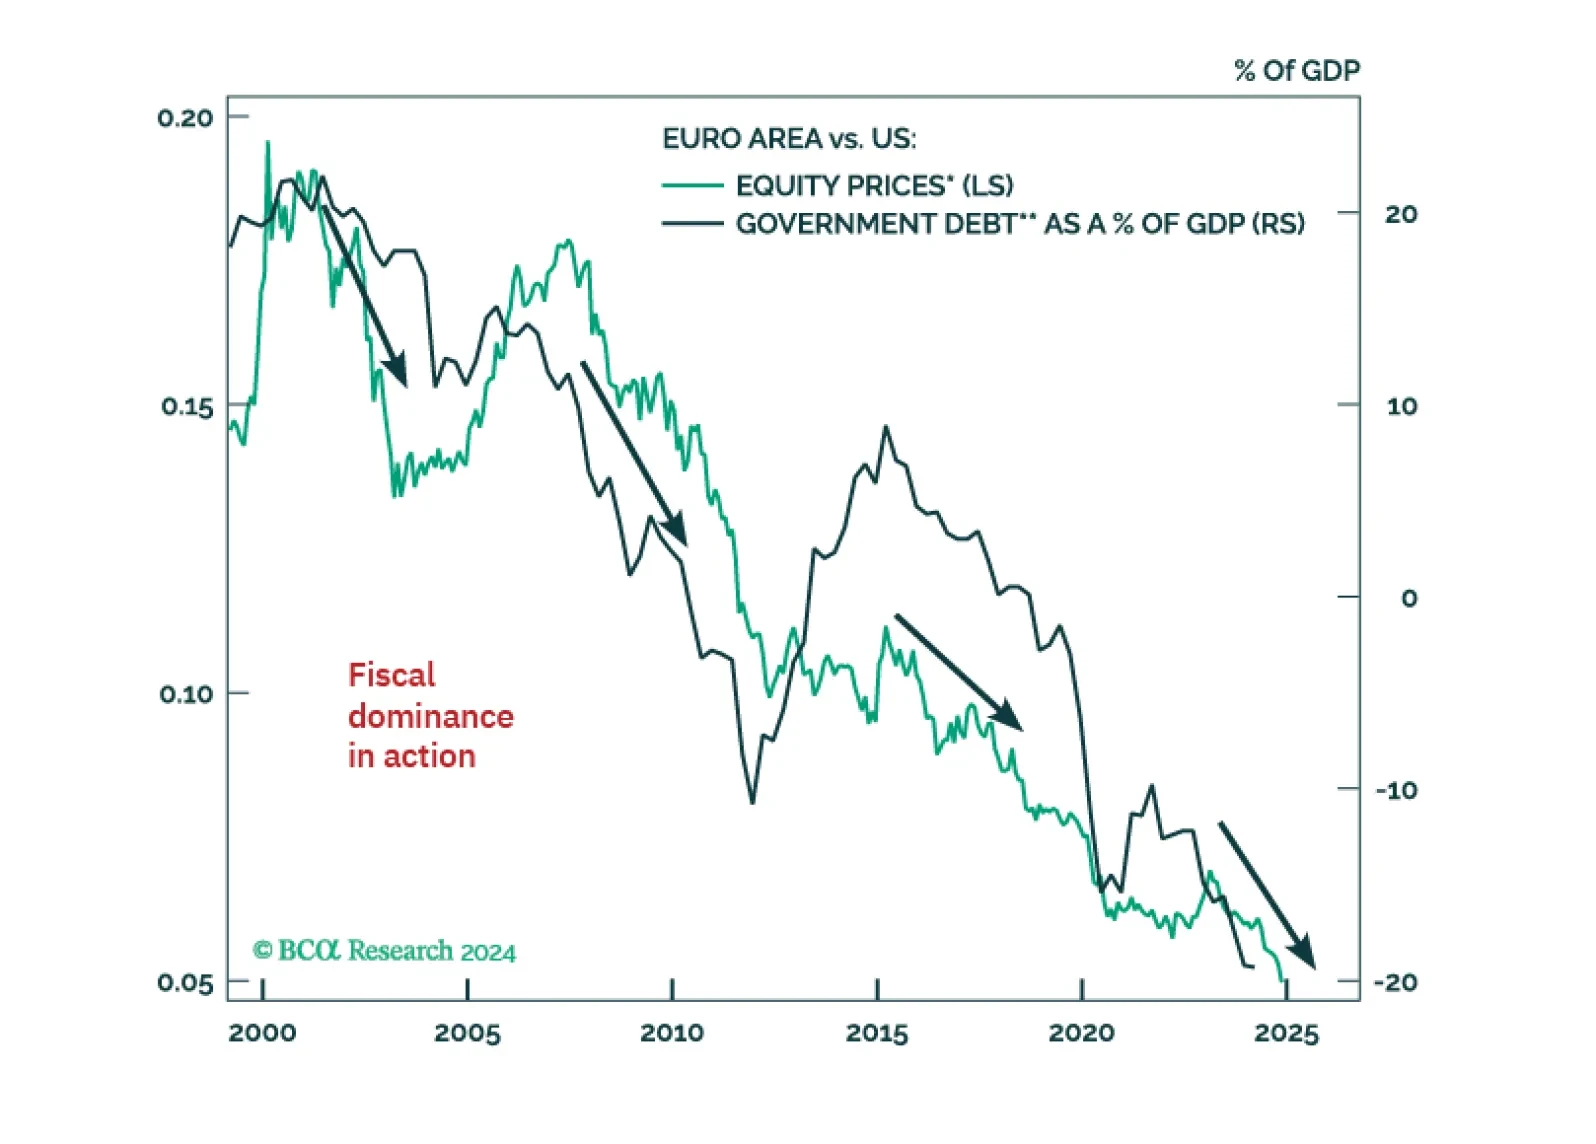
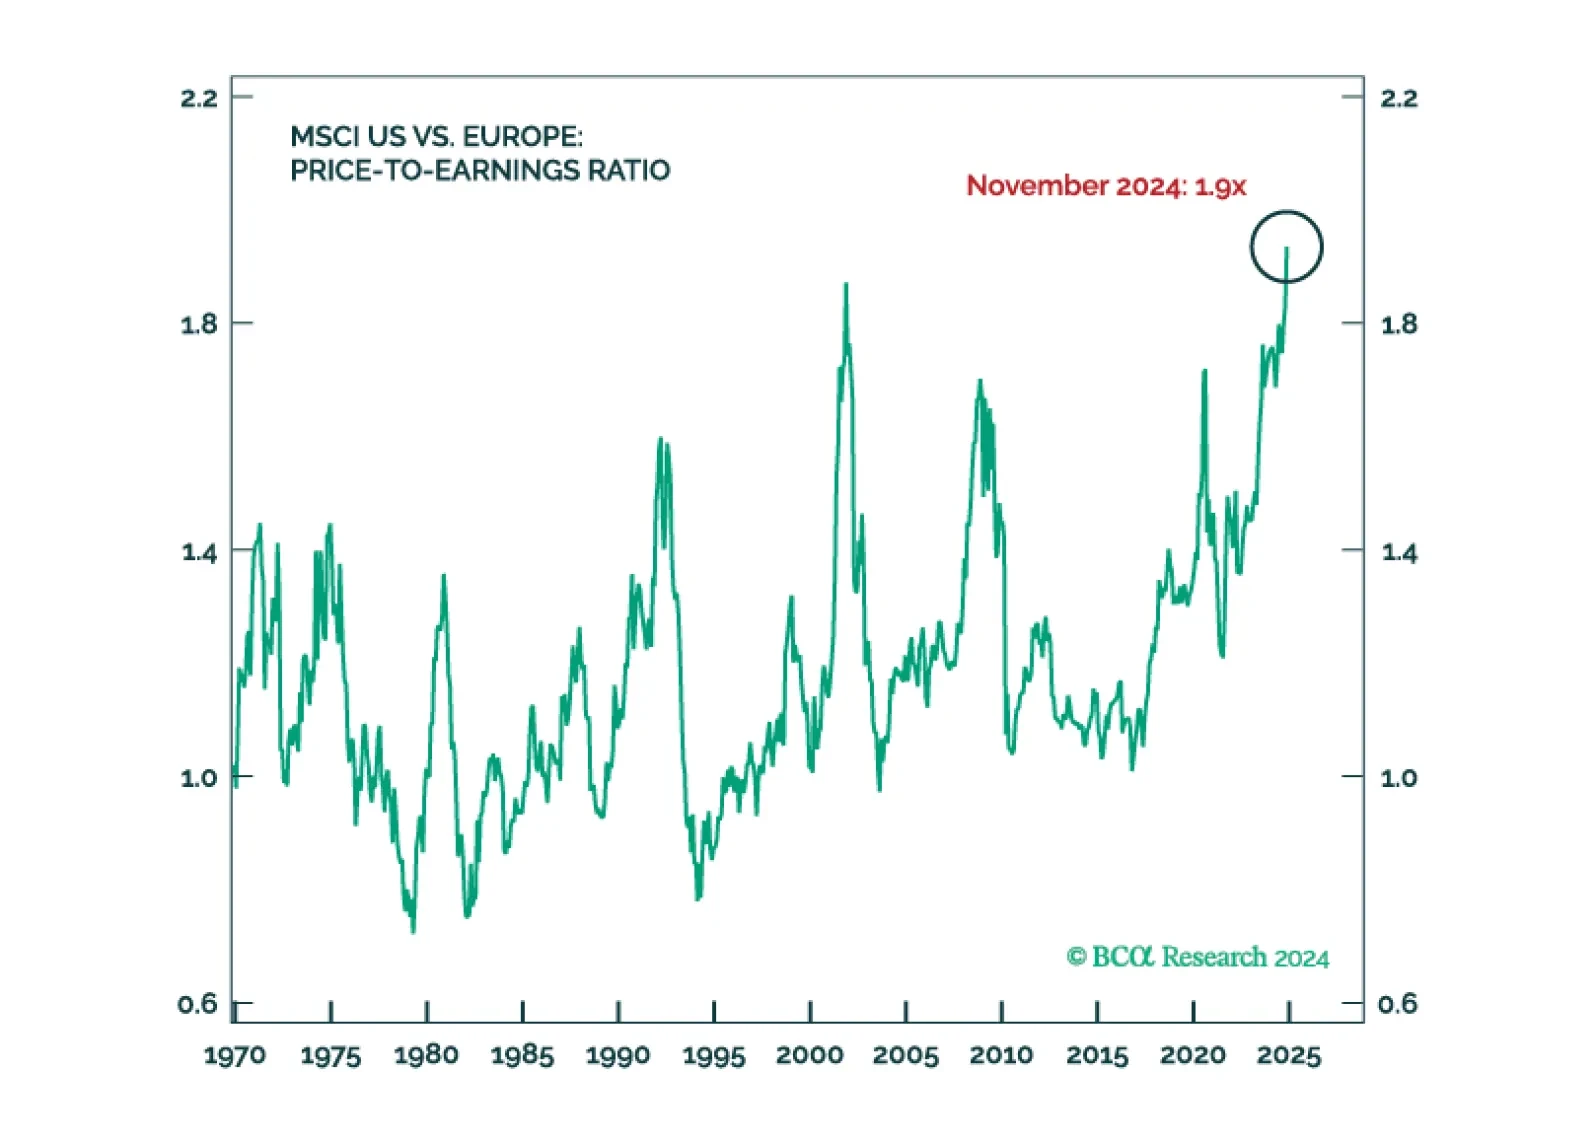
Investors have given up on European assets, which now suffer exceptional discounts to US ones. However, tighter US fiscal policy, the end of Europe’s austerity and deleveraging, the LNG Tsunami about to hit European shores, and the global capex fueled by the Impossible Geopolitical Trinity mean that Europe’s time to shine will soon come back.