Russia
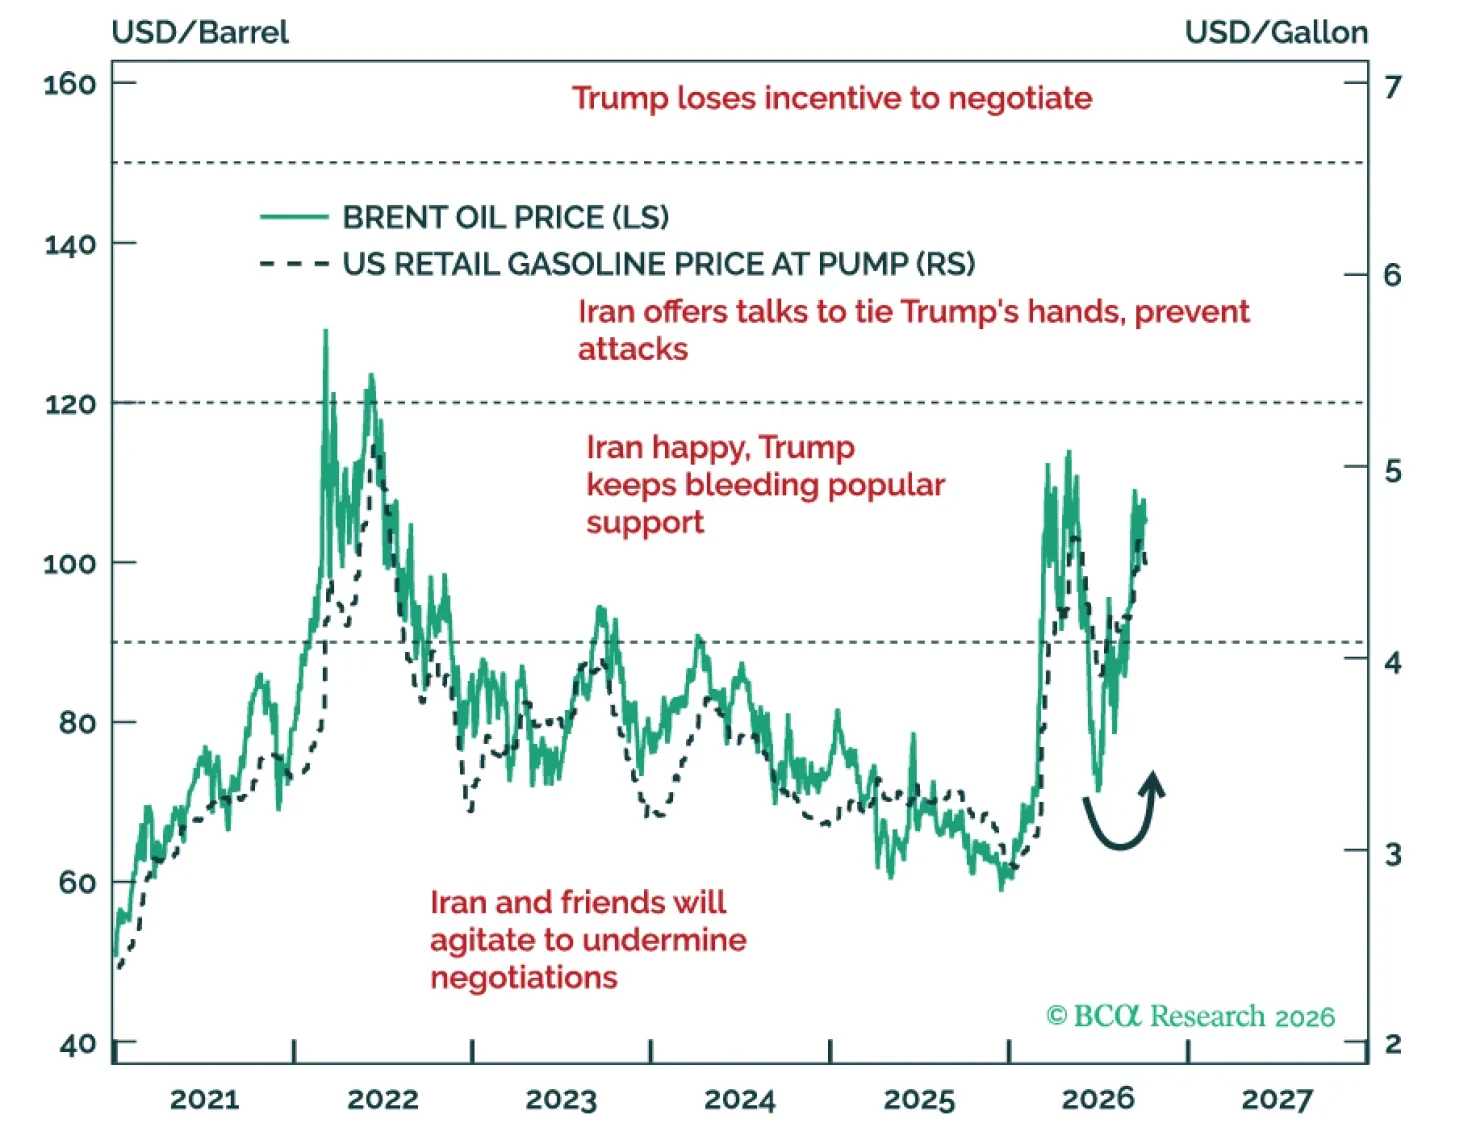
We keep the Global Geopolitical Risk Score at 8 because there are still no ceasefires in Europe or the Middle East. Russia is provoking NATO, which will need to push back. Iran, emboldened by the lack of definitive US success, pushes its luck, which could invite a destructive response from the US. The Chinese economy remains fragile, increasing the likelihood of foreign belligerence. After the US midterm, President Trump faces fewer political constraints, allowing him to pursue a maximalist foreign policy to cement his legacy during his lame-duck period.
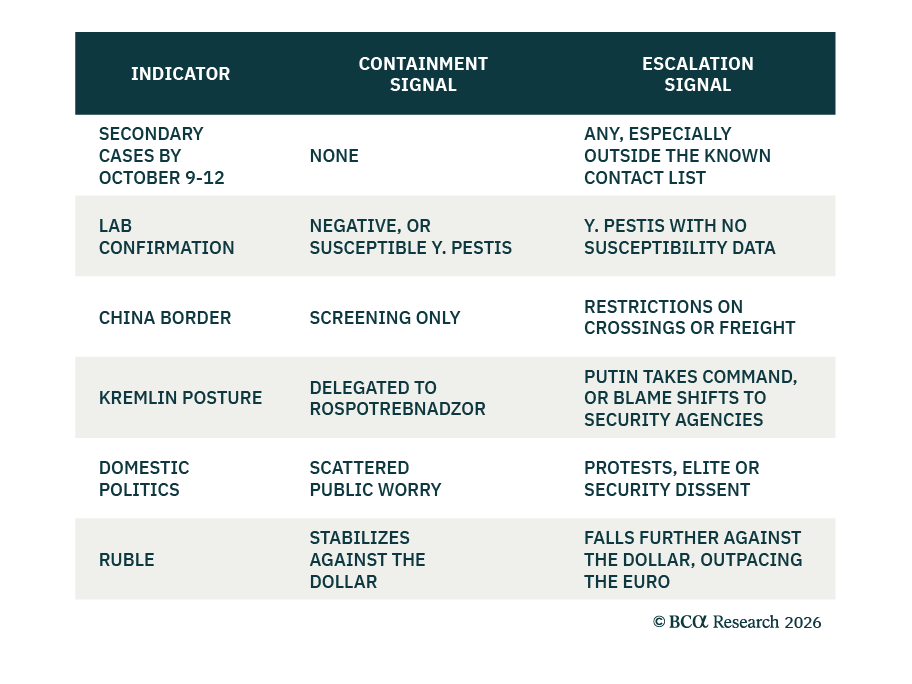
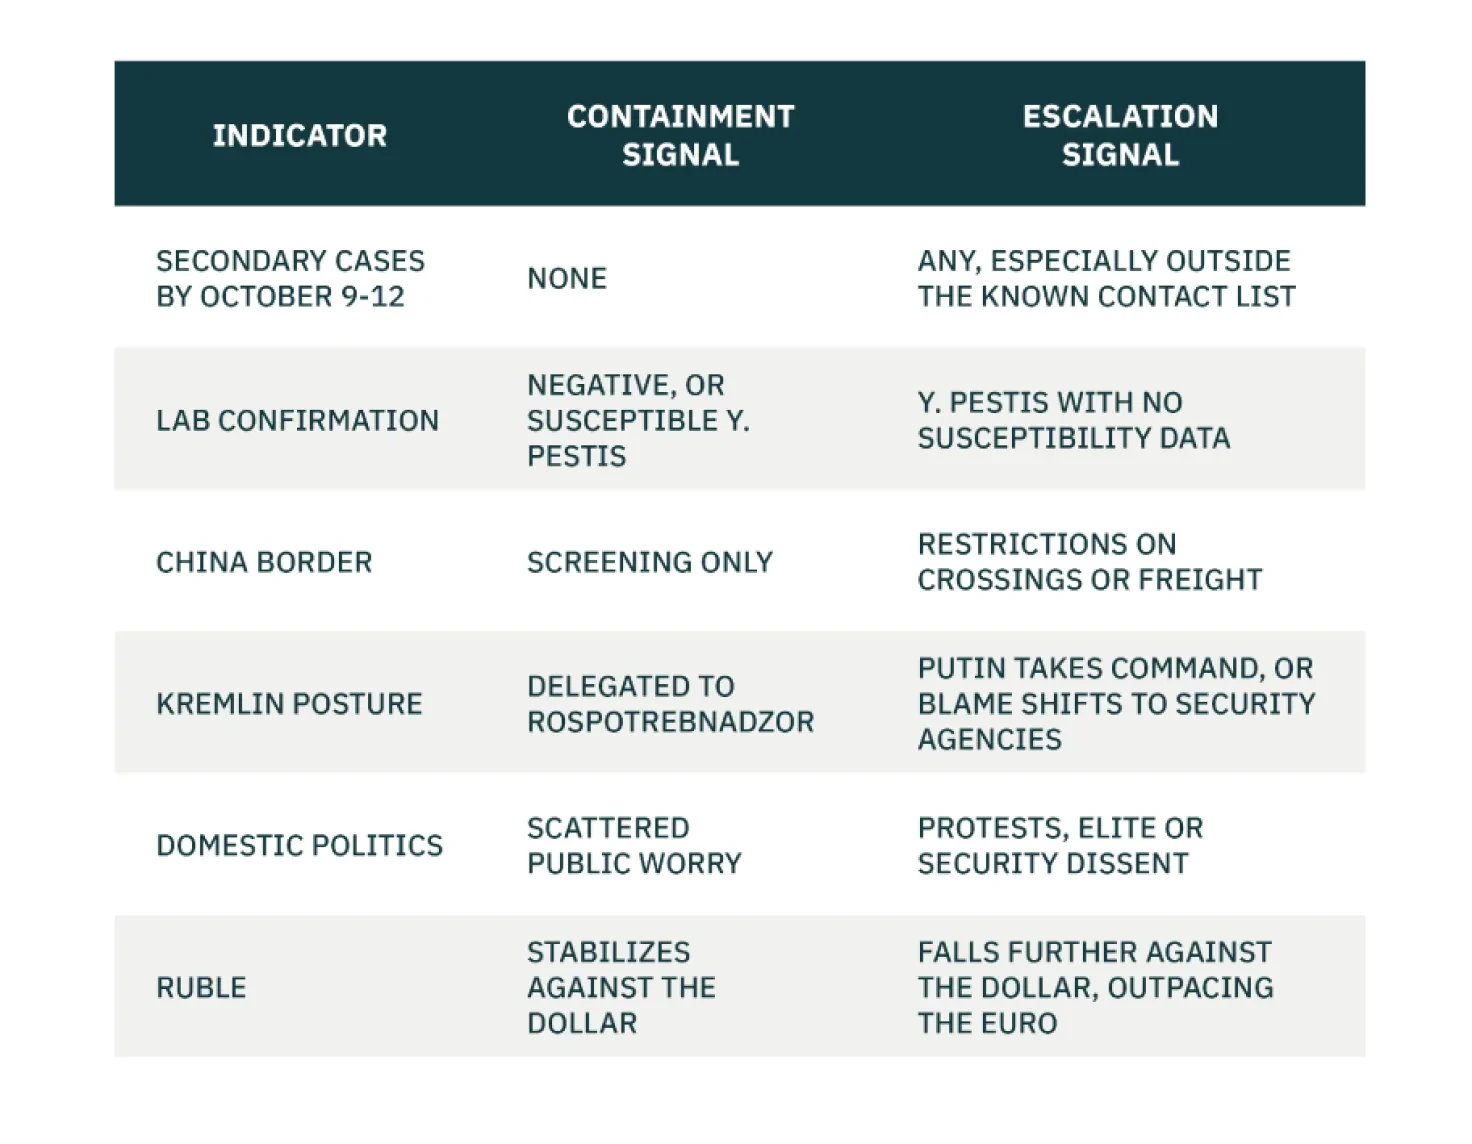
The Irkutsk plague scare is not yet a crisis, but if it becomes one, Russia is a bad place for it to happen.
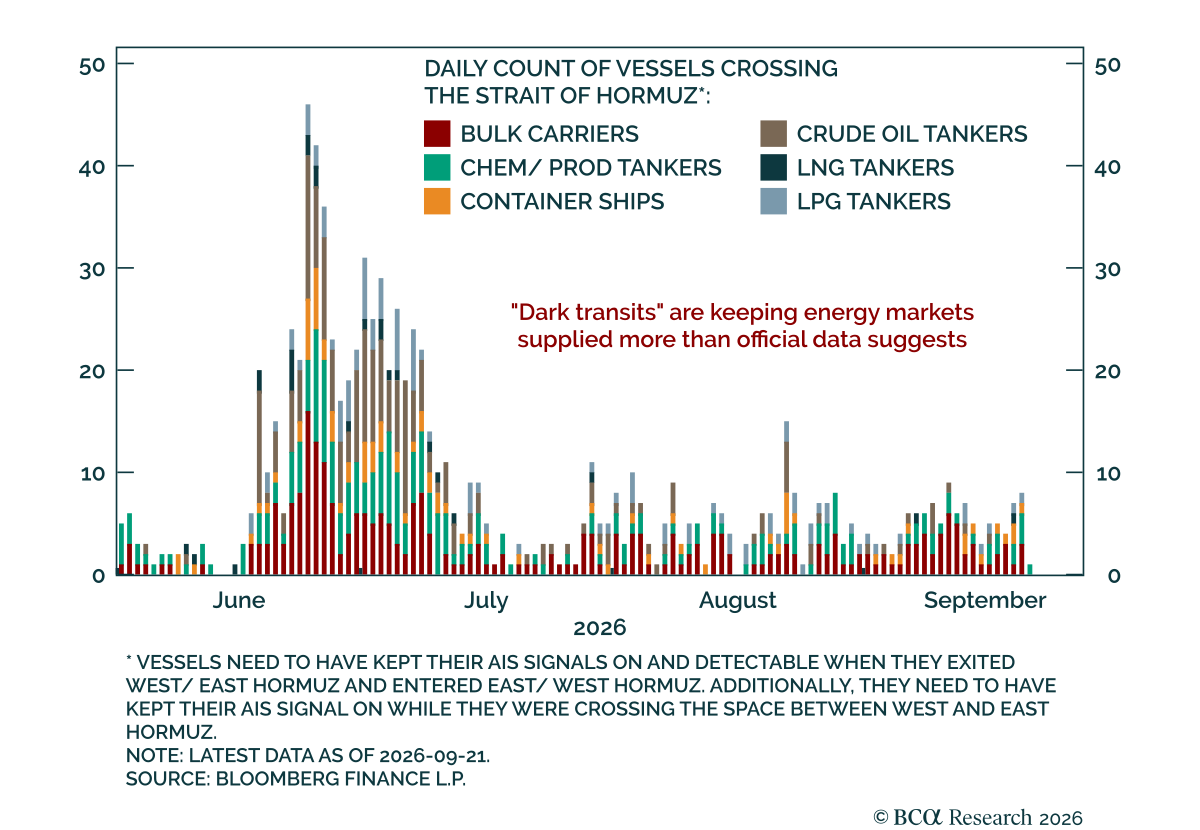
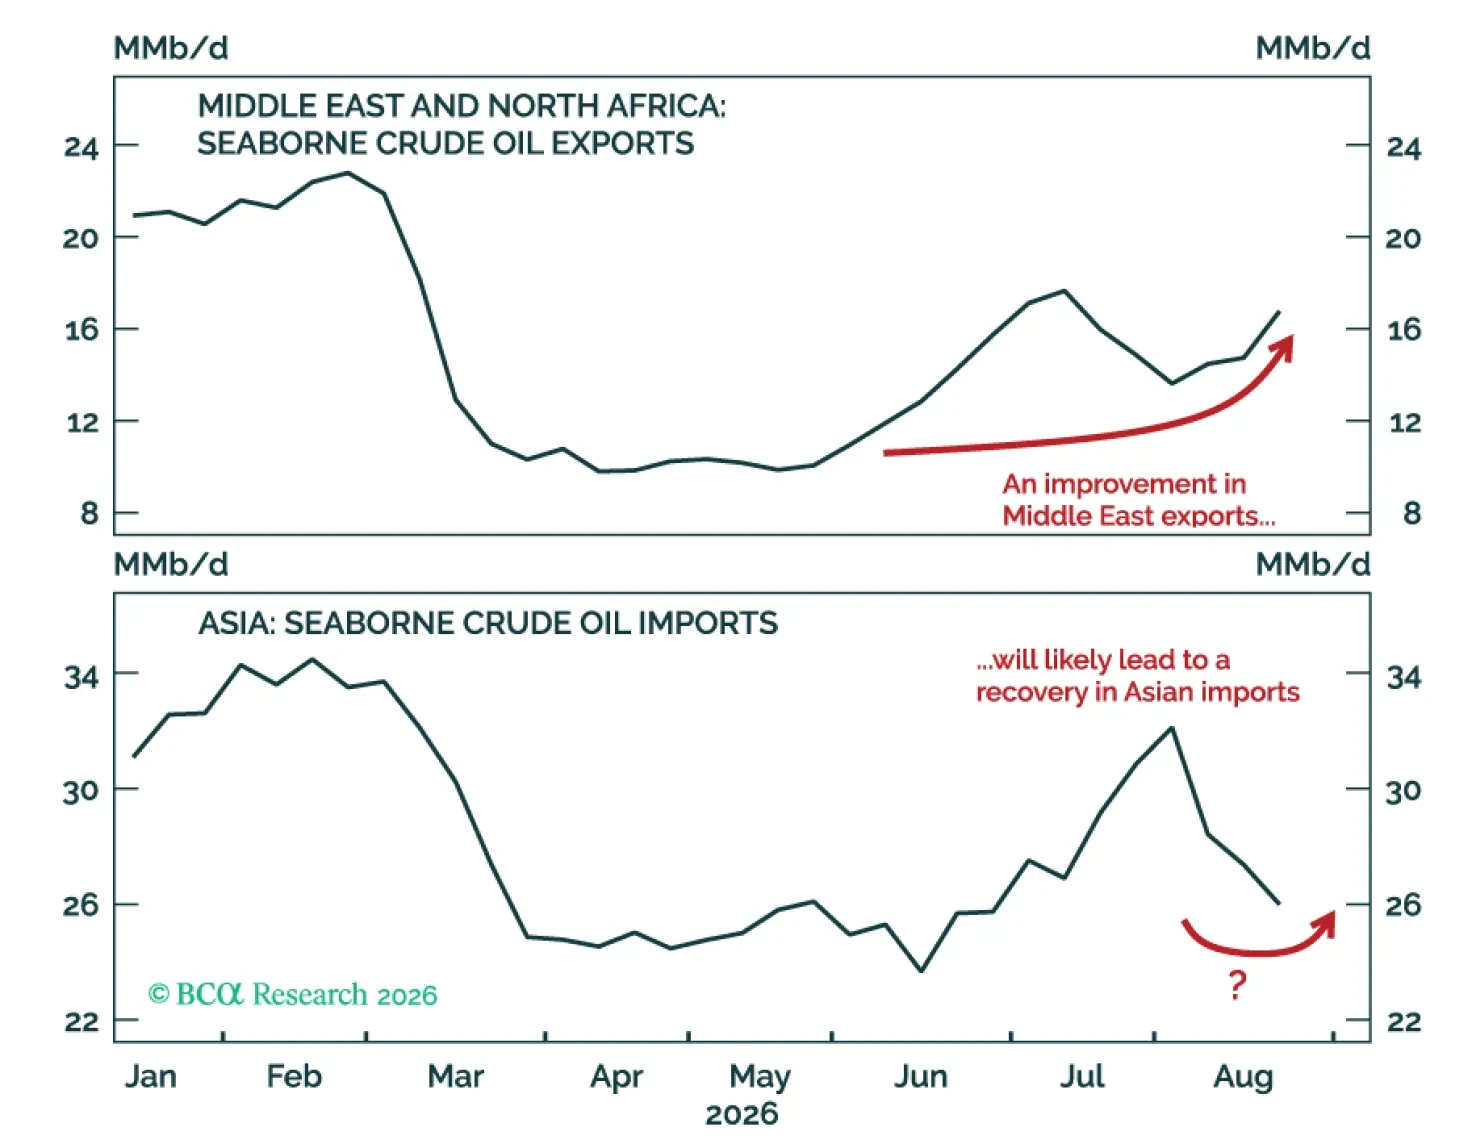
The wide crack spread reflects a bifurcated oil market. The severity of the crude oil disruption has recently softened, while the US-Iran and Ukraine-Russia conflicts have created a perfect storm for refined product markets. Going forward, even though conditions are not yet in place for the crack spread to return to its pre-conflict level, it is likely to narrow over the coming months.
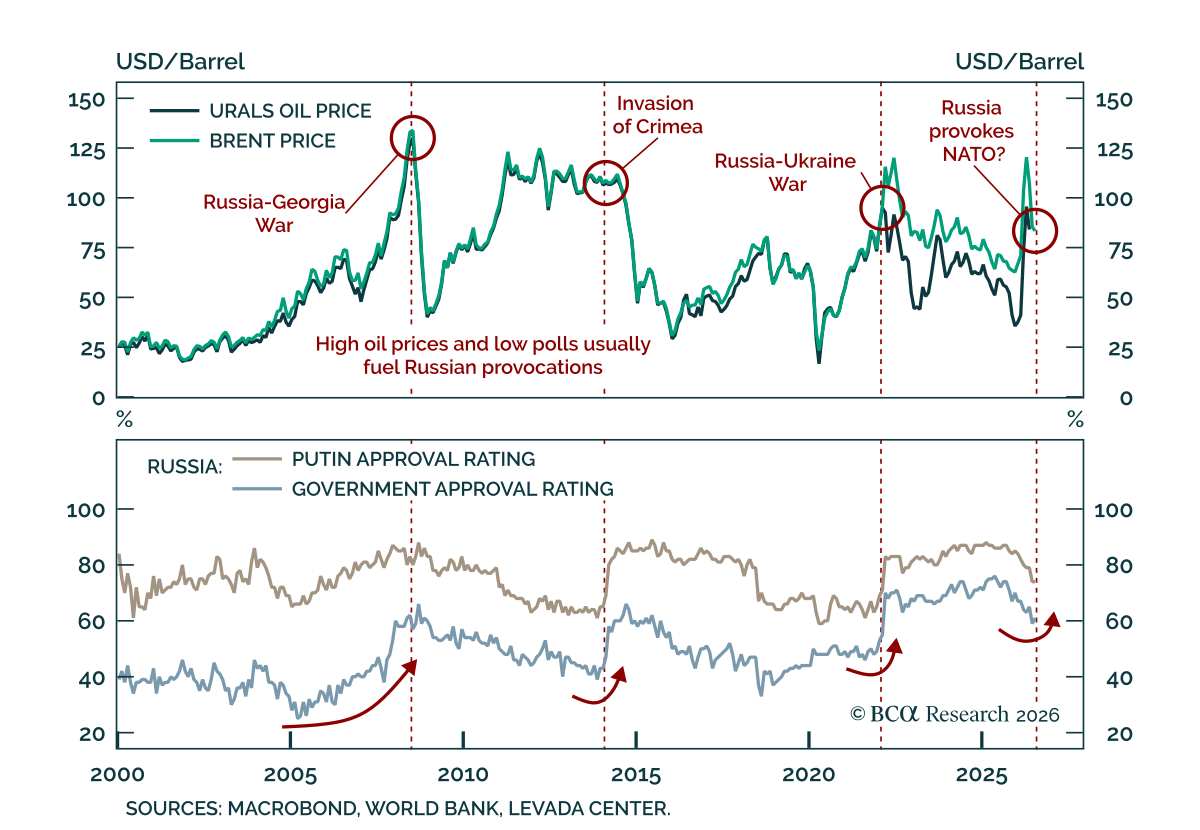
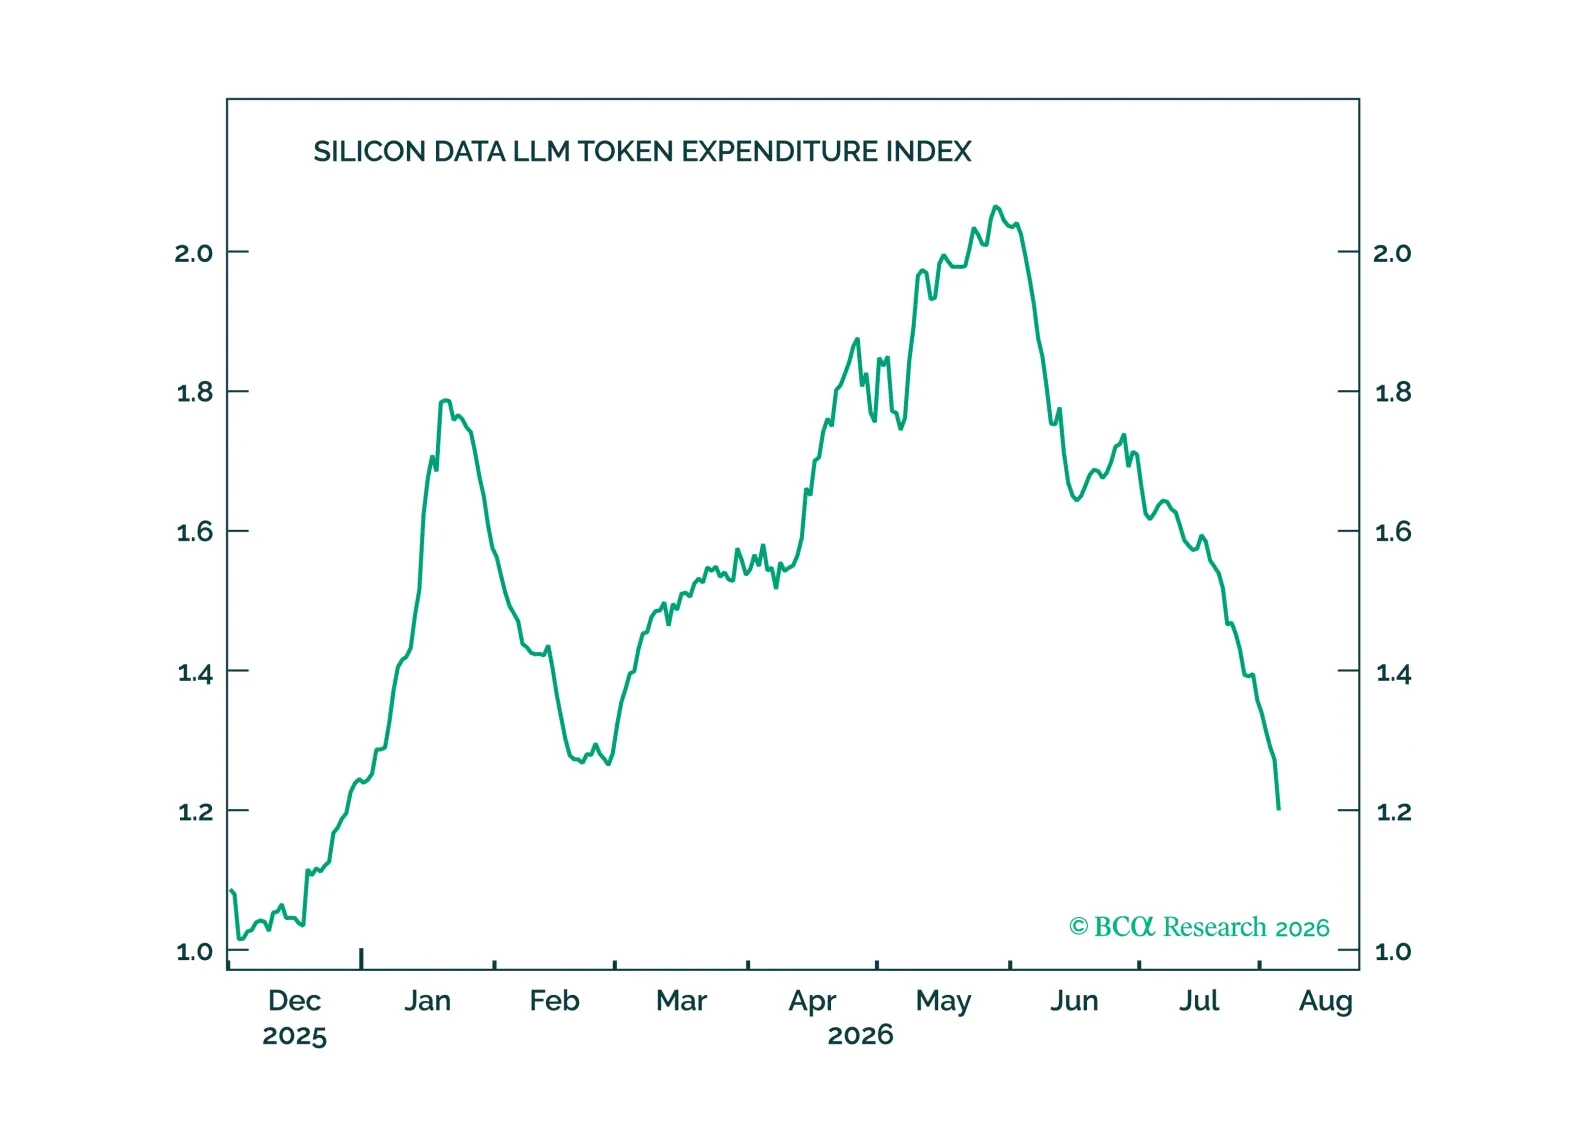
We remain tactically bullish due to the combination of geopolitical risks in the Middle East easing and the ramping up of the AI boom. In this month’s chartpack, we articulate the reasoning behind both sanguine views.
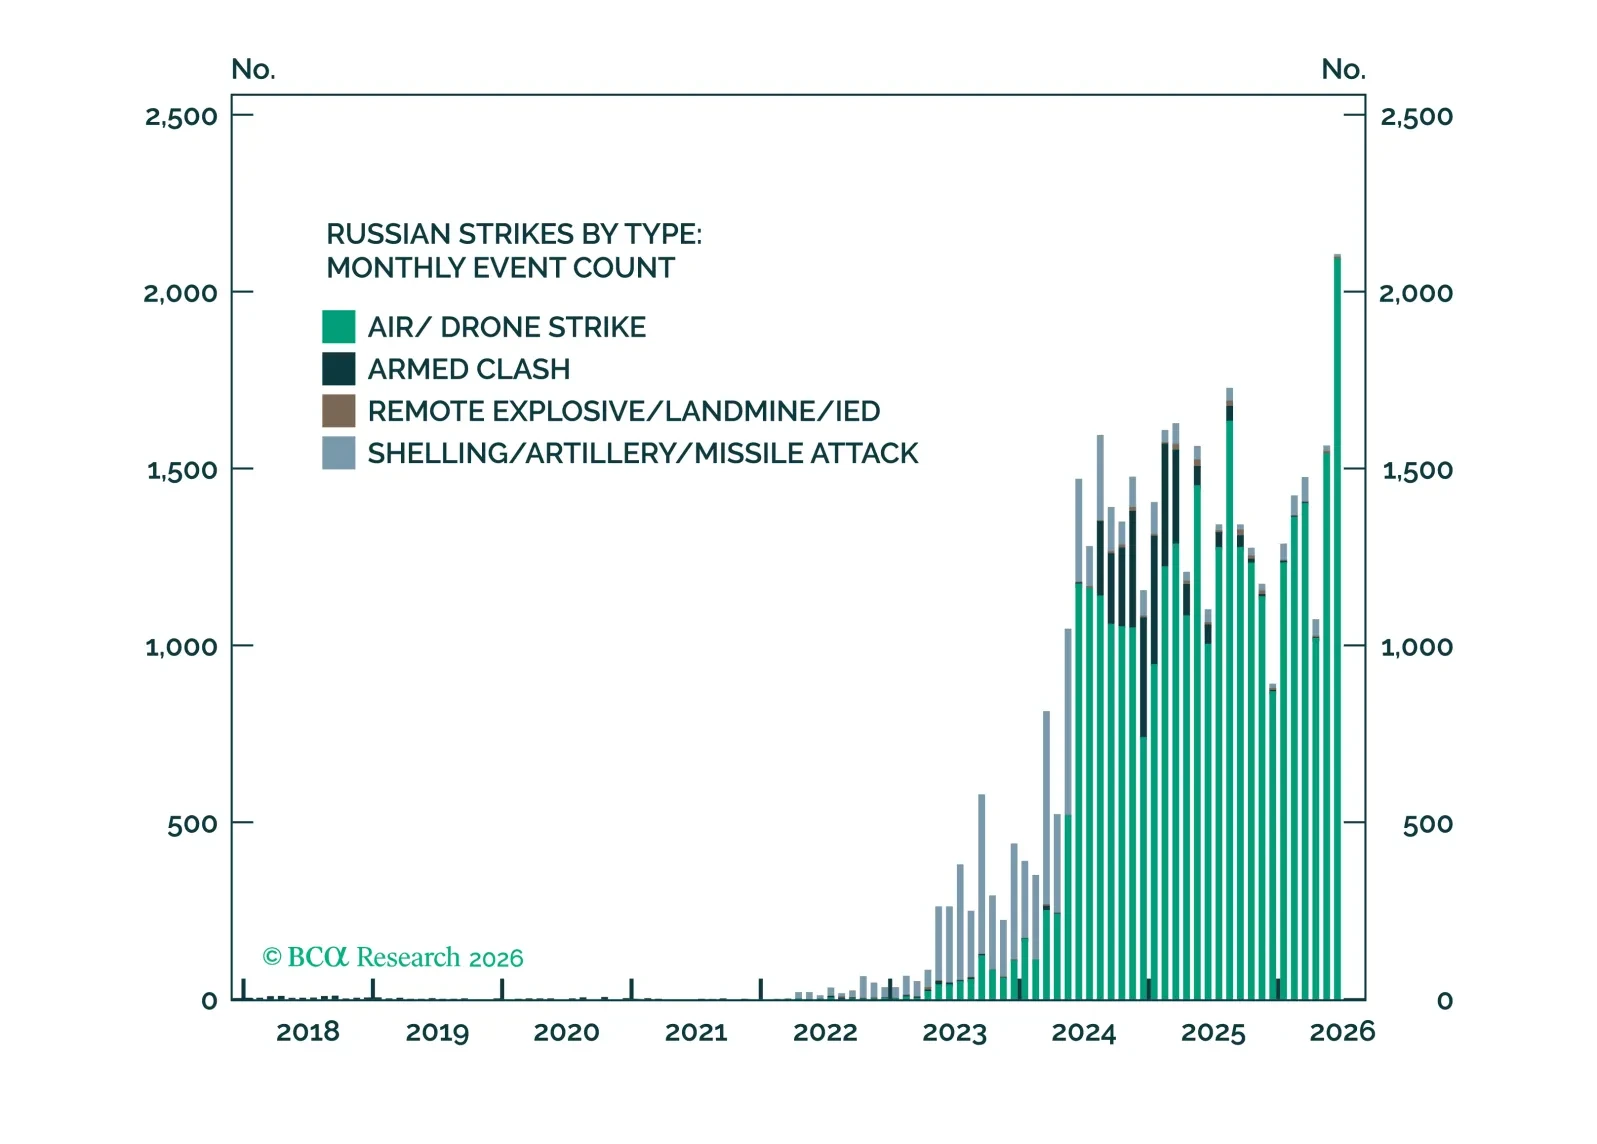
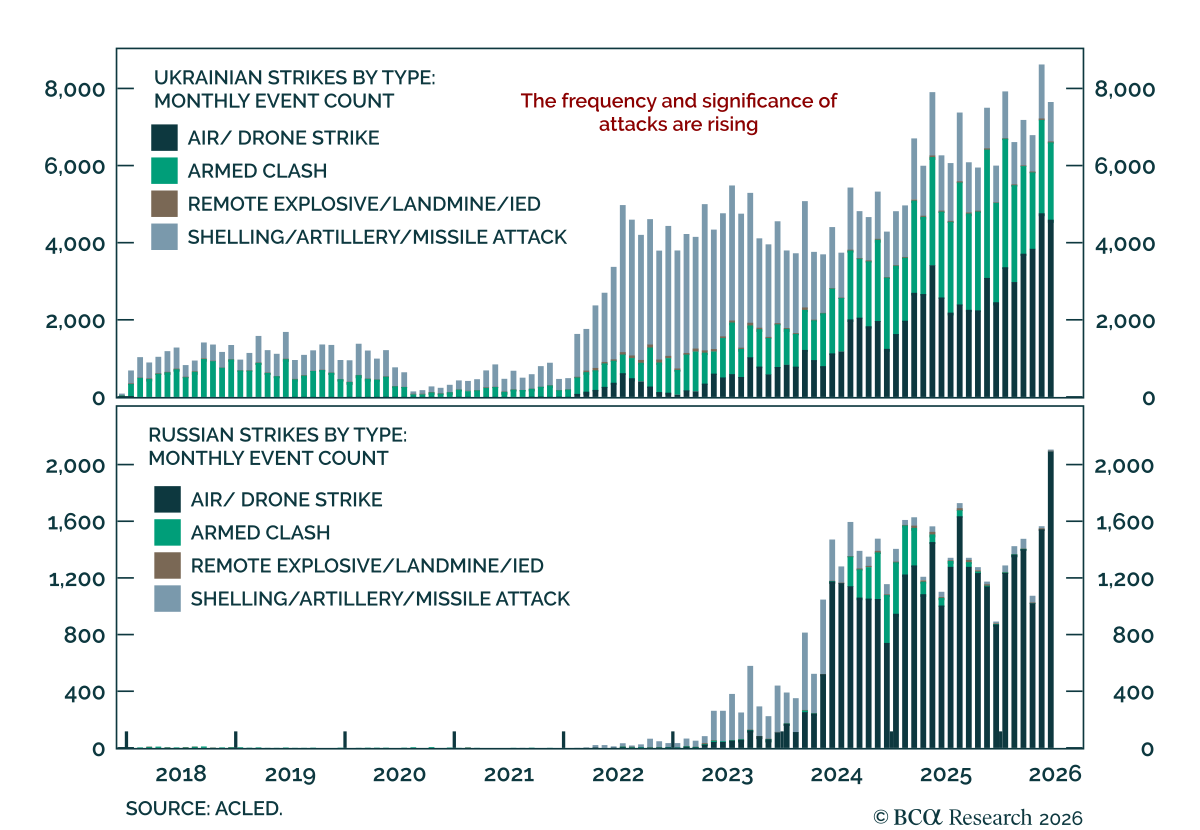
The fragile balance in the Ukraine war has broken – the conflict can escalate and take investors who are focused on Iran by surprise.
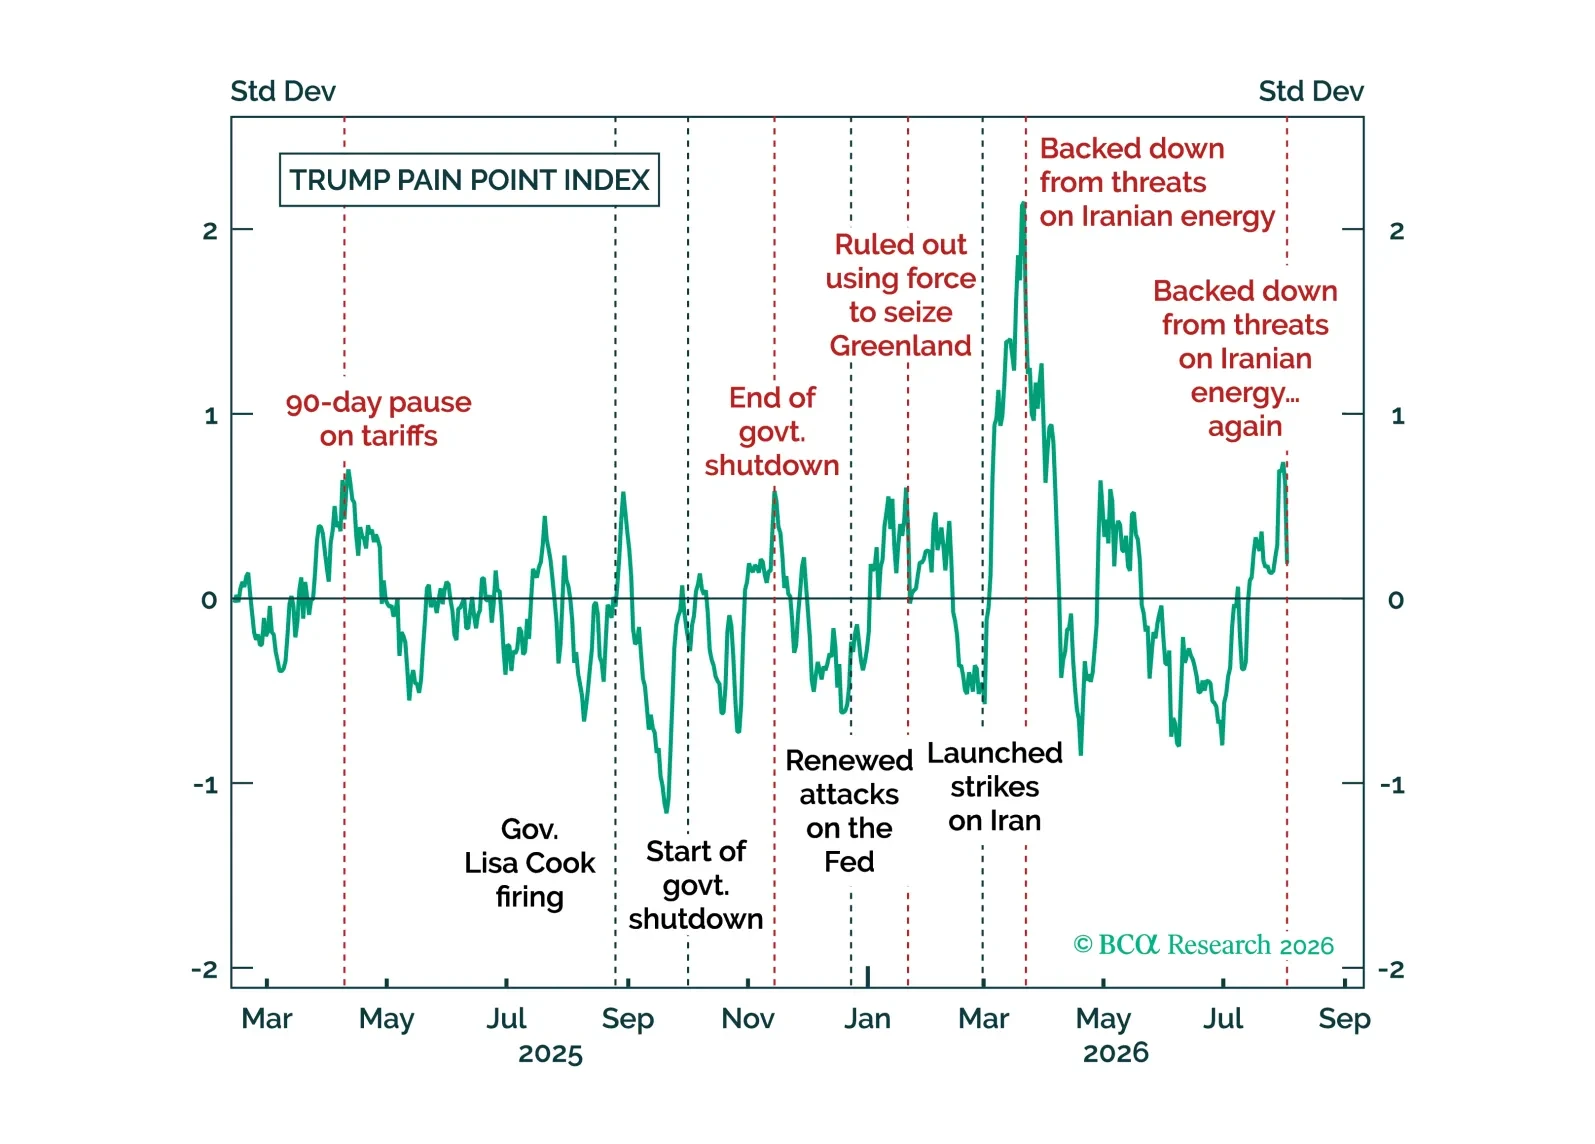
Last month we "stuck our neck out" and reaffirmed our bullishness towards risk asset. This month, we have confirmation that the risky bet is paying off. Iran and the US remain materially constrained from total war. The AI capex thesis is holding up and slowly mutating into a price war that will only boost adoption and necessitate more investment. We open a new AI-related trade (long hard disk makers) and go long gold.