Skip to main content

Geopolitics

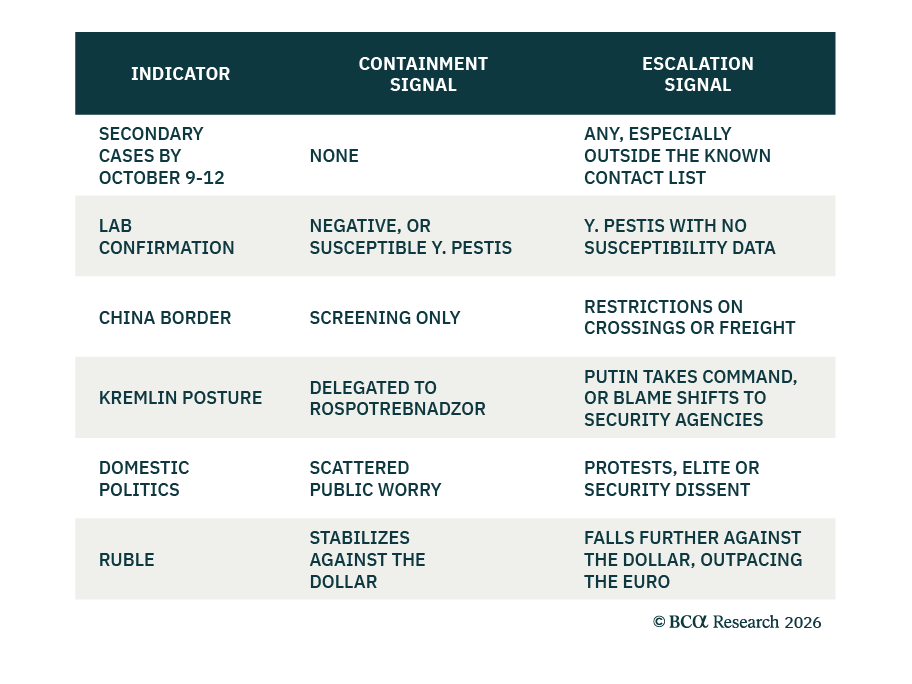
Our GeoMacro strategists argue that the Irkutsk plague scare is not yet a crisis, but Russia is a bad place for one to happen. Based on reported facts, the epidemiological situation is reassuring: Moscow has not confirmed plague, none of the roughly 200…
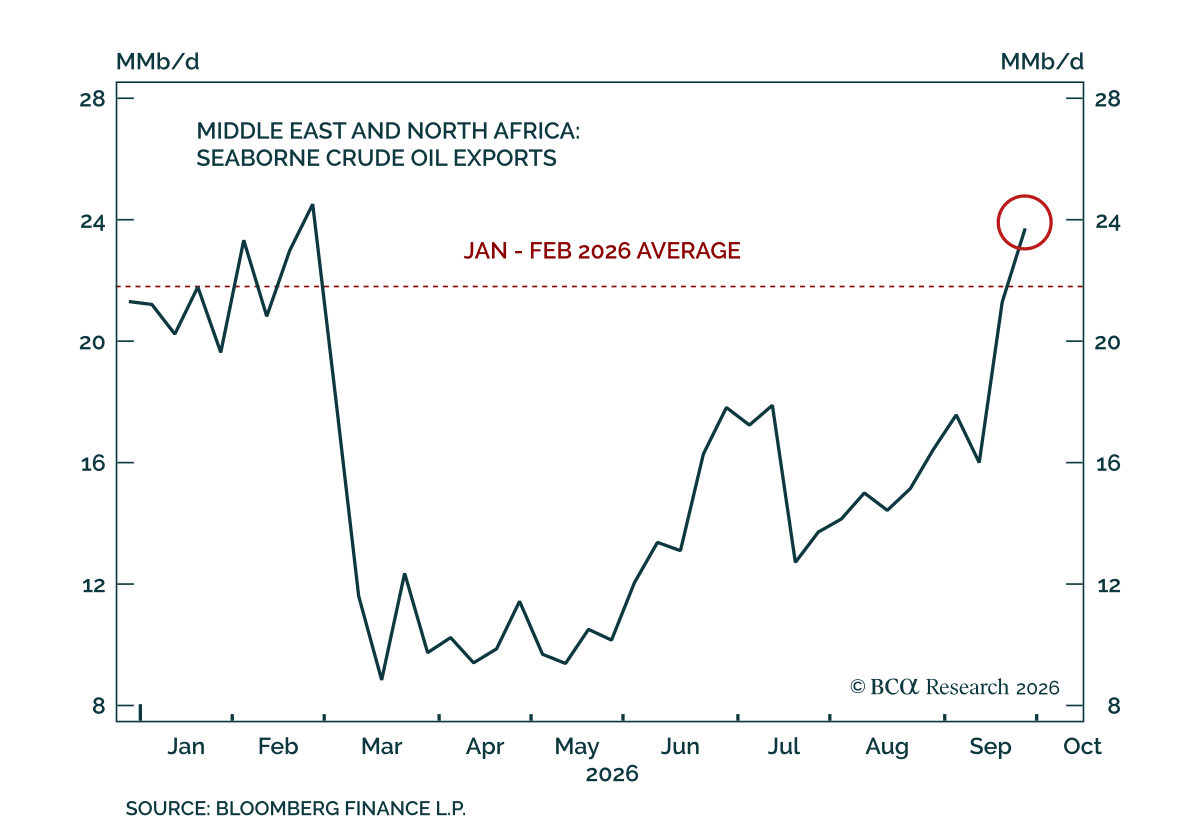
Recovering middle east oil exports should ease prices in the near term, but meaningful relief likely awaits a post-midterm ceasefire. We noted yesterday that investors should pay more attention to global oil inventories, as they will illustrate whether global…
Our GeoMacro strategists remain bullish on equities and and long-term bulls on bonds. They caution investors against treating the recent rise in yields as a reason to turn defensive. Our colleagues held both calls over the past month. The equity call proved…

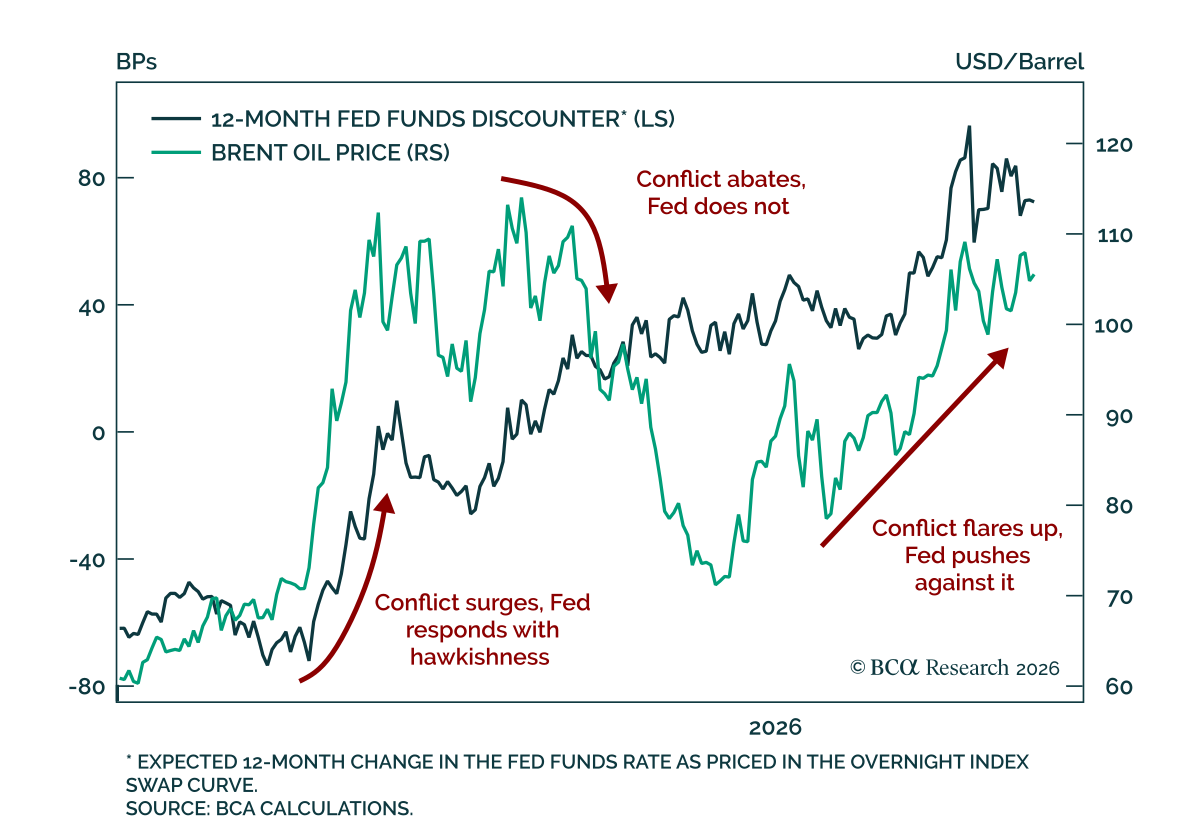
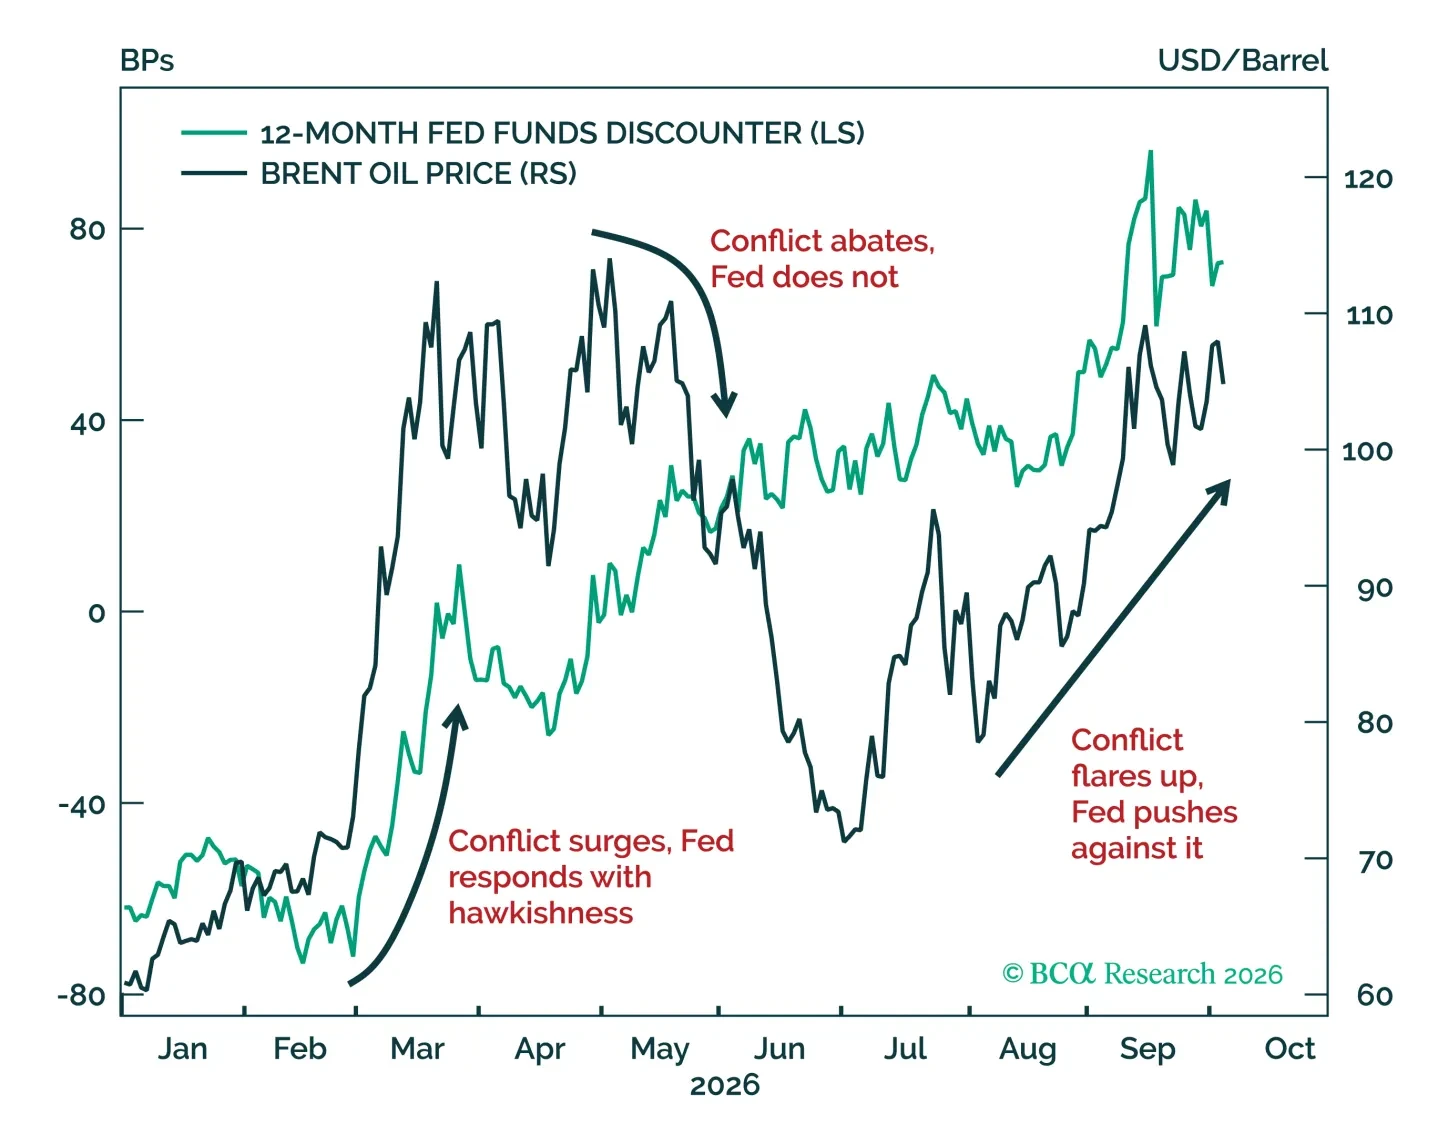
Long-dated bond yields rose another 48 bps since our last missive, quite a move in just a month. And yet, equities have remained resilient. This suggests that the move in bond yields is due to sanguine economic forces, not fiscal profligacy or inflation fears. In addition, the war in Iran is subsiding, partly because the Fed itself has conspired against it. Will President Trump restart the conflict regardless? Perhaps, however, the constraints are mounting against the White House foreign policy. We remain bullish on equities and reaffirm our view that investors with a long-term horizon should be nibbling at the current level of yields.

To make sure that our bearish clients are happy, we pivot to the risk of higher tax rates in the US. Specifically, we try to answer the question of when markets price higher tax rates.
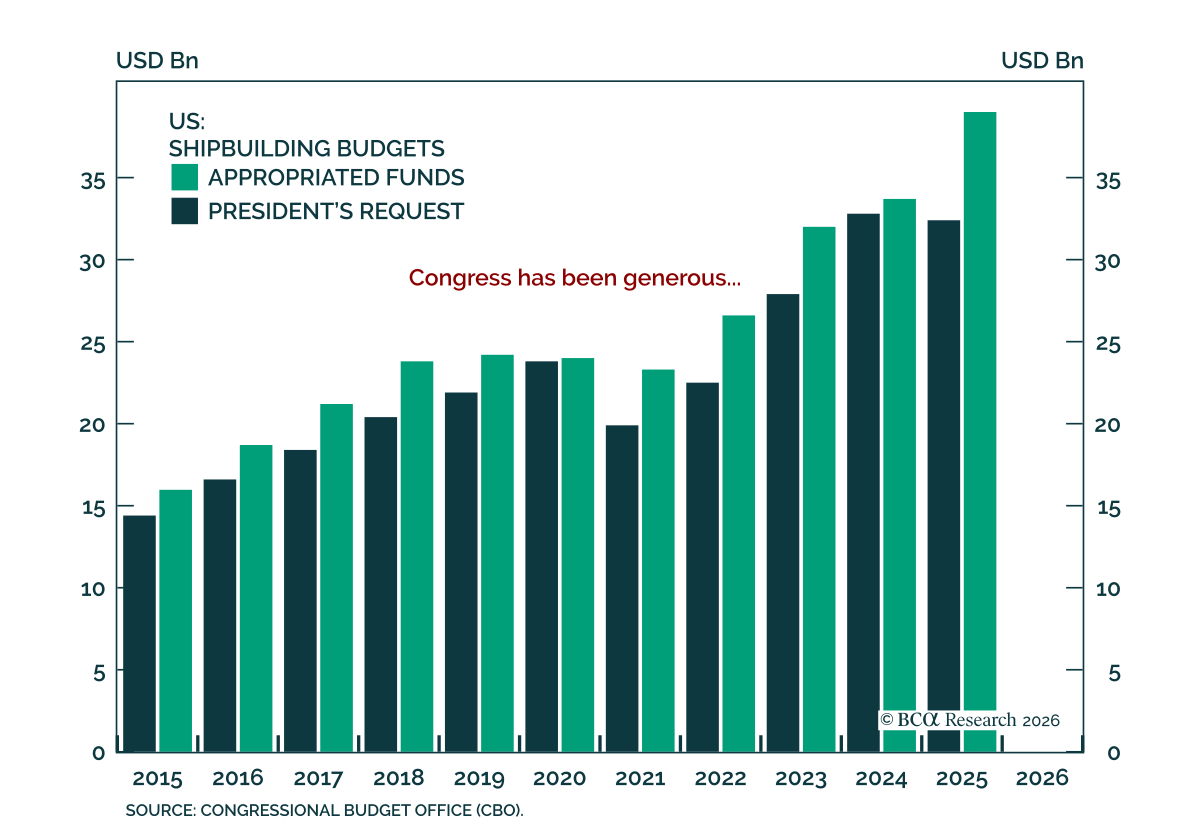
Naval rearmament has become a durable, bipartisan budget priority rather than one administration's ask. Our Chart Of The Week comes from Jose Yanes, analyst in our GeoMacro platform. China already operates a larger naval fleet than the US and has roughly 232x…
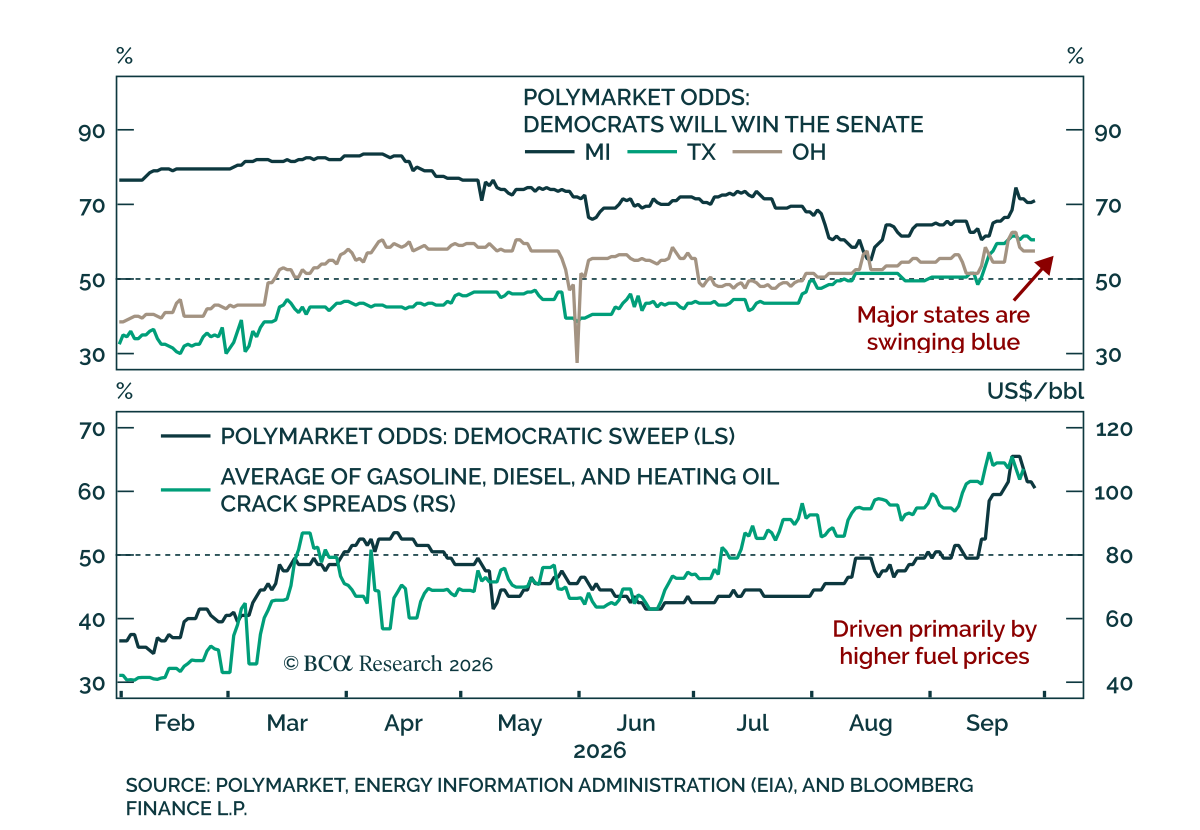
Betting market odds have swung decisively toward a Democratic sweep of Congress, converging on a call our Geopolitical strategists have been making against consensus. Polymarket now puts the odds of Democrats winning both chambers at above 60%, up from just…

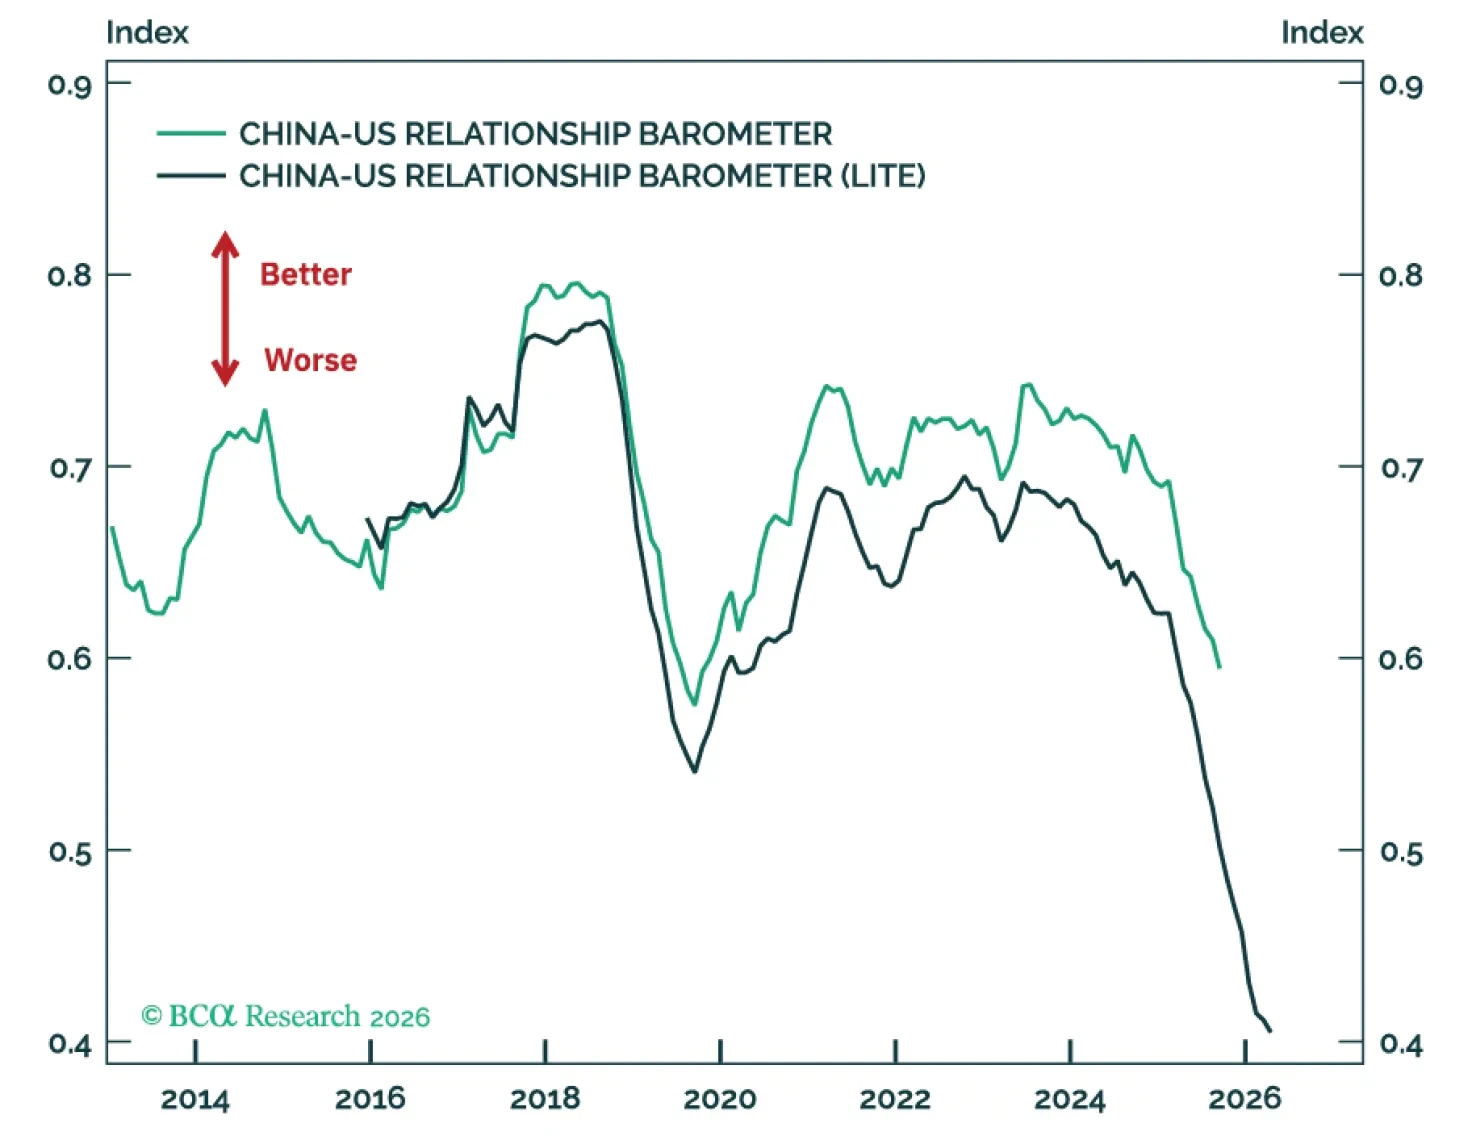
The Trump-Xi summit does not imply concrete benefits to US-China trade. Strategic tensions persist, forcing China to increase fiscal stimulus in 2027. 
A busy geopolitical weekend reinforced that both Russia and Iran are still calibrating escalation to avoid triggering a broader conflict. Our Monday BCA Live & Unfiltered meeting focused on the weekend’s geopolitical developments. Russian and Ukrainian…
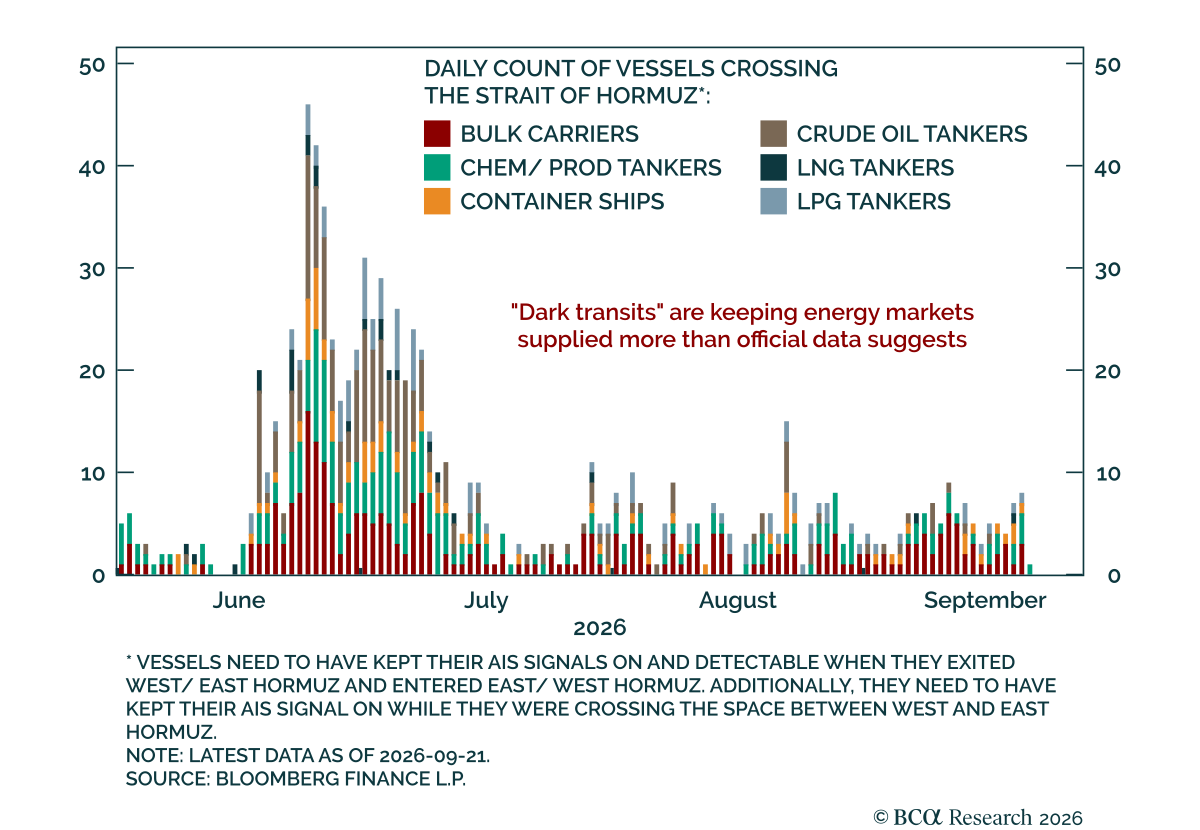
The latest Middle East escalation fits Iran’s existing strategy of keeping oil prices elevated ahead of the US midterms, but attacks on energy infrastructure and tankers now threaten the recovery in regional crude exports. Our GeoMacro strategists see…
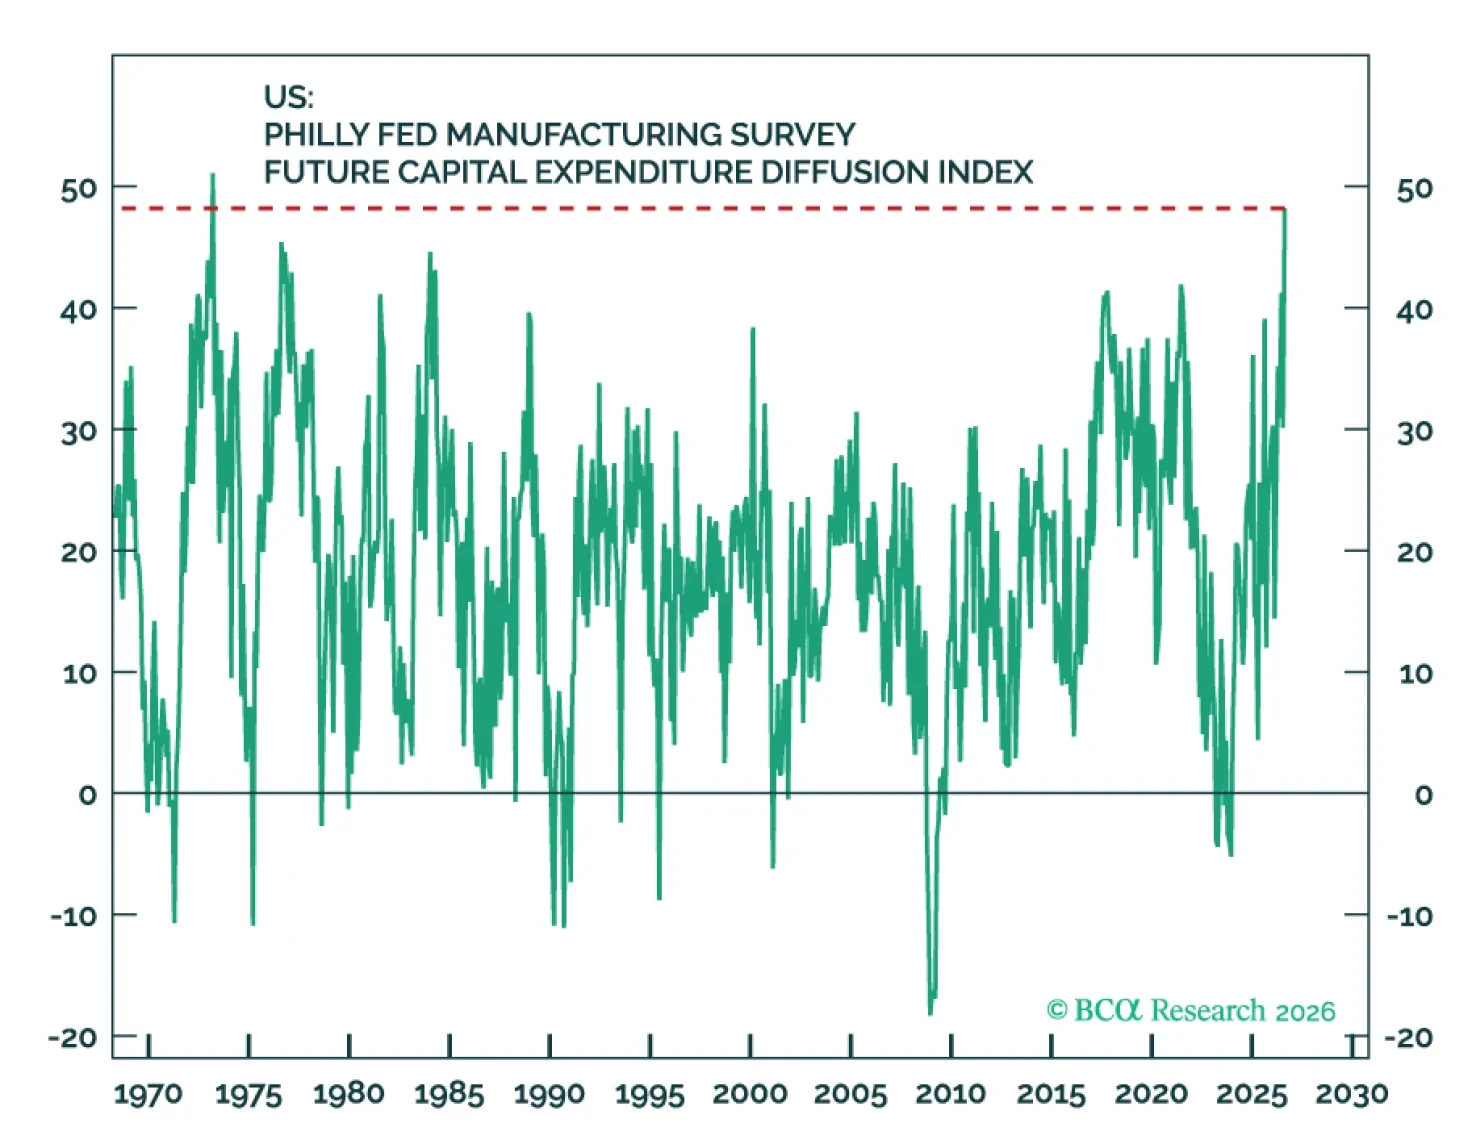
Dear Friends,Does the world need an 87-page deck? Probably not. But you're getting it regardless. We are itching to turn bond bullish and we remain equity bulls for now. Are there risks to these views, you bet. Thus the 87 pages. Plenty for bulls and bears alike. But if you were to pin us down to the main risk in 2027, it would be a combination of Midterm Dem sweep and end of Iran war. End of Iran war? Yes, indeed. If the economy can withstand high interest rates and gasoline prices today (Chart of the Month), what is it going to do next year if both abate? The Fed does not have an inflation problem today, but it may next year. For an in depth analysis of these topics, read my full Here, There, and Everywhere Chartpack.