 GeoMacro
Find out more
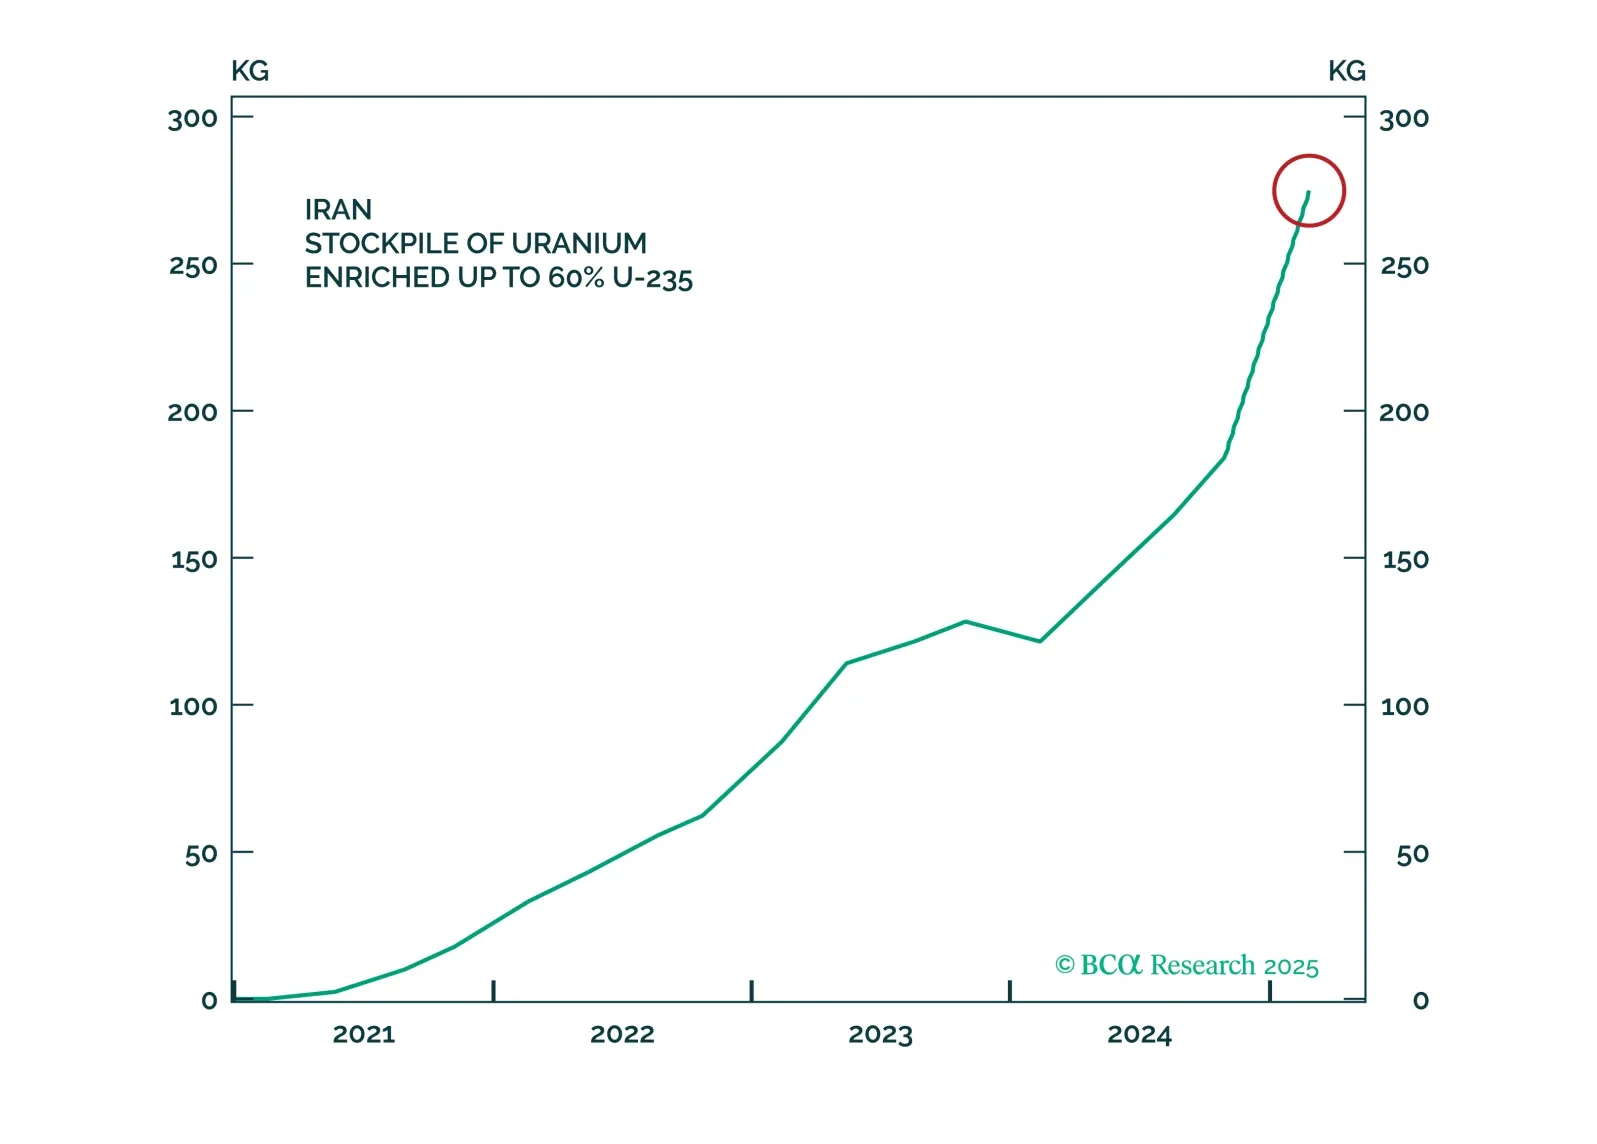
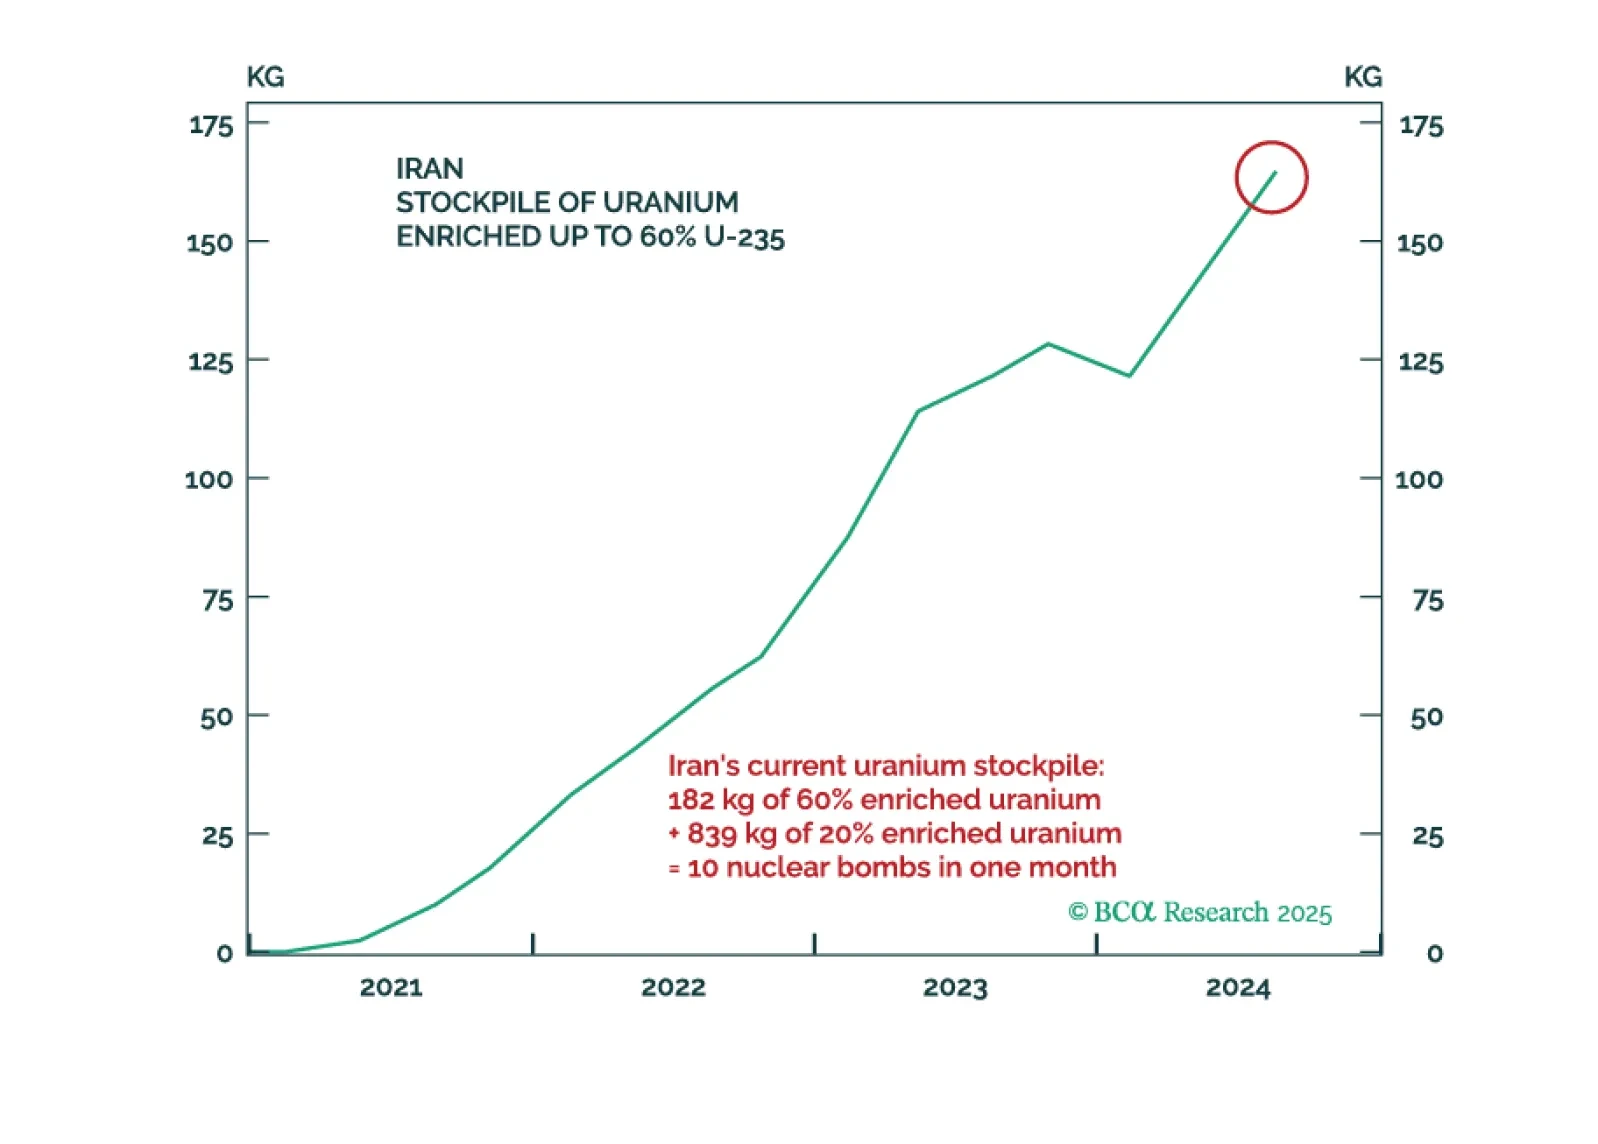
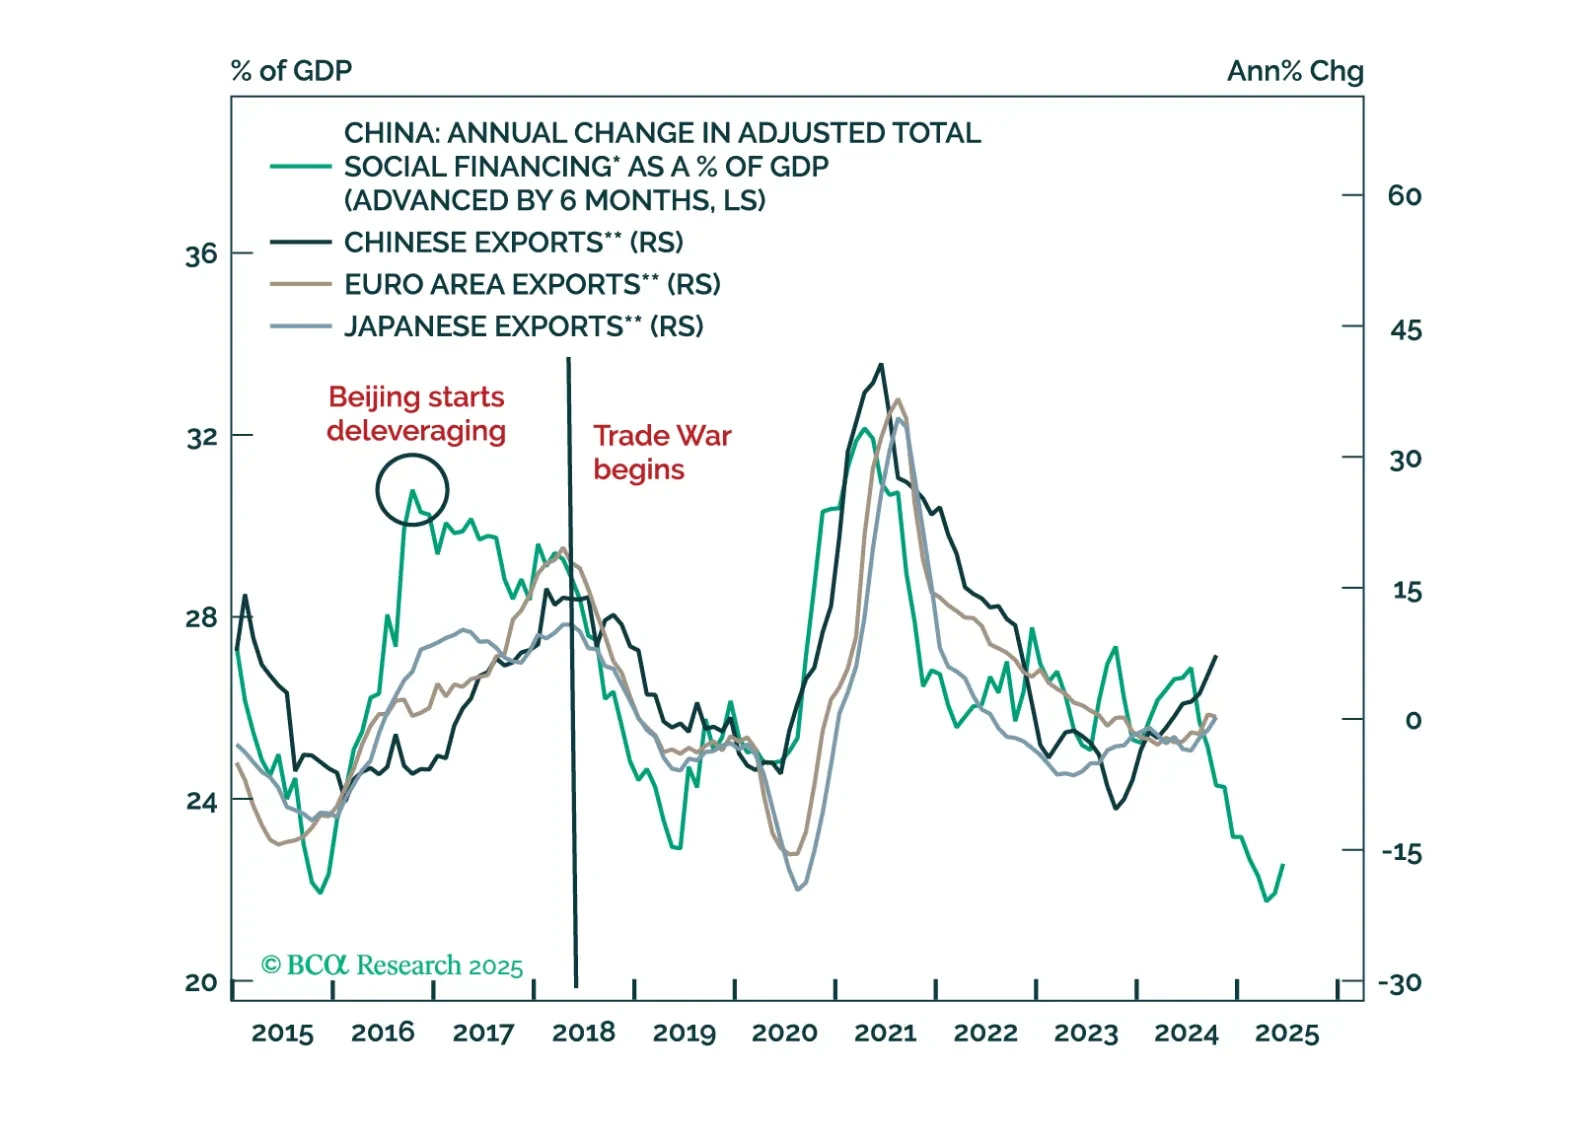
The tariffs on Canada and Mexico will come into effect as scheduled while the tariffs on China will be doubled. In the Middle East, Iranian response to any attack will threaten Middle Eastern oil supply. Meanwhile, Chinese fiscal support will surprise to the upside at the Two Sessions. But Trump's China policy will cause volatility. Now that the stock market is cracking, reinitiate defensive trades, such as long treasuries versus US stocks and long global defensives versus cyclicals.
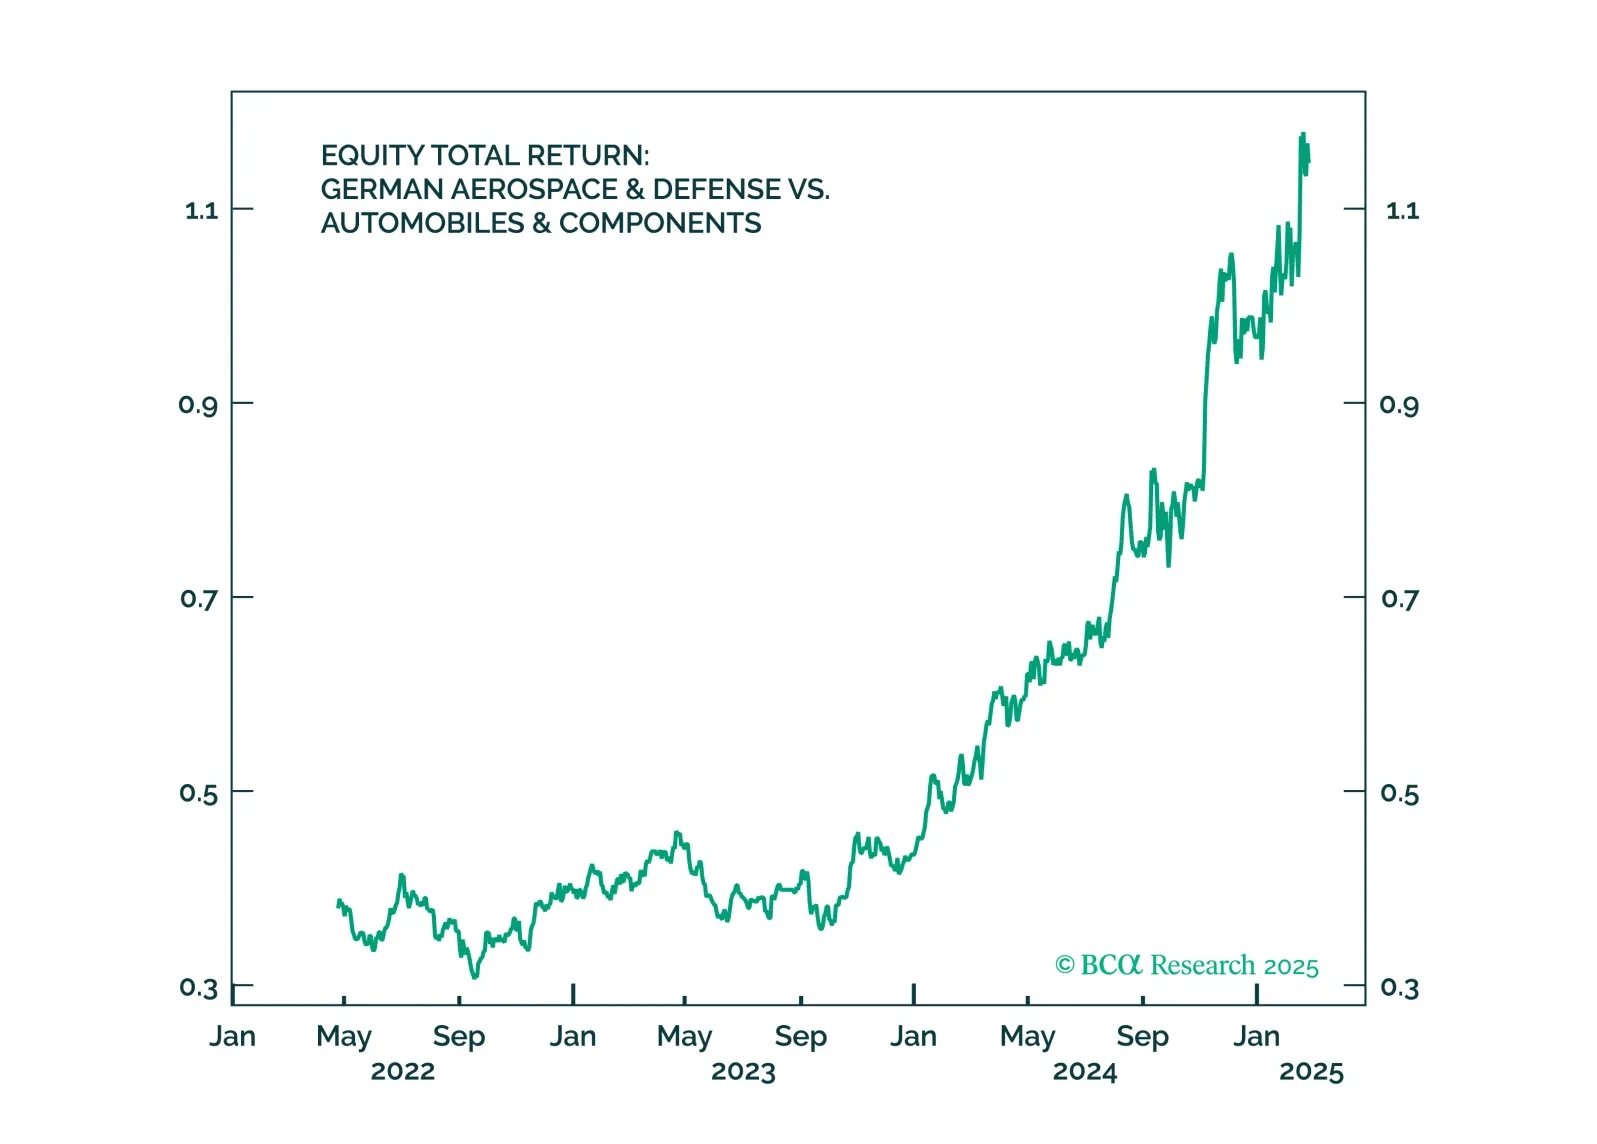
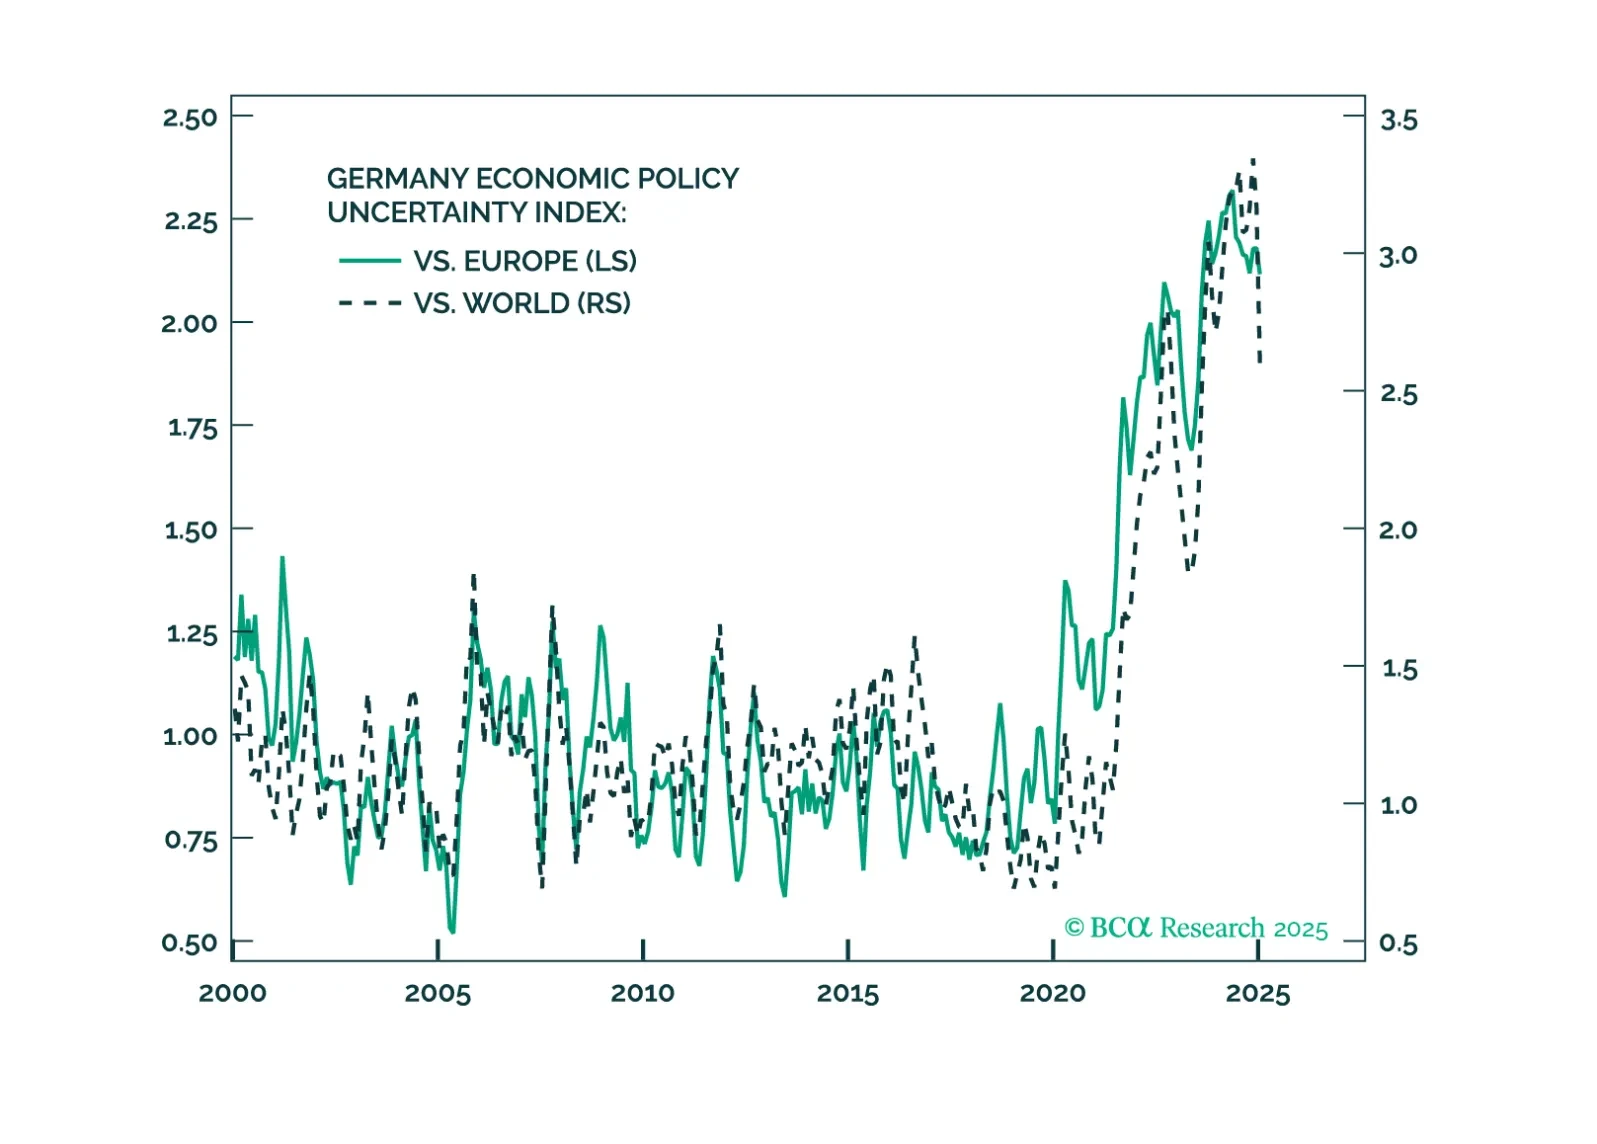
Trump’s ceasefire talks are positive for Germany – and so was the German election result. But Trump’s tariffs will hit Germany soon. Investors should use near-term volatility to increase exposure to Germany.
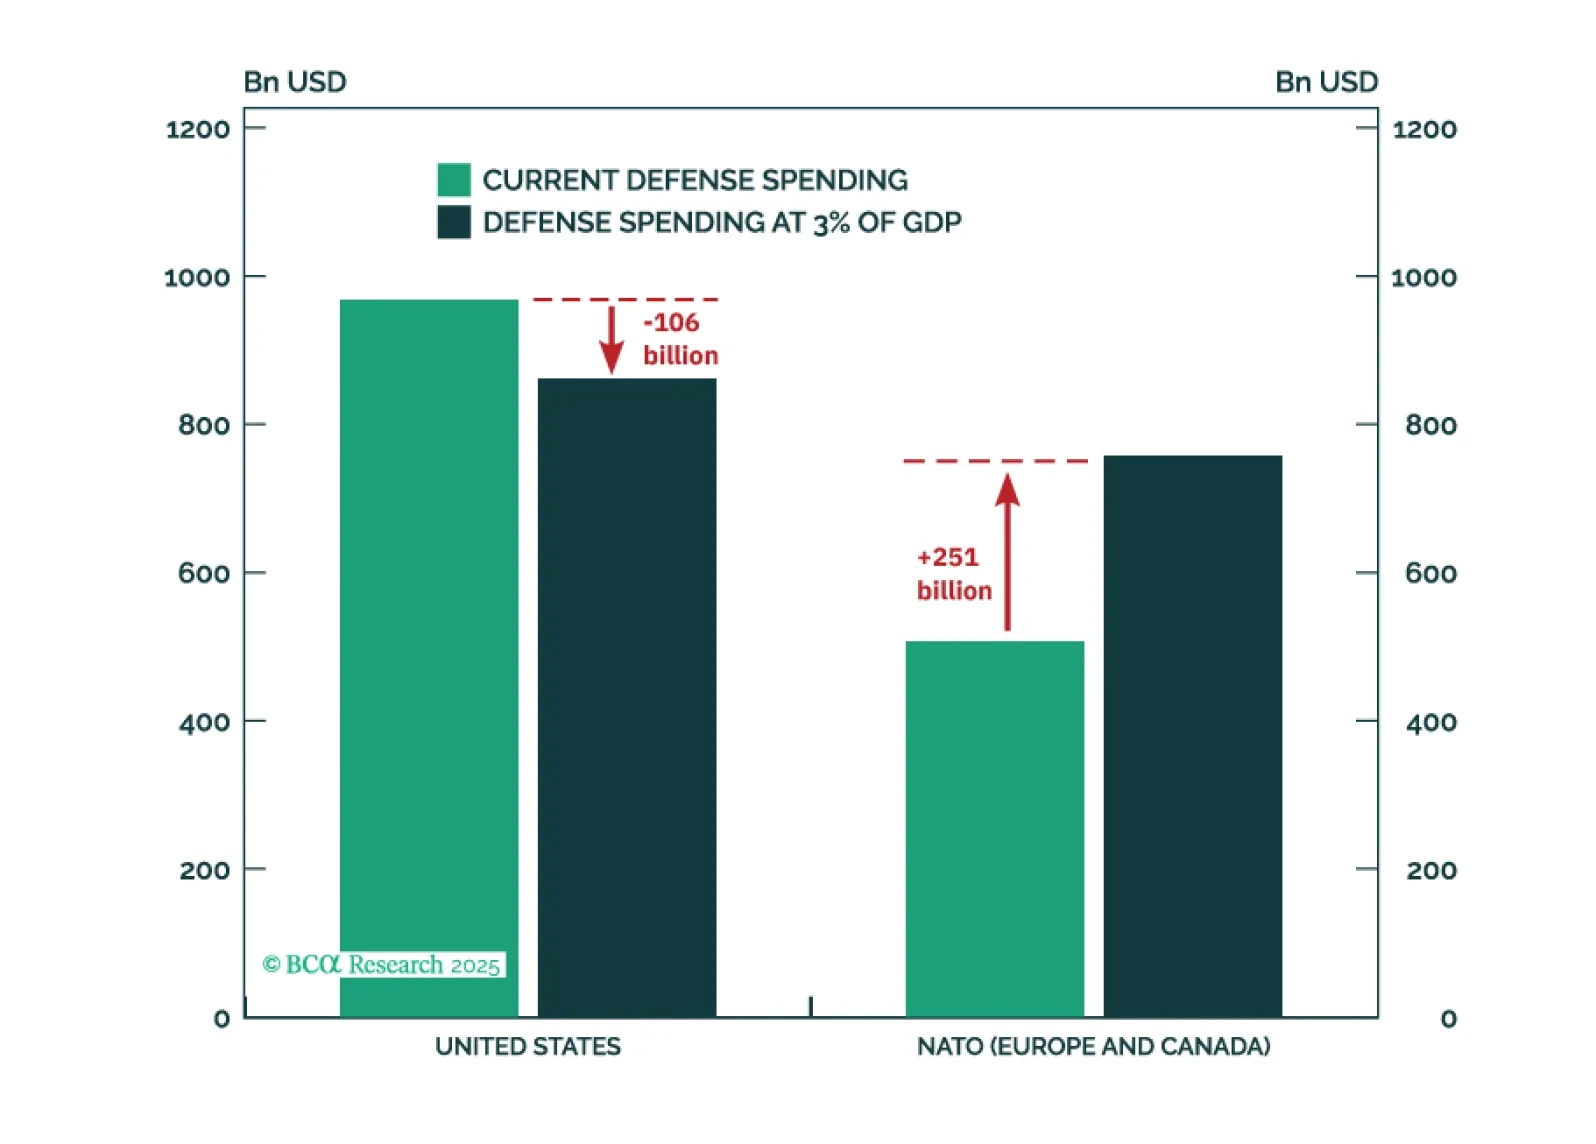
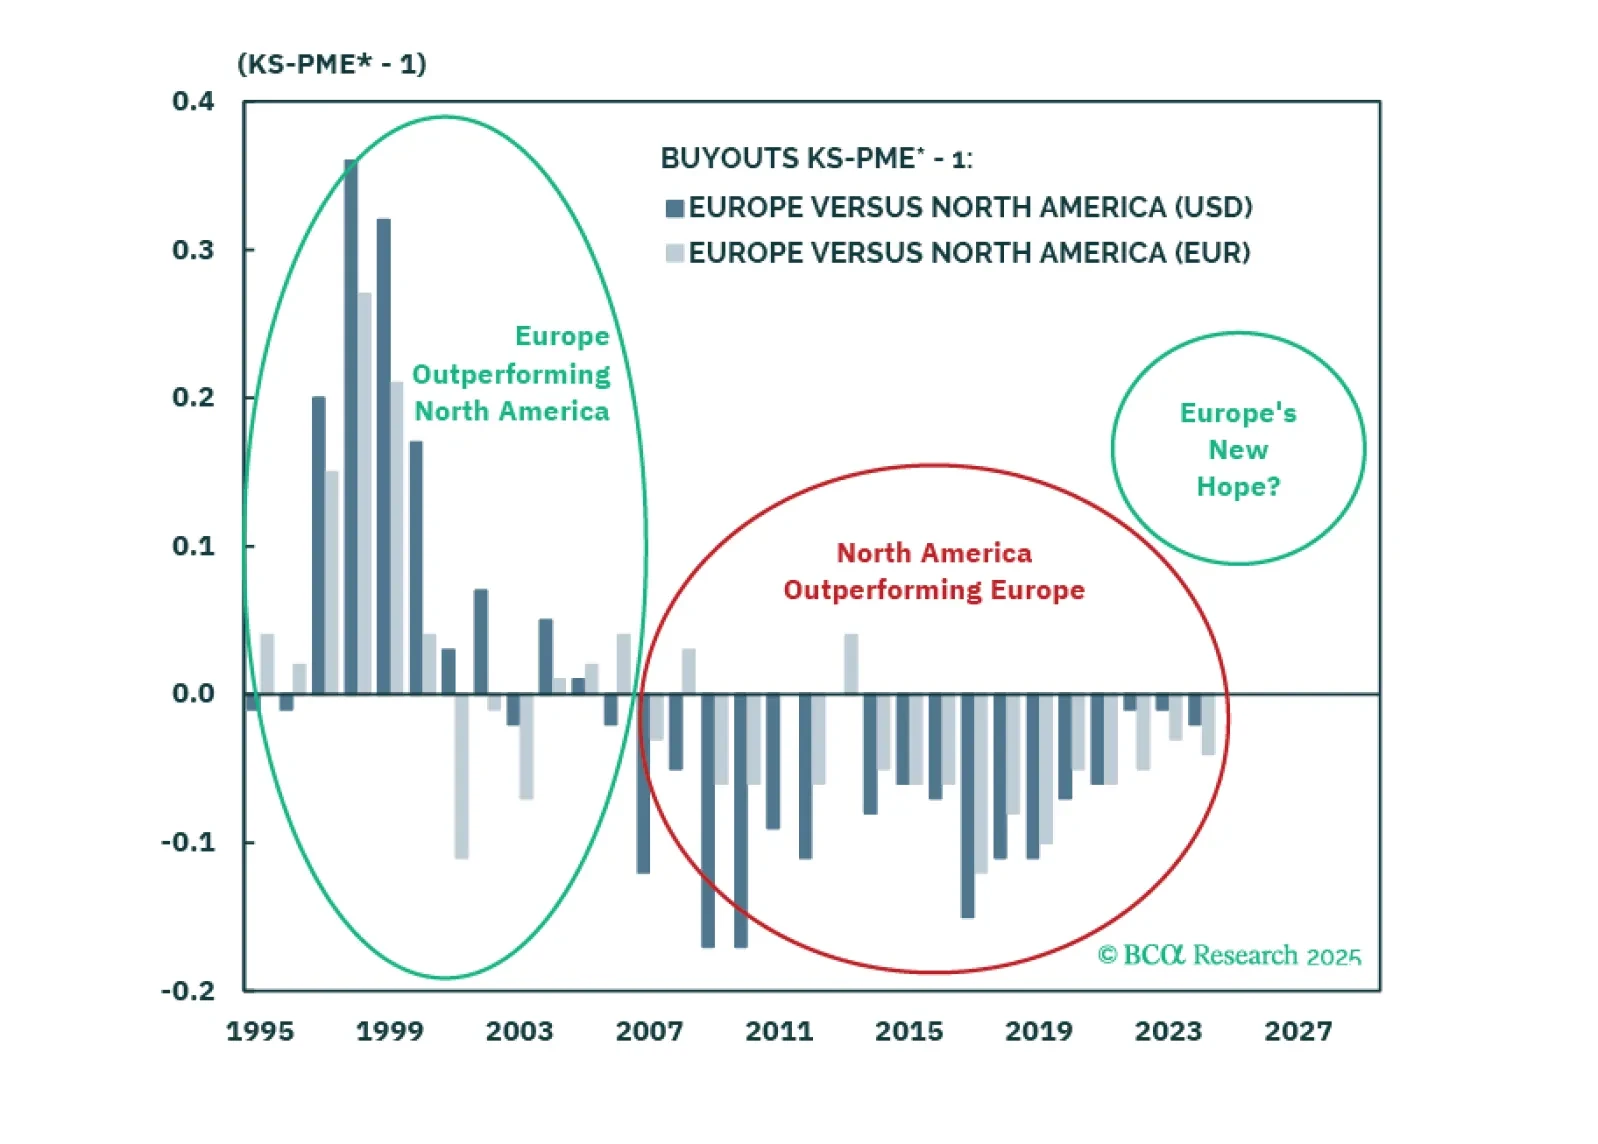
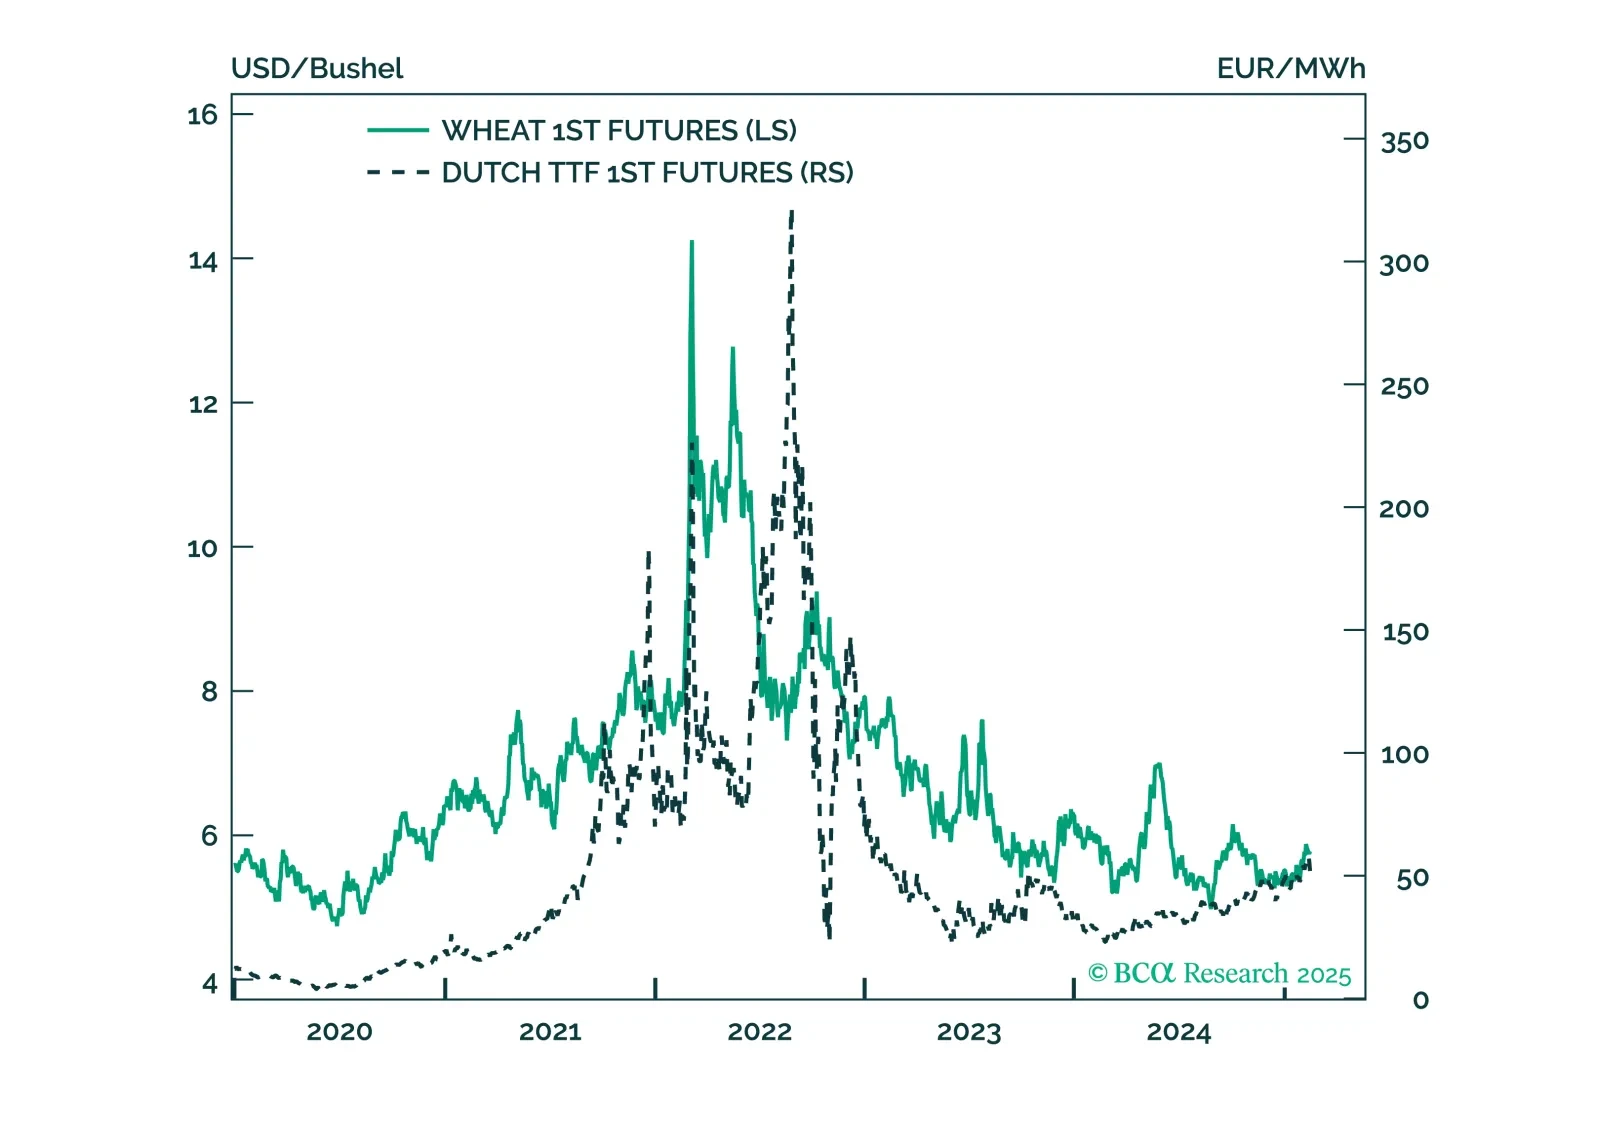
President Trump is negotiating a ceasefire in Ukraine. This will be a marginal headwind to some commodities which benefitted from the conflict like natural gas and wheat, and will be a marginal tailwind for European assets, specifically EM Europe. Use Trump’s tariff shock as an opportunity to buy European assets.
The budget process and debt ceiling will cause stock and bond market volatility. US trade policies will provoke foreign pushback at a time of stretched valuations. Hence US politics and geopolitics will be bullish for US energy, but bearish for the internationally exposed US tech sector.
The bond market has paused its selloff thanks to a revolt by the Republicans in the House of Representatives against much of President Trump’s fiscal agenda. Gone are the lofty projections of the expanded deficit and we are now looking at merely the 2017 tax cuts being extended. This is positive for bonds, but by extension of the relationship also somewhat positive for equities. The US economy, effectively, does not need any more growth and certainly does not need any more inflation. Our thesis that we are at peak fiscal is therefore in effect.
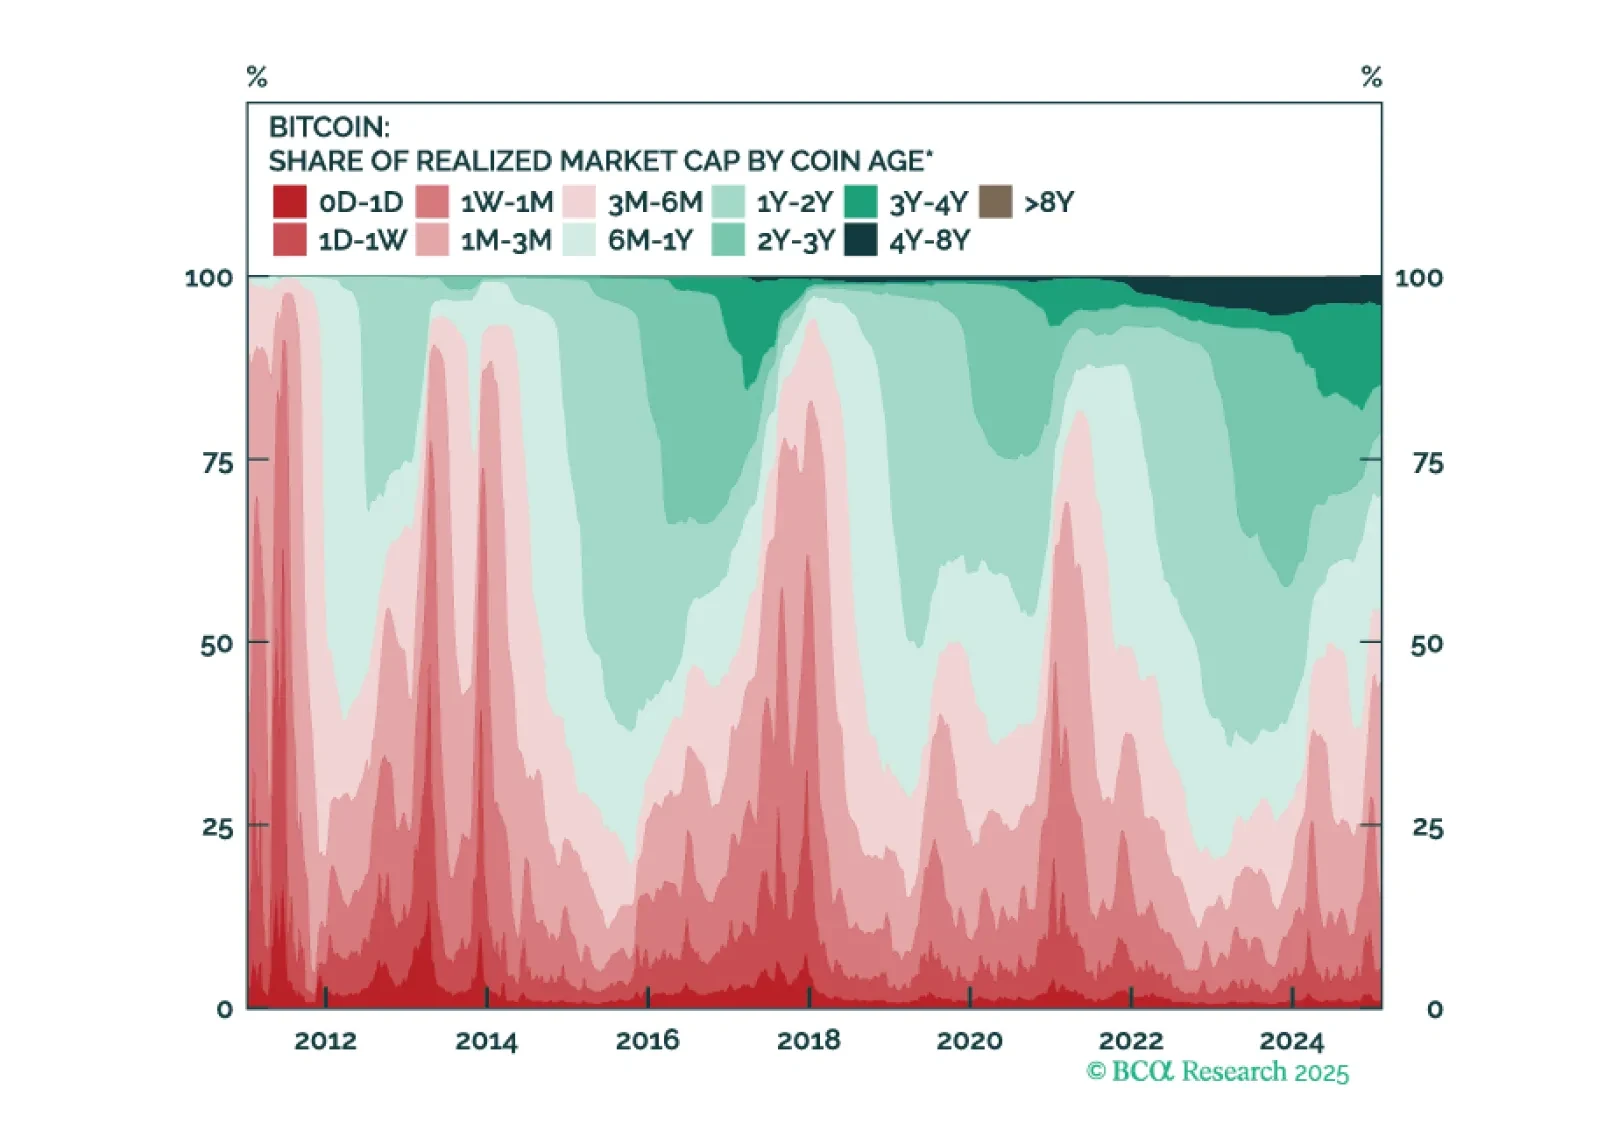
In this report, we reassess our bullish stance on crypto from early 2023, following Bitcoin’s recent all-time highs. While institutional adoption is broadening, there are also signs of excessive exuberance, speculation, and optimism. Given these conditions, a near-term correction appears likely. We are booking profits and will look to re-enter the market at $75,000.
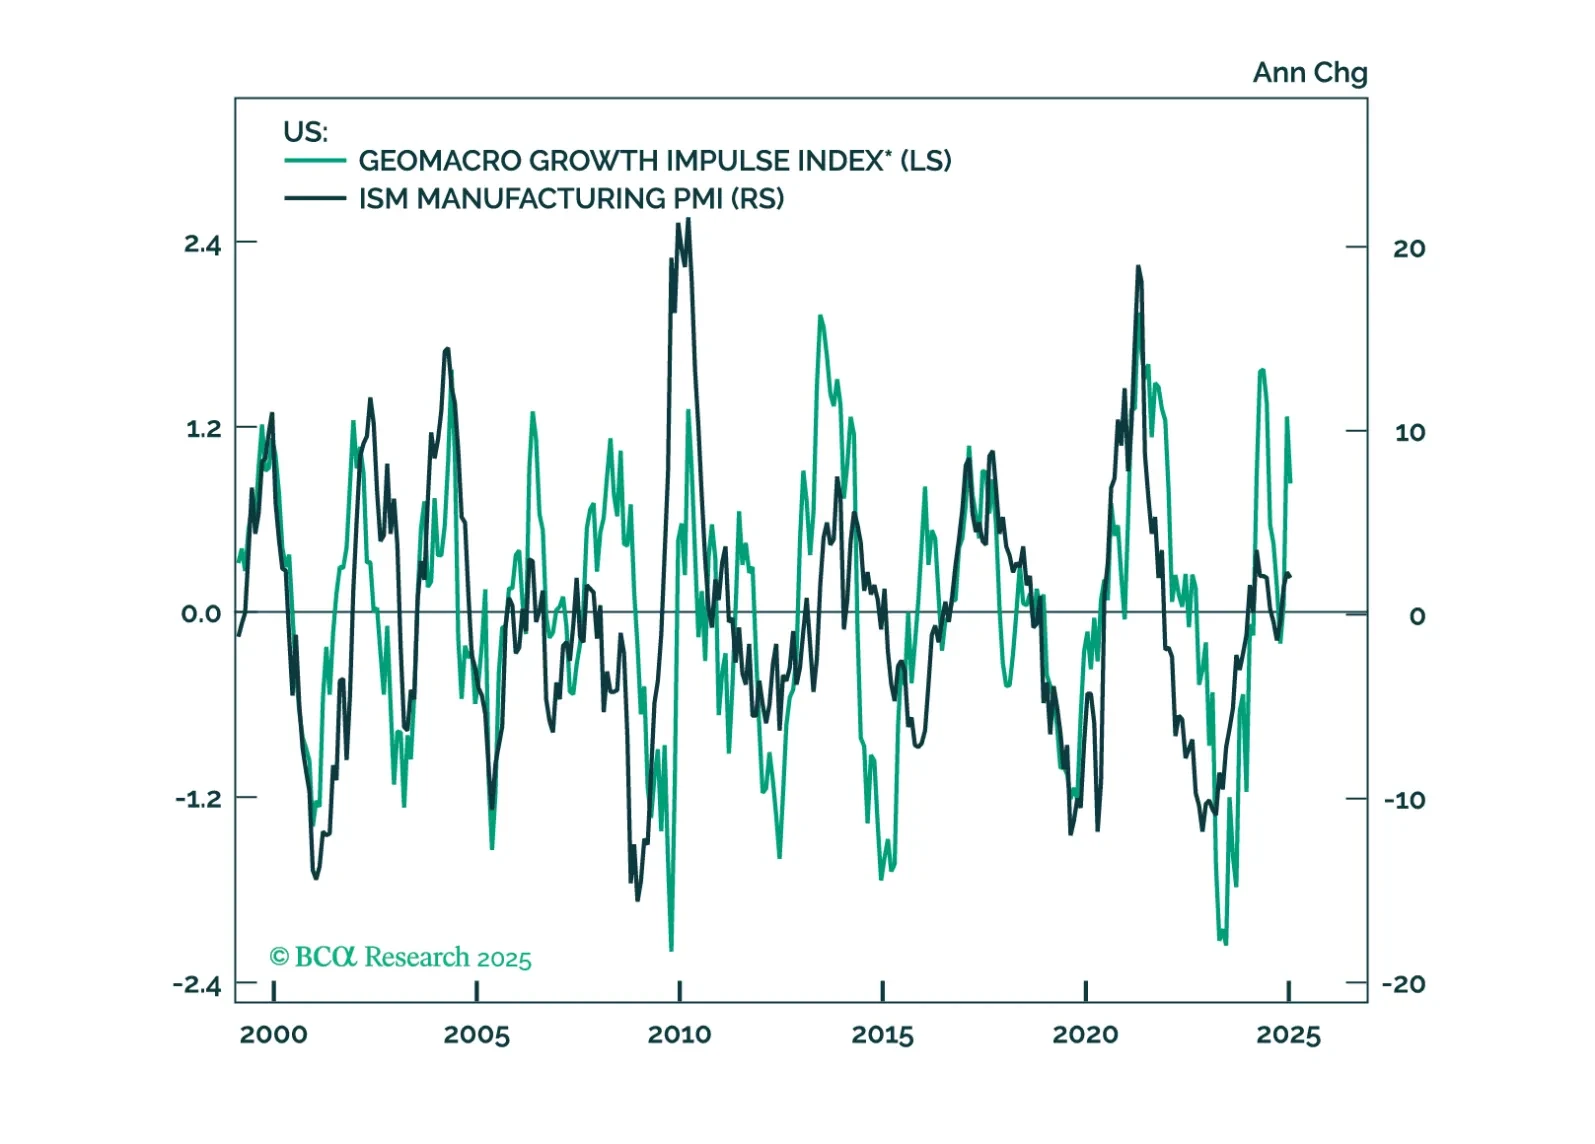
We revisit our view on the “fiscal gravy train” as well as President Trump’s negotiating style. We re-print parts of our March 2024 net assessment, particularly for the benefit of our new clients who have joined us at BCA Research. Our analysis of President Trump’s first term is our guide into how the White House will negotiate future trade wars and skirmishes.