Skip to main content
Trump’s territorial ambitions threaten to deliver negative surprises and “black swan” risks during his four-year term. Military conflicts on the Mexican border raise the biggest risk, but US intervention in Panama can never be ruled out. The investment impact will be limited unless the trans-Atlantic alliance is damaged.
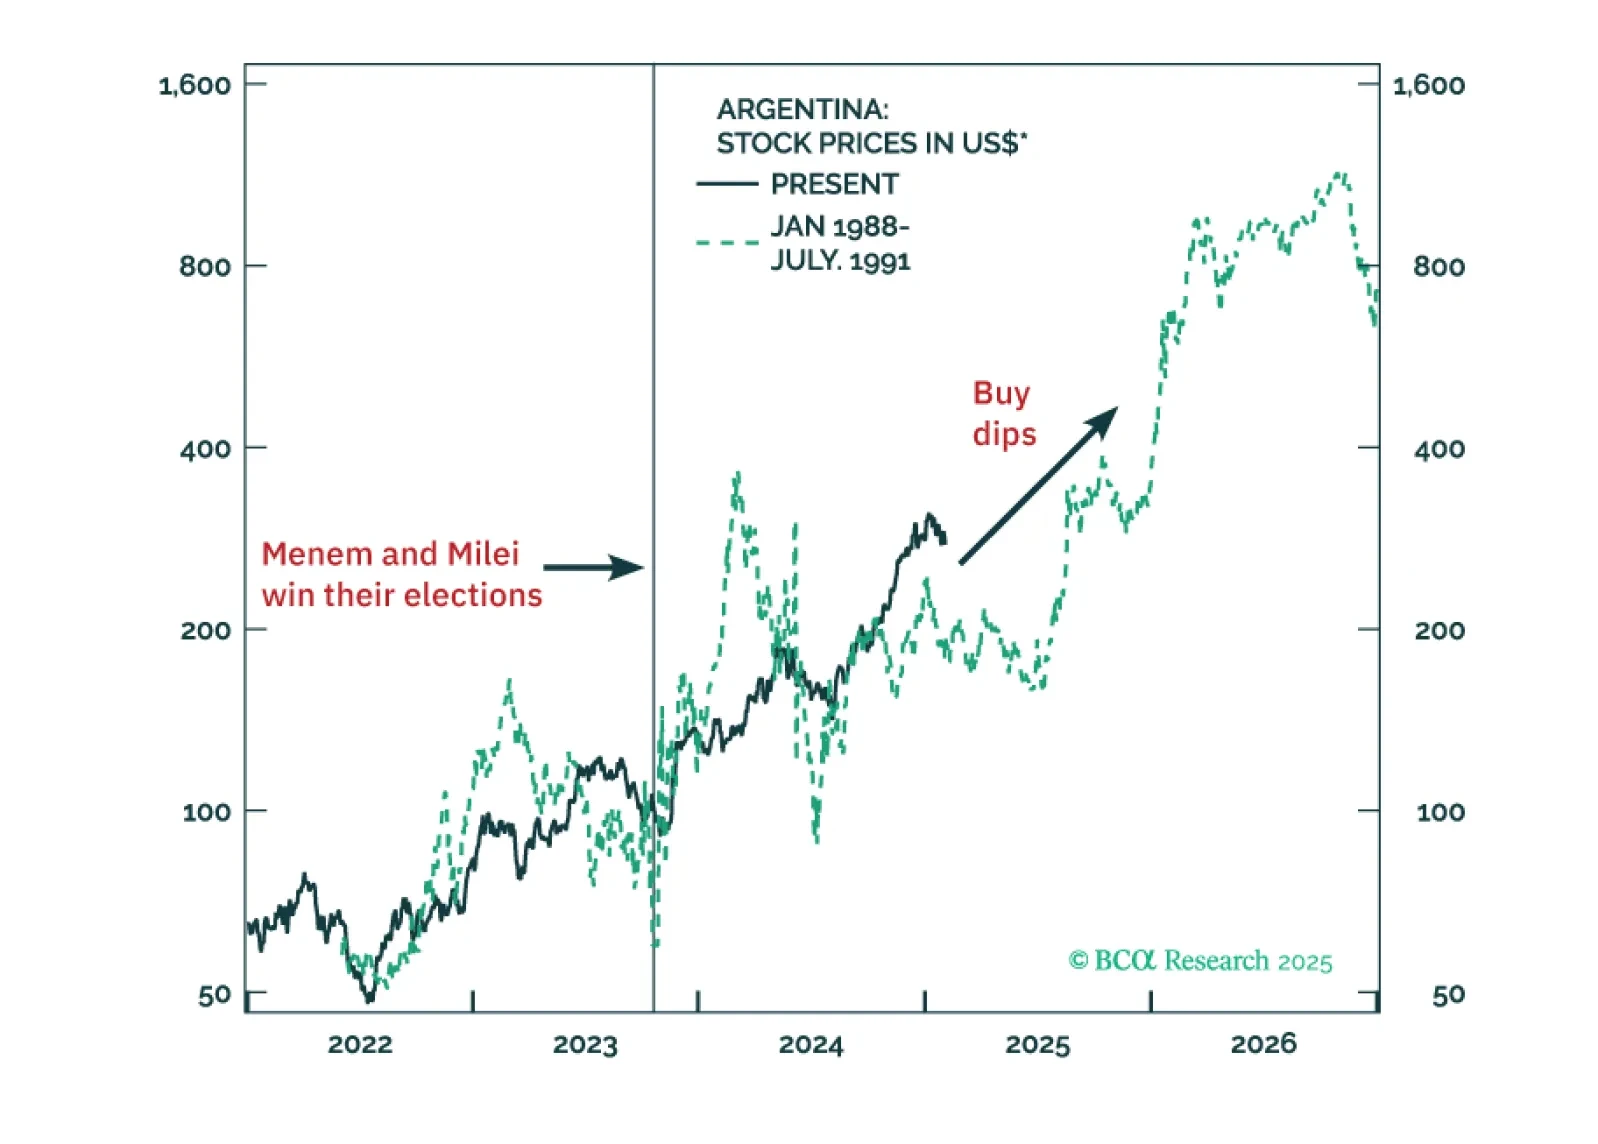
Special Report Argentina is entering a regime shift from the traditional short boom-bust cycles of the past 50 years. Profound structural reforms will result in a productivity boom, leading to a more durable economic expansion while keeping with the disinflation trend. Authorities will likely lift capital and currency controls in the second quarter of this year. All in all, odds are that Argentinian assets have entered a multi-year bull market.
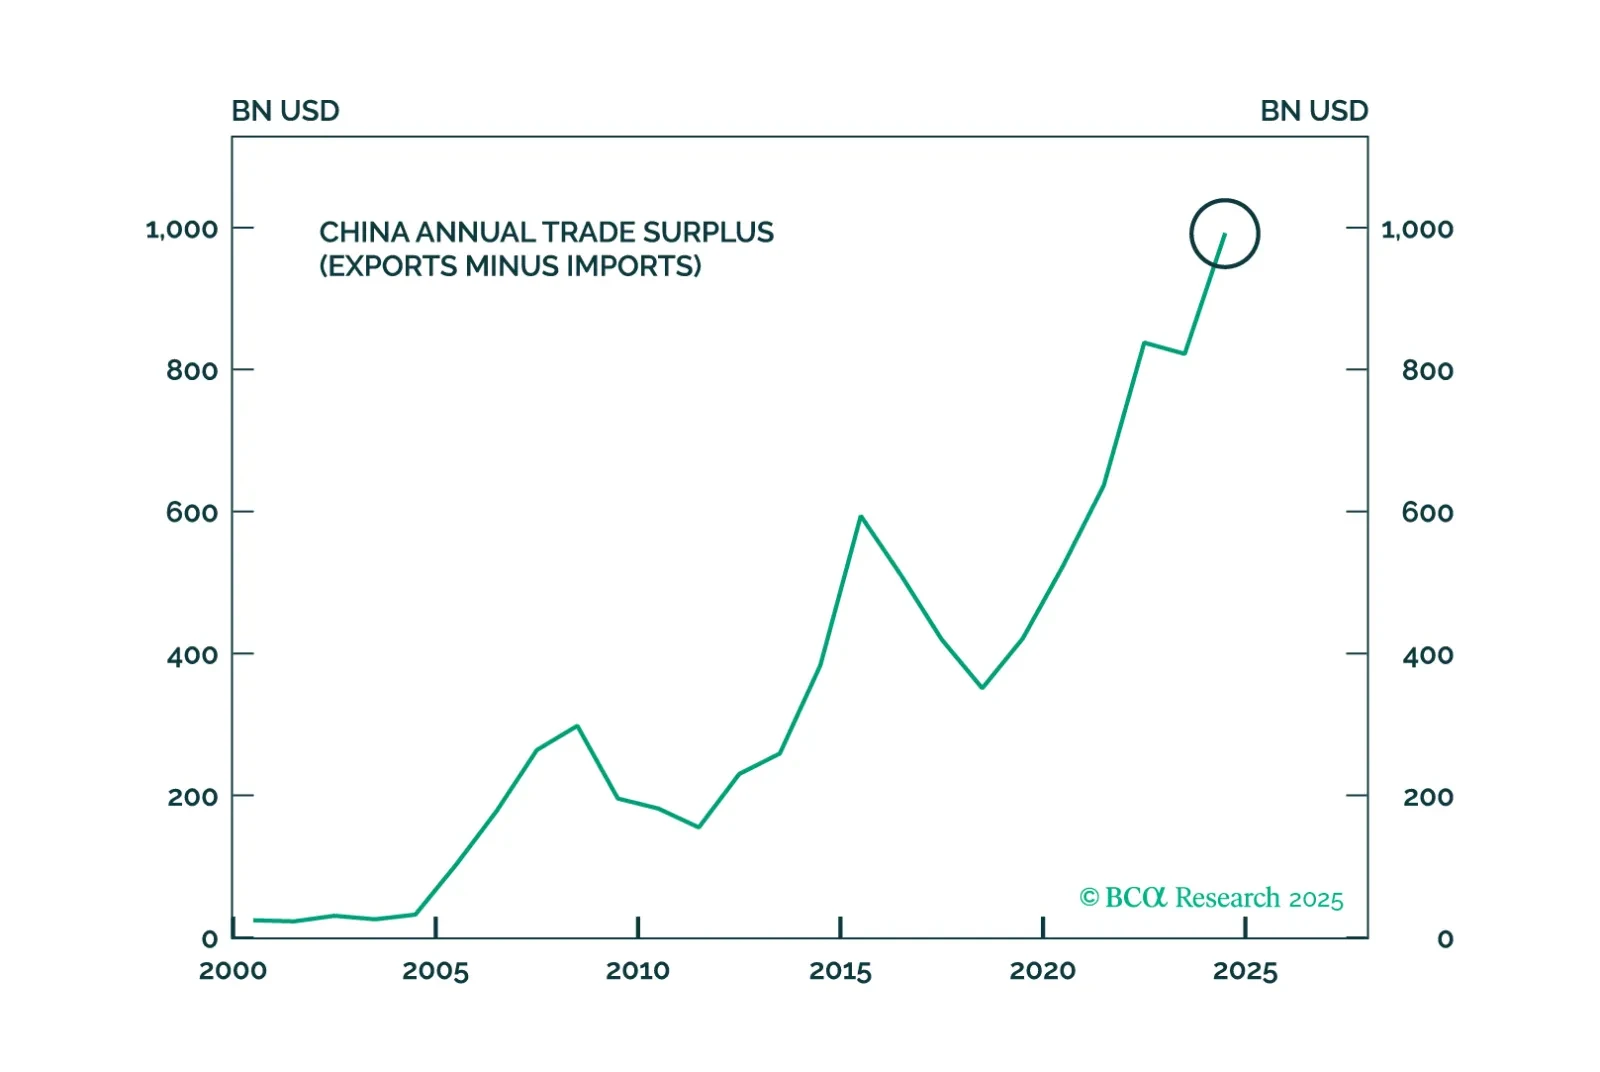
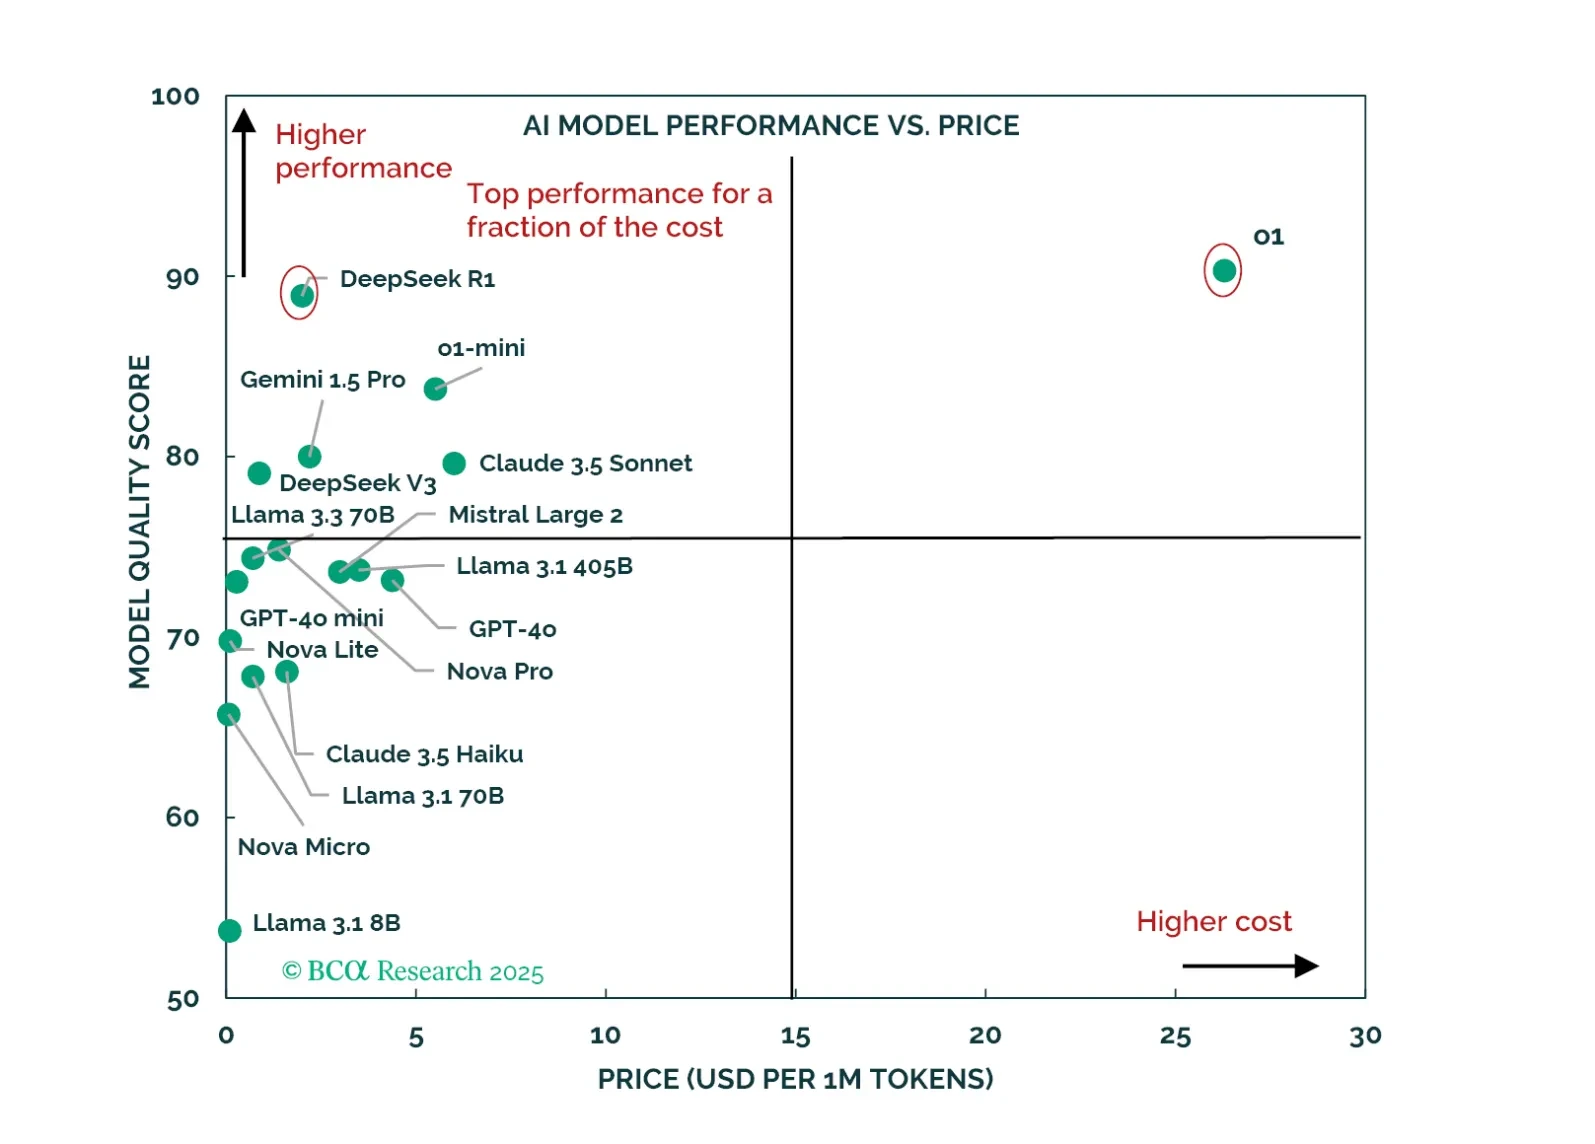
Special Report China barely hit its growth target in 2024 by shifting back to its old model of exports, racking up a record trade surplus with the world – right as Donald Trump walks back into the White House. Tariffs will elicit larger fiscal stimulus even as China rolls out innovations such as DeepSeek to meet its 2025 industrial goals, creating a volatile mix this year.
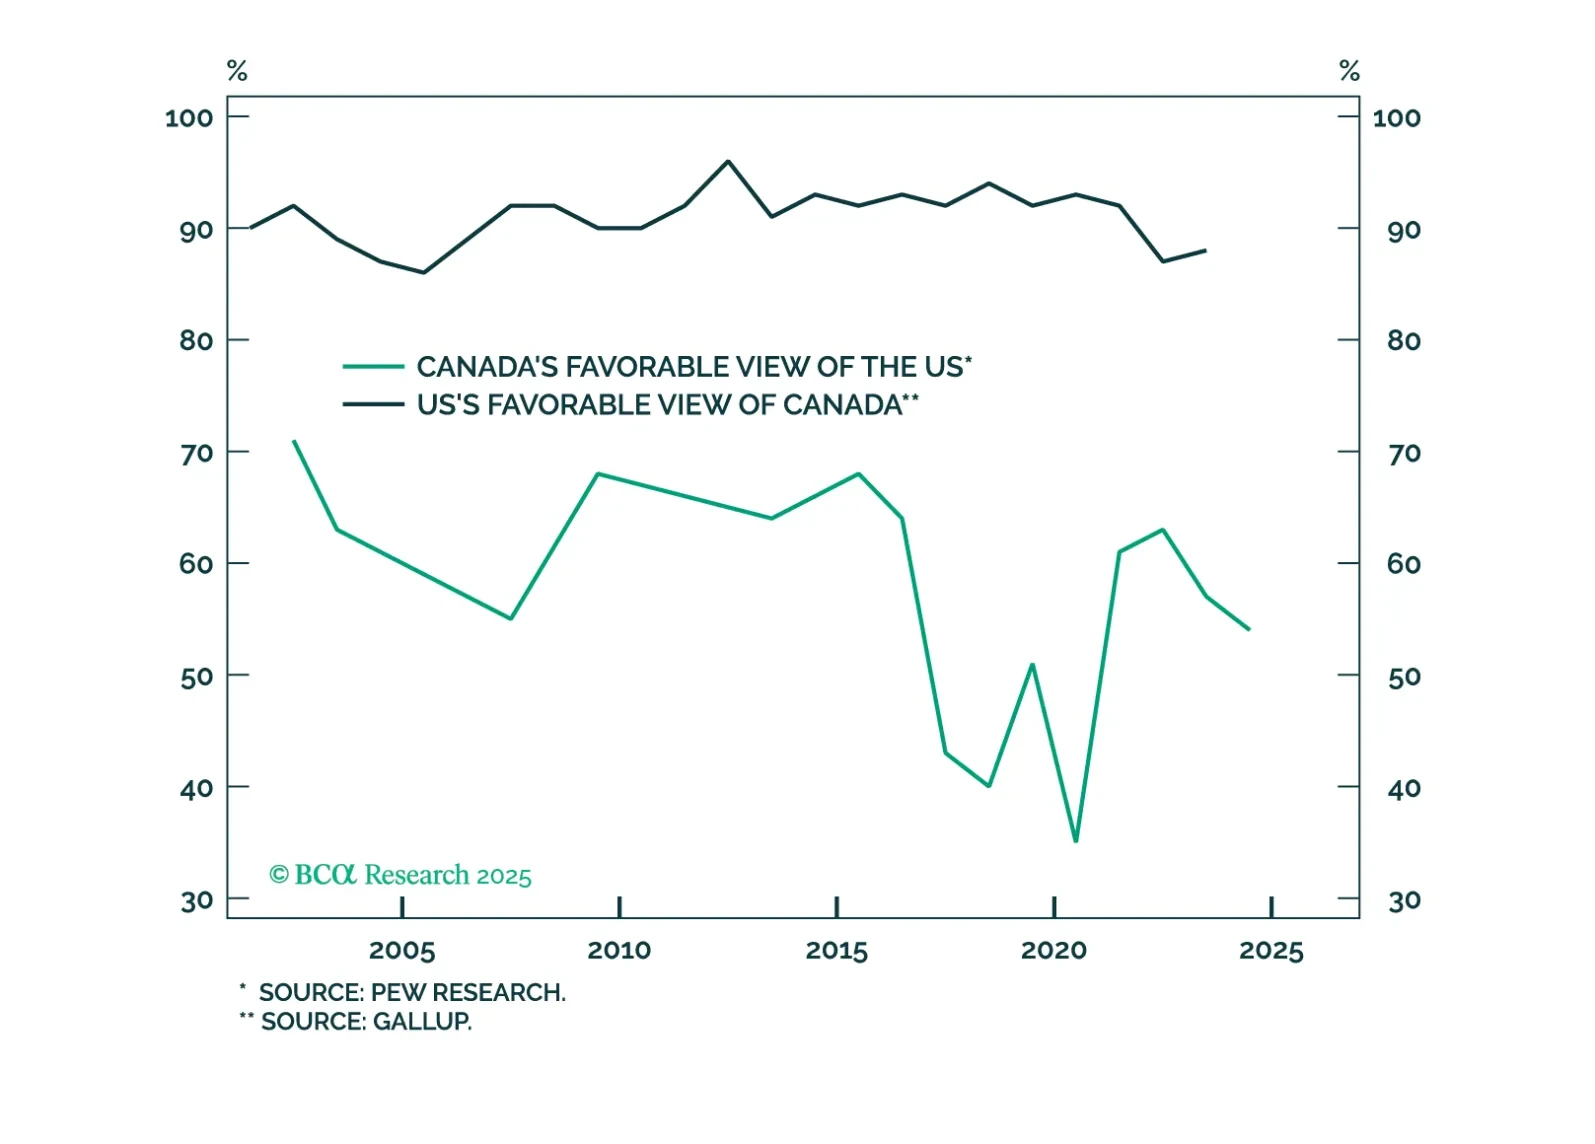
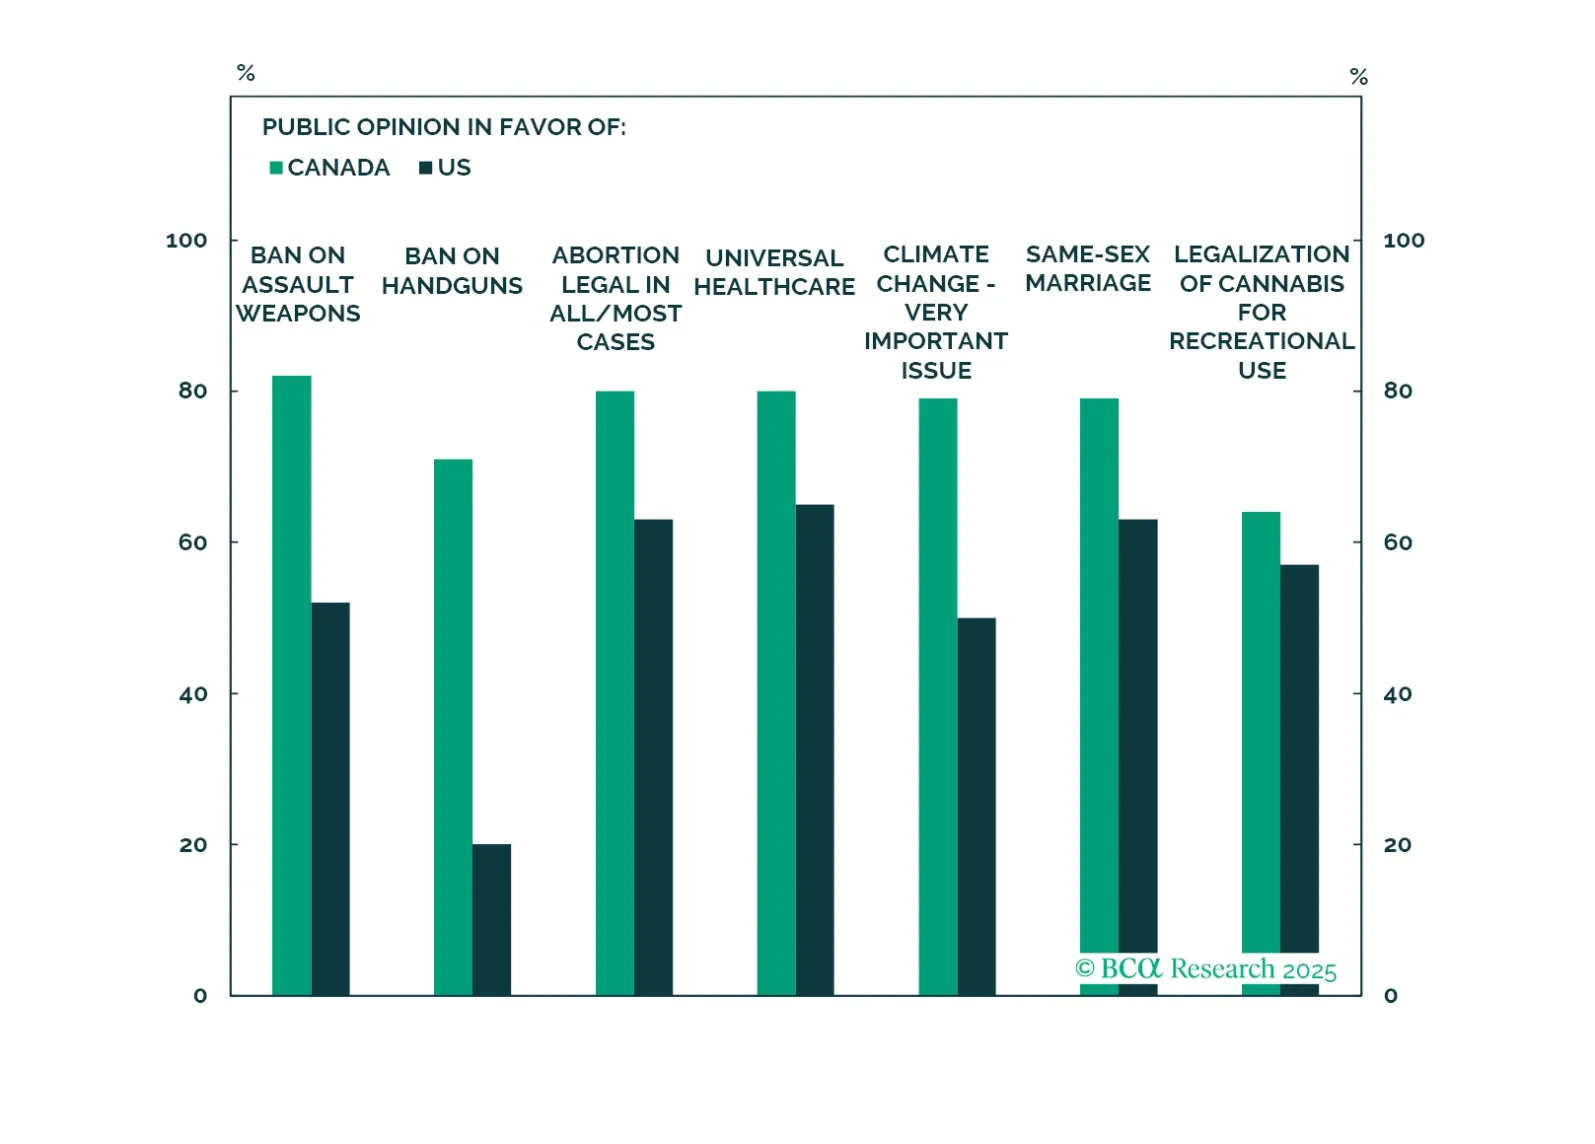
Special Report Should investors take seriously the possibility of Canada becoming part of the US? We strongly argue that such a union is not in the cards. Conservative America will fight it tooth and nail, despite President Donald Trump’s suggestions. There is no mythical “conservative Canada.” The entire country is as liberal as the state of Vermont, with Alberta only as conservative as Minnesota. However, in the very long term, the probability is not zero.
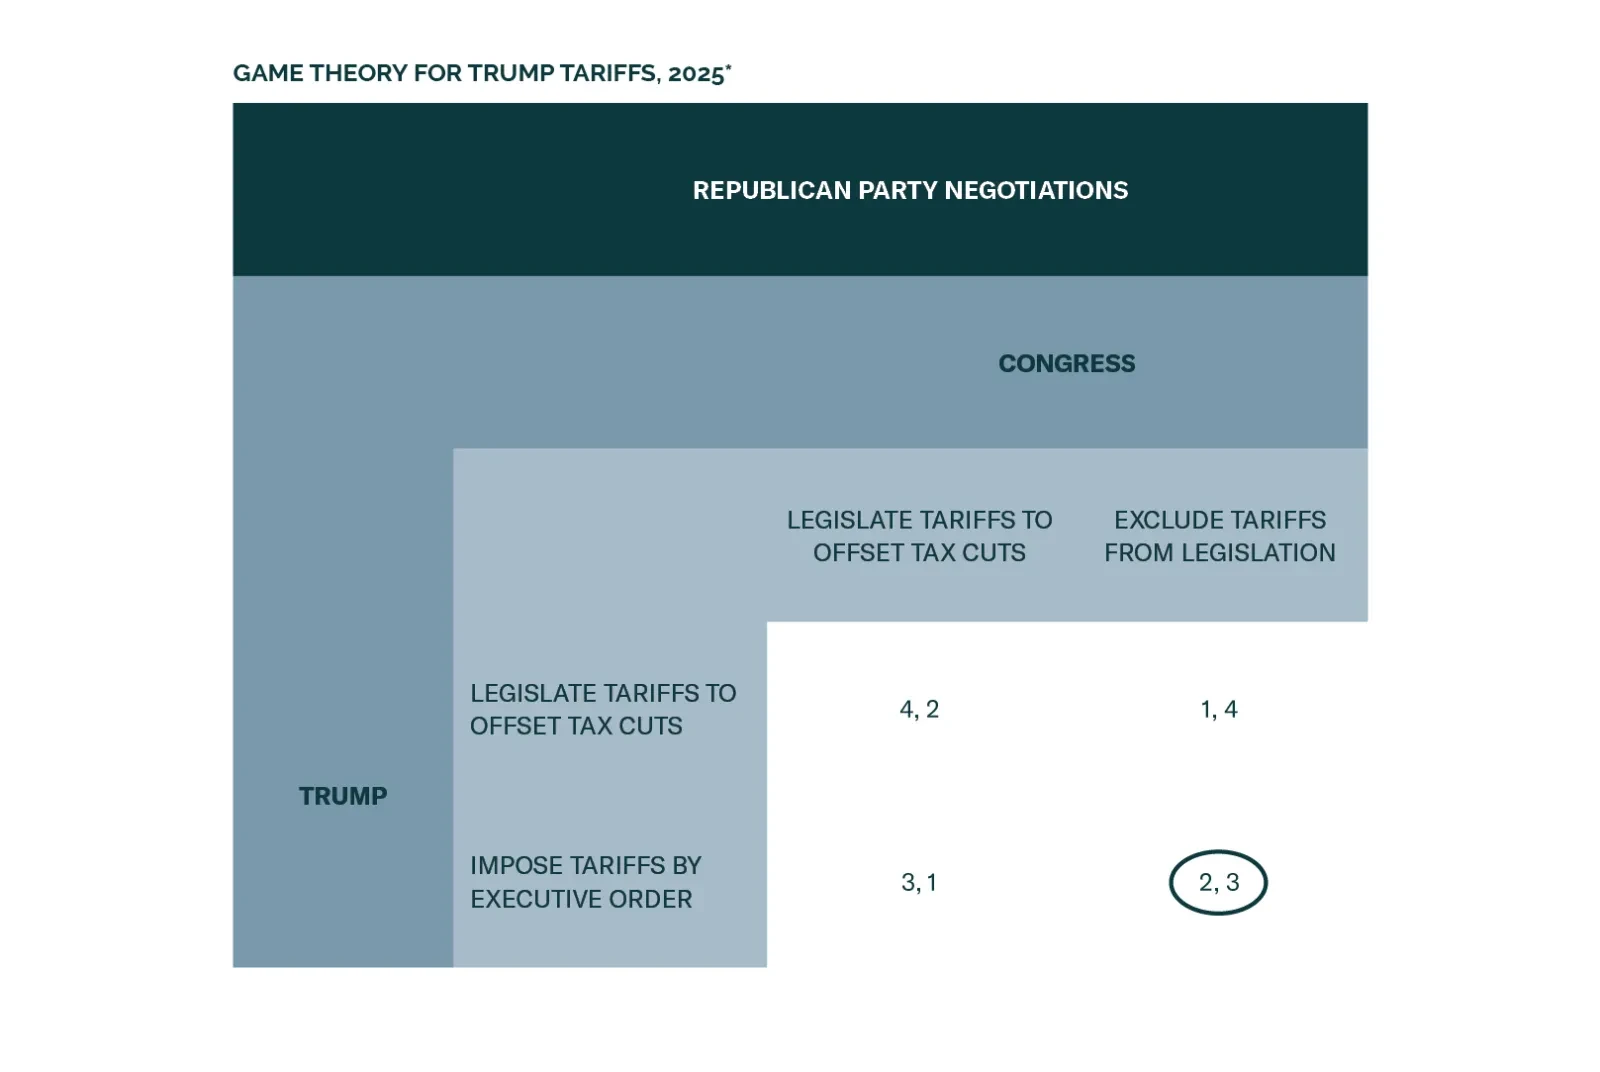
Special Report Simple games allow us to model several of the Trump administration’s most disruptive policies in 2025. We find that markets face an increase in volatility as Congress expands the budget, Trump implements tariffs on the world, China retaliates, and Taiwan tensions persist. A ceasefire in Ukraine is a marginally positive outcome for Europe, although it is not a long-term peace treaty.
Special Report In this Special Report, we share our “thoughts from the field,” gathered during a week of panels and conversations at the World Economic Forum in Davos. Our main takeaways include China’s rising global presence (despite its deceptive absence at the forum), the rising consensus on AI investment as the new corporate best practice, mounting stakes in the AI race, and the global shift toward MAGA-branded ideology as President Trump enters his second term. We also reflect on the surprising lack of geopolitical focus in the discussions and the forum’s broader role in the global geopolitical landscape.
Special Report There is no better way to gauge the macro policies of the new US administration than being privy to President Donald Trump’s discussions with the new Treasury Secretary, Scott Bessent. While we do not have inside information, we have put the pieces of the puzzle together to help clients see the big picture. This report presents our take on a hypothetical conversation between President Trump and Scott Bessent that led to the latter’s appointment as Treasury secretary.
President Trump is only the second president to have won, lost, and won again in US history, so today’s inaugural address was unlike any other since Grover Cleveland in 1893.
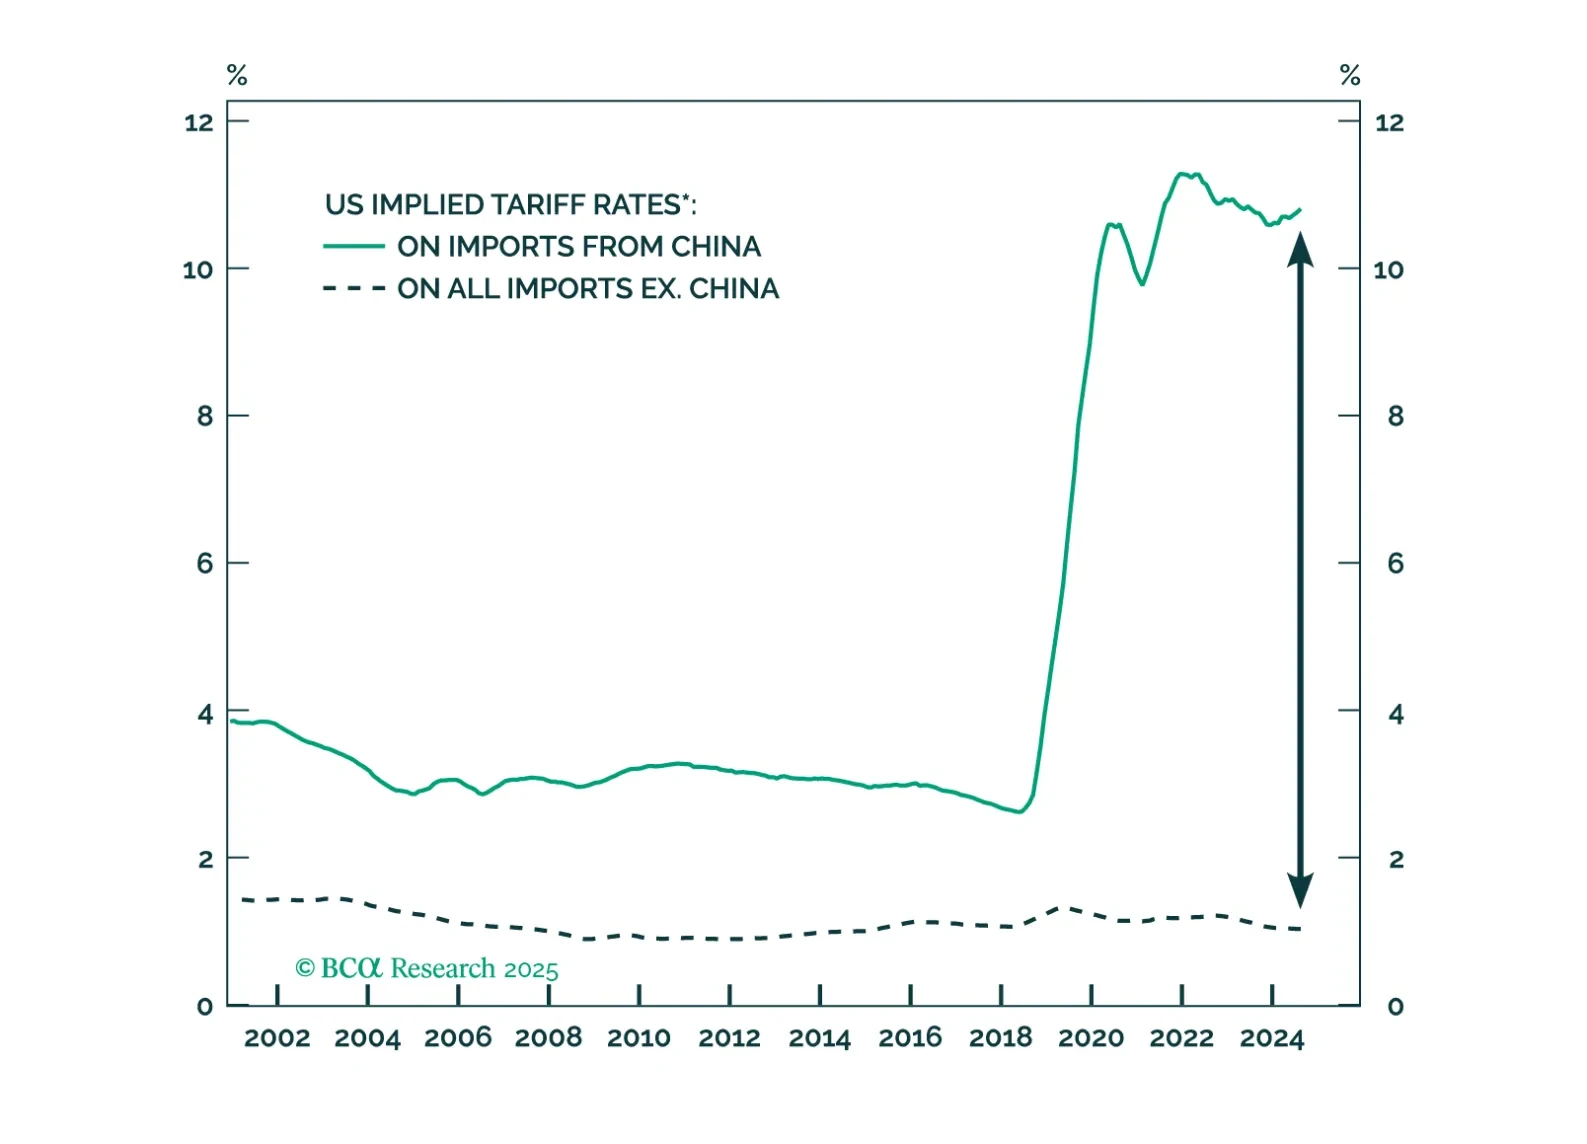
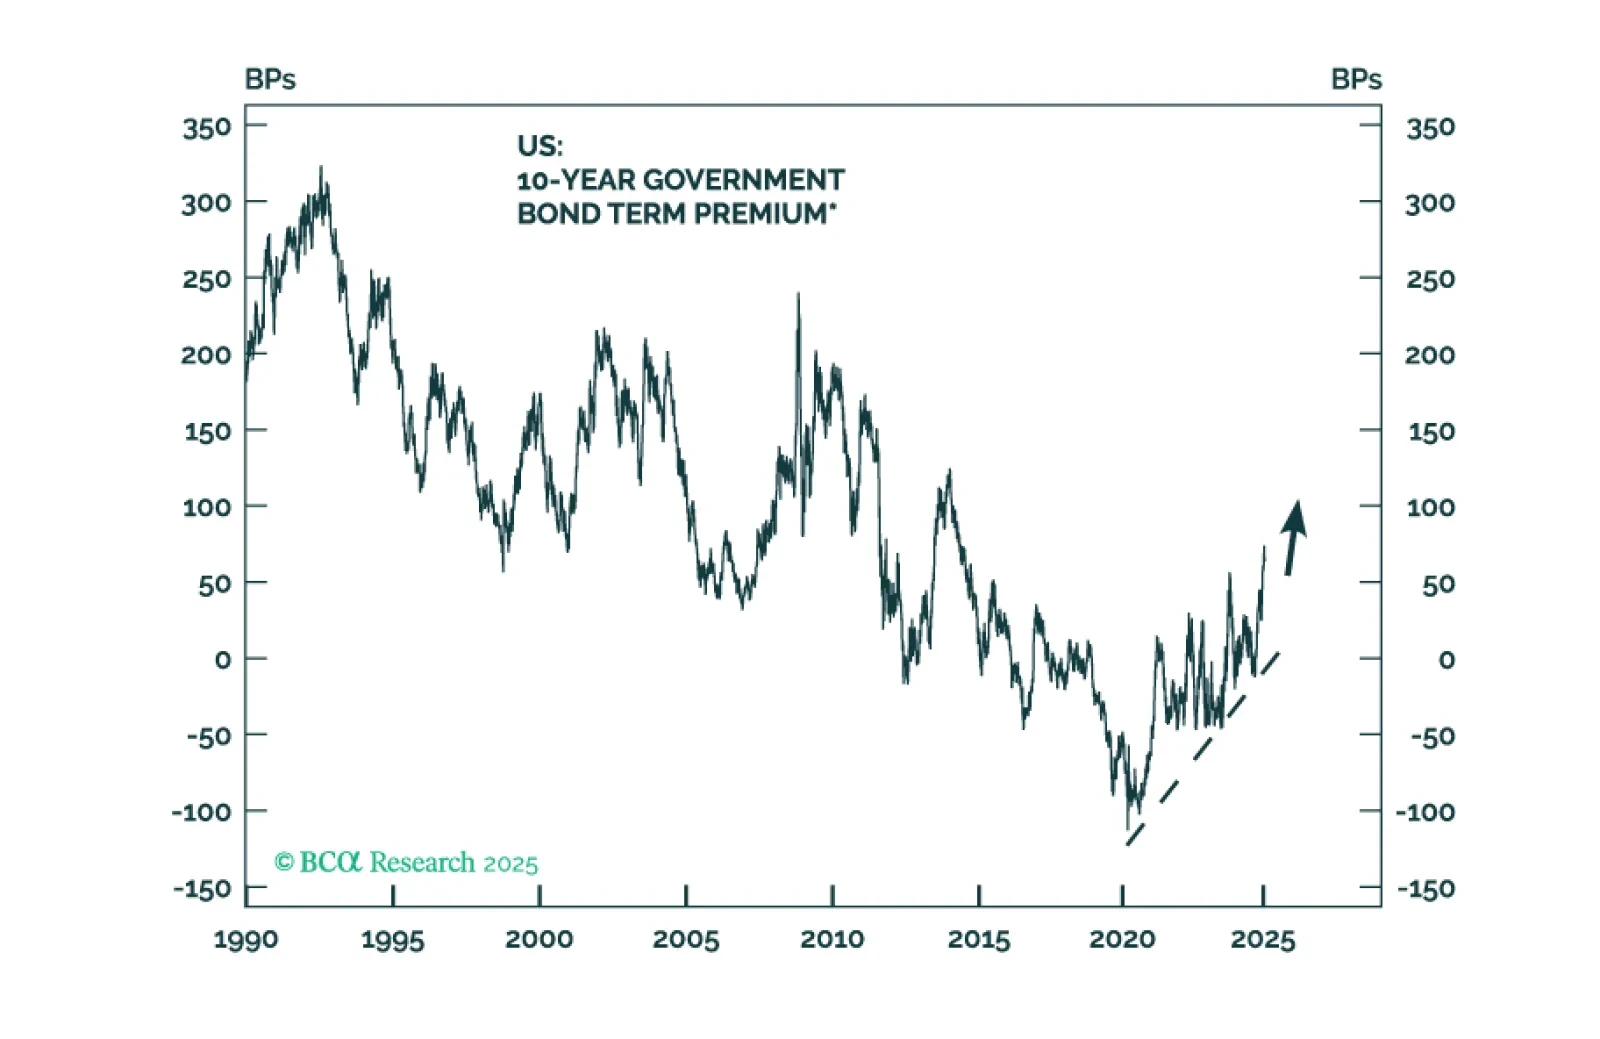
Special Report Inauguration Day or shortly thereafter will see either a global tariff of 10% or targeted but substantial tariffs on China, Mexico, and Canada. Treasury yields will rise on tax cuts, the dollar will stay strong, yet oil will also continue to rally, causing equity volatility in the near term.
This month, our Here, There, And Everywhere chartpack reiterates our main thesis for 2025: the three main narratives driving markets today – fiscal profligacy, trade war, and geopolitical conflict – will peak at some point in 2025. Why does this matter? All three have been tailwinds to US assets, and their peak should help usher in the peak in US outperformance relative to RoW. We conclude with some slides on our bullish Europe thesis.