 GeoMacro | Tactical Risks & Opportunities
Near-term geopolitical analysis, focused on the 0-3 month horizon. Publication frequency shaped by urgent global events.
There is no evidence that there is a run on US government bonds. All the data at our disposal, and the curated views of our bond specialists, suggest that the US bond market may have 99 problems, but a coordinated run on its safe haven status is not one.
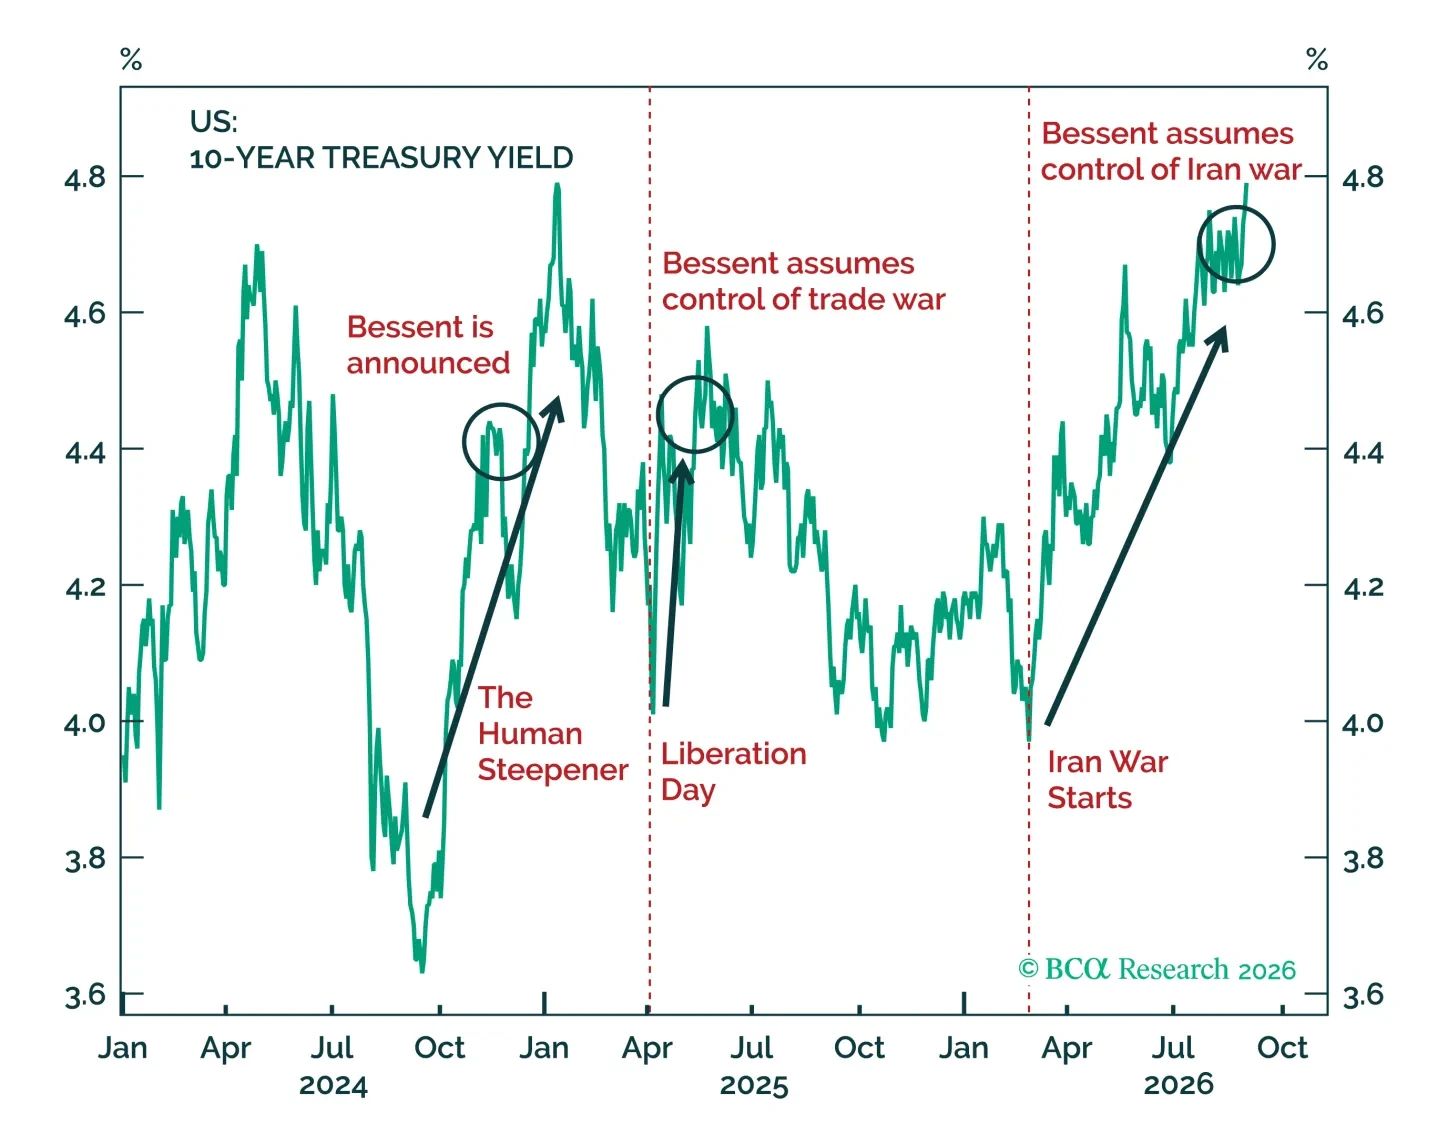
Markets have become obsessed with the rise of global long-dated yields. To some extent, we agree with the concern. Bonds are trading on "vibes," alarmed by the incoherent US geopolitical policy. Oil prices are obviously the conduit between that policy and the markets. On the other hand, growth is also robust. As such, bond market selloff is not all just negativity. The one secular theme driving the bond market selloff that does not bother us all that much is fiscal policy. We see signs — including actual budget deficit data! — that the US, policymakers and voters alike, is starting to understand that there are limits to profligacy. As such, we would advise clients with a long term focus to begin nibbling at the hated bonds.
Our colleague Matt Gertken has penned a sober analysis on the midterms, calling for a Democratic Party sweep in 2026. It is a measured, data-driven, analysis that we encourage you to read. This quick Insight is neither sober nor data driven. It is hyperbolic and based on “vibes.”
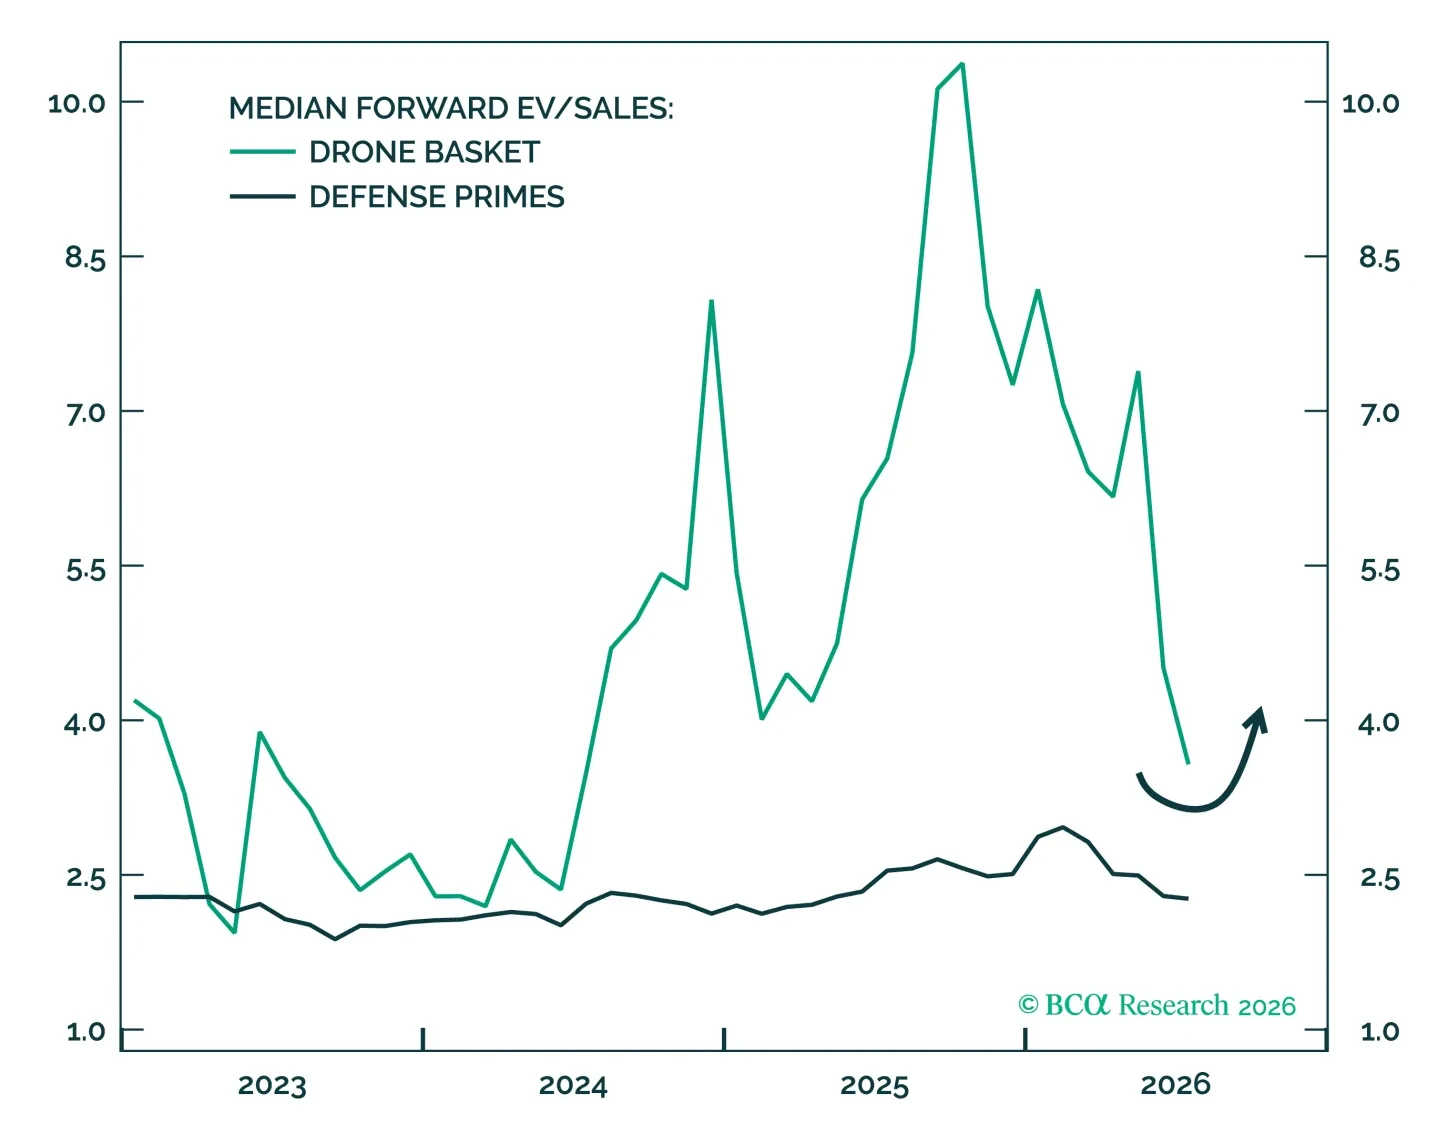
US aerospace and defense stocks still have a structural tailwind from geopolitics, but face rising cyclical challenges from macro and market fundamentals, as well as eventual Iran and Ukraine ceasefires and political change in the United States.
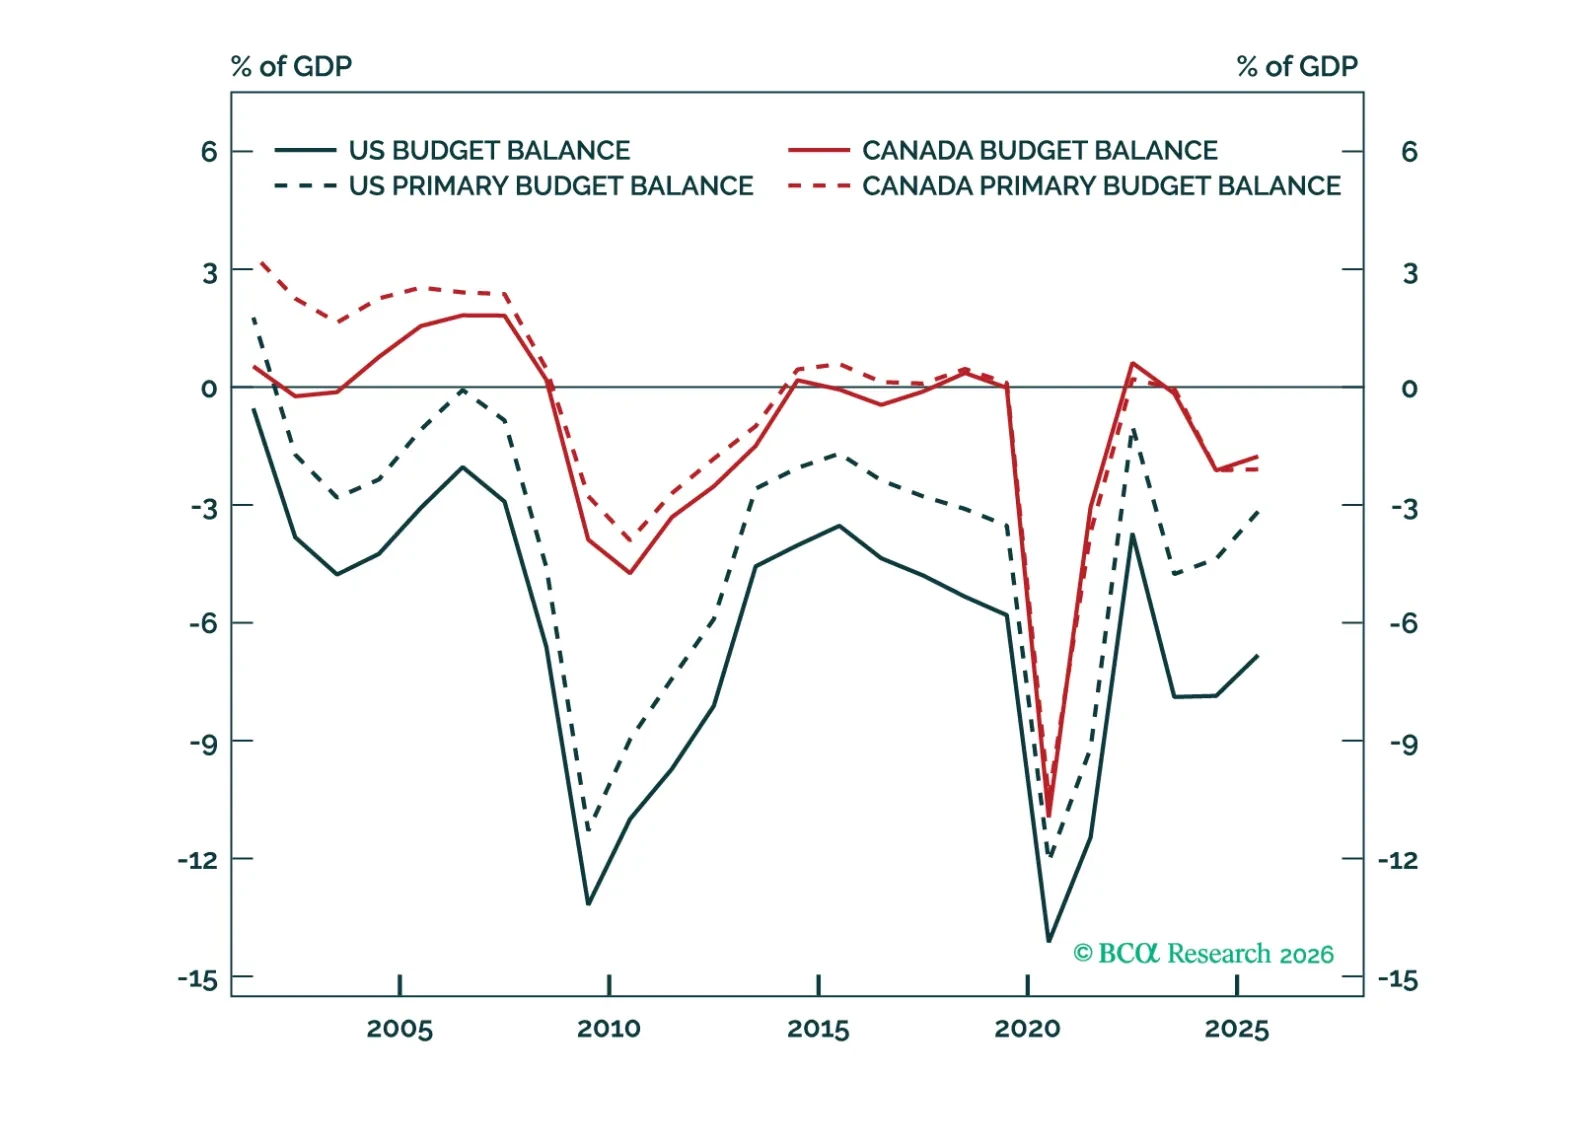
Canada may welcome a trade skirmish with the US. It has ample fiscal room with which to retaliate and its domestic political calculus – with bubbling risk of secession – means that fighting an external threat is a boon, not a bore.
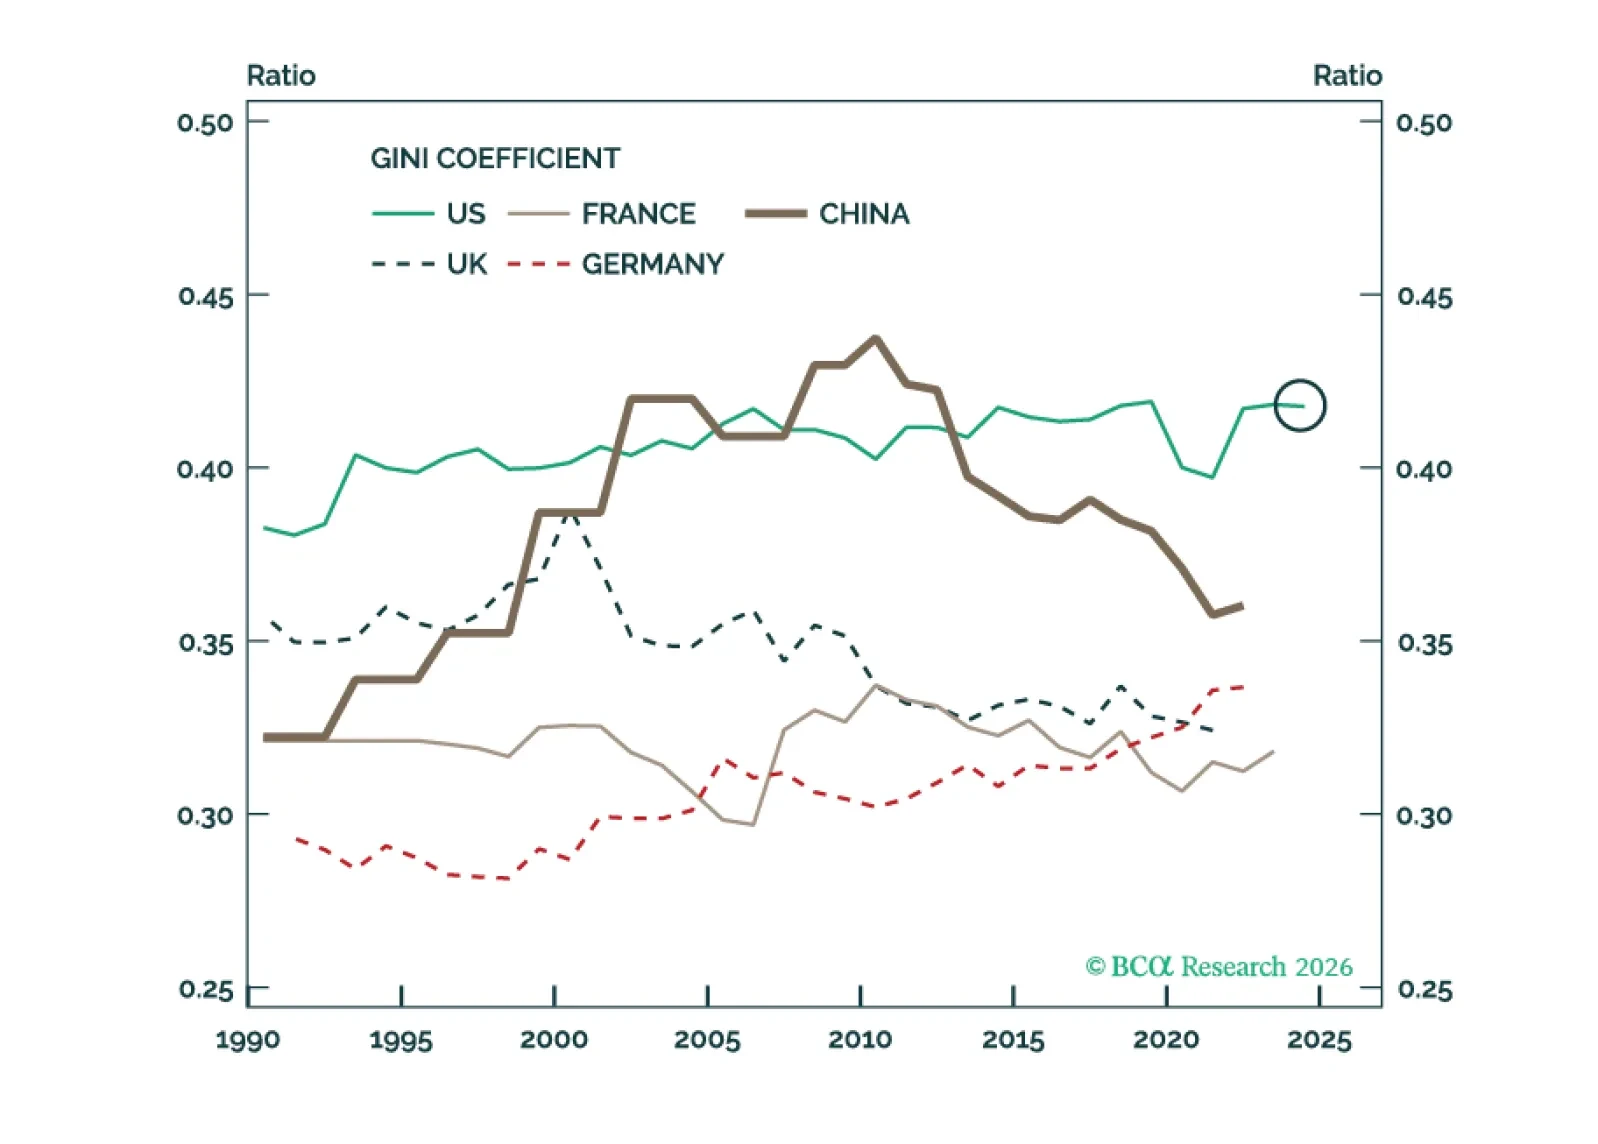
Left-wing populism will likely prevail within the Democratic Party and inspire large tax hikes in 2029. But the US does not face a socialist takeover.
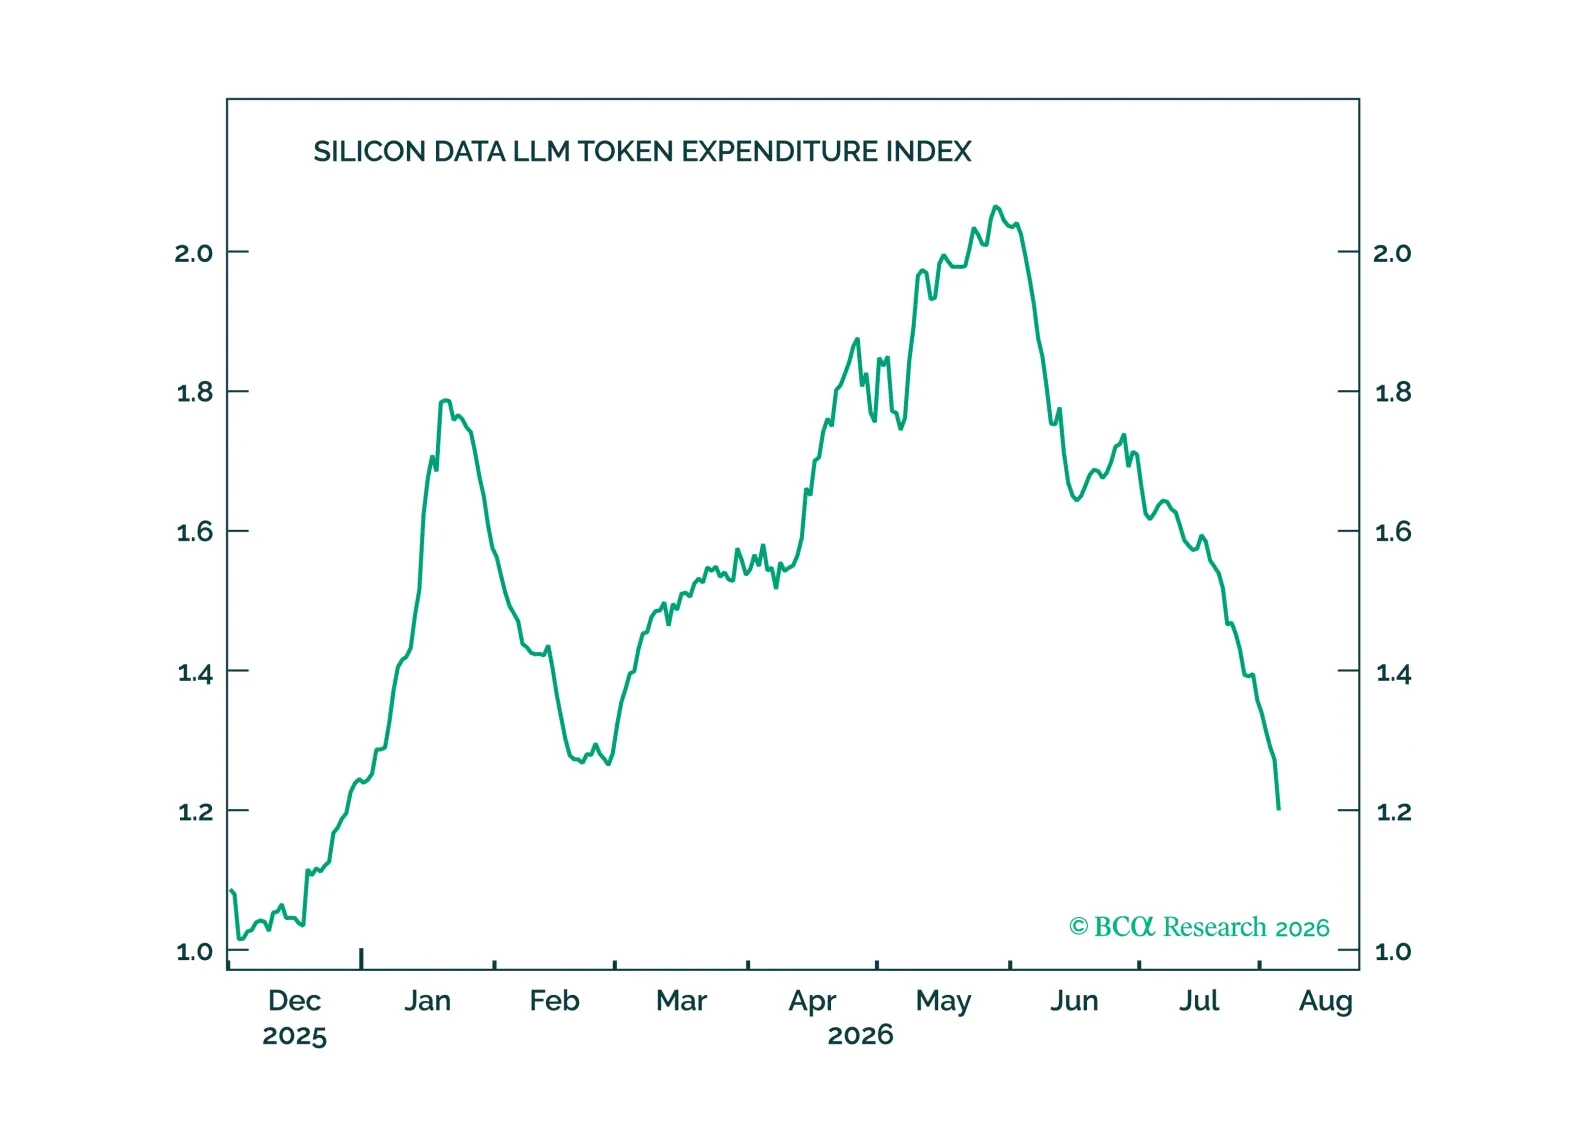
We remain tactically bullish due to the combination of geopolitical risks in the Middle East easing and the ramping up of the AI boom. In this month’s chartpack, we articulate the reasoning behind both sanguine views.
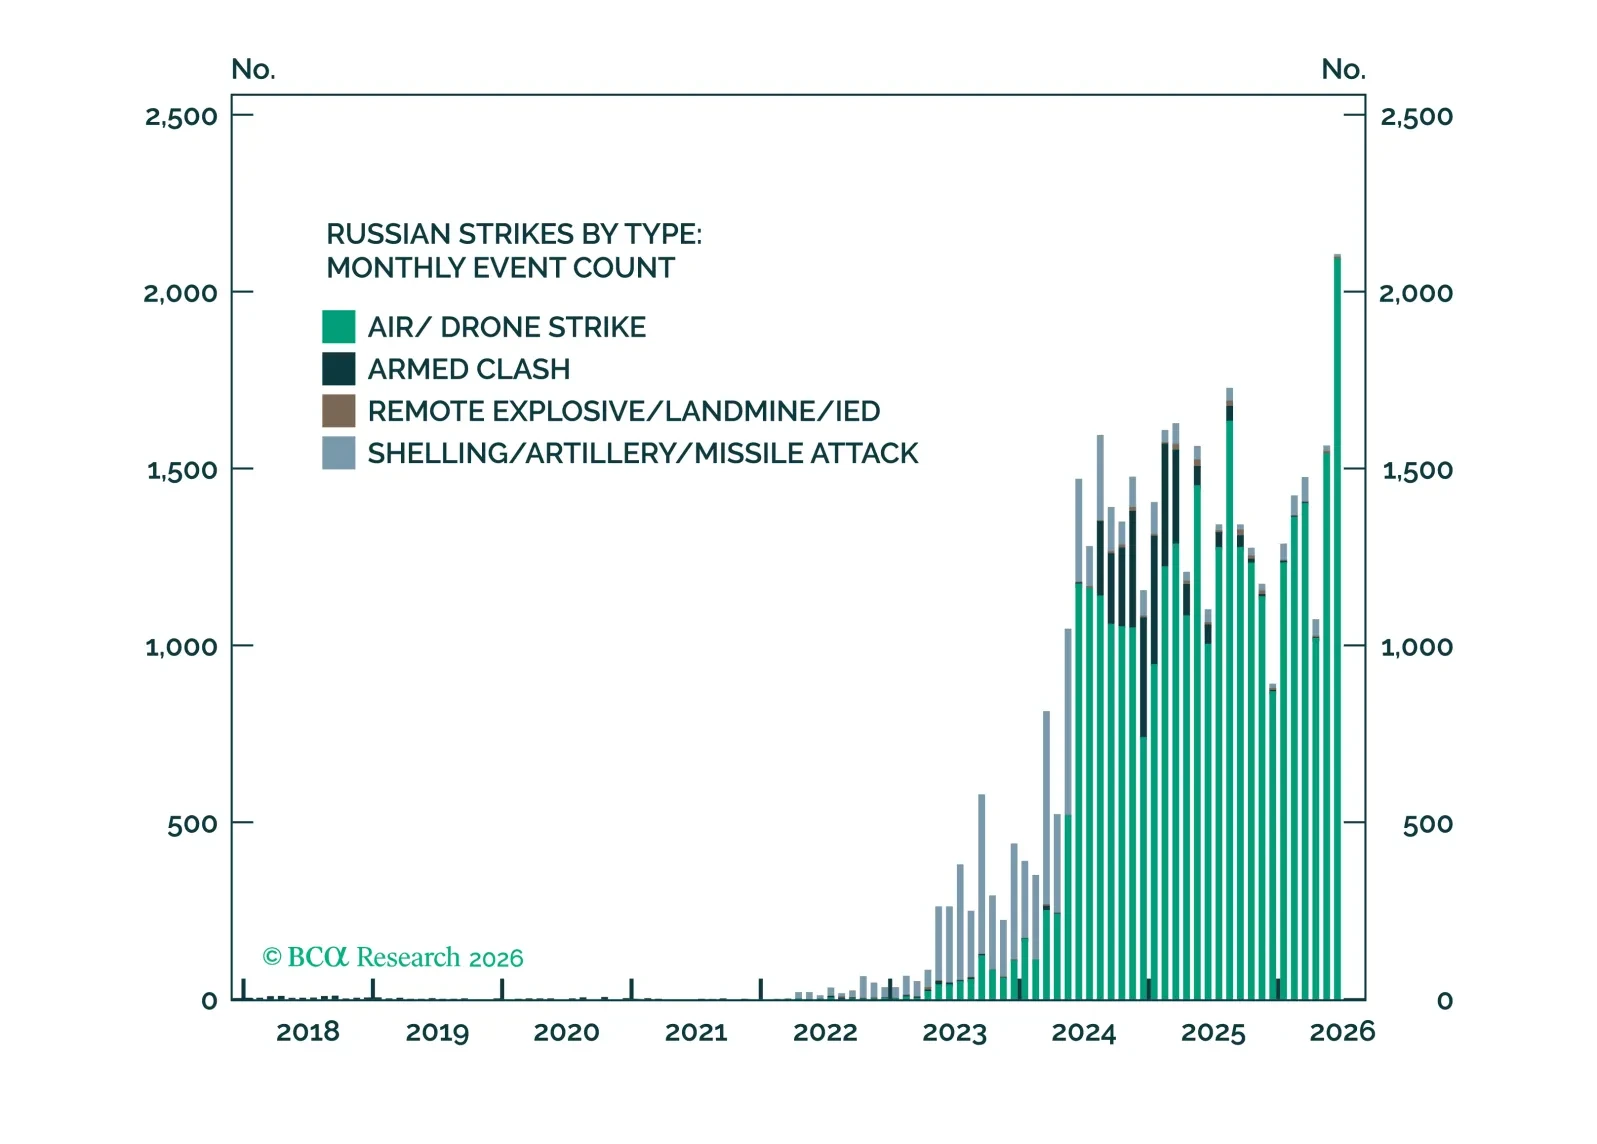
The fragile balance in the Ukraine war has broken – the conflict can escalate and take investors who are focused on Iran by surprise.
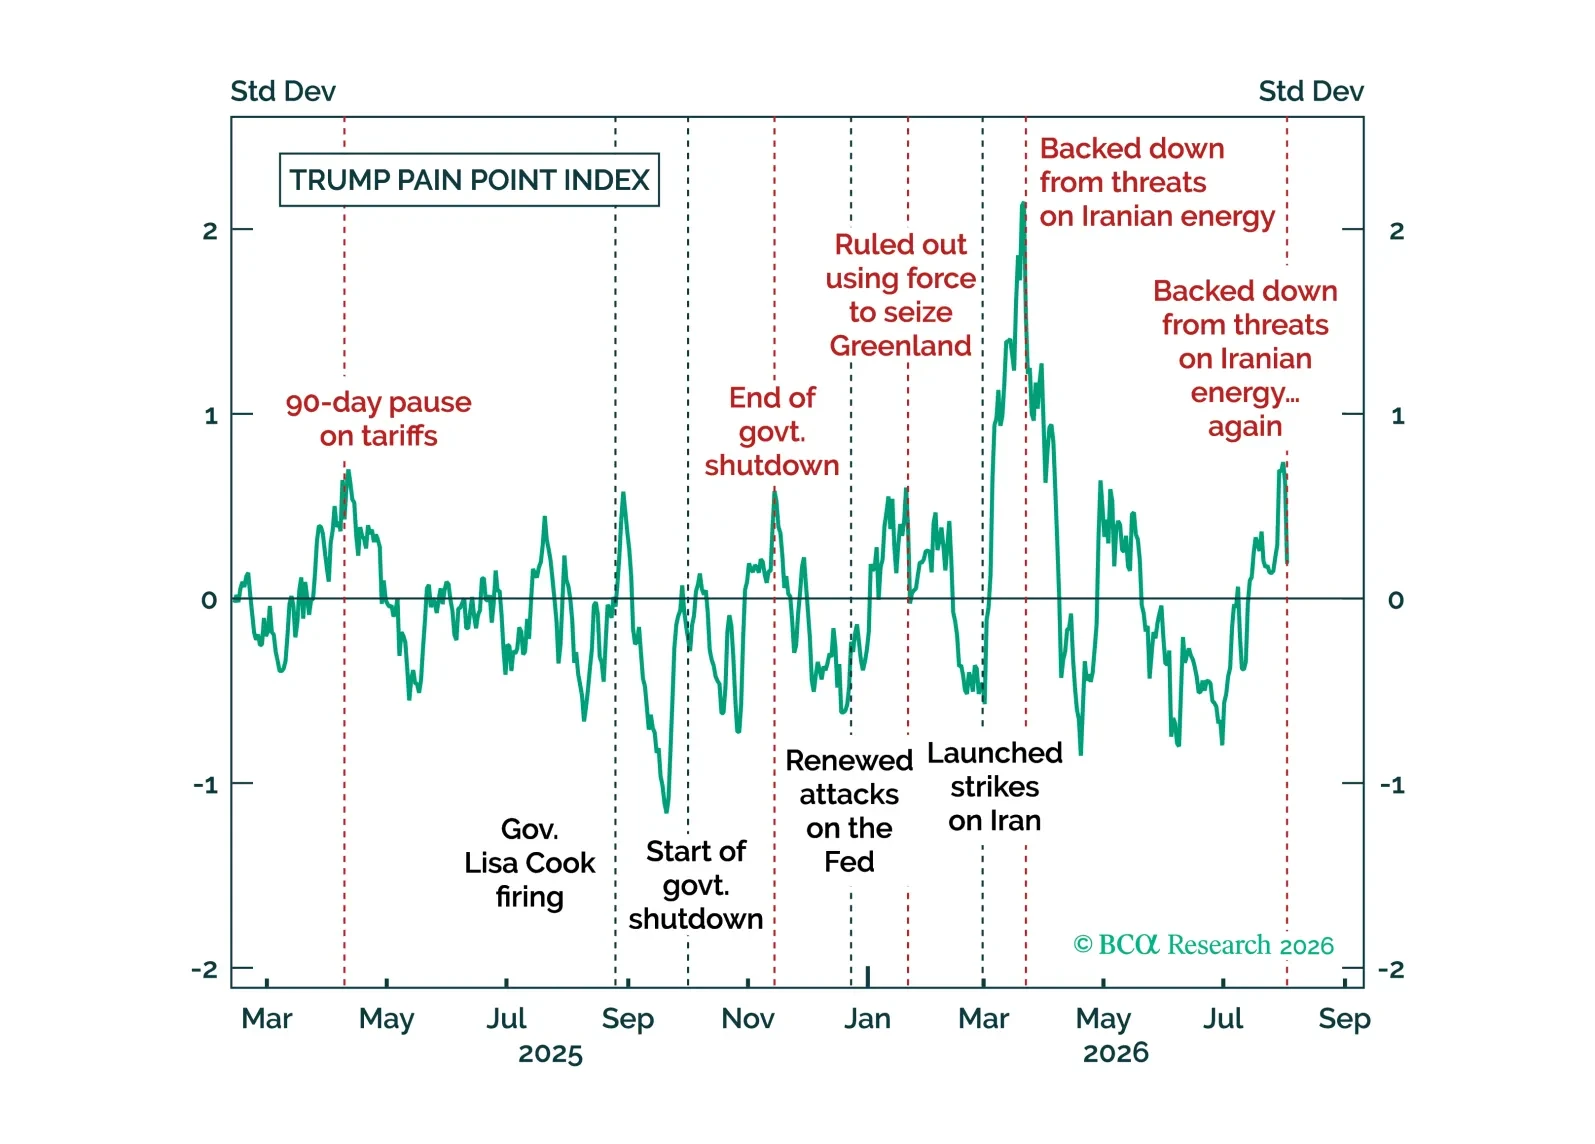
Last month we "stuck our neck out" and reaffirmed our bullishness towards risk asset. This month, we have confirmation that the risky bet is paying off. Iran and the US remain materially constrained from total war. The AI capex thesis is holding up and slowly mutating into a price war that will only boost adoption and necessitate more investment. We open a new AI-related trade (long hard disk makers) and go long gold.
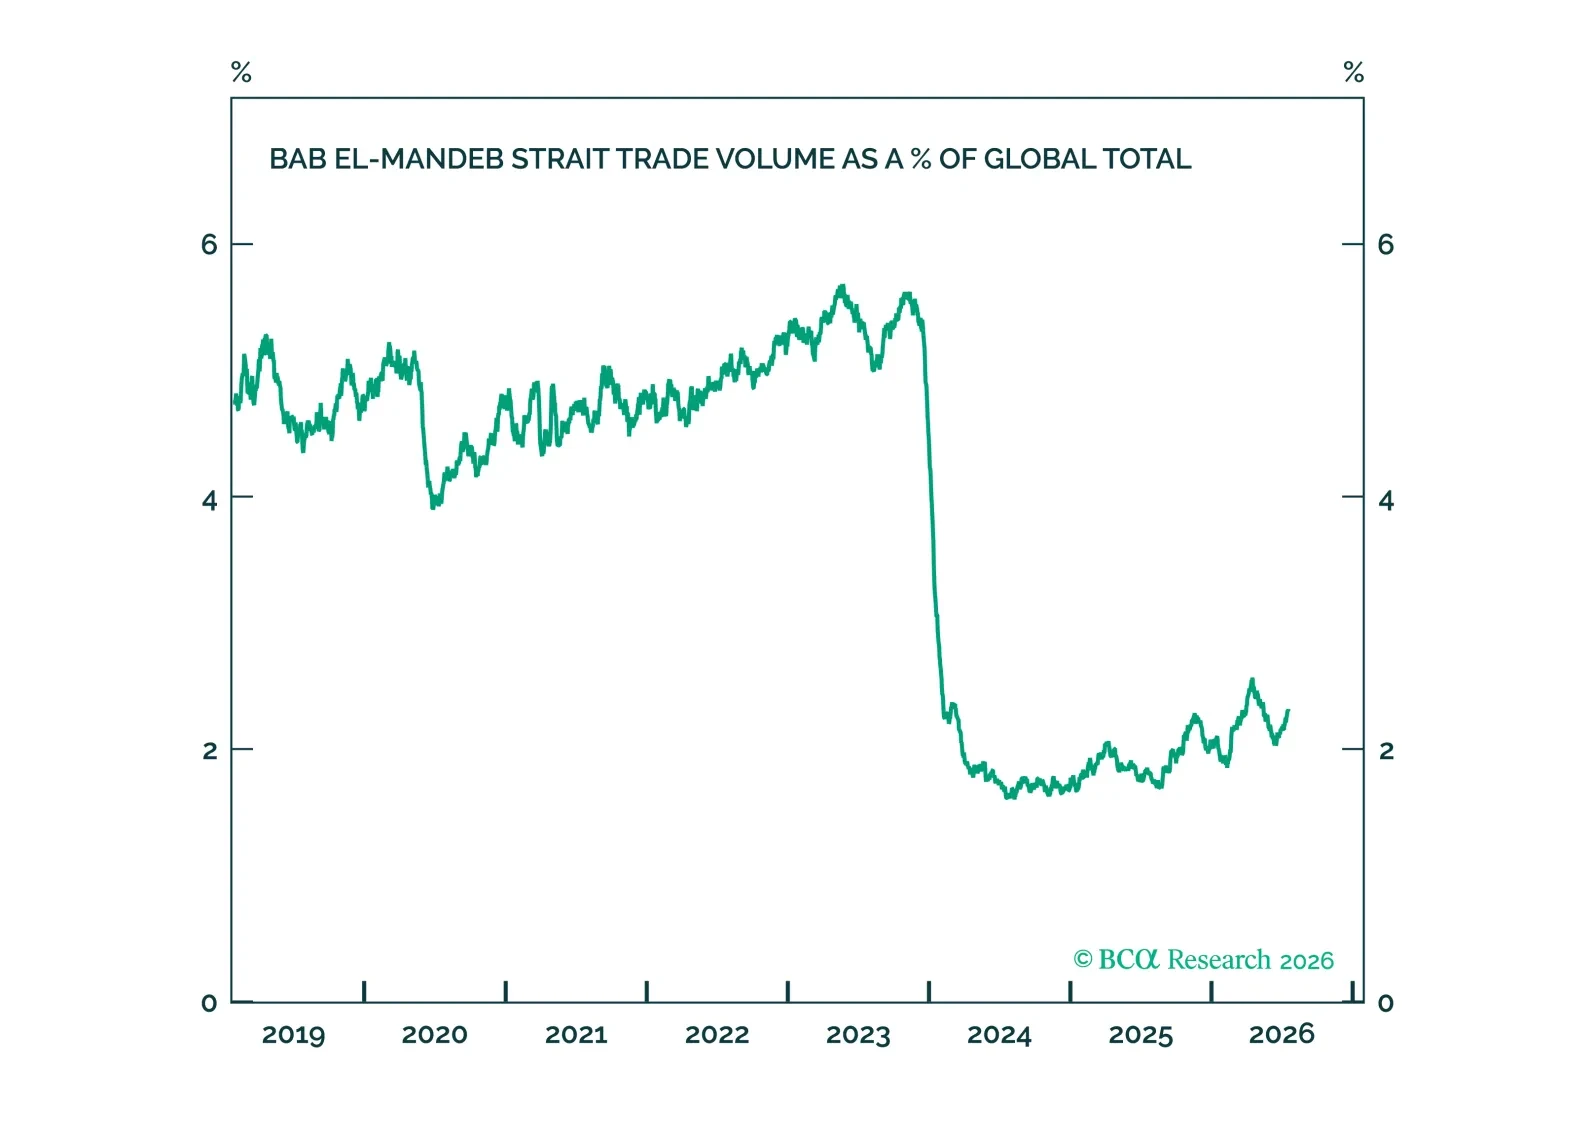
The Strait of Hormuz is a unique geographical feature. Other than the Bosporus and Dardanelles Straits that allow passage between the Mediterranean and the Black Sea (via the Sea of Marmara), there are very few other such, economically valuable, choke points. What many armchair geopolitical strategists consider “critical” naval routes – Strait of Malacca, Panama Canal, Suez – are really just pathways of convenience. “Nice to haves” – in that they significantly reduce sailing times – as opposed to the “must have” that is Hormuz.