 Explore FICC
FICC | Bonds
Actionable asset allocation recommendations for your bond portfolio, drawing on macro analysis of interest rates and global debt market dynamics. Typically published weekly.
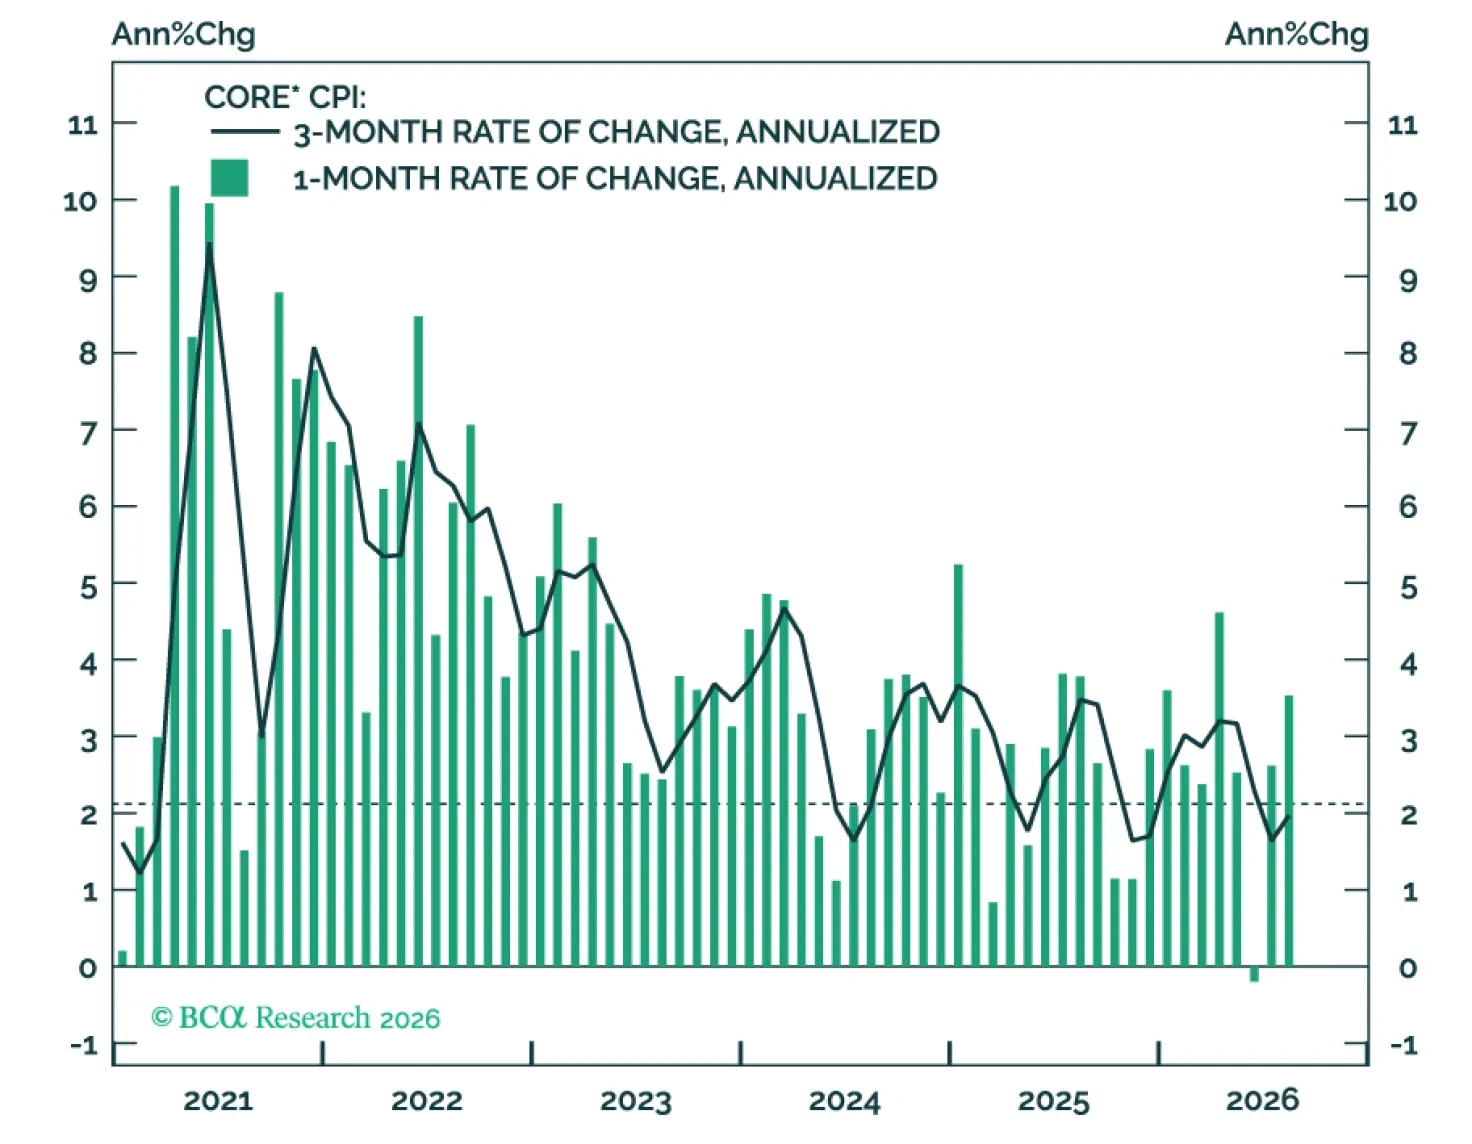
August’s 0.3% increase in core CPI breaks inflation’s 3-month downtrend and is likely hot enough for the Fed to hike rates when it meets next week.
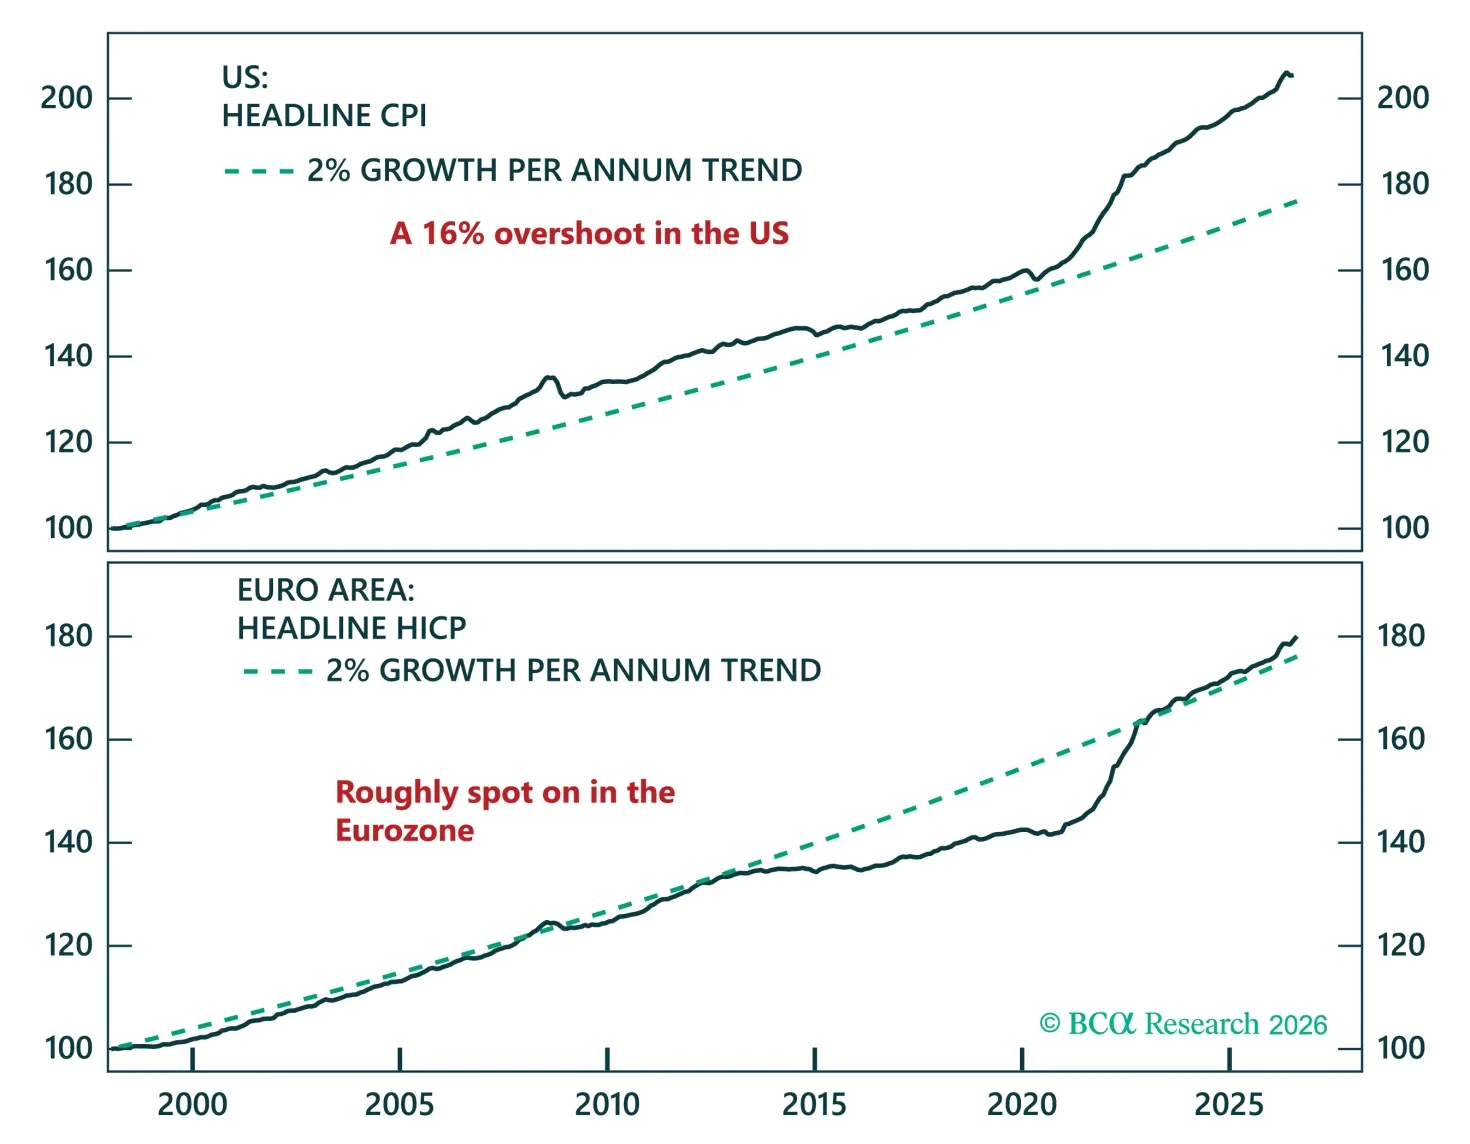
The ECB is winning, and almost nobody's pricing it in. A flatter Phillips curve, a shrinking term premium, a euro built to shrug off France, credibility is the trade.
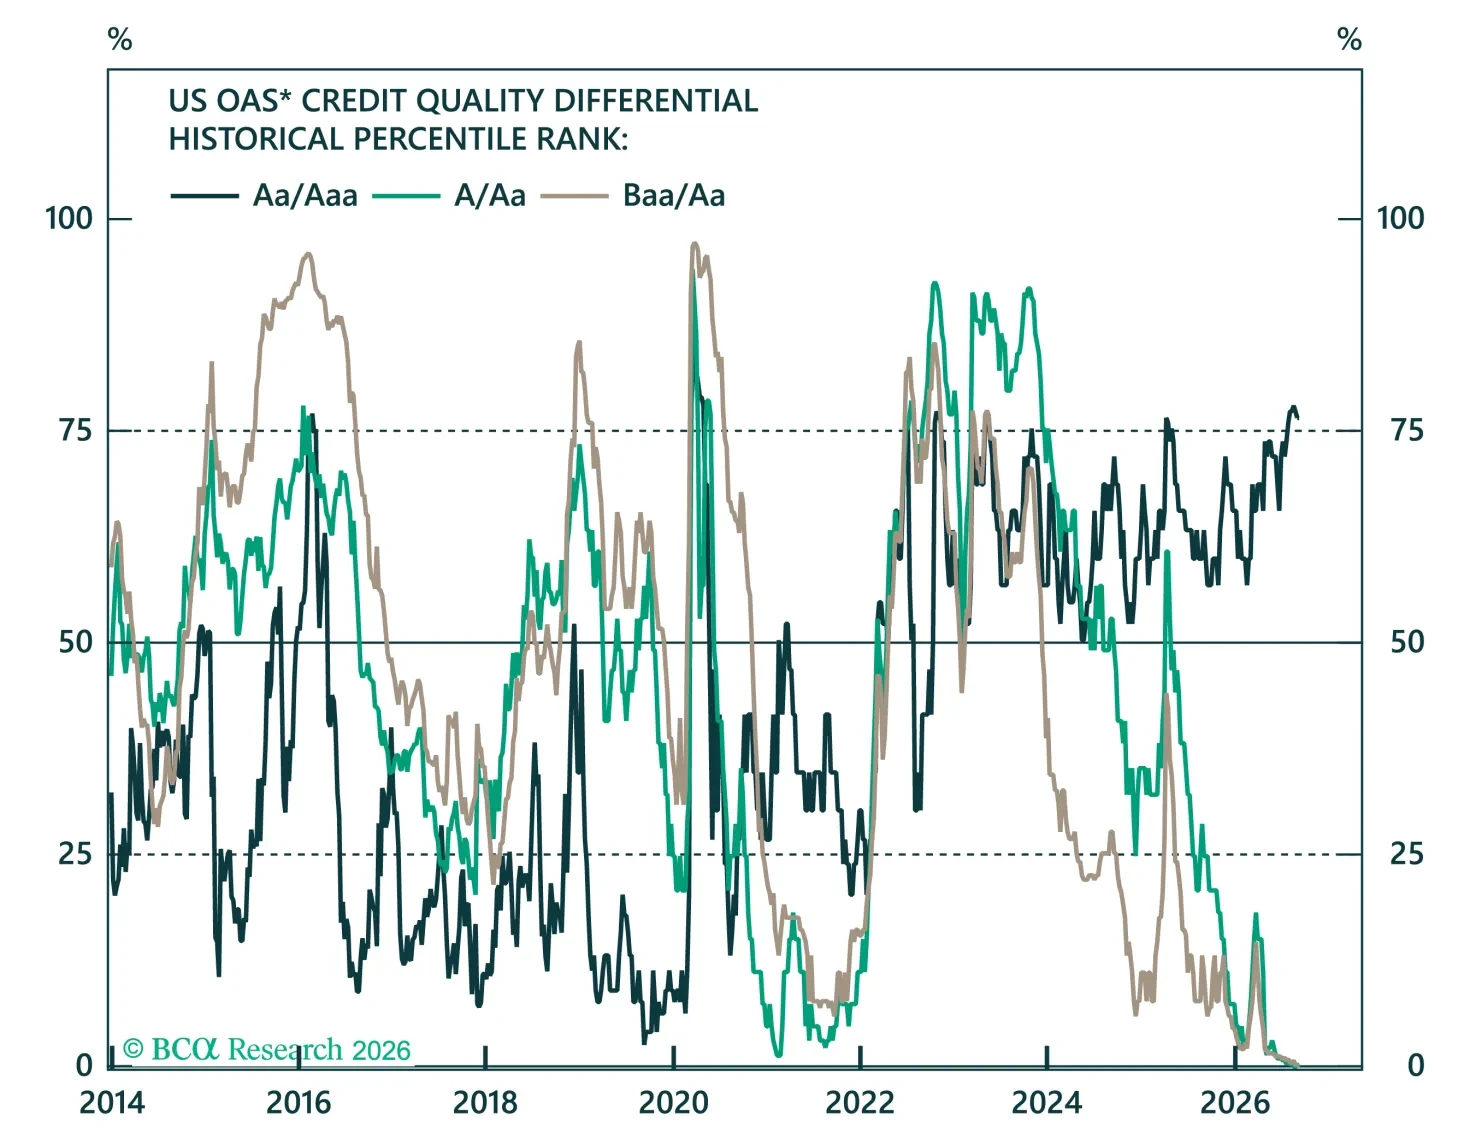
After two weeks on the road talking to investors across ANZ and India, this report addresses the questions that came up most: from investment grade issuance concerns to the selloff at the long end, and what's really driving JGBs, the yen, and the outlook for Australian and New Zealand rates.
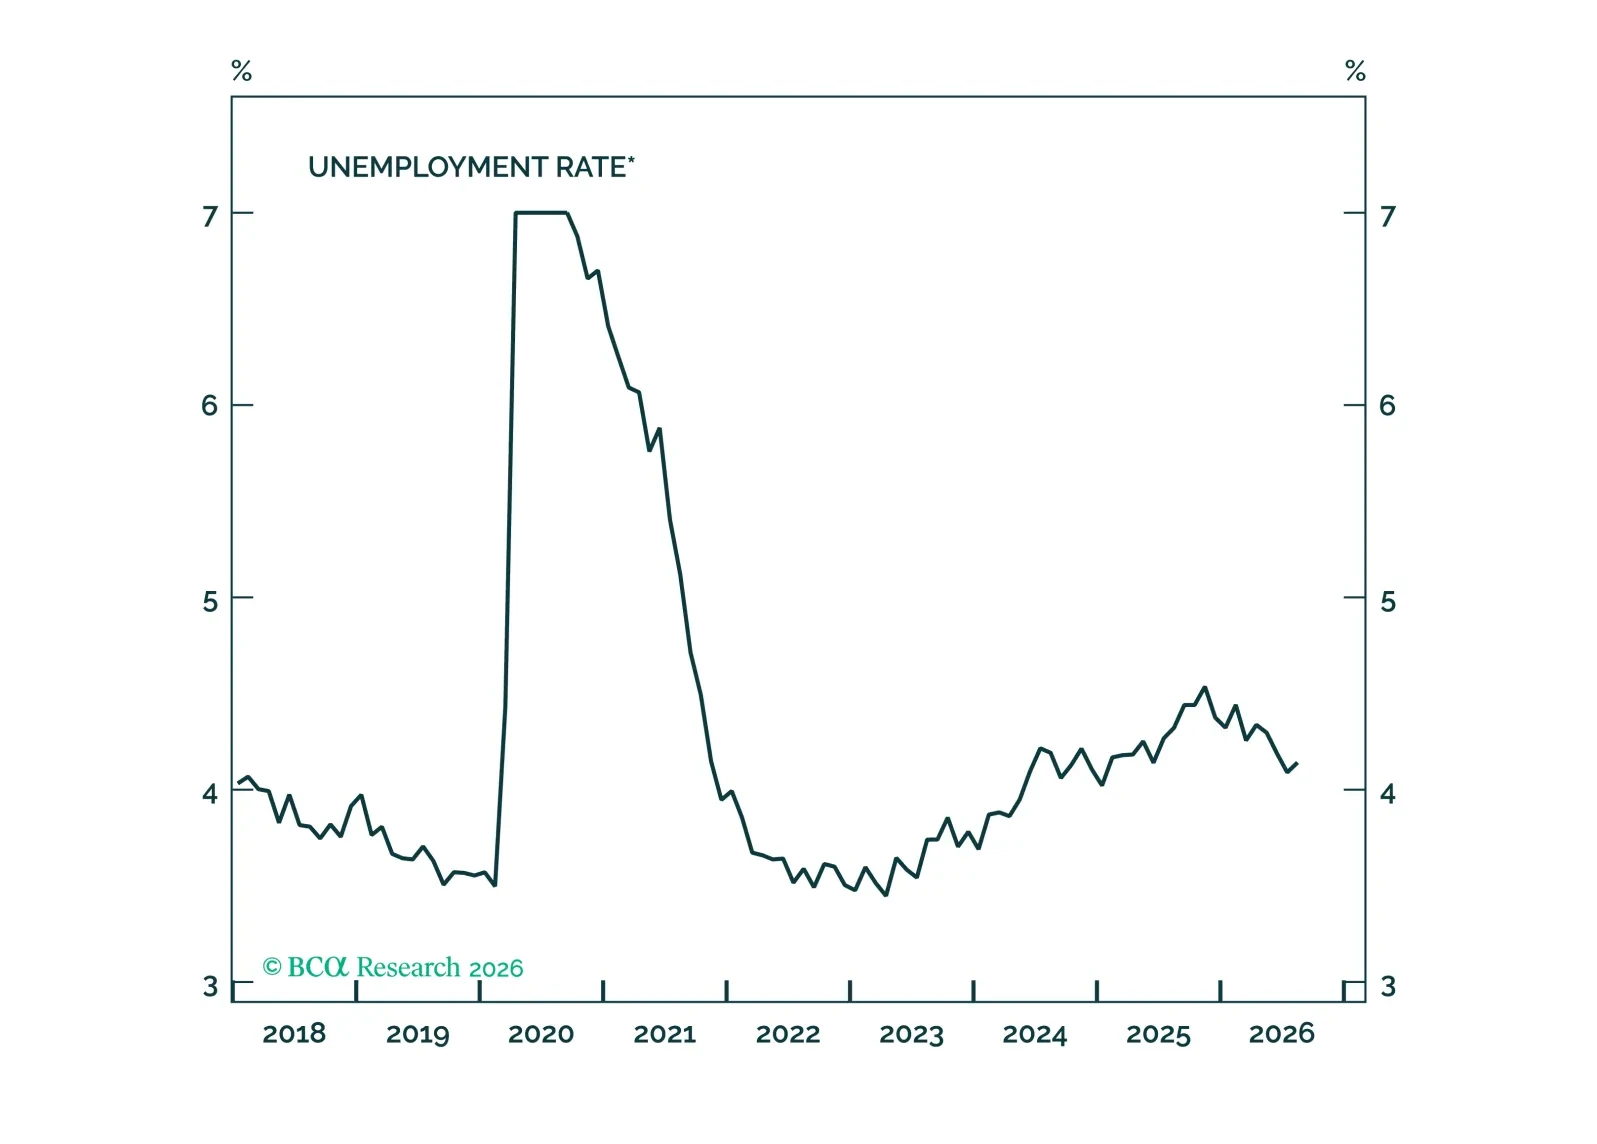
Next week’s CPI and PPI reports will be much more important determinants of the near-term Fed policy path than this morning’s employment report. However, if the trend of labor market tightening continues through year-end, it could lead to a re-acceleration of wage growth in 2027.
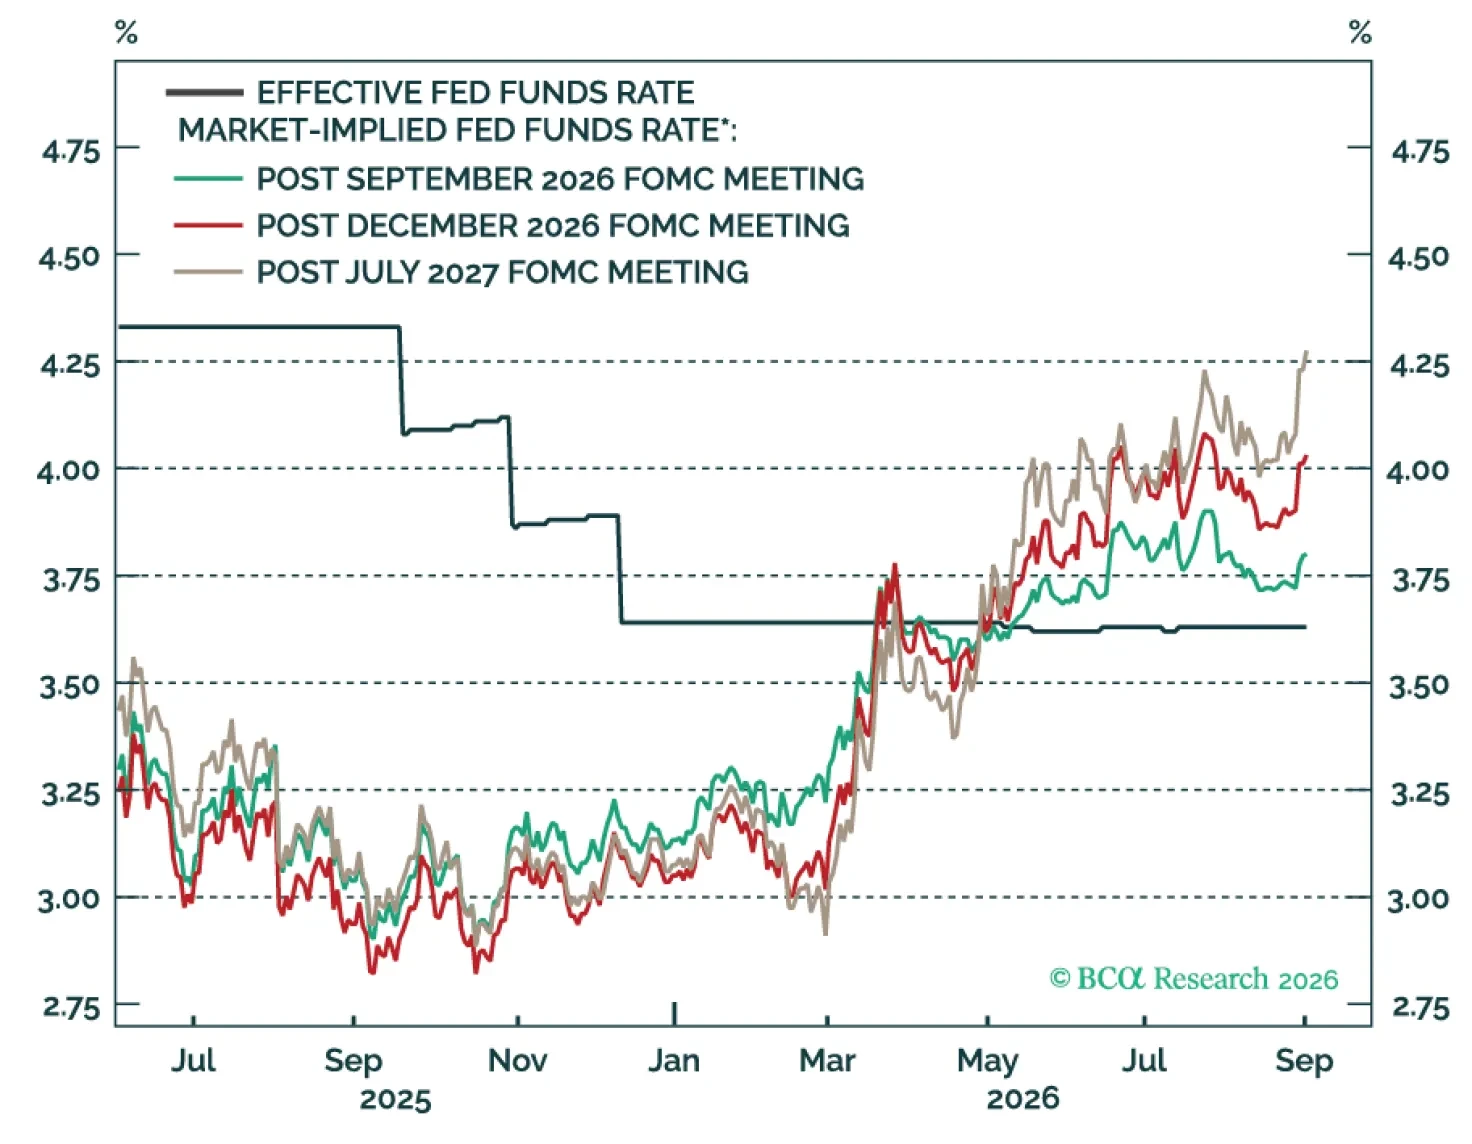
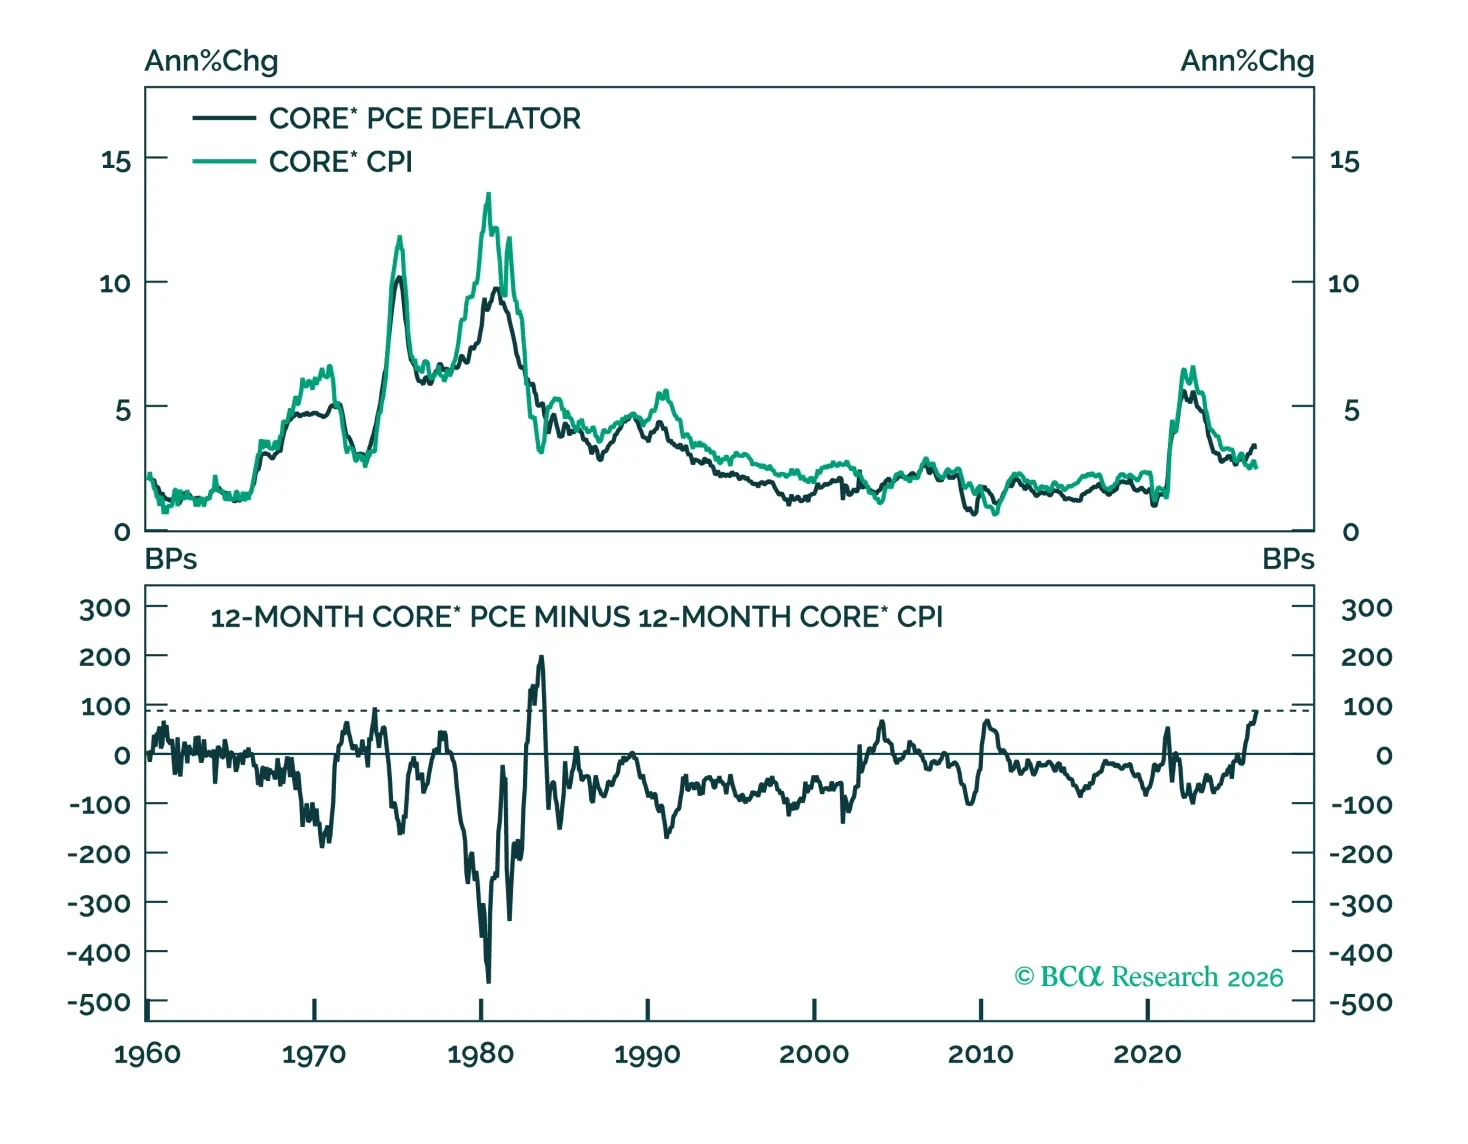
The PCE/CPI gap is an increasingly important factor driving the near-term outlook for Fed policy. We discuss the drivers of that gap and conclude that it’s likely to narrow in the coming months.
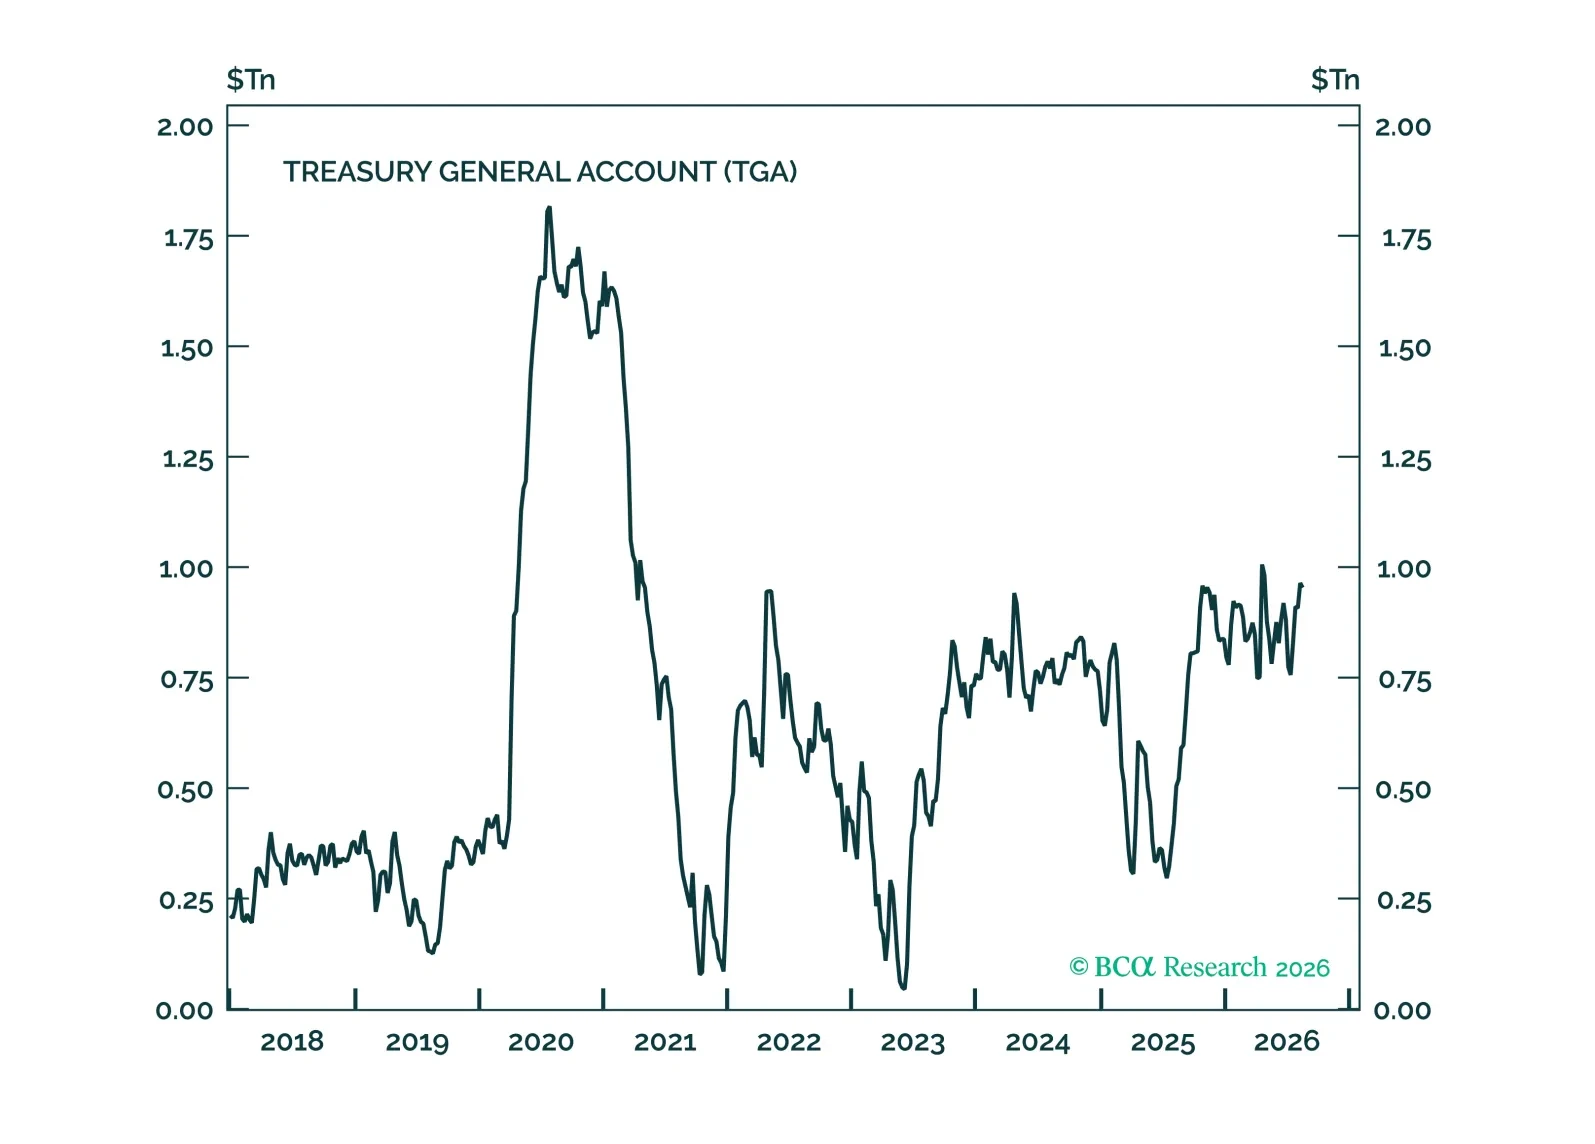
The US Treasury department’s attempts at yield suppression are doomed to fail unless the Federal Reserve gets involved.
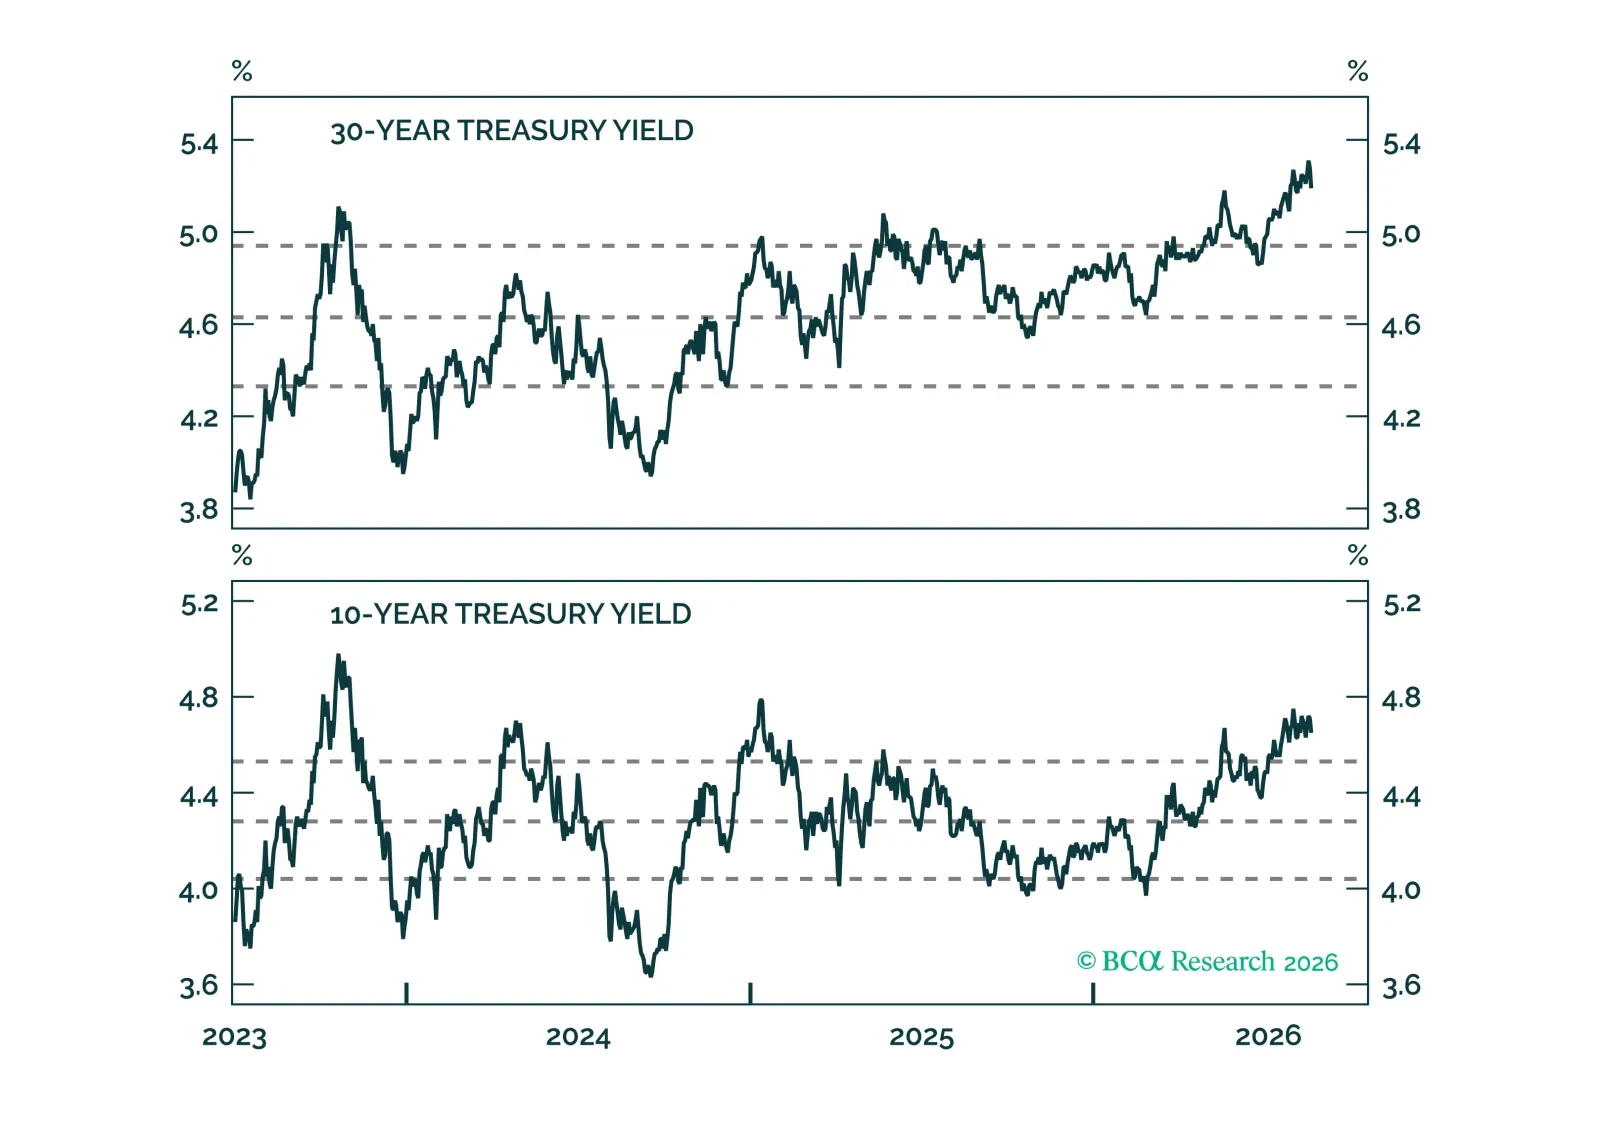
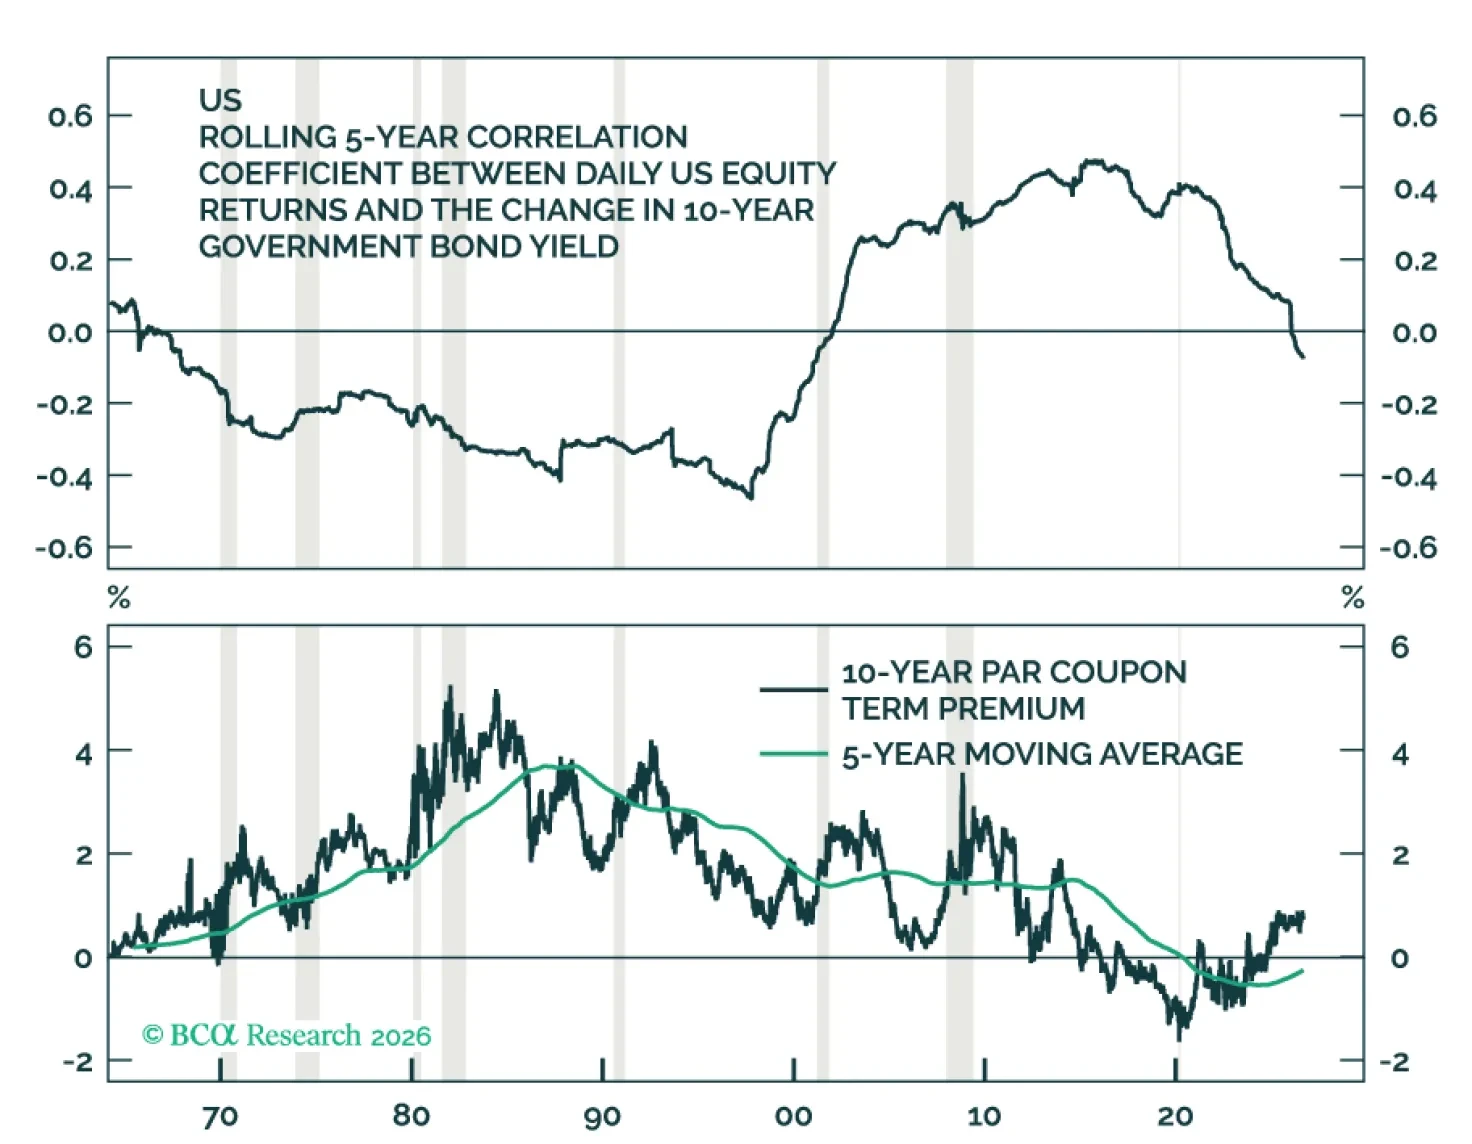
Despite recent increases, long-maturity Treasury yields are roughly consistent with fundamental fair value. We see limited value in long duration plays.
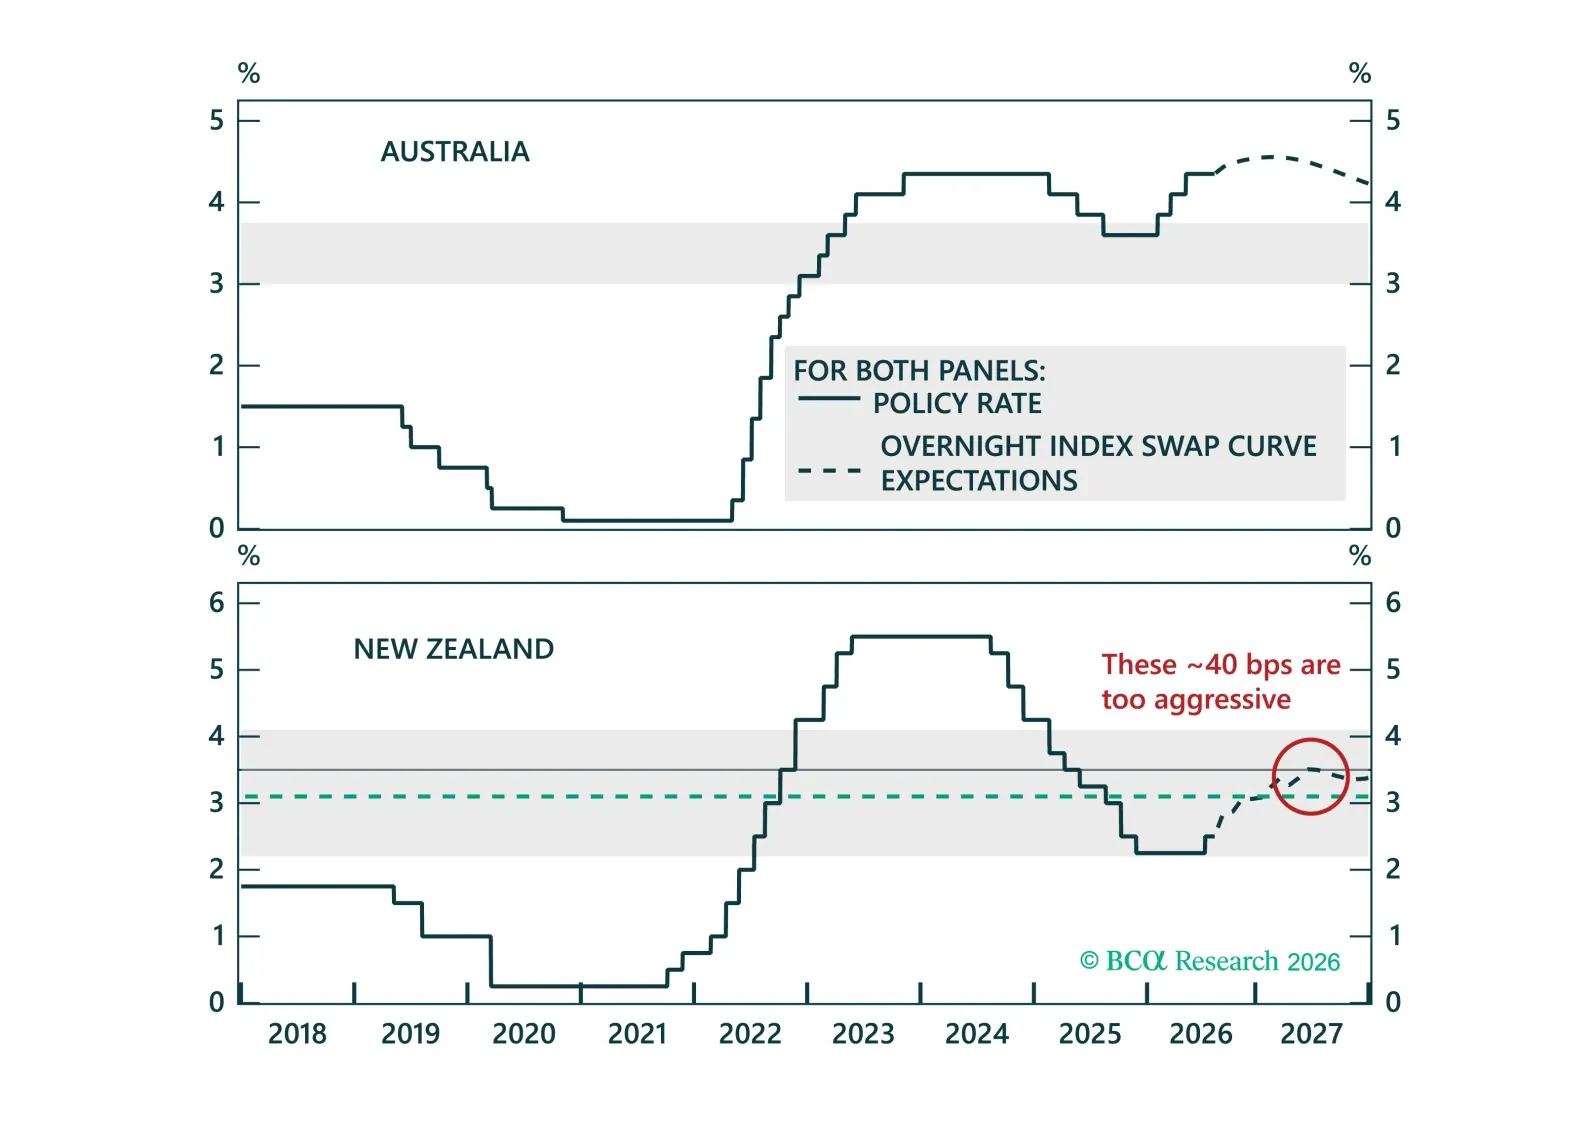
The RBA is likely done hiking, and the RBNZ overpriced for more hikes. We trace both conclusions back to housing, credit, and external dynamics, with implications for our country allocation in ANZ bonds and our long AUD/NZD view.