 Essentials
Concise macro insight that cuts through daily noise, helping clients stay informed on what matters in markets, why it matters, and how to talk about it, without spending hours reading research.
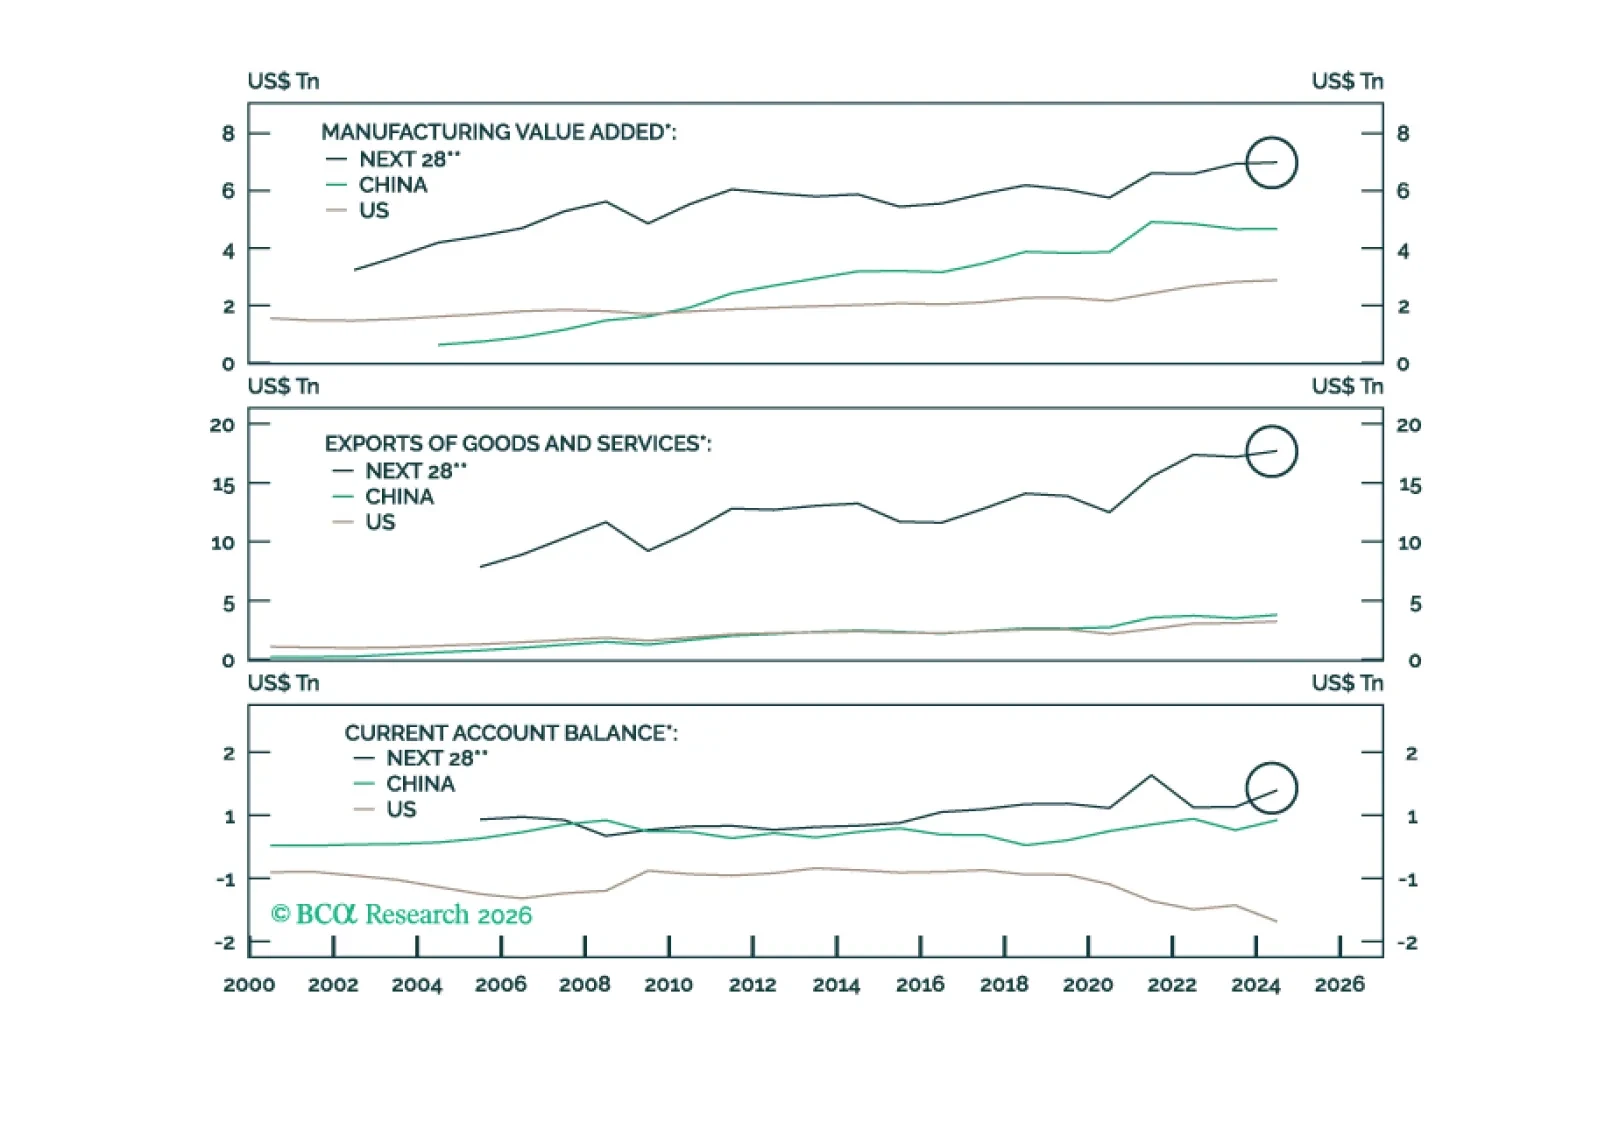
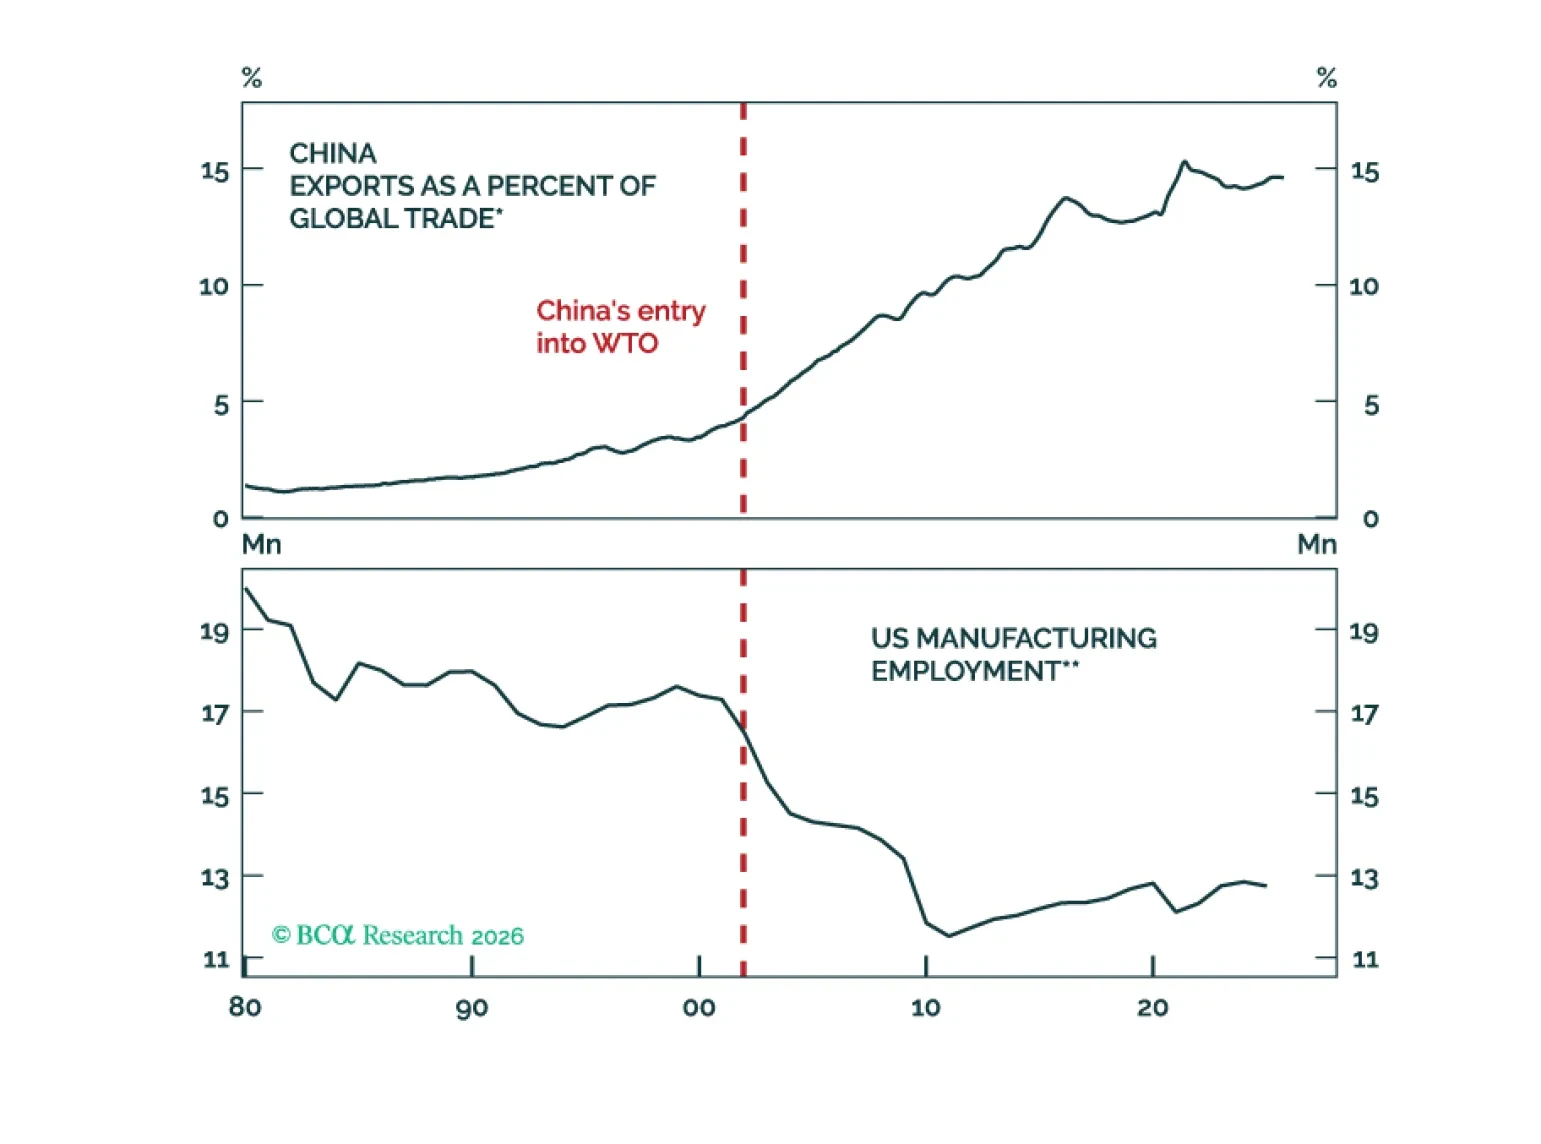
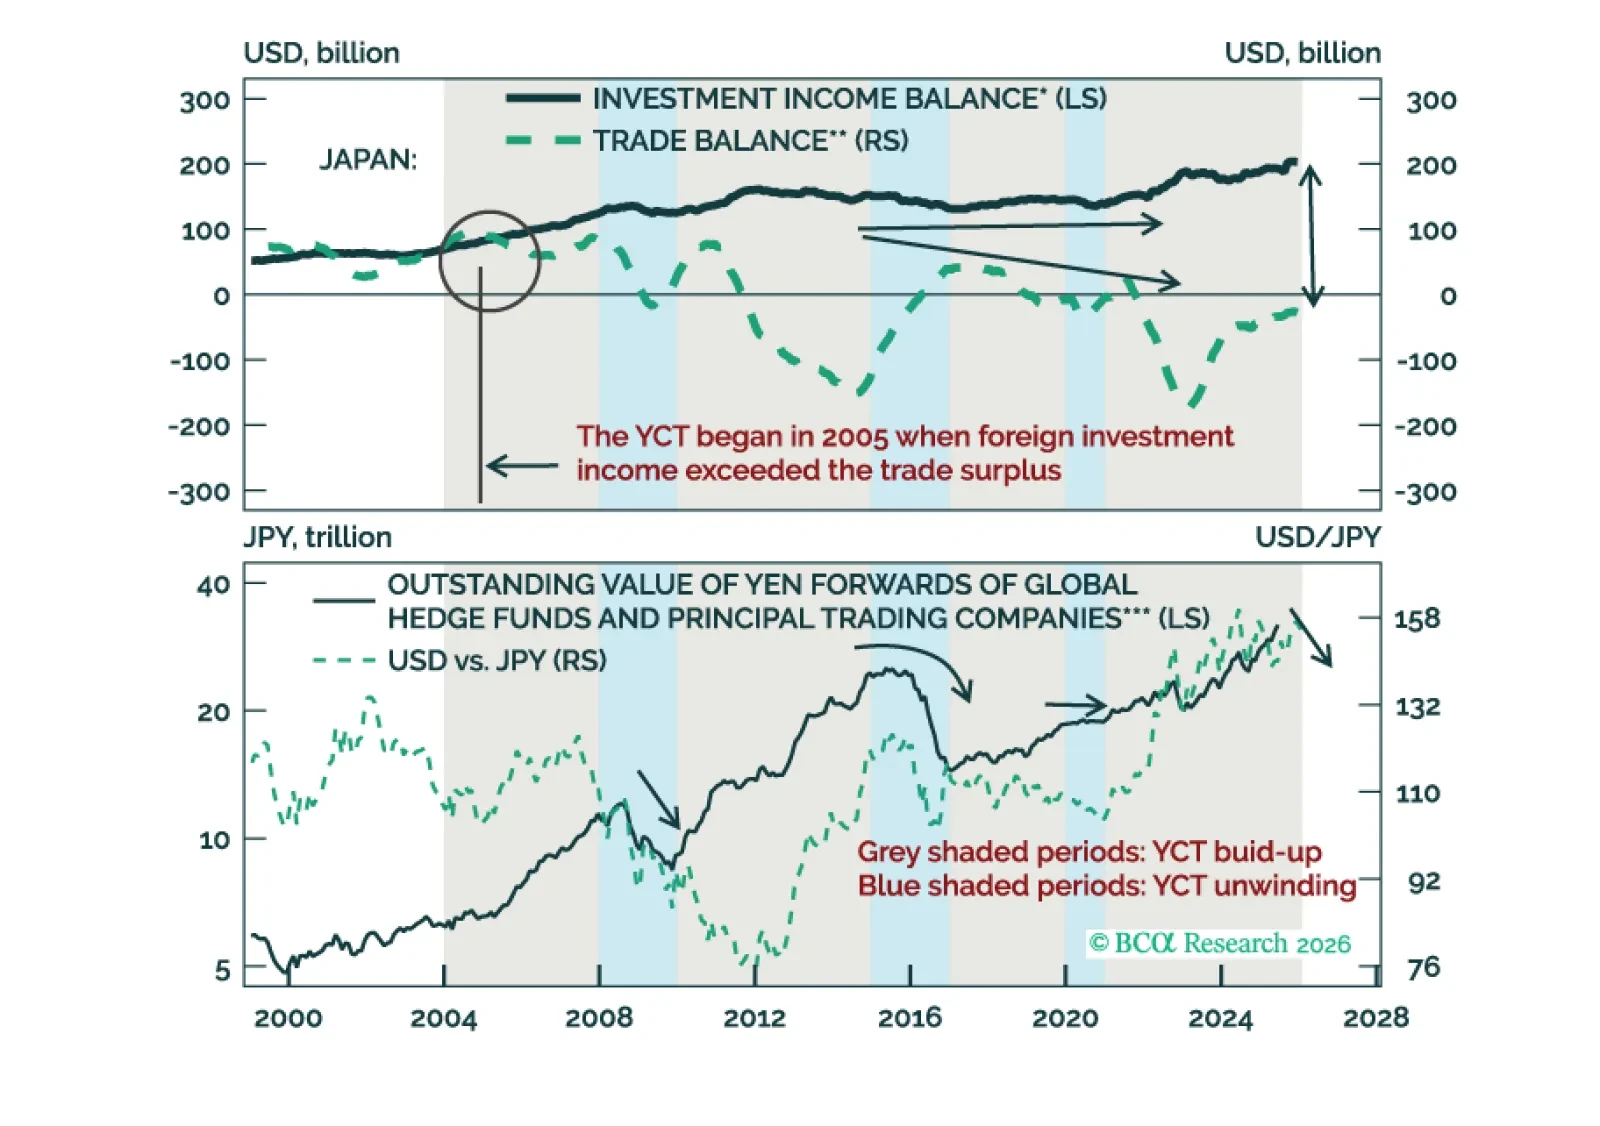
In Section I, Doug recommends cutting US equity exposure in favor of Europe as reduced recession odds make it unlikely that the US will draw safe-haven capital flows. In Section II, Jesse ranks middle economic powers across hard and soft power dimensions and recommends investing in their defense and industrial sectors.
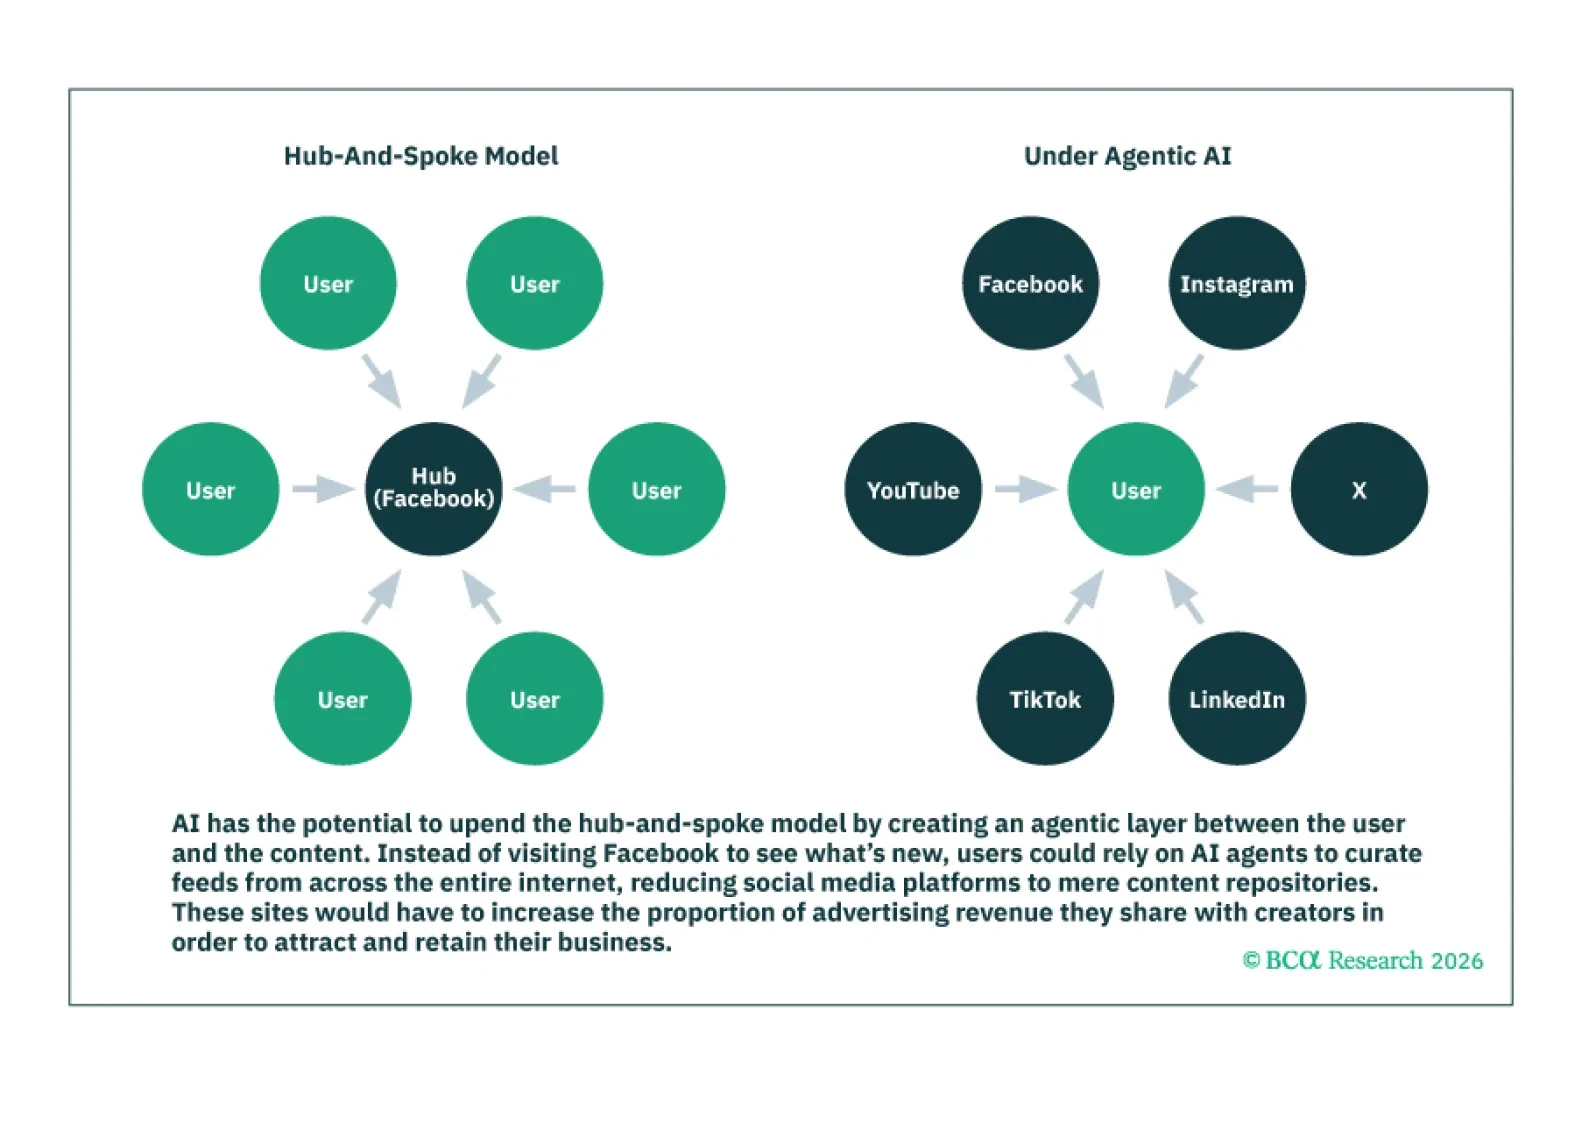
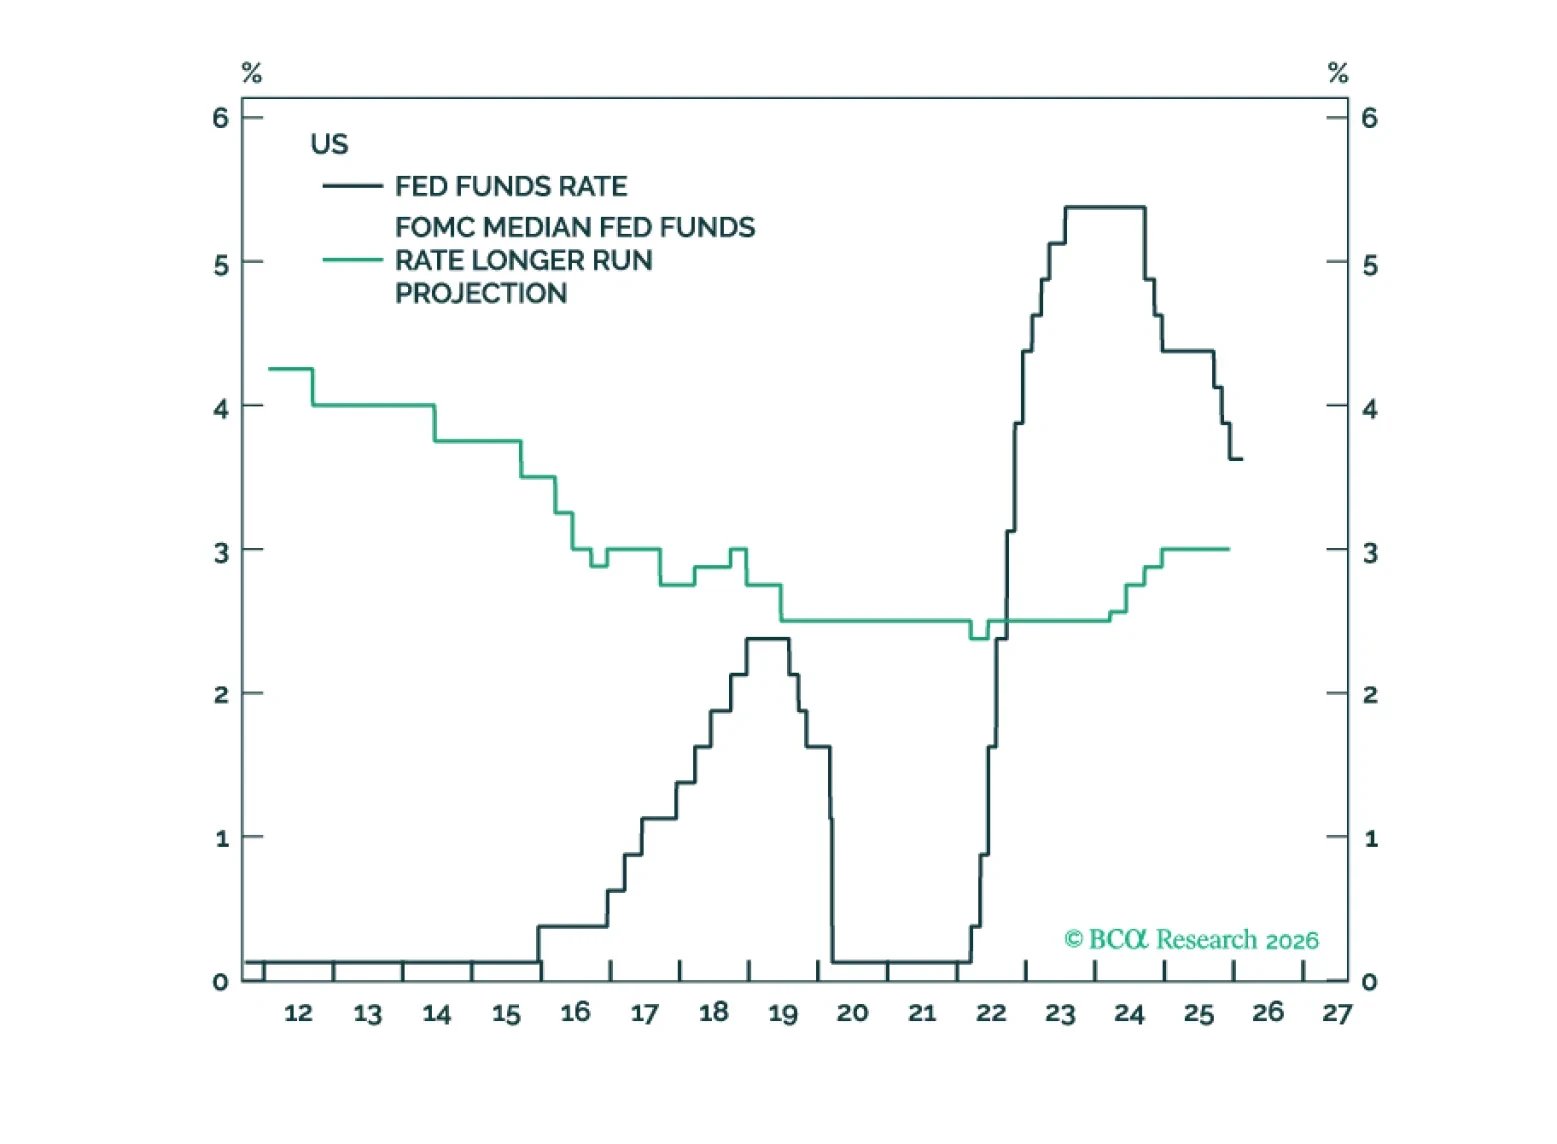
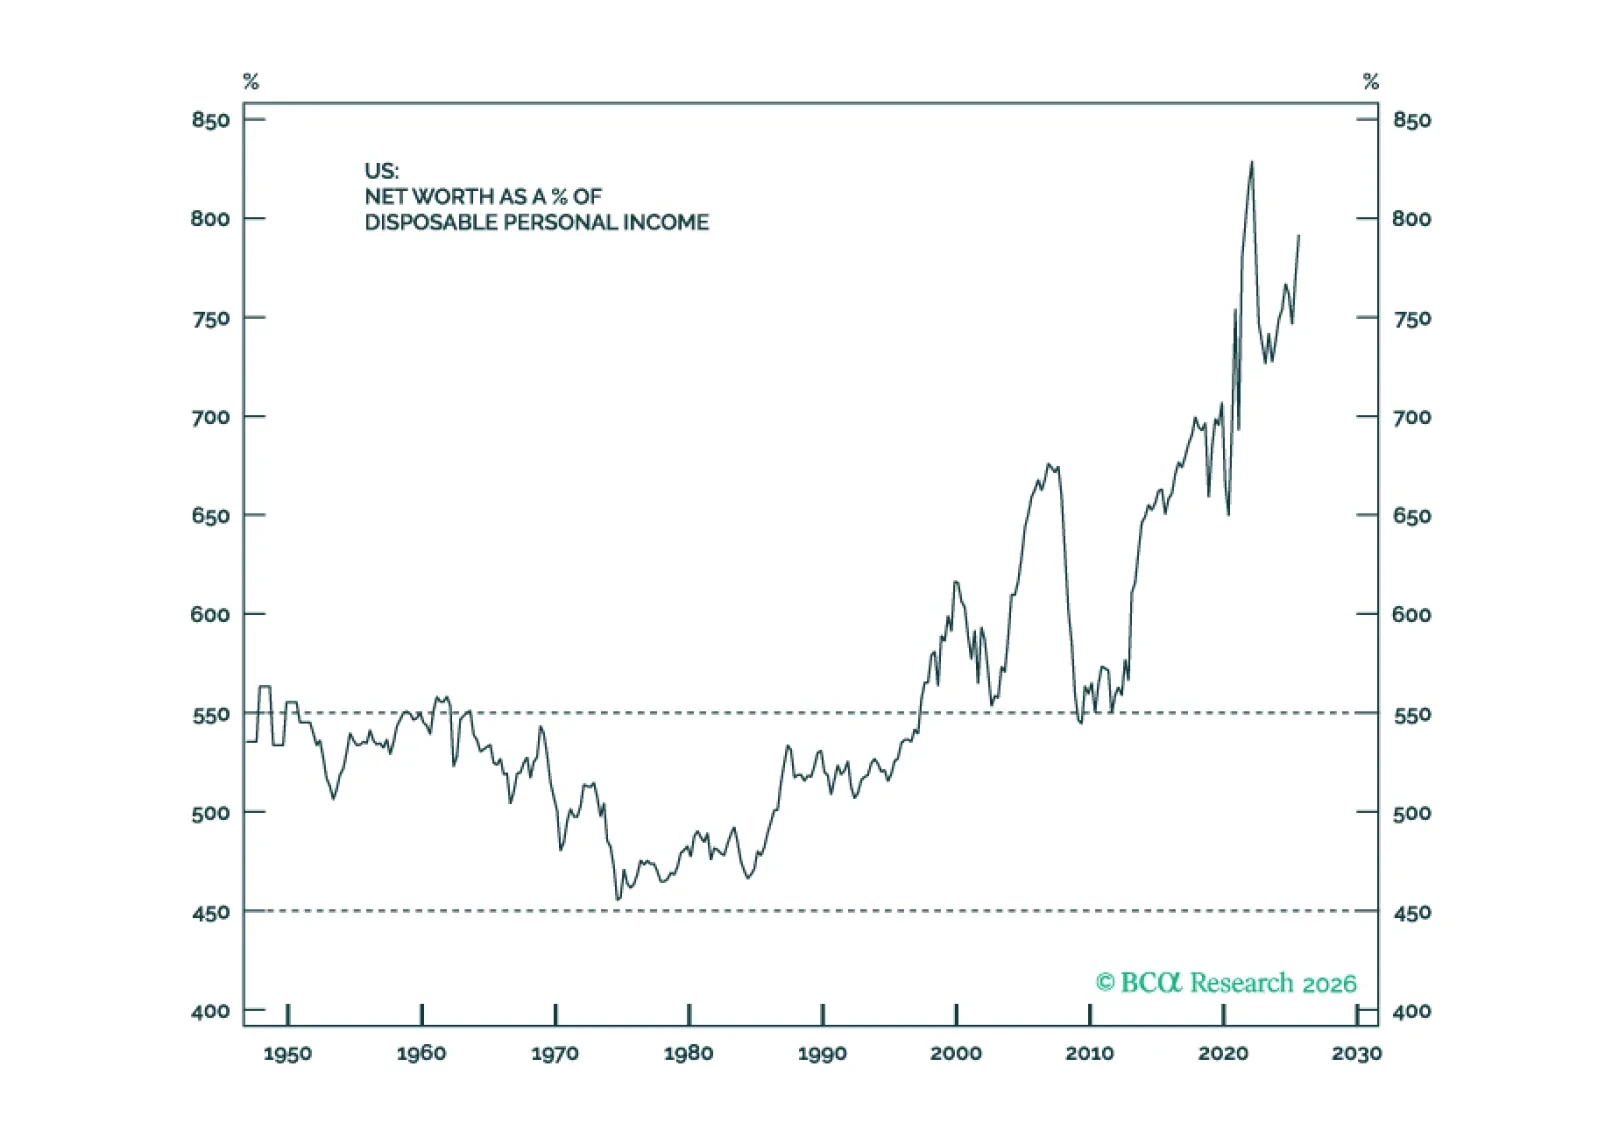
The neutral rate in the US is being propped up by a variety of forces that are at risk of reversing. These include the AI capex boom, large budget deficits, and the extraordinarily high level of household wealth. As such, interest rates are likely to surprise to the downside over the next few years.
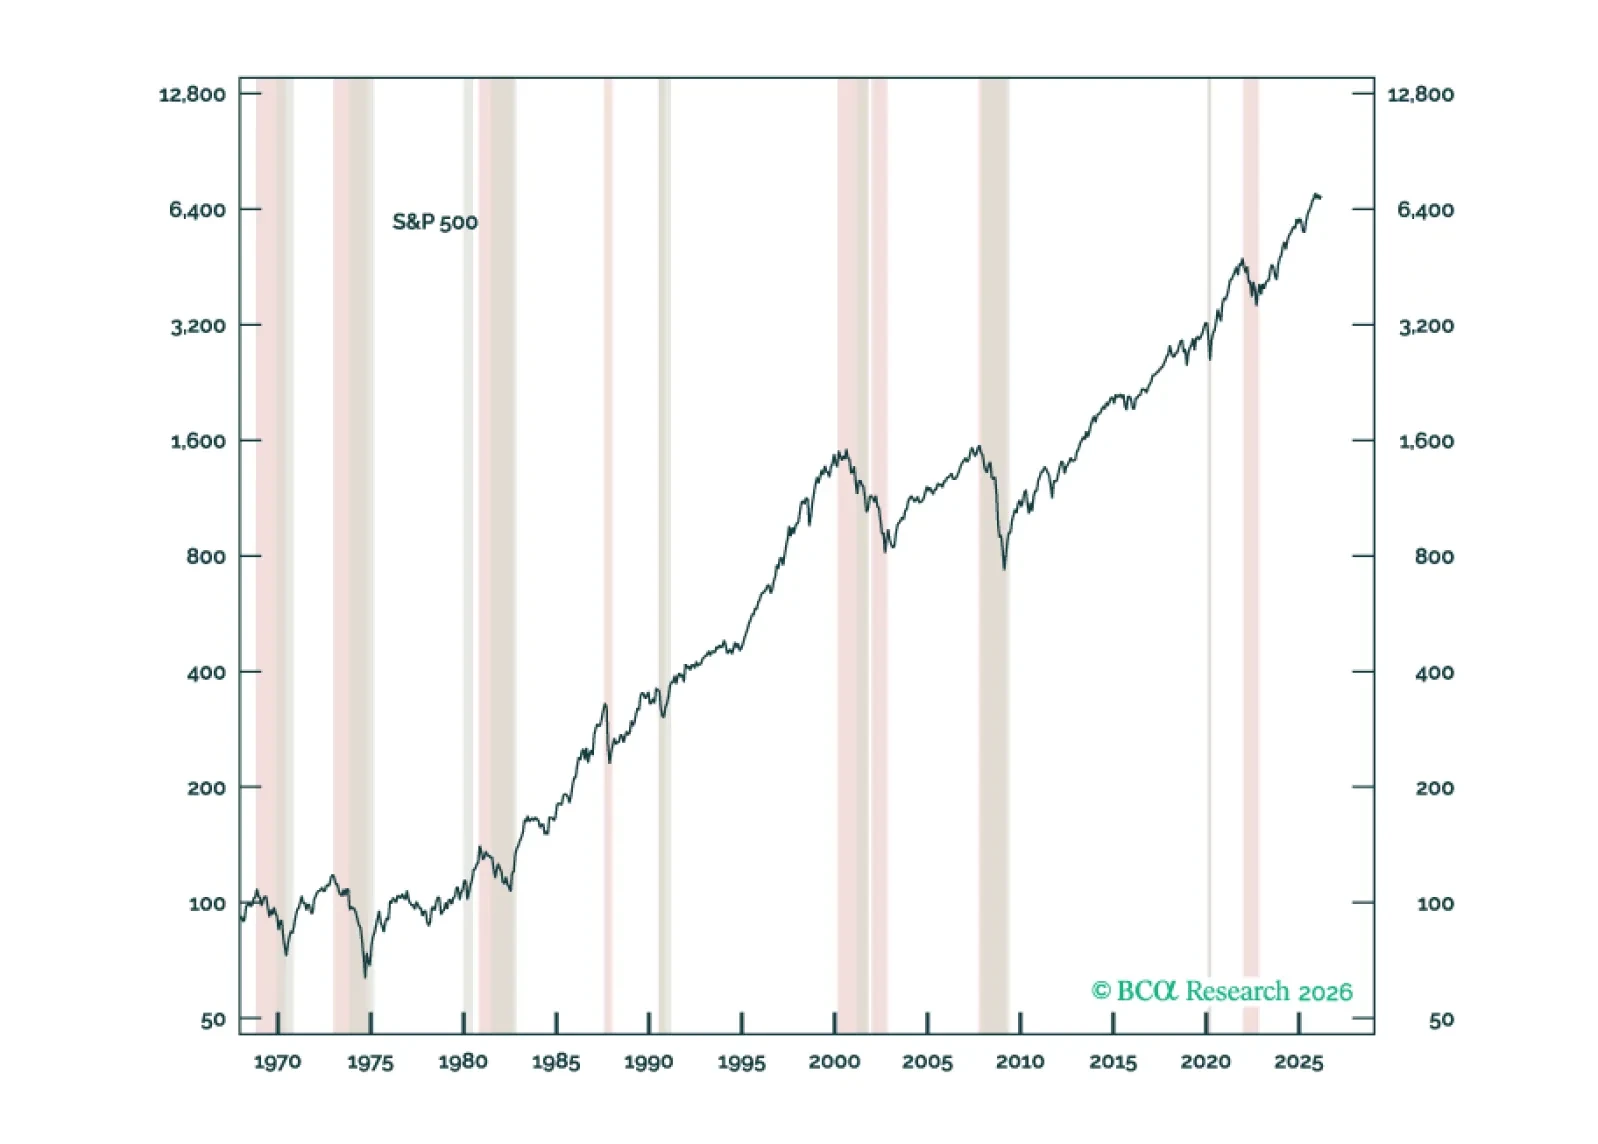
In Section I, Doug highlights the risks to US consumption if job growth does not soon recover. The US economy has yet to pass its tipping point, however, arguing against defensive positioning for now. In Section II, Jonathan examines whether the AI “scaling laws” are likely to hold. They will over the near term, but cracks are already beginning to form in the narrative of ever-improving AI.
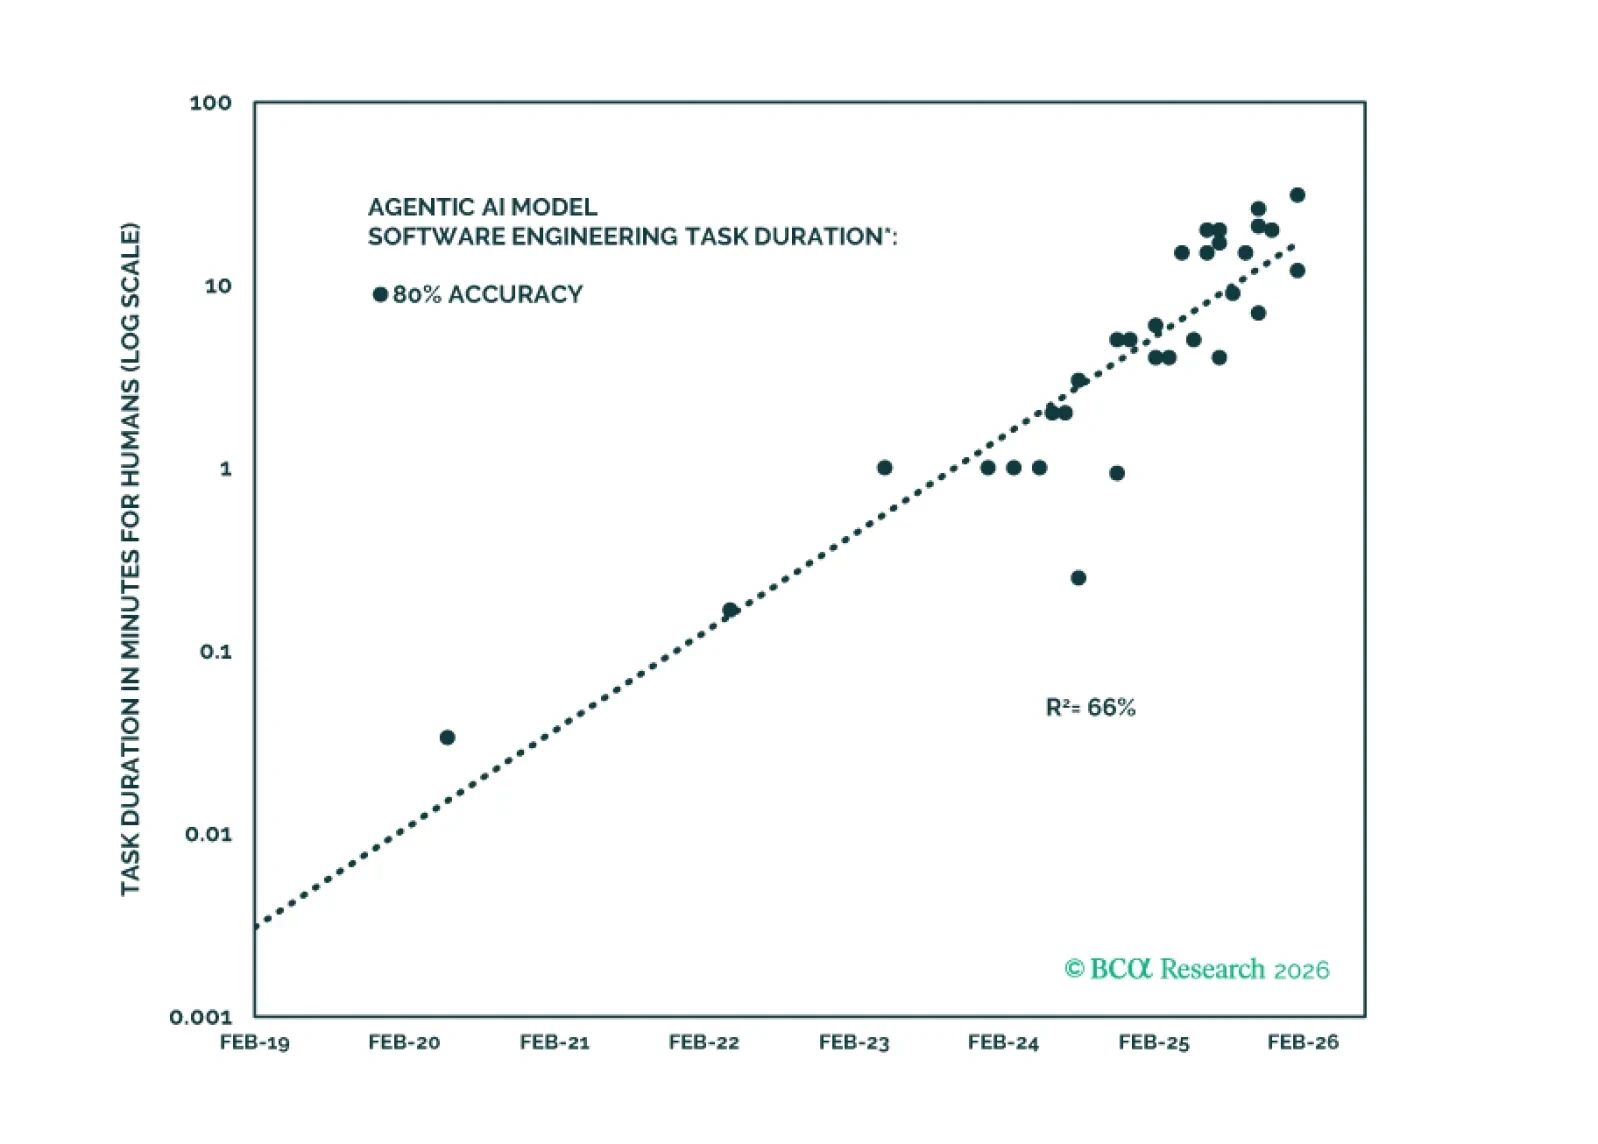
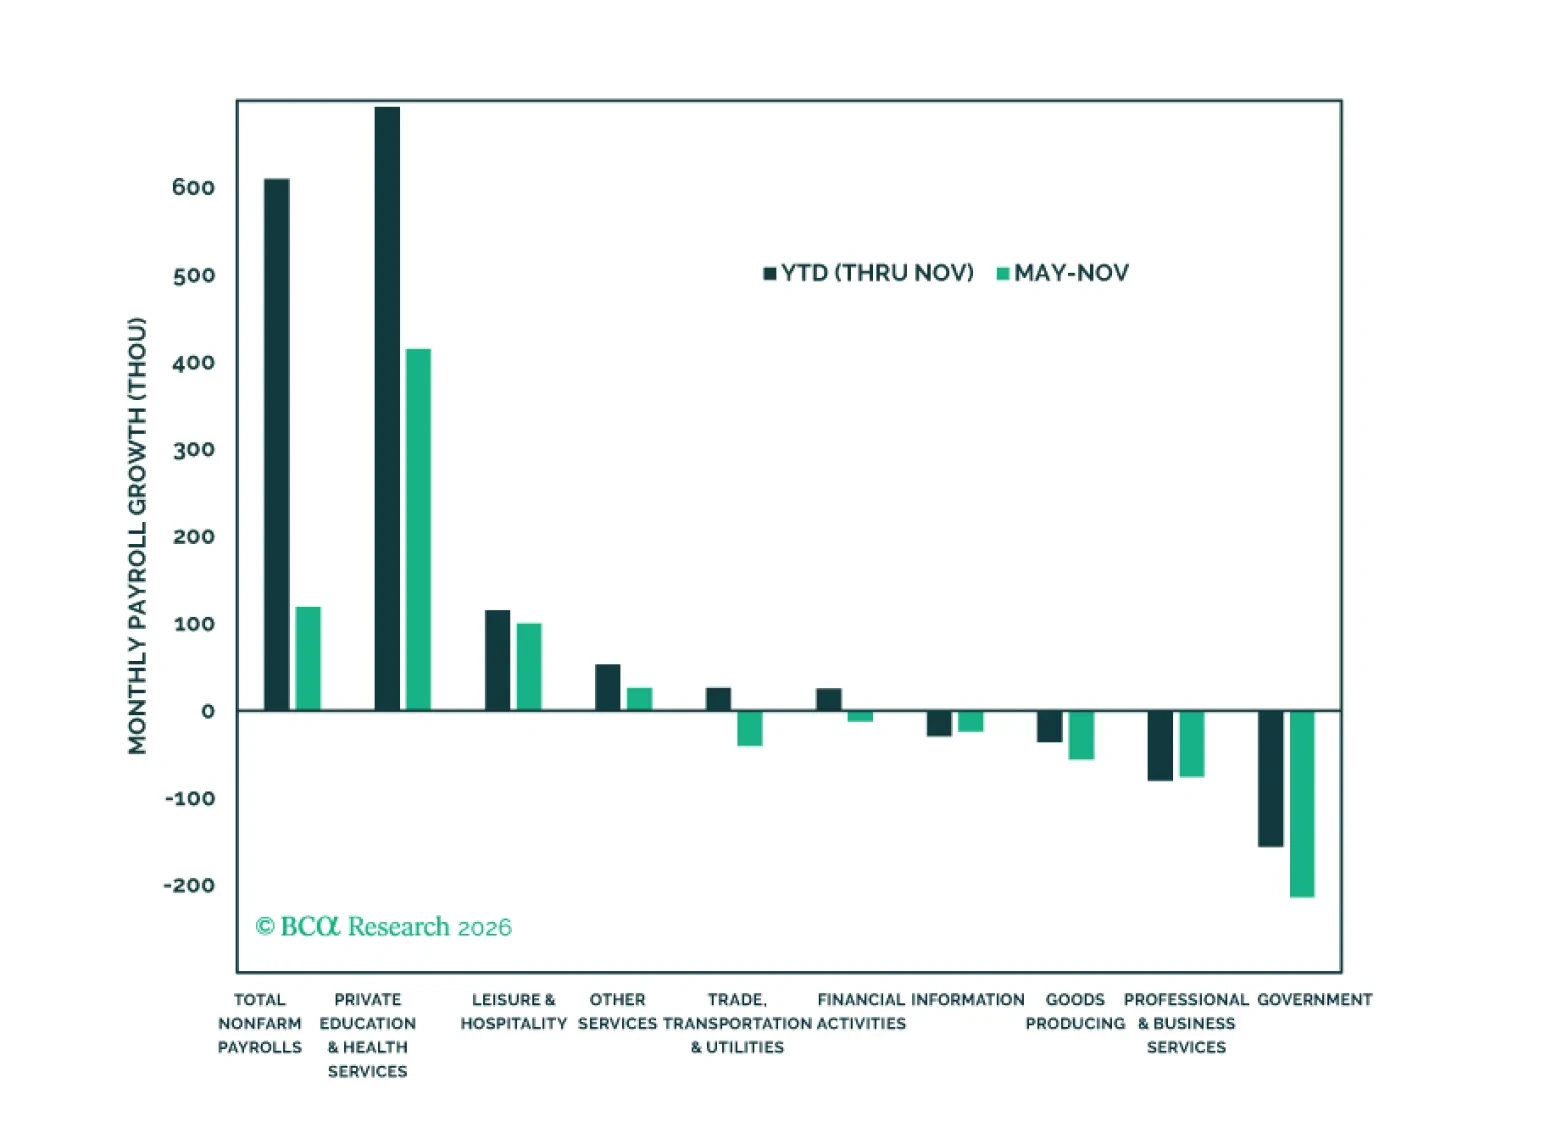
In Section I, Doug underscores that the US labor market remains weak, crimping the outlook for disposable income growth. It is too soon to decisively bet against the bull market, but downside risks remain quite elevated. In Section II, Jonathan updates the BCA Artificial Intelligence Productivity Checklist and concludes that the evidence of an AI-driven productivity boom is not convincing.