CoreMacro
Find out more
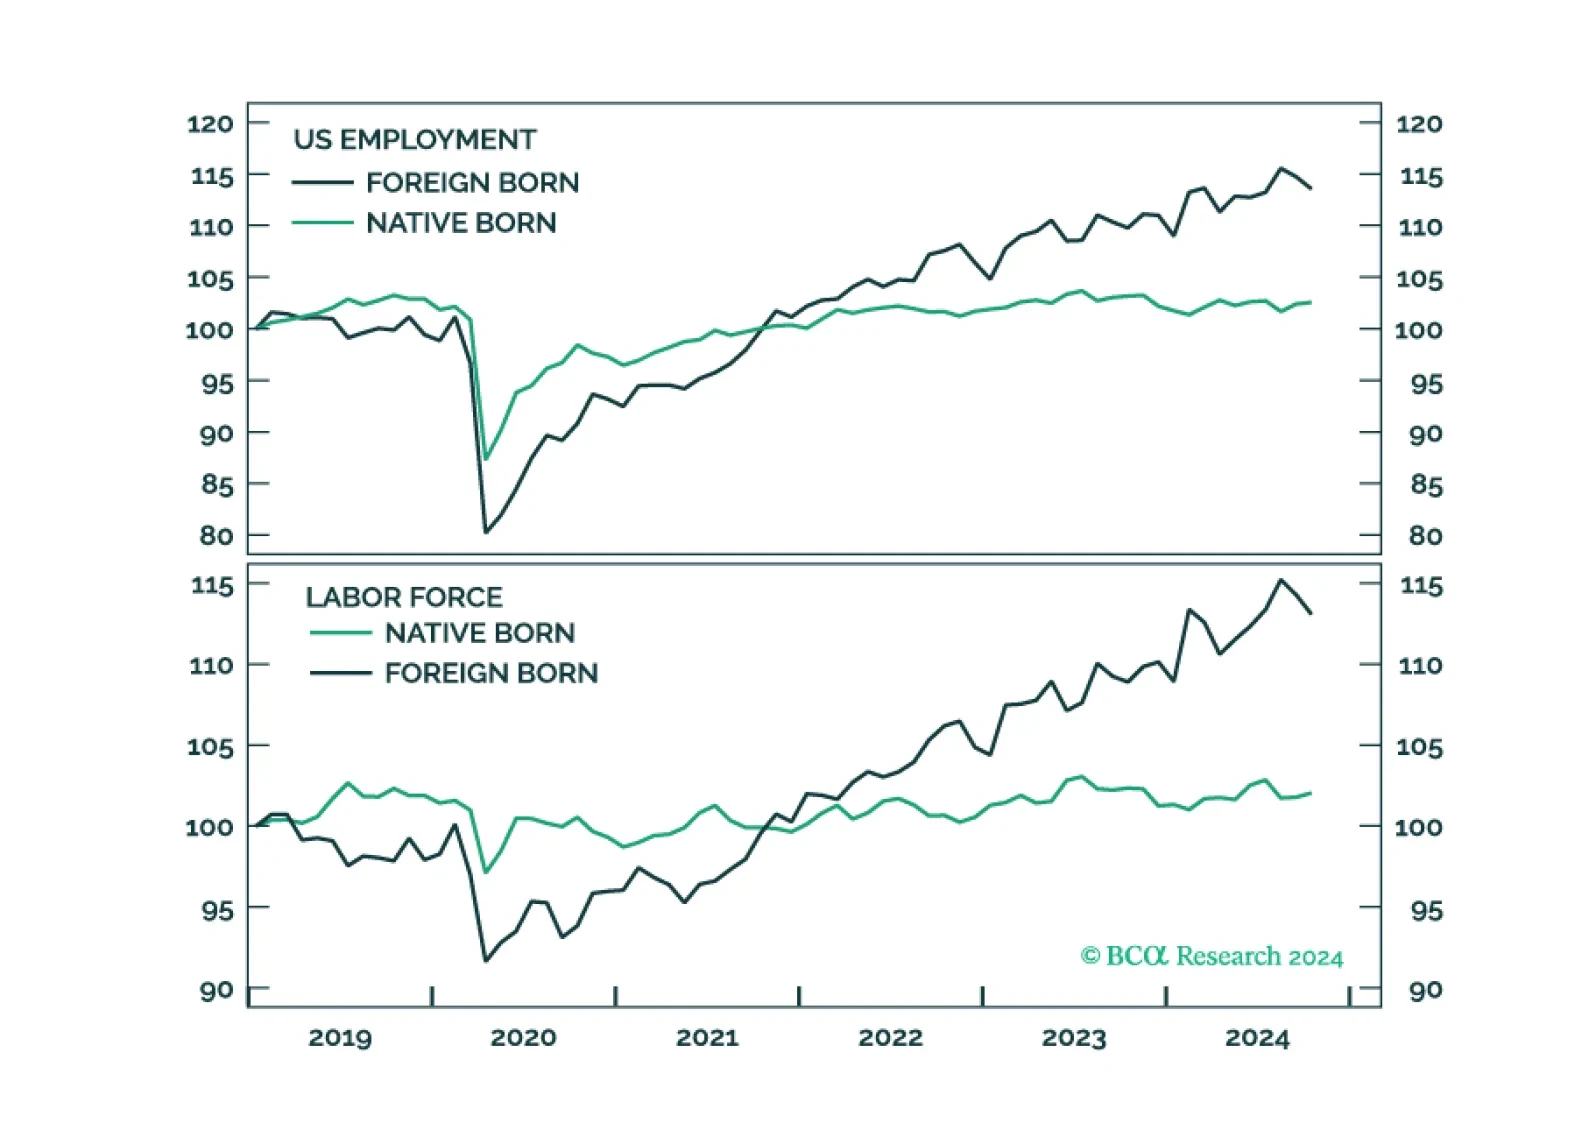
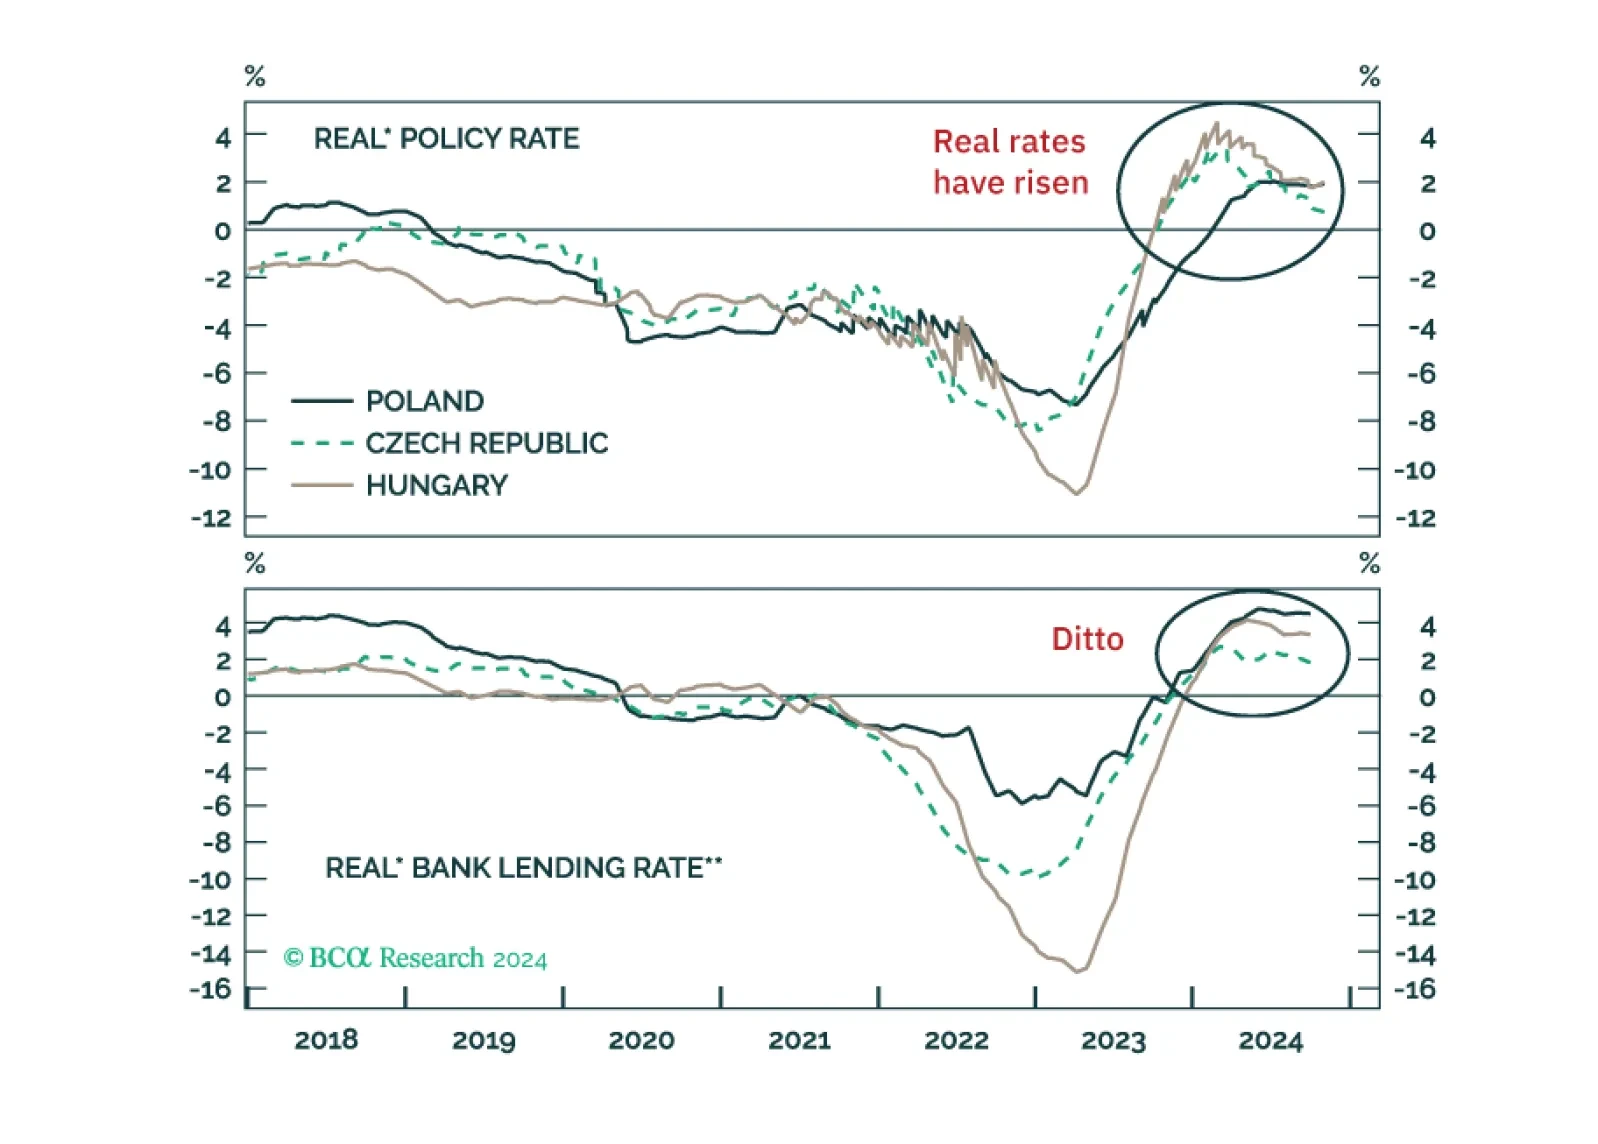
I have been generally sceptical of the reflationary aspects of the so-called Trump trade. If Trump's first term is any guide, lower tax rates will have little impact on business spending while higher tariffs are unlikely to trigger much reshoring of manufacturing activity. Meanwhile, rising debt-service costs could force the Trump administration to cut social spending under the guise of reducing government waste. One open question surrounds immigration. The market consensus seems to be that decreased immigration will lead to a tighter labour market, stoking inflationary pressures in the process.
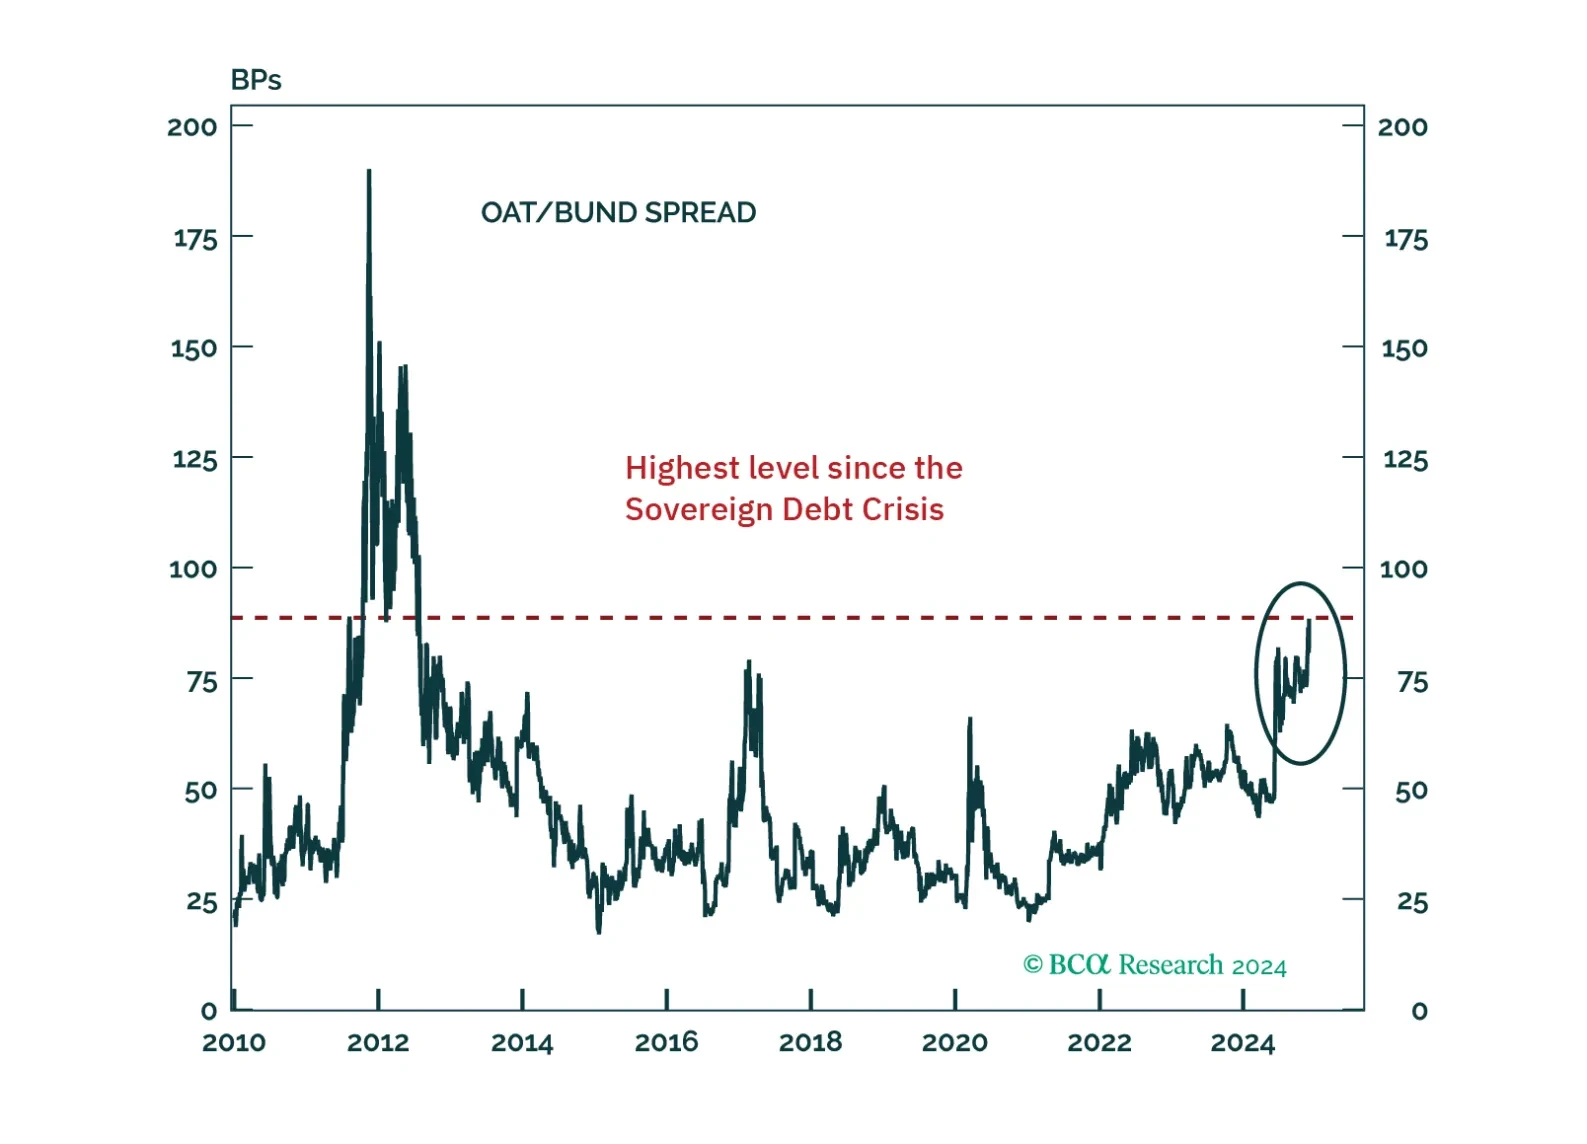
France finds itself in a unique, thorny situation. Can it heave itself out of it? And what does it mean for investors?
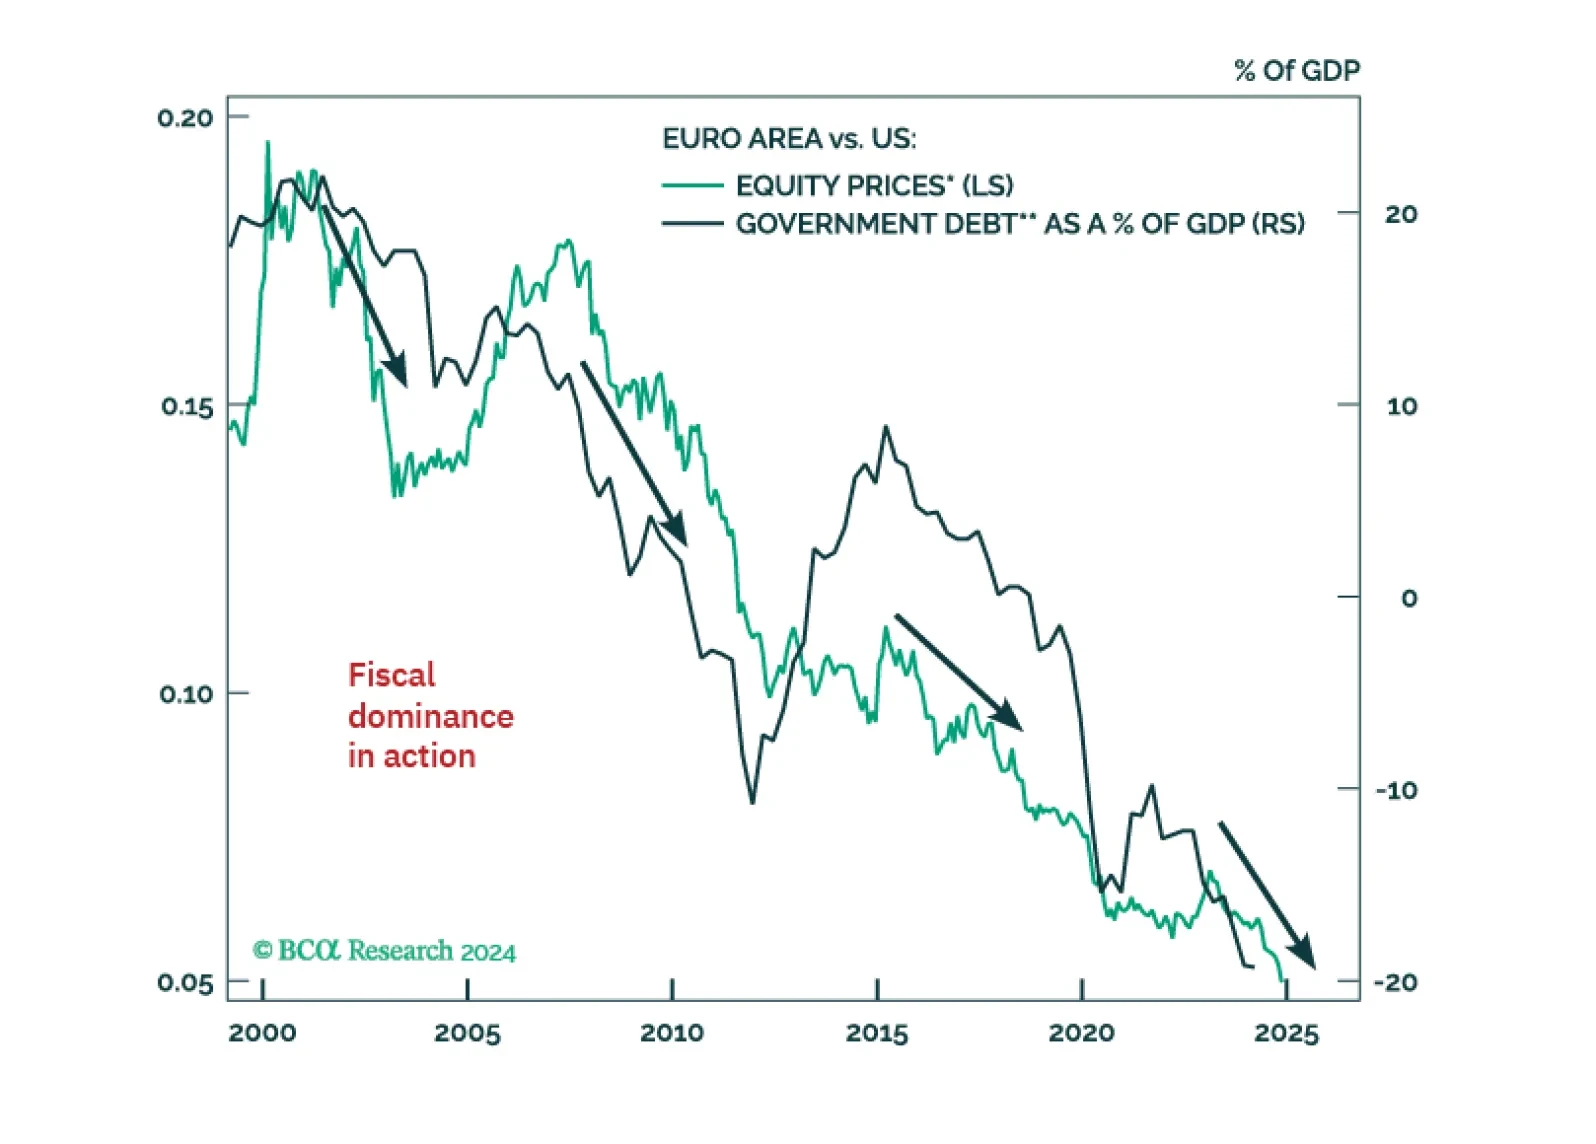
Investors have given up on European assets, which now suffer exceptional discounts to US ones. However, tighter US fiscal policy, the end of Europe’s austerity and deleveraging, the LNG Tsunami about to hit European shores, and the global capex fueled by the Impossible Geopolitical Trinity mean that Europe’s time to shine will soon come back.
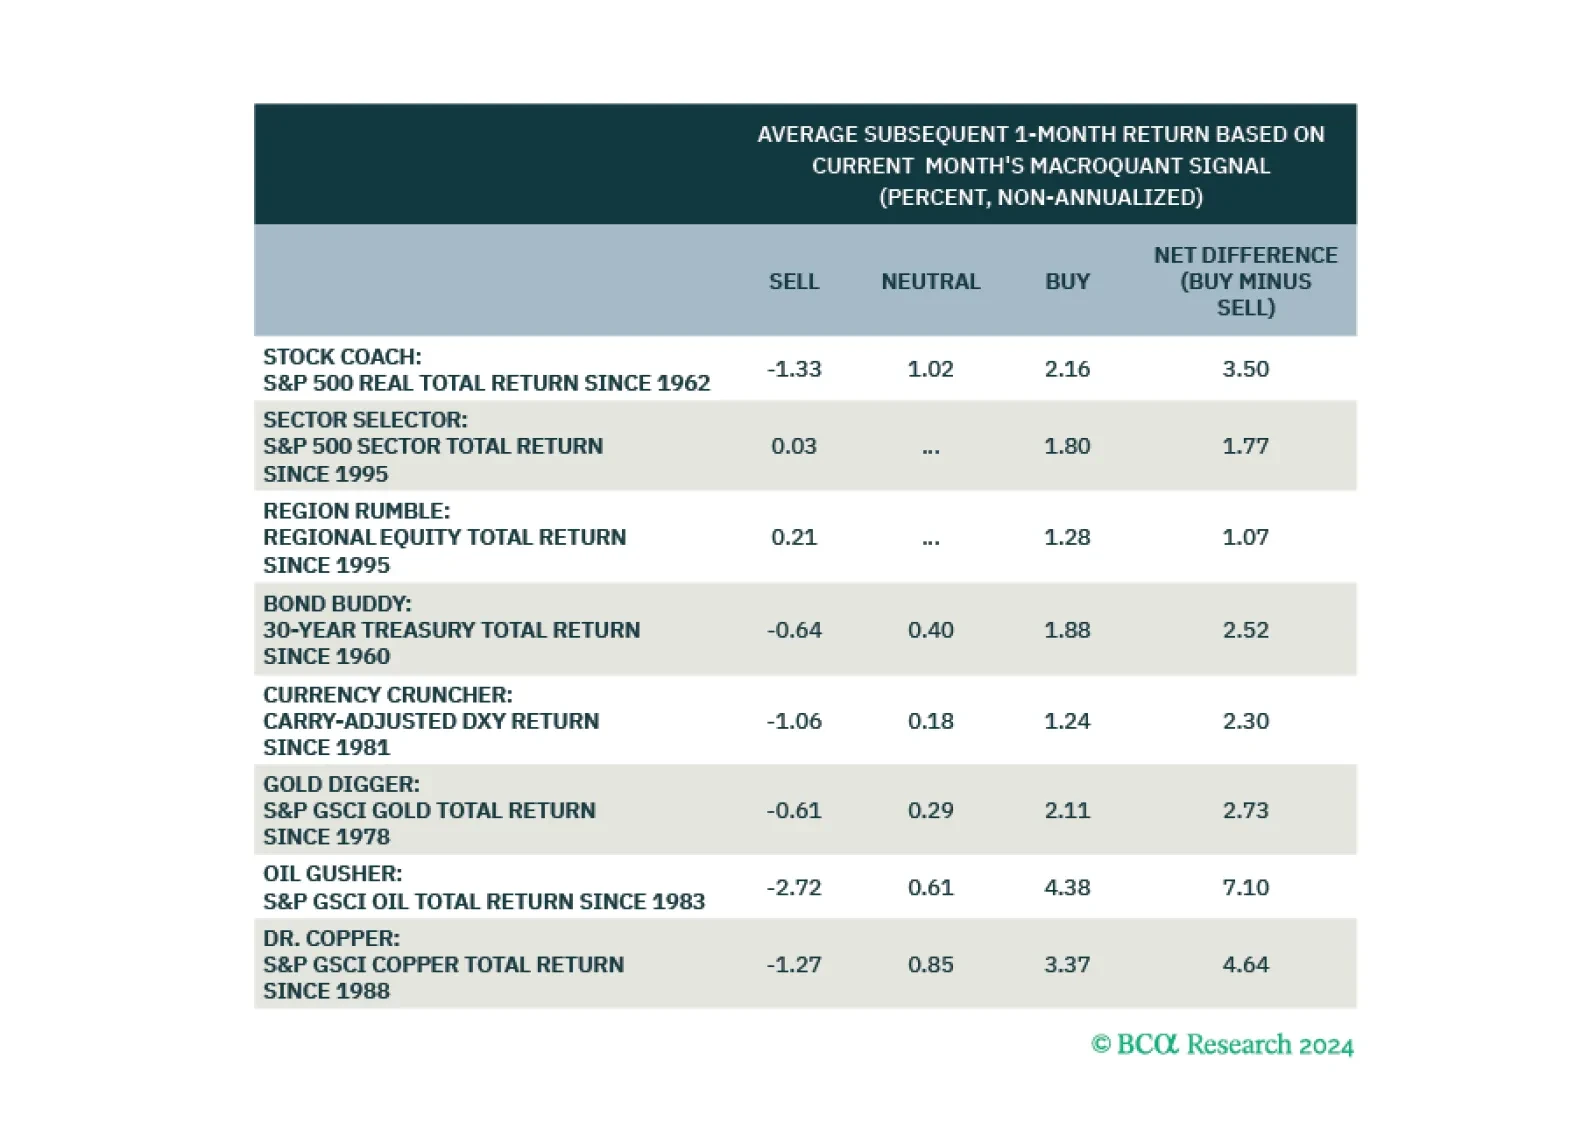
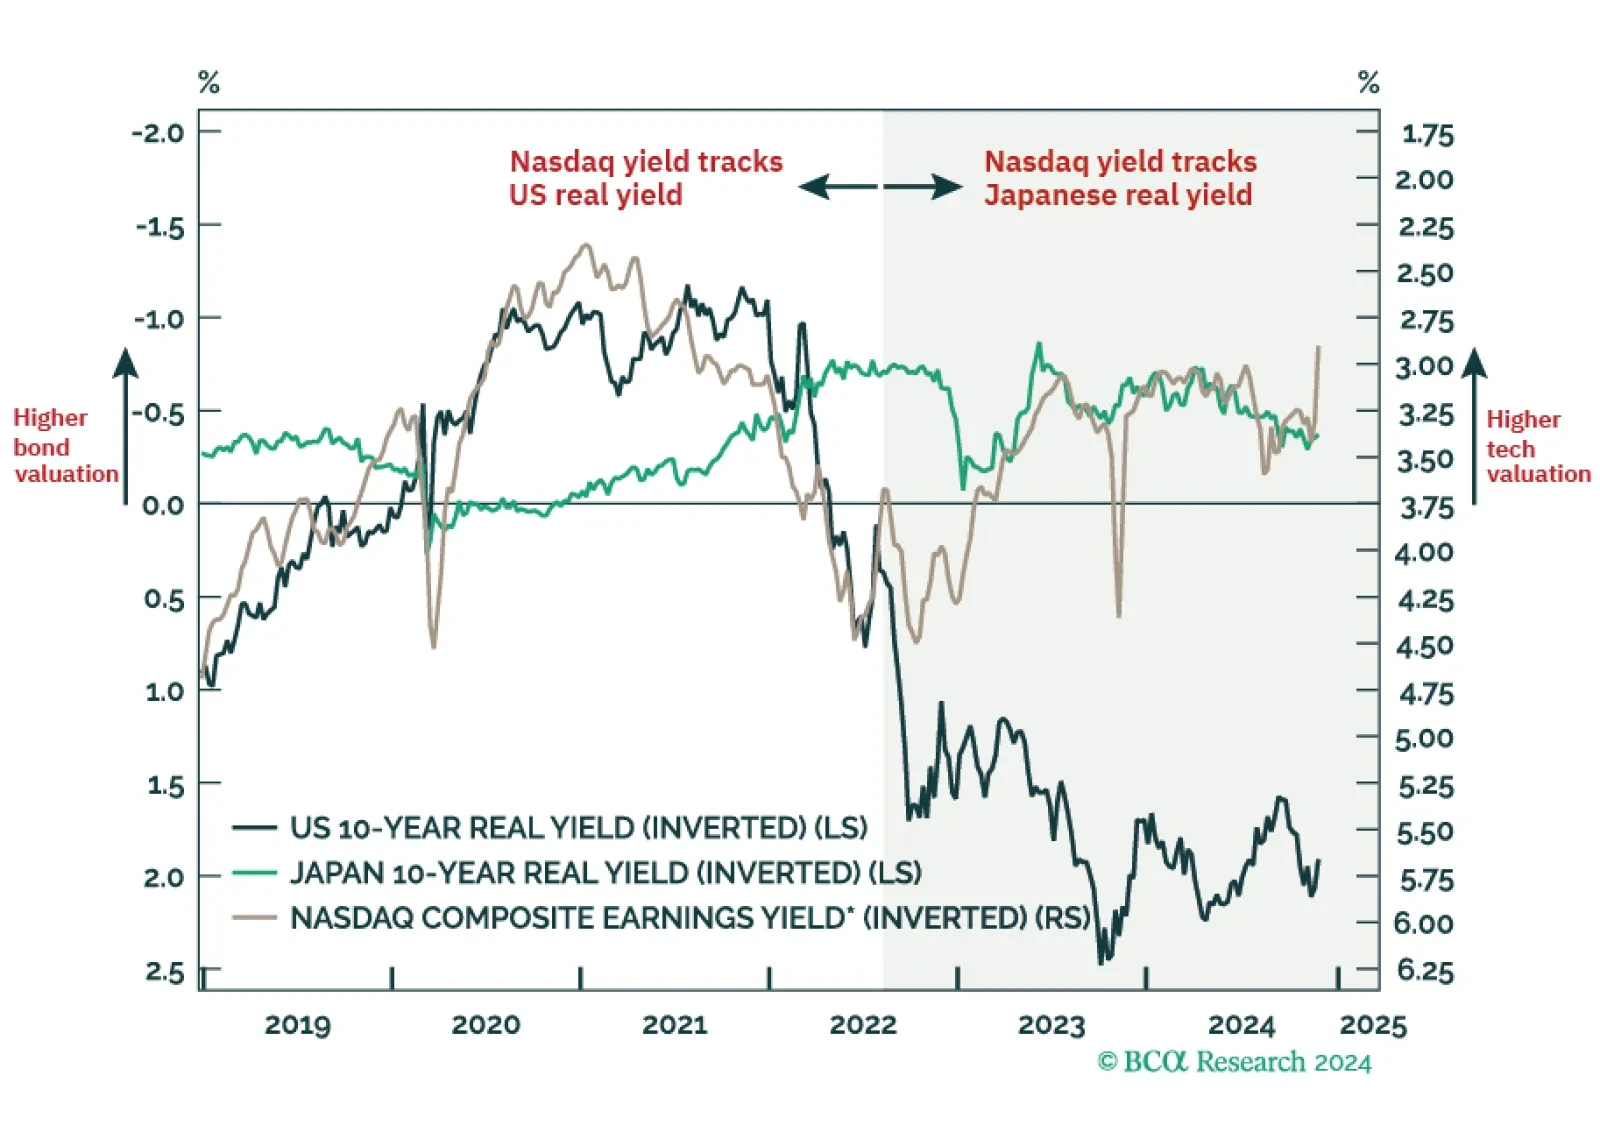
Today, we are unveiling an update to our MacroQuant model. The latest version of the MacroQuant model sees downside risk to stocks going into December and recommends increasing duration exposure in global fixed-income portfolios.
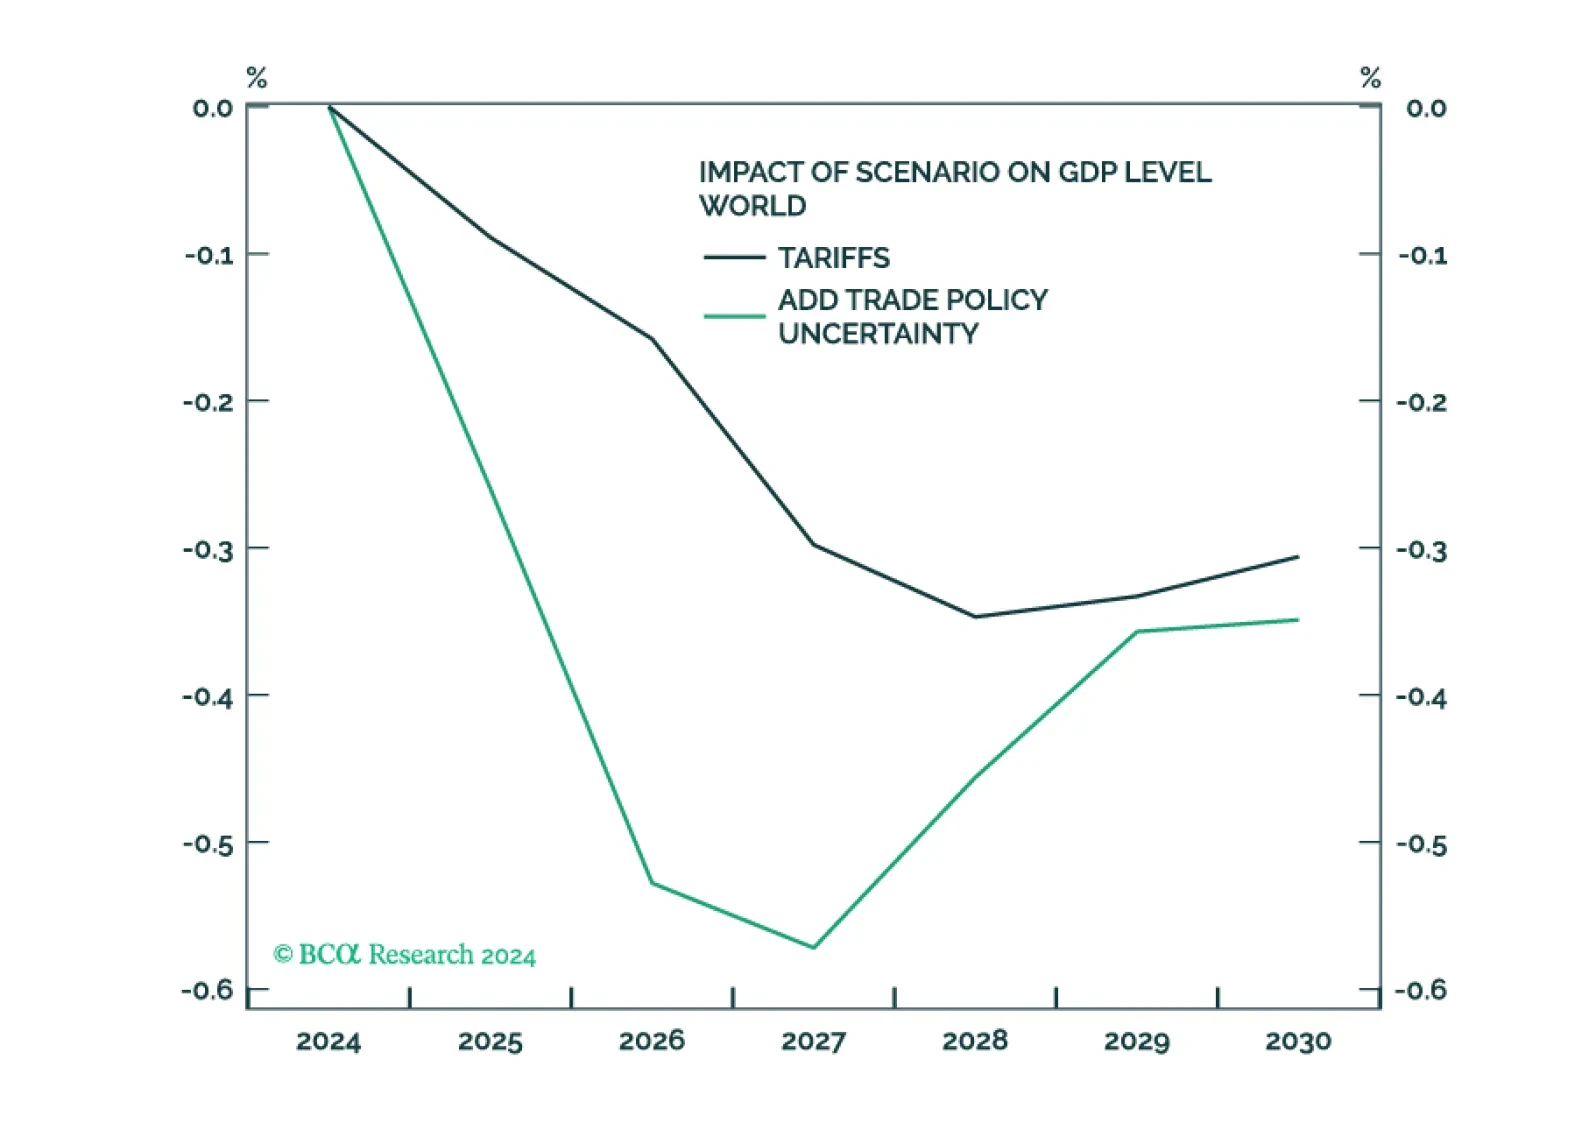
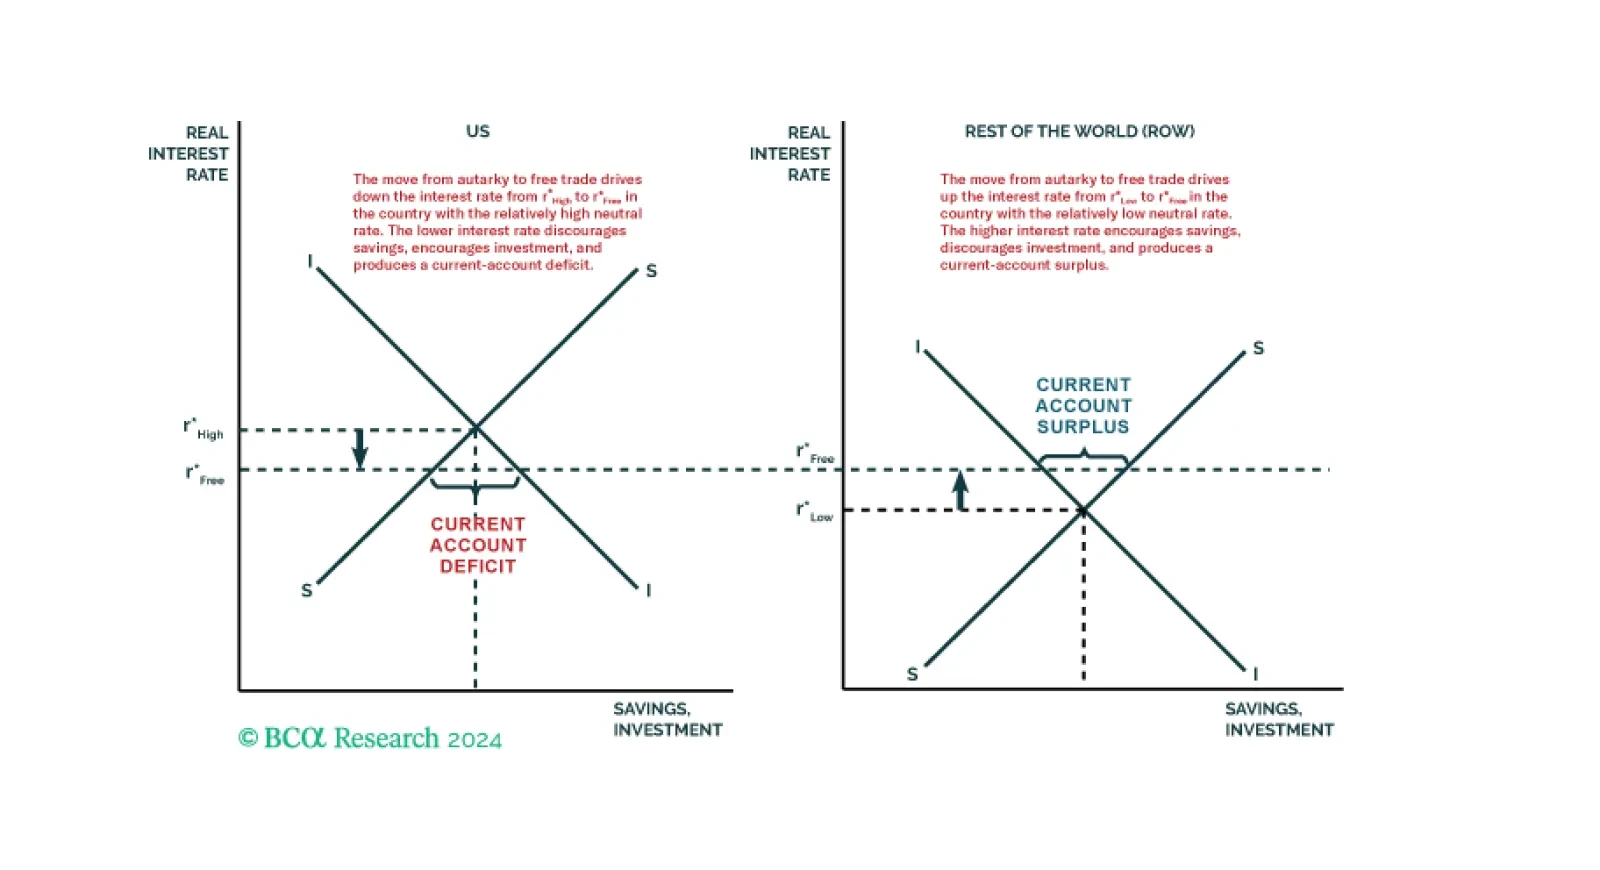
On October 15, speaking at the Economic Club of Chicago, Donald Trump called tariffs “the most beautiful word in the dictionary.” On Monday, he put those words into action by threatening to slap a 25% tariff on all imports from Canada and Mexico, and an additional 10% tariff on Chinese imports. Collectively, the three countries account for 45% of US imports.
This week we conduct a thorough audit of our open positions by revisiting the original basis and subsequent performance of all 13 cyclical recommendations. Following the review, we recommend closing 6 of the 13 positions.