Capex
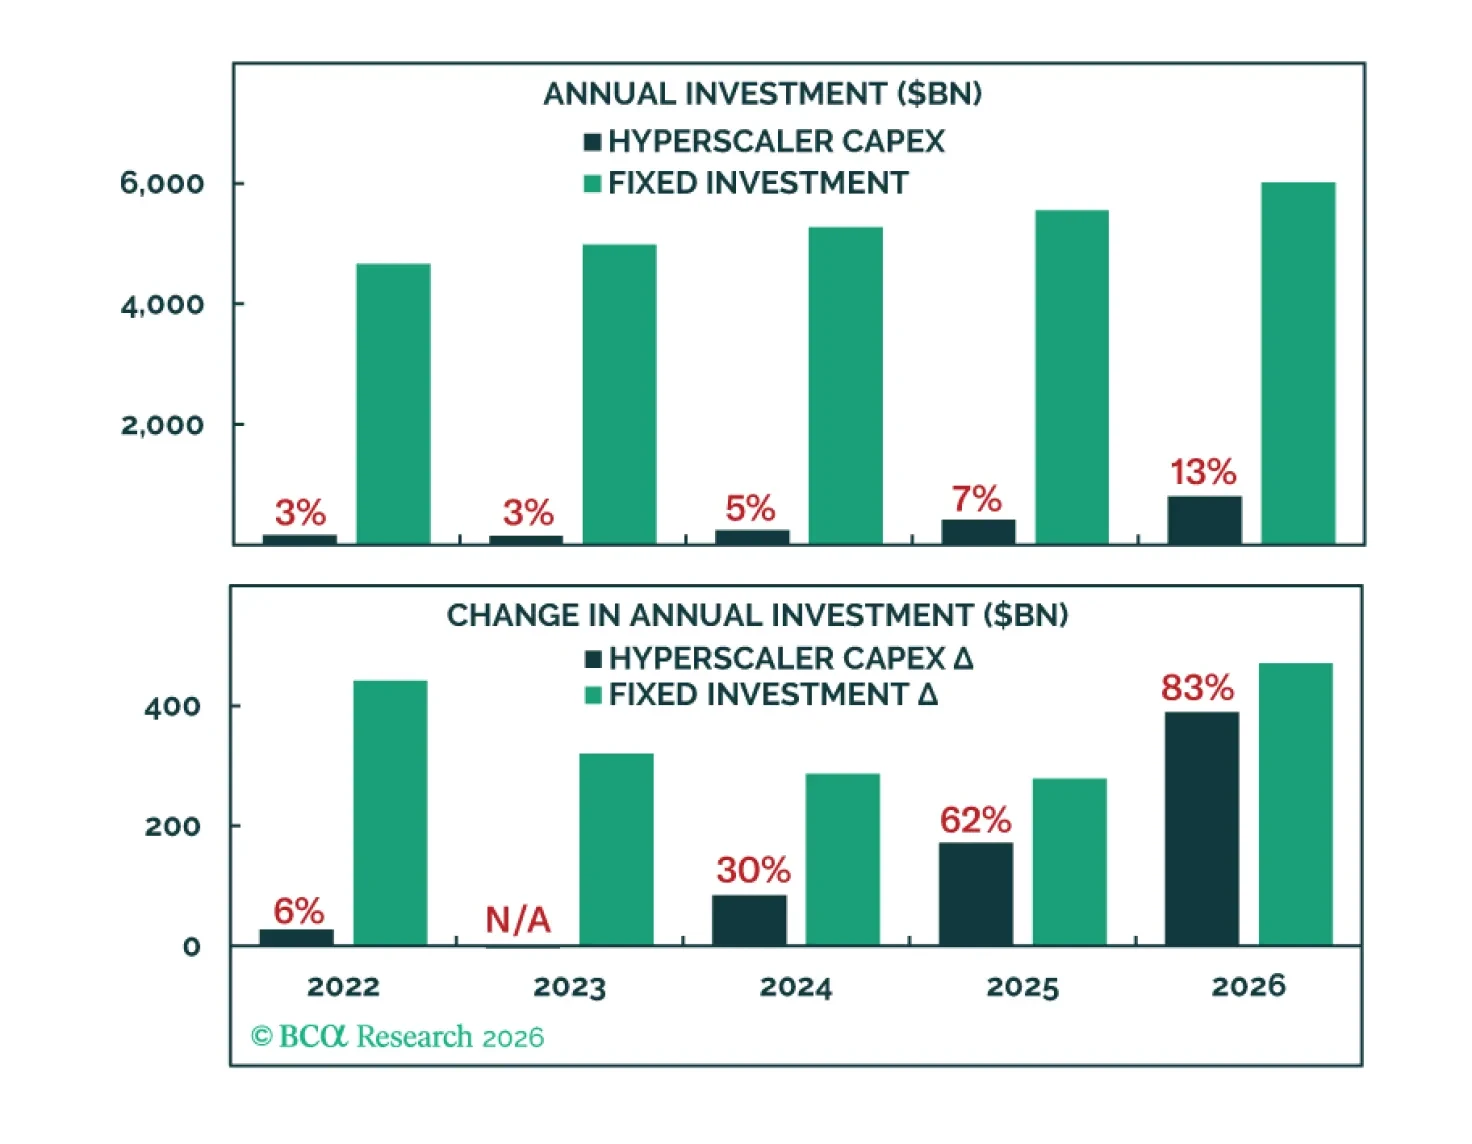
Data centers have swallowed aggregate US investment to such an extent that even a modest hyperscaler capex pullback could sink the expansion and bull market.
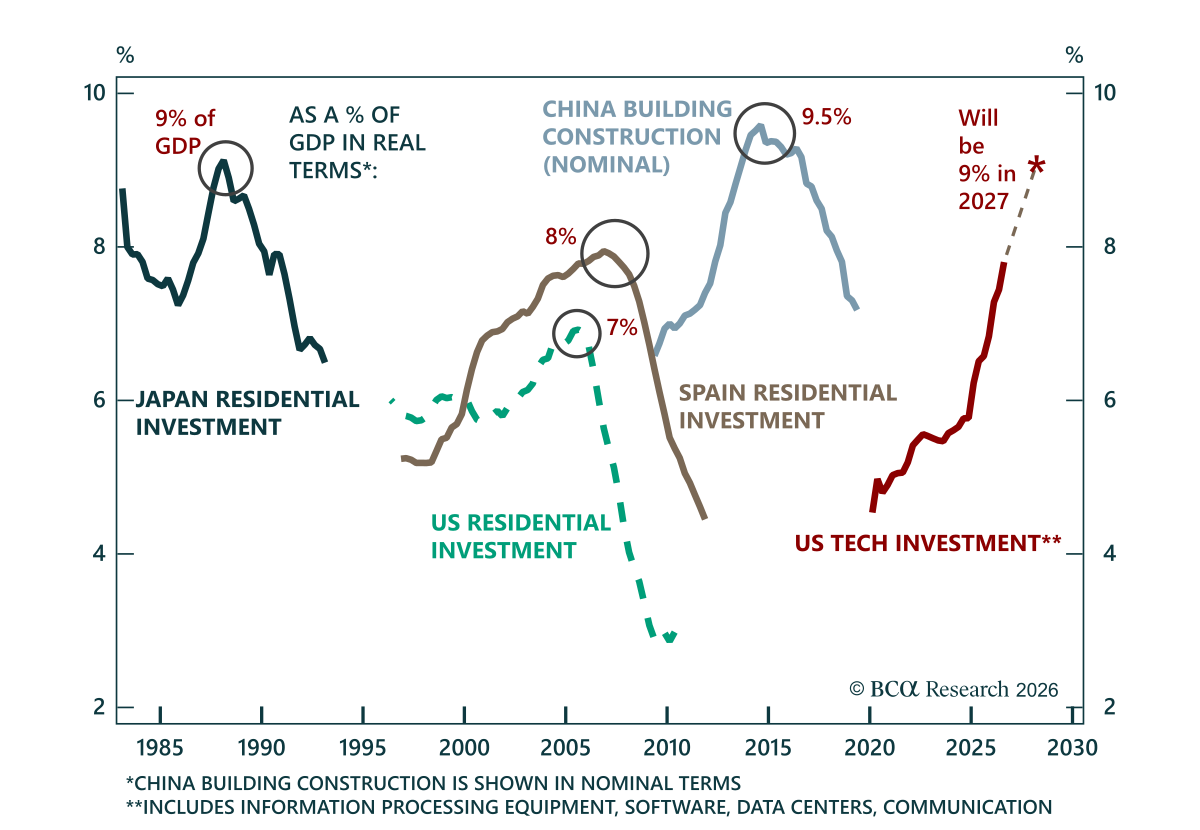
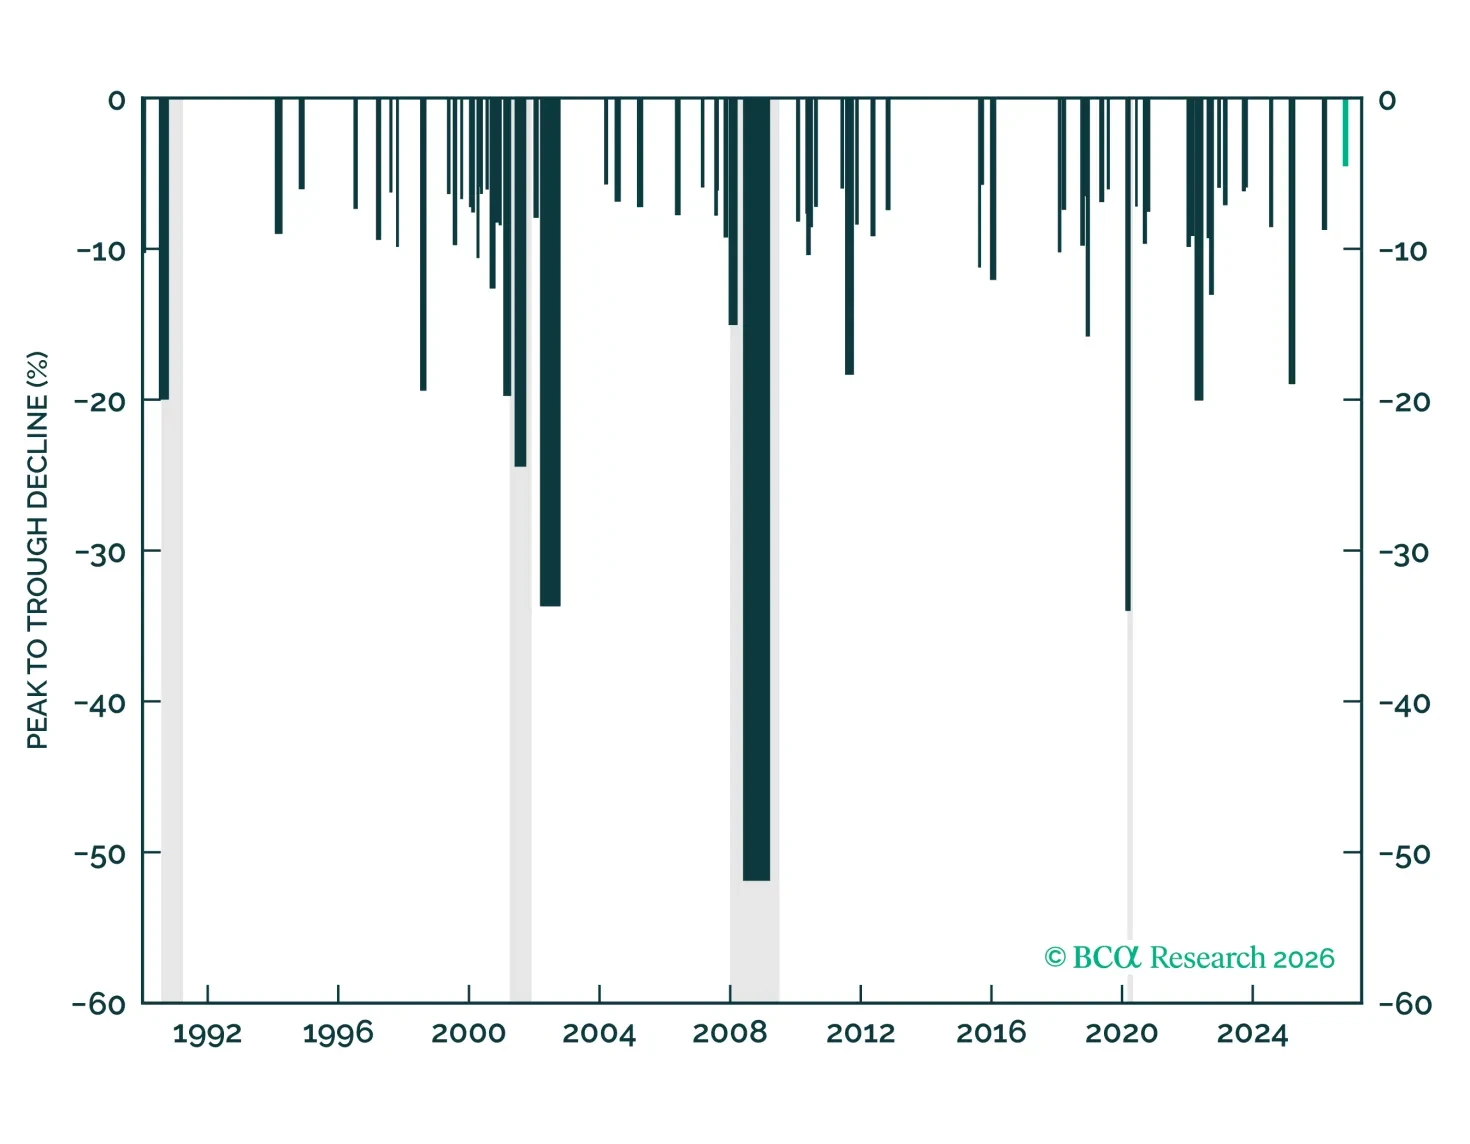
AI capex concerns have pushed the S&P 500 to the brink of a drawdown. But the cycle remains strong, drawdowns rarely last long, and Tech valuations had already compressed. And while Democratic governors now oversee about 80% of the data-center pipeline, a blue governor alone is not necessarily a build-out moratorium.
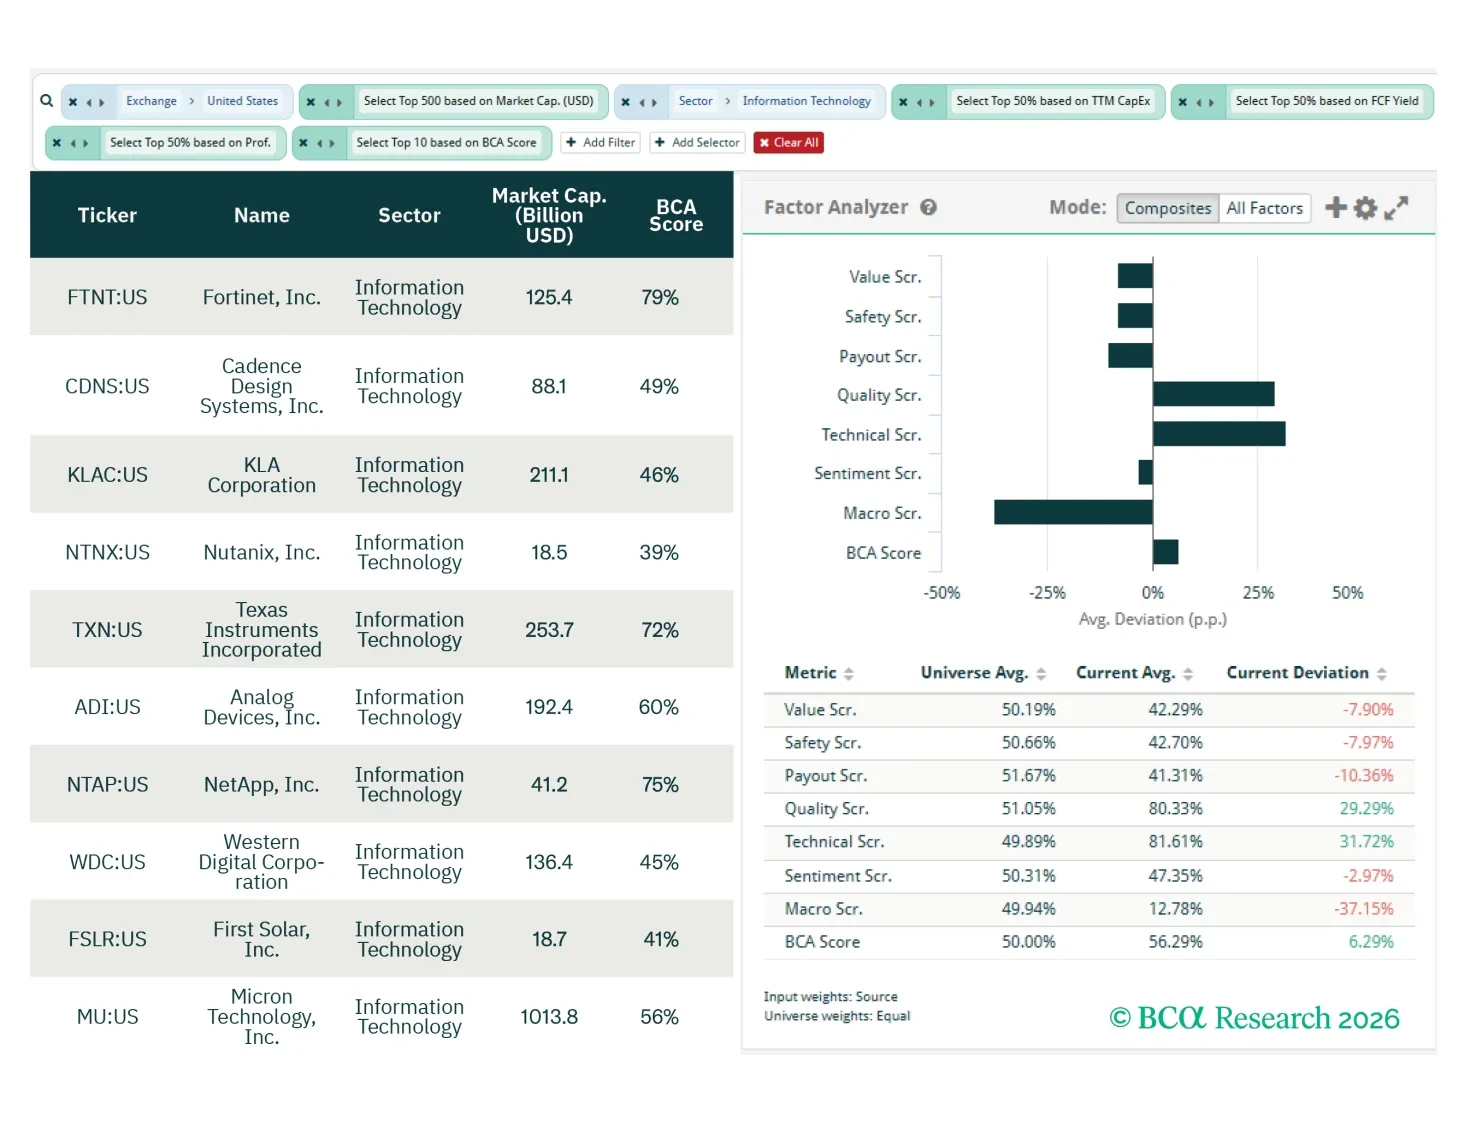
In this screener report, we explore opportunities in high-quality Tech, European integration winners, and selective US cyclicals in Industrials and Materials.
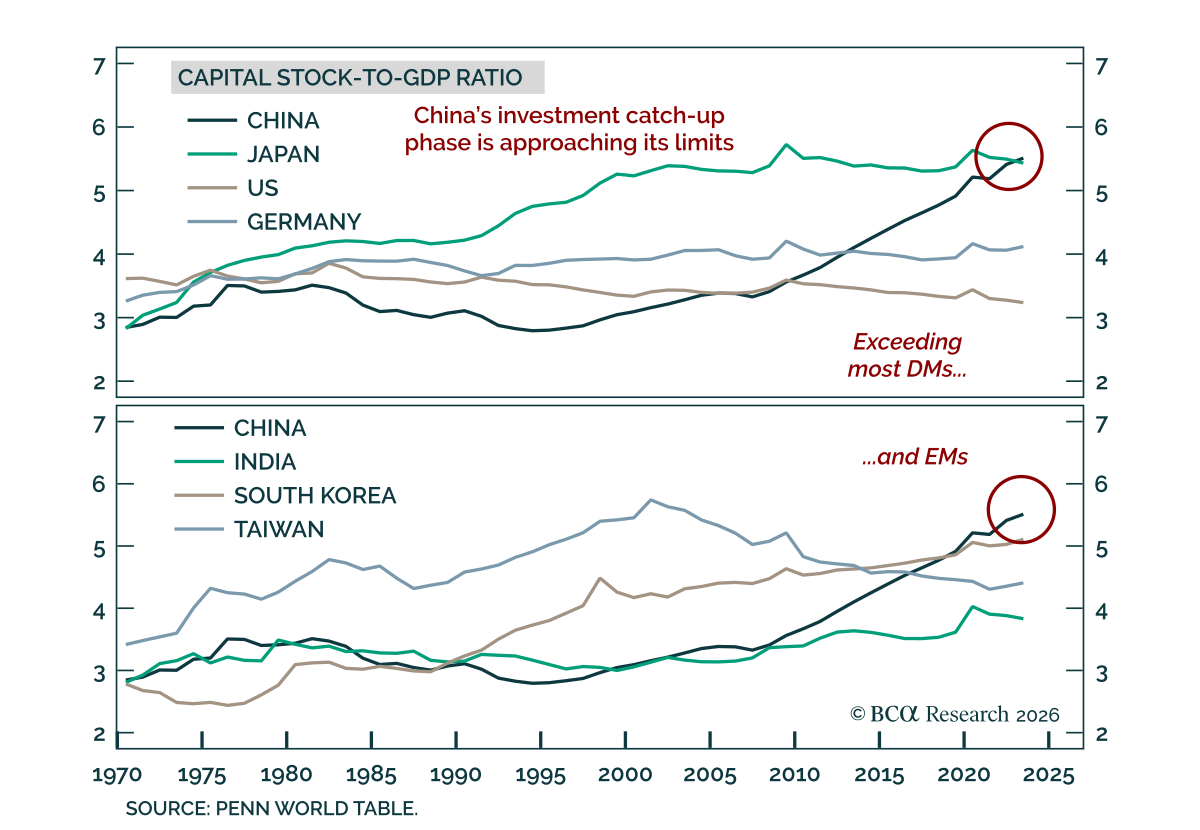
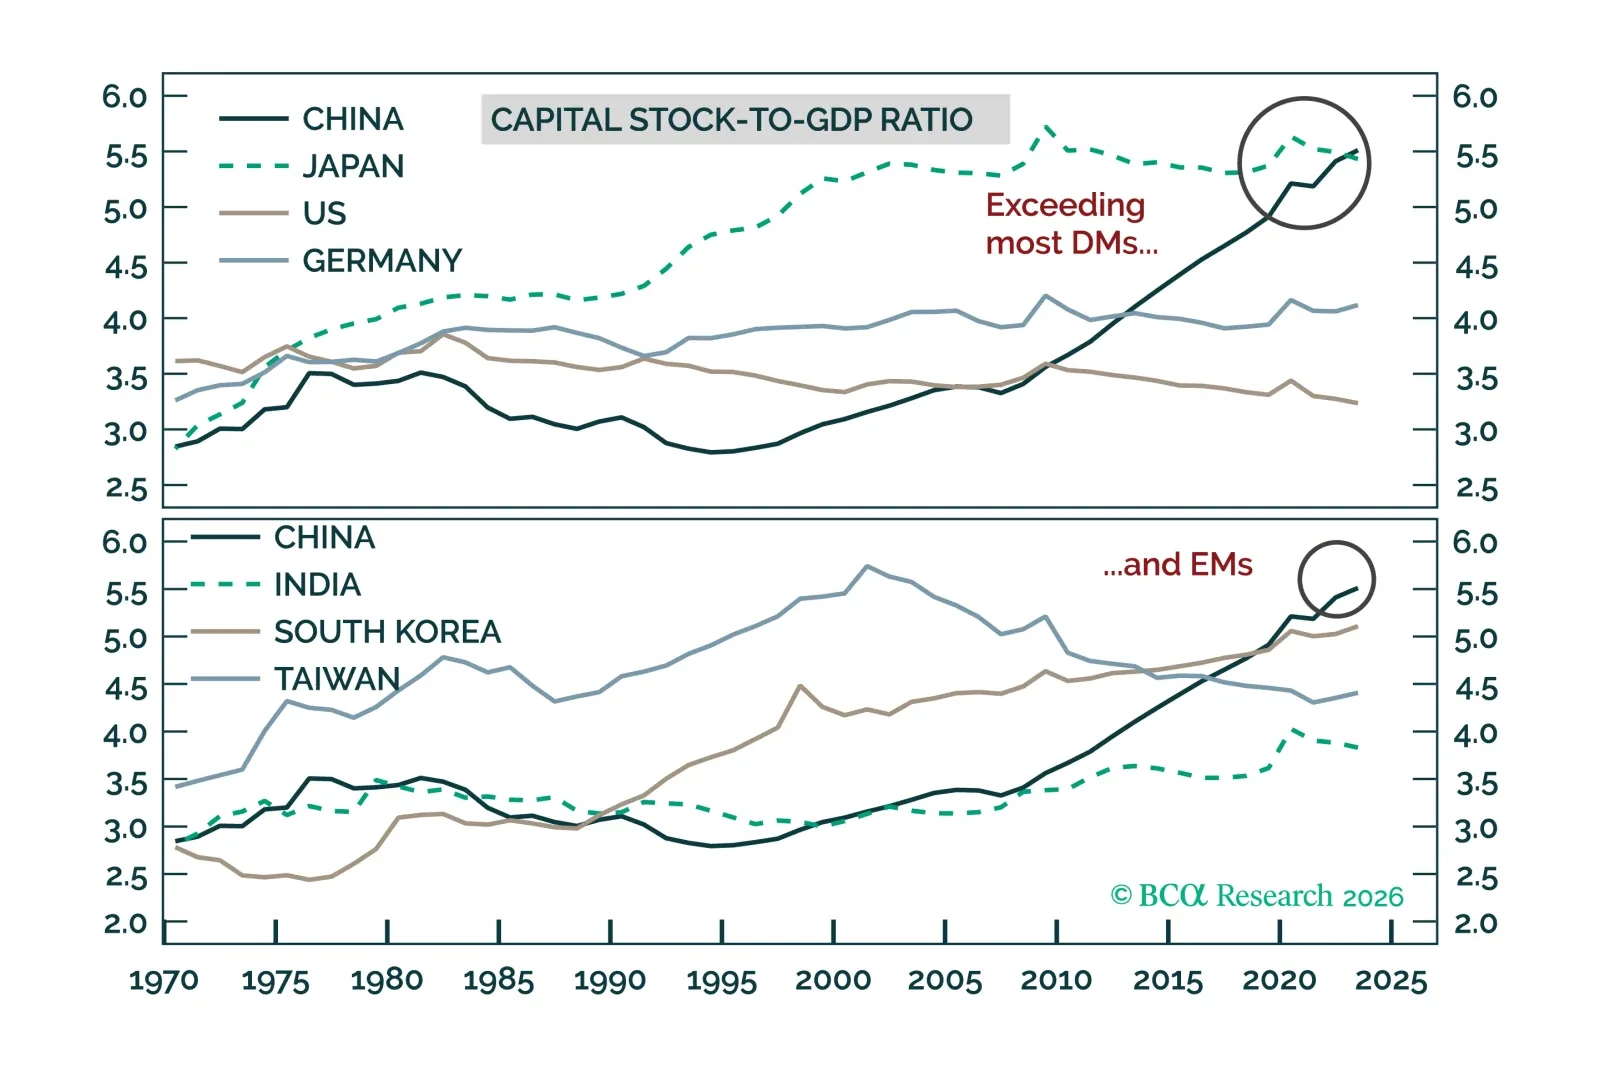
China’s investment has hit cyclical and structural limits. Mounting economic pressures will likely push Beijing toward a more aggressive, consumer-focused reflationary stance over the next one to two years.
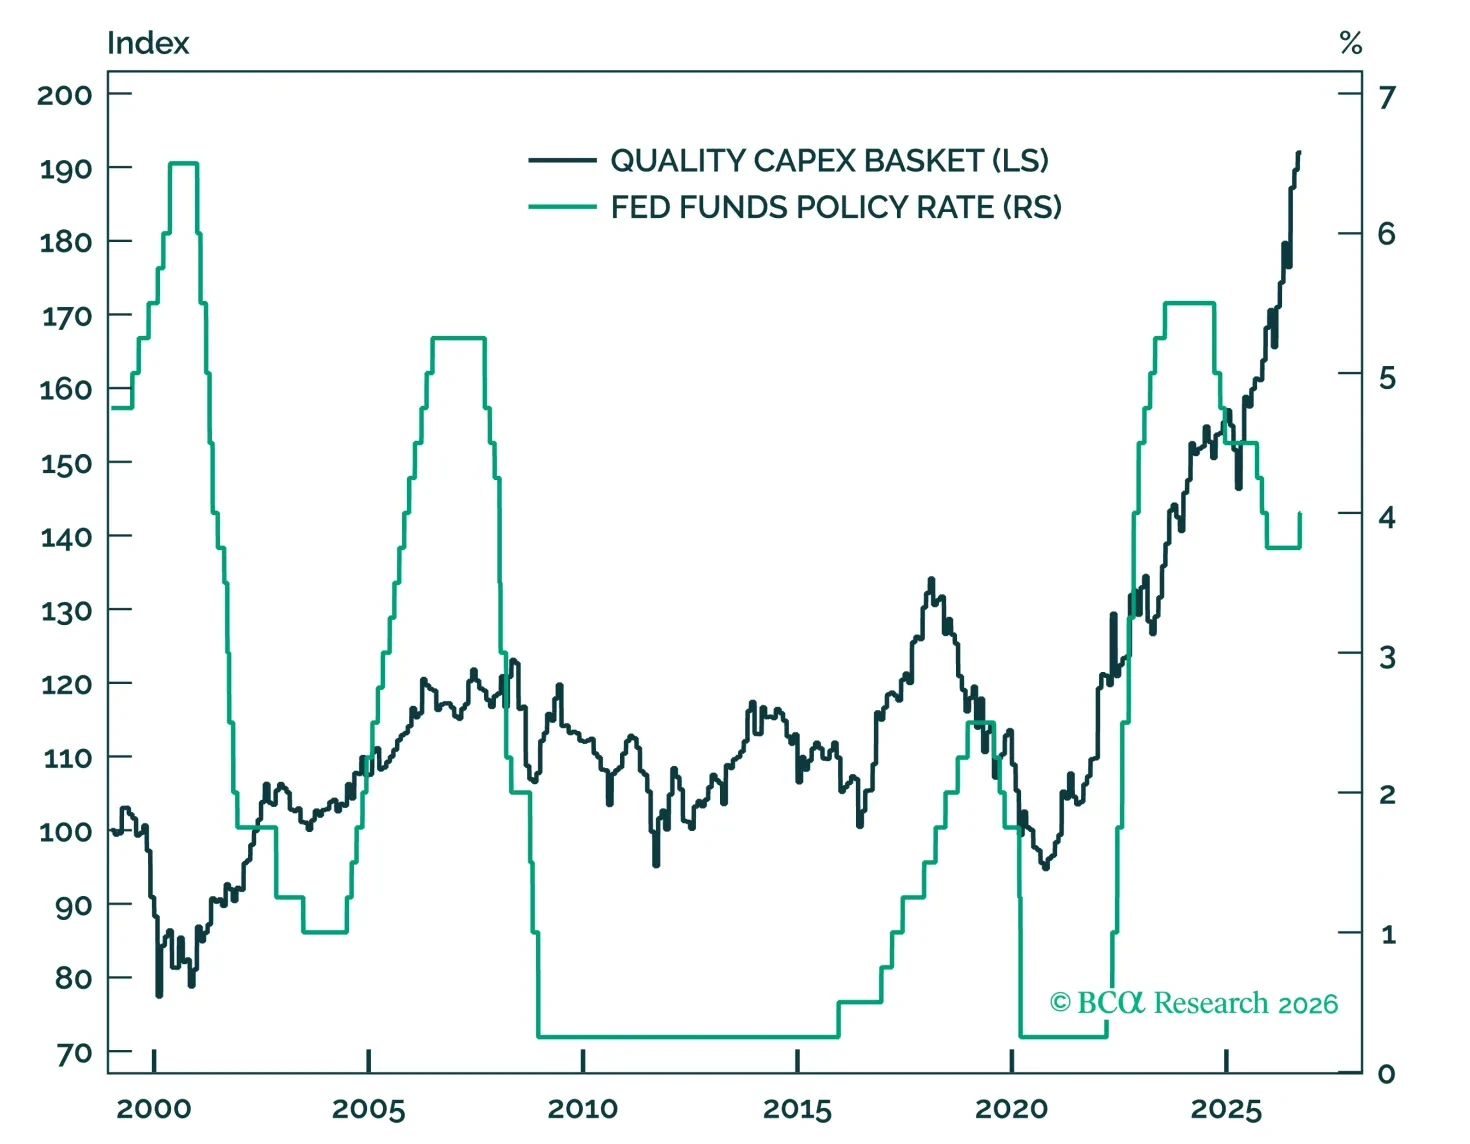
The Fed’s first hike is unlikely to be an equity-market cliff. Recent multiple compression has absorbed some of the rate shock, while bond risk premia, rate volatility, and inflation expectations remain contained. Stocks have typically climbed through hiking cycles, but we favor moving up in quality through our long/short Quality Capex Basket.
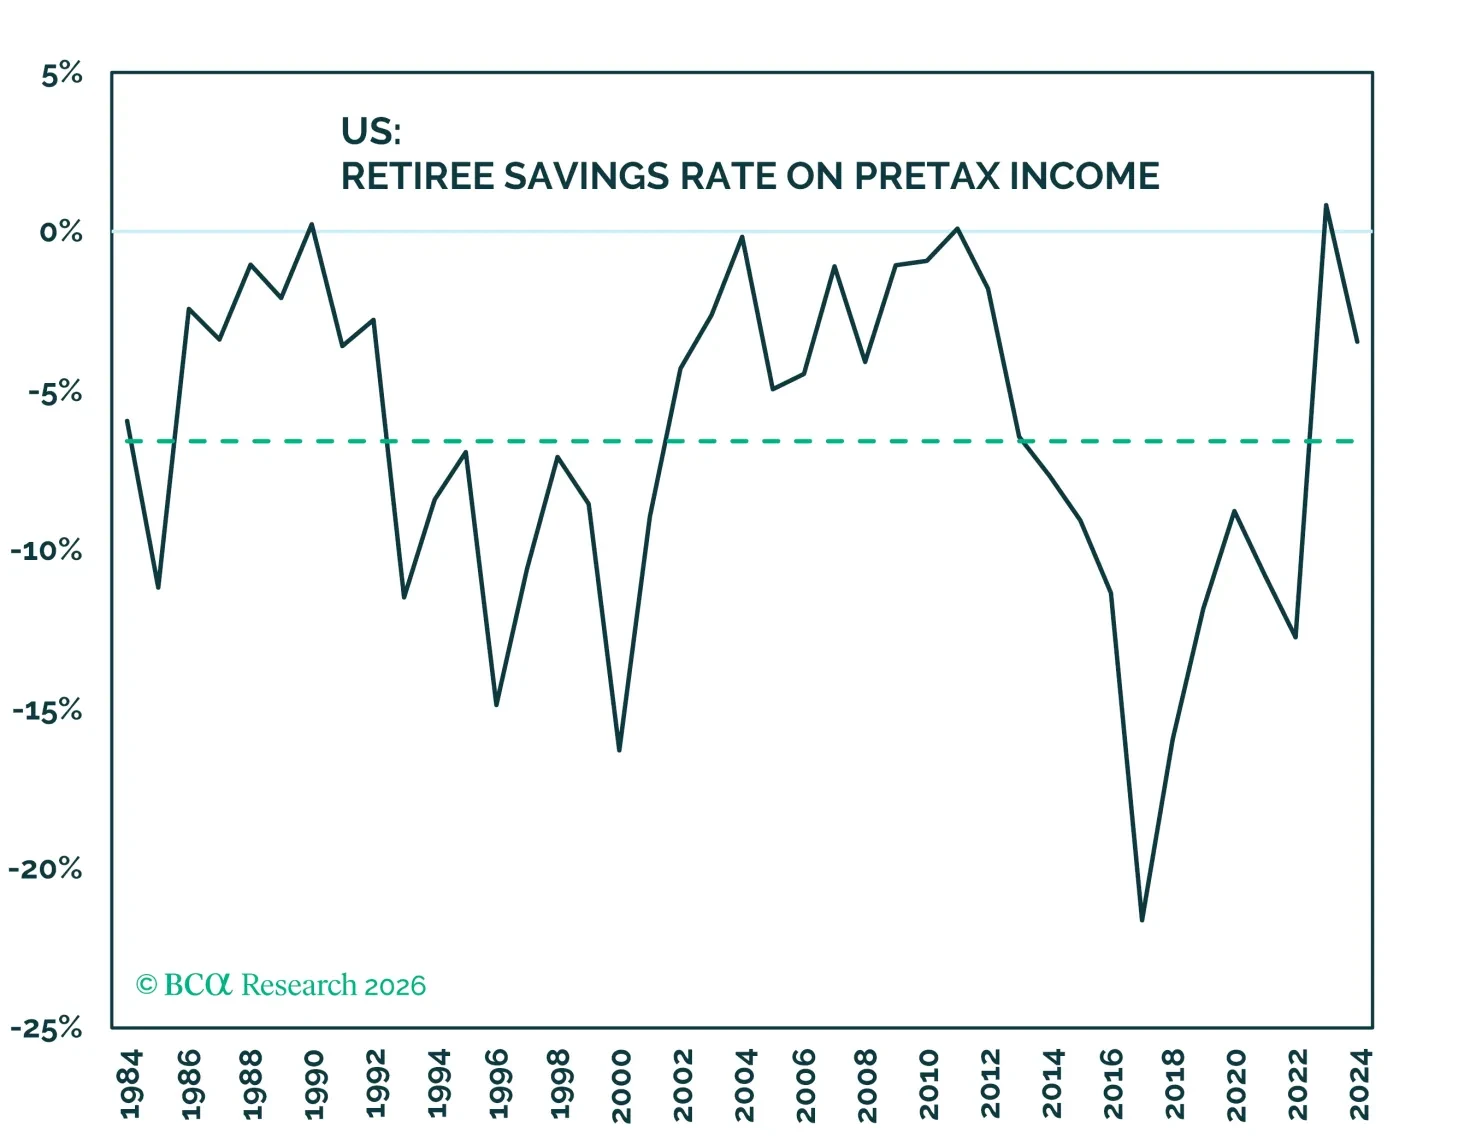
Concerns about the savings rate’s sustainability ease after adjusting for retirements and capital gains. The US economy continues to grow at a pace that is neither too hot nor too cold and investors should remain fully invested in risk assets.
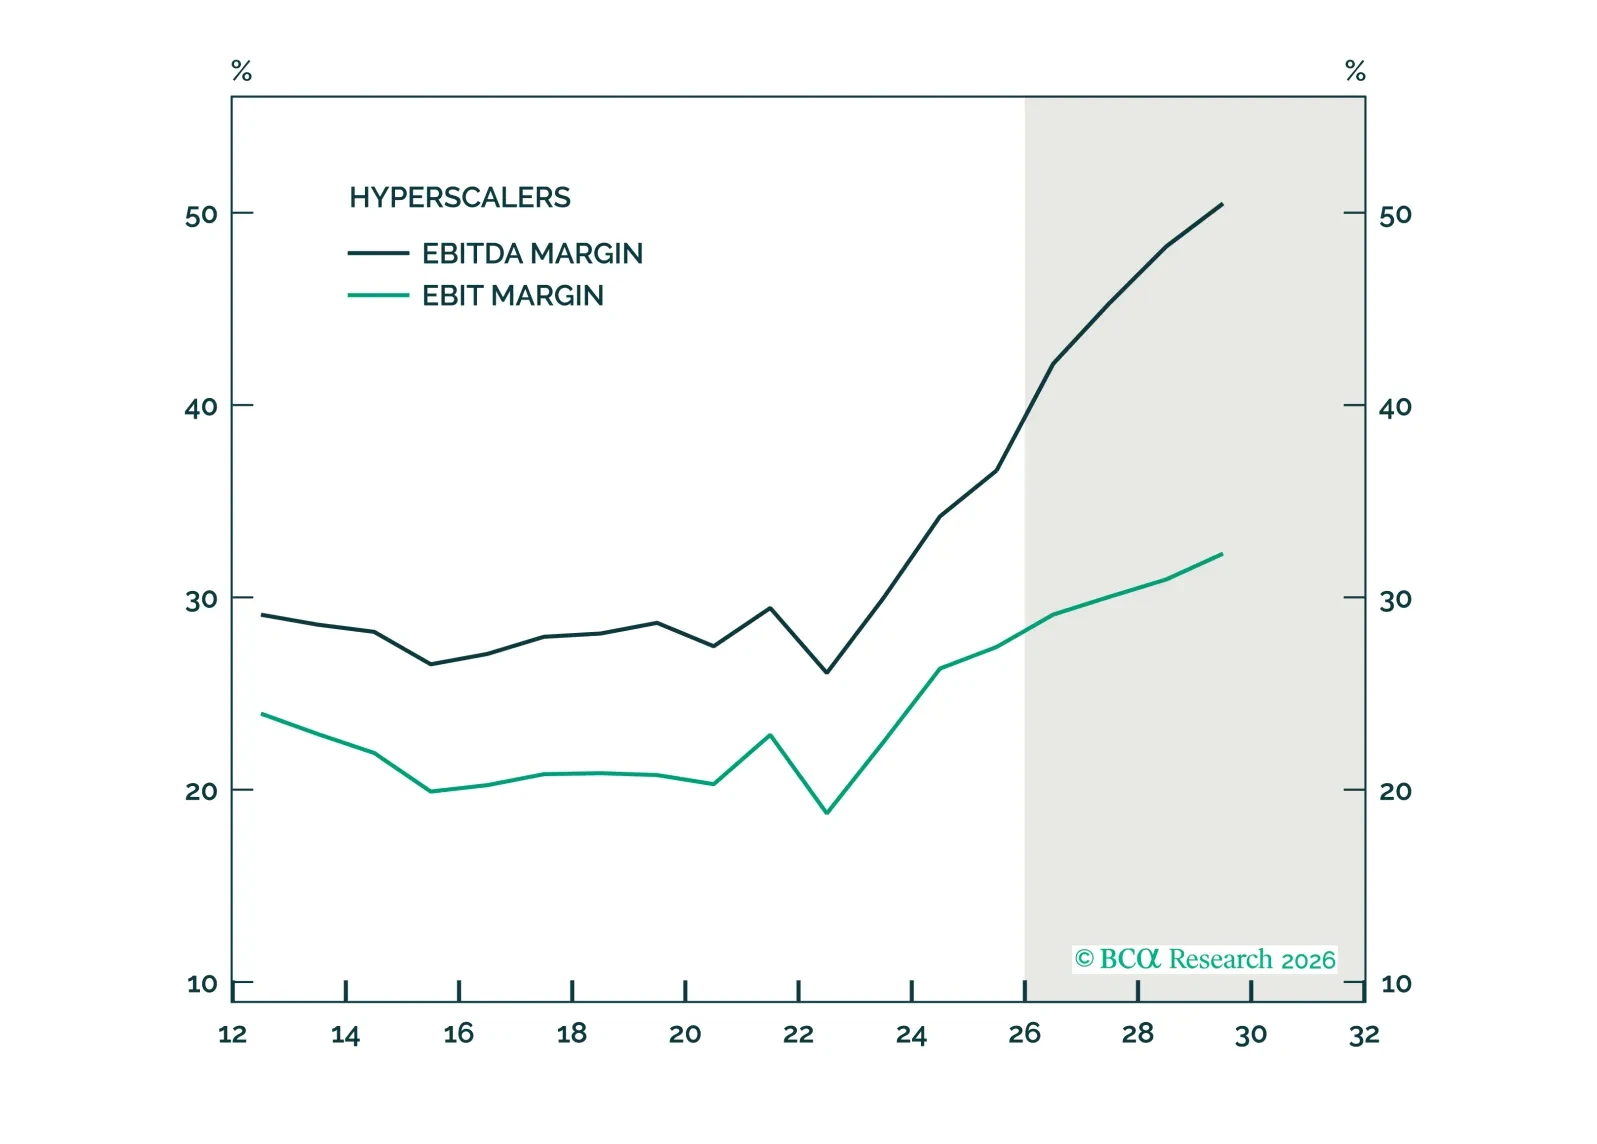
An acute shortage of AI hardware will support tech stocks into year-end. However, AI companies may need to ultimately generate $10 trillion per year in revenue to justify their capex. Barring a massive increase in productivity growth, this will be very difficult to achieve. Despite today’s Treasury announcement of upsized buyback operations, bond yields are likely to remain elevated over the coming months. Rising crack spreads have reduced the demand for crude, which is not encouraging for global growth. On the FX front, recent intervention to support the yen will probably be insufficient, but there is significant long-term upside for the currency.
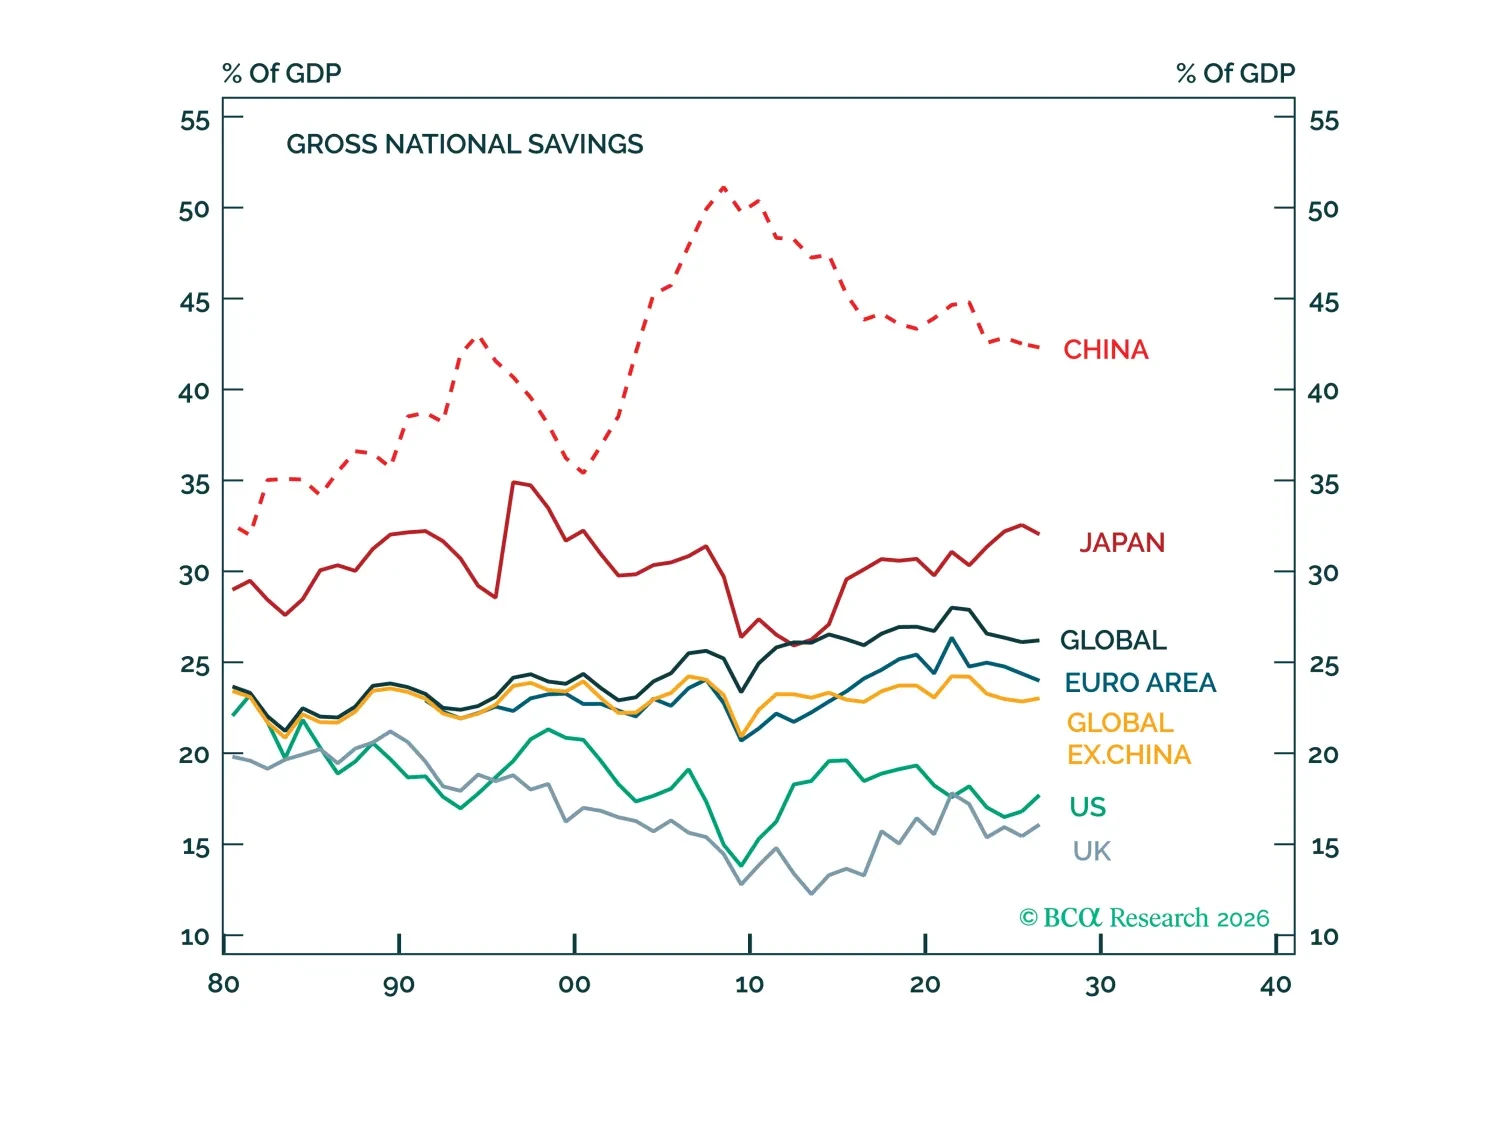
China does not produce too much. It spends too little. The only viable way for China to reduce investment without raising unemployment is by lowering national savings. Doing so is likely to be politically challenging, however. This suggests that China will suffer from subpar growth and deflationary pressures for the foreseeable future.