Latest from BCA Research
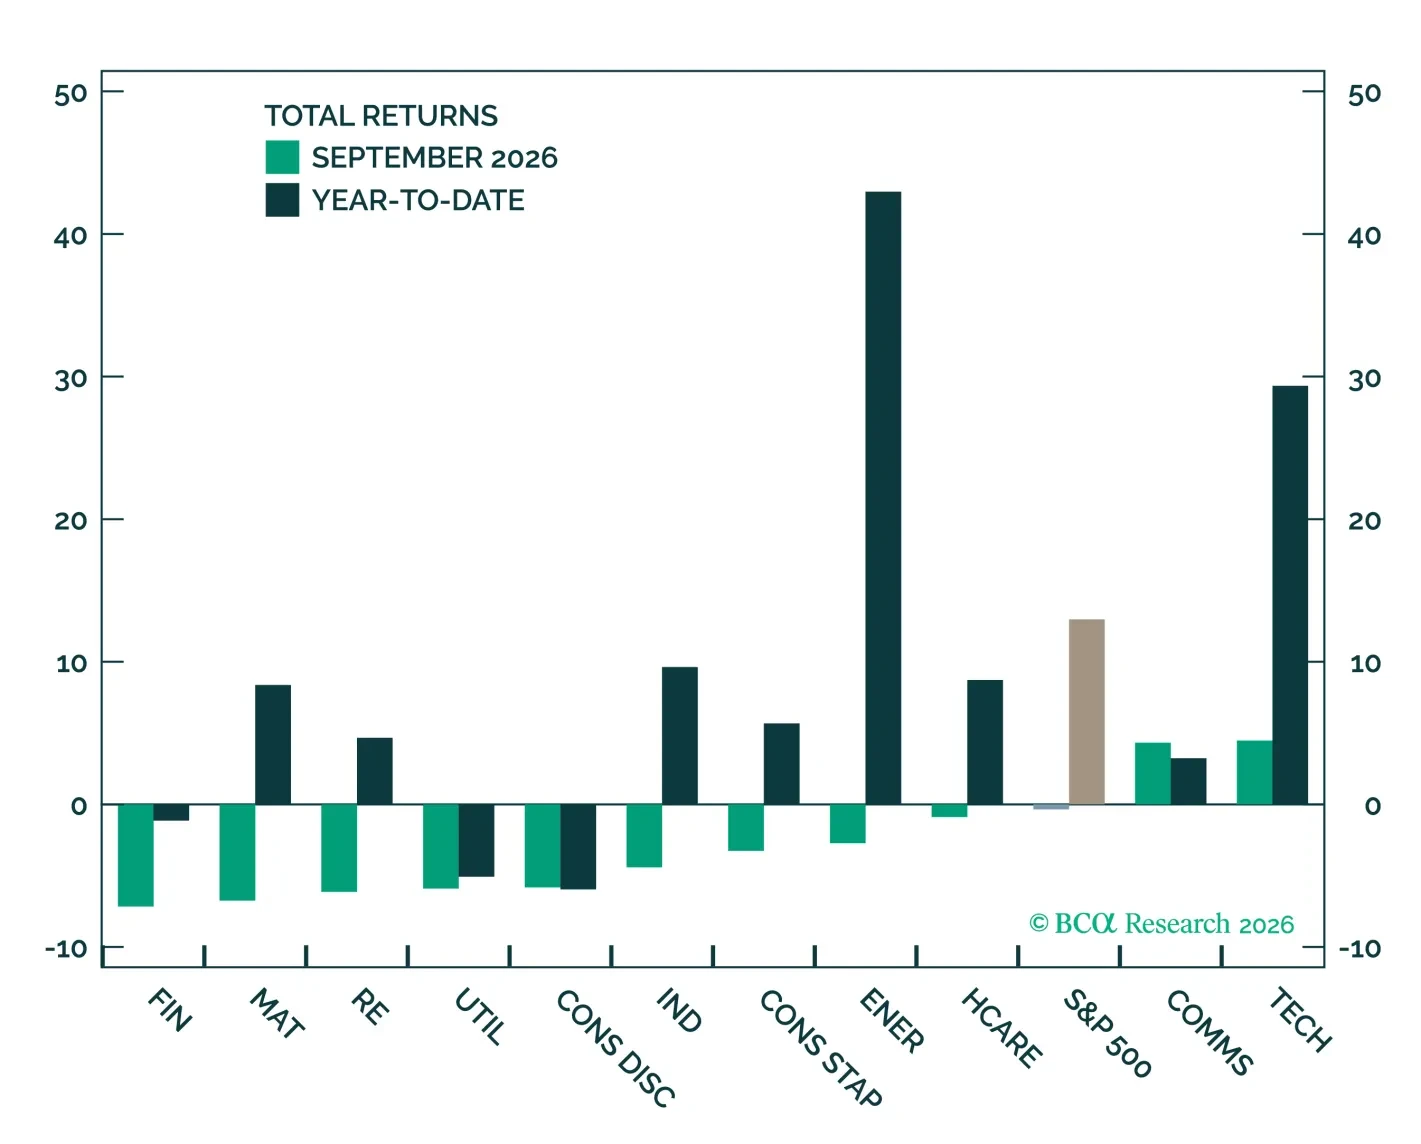
As the 10-year yield surged in September, the S&P 500 slipped but only by 0.3%, supported by Technology and Communication Services. We see upside into year end, with bond yields remaining the key risk.
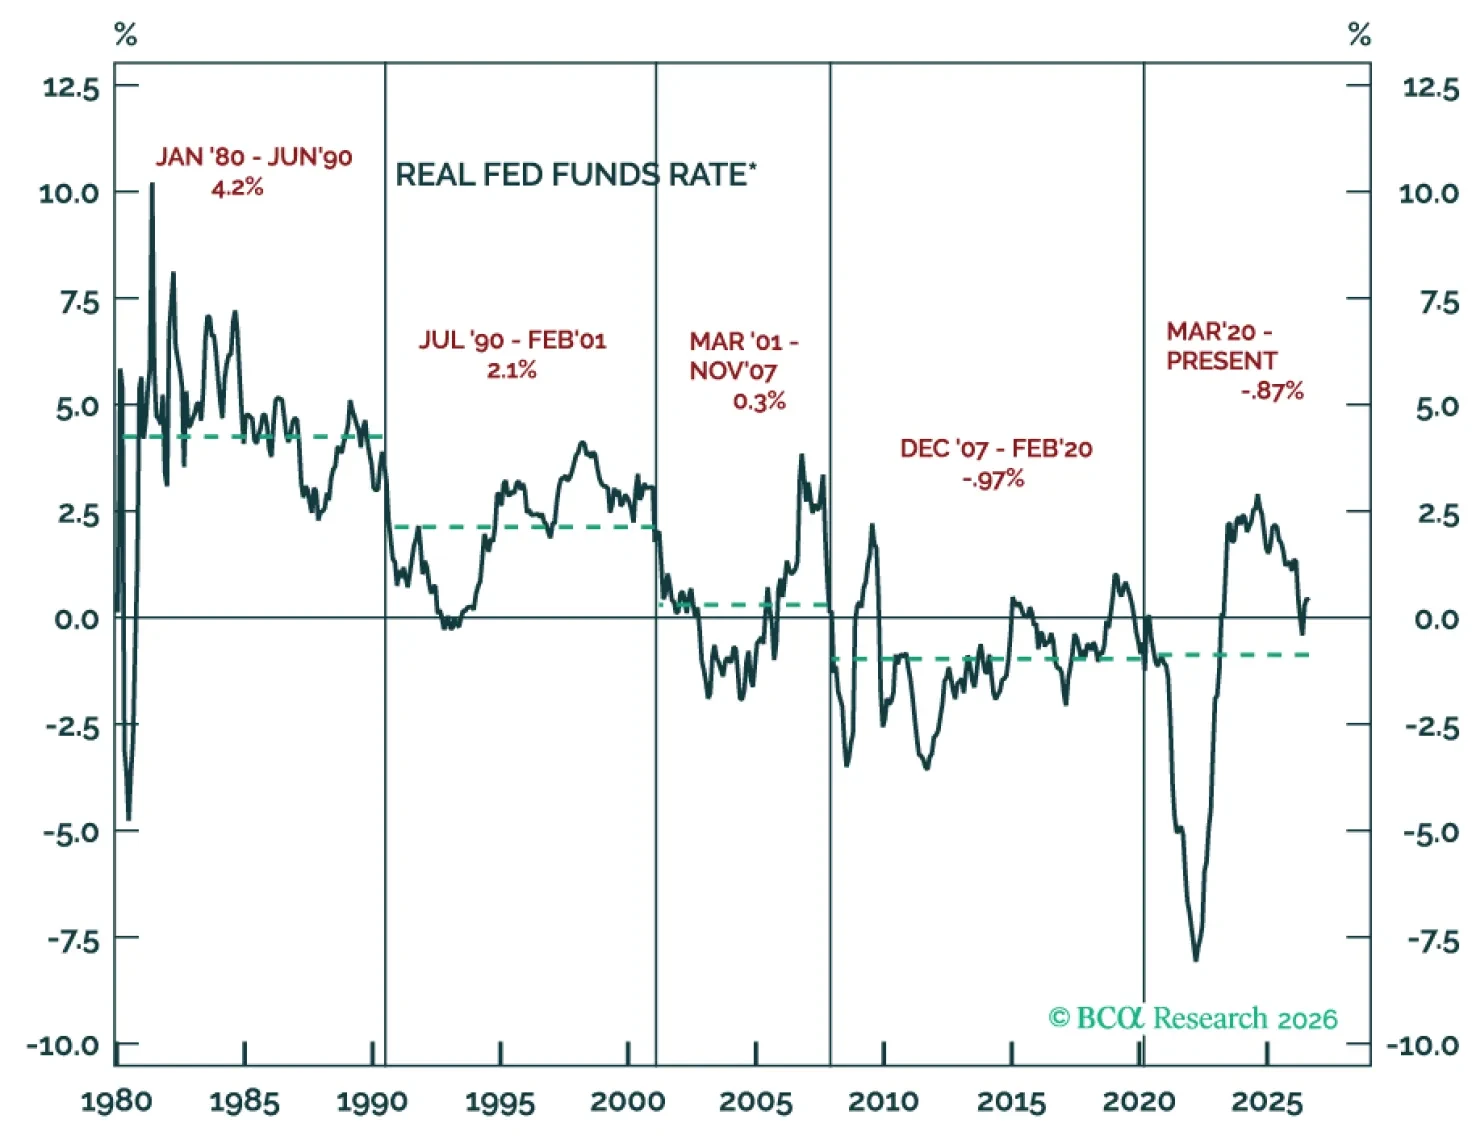
Rising rates don’t halt bull markets but real yields exceeding the economy’s potential long-run growth rate could. That relative level could lead to a stock-bond collision if it persisted long enough to slow the economy.
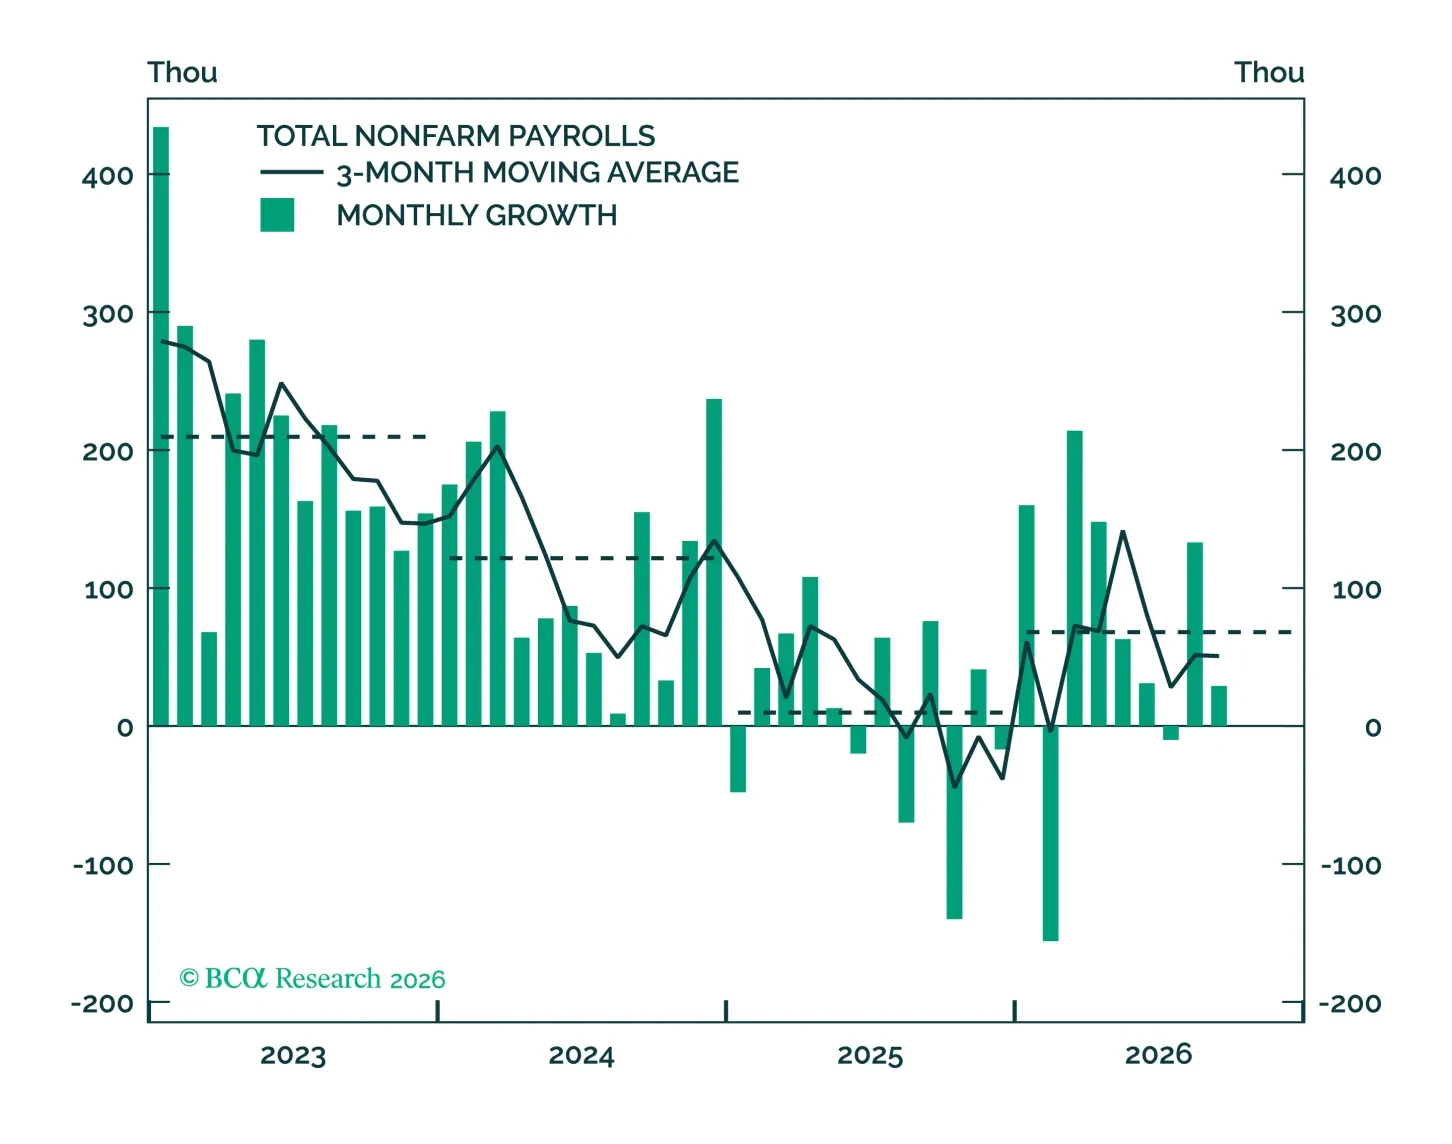
This morning’s jobs report serves to underscore that the labor market is not a source of inflationary pressure and therefore of second-order importance when it comes to the Fed’s near-term decision making.
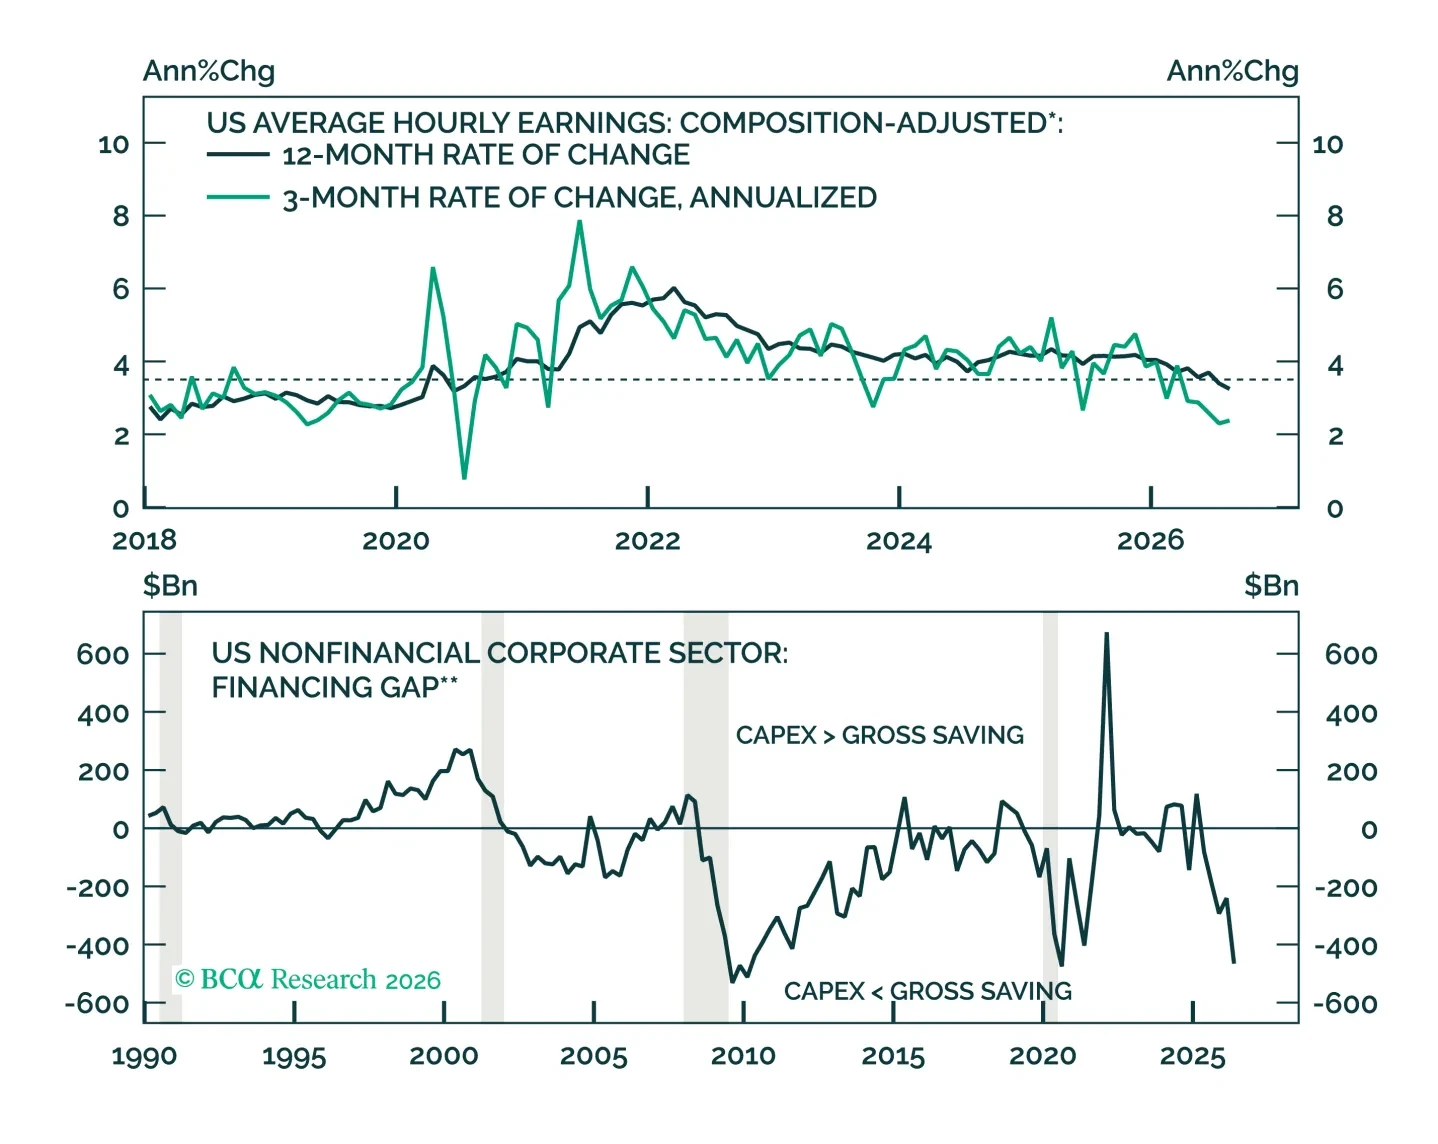
Politics, wars, a global tightening cycle, doubts over AI capex: the wall of worry keeps rising. But the spark that would topple risk assets is missing. Our Q4 FICC outlook explains why to stay long risk, and where the danger lies.
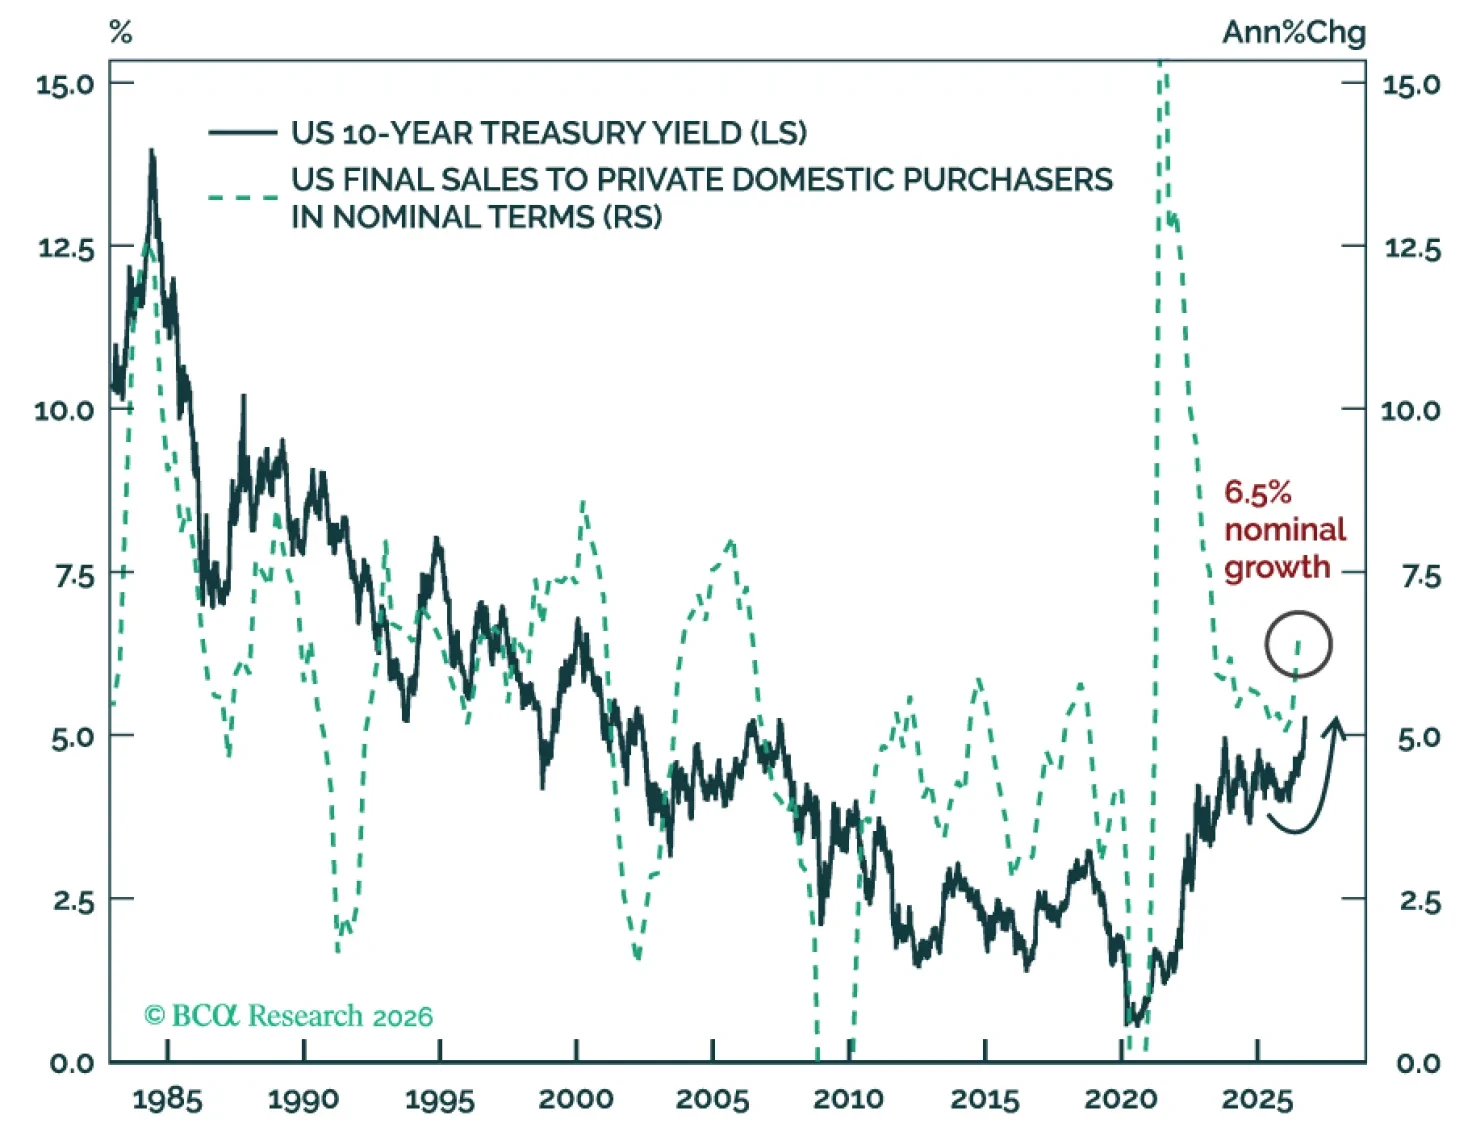
US bonds will likely continue selling off until tighter financial conditions – most plausibly a double-digit decline in the S&P 500 – cool nominal growth. Higher discount rates will threaten US equity valuations before earnings weaken. AI stocks will peak well ahead of AI capex. Remain downbeat on EM stocks.
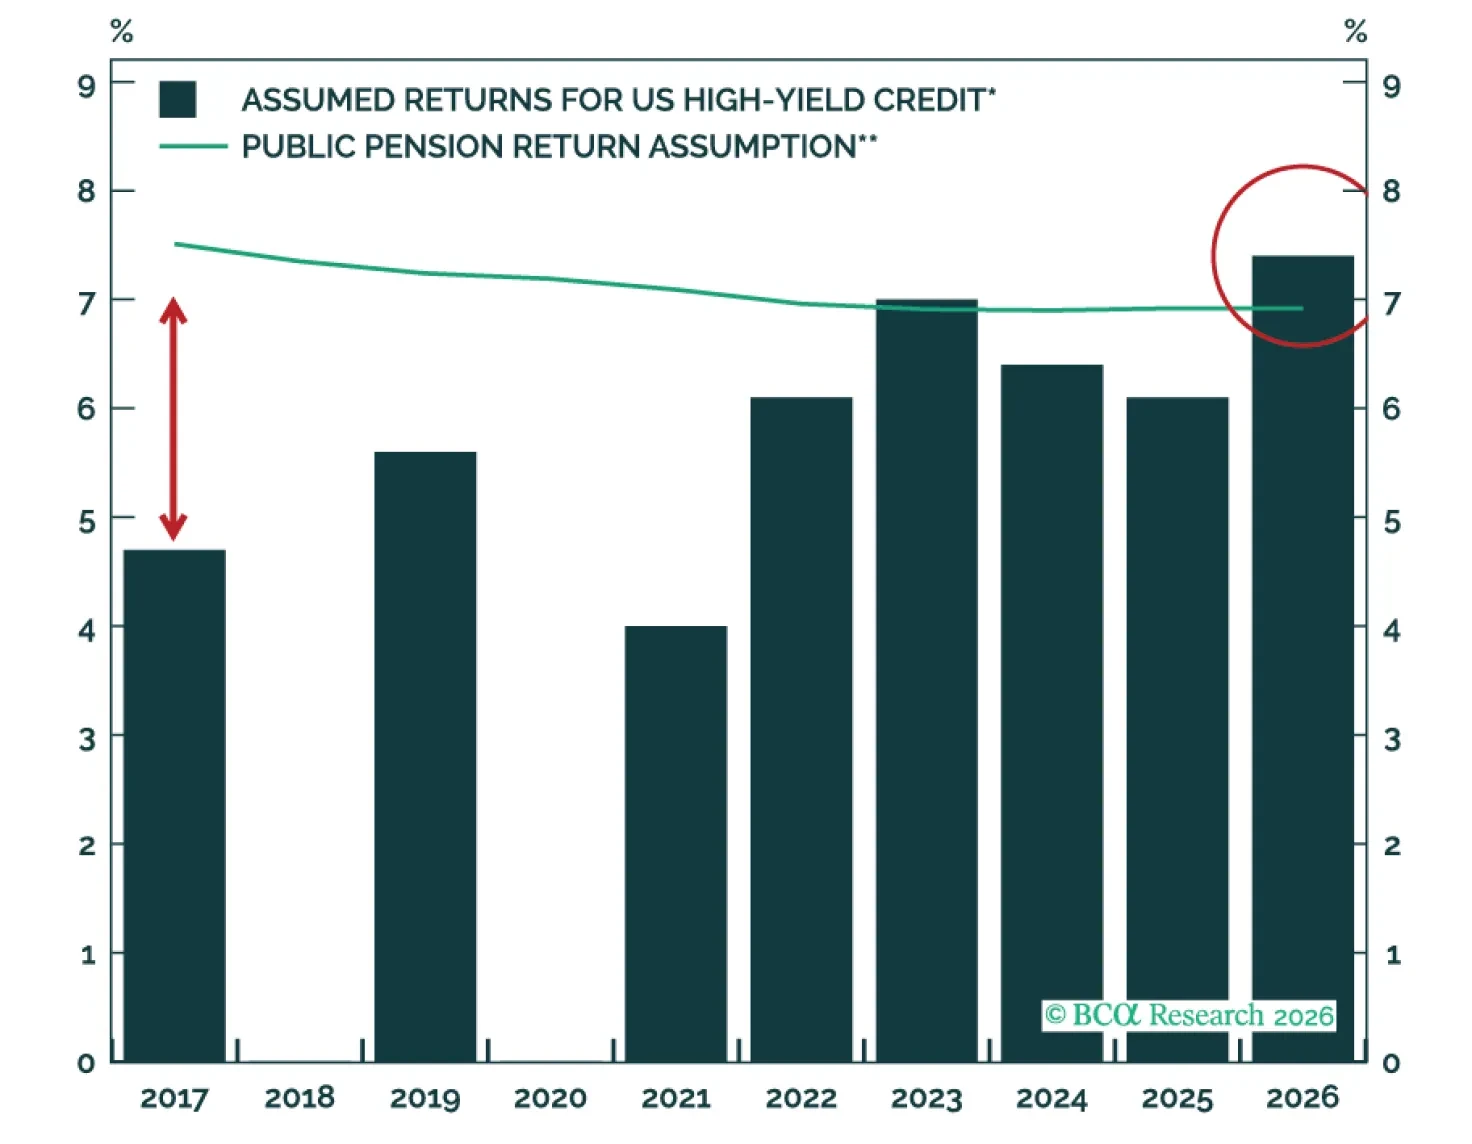
Higher rates have changed the opportunity set. Overweight High-Yield Credit, both within asset allocation and versus Private Credit. Investors are no longer picking up pennies in front of a steamroller.
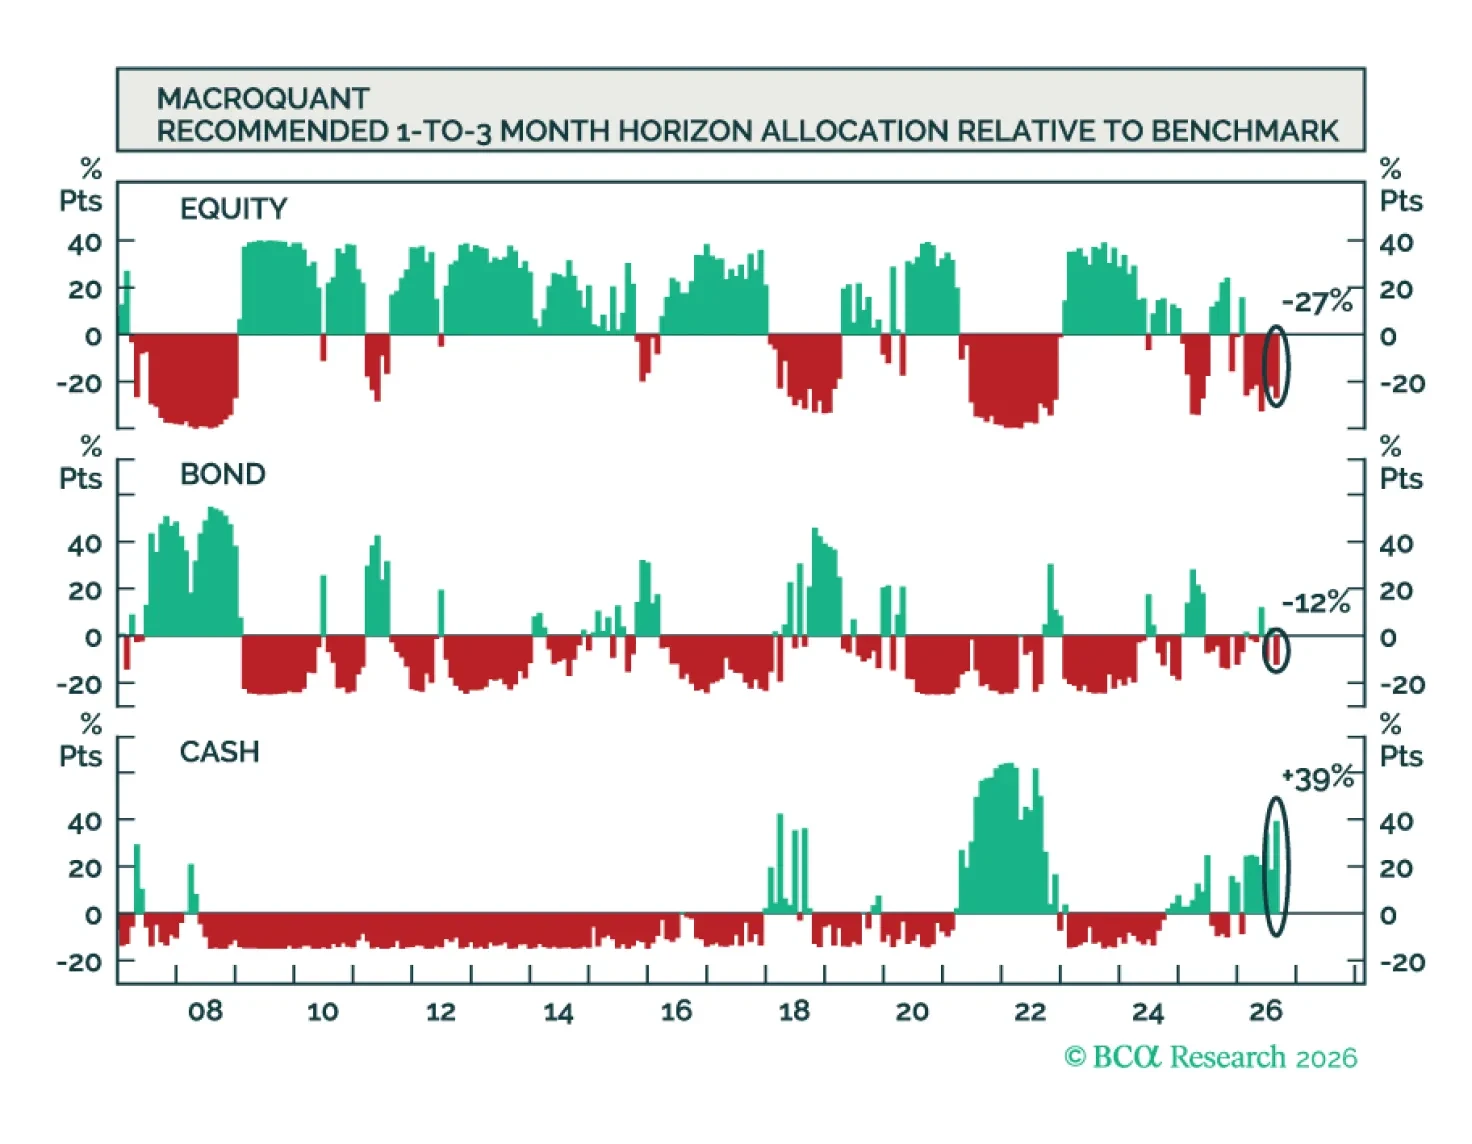
MacroQuant recommends an underweight to equities and bonds, counterbalanced by a significant overweight to cash. The model is very bullish on the US dollar, slightly negative on gold and copper, and positive on oil.
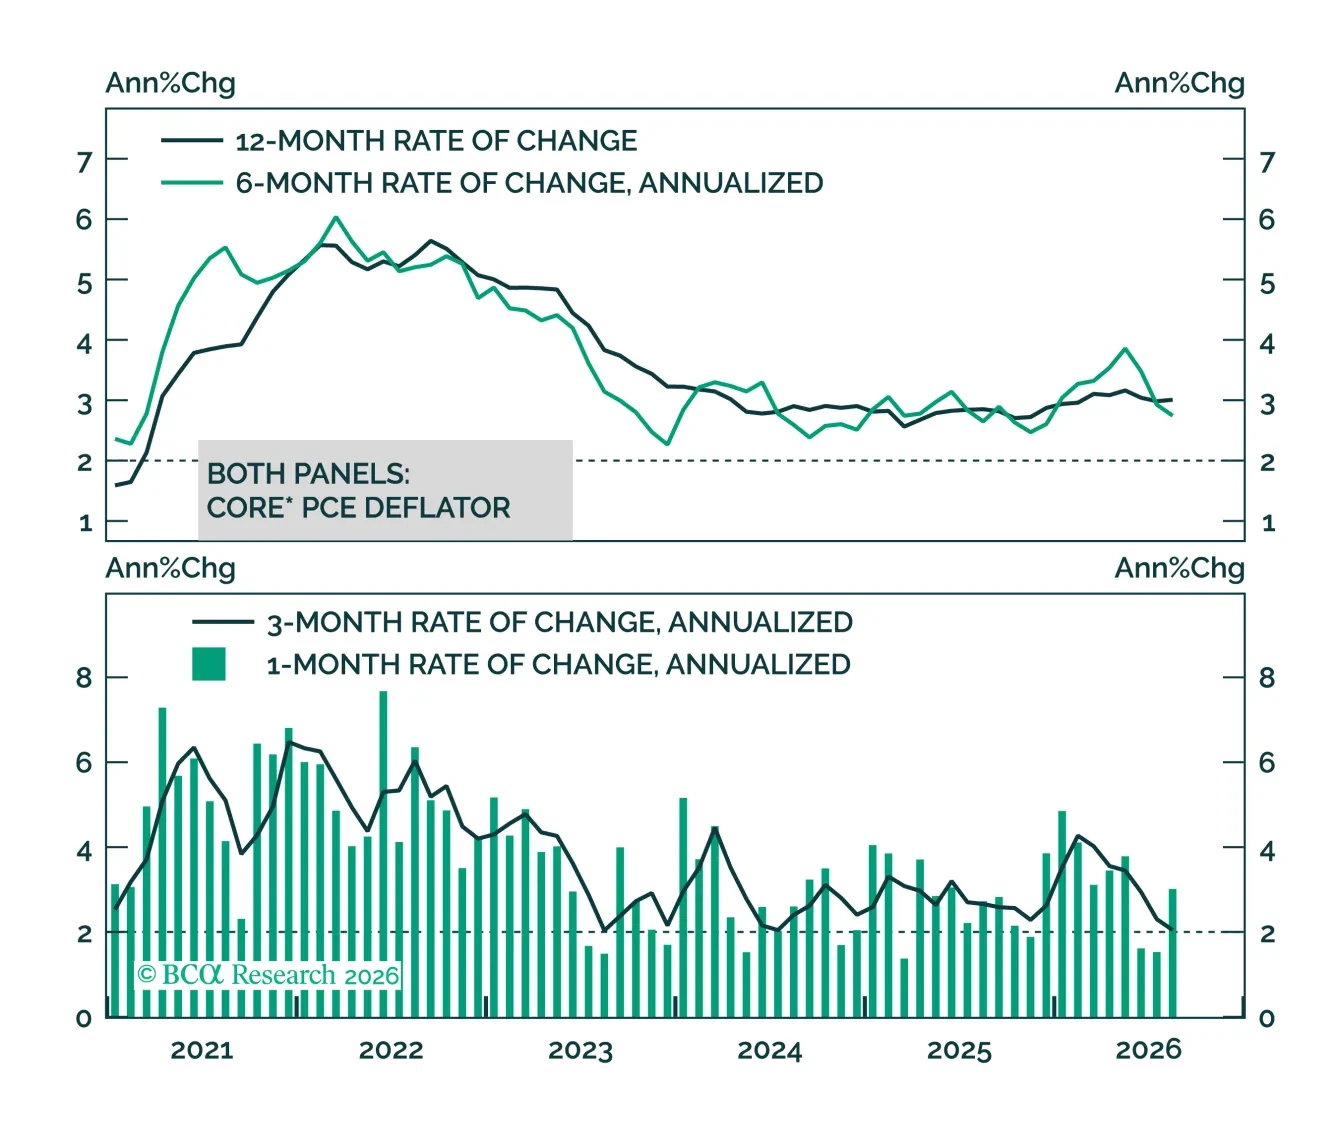
Core US inflation is still running above target. But this morning’s data revisions reveal that the gap is not nearly as large as it appeared yesterday.
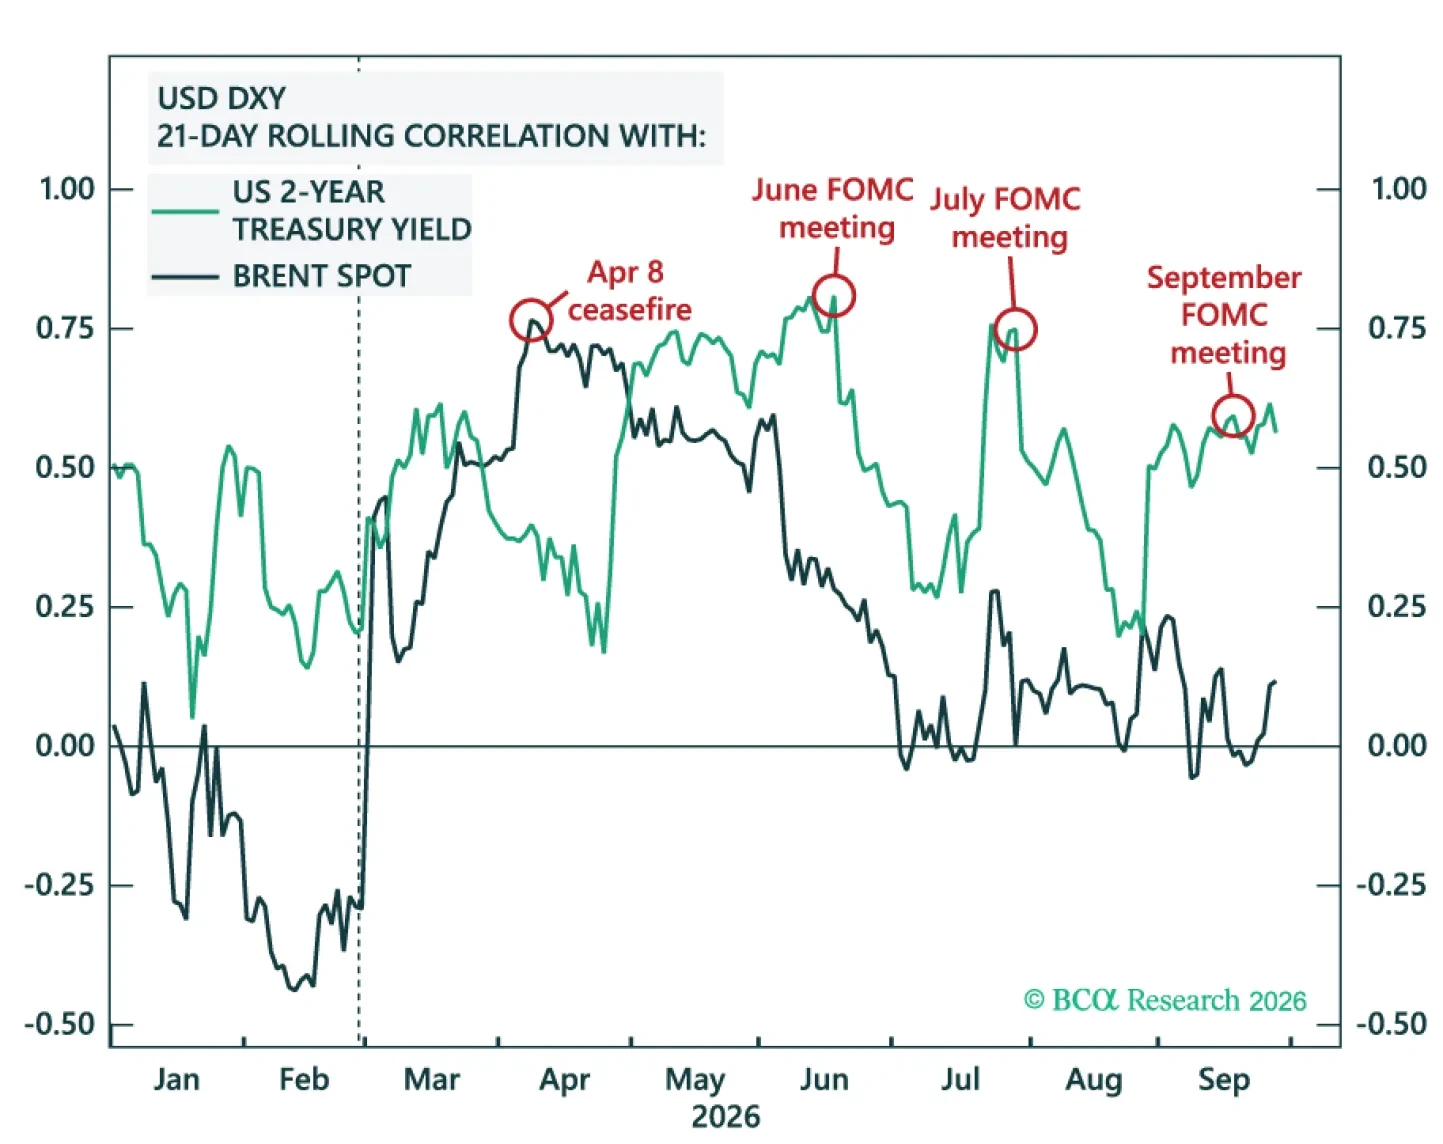
Global capex is driving the strongest industrial cycle since 2021. The US is best positioned to capture the gains and to weather near-term risks, supporting widening real-rate differentials and favoring continued upside in the dollar in the coming months.