Latest from BCA Research
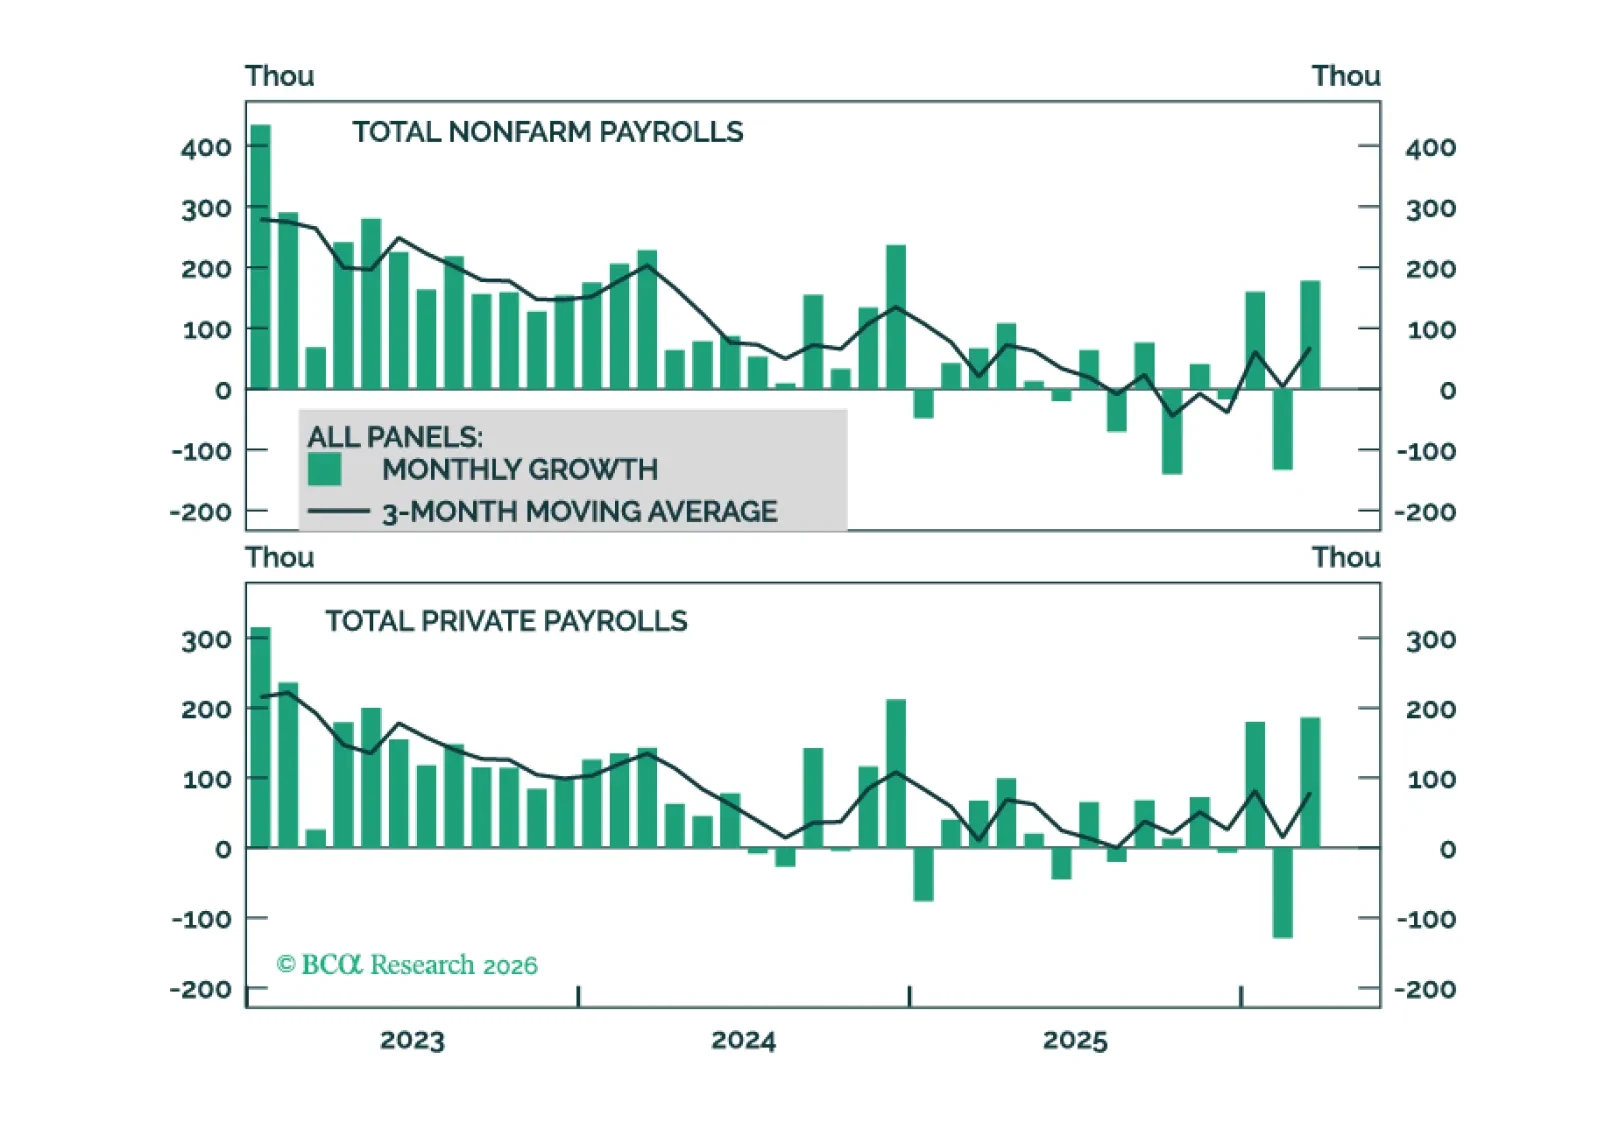
US employment data show some tentative signs of job growth acceleration and stable utilization. We see breakeven monthly job growth as closer to +30k per month than zero.
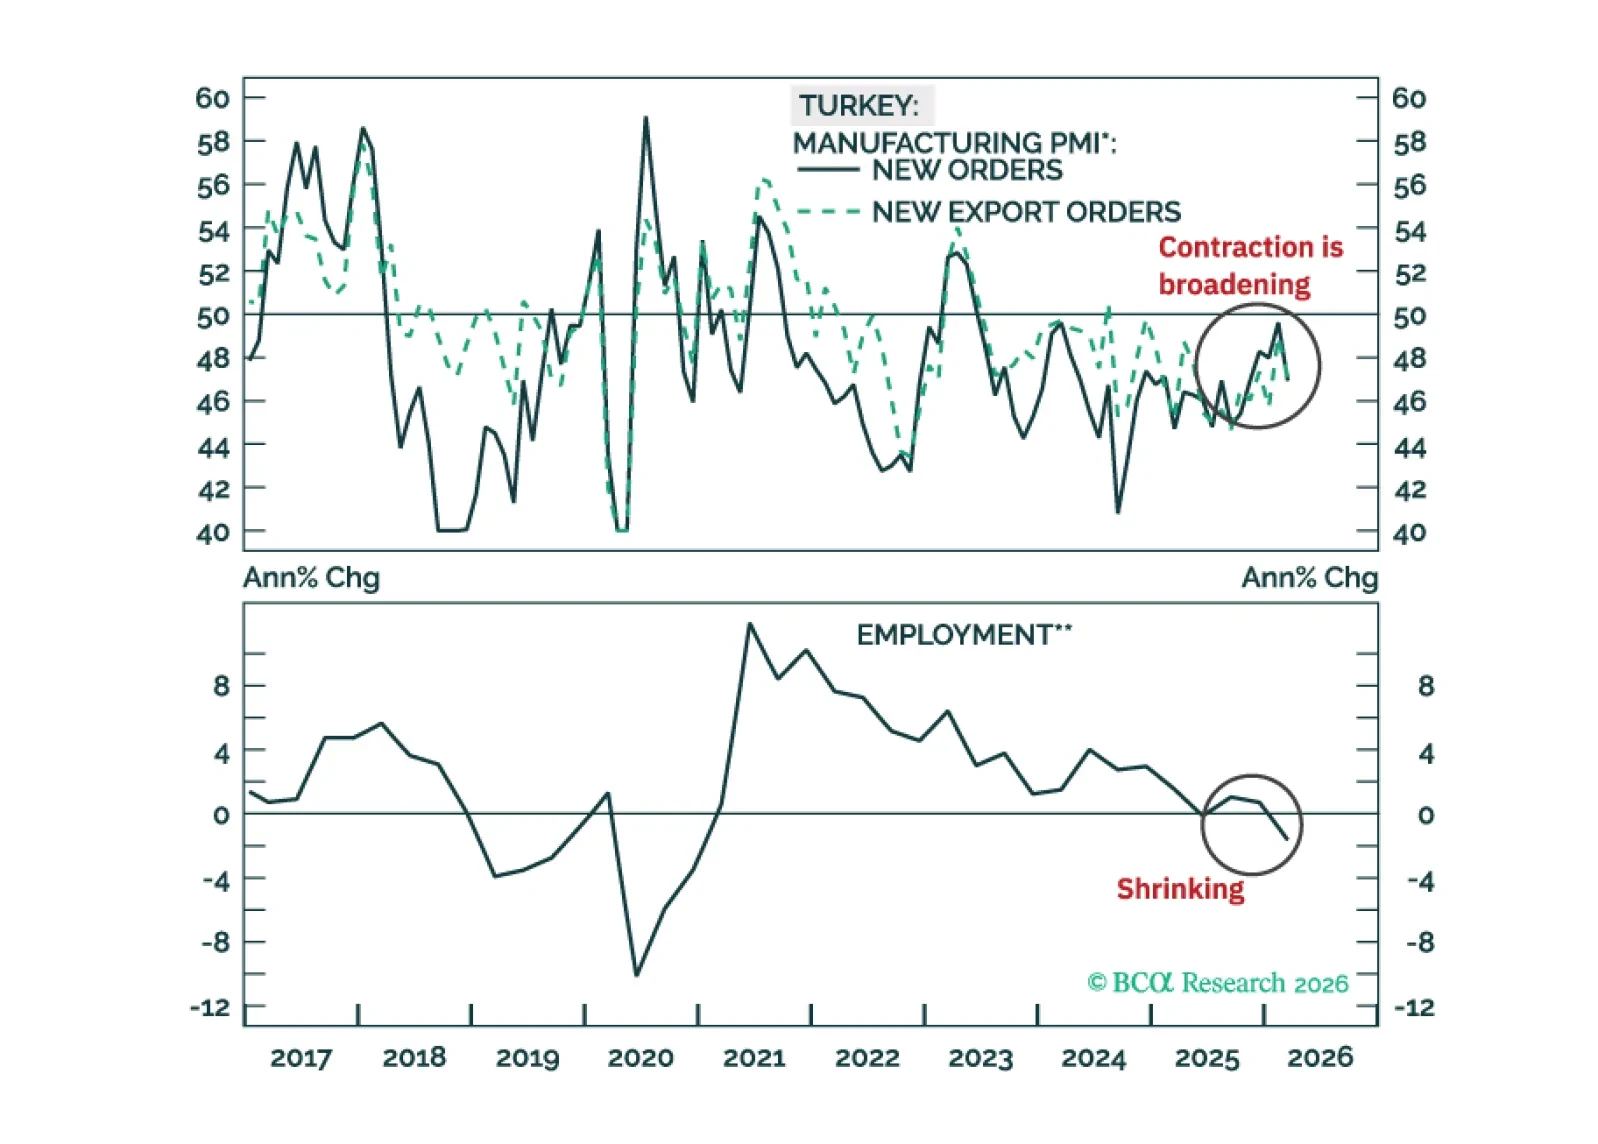
The Turkish financial markets will struggle in the very near term, but beyond that, the cyclical disinflation process will resume. Fixed-income investors should put Turkish 2-year local currencybonds on a ‘buy’ watch list.
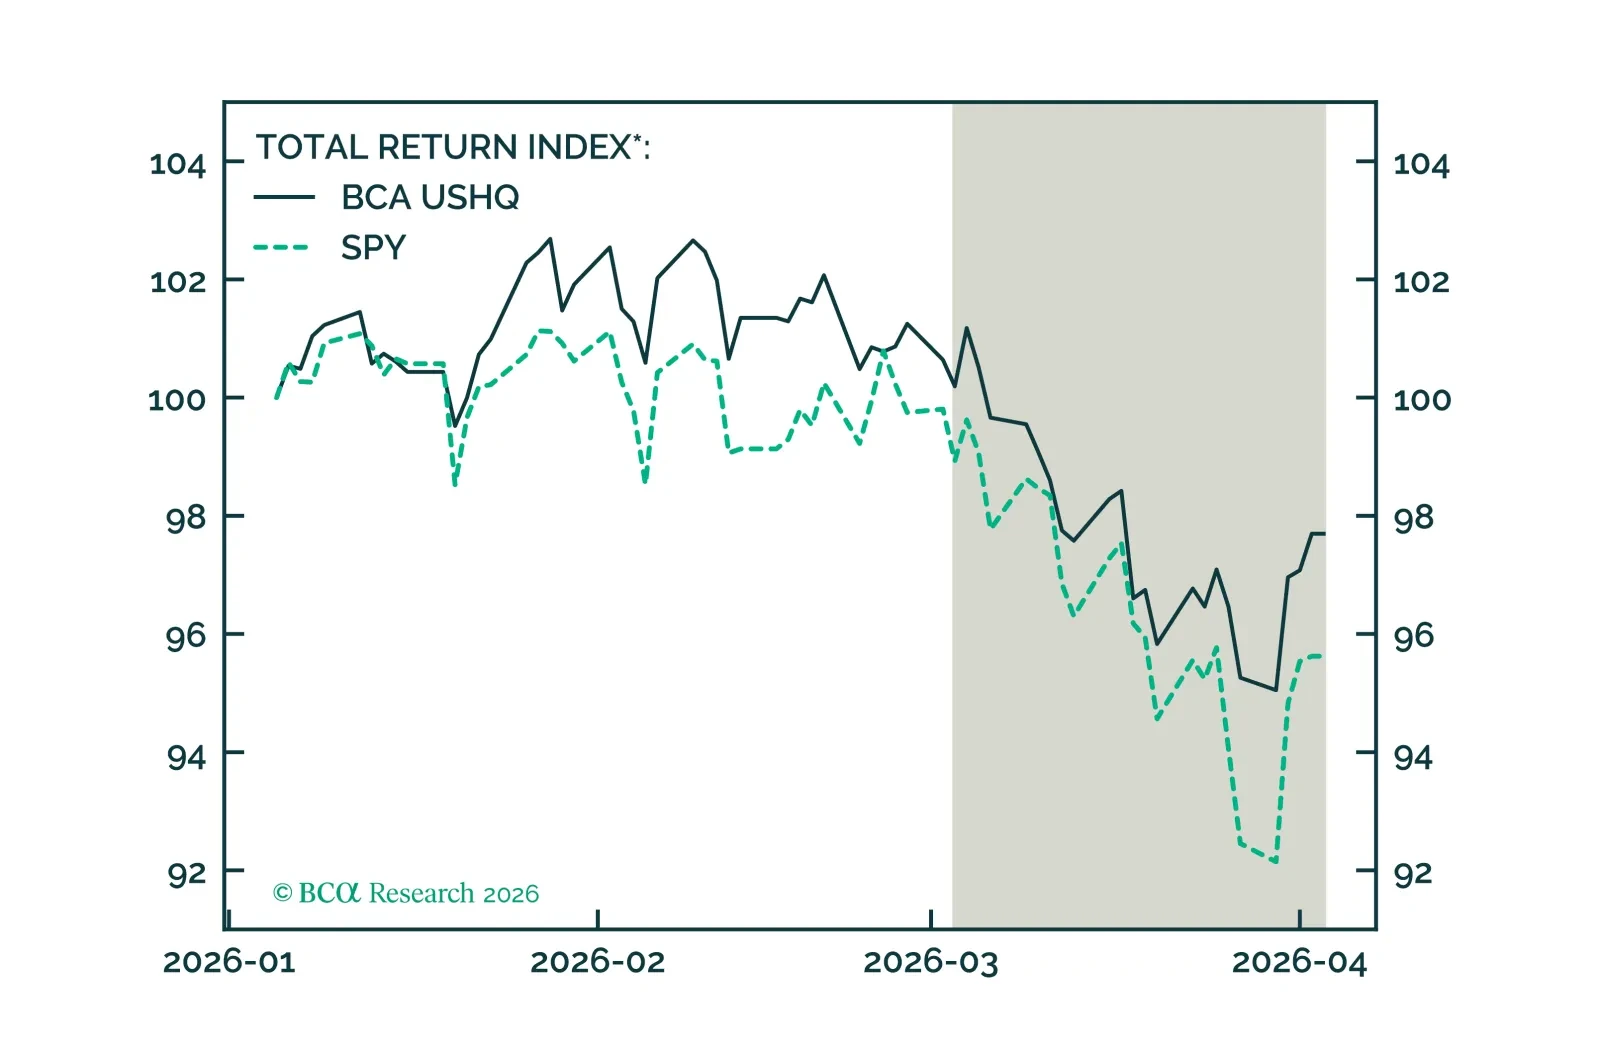
The US High Quality (USHQ) portfolio continues to outperform its benchmark through March, returning -2.49%, while its SPY benchmark returned -3.34%. On a trailing three-month basis, the USHQ portfolio’s performance was stronger than the benchmark as well, with USHQ outperforming by approx. 208bps.
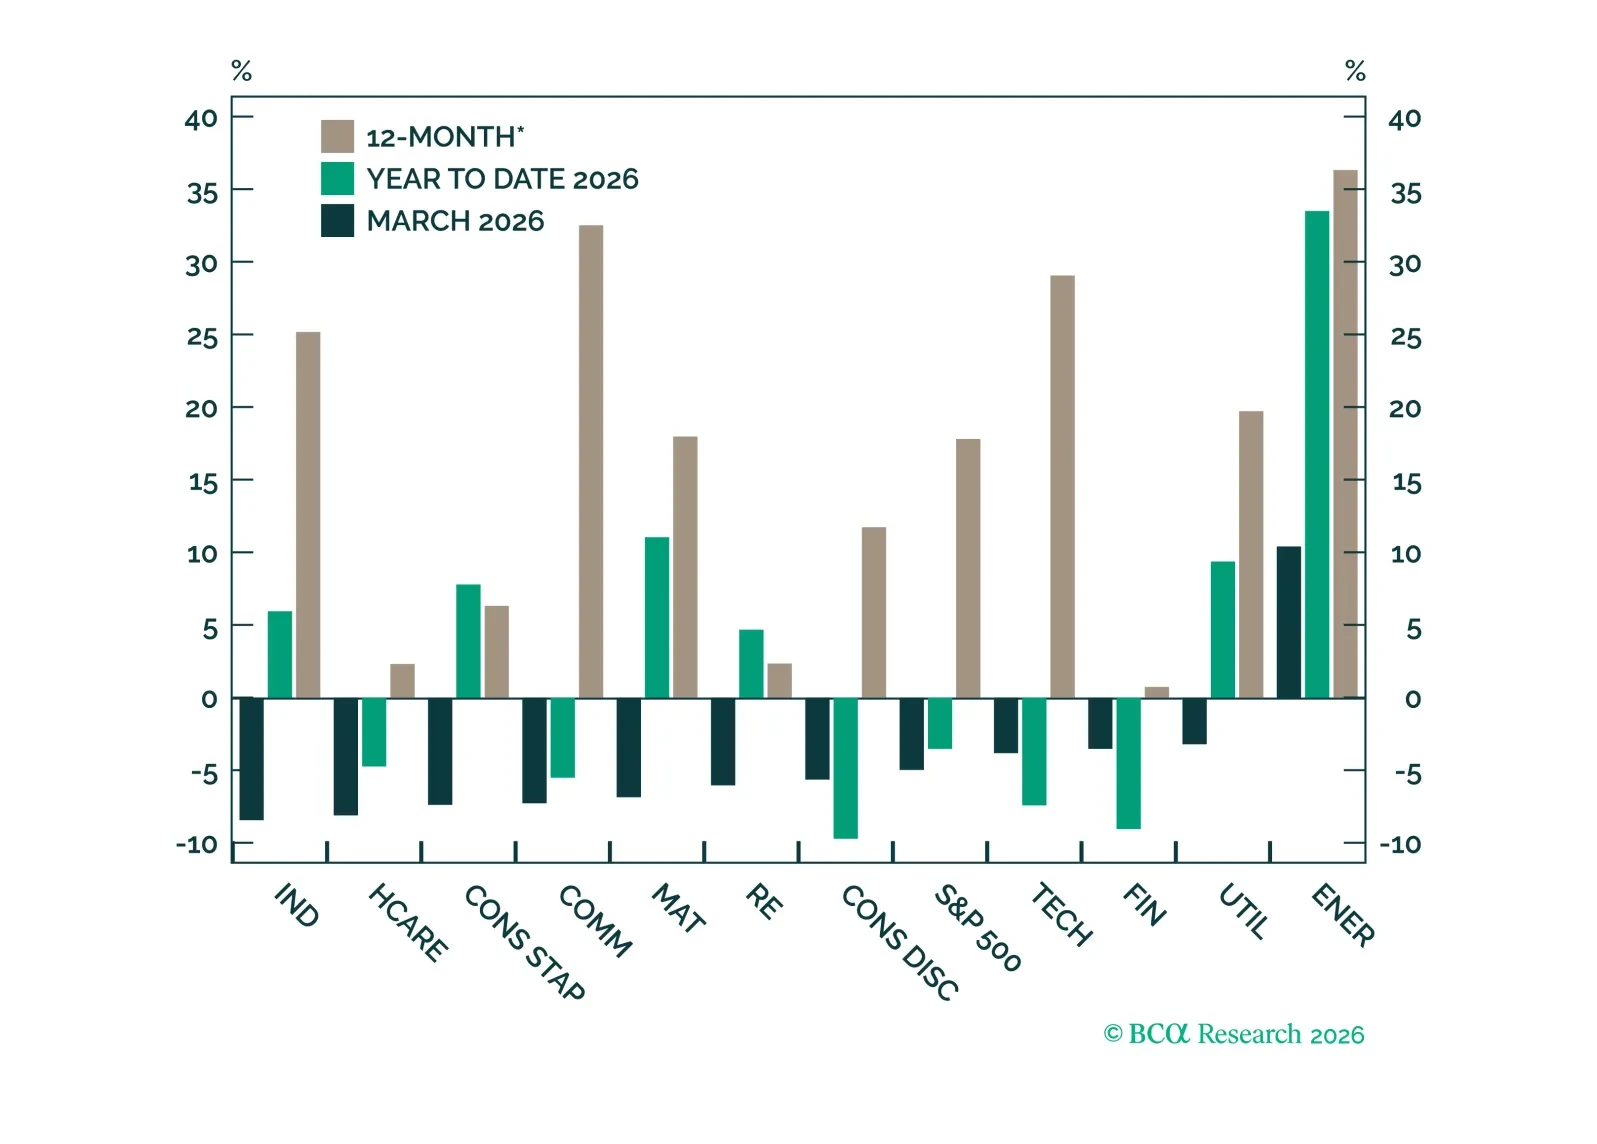
We expect the S&P 500 to deliver $308 of EPS in 2026, with a year-end target of 7700. Revenue growth drives upside, with little margin or multiple expansion. With economic growth tilted toward investment, we are overweight Technology, Industrials, and Materials, market-weight Financials, Energy, Health Care, Communication Services, and Real Estate, and underweight Consumer Staples, Consumer Discretionary, and Utilities.
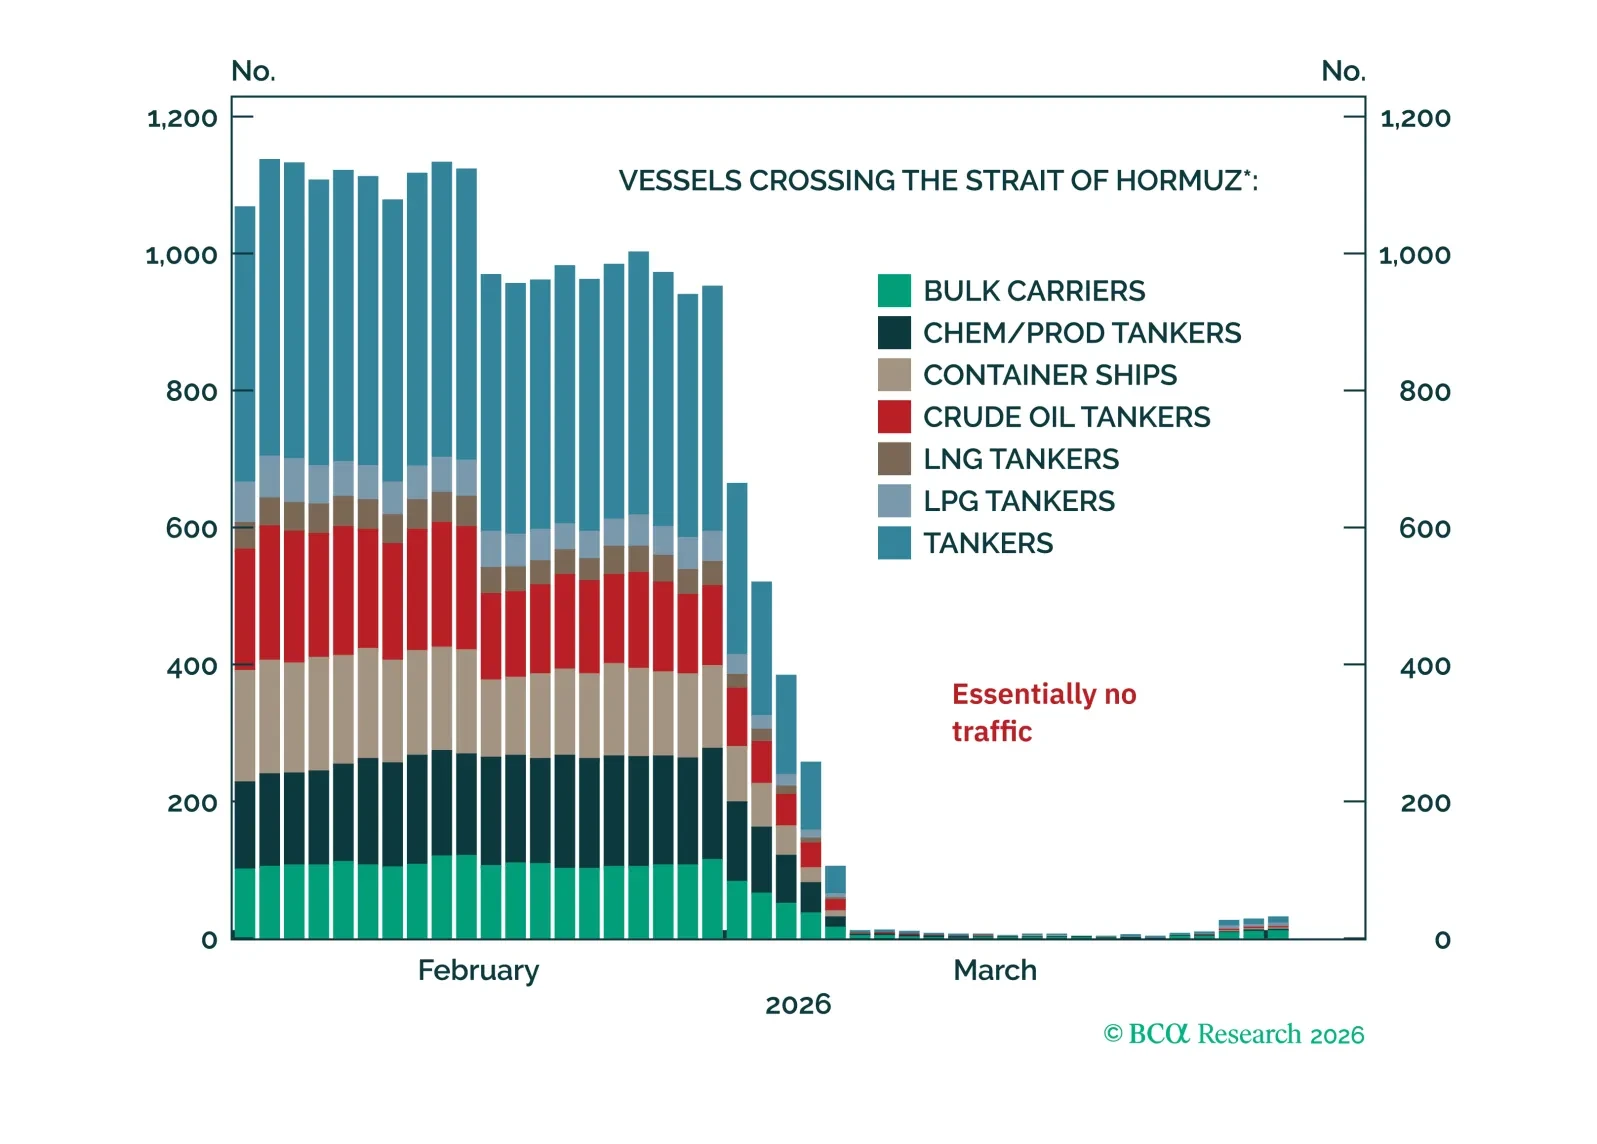
Our "miniature stagflation" episode is coming together on the back of the Iran shock, China slowdown, and American political division.
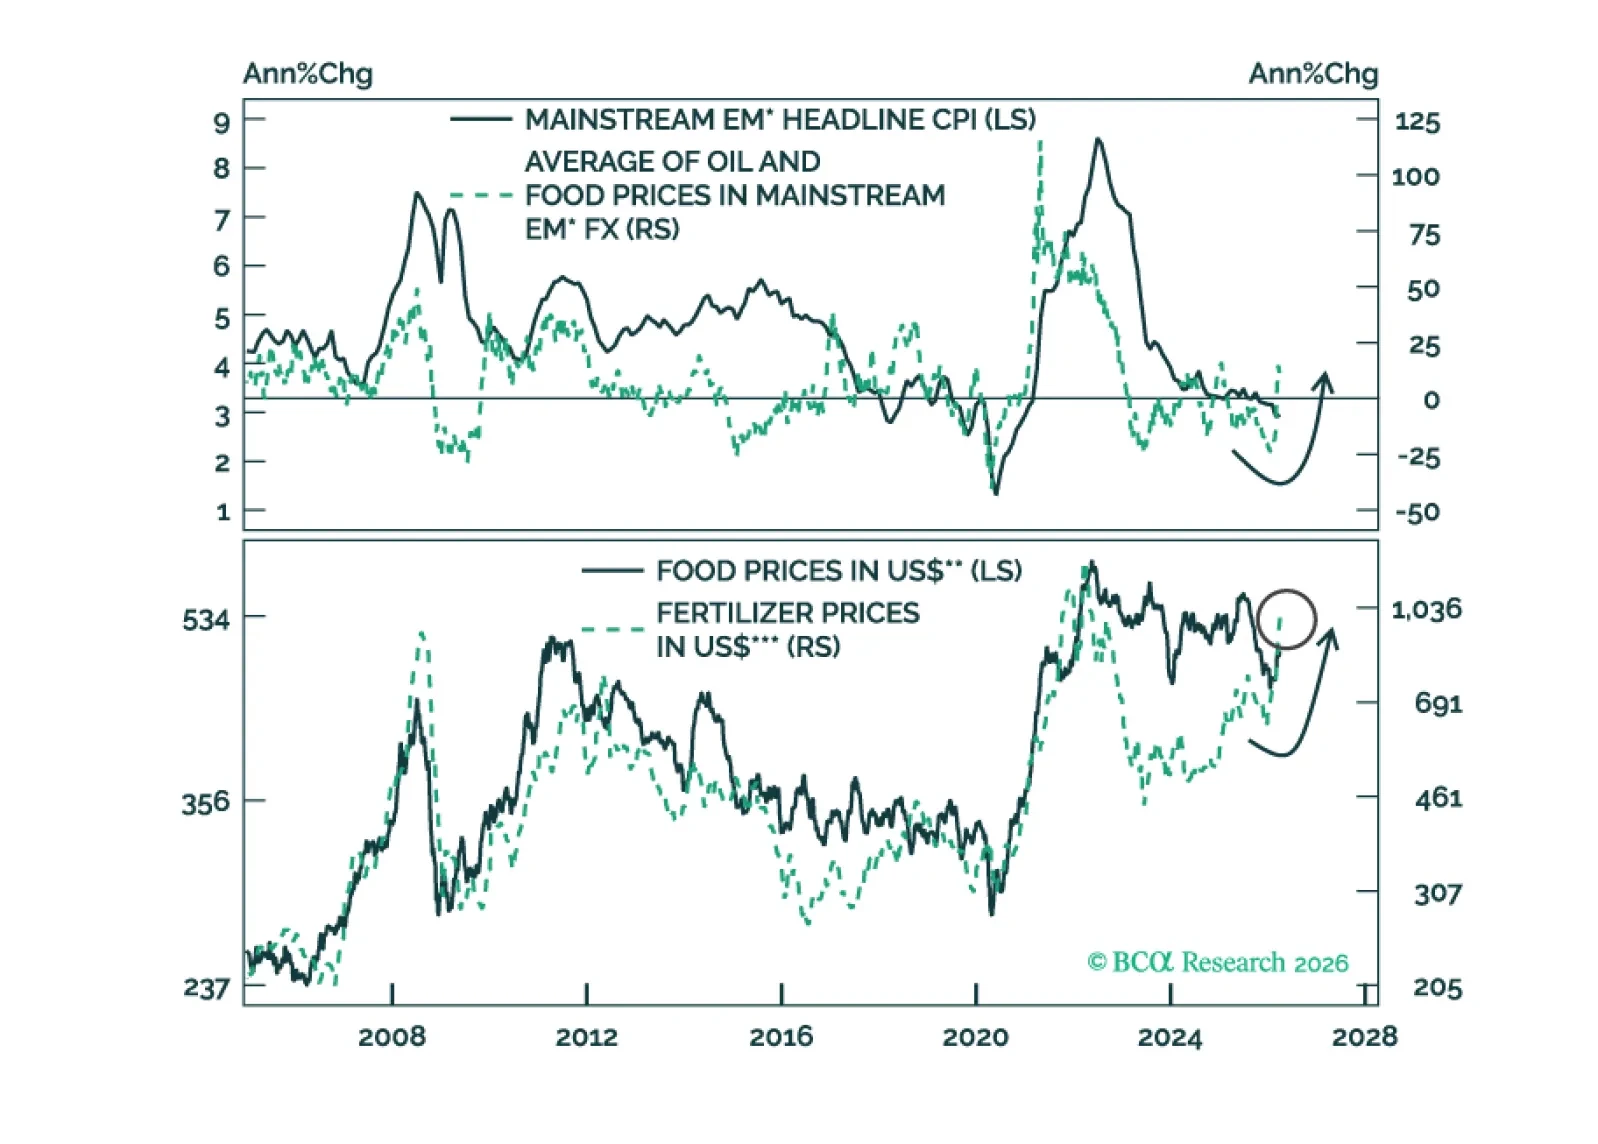
The global risk-off phase will persist. It is too early to buy local-currency bonds in Mainstream EM, but it is not too late to sell EM sovereign and corporate credit (USD bonds).
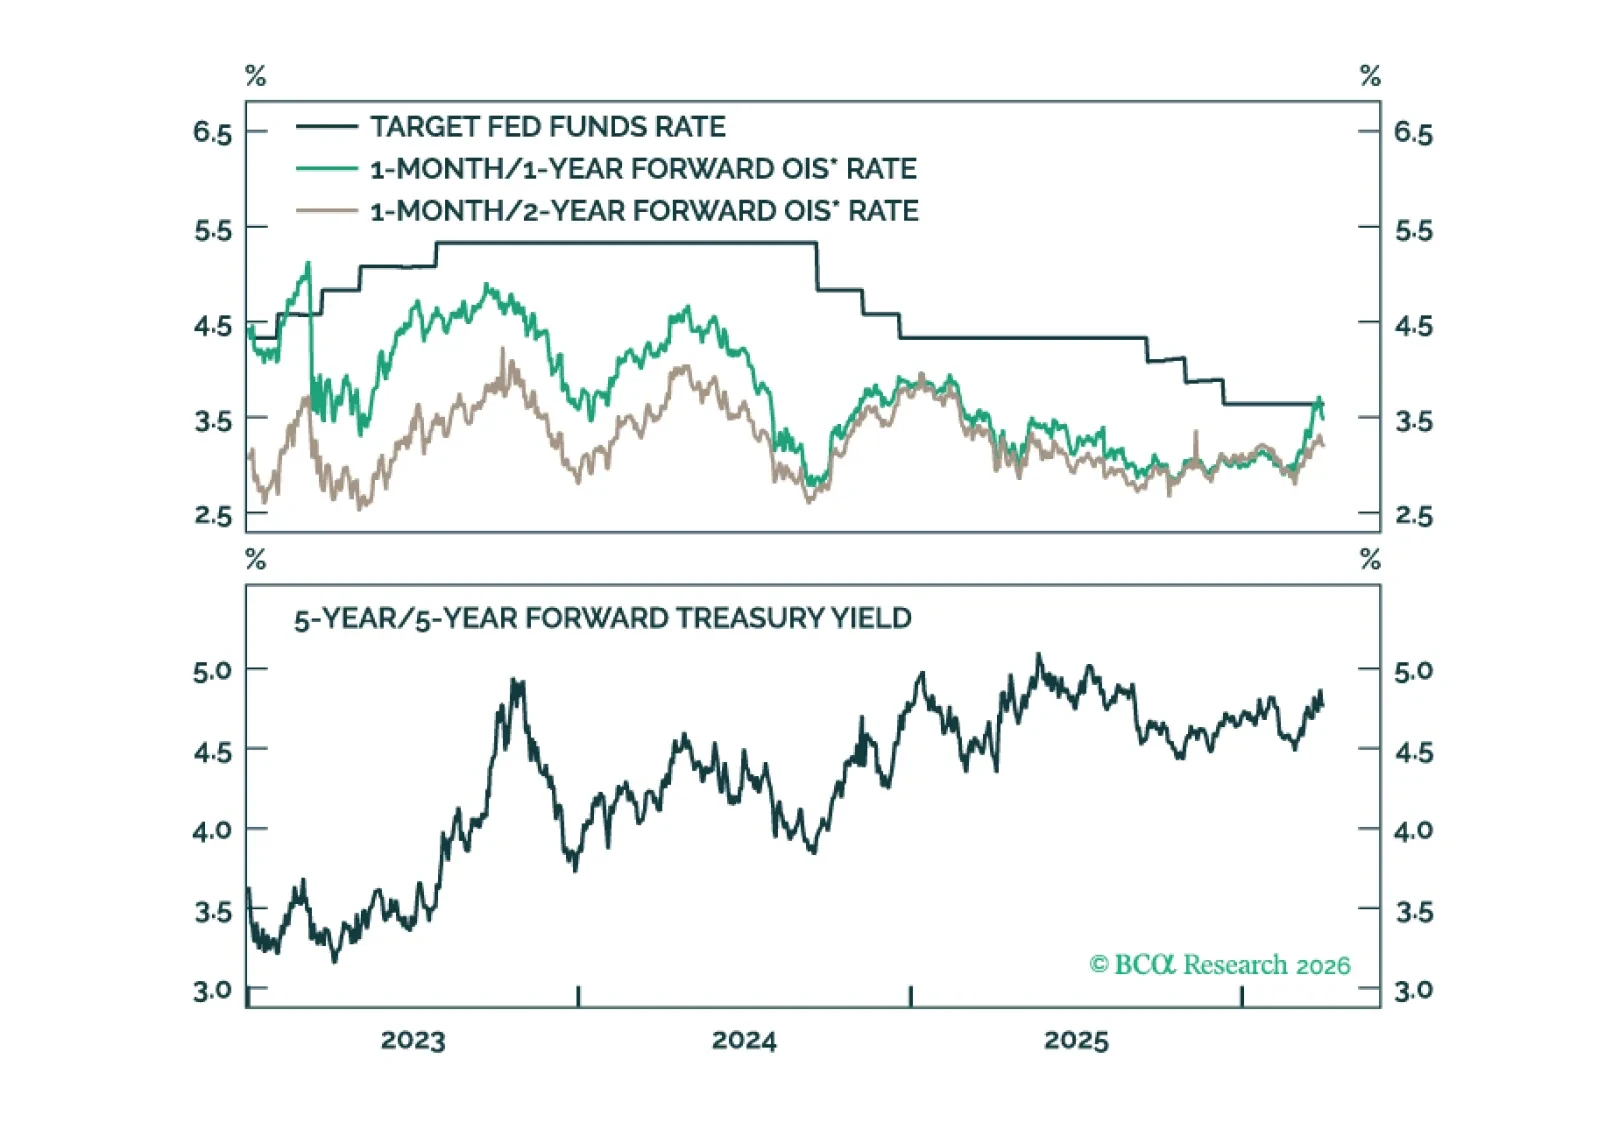
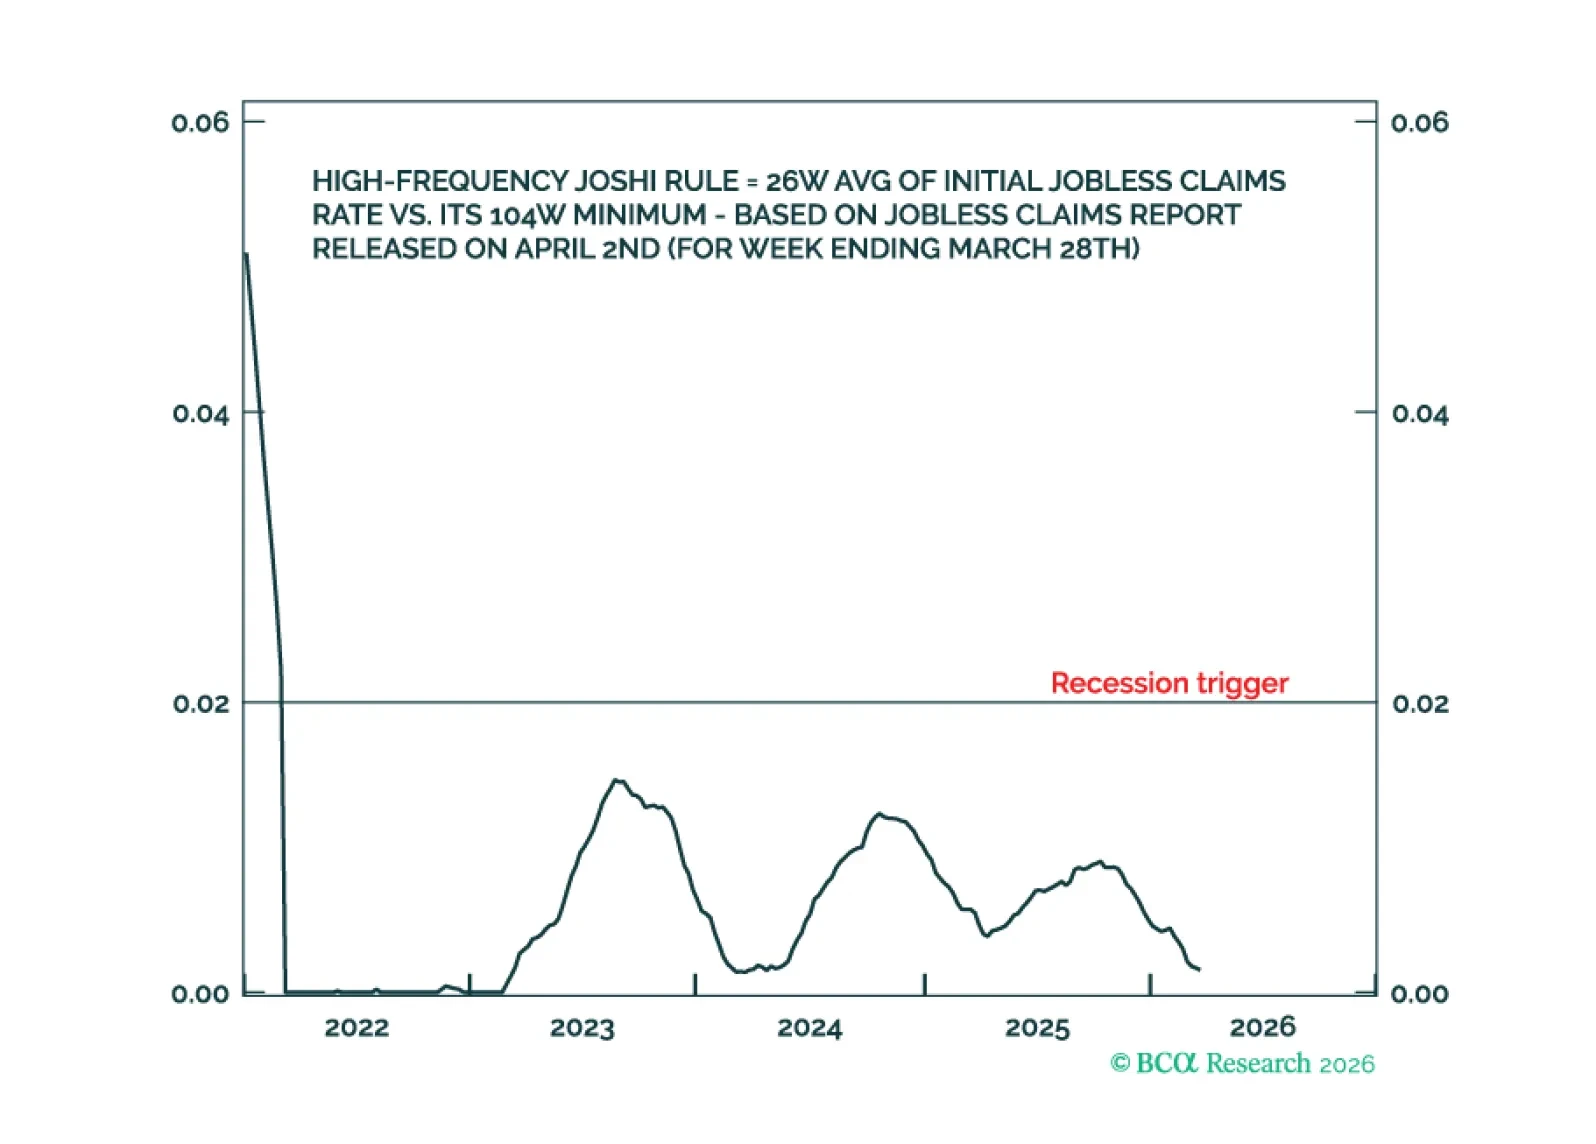
While the Middle East conflict’s inflationary impact is likely to persist, US recession risk is contained whereas non-US recession risk is more elevated. We discuss what this means for investment strategy. Plus, a new tactical trade is to underweight Utilities.

Over the past 48 hours, there has been a cacophony of statements back and forth between Tehran and Washington, DC, some suggesting that the probability of de-escalation is rising. At the same time, kinetic action has continued unabated. A Kuwaiti tanker was targeted by Iran off the coast of the UAE, followed by a Qatari tanker off Doha, and the US ramped up its attacks on Iranian industrial capacity. The world now awaits with great anticipation President Trump’s remarks to the nation on April 1.

We explore how markets reacted to different oil supply shocks in the past, how conditions differ today, and provide a playbook for investors to navigate the current crisis. Remain neutral between equities, bonds, and cash. Downgrade Tail Risk Strategies from Max Overweight to Overweight.