Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Fixed Income

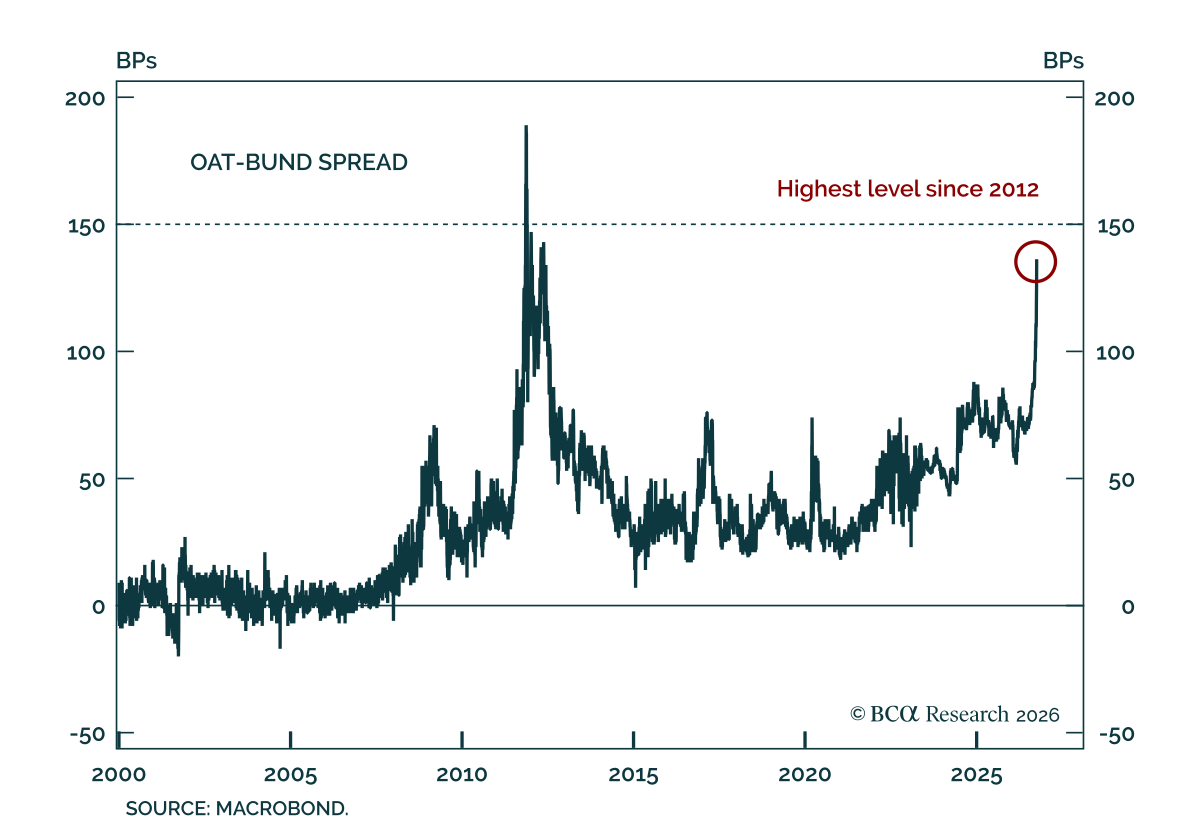
The OAT-Bund spread has widened sharply in recent weeks, reaching 150 bps last Friday, before falling back towards 140 bps. The drivers are homegrown: rising concerns about the fiscal outlook and the political uncertainty surrounding the upcoming presidential…
Our FICC strategists recommend staying long risk, holding neutral duration, and fading volatility spikes over the next six to nine months. While worries keep piling up, spanning politics, wars, higher yields, and doubts about AI, our colleagues argue the one…

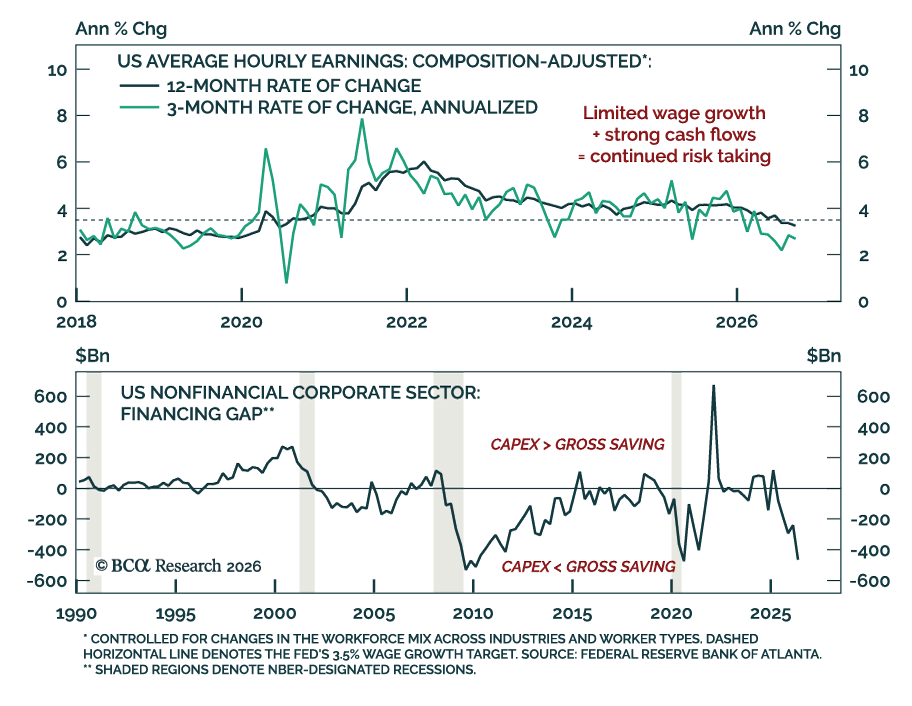
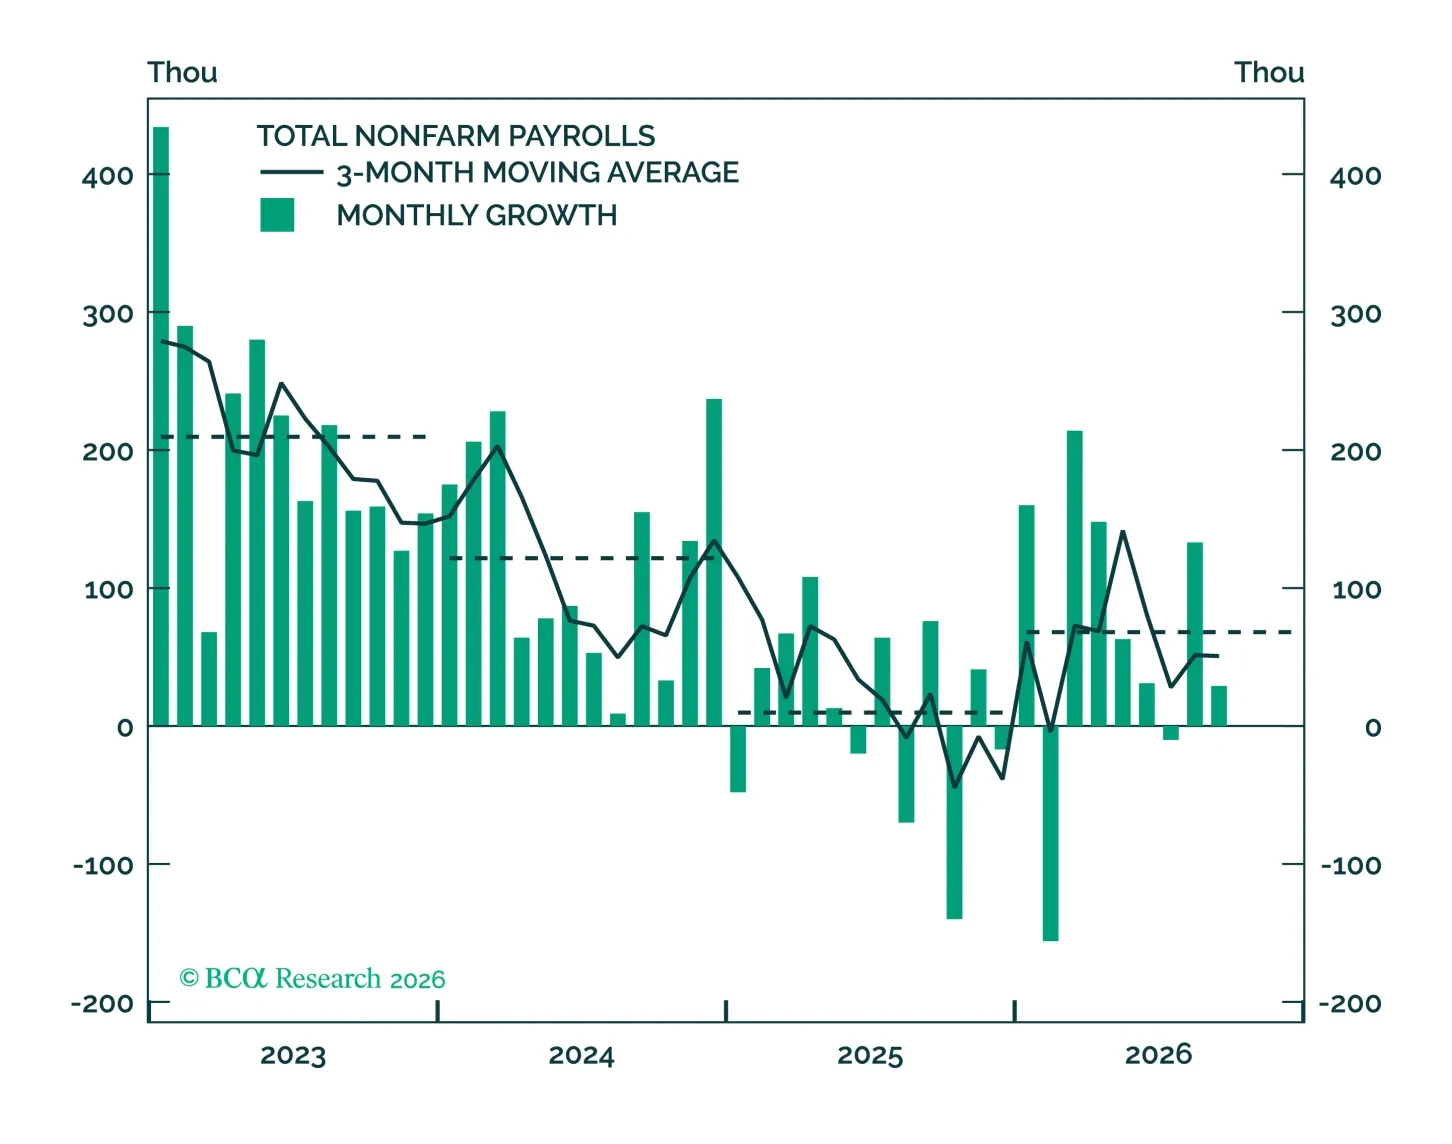
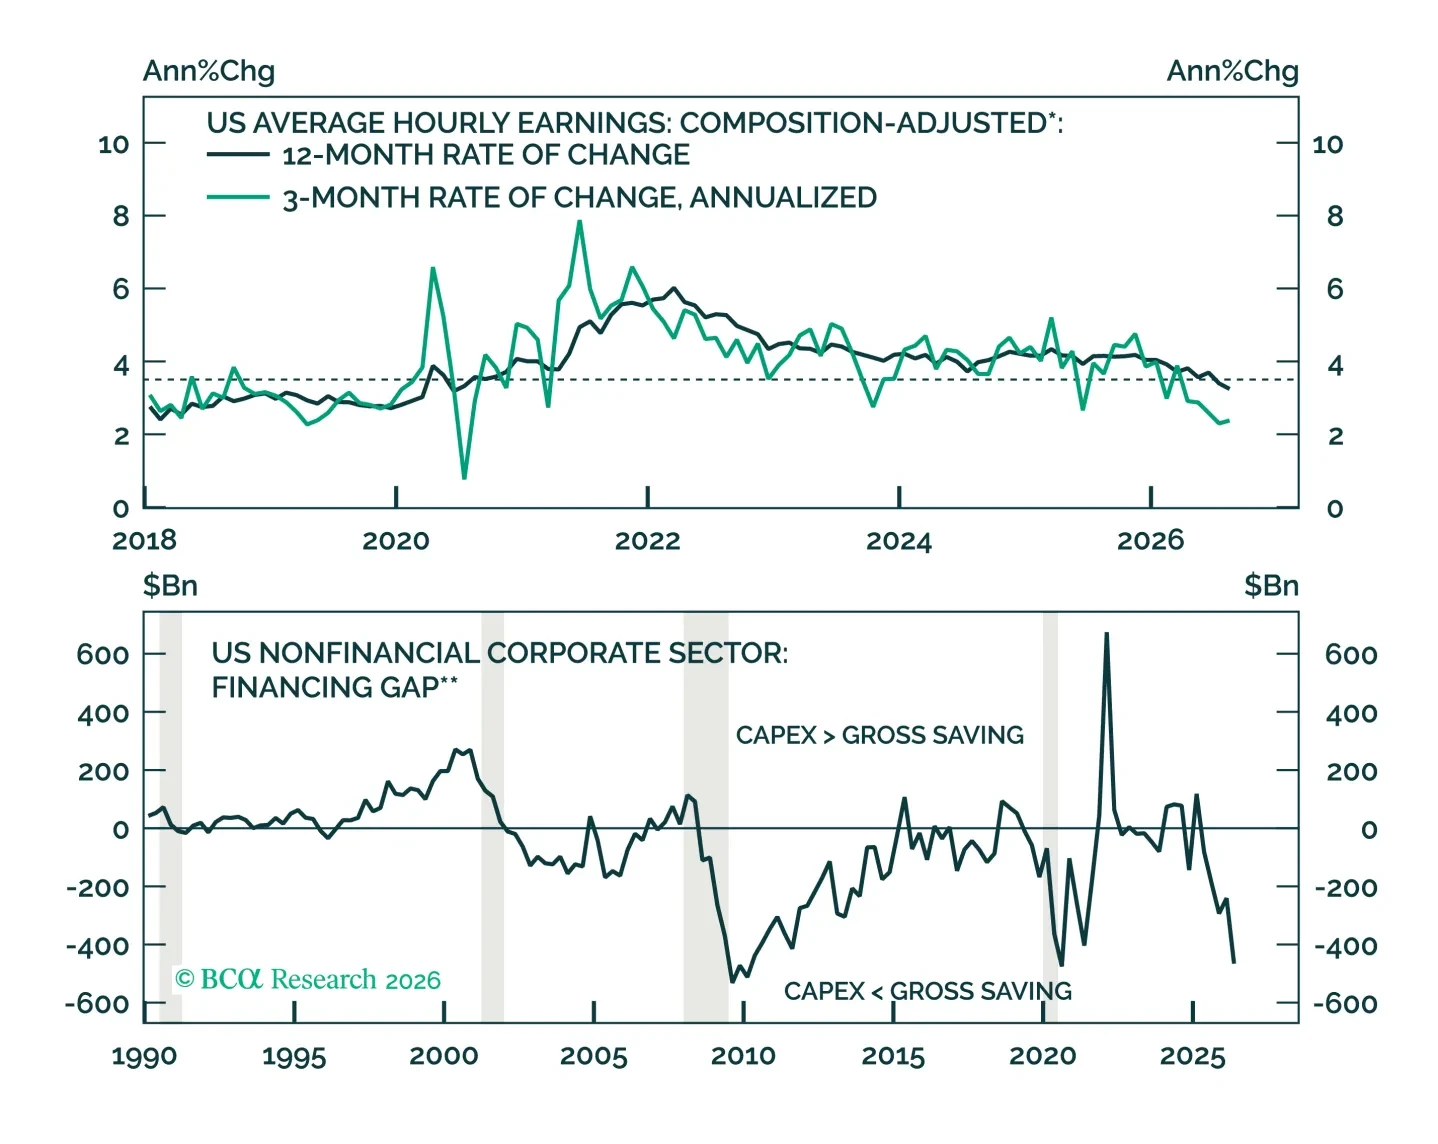
This morning’s jobs report serves to underscore that the labor market is not a source of inflationary pressure and therefore of second-order importance when it comes to the Fed’s near-term decision making.
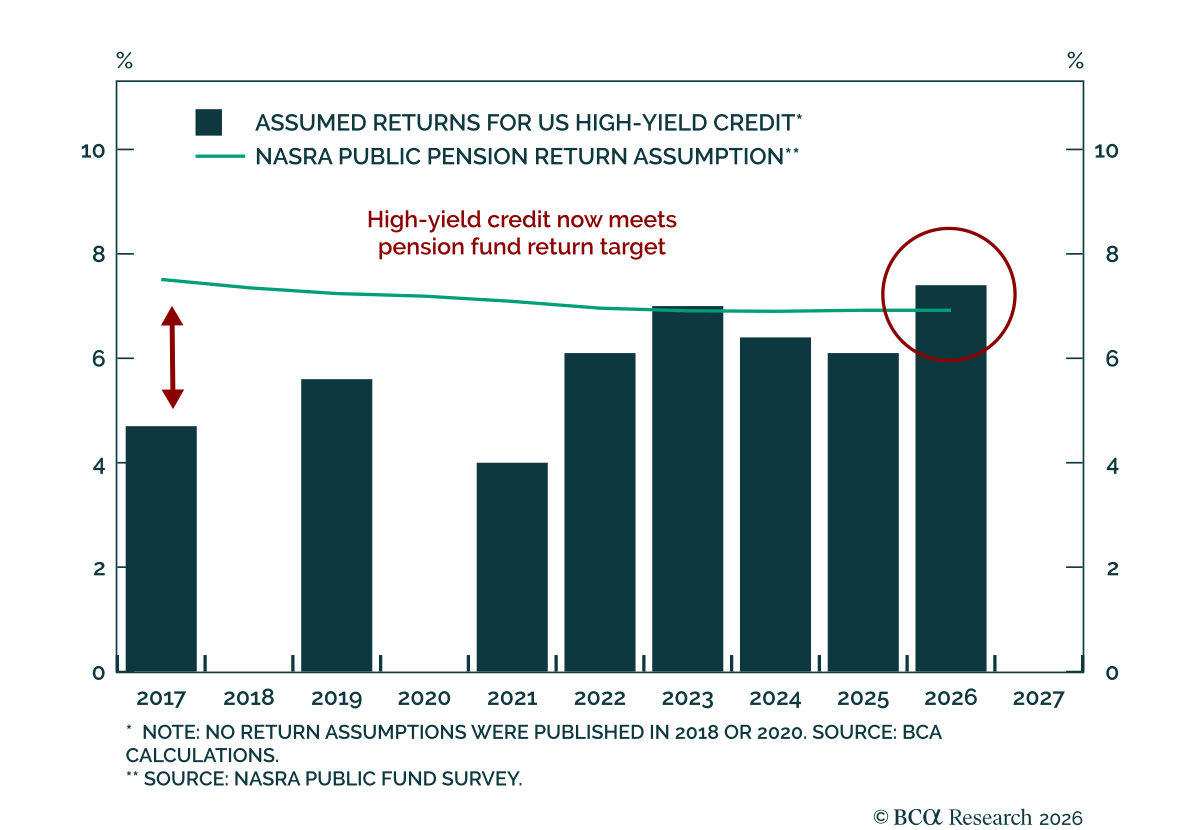
Our Portfolio Construction strategists maintain their overweight to high-yield credit, both within their public asset allocation and versus Private Credit. Higher government bond yields have reset the opportunity set. BCA's capital market assumptions project…

Politics, wars, a global tightening cycle, doubts over AI capex: the wall of worry keeps rising. But the spark that would topple risk assets is missing. Our Q4 FICC outlook explains why to stay long risk, and where the danger lies.
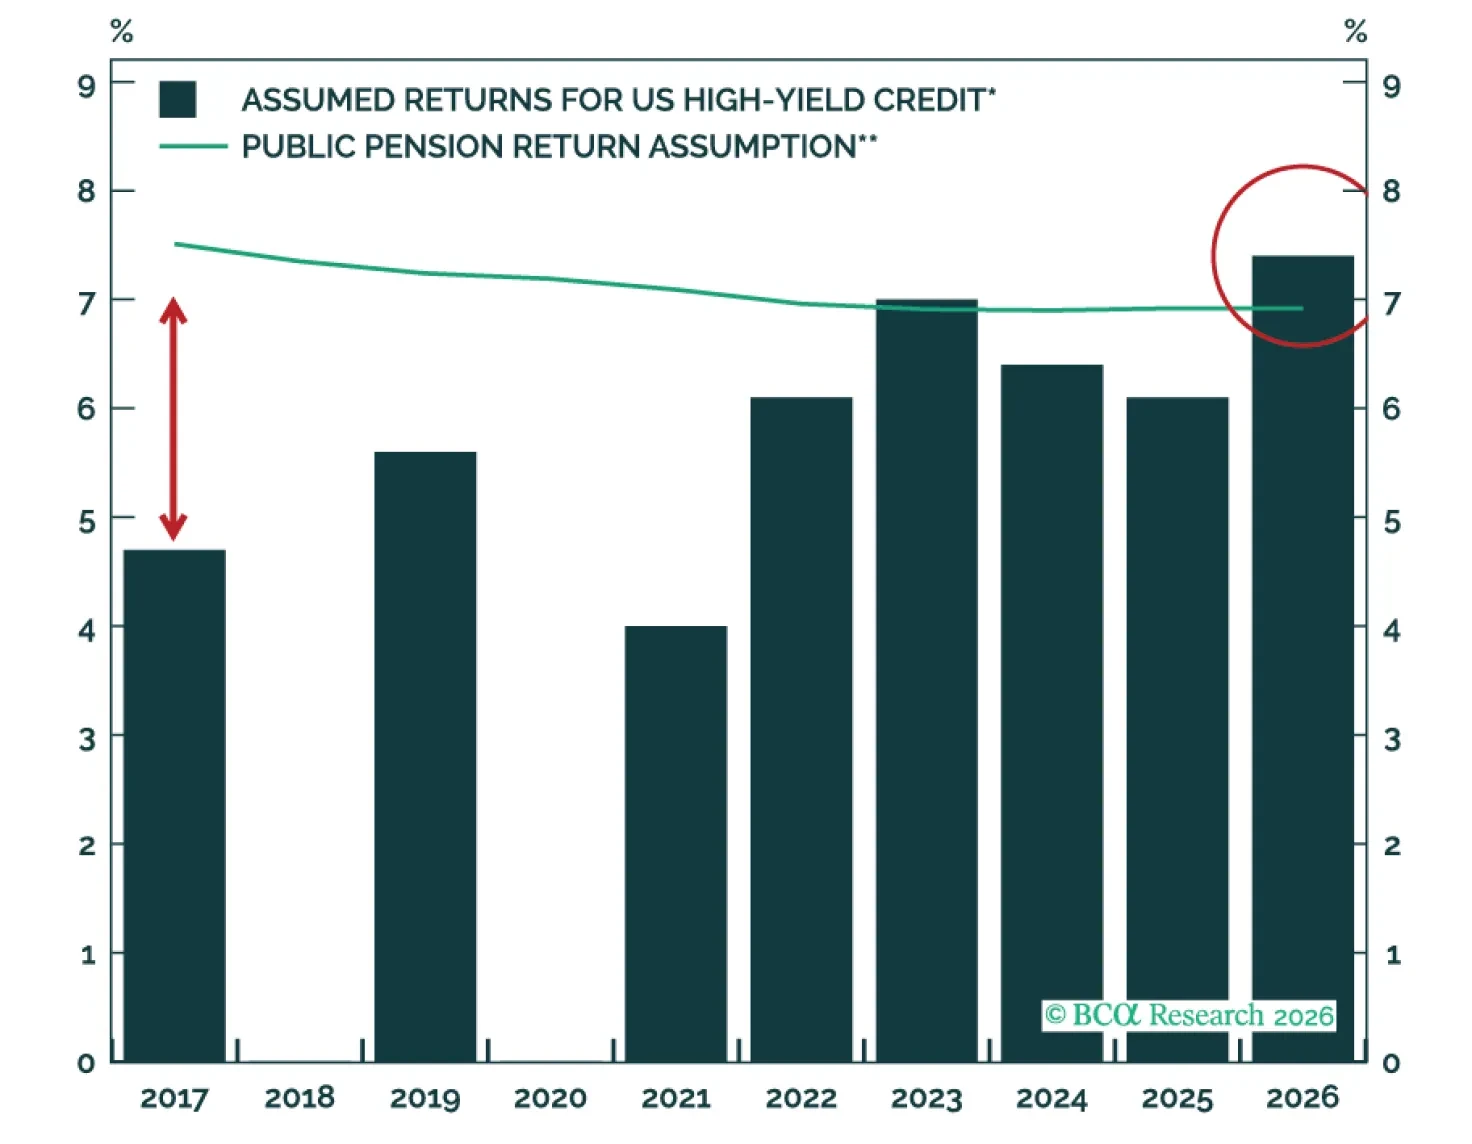
Higher rates have changed the opportunity set. Overweight High-Yield Credit, both within asset allocation and versus Private Credit. Investors are no longer picking up pennies in front of a steamroller.
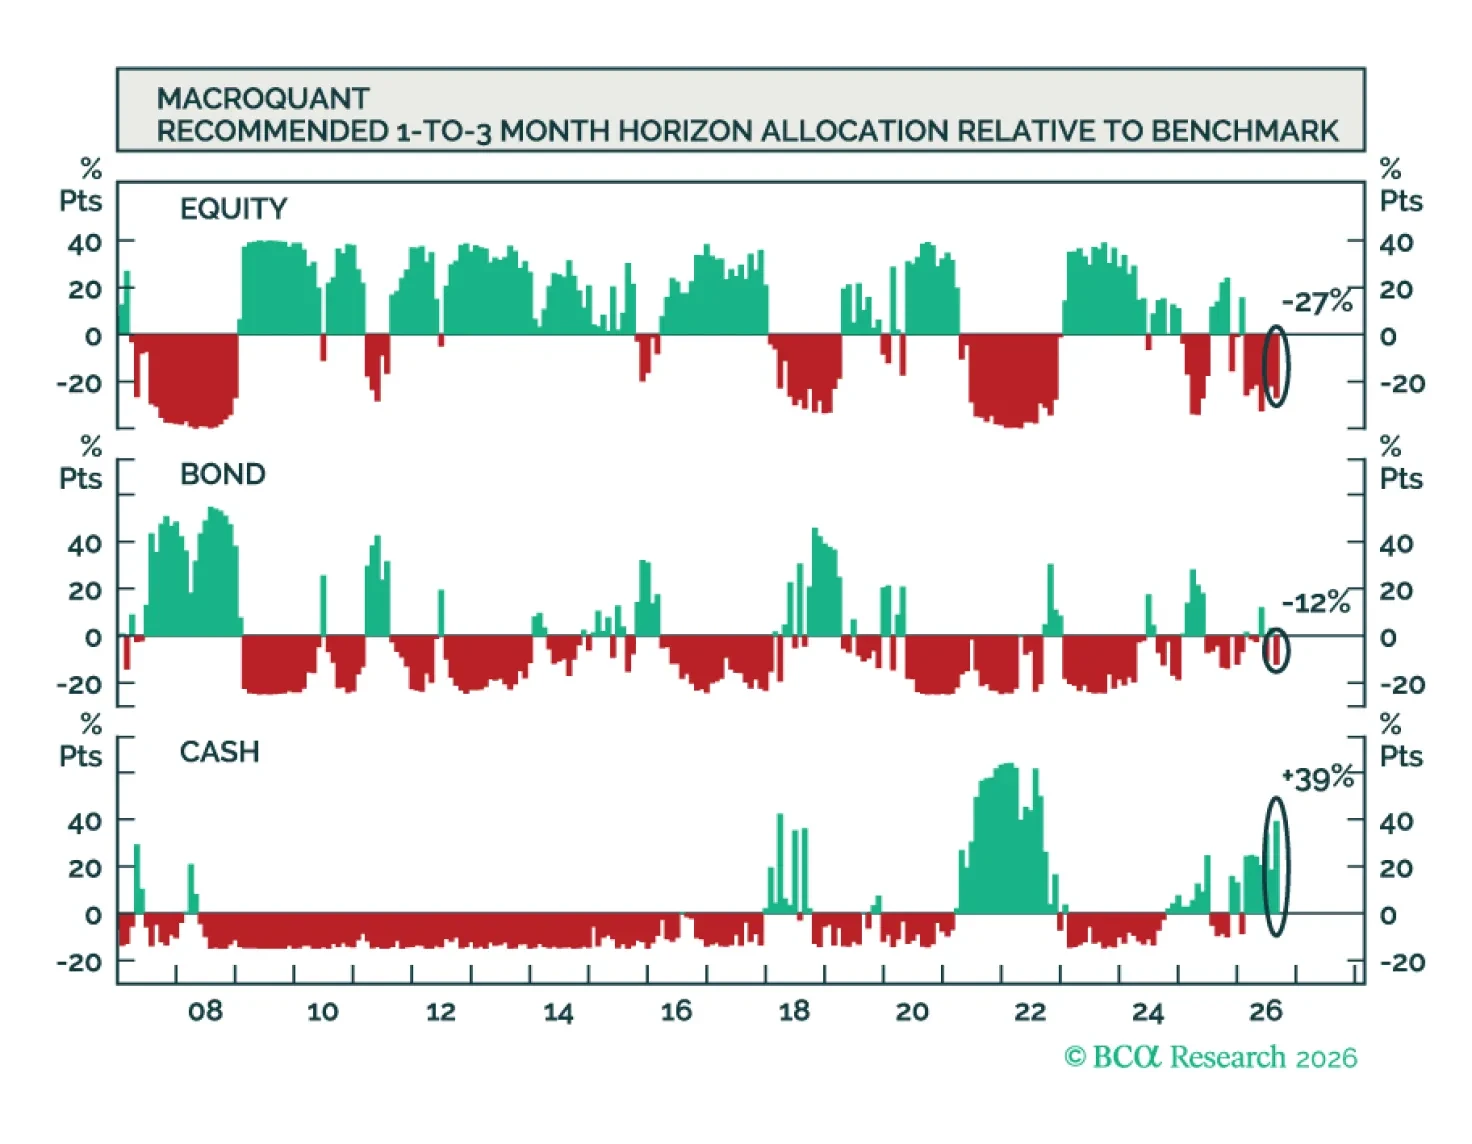
MacroQuant recommends an underweight to equities and bonds, counterbalanced by a significant overweight to cash. The model is very bullish on the US dollar, slightly negative on gold and copper, and positive on oil.
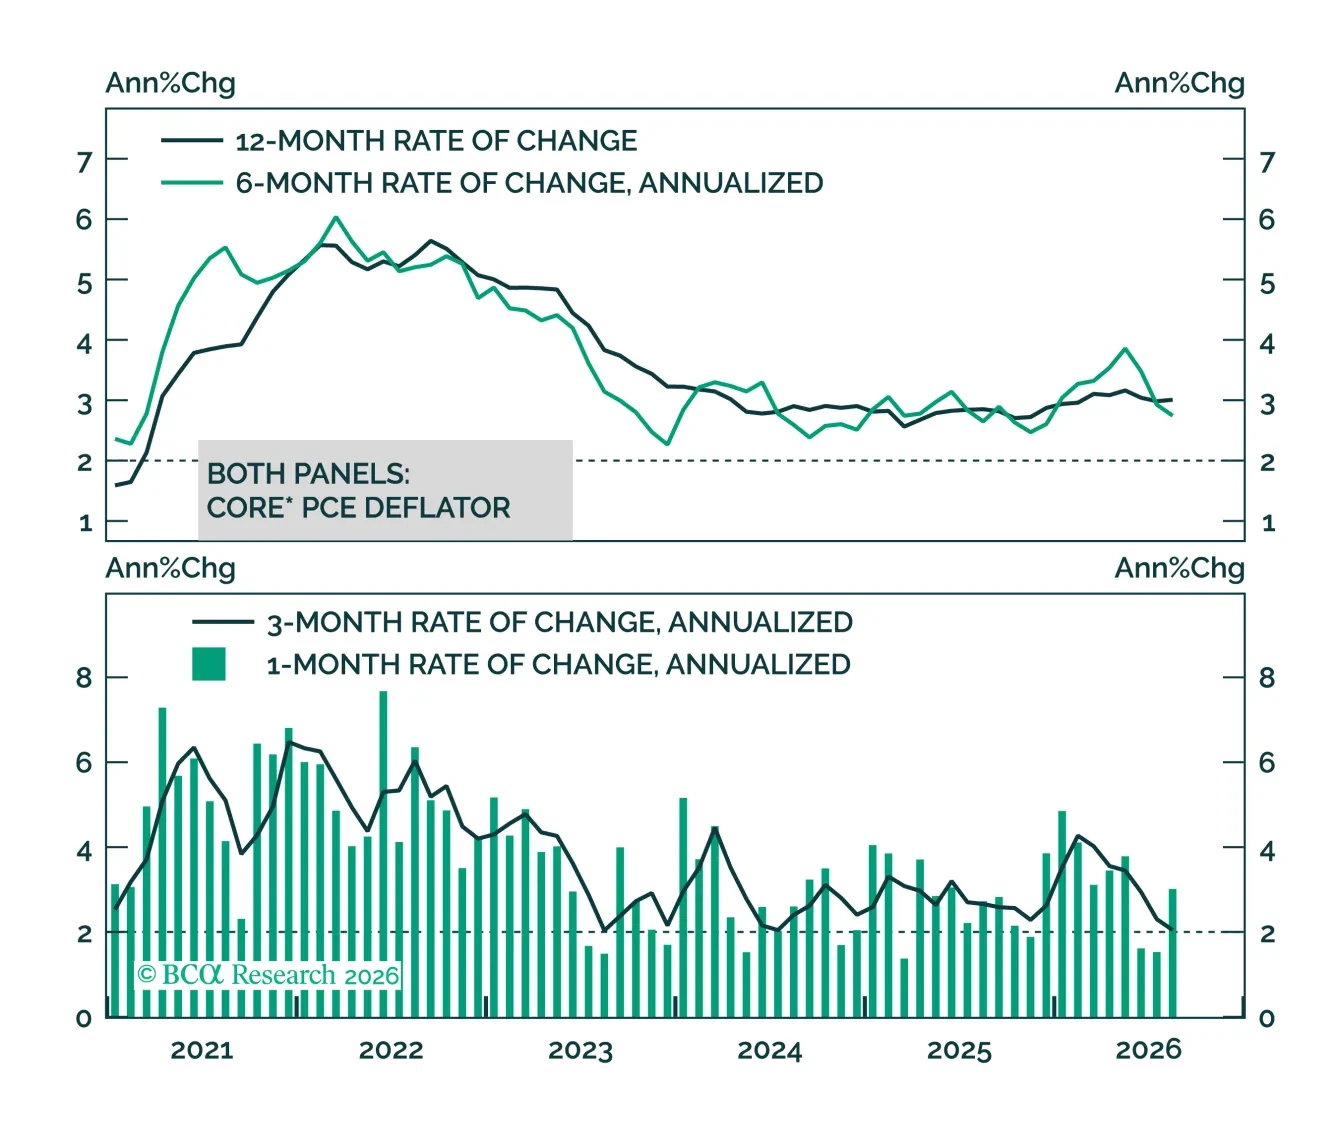
Core US inflation is still running above target. But this morning’s data revisions reveal that the gap is not nearly as large as it appeared yesterday.
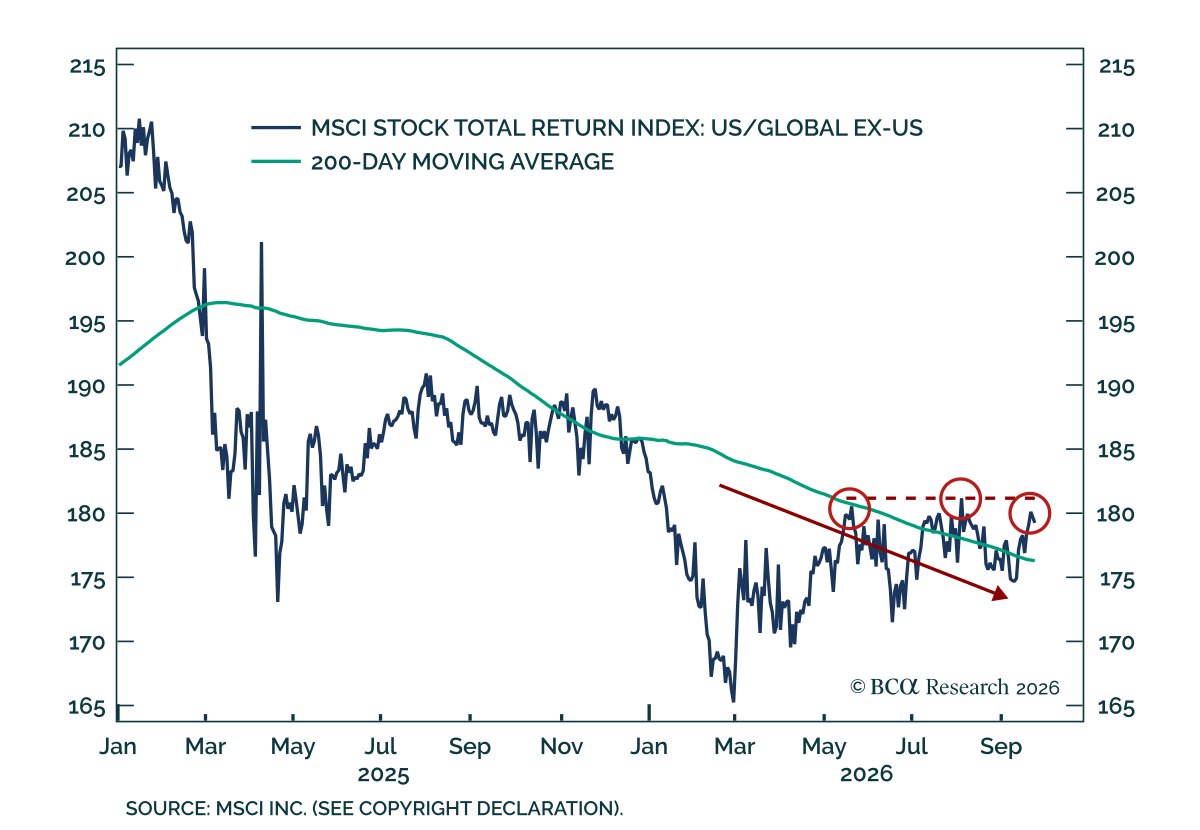
 

The consensus among BCA's strategists remains overweight equities and neutral across bonds and cash on a 12-month horizon. Within equities, the US moves to underweight relative to MSCI ACWI on a 12-month view; on a 3-month horizon, we remain overweight.…
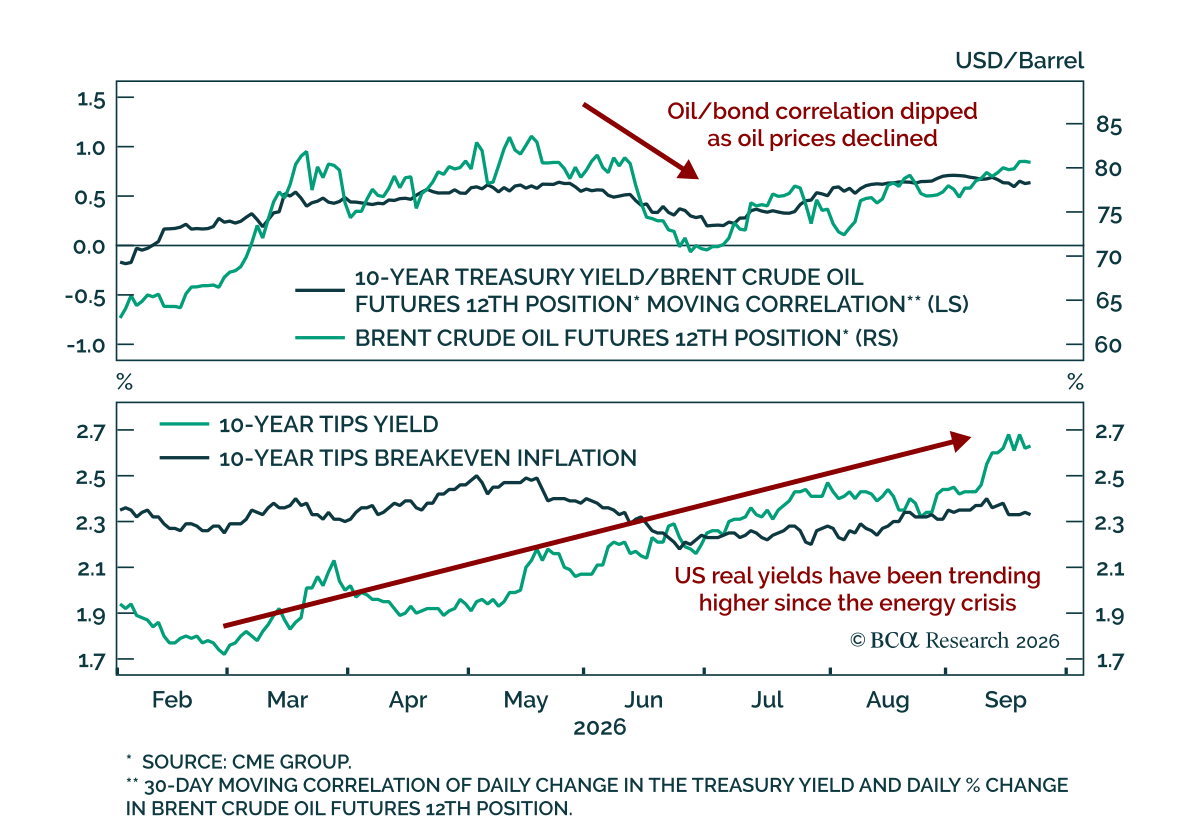
Oil prices and US Treasury yields have moved in lockstep this year, but oil matters less for US yields than the correlation suggests. The joint rise is not purely a coincidence. Higher oil prices play a role in the hawkish repricing of the Fed's policy path,…