 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
An intriguing dichotomy is emerging in how the US government has responded to Israel’s attack against Iran. First, following the attack, Secretary of State Marco Rubio issued a terse statement denying US involvement.
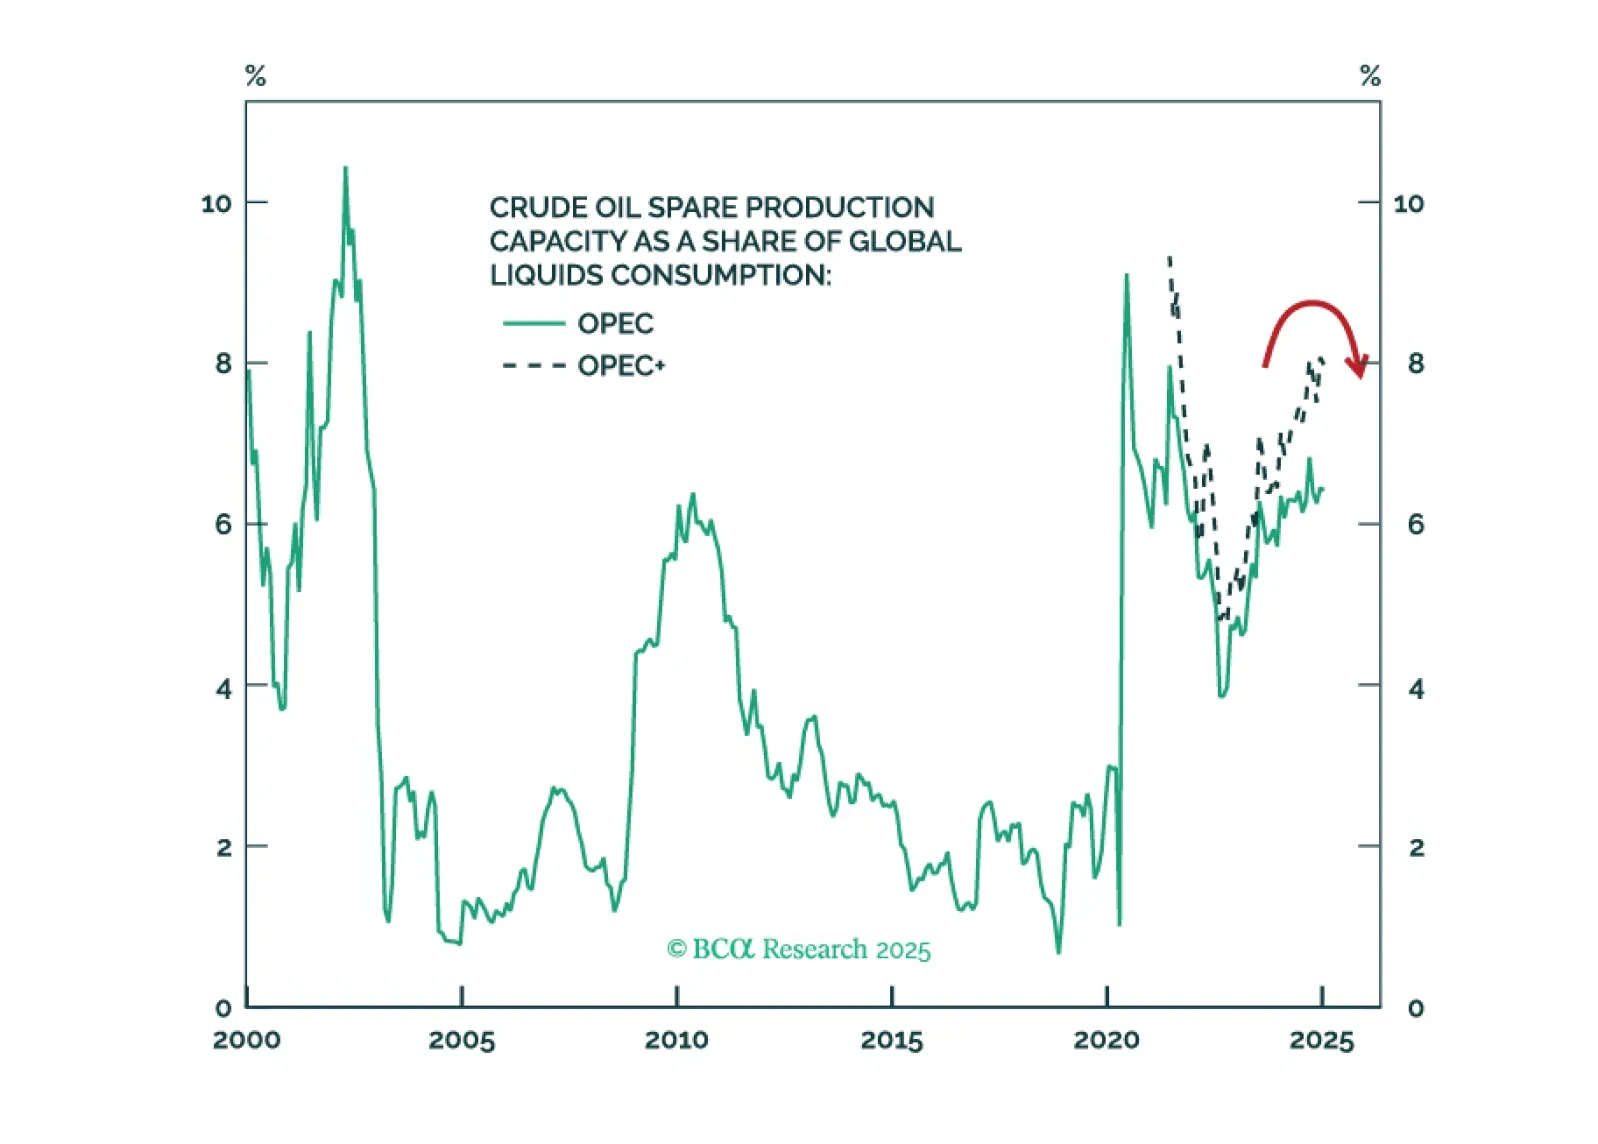
Investors should hold gold, build up some cash, tactically overweight US equities relative to global, and prepare for at least minor oil supply shocks – possibly major shocks – as the Israel-Iran war escalates.
Israel has taken unilateral action against Iran on June 12. According to the media reports, the following are the key developments: Israel has attacked multiple targets across Iran, including in the capital Tehran. Israeli Prime Minister Benjamin Netanyahu has stated that the Operation Rising Lion would “continue for as many days as it takes to remove” the alleged Iranian nuclear threat. The US has stated that it did not participate in the attack, calling Israel’s action unilateral.
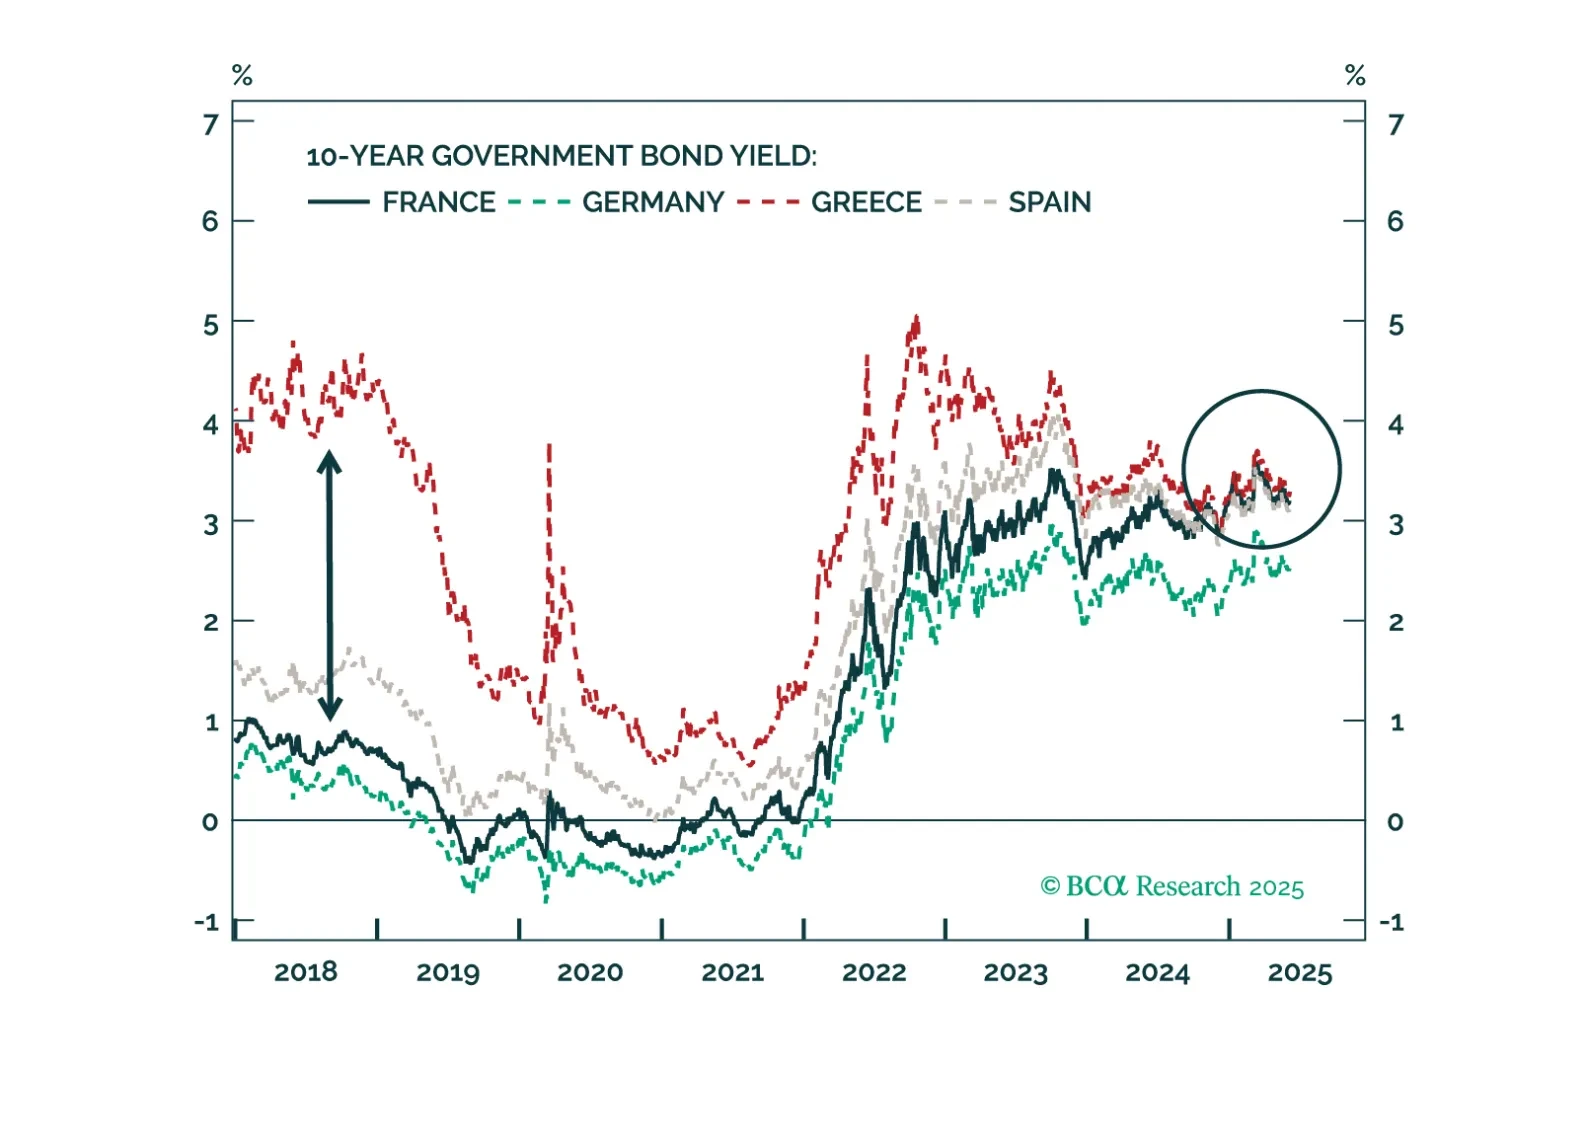
Bond market volatility will spike again in the near term. The Fed is committed to an easing cycle yet the Trump administration’s signature fiscal policy action will stimulate the economy. Tariffs are supposed to keep the budget deficit contained but they are inflationary.
This month, we flip the order of our chartpack. We focus on the secular/long-term first. Both because we think that we have something profound to say and because we believe that our tactical call has very little new value-add. We remain convinced, as we have been for over a year, that President Trump is not willing to upend decades of US trade policy.
President Trump has activated the California national guard as protests envelop the city of Los Angeles for the third day in the row. This is the first time that the national guard has been activated by the federal government in Los Angeles since the 1992 riots. Our clients from Australia to Greece have inundated us with questions of how far the situation can go.
Several astute clients have asked us to comment on the recent extraordinary attack by Ukraine against Russia. The attack, which did not harm any Russian military personnel, occurred on June 1 and struck airfields across the vastness of Russia, as far as the Far East. According to Ukrainian officials, 41 military aircraft were successfully targeted. This information has not been verified by either Russian or Western officials.
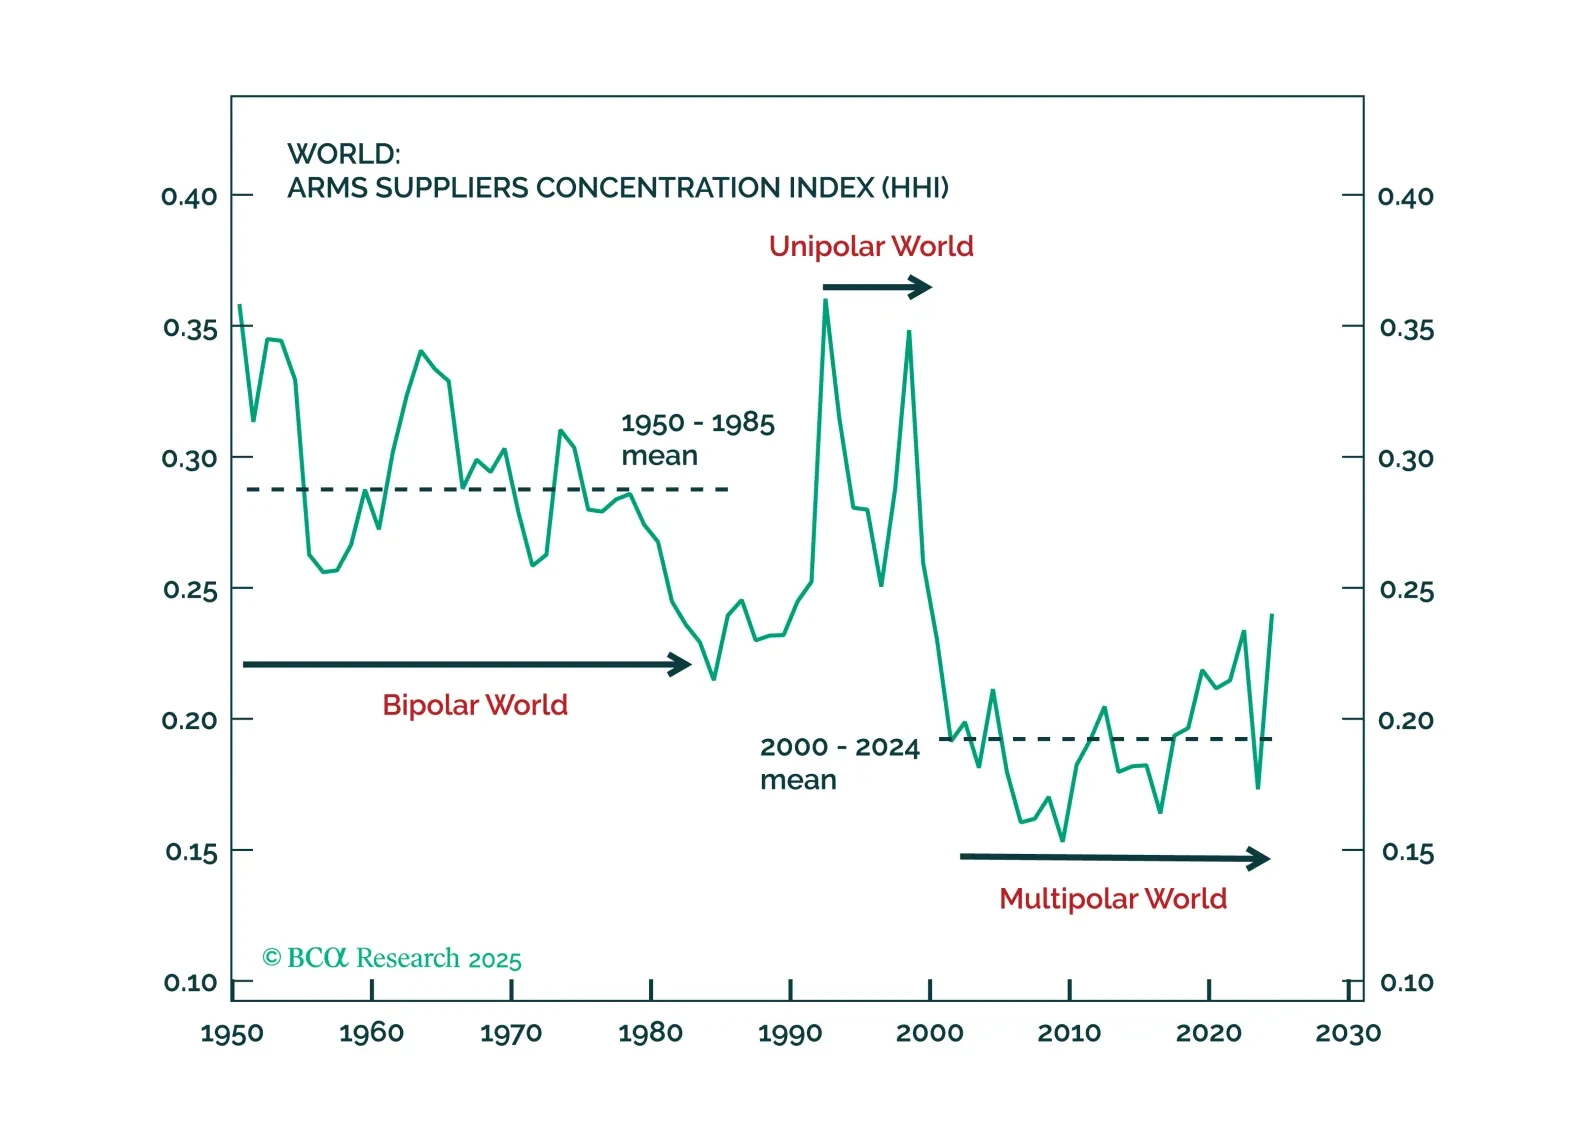
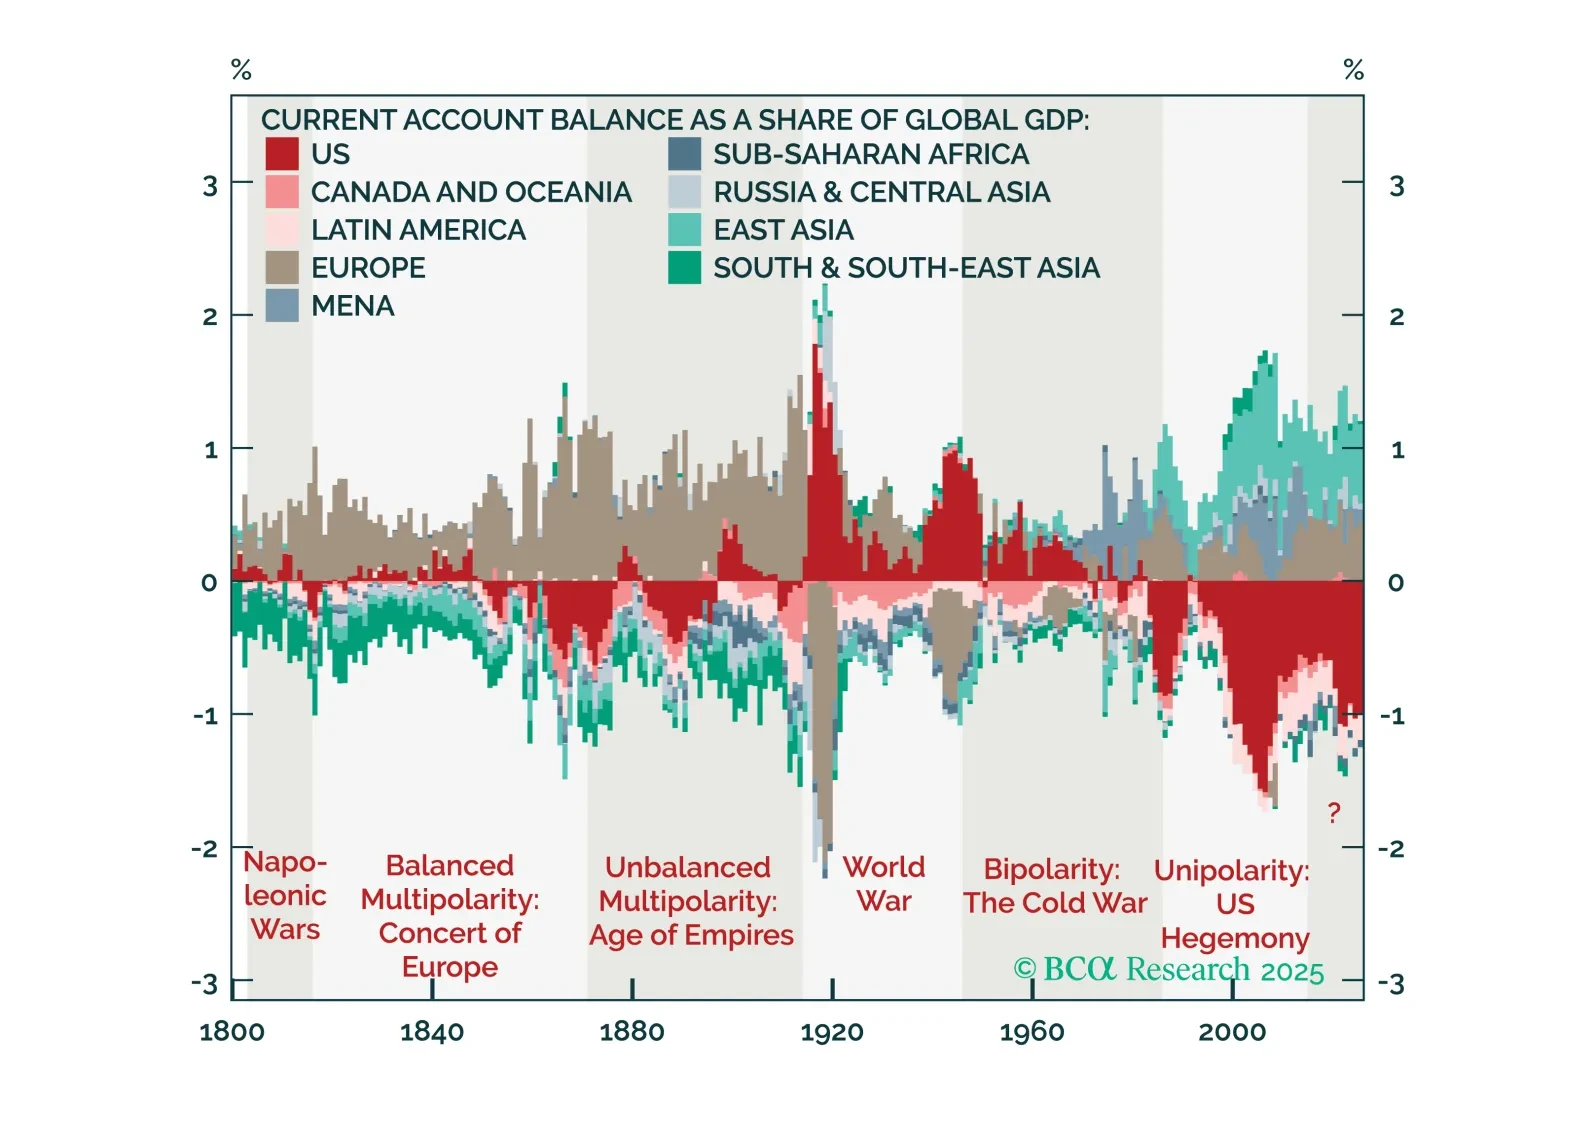
In our Beta report, we focus on our decade view. Many of our global allocator clients are scrambling to incorporate geopolitics into their strategic asset allocation. For most, this means thinking about war… or about future end-states. This is a mistake. We consider the next five years (maybe a decade) as the transition to the new era, a transition away from American unipolarity. And the transition itself is investment relevant. A transition to a multipolar world – which we think is occurring – will crush the USD and favor non-US assets. A transition to a bipolar world – not our base case, but still possible – would do the opposite.
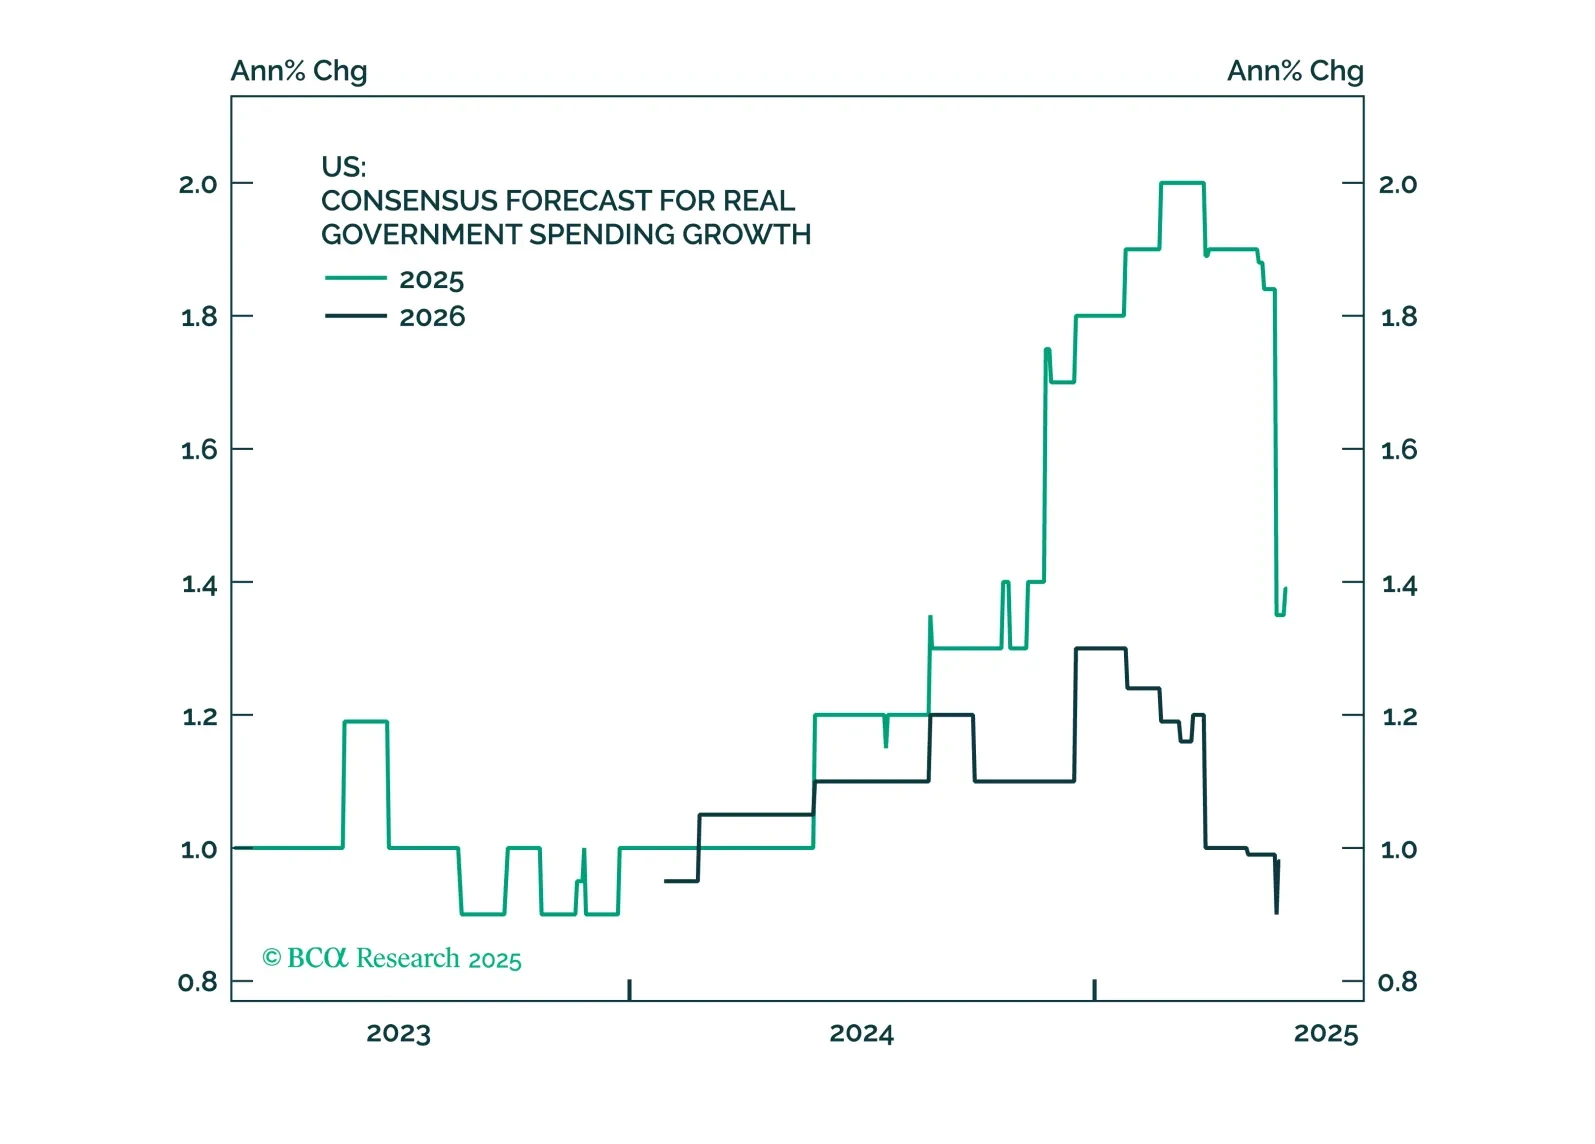
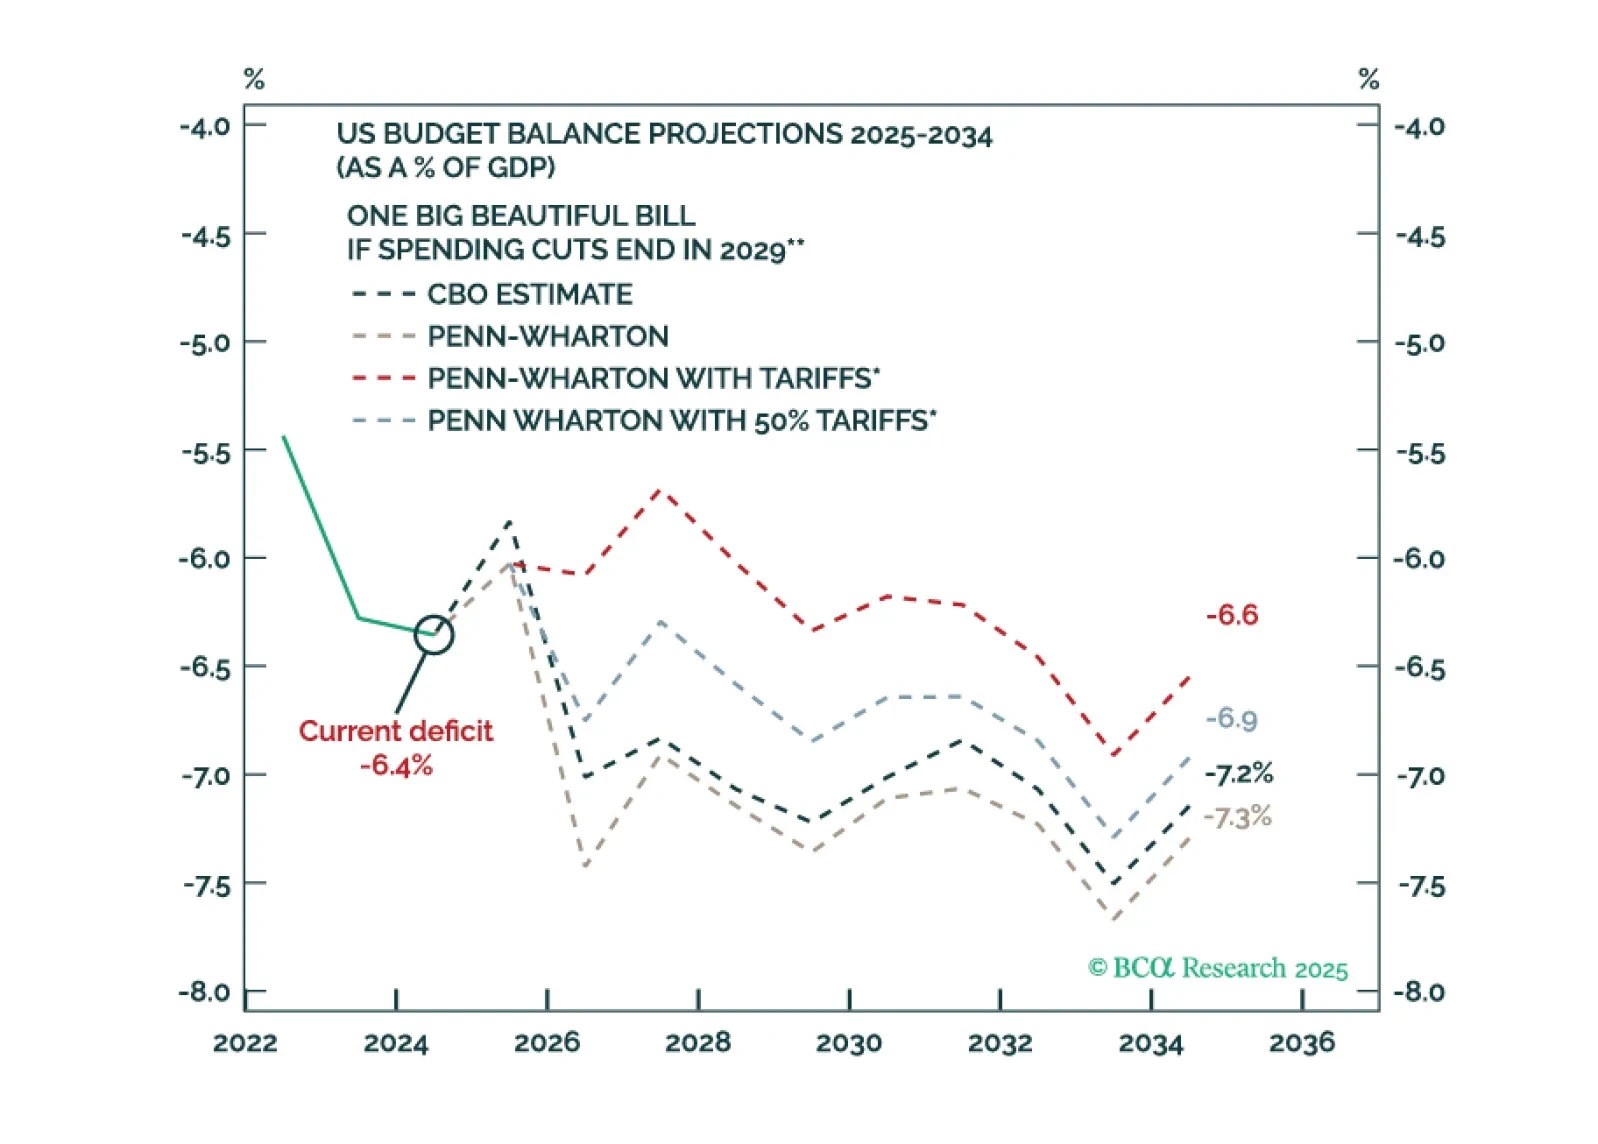
This month, we focus on the One Big Beautiful Bill Act (OBBBA). Our assessment in the Alpha report is that there won’t be any remaining alpha to harvest by shorting duration. The team that coined the “Human Steepener” moniker for President Trump is, effectively, throwing in the towel on looking for more upside to yields. There are many reasons for that view, but the main one is that the OBBBA legislation is just not that profligate, especially not relative to the investors’ expectations in the early days of the Trump 2.0 term.